MUTHOOTFIN
Equity Metrics
September 24, 2026
Muthoot Finance Limited
Non Banking Financial Company (NBFC)
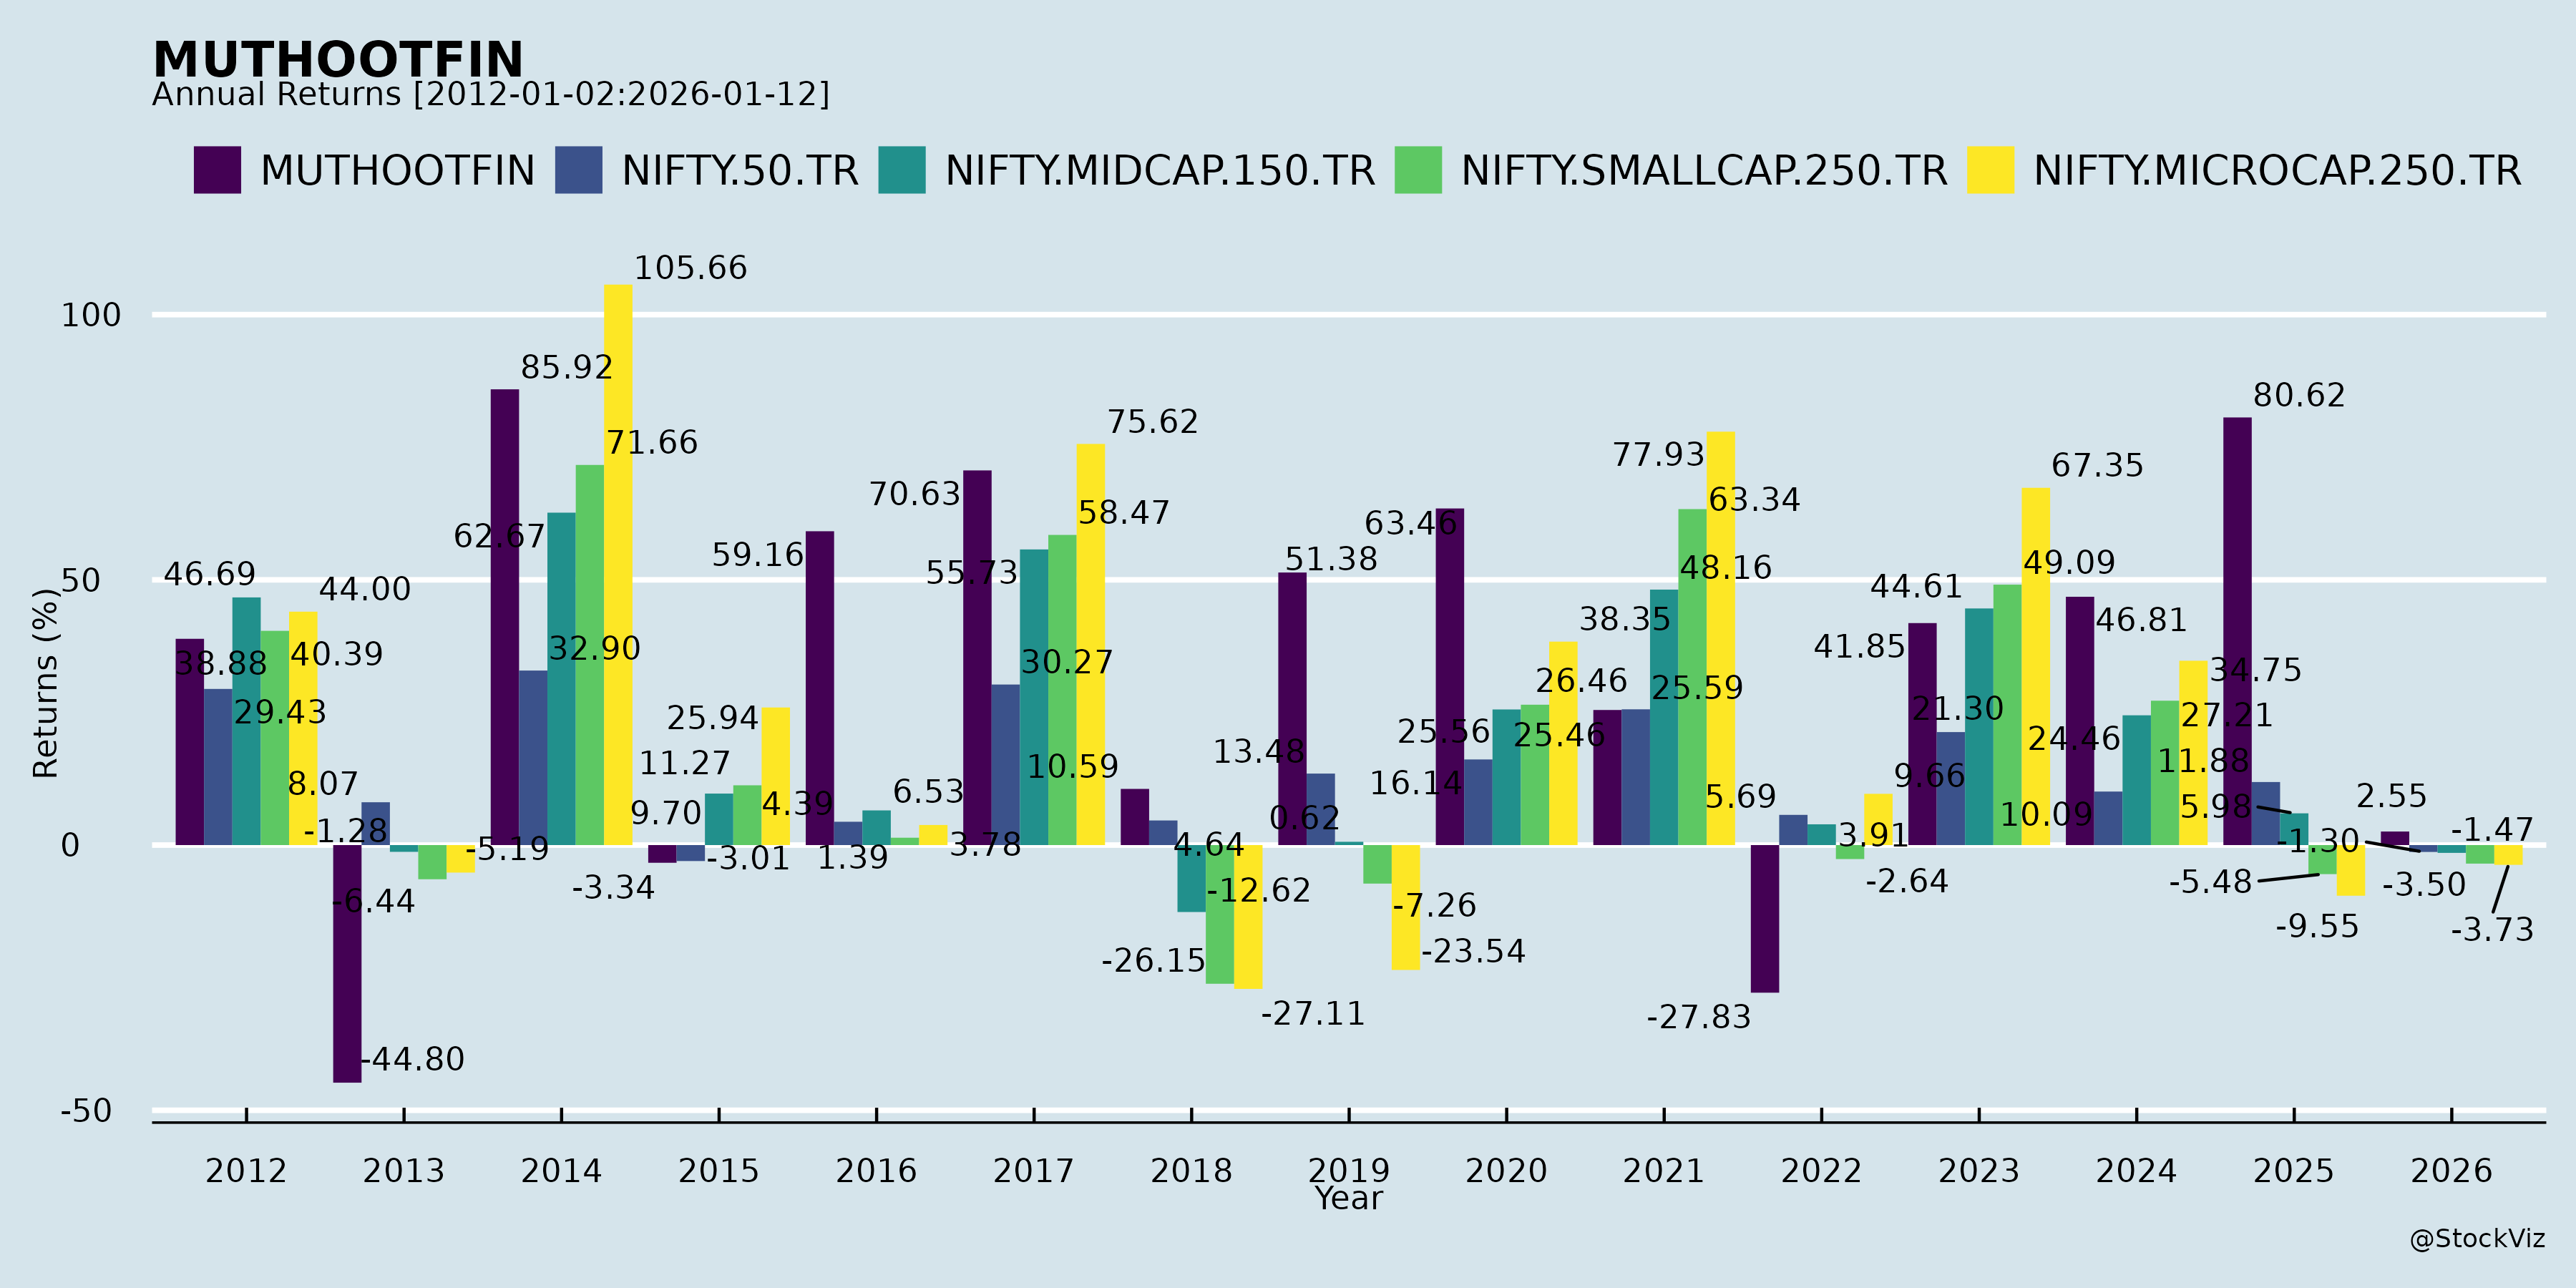
Annual Returns
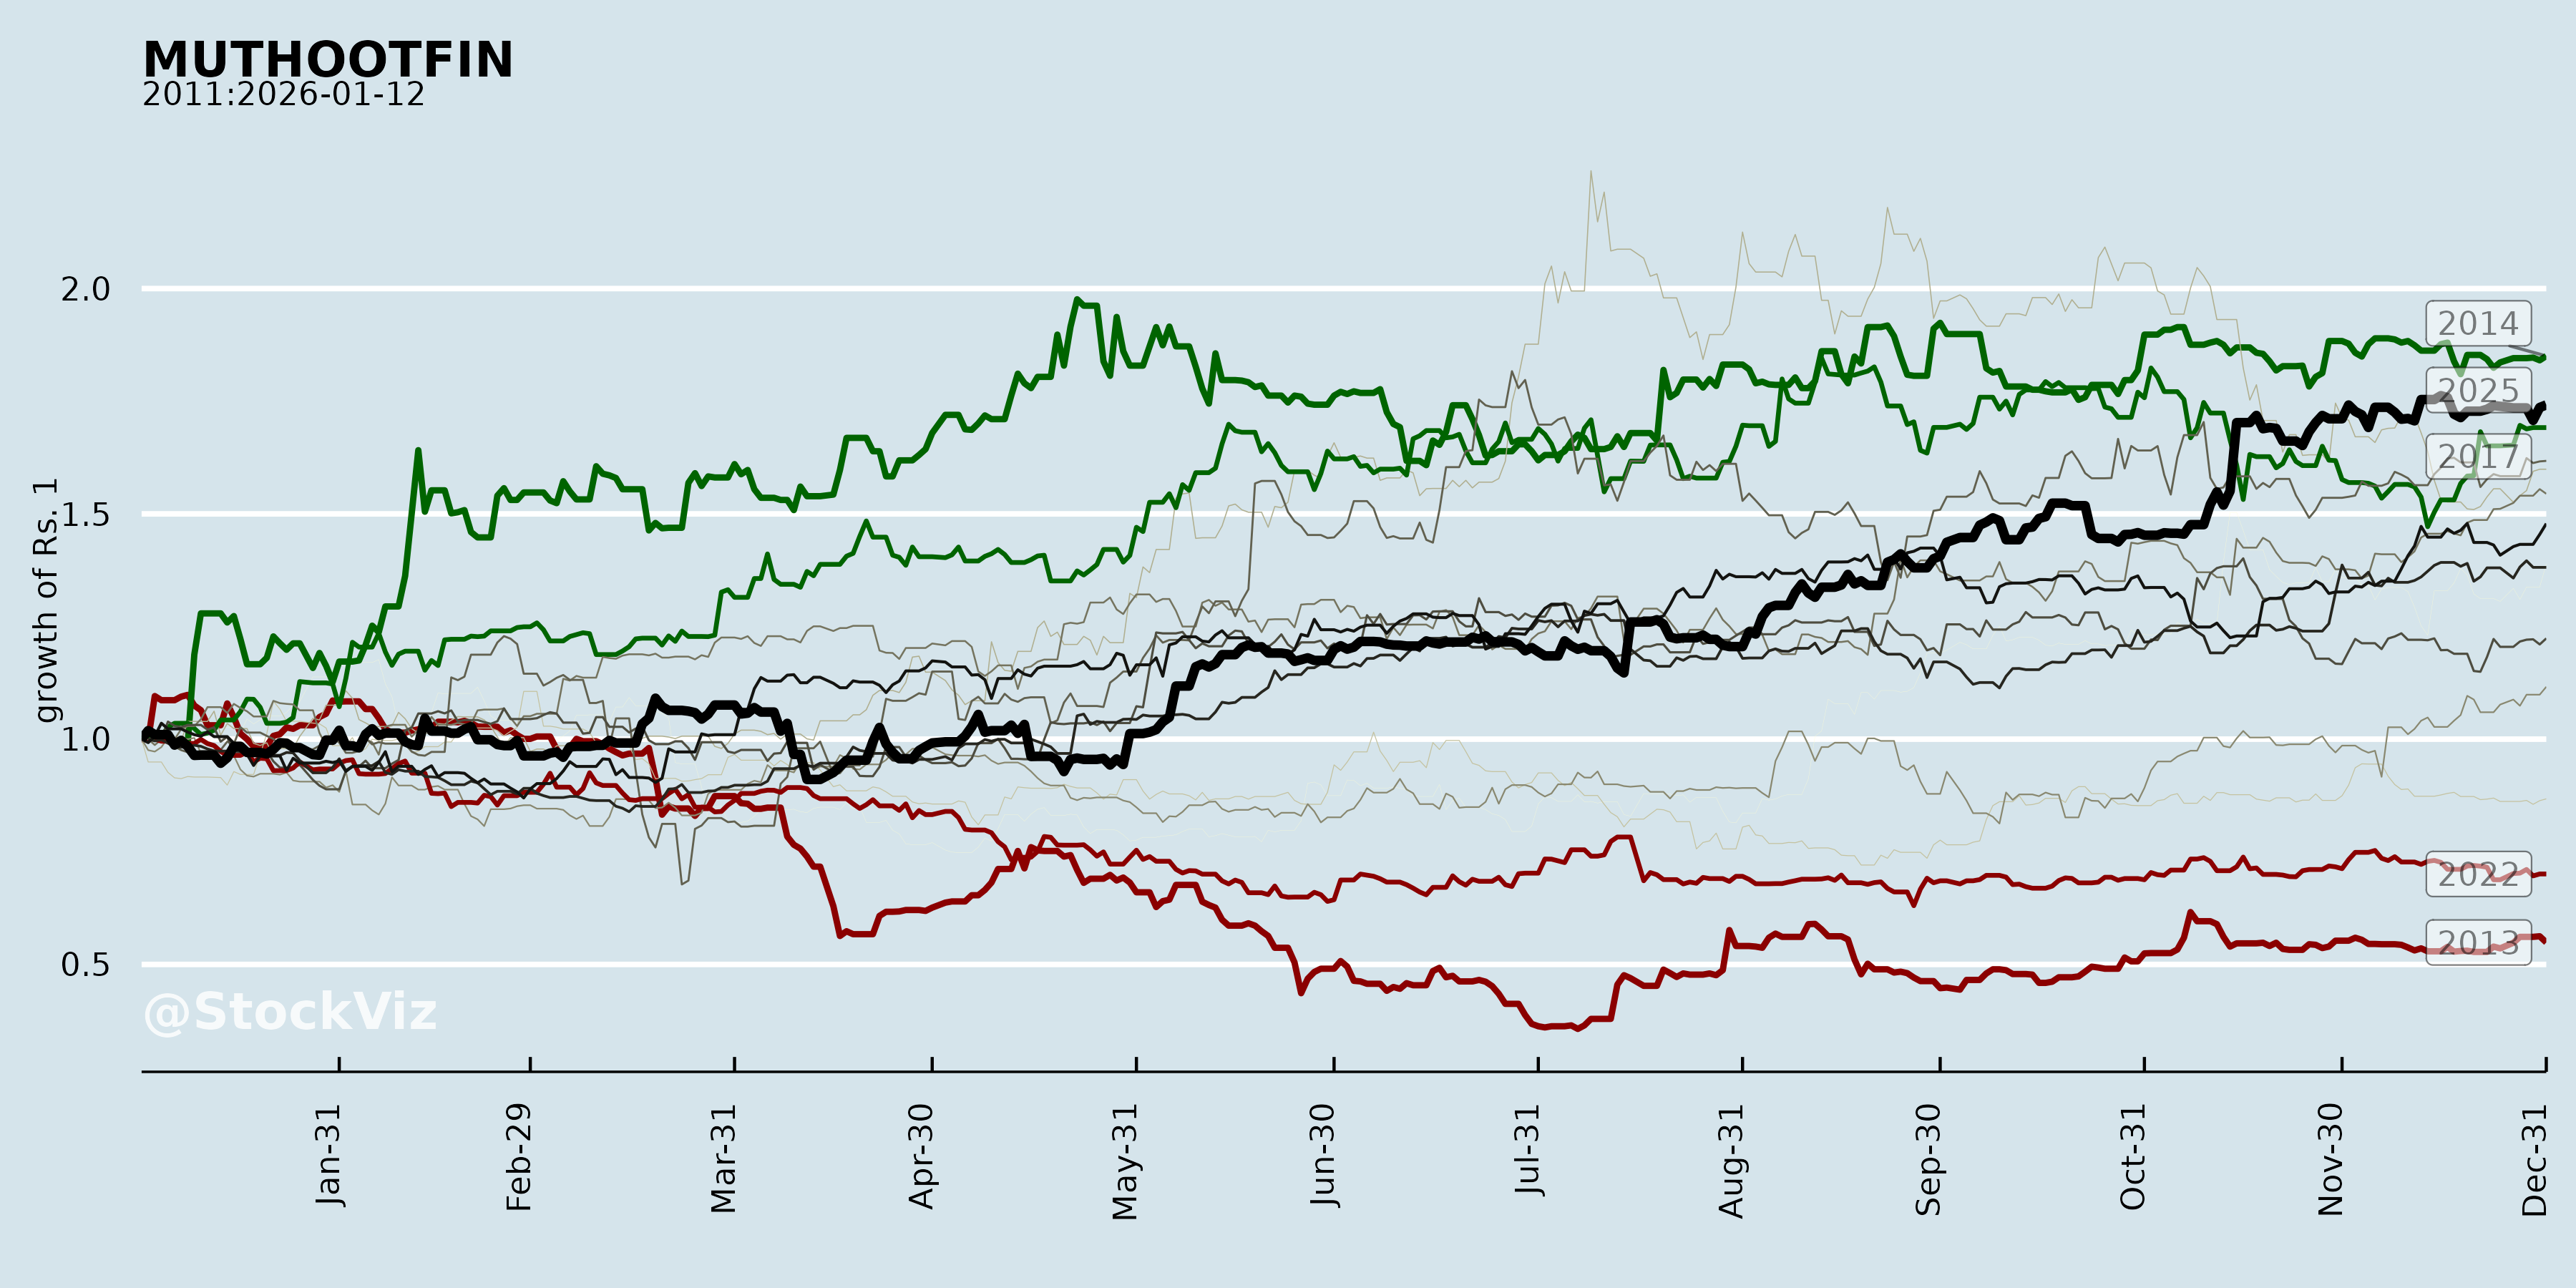
Cumulative Returns and Drawdowns


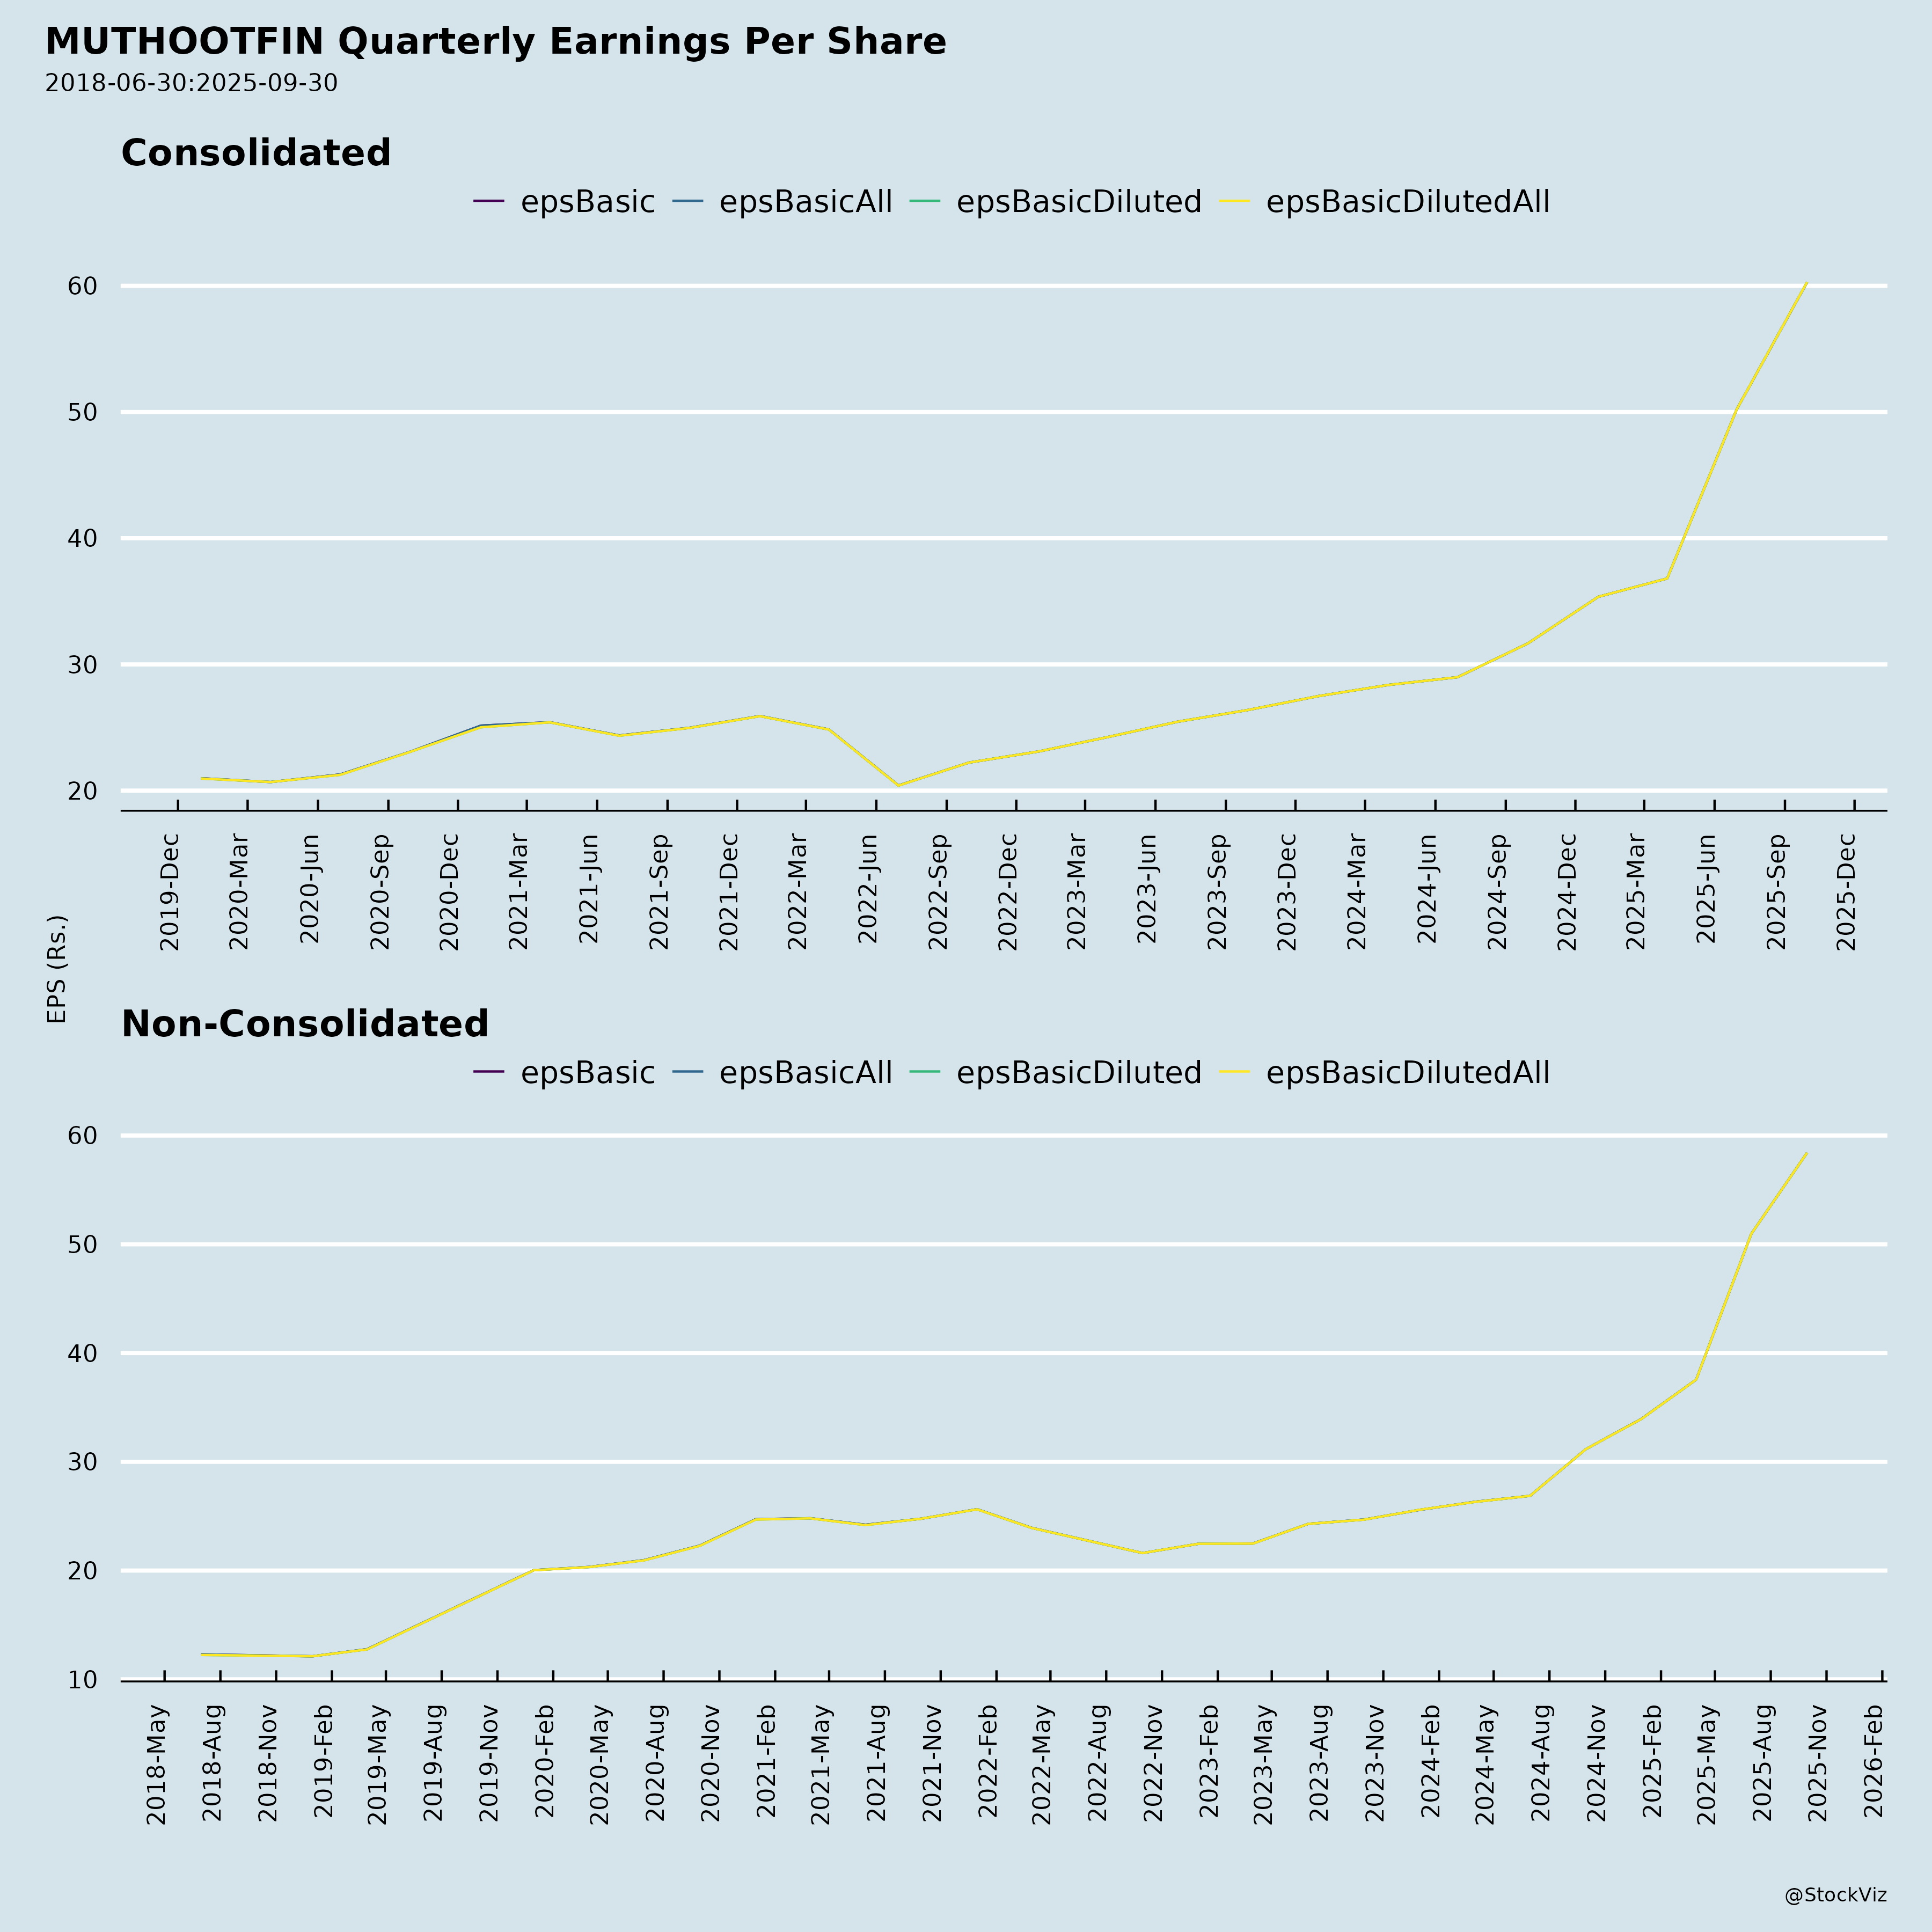
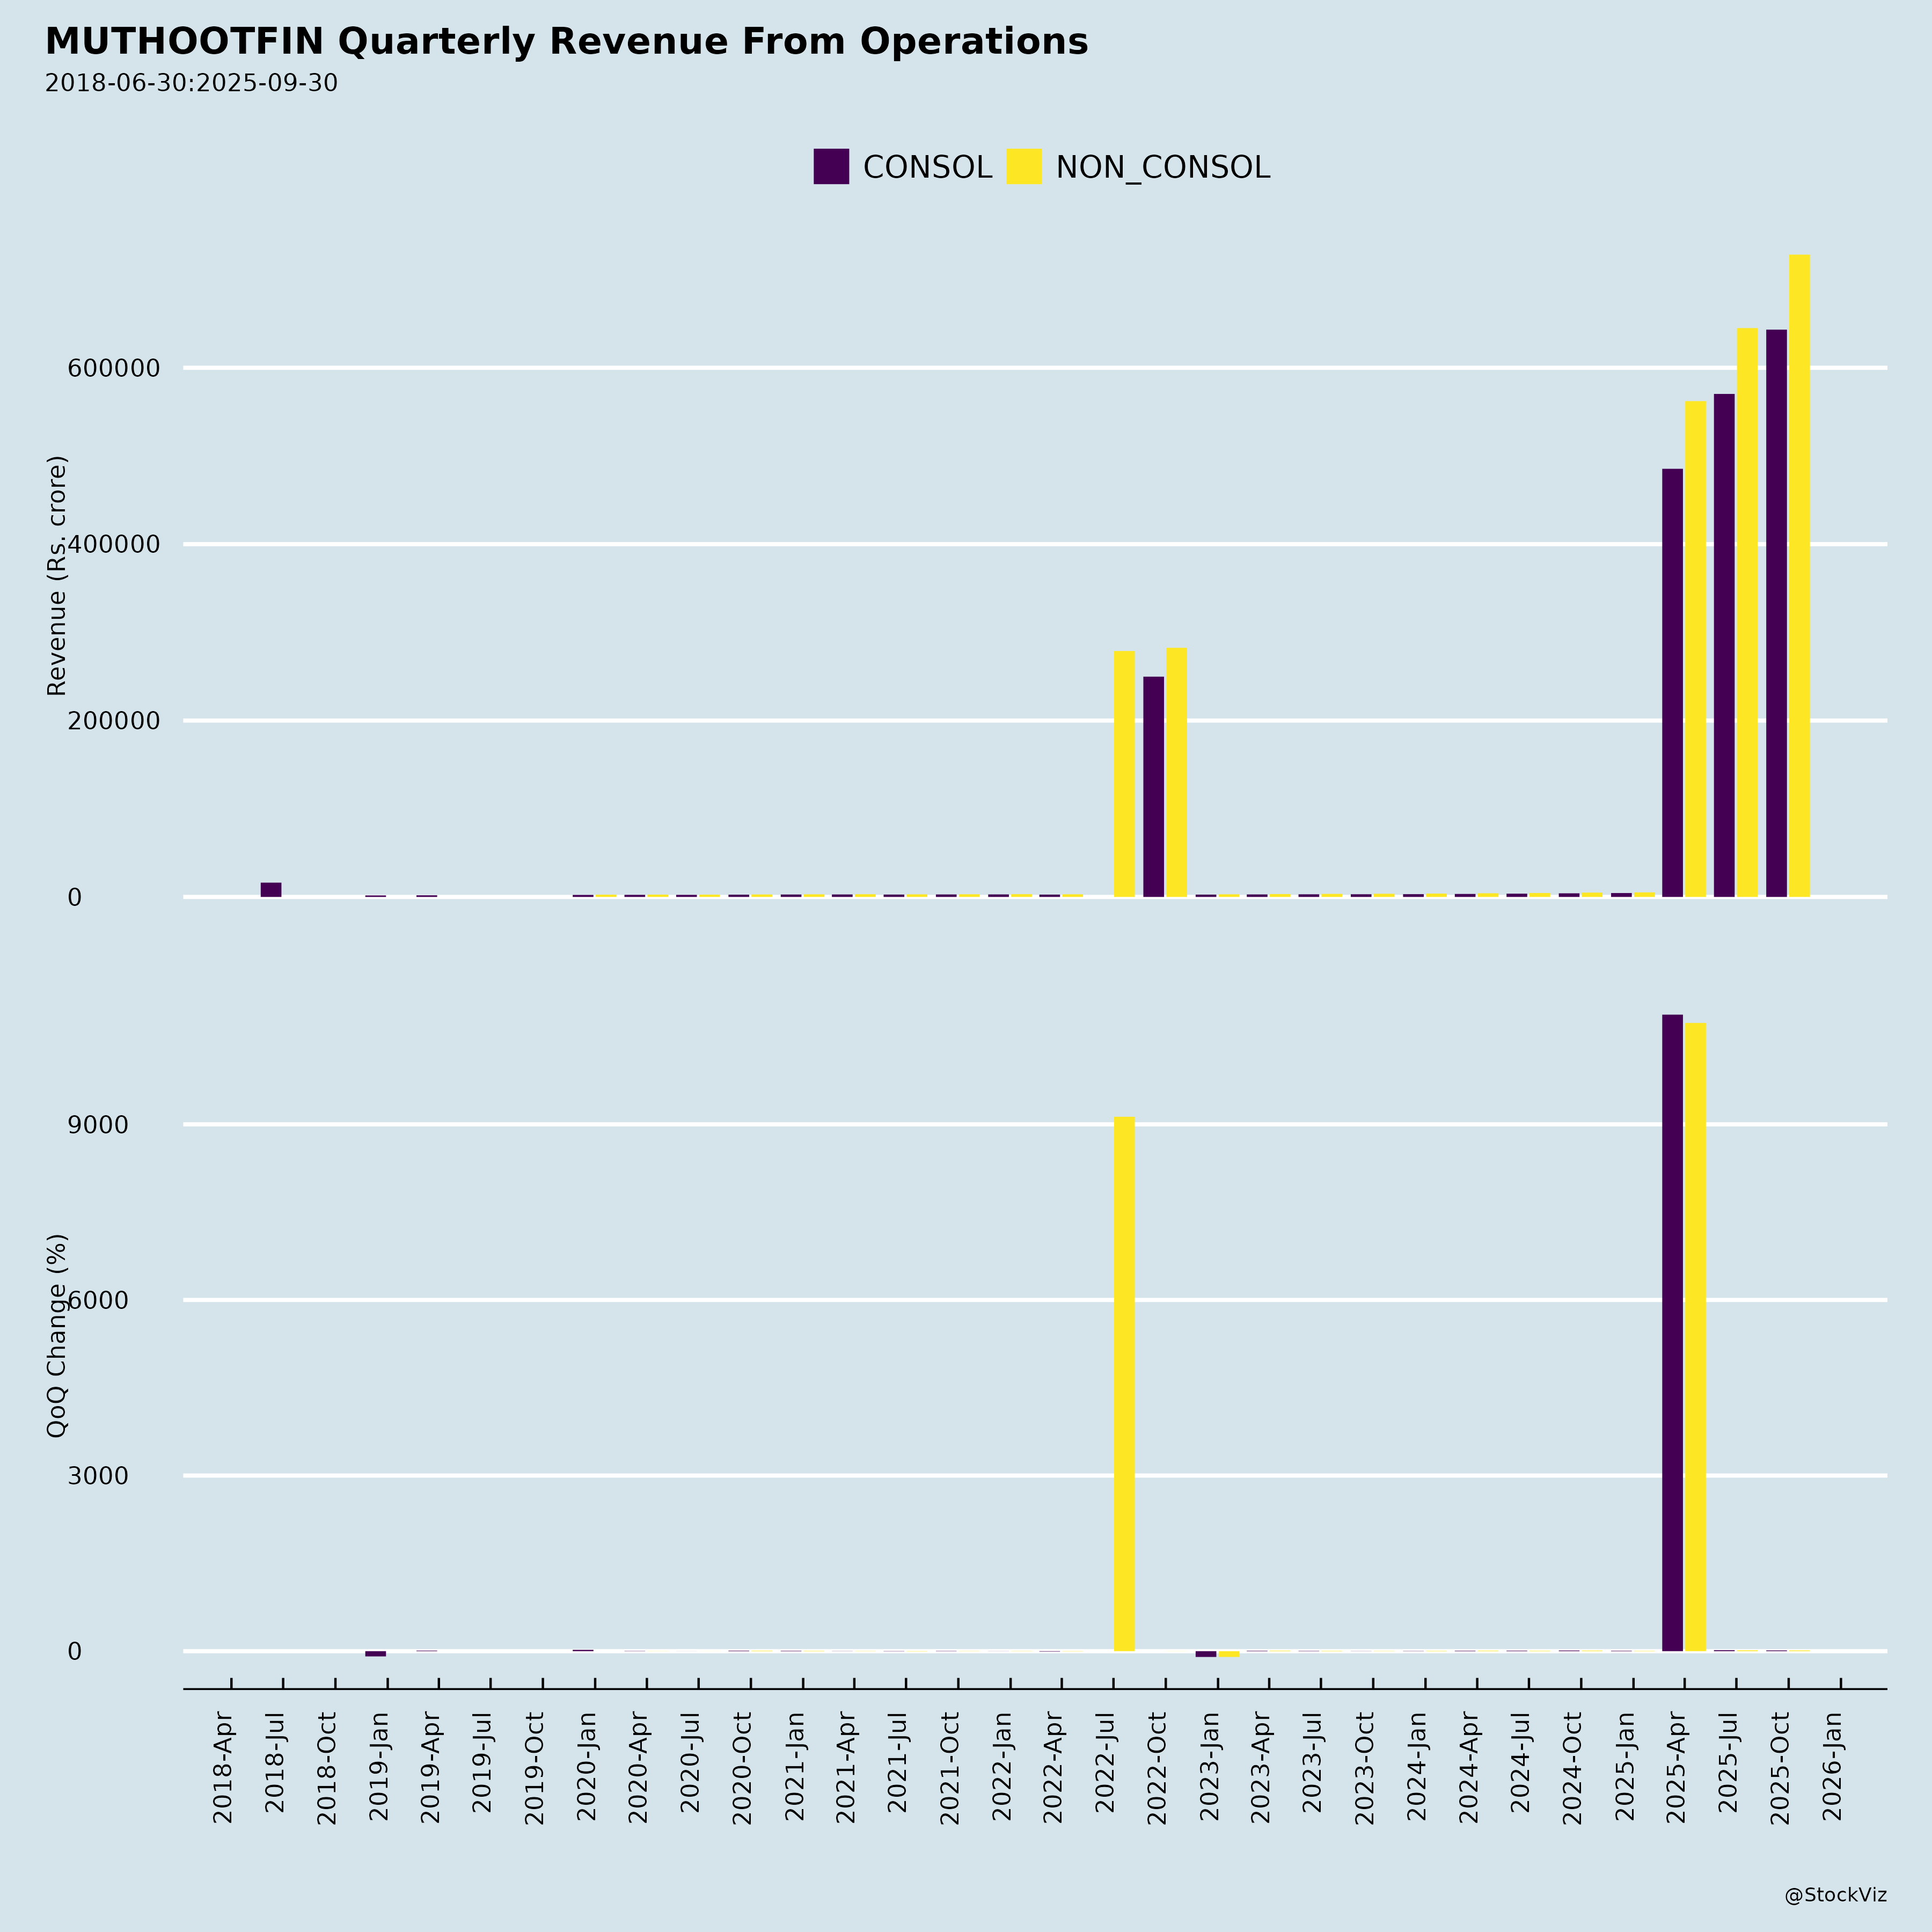
Fundamentals
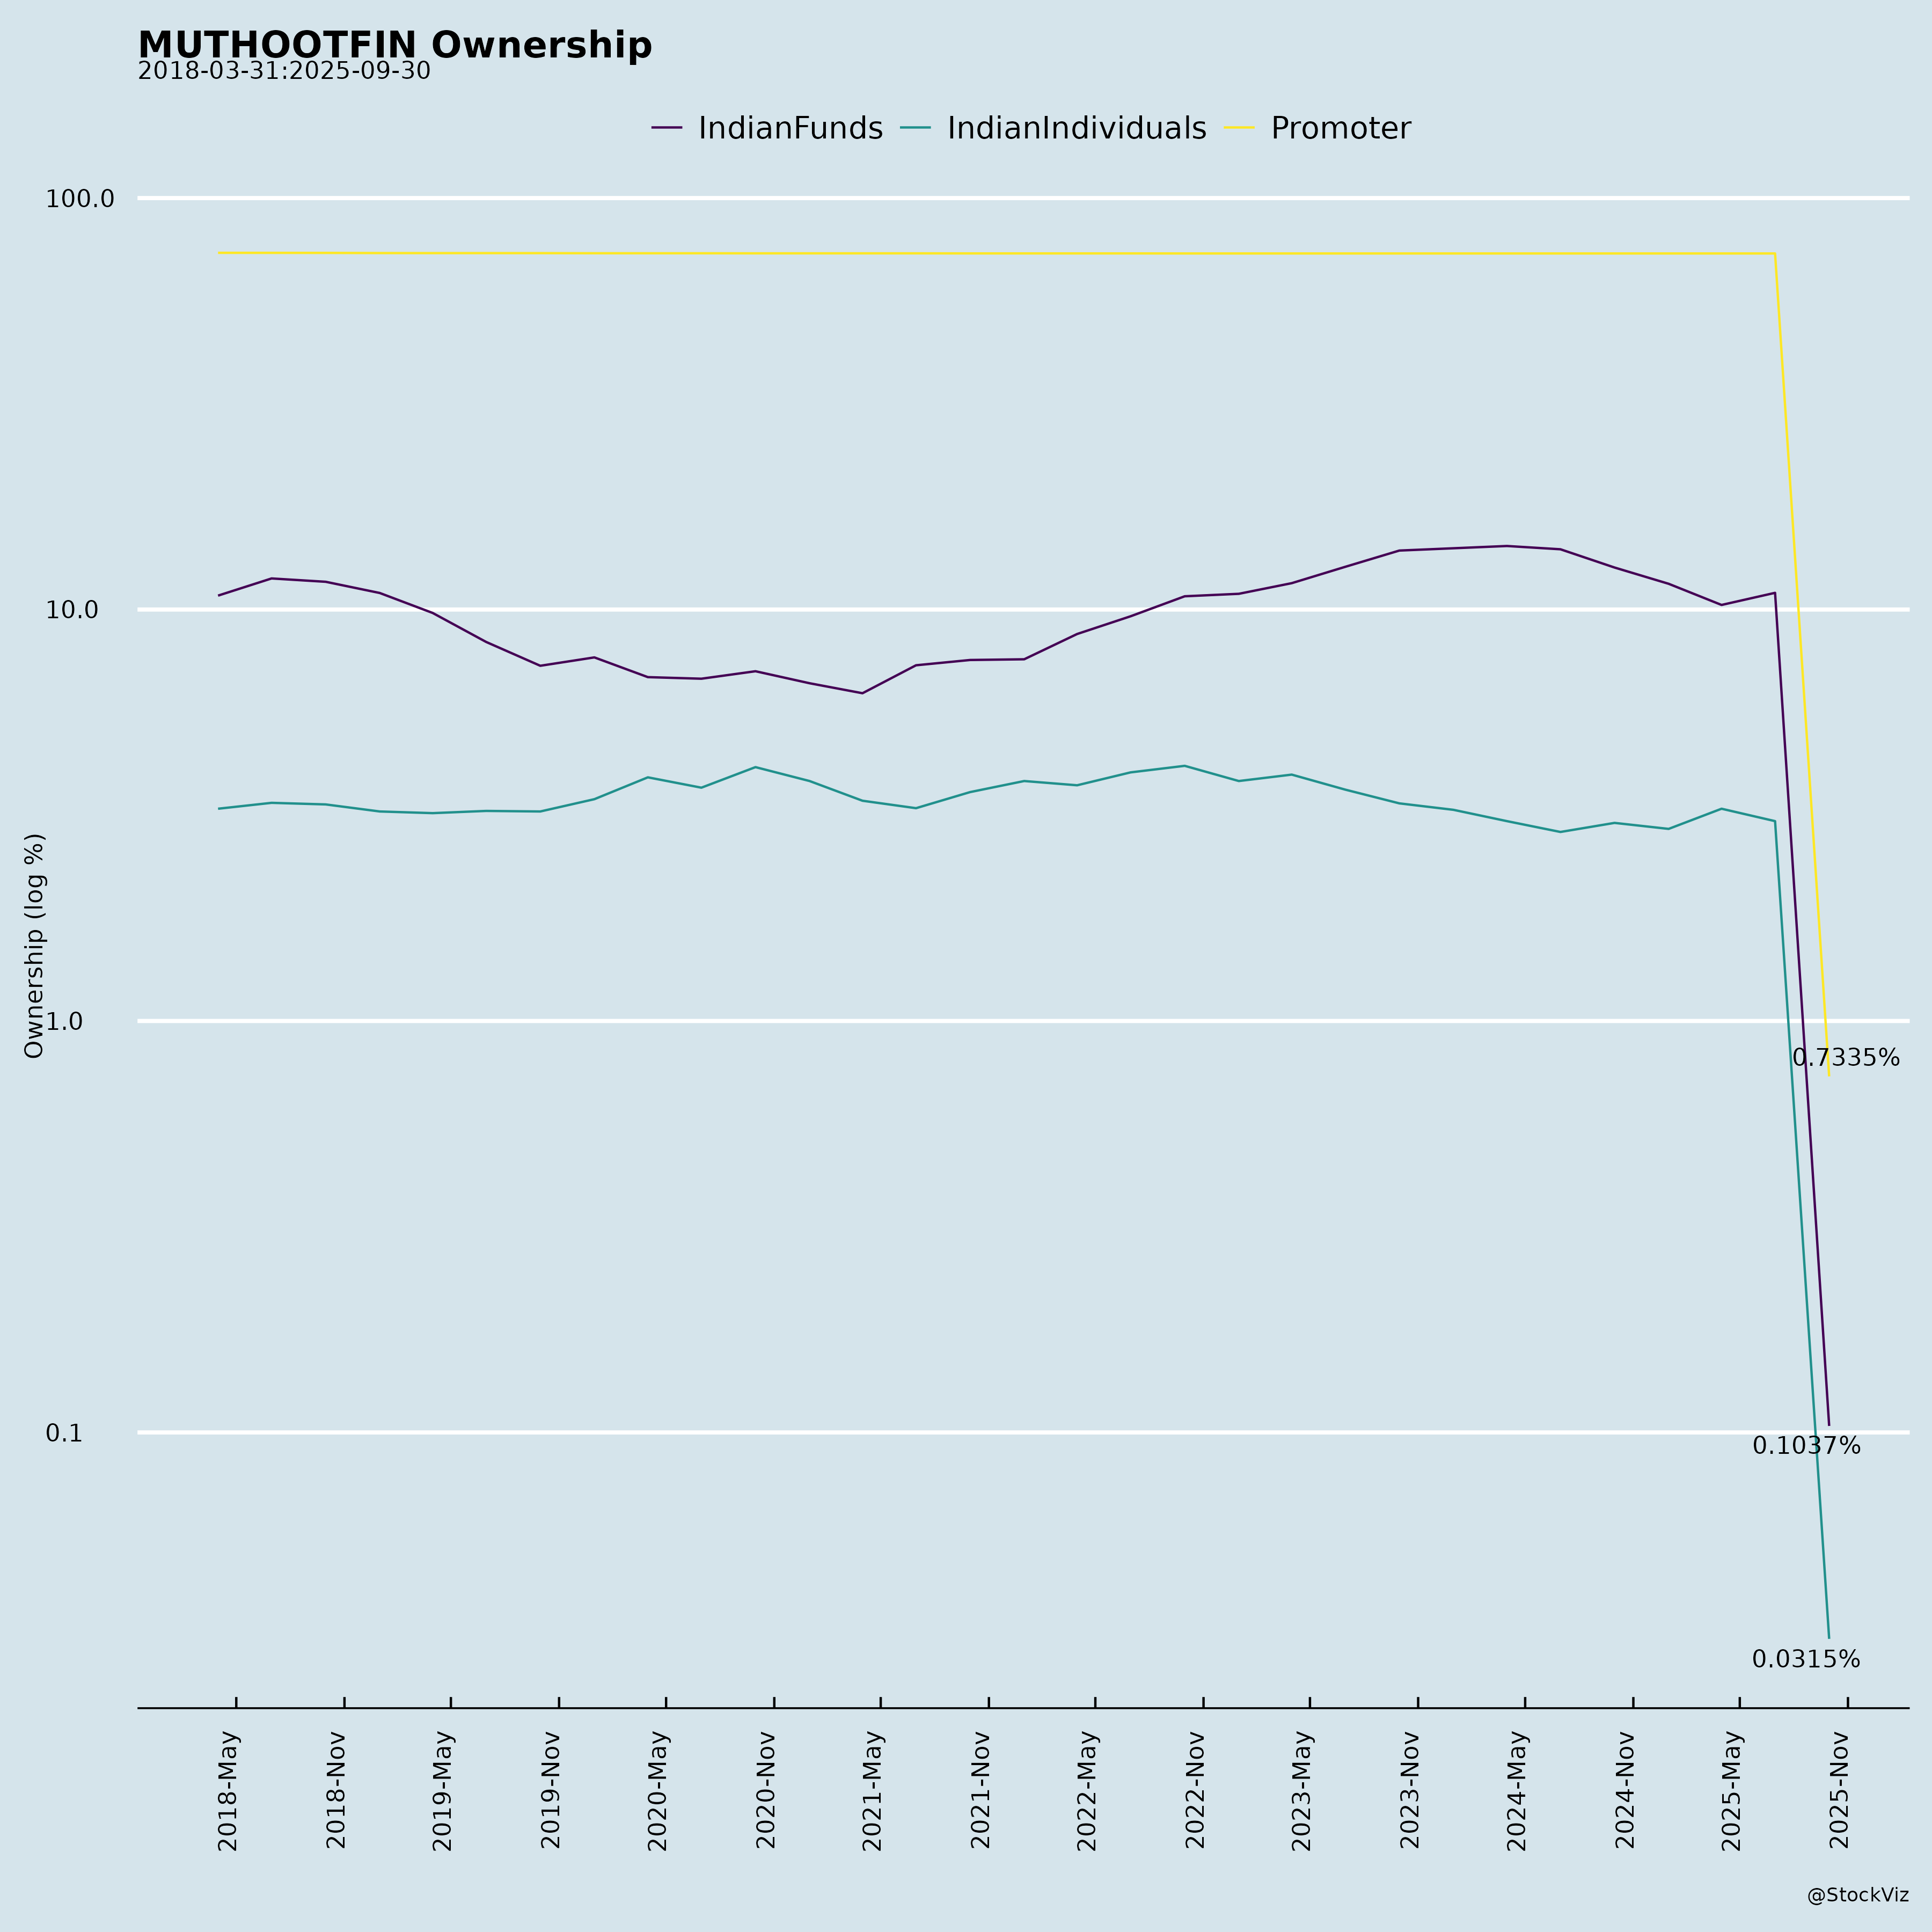
Ownership
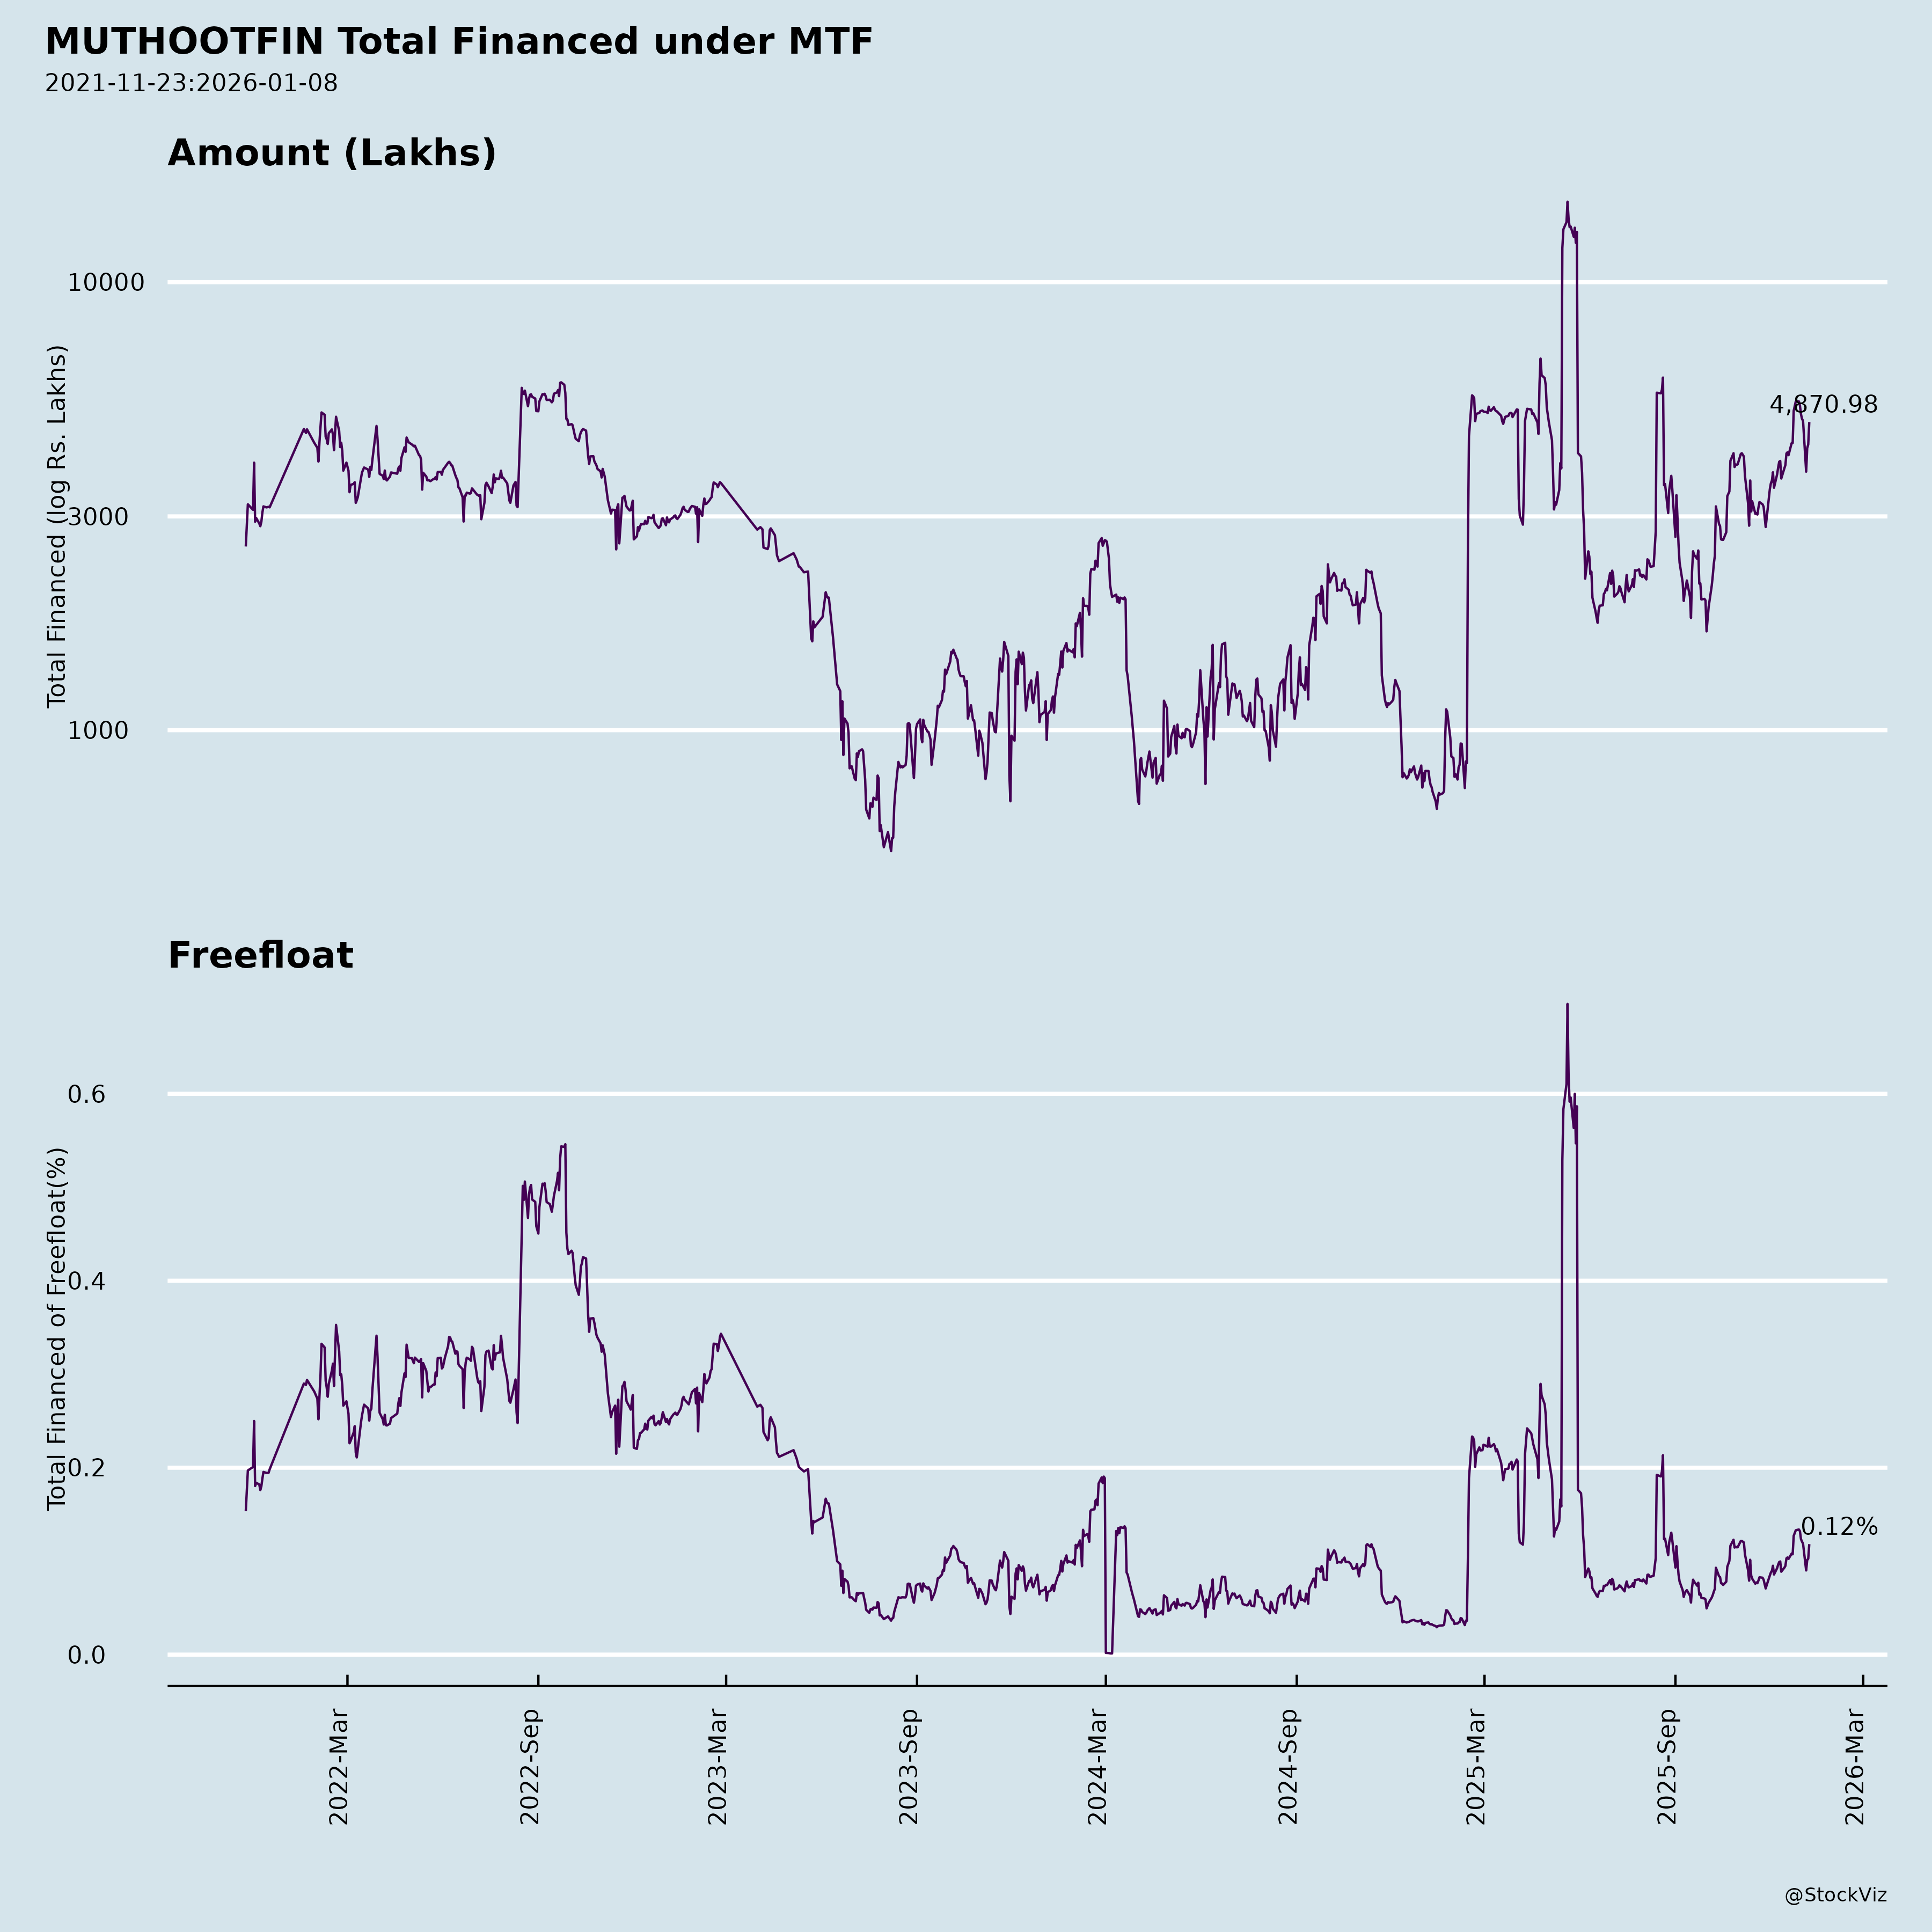
Margined
AI Summary
asof: 2026-09-14
Muthoot Finance: Recent Corporate Developments
Headwinds and Challenges
The company operates in a financial sector exposed to market cycles and macroeconomic volatility. Industry-wide stress has been moderating disbursement growth in microfinance, which affects Belstar Microfinance Limited, the group’s NBFC-MFI subsidiary. Belstar’s gross loan AUM grew only 2% year-on-year to ₹78,422 Mn in Q1 FY 2027, and its Stage III assets stood at 2.85% of gross loan assets, though this improved from 5.54% in Q4 FY 2026 and 4.44% in Q1 FY 2026.
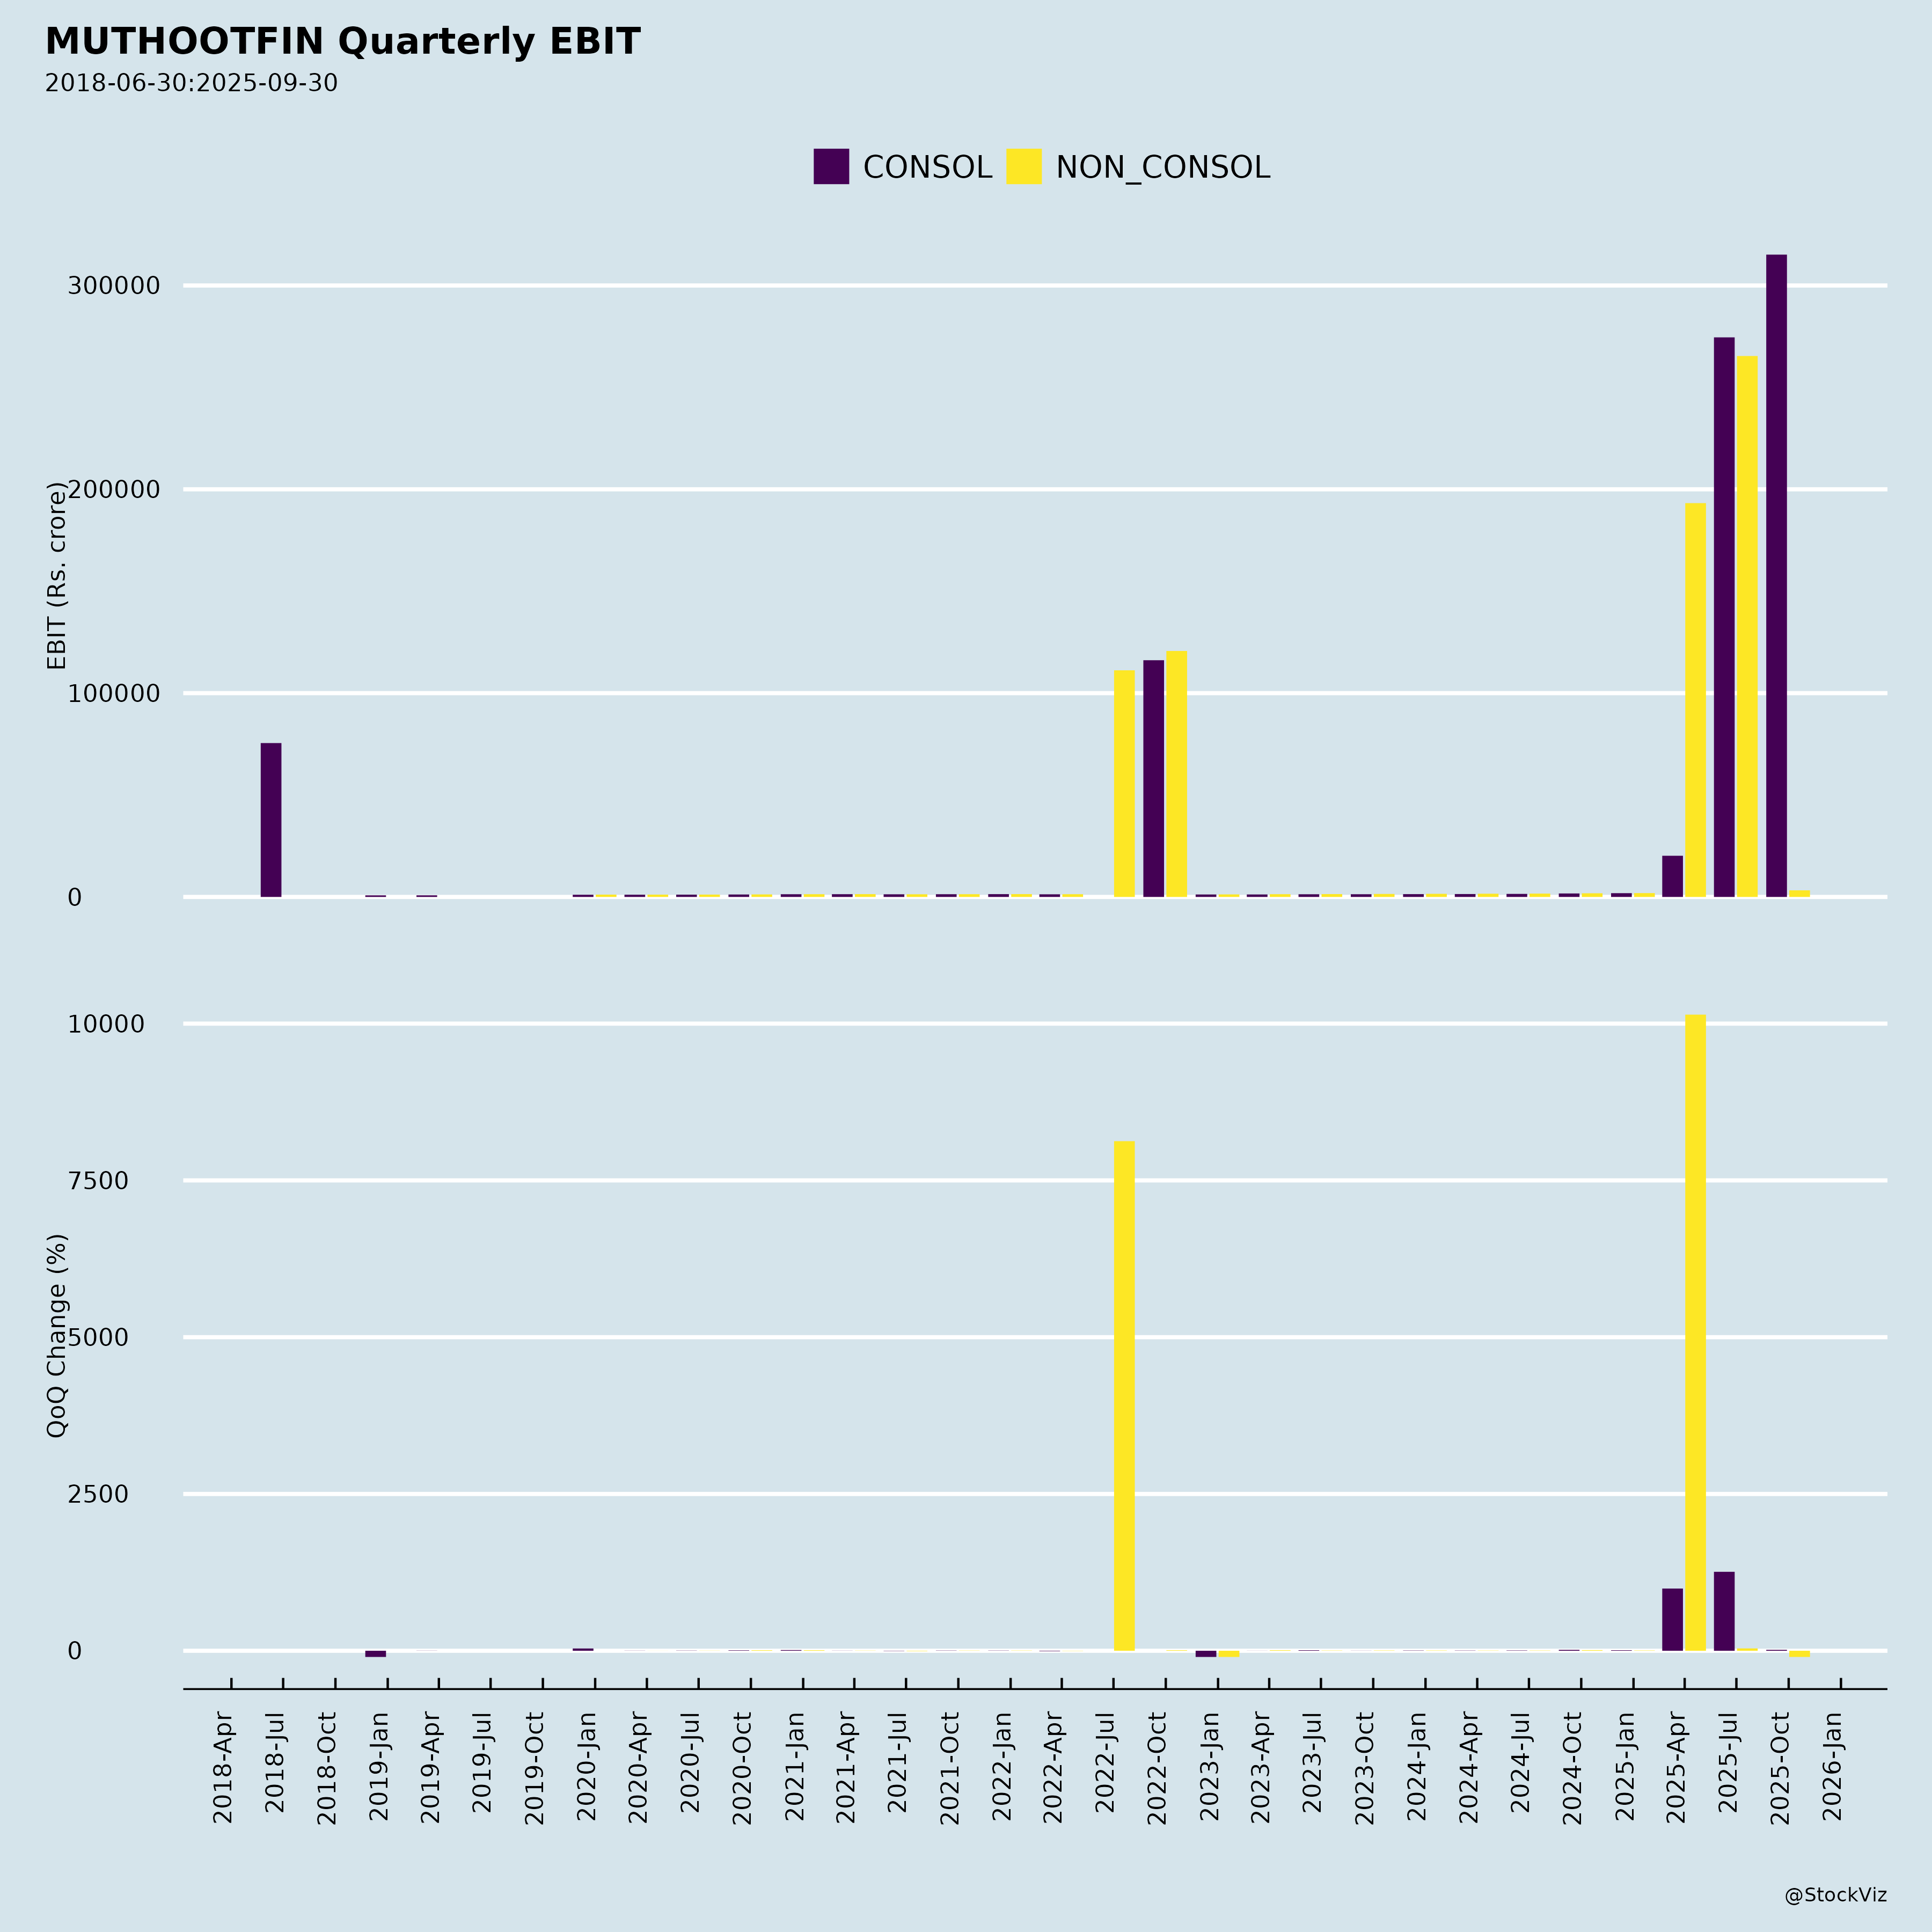
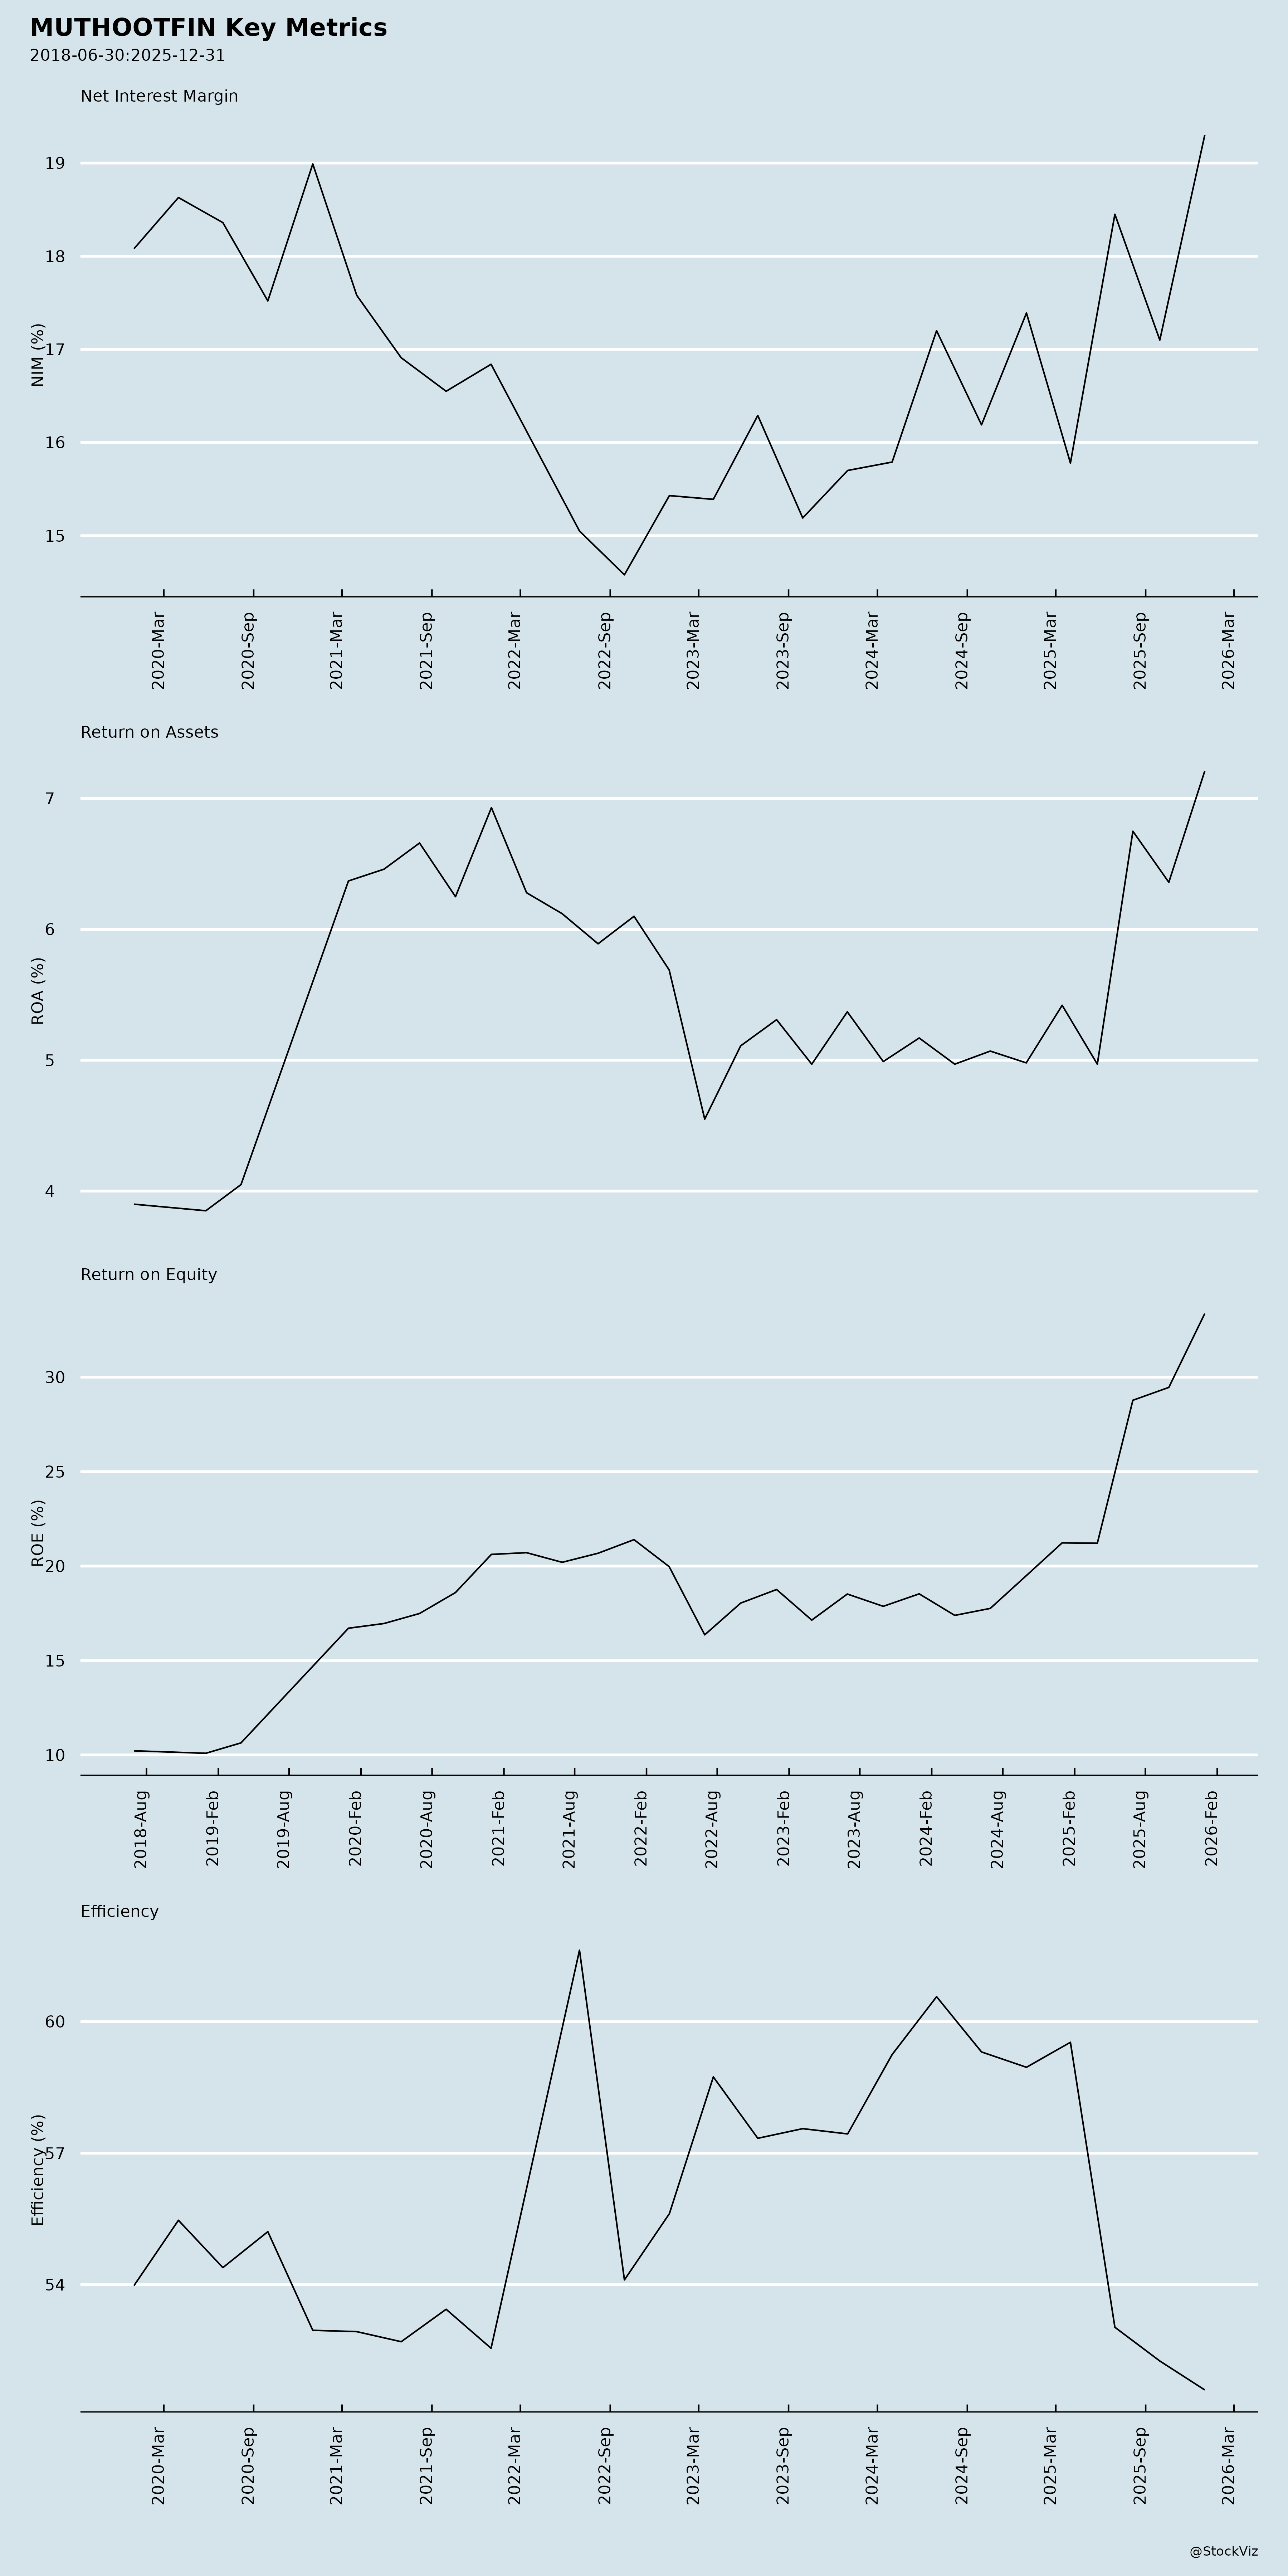
At the standalone level, finance costs rose 48% year-on-year in Q1 FY 2027 to ₹31,459 Mn, and 47% at the consolidated level to ₹34,584 Mn, reflecting the cost of funding a rapidly expanding loan book. Standalone net interest margin declined to 10.41% in Q1 FY 2027 from 12.15% in Q1 FY 2026 and 13.38% in Q4 FY 2026. Consolidated interest income to average loan assets fell to 17.93% in Q1 FY 2027 from 19.56% a year earlier.
The company also flagged the need for shareholders and debenture holders to update KYC and register email addresses, as part of ongoing compliance and communication efforts.
Tailwinds and Growth Prospects
The organised gold loan market is projected to reach ₹16 lakh crore in FY 2026, growing 33–36% year-on-year from ₹12 lakh crore in FY 2025. Of the 34,600 tonnes of household gold in India, only 2,950–3,350 tonnes is currently used as collateral, indicating significant untapped potential. Borrowers are shifting from local moneylenders to organised lenders for safer custody, transparent valuation, and fairer rates. Micro-enterprises are increasingly using gold loans intentionally to fund inventory, expansion, and working capital rather than pledging in distress. Demand is expanding beyond the South into the North, East, and West.
Muthoot Finance is positioned as India’s largest gold loan NBFC with a 47% gold loan market share among NBFCs, recognised by the RBI as an Upper Layer NBFC. The group operates 7,654 branches across 29 states and union territories, serving over 2,00,000 retail customers daily. Consolidated Loan AUM reached ₹1,91,532 crore in Q1 FY 2027, up 43% year-on-year, while consolidated PAT reached ₹2,825 crore, also up 43%. Standalone Loan AUM stood at ₹1,72,053 crore with standalone PAT of ₹2,550 crore, up 25% year-on-year. The company reported 6.58 Mn active customers and 27 Mn iMuthoot app downloads with 6.3 Mn registered users. Digital channels now originate 100% of unsecured cross-sell business, and 26% of gold loan interest repayments flow through the app.
The board recommended the merger of Muthoot Money into Muthoot Finance with an appointed date of April 1, 2027. Muthoot Money’s loan AUM grew 111% year-on-year to ₹105,503 Mn in Q1 FY 2027, with PAT up 366% to ₹1,721 Mn.
Key Risks
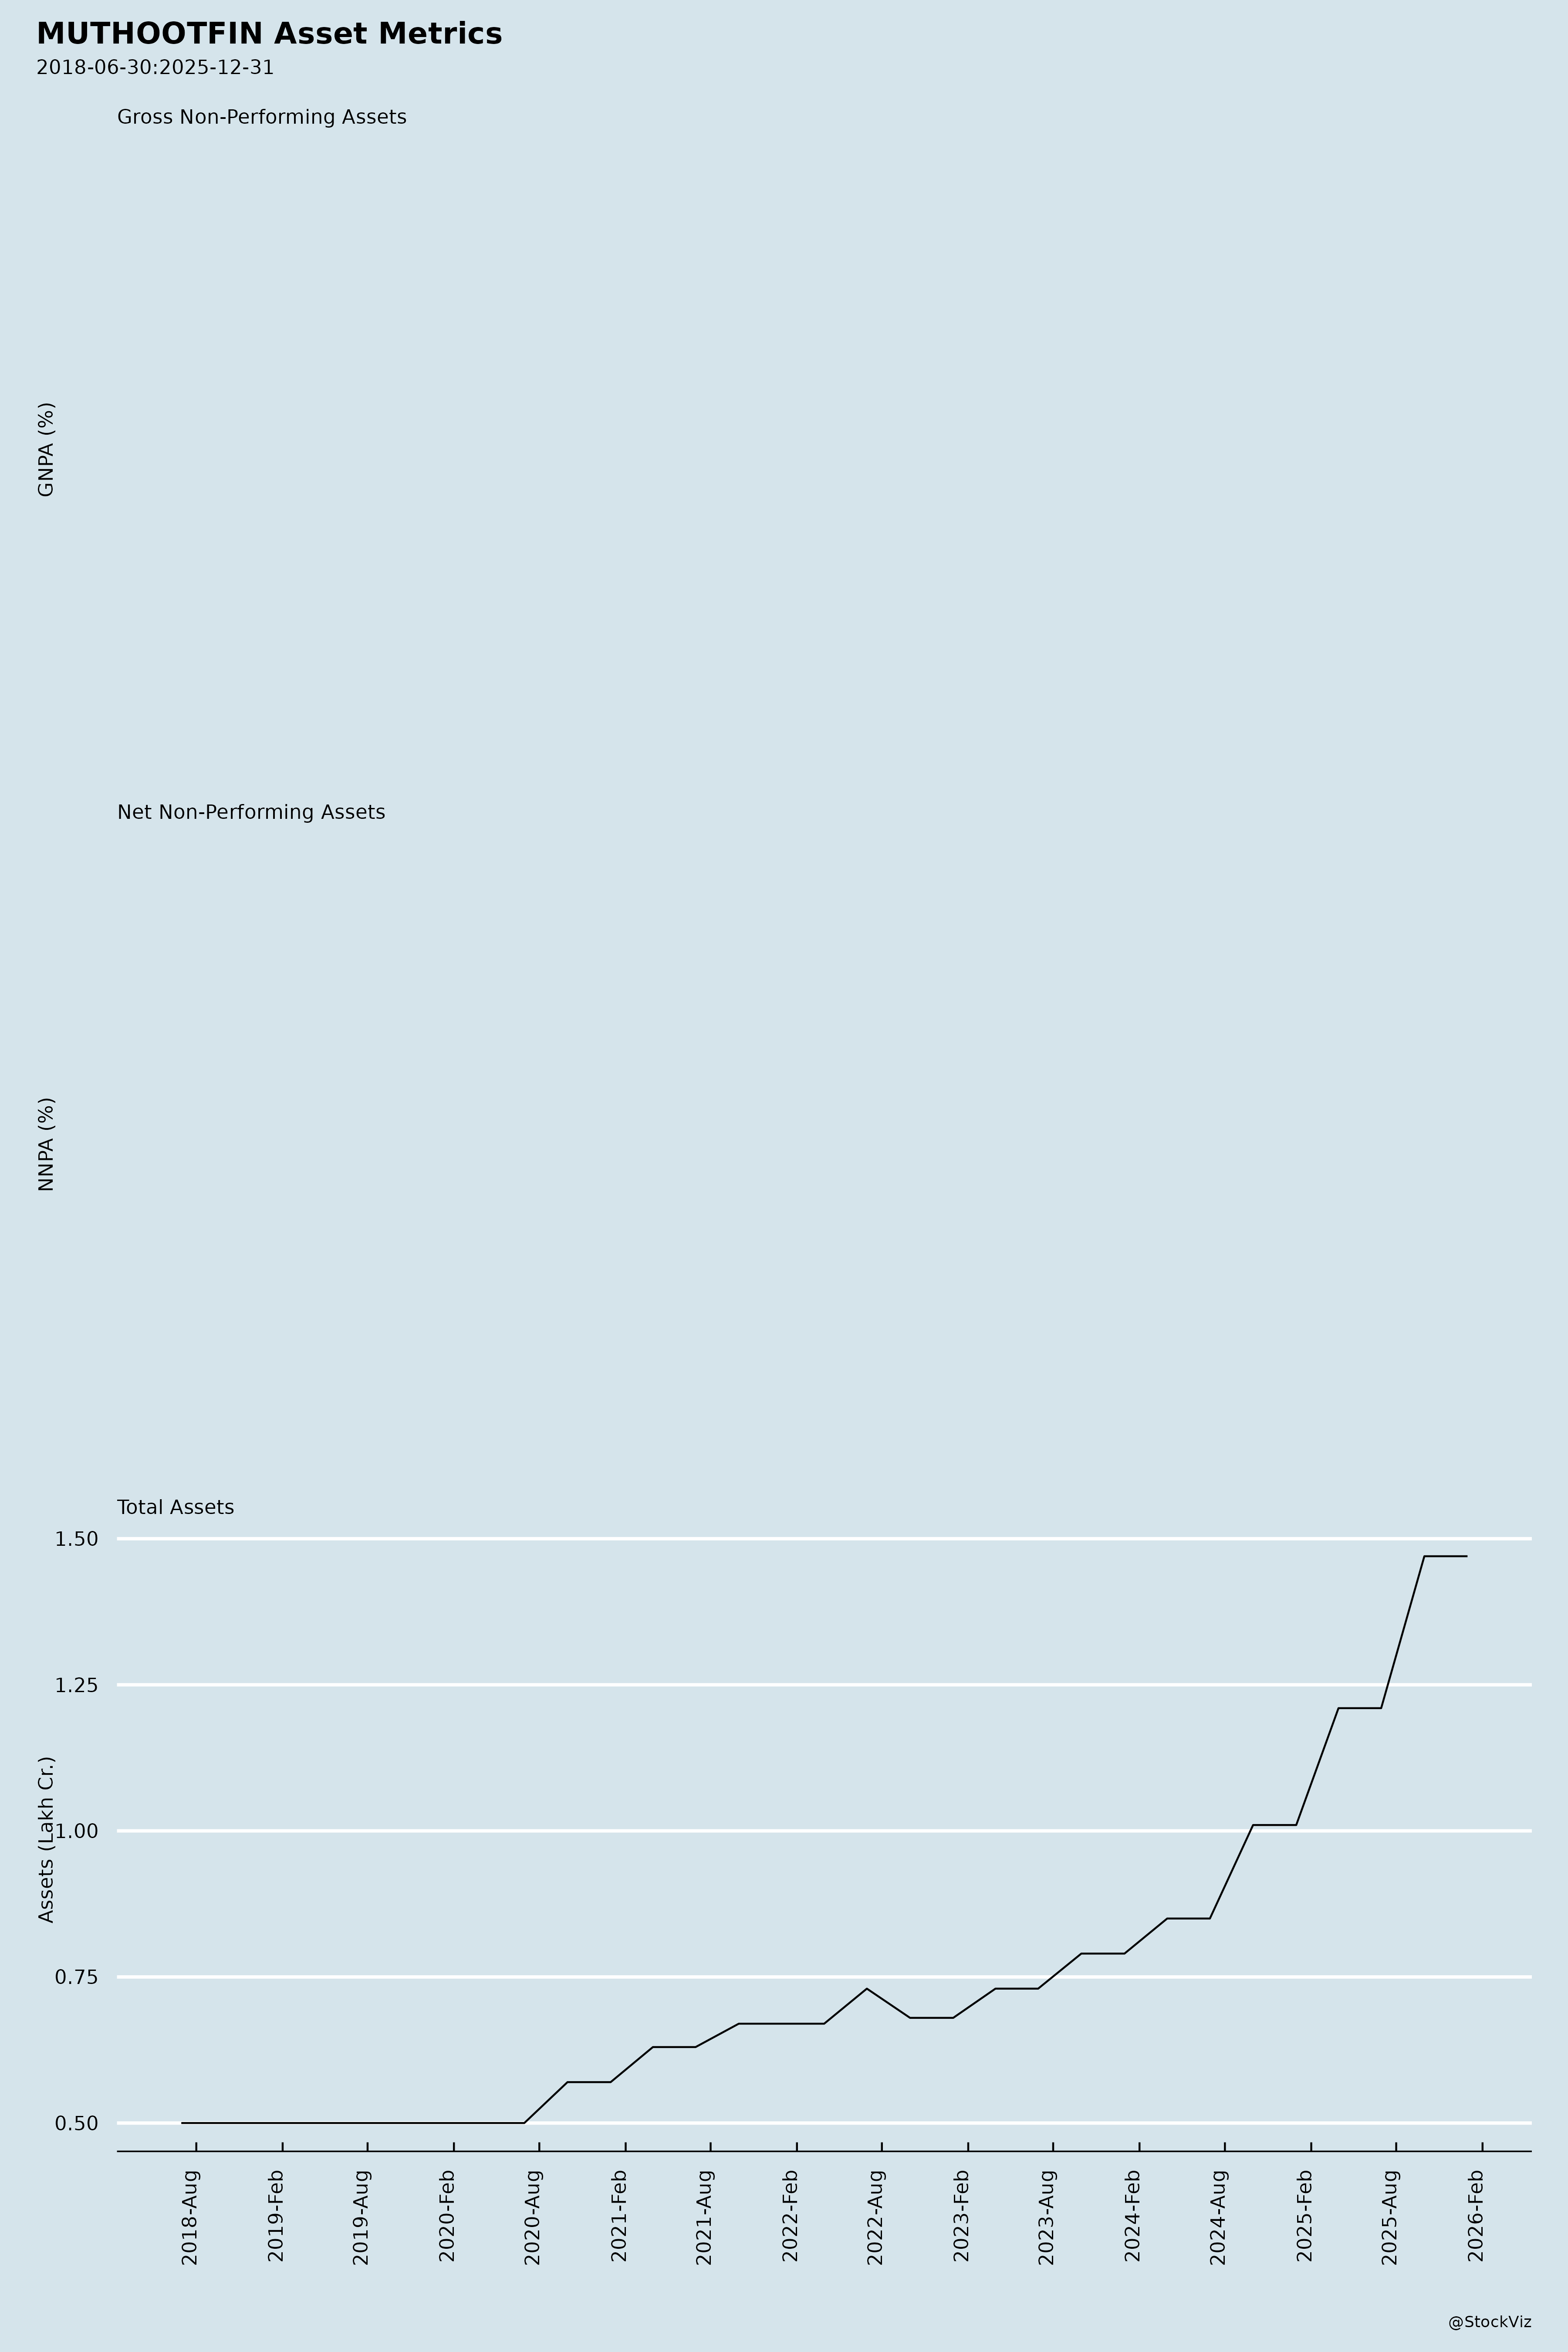
Credit quality remains a watch item. Standalone Stage III assets were 2.28% of loan assets in Q1 FY 2027, down from 2.58% a year earlier, with ECL provision at 1.03% of loan assets. Bad debts written off rose to ₹861 Mn in Q1 FY 2027 from ₹406 Mn in Q1 FY 2026, though as a percentage of loan assets this remained at 0.05%. Belstar’s Stage III ratio, while improving, remains elevated at 2.85%. Muthoot Homefin’s Stage III ratio rose to 2.52% in Q1 FY 2027 from 1.60% a year earlier.
Concentration risk is inherent in the business model, with 92% of the loan book secured by gold. Gold price movements affect collateral coverage; gold price per gram declined to ₹12,942 in June 2026 from ₹13,441 in March 2026, though it was up sharply from ₹8,783 in June 2025. The quantity of gold held as security declined to 197 tonnes from 209 tonnes a year earlier.
Funding profile shows increased reliance on debt securities, which rose to ₹518,458 Mn in June 2026 from ₹318,706 Mn a year earlier, alongside borrowings from banks and financial institutions of ₹1,099,054 Mn. Capital gearing stood at 3.59x. The company maintains domestic long-term ratings of AA+ (CRISIL, ICRA) and international ratings of Ba1 (Moody’s), BB+ (Fitch), and BB+ (S&P).
Management Guidance Versus Observed Performance
Management stated confidence in sustaining growth momentum, creating long-term stakeholder value, and leveraging the branch network, domain expertise, and digital investments to capture structural growth potential in the gold loan industry. This is supported by observed performance: consolidated Loan AUM grew 43% year-on-year in Q1 FY 2027, consolidated PAT grew 43%, and the group added 18 lakh new customers. The company crossed ₹1.91 trillion in consolidated Loan AUM as of June 30, 2026, and reported consolidated PAT of ₹106.06 billion for FY 2025-26.
The board recommended the appointment of Mr. Alexander George as Managing Director effective October 1, 2026, subject to shareholder approval at the AGM on August 31, 2026, with the current Managing Director, Mr. George Alexander Muthoot, transitioning to Executive Vice Chairman. Mr. K. R. Bijimon was recommended for elevation to Chief Executive Officer. Management described this as the culmination of over two decades of planned leadership succession, reflecting continuity and institutional stability.
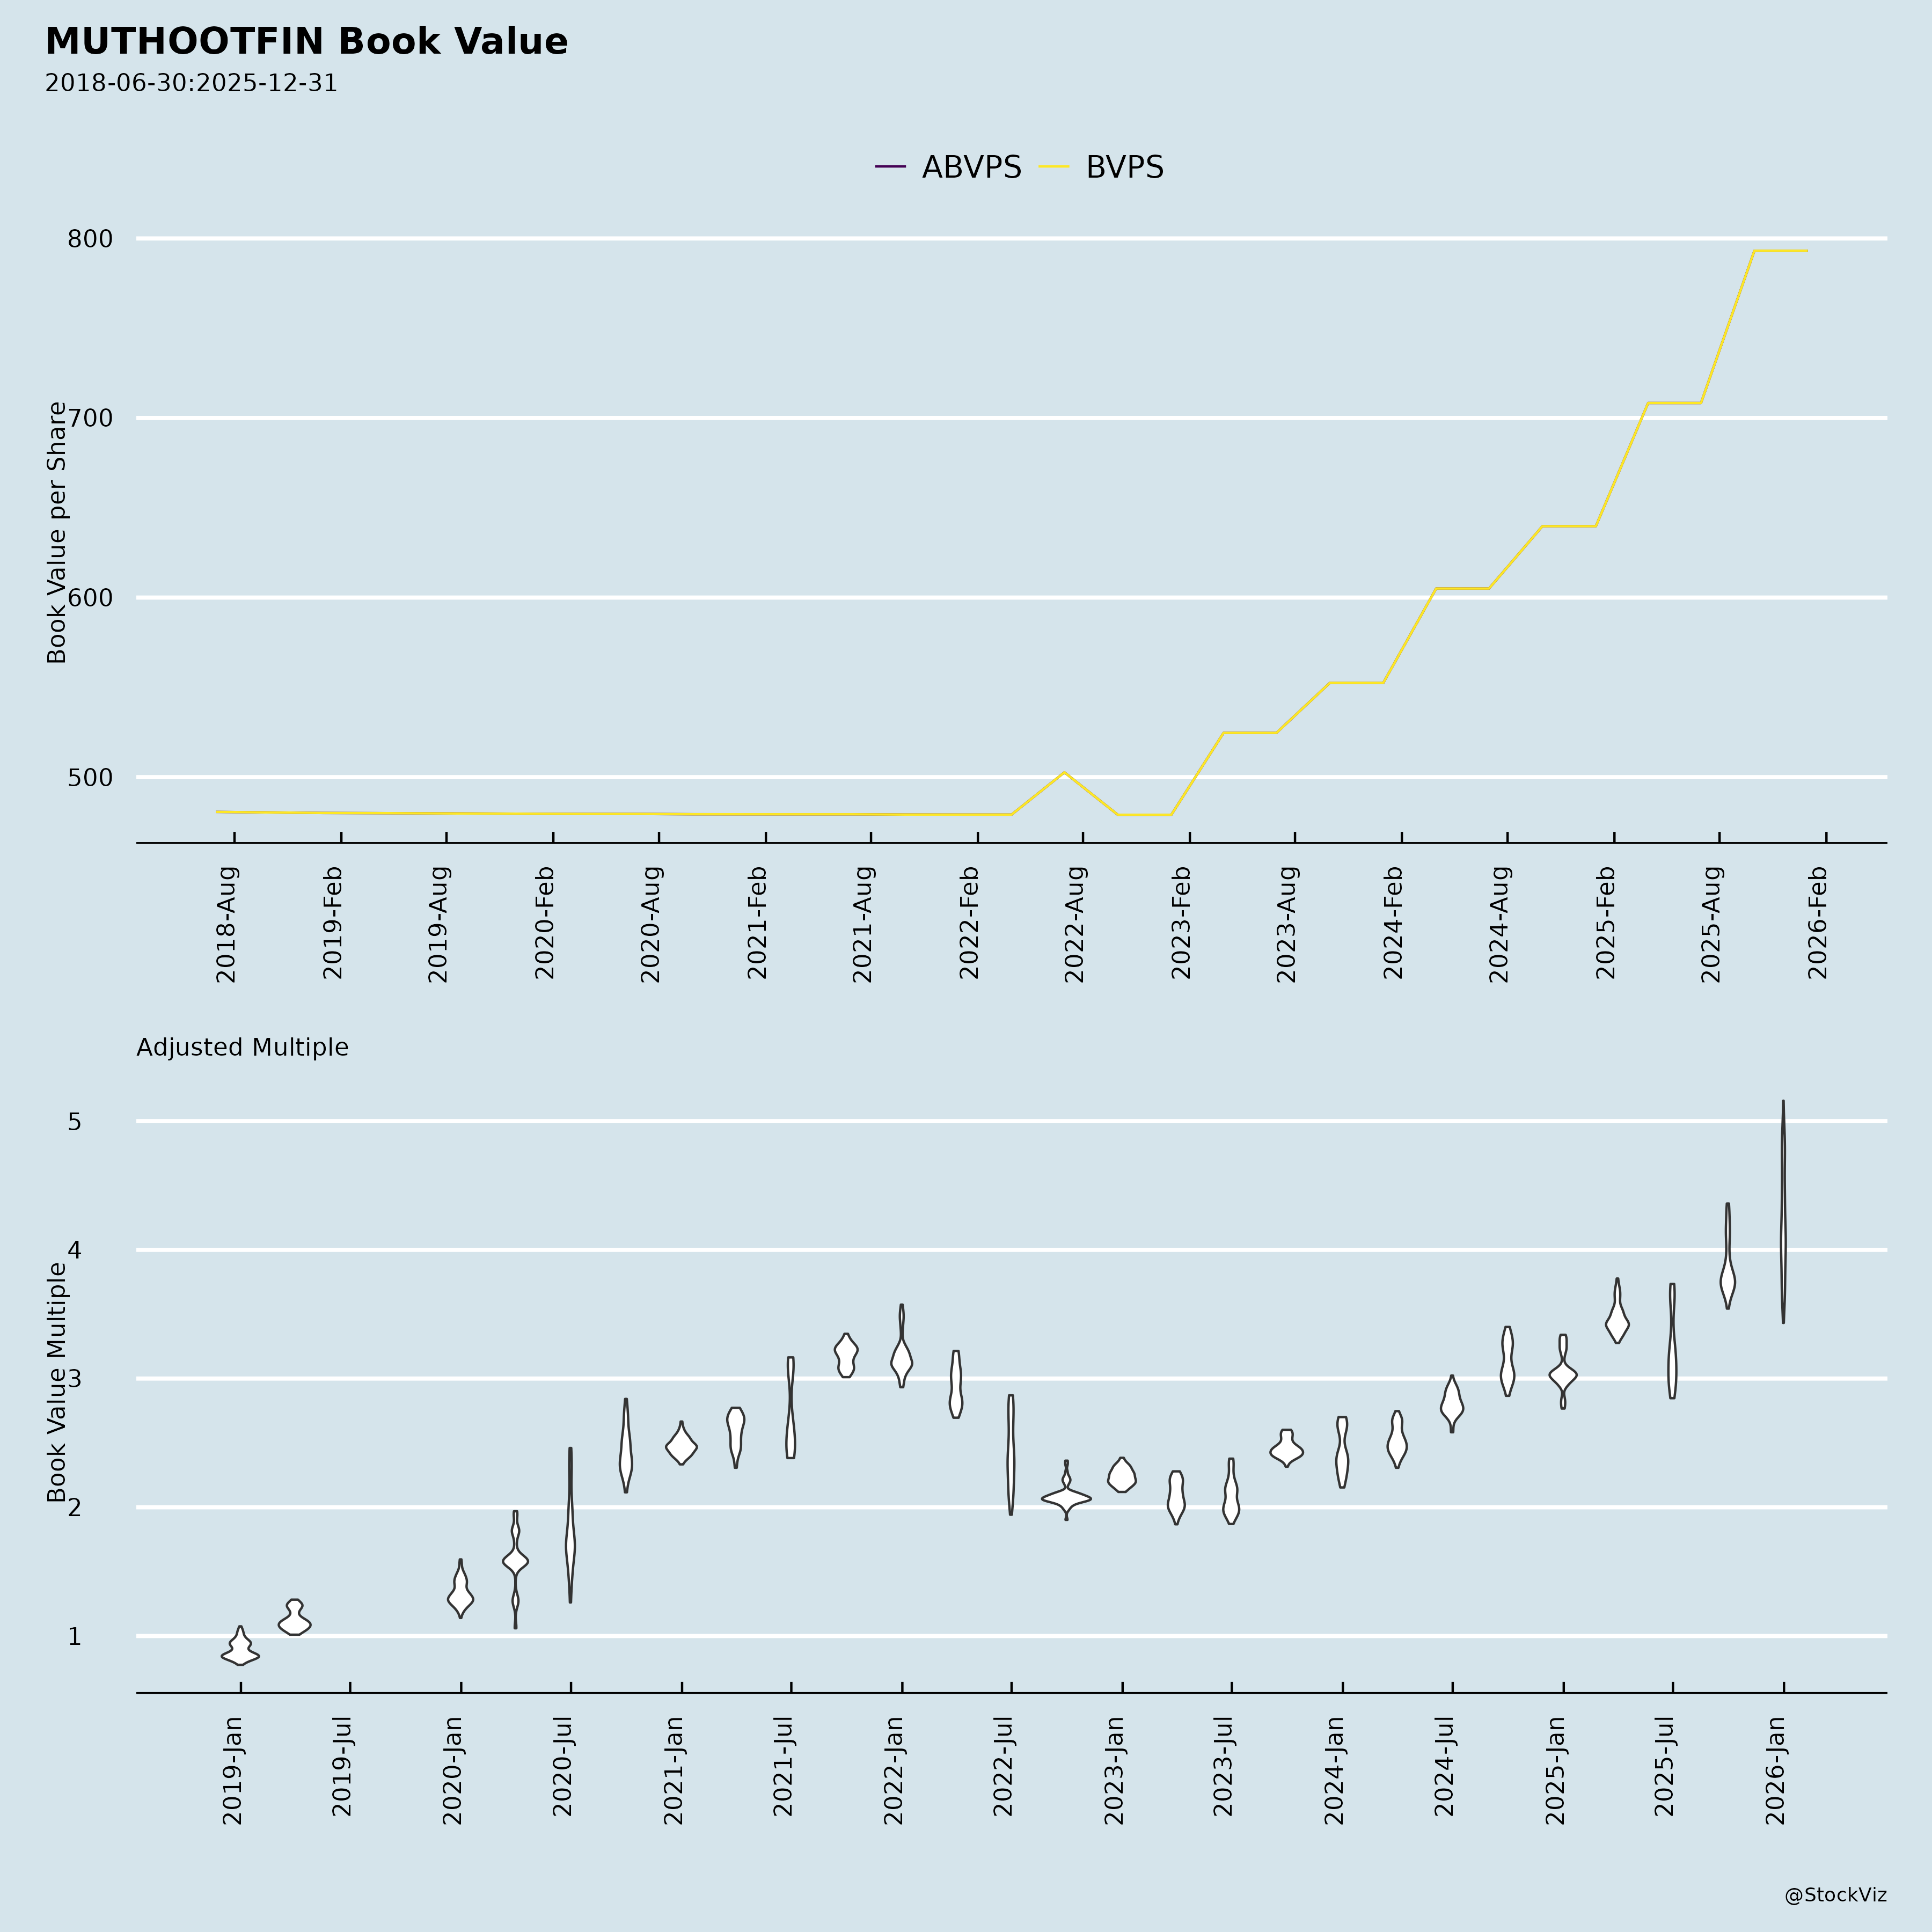
The company recommended a record dividend of 300% (₹30 per equity share) for FY 2026. Return on equity stood at 26.60% in Q1 FY 2027, and earnings per share was ₹63.53. Book value per share was ₹970.70, and market capitalisation exceeded ₹1,203,321 Mn as of June 30, 2026.
Broker Narrative
The narrative shifted from an unreservedly bullish first report in June 2023, which saw no headwinds and expected customer growth without yield sacrifice, to a cautious Neutral call by August 2026 focused on margin compression, rising competition, and a likely FY27 earnings downcycle. Persisting themes were strong gold loan demand, robust AUM growth, branch expansion, and stable asset quality, but the later report replaced yield optimism with concerns over NIM decline, spreads, and borrowing costs.
Optimism that failed
- The early expectation of customer growth ‘without reduction in yield’ failed, as gold loan yields fell to 18.1% and NIM declined ~3pp QoQ to ~10.6% by 1QFY27.
Broker Timeline
43 broker calls · 2023-08-10 to 2026-08-02
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.