MANALIPETC
Equity Metrics
October 23, 2026
Manali Petrochemicals Limited
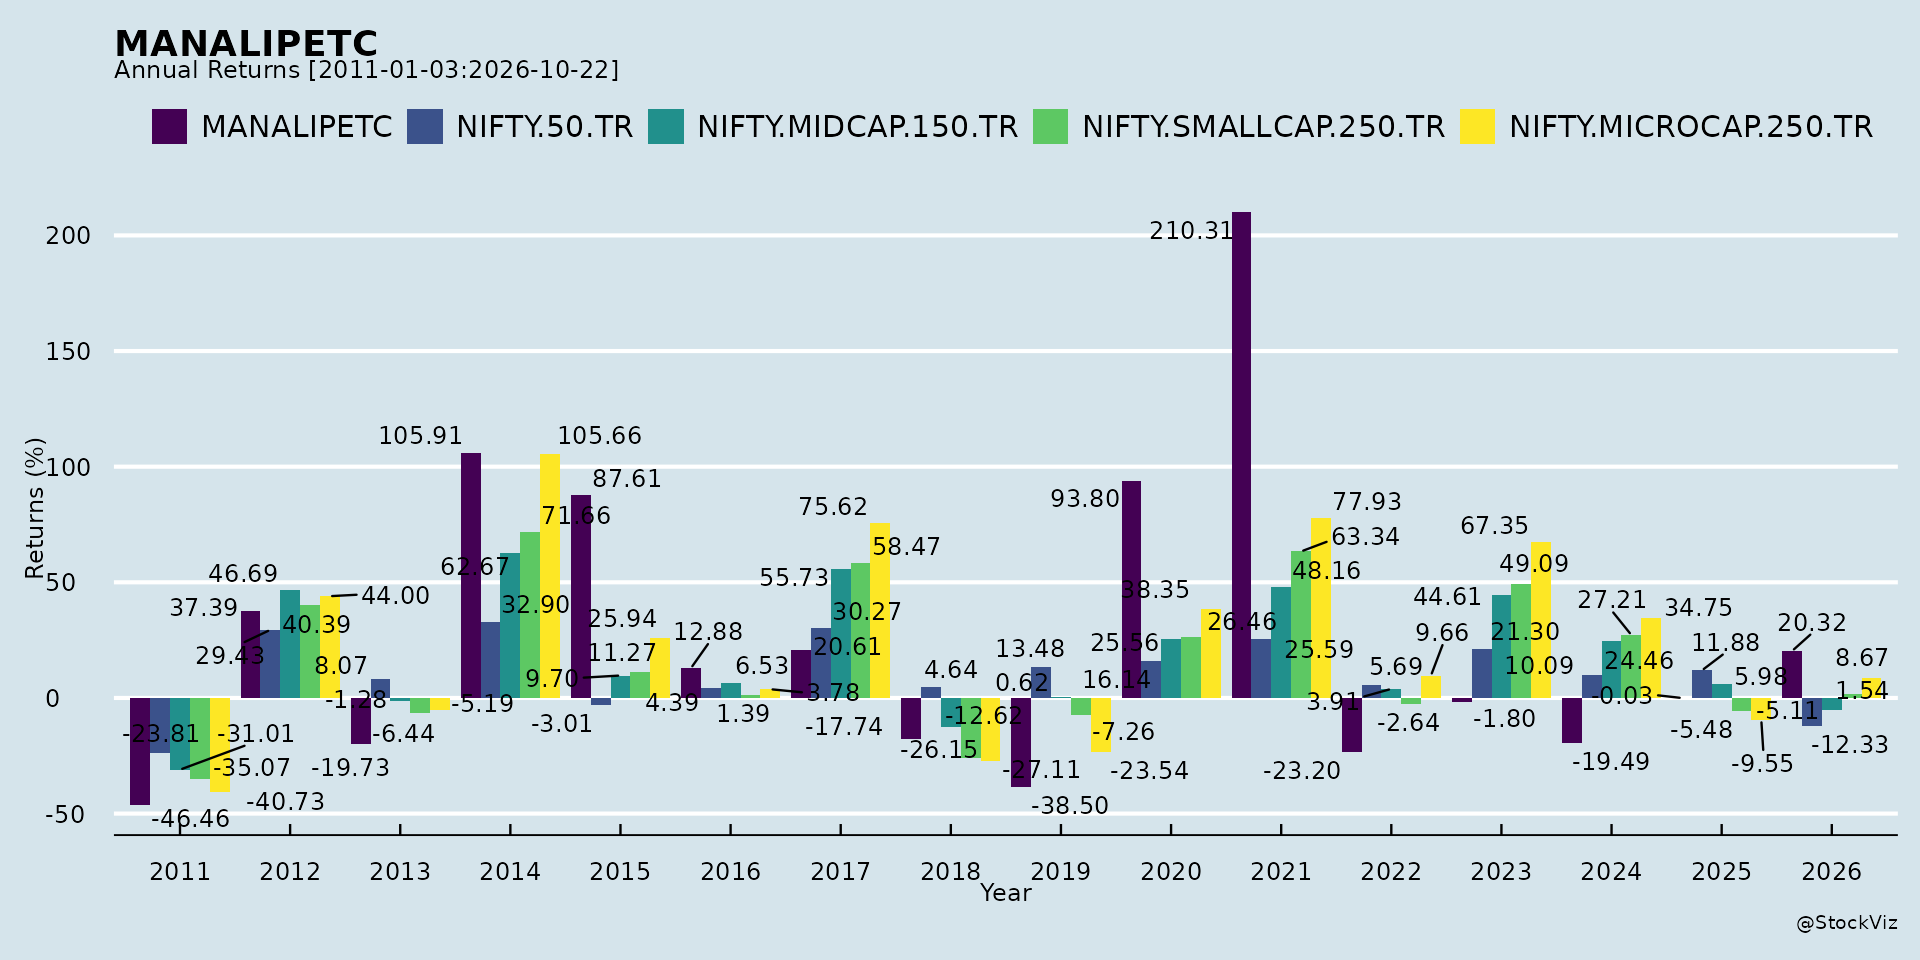
Annual Returns
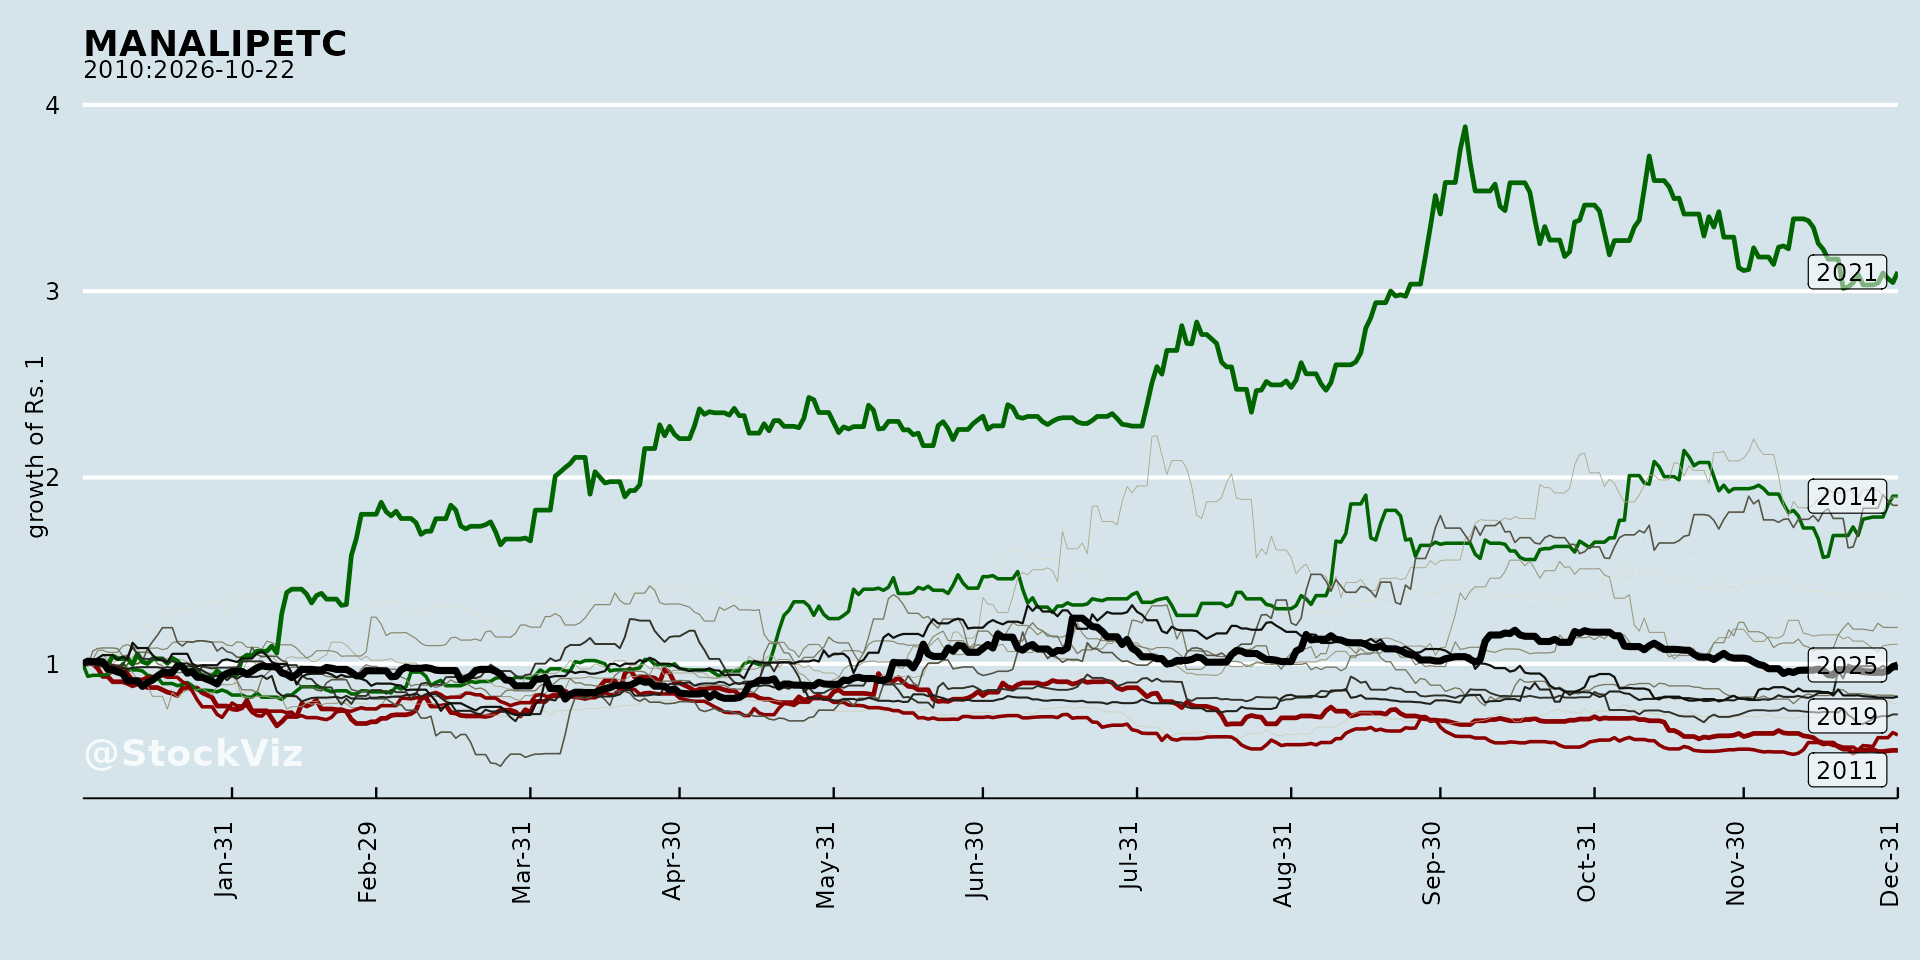
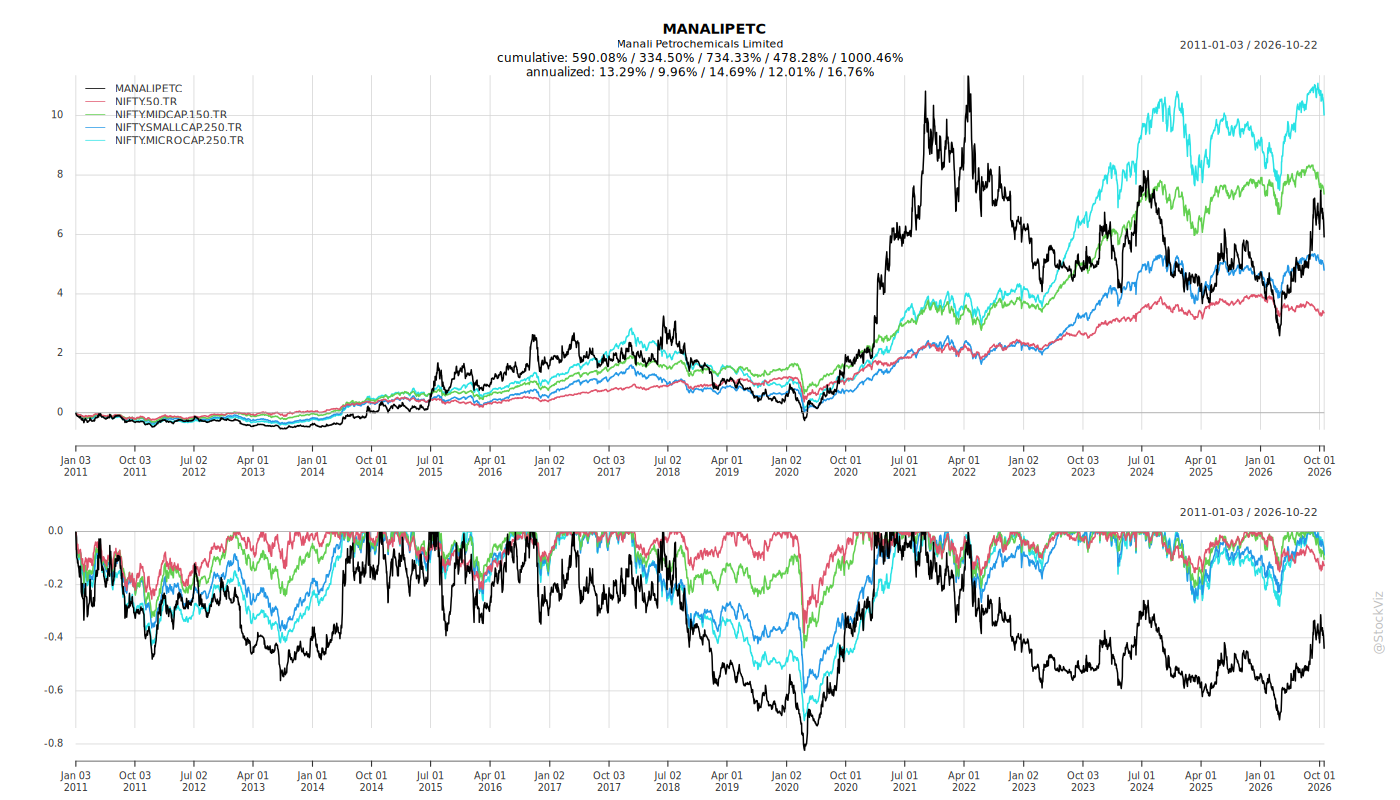
Cumulative Returns and Drawdowns
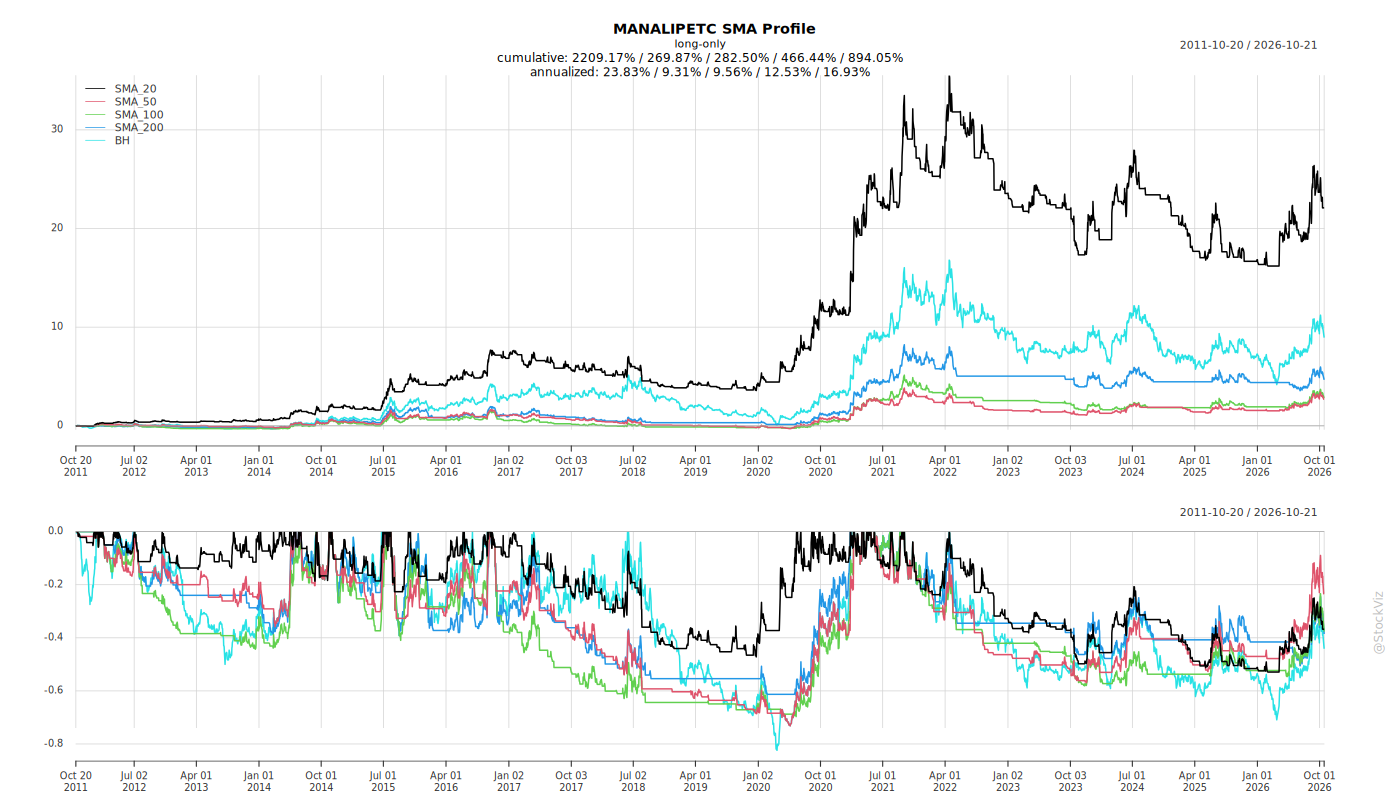
Fundamentals
Ownership
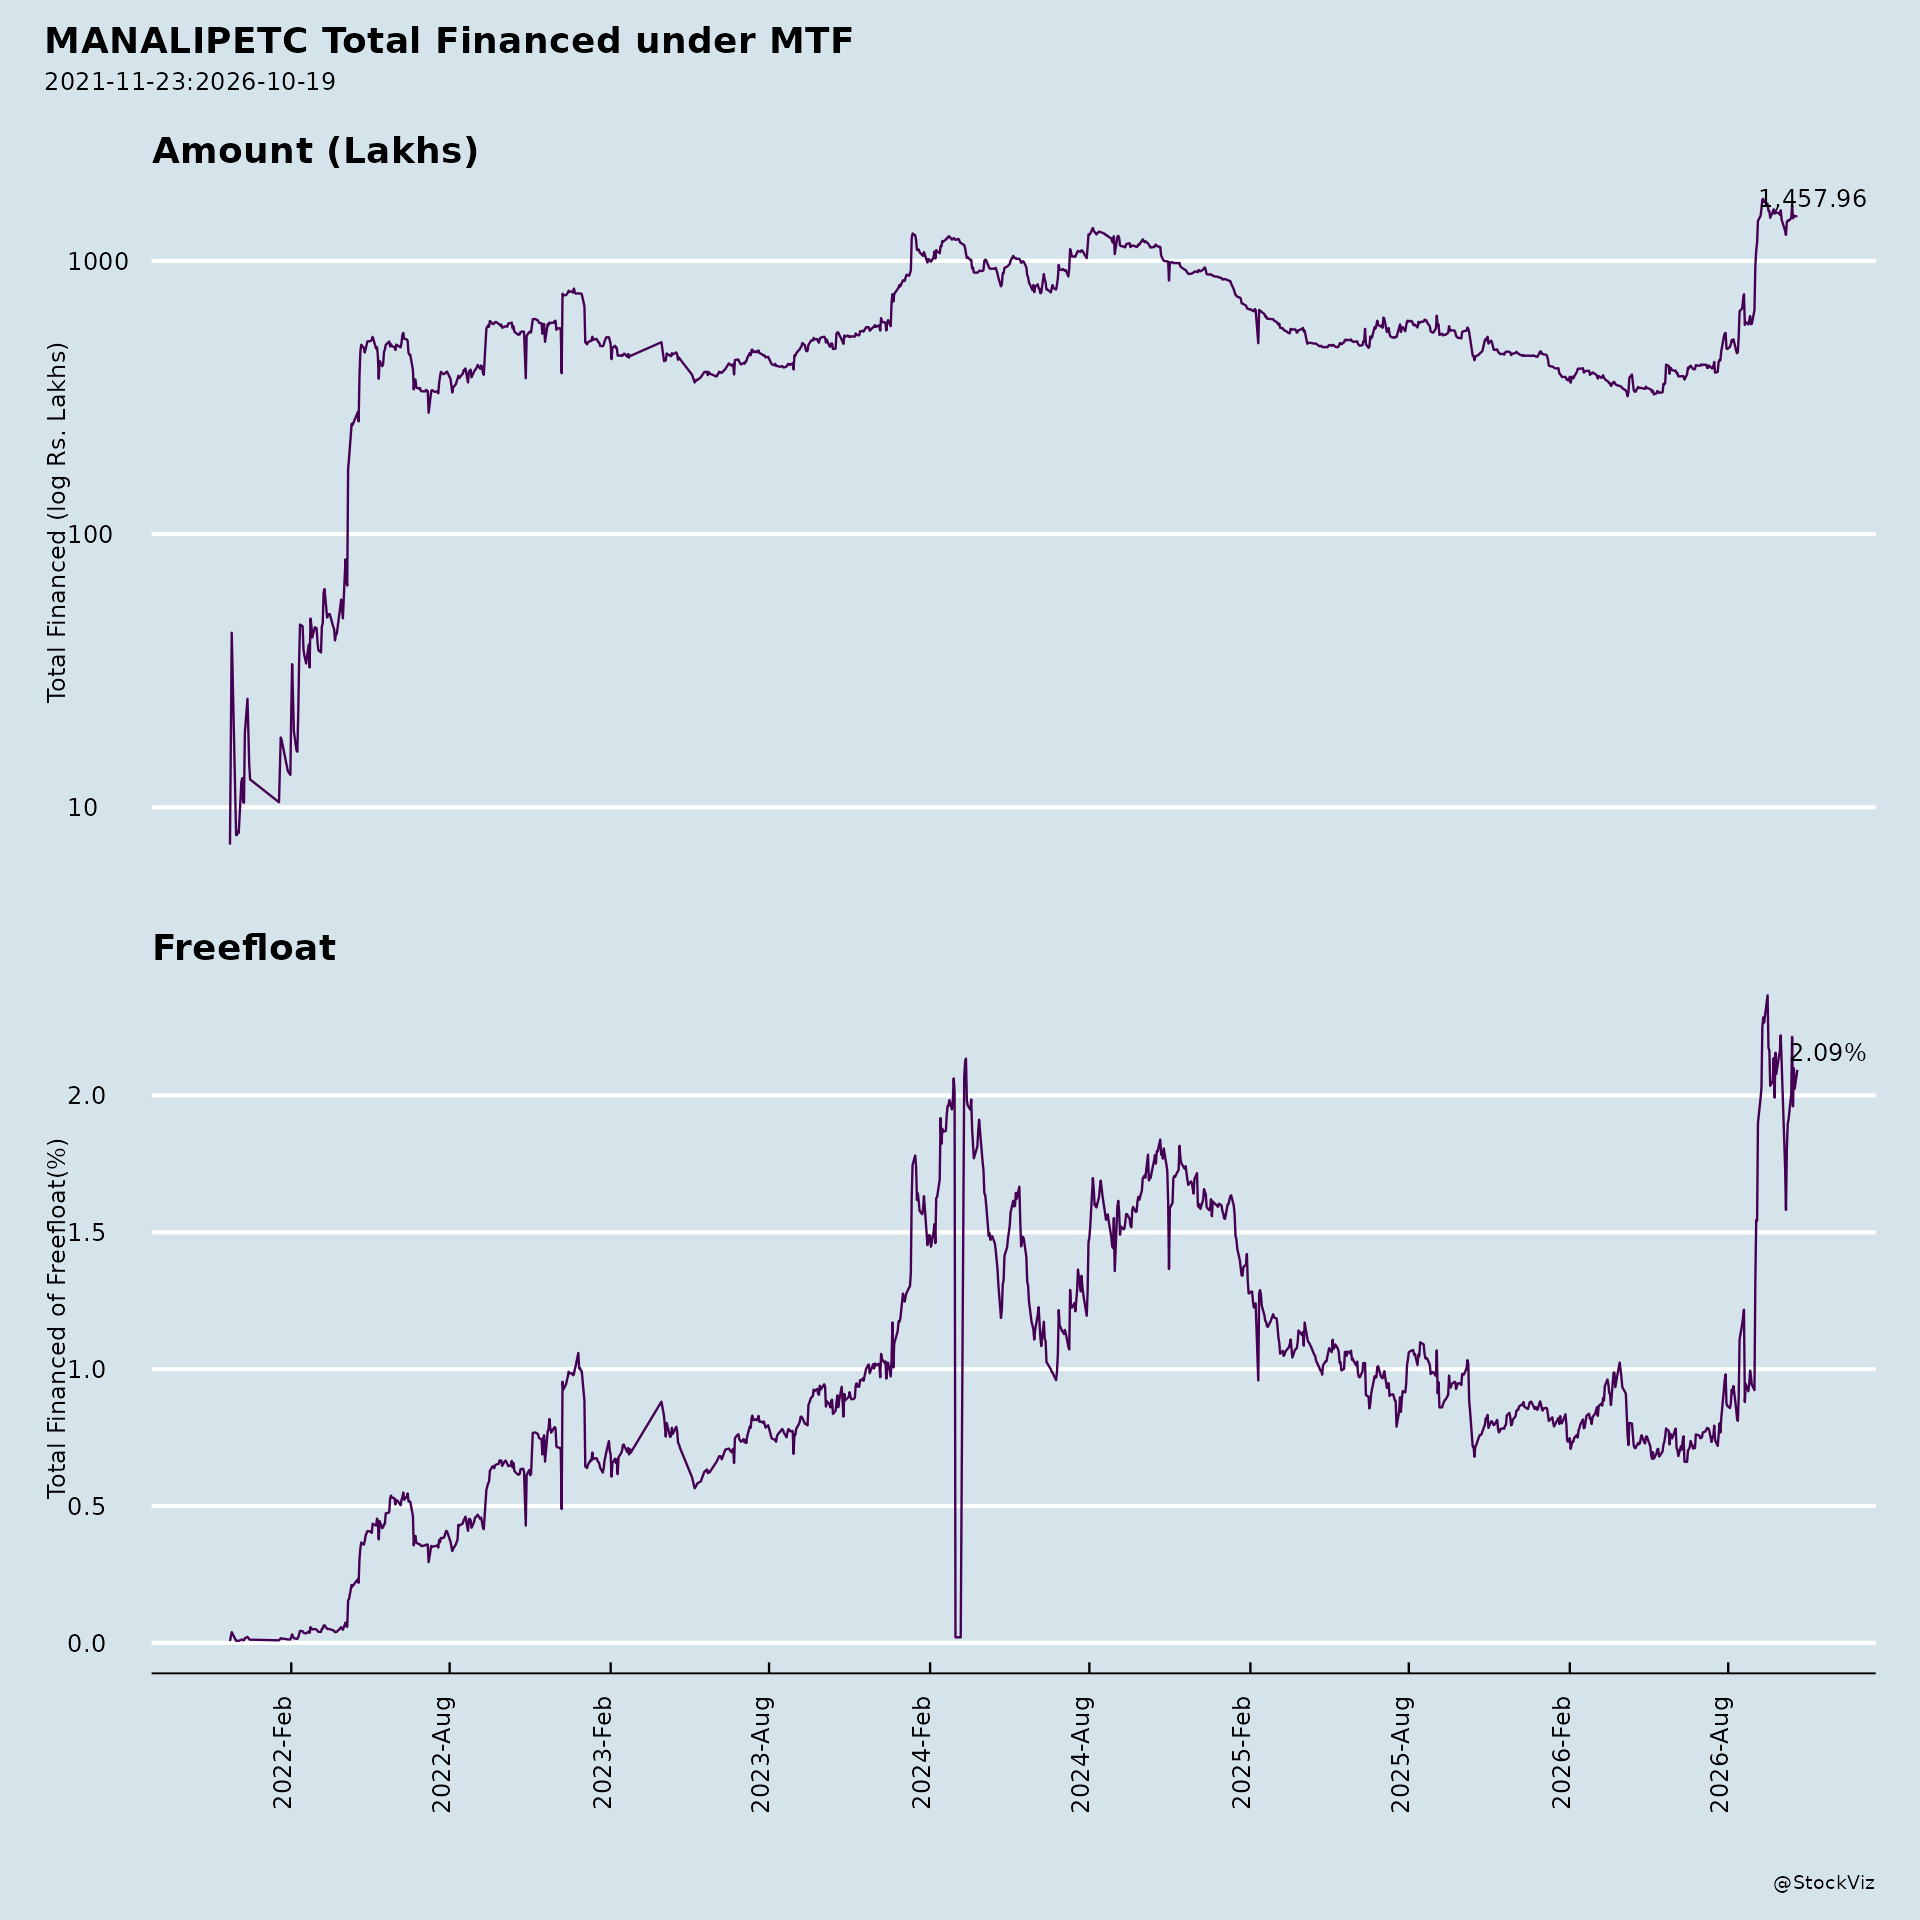
Margined
AI Summary
asof: 2026-09-18
Headwinds and Challenges
Manali Petrochemicals operates in a market marked by competitive import-led pressure across key product segments, which weighs on domestic pricing and margins. Intense price competition and global oversupply have led to surplus import inflows into India. The company also carries high dependence on imports for key raw materials such as Polyols and PG. Geopolitical tensions and conflicts, including developments in West Asia, affect feedstock availability and drive up freight and insurance costs. Evolving and stringent environmental regulations, such as potential Zero Liquid Discharge requirements, add compliance pressure, alongside broader supply chain uncertainties.
In its results commentary for the quarter ended 30 June 2026, the company noted continued volatility across markets arising from developments in West Asia, and stated that management continues to monitor volatility in raw material costs, demand trends and global trade flows.
Tailwinds and Growth Prospects
The Indian PU market is described as under-penetrated in per-capita usage, with strong demand across flexible foam, footwear, automotive interiors, and construction insulation. The successful commissioning of the Propylene Glycol Expansion Project in October 2025 strengthens the company’s market position, enables pharmaceutical-grade sales, and reduces import dependence. Additional tailwinds include a strategic shift toward specialized, higher-value polyurethane systems, continuous operational efficiency and cost-optimization measures, increasing renewable energy usage, and growing domestic demand supported by government initiatives such as Make in India.
For the quarter ended 30 June 2026, results were supported by improved realizations and effective management of the product portfolio, with standalone profitability benefiting from disciplined commercial execution and focused sourcing initiatives. Consolidated performance was further supported by contributions from the overseas subsidiary. The Chairman stated that the strategy is to progressively move up the value chain, with greater emphasis on differentiated, higher-value and sustainable products and solutions.
Key Risks
- Leasehold land renewal: The lease for the leasehold land on which Unit-II operates expired on 30 June 2017. The company has filed for renewal for a further period of 30 years with the Government of Tamil Nadu and is awaiting extension. Pending renewal, no adjustments have been made, as the impact of non-renewal cannot be determined. Lease rent has been paid and encashed up to 30 June 2027, and Ind AS 116 has been applied premised on a 30-year renewal. The auditors included an Emphasis of Matter on this.
- Cyclone Michaung insurance claim: The claim for damages to Property, Plant and Equipment remains under assessment by the insurer. A sum of INR 1,180 lakhs (net of INR 300 lakhs on-account payment received) incurred for repairs and reinstatement, and consequent derecognition of affected assets, is treated as insurance claims receivable. The overall implications upon eventual approval are unascertainable, and no adjustments have been made. The auditors included an Emphasis of Matter on this.
- Subsidiary restructuring: Notedome Limited, UK and Notedome Europe GmbH ceased to be step-down subsidiaries with effect from 17 November 2025, following the sale by AMCHEM Speciality Chemicals Private Limited, Singapore of its 100% investment to M/s Chimica Organica Industriale Milanese (C.O.I.M.). A gain on divestment of INR 5,216 lakhs (net of transfer expenses) was recognised as an exceptional item in the consolidated financial results for the previous year.
- Unreviewed subsidiary results: The consolidated results include two foreign subsidiaries and one Indian subsidiary whose interim financial results were reviewed by other auditors, reflecting total revenue of INR 6,693 lakhs and total net profit after tax and total comprehensive income of INR 2,514 lakhs (before consolidation adjustments) for the quarter ended 30 June 2026. One subsidiary’s interim results were not reviewed by its auditor, reflecting total revenue of INR Nil lakhs and total net loss after tax and total comprehensive loss of INR 0.13 lakhs, and are not material to the Group.
Management Guidance Versus Observed Business Performance
Management’s stated focus areas include operational efficiency, cost discipline, prudent working-capital management, and a strategic shift from commodity products to specialized and higher-value systems markets. It also plans to pursue export opportunities in a calibrated manner, implement partial Zero Liquid Discharge systems subject to regulatory approvals, and progress with a proposed manufacturing facility in western India.
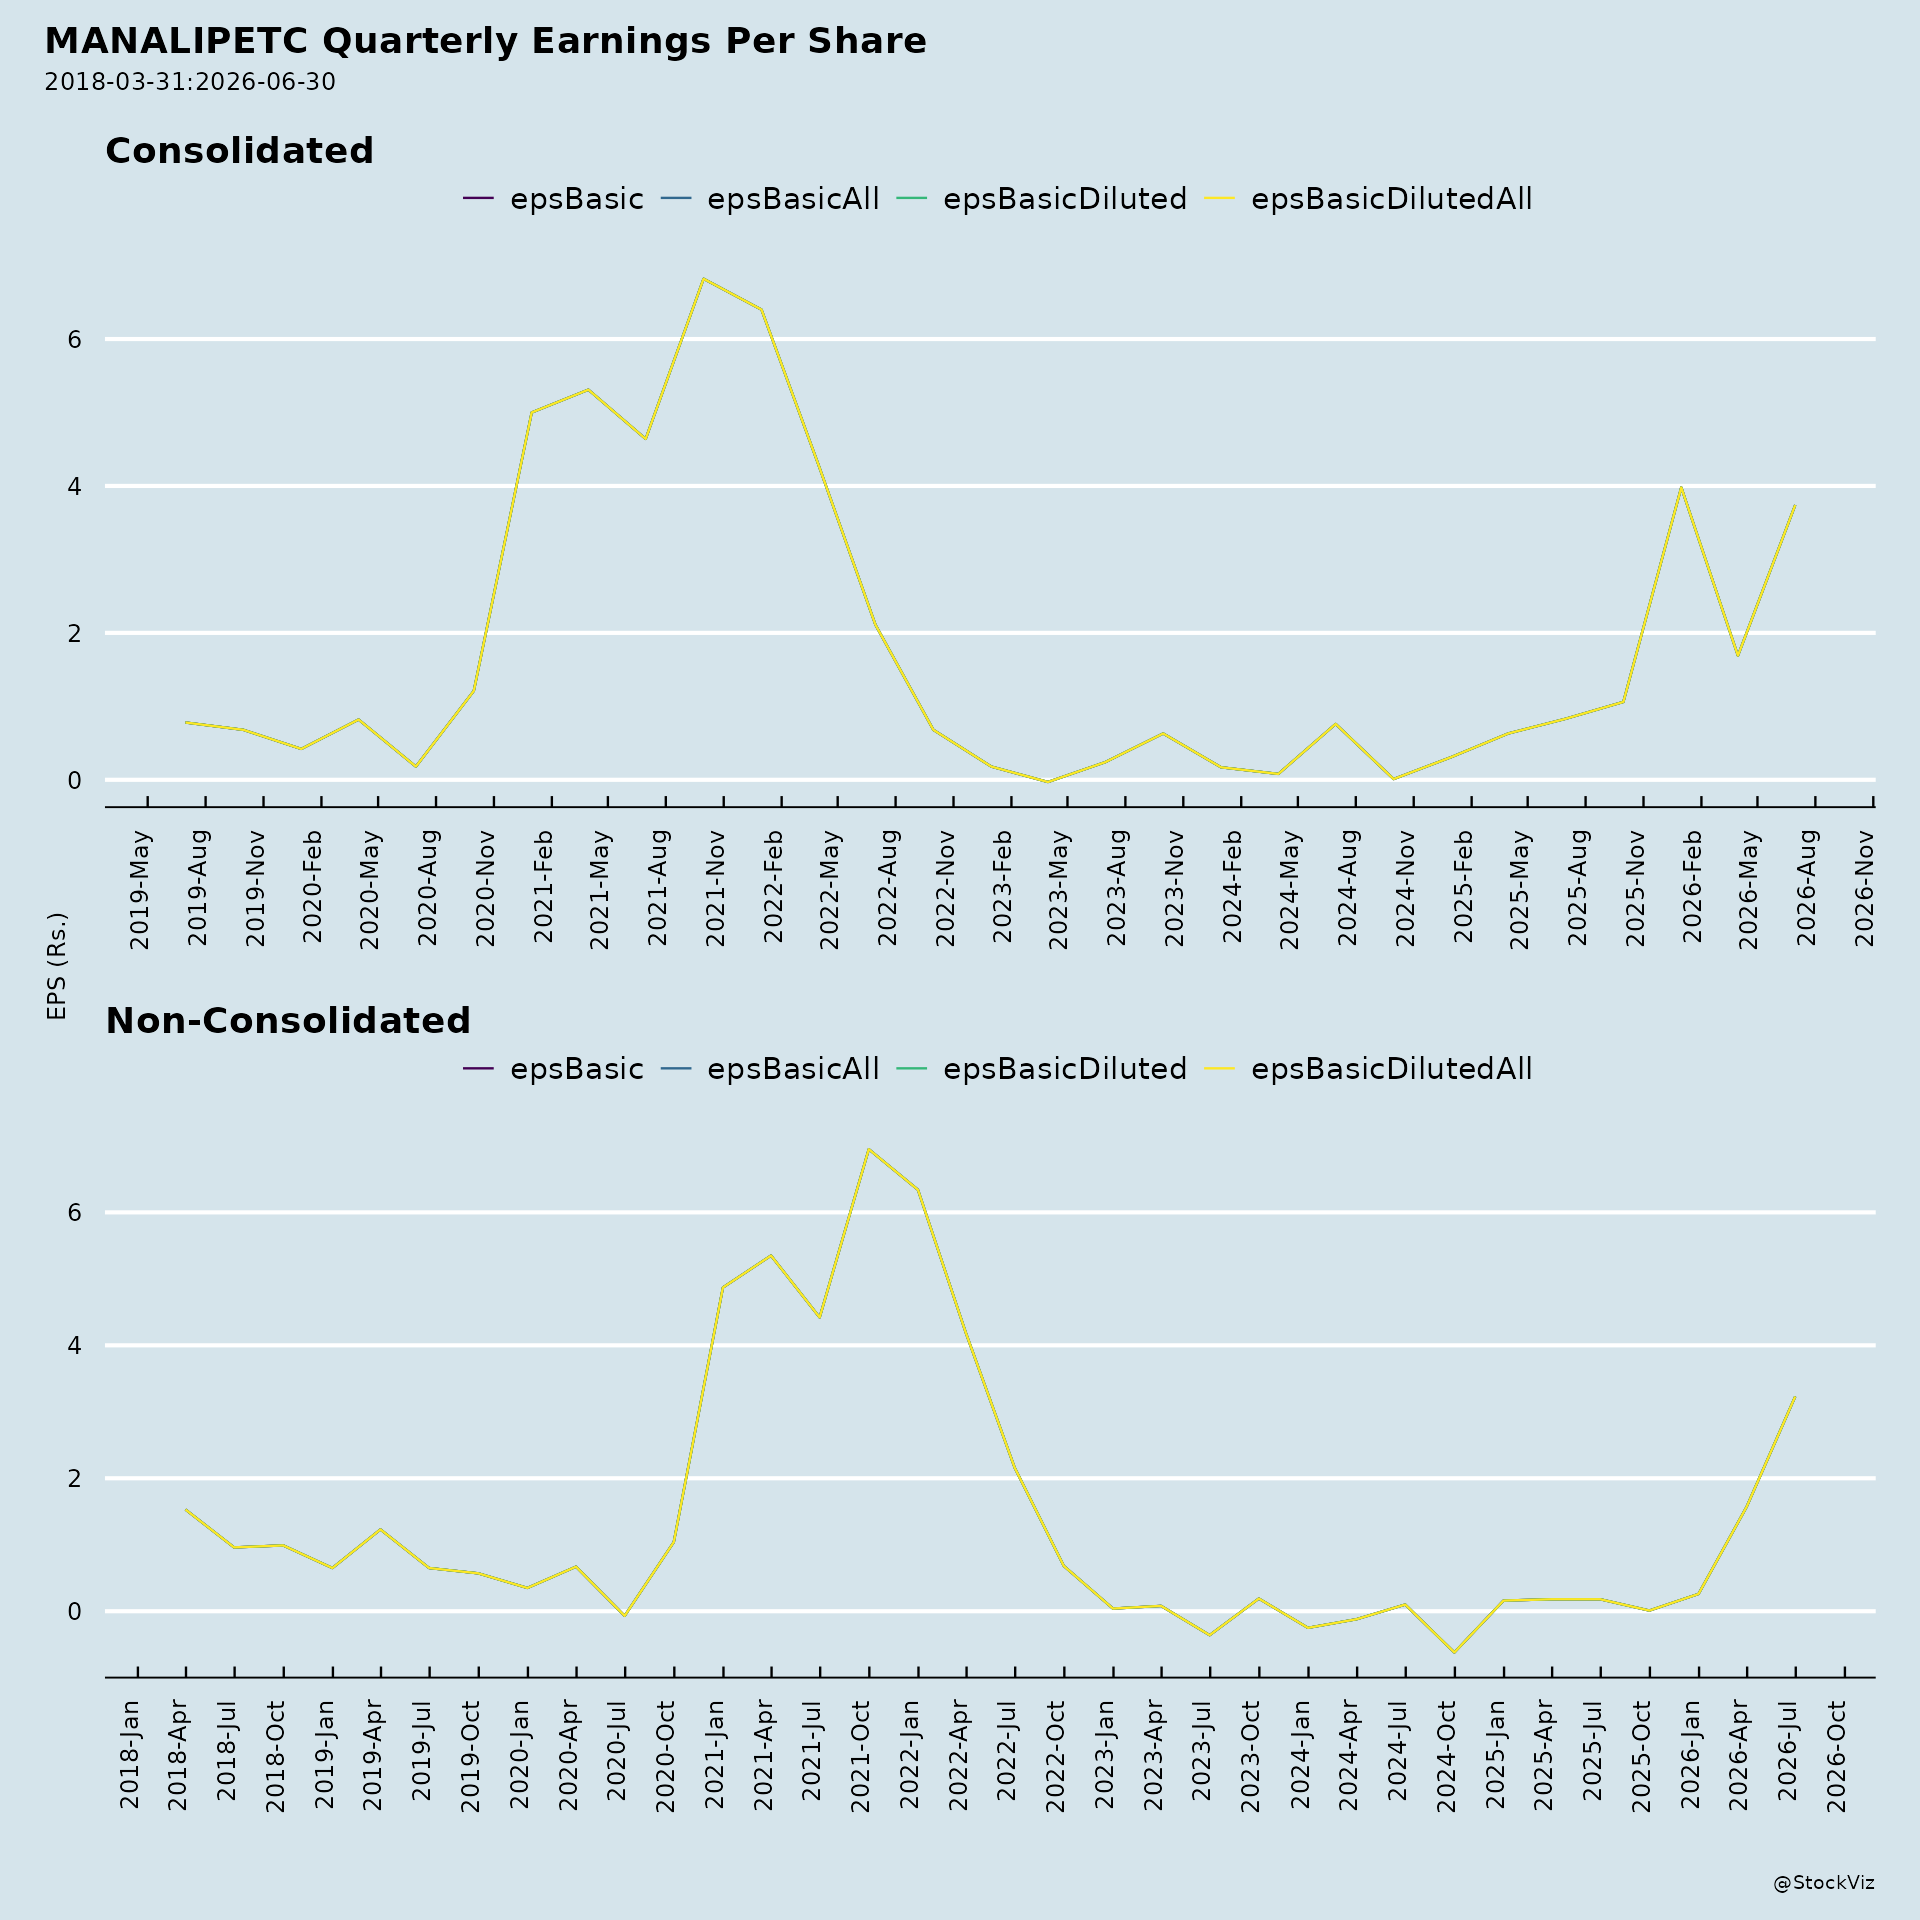
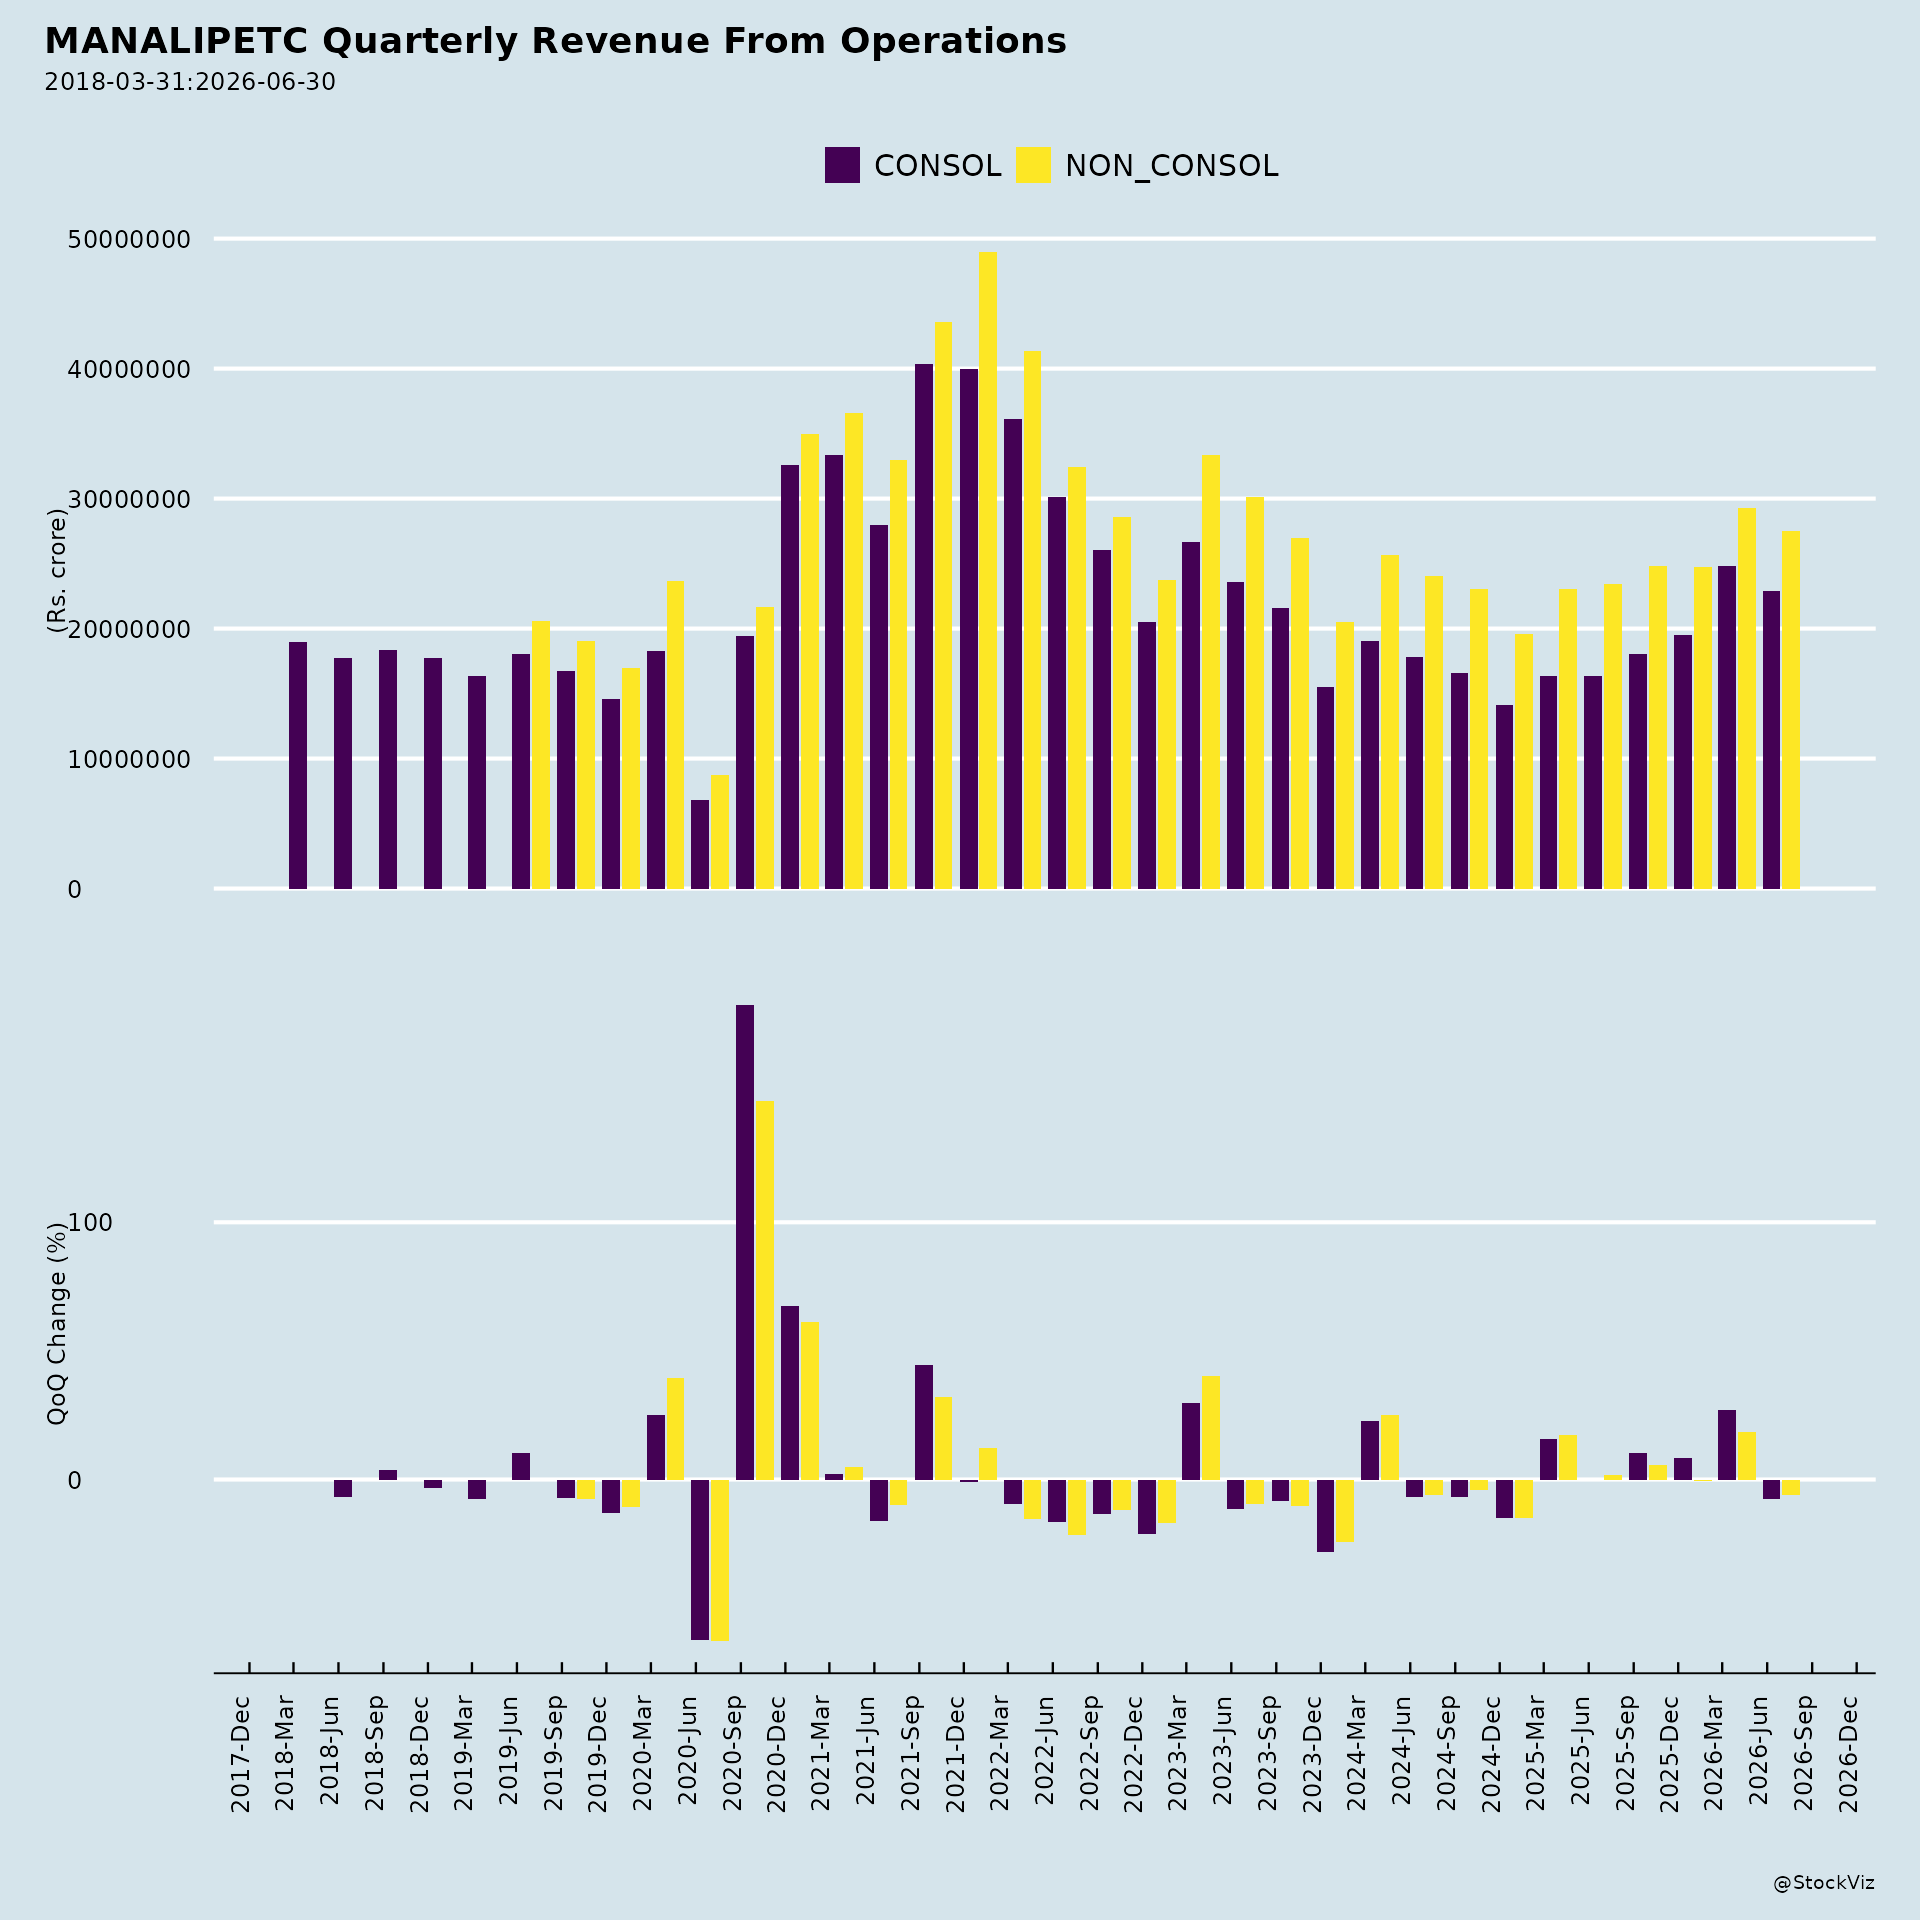
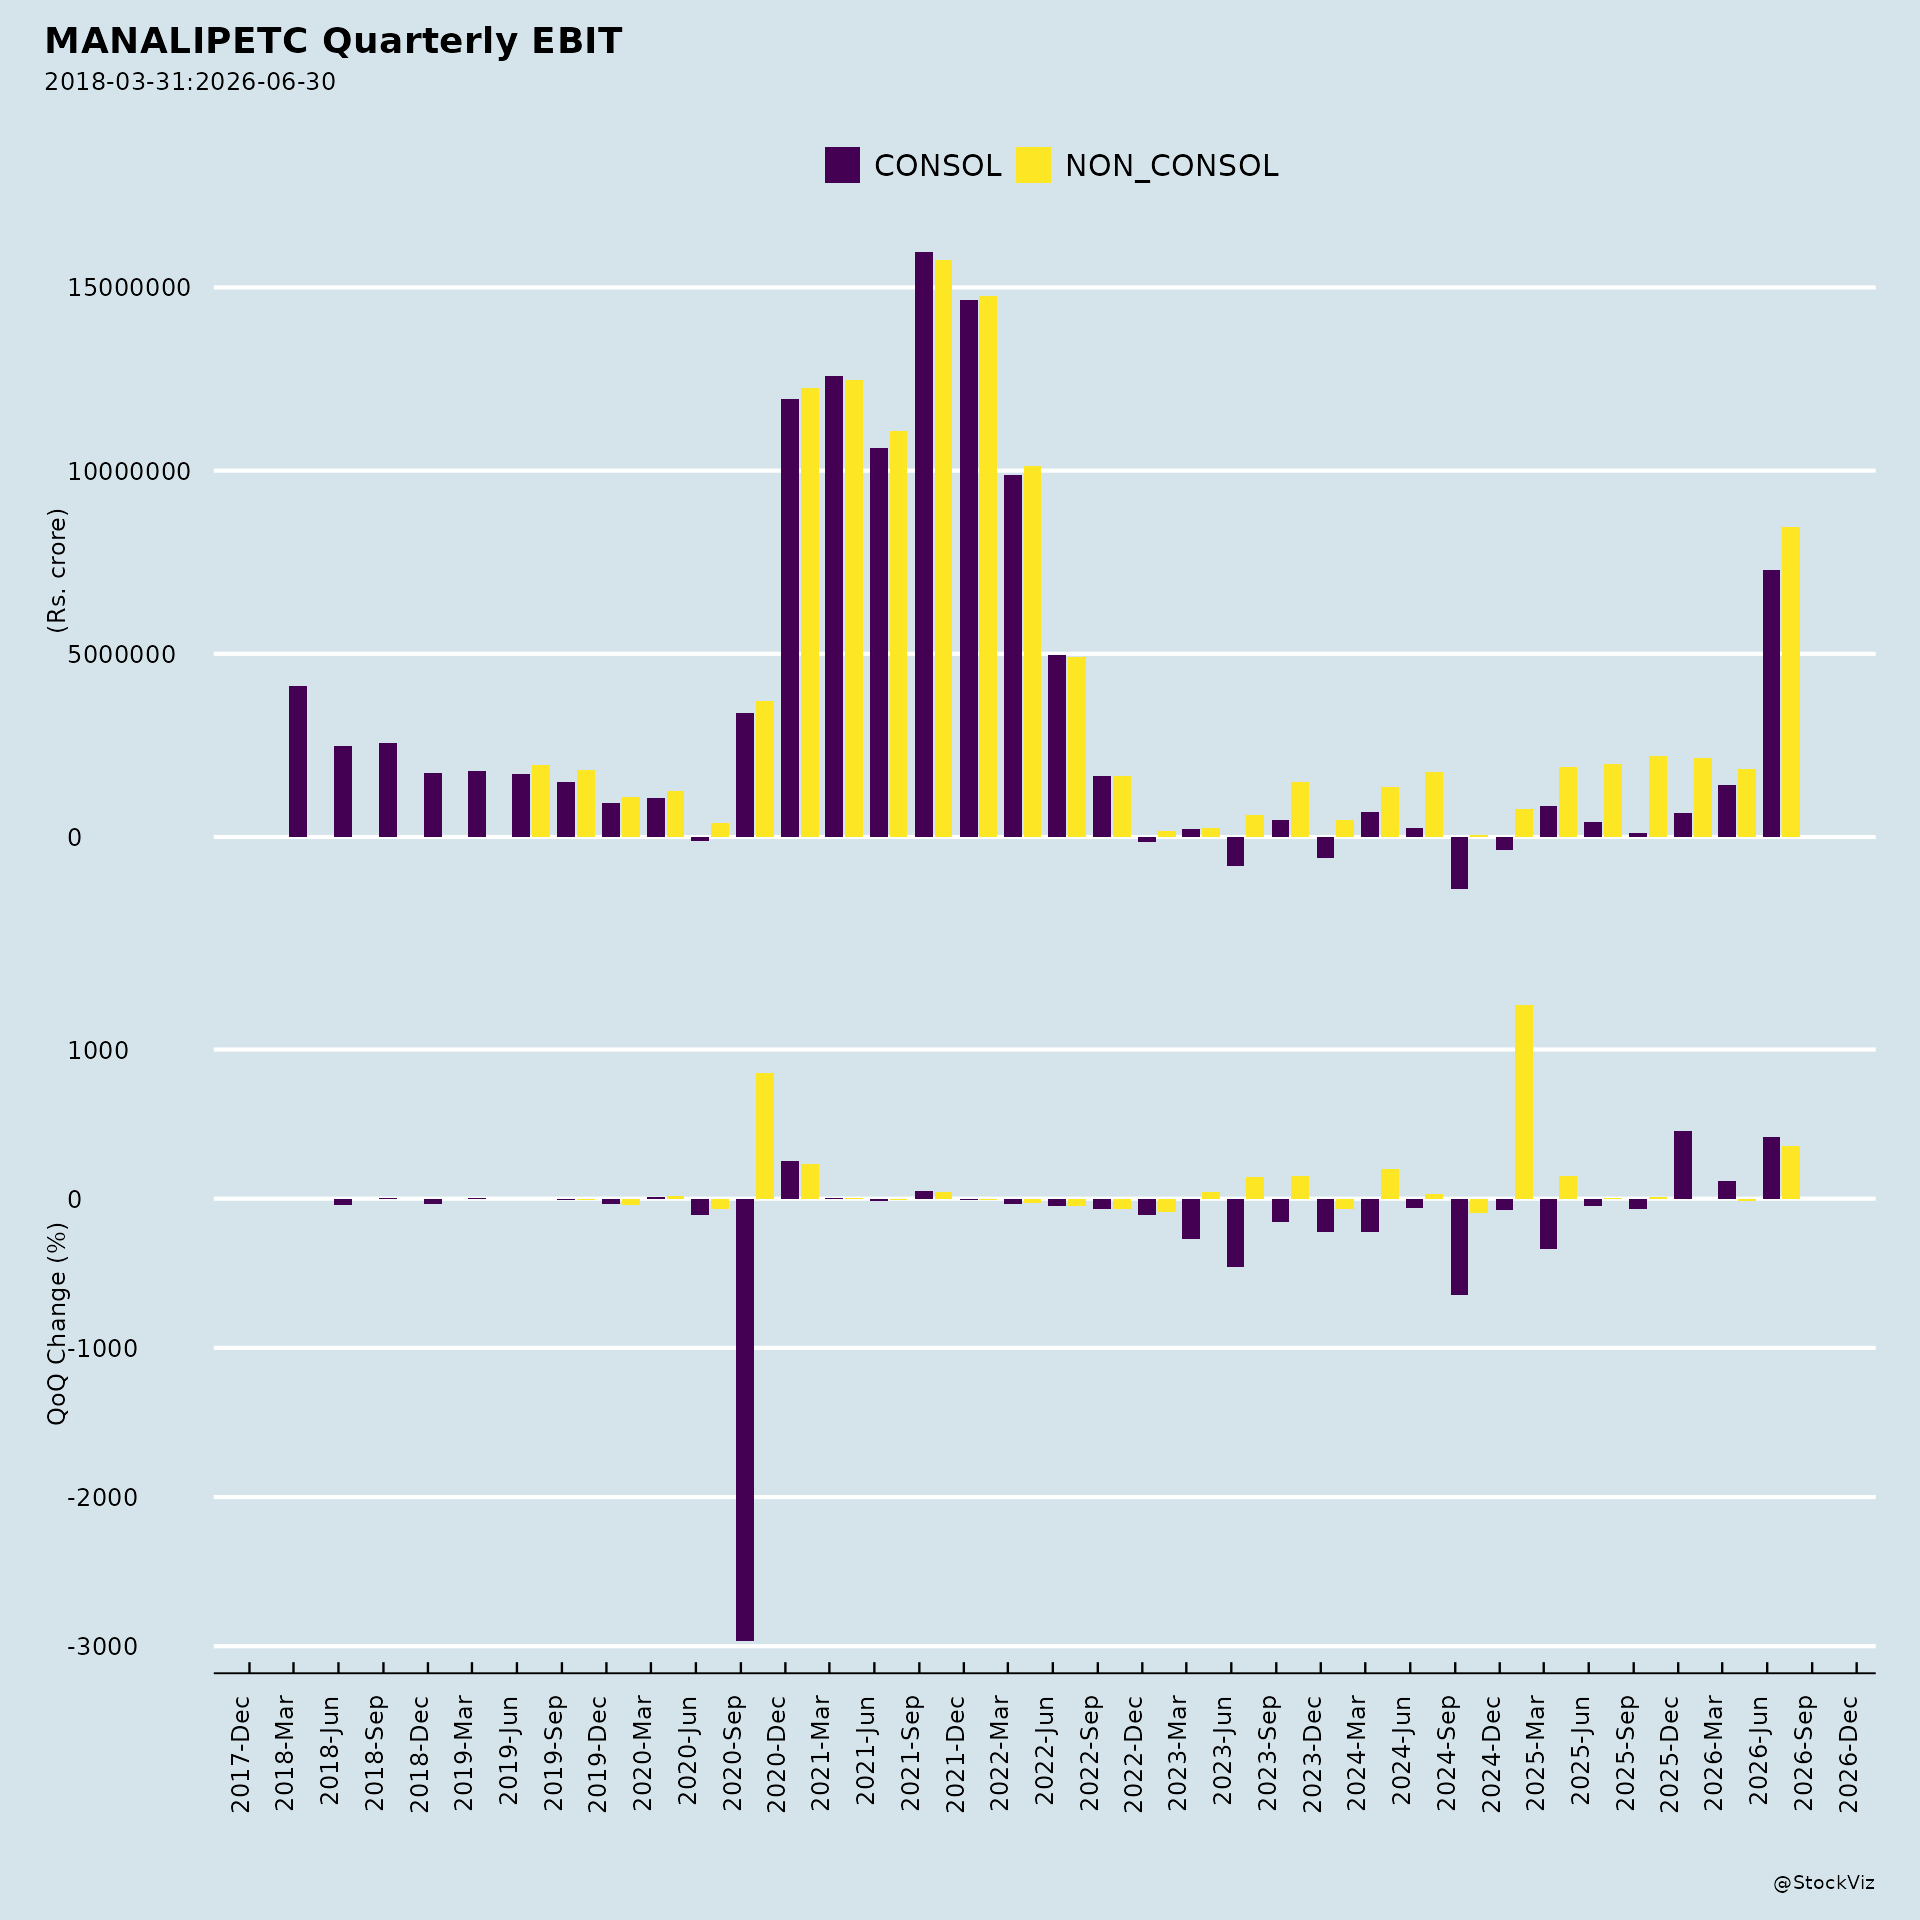
Observed performance for the quarter ended 30 June 2026 shows consolidated total income of Rs. 288.49 crore, PBT of Rs. 84.53 crore and PAT of Rs. 64.36 crore, compared with consolidated total income of Rs. 242.69 crore, PBT of Rs. 19.96 crore and PAT of Rs. 14.34 crore for the quarter ended 30 June 2025. On a standalone basis, total income was Rs. 238.99 crore against Rs. 256.71 crore for the previous quarter, with PBT of Rs. 72.86 crore against Rs. 32.74 crore for the previous quarter. The company attributed the results to improved realizations, effective product portfolio management, disciplined commercial execution and focused sourcing initiatives, with consolidated performance further supported by the overseas subsidiary.
Management’s forward-looking market expectations include the global polyurethane market expanding at a CAGR of around 5-6% to reach USD 115-125 billion by 2031, and India’s PU market growing at a CAGR of 7-8% to reach USD 8-9 billion by 2030-31.
Other Key Facts
- The 40th Annual General Meeting is scheduled for Monday, 28 September 2026 at 05:00 P.M. (IST) through Video Conferencing or Other Audio-Visual Means.
- The Board, at its meeting held on 21 May 2026, recommended a dividend of Rs. 0.50 per equity share of Rs. 5 each (10%), subject to shareholder approval at the AGM, payable within 30 days from the date of the AGM. The record date for the dividend is 28 September 2026 for physical shares and 21 September 2026 for electronic shares.
- Mr. L Thriyambak, Practicing Cost Accountant, Chennai, has been appointed as Cost Auditor for FY 2026-27.
- The company maintains a credit rating of CARE A+; Stable for long-term bank facilities and CARE A1+ for short-term facilities.
- For FY 2025-26, consolidated total income was Rs. 1,069.85 crore and PAT was Rs. 129.95 crore.
- The company markets propylene glycol and polyols and is part of the Singapore-headquartered AM International Group. Its wholly owned subsidiaries are AMCHEM Speciality Chemicals Private Limited, Singapore and Manali Speciality Private Limited, India, with step-down subsidiaries PennWhite Limited, UK and PennWhite India Private Limited, India.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.