KERNEX
Equity Metrics
November 18, 2026
Kernex Microsystems (India) Limited
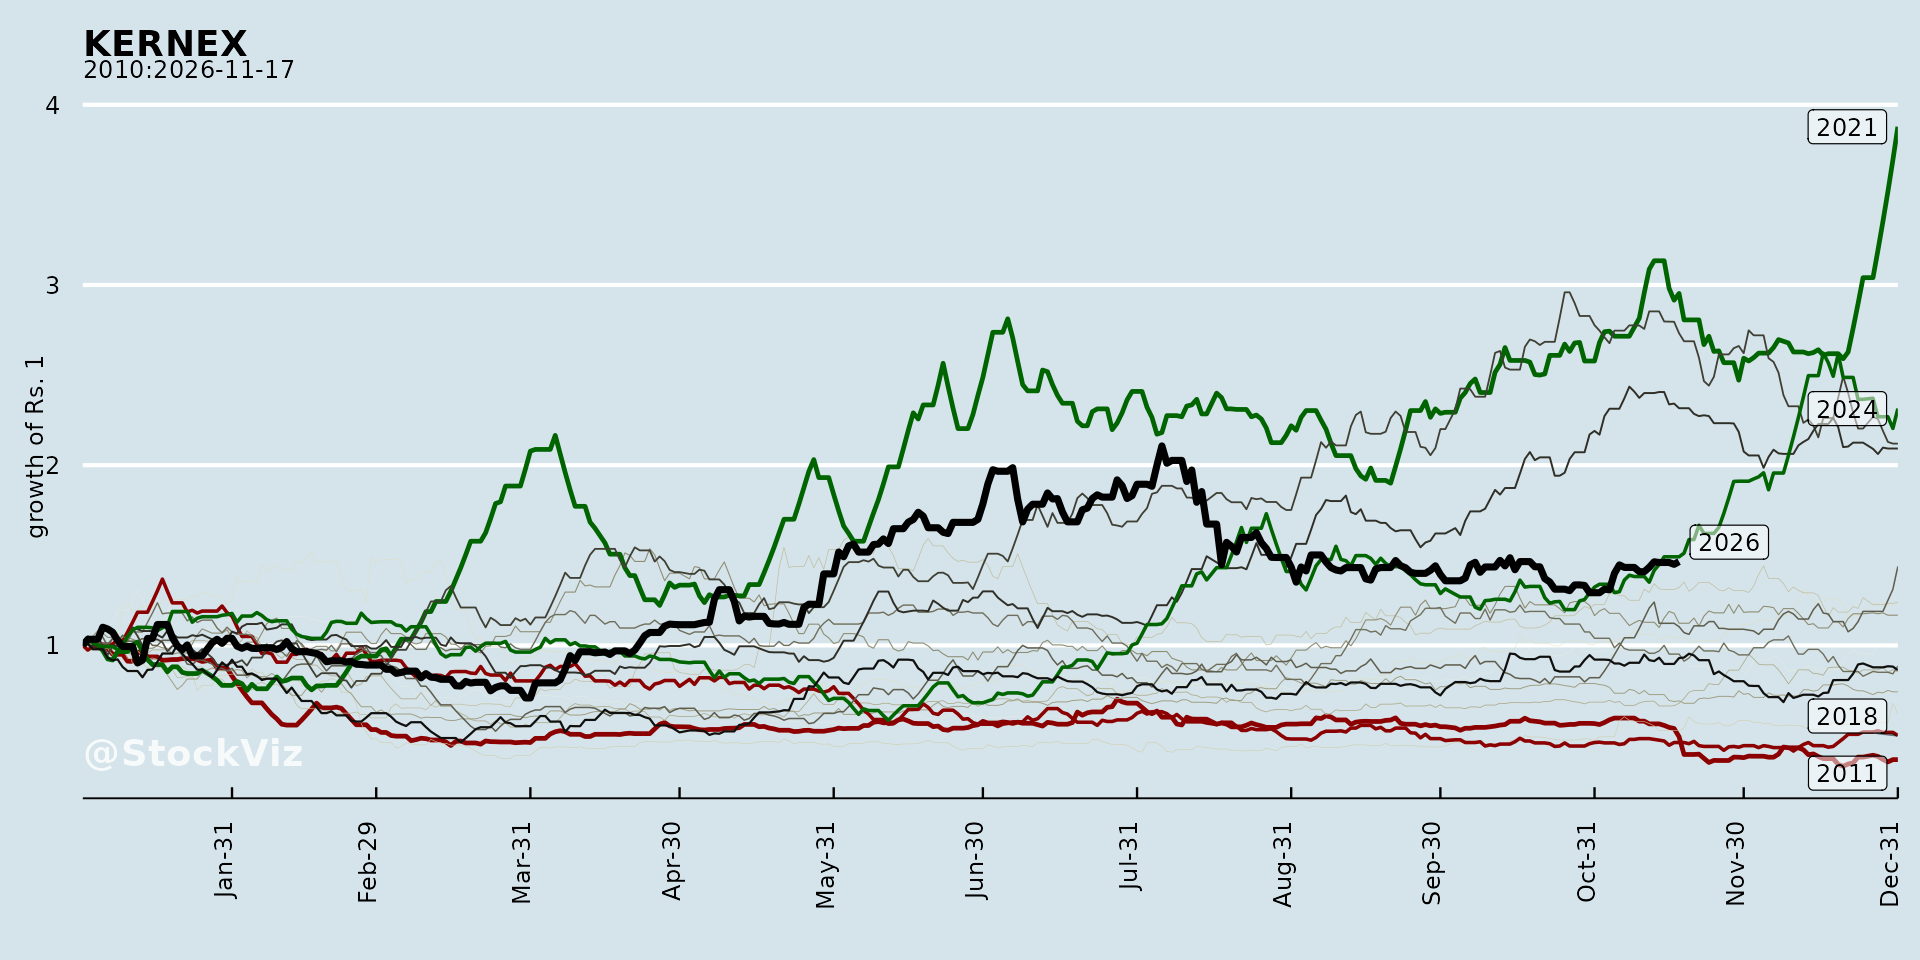
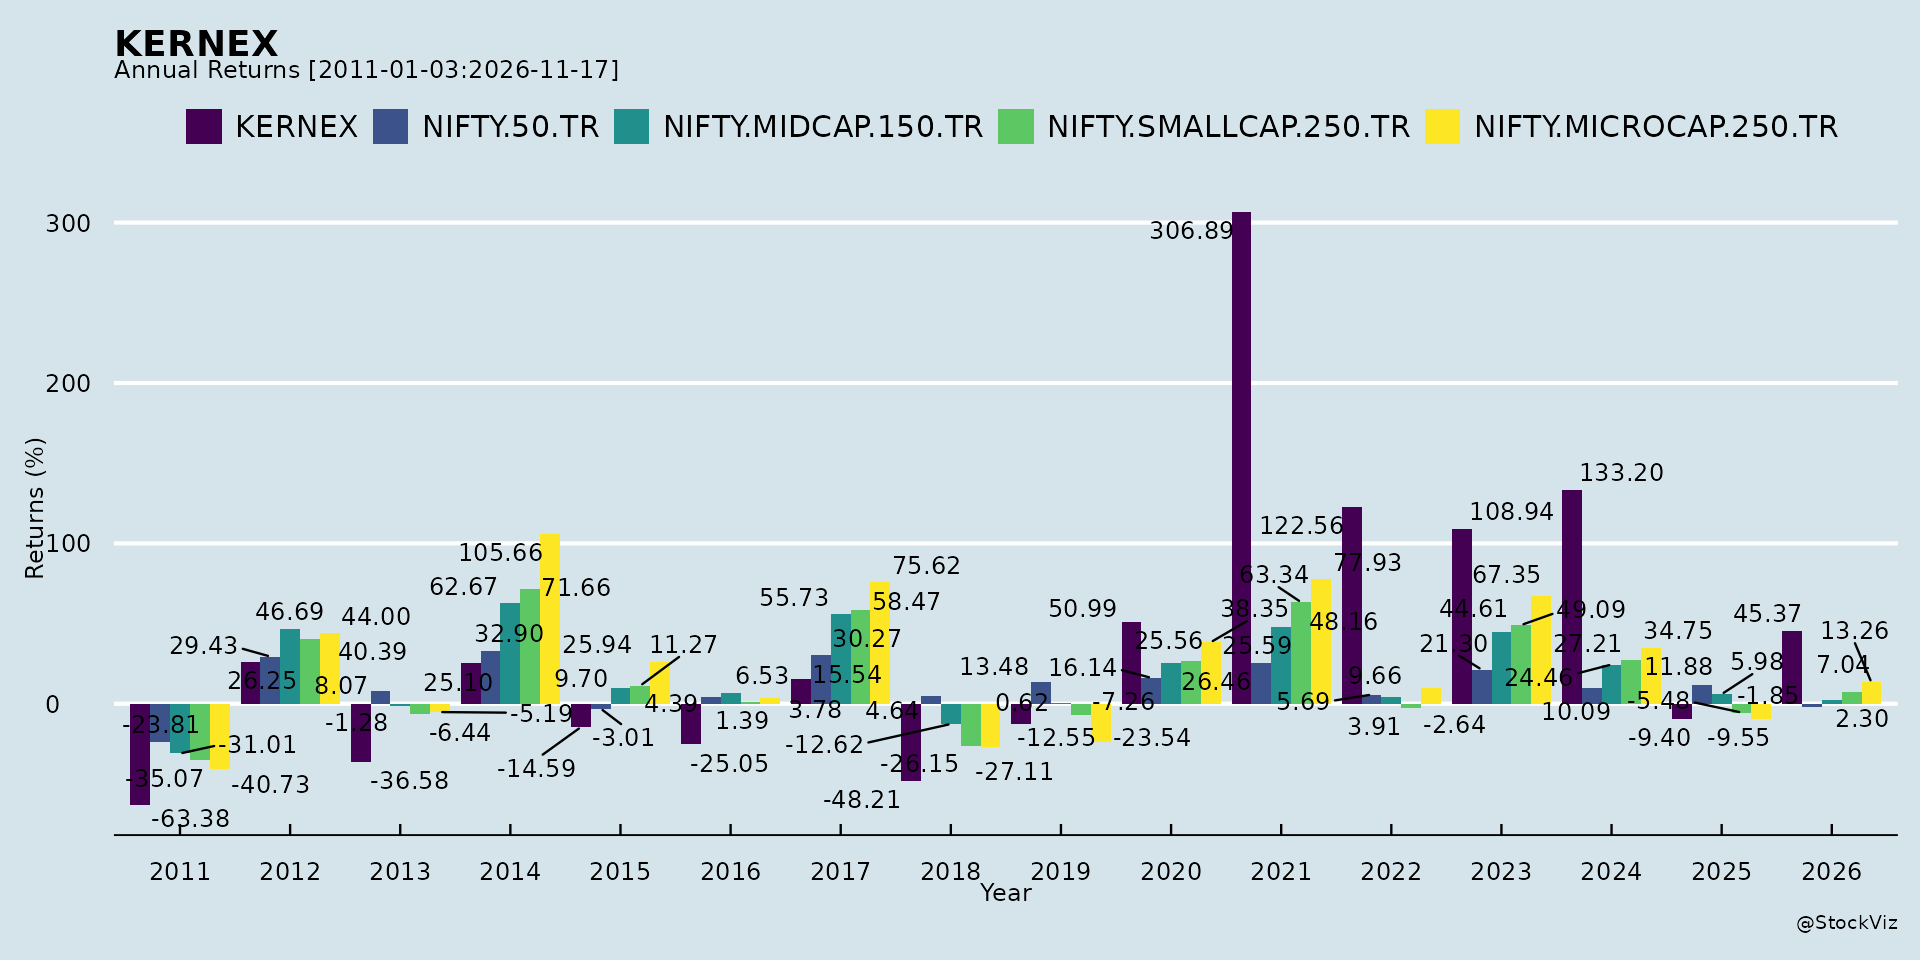
Annual Returns
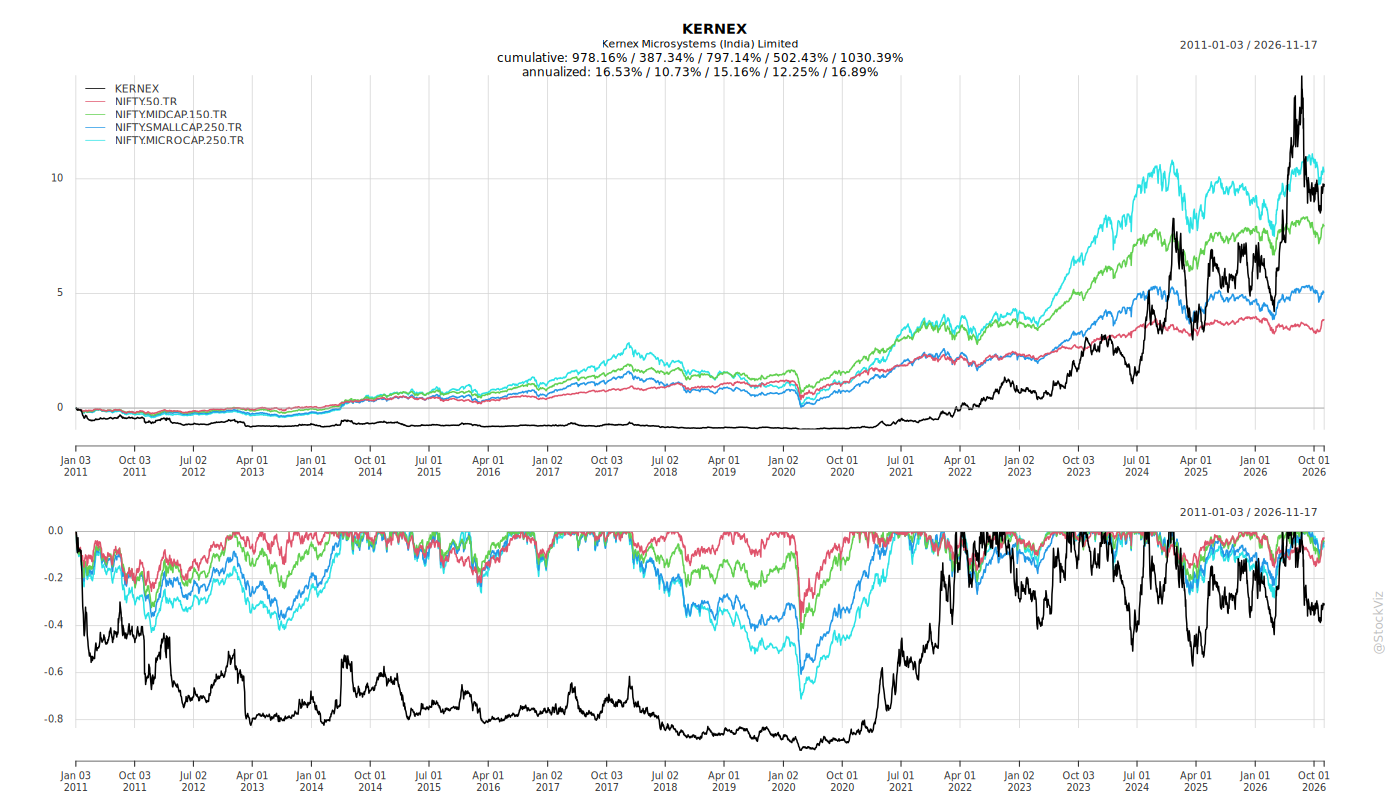
Cumulative Returns and Drawdowns
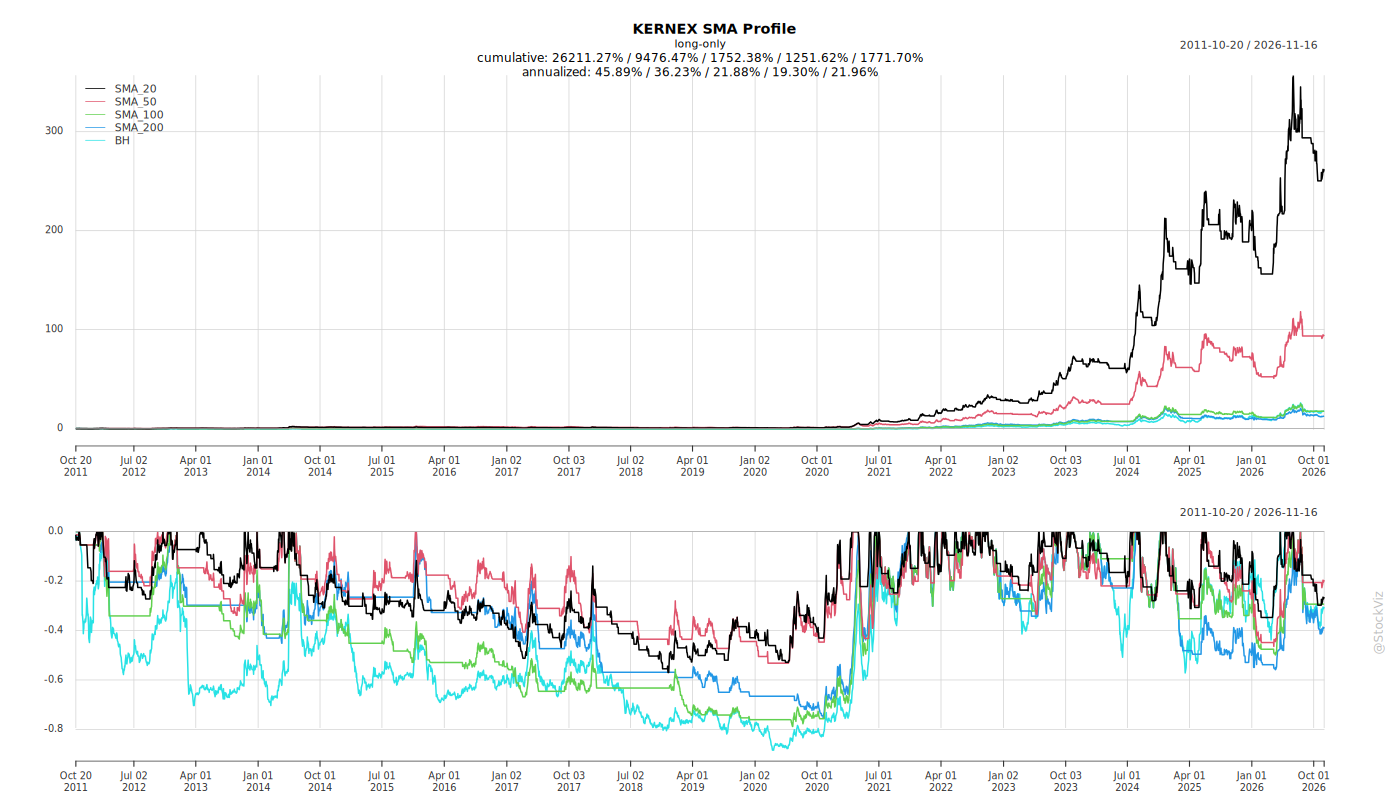
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
KERNEX Microsystems (India) Limited — Recent Corporate Announcements
1. Headwinds and Challenges
- Warranty obligations on delivered KAVACH and signalling systems. During the quarter ended 30 June 2026, the company recognised a provision of ₹30.05 crore towards warranty obligations on KAVACH and signalling systems delivered under its railway safety contracts, included under “Other Expenses.” This weighed on reported profitability for the quarter.
- Long-outstanding receivables and disputed bank guarantees. Trade receivables from customers of ₹422.73 lakhs have been outstanding for more than three years, against which an Expected Credit Loss provision of ₹334.59 lakhs has been carried. Separately, bank guarantees of ₹265.03 lakhs given to one customer are under arbitration/conciliation proceedings. The statutory auditors included an Emphasis of Matter on the recoverability of these financial assets; management believes they are fully recoverable and considers no further provision necessary at this stage.
- Dependence on a single major order for execution. The outstanding order book of ₹3,641 crore (including GST) is dominated by CLW as the major order under execution, against which supplies were completed to the extent of 45% as of 13 August 2026. Execution concentration in one contract is a structural feature of the current book.
- Forward-looking statement risk. The company’s own disclosures note that forward-looking statements involve known and unknown risks, uncertainties, and other factors that may cause actual results, financial condition, performance, or achievements to differ materially.
- Director remuneration in no-profit or inadequate-profit years. The company notes that in the event of no profits or inadequate profits in any financial year, the salary and perquisites of whole-time directors shall be paid as minimum remuneration in terms of Schedule V to the Companies Act, 2013.
2. Tailwinds and Growth Prospects
- Kavach rollout scale. The opportunity set cited includes Kavach rollout across 81,000 RKM of the Indian Railways network and 3,300 RKM of the Dedicated Freight Corridor, with a new EPC pipeline of 41,000 RKM for FY27–29.
- Regulatory mandate. 100% of newly manufactured rolling stock is required to be outfitted with ATP/KAVACH, and Indian Railways is adding 1,900+ new locomotives annually — both supporting sustained demand for on-board KAVACH systems.
- New order inflow. Integral Coach Factory, Chennai awarded the company an order valued at ₹31.87 crore (including GST) on 20 August 2026 for Supply, Installation, Testing and Commissioning of On-board KAVACH, involving upgradation from version 3.2 to 4.0 (hardware and software per RDSO Specification No. RDSO/SPN/196/2020, including warranty and CAMC). Execution is to be completed on or before 31 March 2027. The order is domestic, and no promoter/promoter group interest or related-party transaction is involved.
- Diversification into new business lines. Five new sub-sector business lines are cited: Yard Management, Intelligent Traffic Management, Data Centre & Disaster Recovery, Video Display & Simulators, and AI-BIM Digital Twin.
- International expansion. International expansion of Level Crossing Control Systems (LxCS) is identified as a growth avenue.
- Order book and pipeline projections. Total orders received are stated at ₹5,174 crore with a balance order book of ₹3,487 crore. Future Kavach projections estimate a potential project intake of ₹5,420 crore and a total executable base (excluding AMC revenue) of ₹8,907 crore from FY27 to FY29, with new Kavach orders projected at ₹1,250 crore for FY28 and ₹1,750 crore for FY29.
- Financial capacity. Total working capital limits of ₹655 crore are maintained, with ₹281 crore of undrawn headroom.
- Management’s stated expectation. Management expects a substantial increase in production, leading to good improvement in operating margins, and states that operations are being scaled up to increase revenues.
3. Key Risks
- Execution and receivable recovery risk. The receivables outstanding more than three years and the bank guarantees under arbitration/conciliation represent unresolved collection risk; the auditors’ Emphasis of Matter flags that the final recoverable amounts may vary.
- Warranty and product-performance risk. The ₹30.05 crore warranty provision on delivered KAVACH and signalling systems illustrates the cost exposure attached to deployed railway safety contracts.
- Concentration risk. The order book’s reliance on CLW as the major order under execution means slippage or delay in that contract would materially affect revenue recognition.
- Forward-looking uncertainty. Projected Kavach intake, executable base, and new order figures for FY27–FY29 are subject to the known and unknown risks and uncertainties the company itself identifies.
- Remuneration floor. The Schedule V minimum remuneration provision means director compensation may not flex fully with profitability in weak years.
4. Management Guidance Versus Observed Business Performance
- Guidance: Management expects a substantial increase in production, leading to good improvement in operating margins, with operations being scaled up to increase revenues.
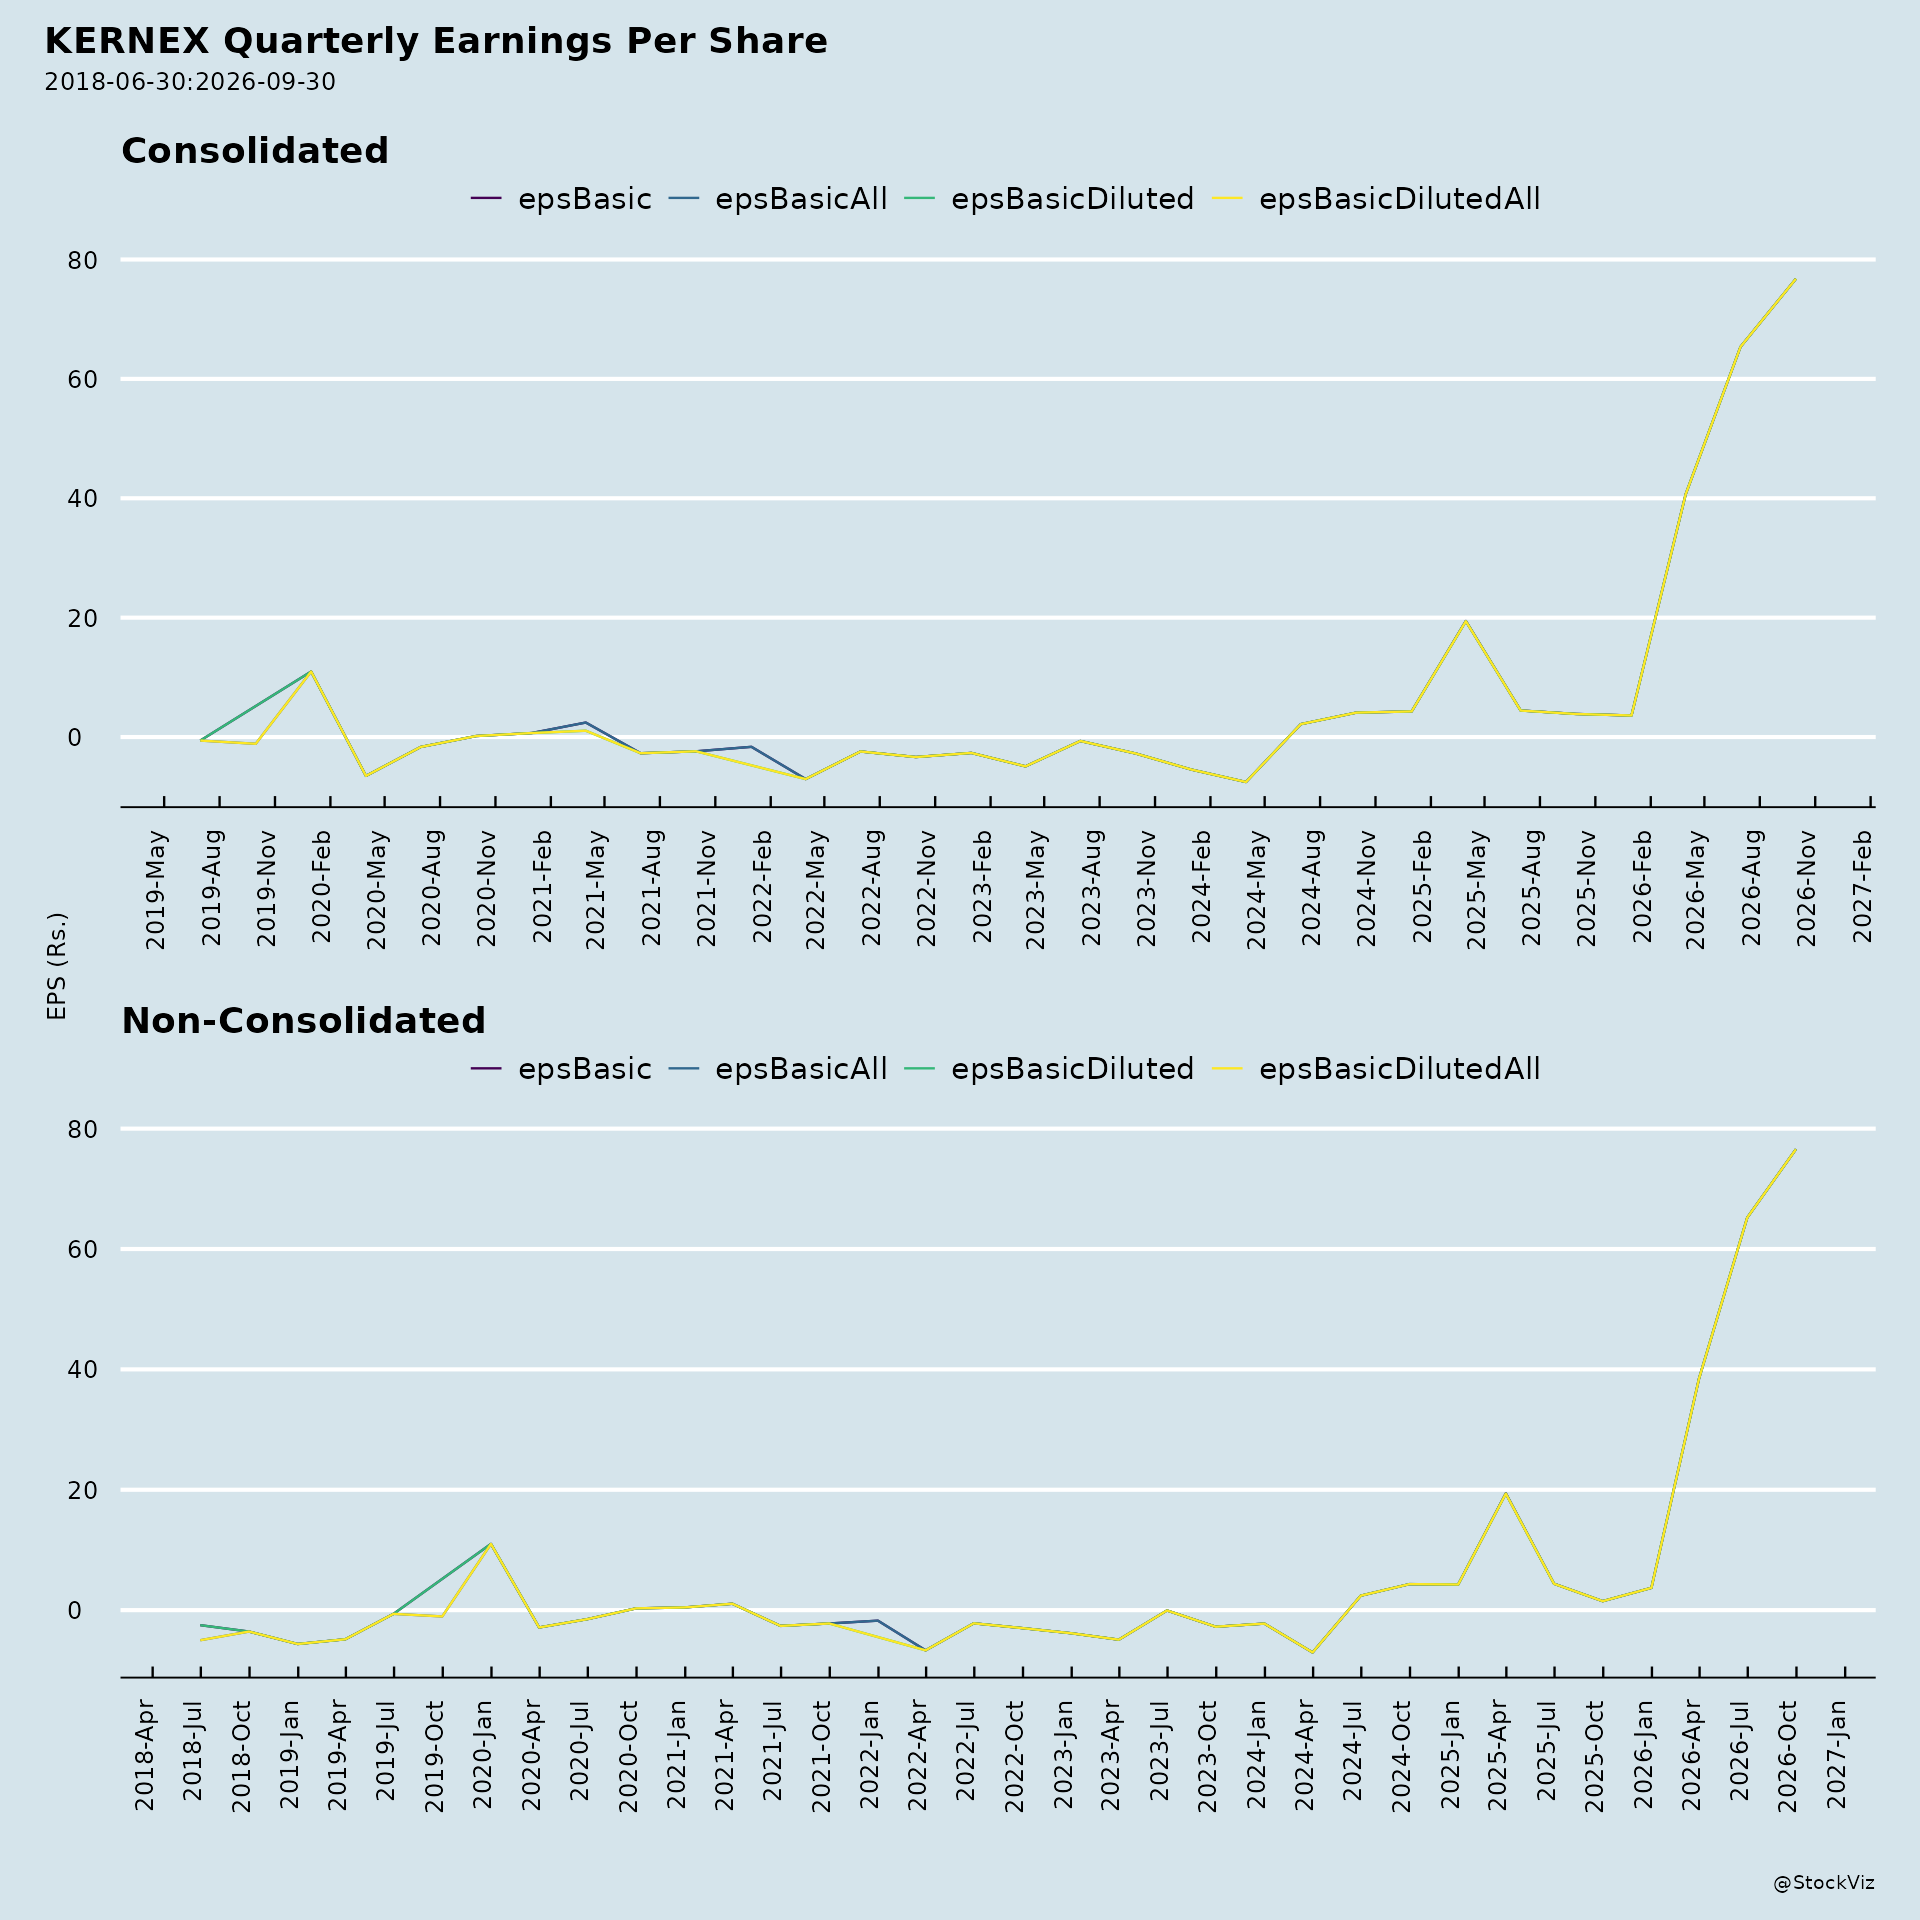
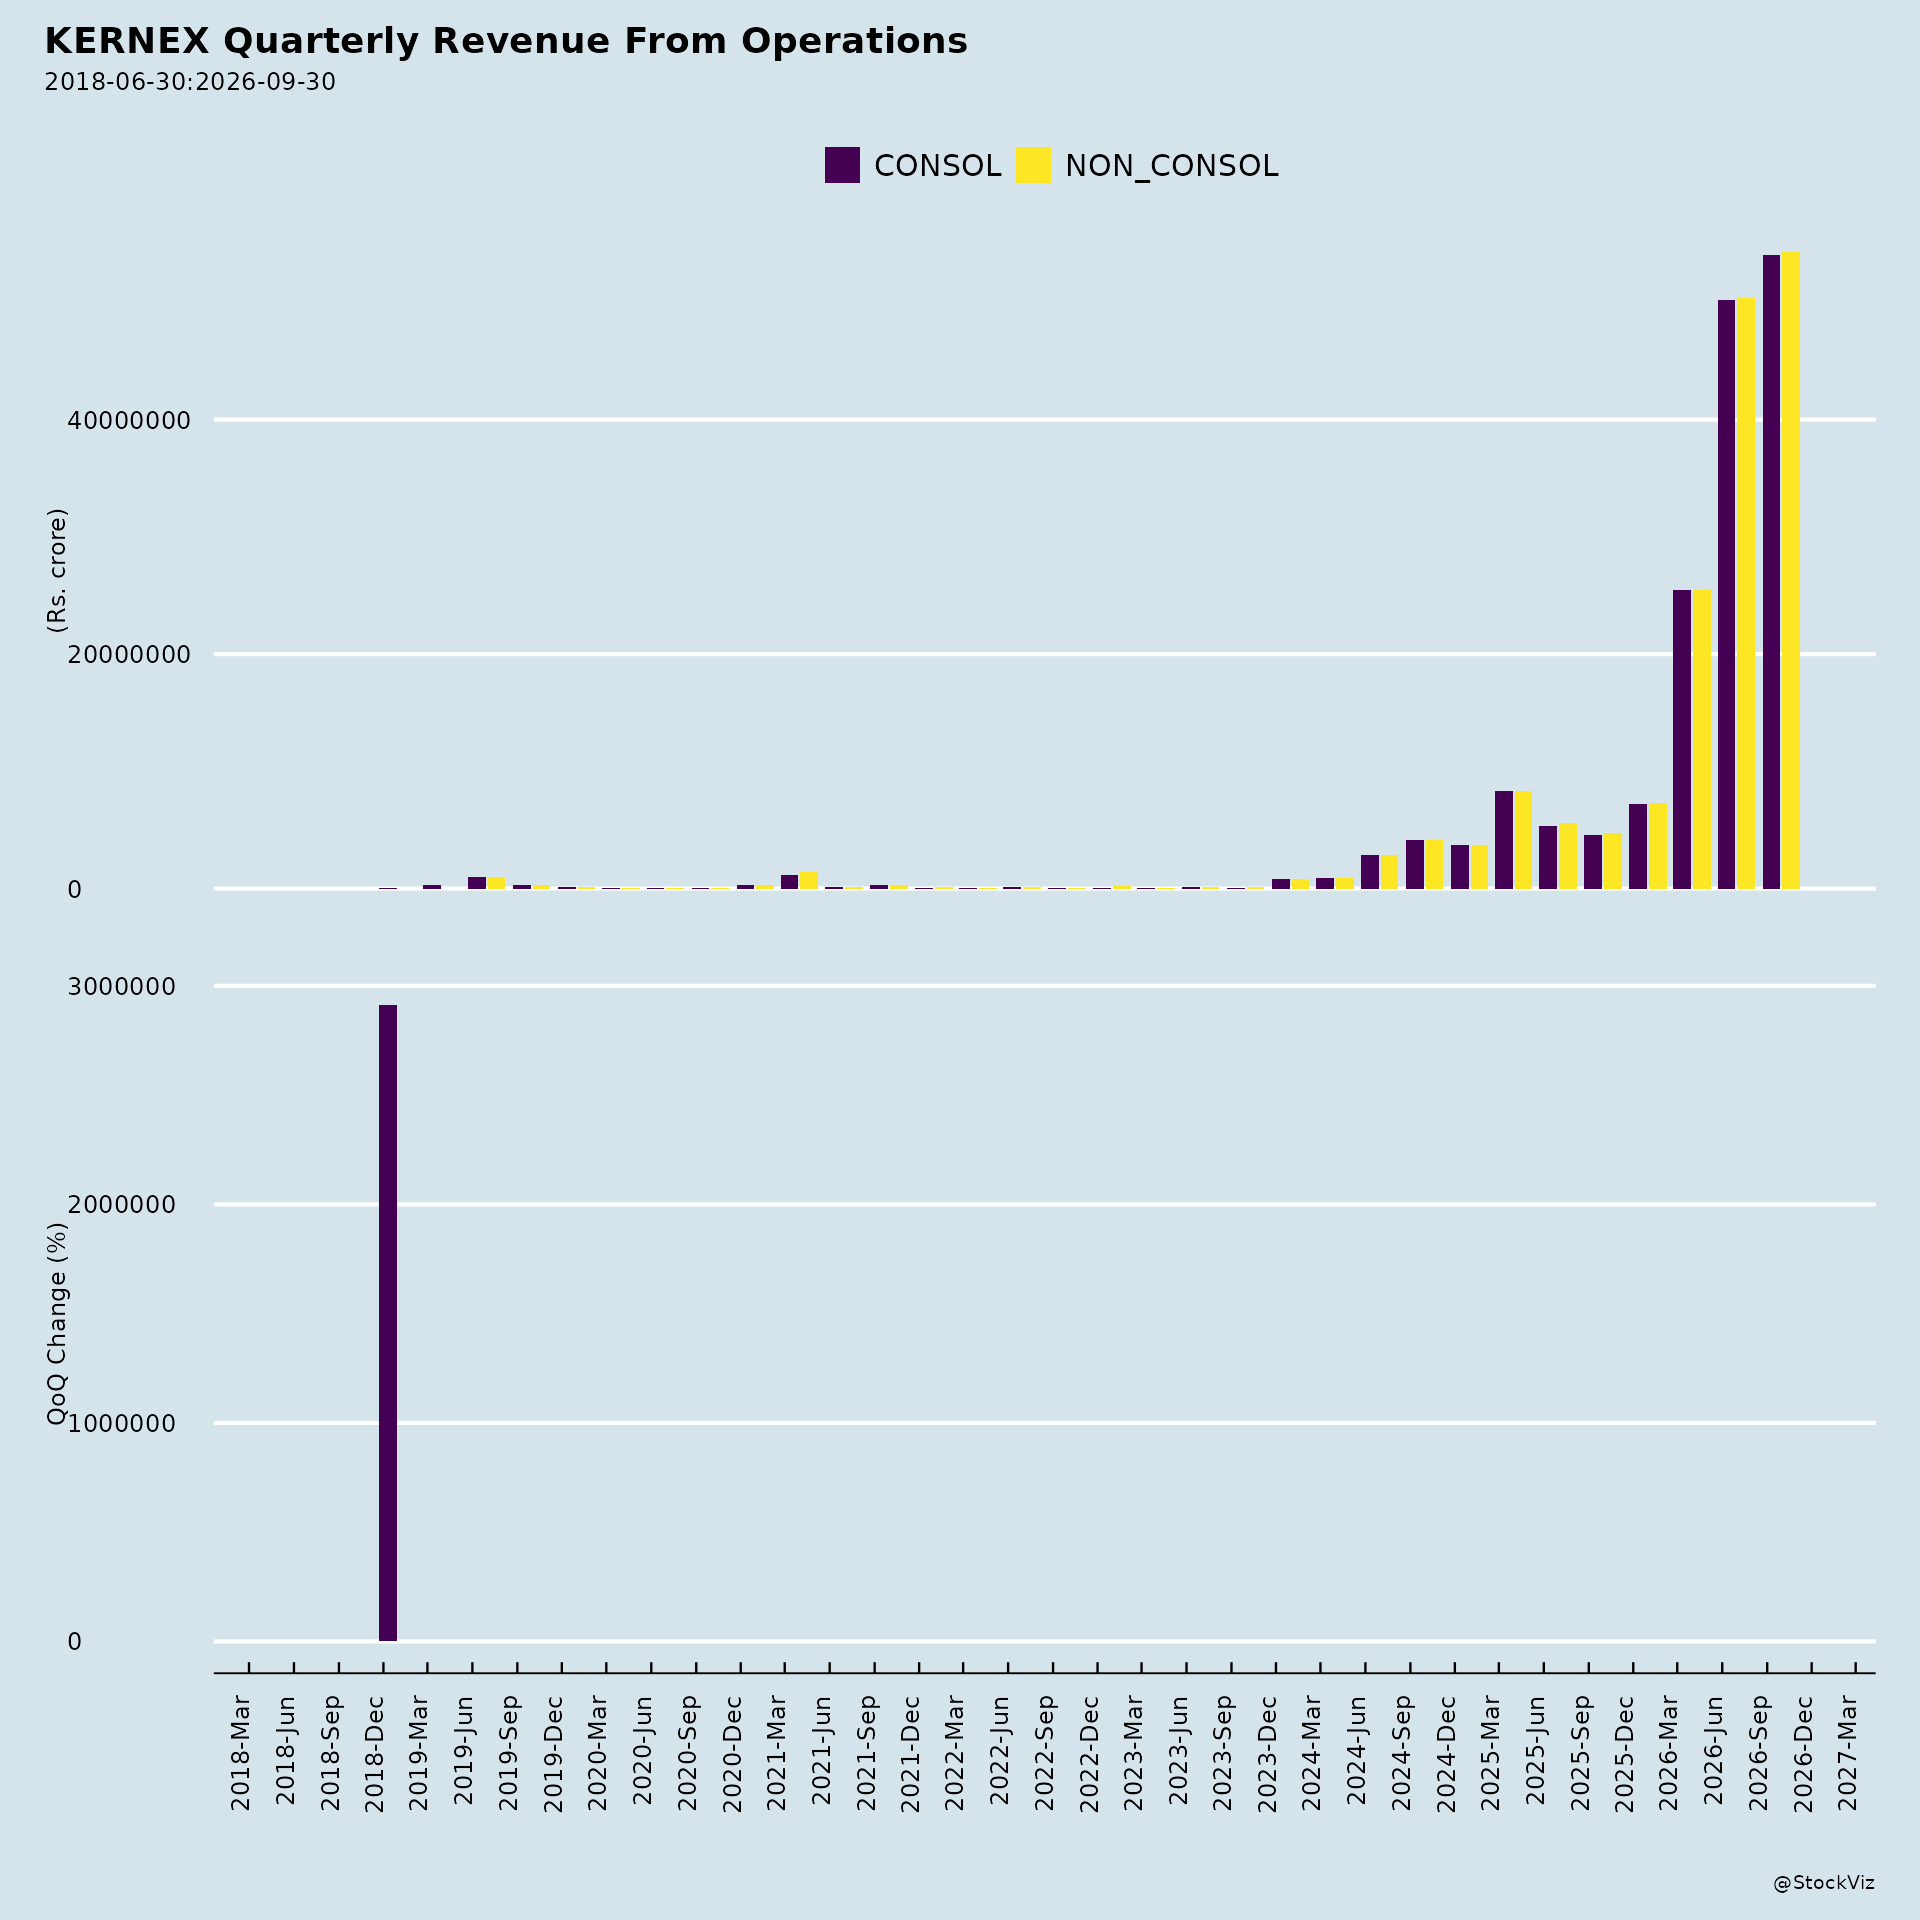
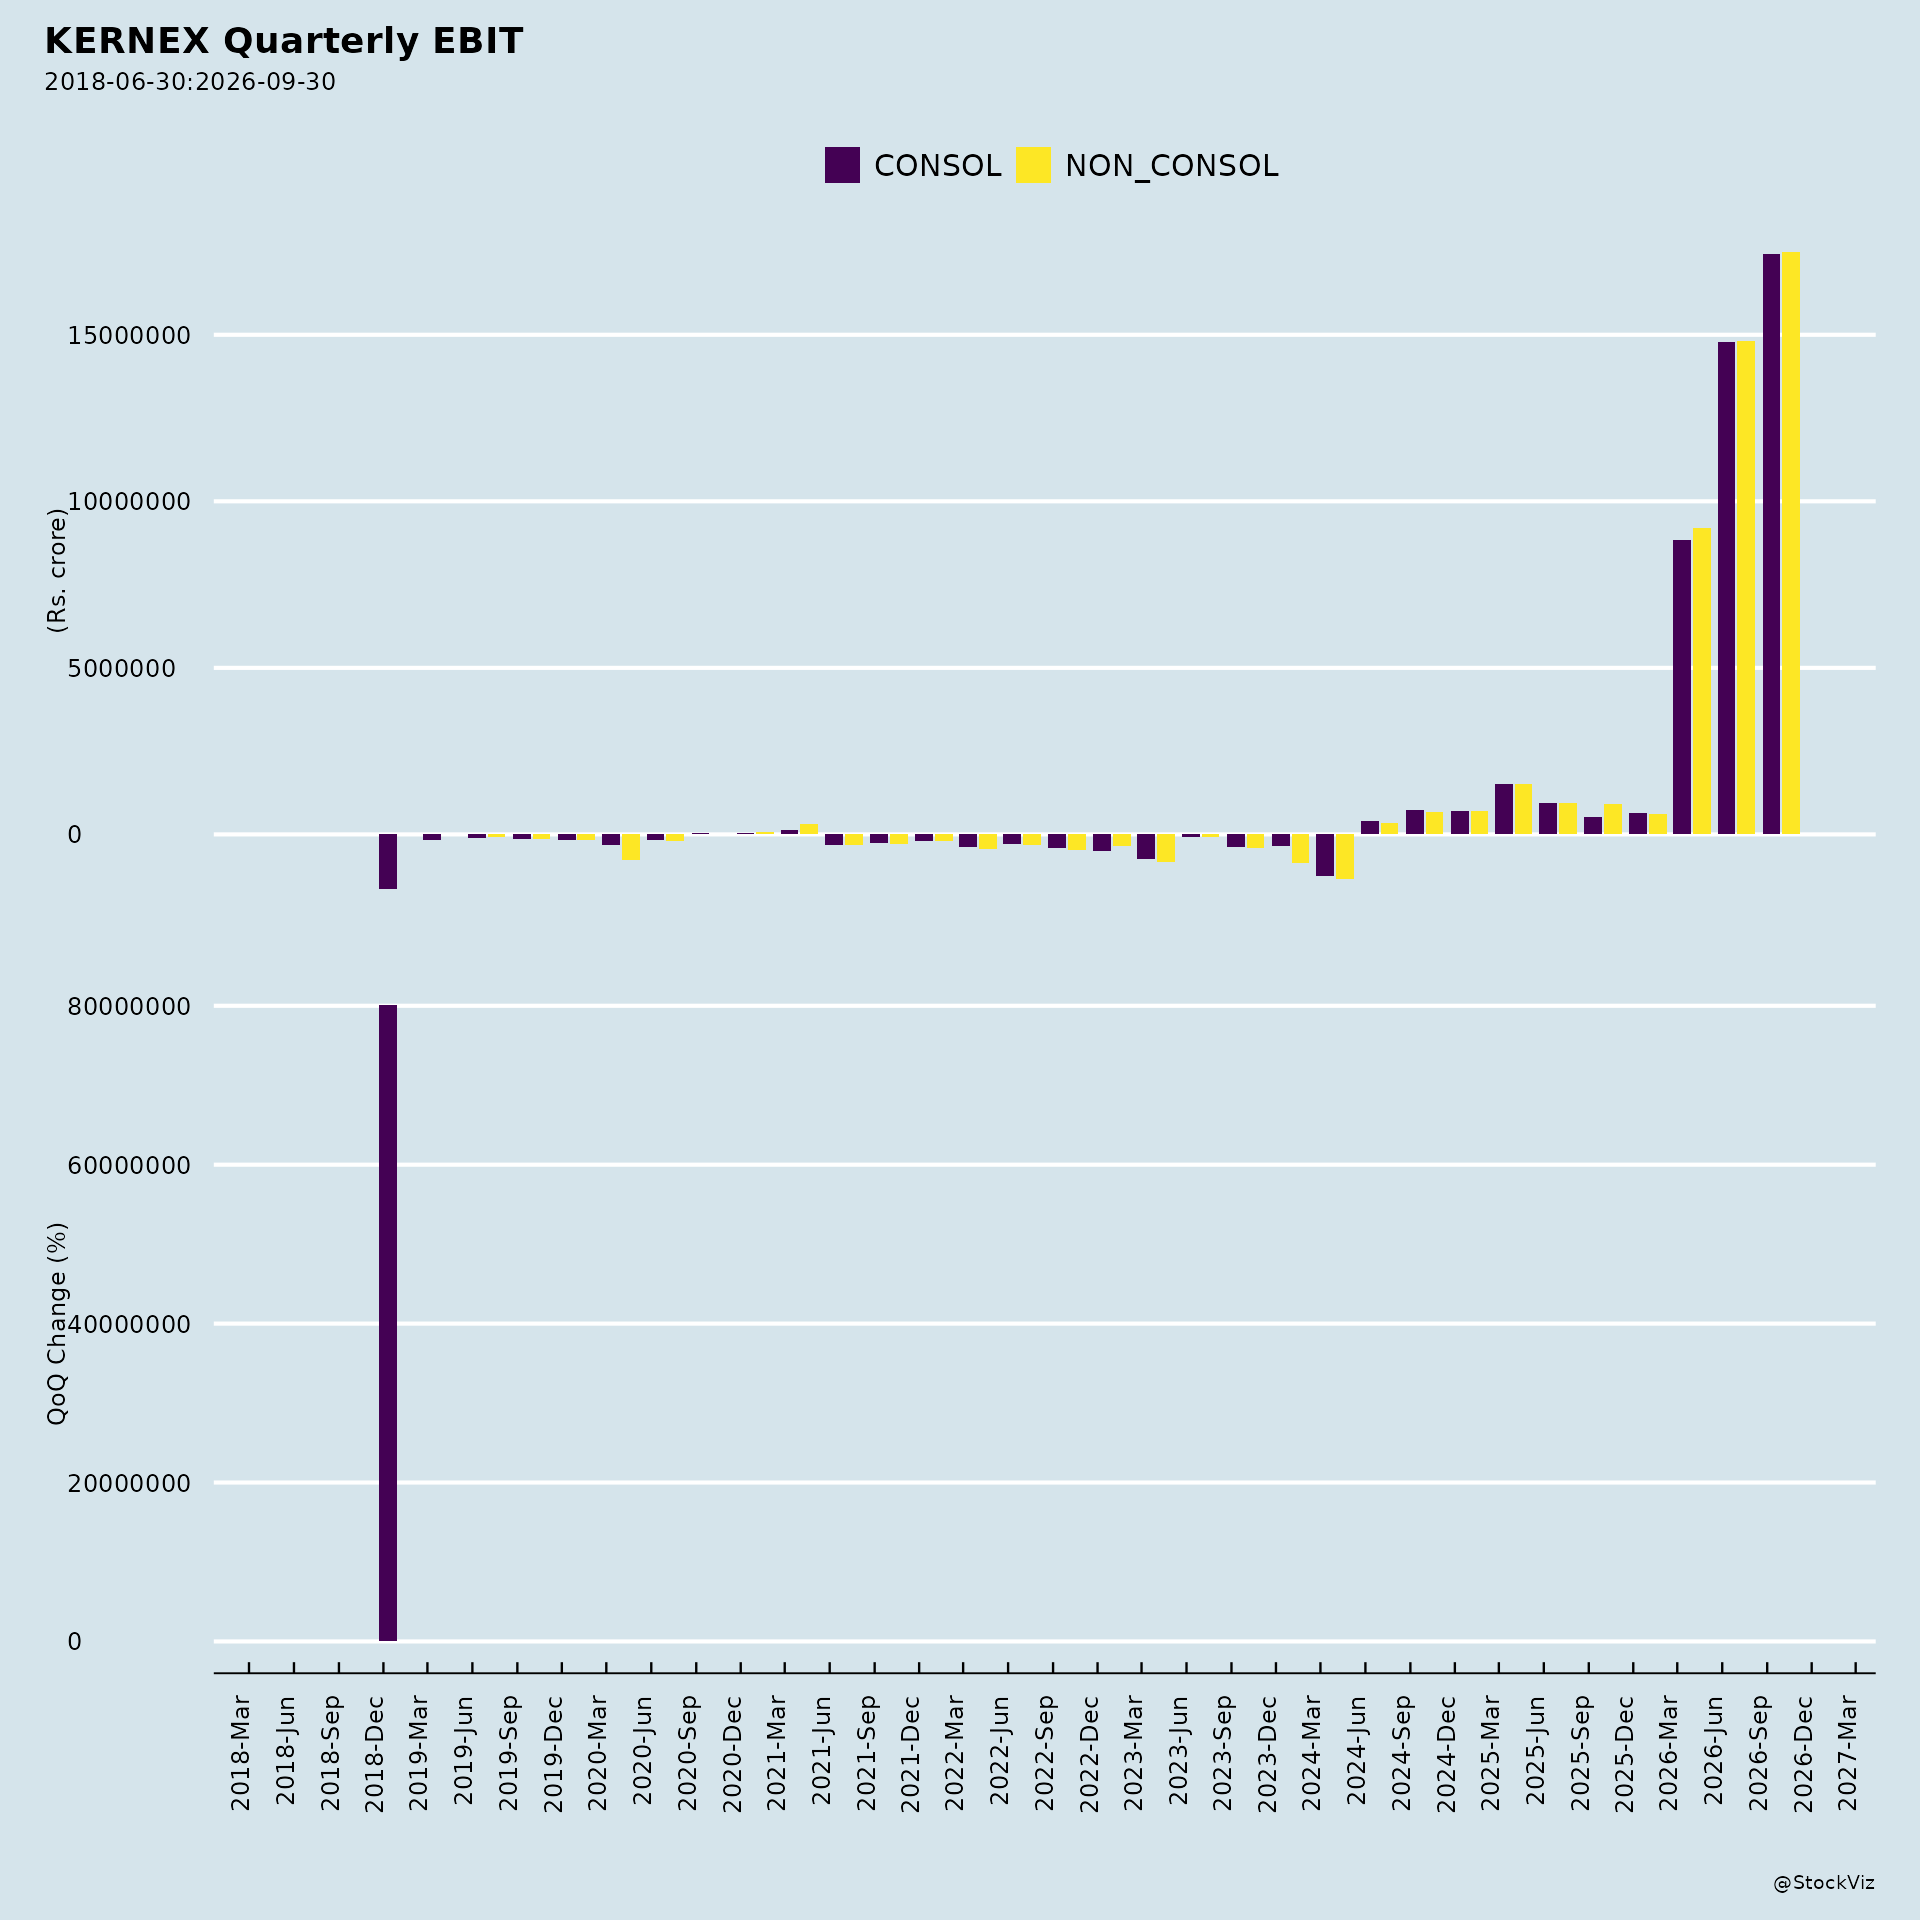
- Observed performance: For the quarter ended 30 June 2026, consolidated revenue from operations was ₹50,358.23 lakhs, compared with ₹25,457.69 lakhs in the preceding quarter and ₹5,592.99 lakhs in the corresponding quarter ended 30 June 2025. Consolidated profit before tax was ₹14,813.71 lakhs, against ₹9,211.88 lakhs in the preceding quarter and ₹955.18 lakhs a year earlier. Consolidated profit for the period was ₹10,984.57 lakhs, versus ₹6,825.09 lakhs in the preceding quarter and ₹741.21 lakhs in the prior-year quarter. Standalone revenue from operations was ₹50,203.27 lakhs, with standalone profit for the period of ₹10,957.16 lakhs. These results are consistent with the scale-up in revenue and margins that management describes, though the quarter also absorbed the ₹30.05 crore warranty provision.
- Guidance: The company points to a large Kavach opportunity and a substantial executable base over FY27–FY29.
- Observed performance: The order book stood at ₹3,641 crore (including GST) as at the reporting date, with CLW supplies 45% complete as of 13 August 2026. The ICF order of ₹31.87 crore awarded on 20 August 2026, to be executed by 31 March 2027, is a concrete addition to the on-board KAVACH upgrade pipeline. The company also formed a joint venture with BHEPL on 7 March 2026, which had not commenced operations as at 30 June 2026.
- Guidance: Management expects operating leverage from higher production.
- Observed performance: Finance costs rose to ₹1,322.77 lakhs in the June 2026 quarter from ₹1,178.91 lakhs in the preceding quarter and ₹255.38 lakhs in the prior-year quarter, indicating that the scale-up is being accompanied by higher borrowing costs. Employee benefits expense also rose sequentially to ₹1,393.29 lakhs from ₹944.17 lakhs.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.