JSWSTEEL
Equity Metrics
November 18, 2026
JSW Steel Limited
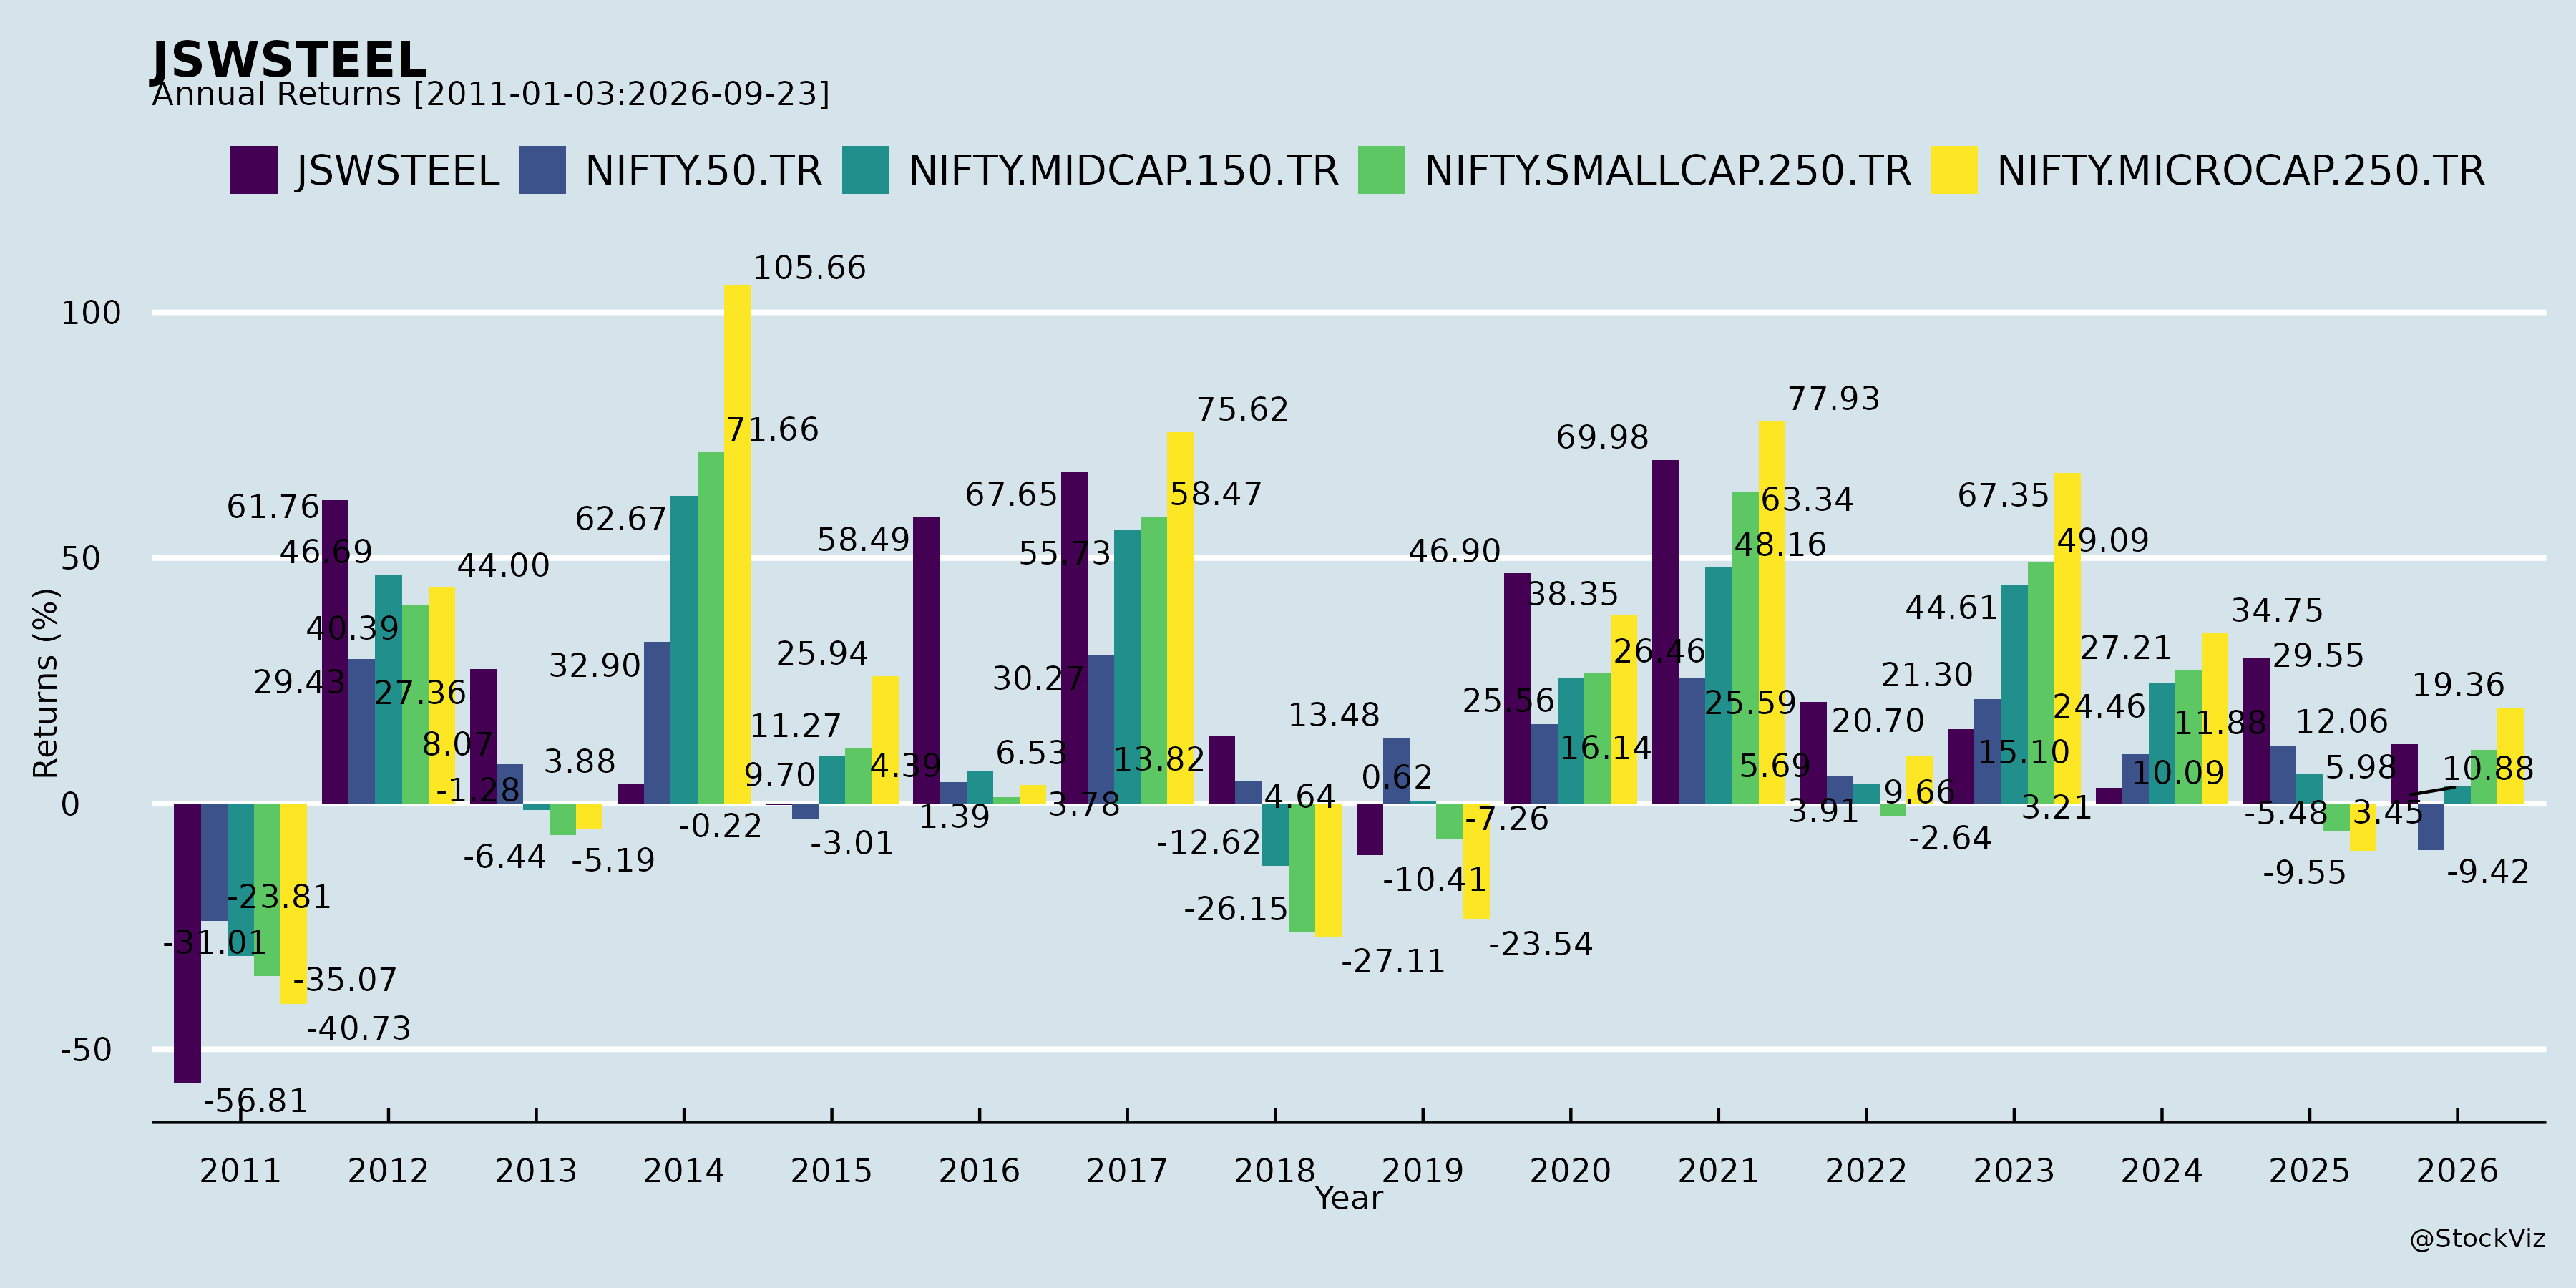
Annual Returns
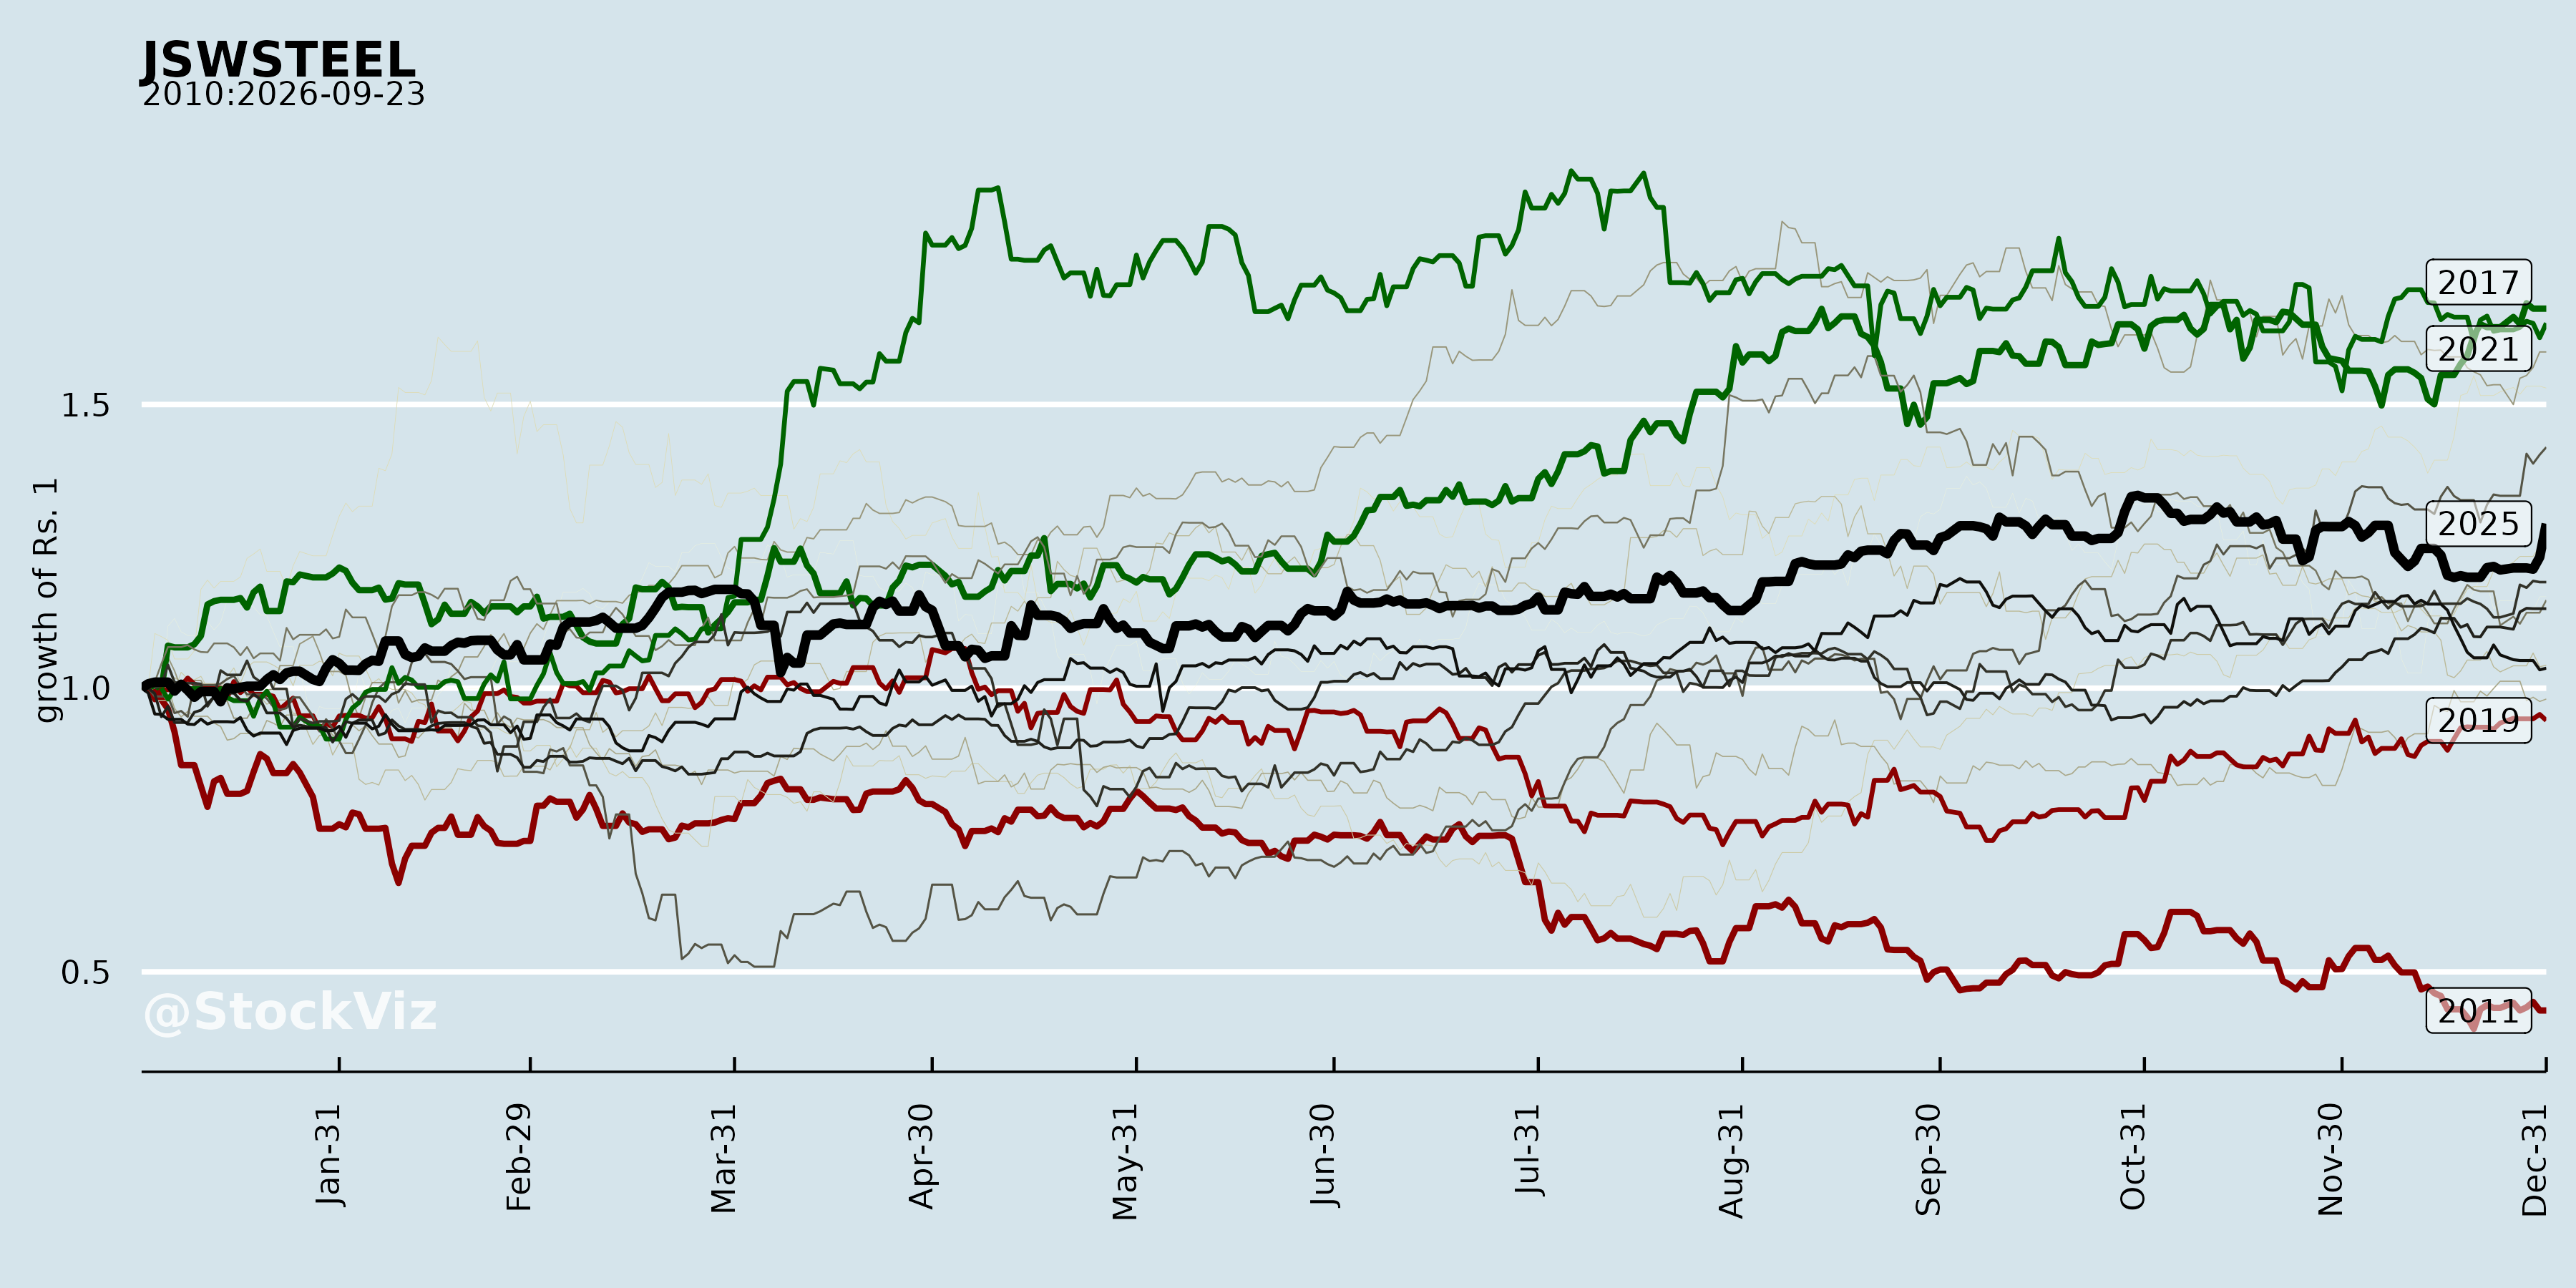
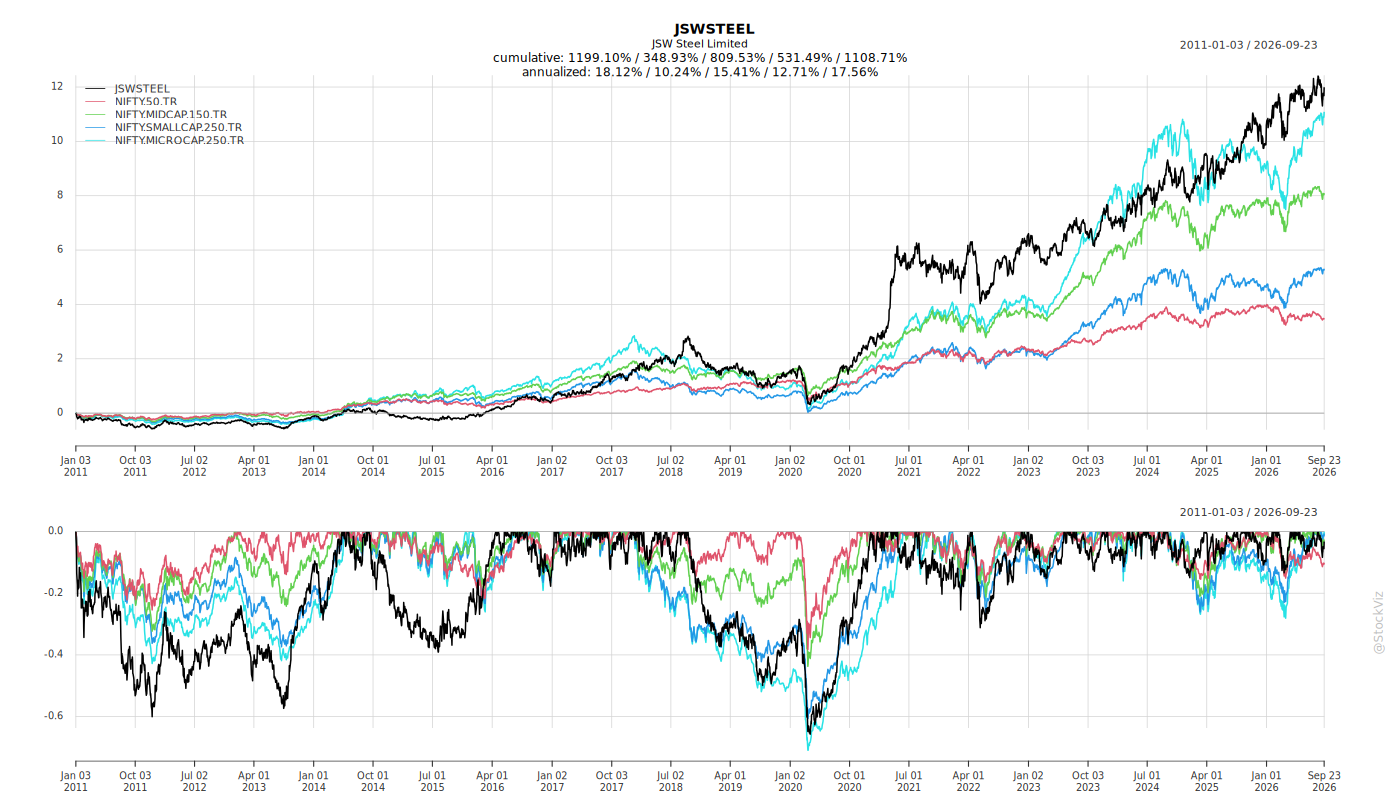
Cumulative Returns and Drawdowns
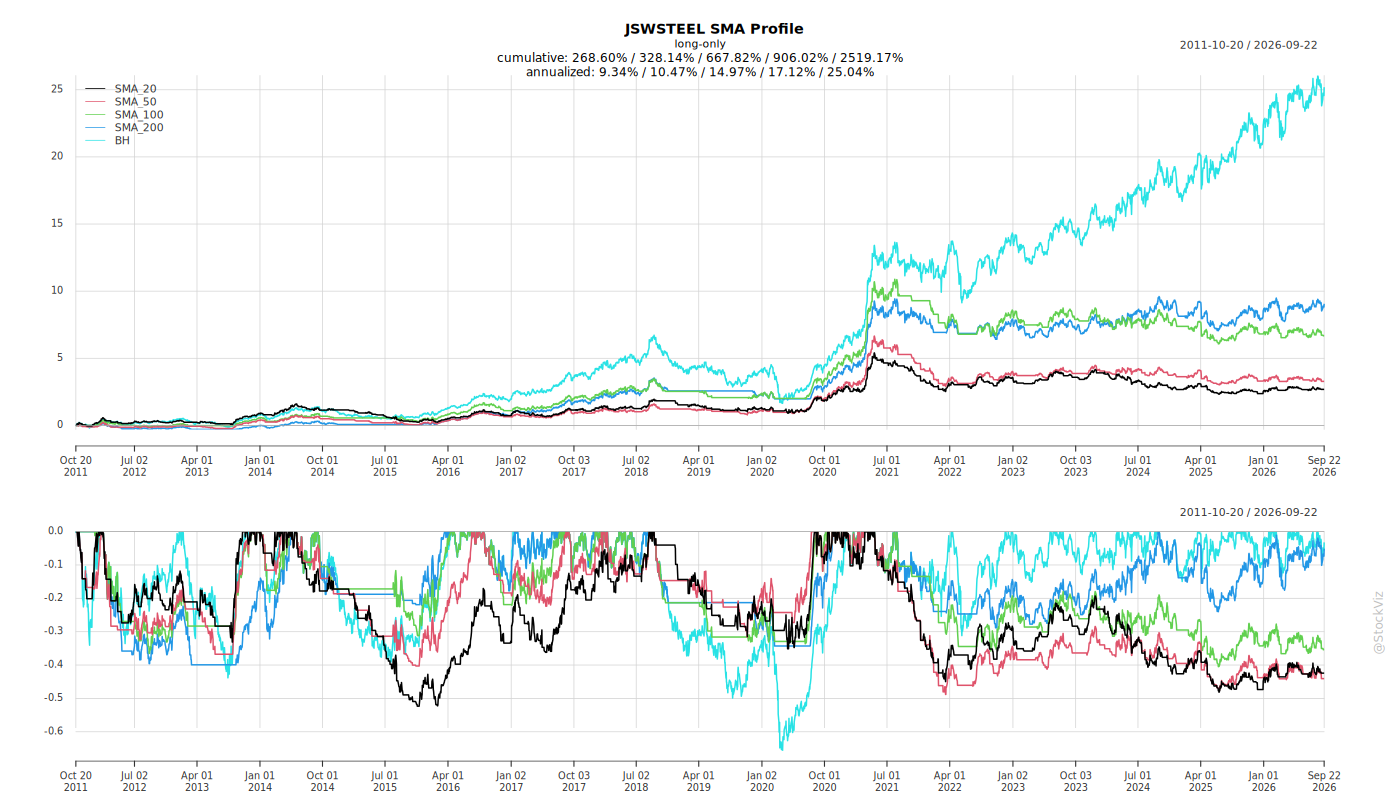
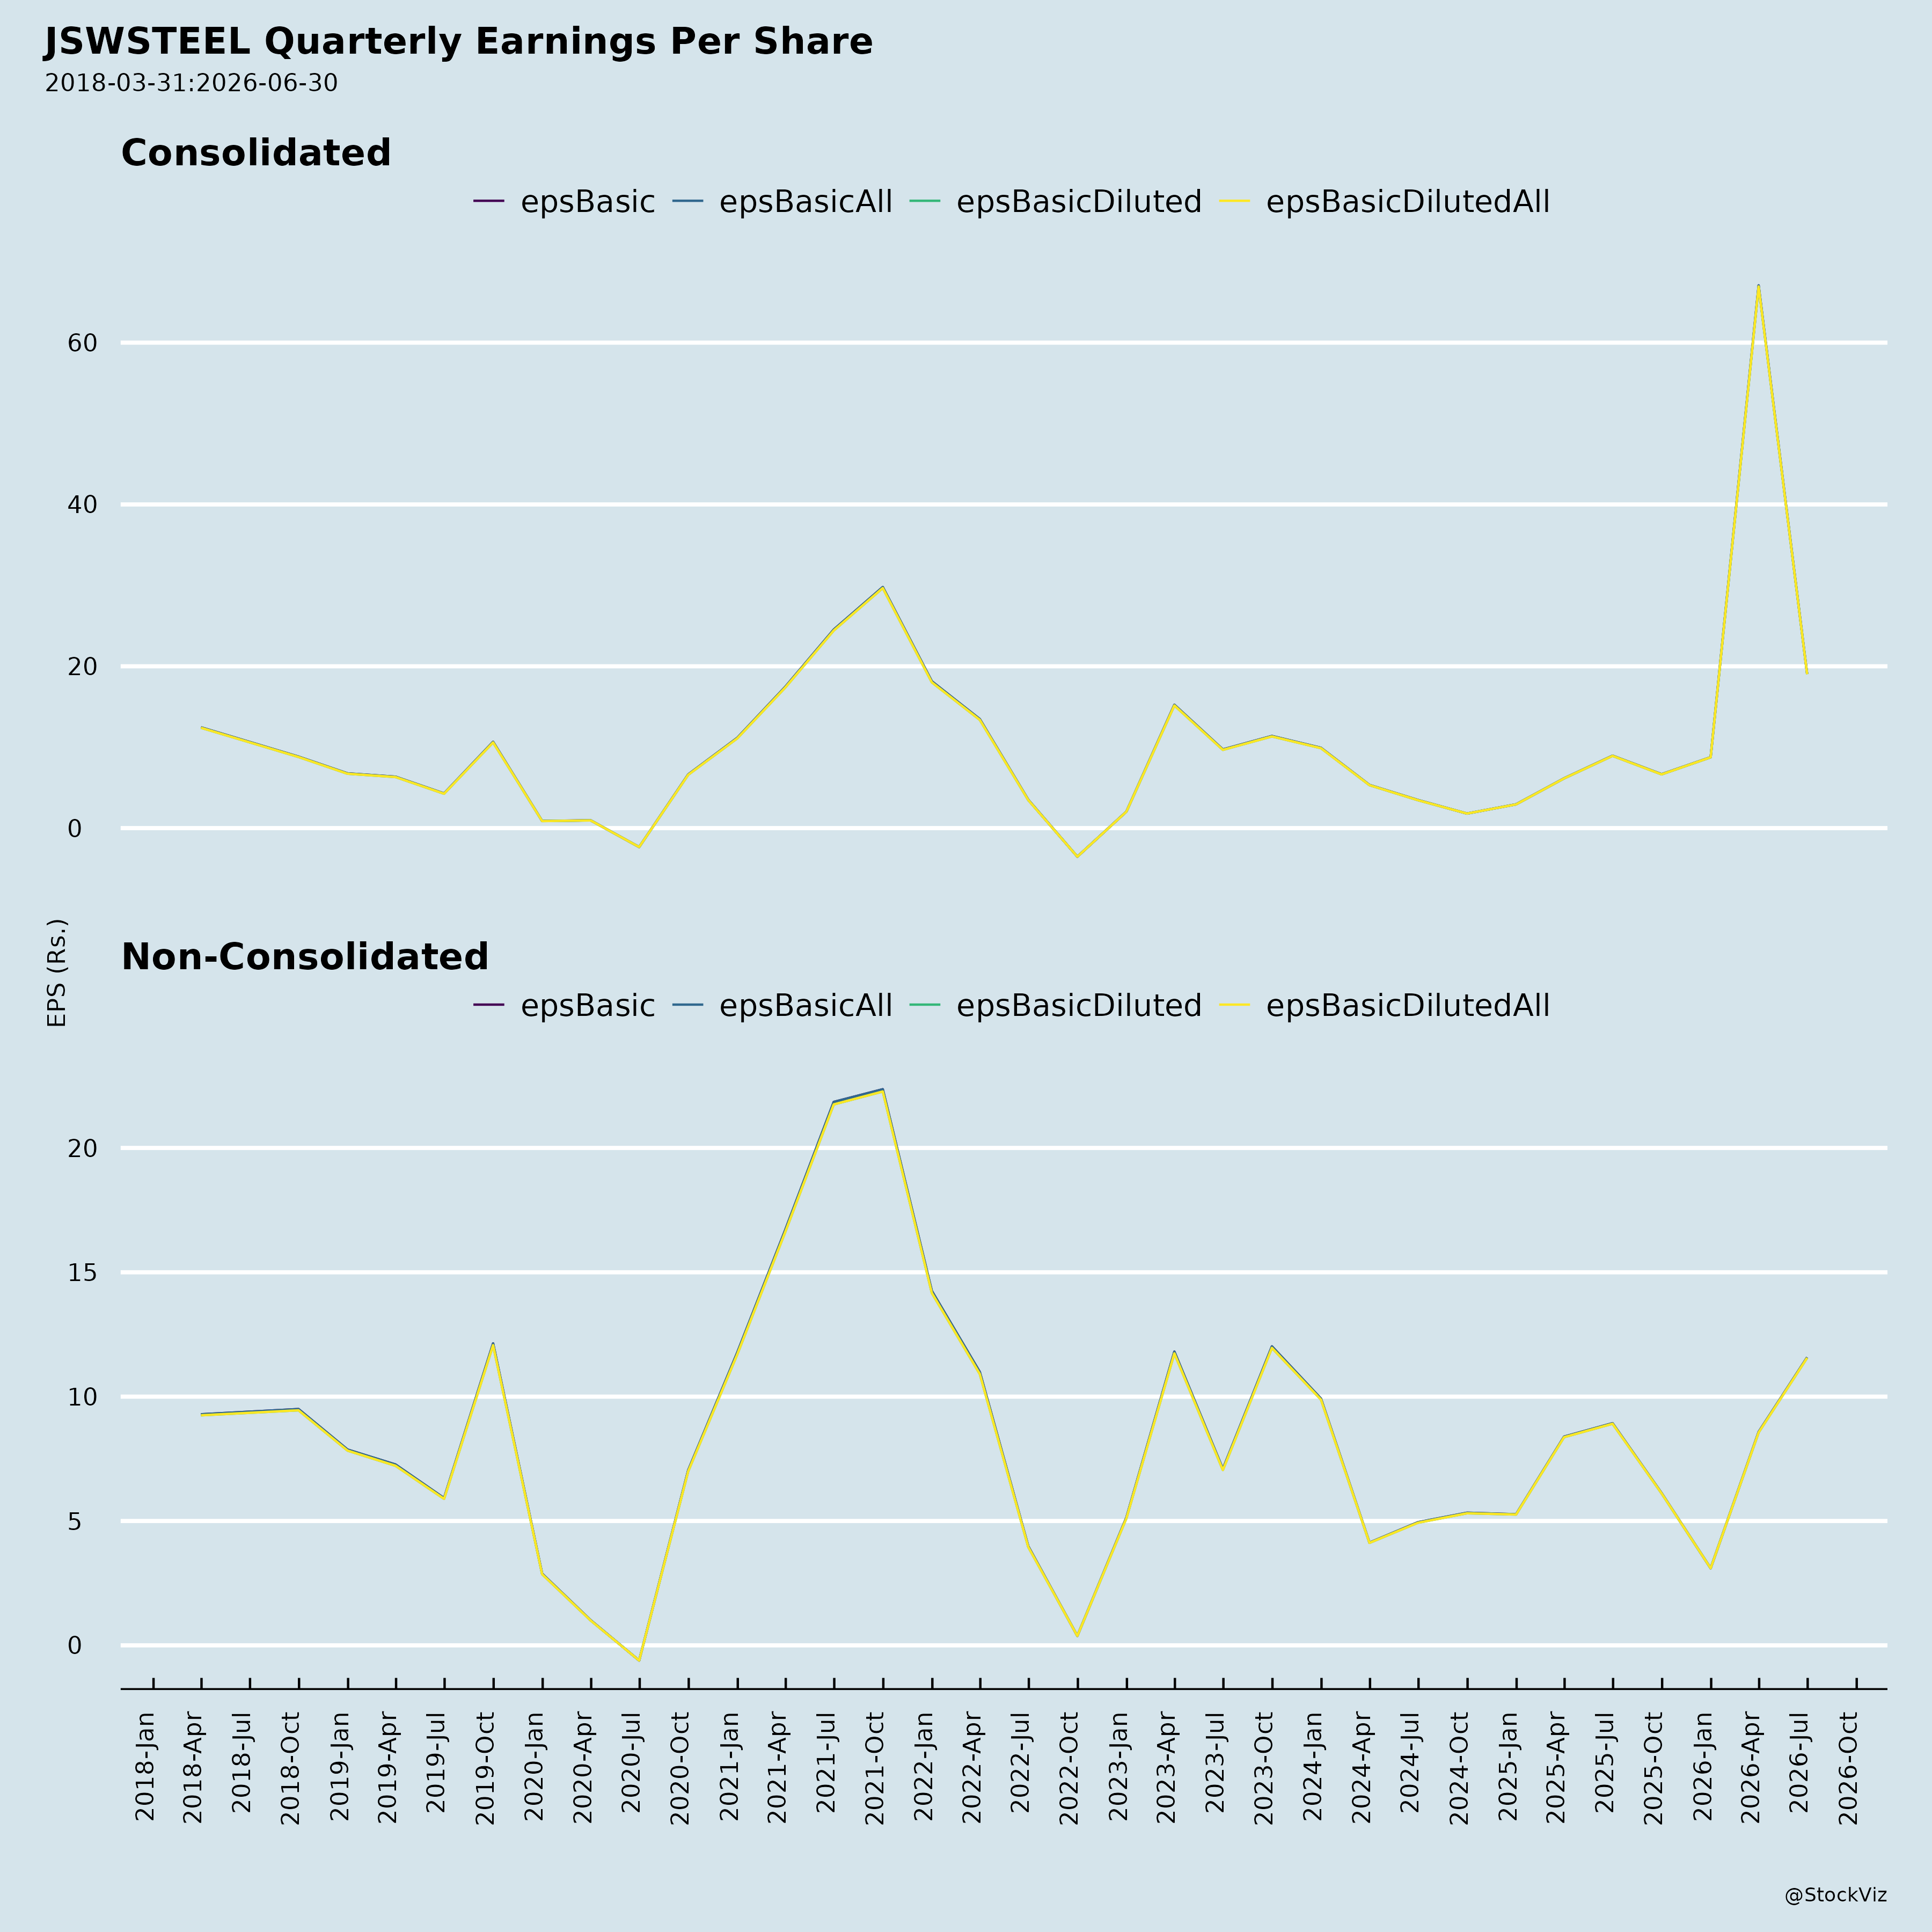
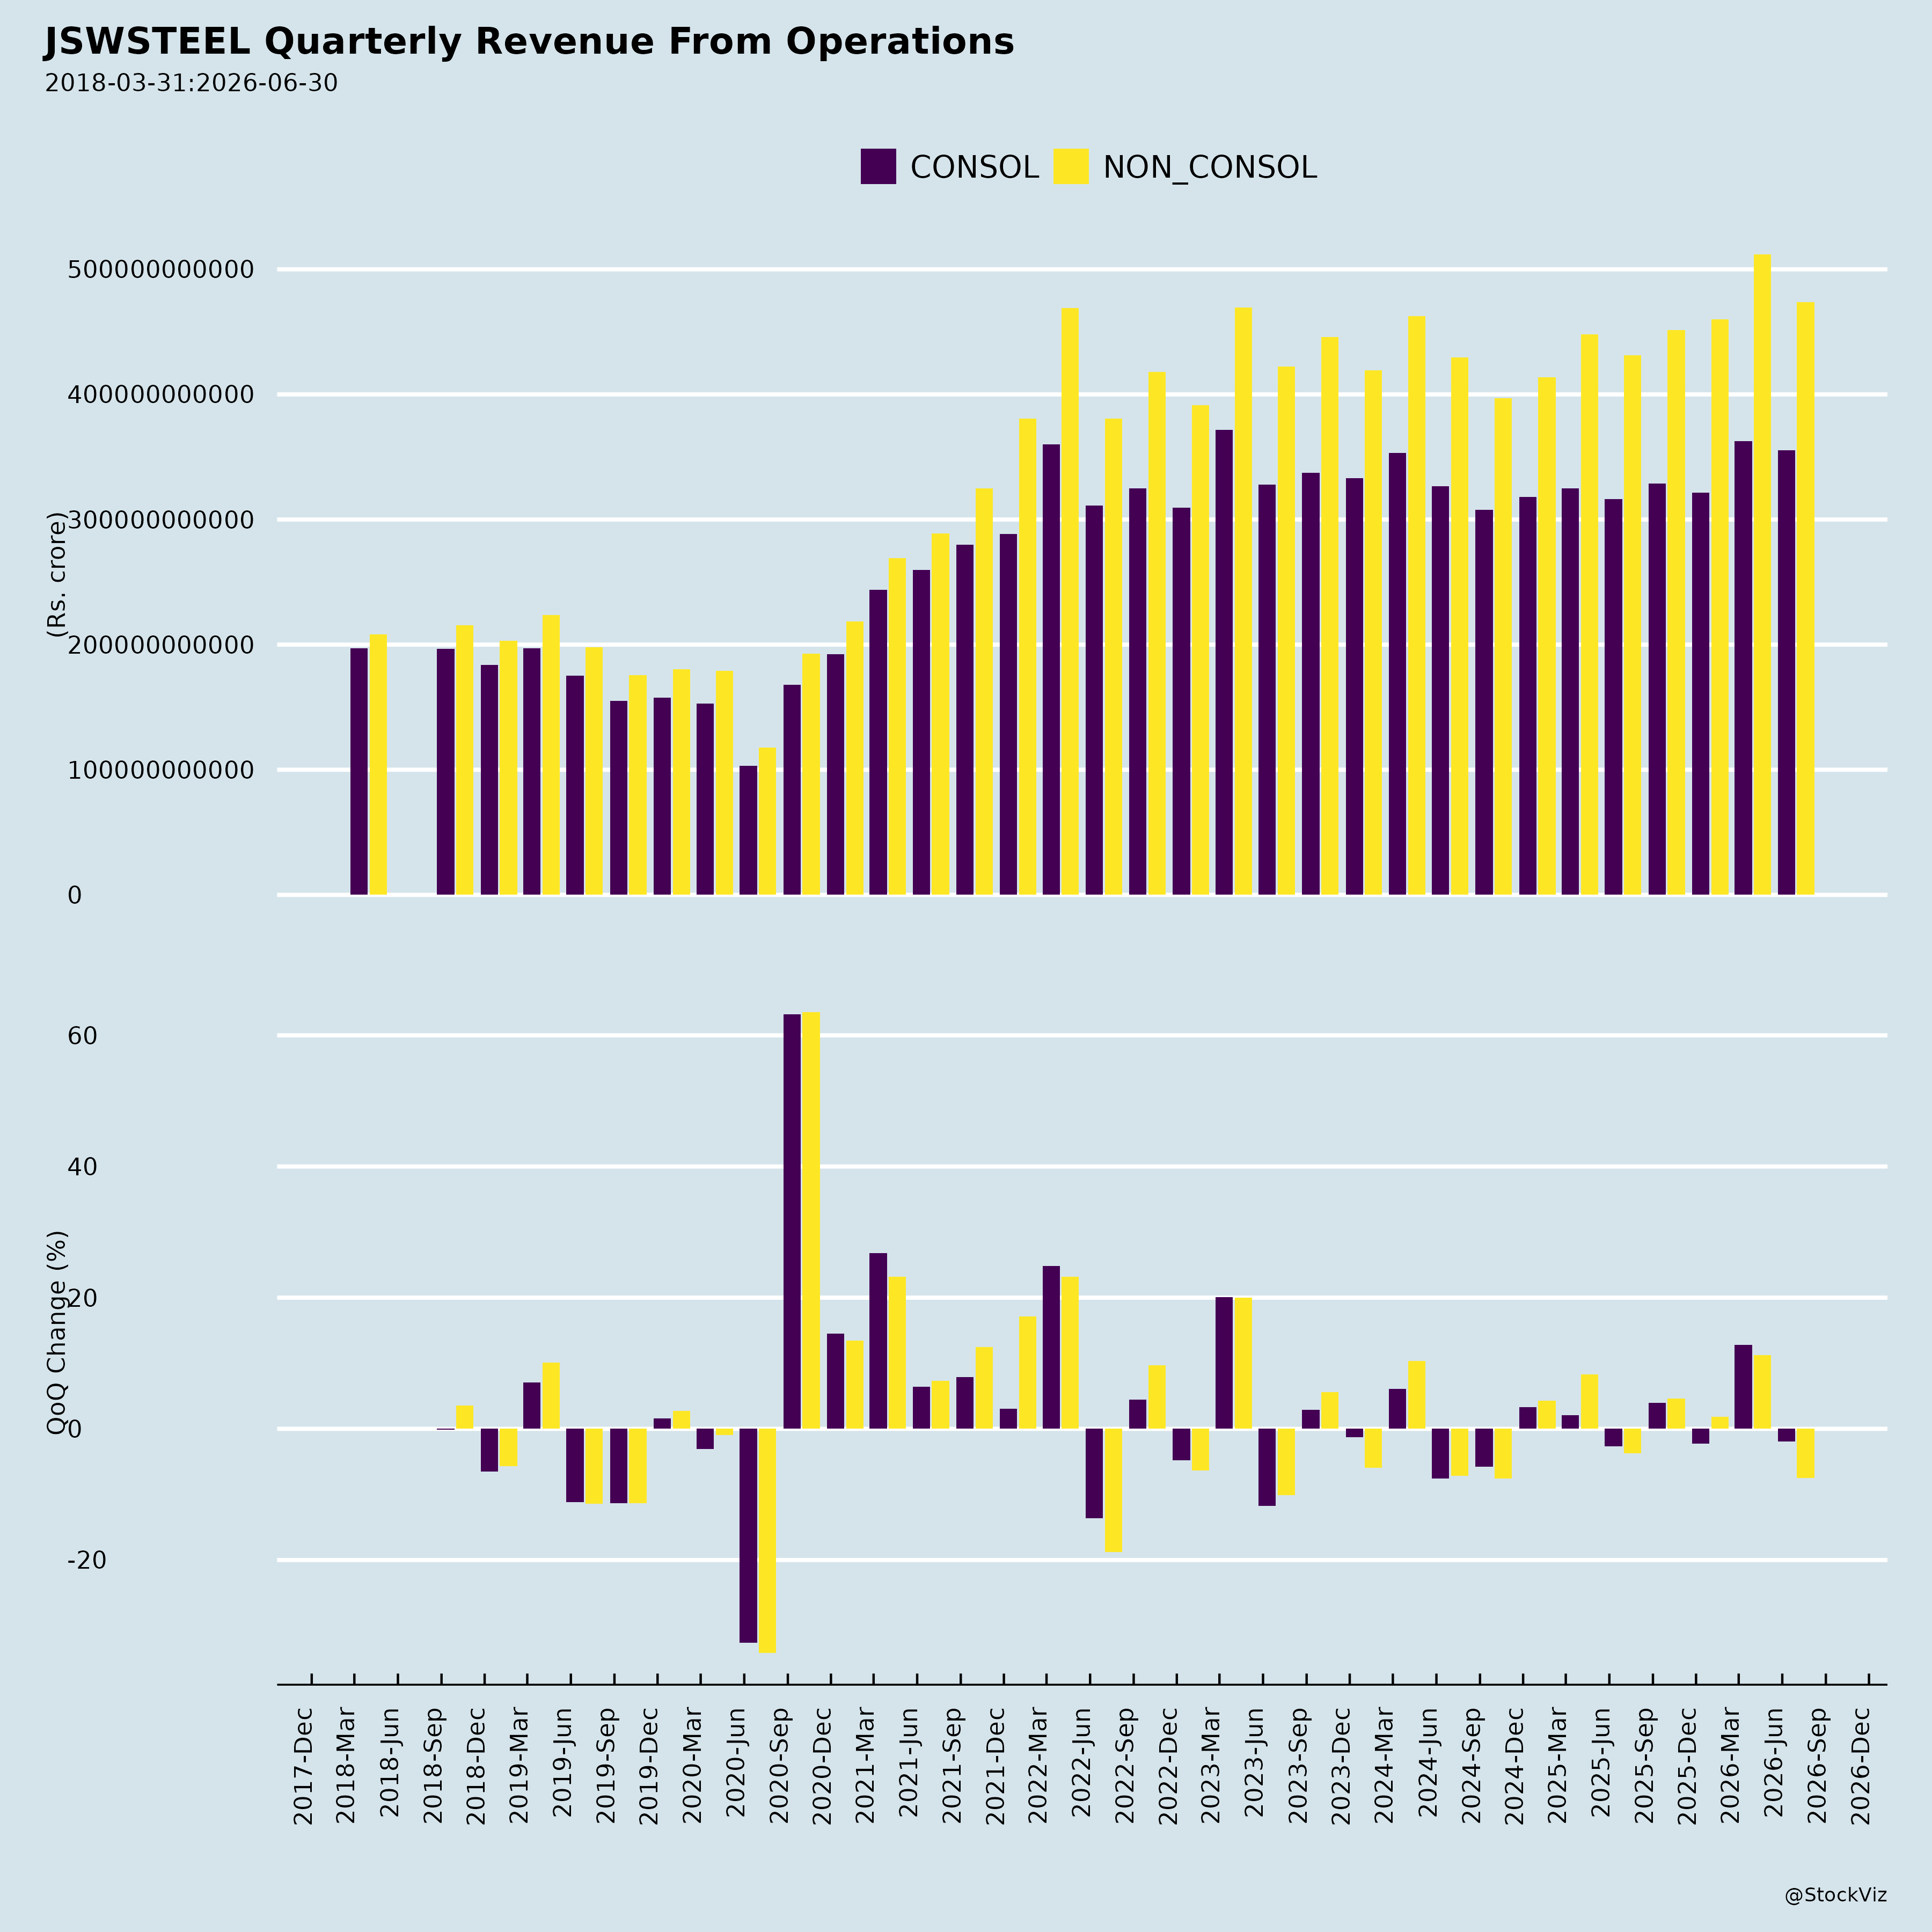
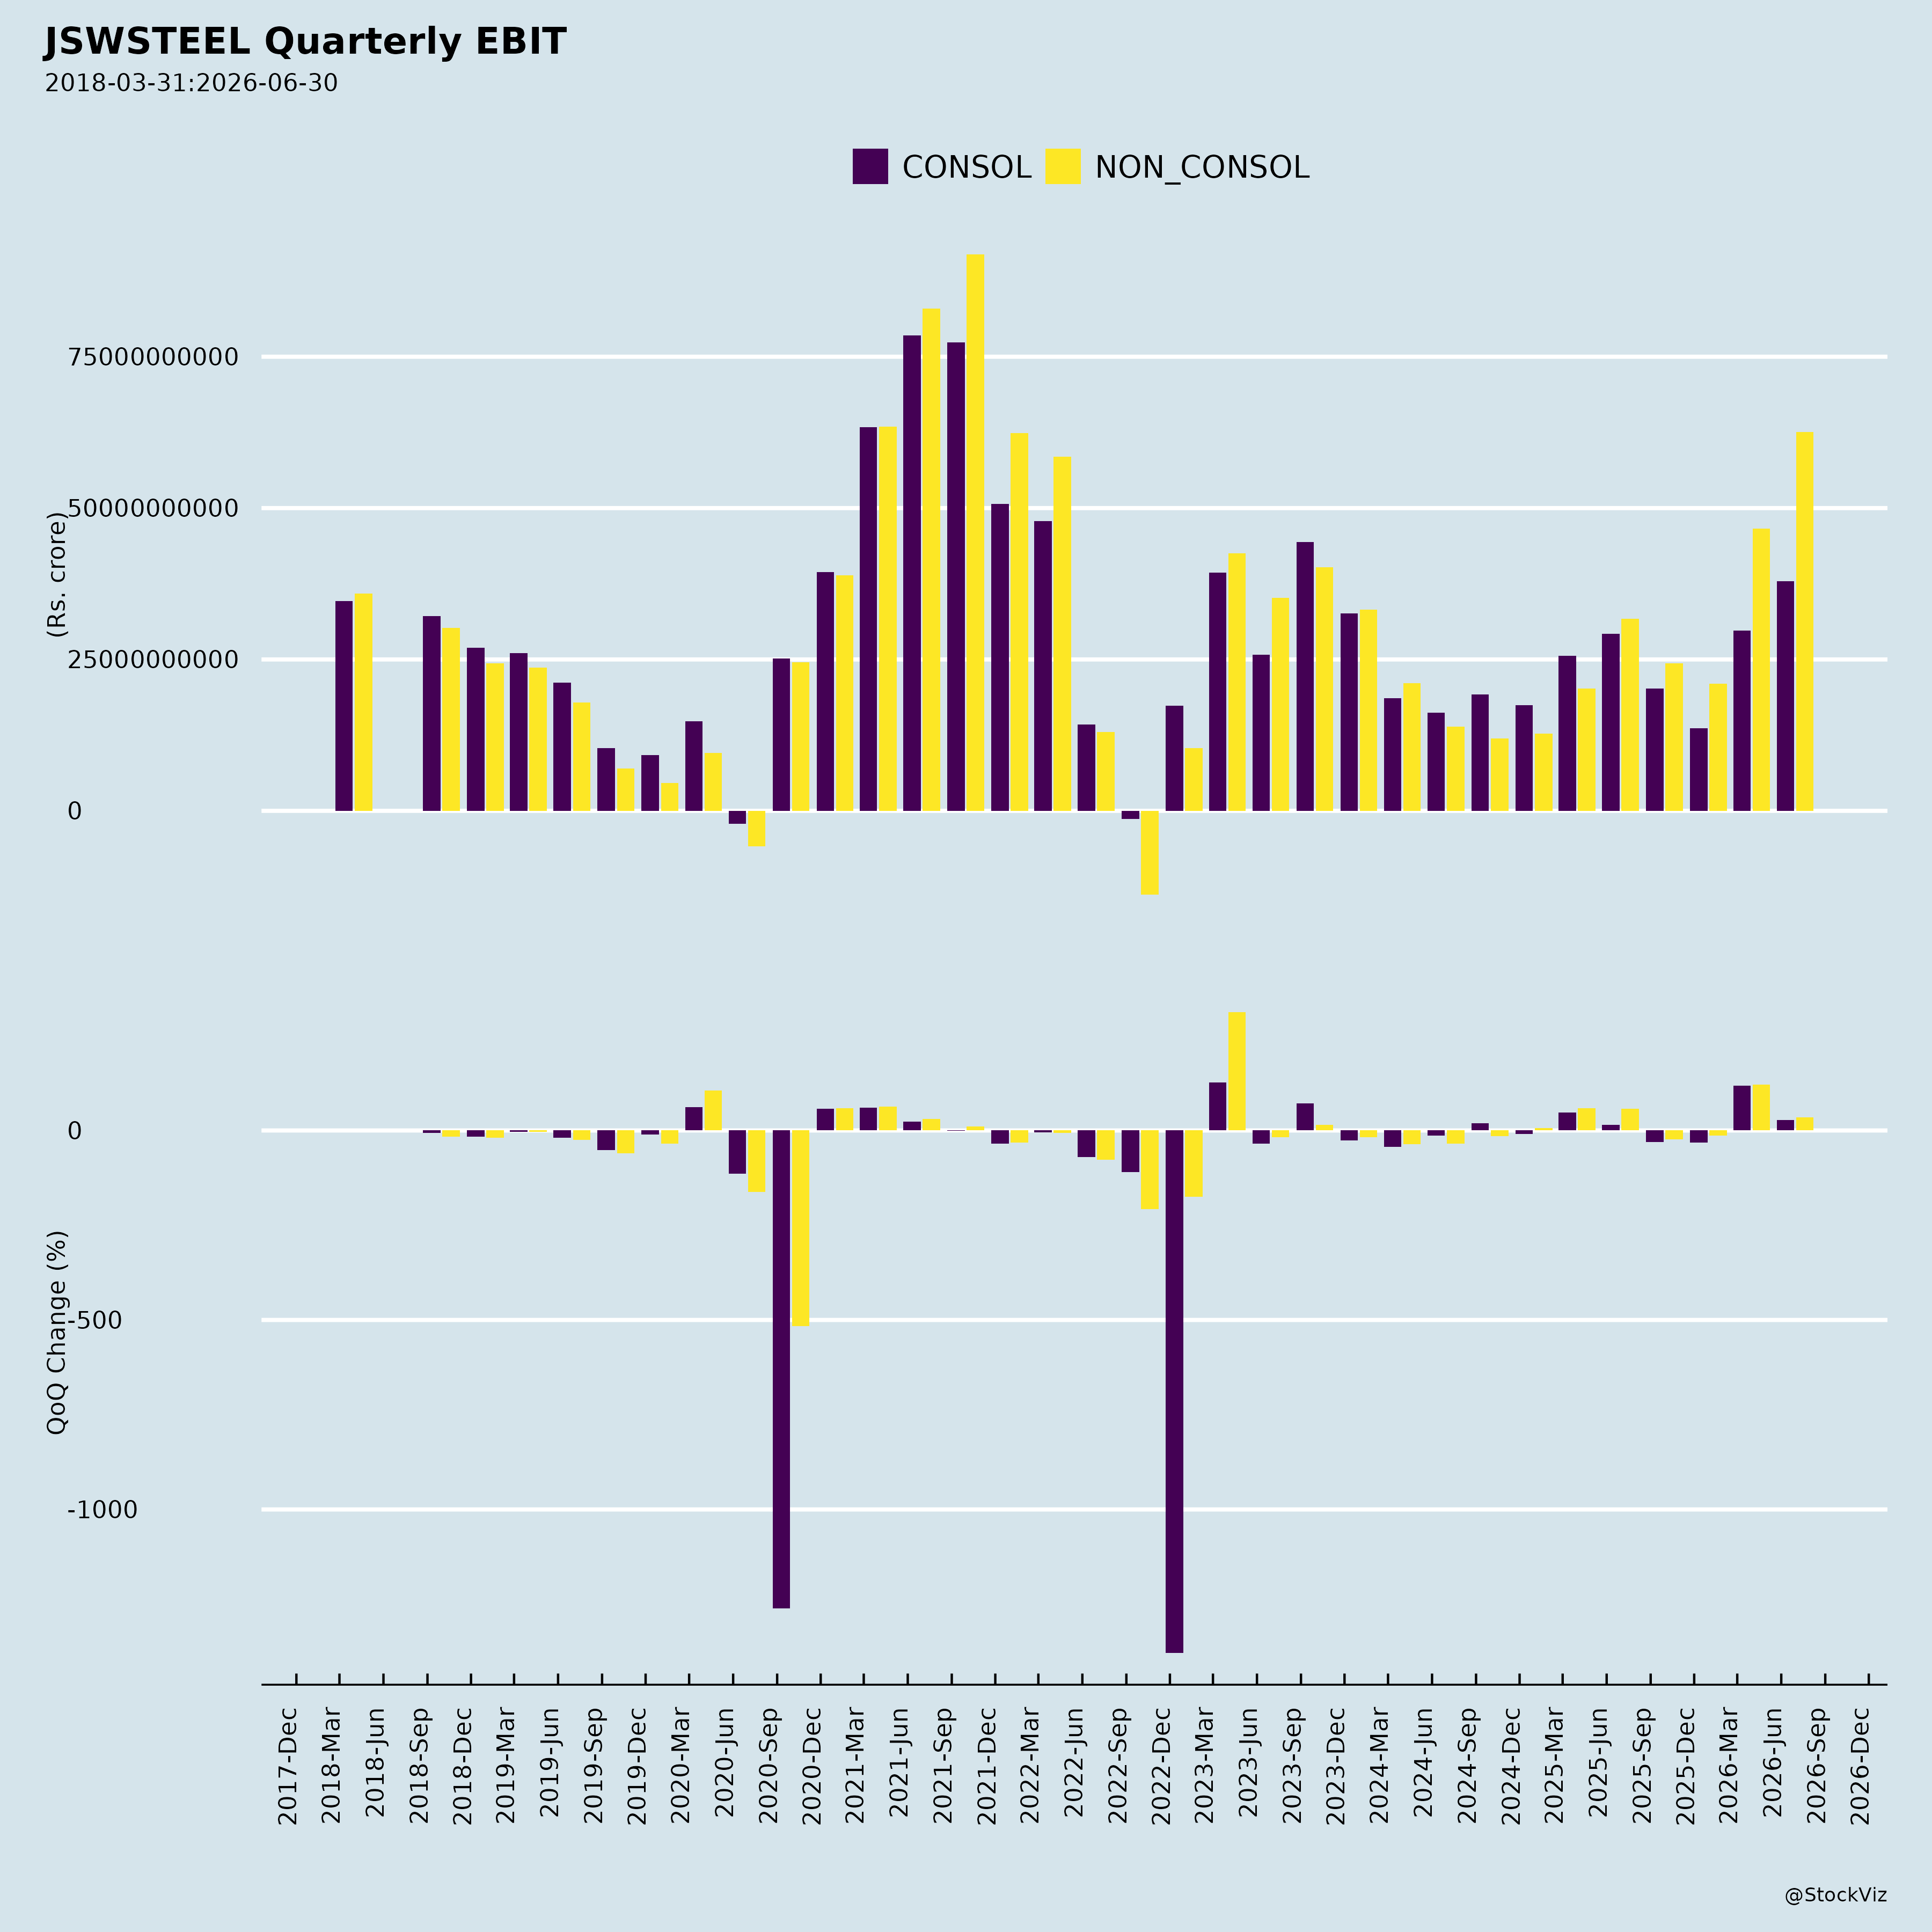
Fundamentals
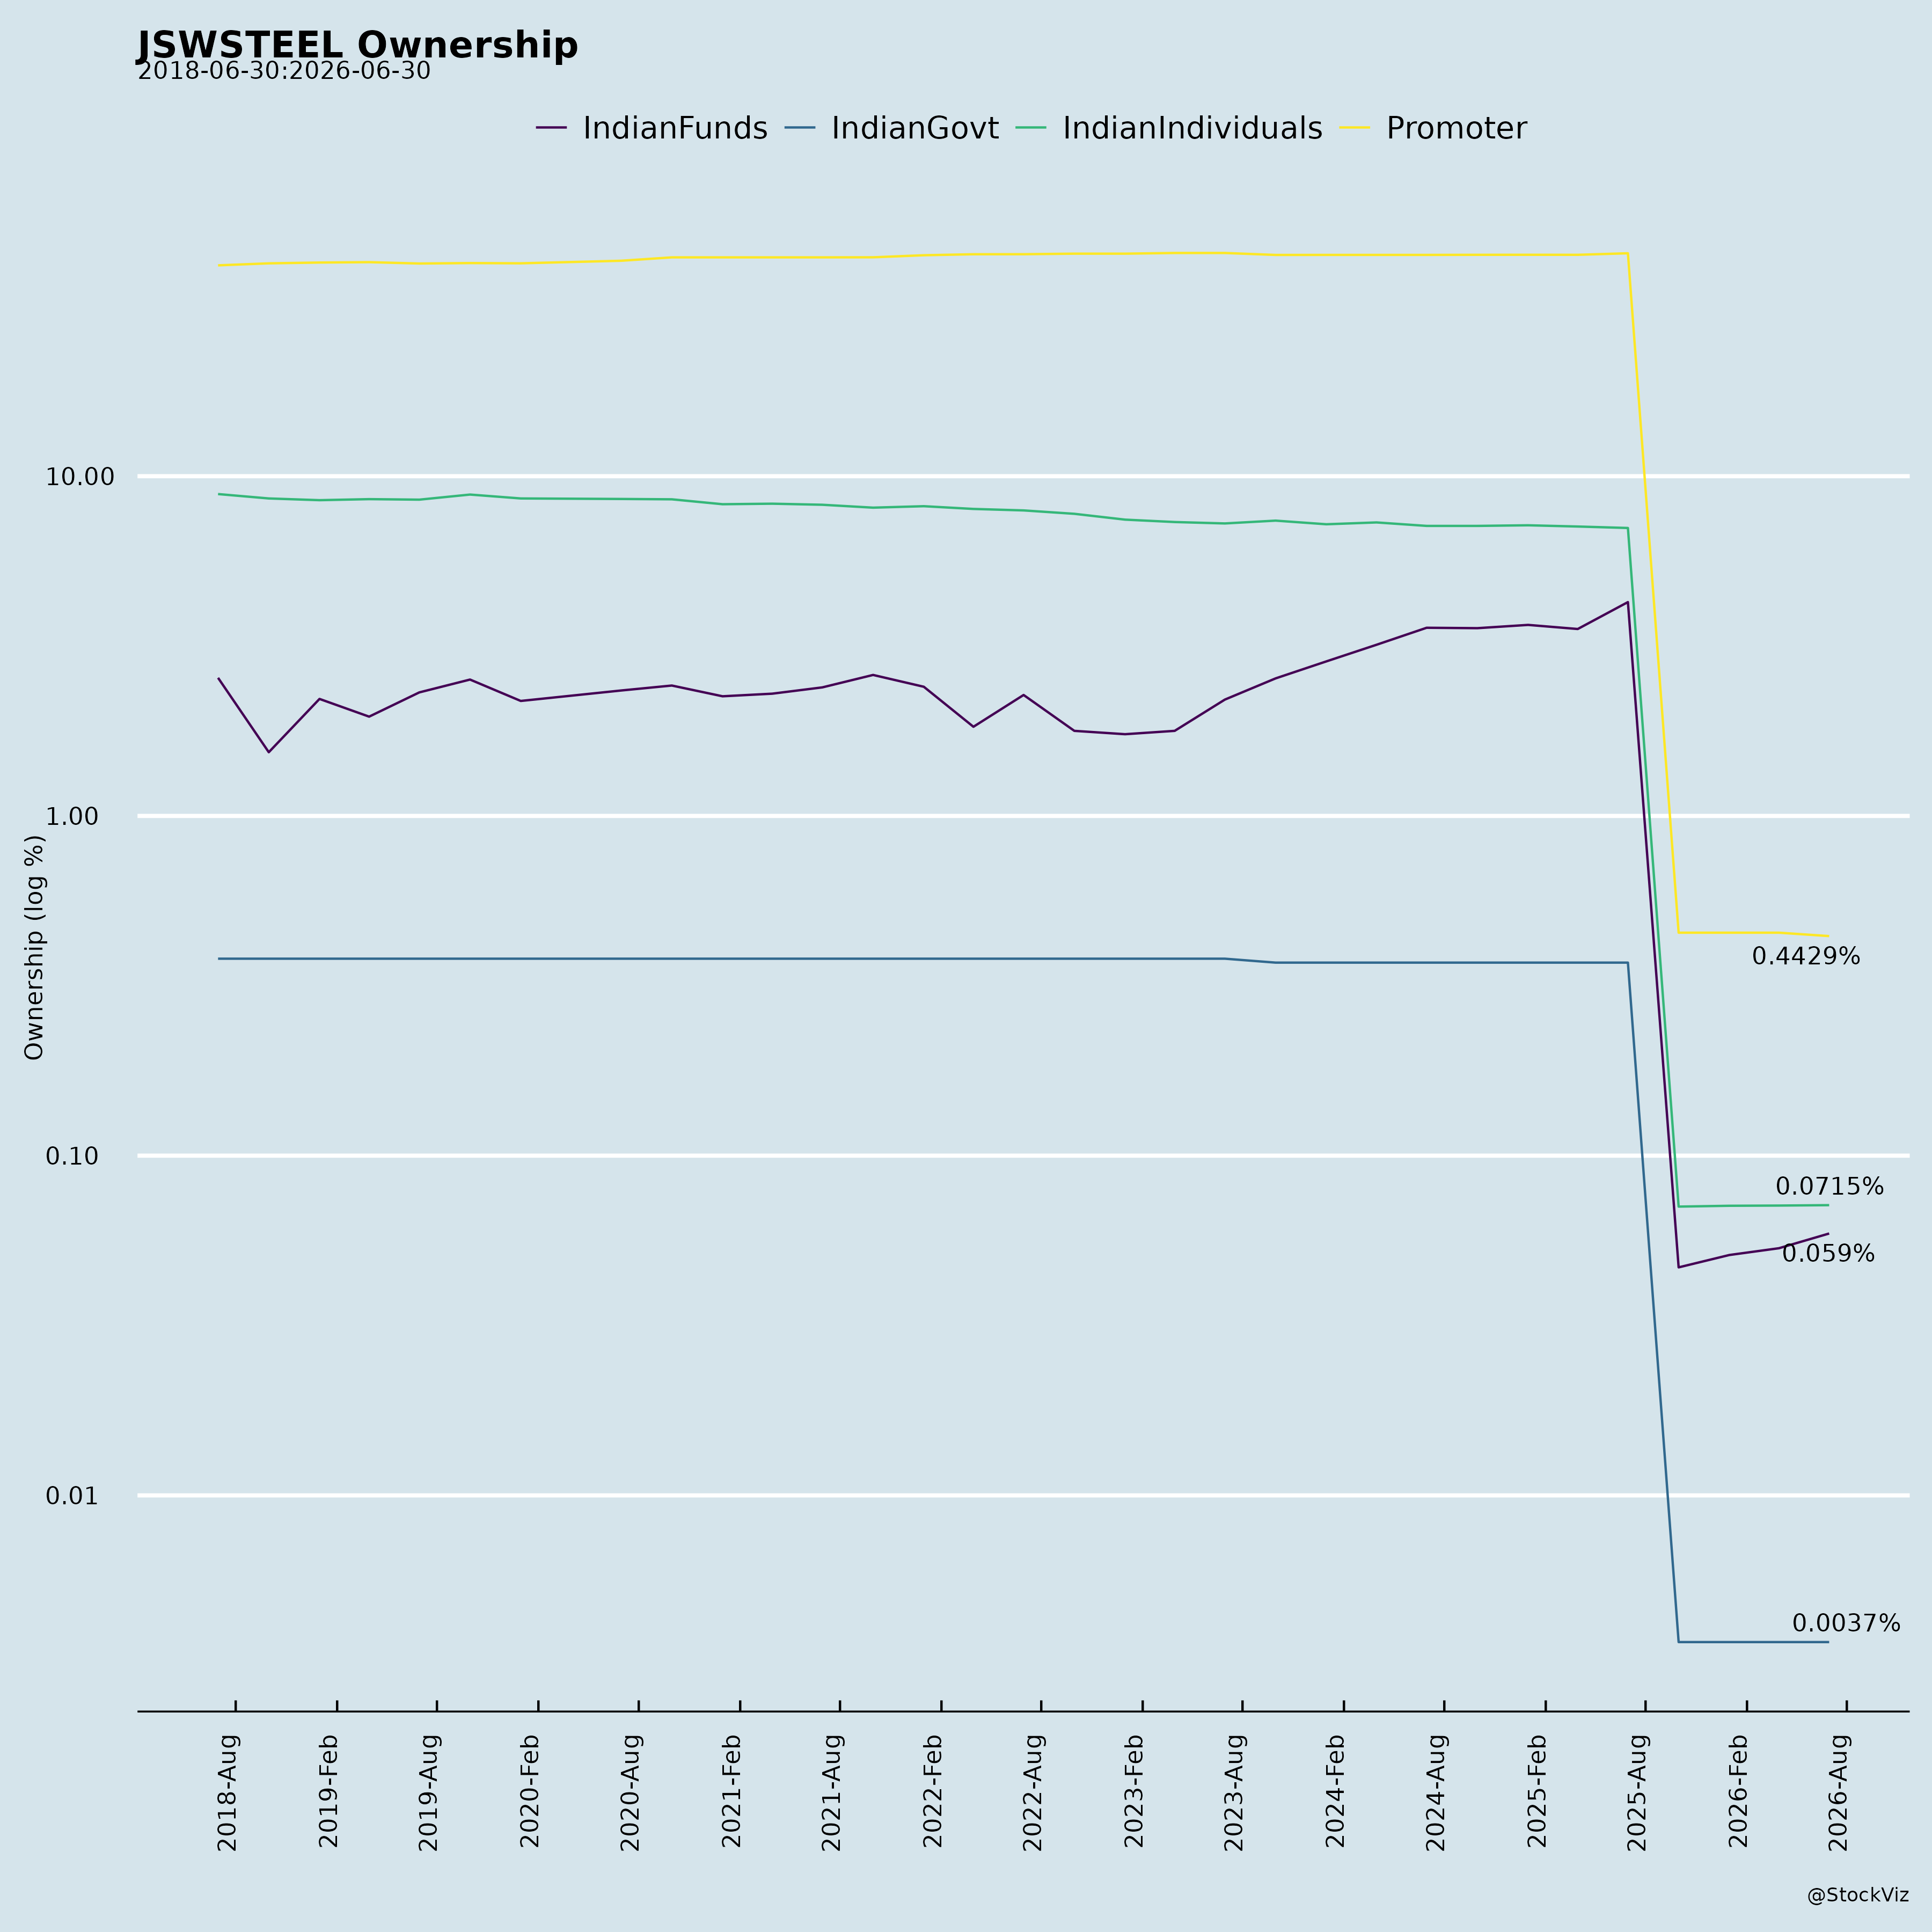
Ownership
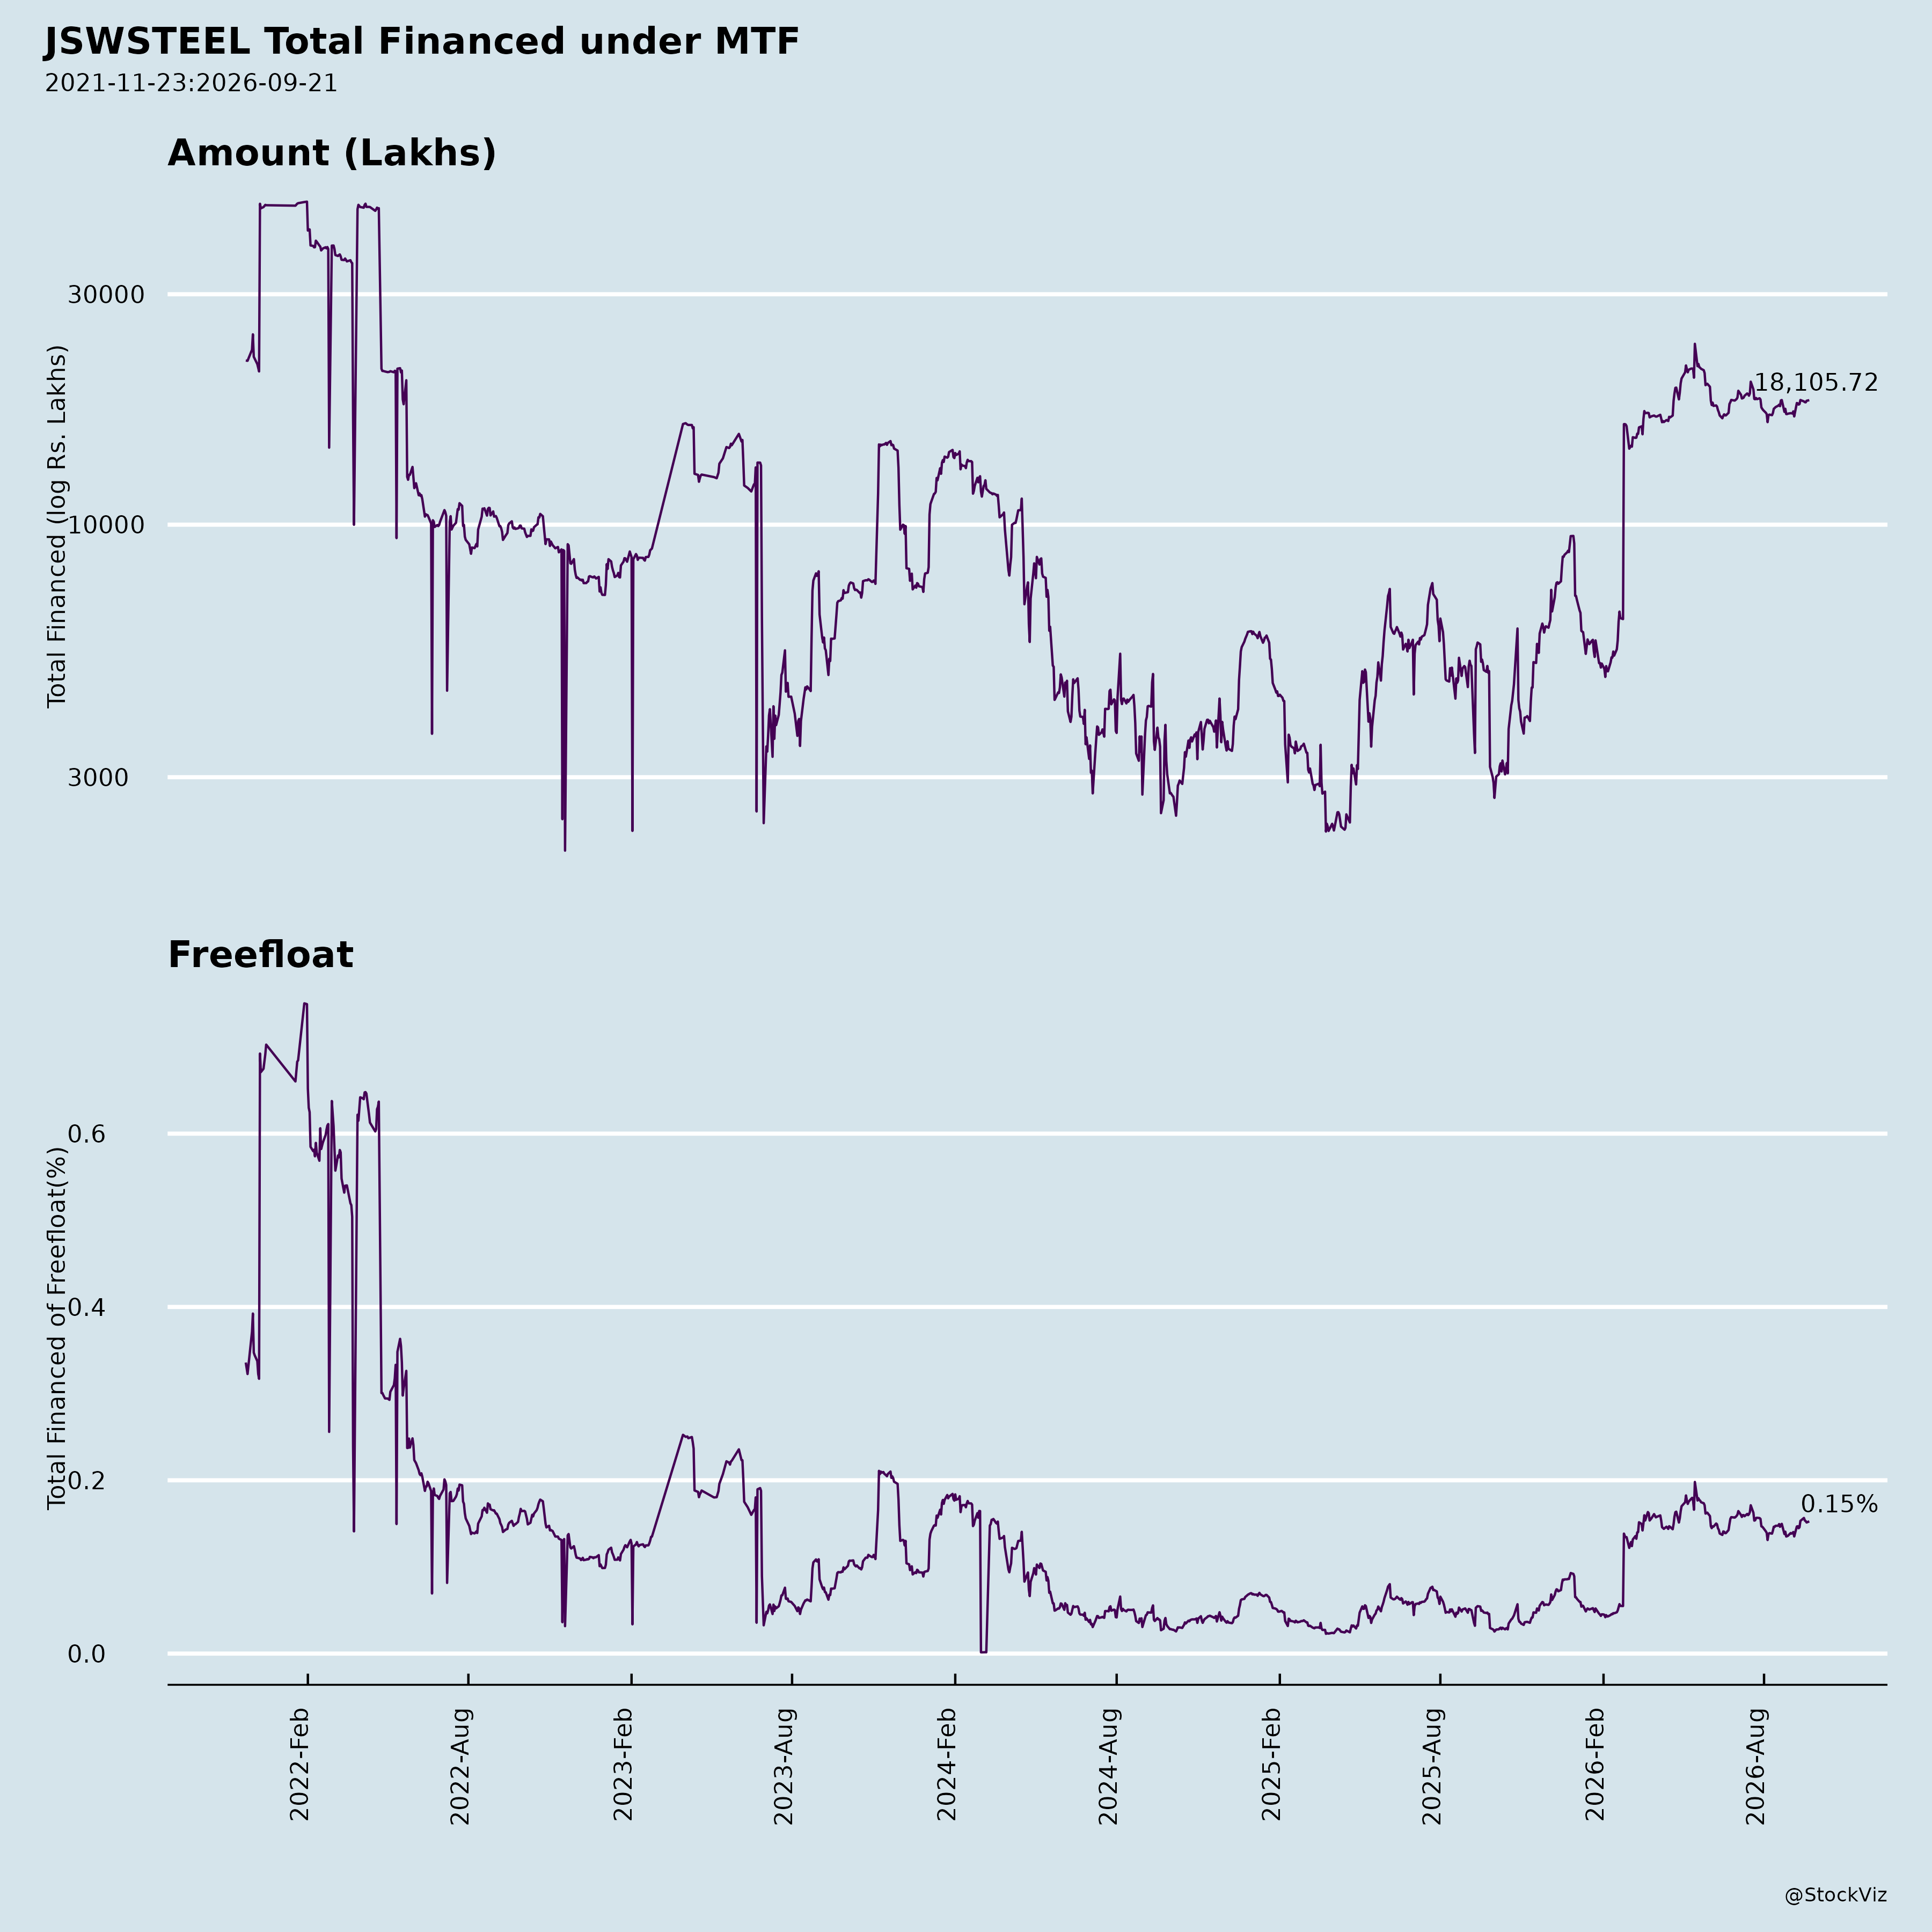
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- Industry and operating pressures: The company’s disclosures cite fluctuations in earnings, intense competition within the steel industry, wage increases in India, reduced demand for steel, and general economic conditions affecting the industry as challenges.
- Execution and integration demands: The company flags its ability to manage growth, manage internal operations, and successfully complete and integrate potential acquisitions as areas of challenge.
- People and contractual exposure: The company cites its ability to attract and retain highly skilled professionals, time and cost overruns on fixed-price and fixed-time frame contracts, client concentration, liability for damages on service contracts, and restrictions on immigration as challenges.
- External and regulatory factors: The company cites withdrawal of fiscal governmental incentives, political instability, legal restrictions on raising capital or acquiring companies outside India, and unauthorized use of intellectual property as challenges.
- Dependence on strategic investments: The success of companies in which strategic investments have been made is cited as a challenge.
Tailwinds and Growth Prospects
- Capacity expansion: The company has a combined crude steel capacity of 37.9 MTPA, including 4.5 MTPA through the JSW JFE Steel JV, and this is growing to 54.8 MTPA over the next four years.
- Vijayanagar expansion: The Vijayanagar plant capacity is being expanded from 19.5 MTPA to approximately 25 MTPA by FY30.
- Production growth: JSW Steel reported consolidated crude steel production of 24.65 Lakh tonnes for August 2026, registering a 3% YoY growth, with 88% capacity utilisation for Indian operations.
- Amalgamation synergies: The amalgamation of Amba River Coke Limited, Monnet Cement Limited, and JSW Retail and Distribution Limited with JSW Steel Limited, effective August 1, 2026 (Appointed Date April 1, 2026), is expected to result in operational efficiency, pooling of technical resources and personnel, cost reduction, a streamlined group structure with fewer legal entities and regulatory compliances, administrative and operational convenience, rationalization of costs by eliminating multiple record keeping, and reduced time and effort for financial consolidation. Because the transferor companies are wholly owned subsidiaries, no new shares will be allotted and the transferor companies are dissolved without winding up.
- Piombino Steel amalgamation approval: The NCLT-convened meeting of equity shareholders held on August 21, 2026, approved the Scheme of Amalgamation of Piombino Steel Limited with JSW Steel Limited, with 98.59% of valid votes cast in favour by equity shareholders and 97.20% of valid votes cast by public shareholders.
Key Risks
- The risks cited in the company’s disclosures include fluctuations in earnings, ability to manage growth, intense competition within the steel industry, wage increases in India, ability to attract and retain highly skilled professionals, time and cost overruns on fixed-price and fixed-time frame contracts, client concentration, restrictions on immigration, ability to manage internal operations, reduced demand for steel, ability to successfully complete and integrate potential acquisitions, liability for damages on service contracts, success of companies in which strategic investments have been made, withdrawal of fiscal governmental incentives, political instability, legal restrictions on raising capital or acquiring companies outside India, unauthorized use of intellectual property, and general economic conditions affecting the industry.
- Management notes that certain statements concerning future growth prospects are forward-looking statements involving risks and uncertainties, and states that the company does not undertake to update any forward-looking statements made from time to time.
Management Guidance Versus Observed Business Performance
- Capacity guidance: Management points to a combined crude steel capacity of 37.9 MTPA growing to 54.8 MTPA over the next four years, and expansion of the Vijayanagar plant from 19.5 MTPA to approximately 25 MTPA by FY30.
- Observed performance: Against this expansion backdrop, JSW Steel reported consolidated crude steel production of 24.65 Lakh tonnes for August 2026, a 3% YoY growth, with 88% capacity utilisation for Indian operations.
- Forward-looking statement caveat: Management notes that statements concerning future growth prospects are forward-looking statements involving risks and uncertainties, and states that the company does not undertake to update any forward-looking statements made from time to time.
Other Developments
- Statutory auditor appointment: On July 17, 2026, based on the Audit Committee’s recommendation, the Board approved the appointment of M/s. Deloitte Haskins & Sells Chartered Accountants LLP as Statutory Auditor for a term of 5 years, commencing from the conclusion of the 33rd AGM (to be held in 2027) until the conclusion of the 38th AGM (to be held in 2032), subject to member approval. M/s. S R B C & CO. LLP continues as Statutory Auditor until the conclusion of the 33rd AGM in 2027, completing its second consecutive term of 5 years.
- Investor presentation: On August 12, 2026, the company intimated the uploading of a new Investor presentation on its website pursuant to Regulation 30 of the Listing Regulations.
- Investor meetings: JSW Steel Limited has scheduled Analyst/Institutional Investor meetings in New York, USA, from September 21st to 22nd, 2026, in the form of 1x1 and Group meetings pursuant to Regulation 30(6) of SEBI (Listing Obligations and Disclosure Requirements) Regulations, 2015.
Broker Narrative
The narrative shifted from broad Nifty technicals in 2021—fear of an intermediate index top and limited near-term upside versus bullish breadth and RSI momentum—to company-specific steel fundamentals by 2026. Early caution centered on market-driven valuation, while later reports focused on coking coal and fuel cost inflation, falling NSR, and EBITDA/t margin pressure. The theme of near-term headwinds persisted, but long-term optimism evolved into a concrete expansion and raw-material security story anchored by Utkal Phase II, a 25mtpa pipeline by FY31E, and 7–9% domestic demand growth.
Broker Timeline
69 broker calls · 2021-06-07 to 2026-10-24
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.