IMFA
Equity Metrics
November 18, 2026
Indian Metals & Ferro Alloys Limited
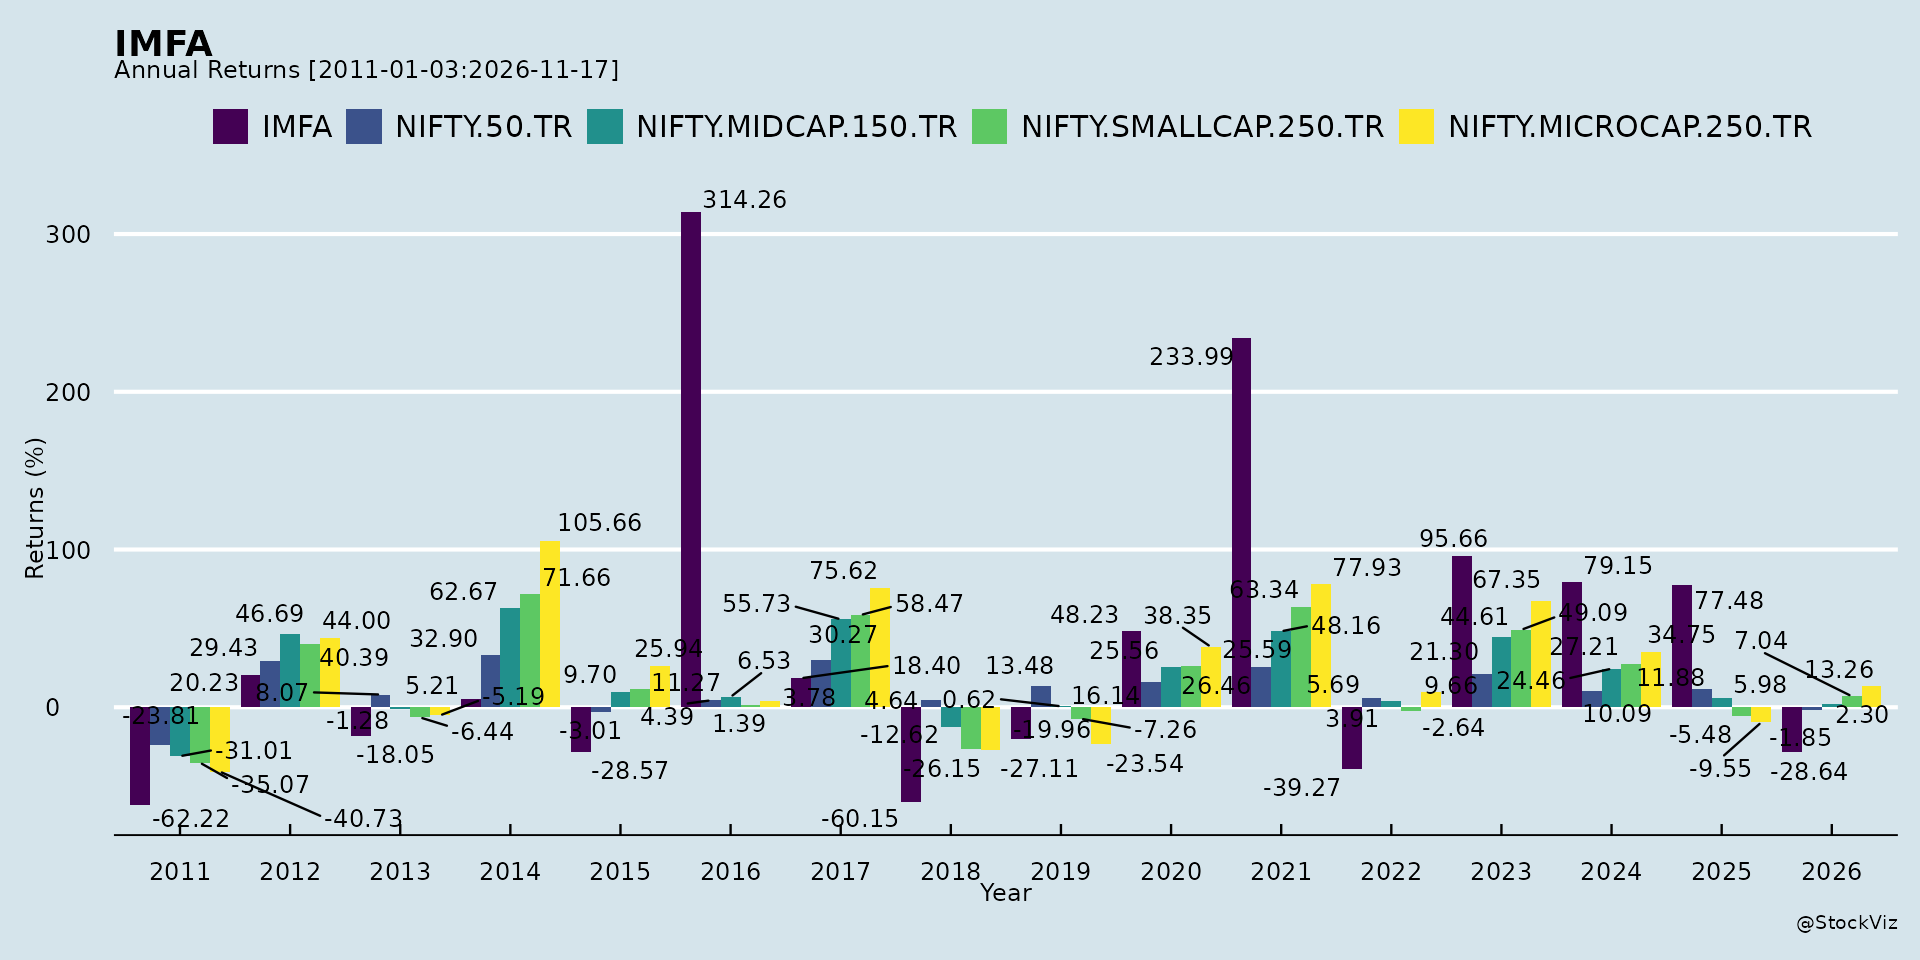
Annual Returns
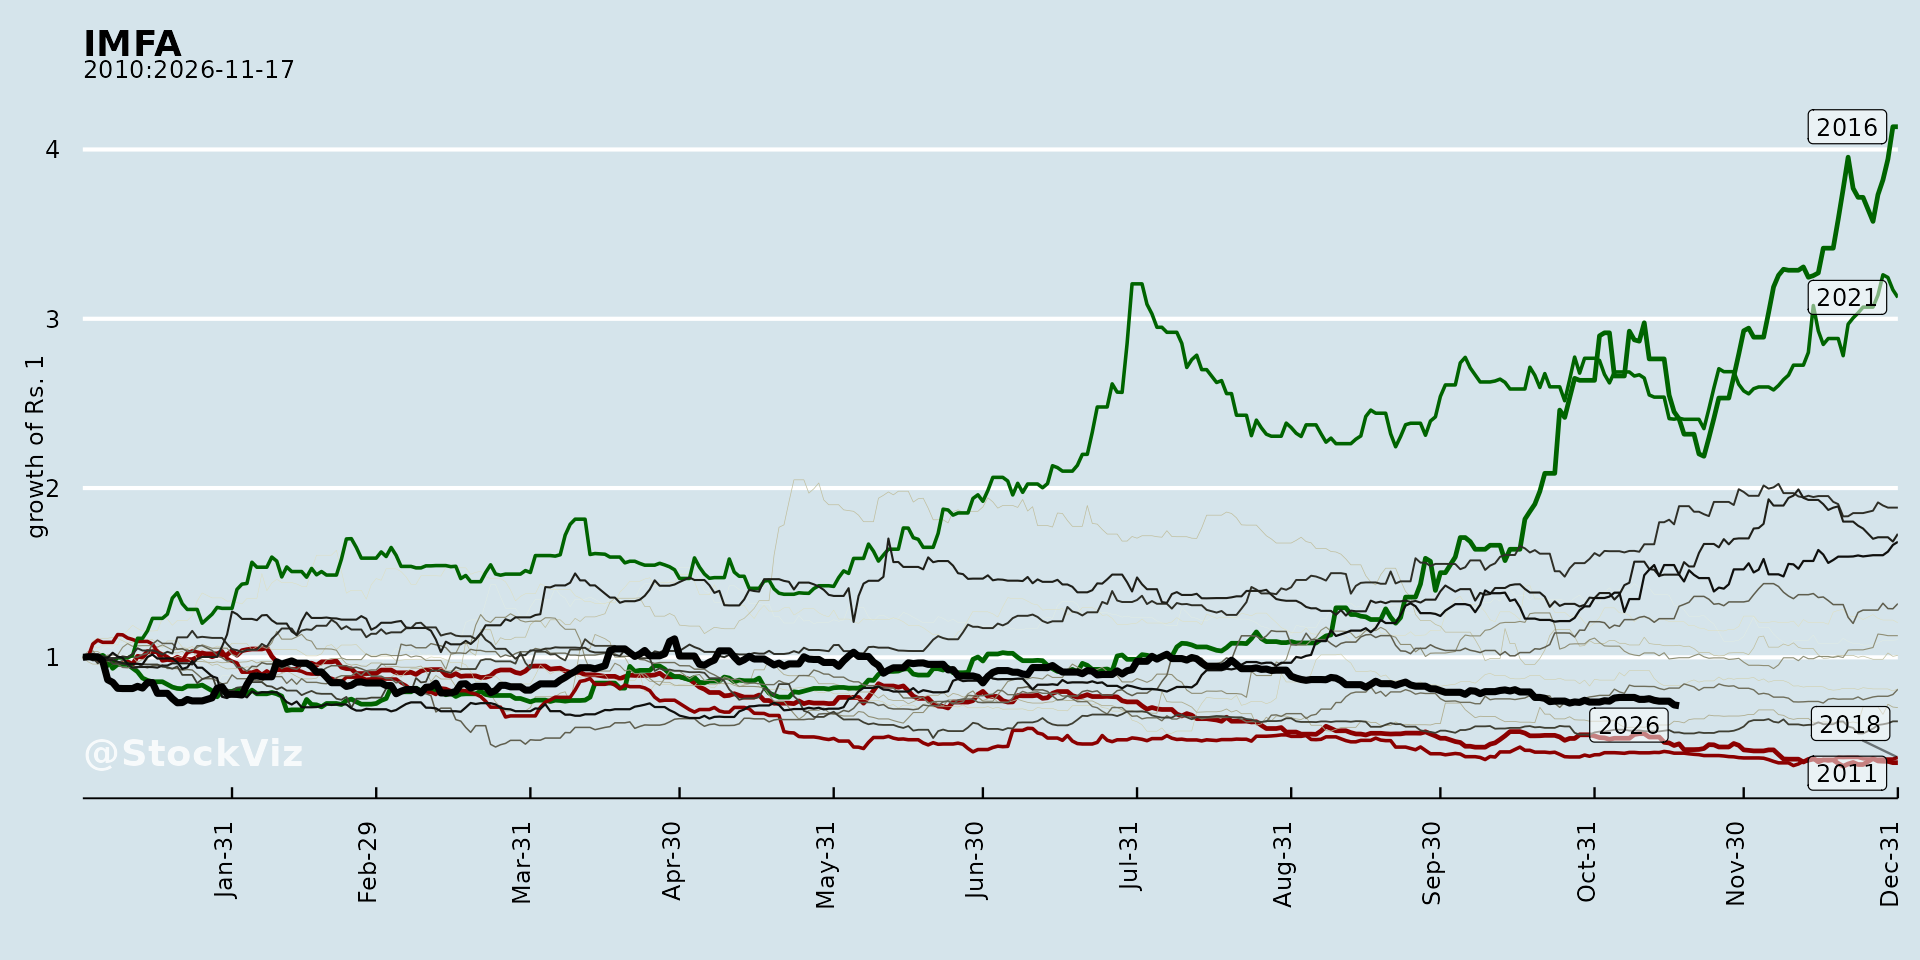
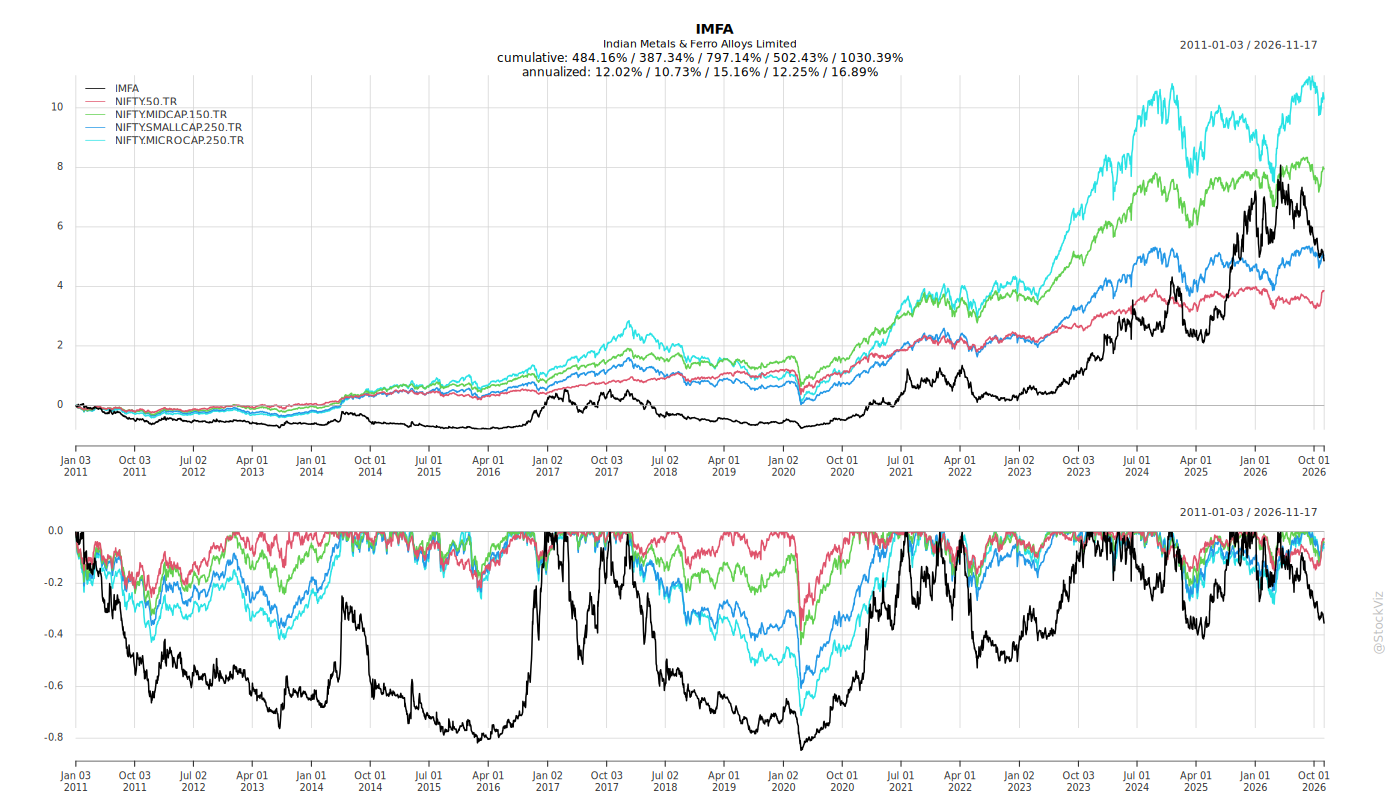
Cumulative Returns and Drawdowns
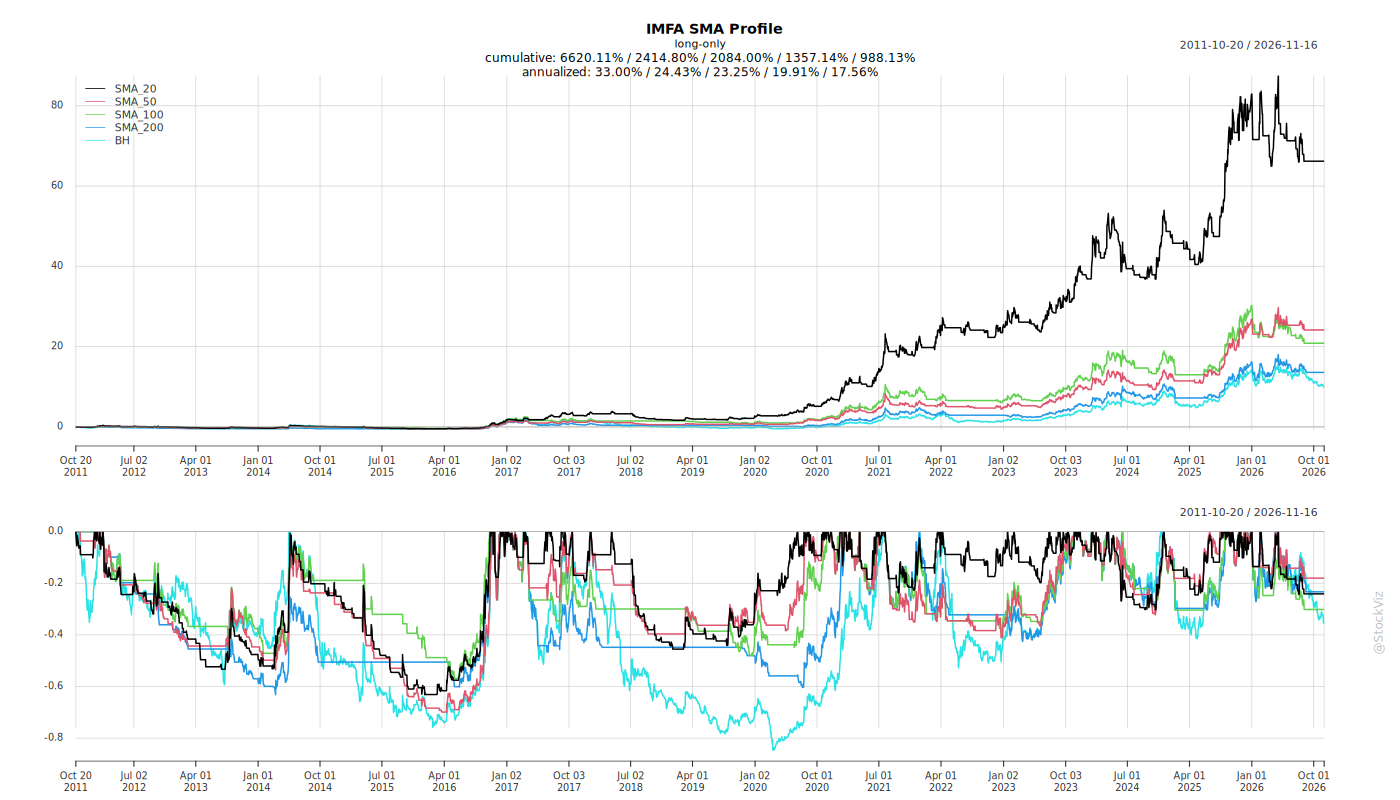
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
IMFA: Recent Corporate Developments
Headwinds and Challenges
- Ethanol project delays at Therubali. The grain-based ethanol project has experienced delays attributable to the second-degree effect of geopolitical uncertainty and monsoon-related disruptions. Management nonetheless expects the trial run in October 2026 and commissioning in November 2026.
- Insider trading compliance lapse. Designated persons in the middle management group traded in the Company’s securities in contravention of clause 4(1) and clause 10 of Schedule B read with Regulation 9 of the SEBI (Prohibition of Insider Trading) Regulations, 2015. This concerned trading during October 2023 to December 2023. SEBI issued an administrative warning letter dated July 31, 2026, received by the Company on August 4, 2026, addressed to the Company Secretary and Compliance Officer. The company has taken necessary action against the individuals concerned, and the letter is cautionary, imposing no fine, penalty, or financial or operational restrictions.
- Mining levy litigation. The Supreme Court judgment upholding the right of States to impose levy on mineral bearing land has financial implications for the mining sector at large as well as downstream industries. An appeal filed by the State Government against the Orissa High Court’s earlier striking down of the Orissa Rural Infrastructure and Socio-Economic Development Act, 2004 is sub-judice before the Supreme Court.
Tailwinds and Growth Prospects
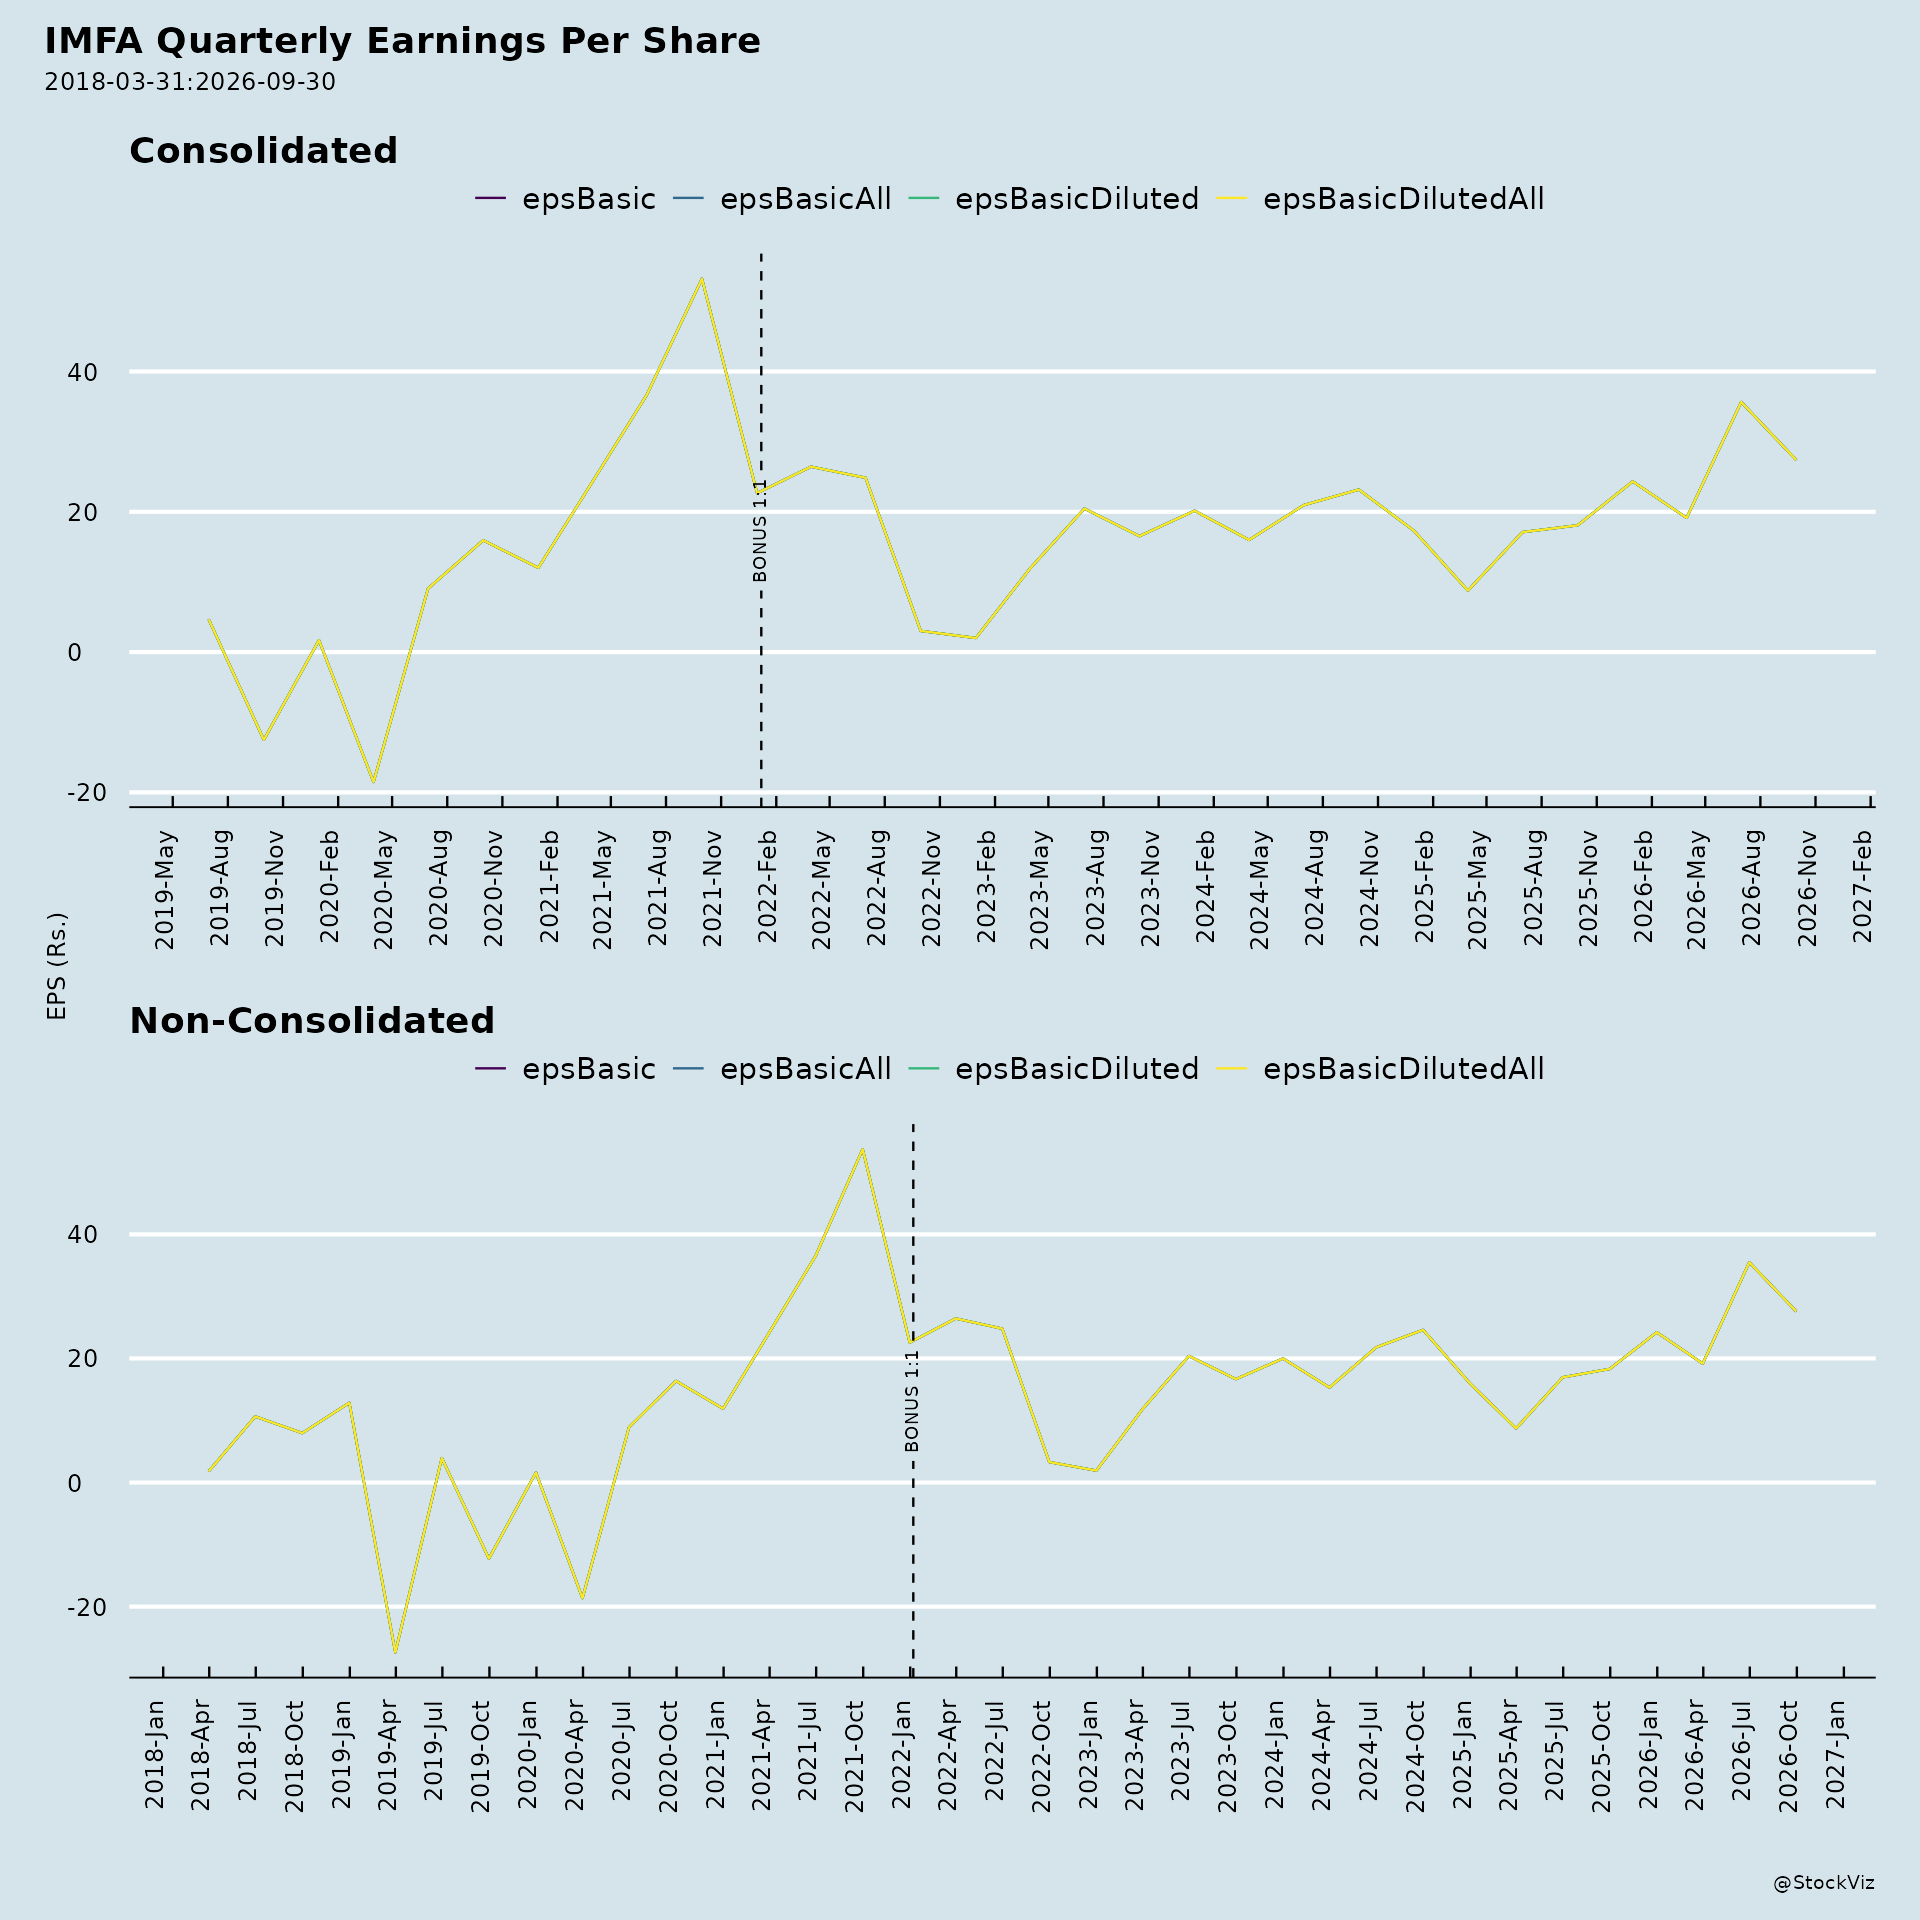
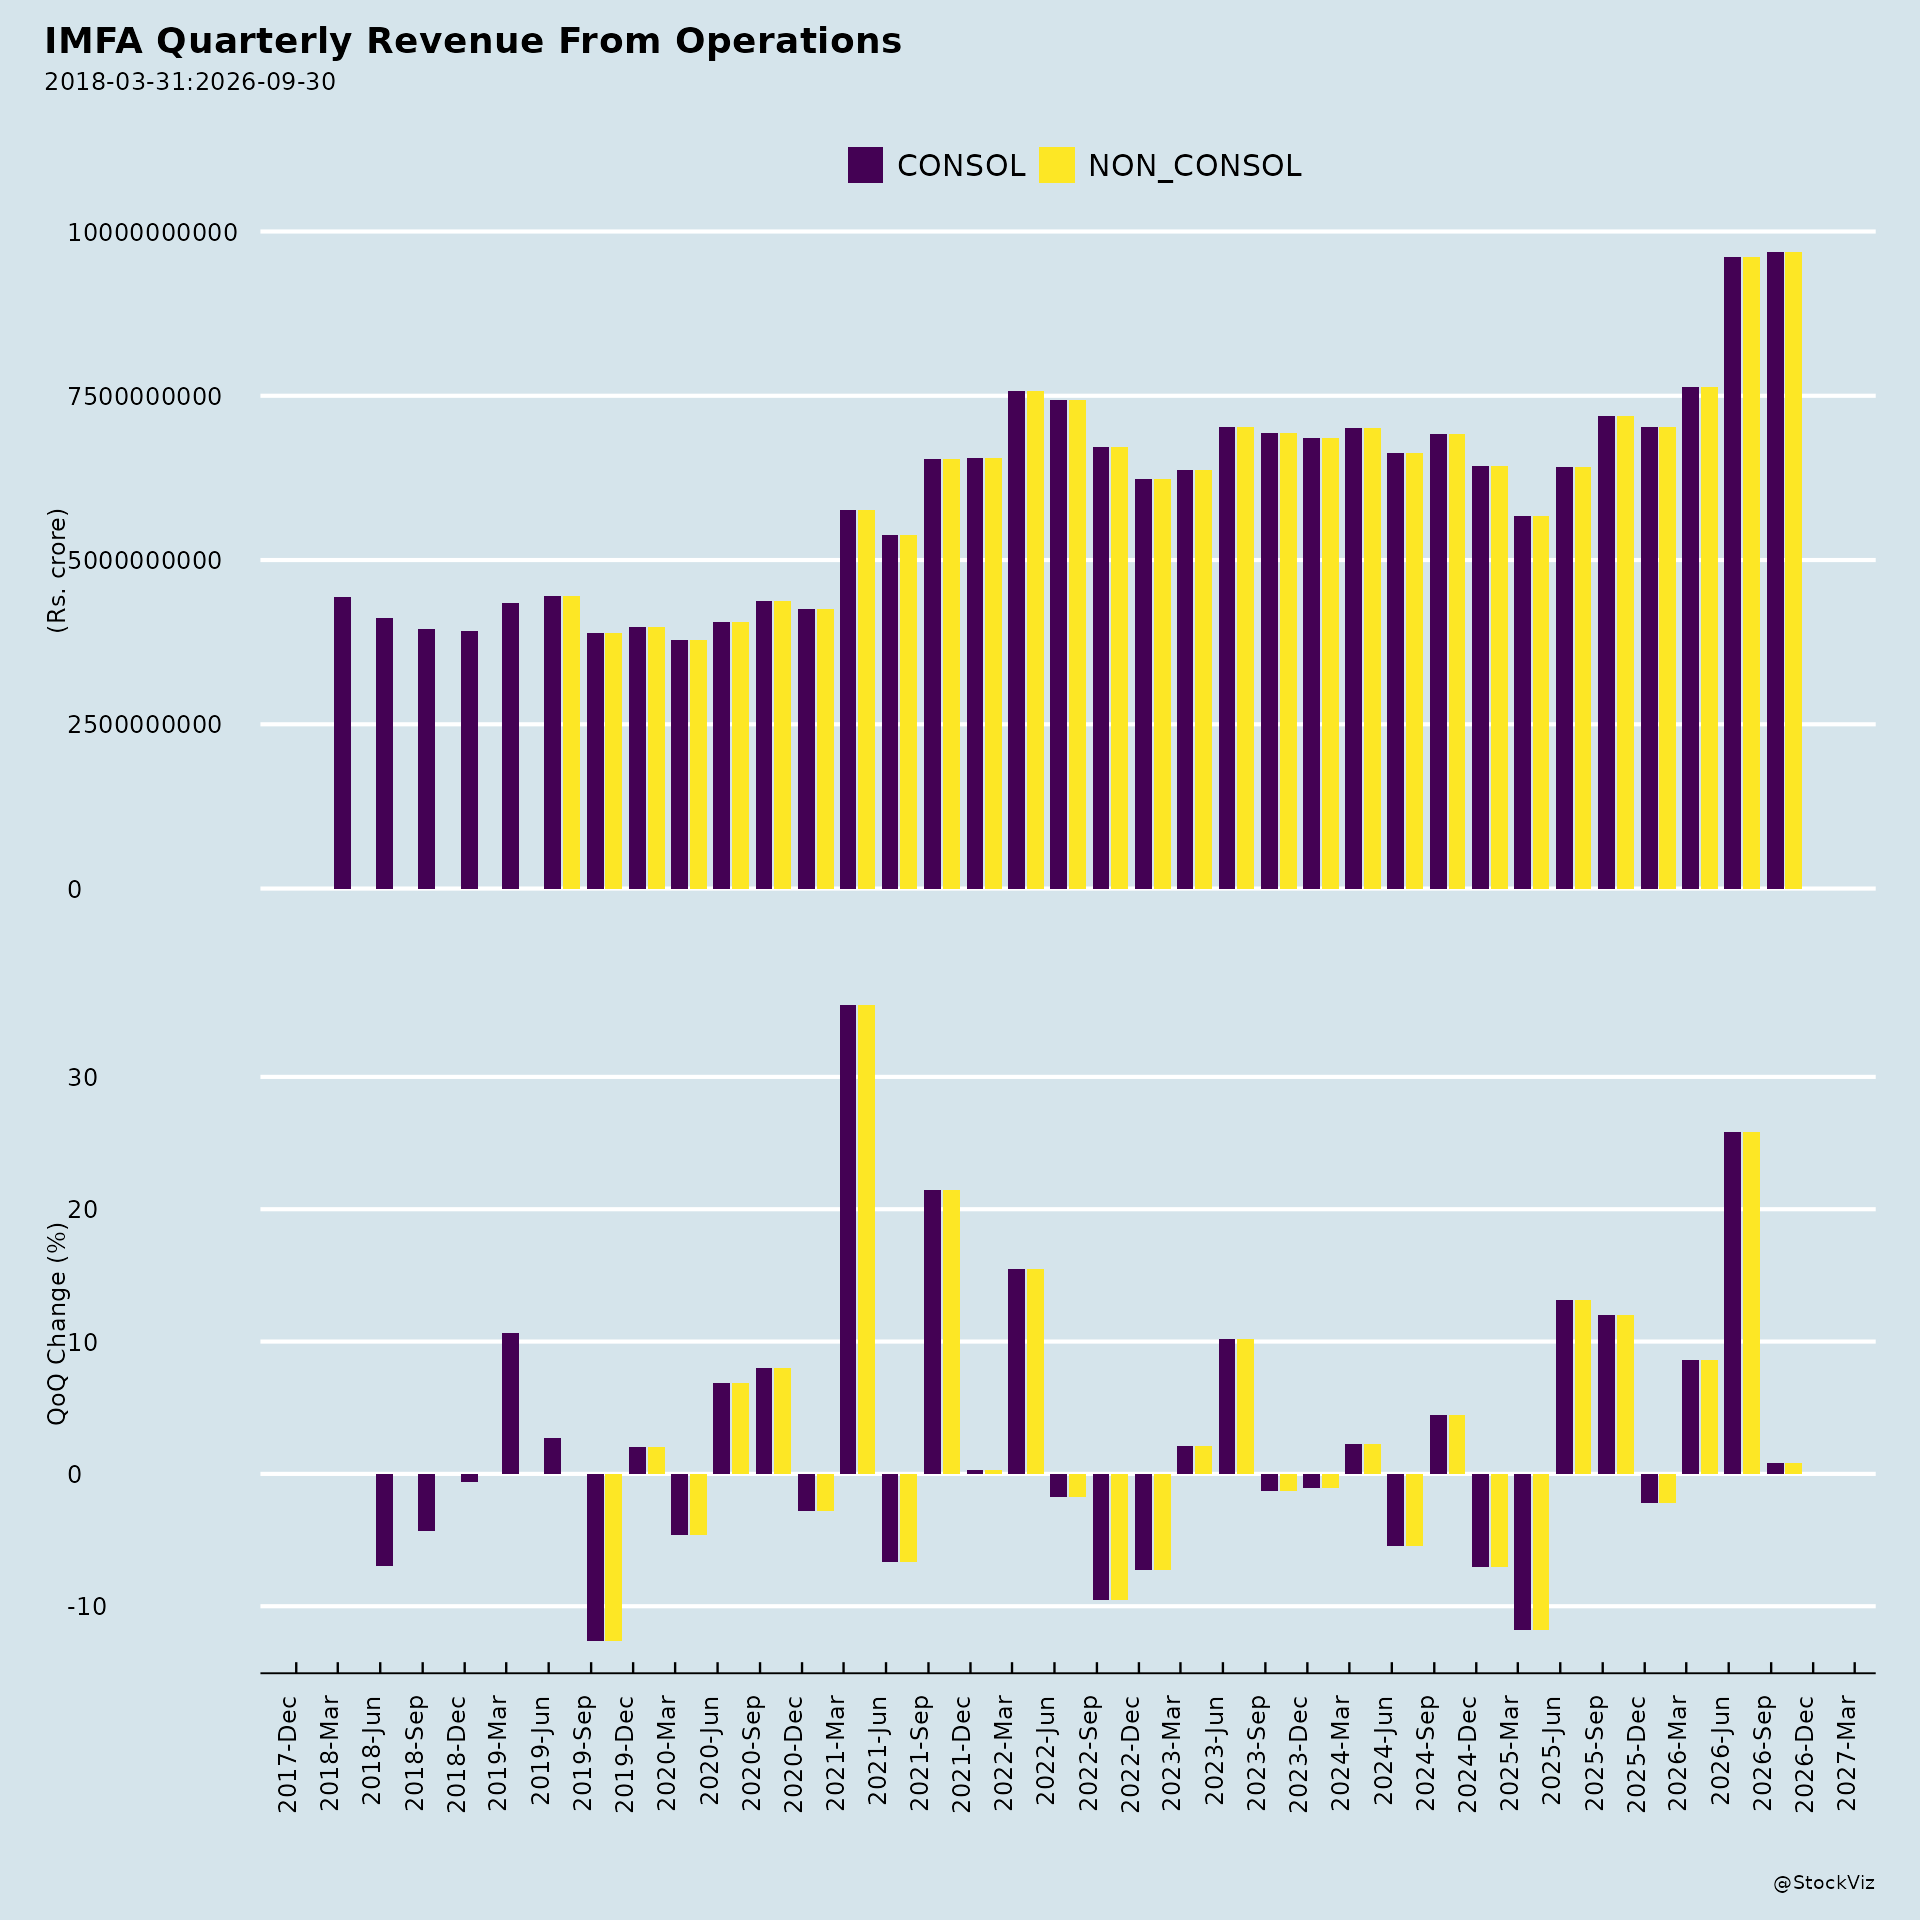
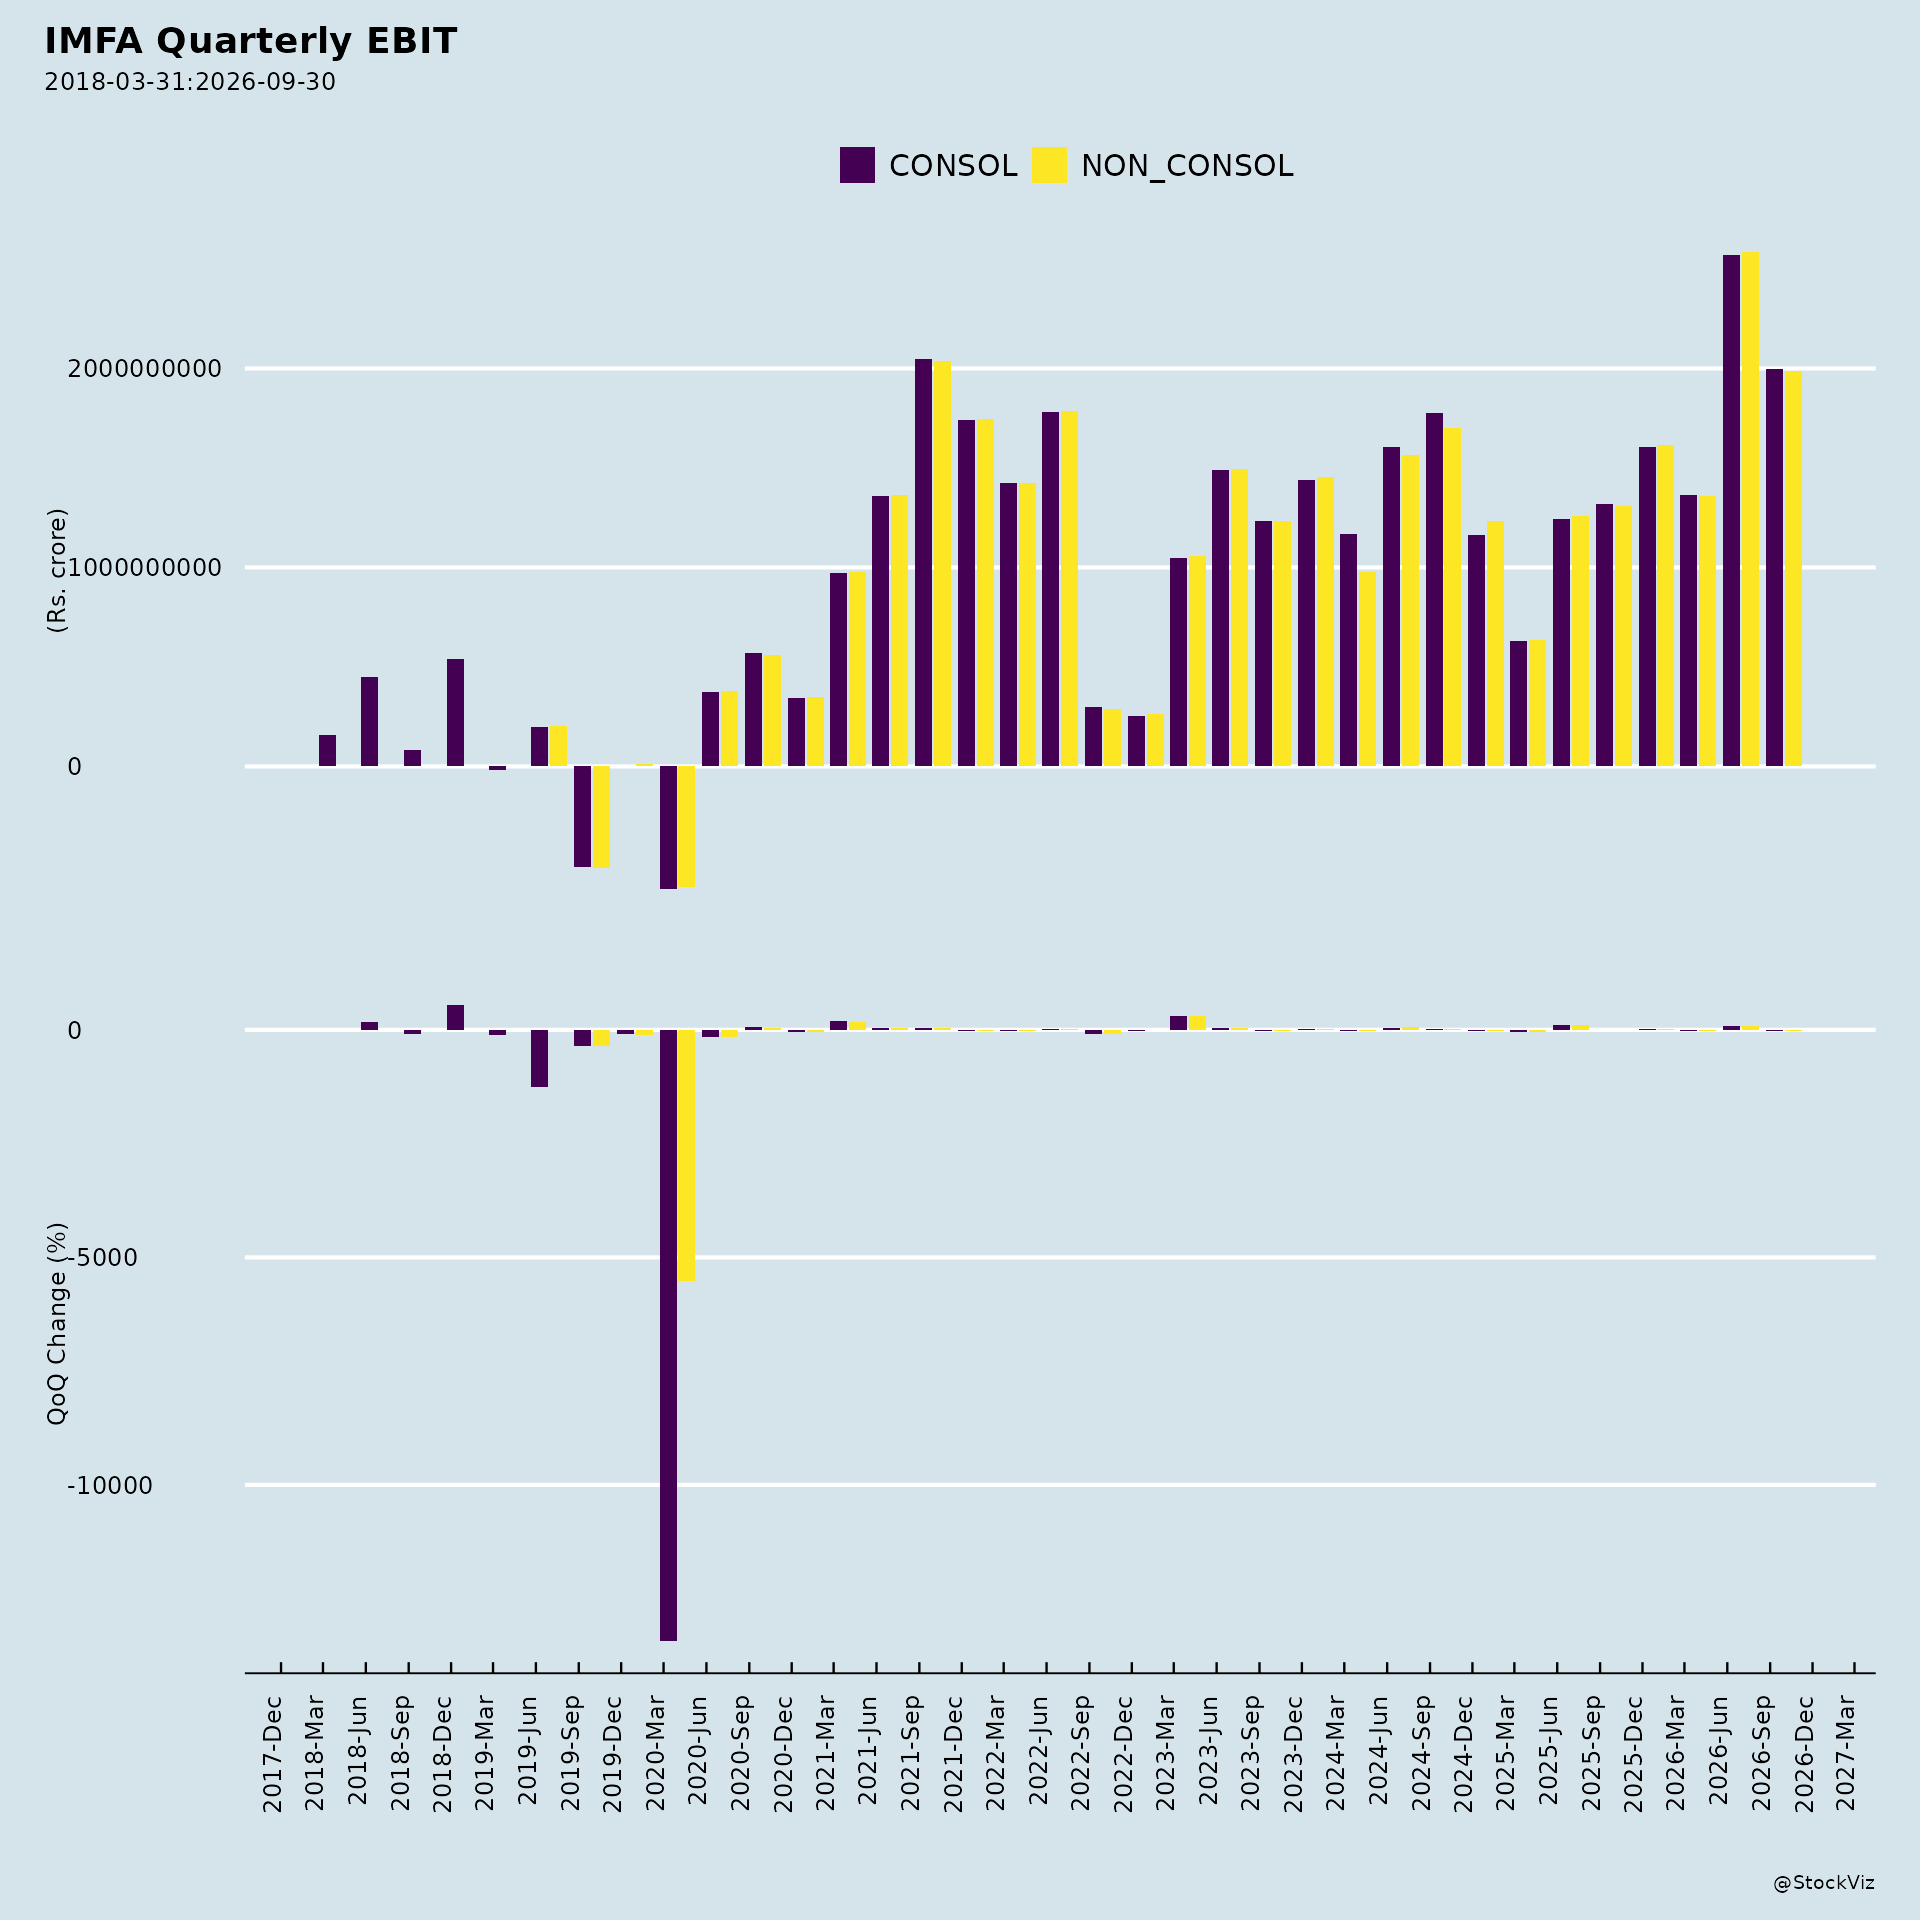
- Record financial performance. Q1 FY27 revenue grew 49.71% year-on-year to ₹960.45 crore, with EBITDA of ₹281.27 crore and PAT of ₹191.49 crore, driven by higher volumes and firm prices. The company maintains a net debt-free business model with strong backward integration.
- Ferro chrome expansion at Kalinganagar. The first tapping of hot metal from the first furnace in the greenfield ferro chrome expansion project (KNR-1) commenced on 25th August 2026, following an earlier disclosure dated 24th July 2026. KNR 2 is fully operational with all four furnaces running. Installed ferro chrome capacity stands at 384k TPA for FY26 and is set to increase to 484k TPA in FY27, with total furnace capacity of 289 MVA.
- Renewable energy expansion. A long-term offtake arrangement with Enfinity Global for an additional 65 MWp hybrid renewable energy is expected by June 2027. Separately, the Holding Company entered into a definitive agreement for procurement of renewable power under a captive consumption arrangement, acquiring equity interest for an aggregate consideration of ₹110.18 crore, payable in tranches up to June 2027.
- Ethanol diversification. The grain-based ethanol project at Therubali is nearing completion, with a trial run expected in October 2026 and commissioning in November 2026.
- Governance developments. Dr Deepak Kumar Mohanty was appointed as a Non-Executive Independent Director for five years starting 30th June 2026, and payment of commission to Independent Directors was enhanced. Both resolutions were approved by members through postal ballot remote e-voting on 10th September 2026. The Board also approved unaudited standalone and consolidated financial results for the quarter ended 30th June 2026, along with reconstitution of committees and appointment of senior management personnel.
- Investor engagement. The company is scheduled to participate in a group meeting at the Anand Rathi Annual Flagship Conference G-200 Summit 2026 on Monday, September 21, 2026, in Mumbai, with no unpublished price sensitive information to be discussed.
Key Risks
- Financial and sector-wide implications from the Supreme Court judgment upholding States’ right to levy on mineral bearing land, with the Orissa Rural Infrastructure and Socio-Economic Development Act, 2004 matter still sub-judice.
- Regulatory compliance risk highlighted by the SEBI administrative warning over insider trading contraventions by middle management designated persons.
- Execution and timing risk on the ethanol project due to geopolitical and monsoon-related disruptions.
- Dependence on the ramp-up of the greenfield KNR-1 project, where production volume is to be gradually increased in due course.
Management Guidance Versus Observed Performance
- KNR-1 first furnace tapping. Management guided hot metal tapping for the first furnace in the third week of August 2026. Observed: first tapping commenced on 25th August 2026, broadly in line with guidance.
- KNR-1 second furnace. Management indicated the second furnace was likely to be commissioned in September 2026. No confirmation of commissioning appears in the supplied material.
- Greenfield project stabilisation. Management expects the Greenfield Project (KNR 1) to be fully commissioned and stabilised by Q3, closing the year with operating smelting capacity of more than half a million tonnes. This remains forward-looking.
- Ethanol unit. Management guided a trial run in October 2026 and commissioning in November 2026, after earlier delays from geopolitical and monsoon-related disruptions. This remains forward-looking.
- Renewable energy share. Management expects approximately 40% of IMFA’s energy consumption to come from non-fossil sources by the middle of next year. This remains forward-looking.
- Financial performance. Management’s commentary on record revenue and robust performance is supported by observed Q1 FY27 results: revenue of ₹960.45 crore (up 49.71% YoY), EBITDA of ₹281.27 crore, and PAT of ₹191.49 crore, alongside ferro chrome production of 80,690 tonnes and sales of 79,268 tonnes.
Broker Narrative
The broker kept a persistent Buy rating and long-term growth thesis centered on captive mines, capacity expansion, and cost advantages, while repeatedly flagging ferrochrome price volatility and demand uncertainty. Over time, the narrative shifted from broad macro tailwinds (Indian stainless demand, import protections, ethanol) to near-term operational milestones and costs, specifically KNR-1/KNR-2 commissioning, thermal coal linkages, and hybrid renewable energy, with greater emphasis on logistics and freight headwinds.
Fears that came true
- Lower offtake volume materialized, contradicting expectations of rising demand and supporting last report’s negative actual return.
- Delay in commissioning of facilities materialized: KNR-1 was delayed to Sep-26 due to labour availability and summer productivity issues.
- Higher freight and domestic logistics costs materialized, attributed to the Middle East crisis, undermining cost-optimization hopes.
Optimism that failed
- Phase-I capacity expansion to ~384,000 tonnes by mid-CY26 failed to materialize on the original timeline, with KNR-1 only expected in phases by Sep-26.
- Expected cost optimization from Kalinganagar’s proximity to mines failed to offset higher logistics and freight costs.
- Expected volume growth from rising Indian stainless-steel demand and import protections did not prevent lower offtake volume.
Broker Timeline
2 broker calls · 2025-09-22 to 2026-05-28
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.