IIFL
Equity Metrics
November 18, 2026
IIFL Finance Limited
Non Banking Financial Company (NBFC)
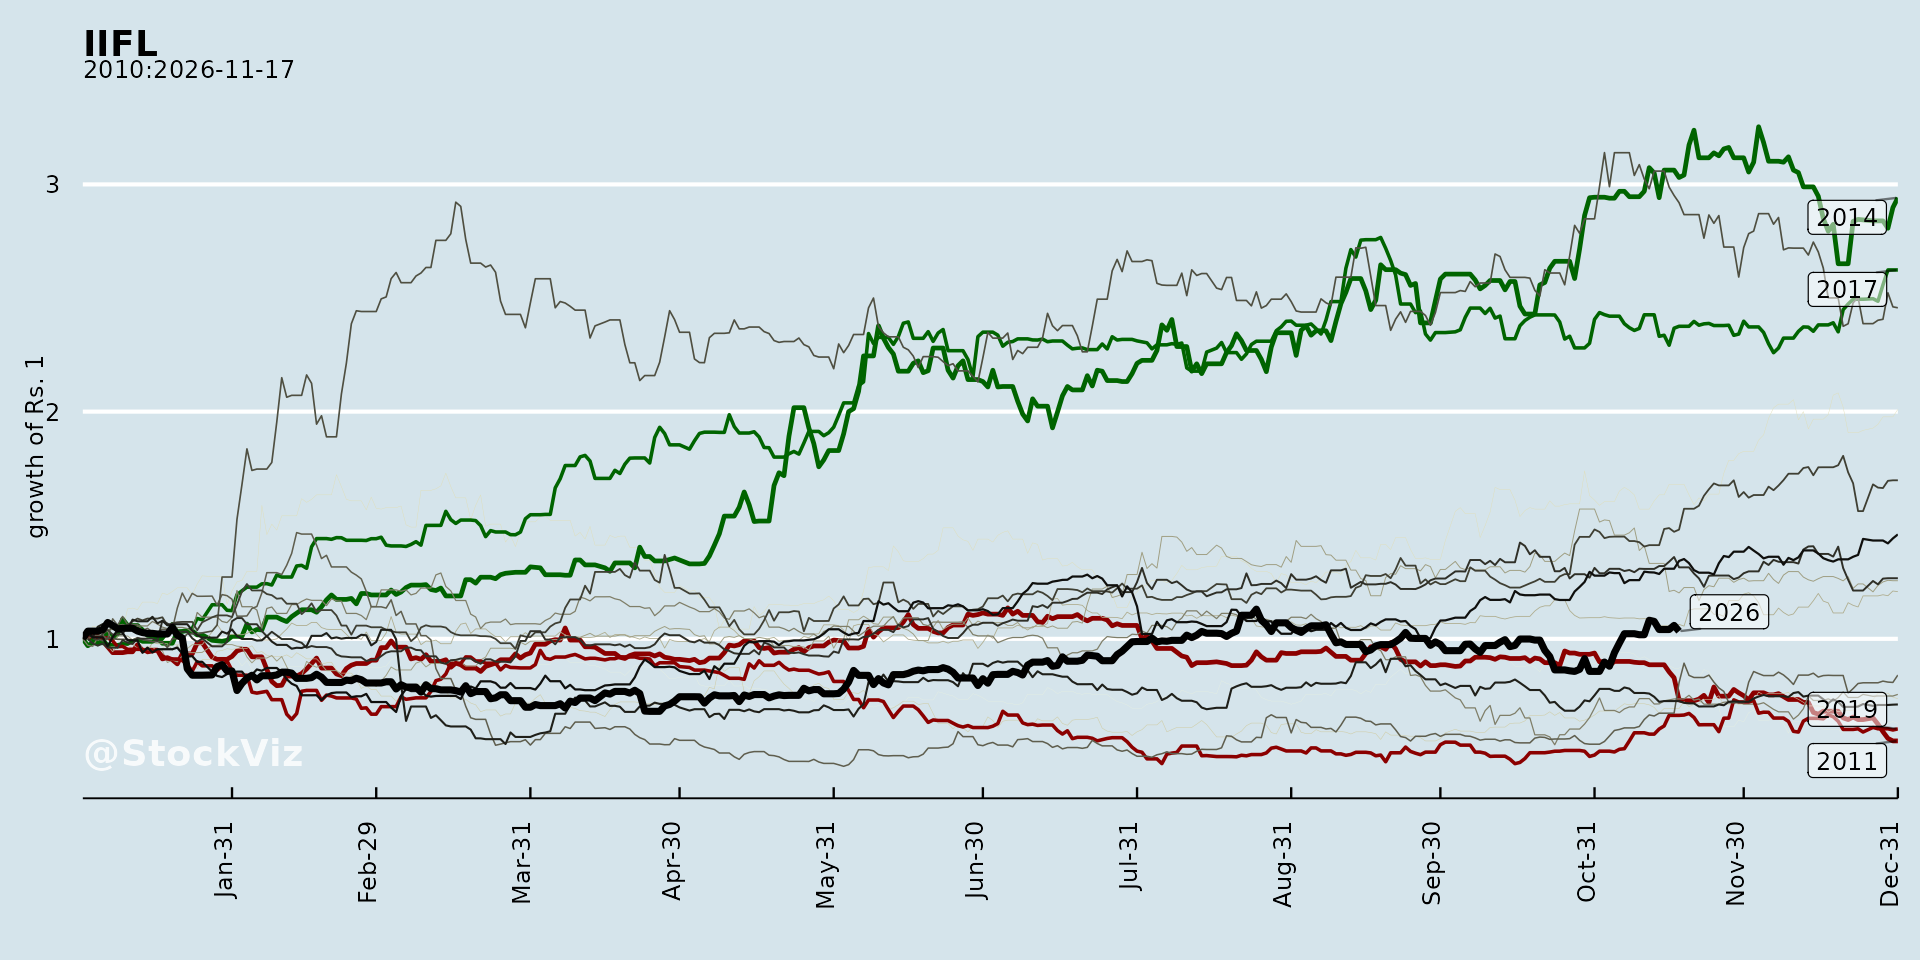
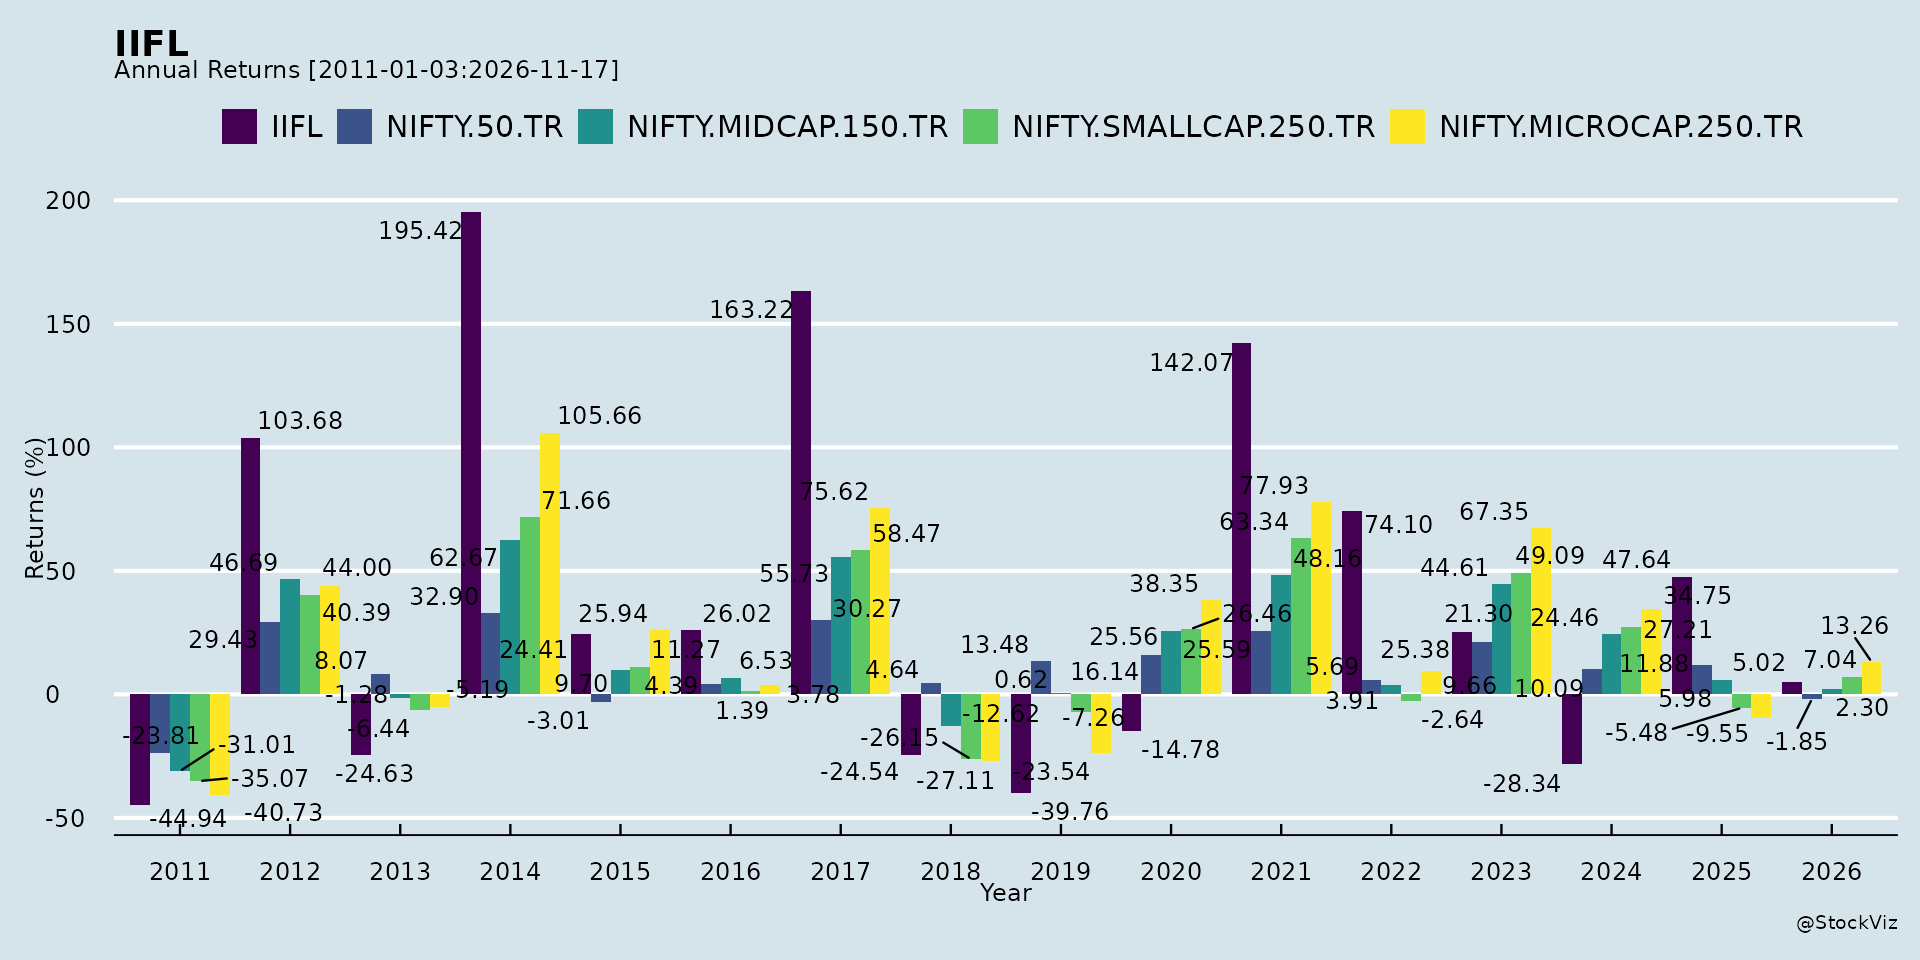
Annual Returns
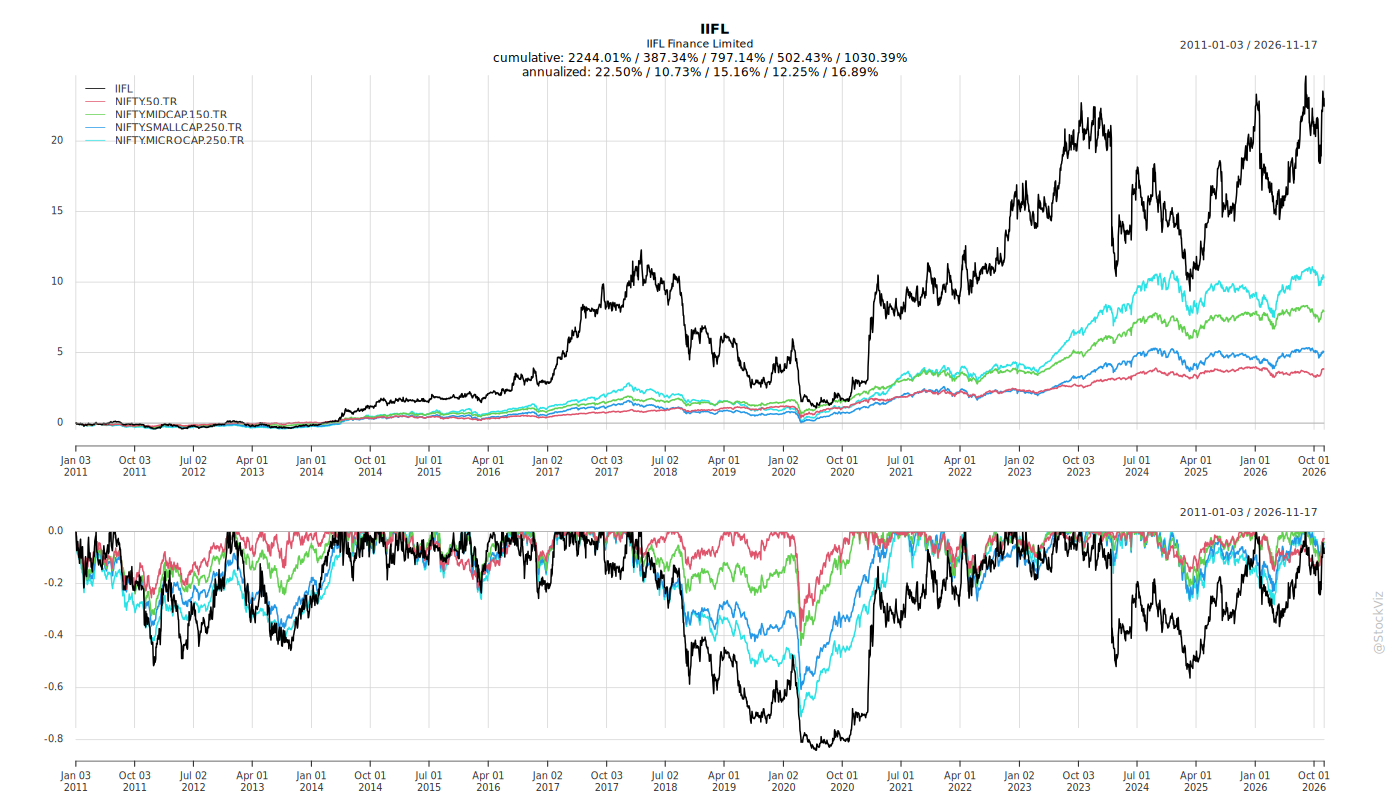
Cumulative Returns and Drawdowns
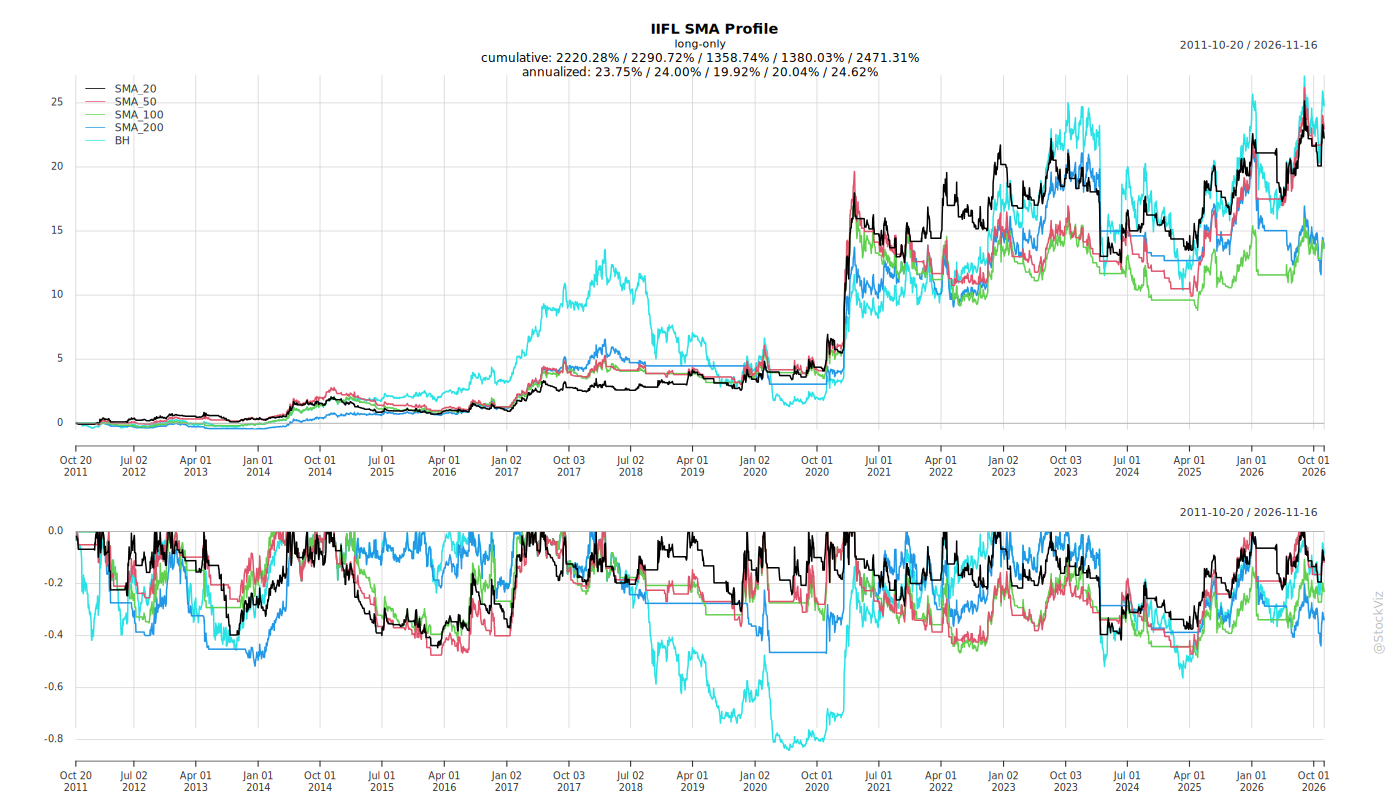
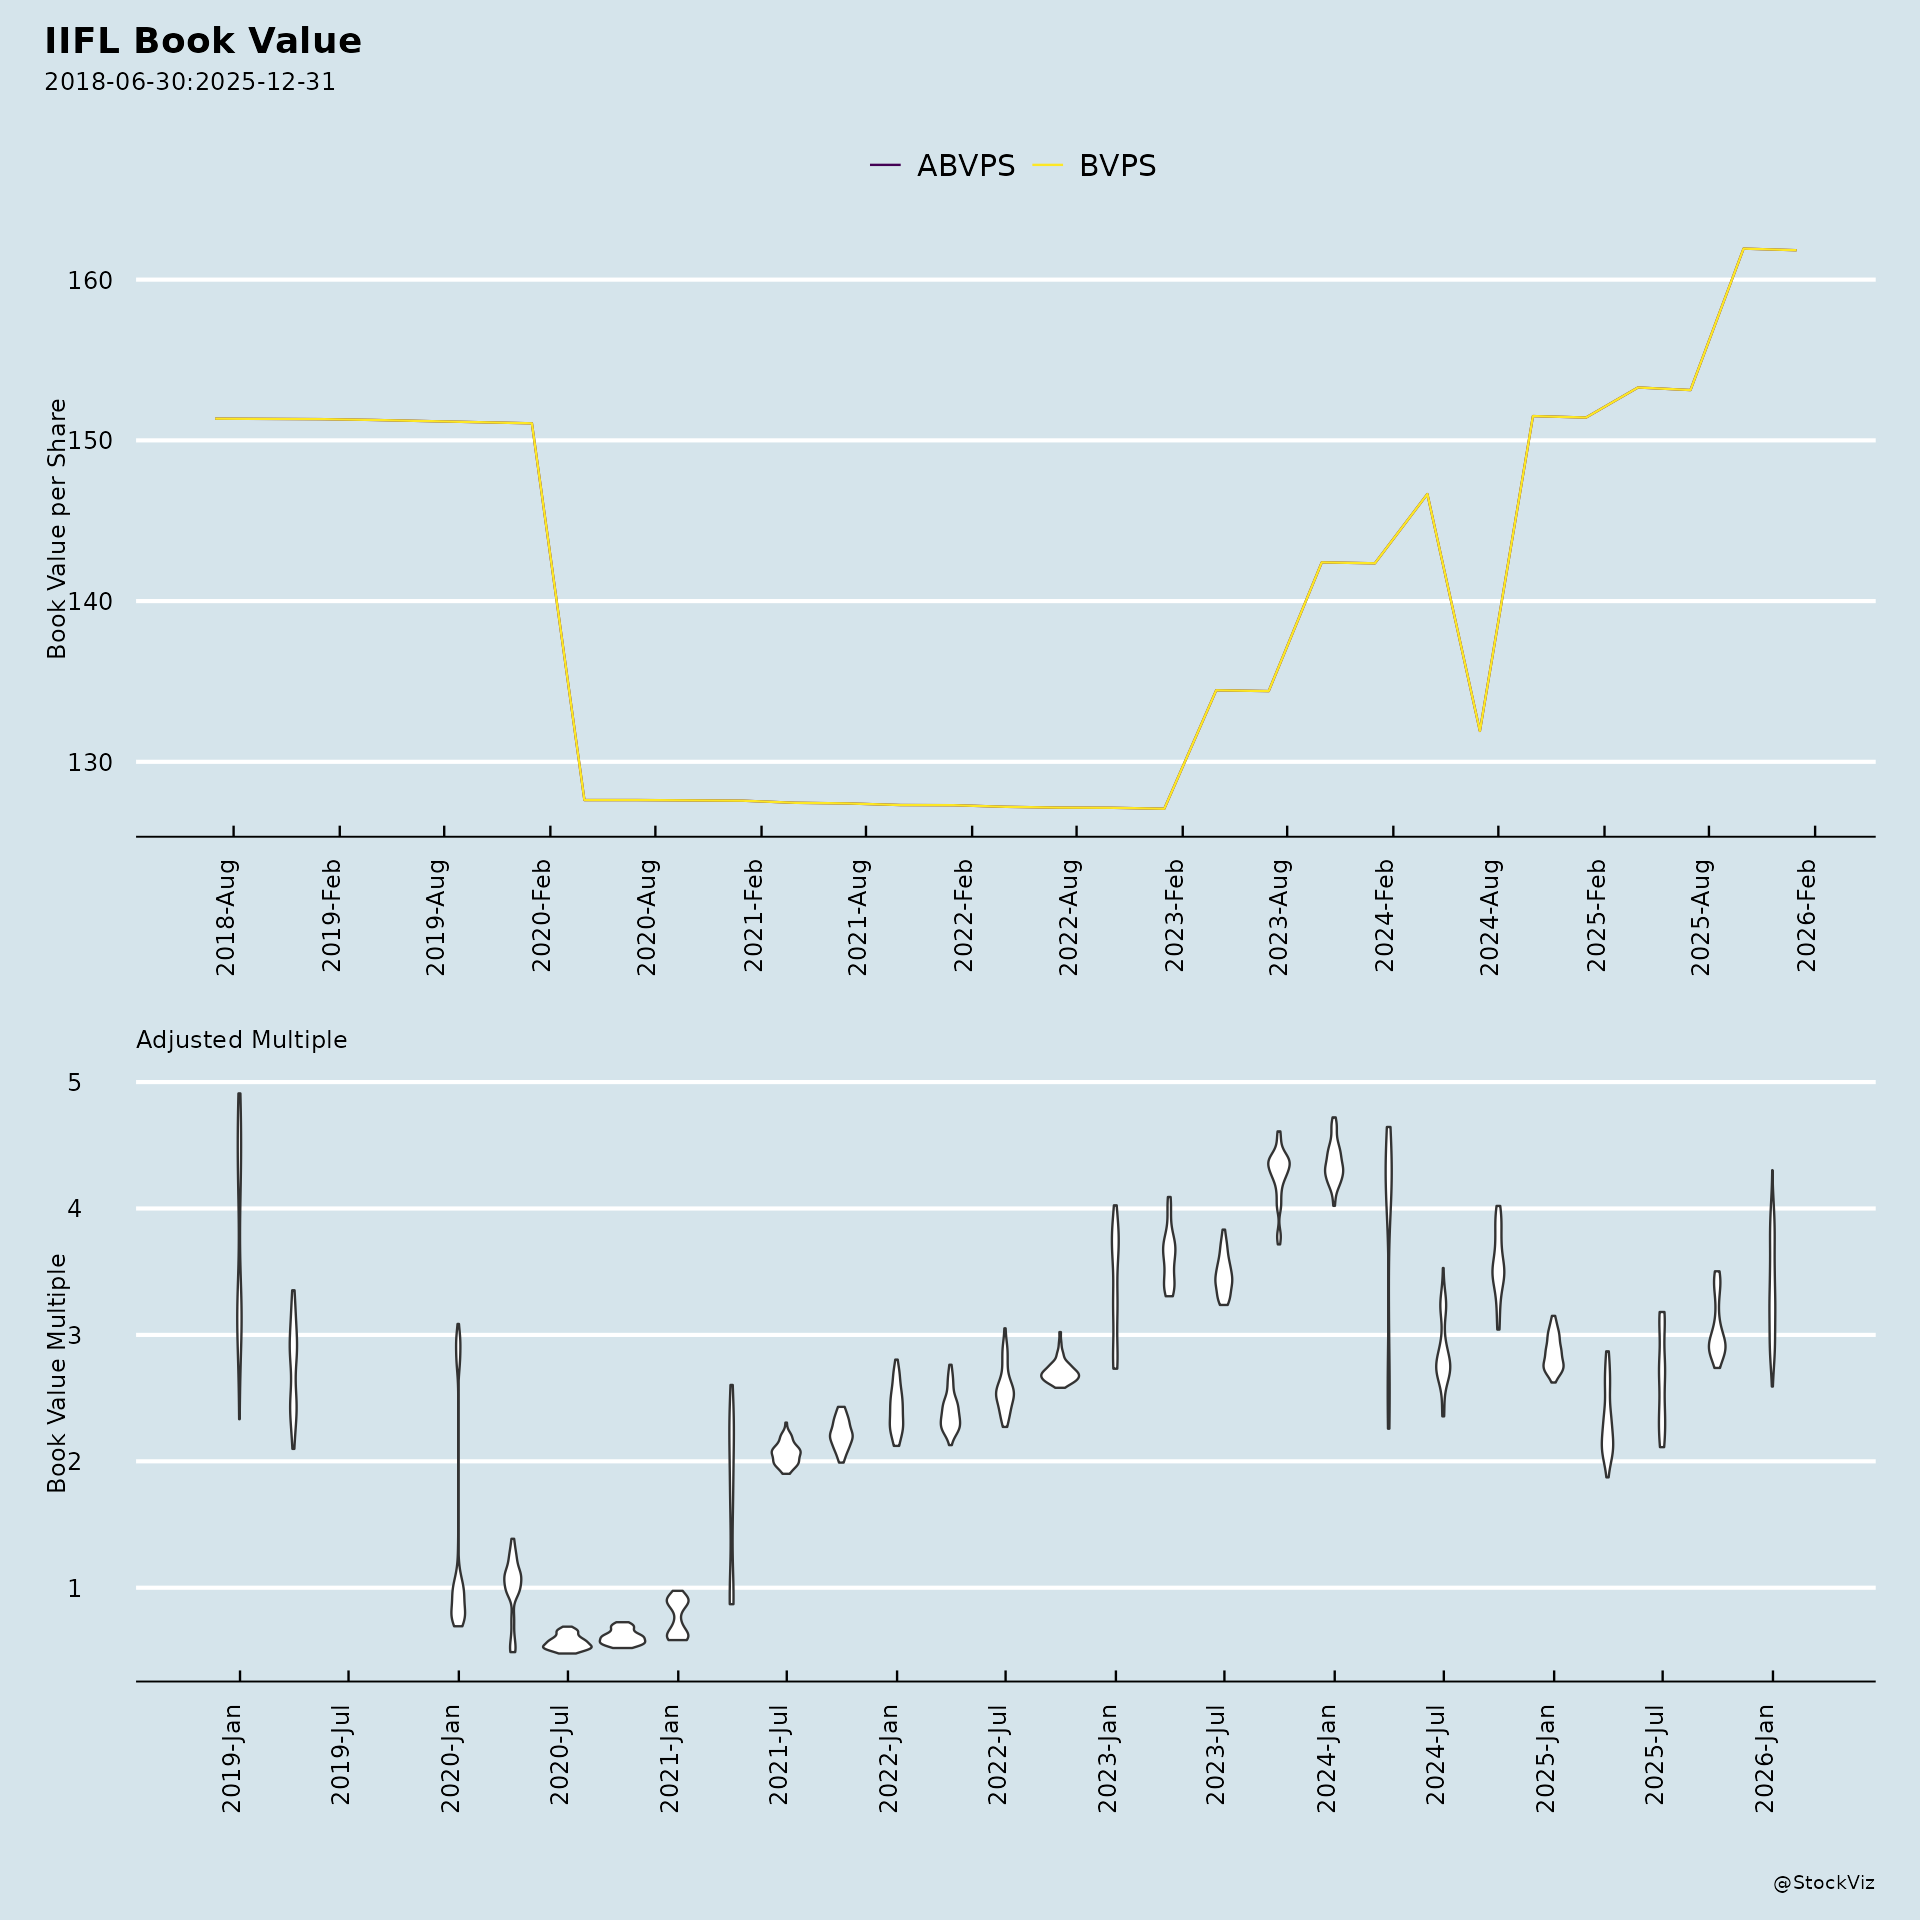
Fundamentals
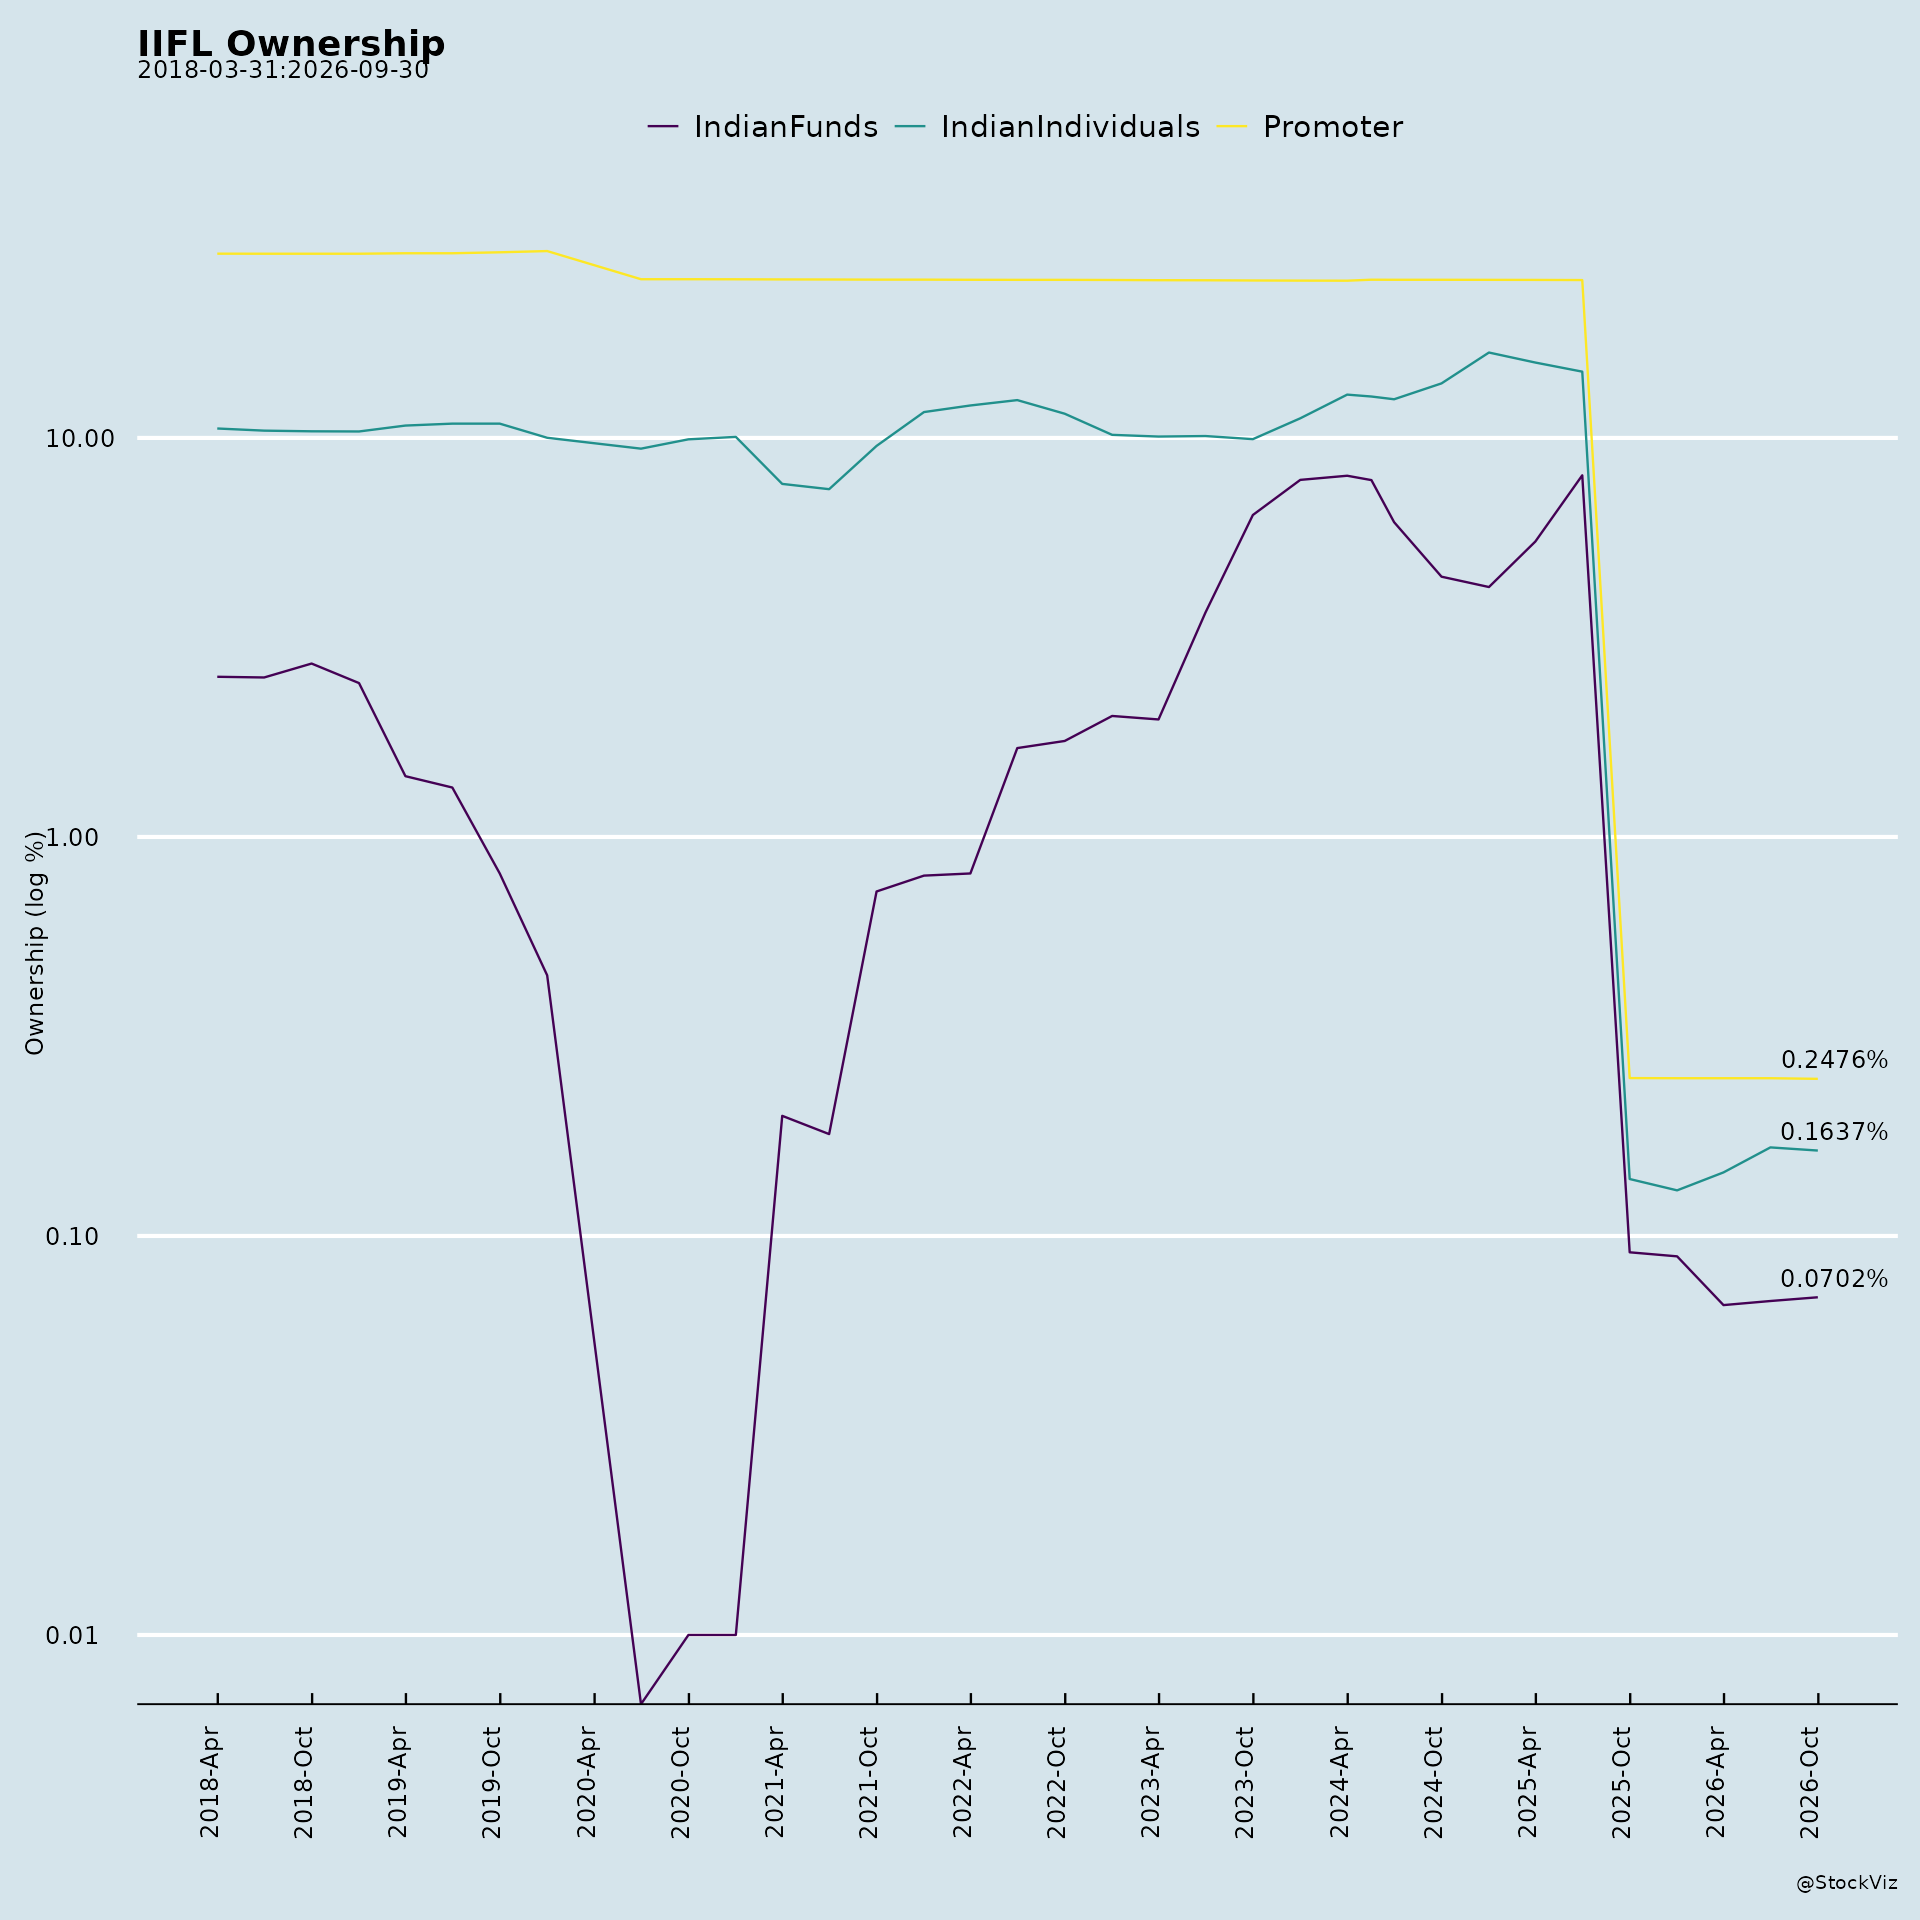
Ownership
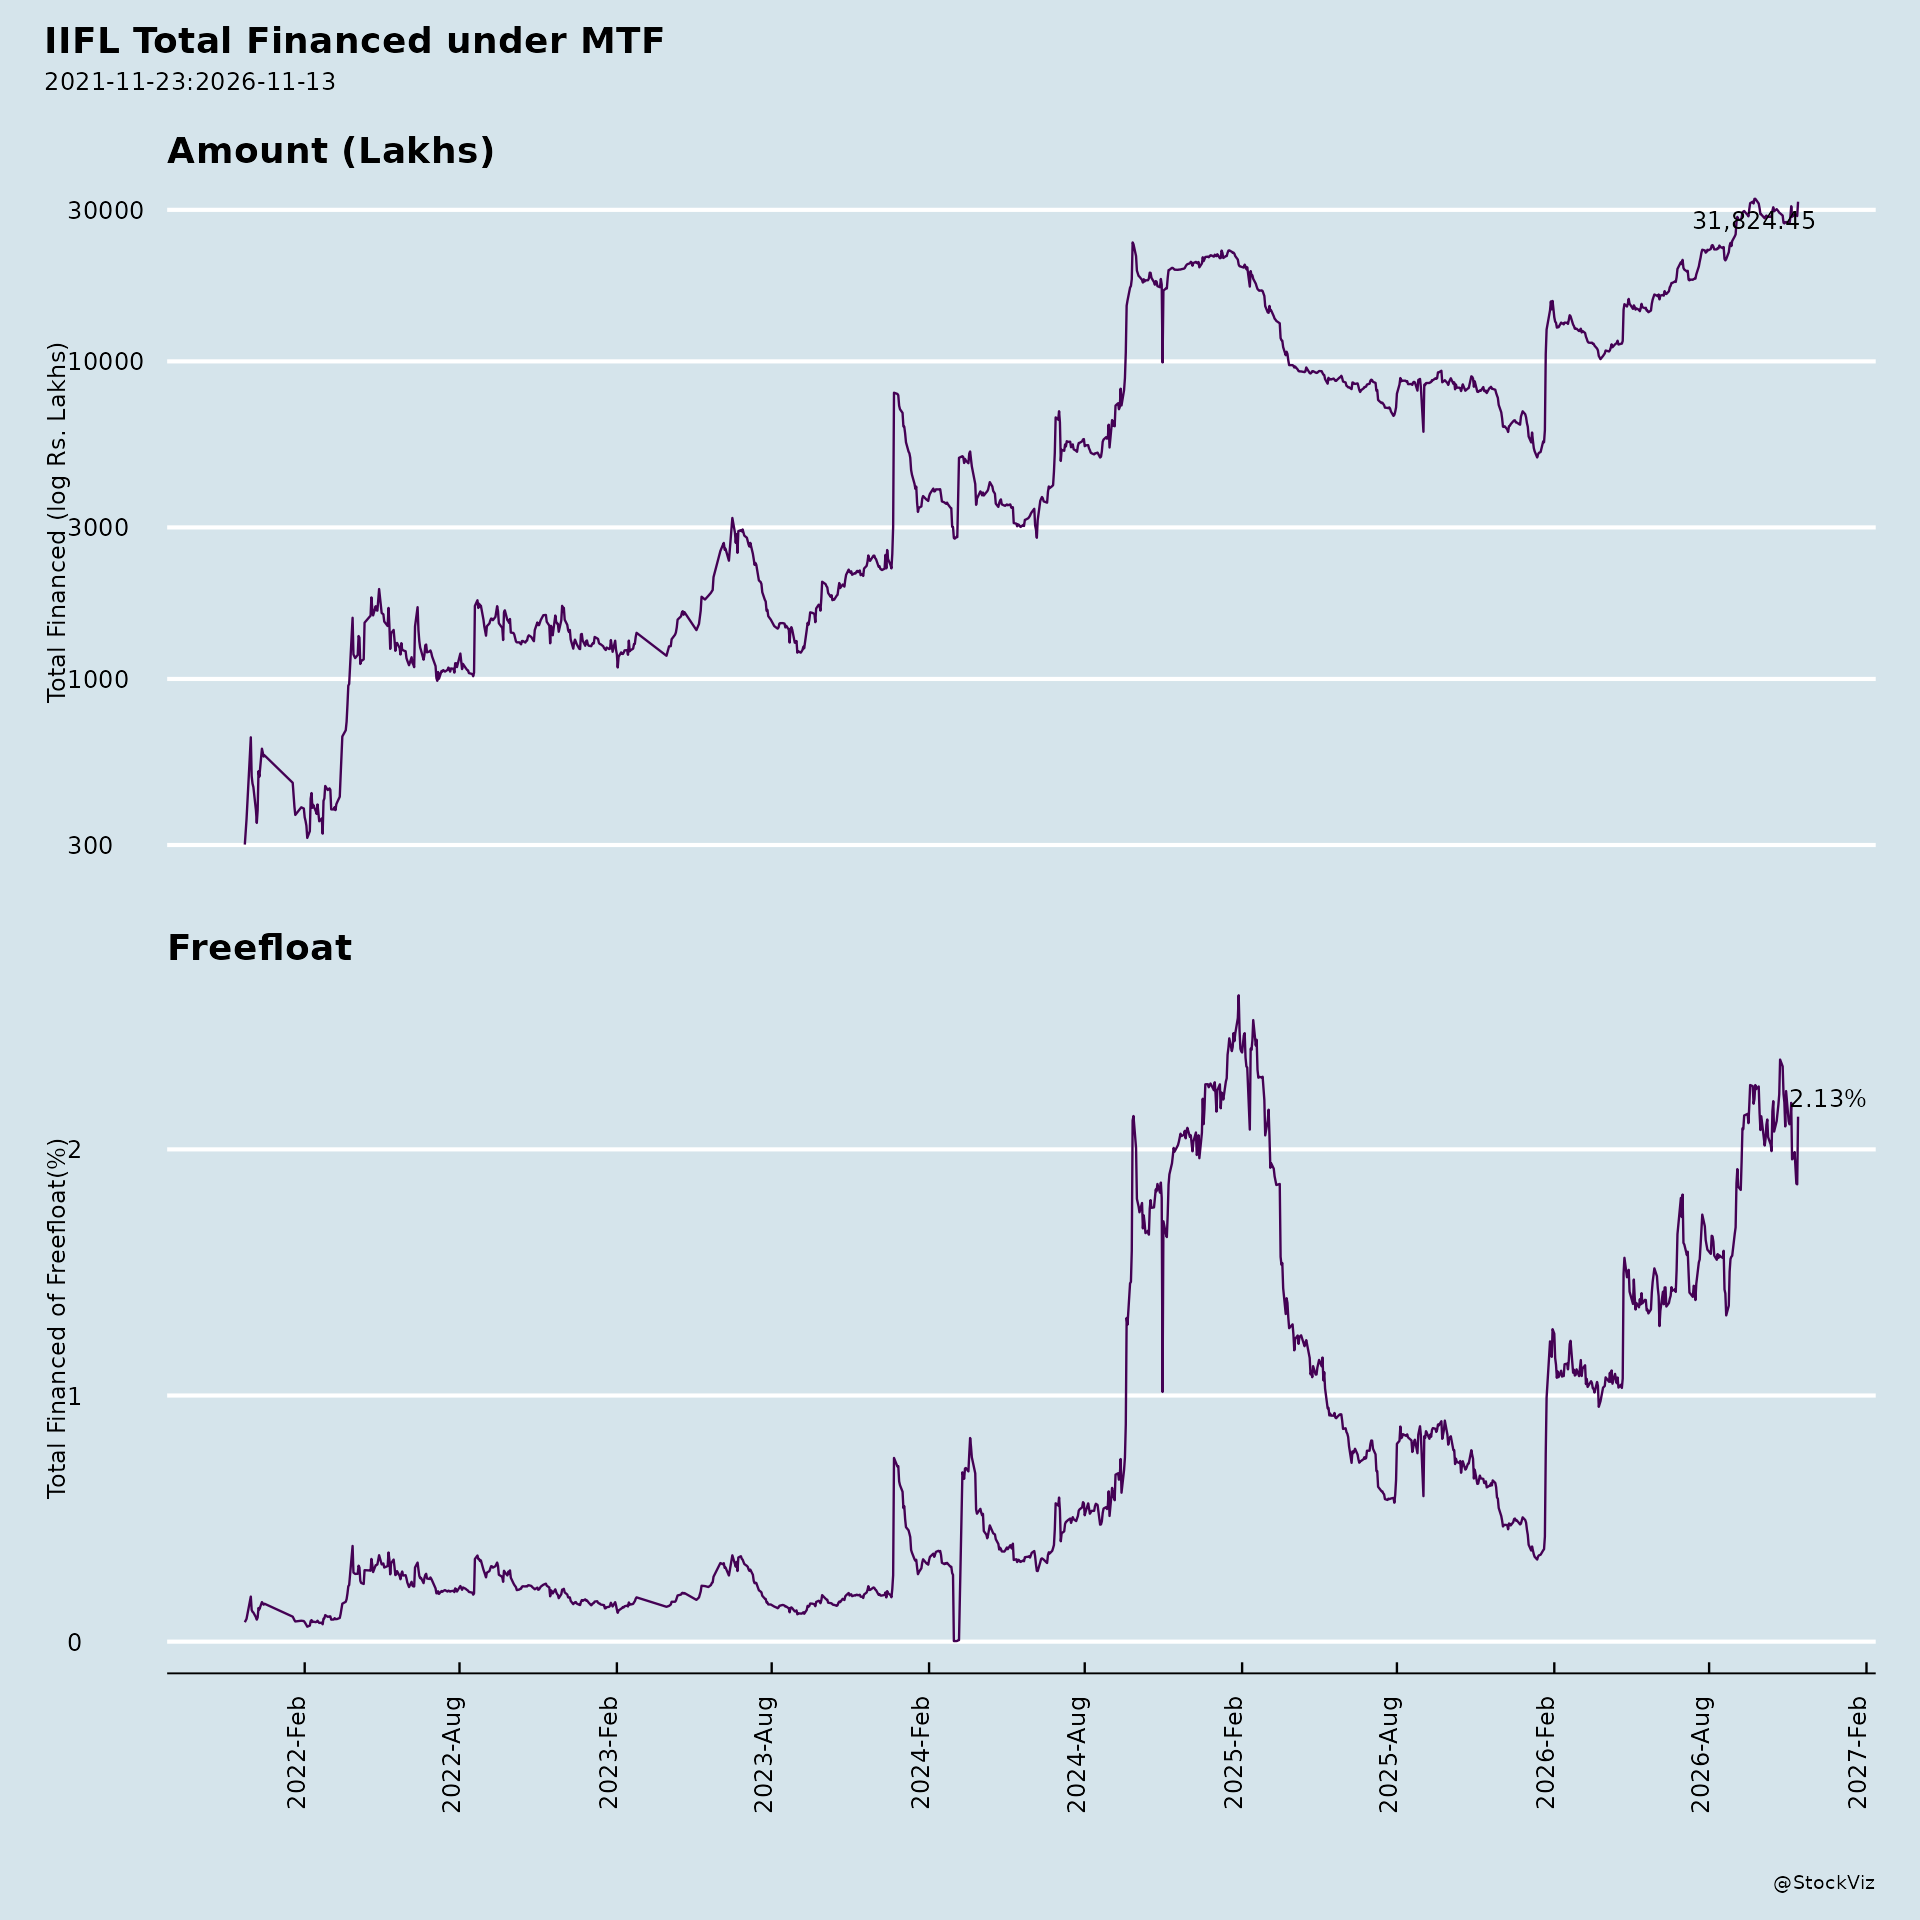
Margined
AI Summary
asof: 2026-09-16
IIFL Finance: Recent Corporate Announcements — Analysis
1. Headwinds and Challenges
- Governance and shareholder dissent: At the 31st AGM held on July 24, 2026, several resolutions drew notable opposition. The appointment of Mr. Gopalakrishnan Soundarajan as a Director liable to retire by rotation (Resolution 2) saw 24,931,228 votes against from Public Institutions, with only 67.47% of votes polled in favour within that category. The payment of commission to Non-Executive Directors (Resolution 5) also attracted 1,813,728 votes against from Public Institutions (2.06% of votes polled in that category). These dissent levels indicate some institutional shareholder unease with board and remuneration matters.
- Low retail participation: Public Non-Institution (retail) shareholders held 184,792,149 shares but only 48.11% of their outstanding shares were polled on most resolutions, and on related-party transaction resolutions (6–10) retail polling dropped to just 13.18%. This suggests limited retail engagement in key governance decisions.
- Related-party transaction scrutiny: Resolutions 6 through 10 sought approval for material related-party transactions with IIFL Home Finance Limited, IIFL Samasta Finance Limited, IIFL Facilities Services Limited, IIFL Management Services Limited, and IIFL Capital Services Limited. Resolution 10 explicitly noted that the promoter/promoter group were interested parties. These resolutions passed, but the need for repeated shareholder approval of material RPTs reflects the group’s ongoing related-party exposure.
2. Tailwinds and Growth Prospects
- Fundraising flexibility approved: The AGM passed a Special Resolution (Resolution 15) authorising the raising of funds through the issue of equity shares or other eligible securities by way of Qualified Institutions Placement (QIP), Follow-On Public Offer (FPO), or any other permissible mode. This provides the company with a broad mandate to raise capital.
- Borrowing capacity enhanced: Shareholders approved enhancement of borrowing limits under Section 180(1)(c) (Resolution 13) and Section 180(1)(a) (Resolution 14) of the Companies Act, 2013, both as Special Resolutions. This expands the company’s headroom to raise debt.
- Non-convertible securities issuance approved: Resolution 4 (Special Resolution) approved the issuance of Non-Convertible Securities on a private placement basis, supporting debt-raising plans.
- Debt investor engagement: The company scheduled a Debt Investor Call as a group meeting on August 19, 2026, and made a Q1FY27 Debt Investor Presentation available on its website (intimated August 18, 2026, referencing an earlier intimation dated August 14, 2026). This indicates active engagement with debt investors following the quarter.
- Related-party synergies: Approval of material related-party transactions with group entities (IIFL Home Finance, IIFL Samasta Finance, IIFL Facilities Services, IIFL Management Services, IIFL Capital Services) supports continued operational integration across the IIFL group.
3. Key Risks
- Concentration of promoter voting power: Promoter and Promoter Group held 105,674,667 shares and voted 94,563,556 shares (89.49% of their holding) in favour of all resolutions. On resolutions where promoters were interested (e.g., Resolution 10), they did not vote, leaving outcomes dependent on public shareholders.
- Institutional dissent on board matters: The 32.53% against votes from Public Institutions on Resolution 2 (Director appointment) and 2.06% against on Resolution 5 (Non-Executive Director commission) signal potential governance-related risk.
- Related-party transaction risk: The multiple material RPT resolutions (6–10) and the explicit promoter interest in Resolution 10 highlight the risk associated with related-party dealings.
- Dilution risk: The QIP/FPO authorisation (Resolution 15) could lead to equity dilution depending on how funds are raised.
- Leverage risk: Enhanced borrowing limits under Sections 180(1)(a) and 180(1)(c) increase the company’s capacity to take on debt, which carries associated leverage risk.
4. Management Guidance Versus Observed Business Performance
The supplied material does not contain specific management guidance statements or financial performance figures for comparison. The documents are limited to:
- AGM voting results and scrutinizer’s report (July 28, 2026 filing, AGM held July 24, 2026).
- Schedule of Analyst/Institutional Investor Meeting (August 14, 2026) for a Debt Investor Call on August 19, 2026.
- Intimation (August 18, 2026) regarding the Q1FY27 Debt Investor Presentation made available on the company’s website.
The Q1FY27 Debt Investor Presentation is referenced by URL but its contents are not included in the supplied material, so no guidance-versus-performance comparison can be made from the available extracts. The AGM results confirm that the audited standalone and consolidated financial statements for the year ended March 31, 2026, were adopted with requisite majority (Resolution 1), but no financial figures are disclosed in the supplied material.
Broker Narrative
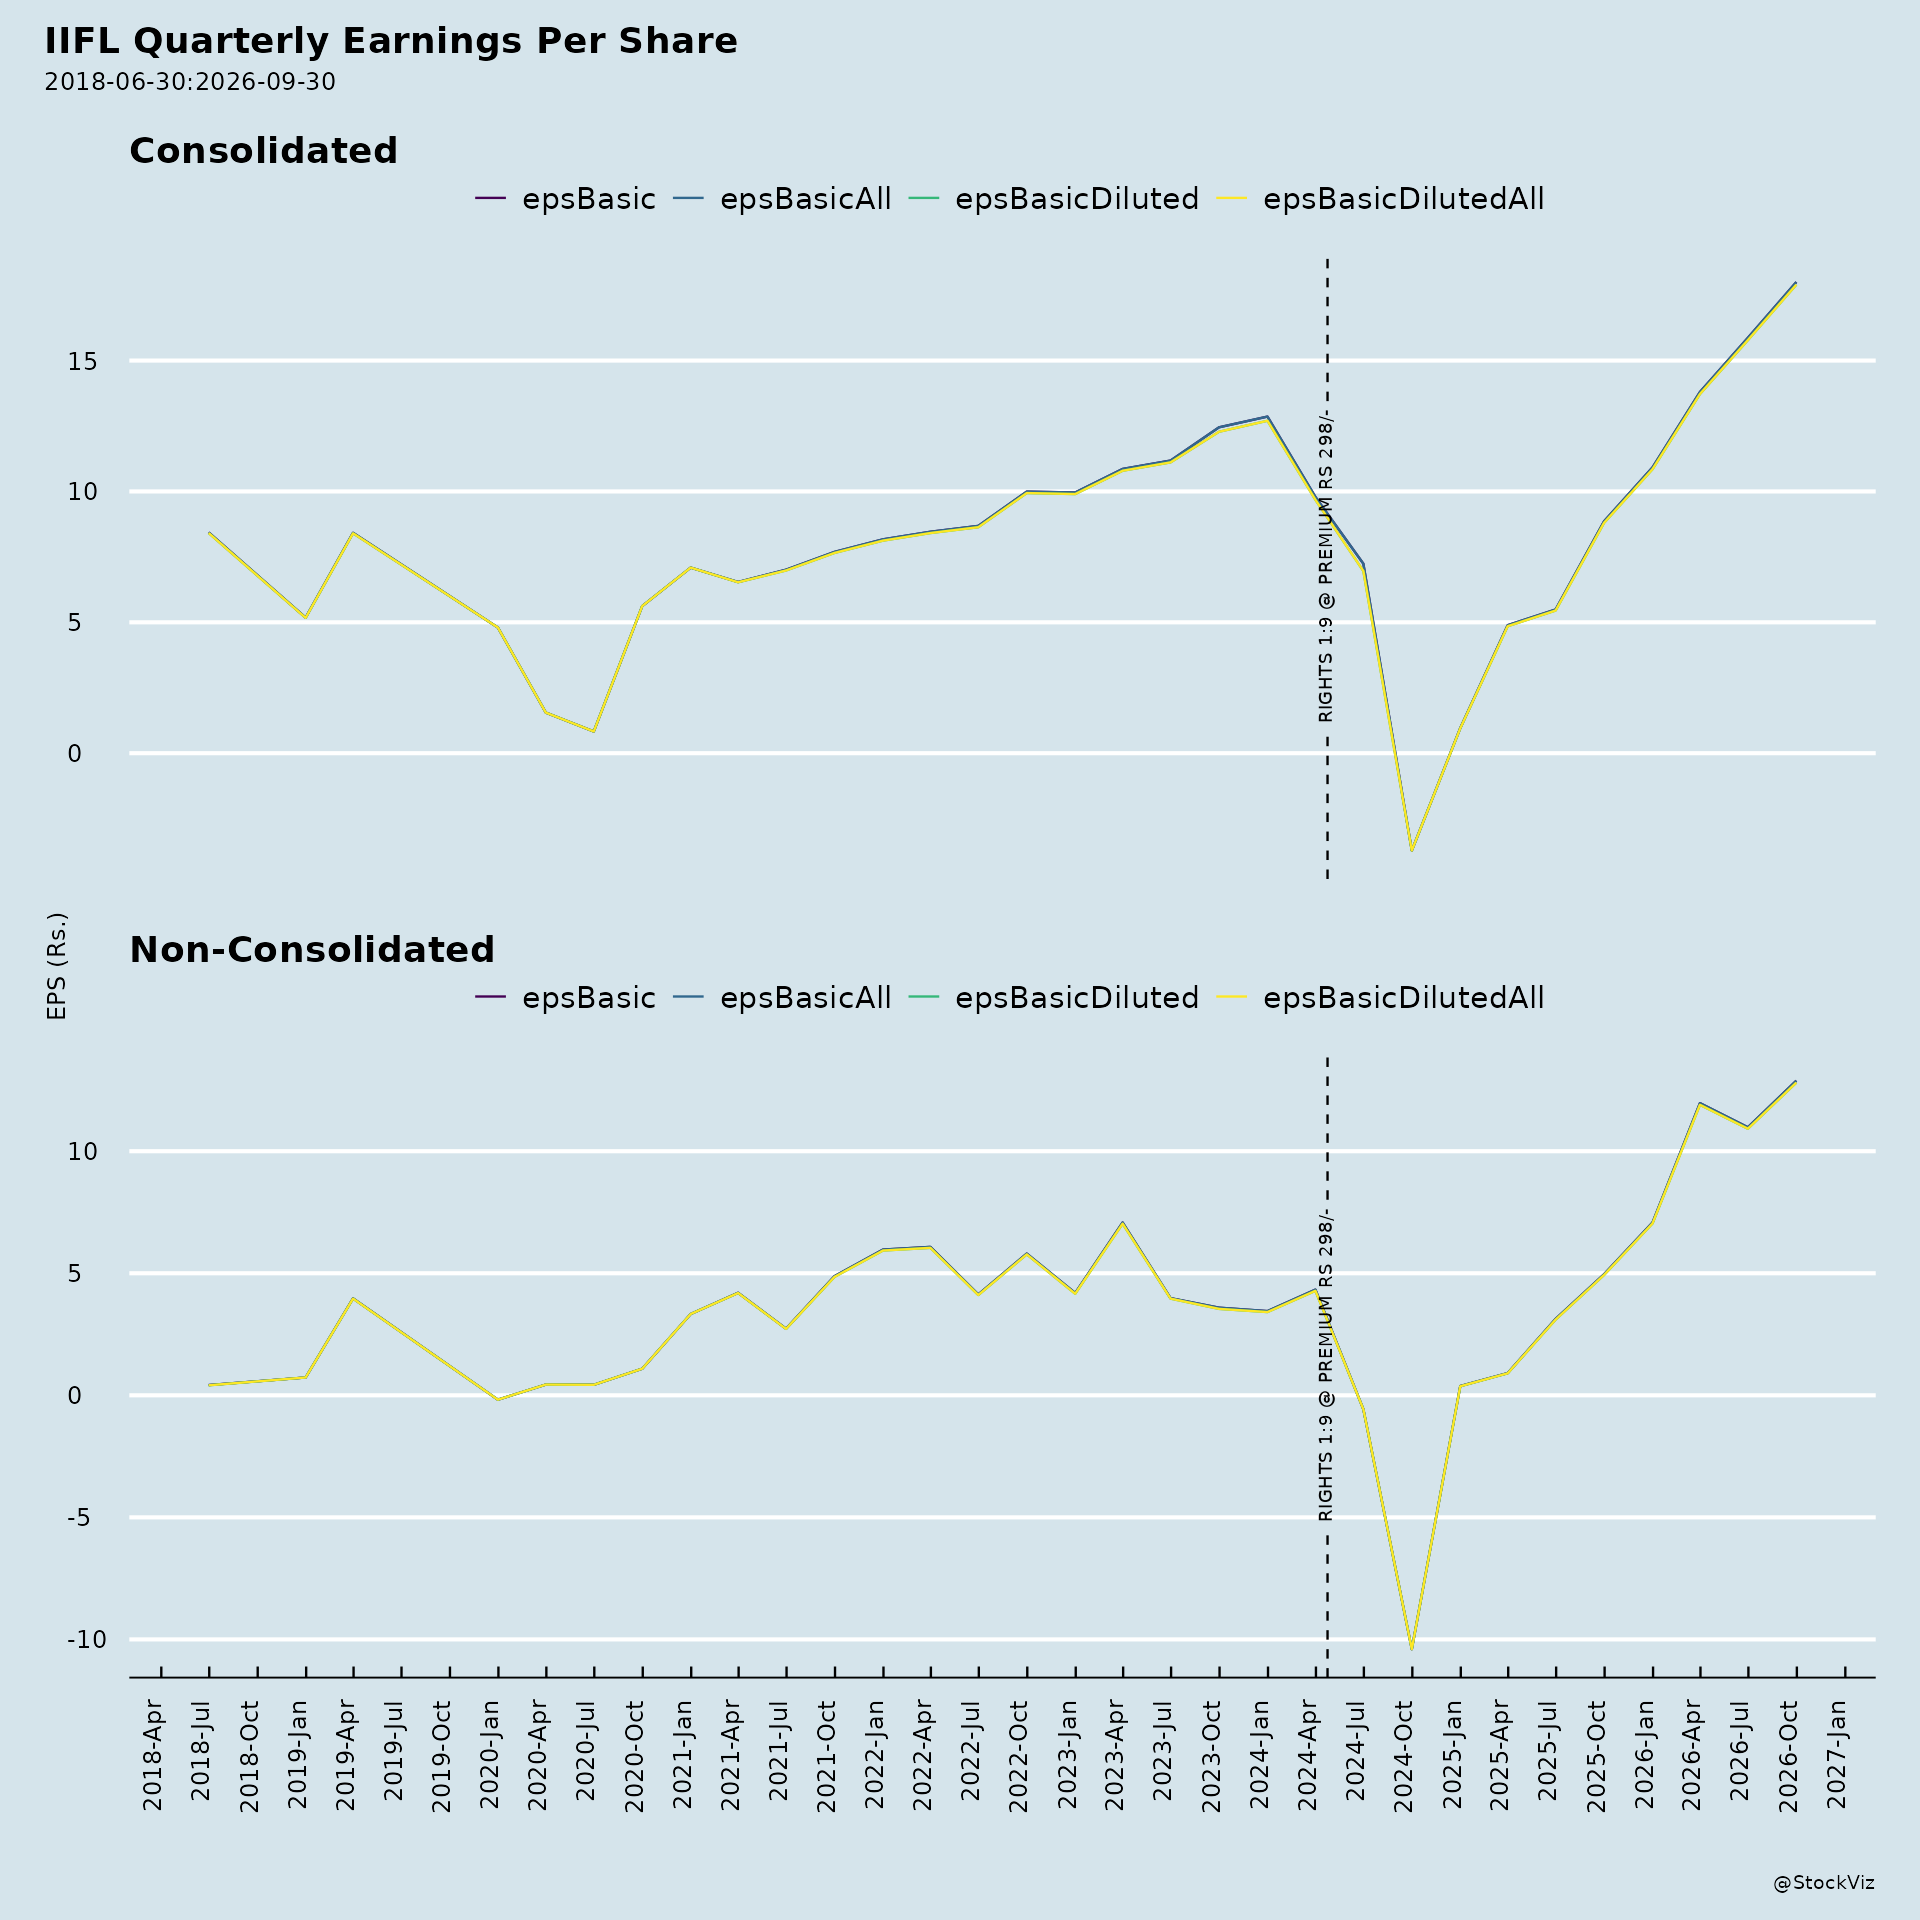
The first report sold IIFL as a 25% AUM / 28% EPS-CAGR growth story with stable 7.5% NIMs, stable Stage-3 assets and a possible AA+ upgrade, while warning of +16bps funding-cost repricing, 5.1% gold-loan opex, a 22.2% QoQ disbursement drop and marginal Home-Finance slippage to 2.0%/1.5%. That funding-cost/asset-quality caution matched the Aug-2023–Feb-2024 DISAPPOINTMENT cluster (actuals -16.6% to -46.6%), before outcomes flipped to SUCCESS from Apr-2024 (+92.5%, +98.8%) and later large positive actuals. By the last report the narrative had shifted from organic NIM/RoE expansion and an imminent rating upgrade to a capital-and-partner story — Blackstone (INR50b) plus INR64.14b raised, CAR 17%→30%, gold-finance acceleration and stronger co-lending — with lower borrowing costs/ratings still only ‘potential’ and no headwinds listed.
Fears that came true
- Rising Cost of Funds (borrowings +16bps QoQ, older-loan repricing expected to offset yield gains) persisted as a real drag — the last report still lists ‘lower borrowing costs’ only as a prospective benefit — and lined up with the early DISAPPOINTMENT streak of actual -16.6% (2023-08-21) to -46.6% (2024-02-16).
- Minor Asset Quality Slippage in Home Finance (GNPA/NNPA up to 2.0%/1.5%) tracked the same negative window, with actuals of -25.4% (2024-01-01), -29.9% (2024-01-19), -26.4% and -46.6% (both 2024-02-16), i.e. the ‘minor’ slip fed a deep drawdown rather than staying benign.
Optimism that failed
- Potential Credit Rating Upgrade — management’s expected move to AA+ ‘within the next 12 months’ did not occur; the 2026-11-10 report still frames rating improvement (and lower borrowing costs) only as ‘potential’ roughly three years later.
Broker Timeline
28 broker calls · 2023-07-28 to 2026-11-10
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-12 |
GreenEdge Wealth
Digant Haria
|
Top pick
|
Top picks are IIFL Fin, Fedfina, & Tamilnad Mercantile Bank. |
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-12 |
GreenEdge Wealth
Digant Haria
|
—
|
When it comes to IIFL Fin, this is the second biggest private equity deal. IIFL Fin really needed this capital infusion. |
| 2026-11-11 |
IIFL Finance
|
—
Horizon: about 2 years
|
₹5,000 Cr profit possible in about 2 years and funds will sustain growth for next 3-4 years |
| 2026-11-11 |
IIFL Finance
Nirmal Jain
|
—
|
Fairfax May Look To Exit, But They May Have Time. With This Infusion Fairfax's Stake Will Dip To 10.9%. Promoters Won't Raise Stake Beyond 25%. IIFL Capital Will Be A Fairfax Entity. ₹5,000 Cr Profit Possible In About 2 Years. |
| 2026-11-11 |
IIFL Finance
Nirmal Jain
|
—
|
The capital infusion will support growth in its gold loan business, where it holds about 3% market share. He sees ₹5,000 crore profit as possible in around two years and says the housing finance arm has the scale for a separate listing. |
| 2026-11-11 |
IIFL Finance
Nirmal Jain
|
—
|
Blackstone will also get 1–2 board seats. |
| 2026-11-11 |
IIFL Finance
Nirmal Jain
|
—
Horizon: 3-4 years
|
Growth has been strong and we needed capital. Strong balance sheet will enable co-lending by banks. The funds will almost double our capital adequacy. Expect 70% funds for new loans, 30% to repay borrowings. The funds will sustain growth for next 3-4 years. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.