ICRA
Equity Metrics
September 24, 2026
ICRA Limited
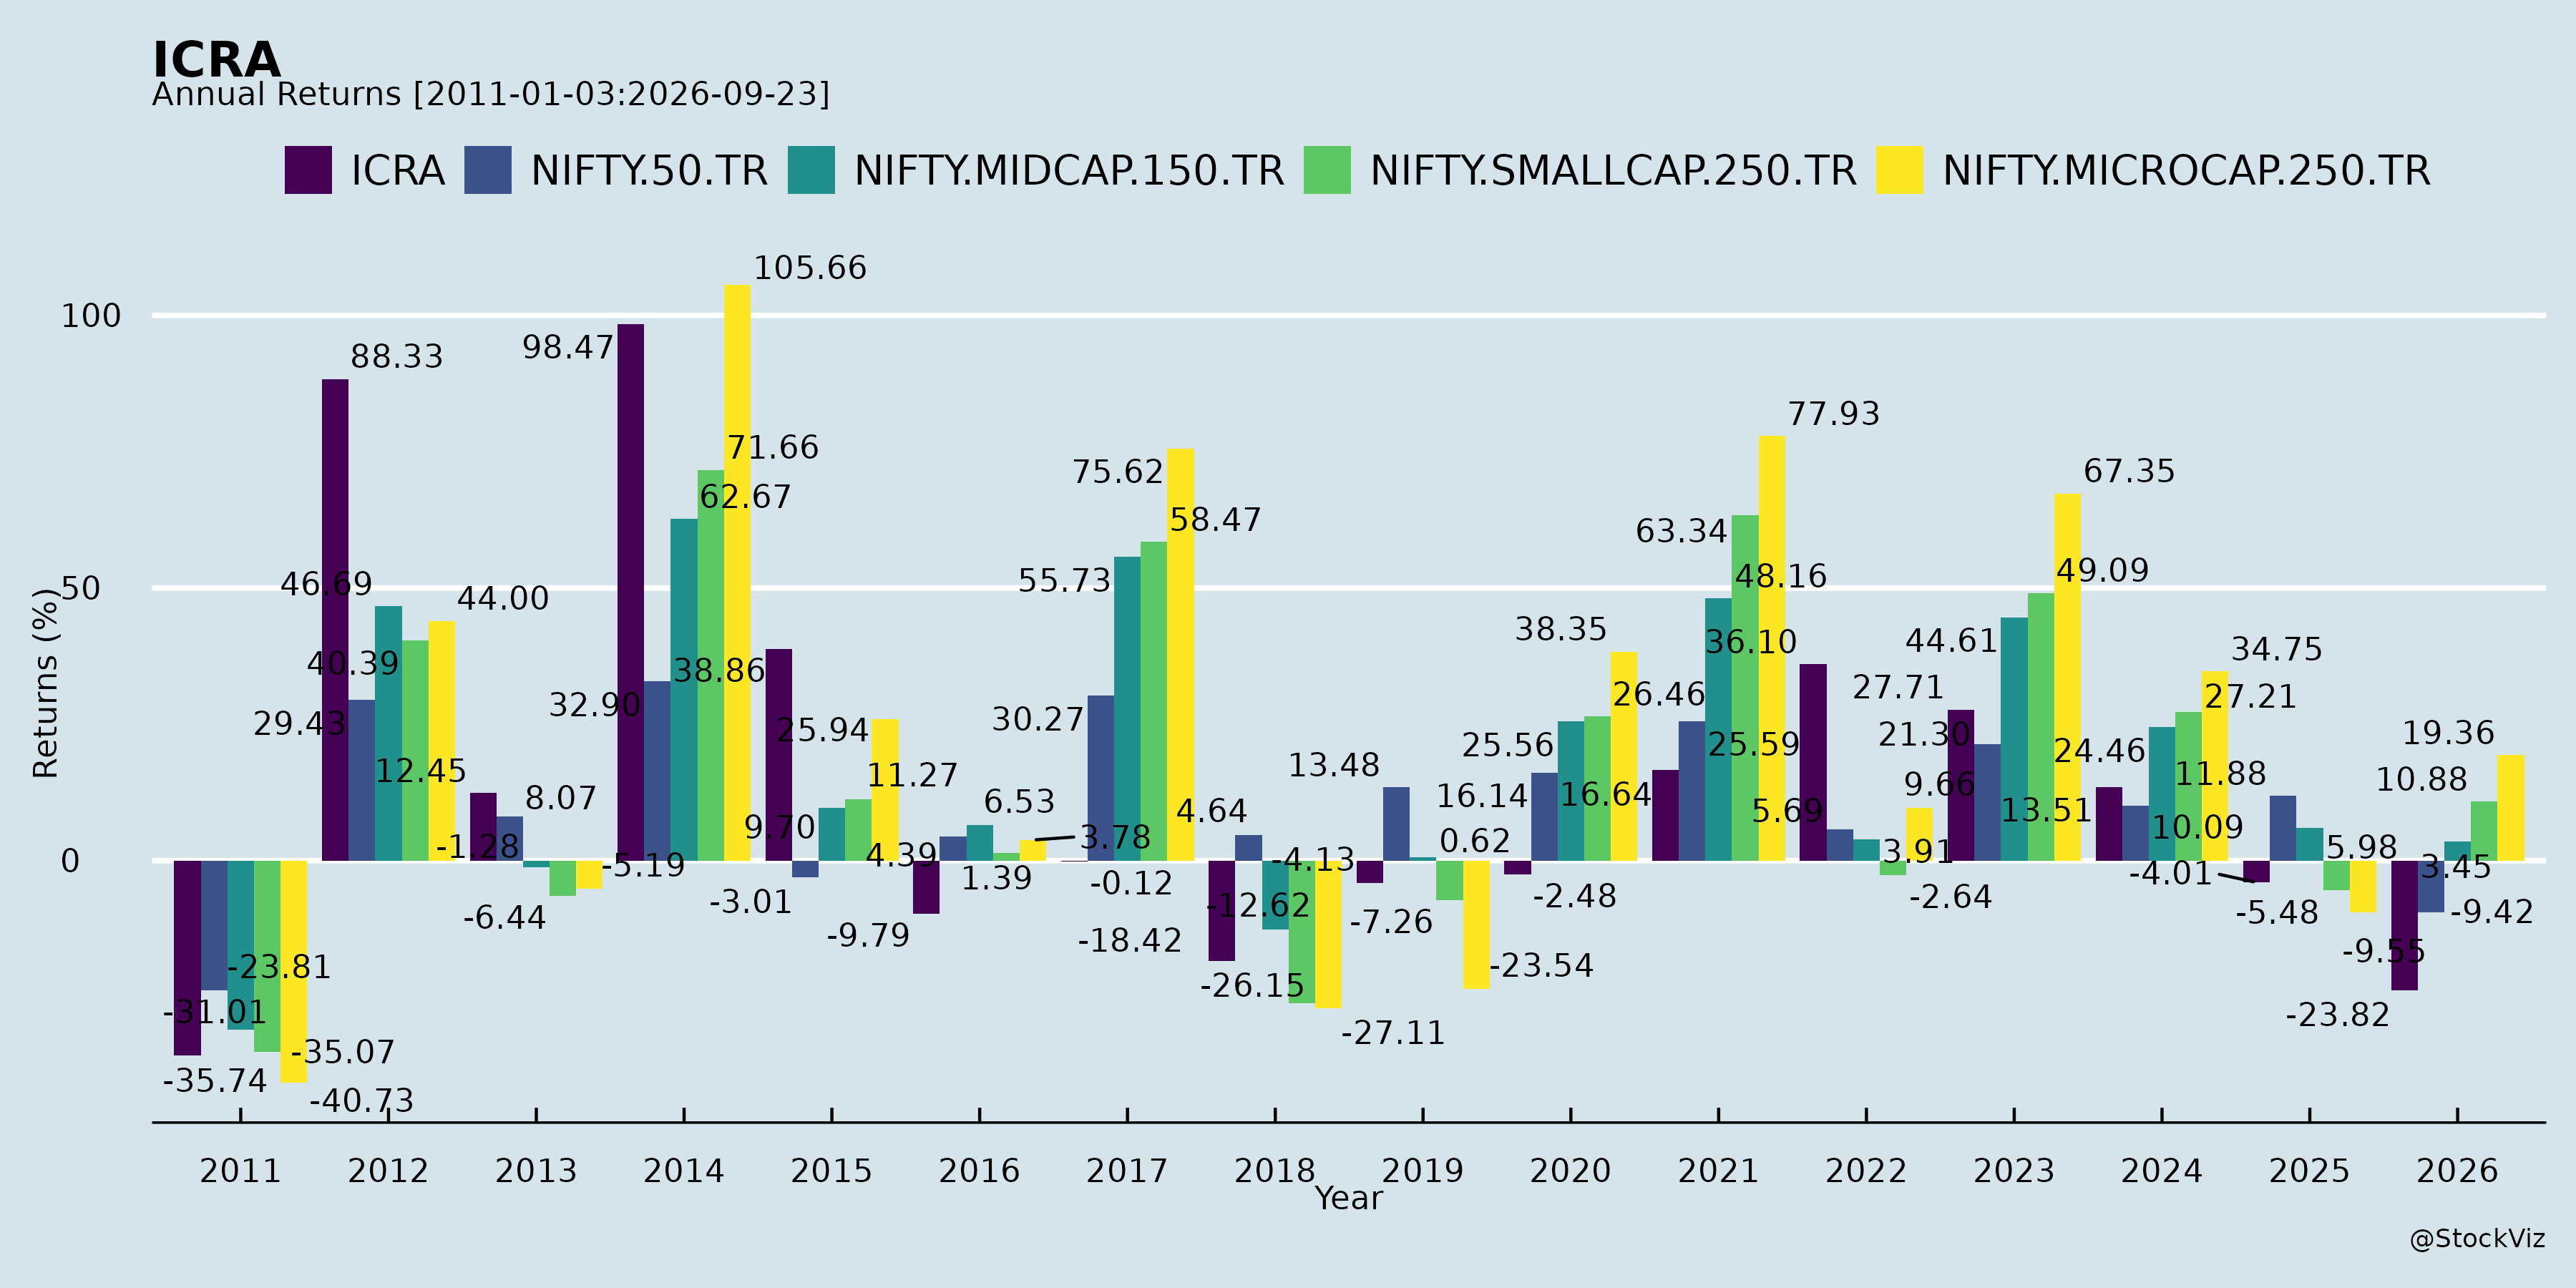
Annual Returns
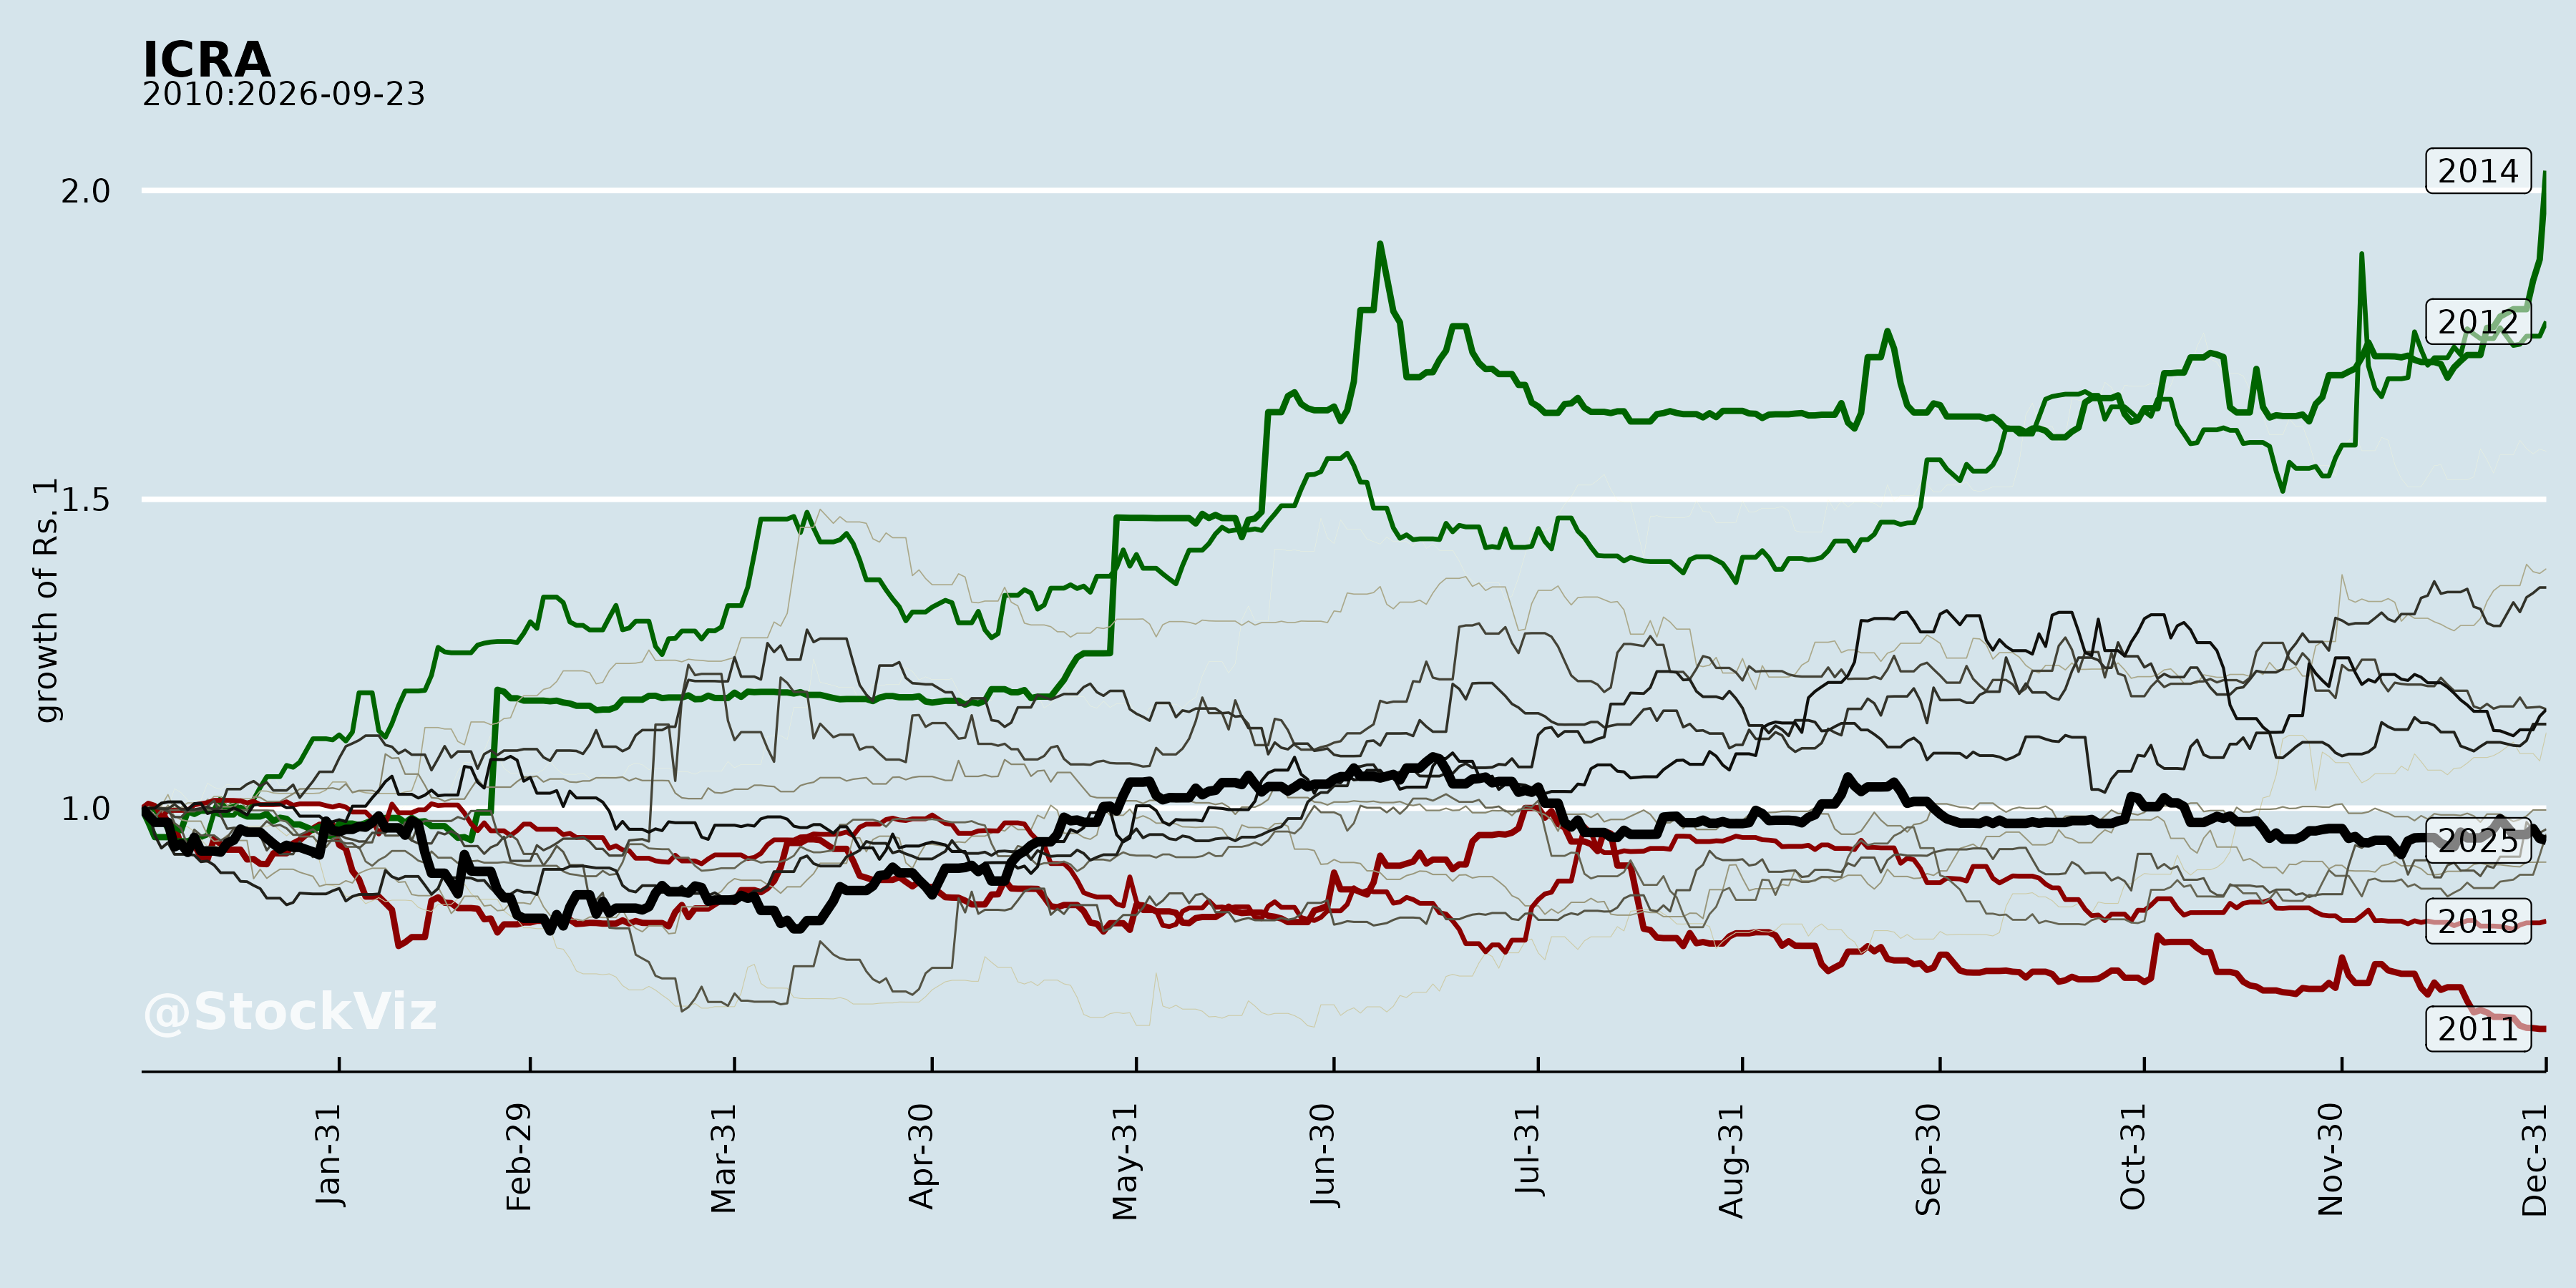
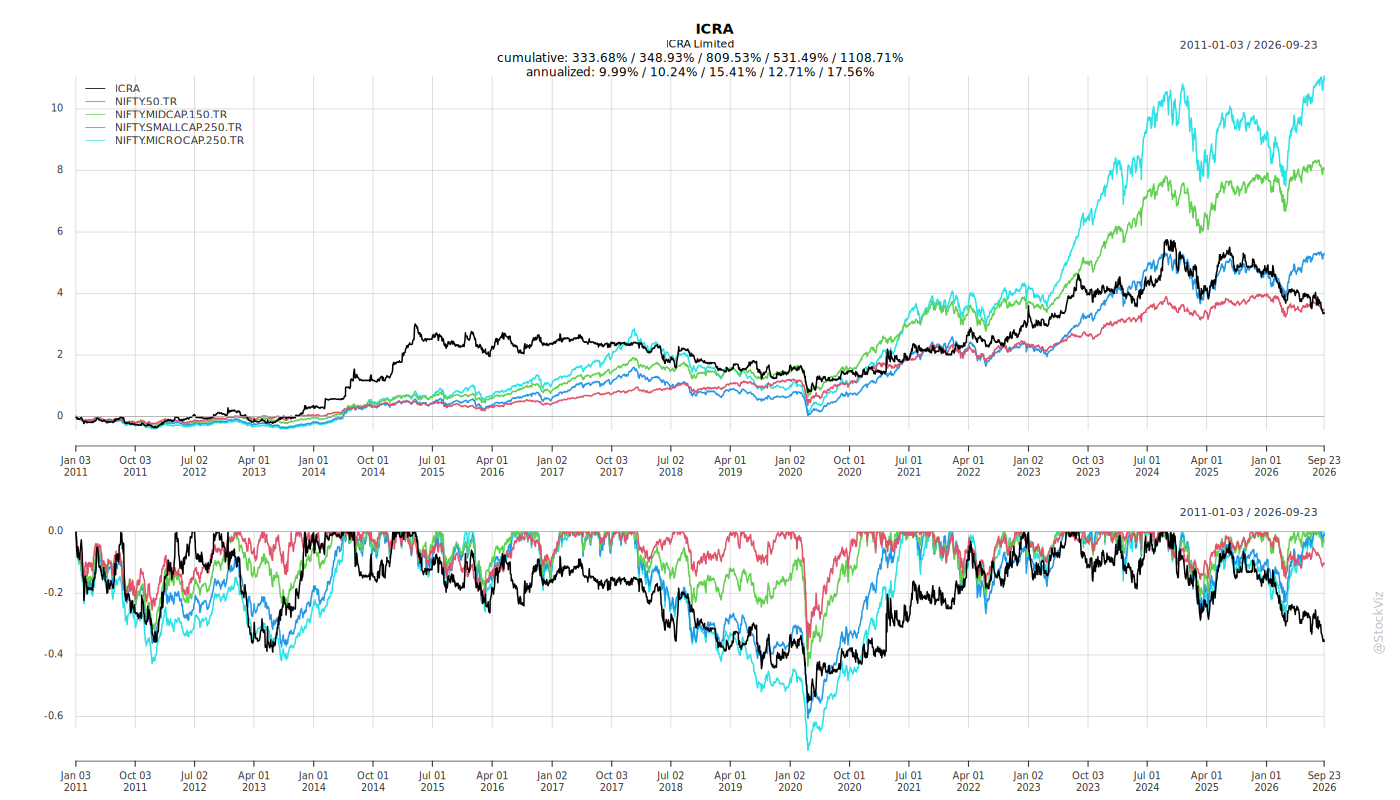
Cumulative Returns and Drawdowns
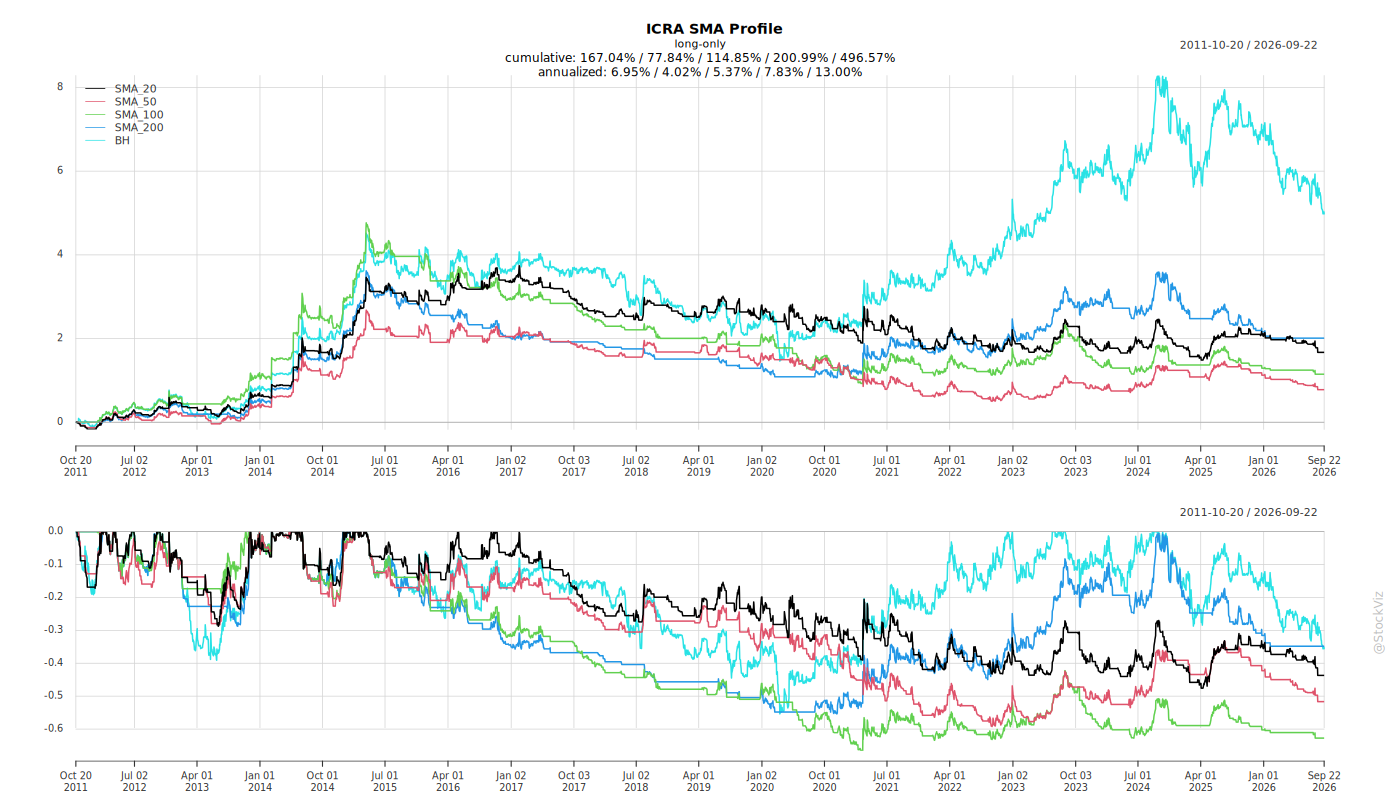
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
ICRA Limited — Recent Corporate Announcements: Headwinds, Tailwinds, Risks, and Guidance vs. Performance
1. Headwinds and Challenges
- Macro moderation: India’s GDP growth is expected to have moderated in Q1 FY2027 from 7.8% in Q4 FY2026. ICRA expects GDP growth to ease to 6.7% in FY2027 from 7.7% in FY2026, with risks tilted to the downside.
- West Asia conflict and commodity prices: The West Asia conflict and the consequent rise in oil and other commodity prices weighed on the performance of several sectors. Energy prices had cooled off but have risen again after the recent renewal of tensions in West Asia, which could have potential consequences on India’s growth outcomes.
- Monsoon risk to rural demand: If monsoon rains remain sub-par and uneven, this would weigh on rural demand and agricultural outcomes, particularly in the latter part of the fiscal.
- Bond issuance decline: Bond issuances declined from the high base of the corresponding quarter of the previous year, as yields remained elevated.
- Automation-related ramp-downs: KnowTech recorded steady growth, aided by favourable currency movement and higher throughput, partly offset by automation-related ramp-downs.
- Comparability impact of acquisition: The consolidated financial performance for the quarter includes the consolidation impact of Fintellix, acquired in October 2025; accordingly, the current quarter’s performance is not directly comparable with the corresponding quarter of the previous year.
2. Tailwinds and Growth Prospects
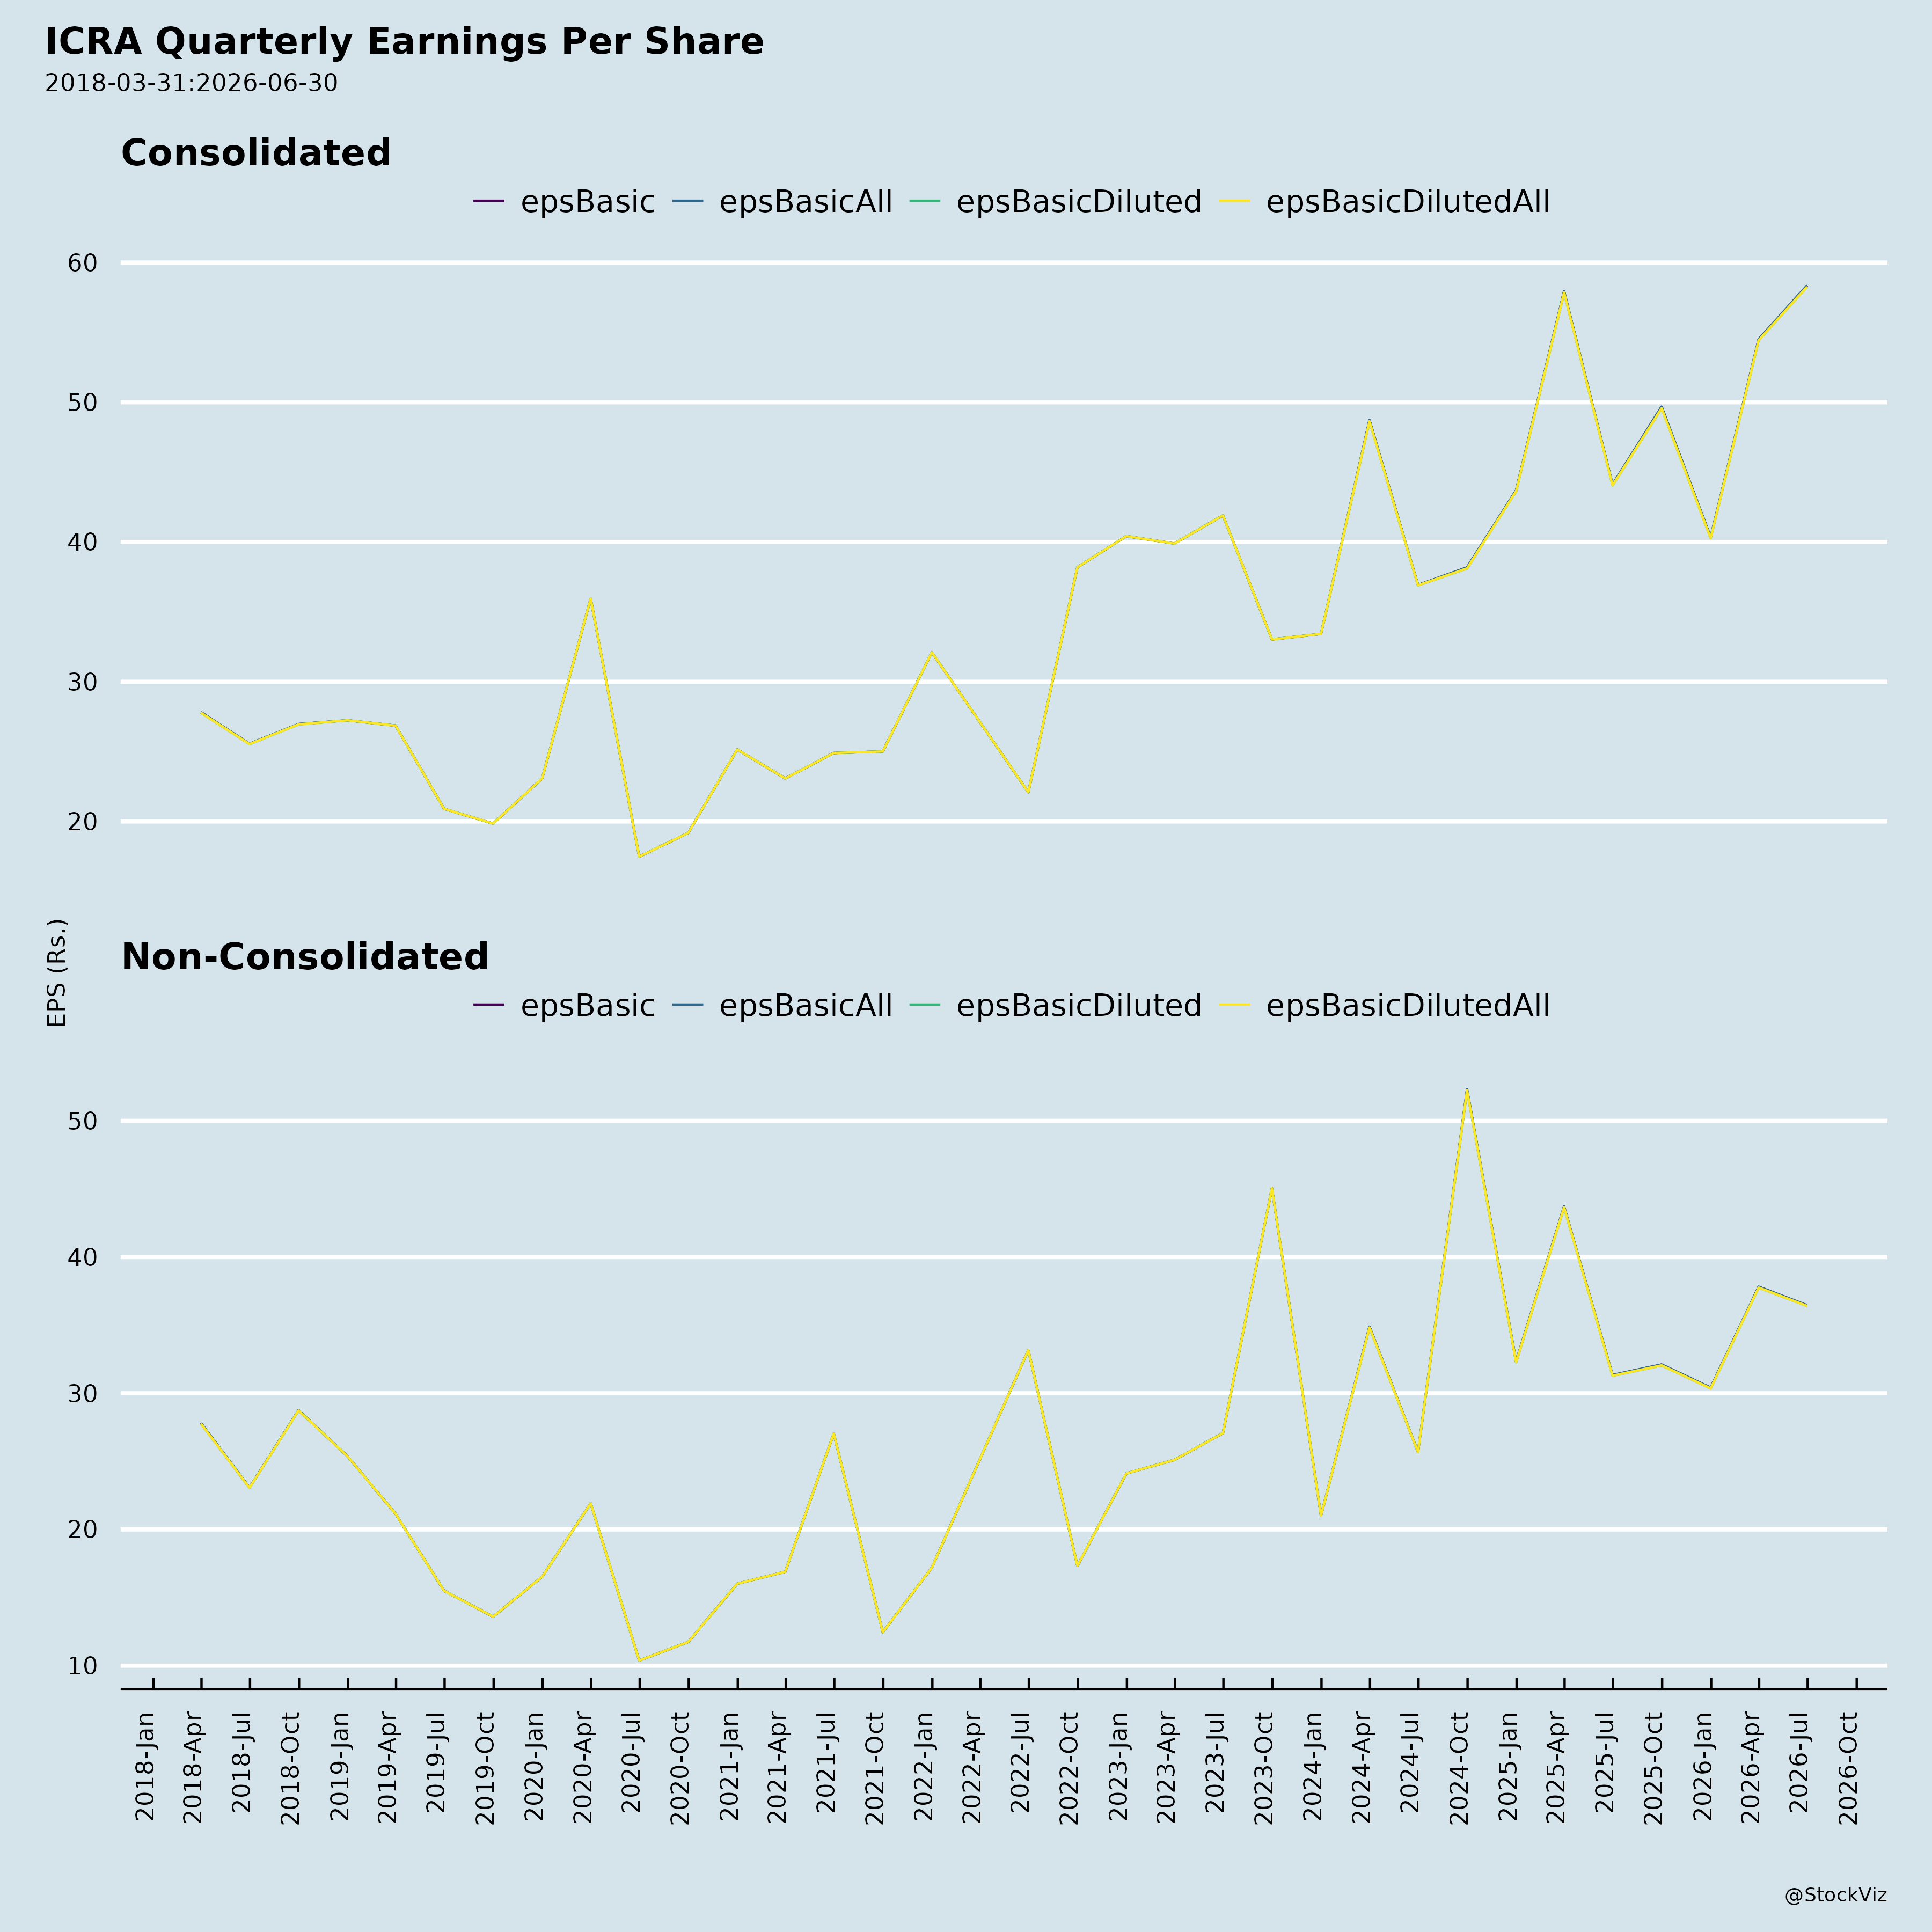
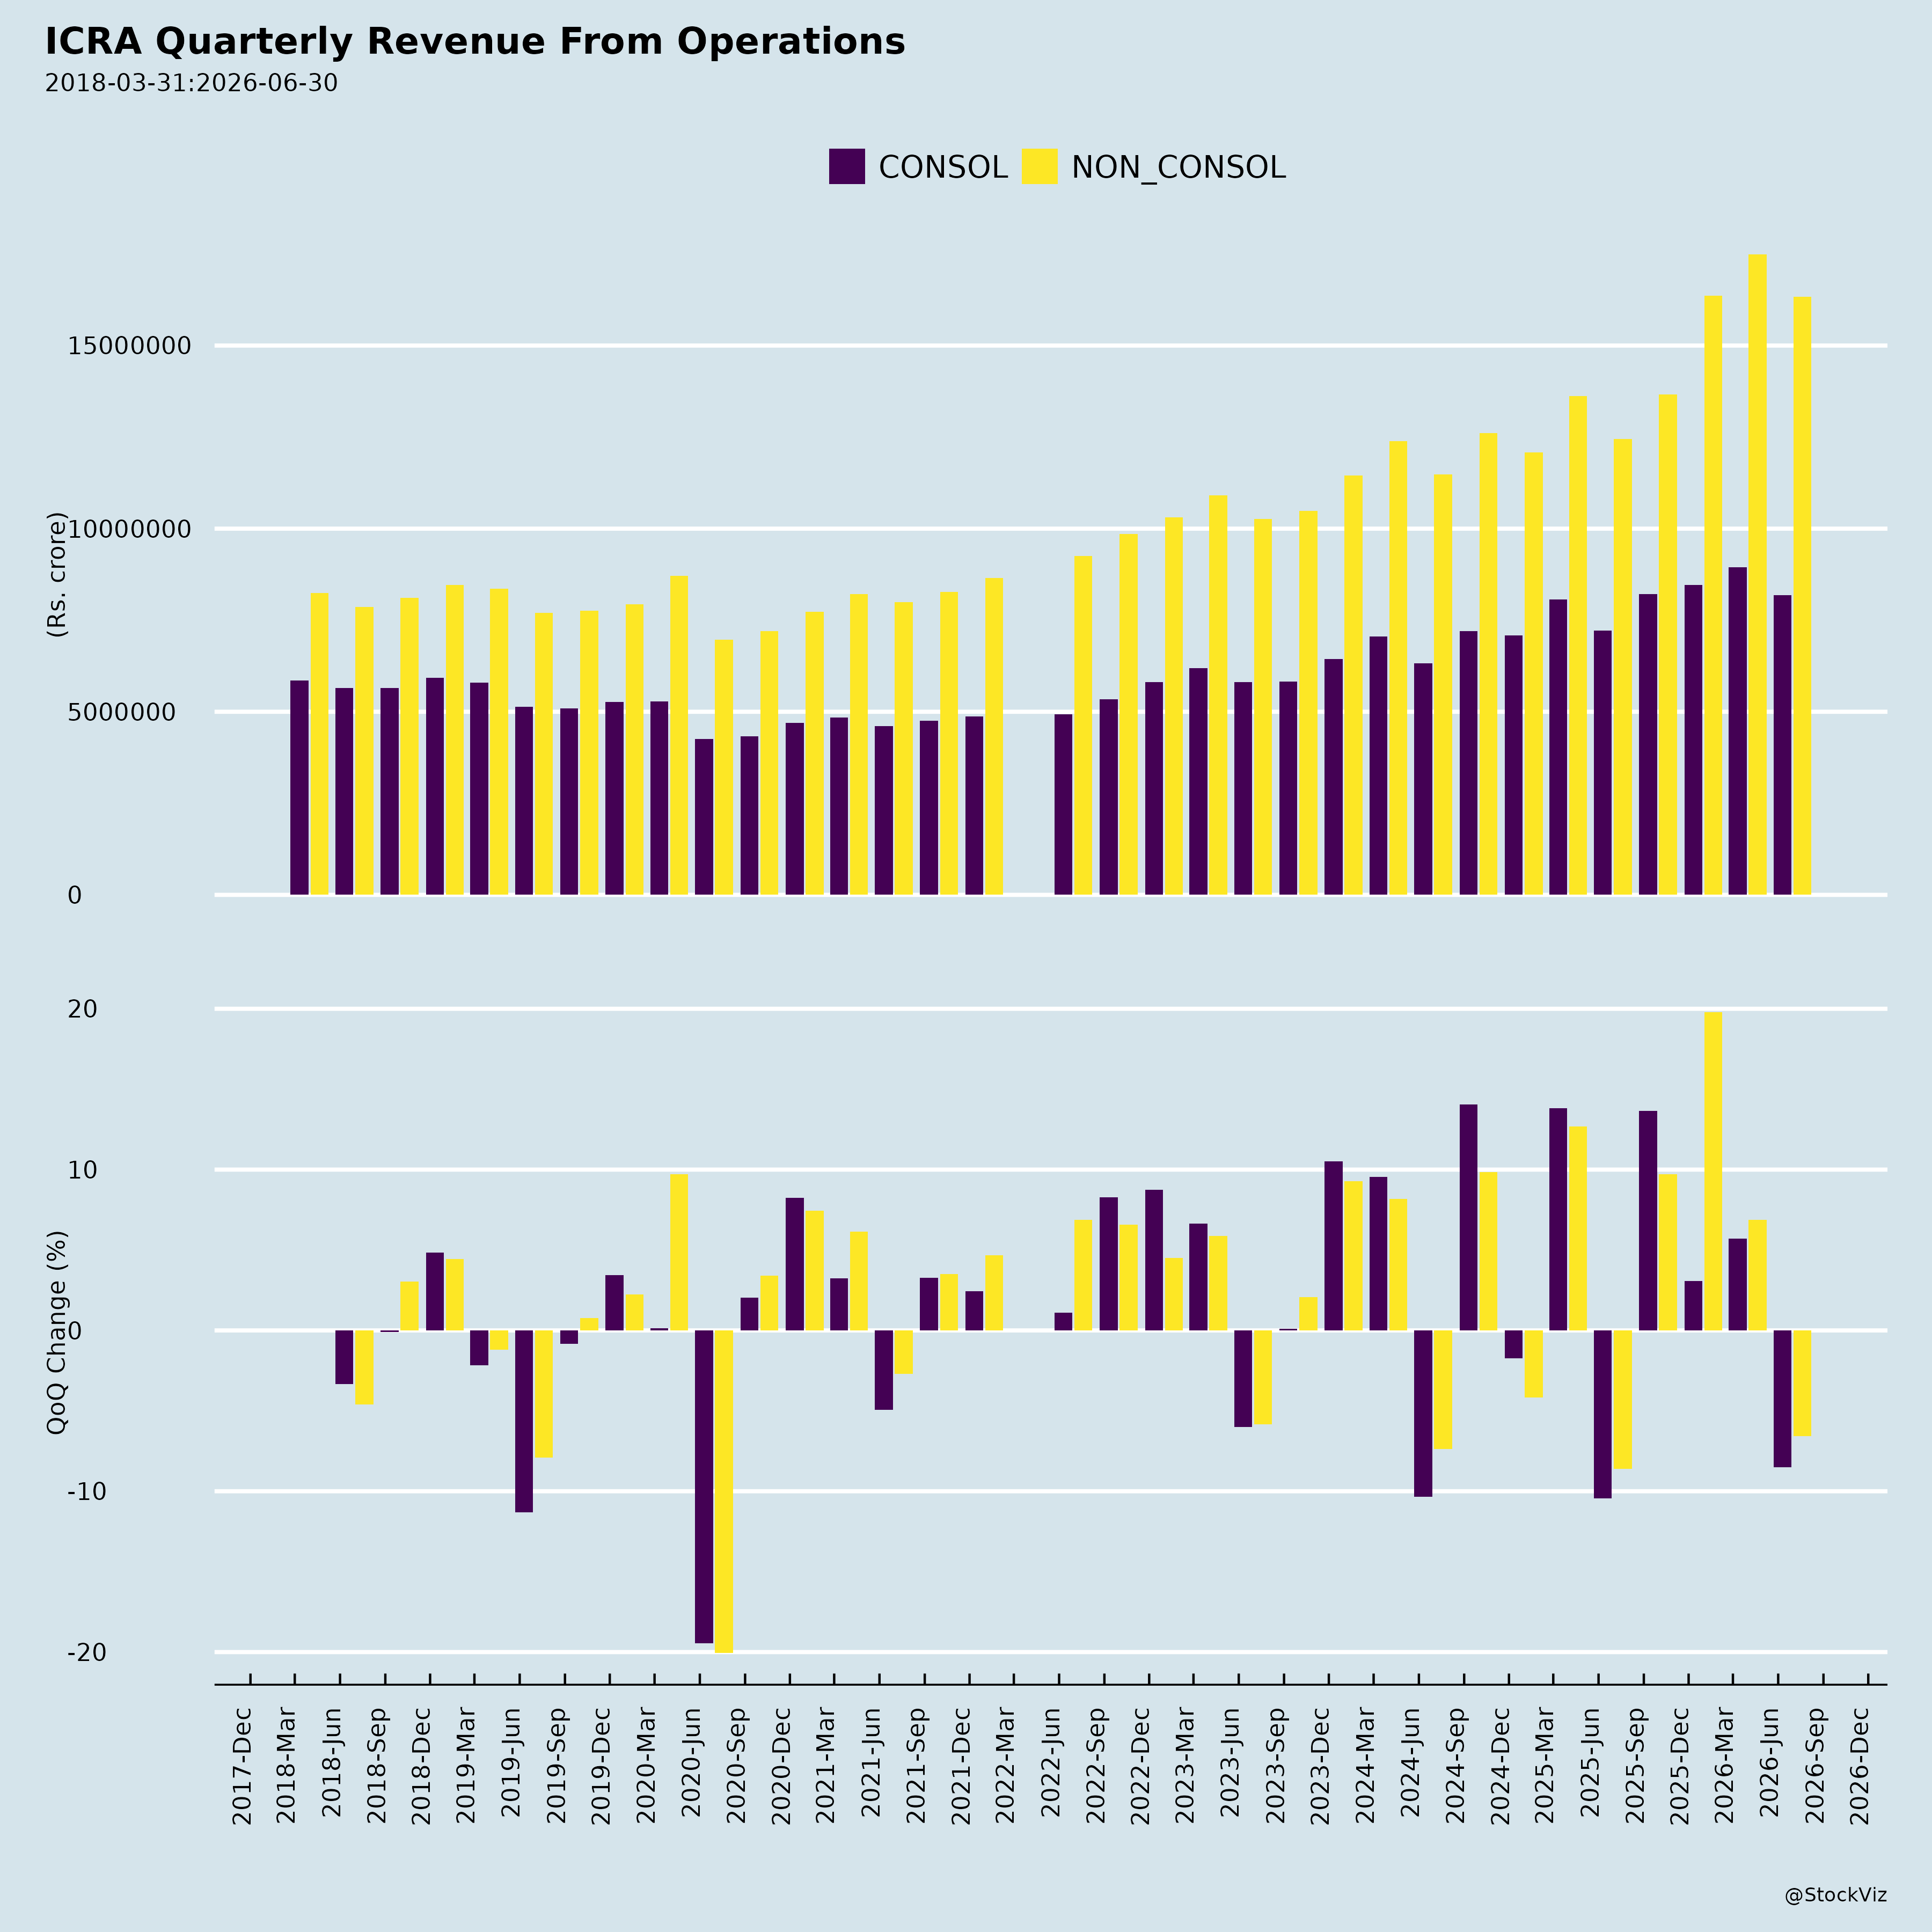
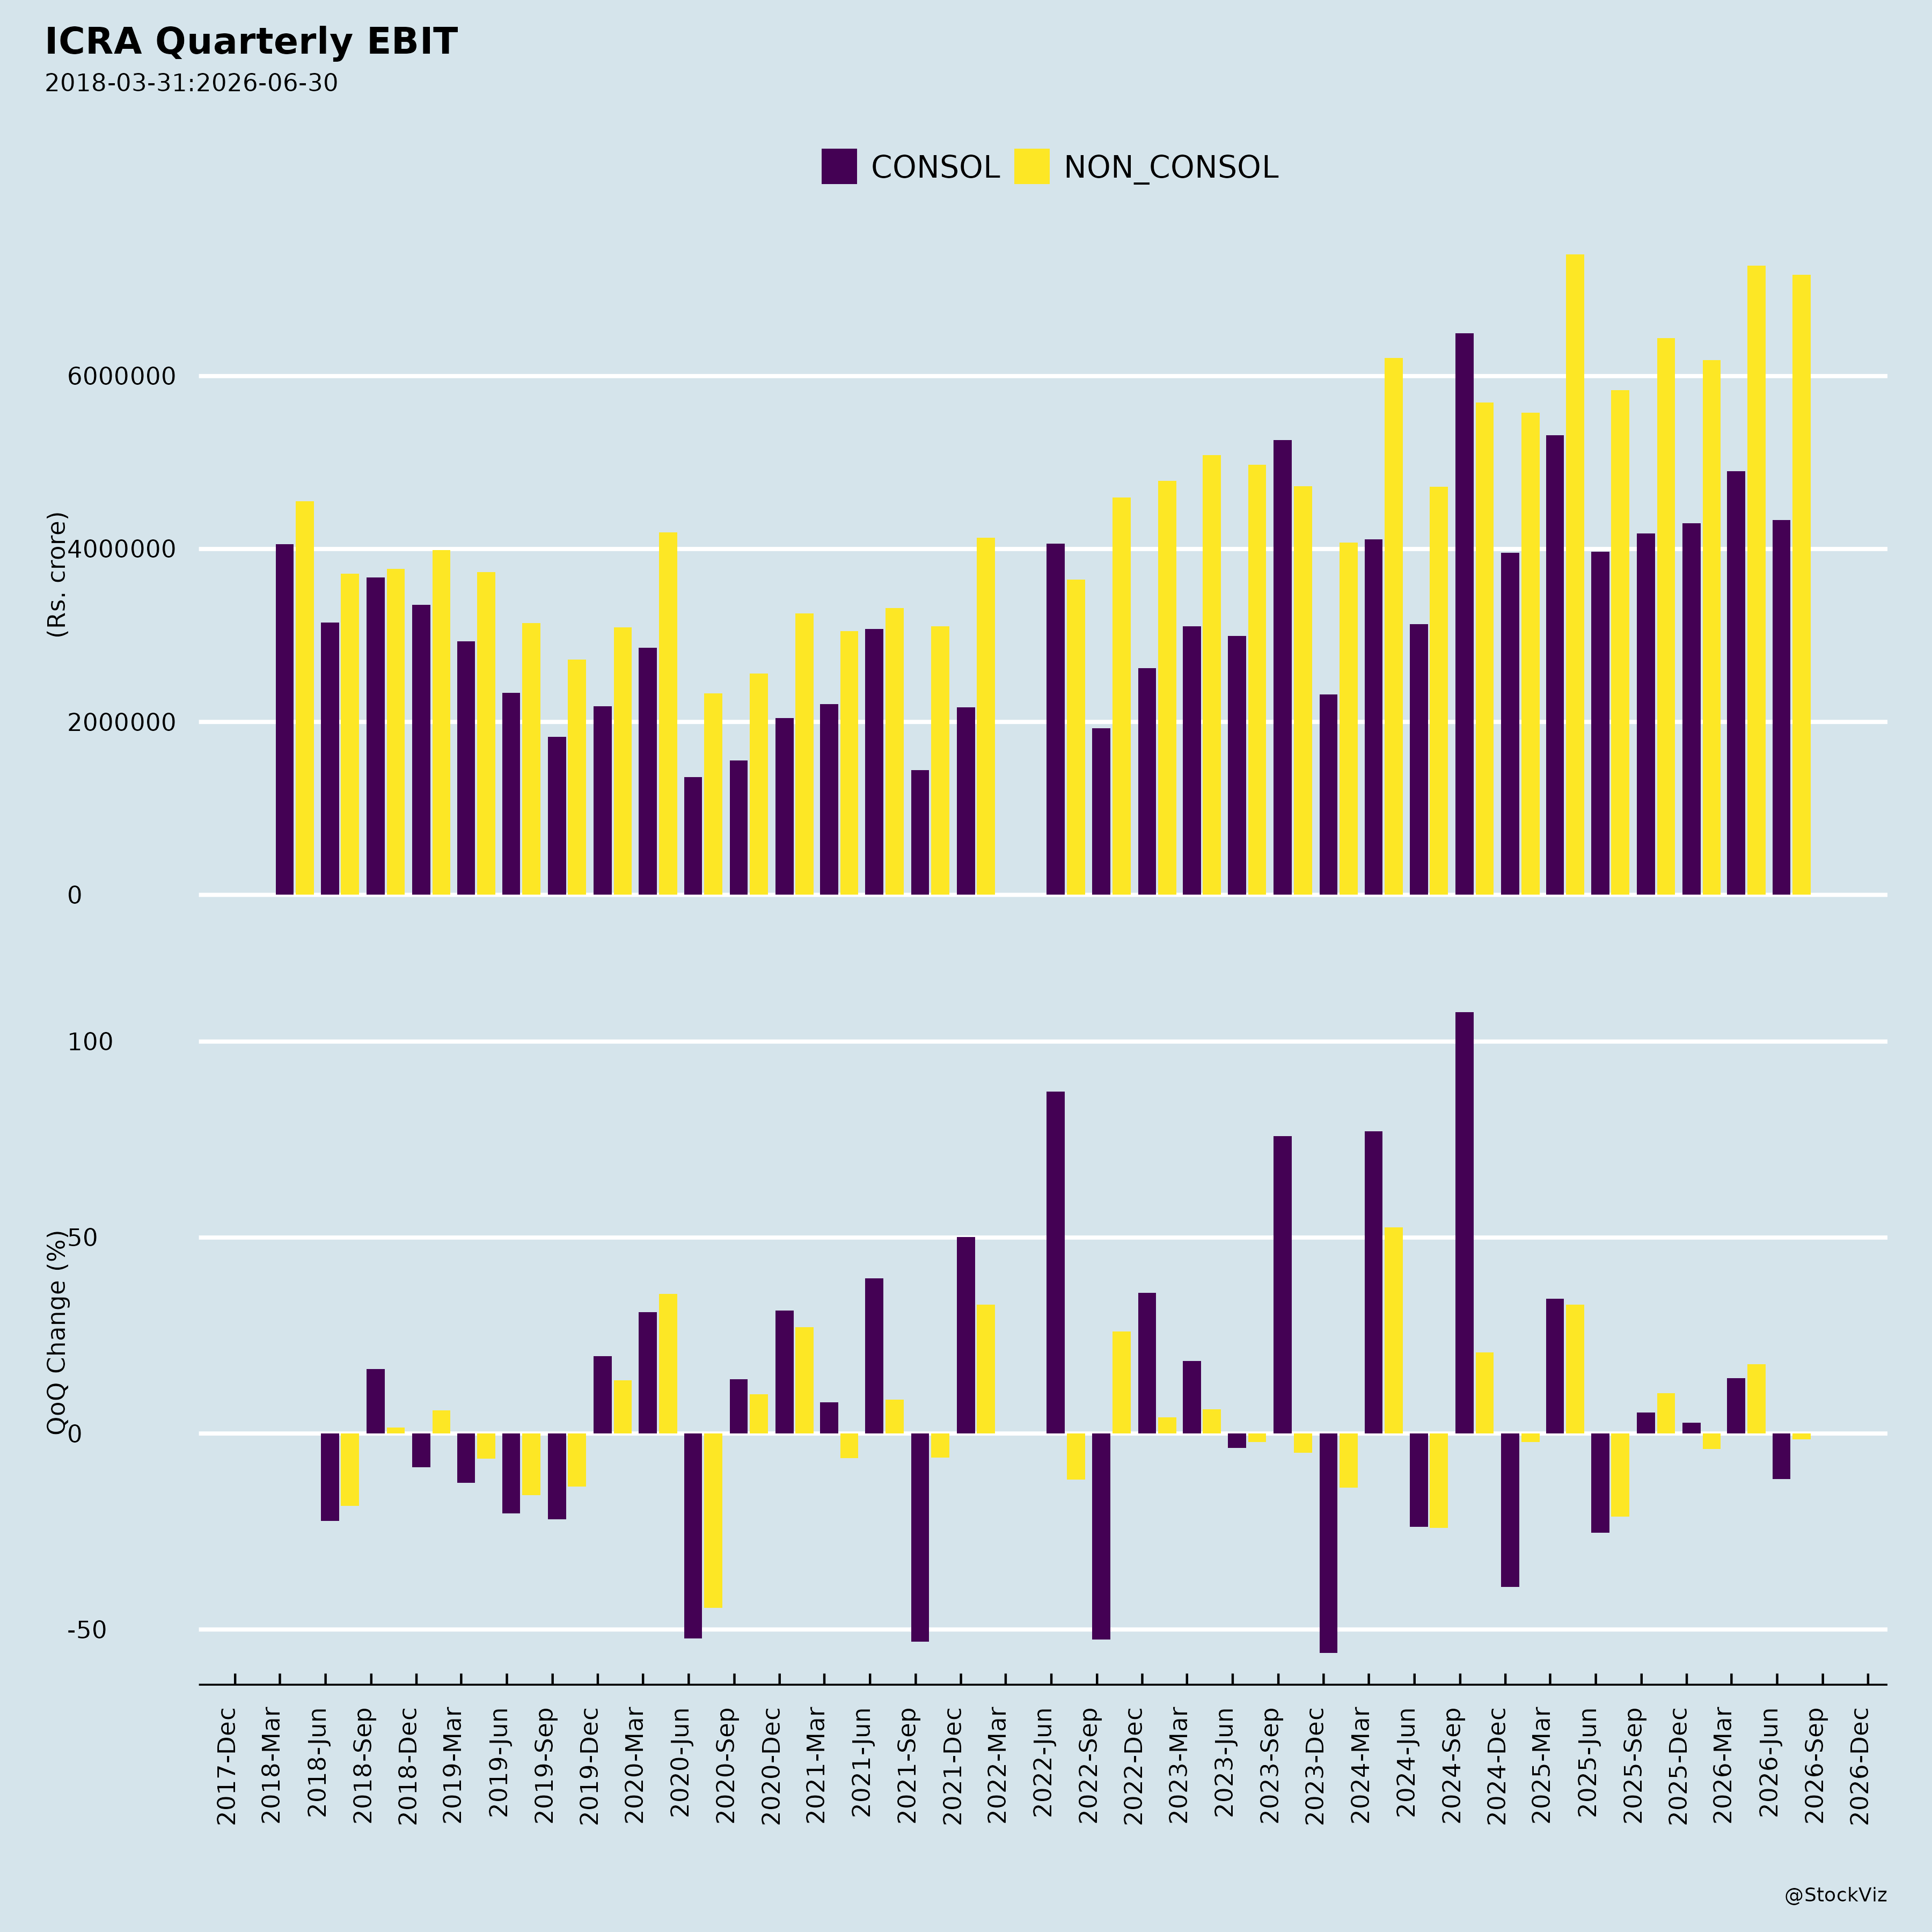
- Strong quarterly performance: Consolidated revenue from operations increased by 31.2% to ₹163.4 crore for Q1 FY2027 (quarter ended June 30, 2026) compared to ₹124.5 crore in the corresponding quarter of the previous year. PAT increased by 32.0% to ₹56.5 crore compared to ₹42.8 crore.
- Ratings business support: Ratings revenue was supported by strong 18.3% year-on-year growth in bank credit as of the end of Q1 FY2027, with demand led mainly by the industries and NBFC segments.
- Late-quarter issuance pickup: Bond and Commercial Paper (CP) issuances increased in the final fortnight of the quarter, helped by moderating yields amid improved liquidity, regulatory measures to shore up INR, and a temporary easing of the West Asian conflict.
- CP and securitization momentum: Growth in CP outstanding was supported by higher working capital demand due to elevated commodity prices, along with increased requirements from brokers and capital market entities. Securitization volumes were driven entirely by NBFCs, as newer and smaller entities used this route to expand access to cheaper funding.
- Risk & Analytics momentum: Risk & Analytics (formerly ‘Research & Analytics’) revenue for the quarter was up 58.7%, driven by the Fintellix acquisition and sustained demand across risk, data, and regulatory technology solutions. BankTech benefited from momentum in risk-related offerings; CapTech was supported by increasing demand for data solutions. The segment’s performance reflects a gradually evolving business mix, with higher contribution from product-centric engagements.
- Market outreach: The Moody’s ICRA Annual India Credit Conference was held in Mumbai on May 25, 2026, with over 220 participants. During the quarter, ICRA hosted five sector-focused webinars, participated as a thought leader in 13 external industry forums, published 136 industry research reports, and issued 11 media releases.
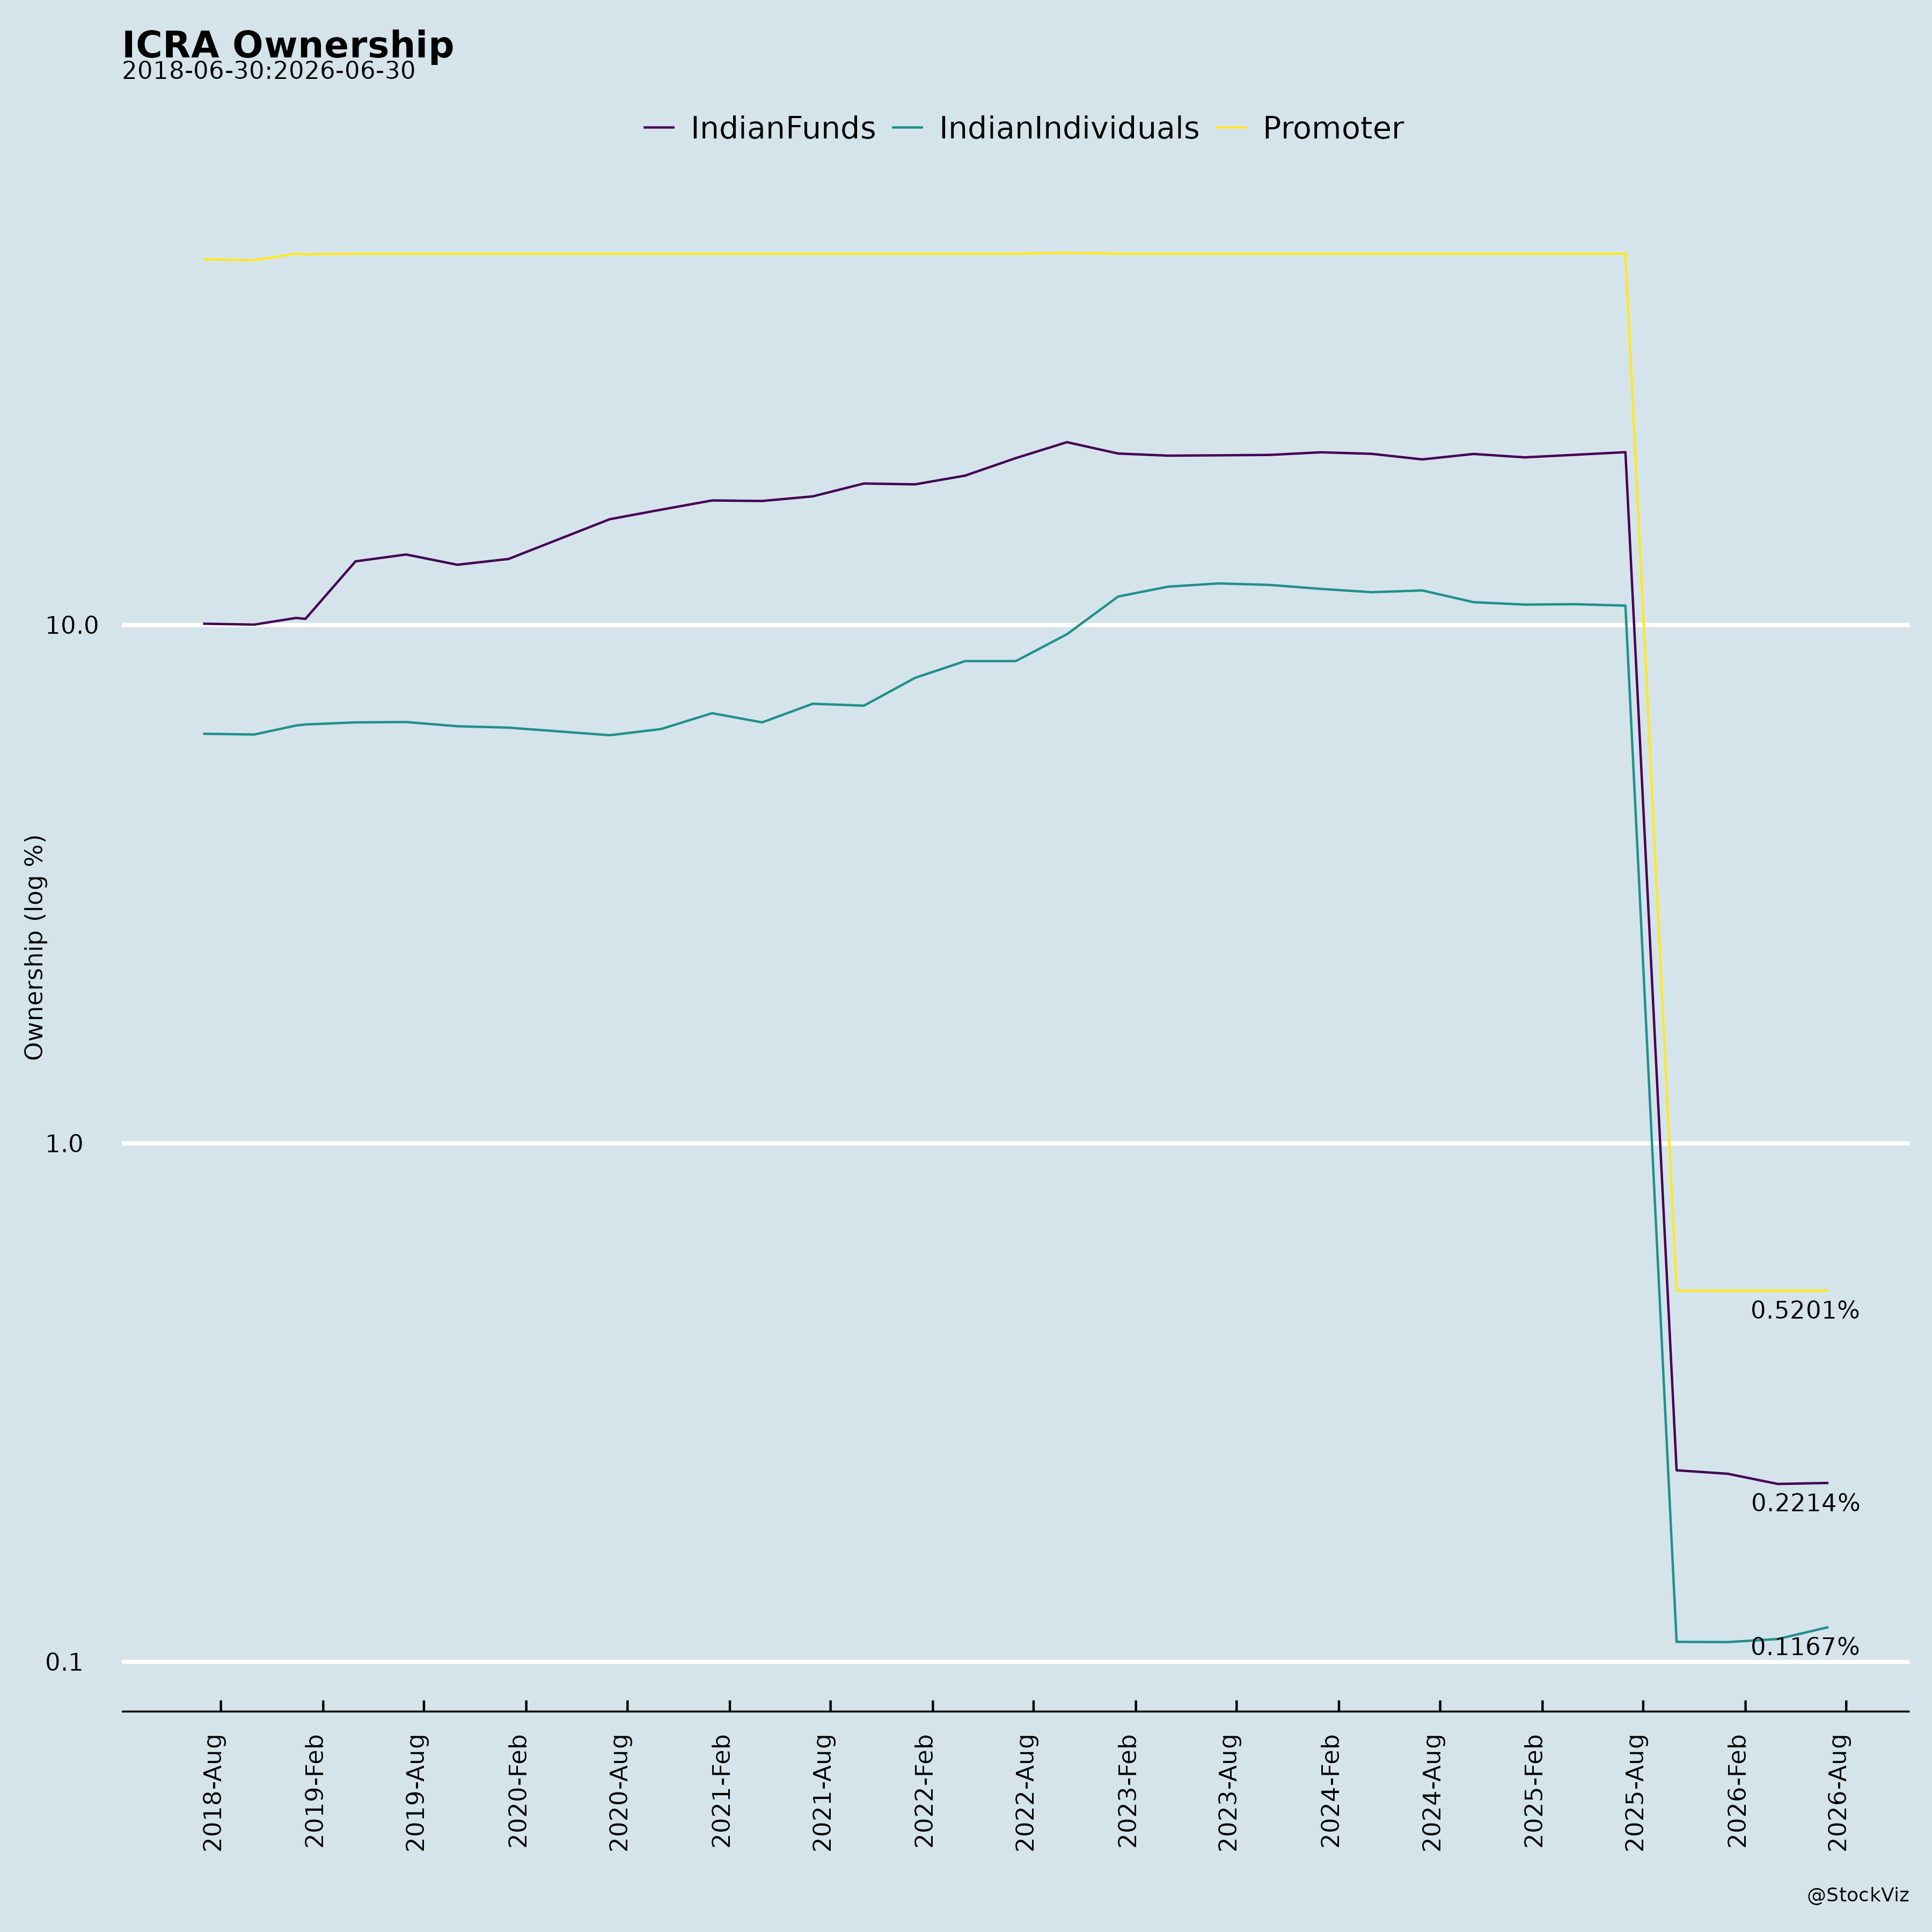
- Ownership consolidation: ICRA acquired the remaining stakes in both D2K Technologies India Private Limited and Fintellix India Private Limited, making both wholly owned subsidiaries within the Group.
3. Key Risks
- Macro downside risks: ICRA expects FY2027 GDP growth of 6.7% with risks tilted to the downside, citing the West Asia conflict, renewed energy price tensions, and potential sub-par monsoon affecting rural demand and agricultural outcomes.
- Elevated yields: Bond issuances declined from the prior-year high base as yields remained elevated, indicating sensitivity of issuance activity to the yield environment.
- Dependence on specific segments: Ratings revenue growth was led mainly by the industries and NBFC segments; securitization volumes were driven entirely by NBFCs.
- Automation-related offsets: Automation-related ramp-downs partly offset KnowTech’s growth.
- Unreviewed subsidiary results: The consolidated unaudited financial results include the financial results of 6 subsidiaries not reviewed by the auditors, reflecting total revenue of ₹268.96 lakhs, total profit after tax (net) of ₹38.13 lakhs, and total comprehensive income (net) of ₹50.98 lakhs for the quarter ended June 30, 2026, as considered in the Statement. Management states these financial results are not material to the Group.
4. Management Guidance vs. Observed Business Performance
- Management commentary: Mr. Ramnath Krishnan, MD & Group CEO, stated that ICRA delivered a strong quarterly performance, supported by healthy growth in Ratings and sustained momentum in Risk & Analytics. He noted the Ratings business remained anchored in high-quality analytical delivery and market engagement, while Risk & Analytics benefited from robust demand across data, risk, and technology-led solutions. He reiterated commitment to supporting clients and market participants with independent insights and solutions aligned to evolving business and regulatory needs.
- Observed performance: Consolidated revenue from operations rose 31.2% year-on-year to ₹163.4 crore, and PAT rose 32.0% year-on-year to ₹56.5 crore for Q1 FY2027. Ratings & ancillary services revenue for the quarter was up 12.9%. Risk & Analytics revenue for the quarter was up 58.7%.
- Macro guidance: ICRA currently expects GDP growth to ease to 6.7% in FY2027 from 7.7% in FY2026, with risks tilted to the downside, after expected moderation in Q1 FY2027 from 7.8% in Q4 FY2026.
- AGM outcomes (July 30, 2026): At the 35th AGM held on July 30, 2026, shareholders approved, with requisite majority: (1) adoption of audited standalone financial statements for FY ended March 31, 2026 (99.9993% in favour); (2) adoption of audited consolidated financial statements for FY ended March 31, 2026 (99.9993% in favour); (3) declaration of dividend of ₹105 on equity shares for FY ended March 31, 2026 (99.9993% in favour); and (4) reappointment of Ms. Wendy Huay Huay Cheong (DIN: 08927070) as a Director retiring by rotation (98.3163% in favour, 1.6837% against). The cut-off date for e-voting was July 23, 2026; remote e-voting ran from July 27, 2026 to July 29, 2026.
Broker Narrative
The broker kept a positive stance on the core ratings franchise throughout, repeatedly citing pricing discipline, bond/infrastructure ratings momentum and margin-leverage possibilities. The main shift was on Moody’s-related Knowledge Services: the first report treated weakness as a transient project-related slowdown, while the last report characterized the outlook as hazy and partly structural due to Moody’s insourcing/automation. The call was also downgraded from Buy to Add and the expected return was cut from high-teens to around 10%.
Fears that came true
- The flagged deceleration in ICRA Analytics/Moody’s-related growth proved persistent rather than transient: Knowledge Services grew only 3% in FY24 after 25-30% in FY22/23, and the first Buy call returned -5.9%.
- The concern about dependence on Moody’s projects materialized more structurally, as Moody’s tilted toward insourcing/automation and the outsourcing trend was unlikely to change in FY25; the last Add call returned -1.6%.
Optimism that failed
- The expectation that Moody’s business was on a strong footing with enlarged engagement and new service areas failed to materialize, as the last report flagged a hazy Knowledge Services outlook driven partly by Moody’s insourcing/automation.
Broker Timeline
4 broker calls · 2023-09-03 to 2024-09-17
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.