HINDWAREAP
Equity Metrics
November 18, 2026
Hindware Home Innovation Limited
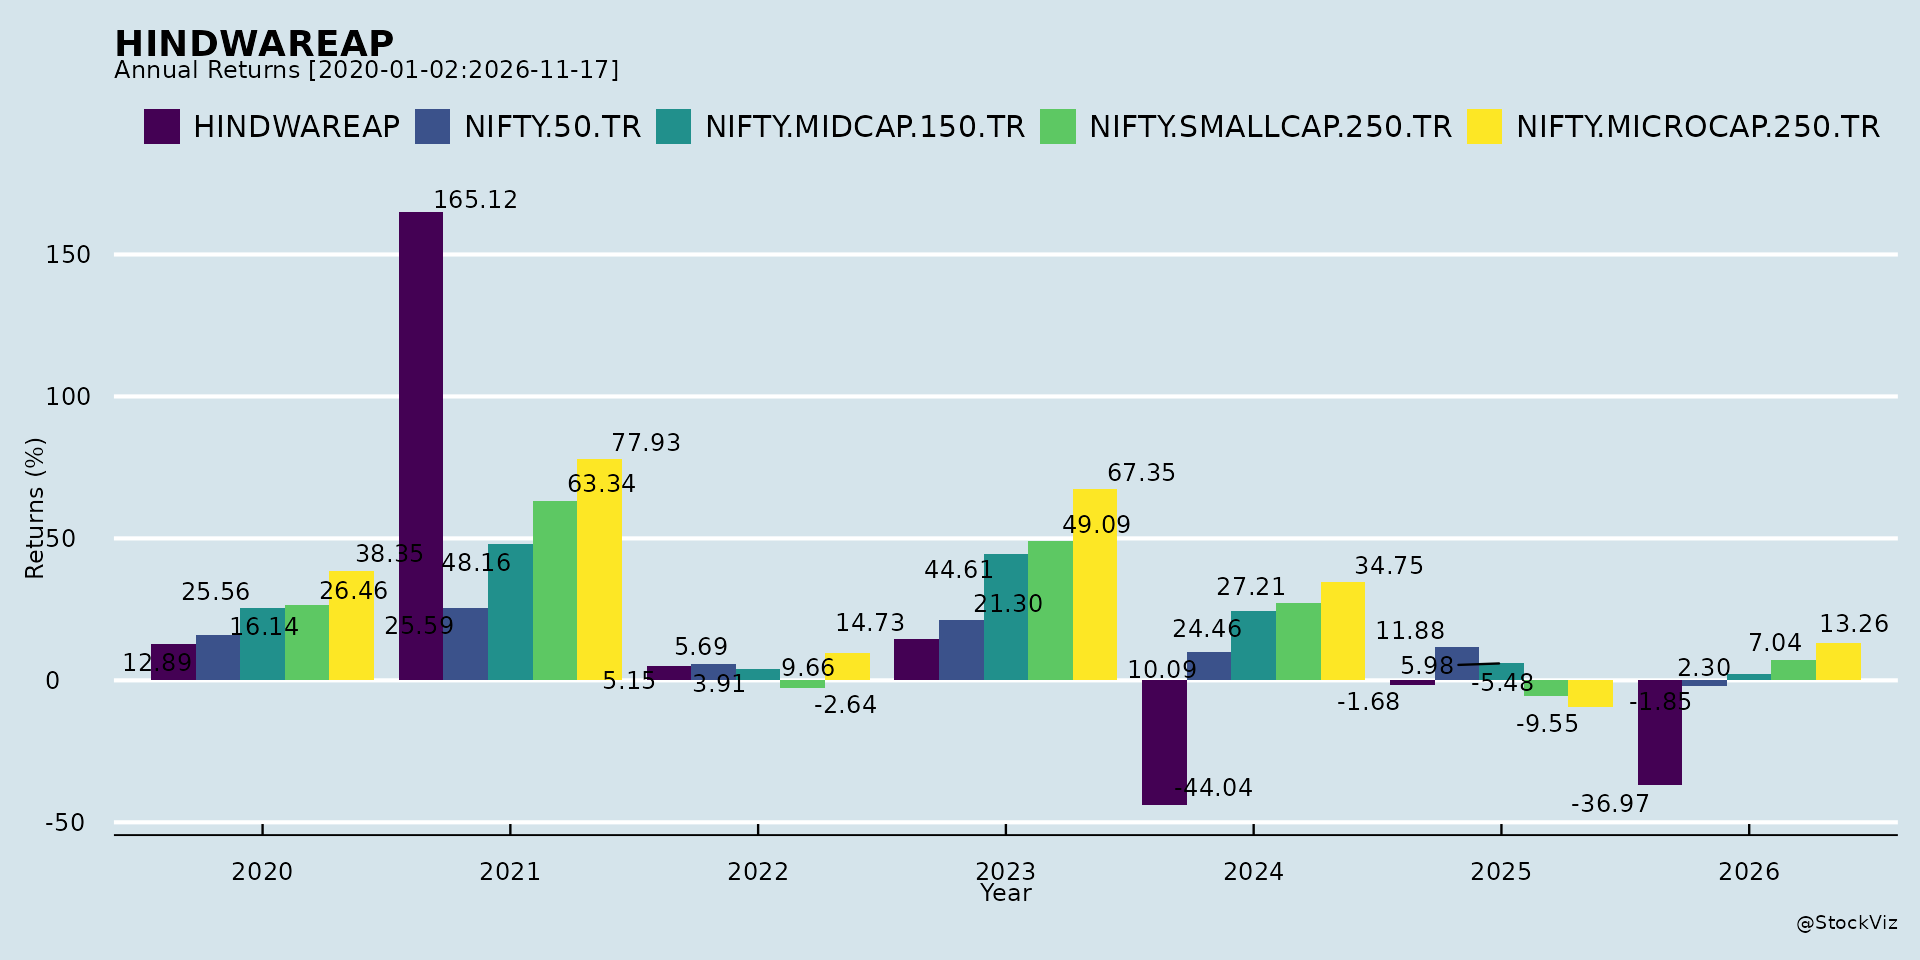
Annual Returns
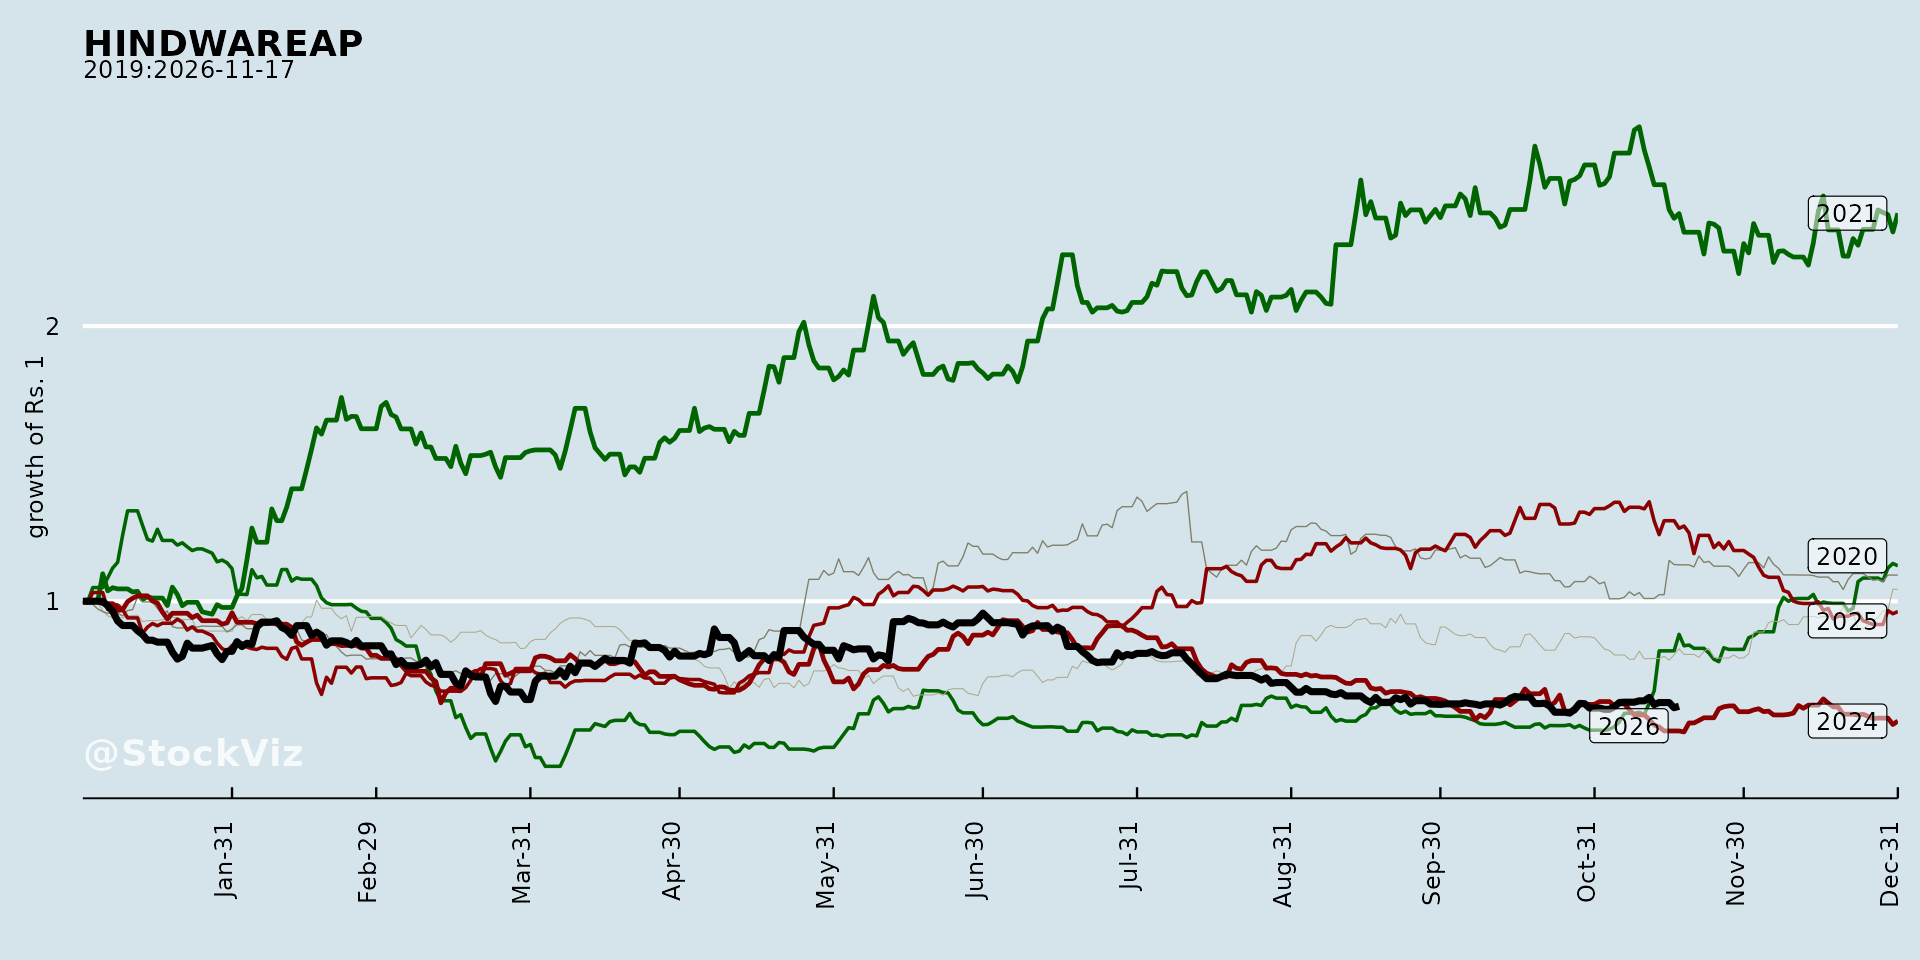
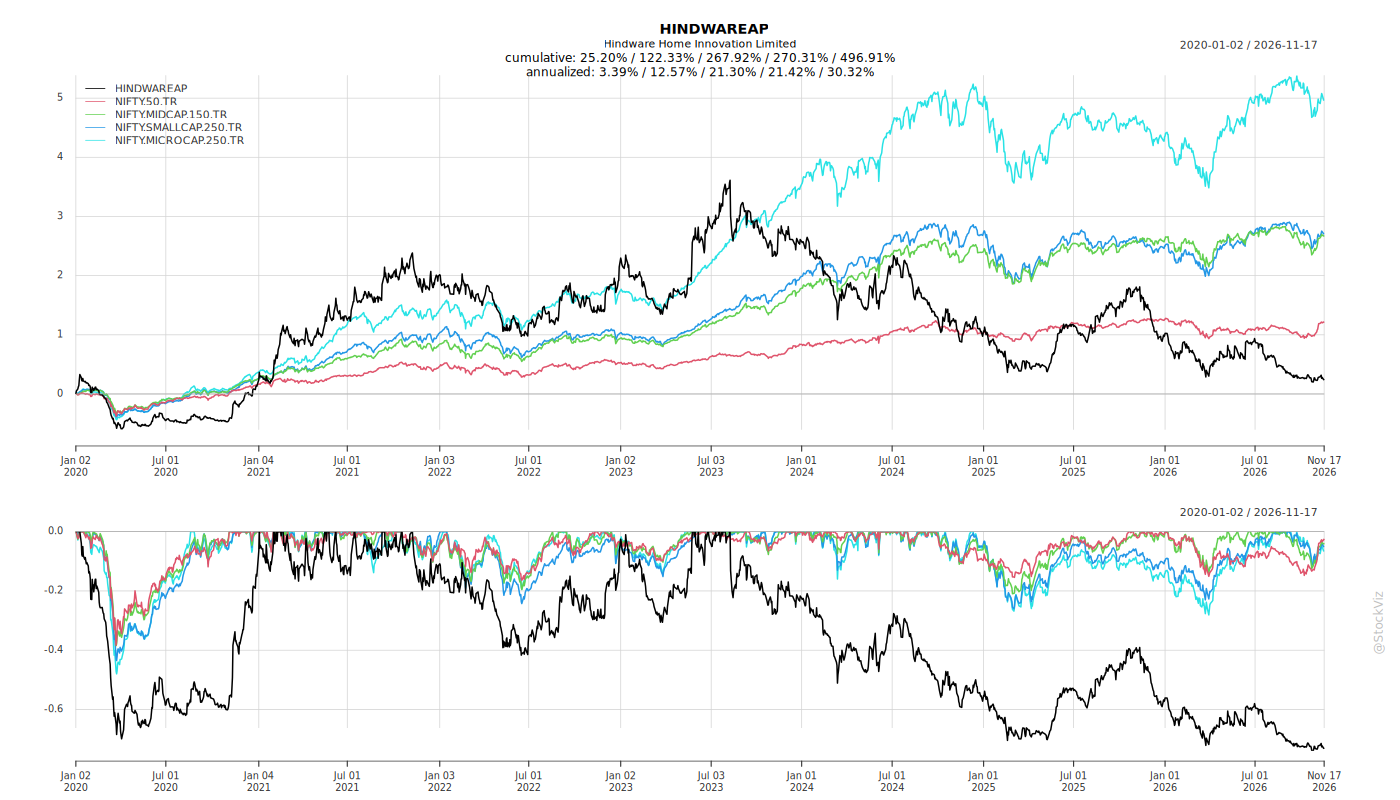
Cumulative Returns and Drawdowns
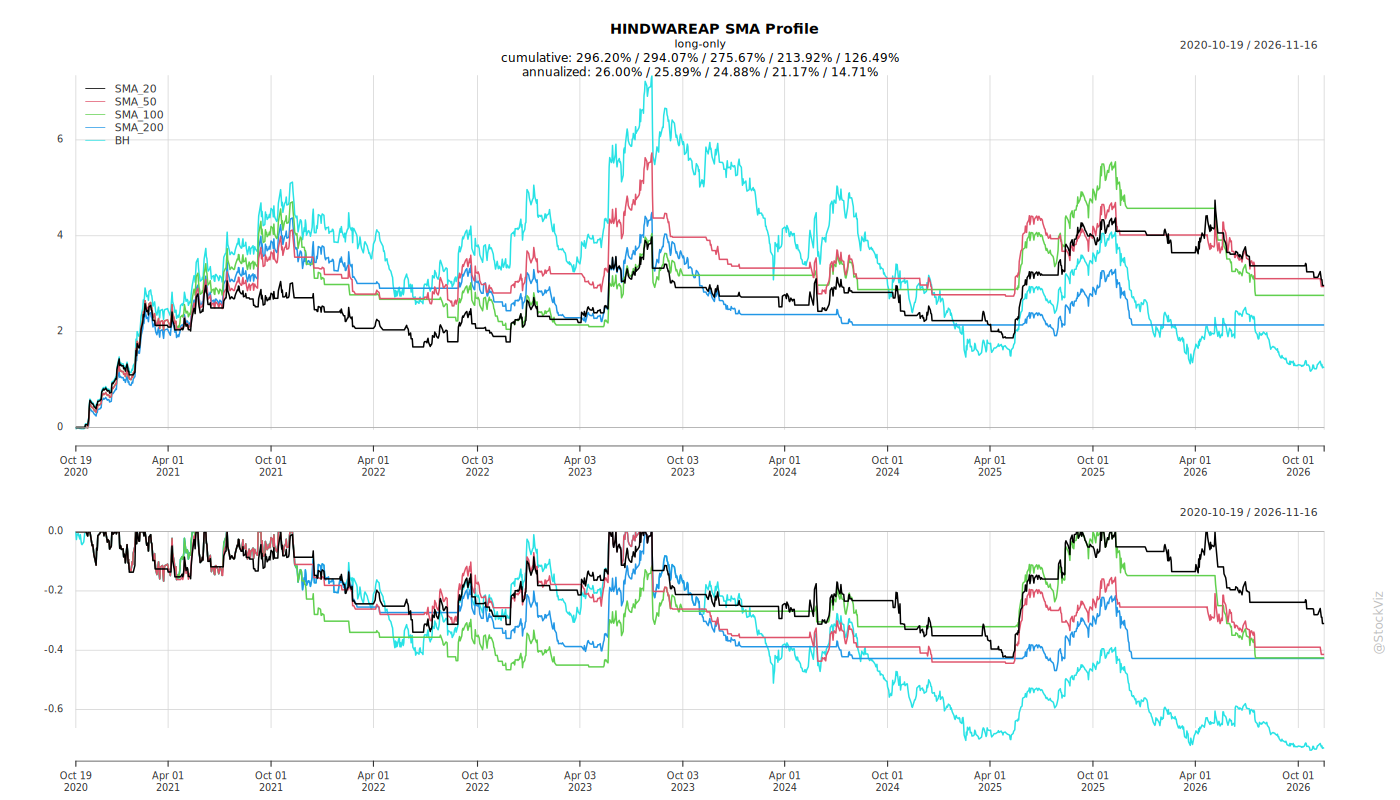
Fundamentals
Ownership
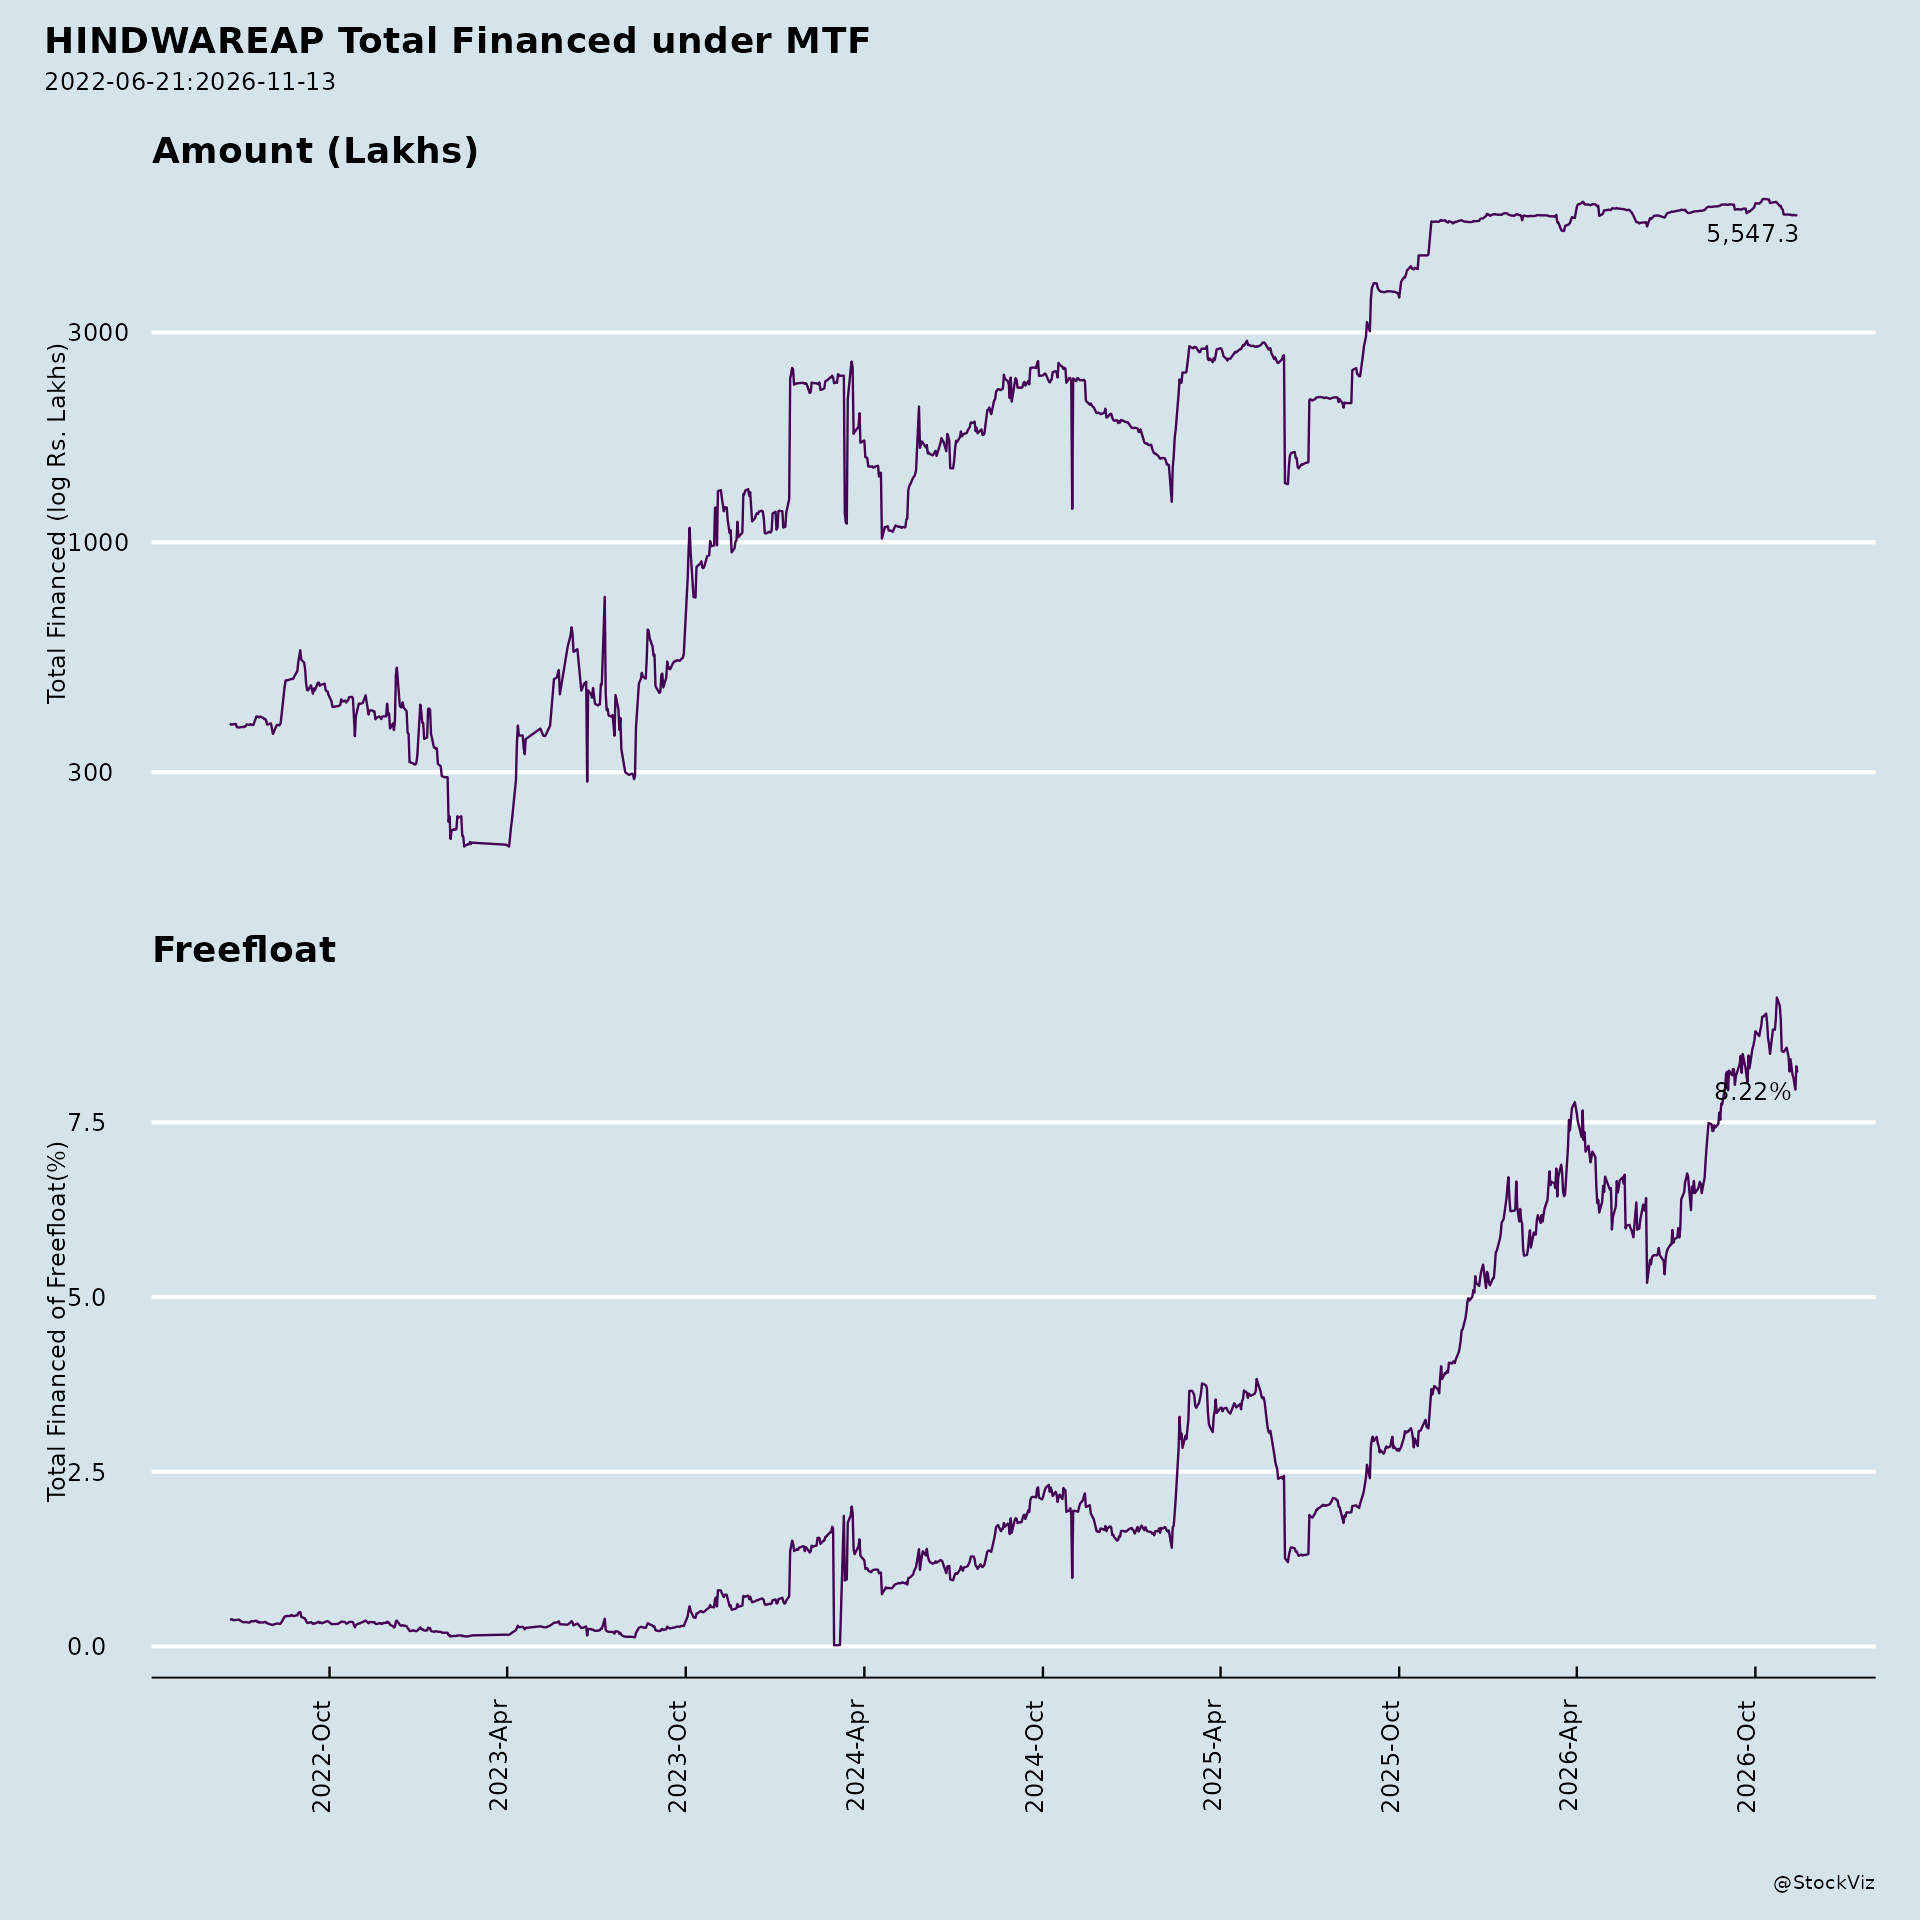
Margined
AI Summary
asof: 2026-09-18
Hindware Home Innovation Limited — Recent Developments
1. Headwinds and Challenges
Pipes & Fittings. Q1 FY27 results were impacted by volatility in currency and PVC resin prices, the capacity ramp-up phase at the recently commissioned Roorkee plant, and aggressive competition and pricing pressure. CPVC products accounted for ~32% of total value mix in Q1 FY27, reflecting typical seasonal softness in plumbing demand during the first half of the year. For FY26, the segment navigated sharp PVC resin price volatility and West Asia-linked supply chain disruptions that compressed industry-wide profitability; declining PVC resin prices weighed on realisations and margins, causing inventory losses and cautious channel behaviour.
Bathware. The business faced industry headwinds and rising input costs in Q1 FY27, though sales still grew ~14% YoY to ₹387 crore. The broader market remained under macroeconomic pressure during FY26, with pricing pressures, raw material cost volatility, and competition from unorganised players weighing on industry margins, while global supply chain disruptions added to logistics costs. Supply disruptions in the final months of FY26 temporarily affected production volumes and product availability.
Consumer Products. FY26 was a year of consolidation, with the segment recording revenue of ₹317 crore and Operating EBITDA of negative ₹12 crore. Persistent inflationary pressures and cautious consumer sentiment weighed on discretionary spending. The kitchen appliances segment saw the entry of online-first brands and value-led imports, intensifying channel fragmentation and pricing pressures.
Macro. Escalation of the West Asia conflict introduced fresh volatility; India remains sensitive to crude oil price volatility with potential implications for inflation, the current account, and import costs. Currency fluctuations and inflationary pressures escalate the landed cost of imported raw materials, while higher living costs pressure consumer discretionary spending.
2. Tailwinds and Growth Prospects
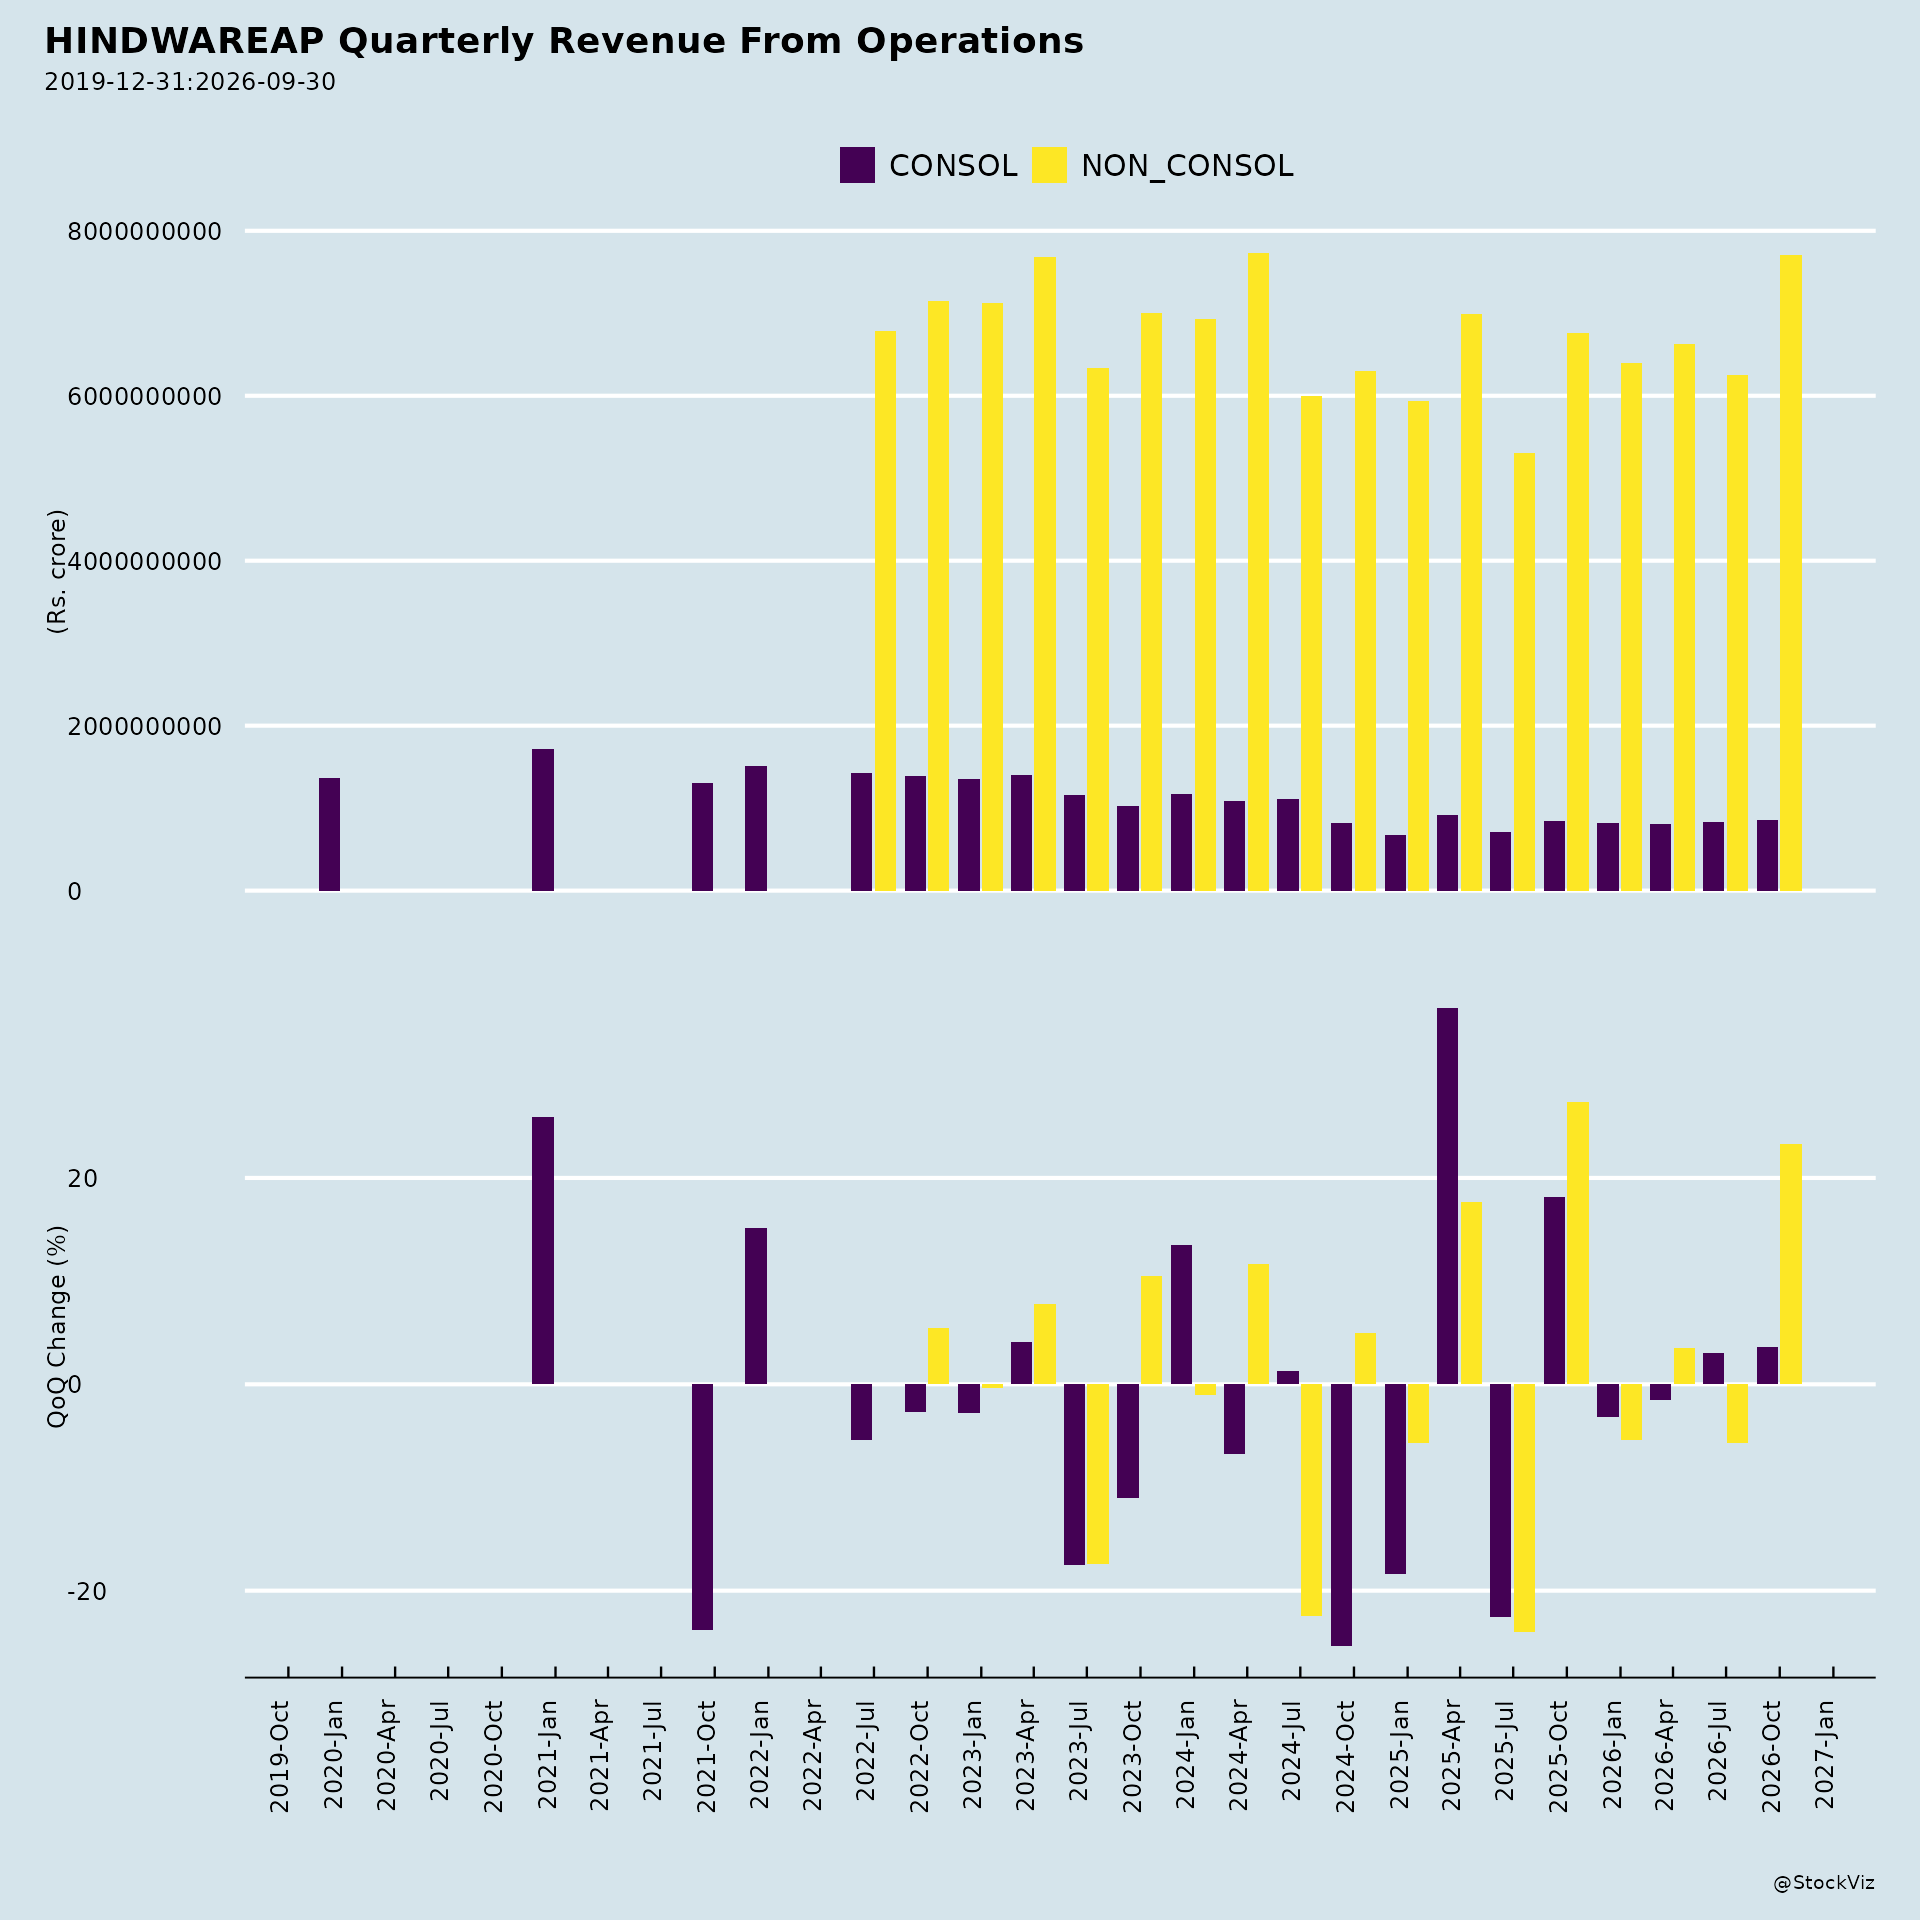
Bathware. FY26 revenue grew 10% to ₹1,520 crore, with Operating EBITDA up 30% to ₹157 crore and a 150 bps margin improvement to 10.3%, driven by premiumisation, expansion of the active dealer network, and deeper Tier II/III penetration. Growth was broad-based across general trade, institutional channels, and e-commerce, with institutional and project sales contributing ~25% of segment turnover. Premium products are ~40% of the portfolio. The Company aims for mid-teen sales growth in FY27. Q1 FY27 sales grew ~14% YoY to ₹387 crore with EBITDA of ₹46 crore, aided by better mix and operating leverage.
Pipes. The Roorkee facility (12,500 TPA initial capacity) was commissioned in January 2026, taking total installed capacity to 78,500+ TPA and establishing a North India manufacturing presence. New high-margin offerings include DWC pipes, PTMT bath fittings, and foam-core pipes; the DWC range has been commercialised in sizes from 100 mm to 600 mm with BIS licence secured. The long-term demand outlook remains positive, underpinned by government investment in housing, water infrastructure, and urban development; near-term recovery is expected from improving channel sentiment, stabilising resin prices, and resuming project execution through FY27.
Consumer Products. Q1 FY27 revenue grew 16% YoY to ~₹83 crore. The business aims to cross ₹500+ crore within 2 years and scale to ₹700–750 crore by FY31, with gross margins of 35–40% and double-digit overall margins as scale builds. Following its transition to a wholly owned subsidiary in Q1 FY27, Hintastica Private Limited operates on an asset-light model. An AI-enabled chimney range (24 new SKUs) anchors the forward strategy.
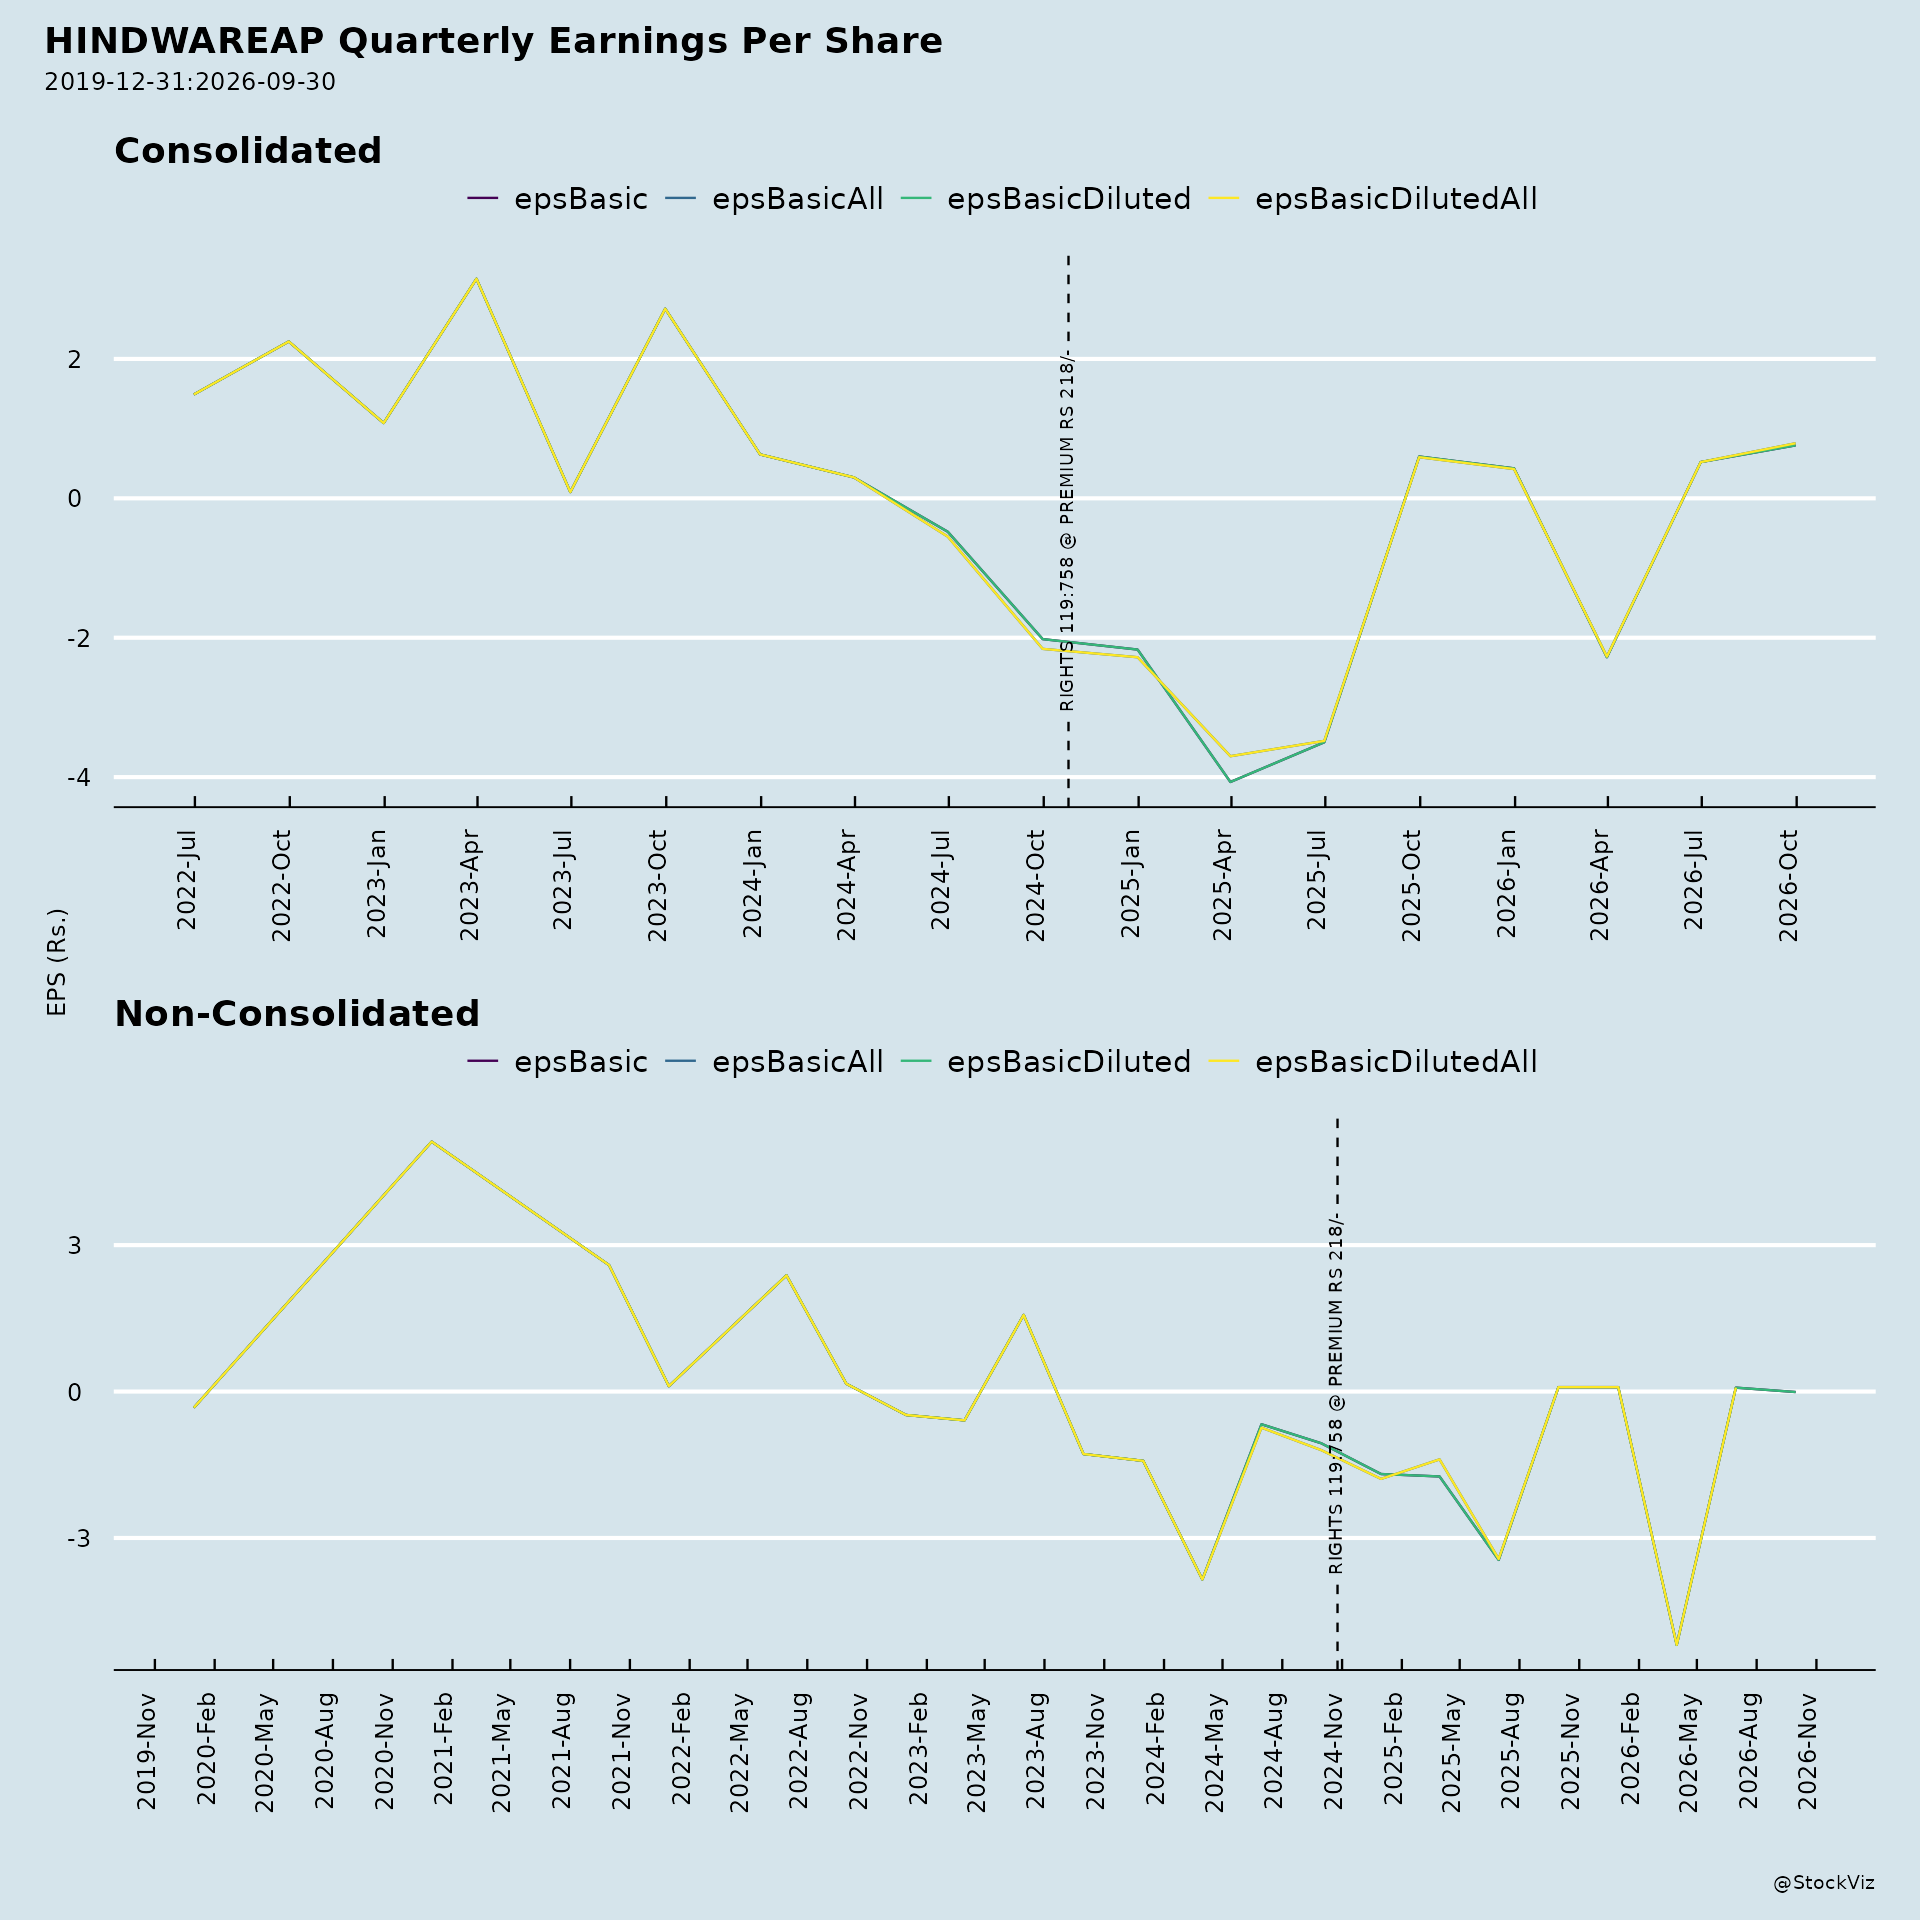
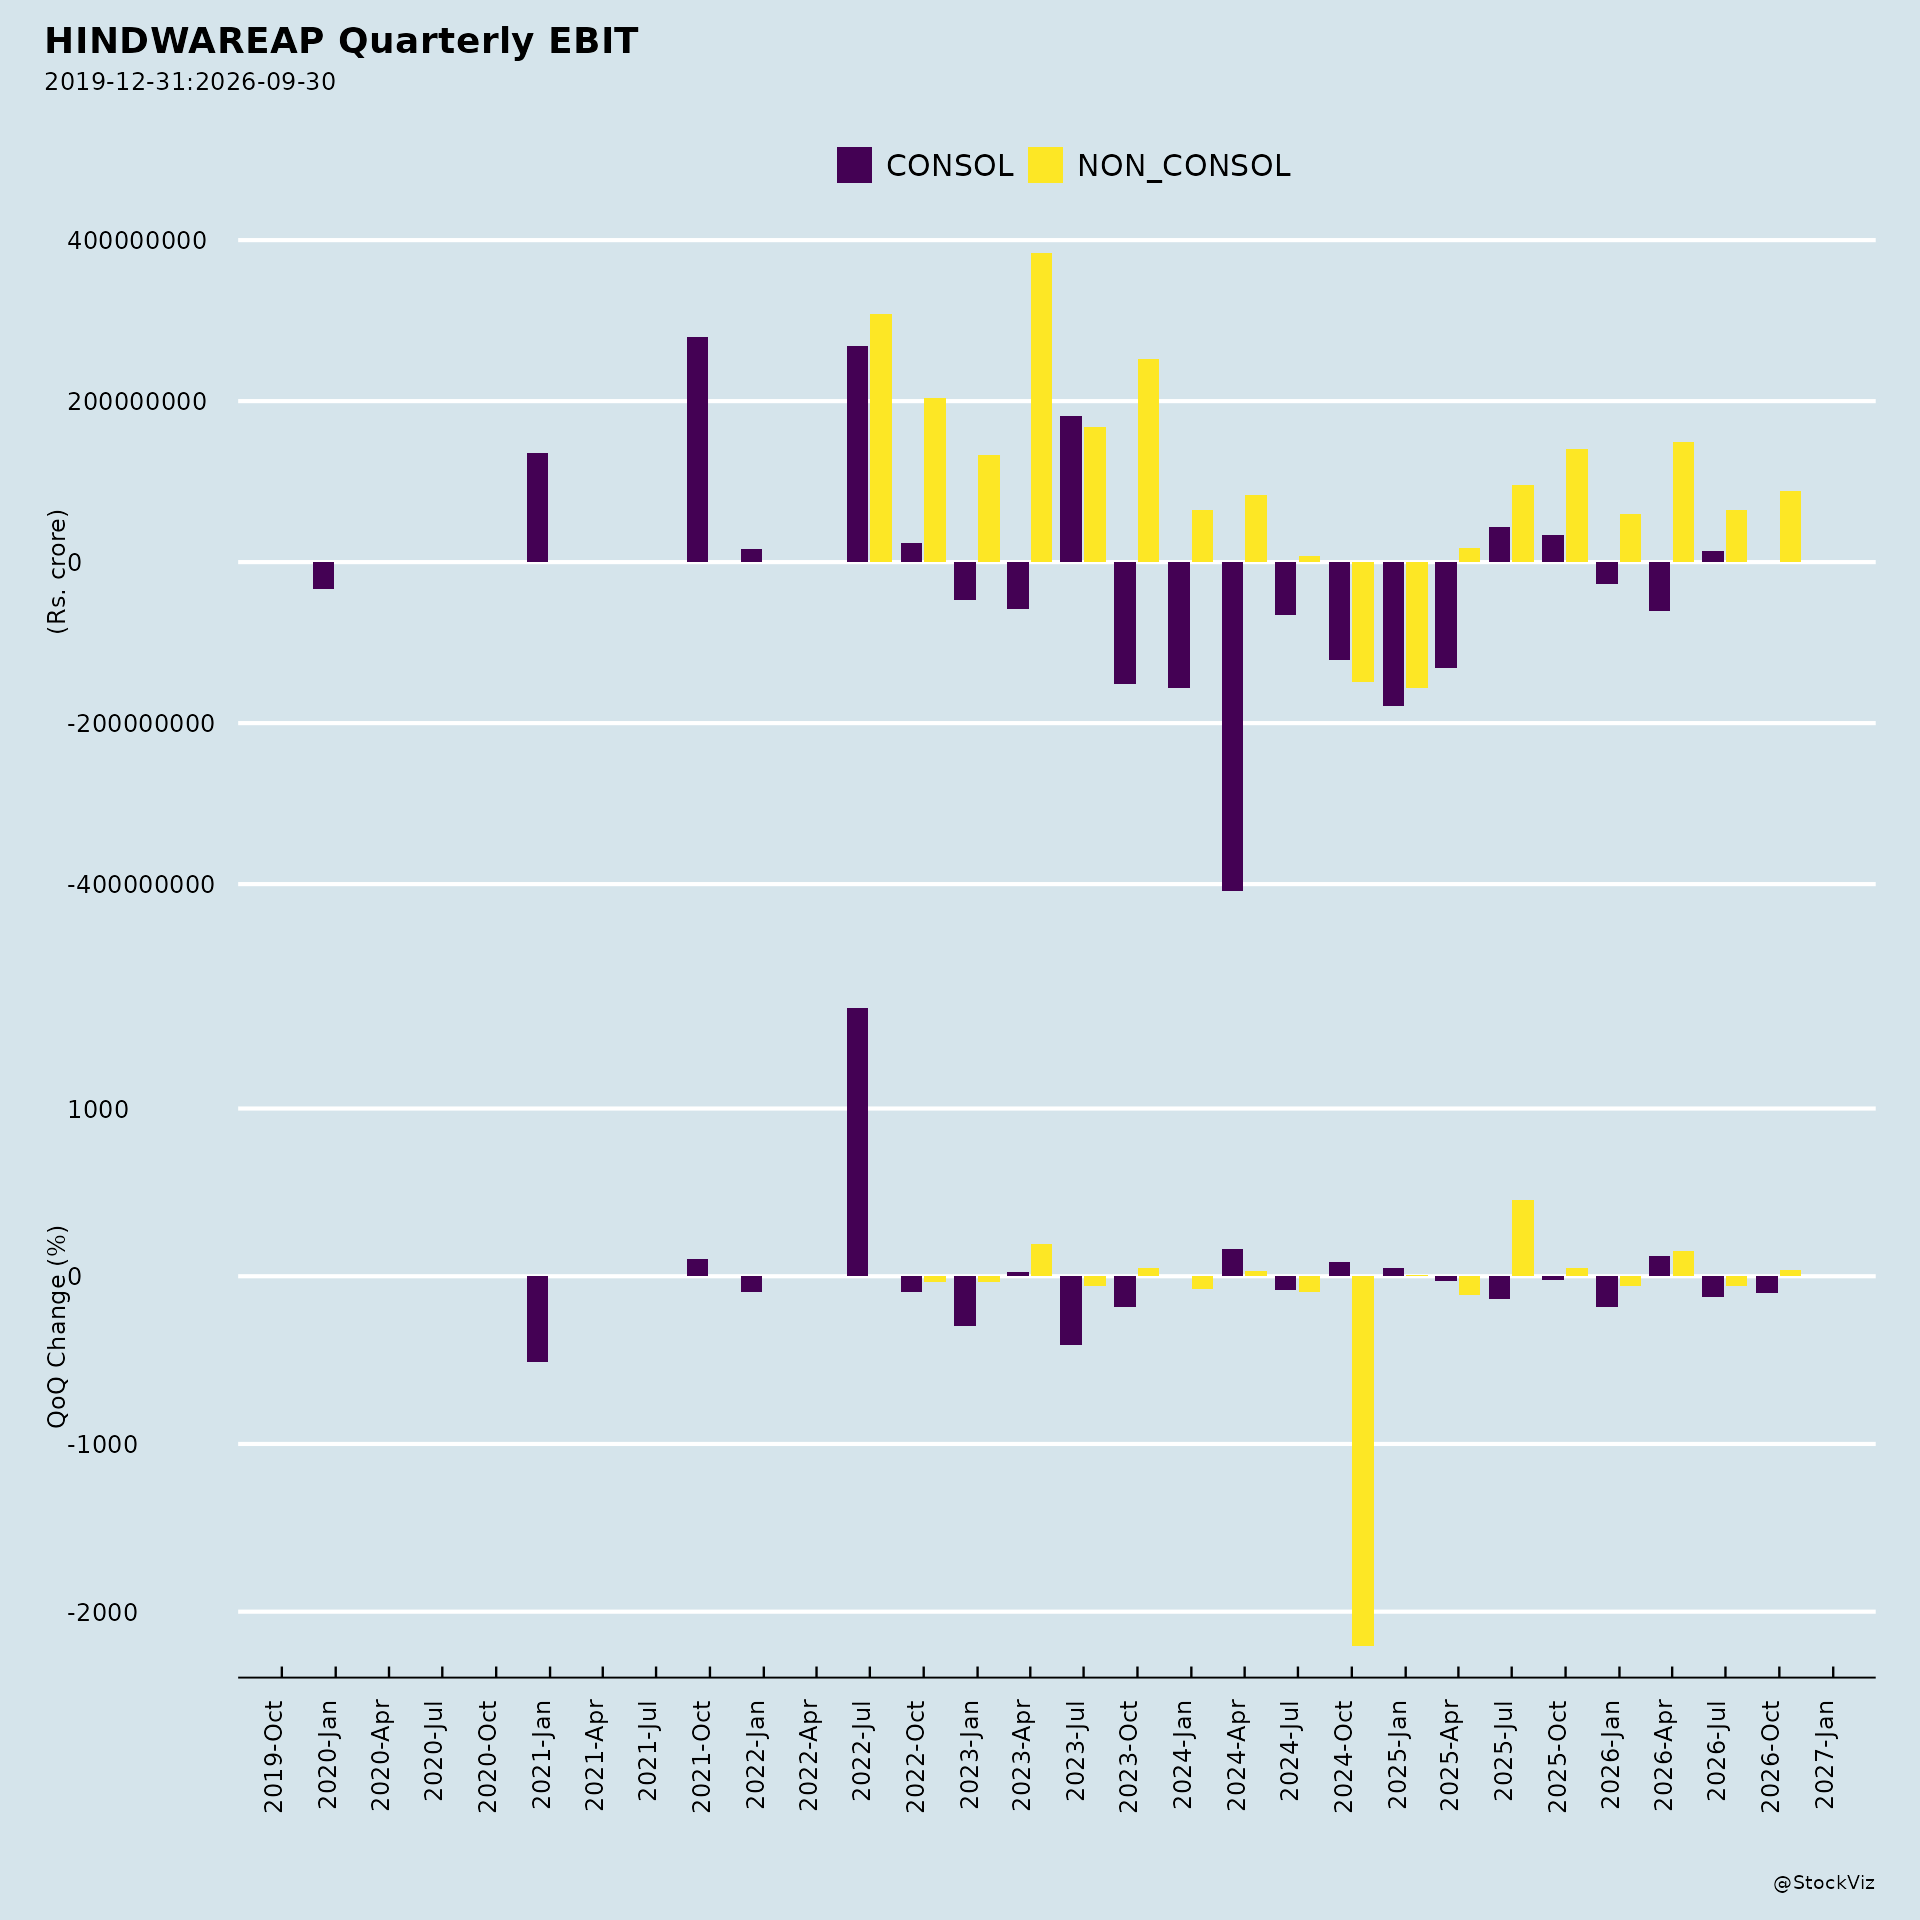
Group. Consolidated FY26 revenue was ₹2,510 crore with EBITDA of ₹233 crore (9.3% margin), expanding 25%. Q1 FY27 consolidated revenue was ₹625 crore with EBITDA of ₹63 crore.
3. Key Risks
- Economic, political and market risk: macroeconomic slowdowns, geopolitical tensions, inflation spikes, and interest-rate hikes dampening consumer demand.
- Competition risk: intensifying competition, particularly from unbranded players, eroding pricing power and compressing margins.
- Consumer risk: rapid shifts in consumer preferences leading to lower product adoption.
- Product quality risk: poor quality damaging brand reputation and sales.
- Technology risk: reliance on outdated technology eroding competitiveness.
- Employee risk: inability to attract or retain talent hindering strategic objectives.
- Distribution risk: shifts in buying habits undermining traditional channels.
- Operating efficiency risk: under-utilisation of assets and supply chain disruptions inflating costs and reducing margins.
- Cyber security risk: cyber-attacks disrupting operations and compromising data.
- Business continuity risk: unforeseen events disrupting daily operations.
- Brand legacy risk: negative perceptions detracting from brand equity.
- Credit profile / credit rating risk: difficulty securing funds at favourable rates; fluctuations influencing cost of capital.
- Currency risk: foreign-exchange volatility eroding profitability on imports and exports.
- Legal and compliance risk: non-compliance resulting in penalties, litigation, and reputational damage.
4. Management Guidance vs. Observed Performance
Bathware FY27 guidance. Management aims for mid-teen sales growth in FY27, supported by improving market conditions and momentum across core categories. Observed: Q1 FY27 sales grew ~14% YoY to ₹387 crore, with EBITDA of ₹46 crore.
Consumer Products guidance. Management aims for revenues to cross ₹500+ crore within 2 years and ₹700–750 crore by FY31, with gross margins of 35–40% and double-digit overall margins as scale builds. Observed: Q1 FY27 revenue grew 16% YoY to ~₹83 crore; FY26 segment revenue was ₹317 crore with Operating EBITDA of negative ₹12 crore.
Pipes outlook. Management expects gradual recovery in industry demand through FY27 on improving channel sentiment, stabilising resin prices, and resuming project execution. Observed: Q1 FY27 revenue declined to ₹153 crore from ₹186 crore in Q1 FY26, with EBITDA of ₹7 crore and PBT of negative ₹15 crore; FY26 revenue was ₹673 crore with Operating EBITDA of ₹41 crore.
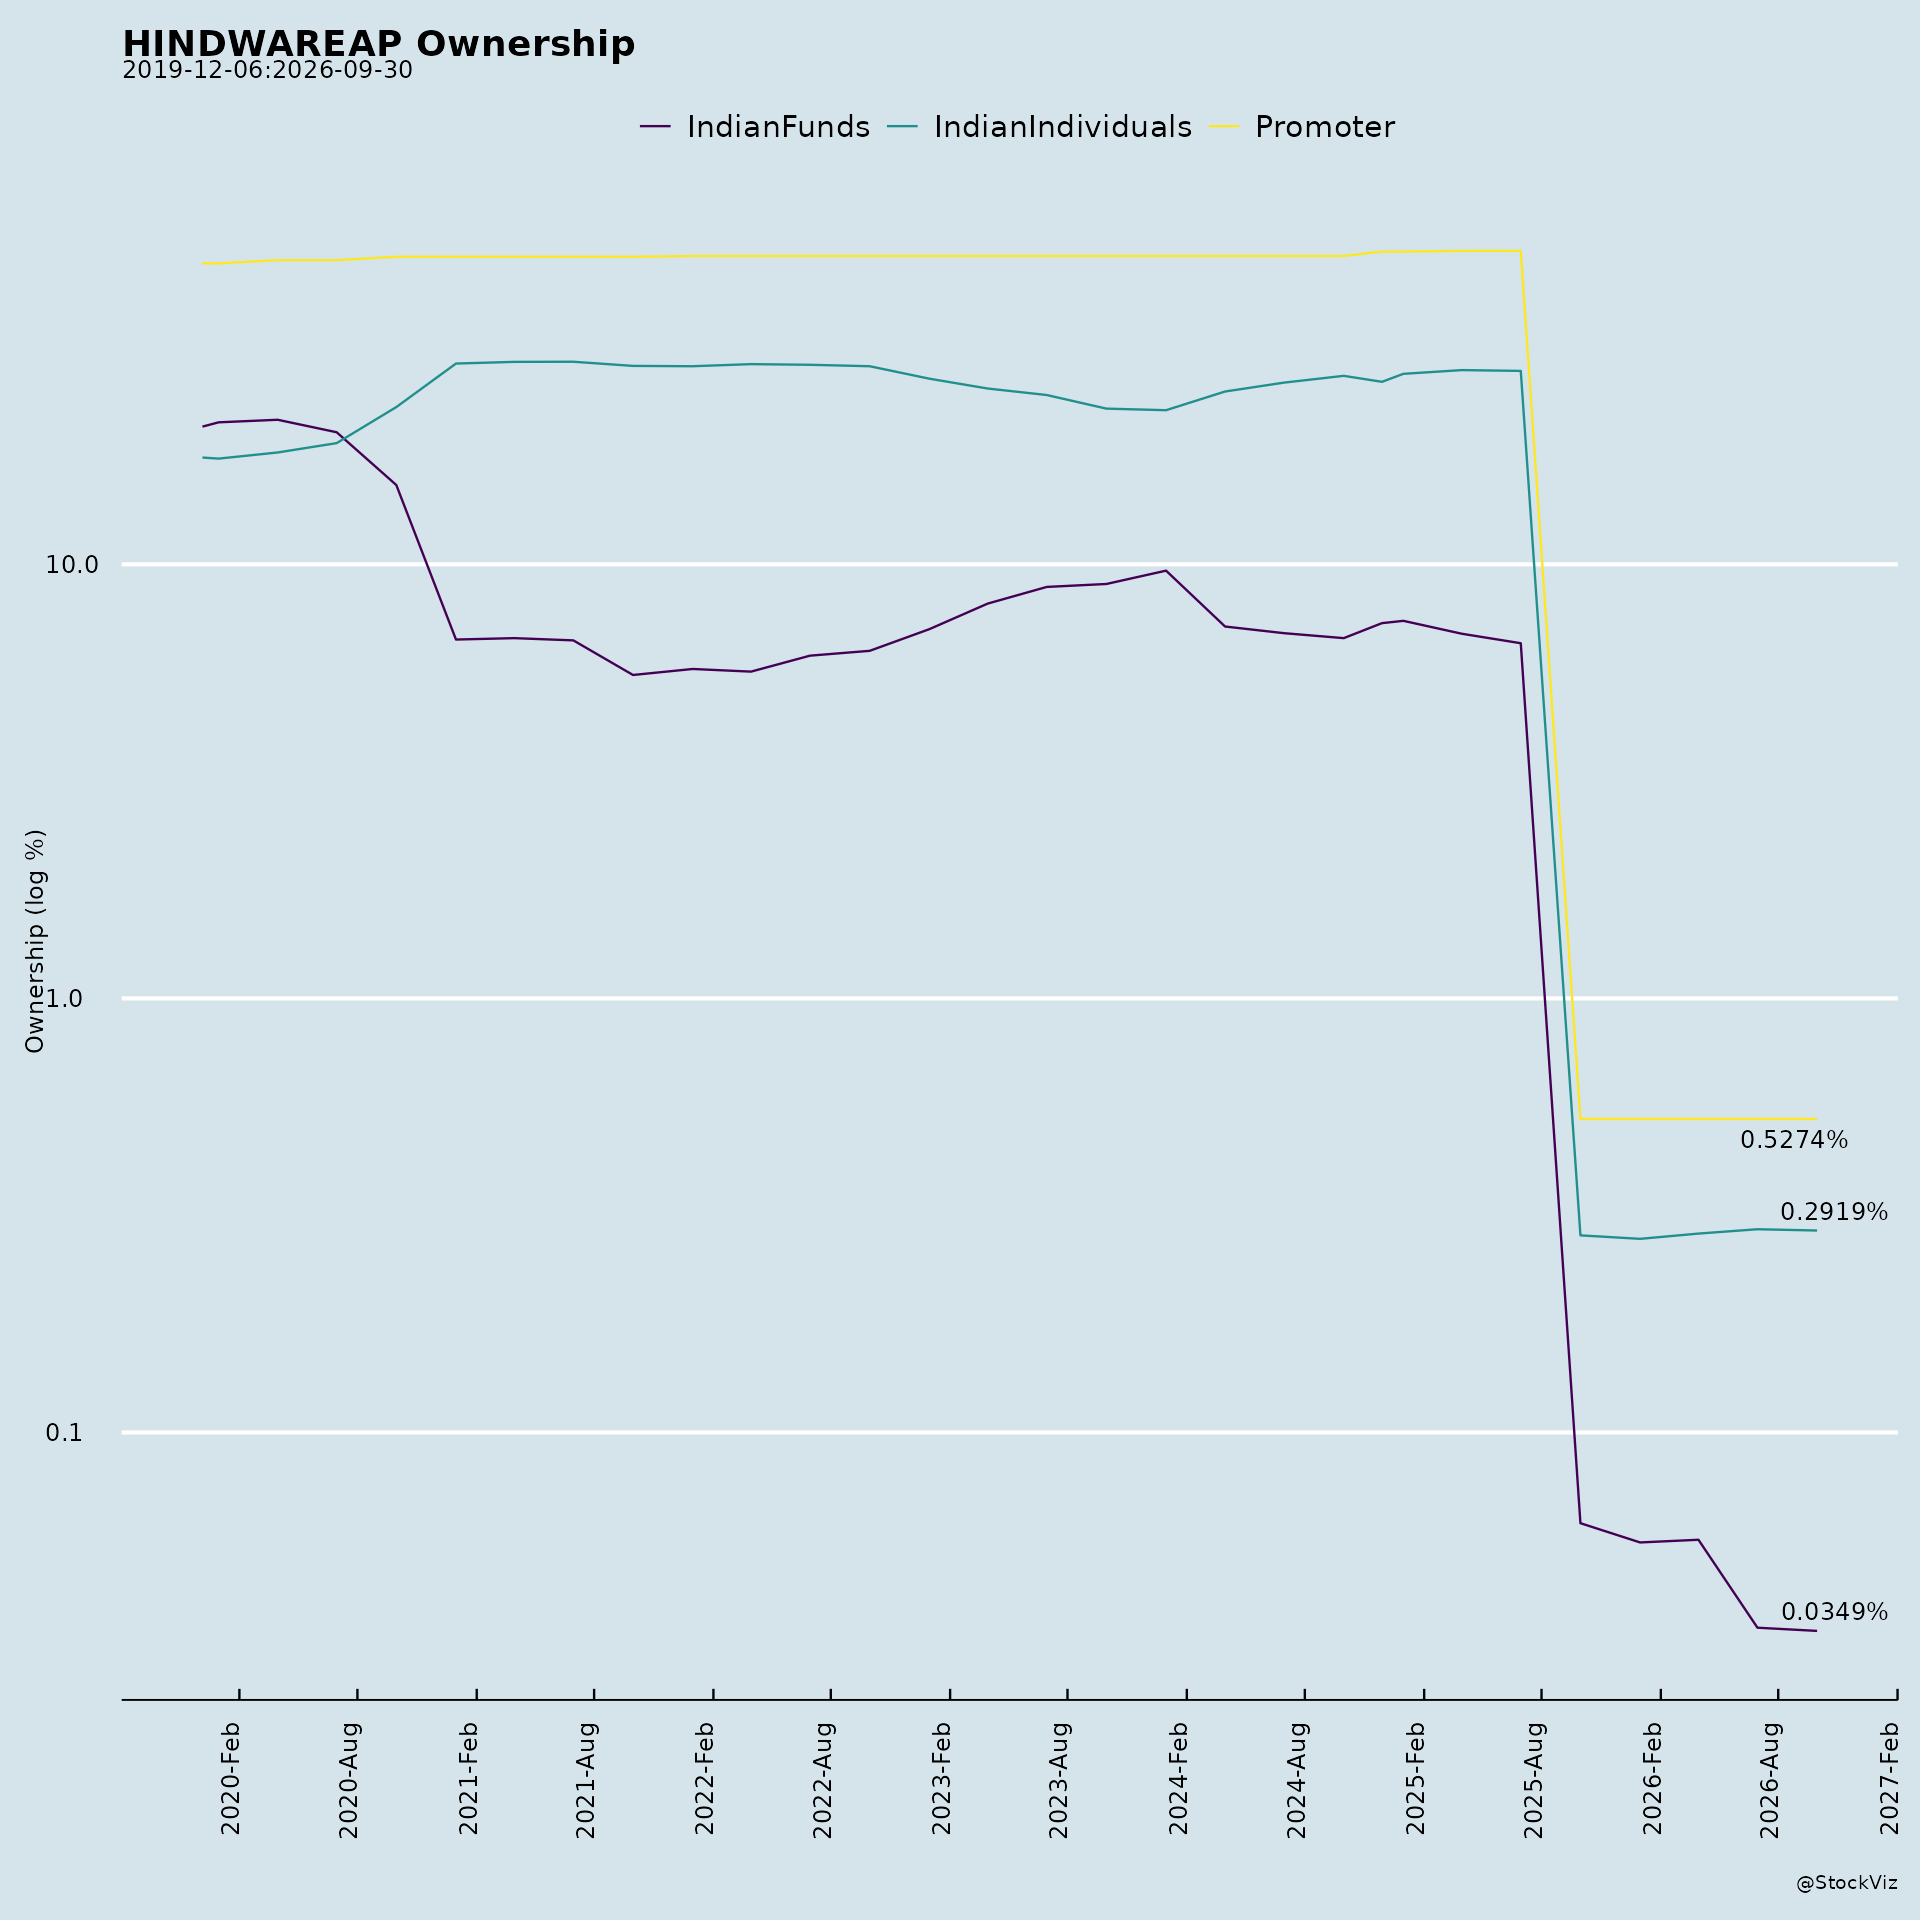
Demerger. The Board approved a Composite Scheme of Arrangement on 27 March 2025 (appointed date 1 April 2025) providing for demerger of the Consumer Products Business into wholly-owned subsidiary HHIL Limited and amalgamation of the remaining Company into Hindware Limited. NOCs were received from NSE and BSE. The Scheme received requisite approval from unsecured creditors and equity shareholders at NCLT-convened meetings held on 7 March 2026. Management expects the process to conclude shortly, subject to remaining regulatory and procedural approvals, with listing of the resulting entities to follow. The Scheme remains subject to NCLT sanction.
Capital expenditure. Management states the major expansion phase capital expenditure is now fully complete, with focus shifting to optimising invested capital for profitable, capital-efficient growth.
Dividend. The Board decided not to recommend any dividend on equity shares for FY26.
Broker Narrative
The broker consistently maintained a Buy rating, but the narrative shifted from broad macro tailwinds such as premiumization, government infrastructure spending, PVC stability, and rural recovery to acknowledging operational deterioration: subdued demand, bathware degrowth, margin compression, and higher net debt. The later reports repositioned optimism on H2FY25 demand recovery, plastic pipes volume growth, and company-specific actions like the Roorkee plant and rights issue, while the initial macro-driven recovery thesis remained unfulfilled.
Fears that came true
- Higher input cost and inflationary pressures contributed to a 287 bps YoY EBITDA margin contraction to 7.2% in Q1FY25.
- Excessive monsoons/demand slowdown materialized as a subdued demand environment, with Q1FY25 topline down 4% YoY and bathware revenue down 10% YoY.
- Sharp contraction in CPVC prices materialized as plastic pipes ASP declined to Rs160/kg, dragging EBITDA/kg lower.
- Slowdown in the real-estate sector was reflected in bathware segment degrowth and soft consumer appliance demand.
Optimism that failed
- Expected rural demand recovery did not materialize; demand remained subdued and the topline declined 4% YoY.
- Premiumization and renovation-driven bathware growth failed to materialize; bathware revenue degrew 10% YoY and margins contracted to 12.8%.
- Stability in PVC prices did not hold; plastic pipes ASP declined to Rs160/kg, hurting profitability.
- Infrastructure and government-scheme demand was insufficient to prevent overall margin erosion, rising net debt, and persistently high working capital.
Broker Timeline
4 broker calls · 2023-08-24 to 2024-08-12
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.