HFCL
Equity Metrics
October 23, 2026
HFCL Limited
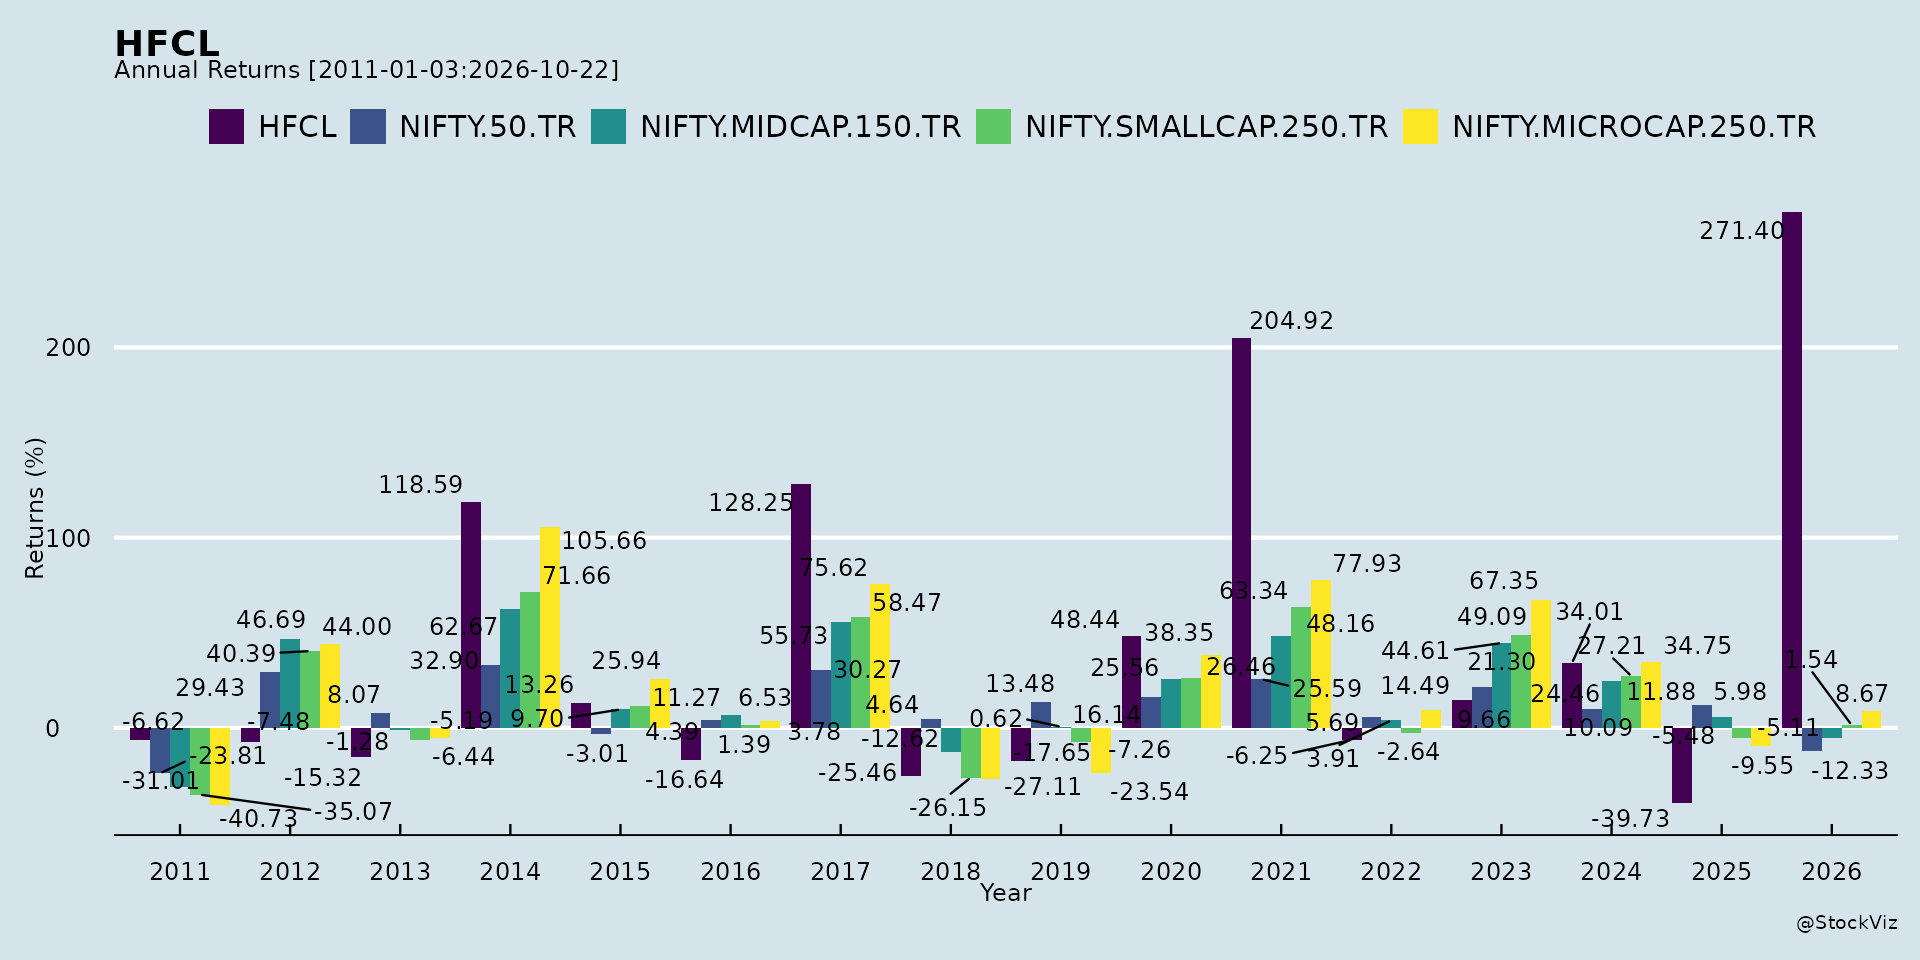
Annual Returns
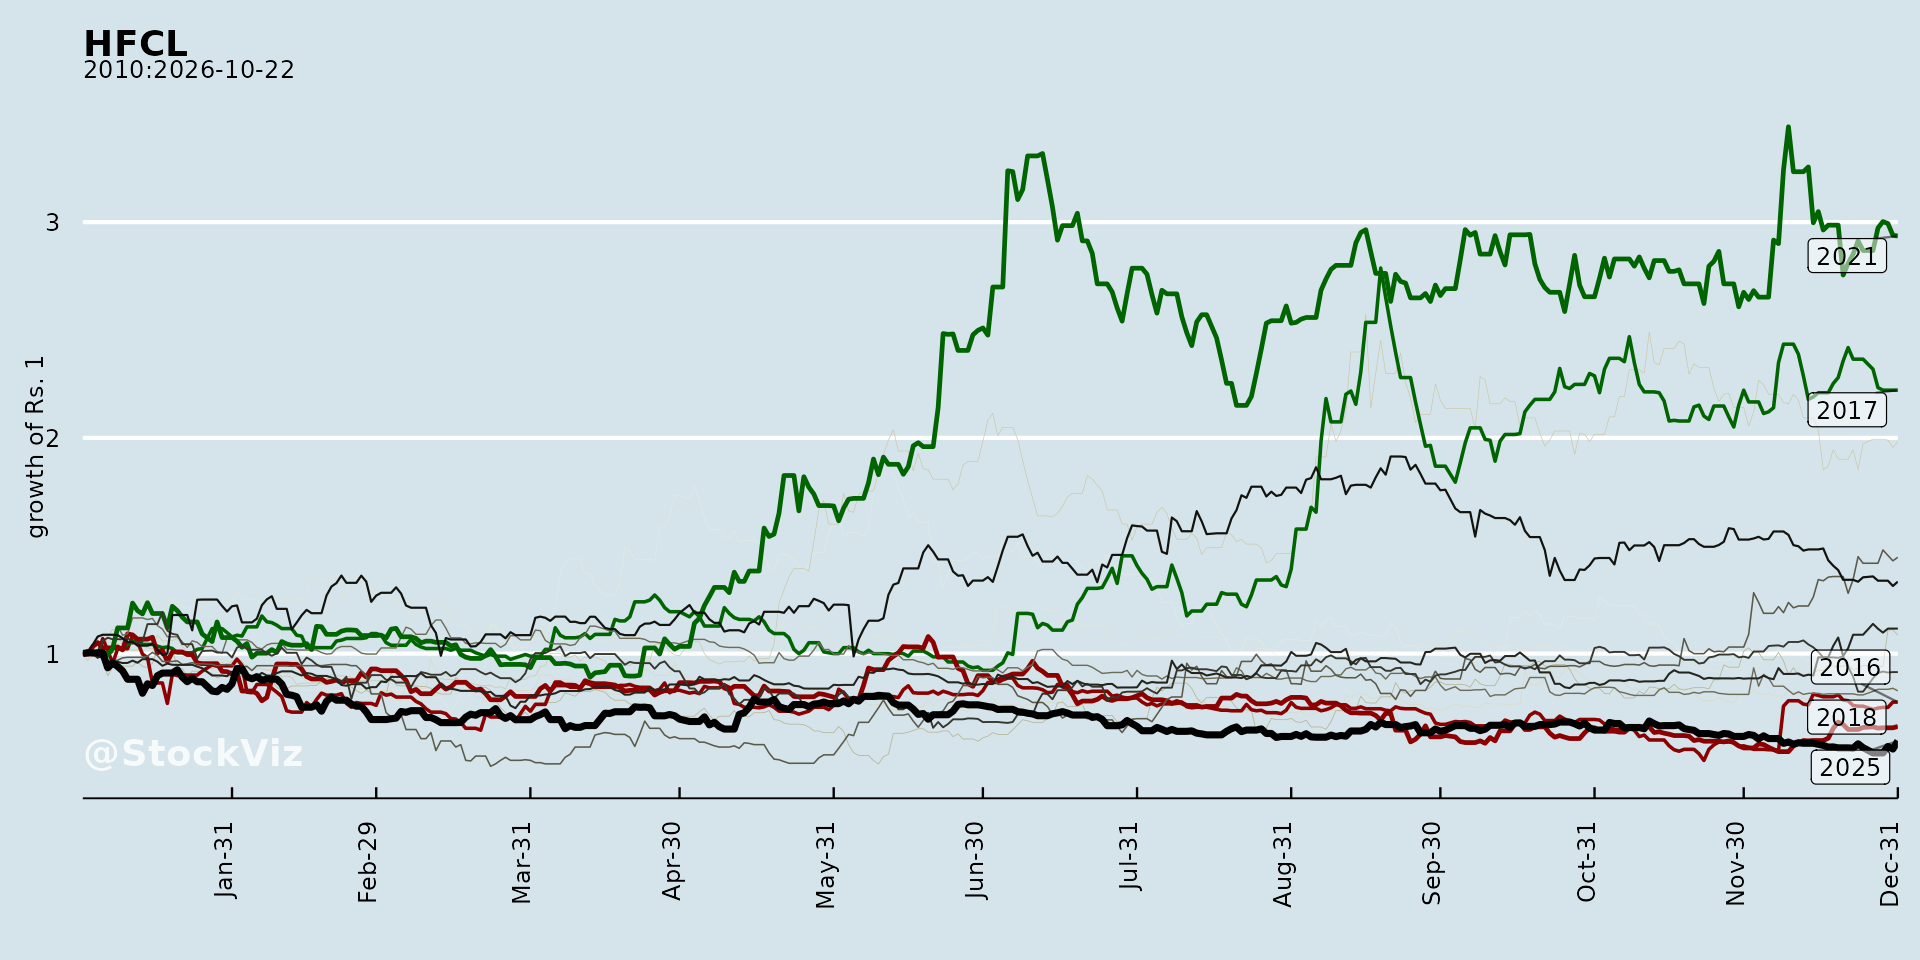
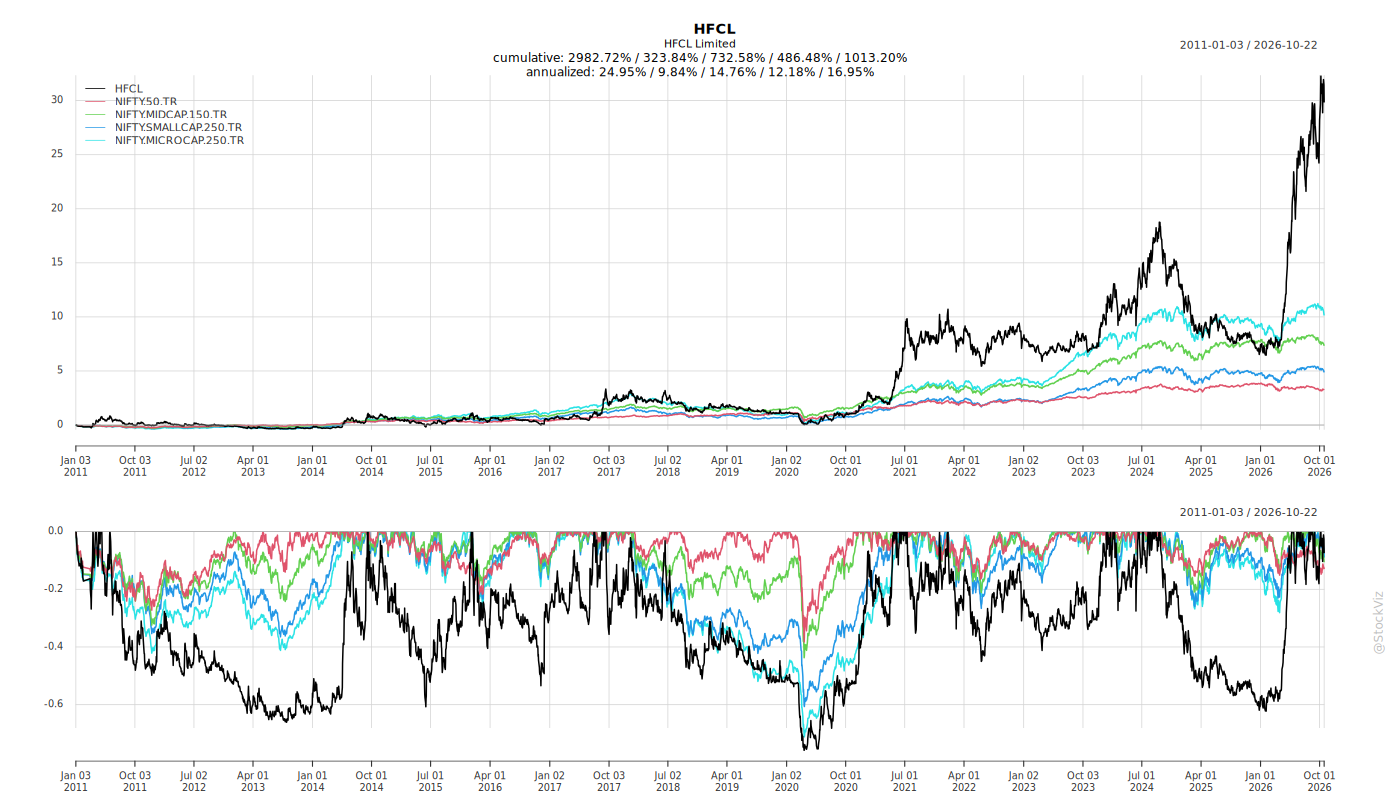
Cumulative Returns and Drawdowns
Fundamentals
Ownership
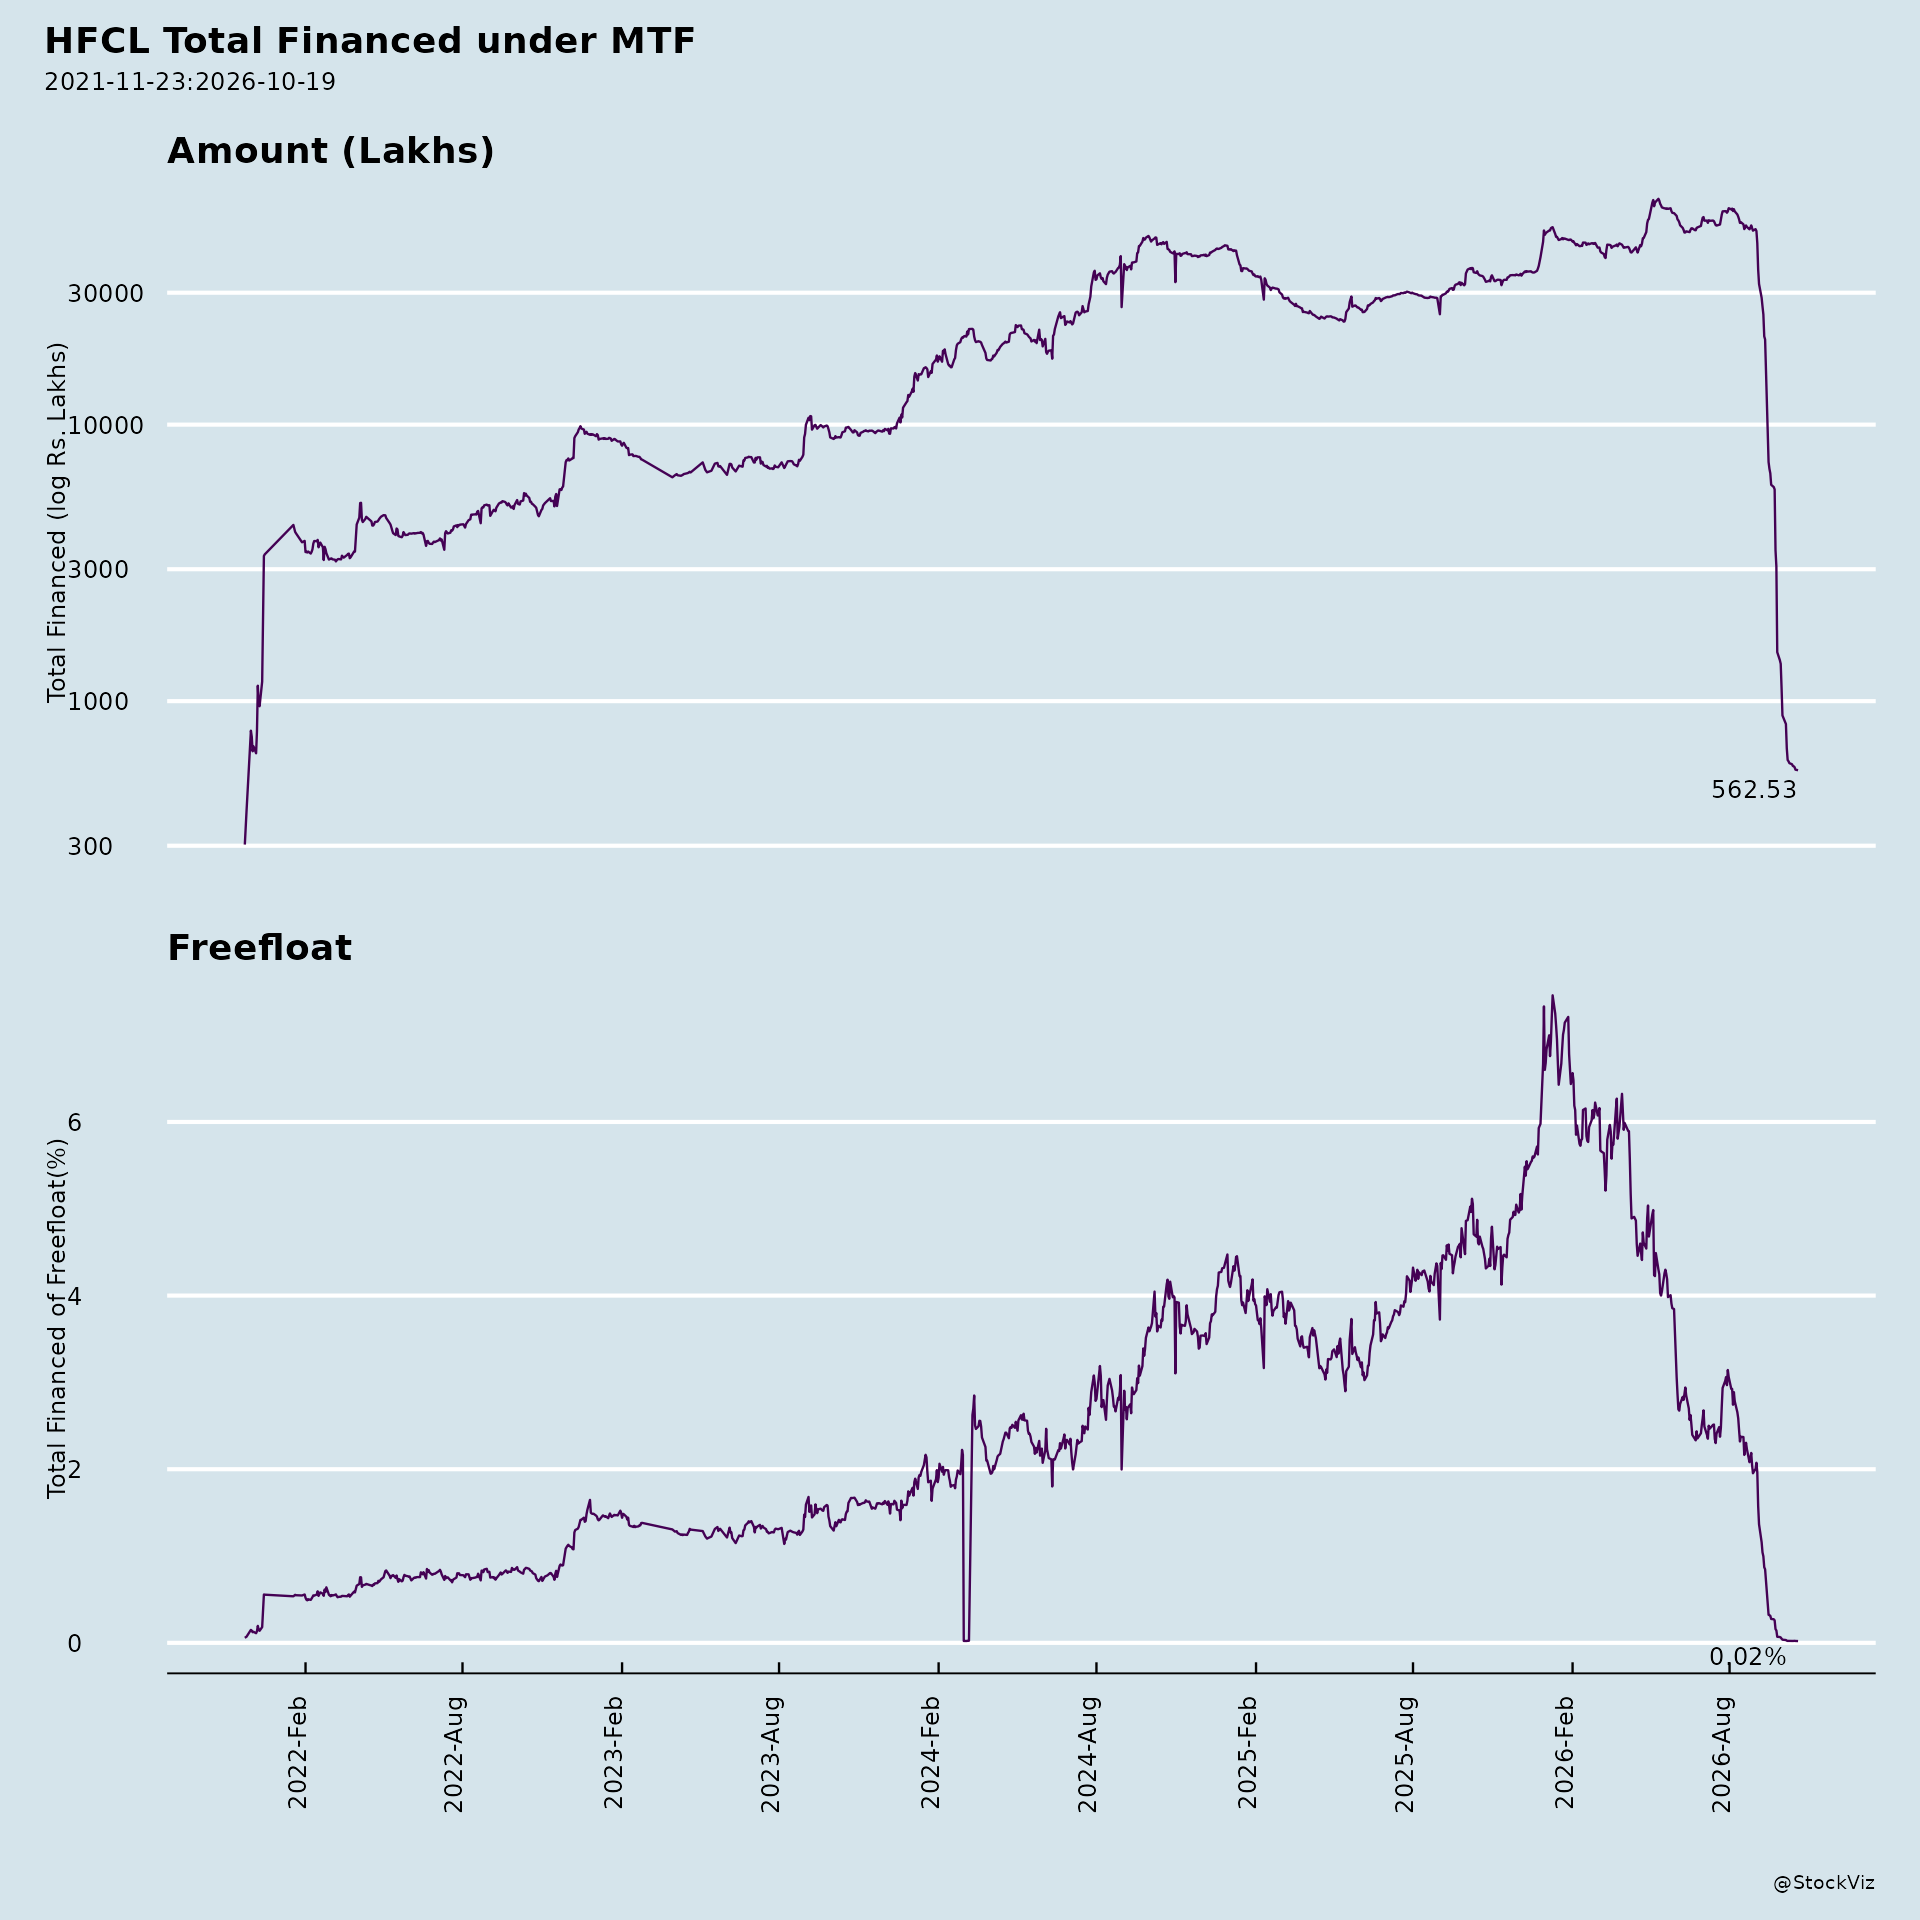
Margined
AI Summary
asof: 2026-09-16
HFCL: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
- Macroeconomic fluctuations affecting demand and profitability.
- Intense market competition affecting order acquisition and margins.
- Foreign exchange fluctuations arising from import/export operations.
- Rapid technological change that can render existing solutions obsolete.
- Regulatory or government policy shifts that can alter priorities.
- Execution risk: delays in project execution can attract penalties or reputational damage.
- Physical share certificate risks: loss, theft, and mutilation; transfer, transmission, and transposition requests are processed only in dematerialized form per Regulation 40 of the SEBI Regulations.
- Business-mix transition: management describes a deliberate pivot away from low-profit turnkey work toward a product-led mix, which affects the composition of revenue.
- Segment performance: in Q1FY27, the Turnkey Contracts and Services segment recorded a loss at the segment-result level, and the Defence Product & Services segment also showed a negative segment result for the quarter.
2. Tailwinds and Growth Prospects
- Global demand drivers: accelerating investments in artificial intelligence, cloud computing, hyperscale data centres, high-performance computing, 5G networks, and digital infrastructure, driving demand for advanced optical connectivity.
- Domestic drivers: BharatNet, PM-WANI, Production-Linked Incentive (PLI) programmes, Atmanirbhar Bharat, rising domestic consumption, and strong public capital expenditure.
- Defence: capital expenditure projected to grow significantly, with 75% allocated for domestic procurement; HFCL cites HAL preferred supplier status, DRDO technology transfer, an own-IPR portfolio, and a shift from L1 supplier to strategic partner.
- Data centre connectivity: the Board approved a new manufacturing facility for Data Center Connectivity Products (2,70,000 assemblies per annum, ~₹215 crore capex, expected commissioning by September 2027), producing Miniature Multi-Fiber (MMC) and Super High-Density Multi-Fiber Termination (SNMT) assemblies, in addition to HTL Limited’s existing facility.
- Capacity expansion: an additional ~₹820 crore approved for Optical Fiber, Optical Fiber Cable, and Preform capacity, on top of ~₹980 crore previously approved, taking total planned capex to ~₹1,800 crore. Target capacities: 43.10 mn fkm p.a. (Optical Fiber), 62.00 mn fkm p.a. (Optical Fiber Cable), and 600 MT p.a. (Preform).
- Order book: consolidated order book exceeding ₹21,200 crore, increasing to ₹26,665 crore as of June 30, 2026; the combined order book for Optical Fiber Cable and connectivity solutions is ~₹19,000 crore. A landmark five-year optical fiber cable agreement valued at ~₹10,159 crore was secured.
- Export contract: a three-year supply agreement with a global multinational for high-fibre-count OFC through an overseas wholly owned subsidiary, total contract value ~USD 244 million (~₹2,329 crore), with supplies in each calendar year from CY27 to CY29 and execution up to December 2029.
- Defence order book: ~₹2,300 crore total, of which ~₹2,000 crore is through an entity proposed to be acquired; a confirmed export order book of ~₹2,000 crore through the proposed aerospace business acquisition.
- Revenue mix targets: exports at 56% of revenues with a target of 60%+ from FY27 onwards; private sector revenue at 92%; products at ~85% of revenues.
- Investor engagement: participation in the Jefferies India Forum (September 18, 2026), Nomura India Power, Data Center & AI Infrastructure Tour 2026 (September 23, 2026), and Arihant Capital Bharat Connect Conference (virtual, September 29, 2026).
3. Key Risks
- Macroeconomic, competitive, foreign-exchange, technological-obsolescence, and regulatory/policy risks (as listed above).
- Project execution delays leading to penalties or reputational damage.
- Dependence on the pace of global AI, cloud, and data centre investment, and on domestic government programmes such as BharatNet and PLI.
- Execution and integration risk associated with proposed acquisitions (including the aerospace business and the entity holding ~₹2,000 crore of the defence order book).
- Capacity expansion execution risk: Optical Fiber and Optical Fiber Cable expansions are targeted for completion by December 2026 and July 2028, and the Preform facility by October 2028; the data centre connectivity facility by September 2027.
- Funding mix risk: the data centre facility is to be financed through a mix of internal accruals and/or debt.
- Shareholder servicing constraints: physical share certificates carry loss/theft/mutilation risk, and transfers are only processed in dematerialized form.
4. Management Guidance vs. Observed Business Performance
Guidance and forward-looking statements:
- FY27 revenue growth aspiration raised to the best of management’s estimates at 40%, with EBITDA margin of over 23% (achieved in Q1FY27).
- Exports targeted at more than 50% of total revenue for FY27 (presentation elsewhere cites 60%+ from FY27 onwards); product revenue targeted above 85% in FY27.
- Defence revenue target of ₹500 crore in FY27, up from ₹77 crore in FY26.
- EBITDA margin expansion from ~16.7% in FY26 to 22–25% by FY29.
- Capacity timelines: Optical Fiber and Optical Fiber Cable expansions by December 2026 and July 2028; Preform facility by October 2028; data centre connectivity facility by September 2027.
- Investor meeting schedule may change due to exigencies.
Observed performance (Q1FY27, quarter ended June 30, 2026):
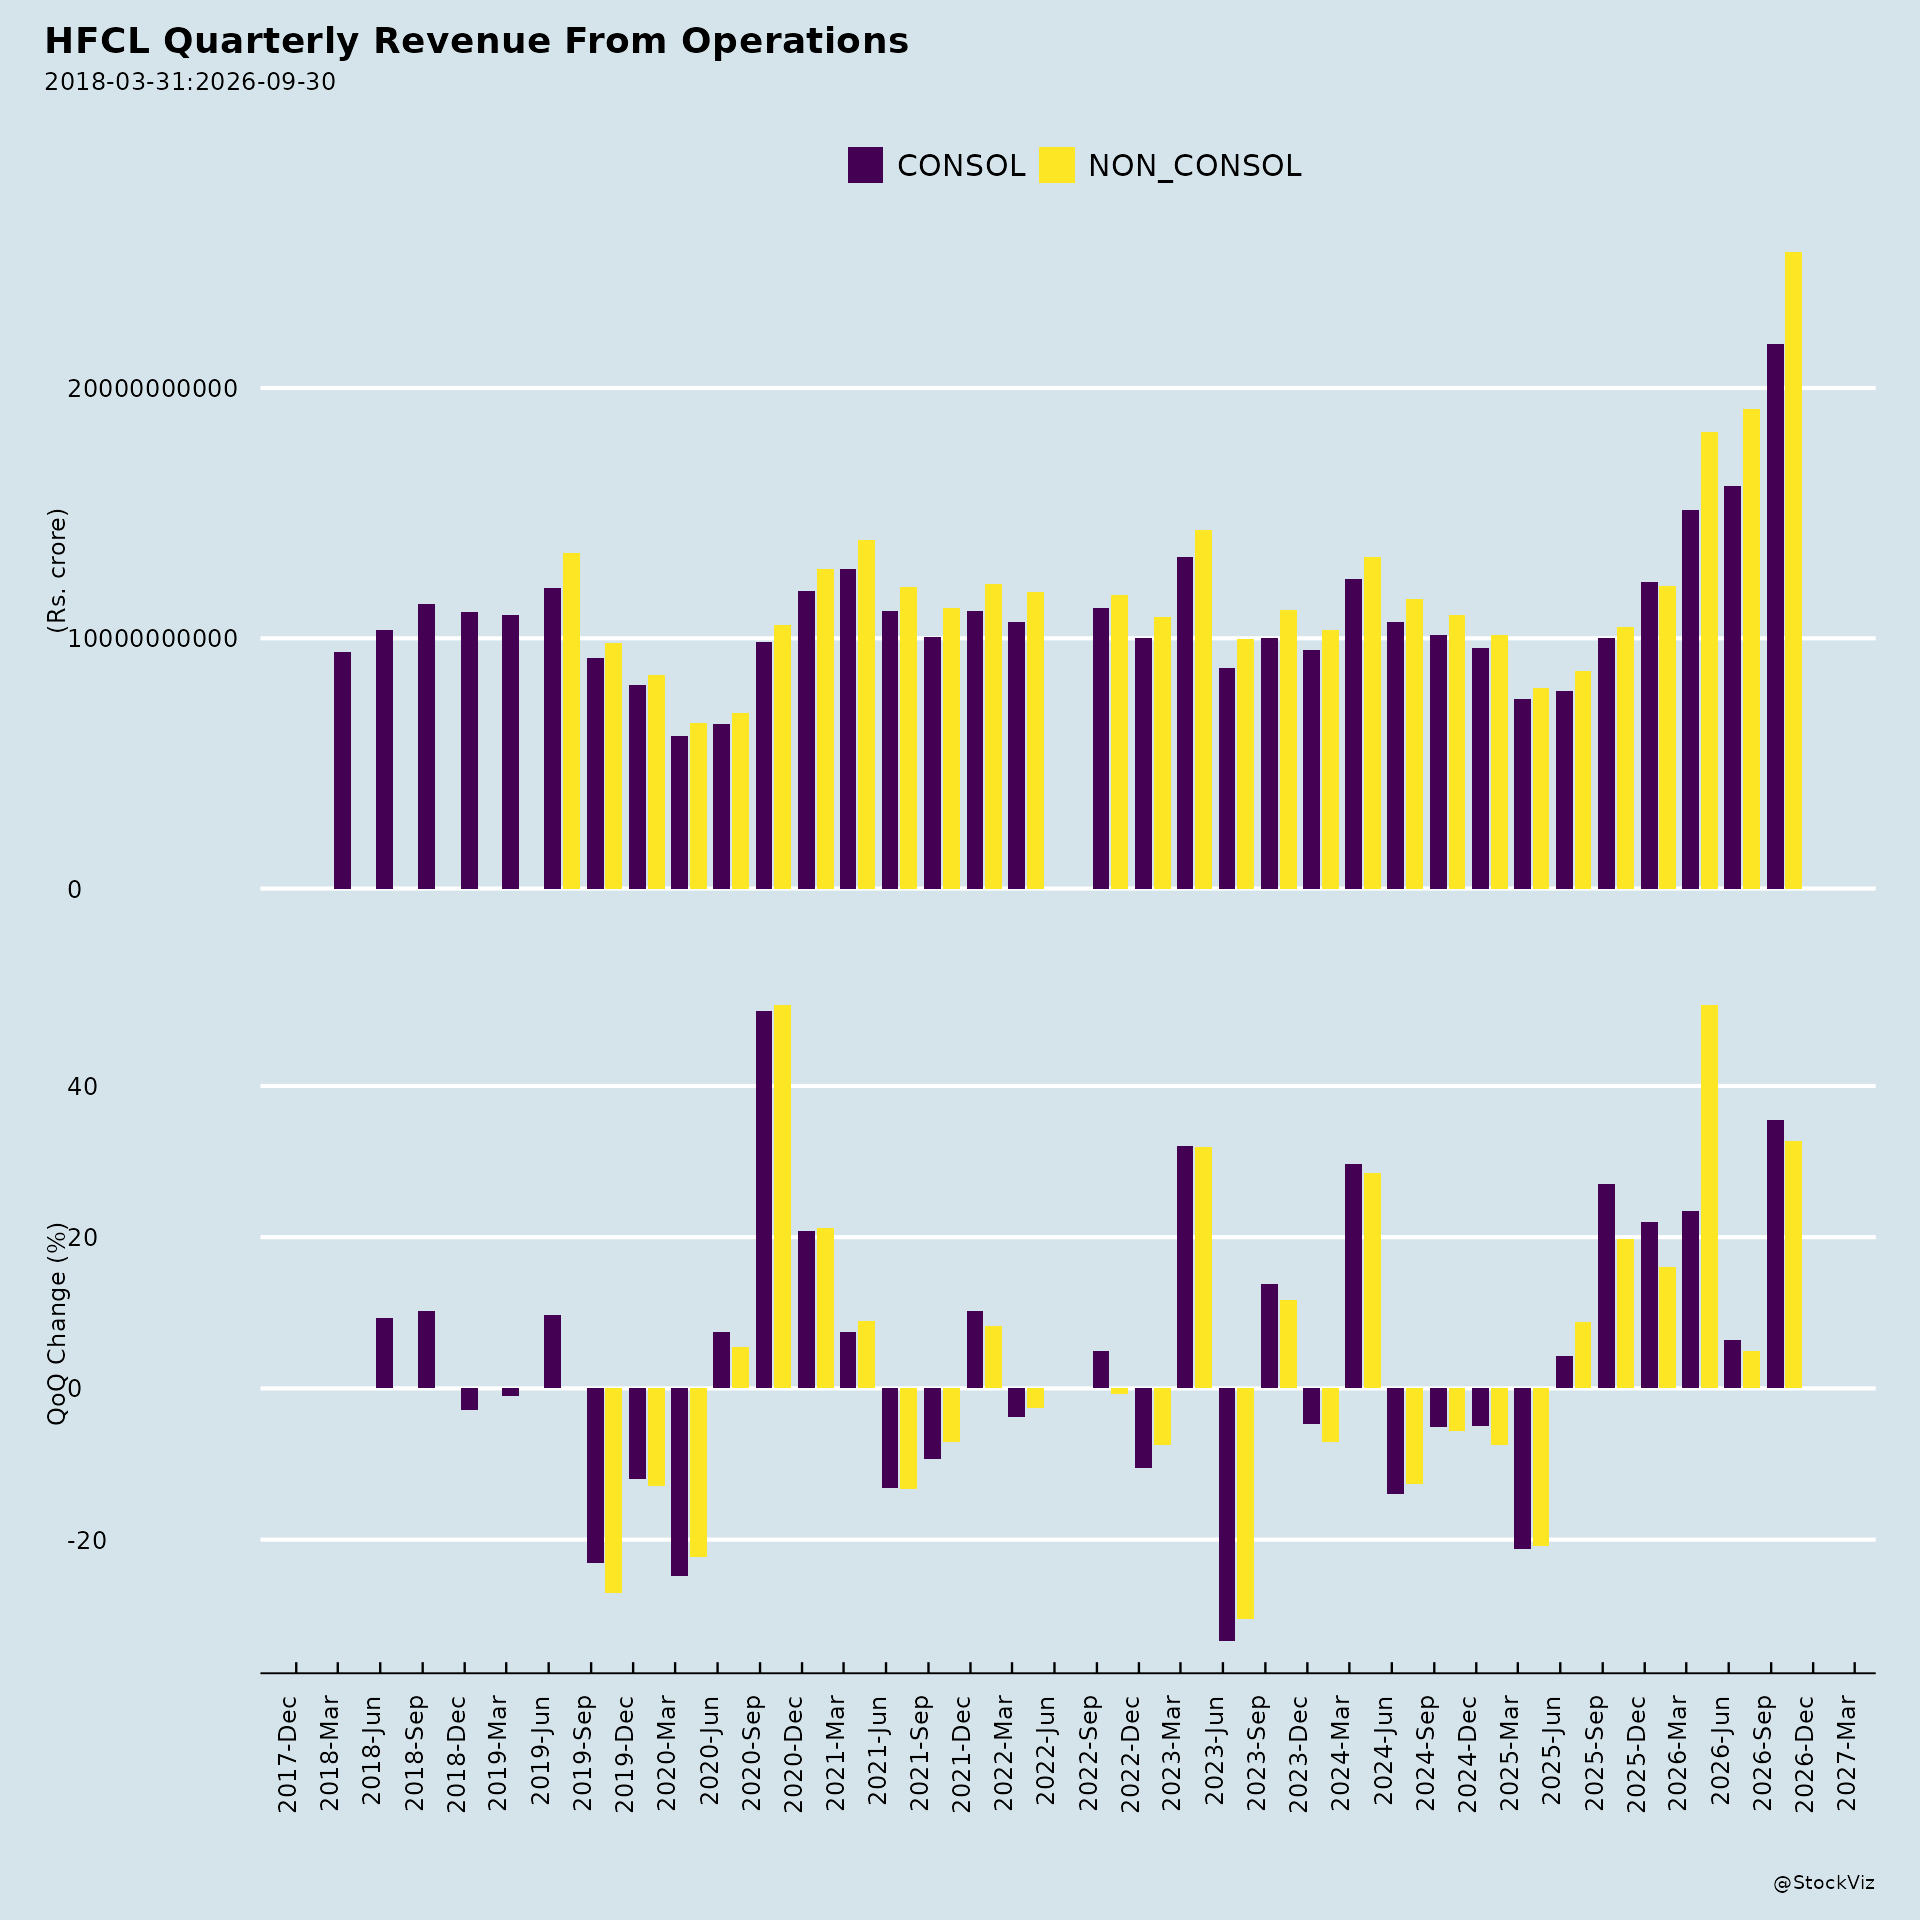
- Consolidated revenue from operations: ₹1,914.98 crore, up 119.85% year-on-year from ₹871.02 crore and up 4.98% quarter-on-quarter from ₹1,824.12 crore.
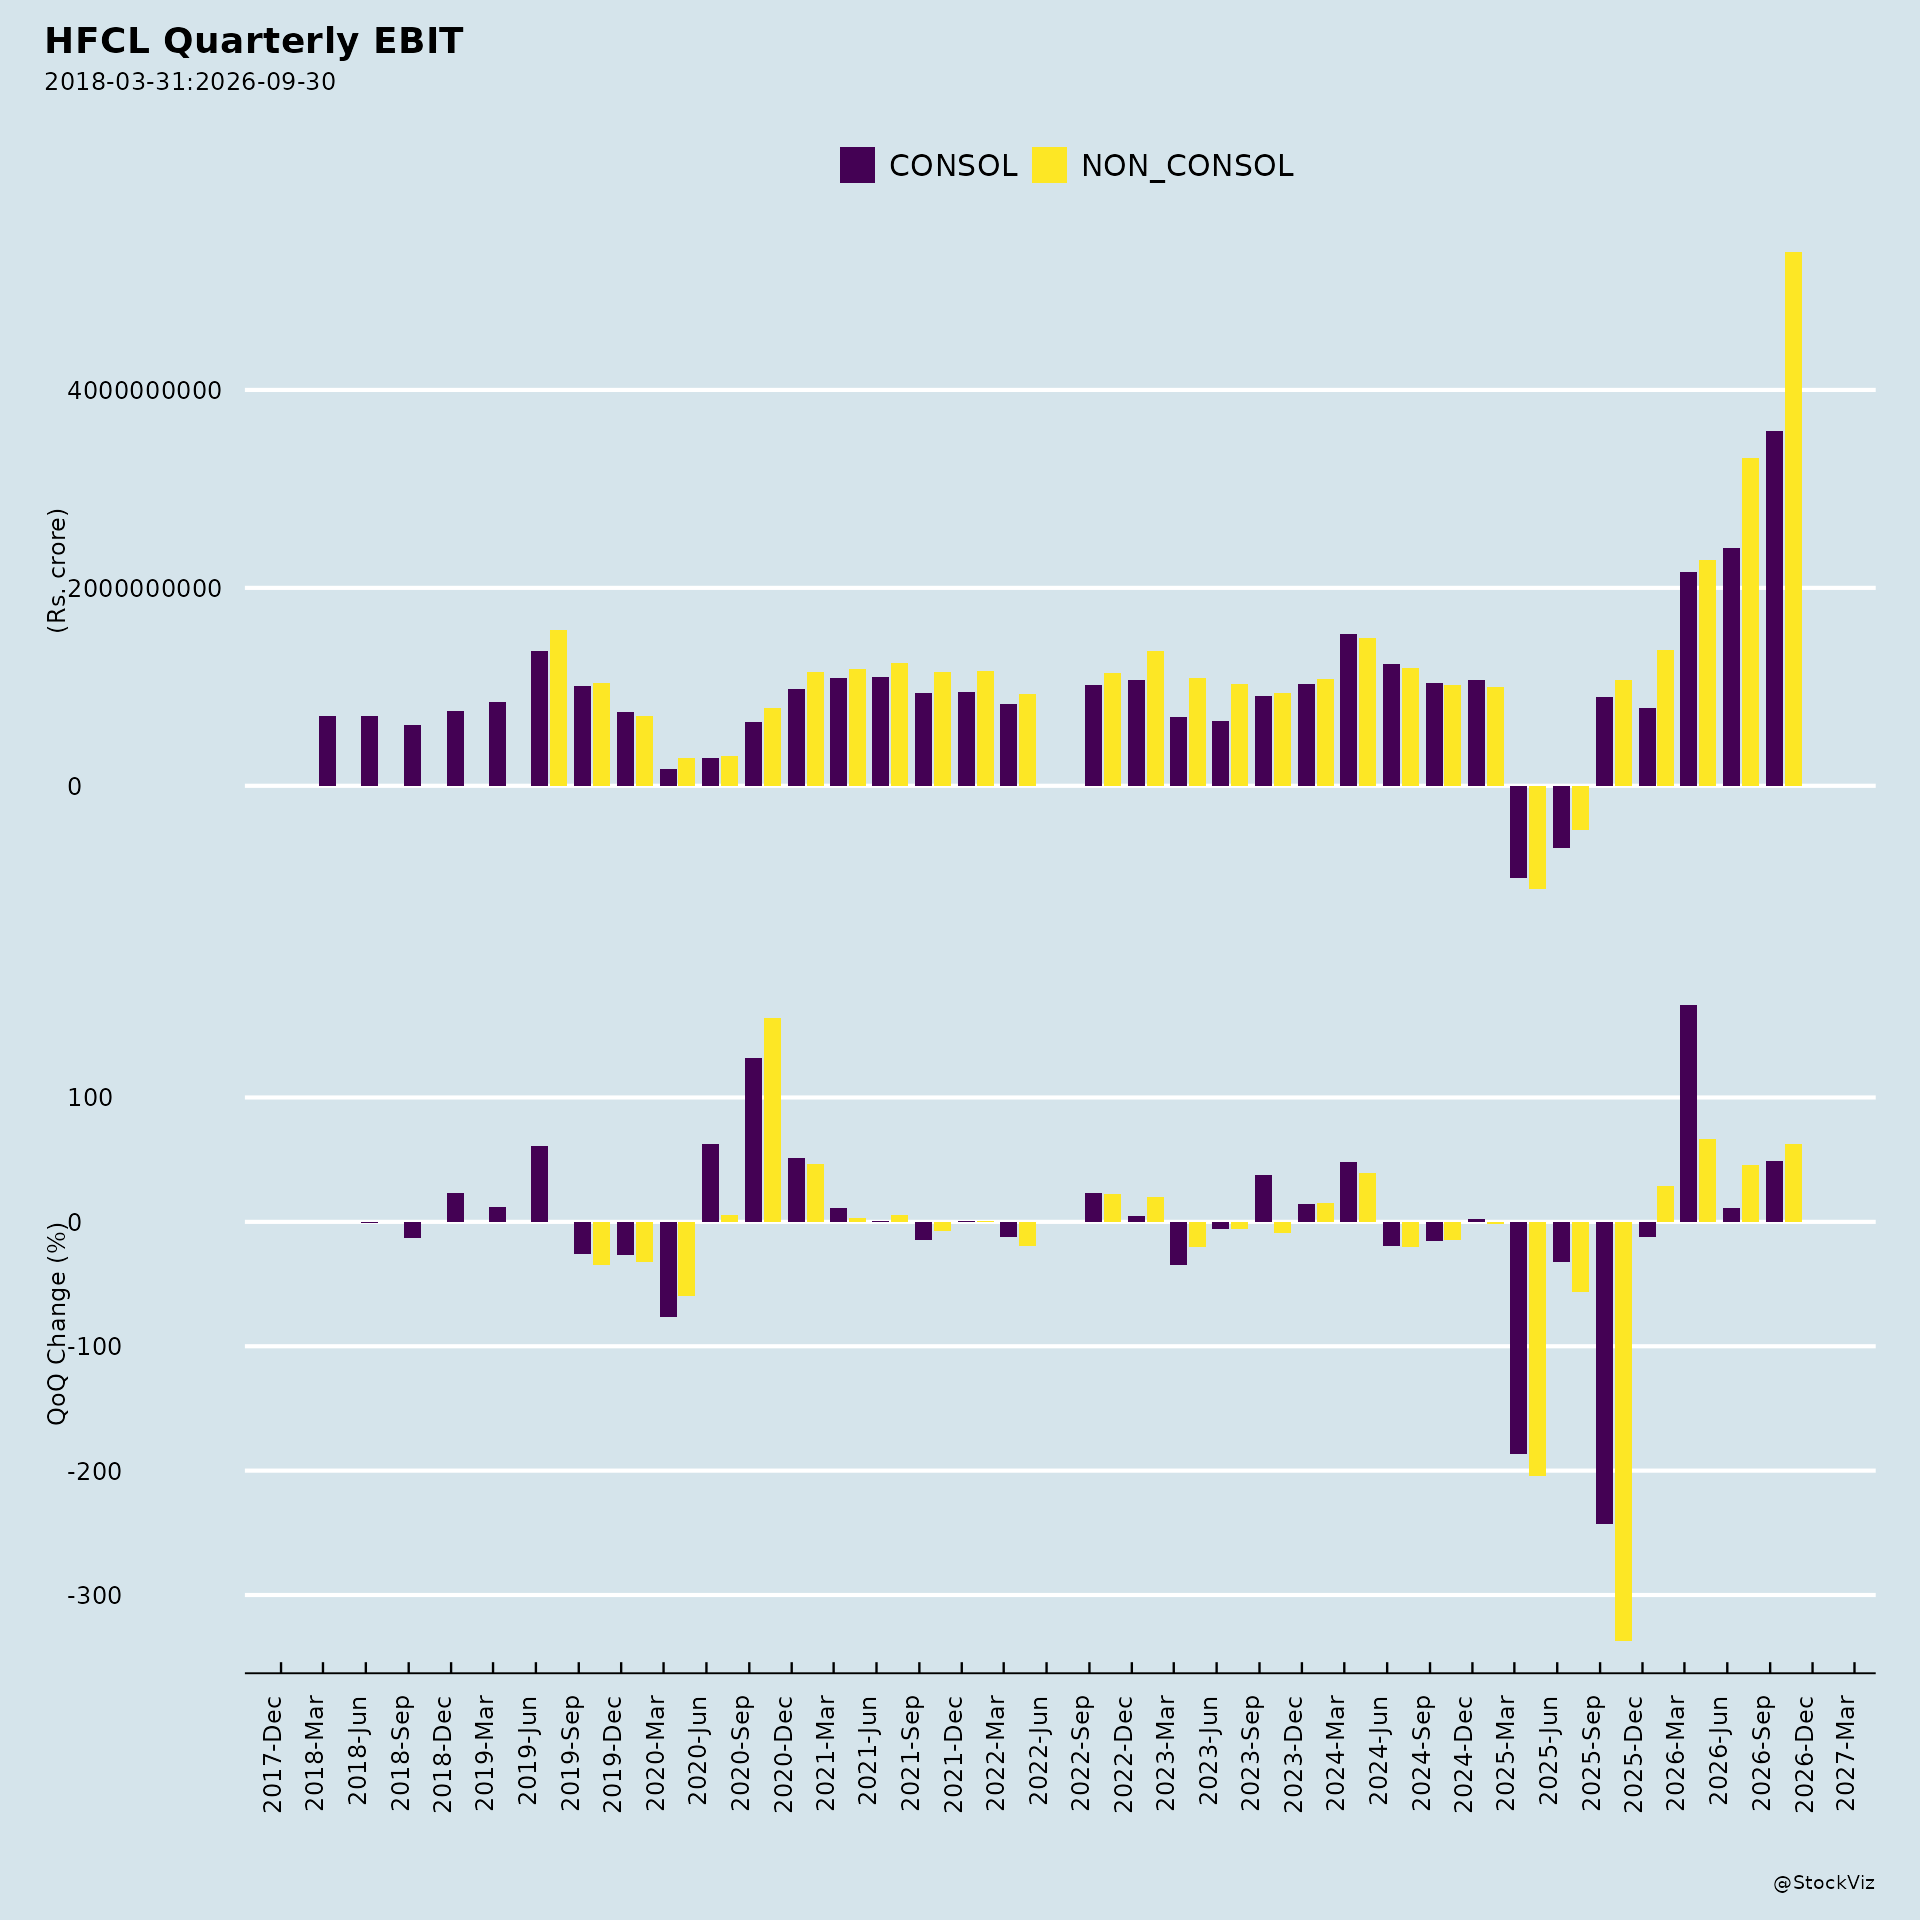
- Consolidated EBITDA: ₹445.27 crore, with EBITDA margin of 23.25% — above the “over 23%” FY27 aspiration in the first quarter itself.
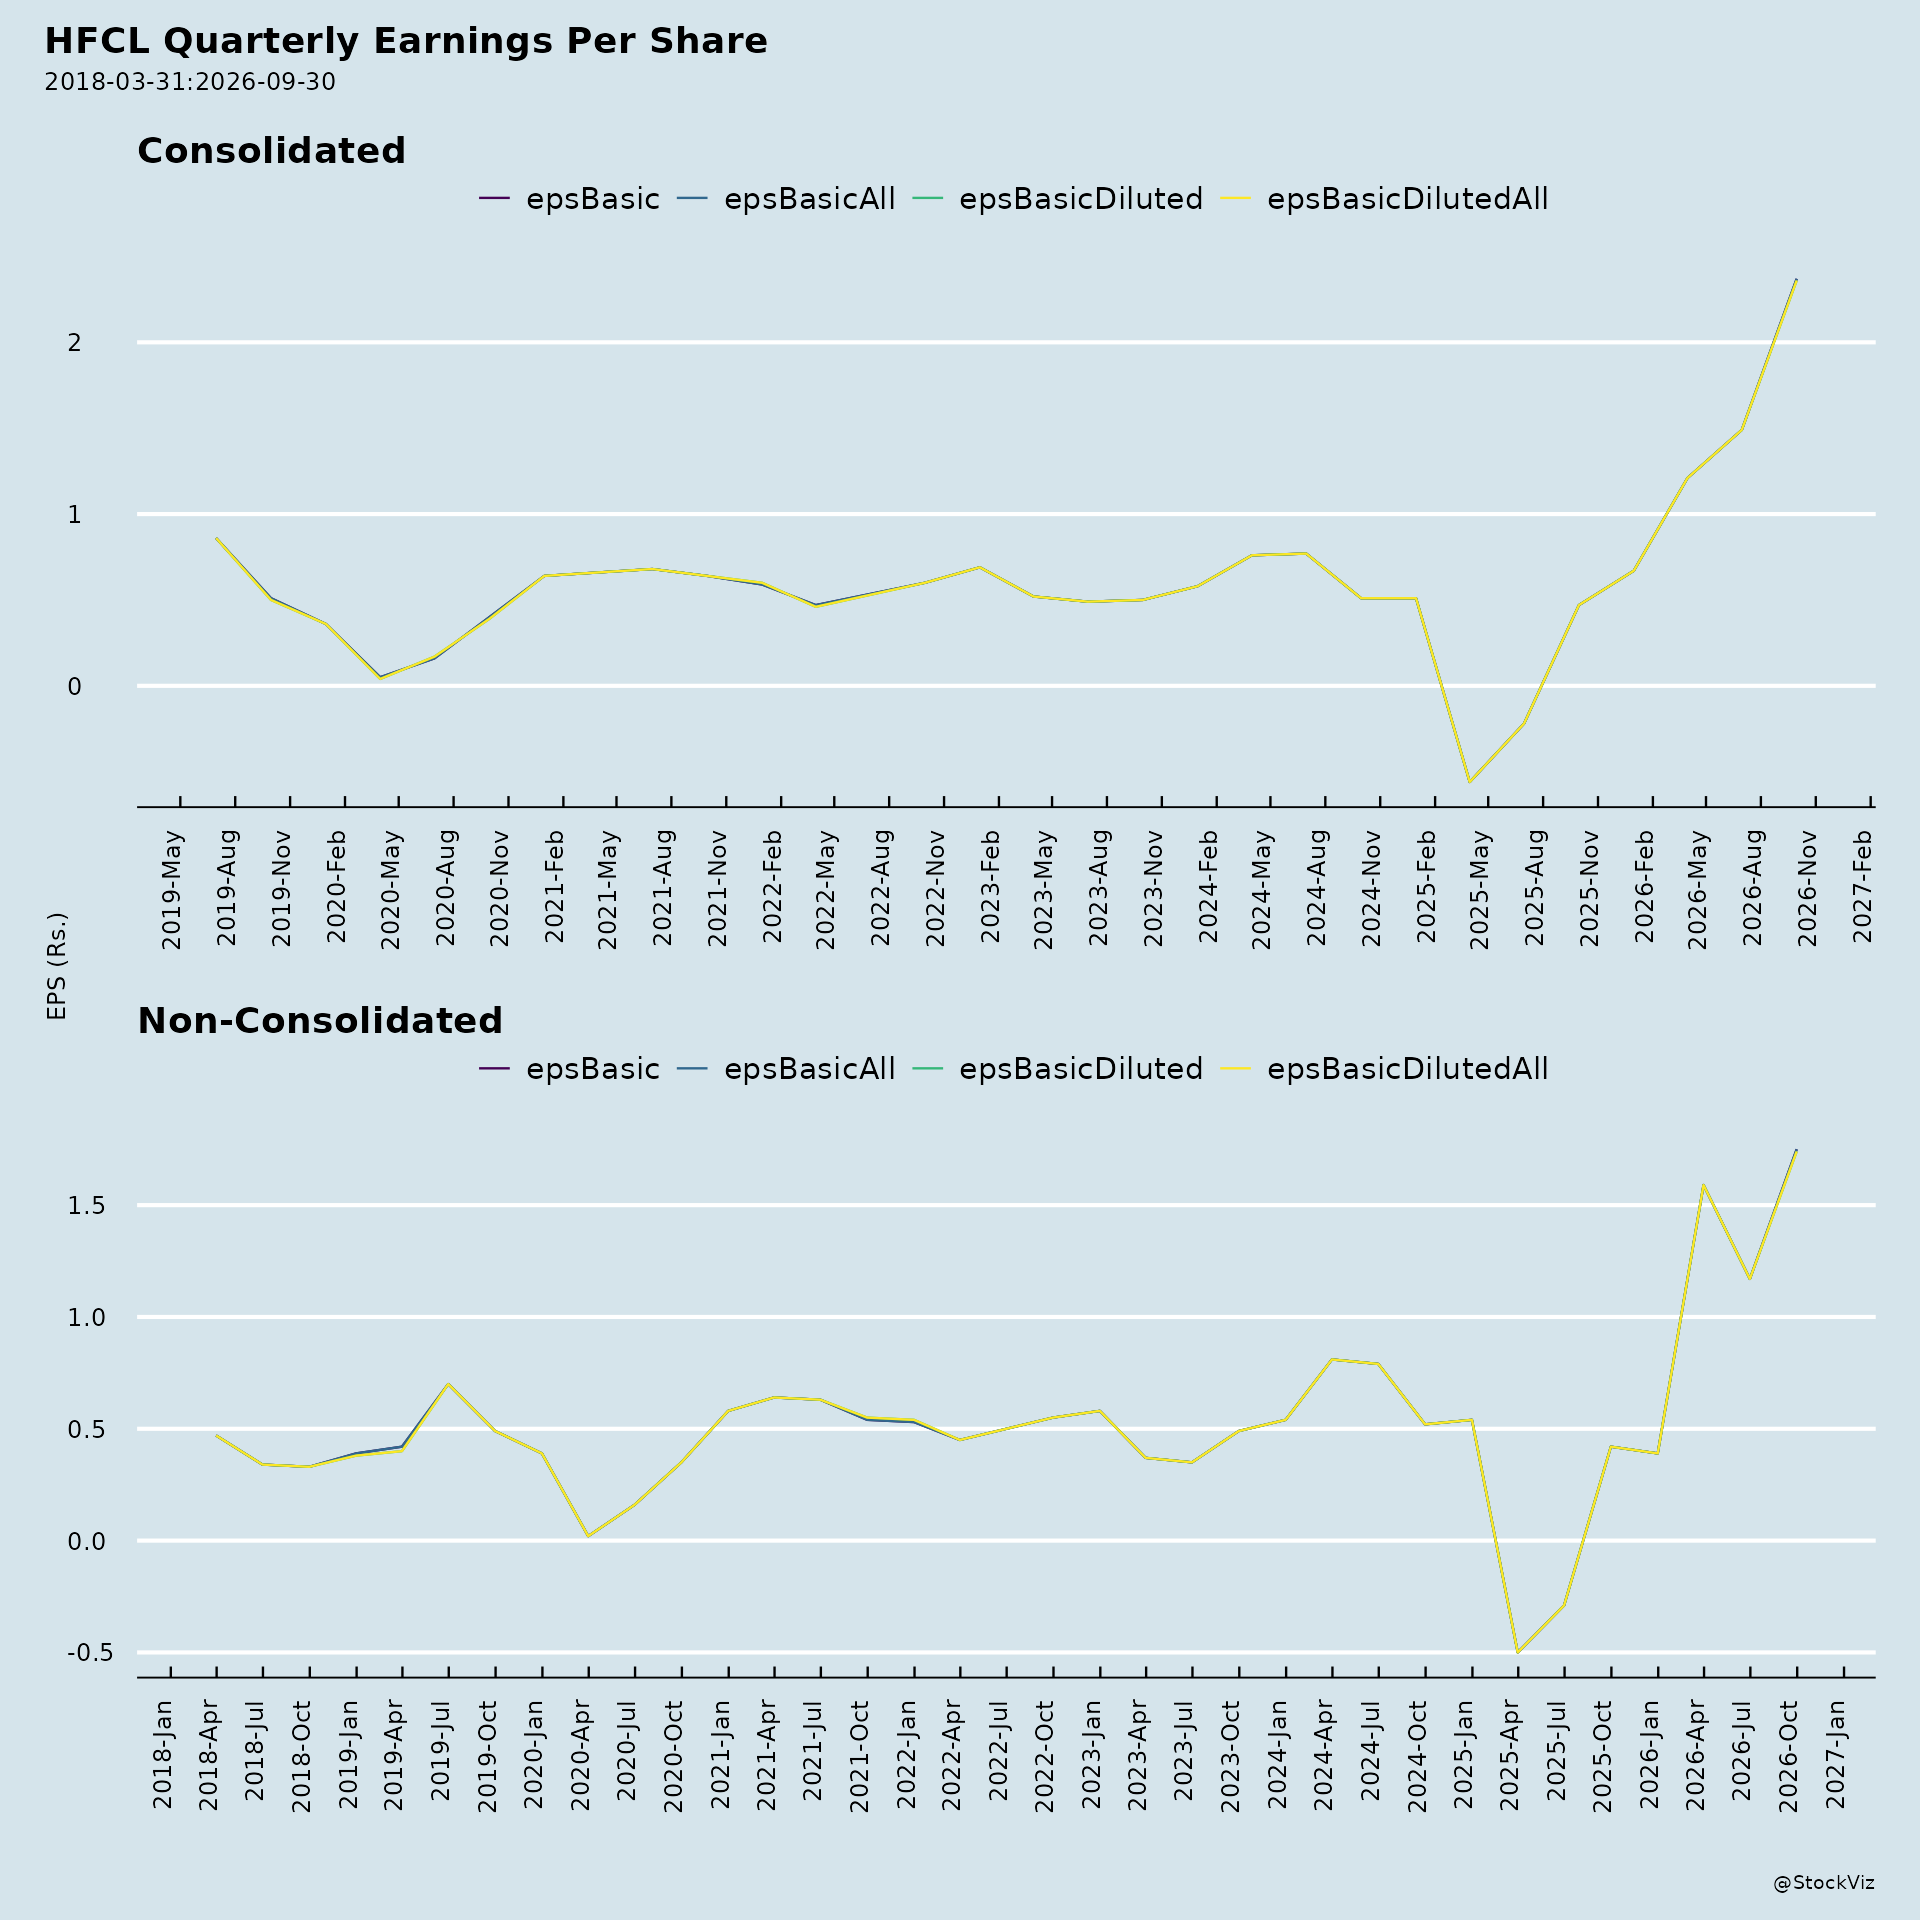
- Consolidated PBT: ₹331.52 crore (17.31% margin); PAT: ₹245.64 crore (12.83% margin); diluted EPS ₹1.49.
- Standalone revenue from operations: ₹1,607.80 crore; standalone PAT ₹179.21 crore.
- FY26 (audited, per the annual disclosure): revenue from operations ₹4,949.27 crore, EBITDA ₹826.75 crore, PAT ₹329.44 crore.
- Segment mix in Q1FY27 (consolidated): Telecom Products ₹1,589.53 crore; Turnkey Contracts and Services ₹280.32 crore; Defence Product & Services ₹23.74 crore; Others ₹21.39 crore.
- Order book progression: from over ₹21,200 crore to ₹26,665 crore as of June 30, 2026.
- Fund-raising: QIP of ~₹550 crore completed in the previous year, with ₹36.28 crore of proceeds remaining (₹35.92 crore in fixed deposits and ₹0.36 crore in the monitoring account); warrants convertible into 7,50,00,000 equity shares at ₹74 per share to a promoter and promoter group member, with 25% (~₹138.75 crore) received on May 25, 2026, of which ₹48.75 crore utilized and ₹90 crore held in fixed deposits.
- Share information as of June 30, 2026: market cap ₹32,563.57 crore; free float 71.69%; shares outstanding 1,53,06,02,463.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.