HEROMOTOCO
Equity Metrics
October 23, 2026
Hero MotoCorp Limited
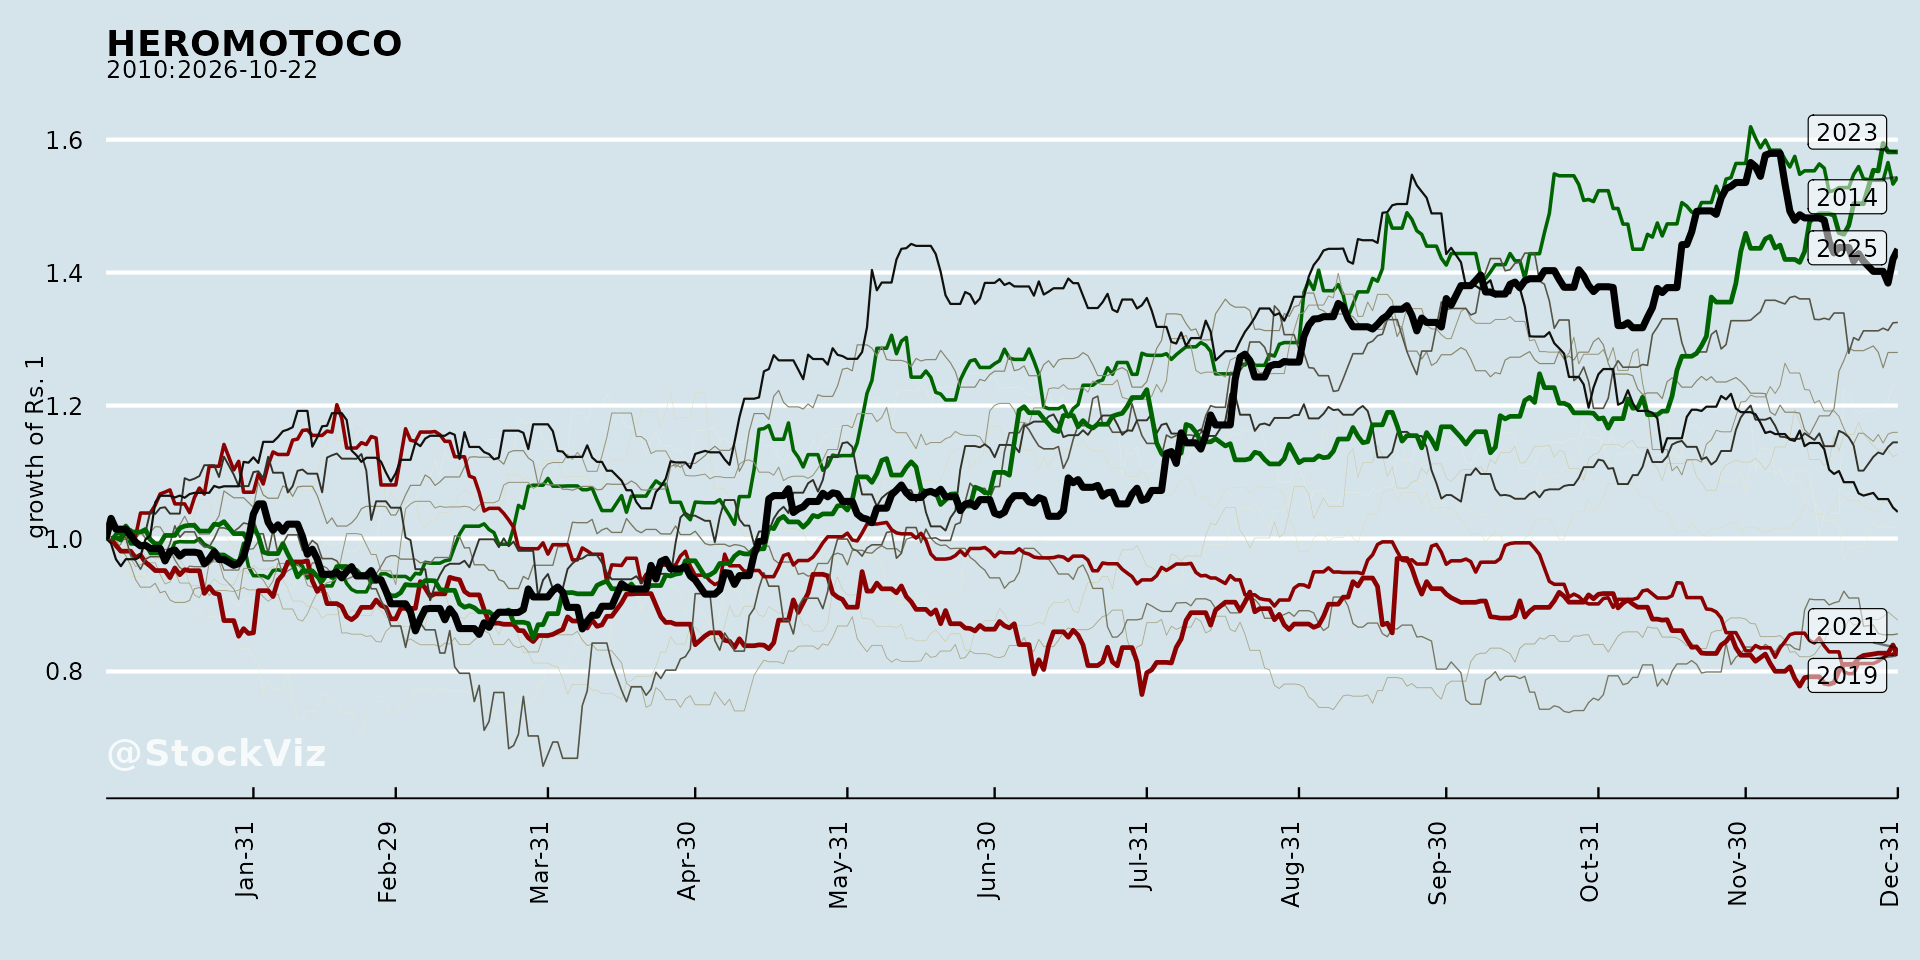
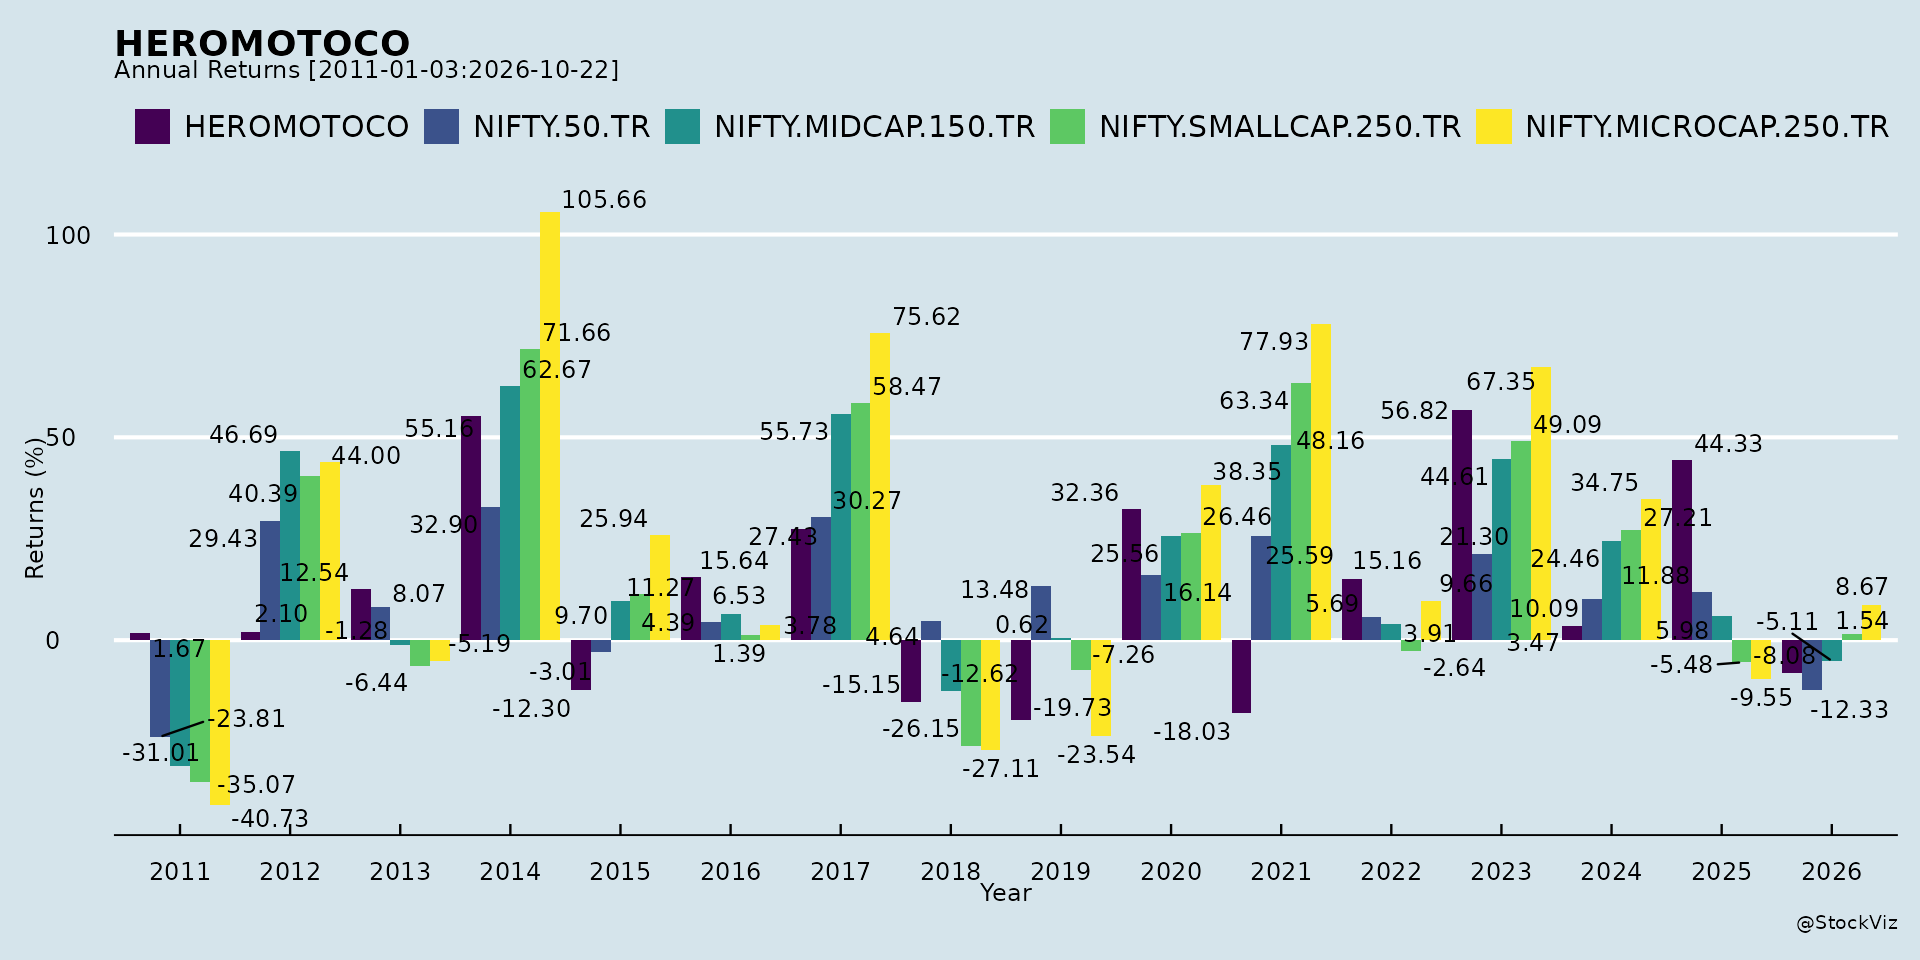
Annual Returns
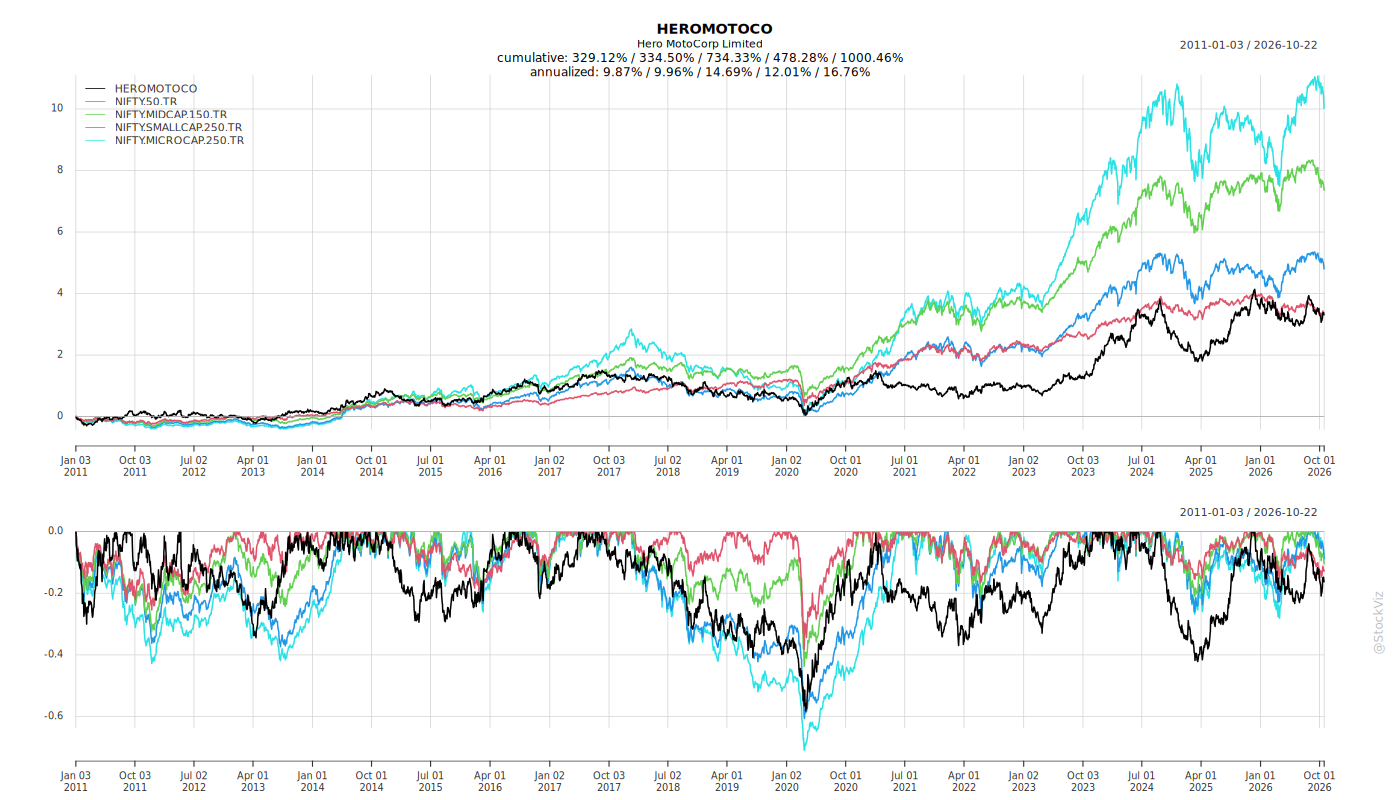
Cumulative Returns and Drawdowns
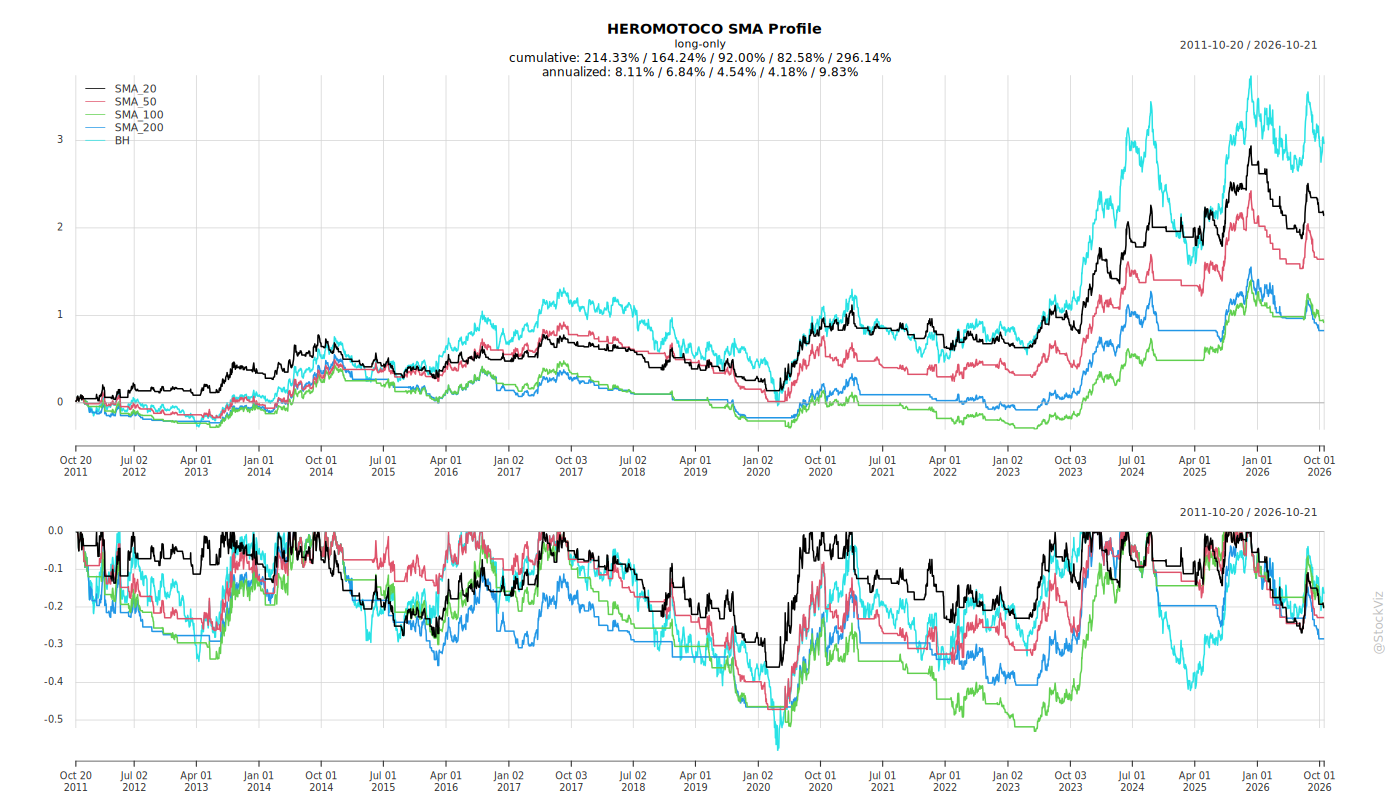
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Hero MotoCorp — Recent Corporate Announcements
1. Headwinds and Challenges
- Commodity cost pressure: Q1 FY27 EBITDA margin stood at 13.3%, impacted by commodity headwinds, partially offset by cost savings and operating leverage.
- Statutory lien on bank accounts: An order from the Employees’ State Insurance Corporation, Gurugram, Haryana, marked a lien of approximately ₹4.80 crore on bank accounts over alleged failure to settle outstanding arrears of approximately ₹3.19 crore under certificates dated November 12, 2018. The orders were received on September 7, 2026. The amount under the order stands paid, and the Company has filed an appeal with court(s)/appellate authorities.
- Dividend disbursement friction: The final dividend for FY 2025-26 has been withheld for shareholders with incomplete or incorrect bank details or non-submitted KYC details against physical holdings. Following SEBI regulations effective November 19, 2025, dividend payments must be remitted compulsorily through electronic mode, and payable-at-par warrants or cheques have been discontinued.
- Elevated fuel prices: In the core motorcycle segment, customer focus on mileage has sharpened amid elevated fuel prices, shaping demand dynamics in the 100cc portfolio.
- Motorcycle dispatch softness in August 2026: Motorcycle dispatches for August 2026 were 493,851 units, compared to 501,523 units in August 2025, even as total dispatches rose.
2. Tailwinds and Growth Prospects
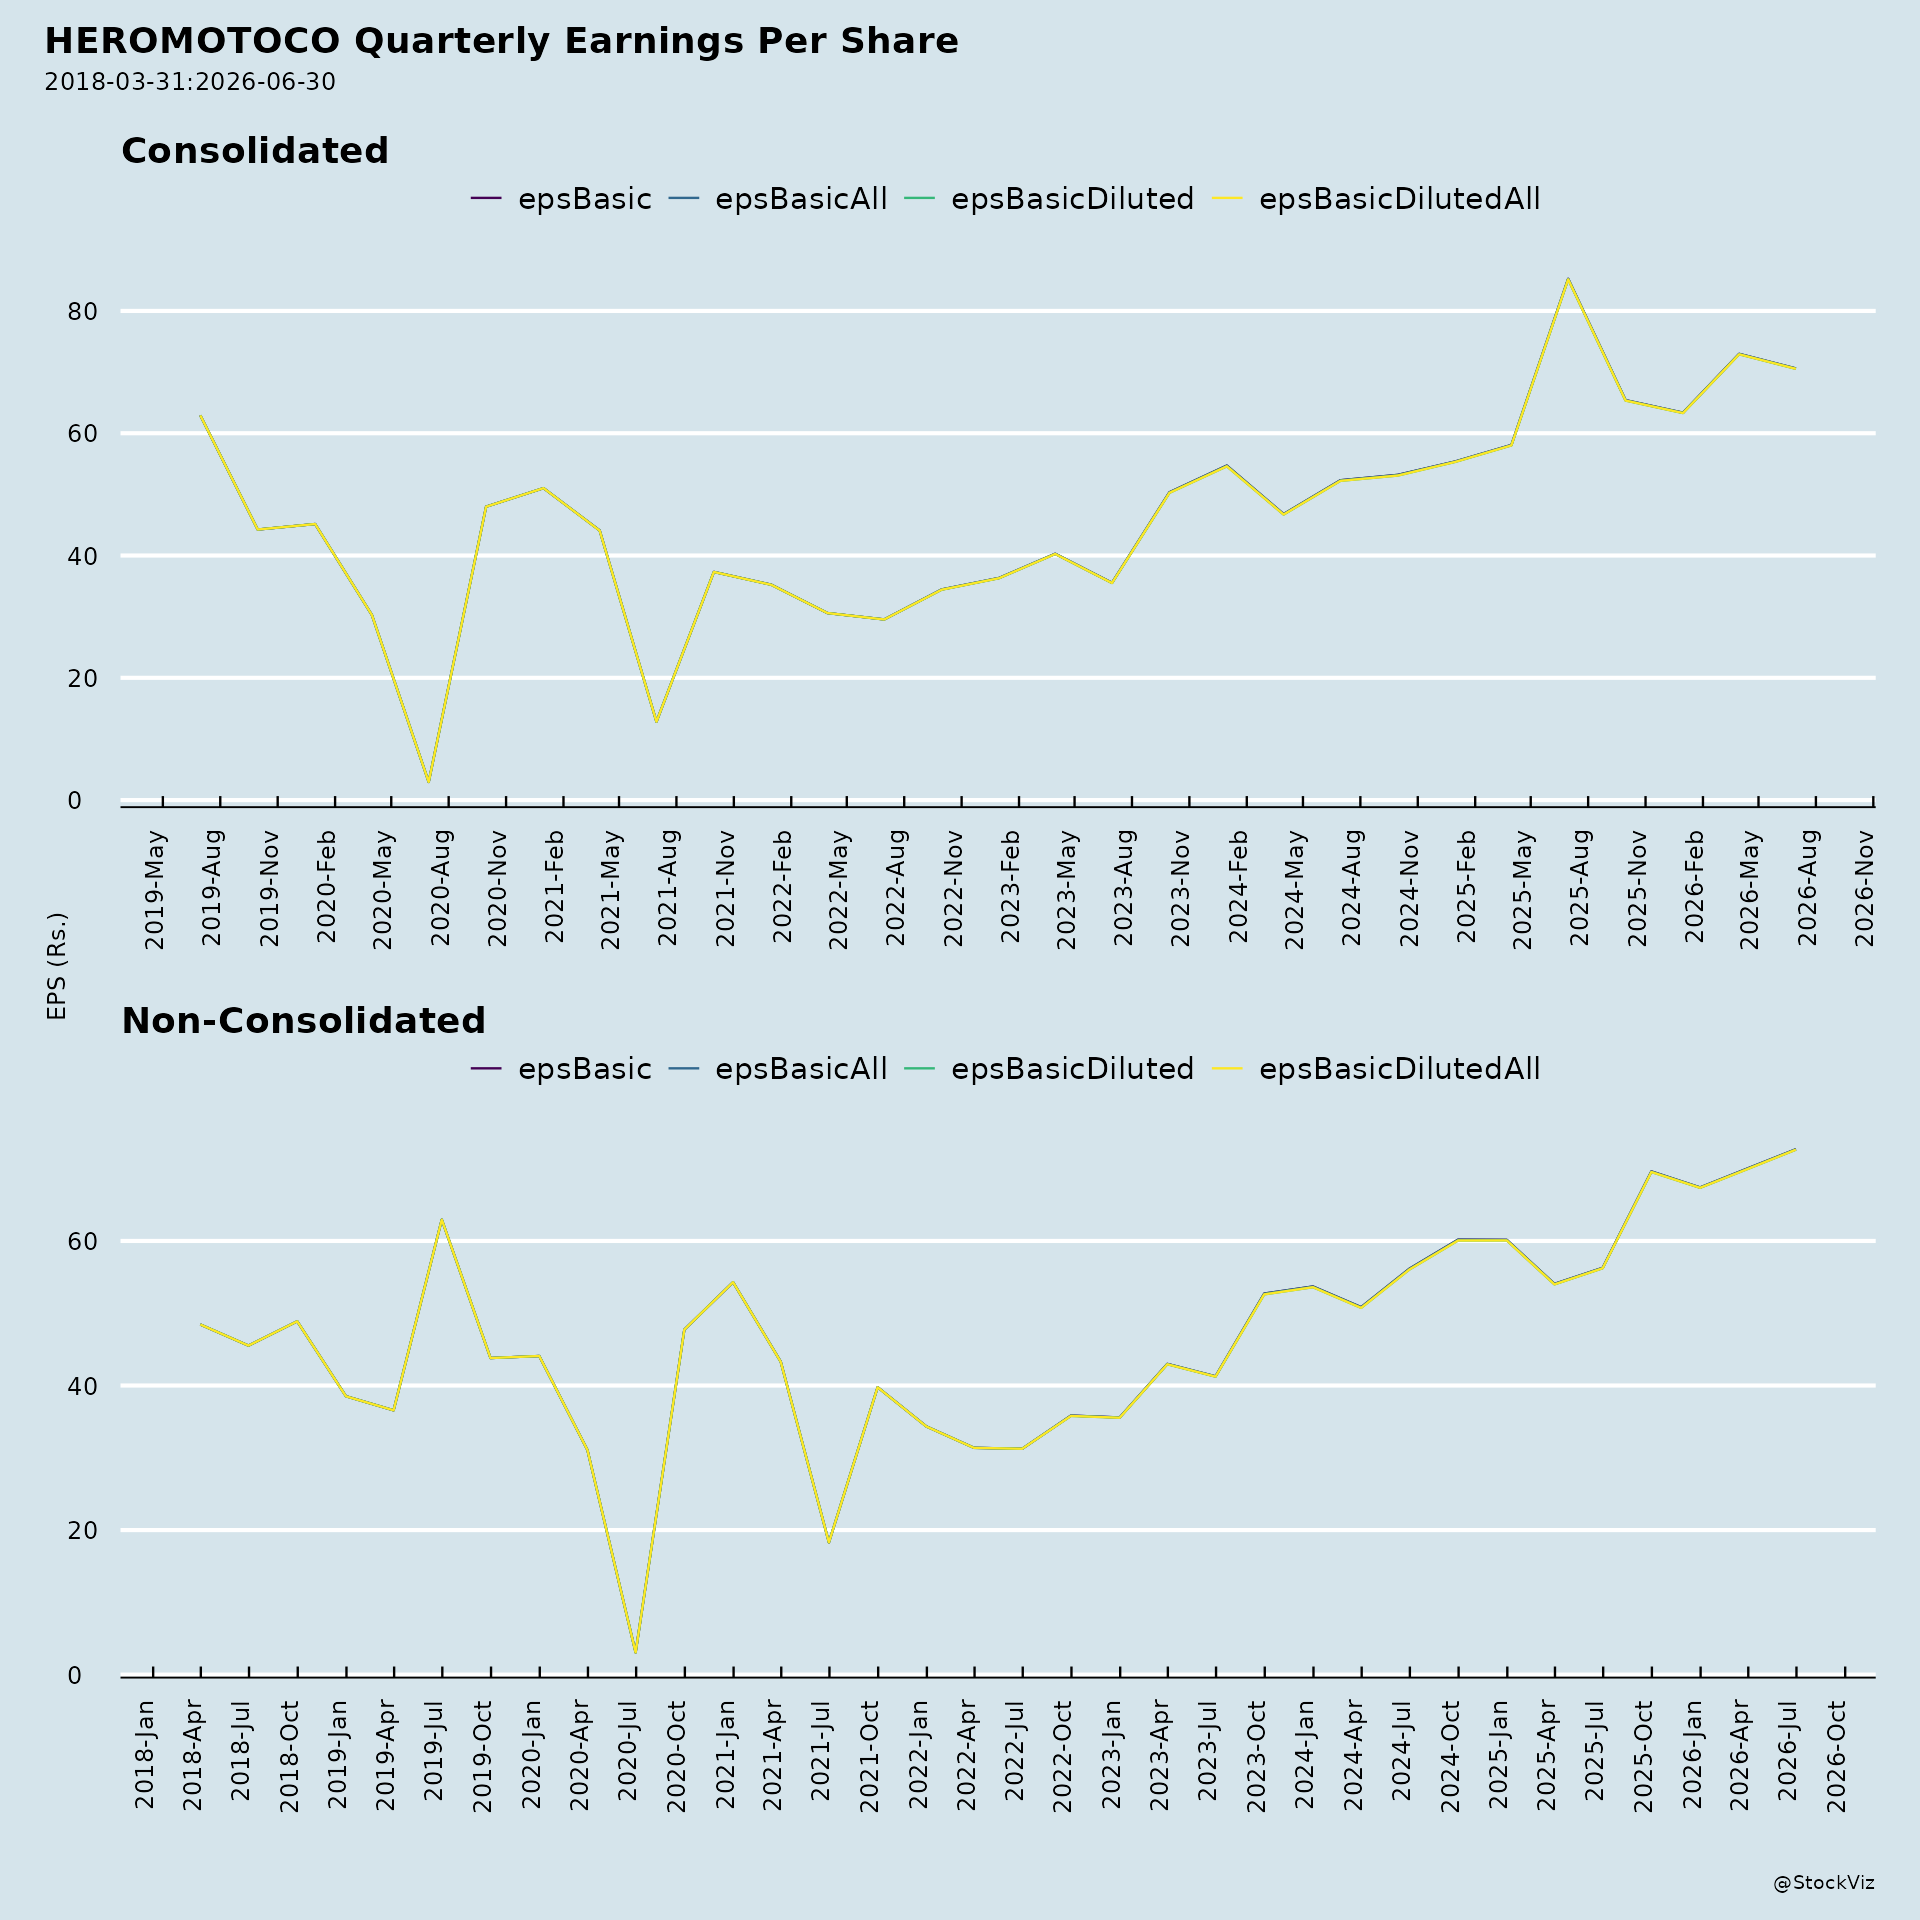
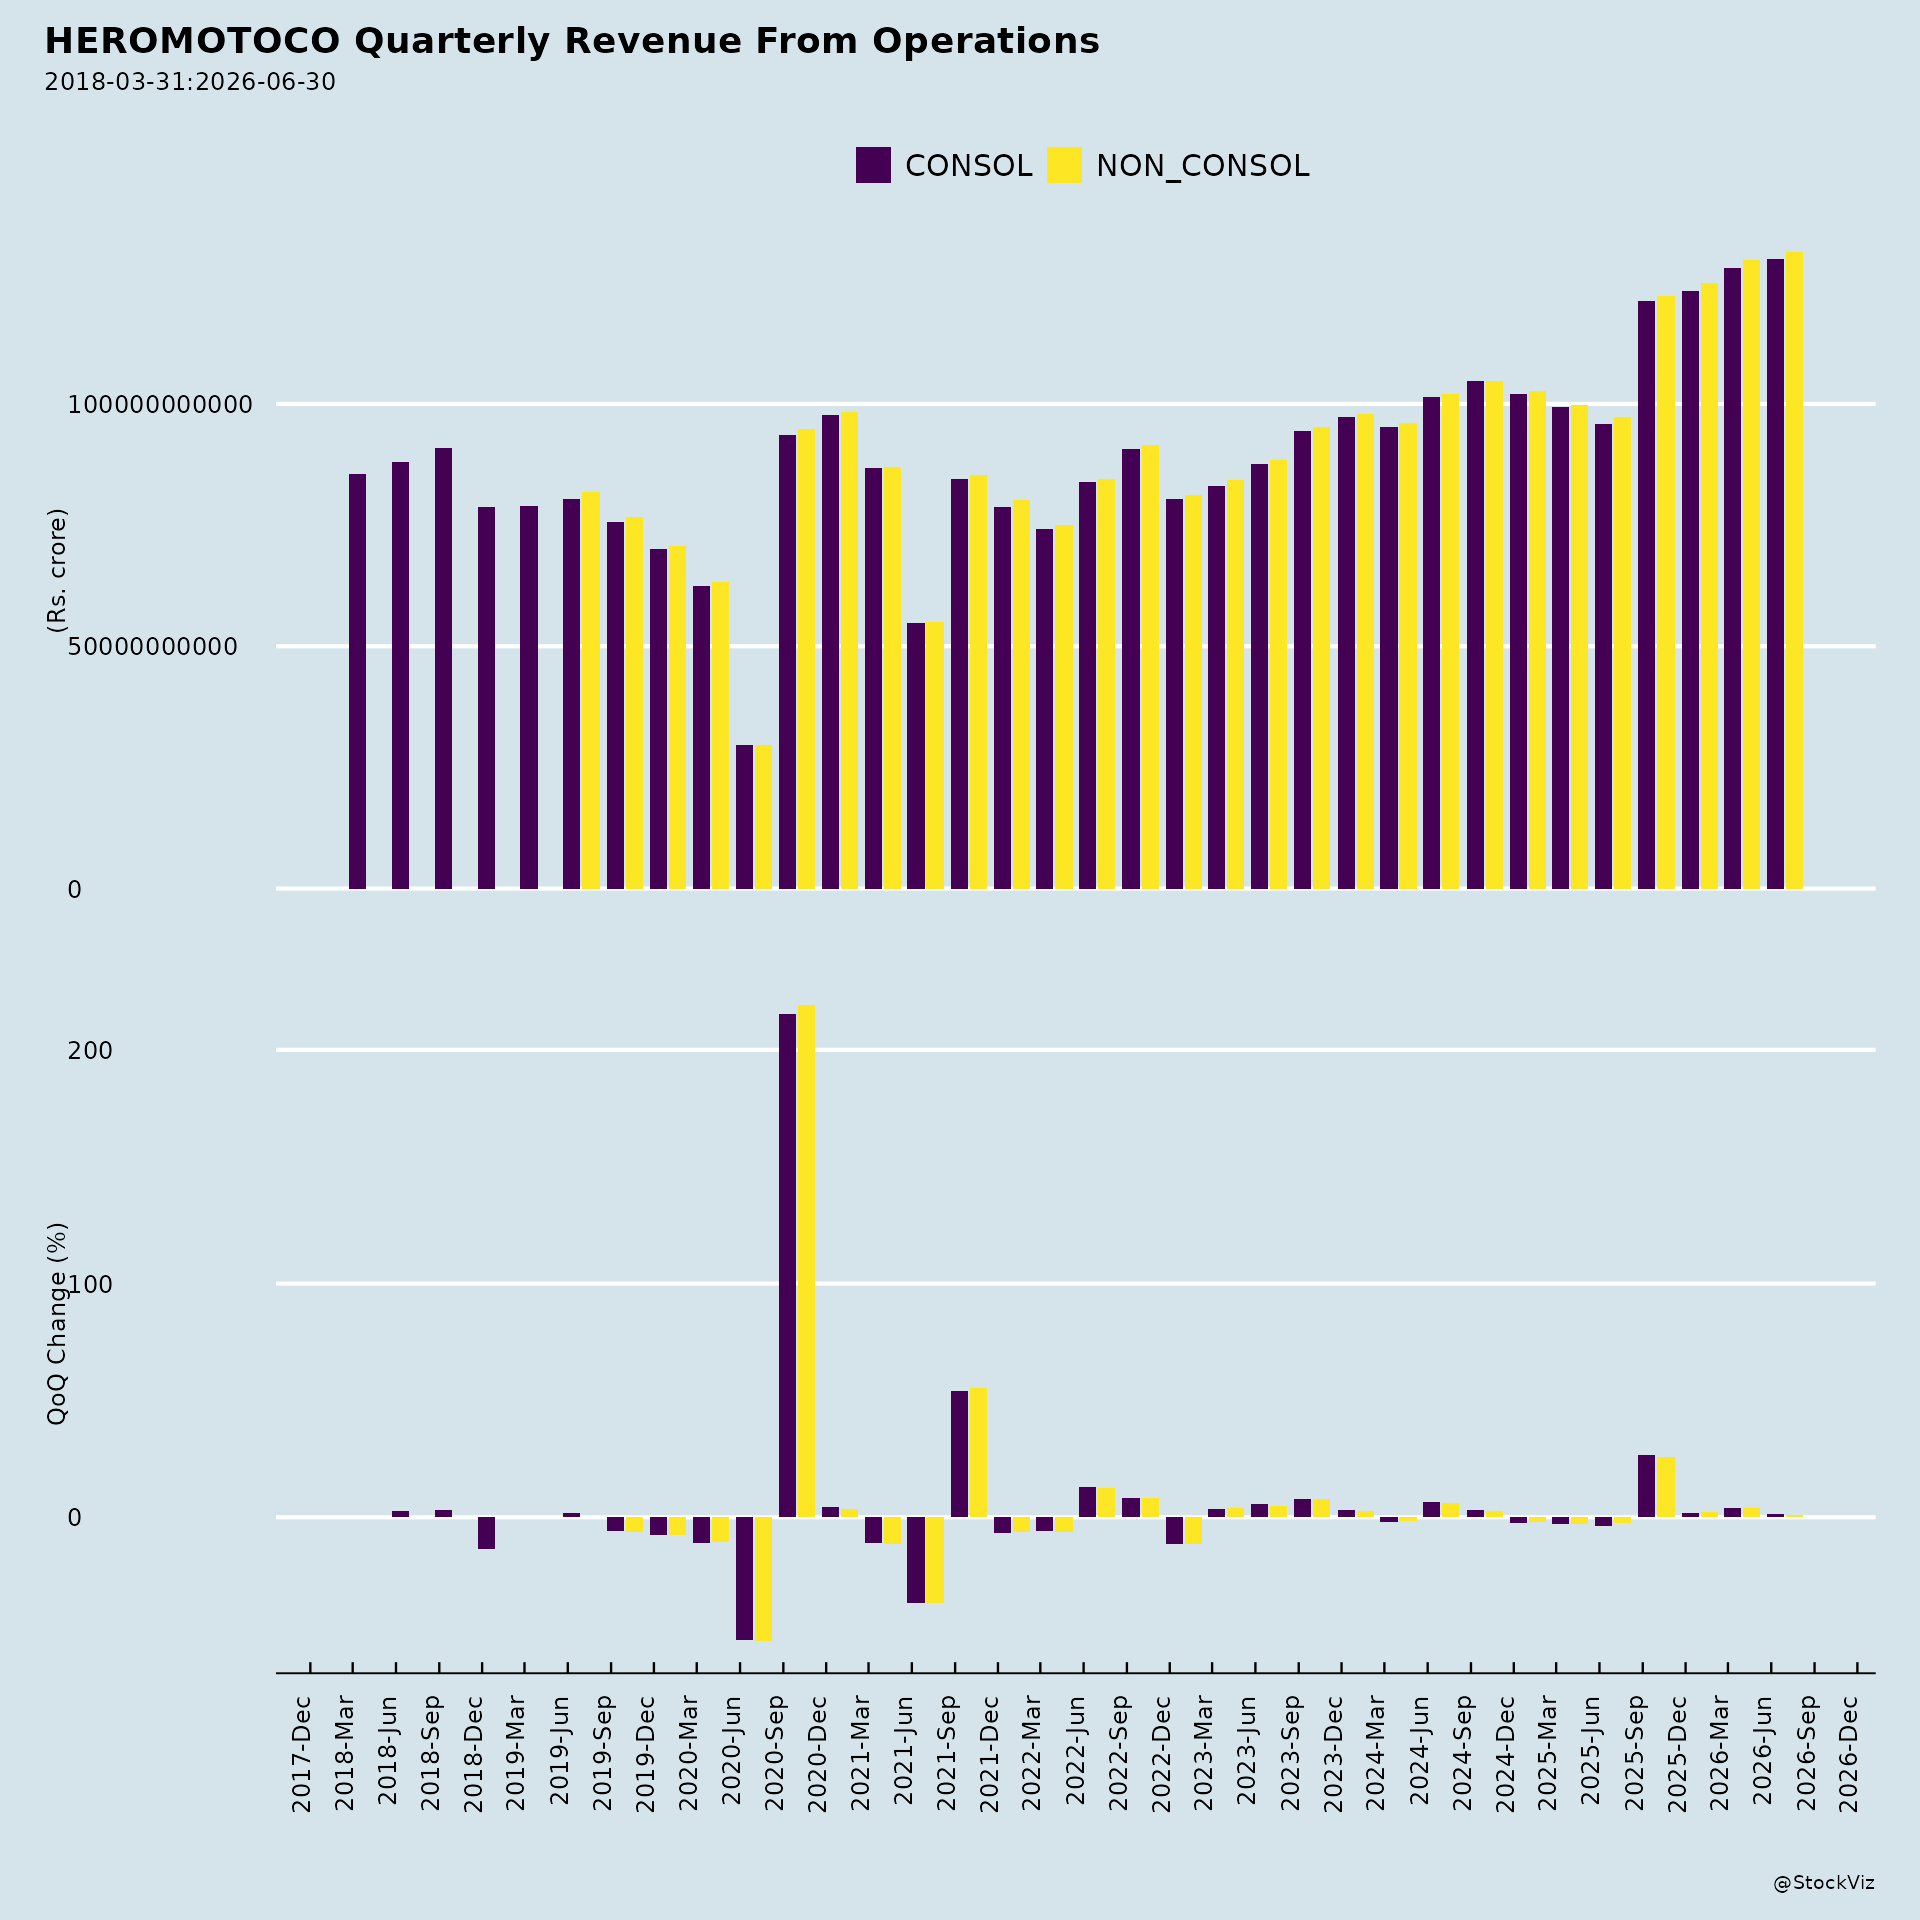
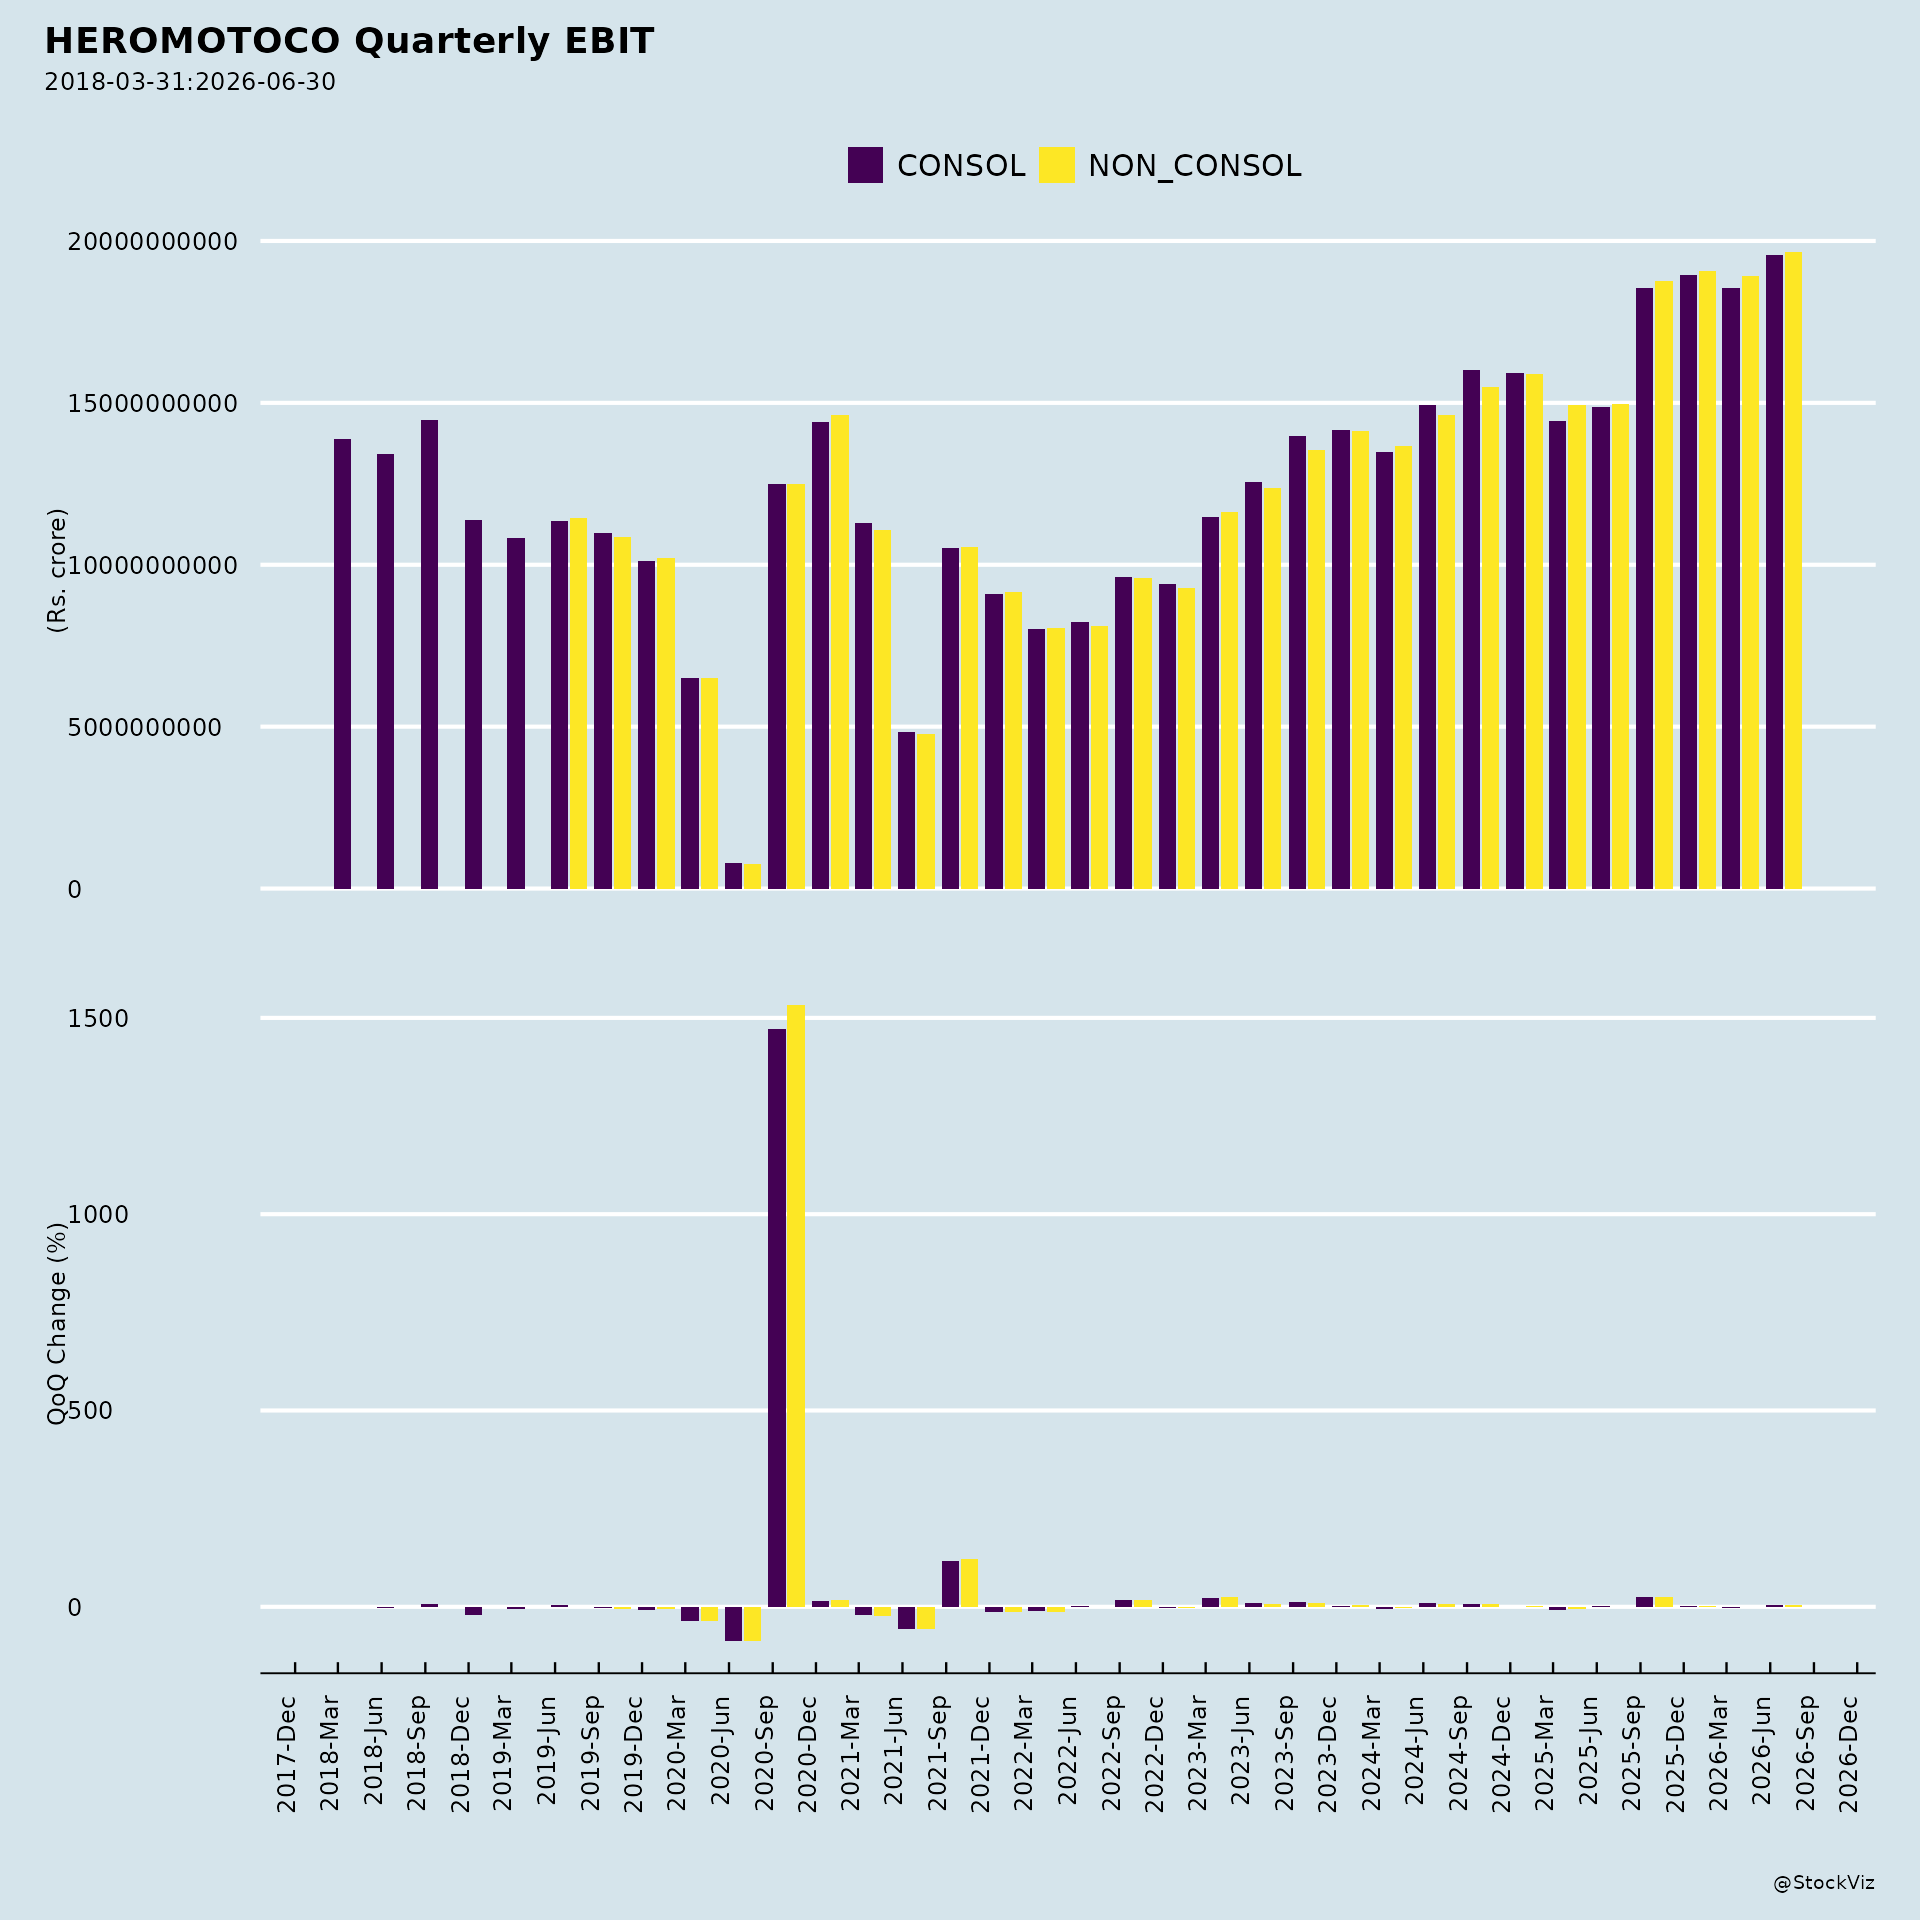
- Broad-based Q1 FY27 growth: Revenue from operations rose 36% to ₹12,999 crore, driven by 23% volume growth, mix improvement and pricing benefit. EBITDA grew 25% to ₹1,727 crore; PAT grew 29% to ₹1,454 crore. Consolidated revenue was ₹13,126 crore, up 35%.
- Segment momentum: Total dispatches rose 17% to 1,484 thousand units. Scooter dispatches (ICE + EV) more than doubled to 193,058 units. Global business dispatches grew 63%. Harley-Davidson business grew 105% year-on-year, with the retail network expanded to 21 full-line dealerships.
- EV leadership: VIDA recorded 151% year-on-year growth, with VIDA Vahan retails of 57,058 units and market share of 10.9%. The first leg of capacity ramp-up is done, with capacity to be doubled by December 2026. VIDA entered Nepal, marking its global debut, and launched the DIRT.E K3 electric off-road motorcycle. Production Linked Incentive of ₹48 crore was recorded in Q1 FY27, with 60% of the portfolio eligible and 100% targeted by December 2026.
- Market share gains: Domestic ICE market share at 29.0% (+0.3% YoY); 100cc motorcycle market share at 85.8% (from 83.5%); Deluxe 125cc market share at 17.8% (from 12.8%); ICE scooter market share at 6.9% (from 4.6%); global business market share at 6.8% (from 5.7%).
- Premium and scooter expansion: Premia network reached 132 outlets as of June 2026, with new outlets in Tamil Nadu and Assam. Capacity expansion plans include doubling Destini capacity, expanding Xoom capacity, a greenfield premium line at Neemrana, and a Global Parts Centre 2.0 at Tirupati (foundation stone laid July 1, 2026, to be commissioned by end of 2027).
- Parts, Accessories & Merchandise: PAM revenue grew 30% to ₹1,689 crore, with network expansion to taluka level and scaling of premium riding gear.
- Flex-fuel innovation: Flex-fuel variants of Splendor+ and HF Deluxe were launched, compatible with ethanol-blended fuels from E20 to E85, with strong customer response.
- August 2026 retail momentum: VAHAN growth of 19% year-on-year; VIDA dispatched 25,558 units with 38% VAHAN growth; domestic ICE business recorded 516,747 units with 18% VAHAN retail growth; global business recorded 26,093 units. YTD FY27 total dispatches stand at 2,779,127 units versus 2,370,552 units for YTD FY26.
- FY26 baseline: Highest-ever revenue from operations of ₹46,830 crore, EBITDA of ₹6,871 crore, PAT of ₹5,268 crore, ROCE exceeding 31%, and sales of approximately 6.47 million motorcycles and scooters. VIDA grew 190% year-on-year and global business grew 40% year-on-year in FY26, with a footprint across 53 countries.
- Strategic investments and partnerships: Increased strategic investments in Ather Energy and Euler Motors; collaboration with Zero Motorcycles; VIDA and NOVUS shaping the electric mobility ecosystem.
- Leadership strengthening: Appointments include Harshavardhan Chitale as CEO, Sachin Agrawal as CTO (effective May 21, 2026), Kausalya Nandakumar as CBO – Emerging Mobility, Madhuri Mehta as CHRO, Latika Taneja as Head – Communications, Corporate Affairs and CSR, and Anuj Dua as CBO – Premium Segment with a mandate to drive the next phase of growth in premium mobility.
- Sustainability and CSR: 50% green dealerships, 32% renewable energy consumption, 500% water positive facilities, 100% zero waste to landfill, 95% product recyclability, ranked number 1 in India’s two-wheeler industry on the Dow Jones Sustainability Index, and CSR initiatives touching over 528,000 lives in FY26 and over 214,802 lives in Q1 FY27.
3. Key Risks
- Commodity headwinds pressuring margins, as reflected in the 13.3% EBITDA margin for Q1 FY27.
- Statutory/regulatory exposure: The ESIC order and lien on bank accounts, though the Company believes the orders are unsustainable and unlikely to have a material impact on financials, operations, or other activities.
- Dividend payment compliance risk: Withholding of dividends for shareholders lacking valid bank or KYC details, with release contingent on updates made with the RTA (KFin Technologies Limited) or Depository Participant.
- Segment-specific demand sensitivity: Motorcycle dispatch decline in August 2026 despite overall growth, and mileage-focused customer behavior amid elevated fuel prices.
- Execution risk on capacity expansion: Multiple capacity expansion projects (Destini, Xoom, Neemrana premium line, Tirupati GPC 2.0, EV capacity) are in progress, with the Tirupati facility to be commissioned by end of 2027.
- Conference schedule uncertainty: The schedule of the Jefferies 5th India Forum investor conference is subject to change due to business exigencies or otherwise.
4. Management Guidance Versus Observed Business Performance
- Capacity expansion guidance: Management guided that EV capacity would be doubled by December 2026, with the first leg of capacity ramp-up already done. PLI eligibility is targeted at 100% of the portfolio by December 2026, against 60% in Q1 FY27.
- Festive season outlook: Management stated that continued retail momentum augurs well for the festive season, supported by a more flexible supply chain ecosystem with the ability to respond quickly to festive demand. This follows August 2026 VAHAN growth of 19% year-on-year and YTD FY27 dispatches of 2,779,127 units versus 2,370,552 units in YTD FY26.
- Premium segment mandate: Anuj Dua was appointed as Chief Business Officer – Premium Segment with a mandate to drive the next phase of growth in premium mobility, alongside multiple premium launches planned in FY27.
- ESIC matter: Management is of the opinion that the orders are unsustainable in nature and are unlikely to have a material impact on the financials, operations, or other activities of the Company. The amount under the order stands paid and an appeal has been filed.
- FY27 capex guidance: The investor presentation references FY27 capex guidance across commuter ICE motorcycles, scooters, EV scooters, premium motorcycles, and GPC 2.0, though specific figures are not disclosed in the supplied material.
- Observed performance versus prior-year comparatives: Q1 FY27 revenue growth of 36% and volume growth of 23% were delivered against Q1 FY26. Consolidated PAT of ₹1,418 crore in Q1 FY27 compared against ₹1,706 crore in the previous year, which included a one-time gain of ₹722 crore on dilution of the Company’s share of investment in associates consequent to a public issue and private placement.
Broker Narrative
The broker narrative evolved from early fears about EV competition and export execution challenges into a story where market share gains, global expansion, and cost savings persisted as key drivers, while commodity cost stability — once a tailwind — turned into a headwind. The EV threat narrative inverted as the company gained share in electric scooters and achieved positive EV gross margins, and export skepticism was overturned by 63% global dispatch growth. By the last report, the focus shifted to margin pressure from raw material inflation and a more tempered valuation outlook (Accumulate) despite continued operational execution.
Optimism that failed
- The expectation of stable commodity prices and no further cost escalation reversed when raw material inflation caused gross margin to decline 475 bps YoY and EBITDA margin to fall below the guided range.
Broker Timeline
58 broker calls · 2023-05-06 to 2026-08-07
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.