GANESHCP
Equity Metrics
September 24, 2026
Ganesh Consumer Products Limited
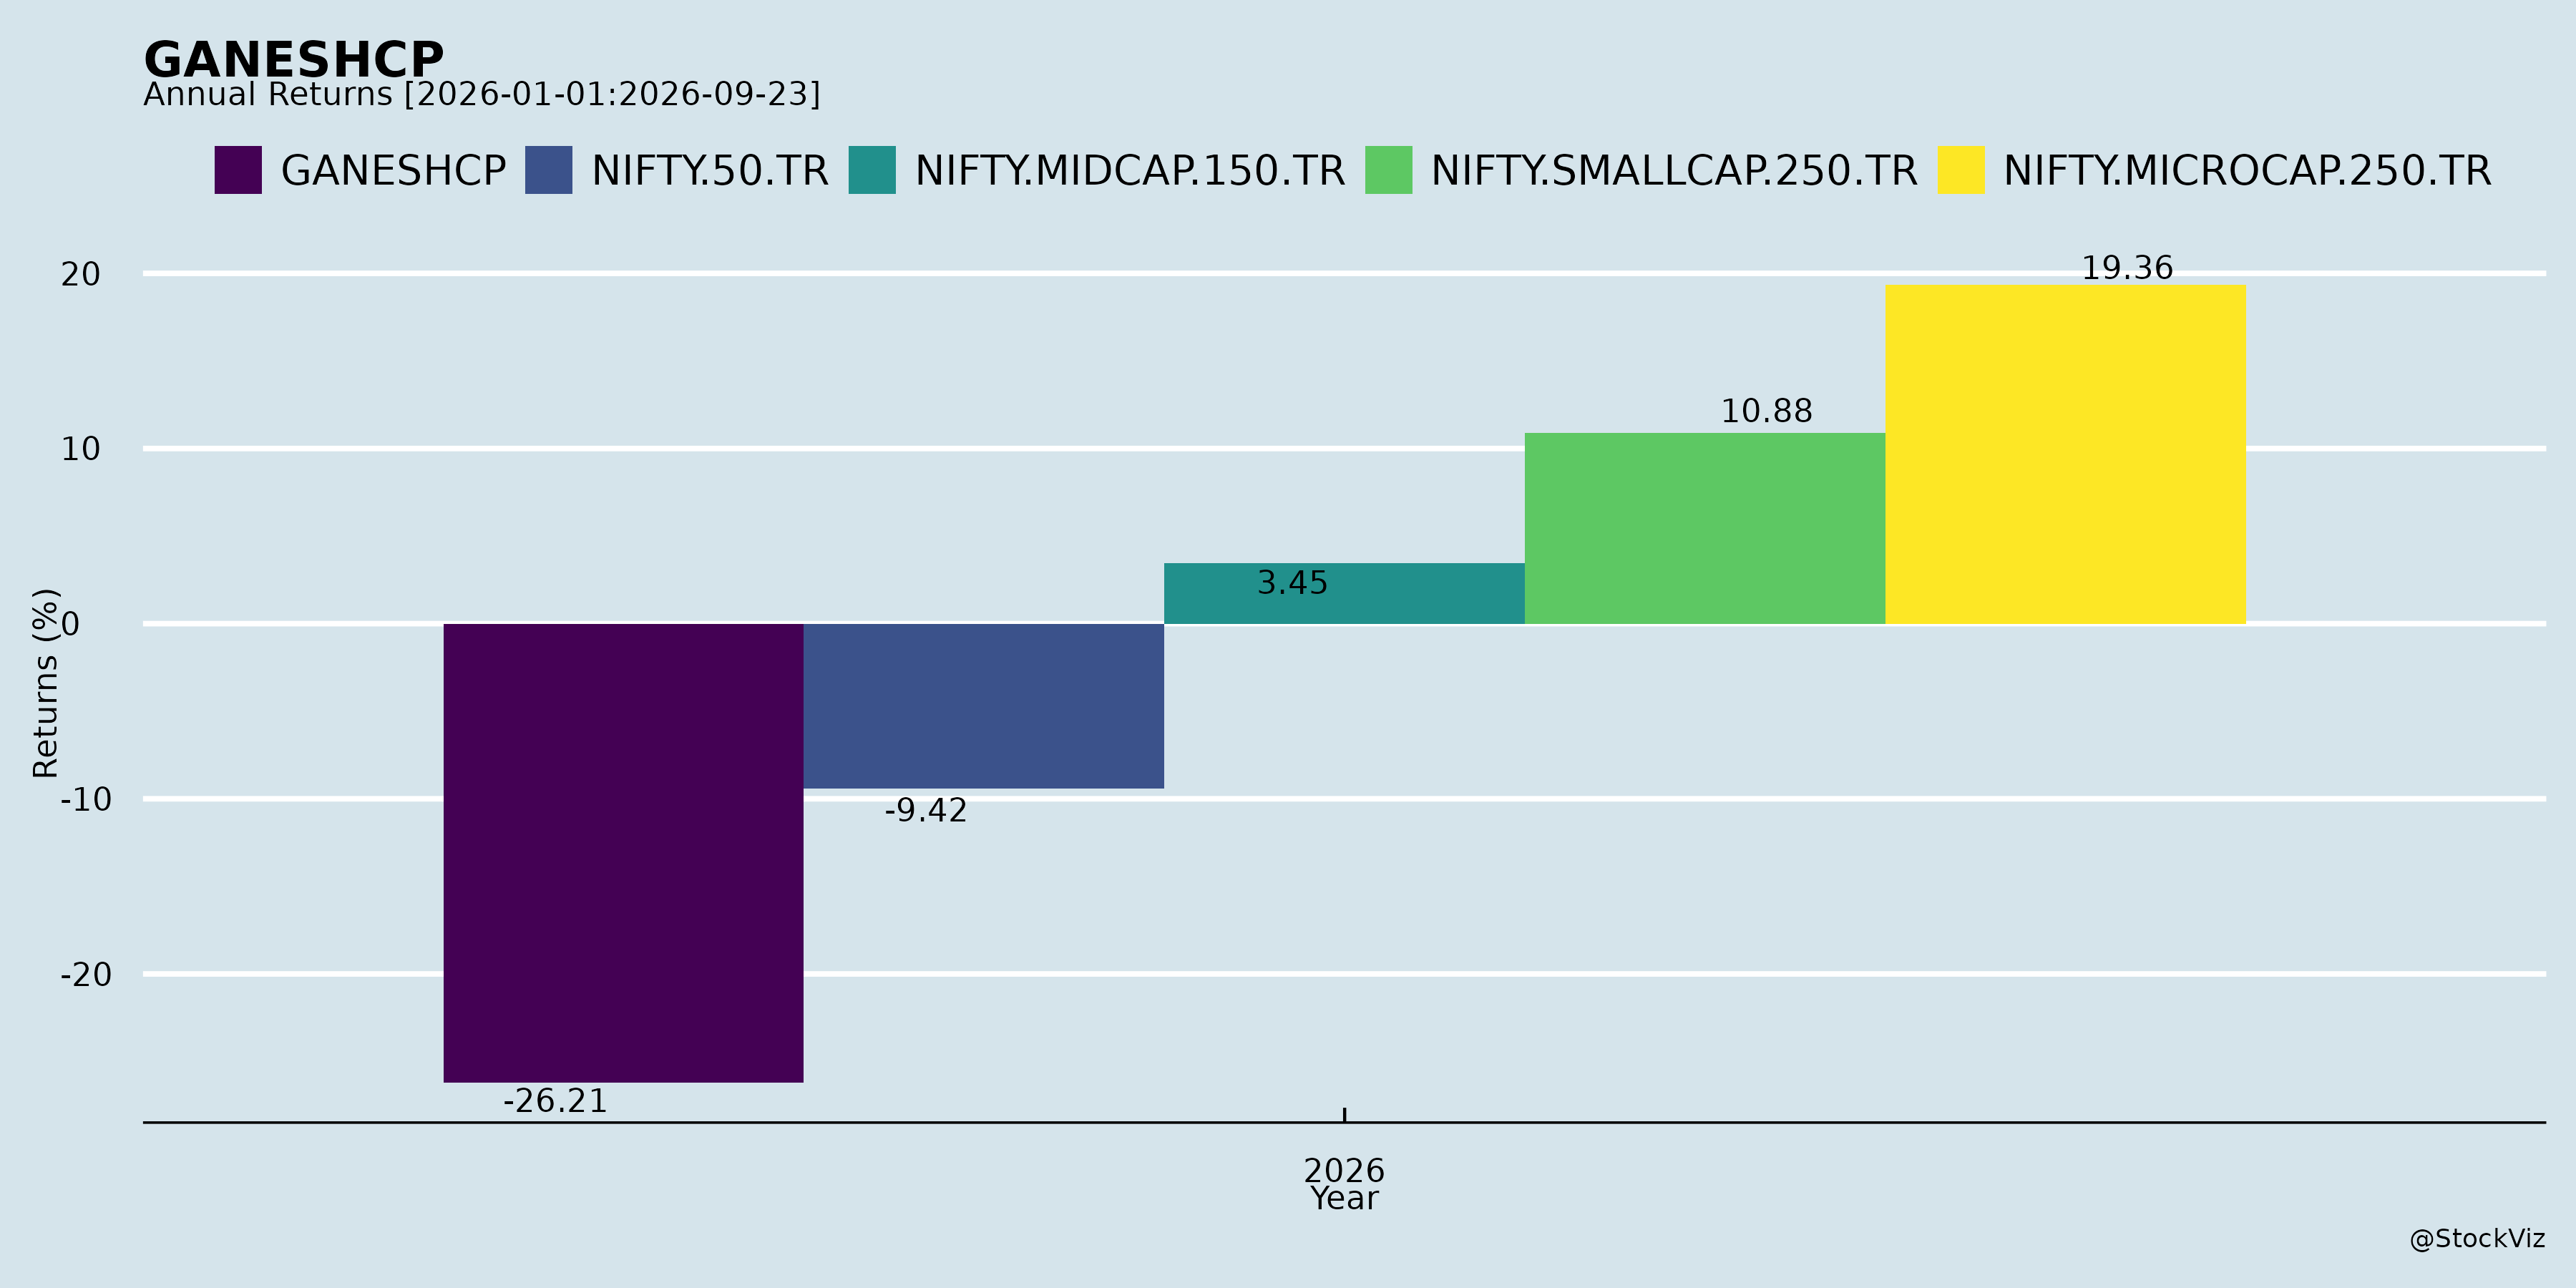
Annual Returns

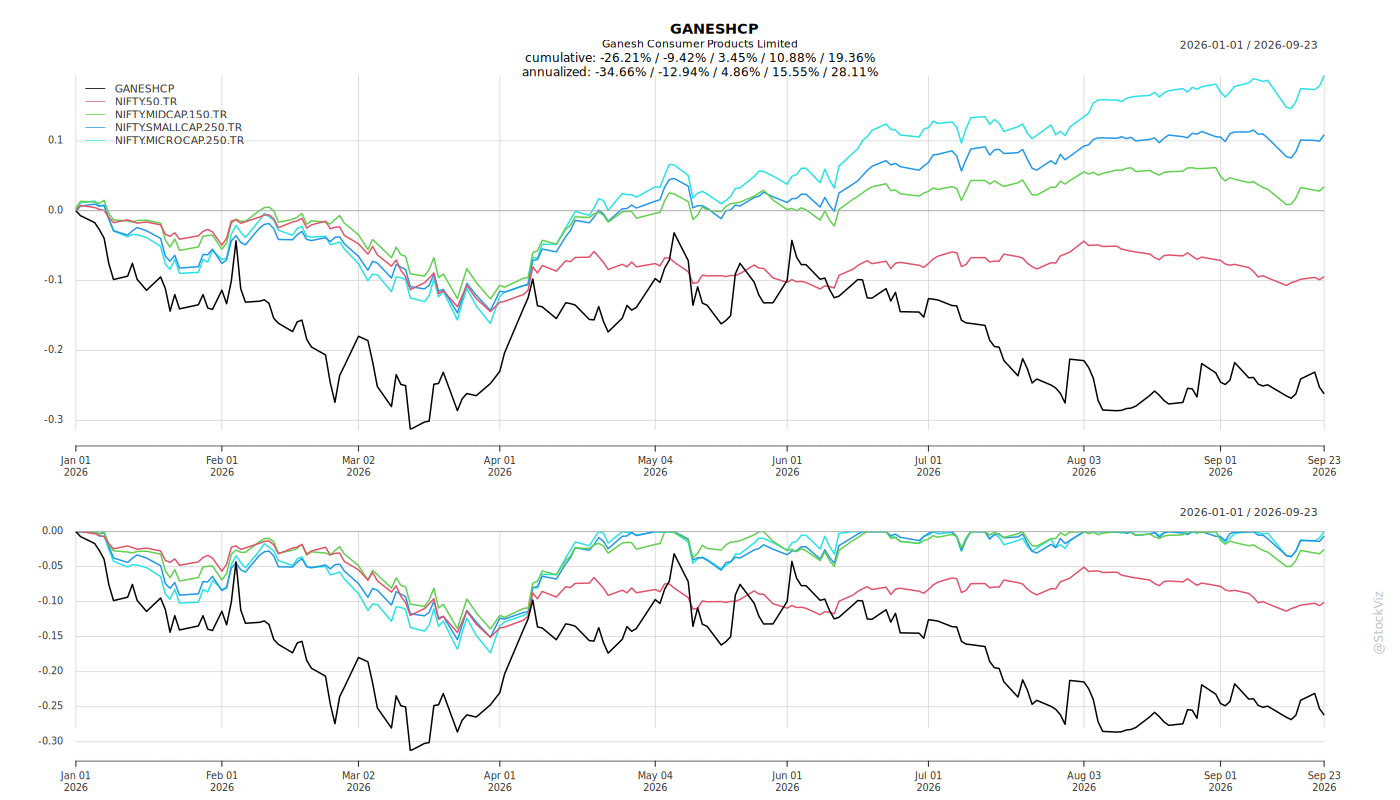
Cumulative Returns and Drawdowns
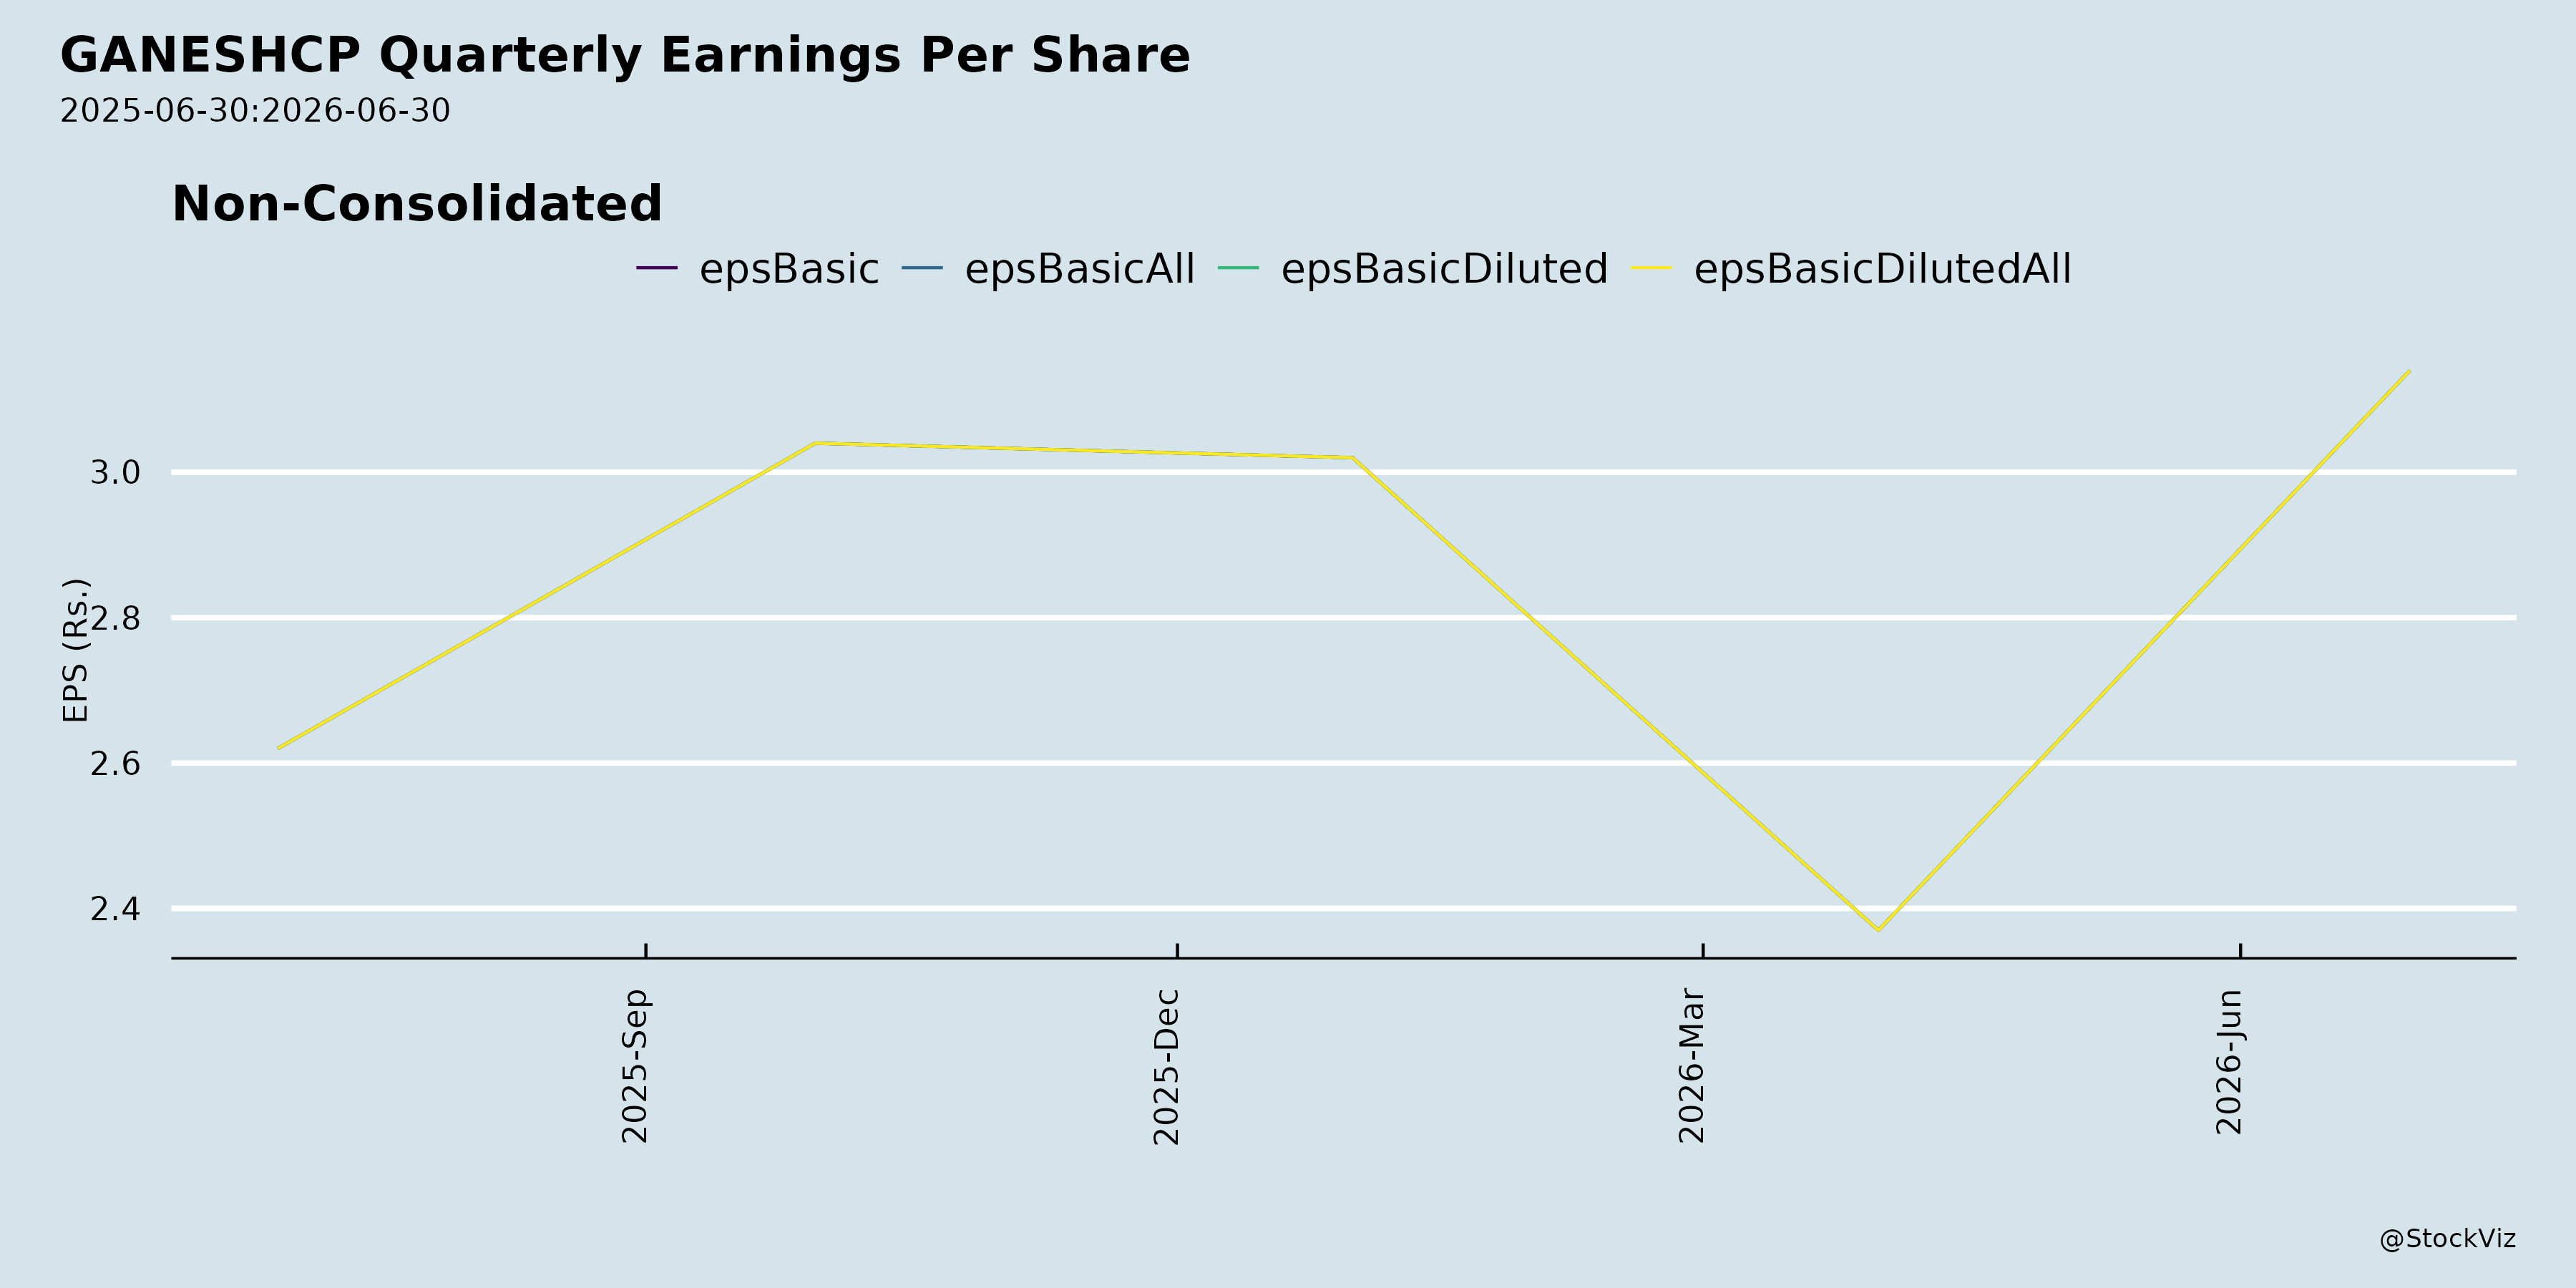
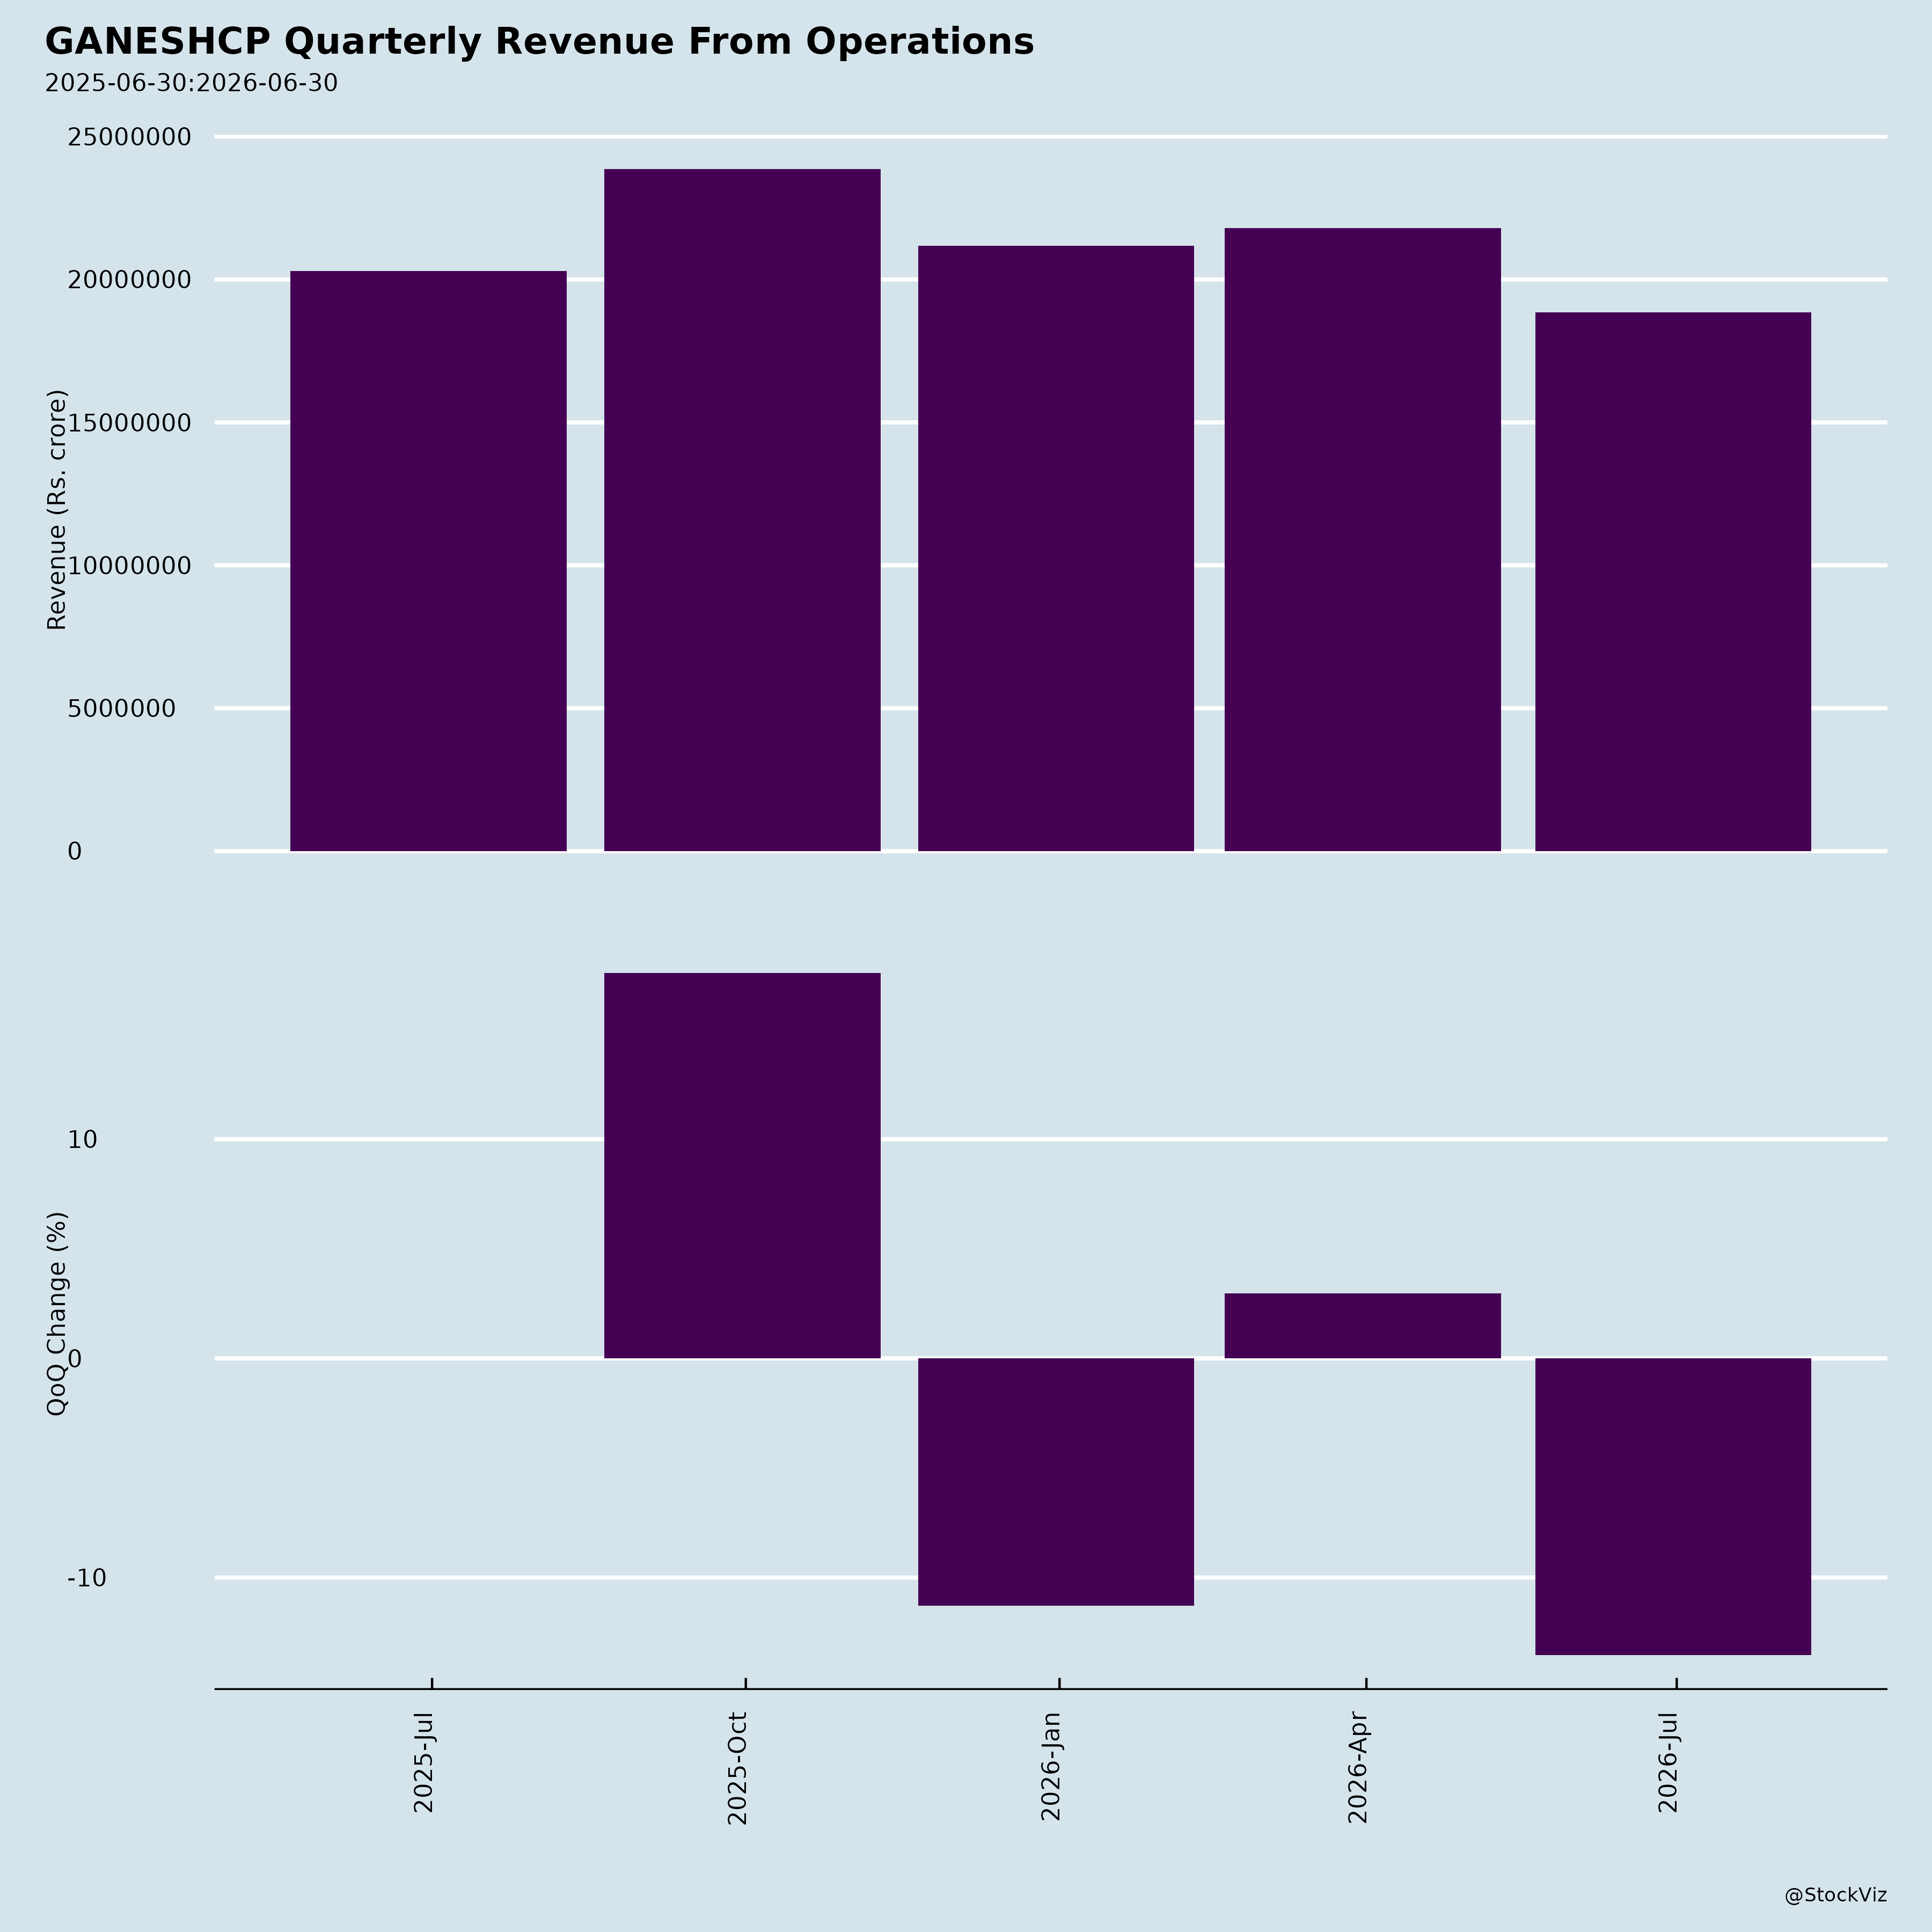
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Ganesh Consumer Products (GANESHCP) — Recent Developments Summary
1. Headwinds and Challenges
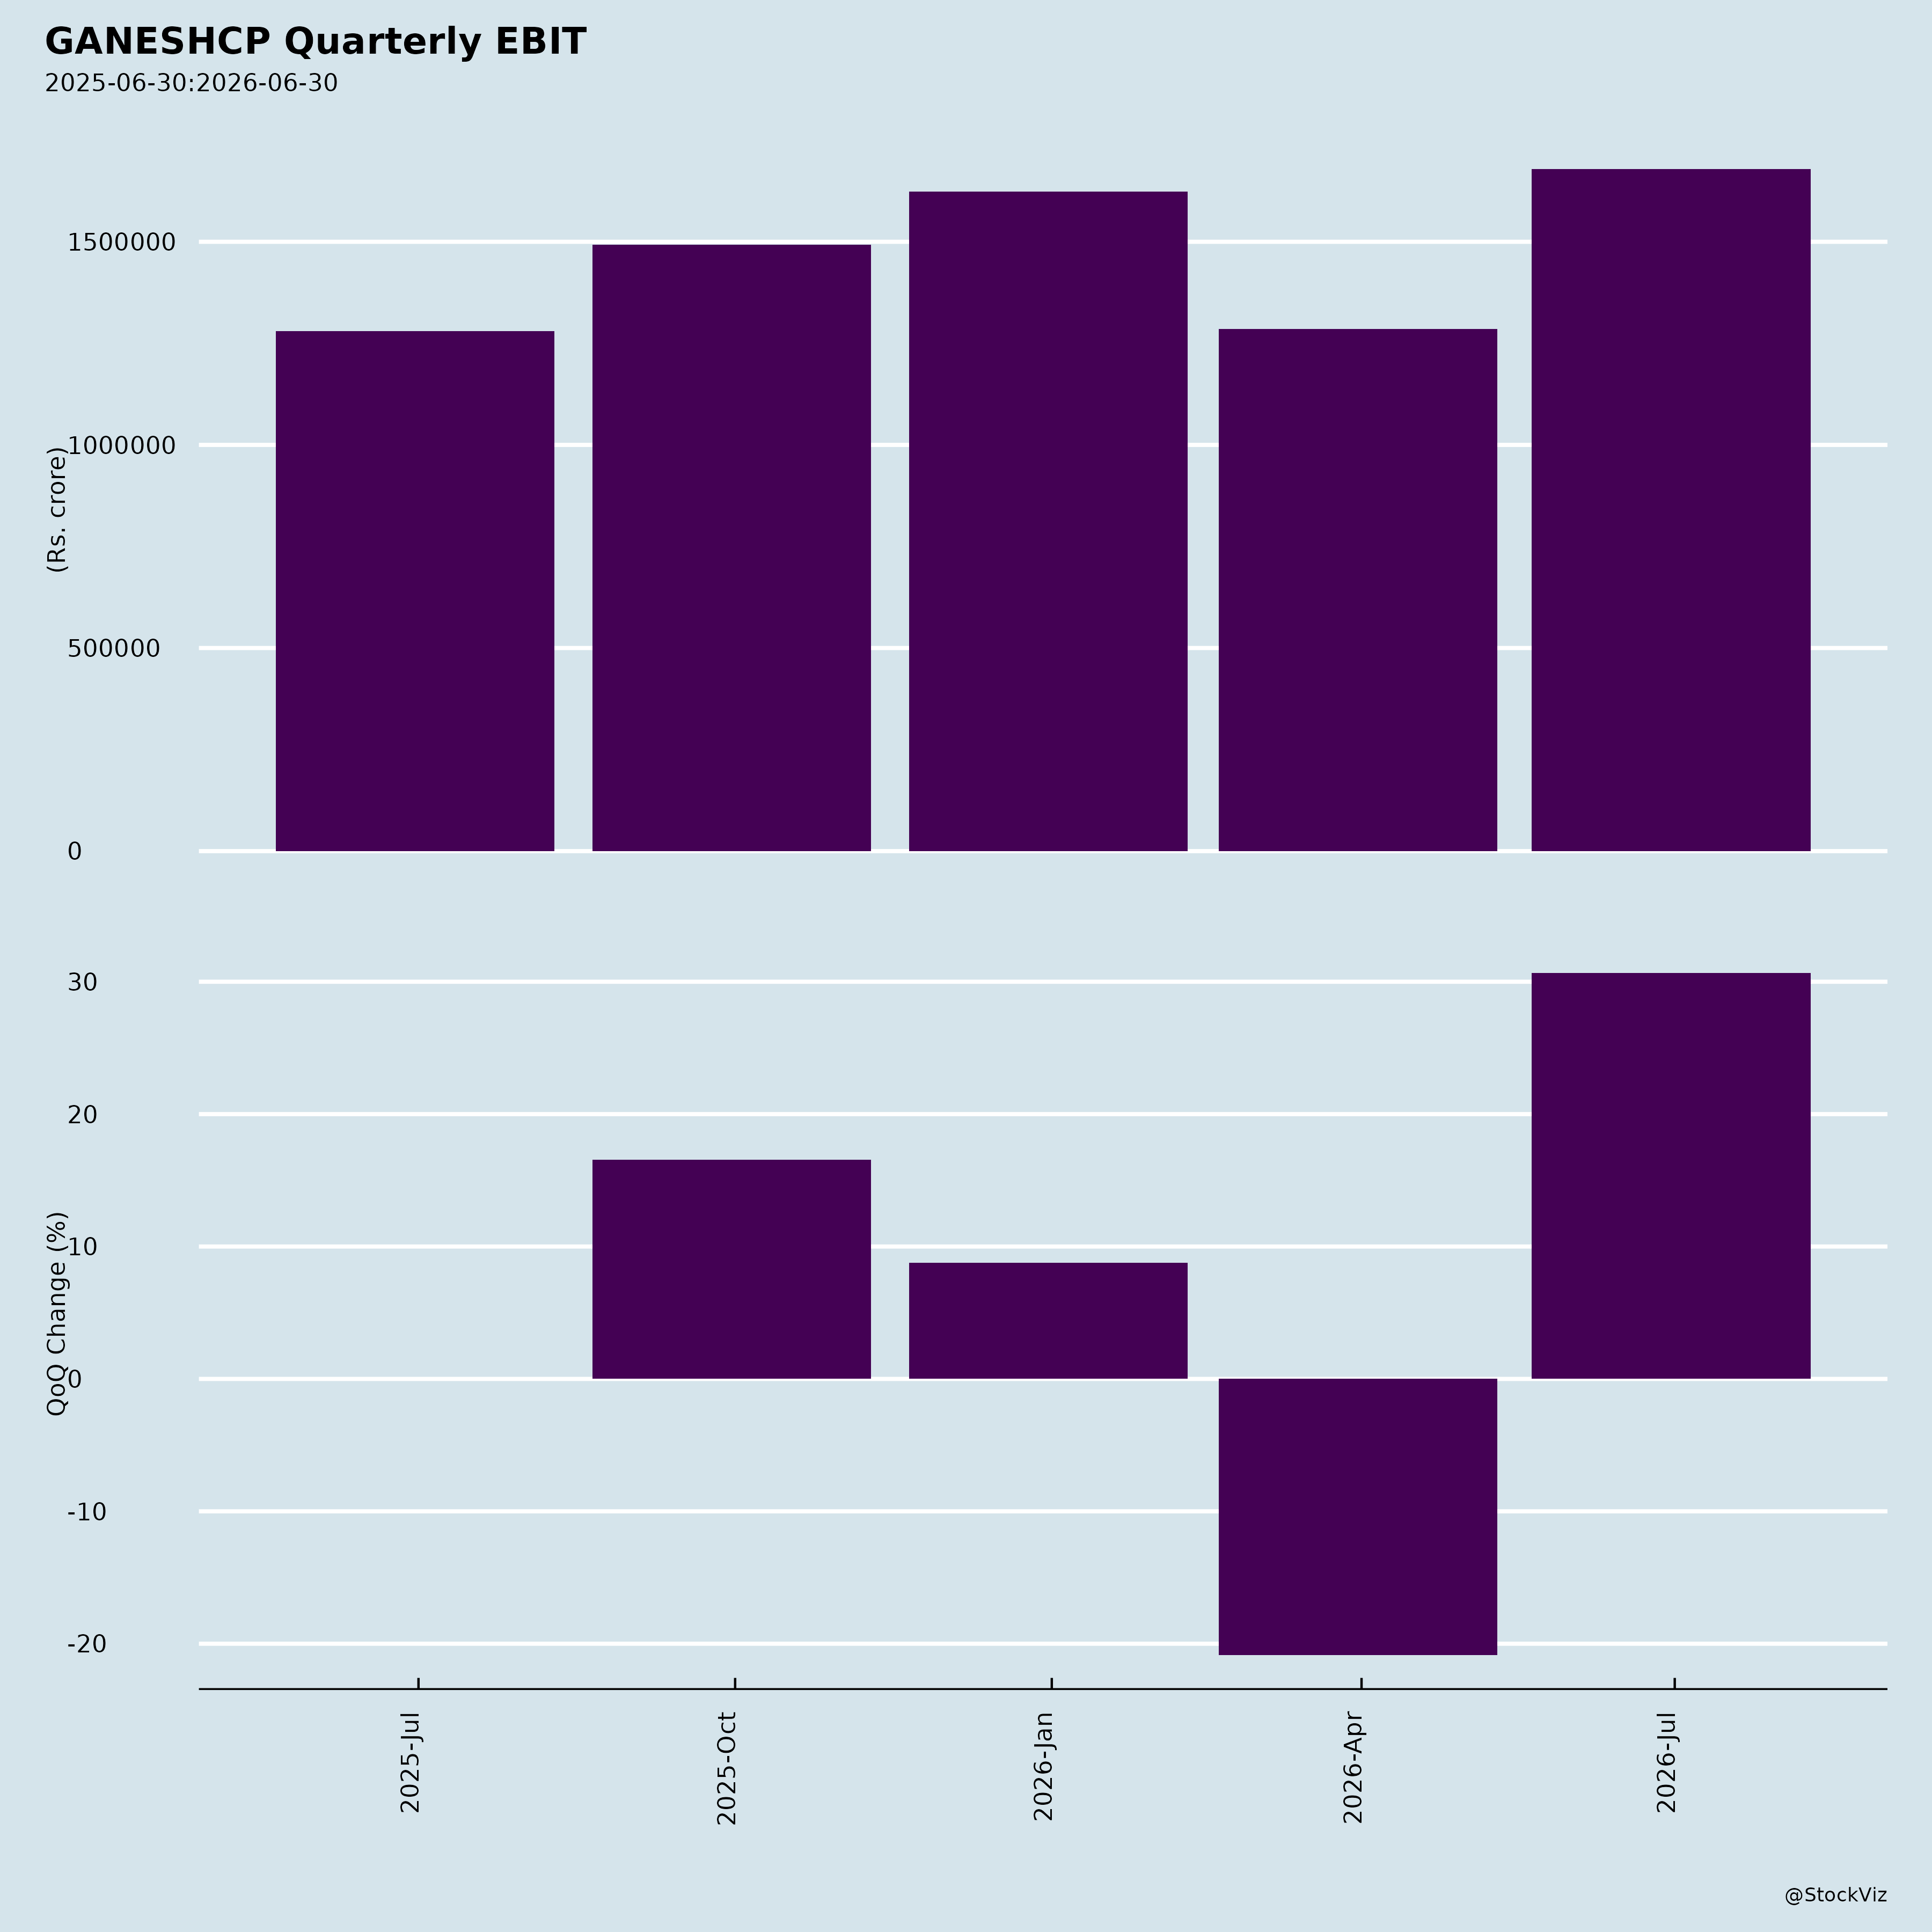
Weak Q1 FY27 demand environment (quarter ended June 30, 2026). Management attributed a challenging operating quarter to an extended heatwave, constrained LPG availability, and disruptions surrounding the Assembly elections. Revenue from operations declined 7.1% YoY to ₹1,885 million, and total income declined 6.8% YoY to ₹1,903 million. Sequentially, revenue fell 13.5% and total income fell 13.6%.
Divergent segment performance. The consumer-facing B2C business declined 4.1% YoY, while B2B declined 17.9% YoY. Management linked softer B2C volumes to knock-on weakness in B2B, with the remaining B2B decline attributed to lower realizations and a conscious decision to reduce exposure to lower-margin B2B volumes.
Contraction in the core West Bengal market. The West Bengal packaged-atta market contracted quarter-on-quarter, even as Ganesh gained share within it.
Capacity utilization well below prior-year levels. Installed capacity (annualized for Q1 FY27) stood at 3,74,508 TPA with utilization of 43.9%, versus 57.4% in FY26 and 57.5% in FY25.
Working capital intensity increased. Cash conversion cycle lengthened to 43 days (annualized) in Q1 FY27 from 23 days in FY26, 21 days in FY25, and 31 days in FY24, driven mainly by inventory days rising to 53 from 34 in FY26.
Return ratios moderated. Annualized ROE was 13.29% in Q1 FY27 versus 14.19% in FY26 and 15.81% in FY25; annualized ROCE was 17.98% versus 17.91% in FY26 and 19.81% in FY25.
Reputational risk from name confusion. Certain media organizations incorrectly associated the company with the suspension of the Food Safety Licence of “Ganesh Products Private Limited” / “Ganesh Products Pvt. Ltd.” due to similarity in nomenclature. The company clarified it is a separate and independent legal entity, has no relationship of any nature with Ganesh Products Private Limited, has received no notice or order suspending or cancelling its own licences, and that all its licences and registrations remain valid and subsisting.
2. Tailwinds and Growth Prospects
Market share and distribution gains despite soft demand. Overall market share in the packaged wheat-based category rose 1 percentage point, and weighted distribution improved 0.8 percentage points (1 percentage point per the press release), reflecting growing reach and availability.
Record profitability. EBITDA margin expanded to 11.2%, described as the highest in the company’s history — up 66 bps YoY and 313 bps sequentially. PAT grew 31.4% YoY to ₹125 million, with PAT margin at 6.6% (up 191 bps YoY and 225 bps sequentially). Margin expansion was attributed to disciplined procurement during a favorable commodity cycle, an enhanced product mix, and cost-optimization initiatives, achieved while advertising investment rose to 3.1% of revenue.
New category launches. Following an encouraging response to the soft launch of the ethnic snacks range, a wider rollout is planned for the later part of the current fiscal year. The entire ethnic snacks portfolio will be manufactured at the Amta unit, where packaged sweets are also planned. Both categories are expected to be launched during Q3 FY27. The company also commenced distribution of Soya Chunks, extending its value-added portfolio into protein-led kitchen staples.
Structural branded-staples opportunity. The presentation cites India’s large and growing population, rising urbanization (urban share to cross 40% by 2030), expanding incomes, rising female workforce participation, growth in modern trade and q-commerce, demand for health-oriented foods, and nuclearization of households as tailwinds for branded packaged staples. It cites organized-market CAGRs (2025–2030P) of ~18–20% for wheat flour and derivatives, ~18–20% for gram flour and derivatives, and ~18% for spices.
Geographic expansion. The company is strengthening distribution in Jharkhand, Odisha, Bihar, and Assam, and scaling distribution by adding distributors and C&F partners. The Board approved, at its September 09, 2026 meeting (3:30 P.M. to 4:05 P.M.), a proposal to purchase land in the State of Assam for strategic expansion and augmentation of infrastructure, intended to support future growth and expansion of business operations.
Distribution and portfolio scale. The company operates 8 manufacturing facilities with total capacity of 1,478 tons per day, 256 SKUs across 44 product categories, 1,003 distributors, 1,000+ C&F agents, and 3.5 lakh+ retail touchpoints, with 10 million+ household reach.
Financial position. Total borrowings fell to ₹59 million as of June 30, 2026, from ₹1,985 million as of June 30, 2025, with cash and cash equivalents of ₹232 million and net debt of negative ₹172 million. Net debt/equity was (0.04) as of June 30, 2026.
3. Key Risks
- Demand sensitivity to weather, fuel availability, and election-related disruption, as evidenced by the Q1 FY27 revenue decline.
- B2B volume and realization pressure, including the company’s deliberate reduction of lower-margin B2B exposure.
- Core-market contraction risk, illustrated by the QoQ decline in the West Bengal packaged-atta market.
- Underutilization of expanded capacity, with Q1 FY27 utilization at 43.9% against 57.4% in FY26.
- Working capital risk, with the cash conversion cycle lengthening to 43 days and inventory days rising to 53.
- Reputational/name-confusion risk, following incorrect media association with the licence suspension of Ganesh Products Private Limited.
- Execution risk on new categories and geographies, including the ethnic snacks and packaged sweets launches planned for Q3 FY27 and the Assam land purchase.
- Forward-looking statement risk, as flagged in the company’s safe harbour statement, covering growth, competition, acquisitions, economic conditions affecting demand, supply and prices, government regulation and tax regimes, and ability to attract and retain talent.
4. Management Guidance vs. Observed Business Performance
Guidance/forward-looking statements:
- Wider rollout of the ethnic snacks range during the later part of the current fiscal year; ethnic snacks and packaged sweets both expected to launch during Q3 FY27, manufactured at the Amta unit.
- Continued distribution of Soya Chunks into protein-led kitchen staples.
- Priorities to strengthen core categories, scale the value-added portfolio, and deepen presence across existing and emerging markets.
- Strategic roadmap targets: geographic expansion into Jharkhand, Odisha, Bihar, and Assam; product diversification; brand visibility campaigns across TV, radio, print, digital, and outdoor; operational efficiency via solar power at four manufacturing units, Warehouse Management System implementation, and Botree DMS, SFA apps, and SAP S/4 HANA Cloud adoption.
- Purchase of land in Assam for strategic expansion and augmentation of infrastructure, supporting future growth.
- Taking up the name-confusion matter with concerned media organizations for issuance of a suitable clarification, with a commitment to transparency and keeping stakeholders informed.
Observed performance against these:
- Margin and profit: Delivered record EBITDA margin of 11.2% and PAT growth of 31.4% YoY in Q1 FY27, alongside increased advertising spend at 3.1% of revenue.
- Share and reach: Market share up 1 percentage point and weighted distribution up 0.8 percentage points, consistent with the stated priority of strengthening the core.
- Revenue: Declined 7.1% YoY and 13.5% QoQ, reflecting the demand headwinds management described.
- Capacity utilization: At 43.9% in Q1 FY27, below FY26 and FY25 levels, indicating that expanded capacity is not yet fully absorbed.
- IPO proceeds deployment: Of the ₹450.0 million proposed for the Darjeeling roasted gram flour and gram flour manufacturing unit, only ₹24.6 million was utilized as of June 30, 2026, leaving ₹425.4 million un-utilized; the ₹600.0 million for prepayment/repayment of borrowings was fully utilized; of the general corporate purposes amount, ₹107.4 million was utilized and ₹39.7 million remained un-utilized.
- Dividend: A recommended final dividend of ₹2.50 per share for FY26 is subject to shareholder approval at the ensuing AGM, with total FY26 dividend at ₹5.00 per share inclusive of the ₹2.50 interim dividend already paid.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.