DHAMPURSUG
Equity Metrics
October 23, 2026
Dhampur Sugar Mills Limited
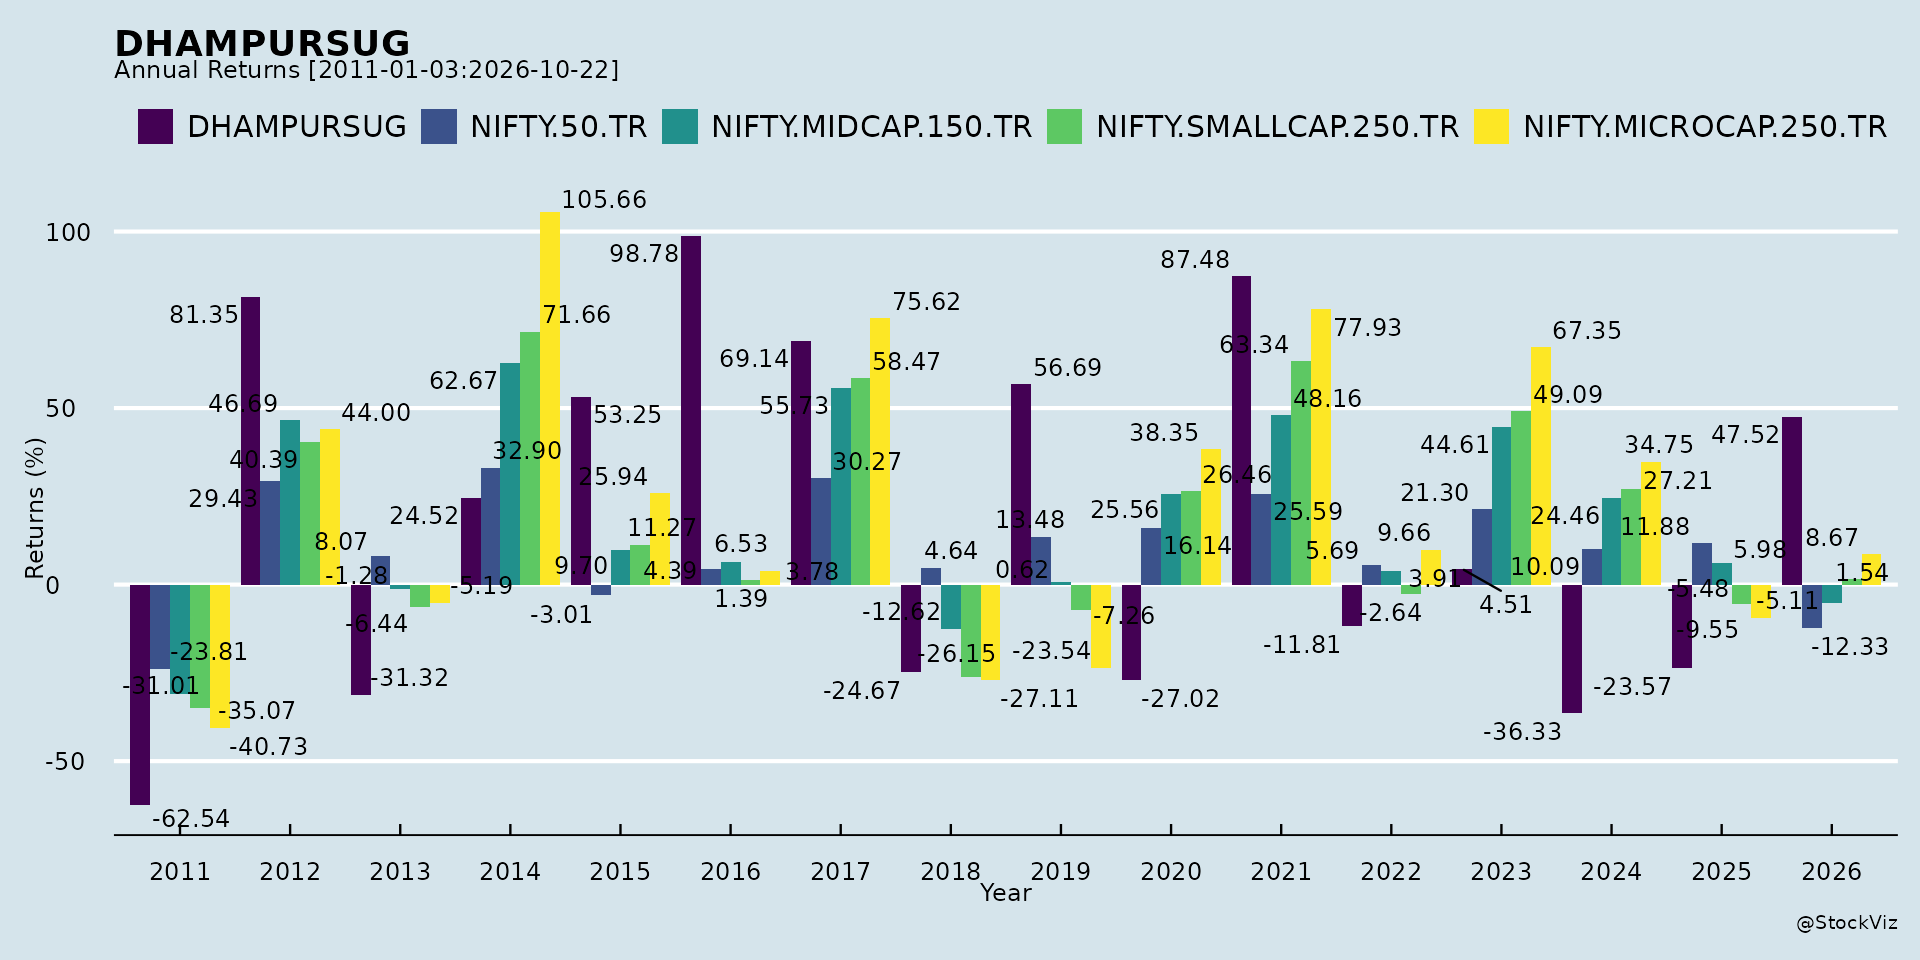
Annual Returns
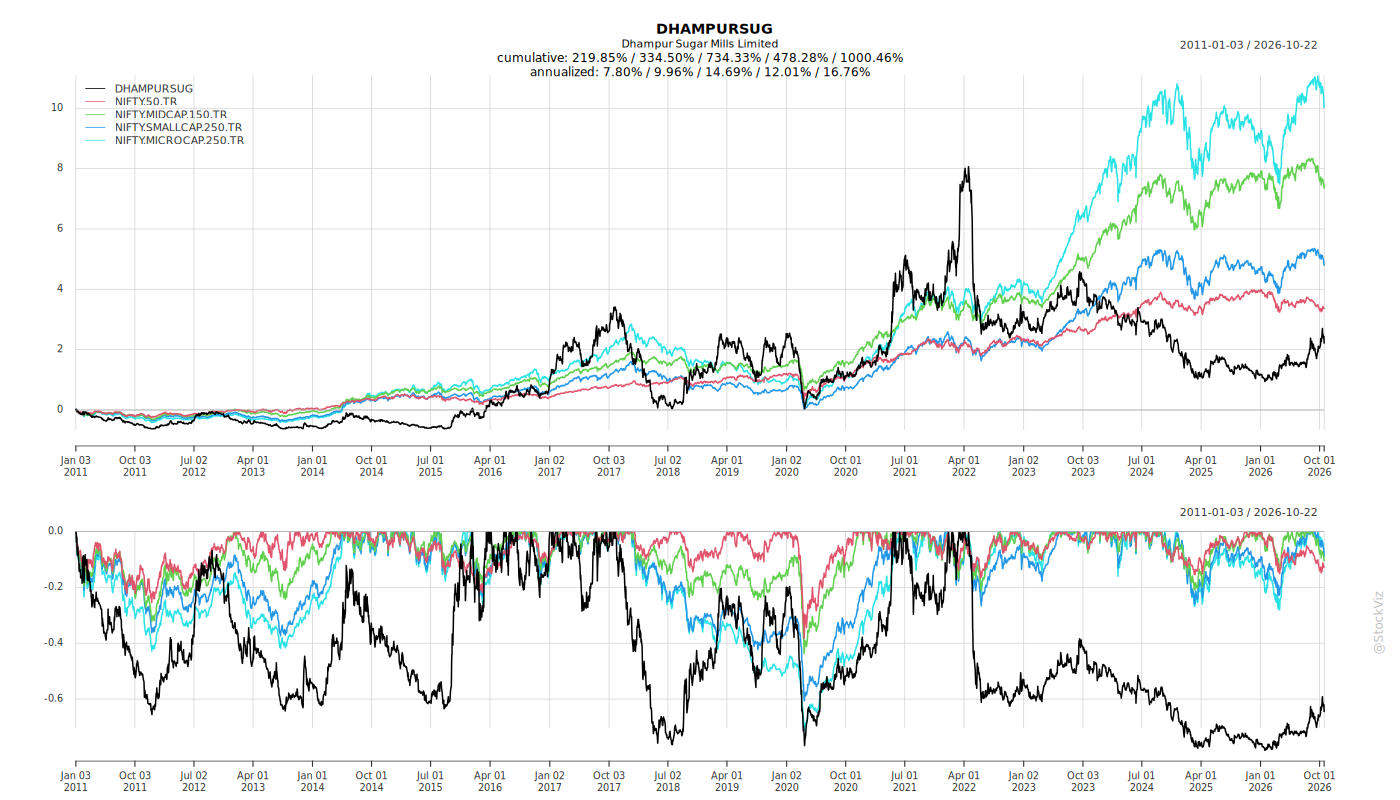
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Dhampur Sugar Mills — Q1 FY27: Headwinds, Tailwinds, Risks and Guidance
1. Headwinds and Challenges
- Ethanol volumes declined sharply. Total ethanol sales fell to 151.53 lakh BL in Q1 FY27 from 182.39 lakh BL in Q1 FY26. The drop was concentrated in maize-based ethanol (42.10 lakh BL vs. 78.46 lakh BL) and C-heavy ethanol (2.44 lakh BL vs. 25.62 lakh BL). Average realisation also slipped to Rs. 62.66/BL from Rs. 64.33/BL.
- Power exports collapsed. Power export fell to 0.36 crore units from 0.95 crore units, which the company attributes to the early closure of the SS 25-26 crushing season.
- Sugar production and recovery weakened. Cane crushed in Q1 FY27 was only 0.44 lakh tons against 1.70 lakh tons a year earlier. Gross recovery dropped to 10.68% from 12.60%, and net recovery to 9.08% from 10.42%. Sugar production was just 0.04 lakh tons versus 0.18 lakh tons.
- Profitability remains thin in absolute margin terms. Standalone EBITDA margin was 4.63% and PAT margin 0.68% in Q1 FY27, while consolidated PAT margin was 0.77%. Finance costs rose to Rs. 15.82 crore from Rs. 15.77 crore, and depreciation was Rs. 13.06 crore.
- Seasonality caveat. The company notes that sugar is a seasonal industry and quarterly performance may not be representative of the annual performance.
2. Tailwinds and Growth Prospects
- Sugar realisations improved. White sugar realisation rose to Rs. 41,202/ton from Rs. 39,999/ton, and sugar sales volumes increased to 0.85 lakh tons from 0.80 lakh tons.
- Sugar segment swung to profit. The sugar segment posted a segment result of Rs. 7.52 crore in Q1 FY27 against a loss of Rs. 3.11 crore in Q1 FY26. On a standalone basis, sugar EBIT moved from -18.87% to +27.25% of the mix.
- Chemicals business scaled up. Chemical sales rose to 86.48 lakh kg from 78.52 lakh kg, with higher margins. Chemicals segment revenue was Rs. 73.41 crore versus Rs. 53.86 crore, and segment result improved to Rs. 4.72 crore from Rs. 1.54 crore.
- Maize ethanol margins improved due to a lower cost of production, even though volumes were lower.
- New rice-based ethanol feedstock contributed. Rice ethanol production of 22.72 lakh BL and sales of 23.03 lakh BL appeared in Q1 FY27, with nil contribution in Q1 FY26.
- Potable spirits remained steady. Production was 8.48 lakh cases (vs. 8.65 lakh) and sales 8.20 lakh cases (vs. 8.38 lakh), with segment result of Rs. 3.17 crore.
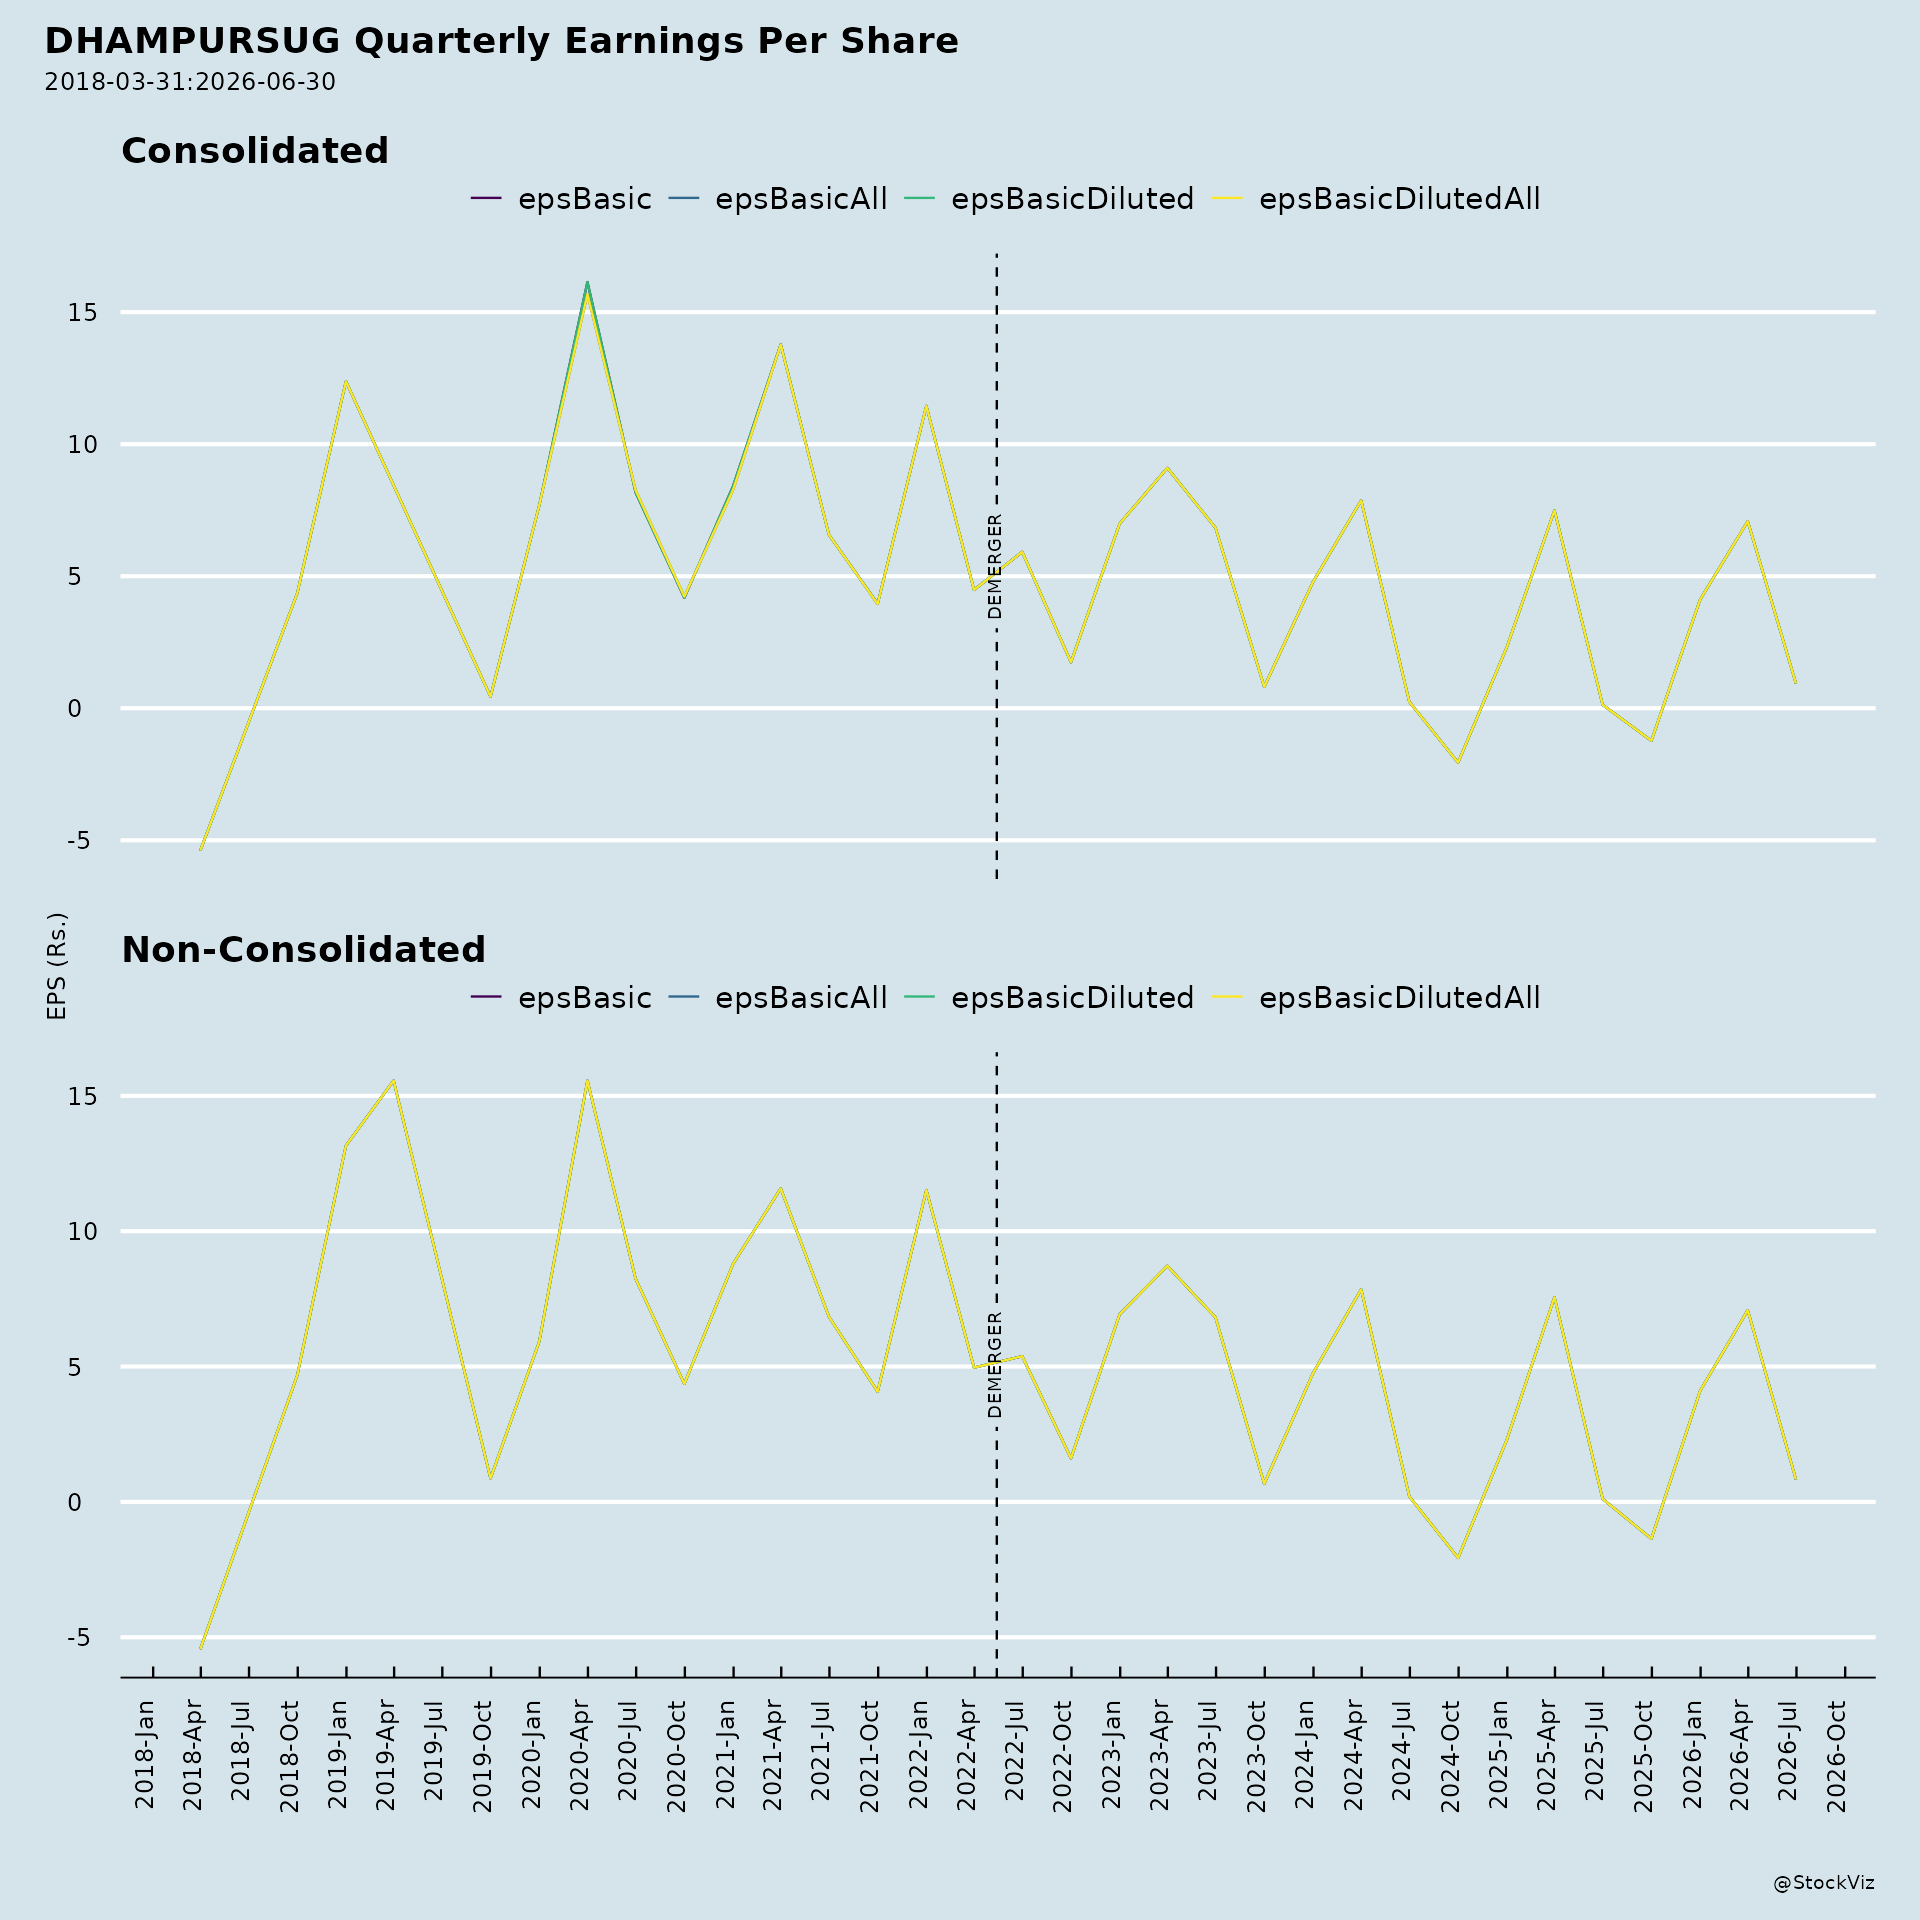
- Overall earnings growth. Standalone EBITDA rose to Rs. 36.34 crore from Rs. 30.68 crore; PBT rose to Rs. 7.46 crore from Rs. 1.11 crore; PAT rose to Rs. 5.31 crore from Rs. 0.72 crore. Consolidated PAT was Rs. 6.09 crore versus Rs. 0.91 crore.
- Credit profile affirmed. India Ratings & Research affirmed Issuer Rating and Term Loan at IND AA-, and Working Capital Limits, Commercial Paper and Public Deposits at IND A1+/IND AA-.
- Brand extension. The presentation features “Mishti by Dhampur” packaged sugar in 5 kg, 1 kg and 500 gm formats.
3. Key Risks
- Concentration of earnings outside sugar. In Q1 FY27, the sugar business contributed 64.63% of revenue but only 27.25% of EBIT, while non-sugar businesses contributed 35.37% of revenue and 72.75% of EBIT. Weakness in ethanol, power or chemicals would disproportionately affect profitability.
- Feedstock and volume volatility. Ethanol production mix shifted materially between B-heavy, C-heavy, maize and rice, and total production fell to 161.57 lakh BL from 177.10 lakh BL, exposing the business to feedstock availability and pricing swings.
- Seasonal and crushing-cycle dependence. Early closure of the SS 25-26 season directly reduced power exports, illustrating how crushing schedules affect multiple segments.
- Working capital and inventory build. Changes in inventories of finished goods, WIP and stock-in-trade absorbed Rs. 326.80 crore in Q1 FY27, compared with a release of Rs. 360.95 crore in the quarter ended 31 March 2026, reflecting the seasonal build.
- Regulatory and excise exposure. Excise duty on sales was Rs. 233.55 crore in Q1 FY27, a large and policy-sensitive cost line.
- Subsidiary reliance on other auditors. The consolidated results include E-HAAT Limited (revenue Rs. 56.81 crore, PAT Rs. 0.66 crore) reviewed by joint auditors, and DETS Limited (revenue Rs. 0.15 crore, PAT Rs. 0.12 crore) reviewed by another firm; the group’s auditors rely on those reports.
- Governance continuity. The 91st AGM held on 26 August 2026 passed all nine resolutions, ordinary and special, with the required majority, as confirmed by the consolidated scrutinizer’s report.
4. Management Guidance Versus Observed Performance
The source material contains no explicit quantitative guidance or forward-looking targets from management for FY27. The only forward-looking framing is the standard safe-harbour statement that the presentation contains forward-looking statements based on currently held beliefs and assumptions, subject to known and unknown risks, and the note that sugar is seasonal so quarterly results may not represent annual performance.
Where observed performance can be compared against the company’s own stated positives and negatives for Q1 FY27:
- Stated positive — higher sugar sales and realisation: confirmed, with sales at 0.85 lakh tons vs. 0.80 lakh tons and realisation at Rs. 41,202/ton vs. Rs. 39,999/ton.
- Stated positive — higher maize ethanol margin on lower cost: confirmed in margin terms, but maize ethanol sales volumes fell to 42.10 lakh BL from 78.46 lakh BL, so the margin gain did not translate into volume growth.
- Stated positive — higher chemical sales and margin: confirmed, with volumes at 86.48 lakh kg vs. 78.52 lakh kg and segment result at Rs. 4.72 crore vs. Rs. 1.54 crore.
- Stated negative — lower ethanol sales: confirmed, at 151.53 lakh BL vs. 182.39 lakh BL.
- Stated negative — lower power export on early closure of SS 25-26: confirmed, at 0.36 crore units vs. 0.95 crore units.
The net effect was that standalone EBITDA rose 18.4% year on year to Rs. 36.34 crore and PAT rose to Rs. 5.31 crore from Rs. 0.72 crore, even as the ethanol and power declines offset part of the sugar and chemicals improvement.
Broker Timeline
1 broker calls · 2023-05-09 to 2023-05-09
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.