COCHINSHIP
Equity Metrics
November 18, 2026
Cochin Shipyard Limited
Ship Building & Allied Services
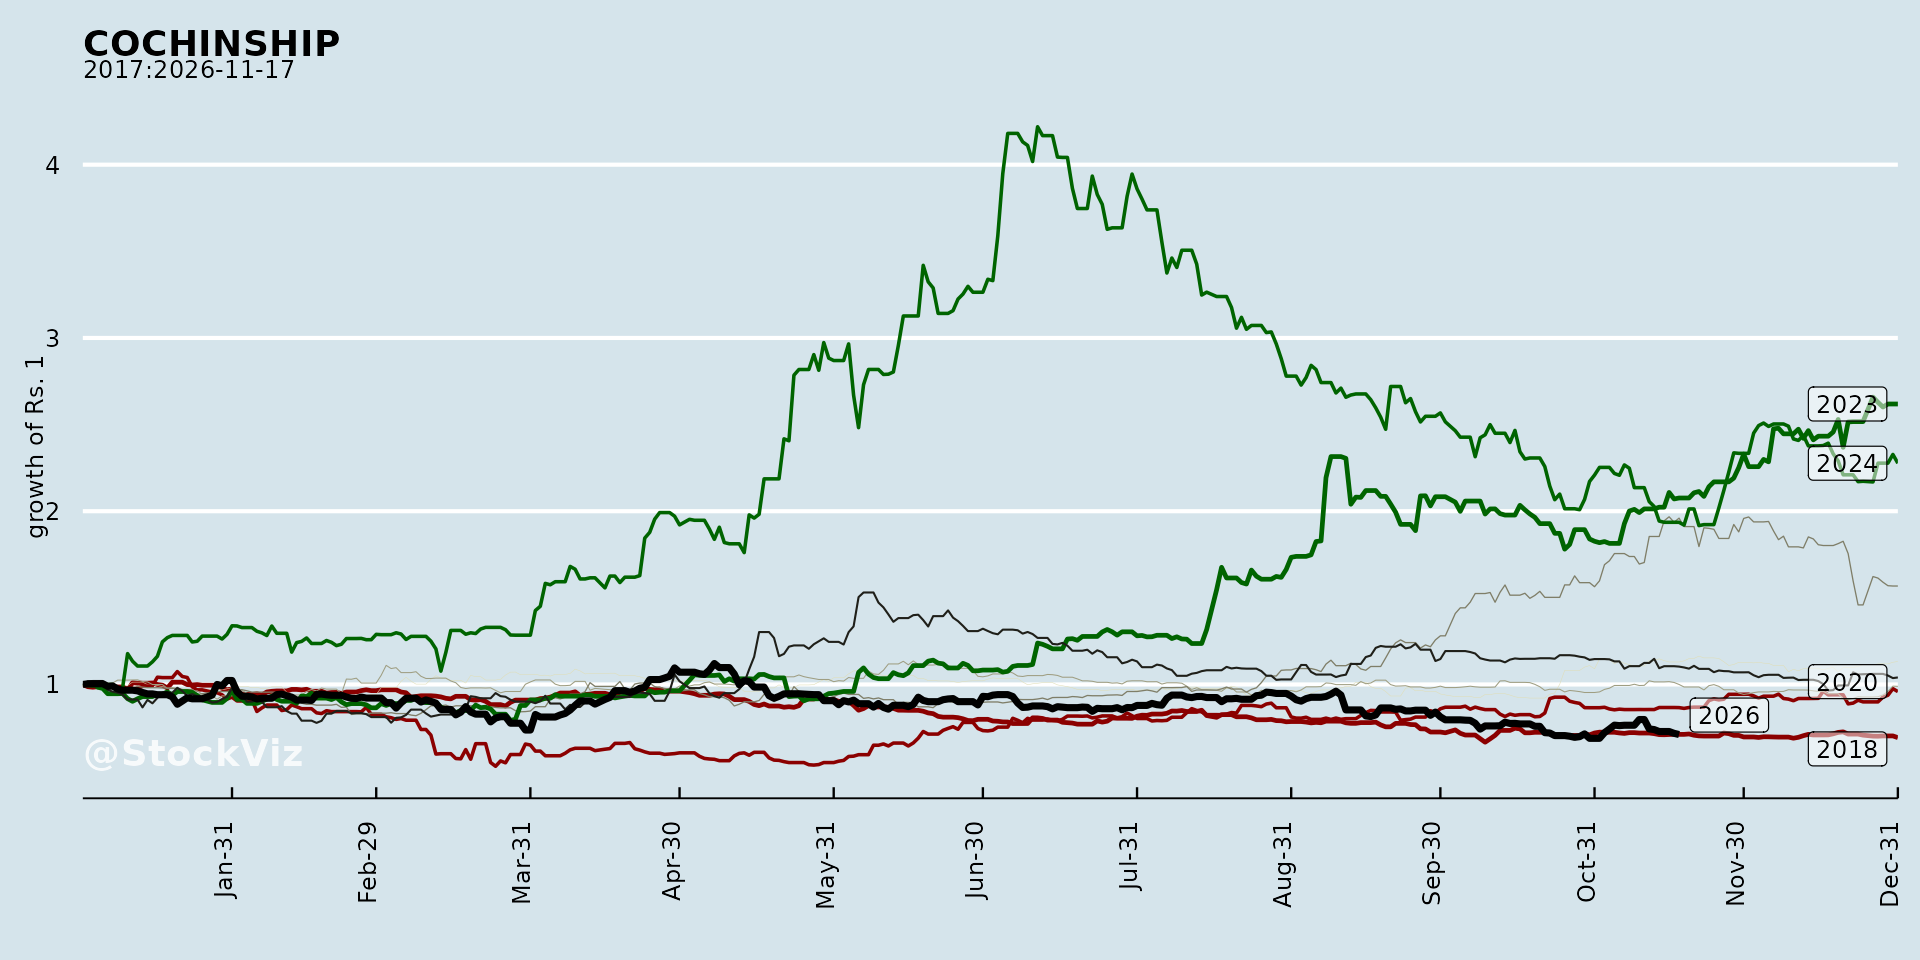
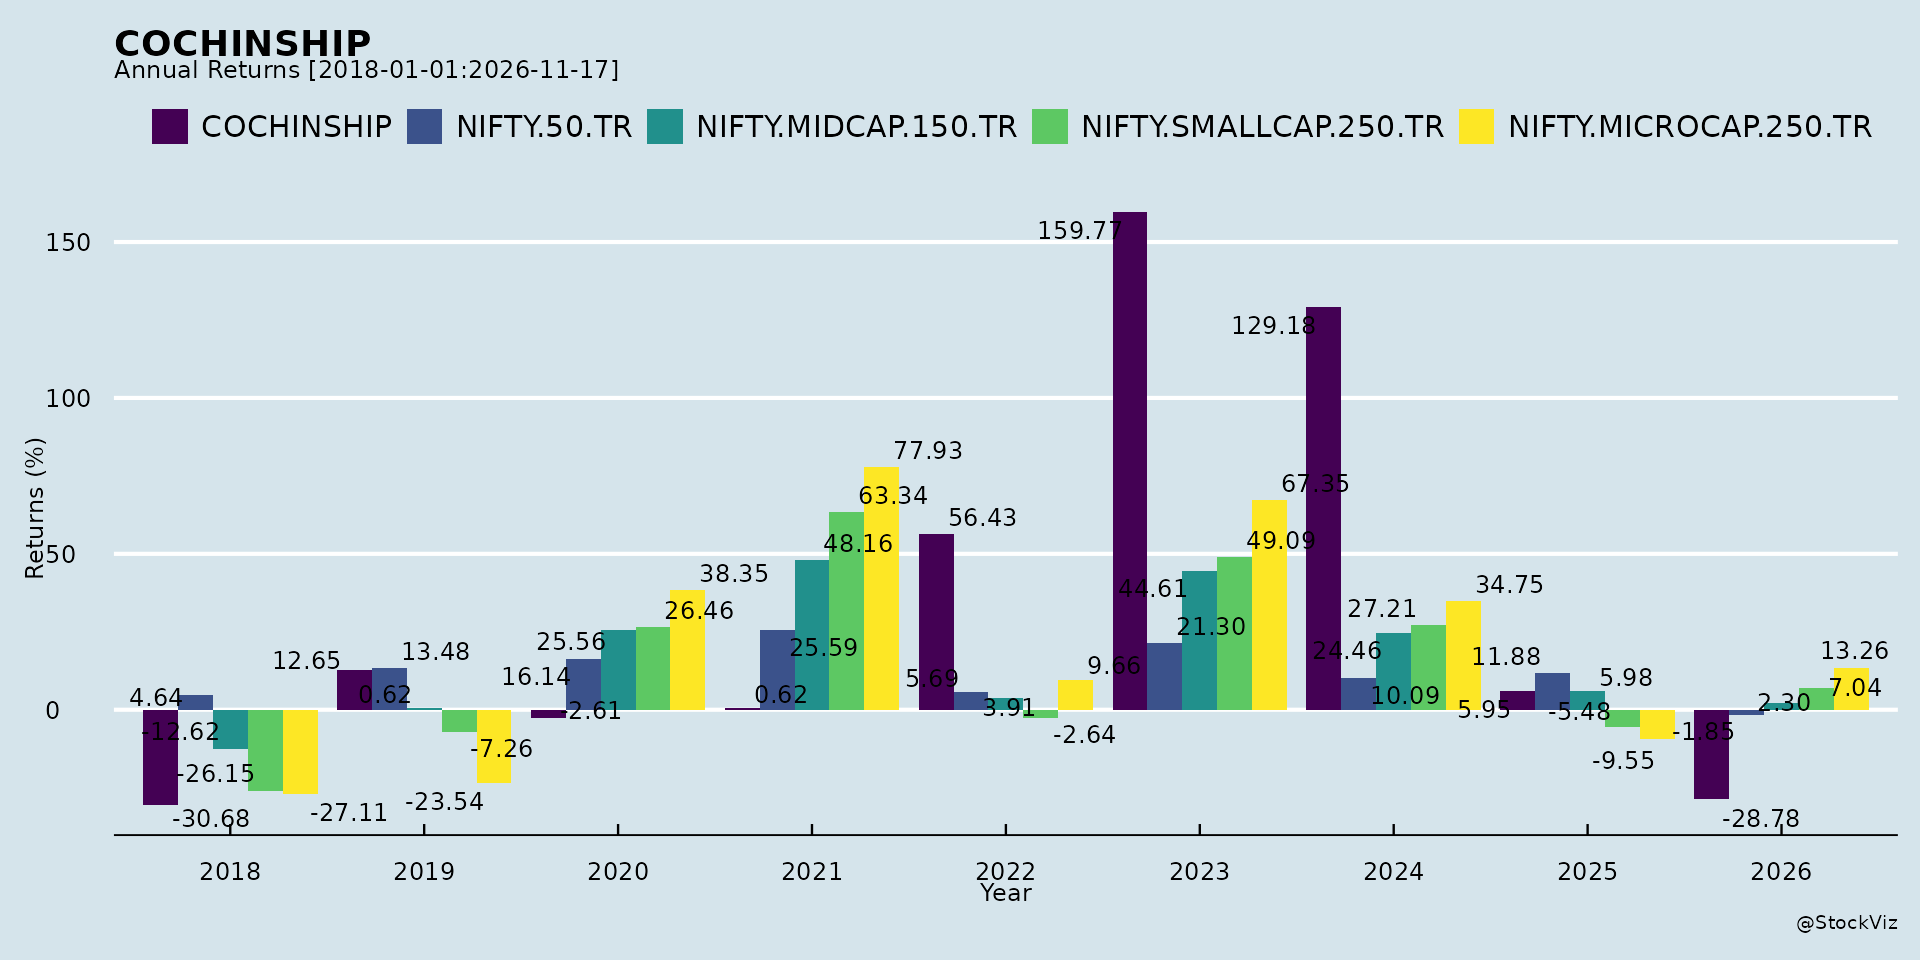
Annual Returns
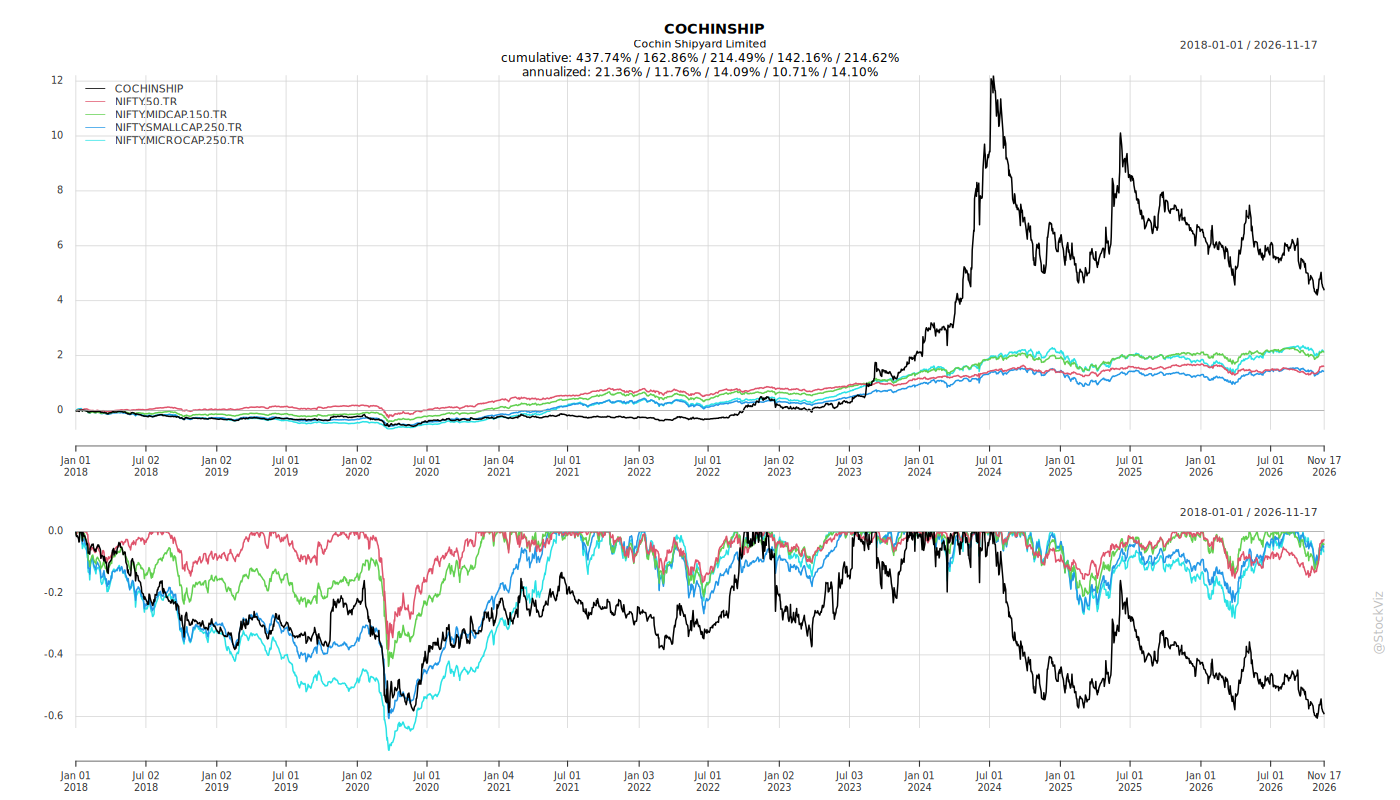
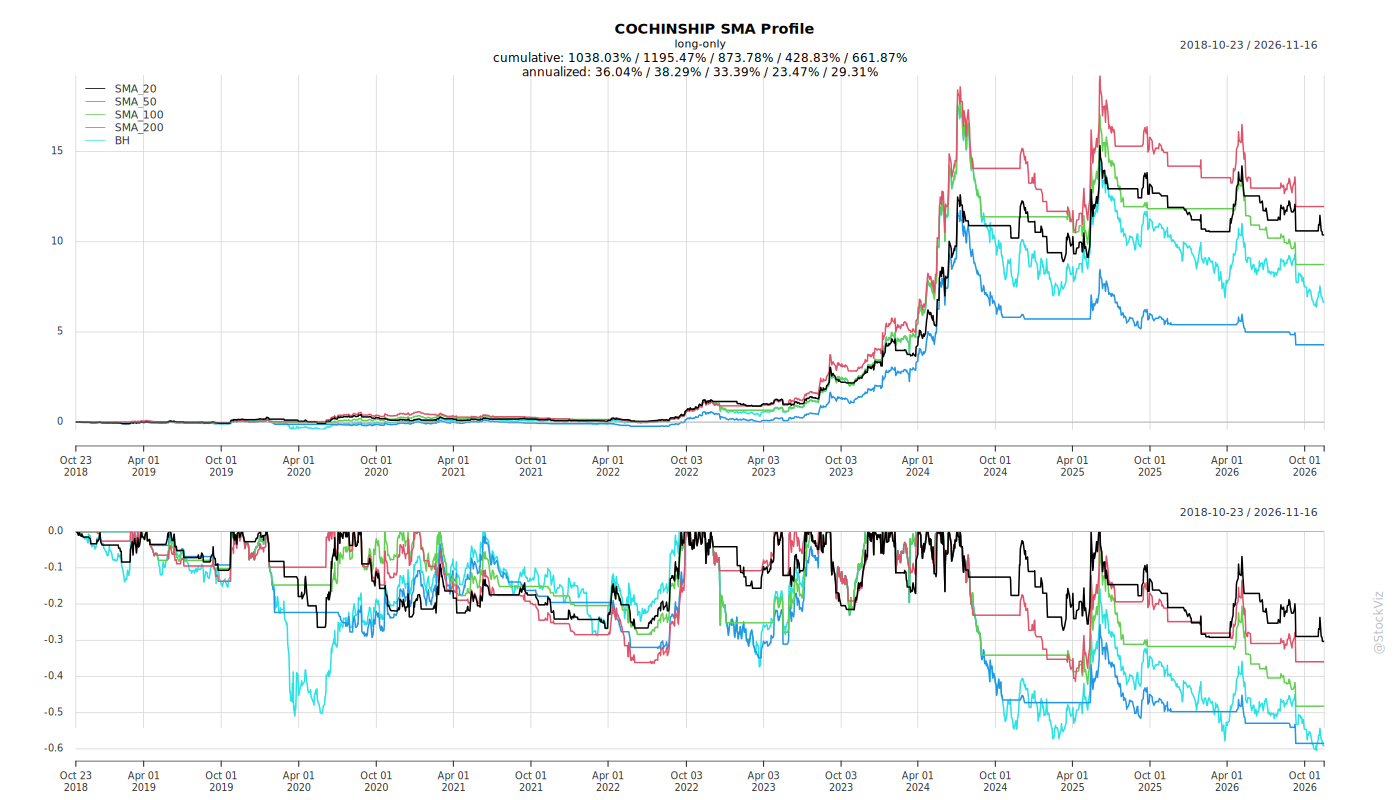
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
- Regulatory non-compliance penalties: BSE Limited and the National Stock Exchange of India Limited imposed fines of Rs. 9,66,420 each (including GST at 18%) on Cochin Shipyard Limited for non-compliance with SEBI LODR Regulations during the quarter ended June 30, 2026. The non-compliance related to the composition of the Board of Directors (absence of a sufficient number of Independent Directors) and the constitution of the audit committee and nomination and remuneration committee.
- Structural constraint on board composition: As a Central Public Sector Enterprise under the Ministry of Ports, Shipping and Waterways, the power to appoint Directors vests with the Government of India, which the company cited in explaining the non-compliances.
- General business and market risks: Fluctuations in earnings, the ability to manage growth and competition, risks and uncertainties associated with forward-looking statements, and general investment risks in securities.
- Execution and integration demands: The company is pursuing a large multi-year expansion program spanning new units, brownfield capacity additions, joint ventures, and a new hybrid shipyard, alongside acquisitions and technology investments.
Tailwinds and Growth Prospects
- Order book: A strong order book position of approximately Rs. 21,900 Crs.
- Capacity expansion: Strategic expansion including 7 new units by 2024, and brownfield expansions adding up to 150,000 CGT delivery capacity, with Rs. 4,100 Crs. for shipbuilding infrastructure and Rs. 2,420 Crs. for shiprepair clusters planned from 2025-30.
- Ship repair joint venture with DDW Dubai: CSL approved forming a 50-50 joint venture with Drydocks World - Dubai FZCO through a private limited company. The JV will own, operate, and manage the International Ship Repair Facility (ISRF) at Willingdon Island, Kochi, transferred on a slump sale basis as a going concern for not less than Rs. 1,800 Crores (50% cash and 50% shares). The ISRF was constructed at Rs. 970 Crores, reported Rs. 207.33 Crores in revenue for FY 2025-26 (4.81% of CSL’s total operational revenue), and has an independent valuation of Rs. 1,800 Crores (30.55% of CSL’s net worth). The JV board will have five directors (three nominated by DDW and two by CSL).
- Expected JV benefits: Leveraging complementary strengths, creating synergies, adopting global best practices, advanced technologies and efficient processes in the domestic ship repair ecosystem, improving quality, efficiency and turnaround time, augmenting ship repair capacity, strengthening domestic infrastructure, enhancing India’s capability to undertake complex and high-value projects, and alignment with Maritime India Vision 2030 and Maritime Amrit Kaal Vision 2047 while supporting Aatmanirbhar Bharat.
- Other growth initiatives: The Vadinar Ship Repair Cluster in Gujarat, the CSL Tutoorin Hybrid Shipyard development (110.14 acres land and 17.29 acres water front), investment in marine electrification technologies via a JV with HBL, and acquisition of a 23% stake in Conoship International Holding B.V., Netherlands.
- Governance remediation: The Ministry of Ports, Shipping and Waterways appointed Dr. Vani Ahluwalia as a Non-official (Independent) Director on August 17, 2026, after which the audit committee and nomination and remuneration committee were duly constituted in line with SEBI LODR Regulations.
Key Risks
- Regulatory and compliance risk: The fines imposed by BSE and NSE for the quarter ended June 30, 2026, and the possibility that waiver requests may not be granted. The company stated the non-compliances were not due to its negligence and plans to file requests for waiver as per the extant Policy for Exemption of Fines.
- Dependence on government action: Board composition and director appointments rest with the Government of India, which contributed to the compliance lapse.
- Earnings volatility and competition: Fluctuations in earnings and the ability to manage growth and competition.
- Forward-looking statement uncertainty: Risks and uncertainties associated with forward-looking statements.
- General securities investment risk.
- Execution risk on expansion: The brownfield expansion projects are planned for 2025-30, the CSL Tuticorin Hybrid Shipyard phases are planned up to December 2027, and the DDW Dubai joint venture is expected to be implemented before the end of the financial year, with the Joint Venture Agreement proposed to be signed on September 11, 2026 and other agreements signed upon incorporation of JVCo and receipt of requisite approvals.
Management Guidance Versus Observed Business Performance
- JV implementation timeline: Management expects the DDW Dubai joint venture for the Kochi Ship Repair Cluster to be implemented before the end of the financial year, with the Joint Venture Agreement proposed for signing on September 11, 2026. Observed performance: the ISRF reported Rs. 207.33 Crores in revenue for FY 2025-26, 4.81% of CSL’s total operational revenue, and has an independent valuation of Rs. 1,800 Crores, 30.55% of CSL’s net worth.
- Expansion timelines: Brownfield expansion projects are planned for 2025-30, and CSL Tuticorin Hybrid Shipyard phases are planned up to December 2027. No completed performance against these timelines is provided in the material.
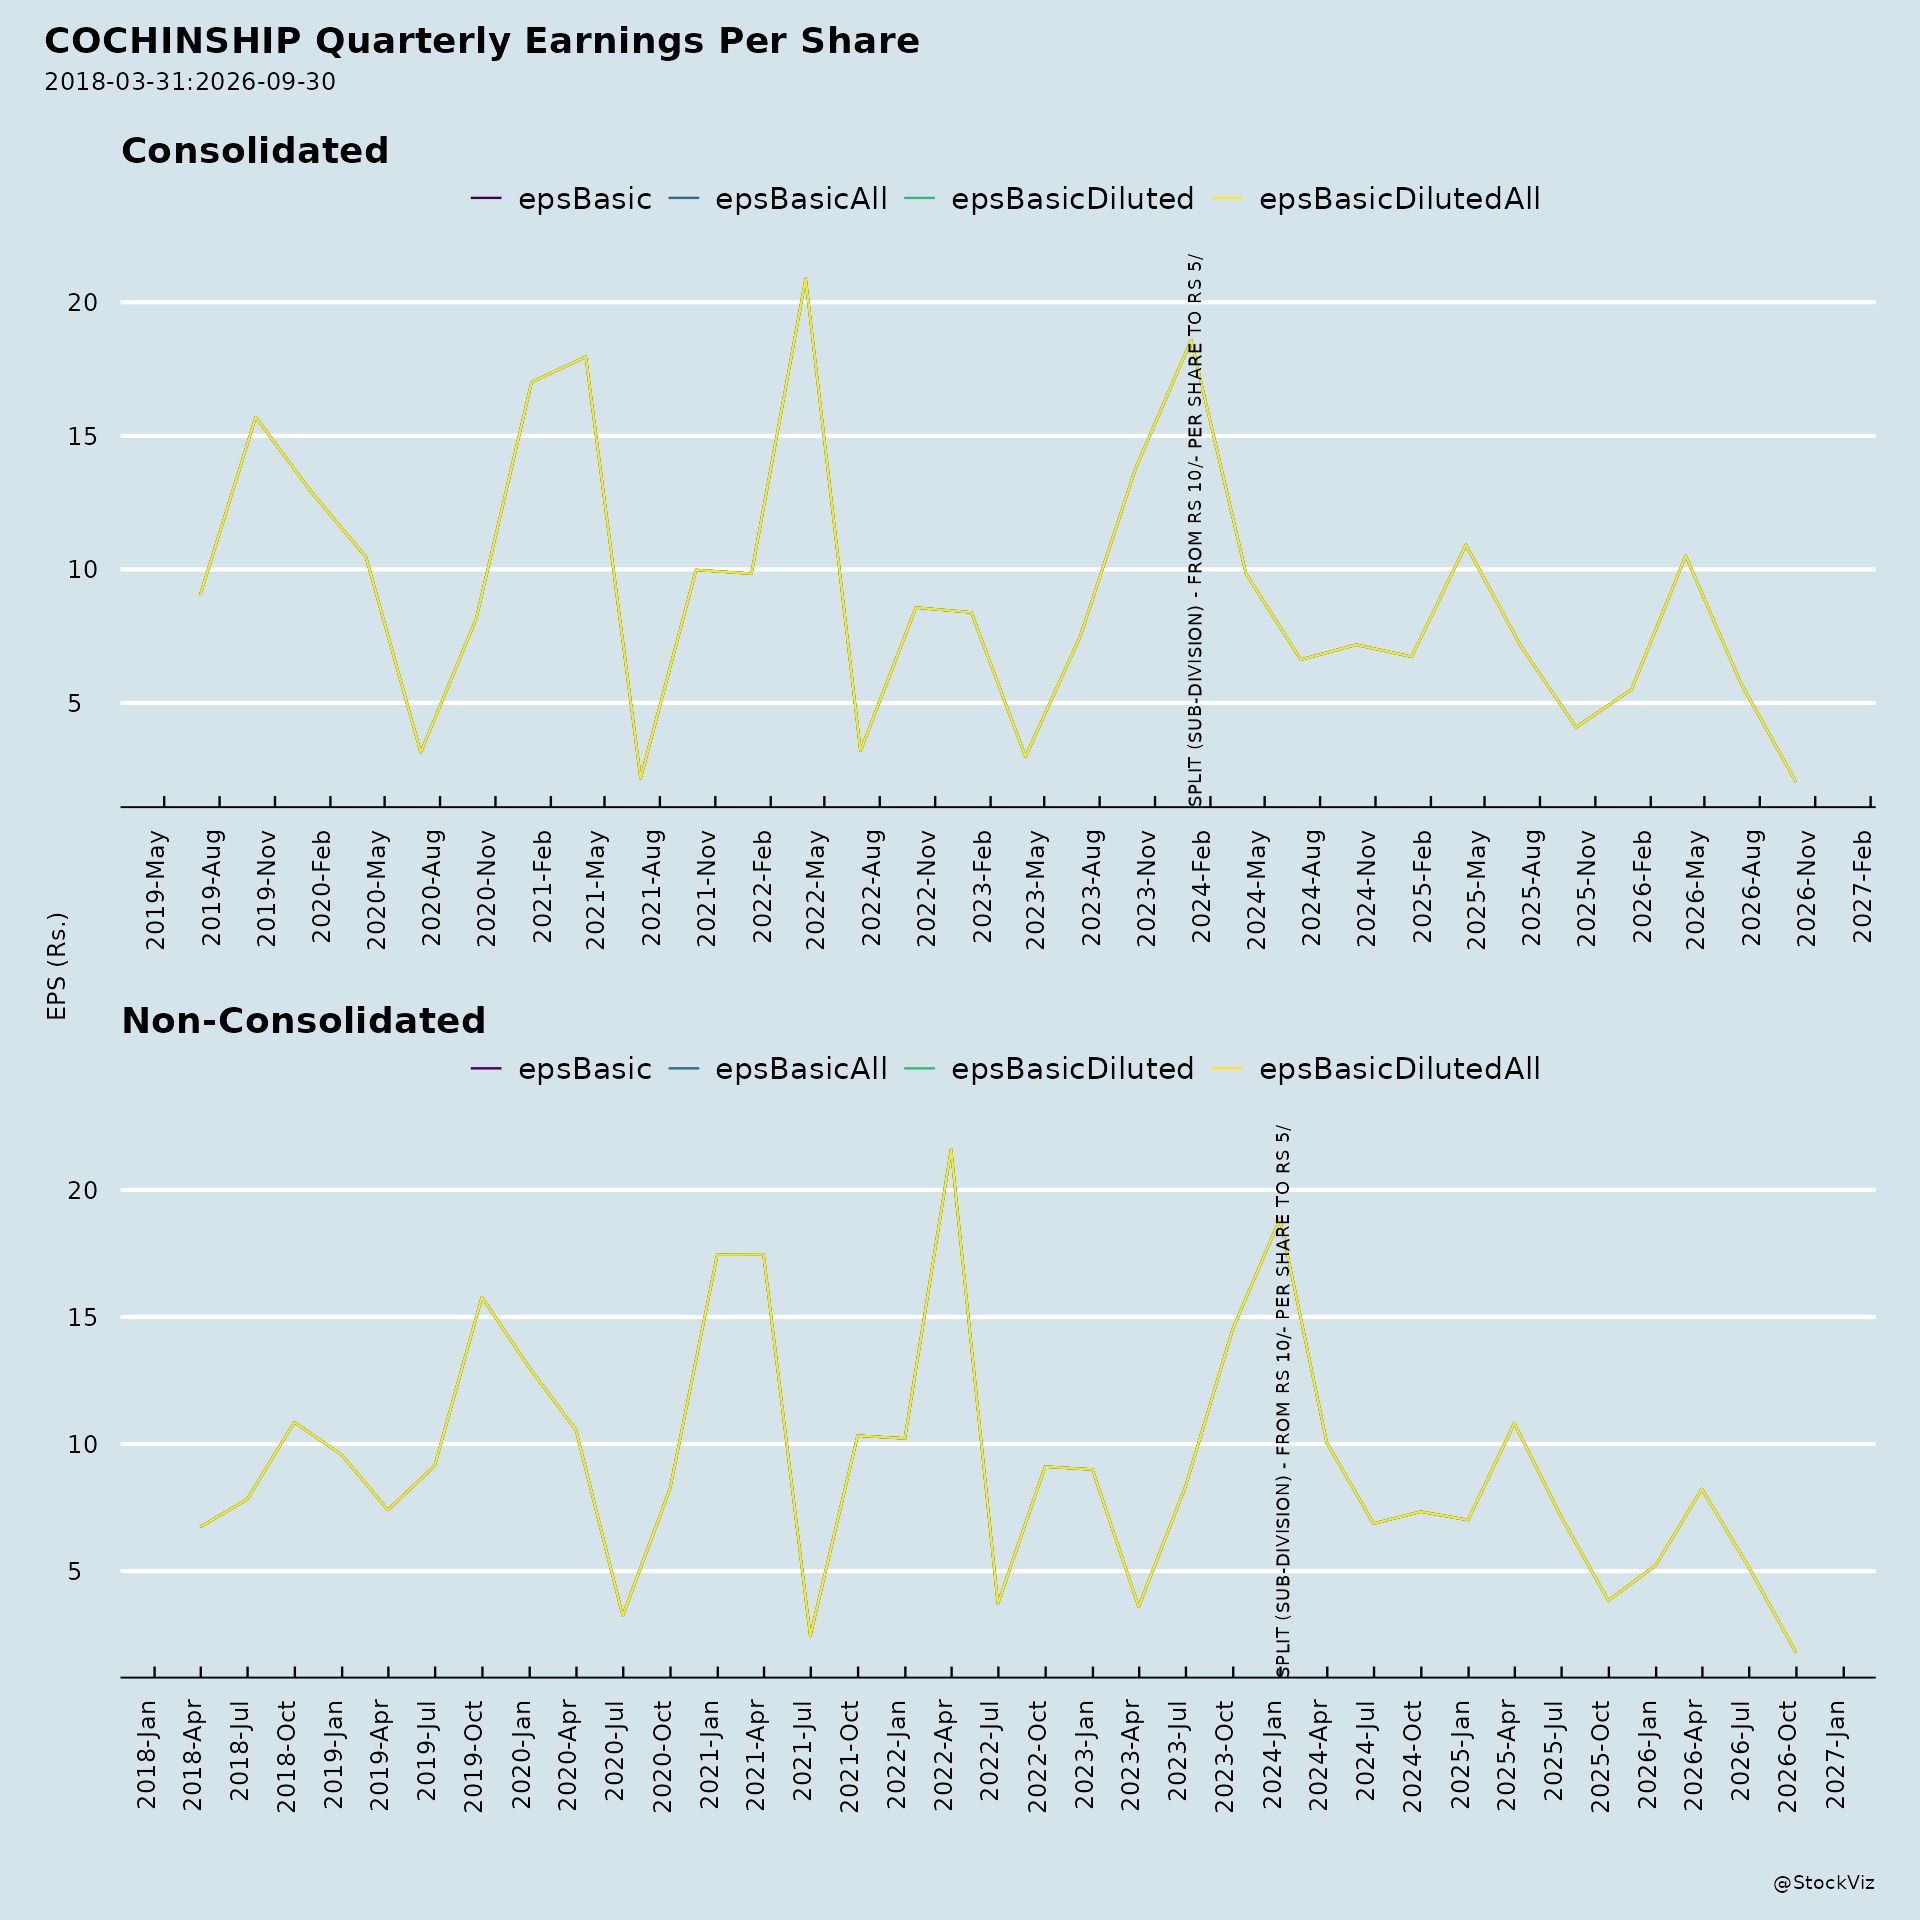
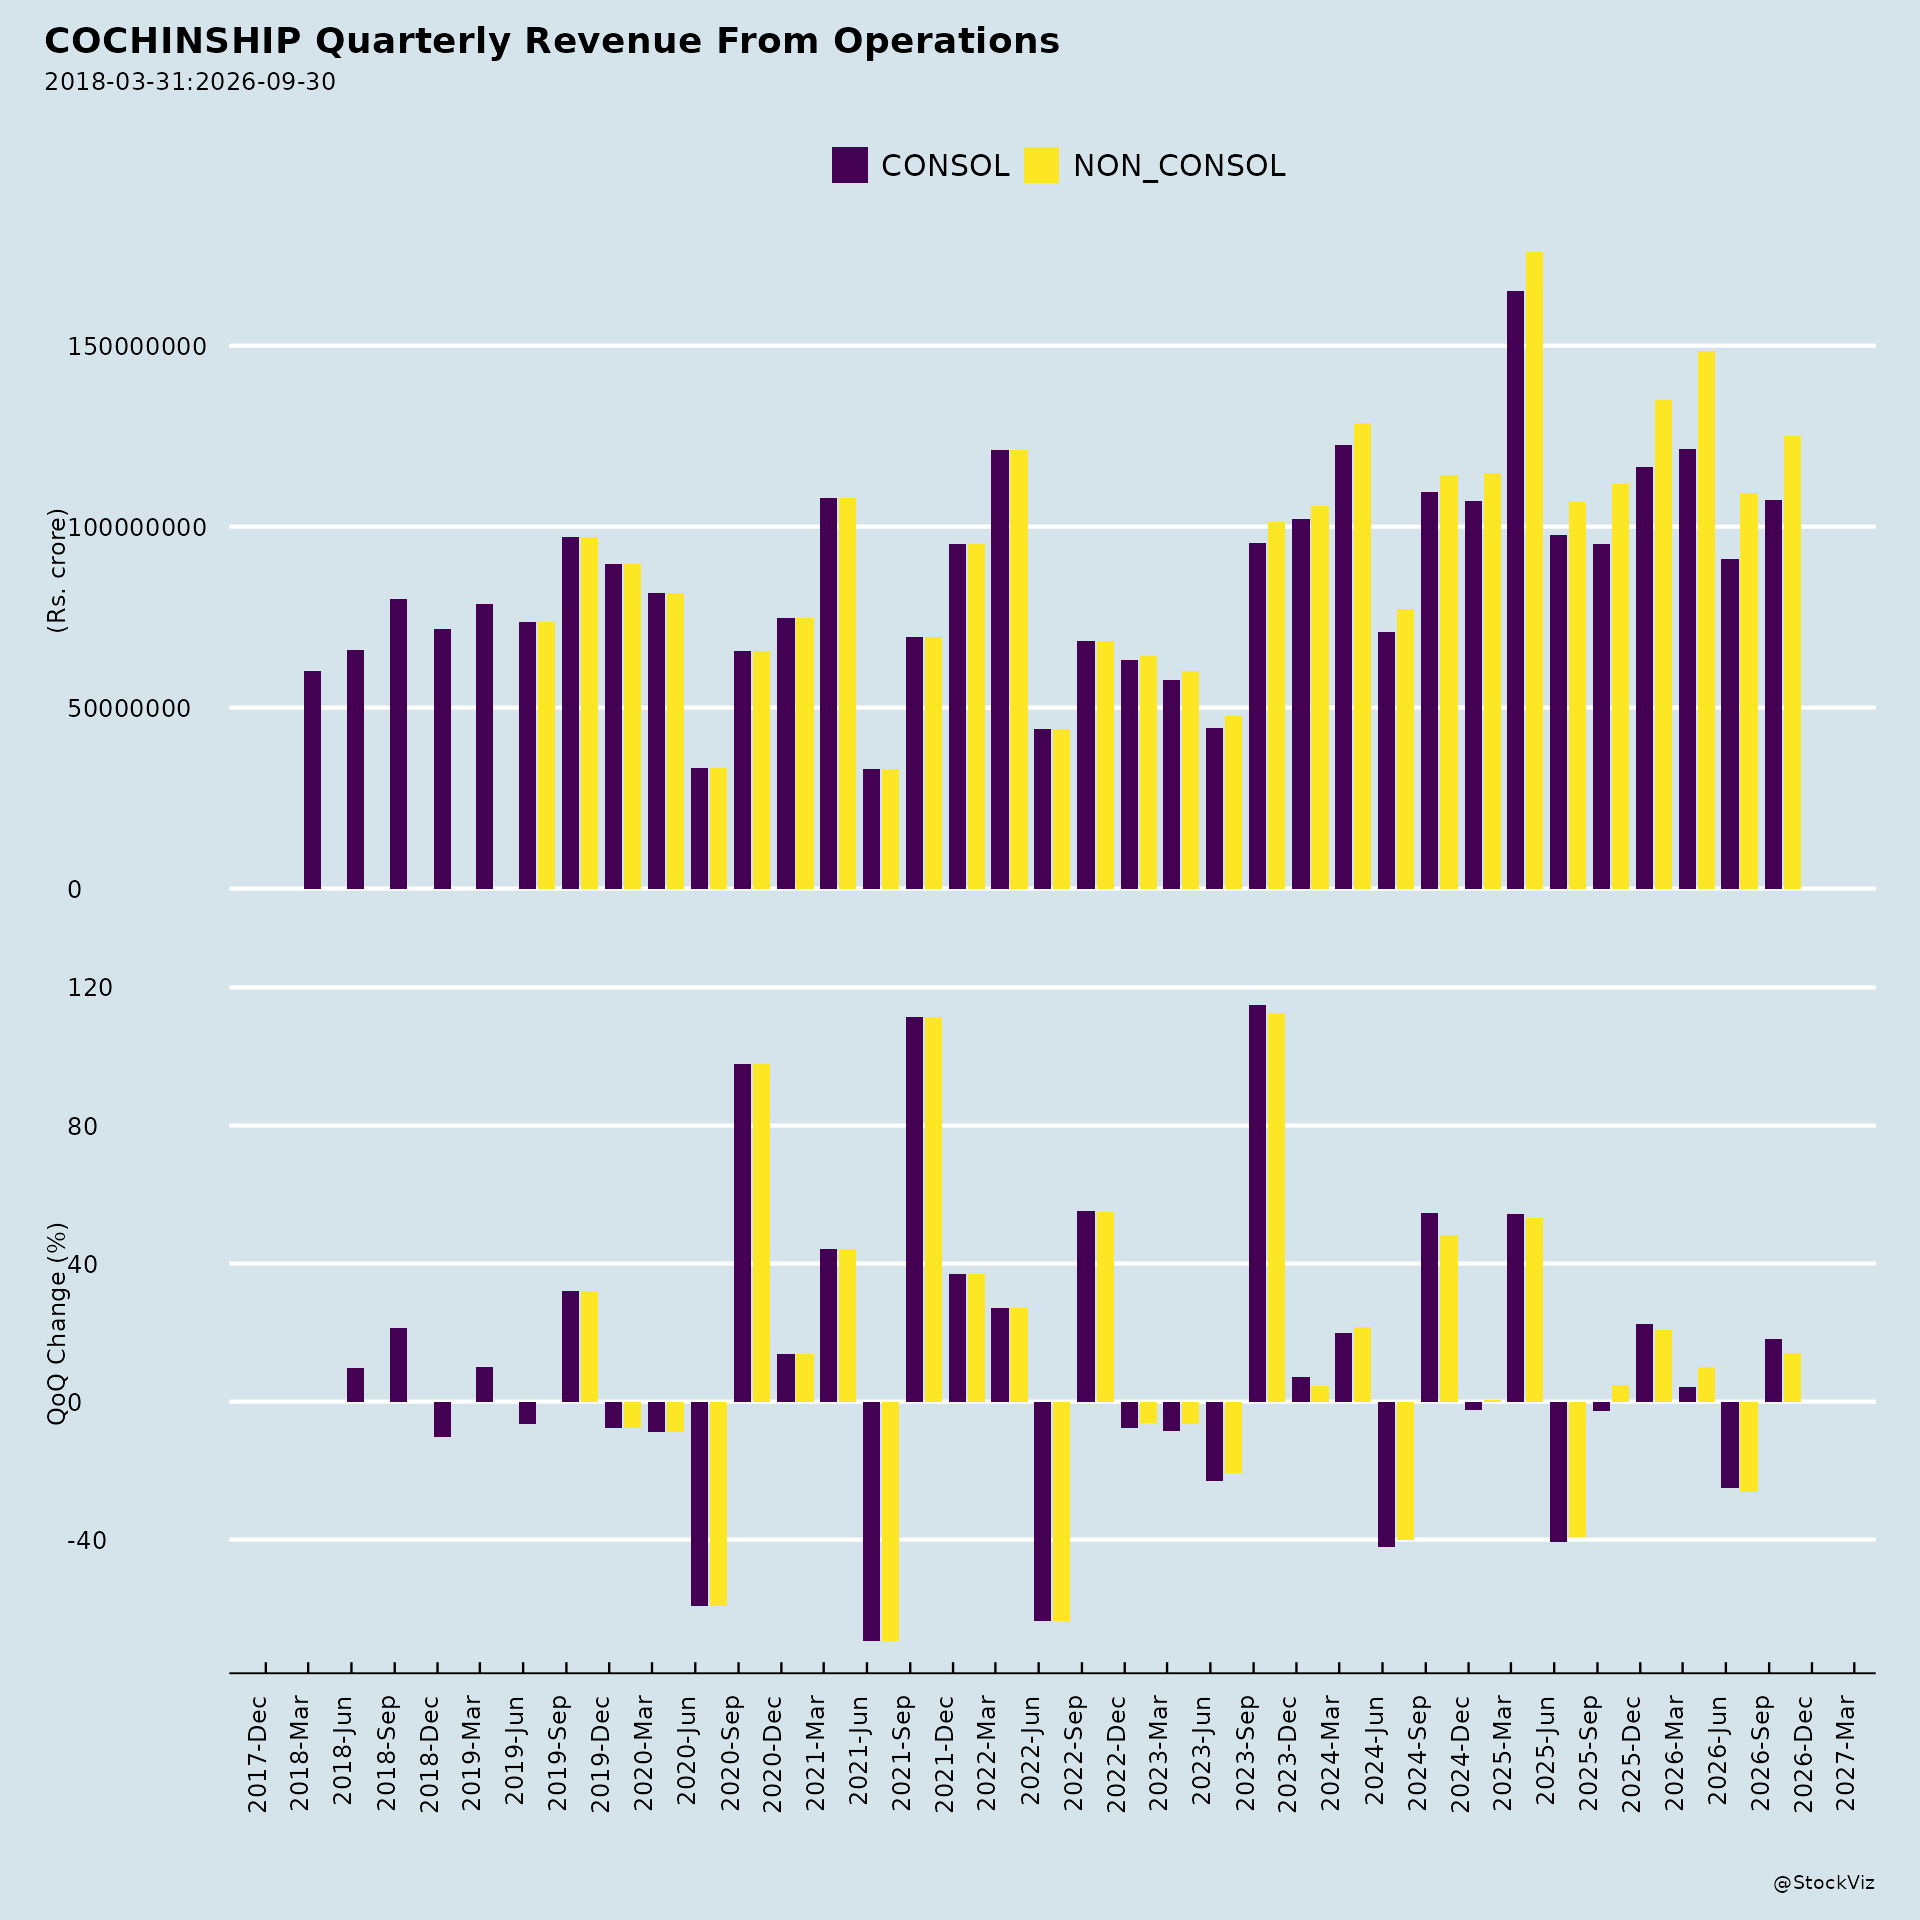
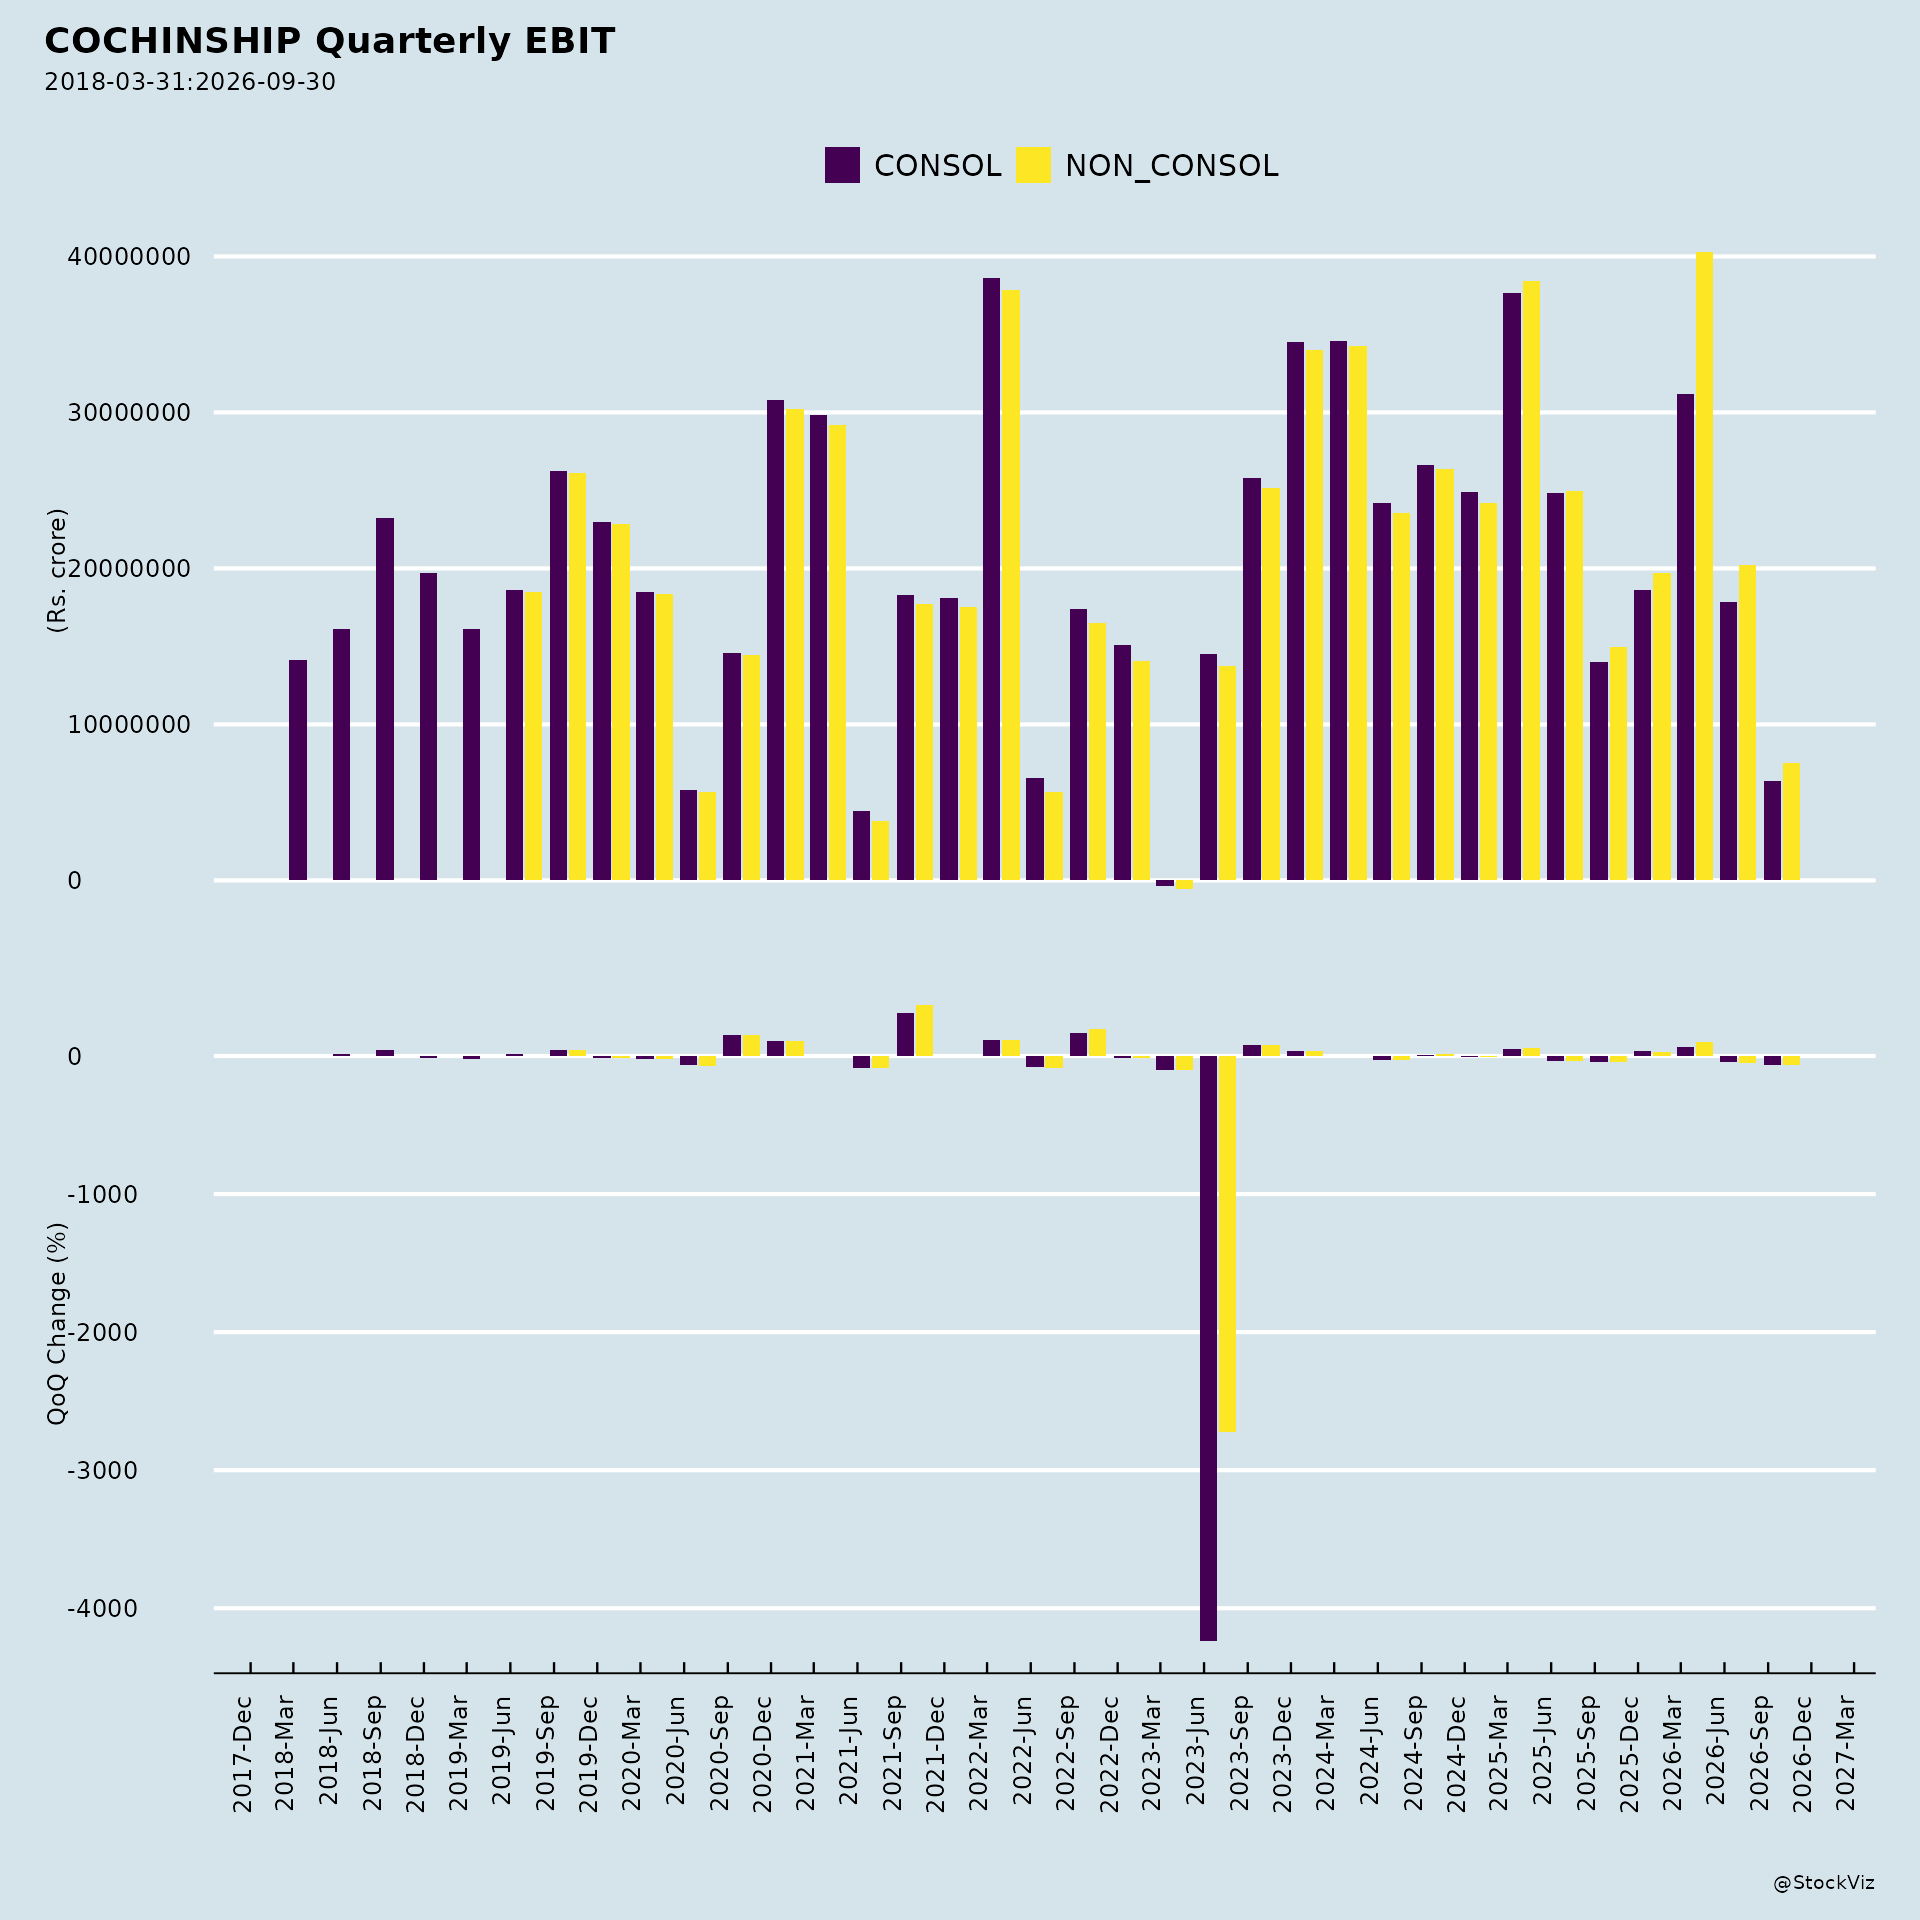
- Financial performance: For FY26, total revenue reached Rs. 5,021 crores, EBITDA was Rs. 1,221 crores, and PAT was Rs. 716 crores. The company has an estimated turnover of about USD 600 Million (Rs. 5000 crores).
- Investor communication: The audio recording of the investor and analyst conference call held on September 10, 2026, at 02:00 PM to discuss the company’s performance and business updates has been uploaded to the company’s website, and the transcript will be submitted in due course. Management guidance on the call is not available in the material beyond the statement that the transcript will be submitted in due course.
- Dividend and governance actions: The 54th Annual General Meeting is scheduled for Tuesday, September 29, 2026, at 11:00 hrs. IST through video conferencing or other audio visual means, with key items including adoption of audited financial statements, confirmation of interim dividends and declaration of a final dividend of ₹1.50 per equity share, appointment and regularization of directors including Shri Mukesh Mangal ITS and Smt. Anupama T. V. IAS as Part-time Official (Nominee) Directors, appointment of Dr. Vani Ahluwalia as a Non-official (Independent) Director, and ratification of the remuneration of M/s. BBS & Associates as Cost Auditors.
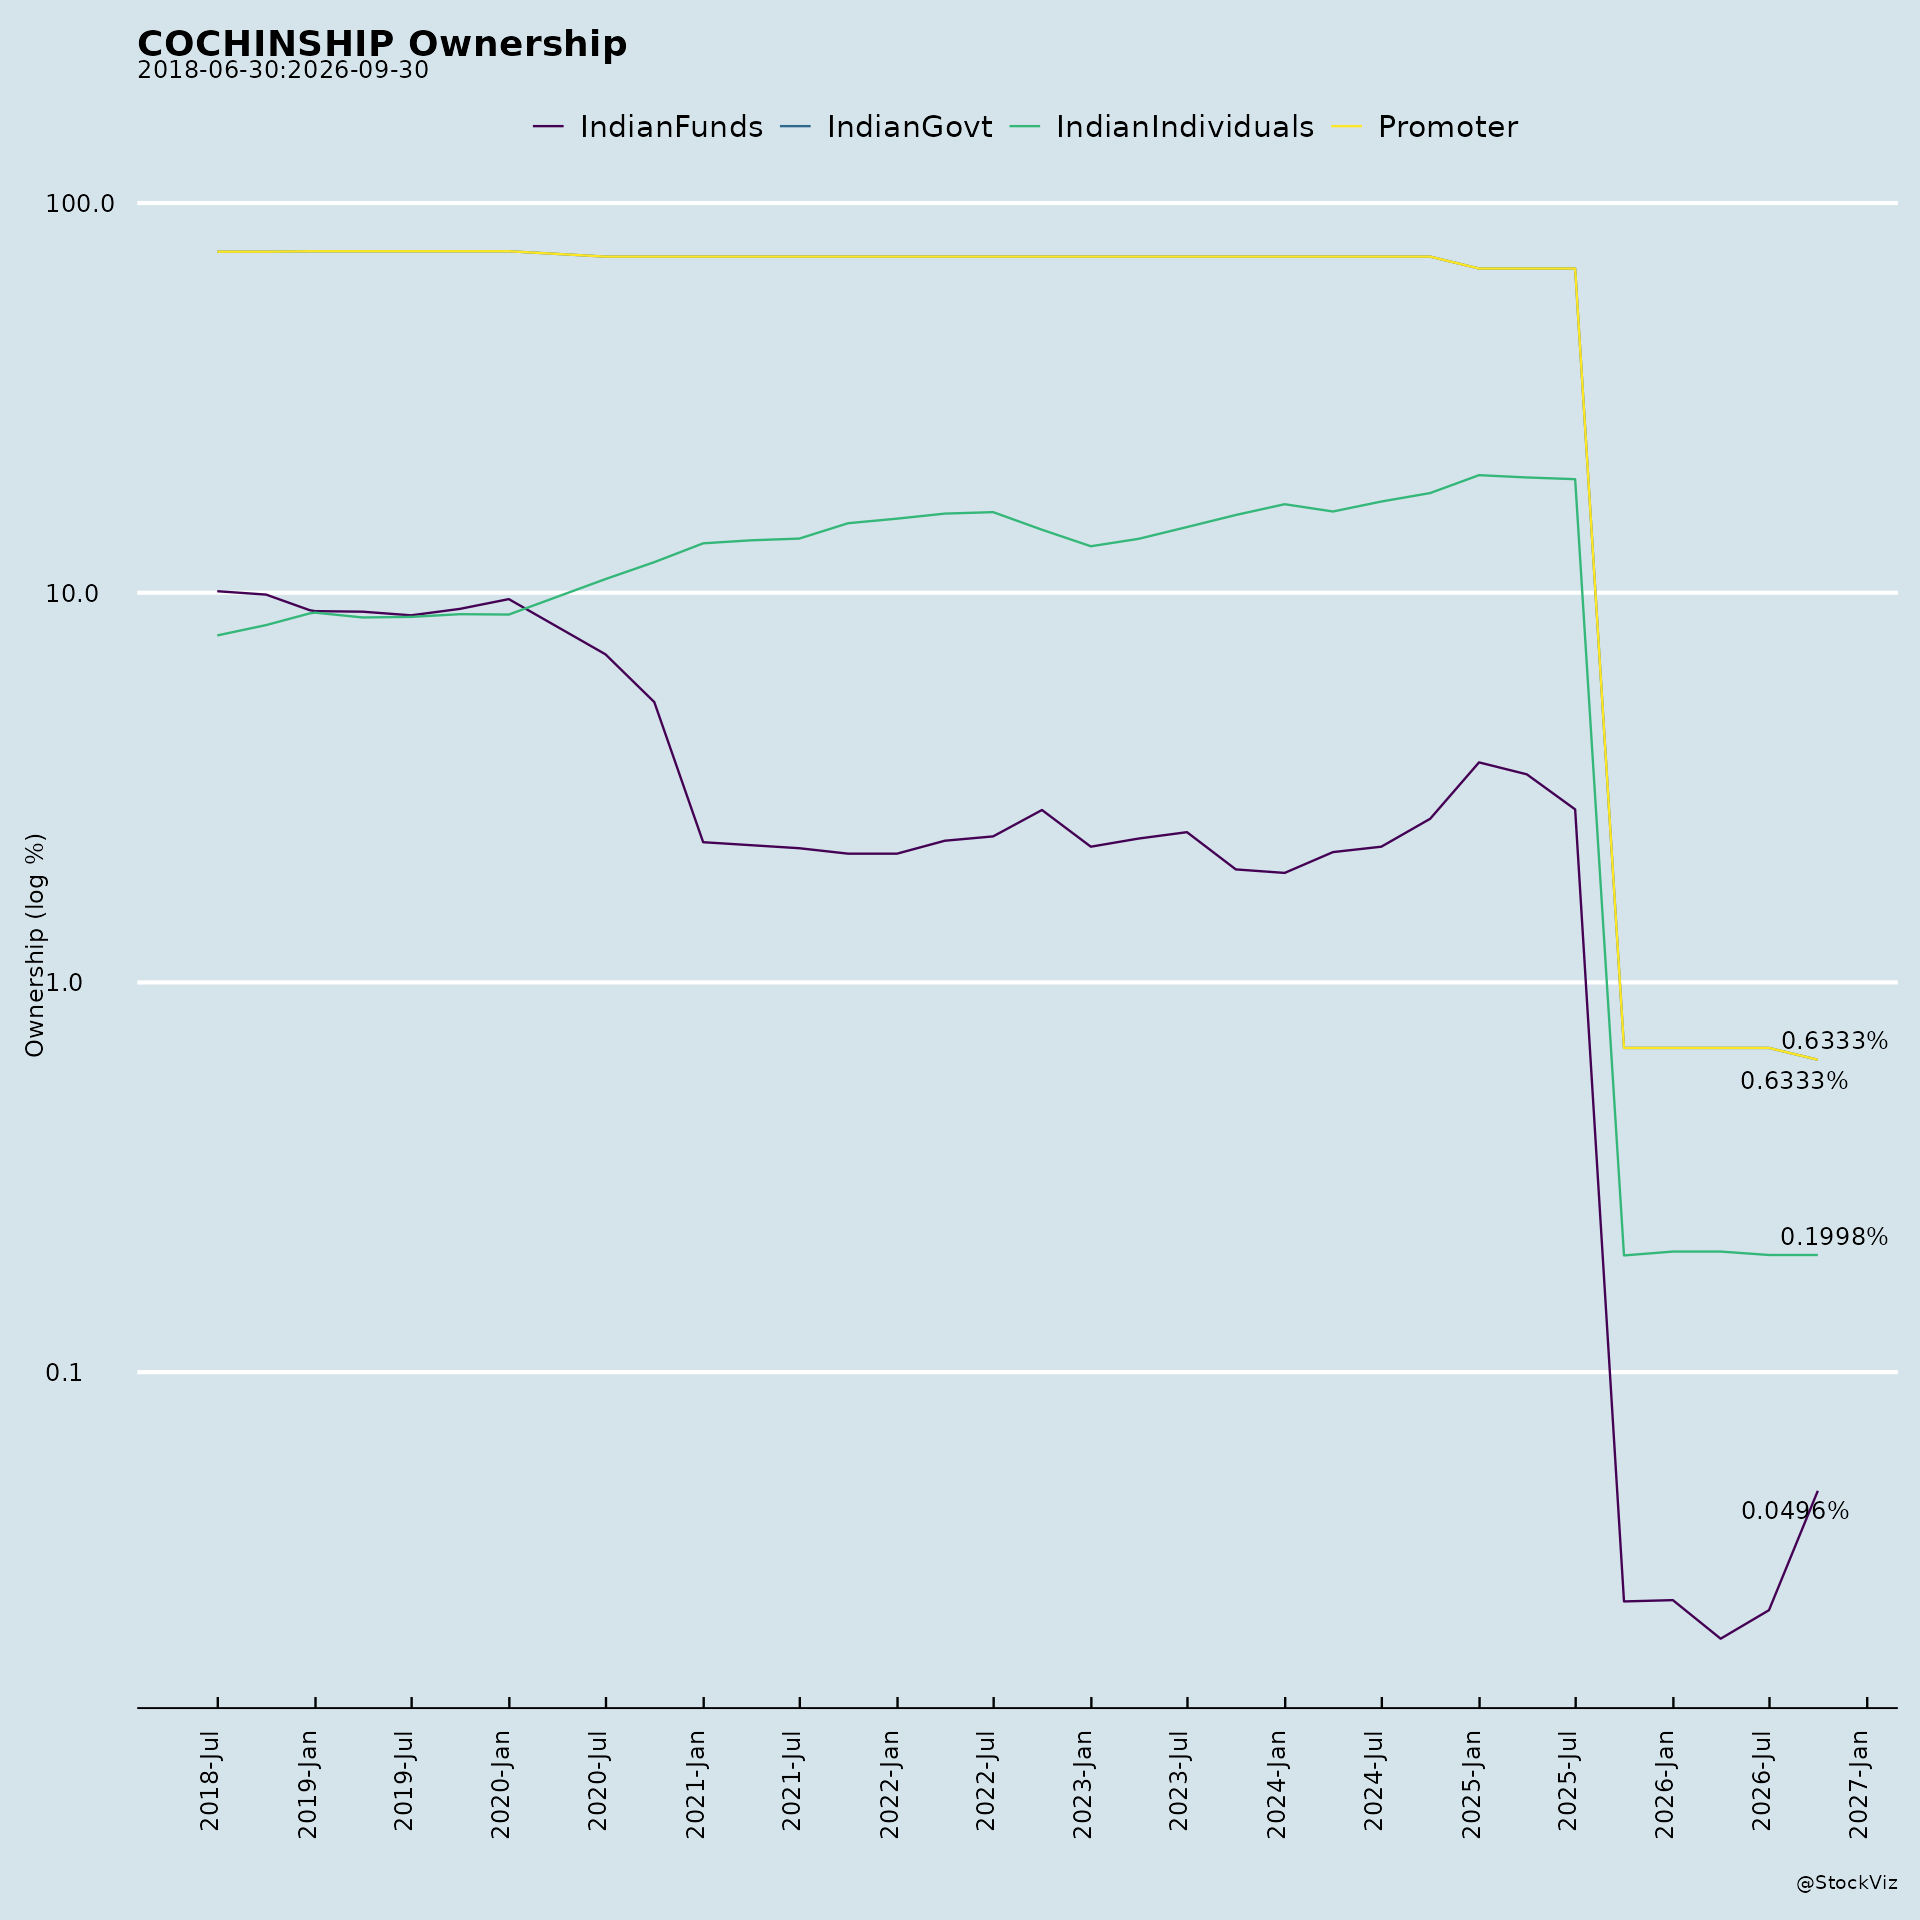
- Capital markets history: CSL has been listed on BSE and NSE since August 2017, with a shareholding structure of 63.33% by the Government of India and 36.67% by the public (~10 lakh shareholders). Its IPO market cap in August 2017 was approximately Rs. 6,000 Cr., with a present market cap of around Rs. 40,500 Cr. Corporate actions post-IPO include a buyback of Rs. 200 Cr. in December 2018 and a share split of 1:2 in January 2024.
Broker Narrative
The narrative began with a high-conviction Buy built on a ₹22,132 Cr backlog (9.3x FY23 revenue), defence orders, dry-dock capacity, and green-vessel export optionality, while flagging execution, design, and supply-chain delays. By 2026, the backlog, dry-dock/ISRF, and ship-repair themes persisted, but the emphasis shifted to uneven execution, shipbuilding margin compression, lower other income, and higher interest cost; the intervening Hold and final Buy both failed to produce positive returns.
Fears that came true
- Execution delays and revenue shortfalls flagged in 2023 materialized as ‘uneven project execution’ in the 2026-11-11 report, which coincided with a -2.0% actual return and DISAPPOINTMENT.
- The early warning that gross margins had contracted and EBITDA turned negative presaged the later ‘sharp decline in gross margin as material expenses increased,’ again tied to the disappointing Buy outcome.
Optimism that failed
- The robust order book/revenue-visibility thesis did not protect against margin pressure and a -2.0% return; backlog coverage fell from 9.3x FY23 revenue to 4.4x FY26 revenue.
- The 2023 green-vessel replacement/export opportunity was not carried forward as a driver in the 2026 reports and did not emerge as a return catalyst.
Broker Timeline
3 broker calls · 2023-06-01 to 2026-11-11
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.