COALINDIA
Equity Metrics
September 24, 2026
Coal India Limited
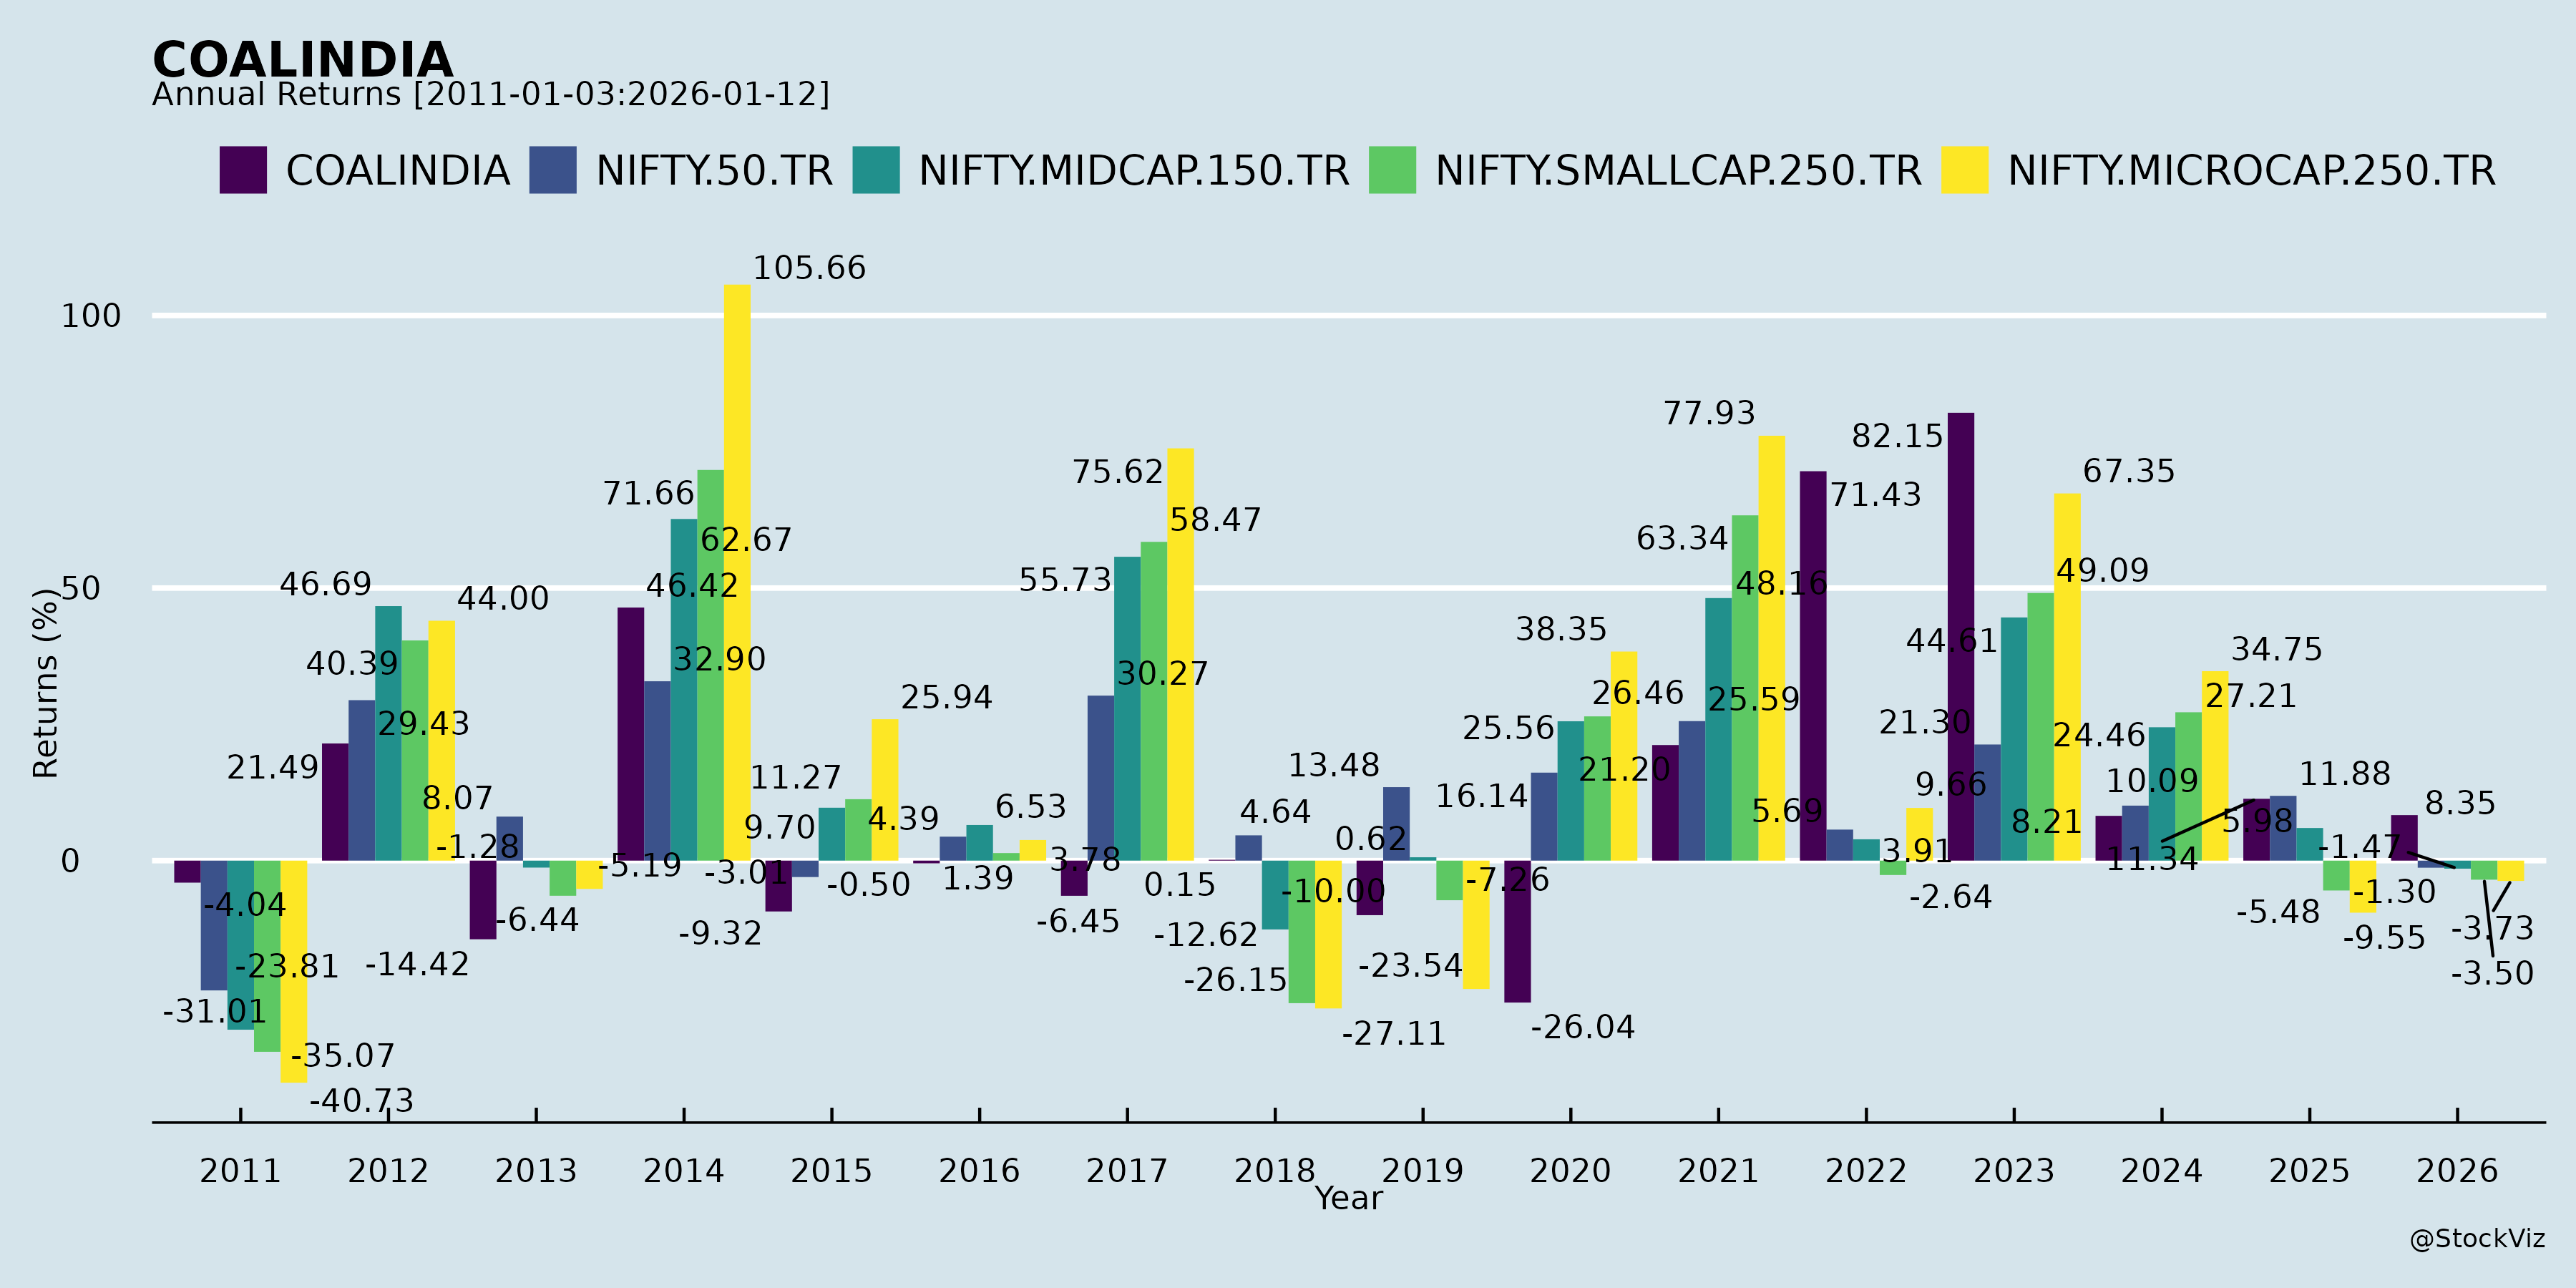
Annual Returns
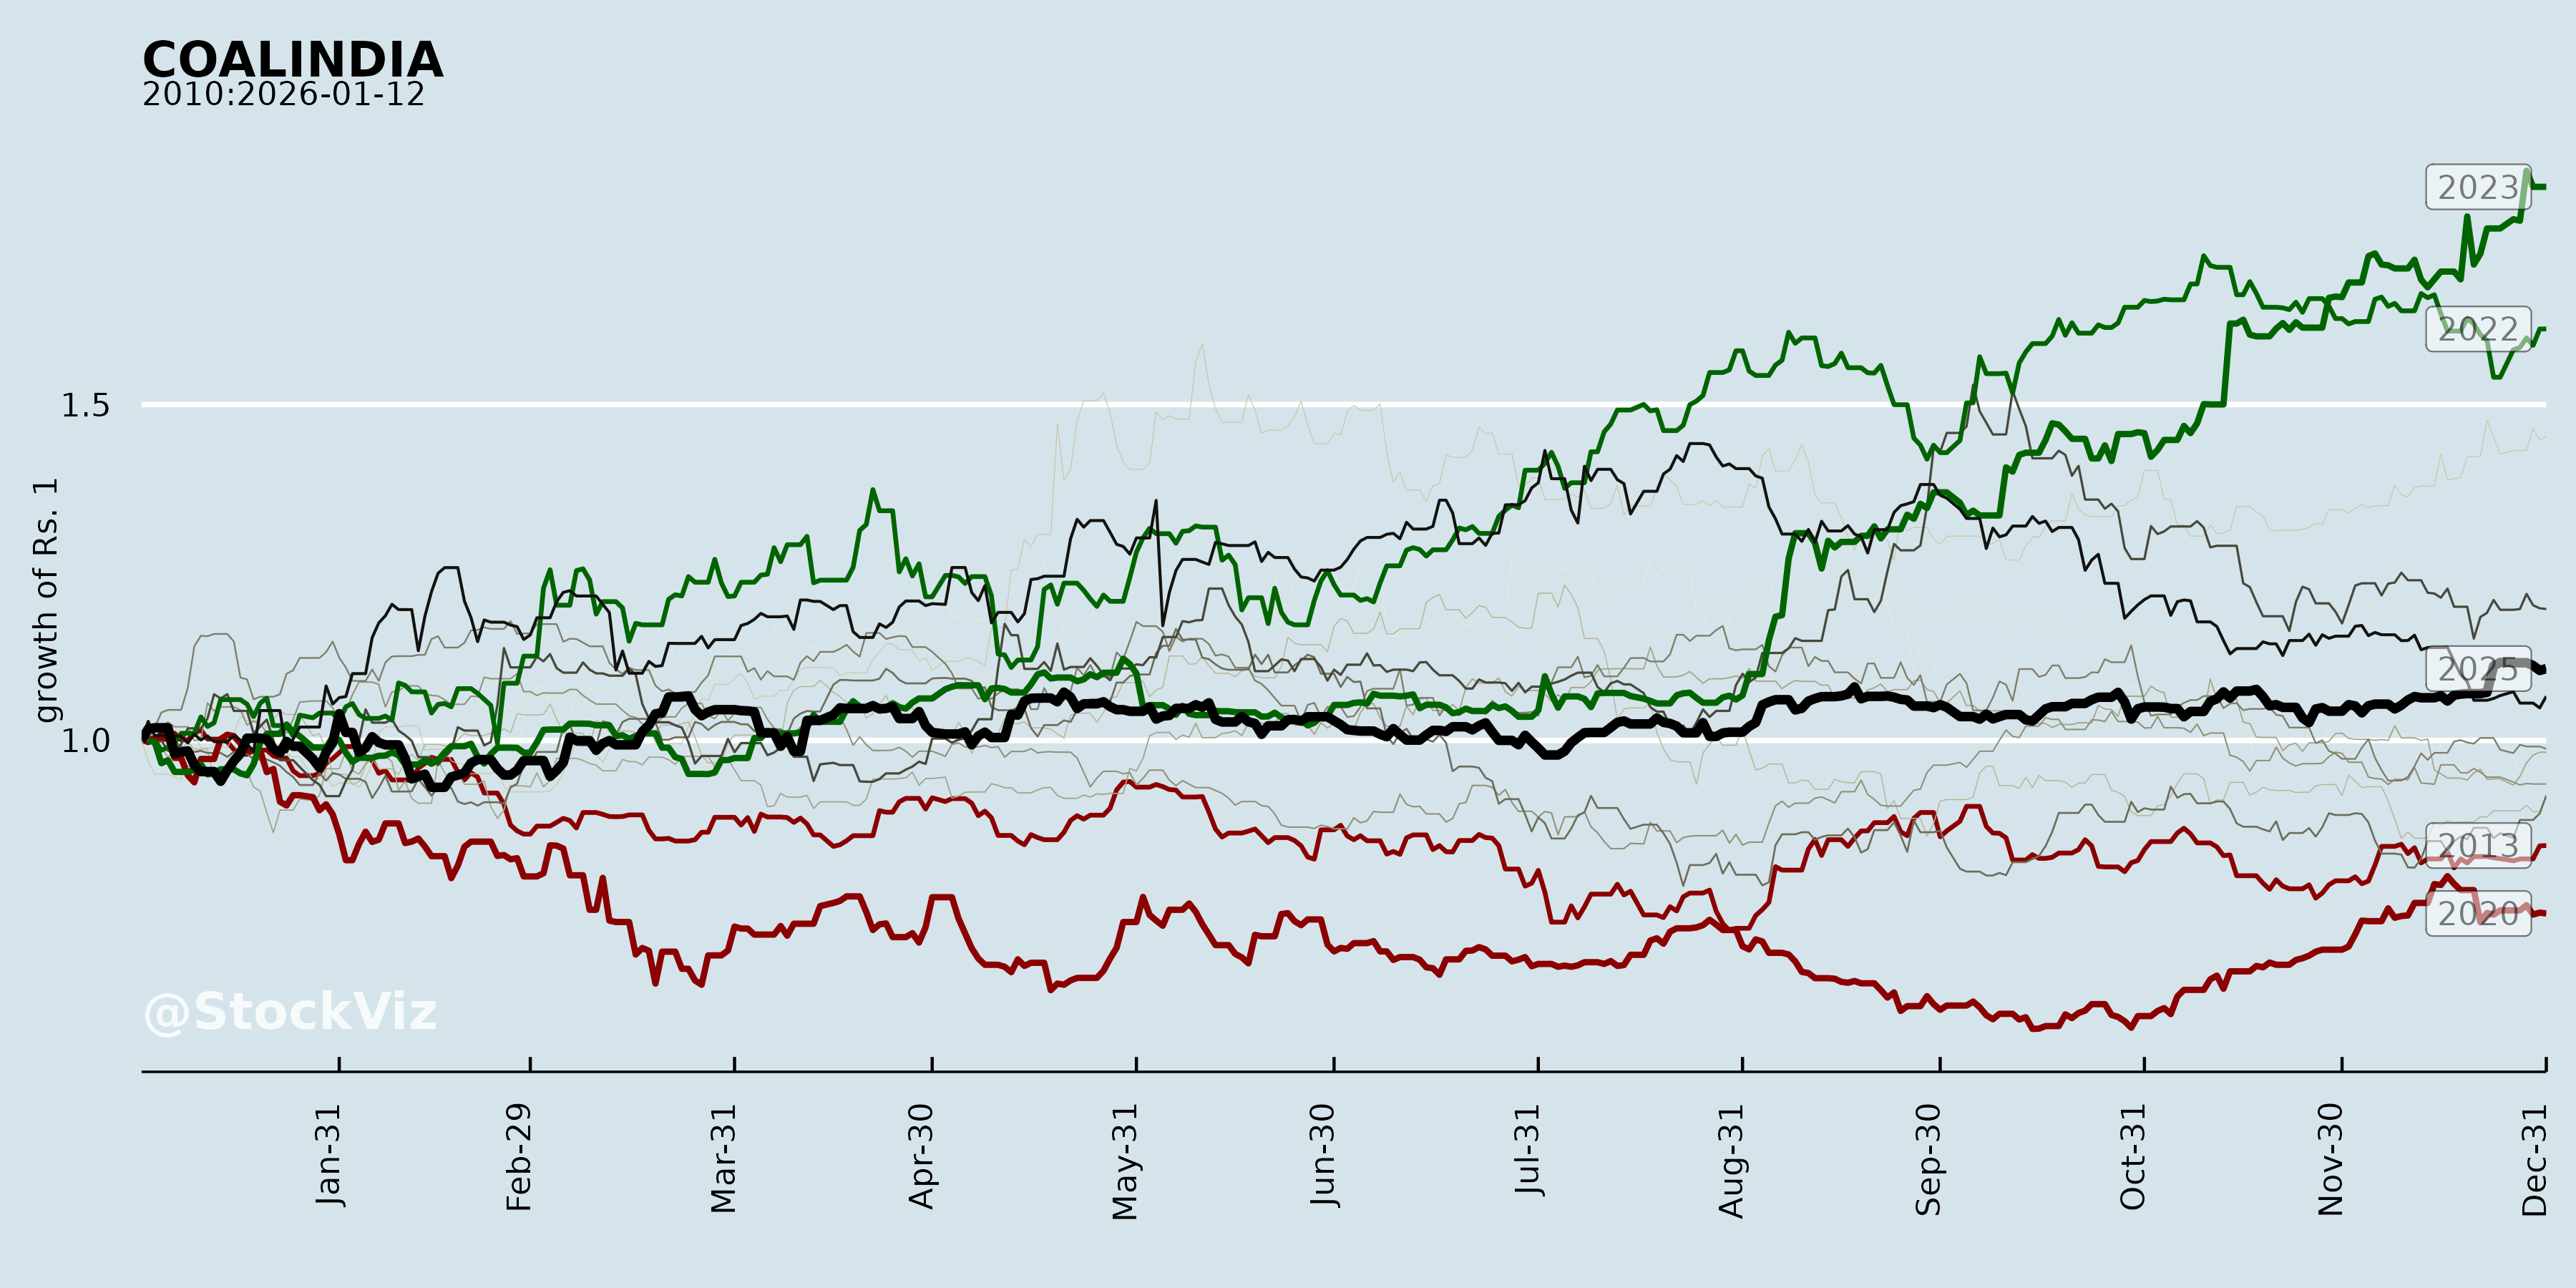
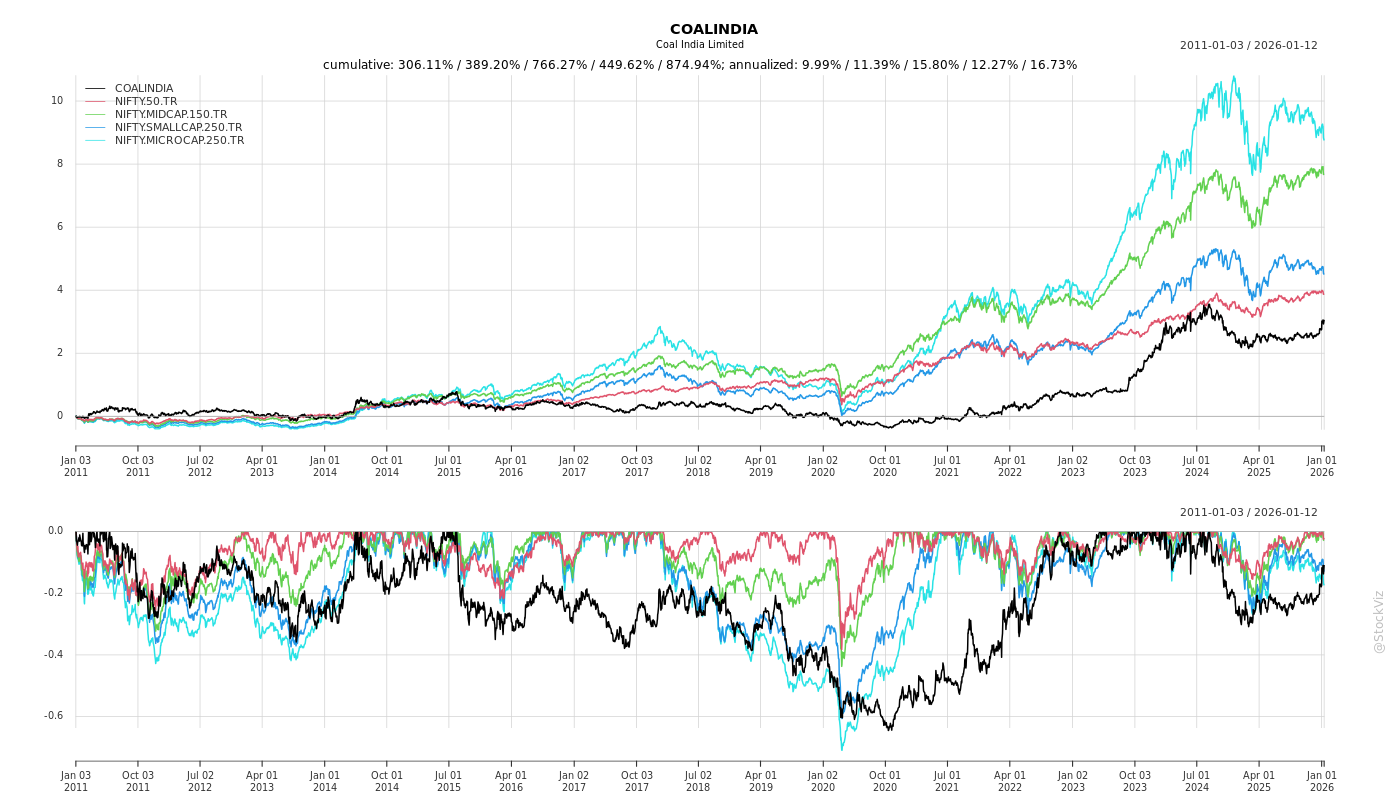
Cumulative Returns and Drawdowns
Fundamentals
Ownership
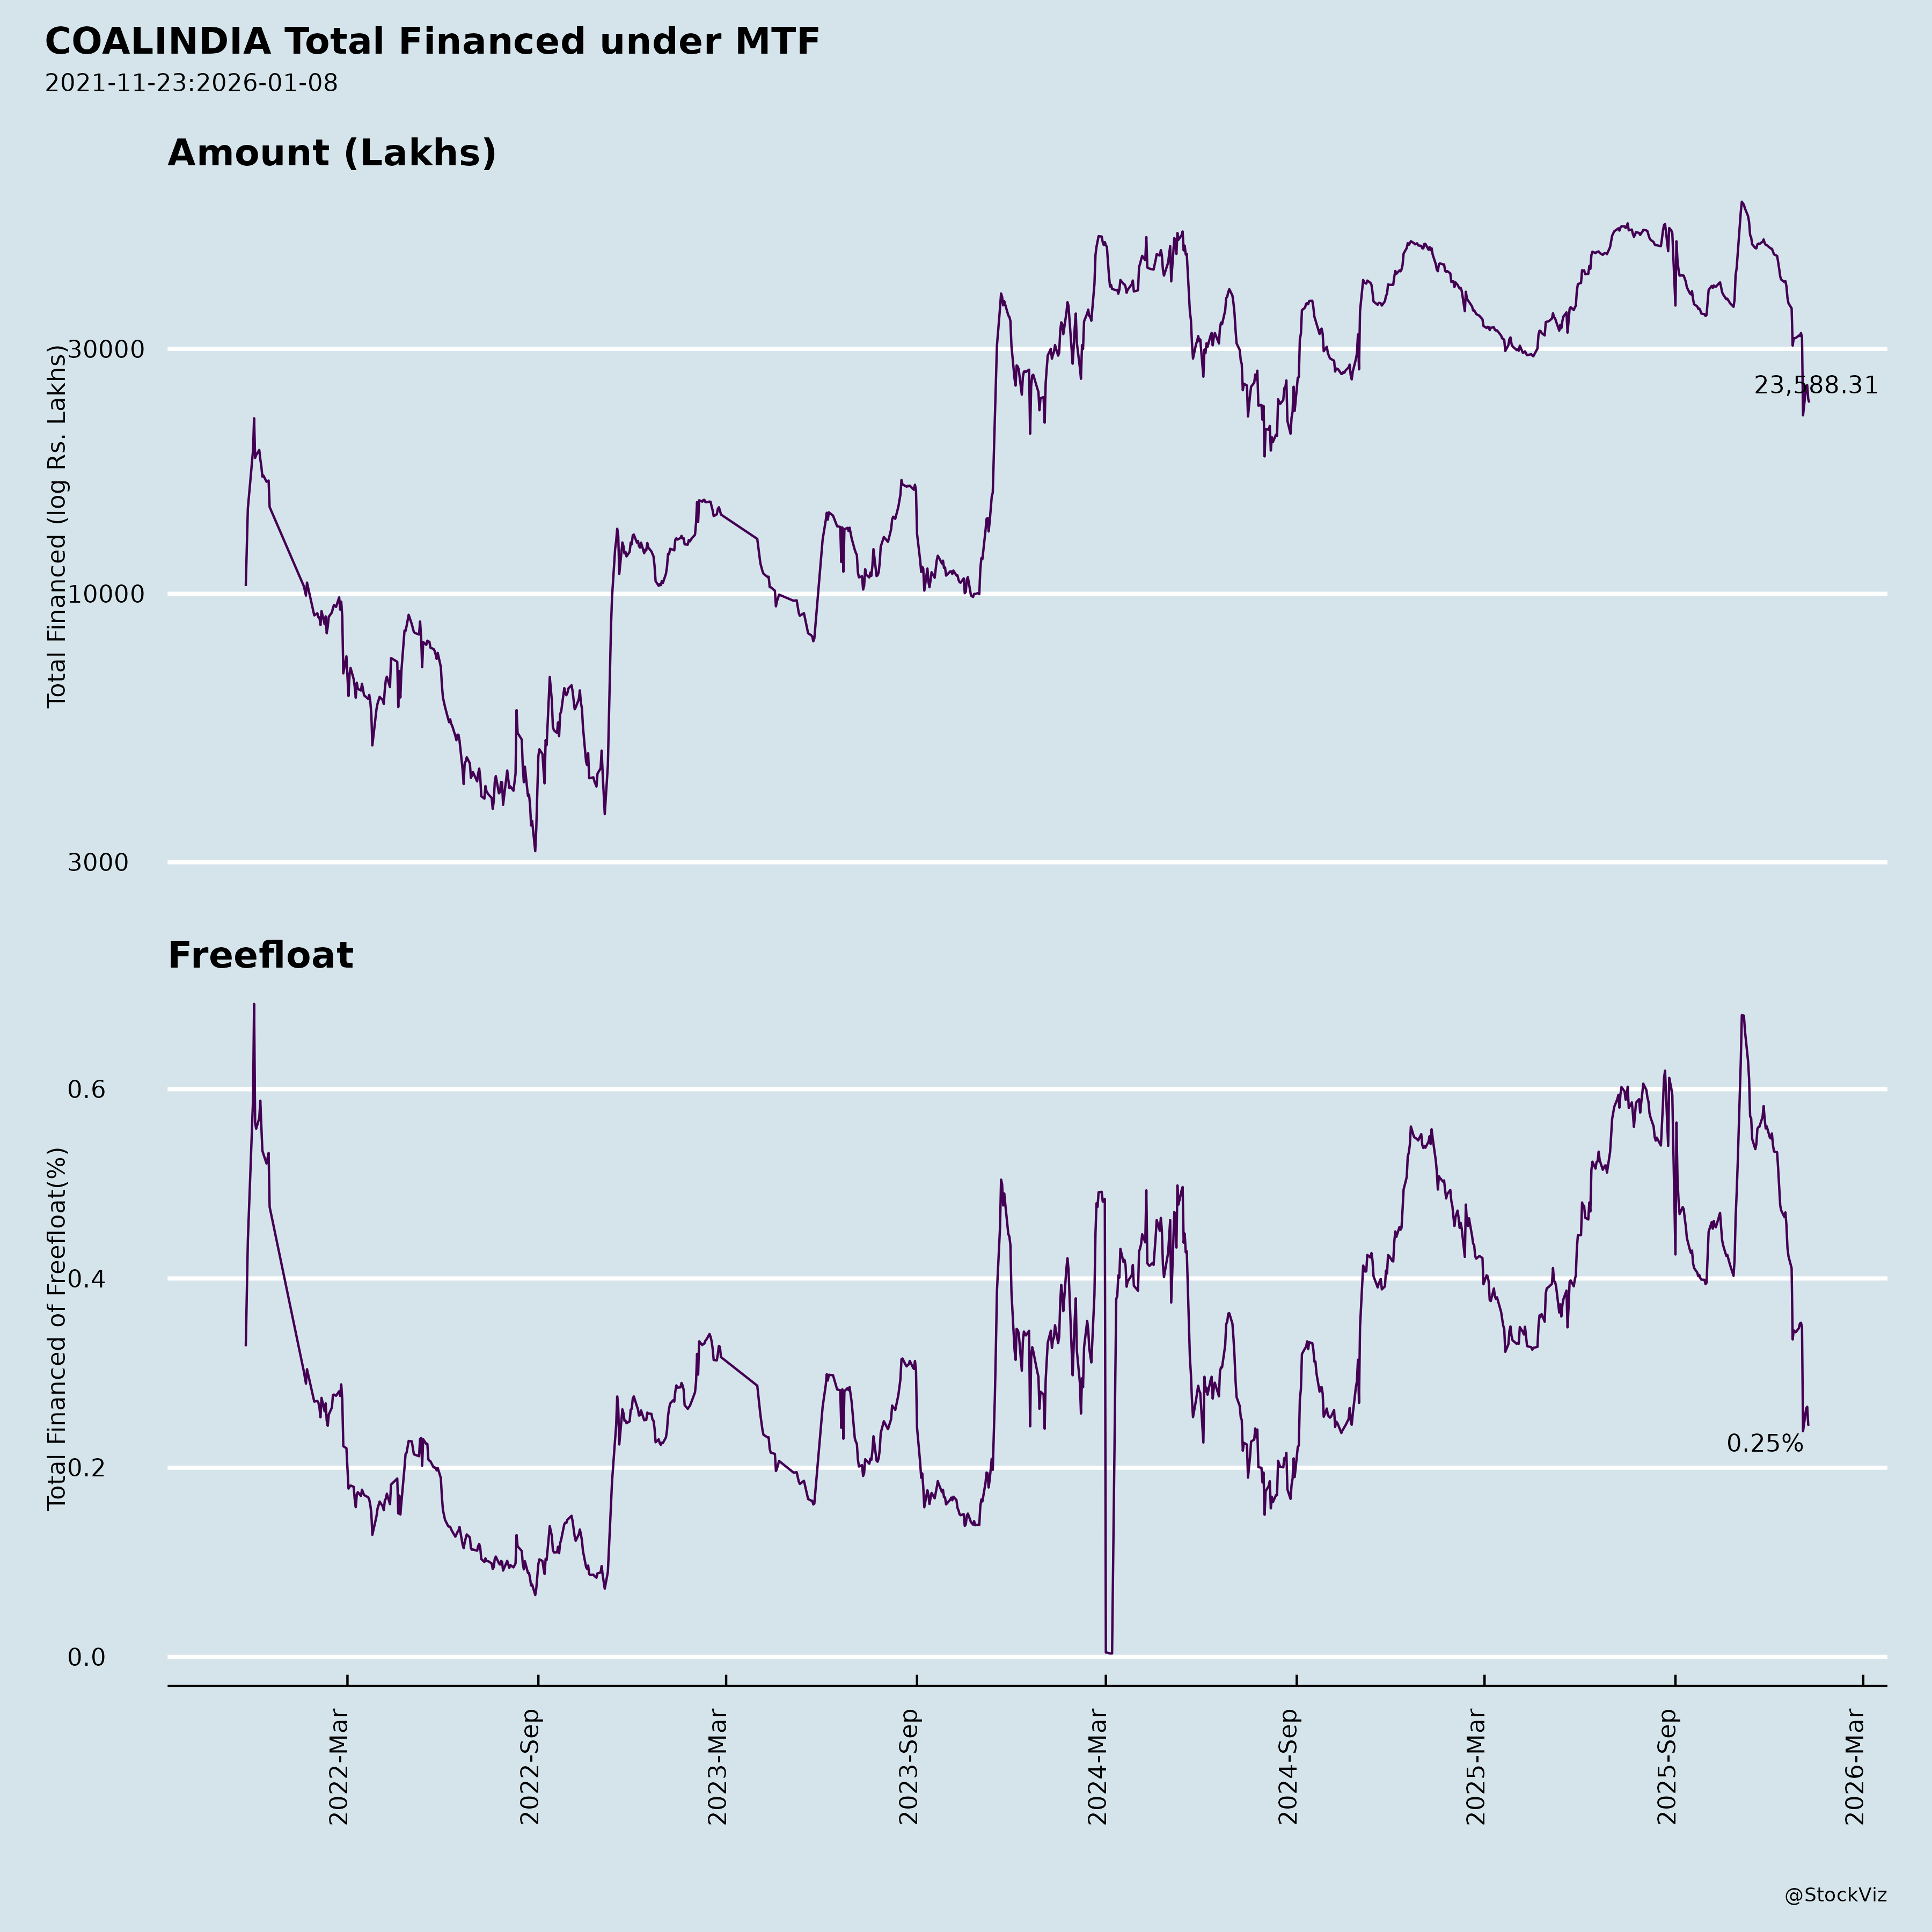
Margined
AI Summary
asof: 2026-09-14
Coal India Limited — Recent Corporate Announcements: Headwinds, Tailwinds, Risks, and Guidance
1. Headwinds and Challenges
Monsoon-related operational disruption. Heavy rainfall and monsoon conditions have created water accumulation and temporary disruptions in mine accessibility and coal movement. This constrained production and dispatch during the affected period.
Governance and compliance gaps flagged by auditors. The limited review reports note that, in the absence of the requisite number of independent directors, the composition of the Board and its sub-committees (including the Audit Committee and the Nomination and Remuneration Committee) was not in compliance with Sections 149, 177 and 178 of the Companies Act and Regulations 17, 18 and 19 read with Schedule II of the SEBI LODR Regulations, 2015. The auditors state this attracts penal provisions.
Subsidiary-level compliance issues. For SECL, the auditors report that TDS liability was neither deducted nor provided for on the reporting date, resulting in non-compliance with the Income Tax Act. SECL also did not raise invoices for performance incentive/compensation cases for State Generation Companies, which the auditors note may result in delayed receipt of payments, opportunity cost in terms of bank interest, GST-related interest penalties for late invoicing, and loss of revenue if buyers discontinue business.
Custodian mine legacy liability. SECL closed mining activities at Gare Palma IV/2 & IV/3 (custodian coal mines) from 21.04.2023 in compliance with a Ministry of Coal letter dated 21 April 2023. Against a Ministry of Coal demand of Rs. 2,880.89 crores relating to Gare Palma IV/1, IV/2&3 and IV/7 mines, SECL crystallized the payable amount at Rs. 513.75 crores, with the remaining Rs. 2,367.14 crores shown as a contingent liability.
Stripping activity provision overhang. The Group continues to carry forward a stripping activity provision balance of Rs. 55,728.17 crores as on June 30, 2026 (Rs. 56,503.61 crores as on March 31, 2026), which is being written back and credited to profit and loss in a systematic manner. Rs. 775.44 crores was written back for the quarter ended June 30, 2026 (Rs. 1,954.90 crores for the year ended March 31, 2026 and Rs. 540.62 crores for the quarter ended June 30, 2025).
Unconsolidated entities. Certain entities were not considered in consolidation: two CBM joint operations (CIL–ONGC at Jharia and Raniganj) for the period April 1, 2026 to June 30, 2026, and International Coal Ventures Private Limited (ICVL) for the same period, whose results were unavailable. Five subsidiaries and four joint ventures were not reviewed by their respective auditors and were furnished by management.
2. Tailwinds and Growth Prospects
Monsoon receding and production ramp-up. With the monsoon receding, NCL and CIL picked up production and dispatch pace. NCL coal production rose by 67% and supply by 75% as of 8th September compared to the 1–3 September average, while CIL average daily production rose by 40%.
Iron ore diversification. Coal India received preferred bidder status for the Gadadharpur Iron Ore Block in Kendujhar district, Odisha, awarded by the Government of Odisha, on an auction premium of 114.05% of the value of mineral dispatched. The block is a G3 exploration stage block with total resources of 288 MT. The timeline is 1 year to become successful bidder and 3 years for execution of the mining lease deed.
Solar energy expansion. Coal India received a Letter of Award from Bundelkhand Saur Urja Limited for setting up a 600 MW (300 MW × 2) solar plant at Jalaun Solar Park, UP, at Rs. 2.73/kWh, with an estimated project cost of Rs. 2831.11 Cr and execution within 18 months from signing of the PPA. The consolidated results show a new “Solar energy” segment with segment revenue of Rs. 5.68 crores and segment results of Rs. 1.56 crores for the quarter ended June 30, 2026.
Mahanadi Coalfields IPO. The draft red herring prospectus dated 1st September, 2026 of Mahanadi Coalfields Limited (MCL), a wholly owned subsidiary of Coal India Limited, was filed with SEBI, BSE and NSE. The proposed IPO comprises an Offer for Sale of up to 661,836,300 equity shares of face value INR 2 each held by Coal India Limited.
Shareholder returns. The Board declared an interim dividend for FY 2026-27 of Rs. 5.50 per equity share on face value of Rs 10, with a record date of Friday, 31st July, 2026 and payment on or before 25th August 2026. Subsequently, at the 52nd AGM held on August 31, 2026, shareholders approved a final dividend of Rs 5.25 per share (52.50%) for FY 2025-26, payable within 30 days to members on the Register of Members as on September 4, 2026. All 09 resolutions at the AGM were approved with the requisite majority.
3. Key Risks
- Monsoon and weather risk: water accumulation and temporary disruptions in mine accessibility and coal movement.
- Governance risk: non-compliant Board and committee composition attracting penal provisions.
- Tax compliance risk: SECL’s non-deduction/non-provision of TDS, resulting in non-compliance with the Income Tax Act.
- Receivables and penalty risk: delay in raising tax invoices by SECL may result in delayed payments, opportunity cost (bank interest), GST interest penalties, and loss of revenue if buyers discontinue operations.
- Contingent liability risk: Rs. 2,367.14 crores contingent liability relating to the Gare Palma custodian mines demand.
- Accounting estimate risk: the ongoing stripping activity provision write-back (Rs. 55,728.17 crores balance as on June 30, 2026) depends on management representation and technical assessment of overburden removal versus the technically assessed ratio.
- Consolidation scope risk: certain joint operations and ICVL were not considered; five subsidiaries and four joint ventures were not reviewed by their auditors.
- IPO execution risk: the proposed MCL IPO remains subject to receipt of applicable approvals, prevailing market conditions, and other relevant considerations.
4. Management Guidance Versus Observed Business Performance
Guidance: The improving trend in September provides a positive outlook for CIL’s production and dispatch, with coal supplies to power plants gradually moving towards pre-monsoon levels.
Observed performance supporting the guidance: NCL coal production rose by 67% and supply by 75% as of 8th September compared to the 1–3 September average; CIL average daily production rose by 40%; NCL rake loading increased to 41 rakes on 8th September. NCL’s total coal production for FY 2026-27 stood at 51.43 MT and supplies reached 55 MT till 8th September, with around 87% of NCL’s total coal supplies directed to the power sector.
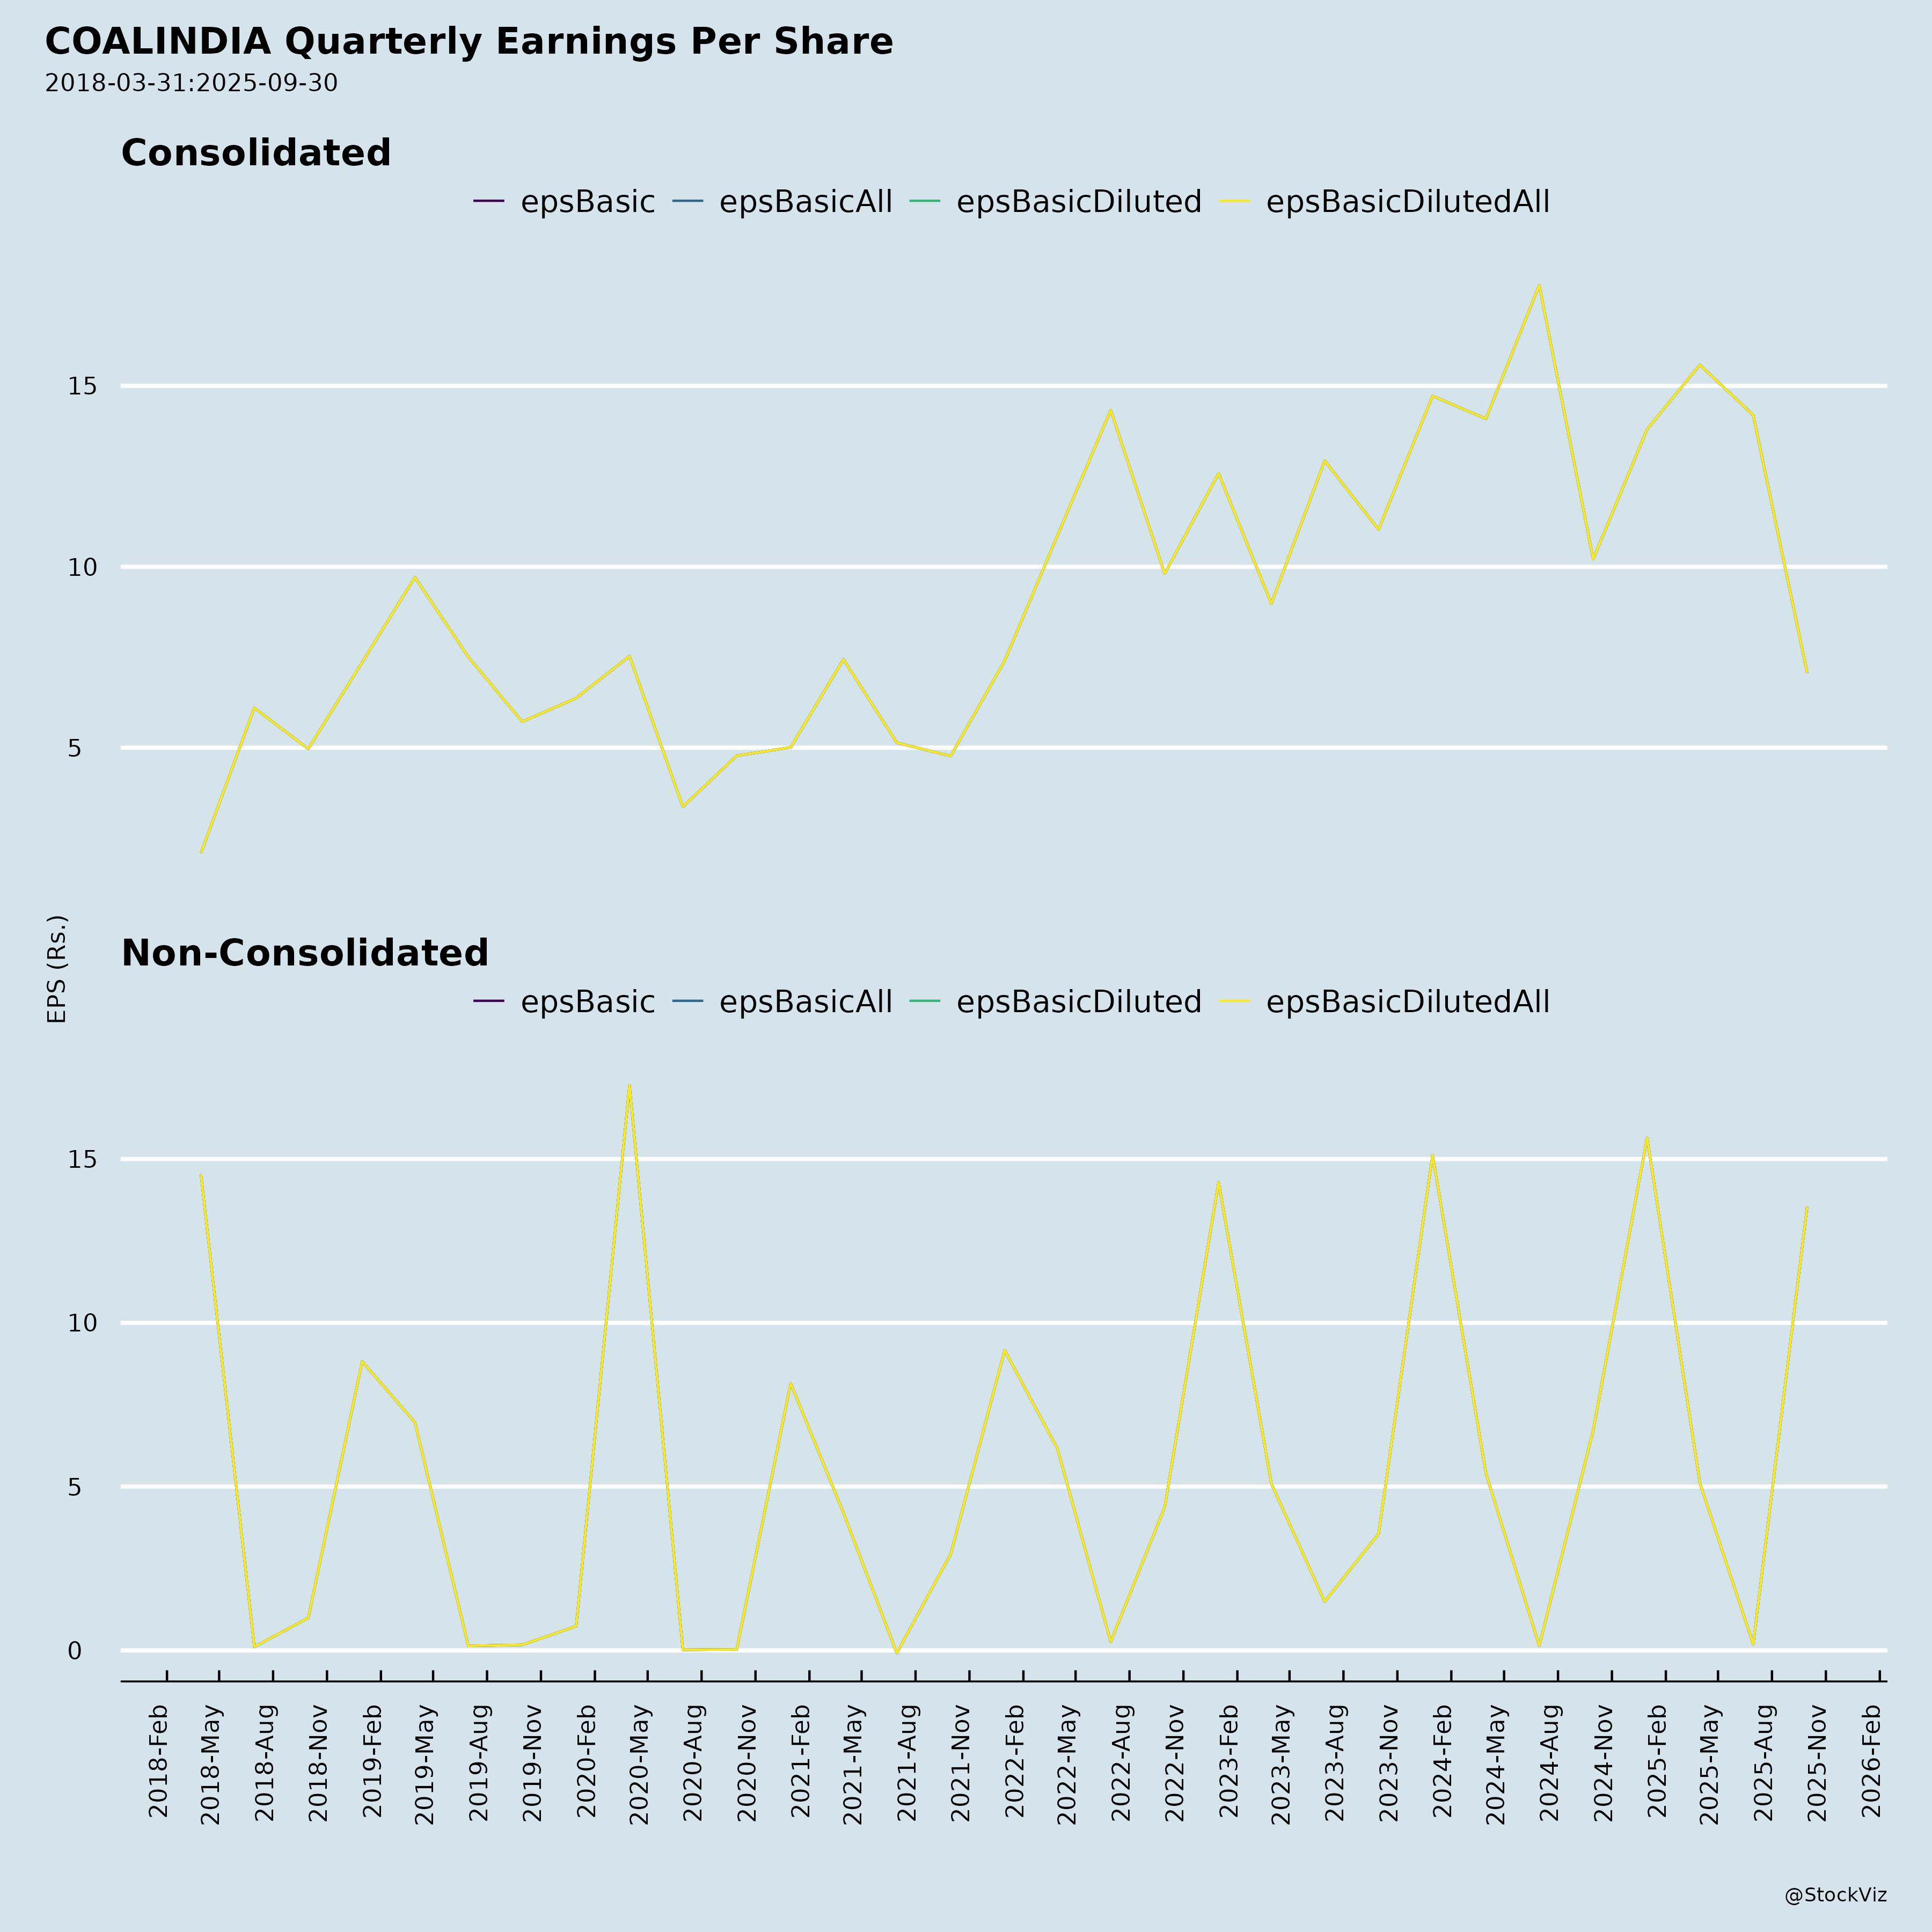
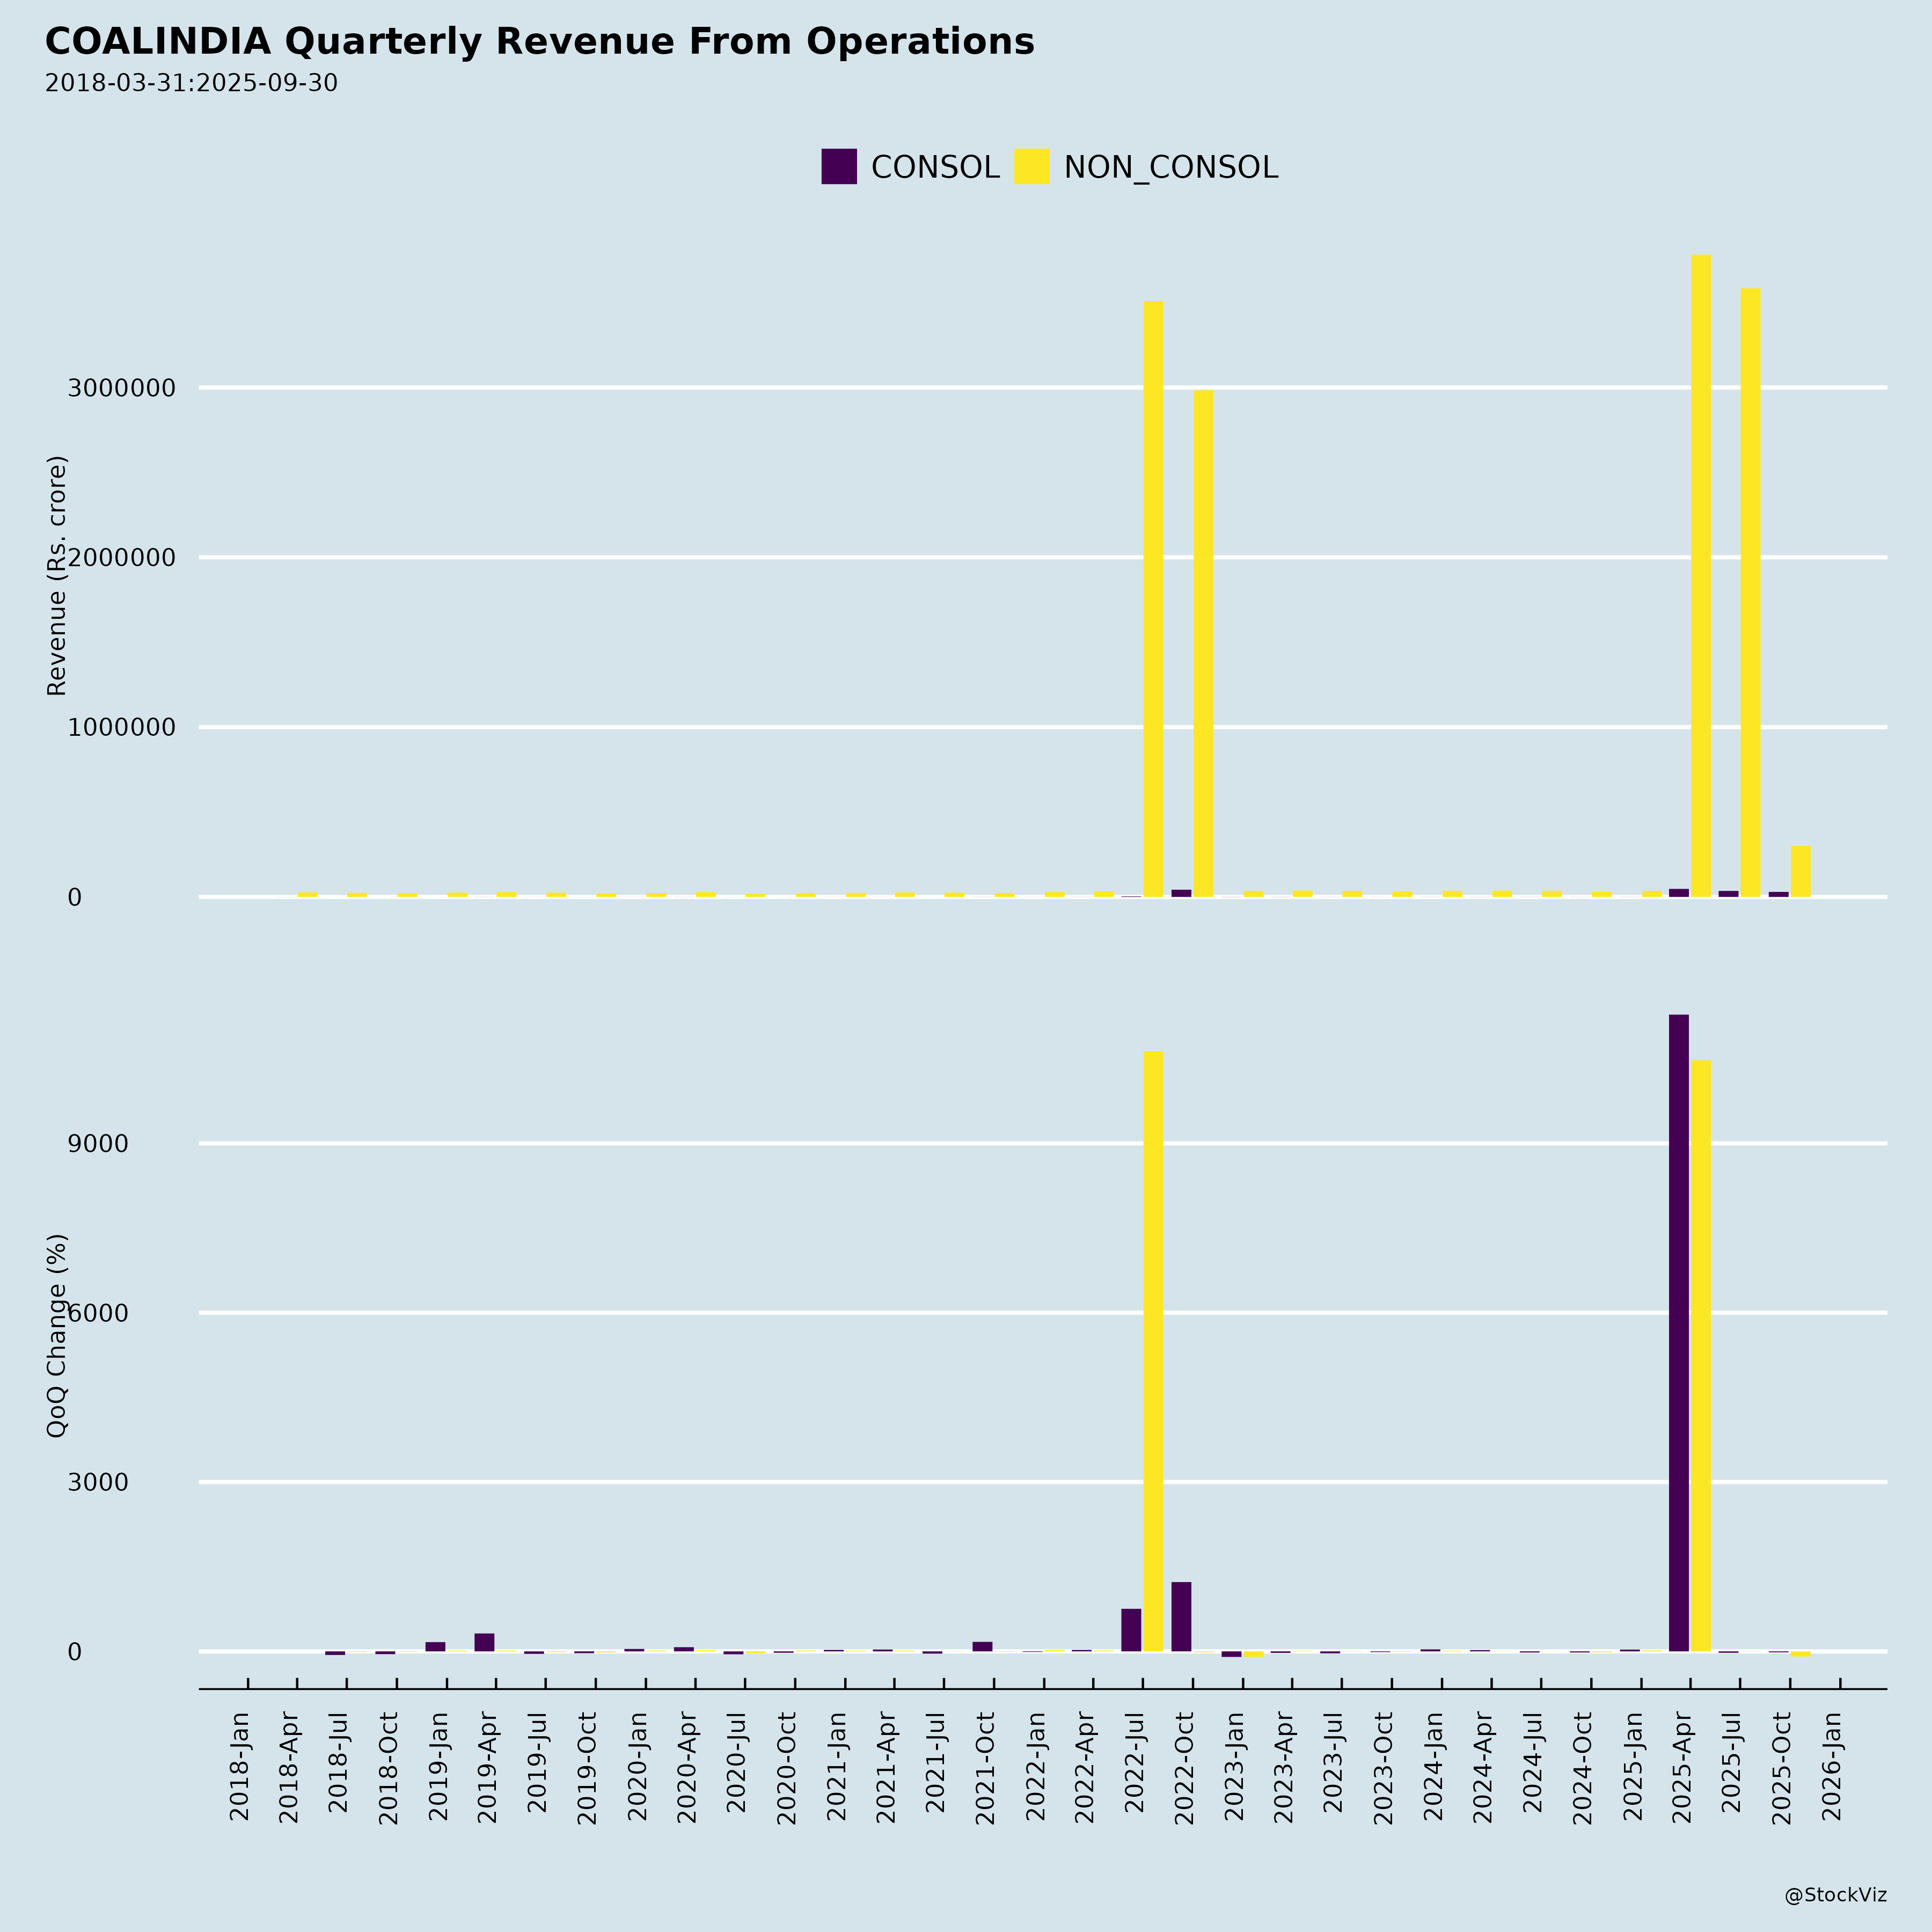
Observed financial performance (quarter ended June 30, 2026, consolidated): Revenue from operations was Rs. 46,254.40 crores against Rs. 42,919.20 crores in the quarter ended June 30, 2025. Profit before tax was Rs. 11,719.36 crores against Rs. 11,776.09 crores. Profit for the period was Rs. 8,849.81 crores against Rs. 8,787.84 crores. Total comprehensive income was Rs. 8,873.81 crores against Rs. 8,456.53 crores. Basic and diluted EPS was Rs. 14.36 against Rs. 14.27.
Standalone performance (quarter ended June 30, 2026): Revenue from operations was Rs. 345.18 crores against Rs. 359.82 crores in the quarter ended June 30, 2025. Profit before tax was Rs. 211.20 crores against Rs. 175.48 crores. Profit for the period was Rs. 153.18 crores against Rs. 115.97 crores. Basic and diluted EPS was Rs. 0.25 against Rs. 0.19. Other income included dividend from subsidiaries of Rs. 1.05 crores for the quarter ended June 30, 2026, against Rs. 16,252.25 crores for the year ended March 31, 2026.
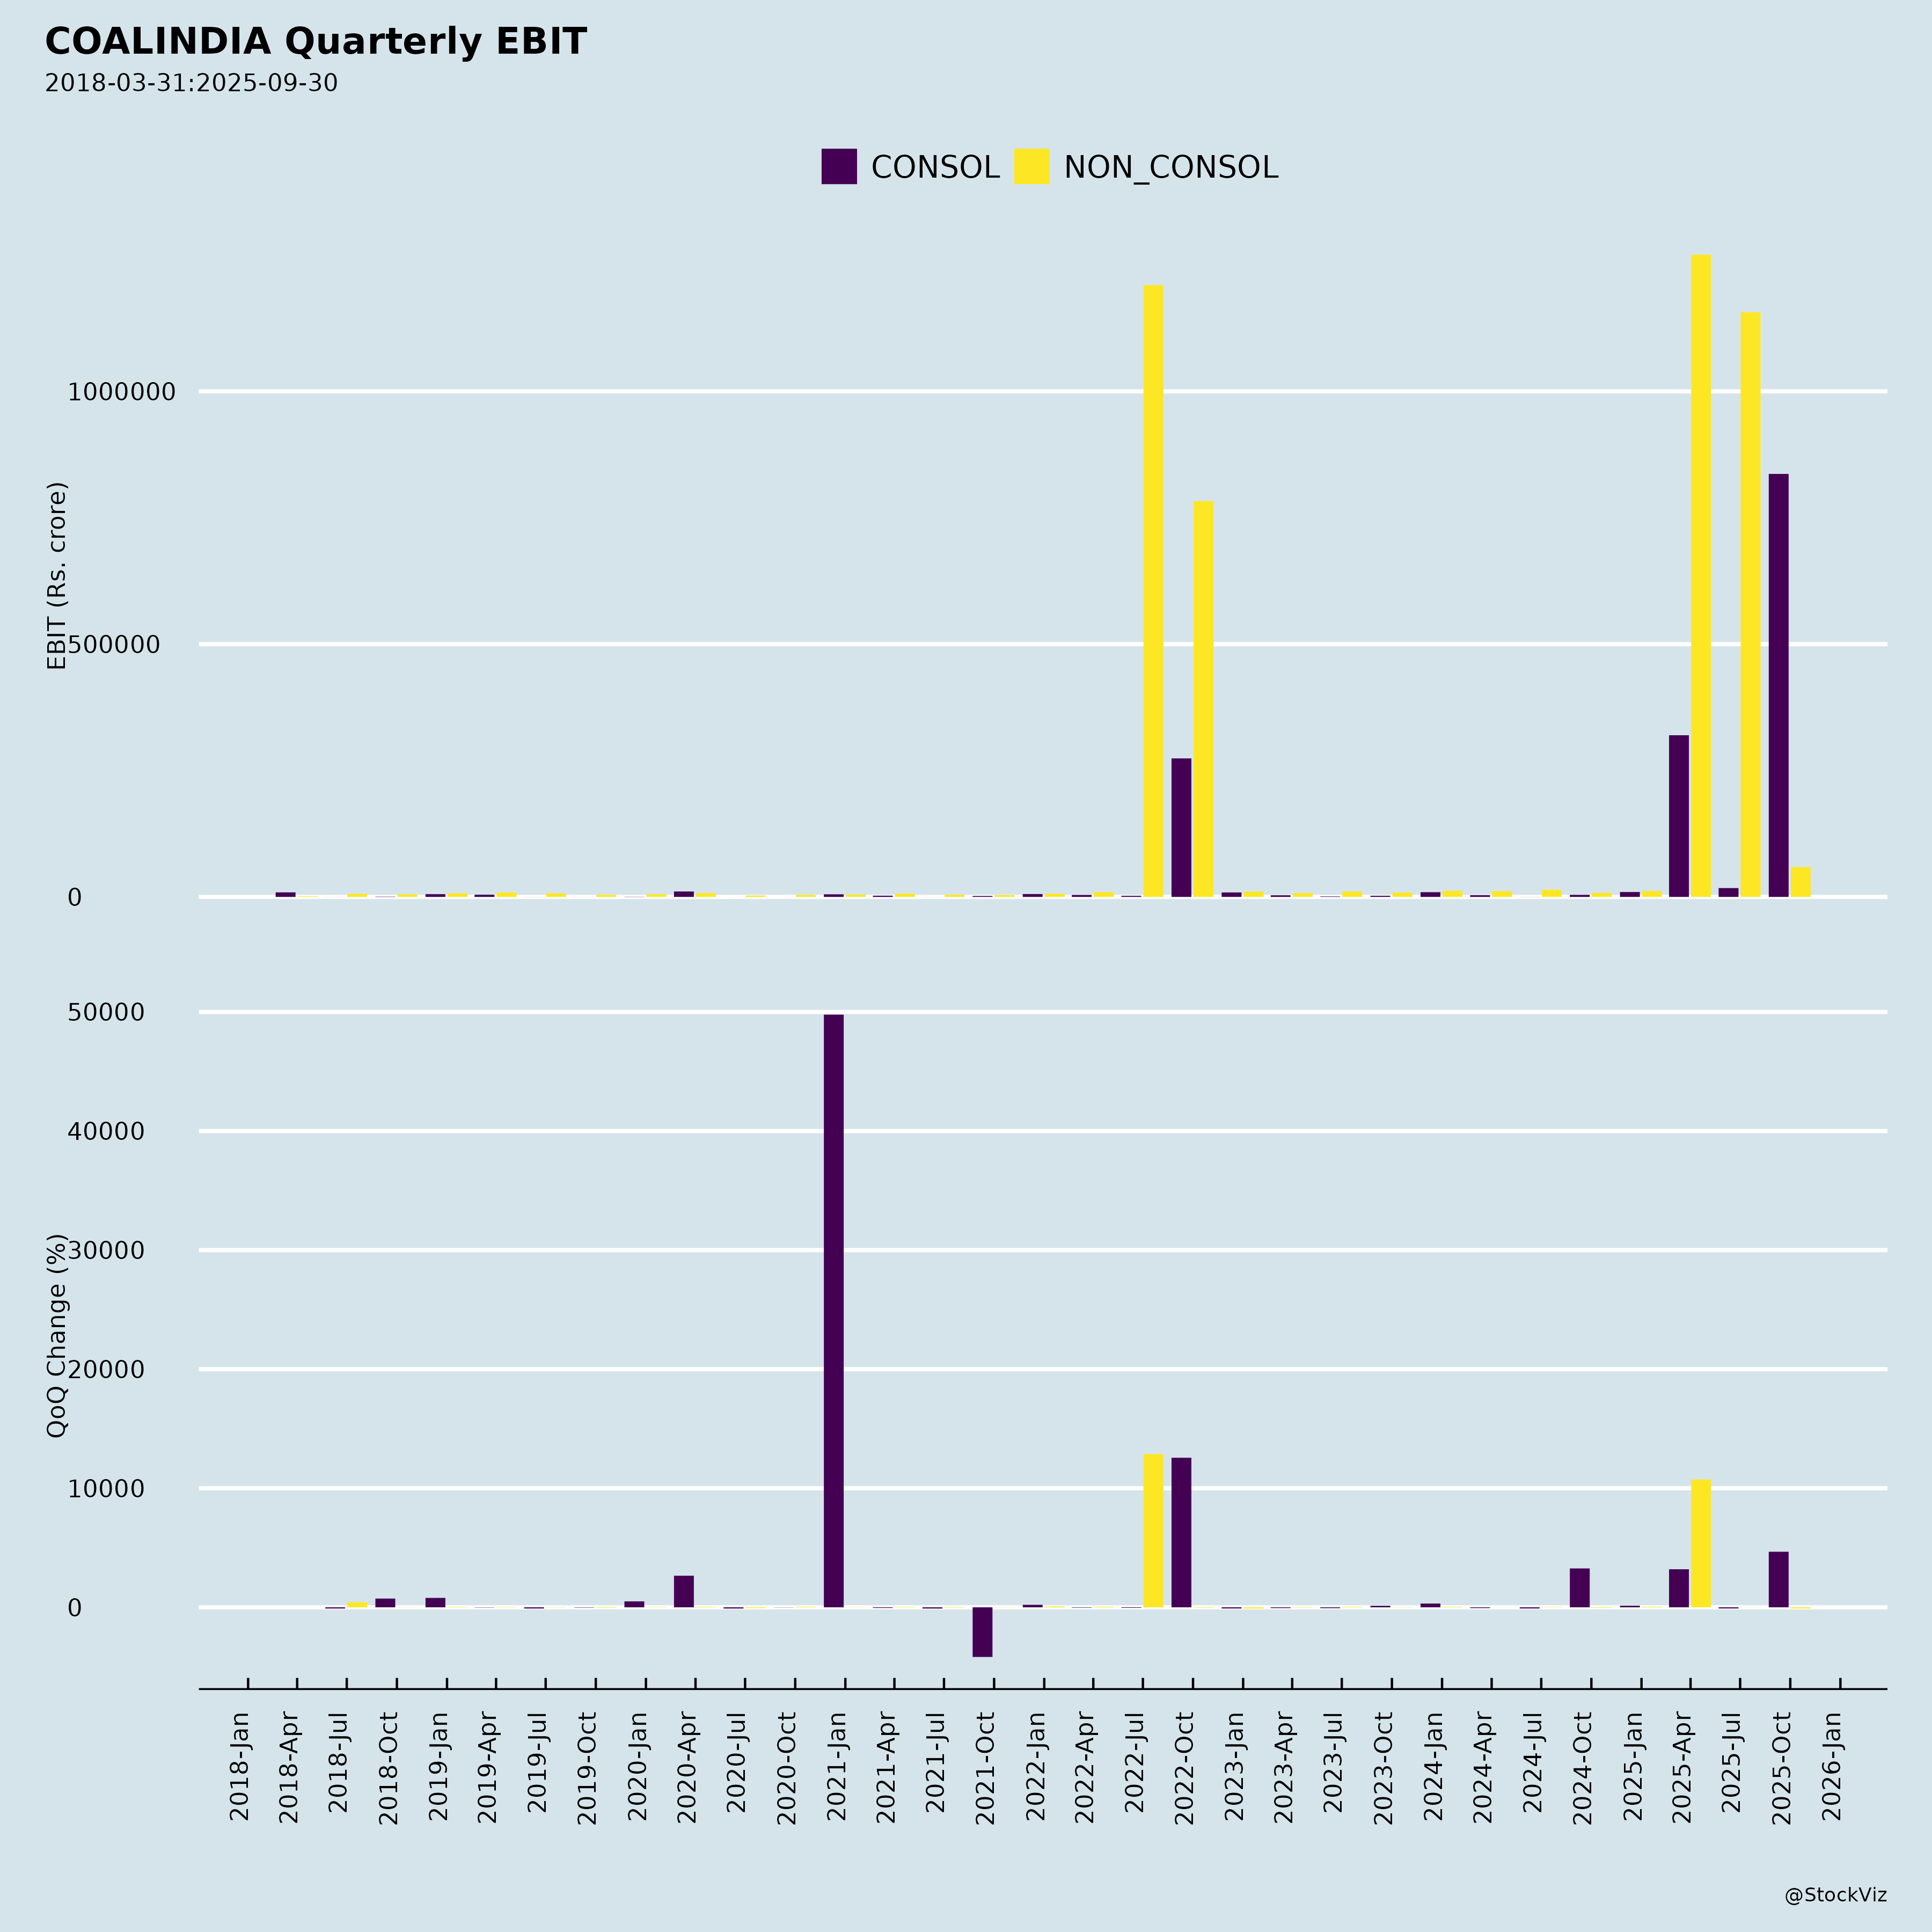
Segment performance (consolidated): Coal segment revenue was Rs. 46,249.12 crores and segment results (profit before interest and tax) were Rs. 11,804.76 crores for the quarter ended June 30, 2026. Solar energy segment revenue was Rs. 5.68 crores with segment results of Rs. 1.56 crores.
Broker Narrative
The broker narrative evolved from a mixed-to-bearish stance in 2023—dominated by declining e-auction realisations, elevated wage and operating costs, and weak near-term power demand—toward predominantly Buy calls through 2025, before settling into a Hold tone by mid-2026. Persistent themes included cost pressures and an attractive dividend yield, while the major shift was the emergence of structural headwinds from renewable energy displacing coal and intensified domestic competition from captive mines, replacing earlier concerns about e-auction pricing and FSA price revision lags.
Fears that came true
- Declining E-Auction Realisations materialised as blended realisations fell 5.9% YoY to ₹1,595/tonne in Q1FY27, correlating with the cluster of DISAPPOINTMENT outcomes from Feb–Oct 2024 when the stock fell on deteriorating pricing.
- Elevated Operating & Wage Costs persisted and compressed profitability, with EBITDA/tonne declining 7.7% YoY to ₹610/tonne, corresponding to multiple DISAPPOINTMENT results throughout 2024.
- High Overburden Removal (OBR) Expenses continued to push production costs higher as foreshadowed (cost of production up 38% YoY in 4QFY23), with margins remaining under sustained pressure through the last report.
- Cash Drain & Capital Outflows materialised as ‘Potential Capex Overruns’ flagged in the last report, threatening balance sheet integrity amid elevated annual capex above Rs 150-160bn.
- Skewed Business Model risk deepened as captive and commercial coal mine production rose ~10% YoY to ~211 MT in FY26, reducing Coal India’s share of incremental domestic production.
Optimism that failed
- Power Demand Recovery proved only temporary as coal’s share in electricity generation declined from ~71% to ~68% between FY25 and FY26 while renewables grew to ~26%, constraining long-term volume growth.
- Steady Offtake Volume Growth expectations were overly optimistic, with volume CAGR settling at a modest ~4% over FY26–28E rather than the stronger annual growth originally projected.
- Expected FSA Price Revision provided only limited downside support as EBITDA/tonne still declined 7.7% YoY despite the projected 8% upward revision in FSA prices.
Broker Timeline
68 broker calls · 2023-05-07 to 2026-07-30
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.