CIFL
Equity Metrics
September 24, 2026
Capital India Finance Limited
Non Banking Financial Company (NBFC)
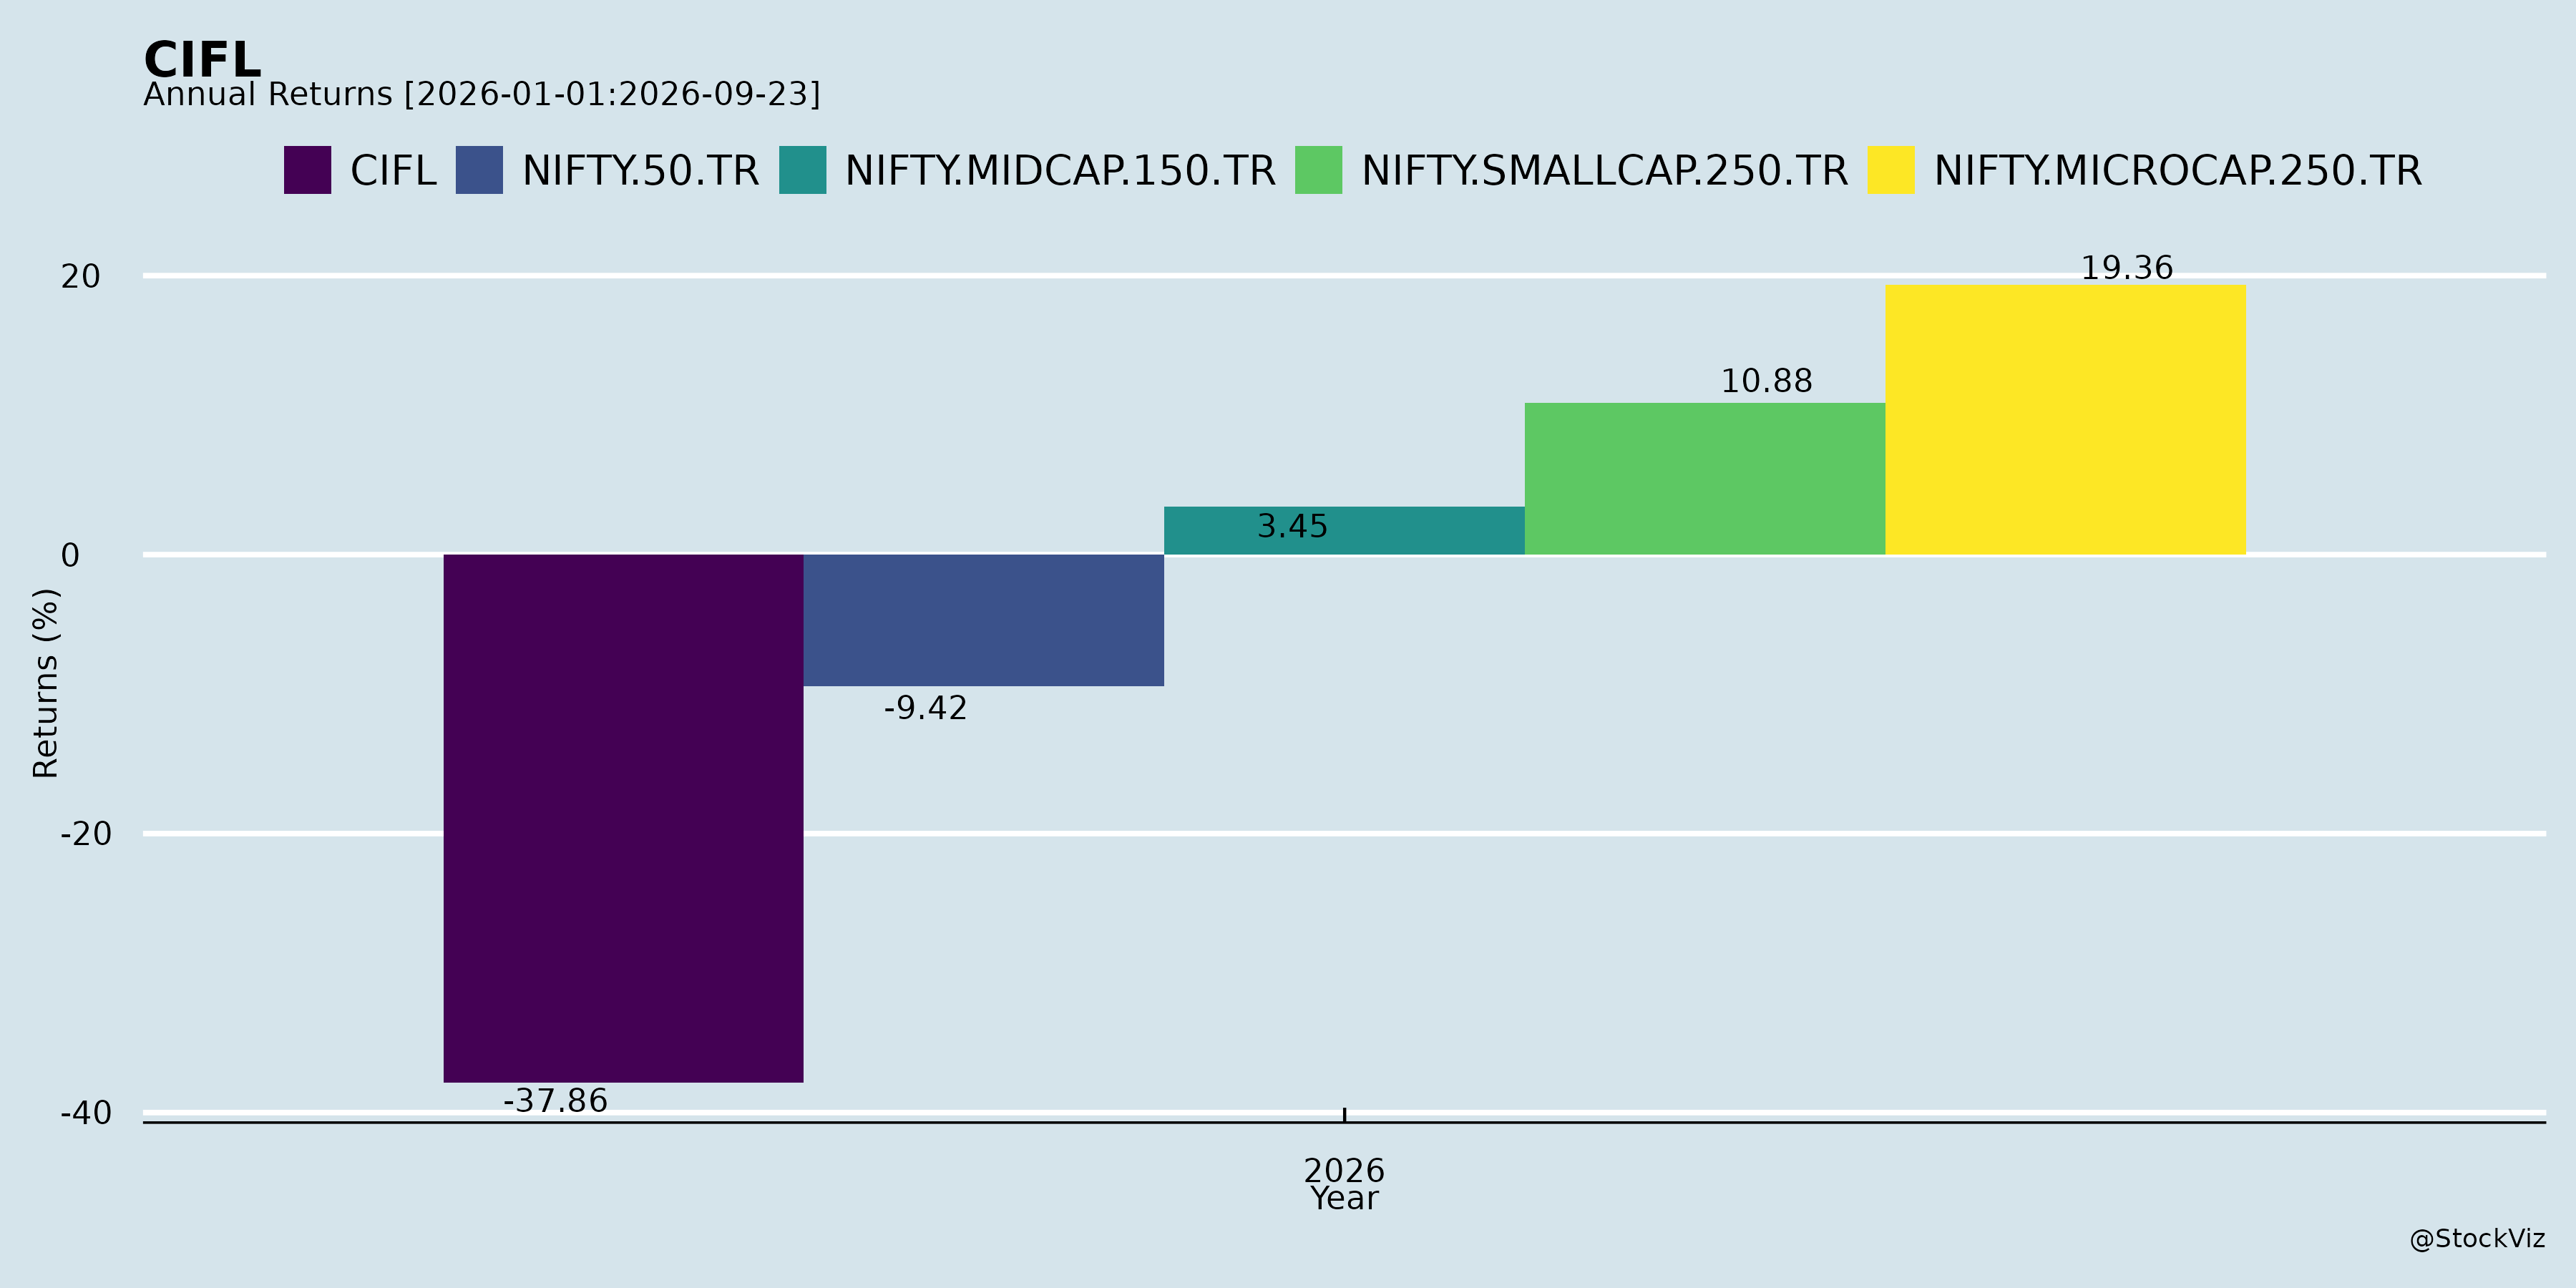
Annual Returns

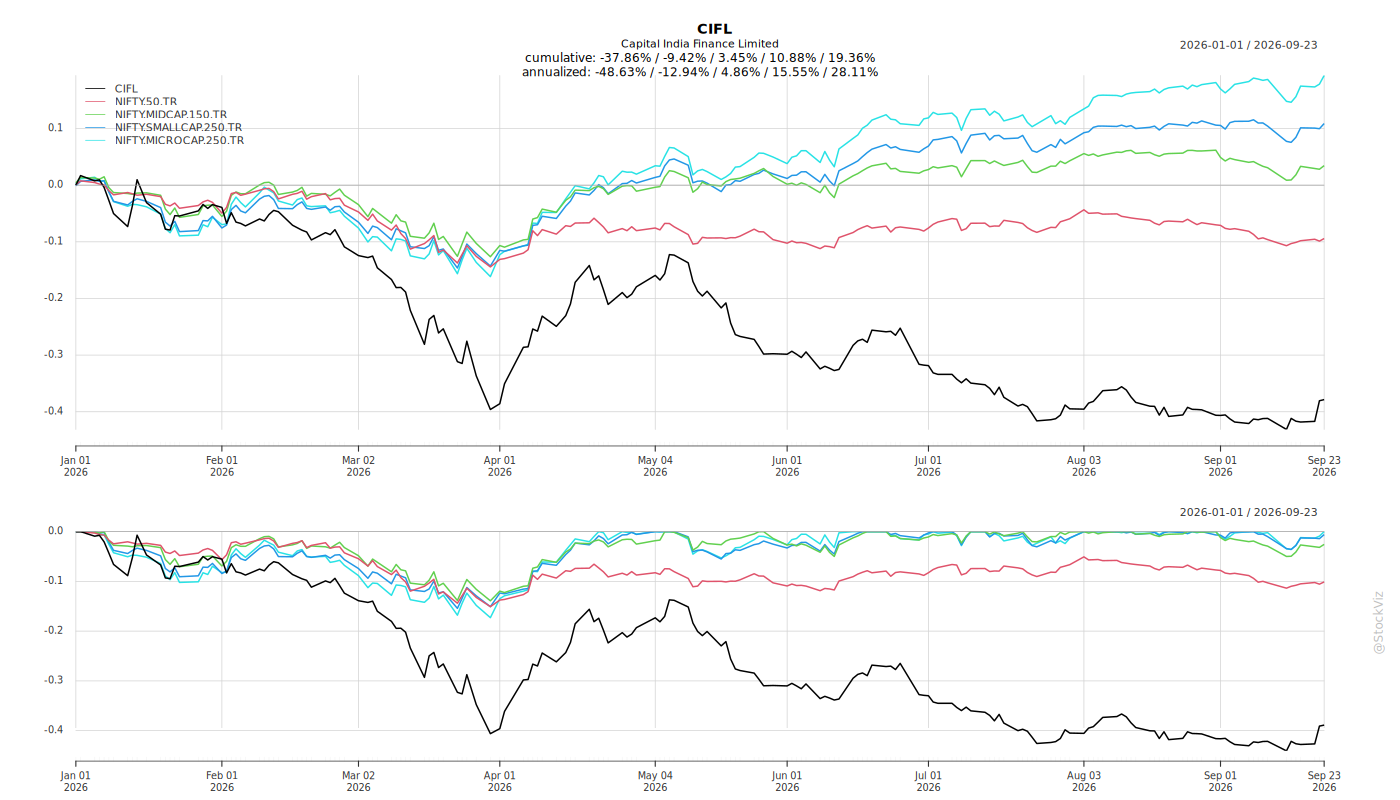
Cumulative Returns and Drawdowns
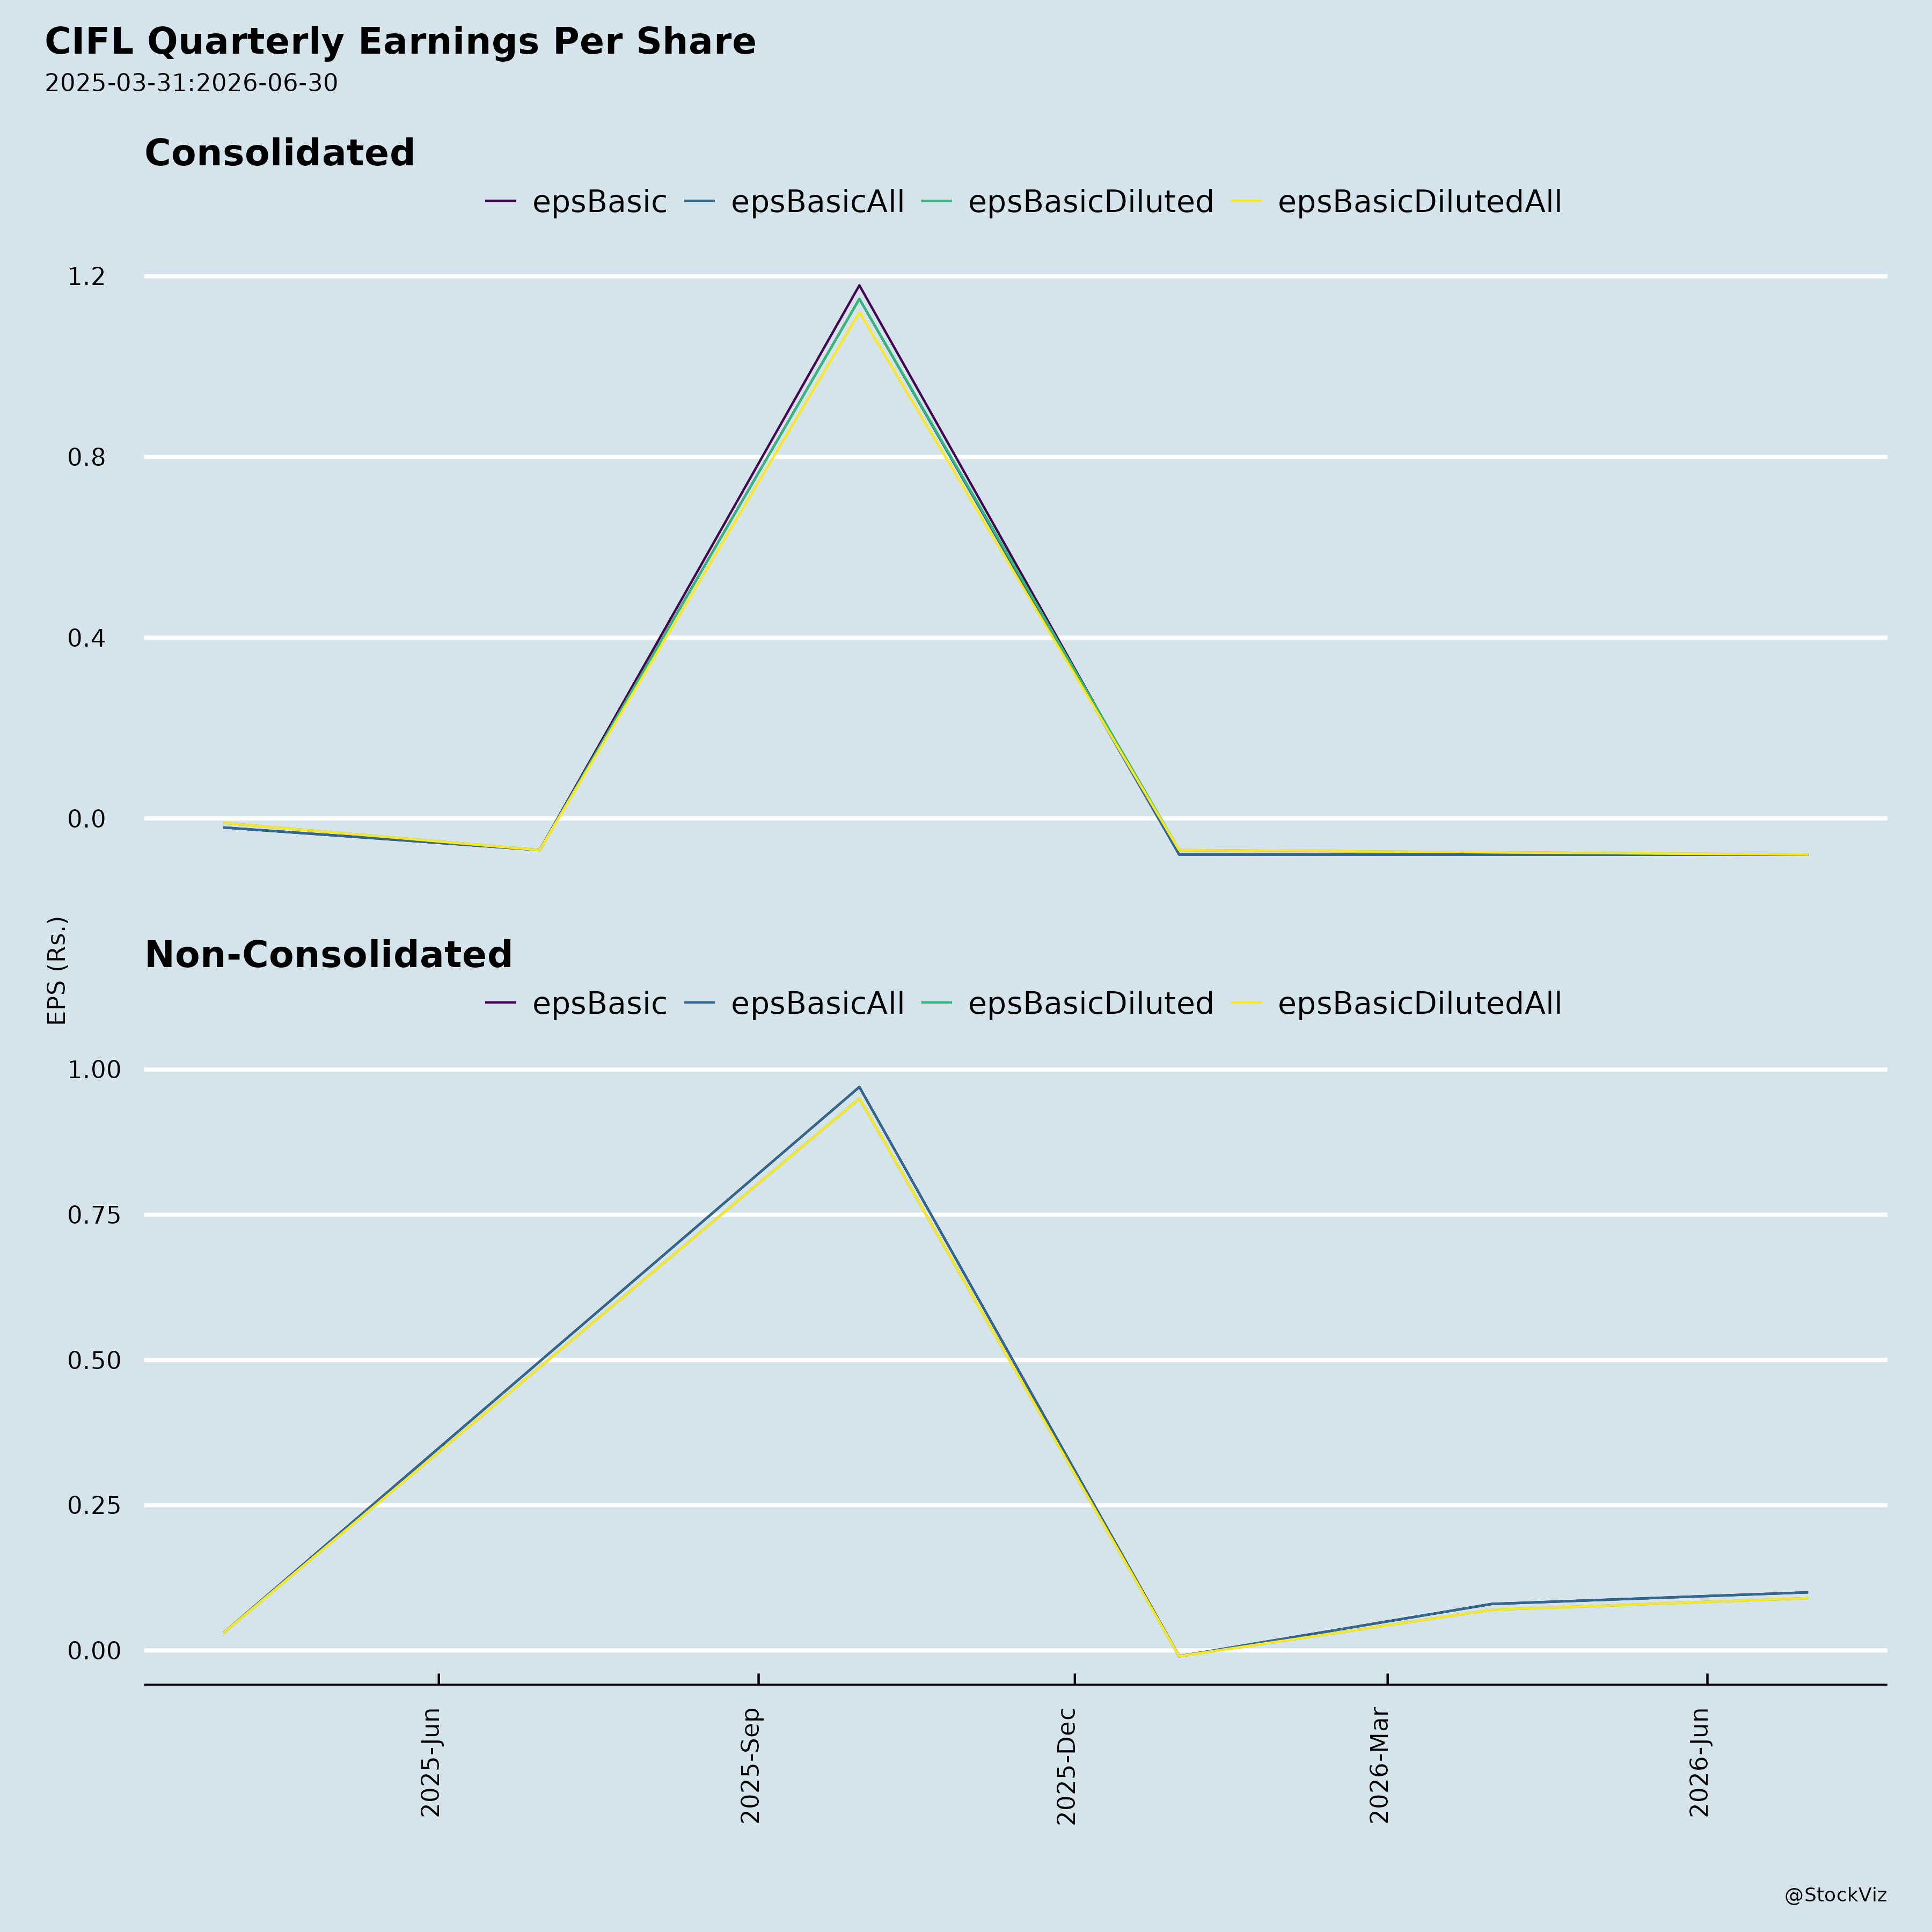
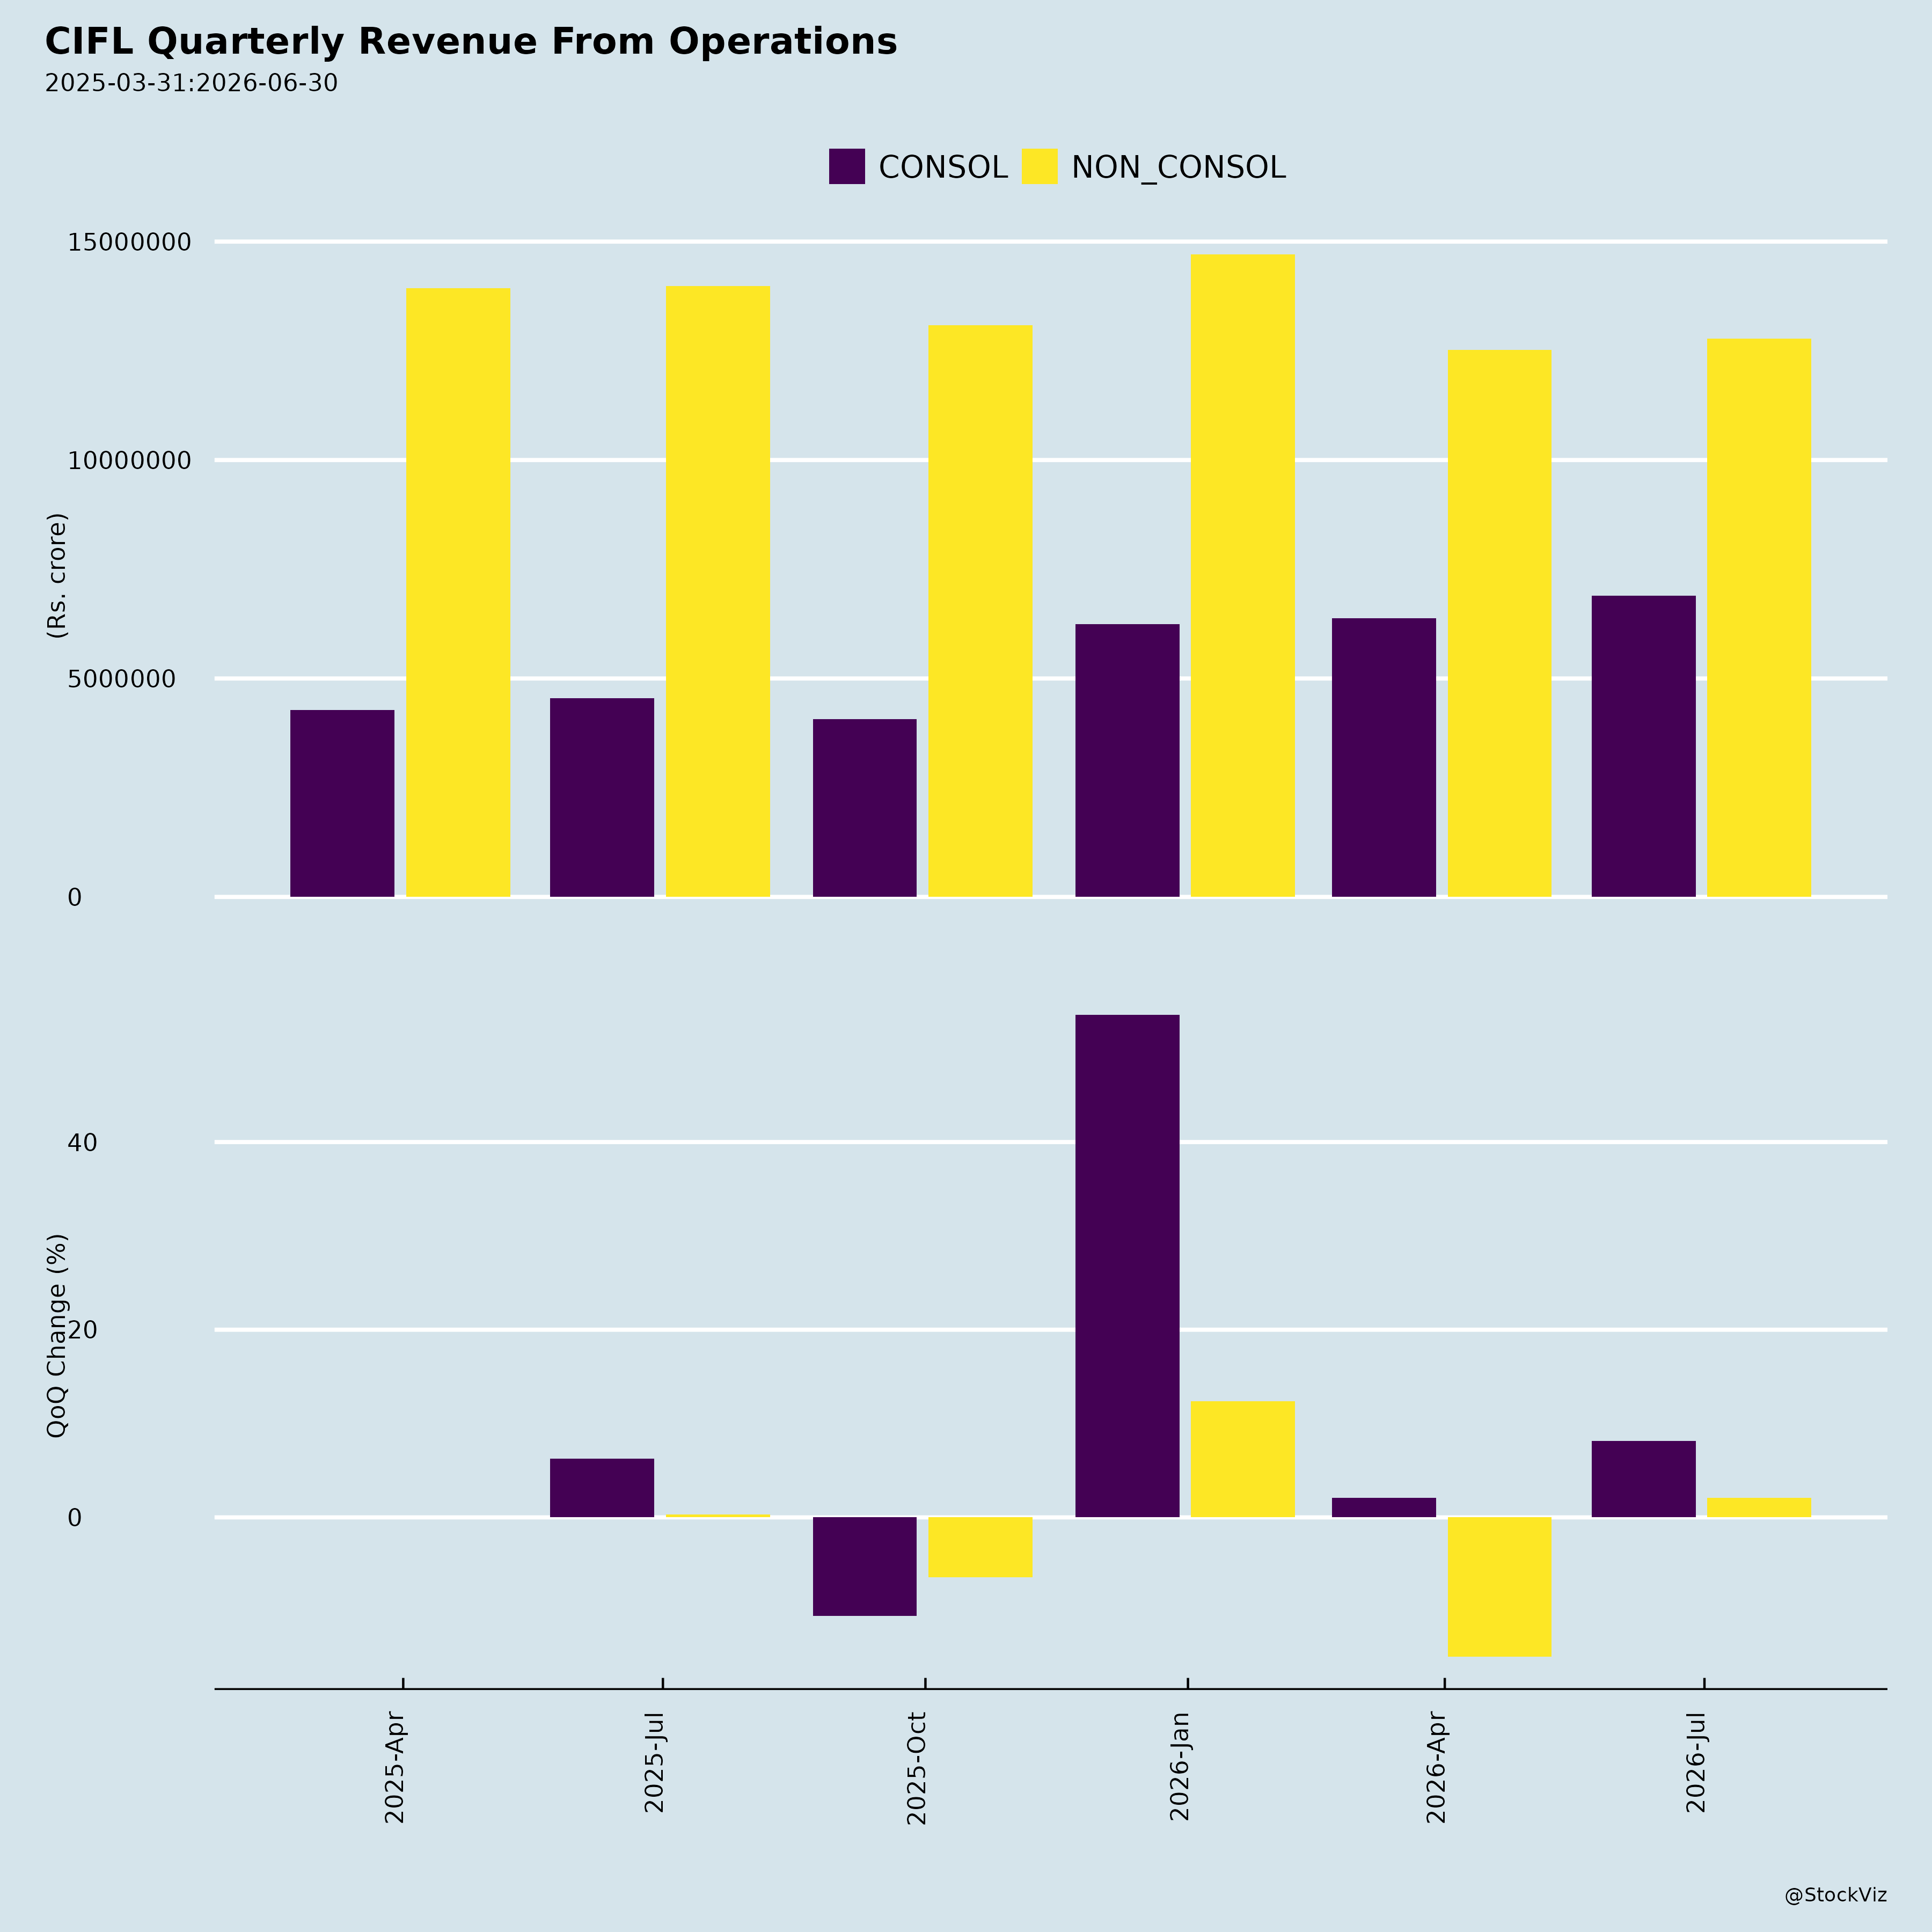
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-18
Capital India Finance Limited — Recent Corporate Developments
Headwinds and Challenges
The supplied material does not identify specific headwinds or challenges. The only structural change disclosed is the exit from the foreign exchange business, which is framed as a portfolio-simplification move rather than a response to a stated adversity. The transfer of the RemitX business is subject to requisite regulatory approvals, permissions, and consents, and to the fulfilment of other applicable terms and conditions set out in the Asset Purchase Agreement — a conditionality that represents execution dependency for the transaction.
Tailwinds and Growth Prospects
Management points to sustainable future growth, with the core lending business positioned as the primary growth engine. The supporting indicators cited are:
- A 32% year-on-year increase in standalone total income to Rs 69.53 crore in Q1 FY27.
- A 36% year-on-year growth in disbursements.
- An approximately 20% year-on-year expansion in AUM.
- A Capital Adequacy Ratio of 43.58% as of June 30, 2026.
- An expanding distribution network reaching 46 branches across nine states.
The company is simplifying its portfolio by concentrating on its core MSME and retail lending business. The proposed transfer of the RemitX forex division to Kanji Forex Private Limited (part of Niyo) is intended to allow CIFL to sharpen its focus on its tech-enabled lending franchise and to deploy resources and management bandwidth toward scaling the lending business in a disciplined manner, building on its capital position, distribution network, and lending momentum.
Key Risks
The material does not set out a dedicated risk list. The identifiable risk-related items are:
- Completion risk on the RemitX transfer: consummation is expected by October 31, 2026, but is subject to receipt of requisite regulatory approvals, permissions, and consents and fulfilment of other APA terms and conditions.
- Regulatory dependency following the transfer: after consummation, the Seller will apply to the Reserve Bank of India to surrender its Authorised Dealer Category-II (AD-II) Licence.
- Related party exposure: members approved material related party transactions with Rapipay Fintech Private Limited at the 32nd Annual General Meeting.
Management Guidance Versus Observed Business Performance
At the 32nd Annual General Meeting held on September 7, 2026, members approved five resolutions: adoption of standalone and consolidated financial statements, re-appointment of Mr. Keshav Porwal as Director, revision of his remuneration as Managing Director effective April 1, 2026, raising of funds through debt securities, and material related party transactions with Rapipay Fintech Private Limited. Management provided an overview of performance for the financial year 2025-26 together with an outlook for sustainable future growth.
On the RemitX divestment, the guidance is that the transfer will be consummated by October 31, 2026, subject to regulatory approvals. The observed baseline for that business is disclosed for the financial year ended March 31, 2026: the RemitX business contributed a turnover of INR 2,492.81 lakhs (4.68% contribution) and a net worth of INR 2,825.50 lakhs (4.20% contribution). The agreed aggregate consideration under the Asset Purchase Agreement dated August 31, 2026 is INR 1,140 lakhs.
For the lending franchise, management’s stated intent to scale in a disciplined manner is accompanied by observed Q1 FY27 performance: 32% year-on-year growth in standalone total income to Rs 69.53 crore, 36% year-on-year disbursement growth, approximately 20% year-on-year AUM expansion, a Capital Adequacy Ratio of 43.58% as of June 30, 2026, and a network of 46 branches across nine states.
Broker Narrative
The broker maintained a Buy rating throughout all seven reports, so the core bullish stance persisted. However, the narrative evolved from an initial report with no stated headwinds or tailwinds to a final report that specified many operational and macro risks, including higher funding costs, weak collections, monsoon disruption, and asset quality deterioration. The later thesis balanced these concerns with growth drivers such as strong disbursements, vehicle finance, and a rating upgrade, shifting from unqualified optimism to a more conditional positive view.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.