CDSL
Equity Metrics
November 18, 2026
Central Depository Services (India) Limited
Depositories Clearing Houses and Other Intermediaries
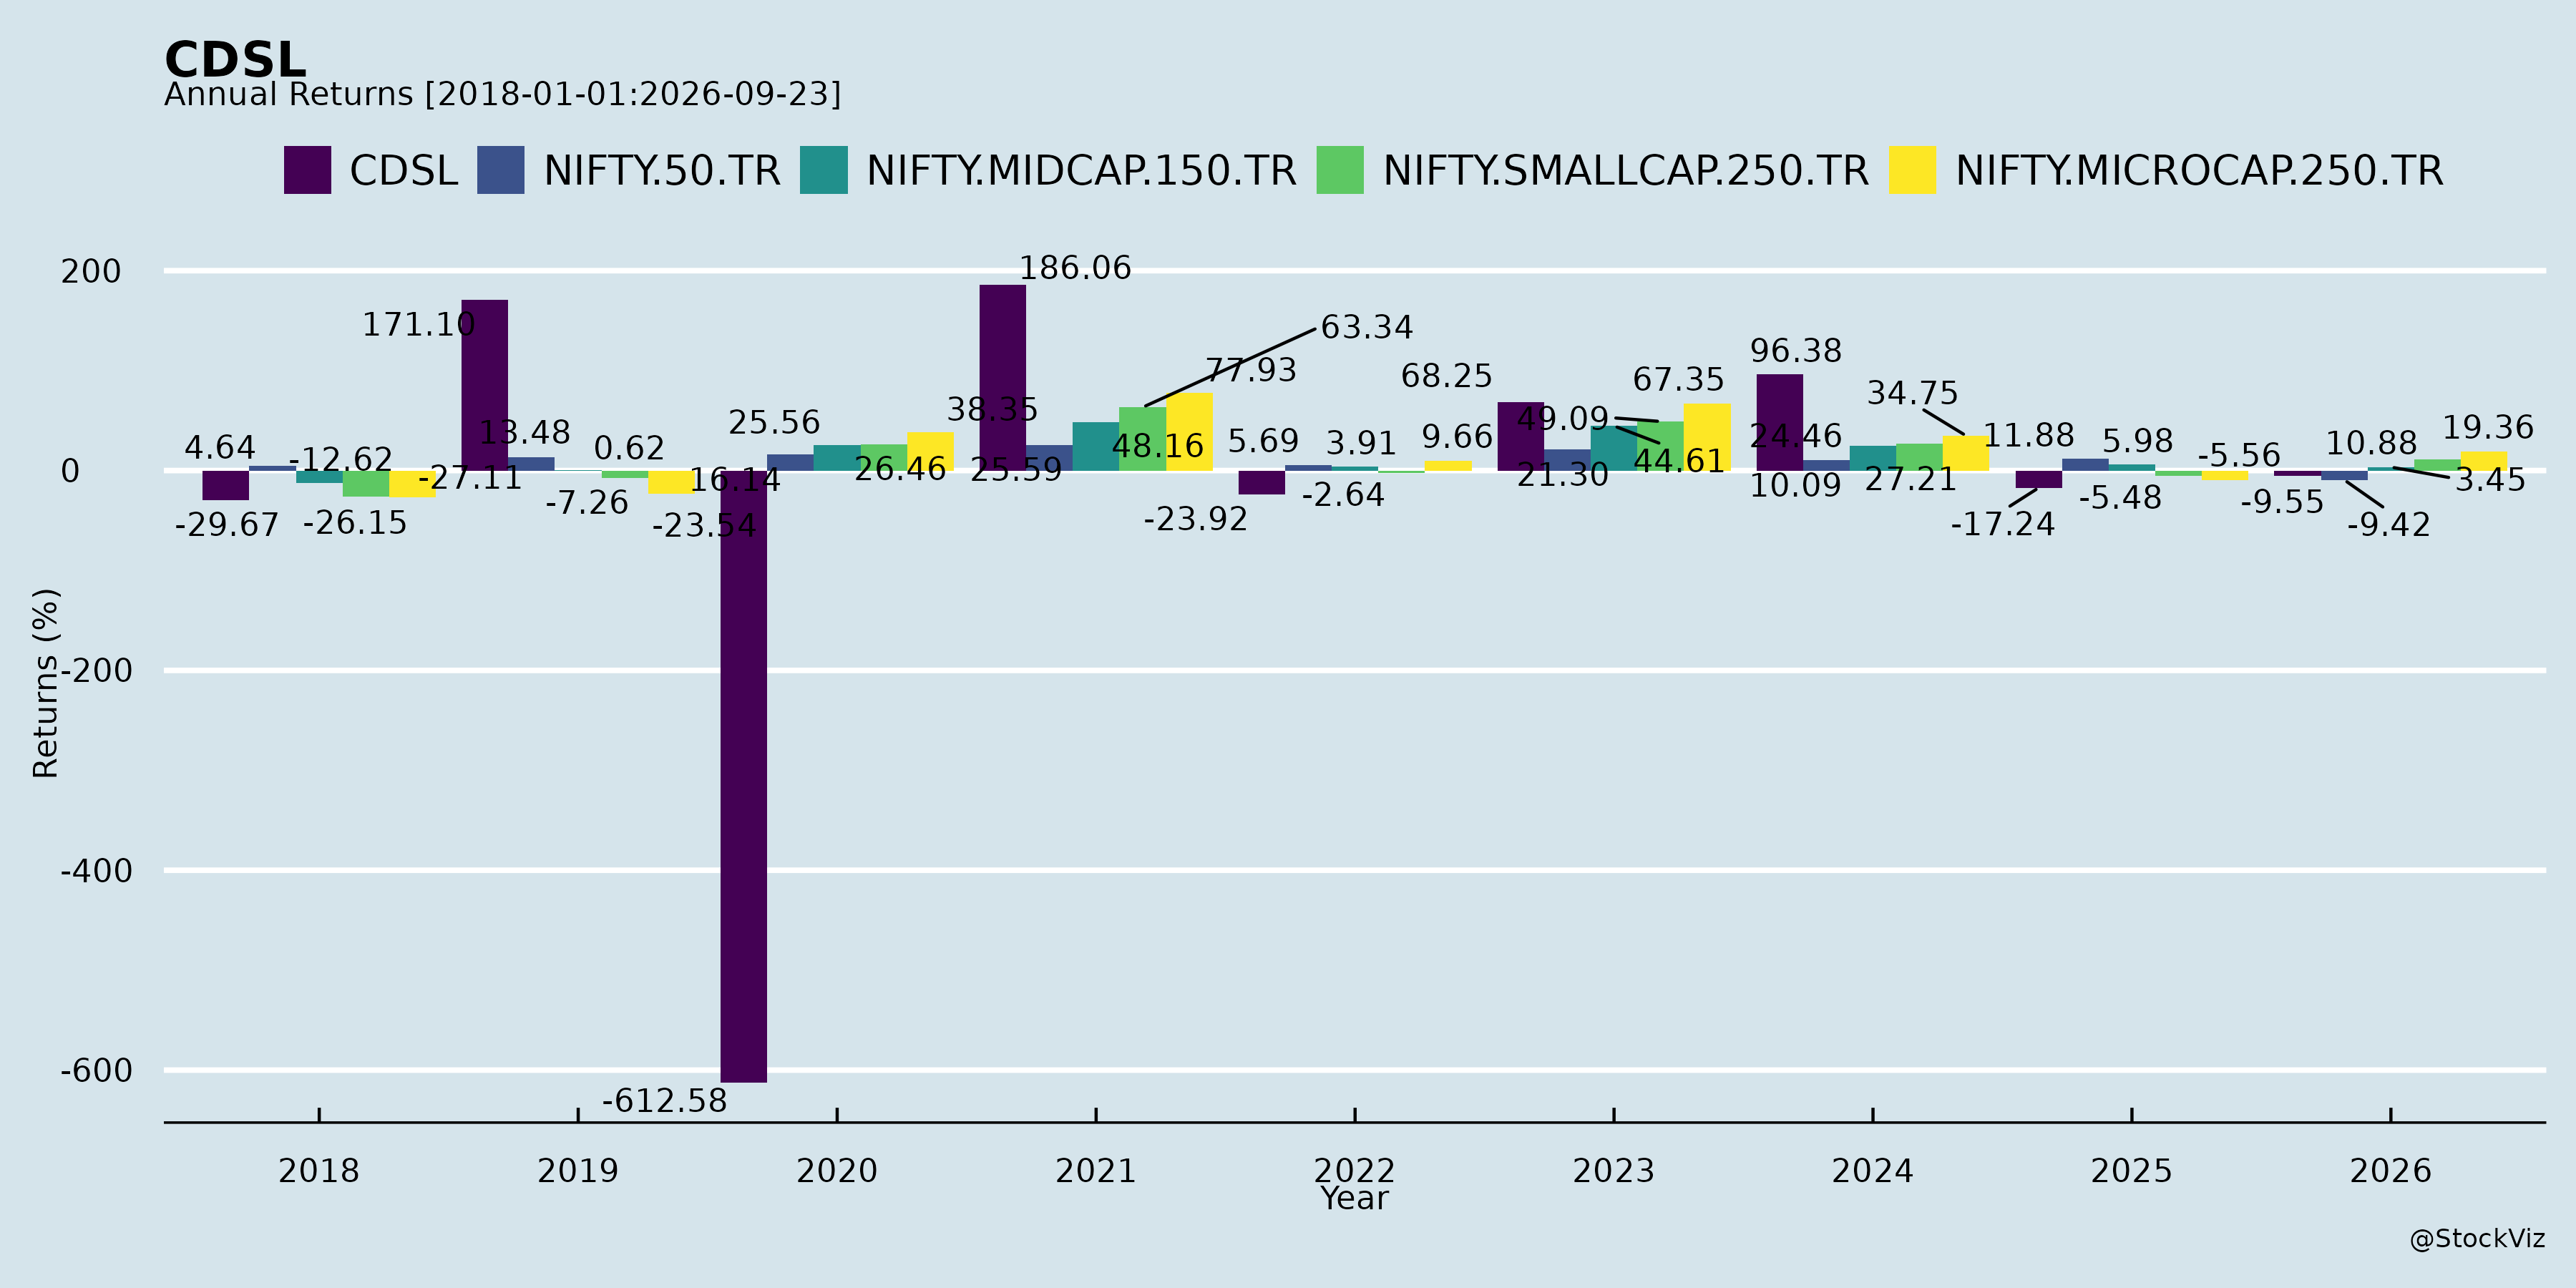
Annual Returns
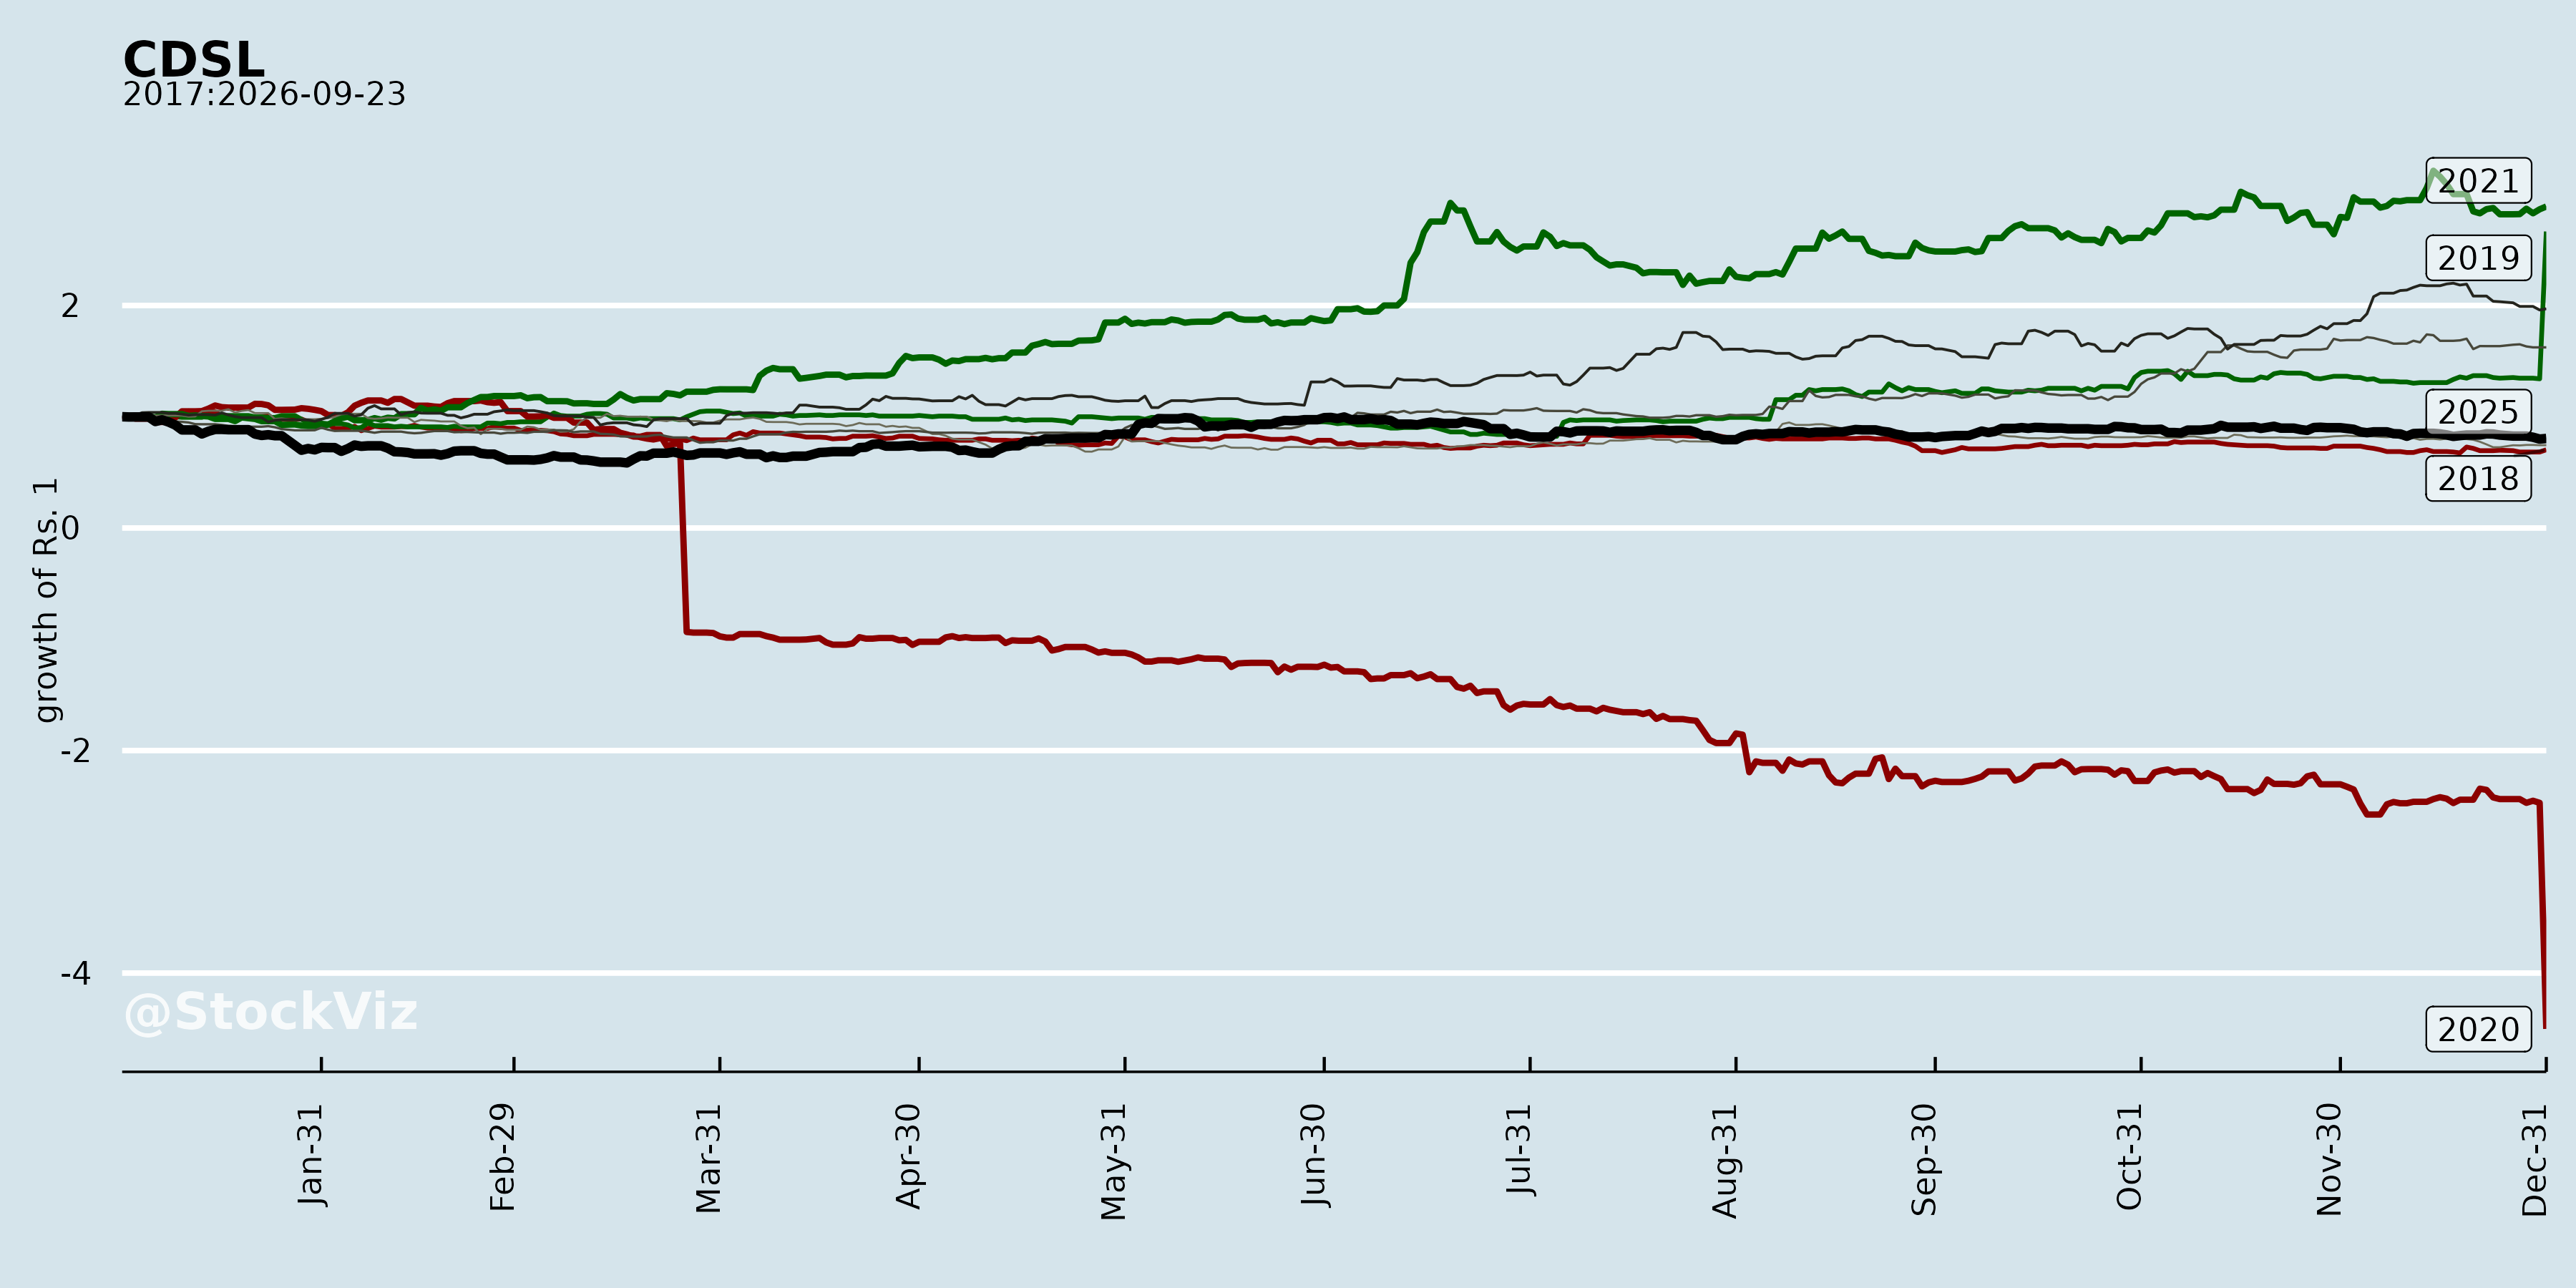
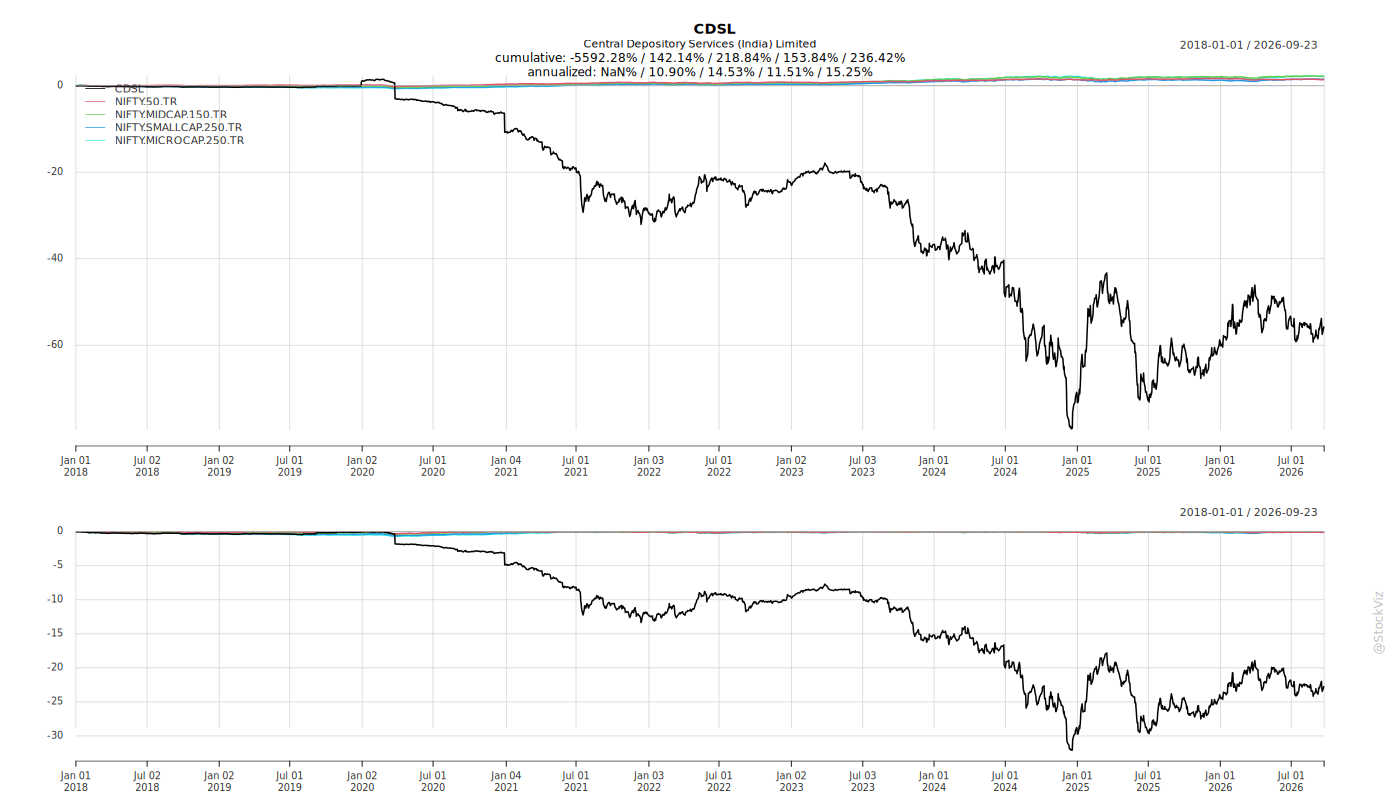
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
CDSL: Recent Corporate Announcements — Summary
1. Headwinds and Challenges
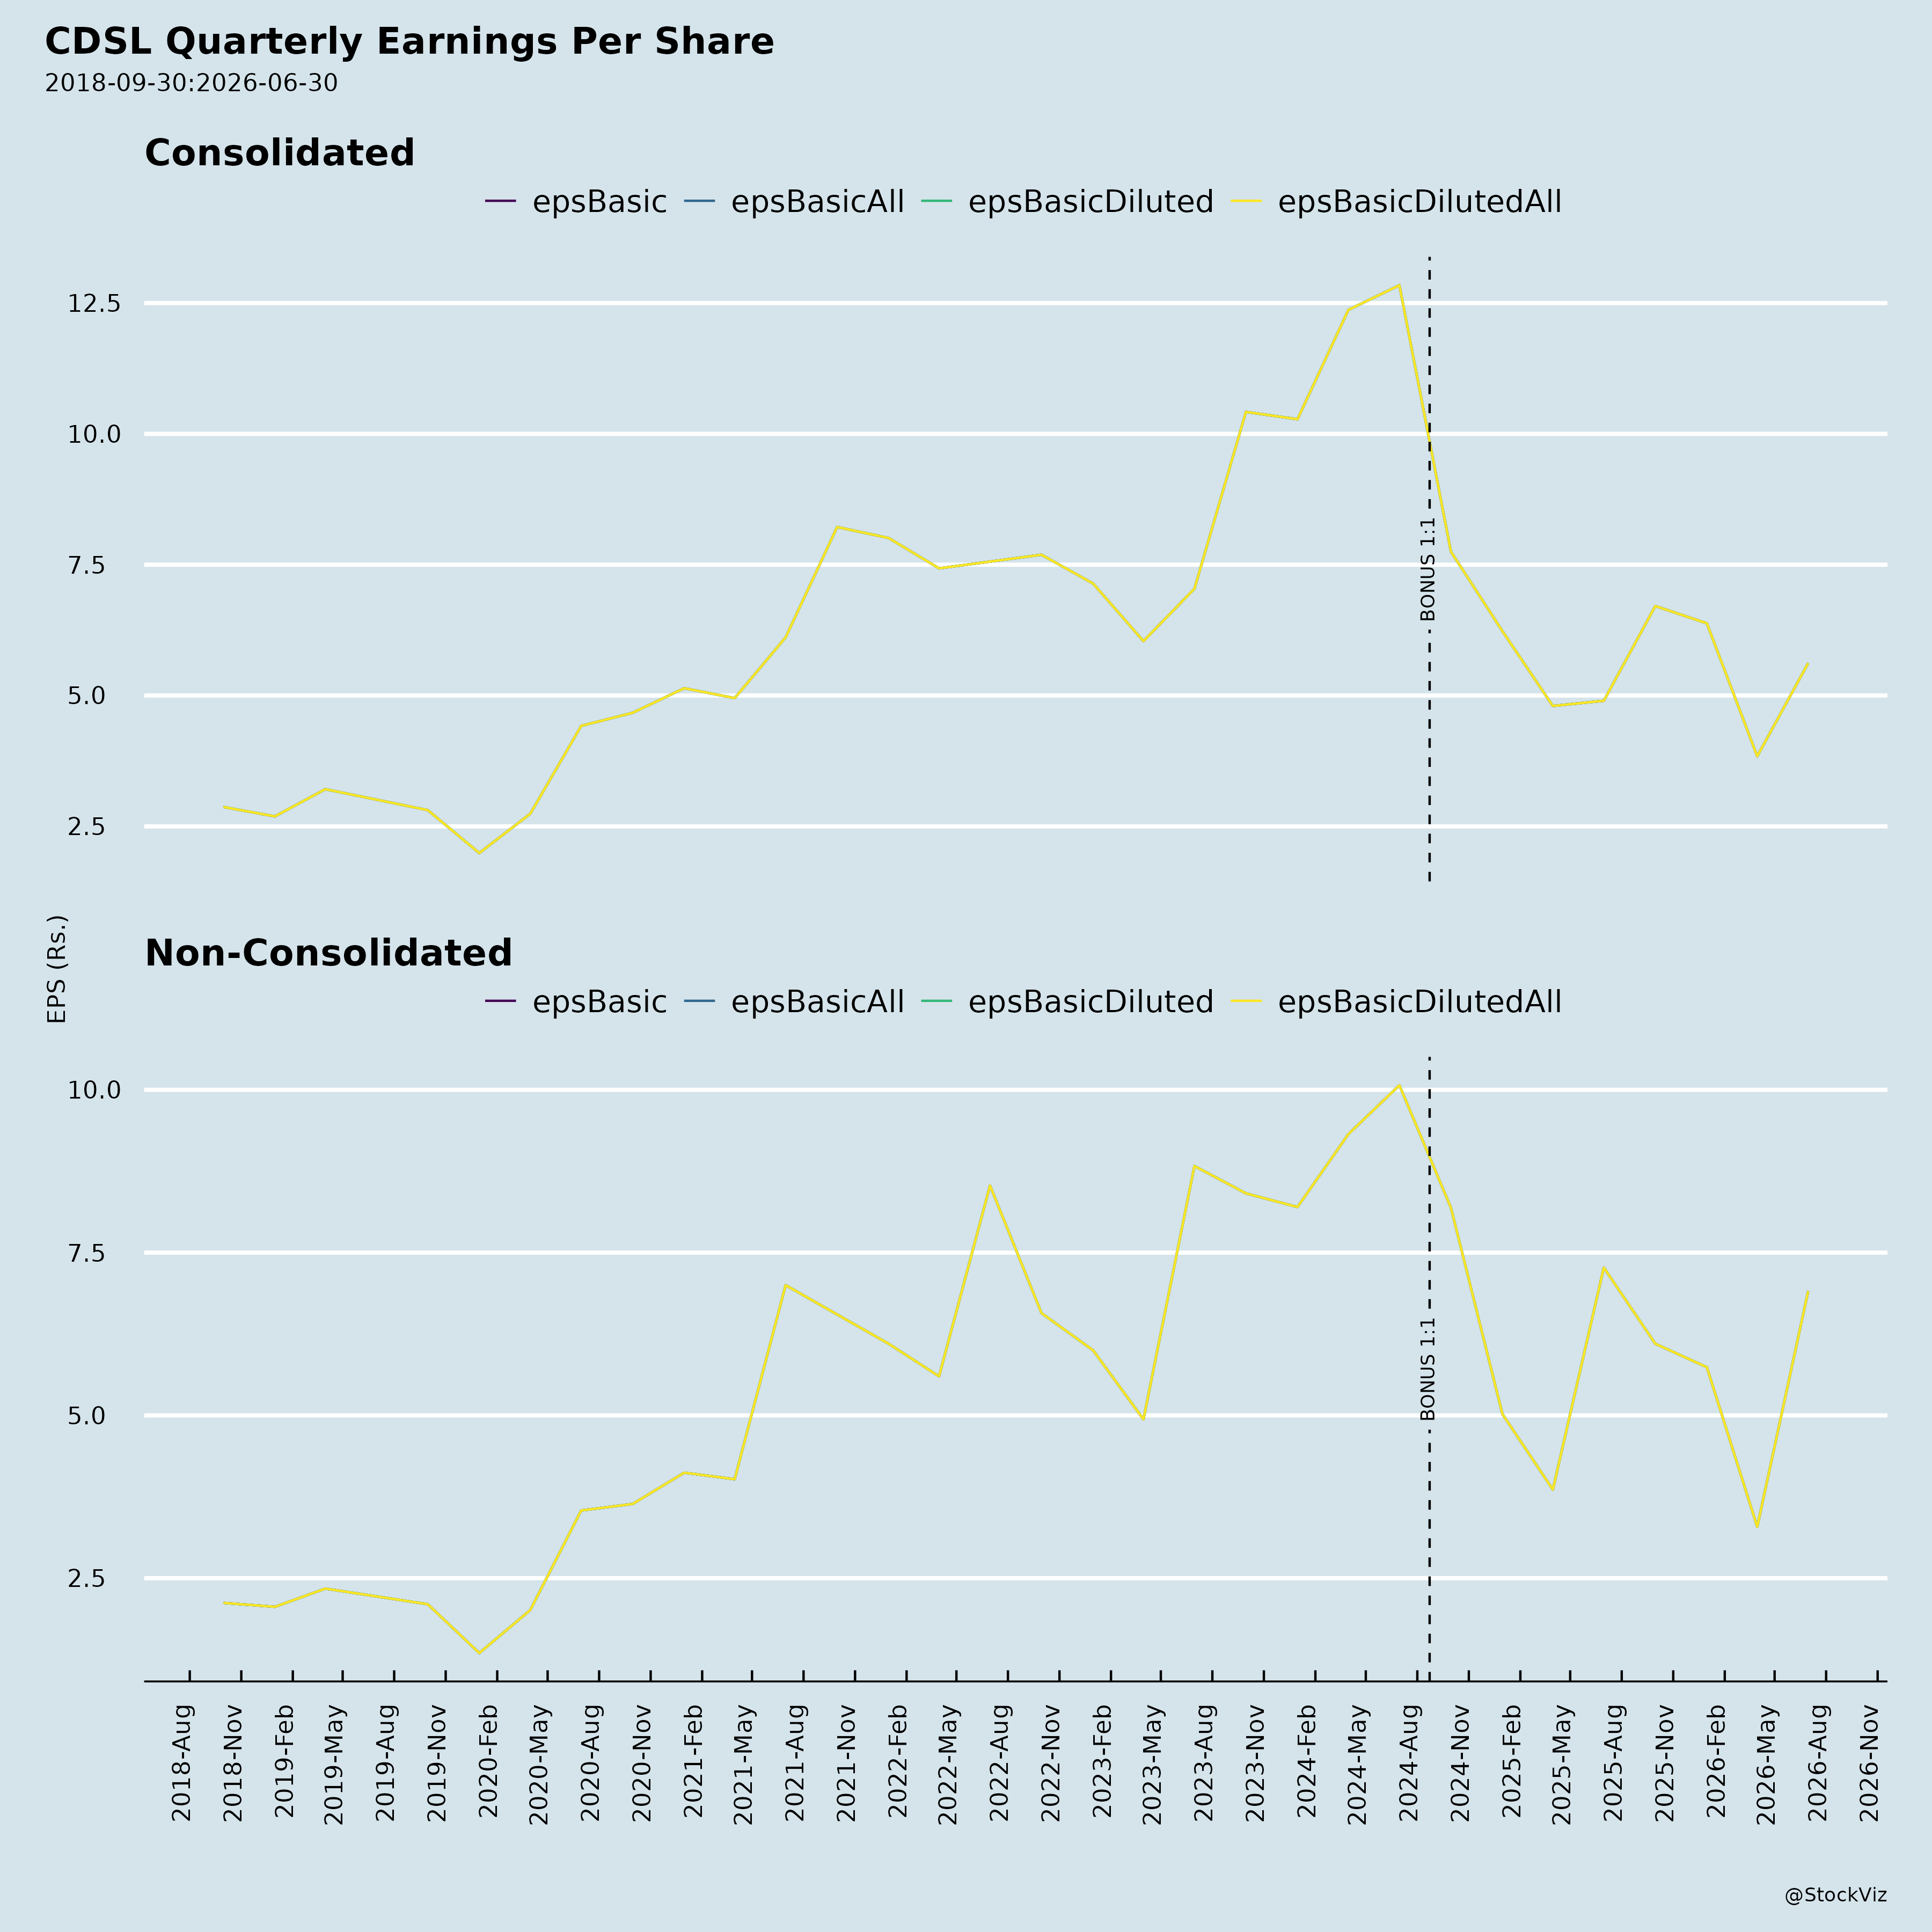
- Standalone net profit declined year-on-year. For Q1 FY26-27, standalone net profit was ₹144 crore, down 5% from ₹152 crore in Q1 FY25-26, even as standalone total income rose 5% to ₹327 crore. The company attributes part of this to lower dividend received from its subsidiary: ₹39.50 crore in Q1 FY26-27 versus ₹62 crore in Q1 FY25-26.
- Substantial dissent on leadership remuneration resolutions. At the 28th AGM (July 30, 2026), the ordinary resolutions ratifying the appointments and remuneration of the two new Executive Directors drew notable “against” votes: 6.07% against for Shri Amit Mahajan and 3.99% against for Smt. Nayana Ovalekar, far higher than the negligible dissent on other resolutions (0.0006%–0.11%).
- Leadership and compliance-function churn. Smt. Nayana Ovalekar ceased to hold the position of Chief Regulatory Officer & Compliance Officer with effect from the close of business hours on August 31, 2026, with Shri Farokh Patel appointed to that role effective September 01, 2026 — a transition in a critical regulatory position shortly after her appointment as Executive Director (Vertical 2) was ratified at the AGM.
2. Tailwinds and Growth Prospects
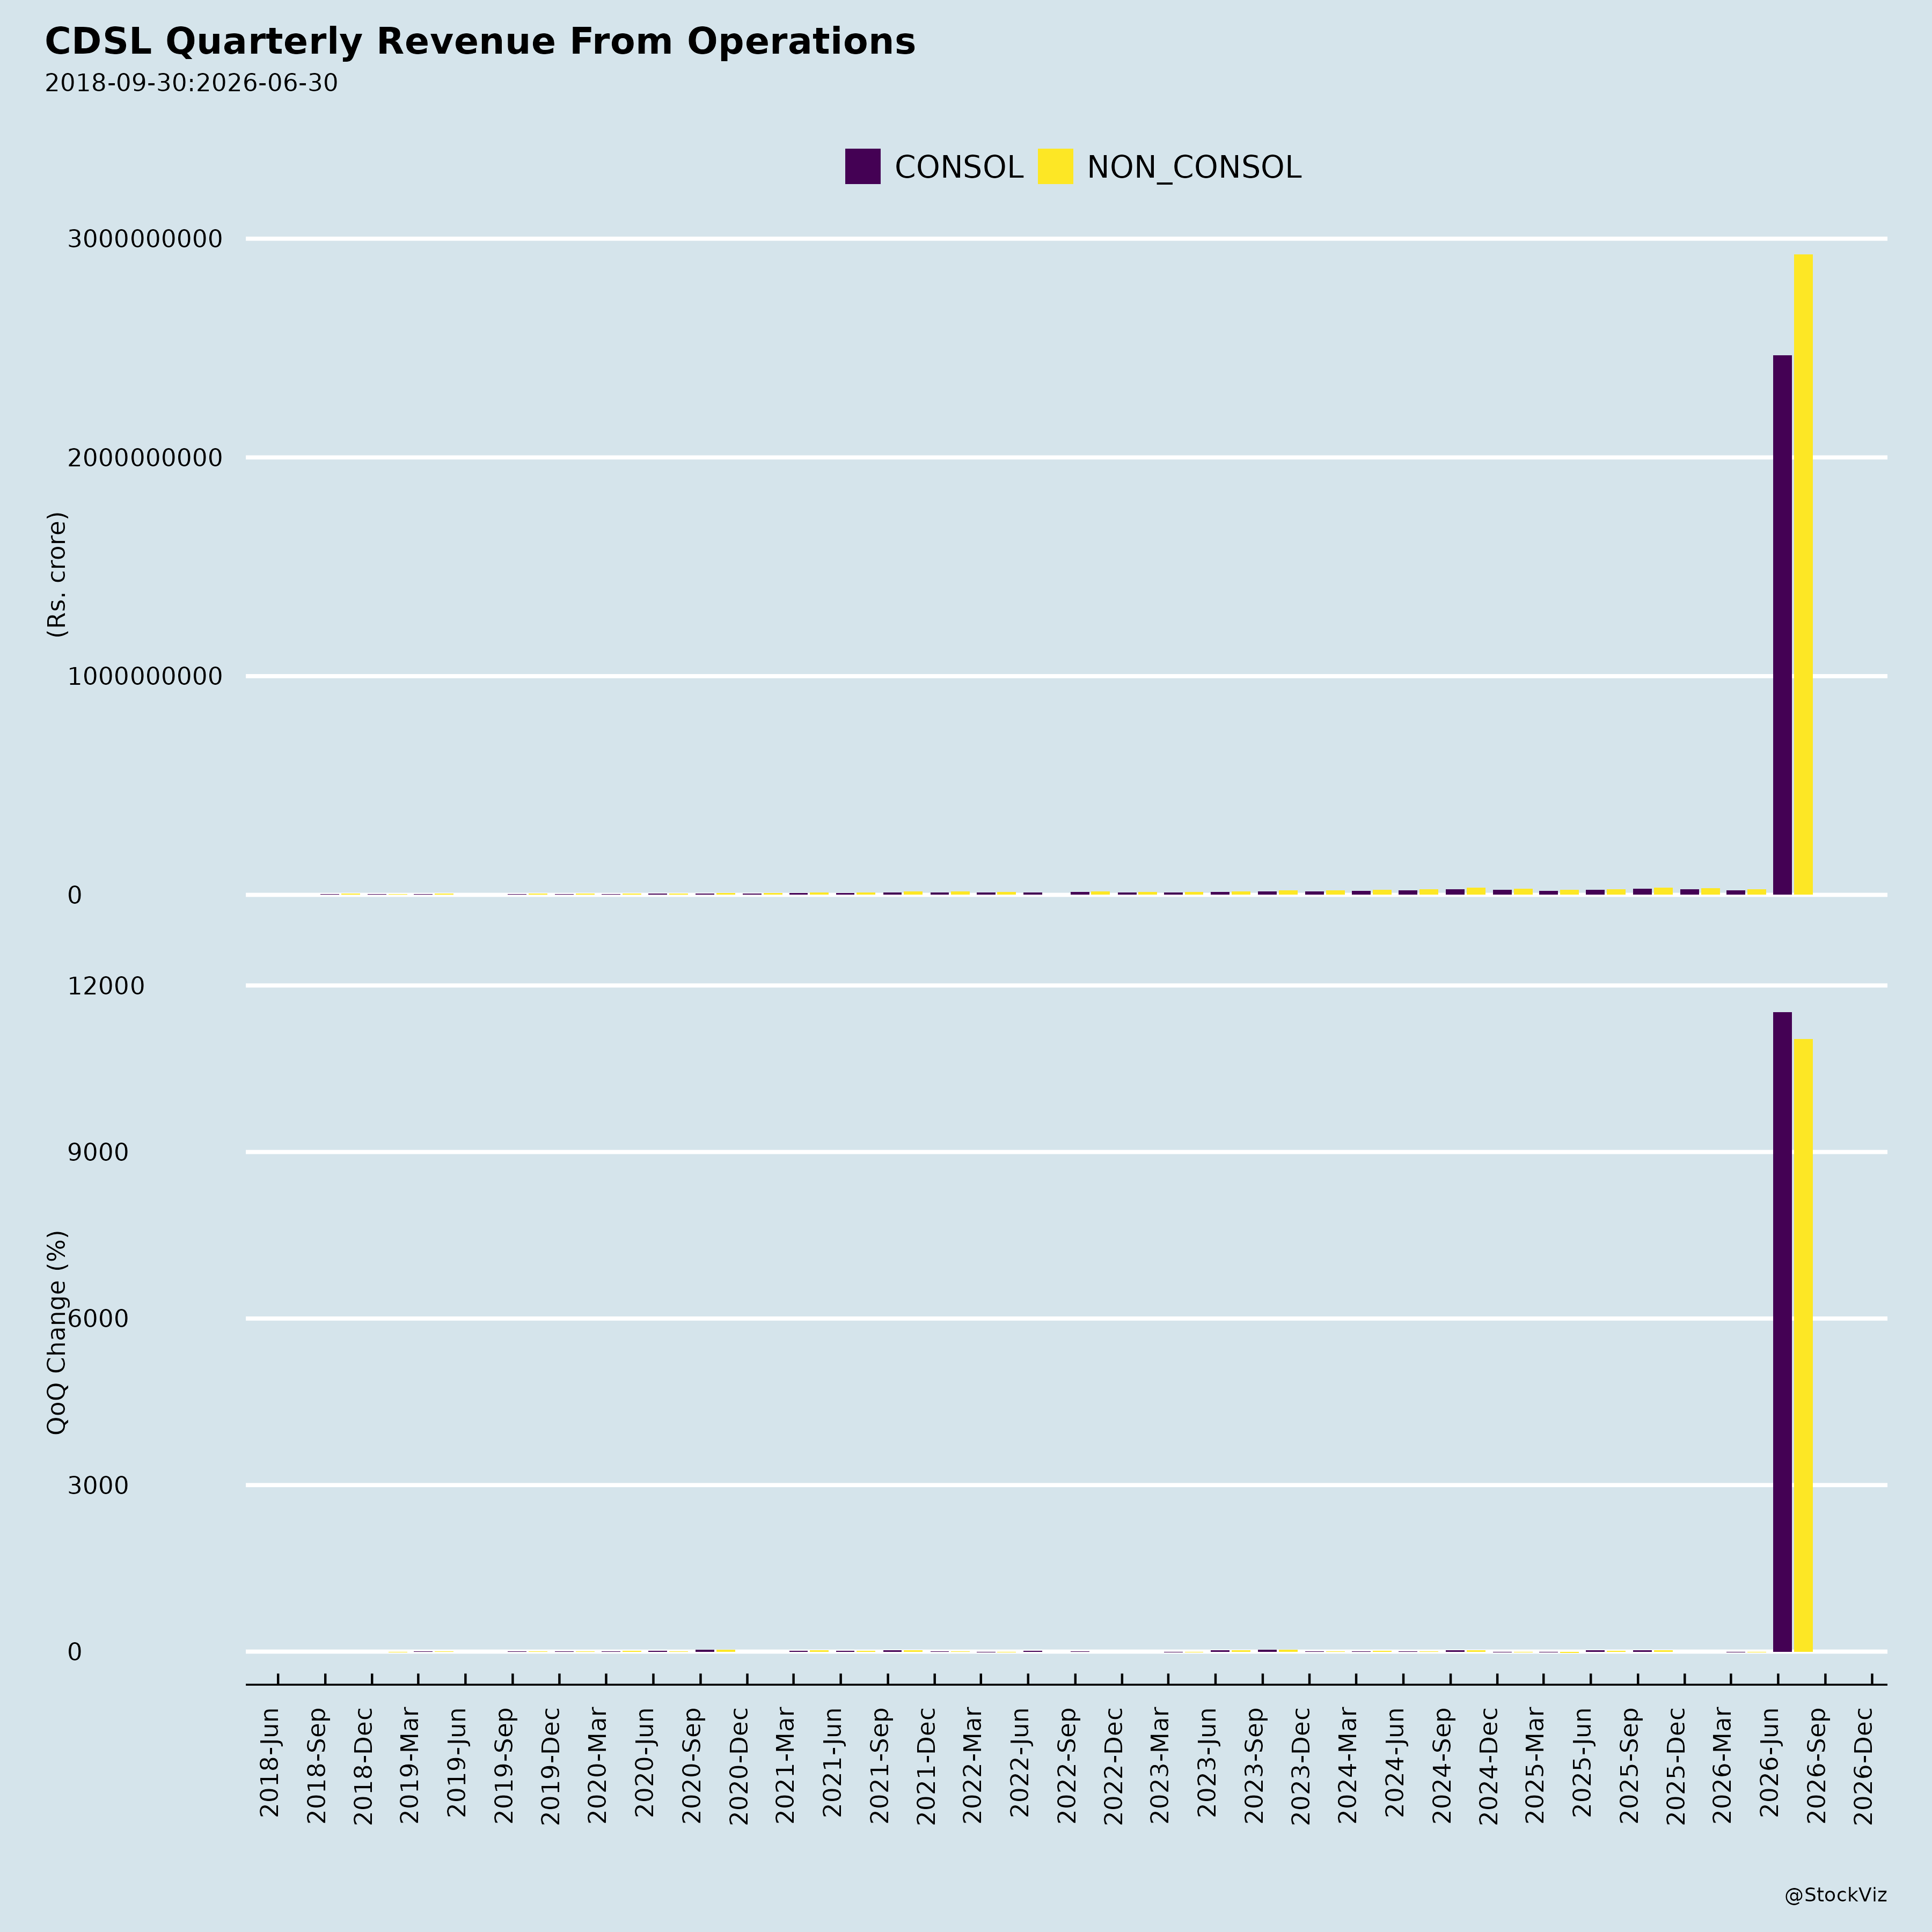
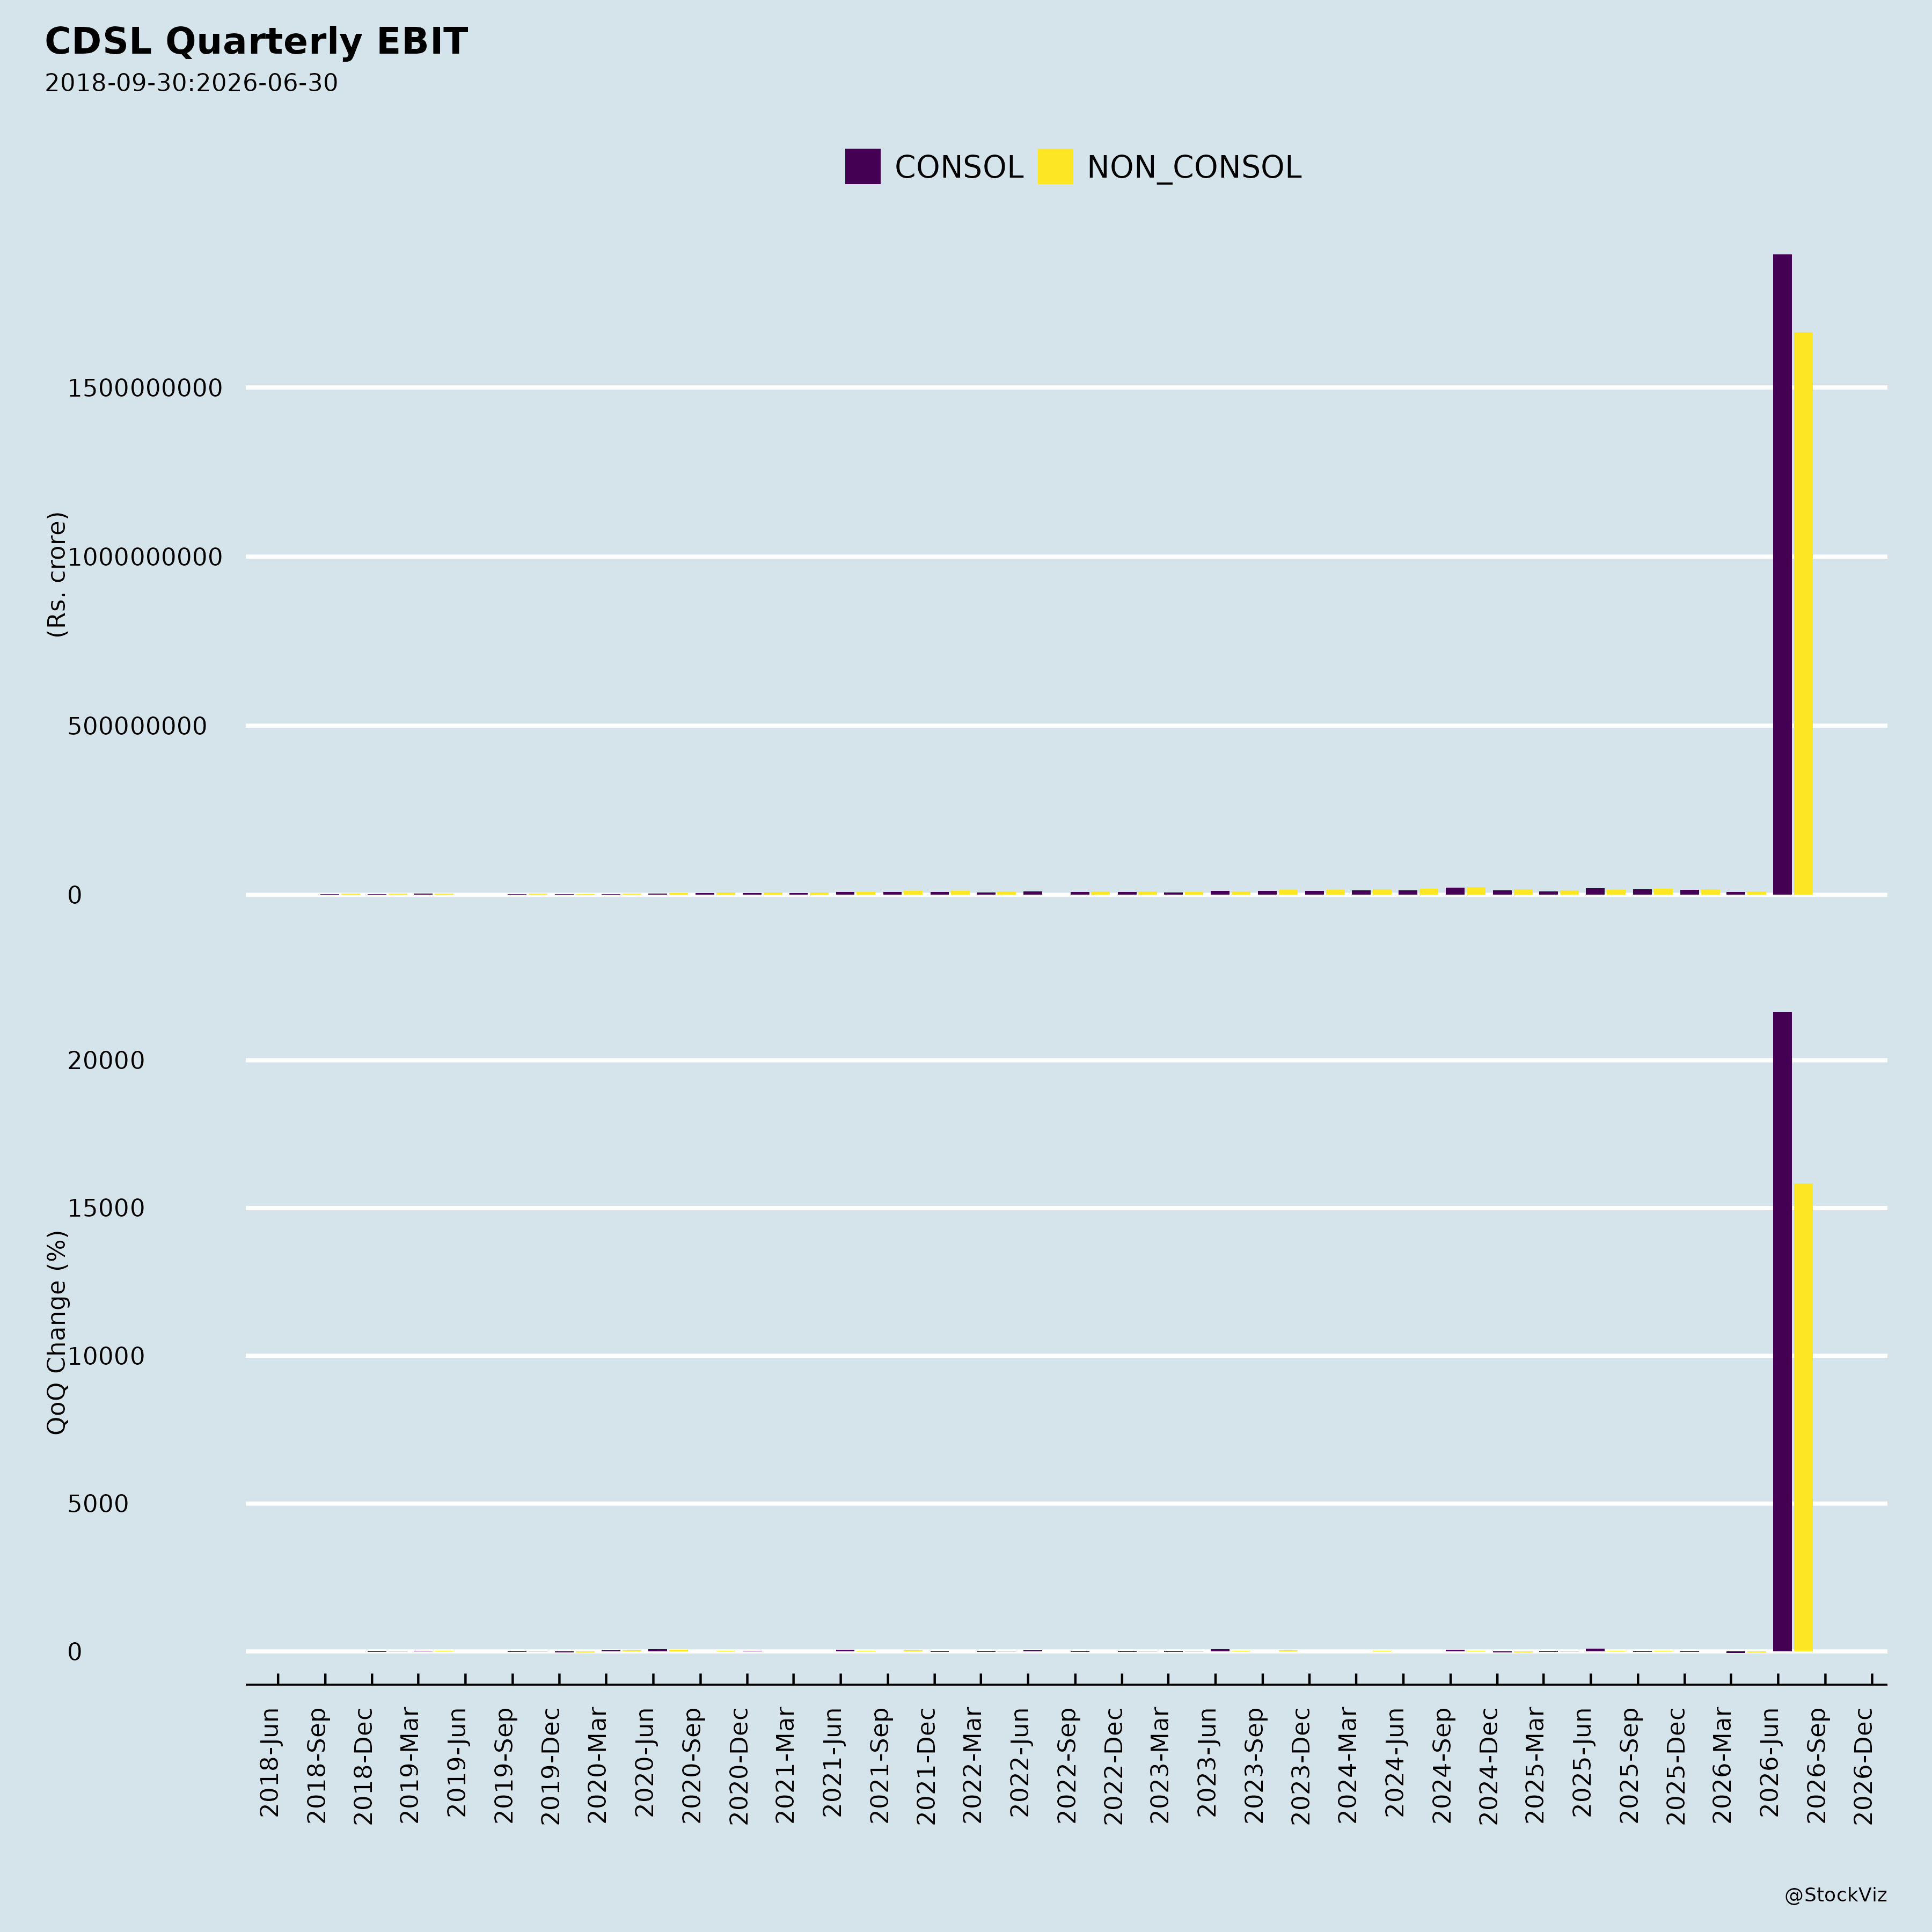
- Consolidated growth. Consolidated total income grew 15% YoY to ₹341 crore and consolidated net profit grew 15% YoY to ₹118 crore in Q1 FY26-27. On a QoQ basis, consolidated total income rose 27% and net profit rose 47%.
- Demat account scale. CDSL became the first depository to register over 18.59 crore demat accounts as on June 30, 2026, up from 15.86 crore as of June 30, 2025, with approximately 58 lakh new accounts opened during the quarter. It serves 588+ depository participants.
- Assets Under Custody rose to ₹88.2 lakh crore.
- Strategic investment in account aggregator ecosystem. CDSL completed a ₹1 crore investment for a 2% stake in Sahamati Foundation, an RBI-recognised Self-Regulatory Organisation for the Account Aggregator ecosystem, as part of a cross-industry initiative to strengthen governance, technology infrastructure, and standards for financial data sharing.
- Investment in bullion market infrastructure. CDSL was allotted the second tranche of a rights issue of India International Bullion Holding IFSC Limited (IIBHL) — 9,20,00,000 equity shares of ₹1 each, amounting to ₹9,20,00,000, representing a 20% equity stake in IIBHL (September 09, 2026).
- Leadership capacity building. The Governing Board approved the appointment of Shri Amit Mahajan as Executive Director for Vertical 1 (Critical Operations), effective June 11, 2026, and Smt. Nayana Ovalekar as Executive Director for Vertical 2 (Regulatory, Compliance, Risk Management & Investor Grievances), effective June 19, 2026, each for five years.
- Investor education and recognition. CDSL IPF conducted 40+ Investor Awareness Programmes during the quarter, and CDSL received multiple awards, including “Most Innovative Fintech Company in Asia-Pacific” (Global Finance Magazine’s The Innovators 2026), “Innovation in Settlement Efficiency” (Global Custodian Leaders in Asia Custody Awards 2026), a Golden Peacock award, and an ET BrandEquity Shark Award for the “SEBI vs SCAM” campaign.
3. Key Risks
- Dependence on subsidiary dividend flows. The standalone results explicitly note that other income includes dividend from a subsidiary, which fell to ₹39.50 crore in Q1 FY26-27 from ₹62 crore a year earlier — a swing that contributed to the standalone net profit decline despite higher total income.
- Governance and shareholder alignment signals. The elevated “against” votes on the Executive Director remuneration resolutions indicate meaningful shareholder dissent on leadership pay and appointment terms.
- Regulatory-key-person transition risk. The change in Chief Regulatory Officer & Compliance Officer effective September 01, 2026, following the AGM ratification of Smt. Ovalekar’s Executive Director role, represents a transition in a critical compliance function.
- No material headwinds, challenges, or risks were identified in the analyst-meeting announcement regarding CDSL’s scheduled one-to-one meetings with Nippon India Mutual Fund and HDFC Mutual Fund in Mumbai on September 16, 2026.
4. Management Guidance Versus Observed Performance
- No explicit forward-looking financial guidance (revenue, margin, or earnings targets) is provided in the supplied material. The analyst-meeting announcement states that no unpublished price sensitive information will be shared at the September 16, 2026 meetings.
- Management commentary versus observed results. Shri Nehal Vora, MD & CEO, described the quarter as reflecting “continued focus on building scale and depth of leadership,” citing the new Executive Directors and investor education initiatives such as Amar Chitra Katha. Observed performance supports the scale narrative — record 18.59 crore demat accounts, ~58 lakh new accounts in the quarter, and AUC of ₹88.2 lakh crore — while the standalone net profit decline of 5% YoY and the lower subsidiary dividend show that reported profitability did not track the scale gains in the standalone numbers. Consolidated net profit did grow 15% YoY, aligning with the growth narrative at the consolidated level.
- AGM outcomes versus board actions. All five resolutions set out in the AGM notice (July 30, 2026) were passed with the requisite majority, including adoption of FY2025-26 audited standalone and consolidated financial statements, declaration of final dividend, appointment of Smt. Geetha Gangadharan as Non-Independent Director in place of Ms. Kamala Kantharaj, and ratification of both Executive Director appointments — though the latter two carried the highest dissent levels.
Broker Narrative
Brokers initiated with a Hold, leaning on CDSL’s ~73% demat duopoly share and stable issuer fees while cautioning about volume declines, alternate KYC stacks, revenue-linked cost caps, and rising SEBI fees. The narrative later shifted as demat additions, IPO volumes, issuer/ISIN counts, and insurance partnerships scaled strongly, but margin expansion stalled under higher expenses and KYC/API pricing cuts. By the final report the stance was Neutral/Reduce, acknowledging 24% YoY revenue growth while flagging PBT/PAT pressure from a 33% expense rise and pricing-driven revenue headwinds.
Fears that came true
- The threat from alternate identification stacks and KYC pricing power materialized when Apr’26 KYC revisions cut revenue and API revenue declined as previously free services became chargeable, periods that coincided with negative actual returns such as -16.4% in Nov’25.
- The flagged revenue-linked cost cap and rising SEBI/regulatory opex manifested as CVL’s PBT/PAT declining 11%/12% YoY on a 33% expense surge and a 52% QoQ other-income drop, contributing to negative-return episodes such as -28.1% in Dec’24.
Broker Timeline
15 broker calls · 2023-08-11 to 2026-11-02
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.