BRITANNIA
Equity Metrics
November 18, 2026
Britannia Industries Limited
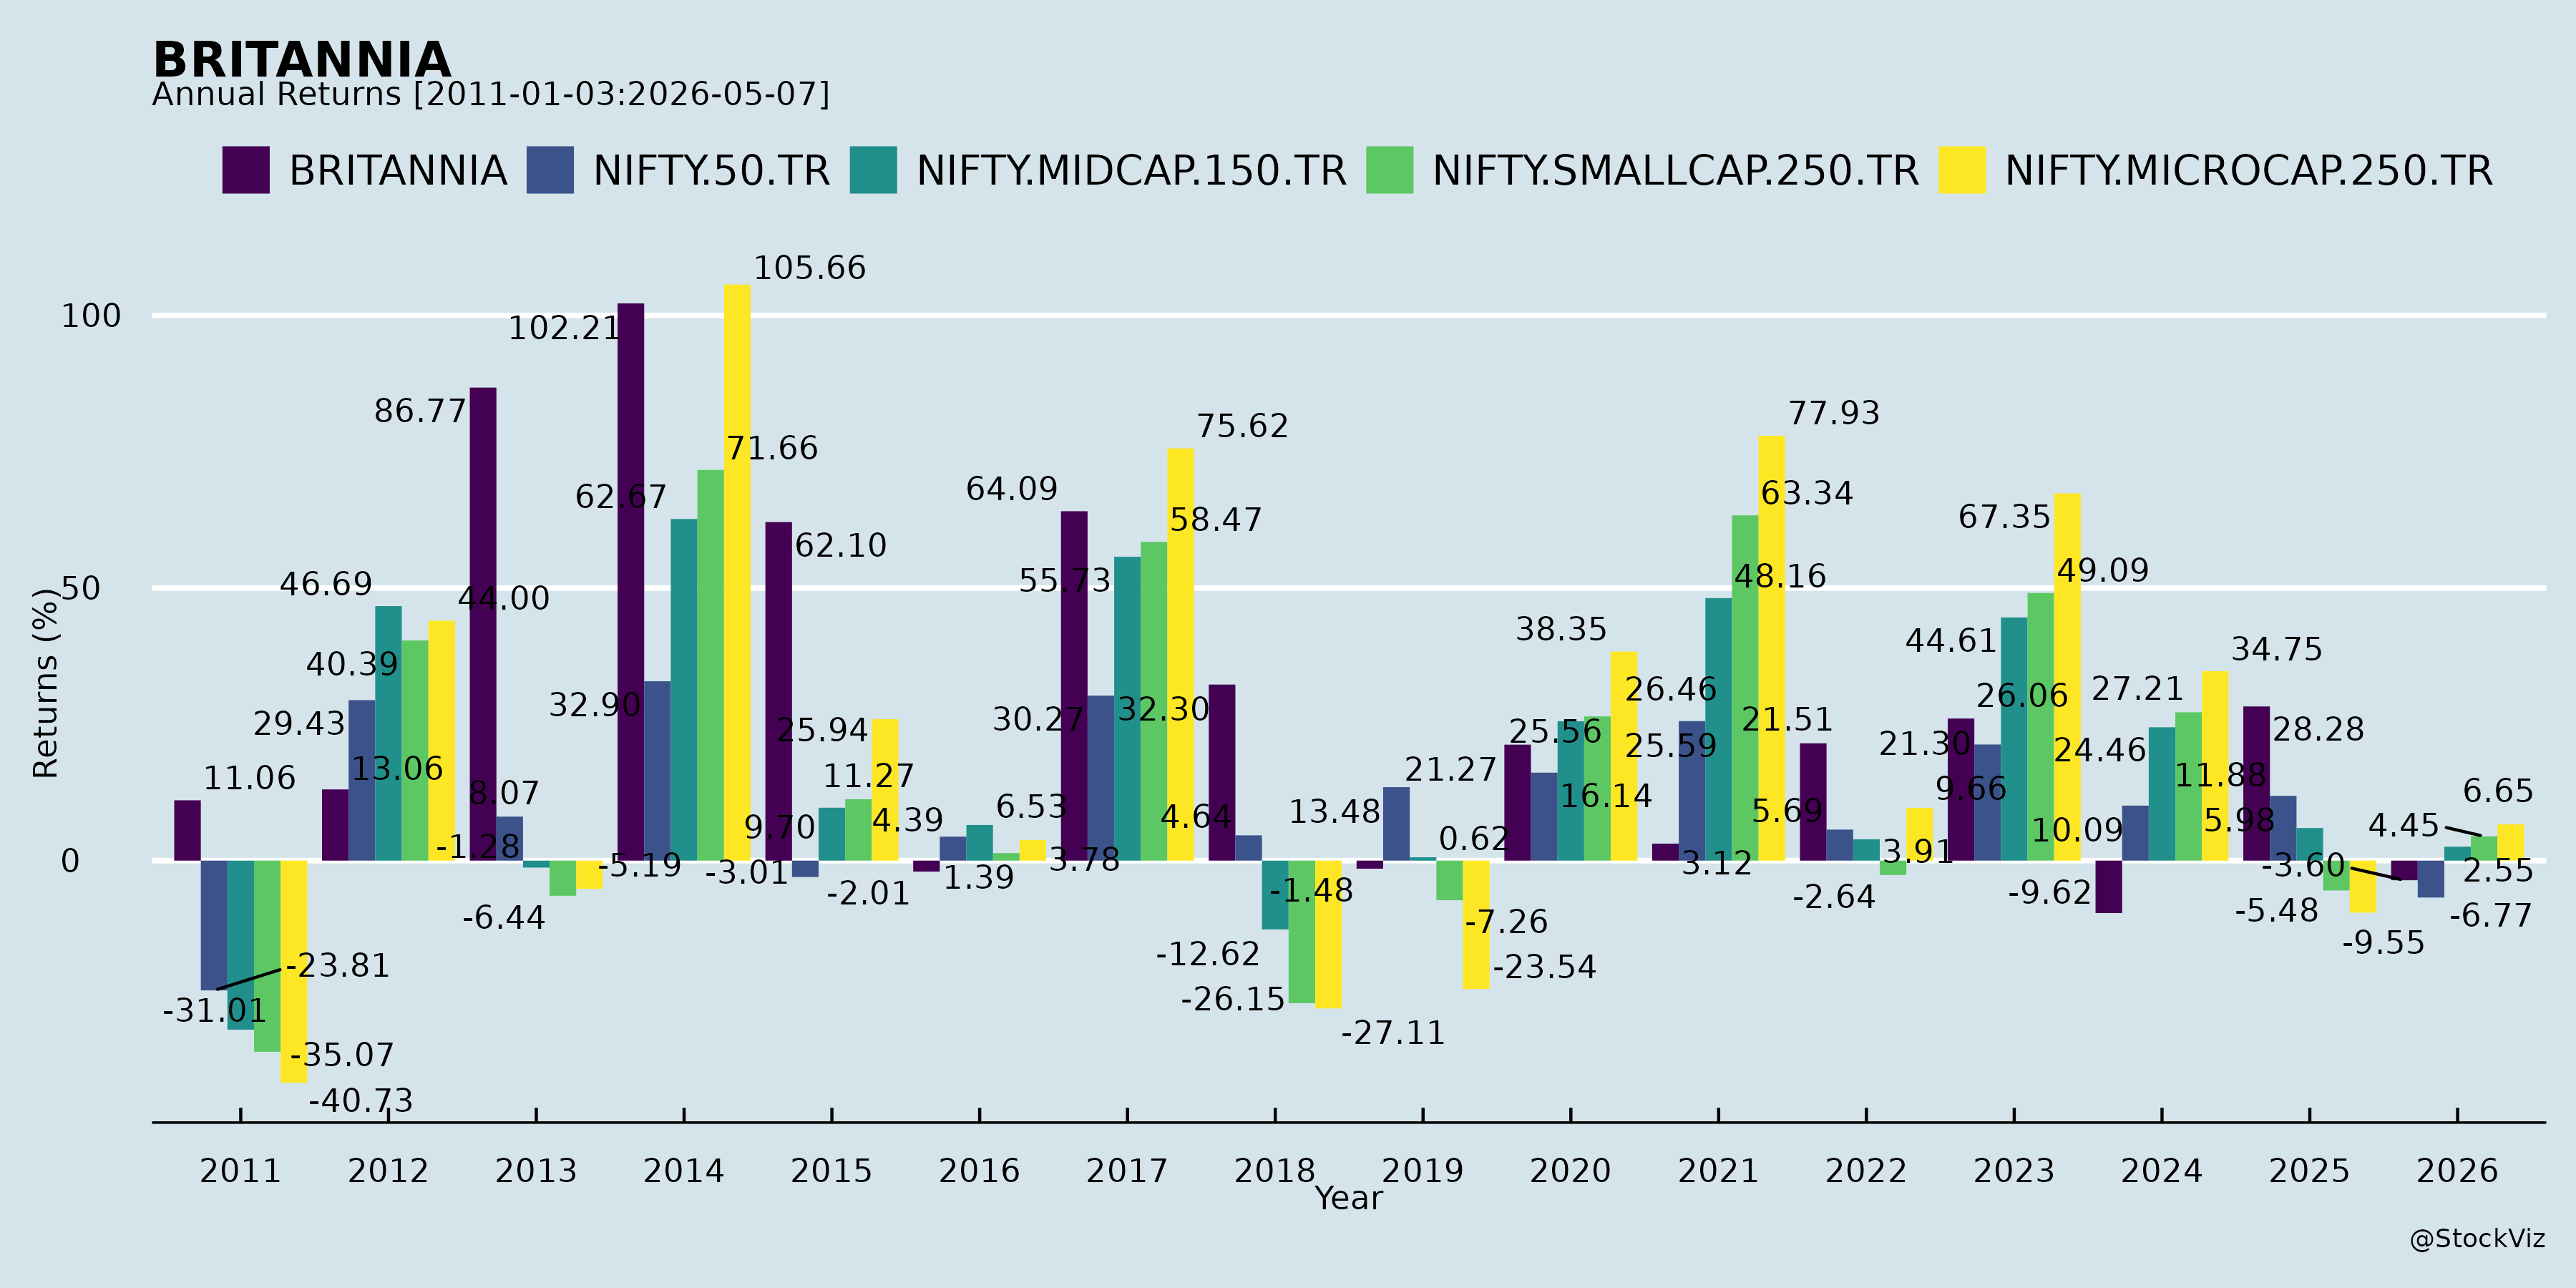
Annual Returns
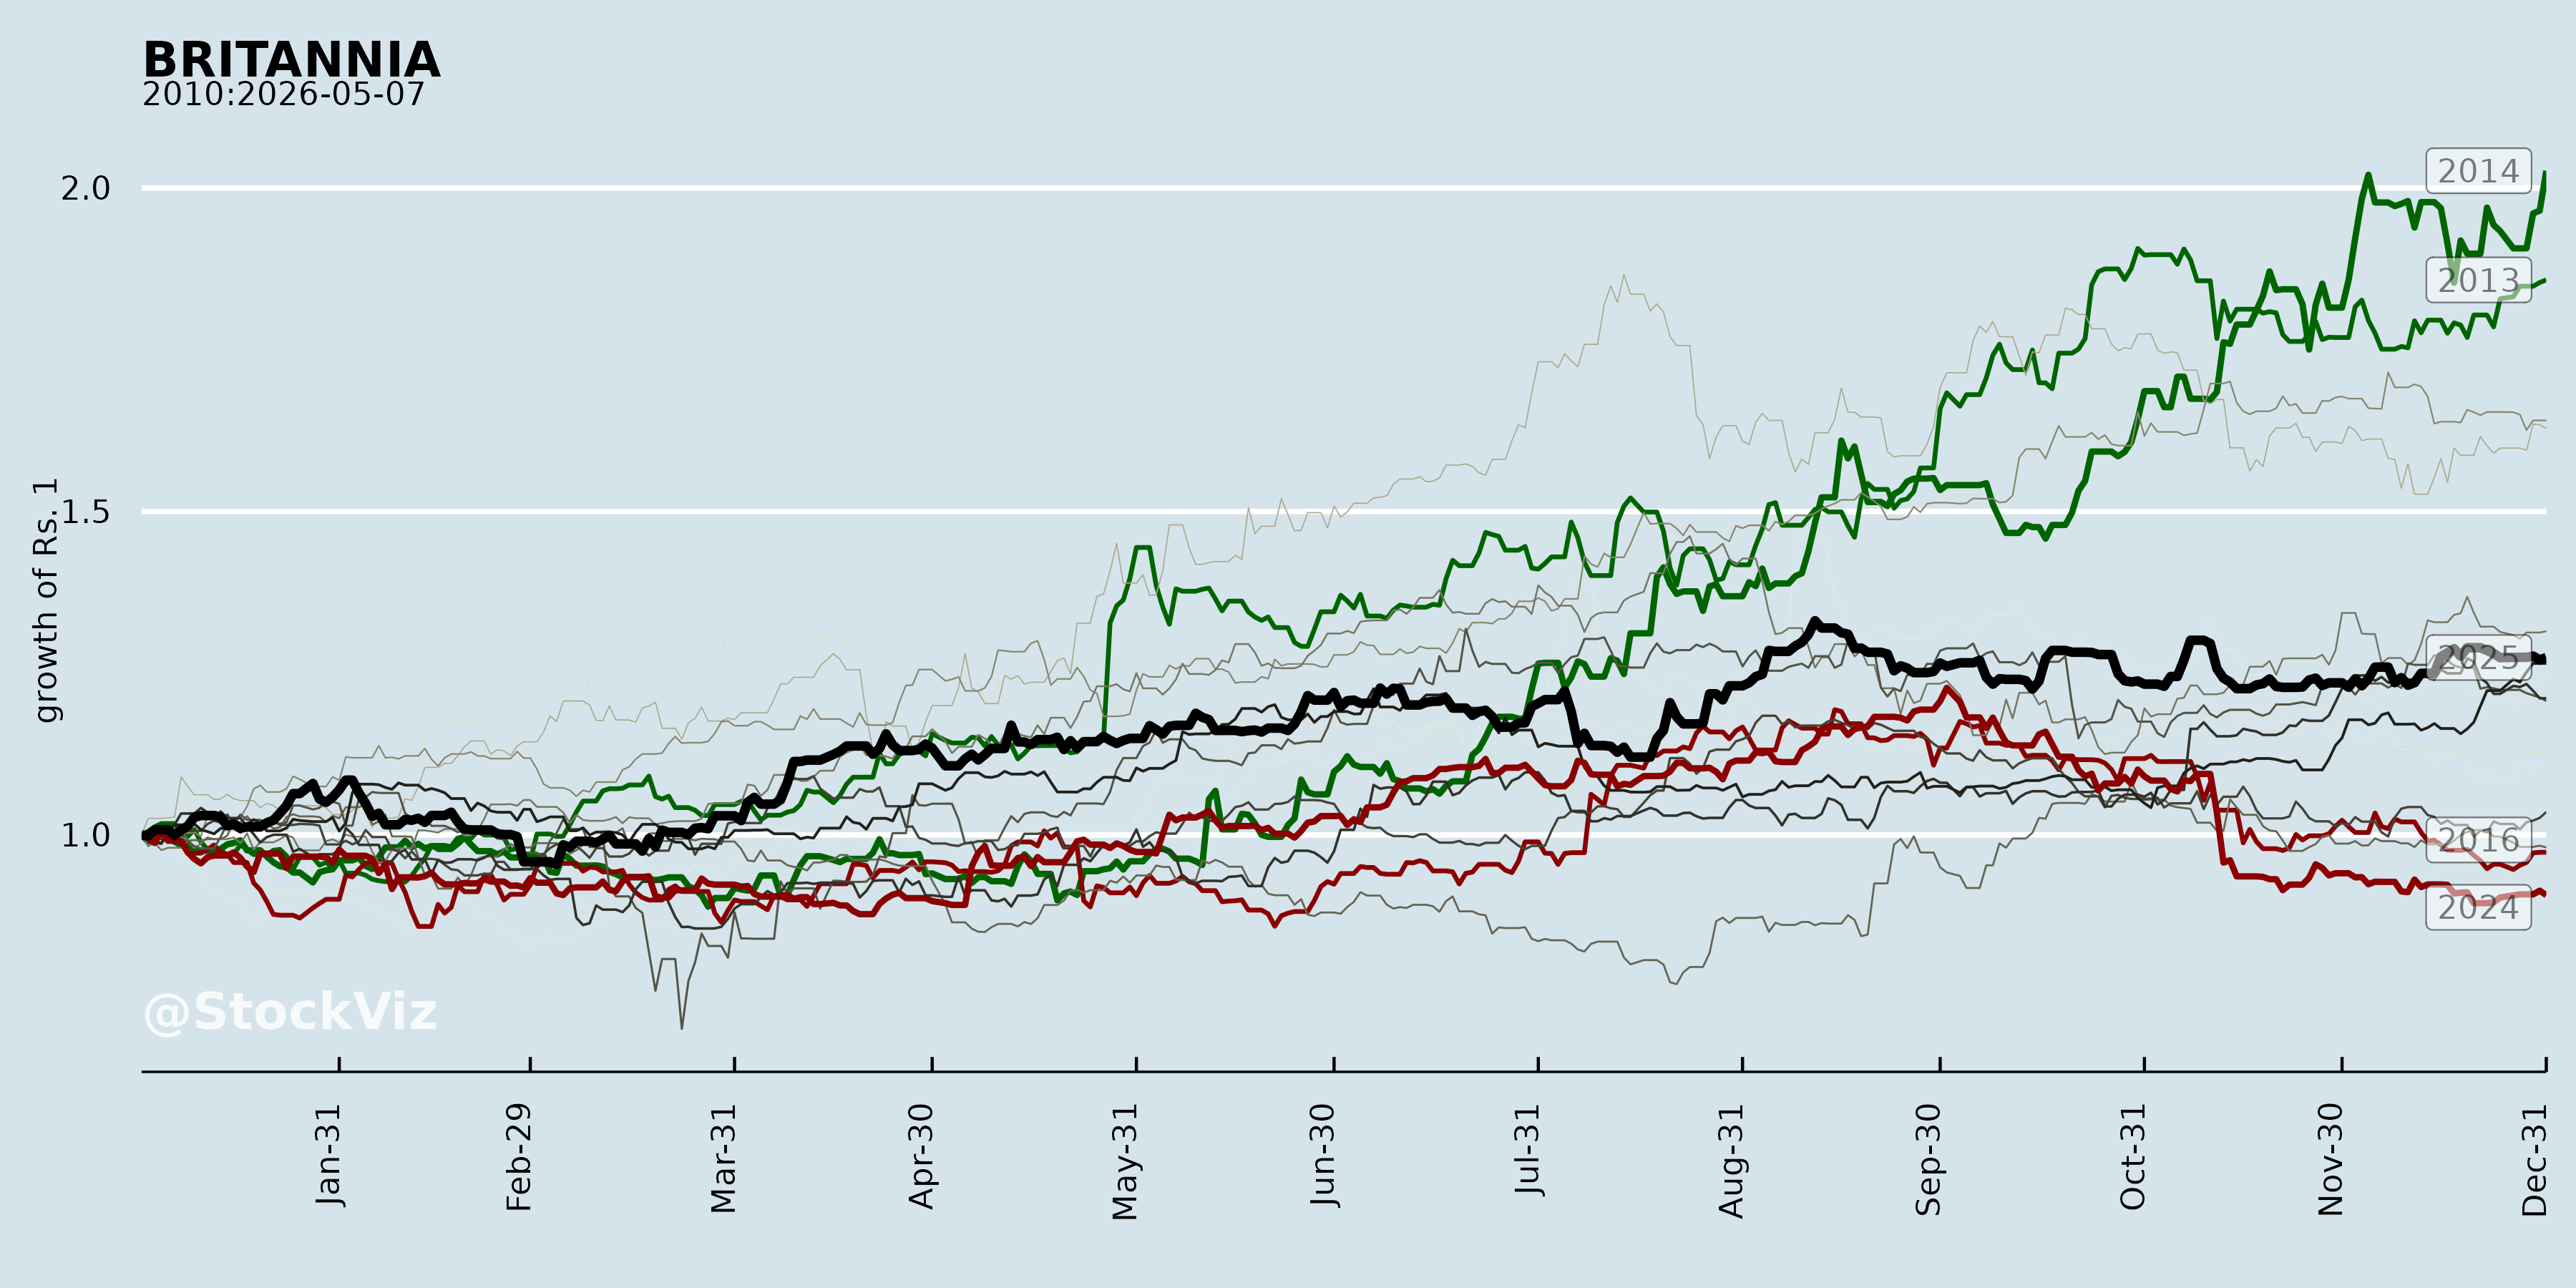
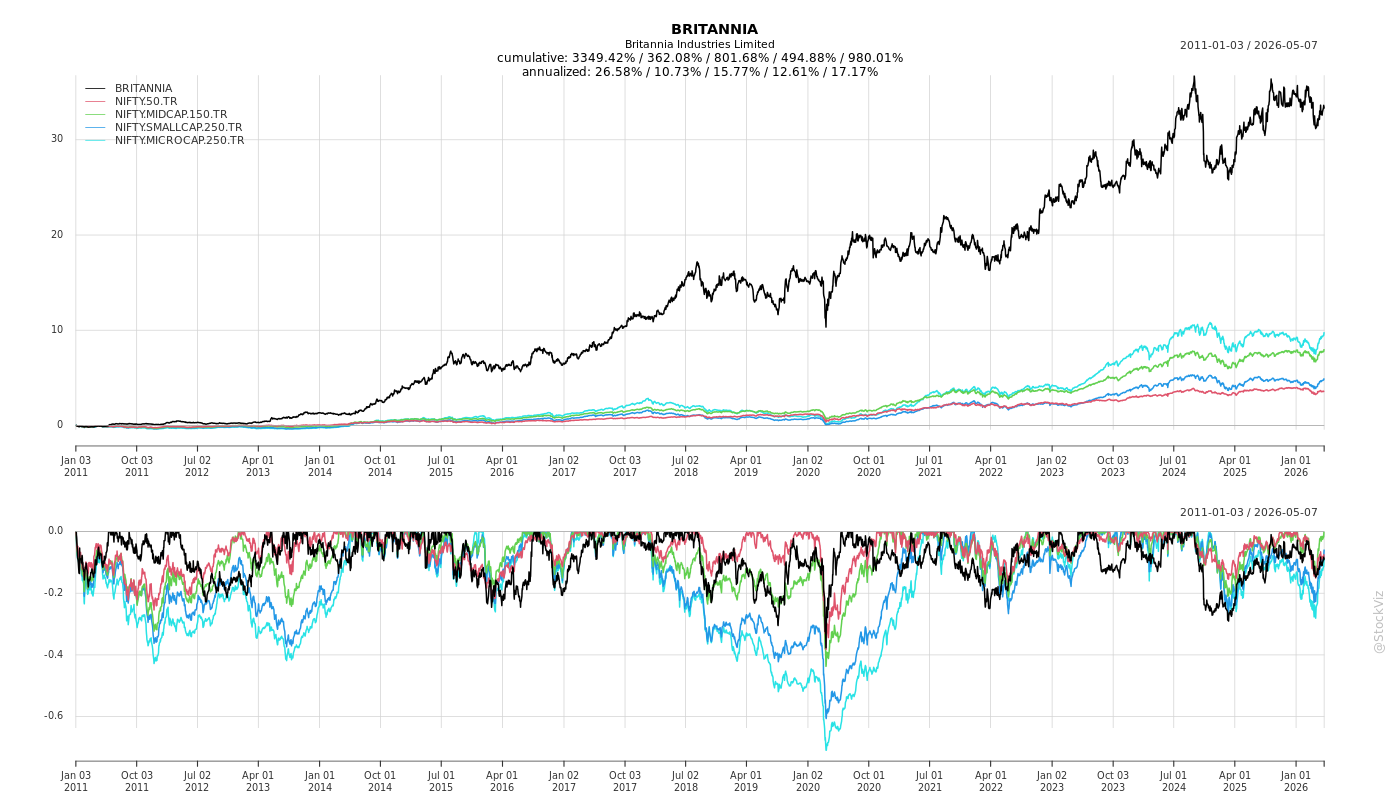
Cumulative Returns and Drawdowns
Fundamentals
Ownership
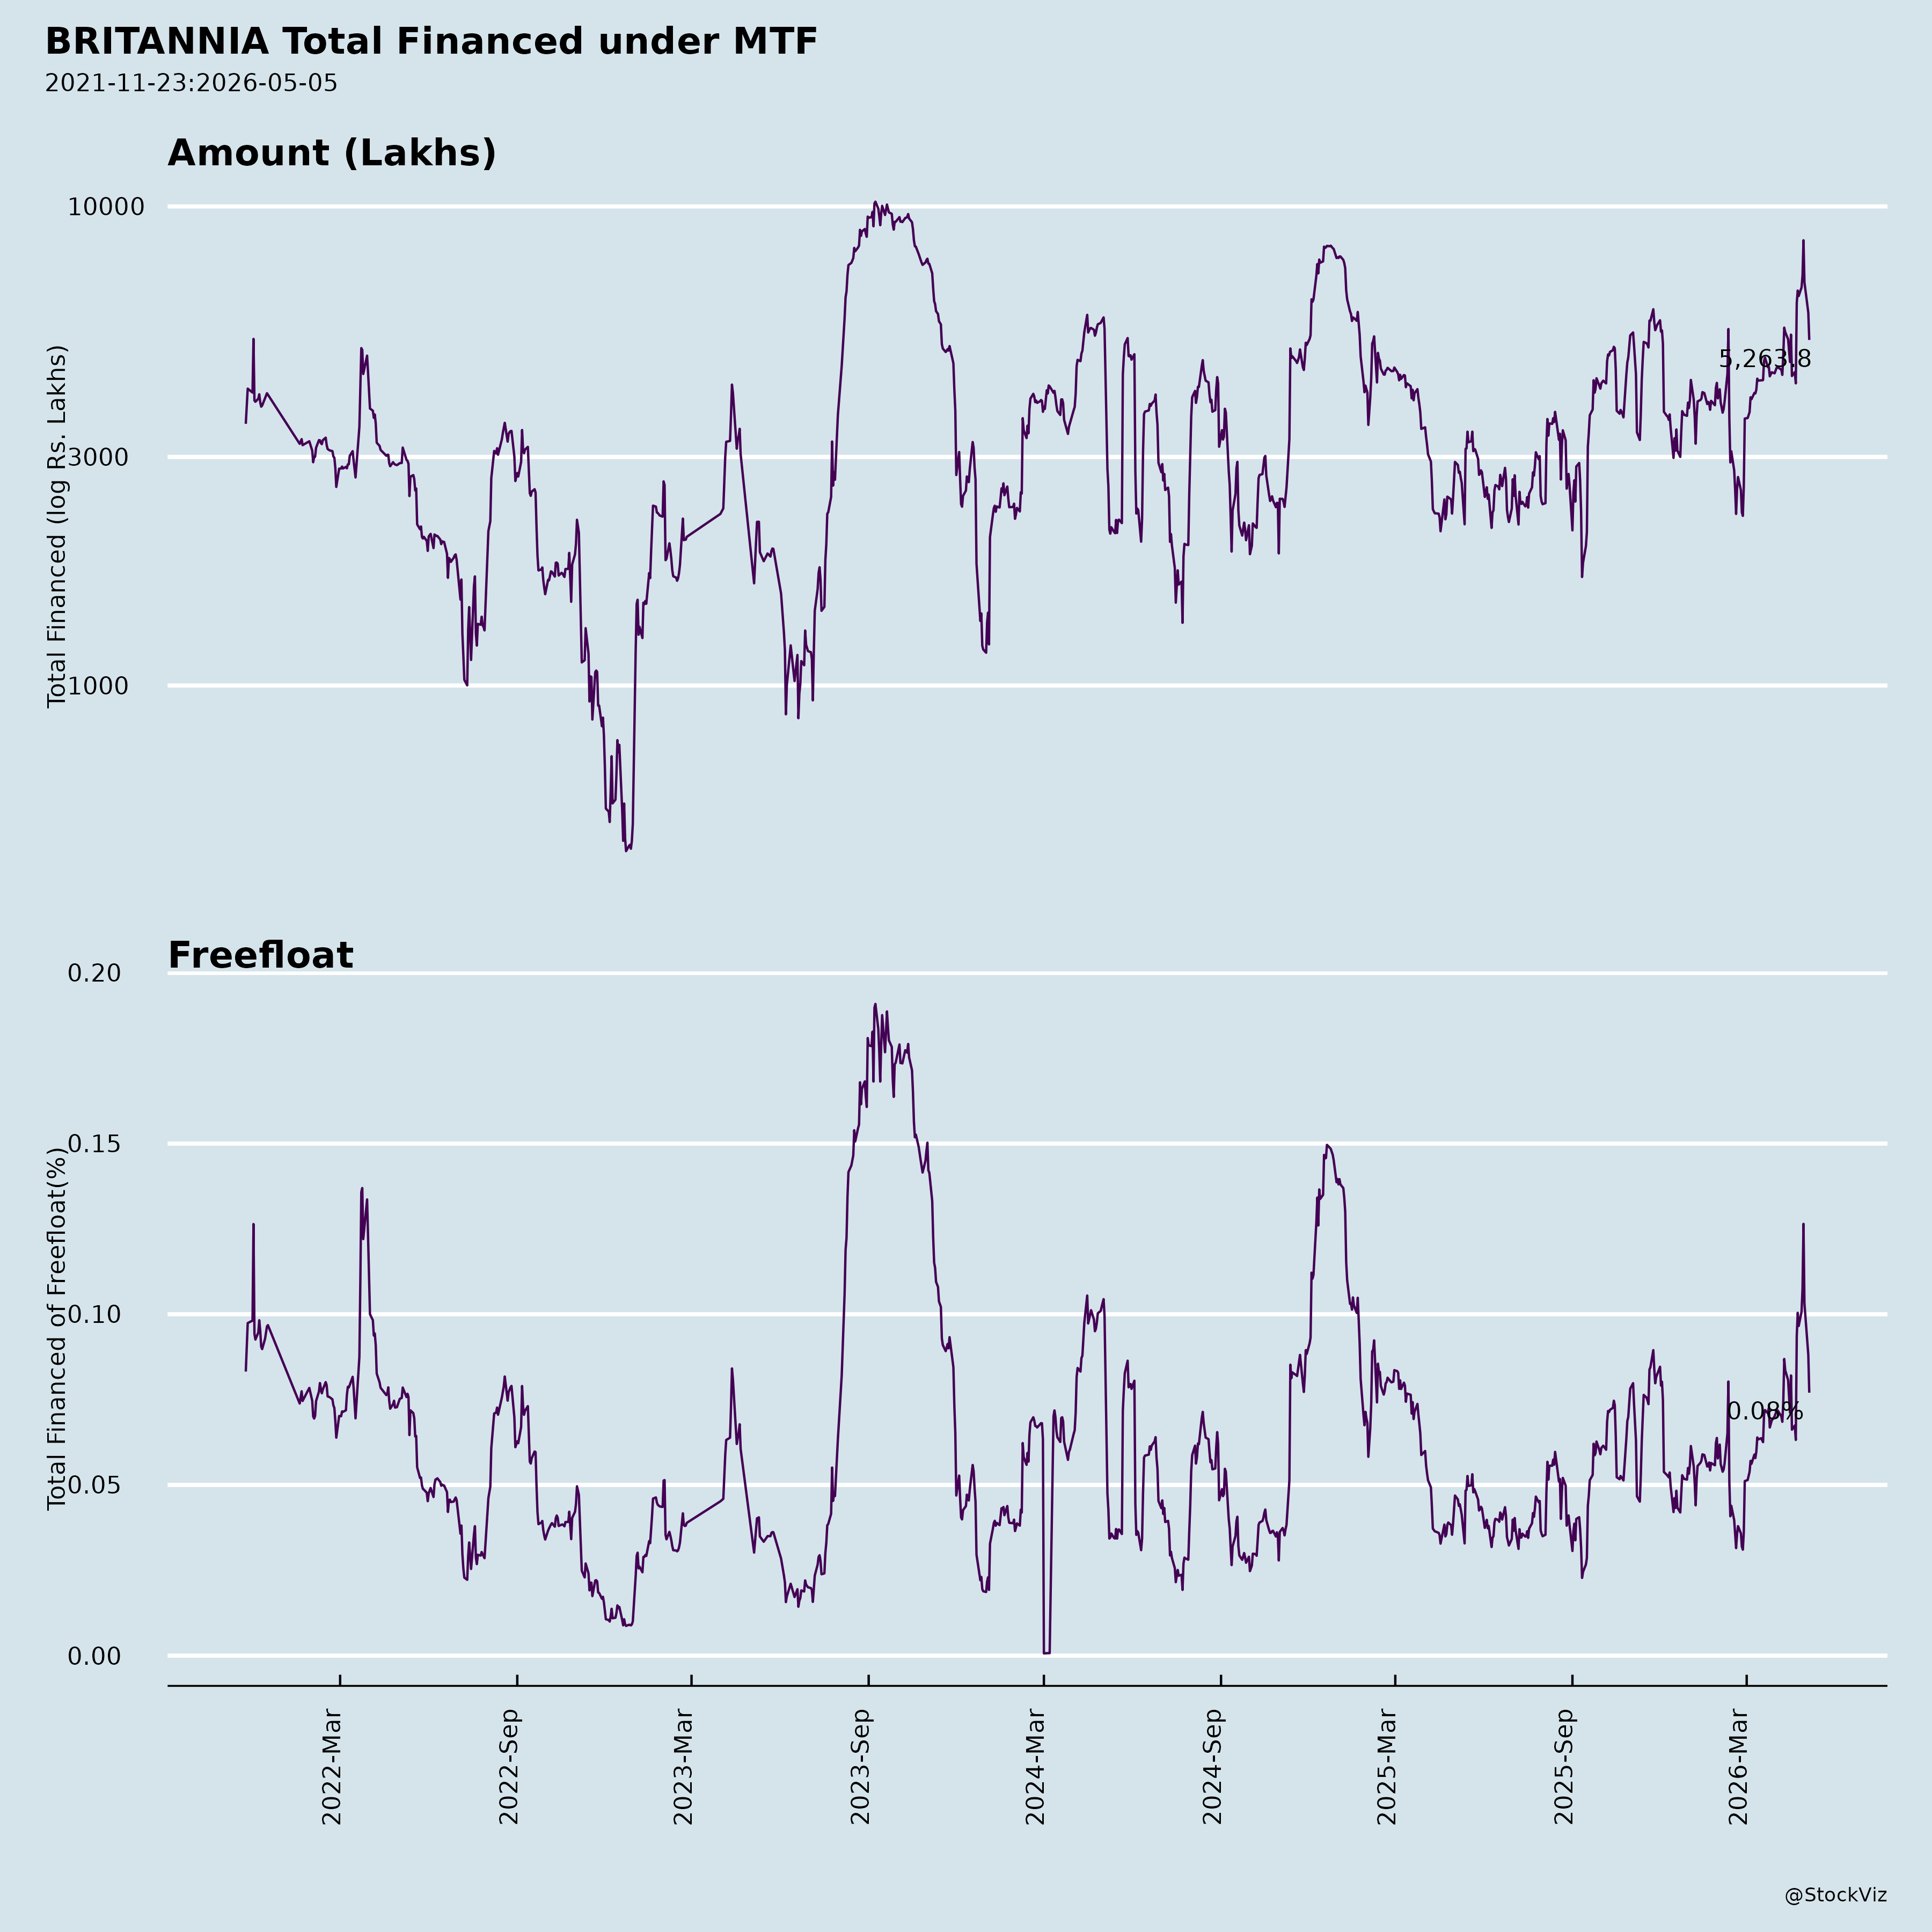
Margined
AI Summary
asof: 2026-09-14
Britannia Industries — Recent Corporate Announcements
1. Headwinds and Challenges
- The year began with a West Asia conflict, which led to a steep increase in the cost of fuel and shipment charges across both domestic and international businesses (CEO & MD statement, 6 August 2026).
- The company continues to closely monitor the evolving geopolitical situation in West Asia and crude oil volatility for potential impact on international operations and domestic input costs.
- International business faced supply chain constraints, which began normalising only in the latter part of the June 2026 quarter.
- The New Labour Codes, notified with effect from 21 November 2025, provide a unified definition of “Wages” for employee benefit computations. This resulted in the Group recognising ₹48.56 crores (consolidated) and ₹46.46 crores (standalone) as past service cost during the year ended 31 March 2026 towards increased gratuity and compensated absences liabilities. The Group continues to monitor implementation developments and associated rules.
- Potential risks and uncertainties cited include general economic conditions, commodities and currency fluctuations, competitive product and pricing pressures, industrial relations, and regulatory developments.
2. Tailwinds and Growth Prospects
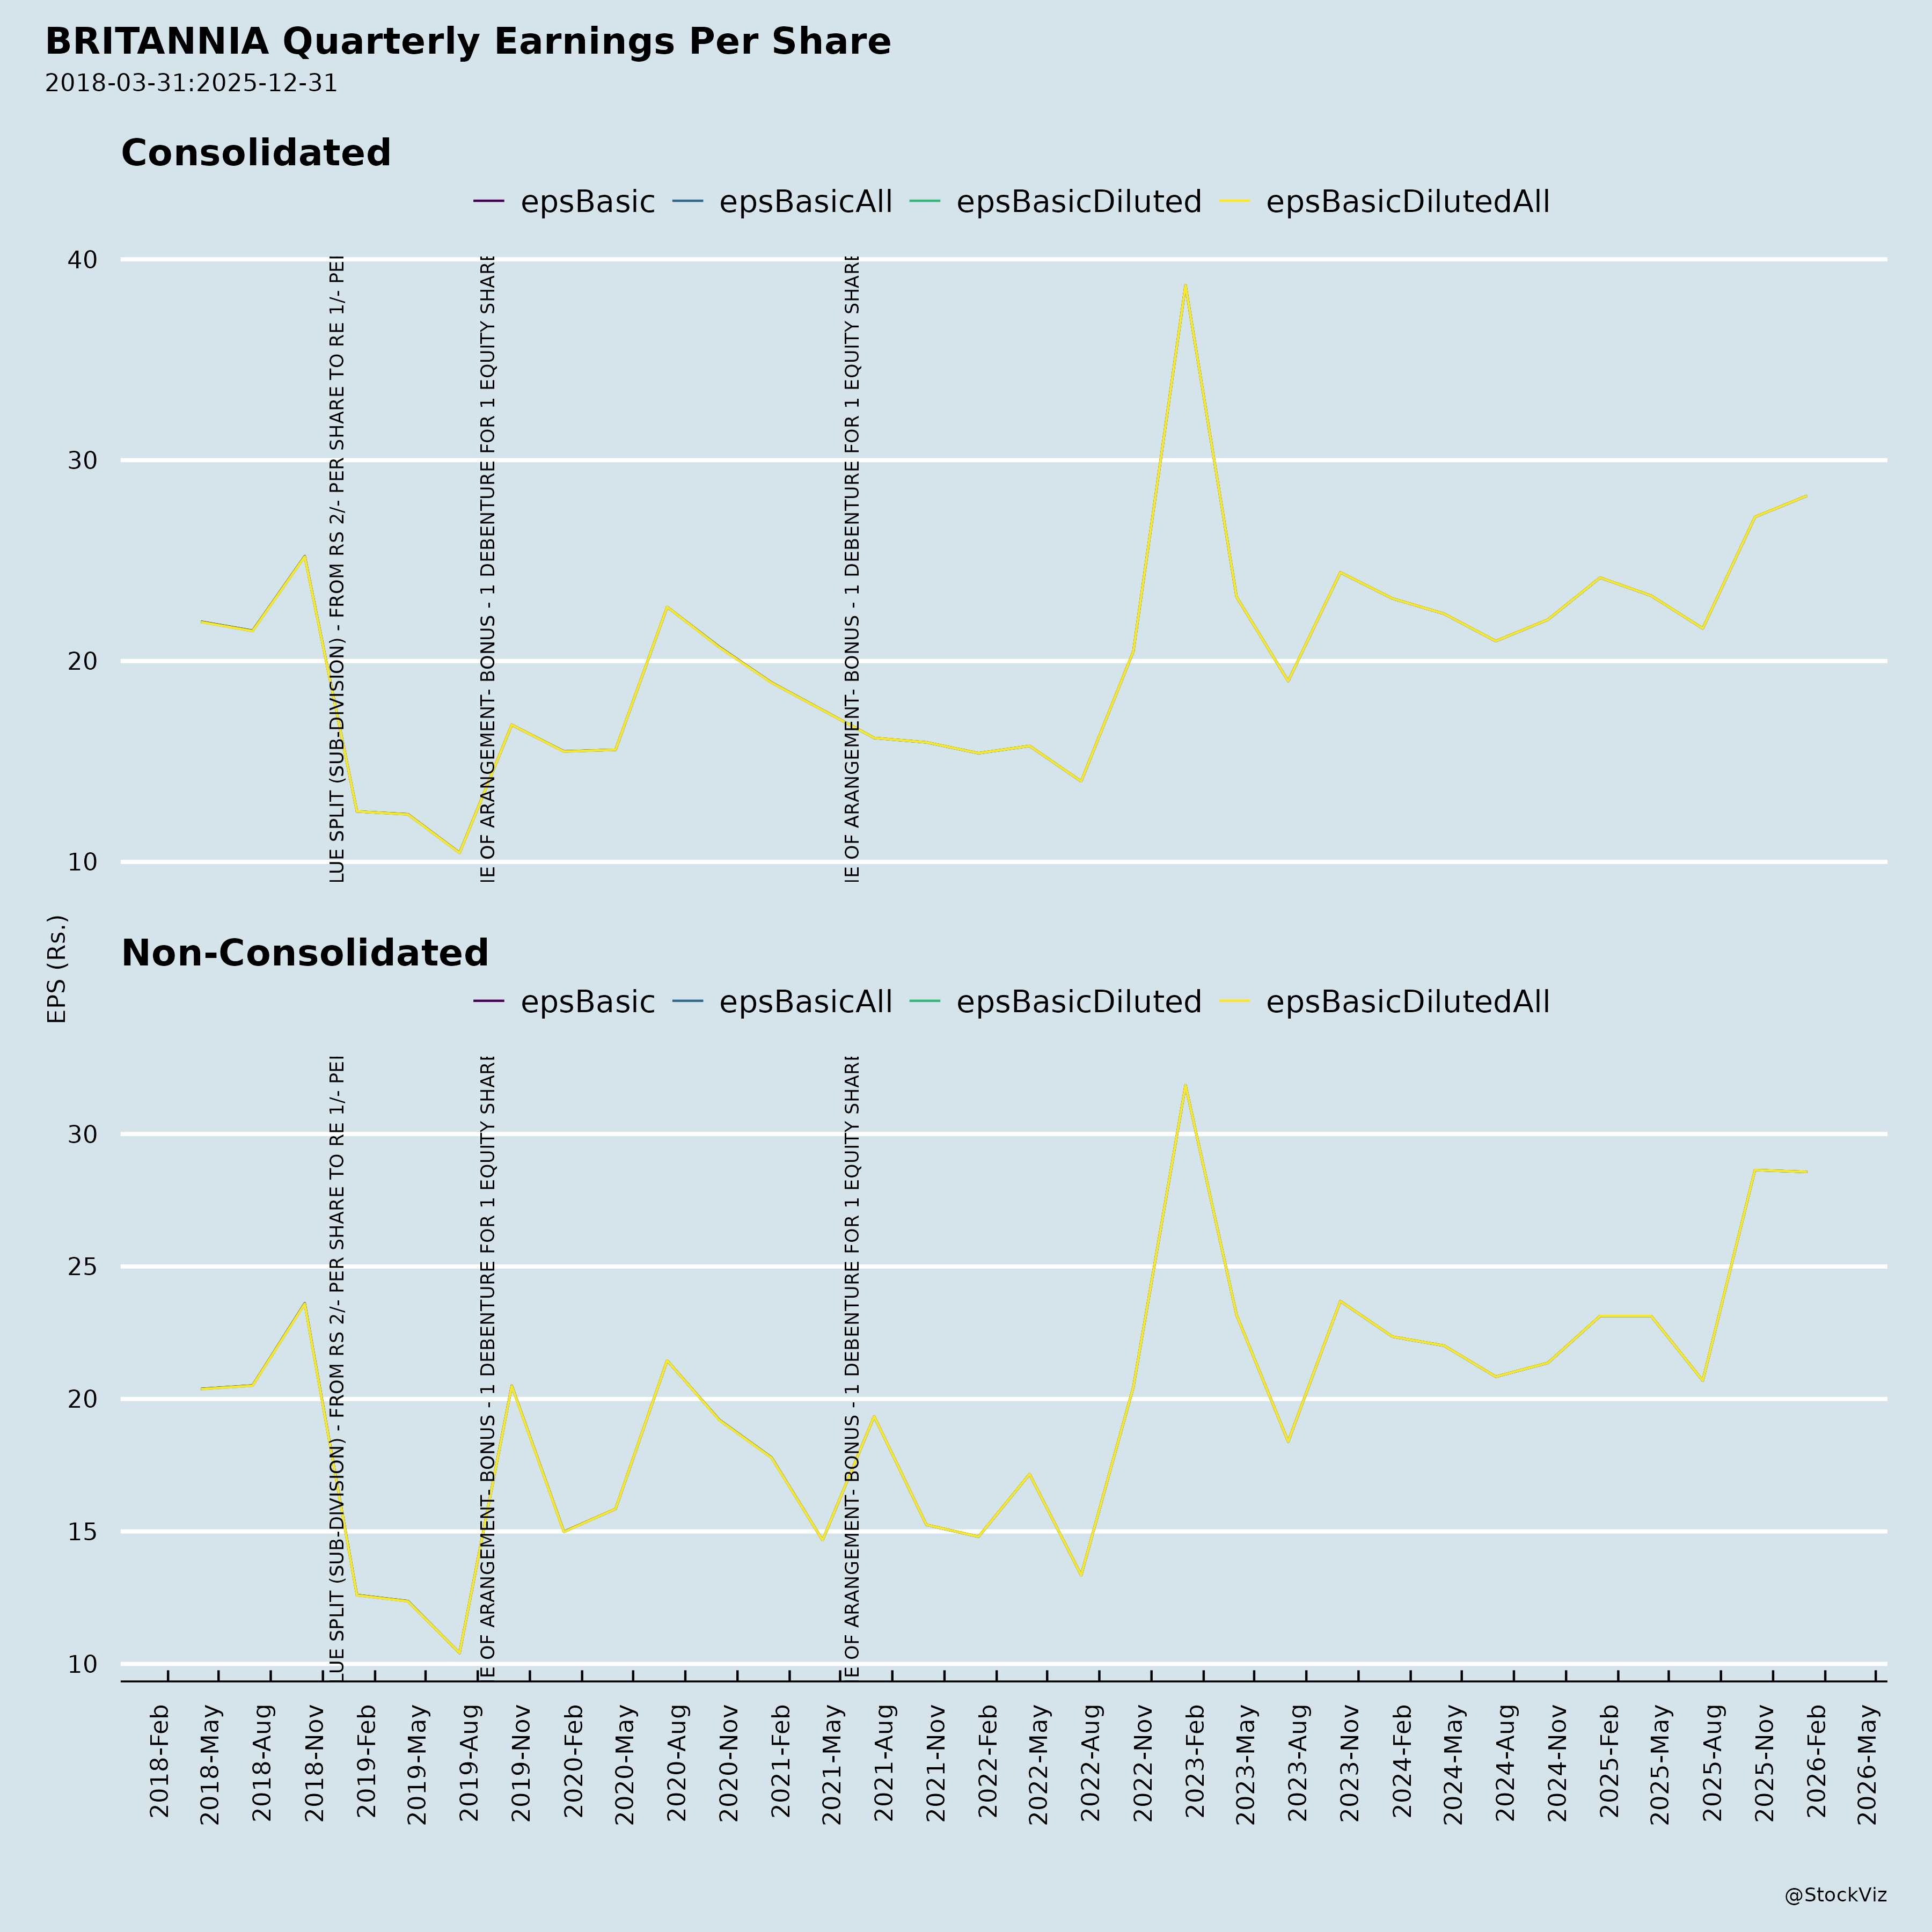
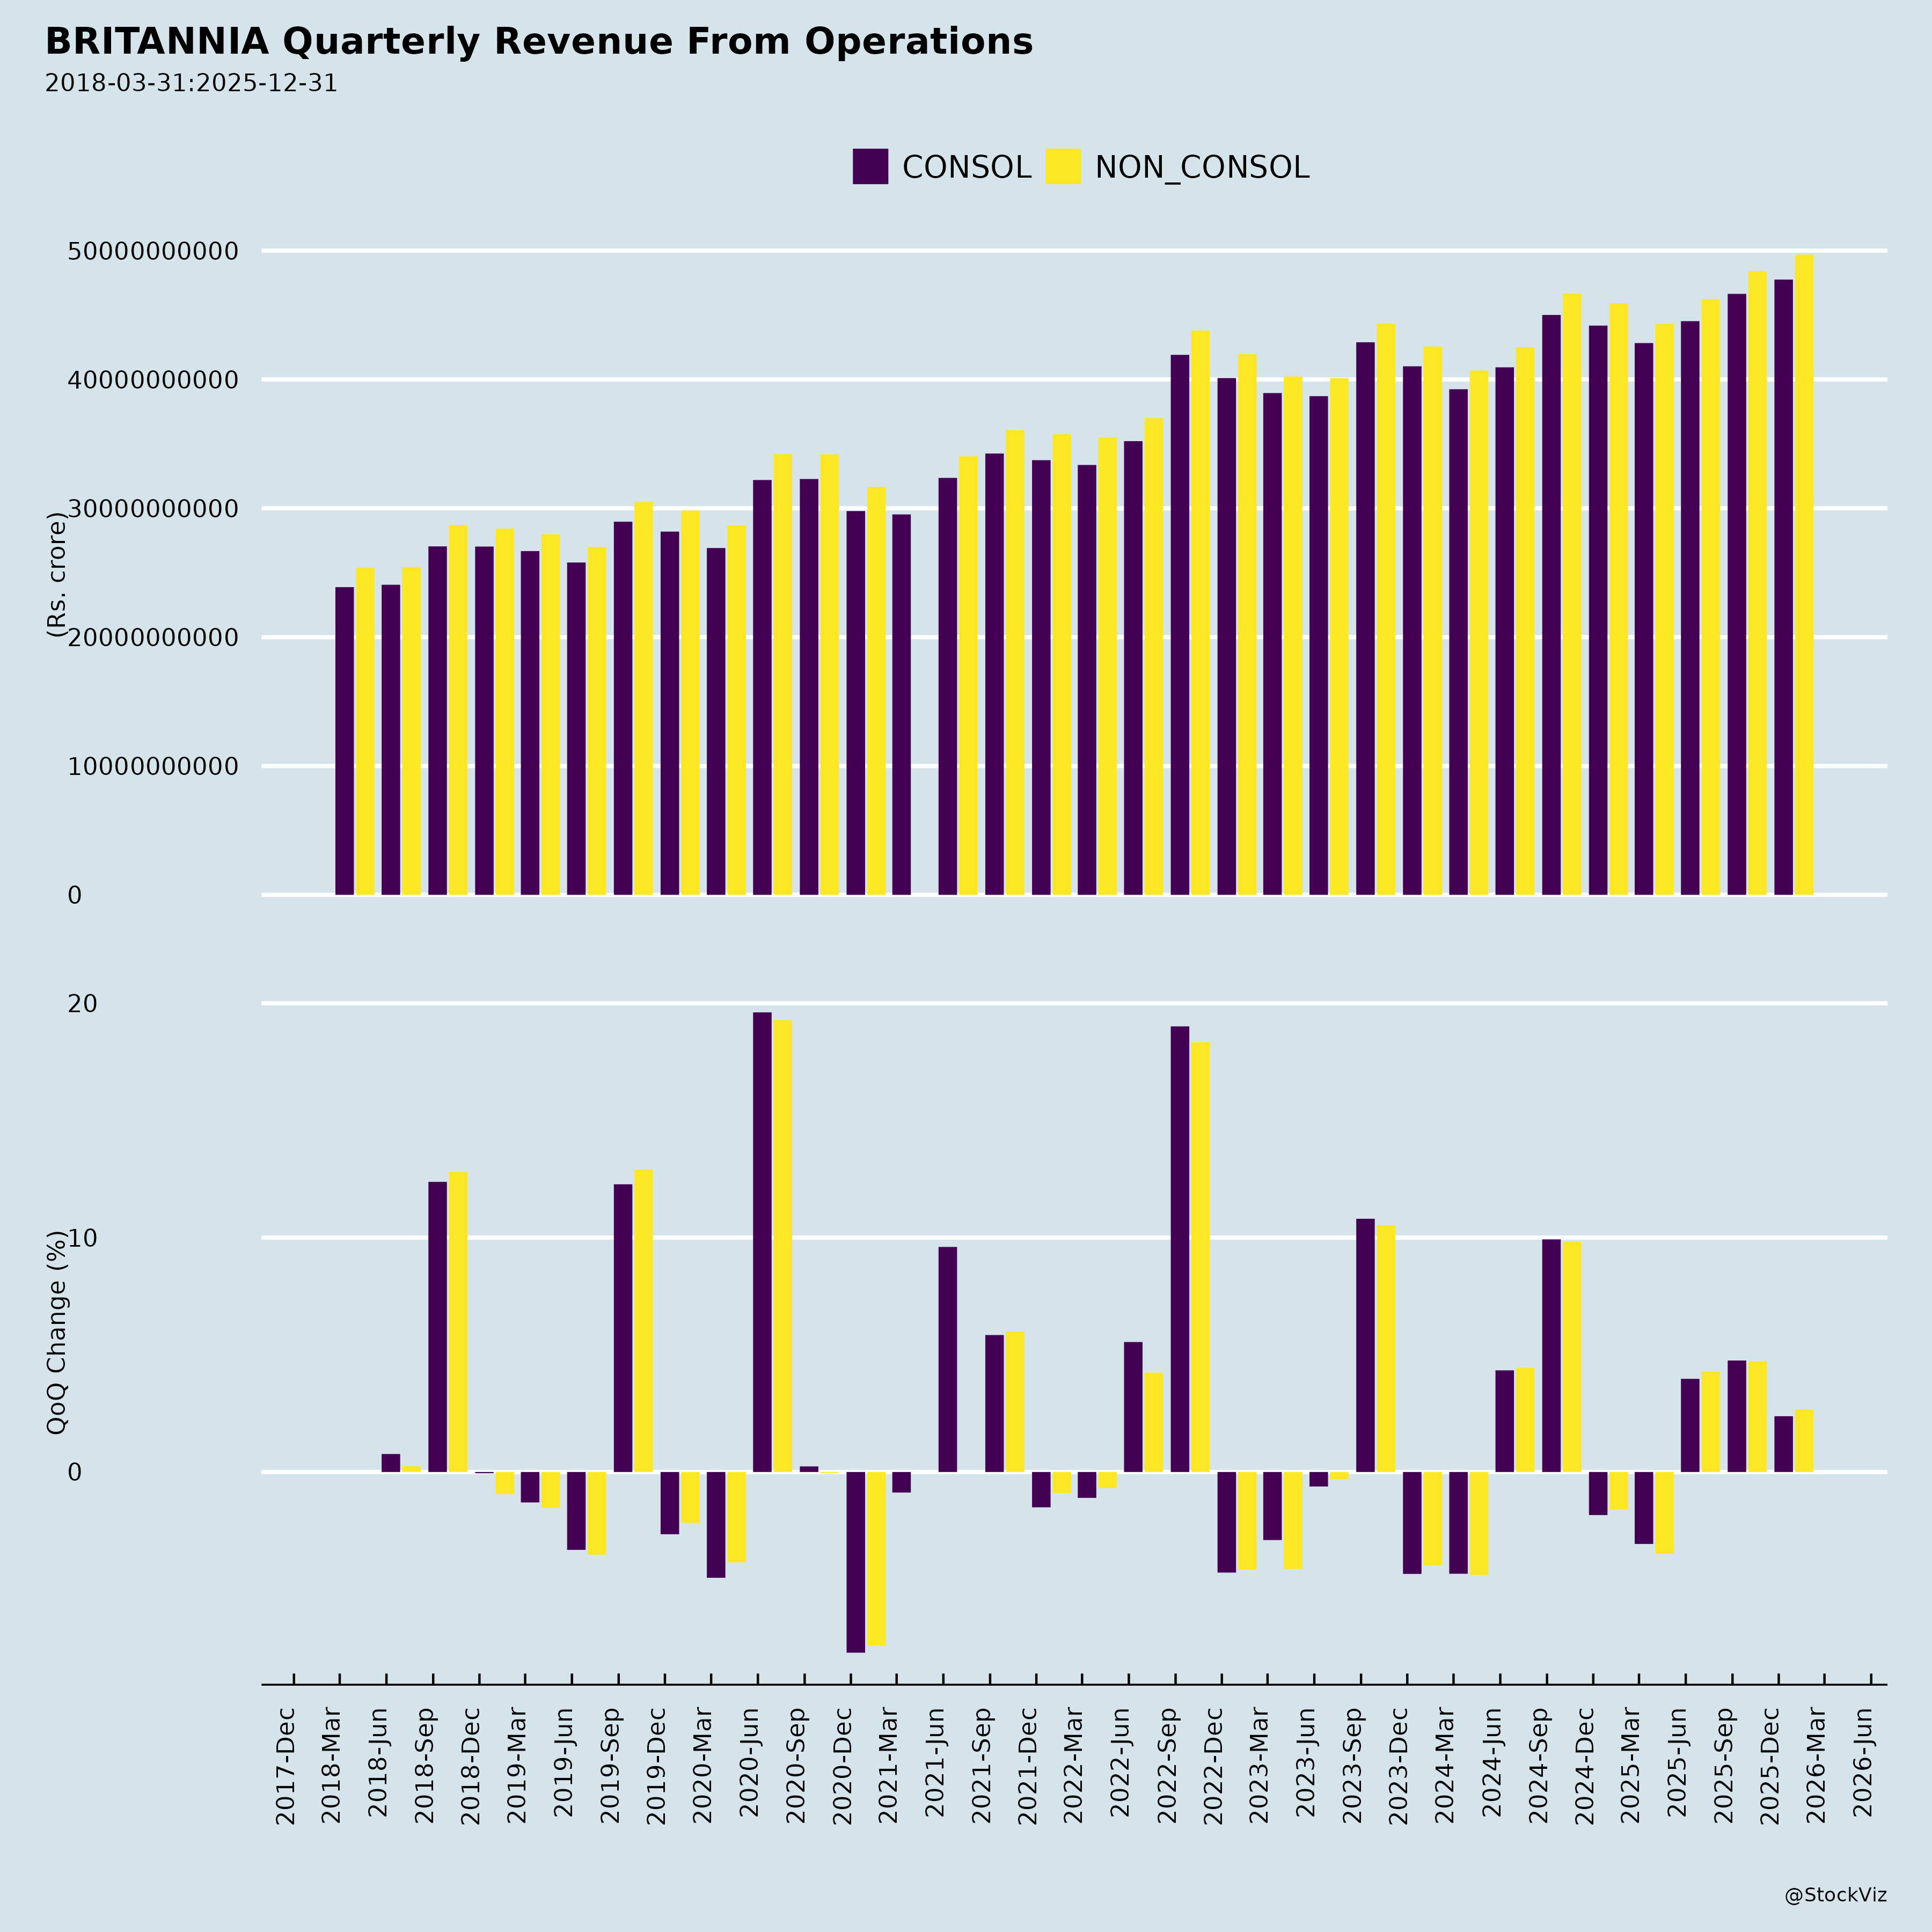
- Consolidated sales for the quarter ended 30 June 2026 stood at ₹4,964 crores, growing 9.5%, with net profit at ₹593 crores, growing 14.1% year-on-year. Standalone sales grew 10.0%.
- Most key categories saw positive sequential momentum, exiting the quarter with mid-teens revenue growth.
- Growth was anchored by rapid scaling in e-commerce and robust growth in General Trade, aided by higher advertisement, influencer and promotion spends.
- Brand salience was elevated through mass media campaigns (Marie Gold for Tea Day, NutriChoice for Health Day, Little Hearts for Mother’s Day) and localised activations such as the Milk Bikis Thirukkural campaign in Tamil Nadu.
- Innovation is described as a key growth engine, with impulse and indulgent offerings such as the Dubai Kunafa Croissant strengthening the portfolio.
- Channel and category momentum in Q1’27: General Trade grew 1.5x of 25-26 growth; other channels grew 2.5x of General Trade with E-Commerce leading in strong double-digits; Key States delivered 1.8x of 25-26 growth while other states grew double-digits at 1.3x of Key States; Croissant Q1’27 growth exceeded 30%; adjacency businesses (Cake, Rusk & Wafers) and the Dairy portfolio both delivered double-digit growth.
- International business recovered sequentially as supply chain constraints normalised in the last part of the quarter.
- The company expects to deliver healthy, sustainable revenue growth amidst an improving domestic demand environment, driven by sharp innovation, strong brand investments, and disciplined margin management through accelerated cost efficiency initiatives.
- Crisil ESG Ratings & Analytics Limited assigned Britannia a Crisil ESG Rating of 66 (category: Strong) and a Crisil Core ESG Rating of 64 on 26 August 2026.
3. Key Risks
- Geopolitical developments in West Asia and crude oil volatility, with potential impact on international operations and domestic input costs.
- Commodity and currency fluctuations.
- Competitive product and pricing pressures.
- Industrial relations matters.
- Regulatory developments, including the ongoing implementation of the New Labour Codes and associated rules.
- General economic conditions.
- Forward-looking statements in the investor presentation reflect management’s current views and estimates and involve future risks and uncertainties.
4. Management Guidance Versus Observed Business Performance
- Management stated it would remain agile to deliver healthy, sustainable revenue growth amidst an improving domestic demand environment, driven by innovation, brand investments, and disciplined margin management. Observed performance for the quarter ended 30 June 2026 showed consolidated sales growth of 9.5%, net profit growth of 14.1%, and profits growing ahead of topline in double digits, with mid-teens revenue growth exiting the quarter.
- Management flagged monitoring of the West Asia situation and crude oil volatility; the quarter’s results reflected the ability to navigate the steep increase in fuel and shipment costs while delivering volume and value growth and gaining ground against competition.
- Management noted international business supply chain constraints were normalising in the last part of the quarter, and the International Business recovered sequentially.
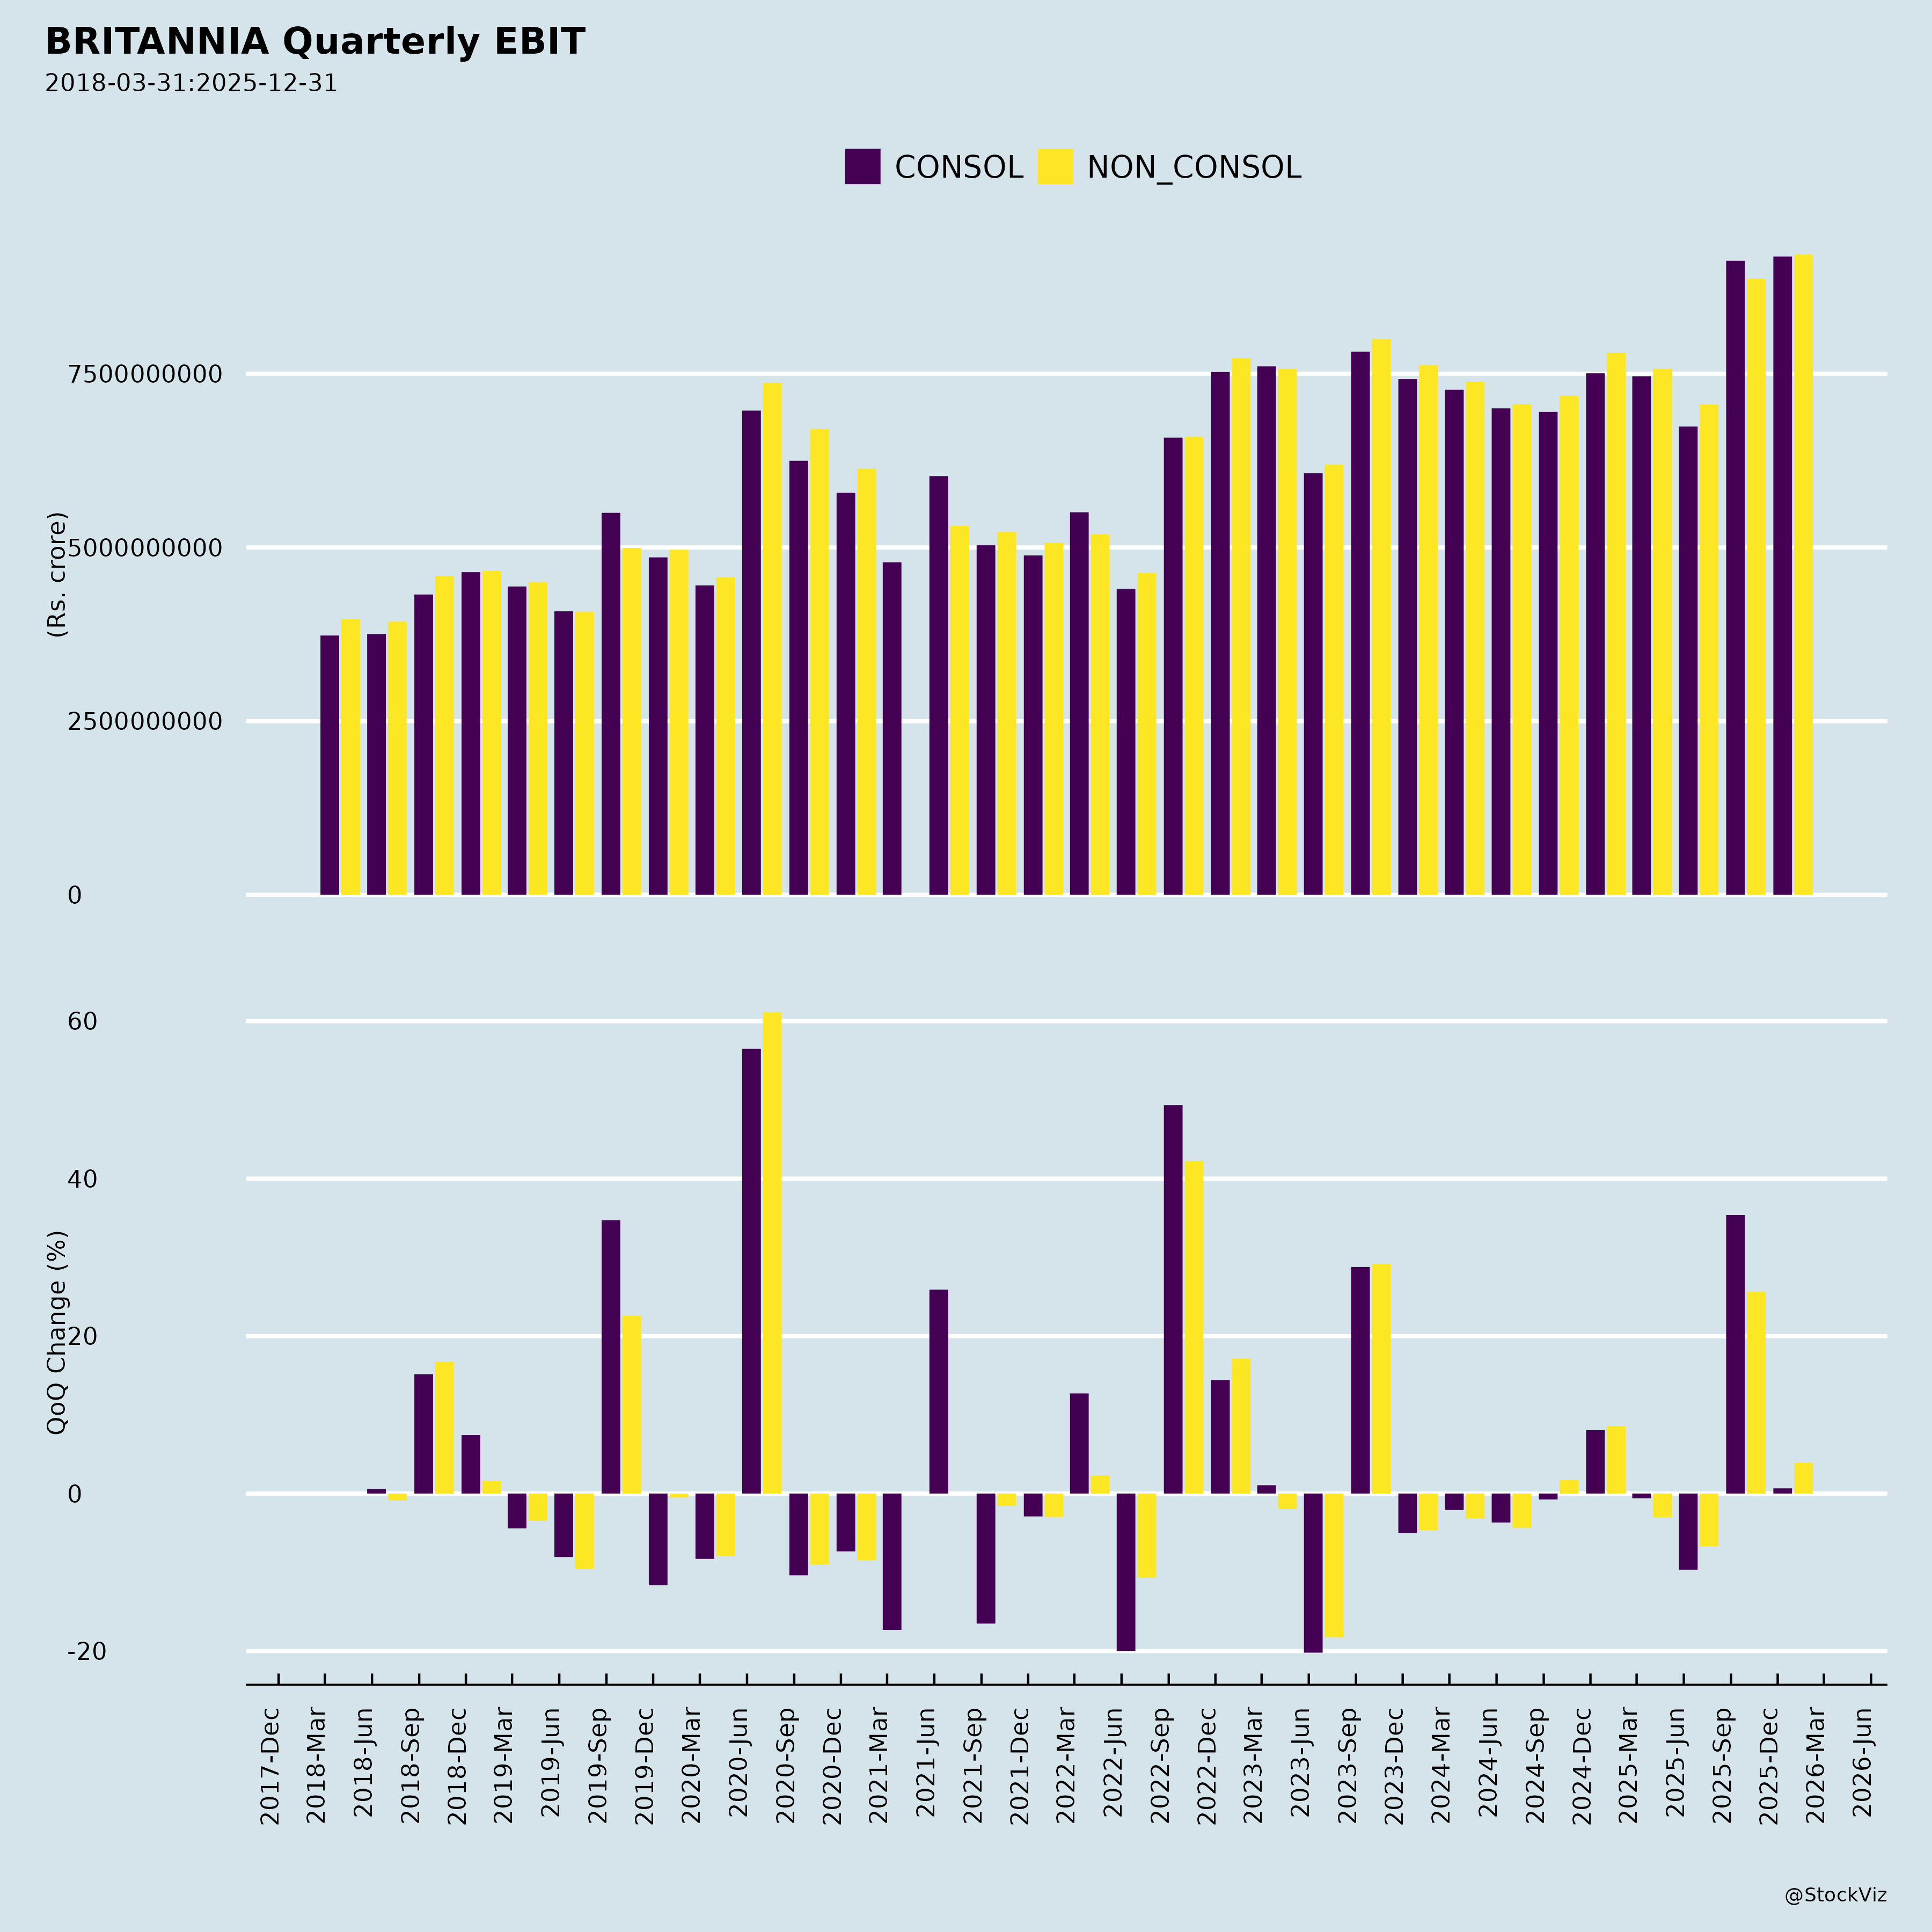
- Q1’27 metrics reported: revenue from operations ₹4,964 crores (up 9.5% vs Q1 25-26); operating profit ₹761 crores (up 12.7%); profit before tax ₹797 crores (up 13.7%); profit after tax (owner’s share) ₹591 crores (up 13.6%), representing 11.9% of revenue.
- The Board meeting on 6 August 2026 approved the unaudited consolidated and standalone results for the quarter ended 30 June 2026; the statutory auditors issued an unmodified review report. The 107th AGM was held on 7 August 2026, where the audited financial statements for FY2025-26 and a final dividend for the year ended 31 March 2026 were among the resolutions passed with requisite majority.
- Management will participate in the Jefferies 5th India Forum on 17 September 2026 and the J.P. Morgan India Conference on 21 September 2026, with no unpublished price sensitive information to be shared.
Broker Narrative
The broker narrative shifted from digital-first themes—internet penetration, e-commerce salience, and venture funding dynamics—to core FMCG cost-push and pricing dynamics. Inflation persisted as the dominant through-line, evolving from generic pressure on unit economics into specific raw-material, milk and fuel cost inflation with only partial price pass-through. Later optimism centered on volume growth, price hikes, innovation, international recovery and faster modern-trade/e-commerce growth, though e-commerce contribution remained limited.
Fears that came true
- Higher inflation impacting unit economics materialized as sustained raw-material, commodity, milk and fuel cost inflation that compressed margins and coincided with repeated negative actual returns and DISAPPOINTMENT outcomes.
Optimism that failed
- Rising internet penetration and ecommerce salience failed to become a meaningful revenue driver, as MT, Ecom and QC contribution remained only around 7% of sales in the last report.
Broker Timeline
65 broker calls · 2022-06-09 to 2026-11-06
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-11 |
UBS
|
Buy
|
UBS cut its target on Britannia by 11% but says 'buy' |
| 2026-11-09 |
Jefferies
|
Hold
Target: INR 5,350
Target action: lowered
|
Downgrade to hold call, target price cut to ₹5,350/sh. Persistent input cost inflation remains a key margin concern. Price hikes and grammage cuts may weigh on volumes. Q2 Volume Growth Was 13%, Though 2-Year Growth Was Around 5%. FY27-29 EPS Estimates Cut By 3%. |
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-17 |
Ashika Institutional Equities
Rahul Arora
|
—
|
He prefers TataConsumer, Britannia, RadicoKhaitan and UnitedSpirits, while also finding value in select metal-recycling stocks |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.