BORORENEW
Equity Metrics
November 18, 2026
BOROSIL RENEWABLES LIMITED
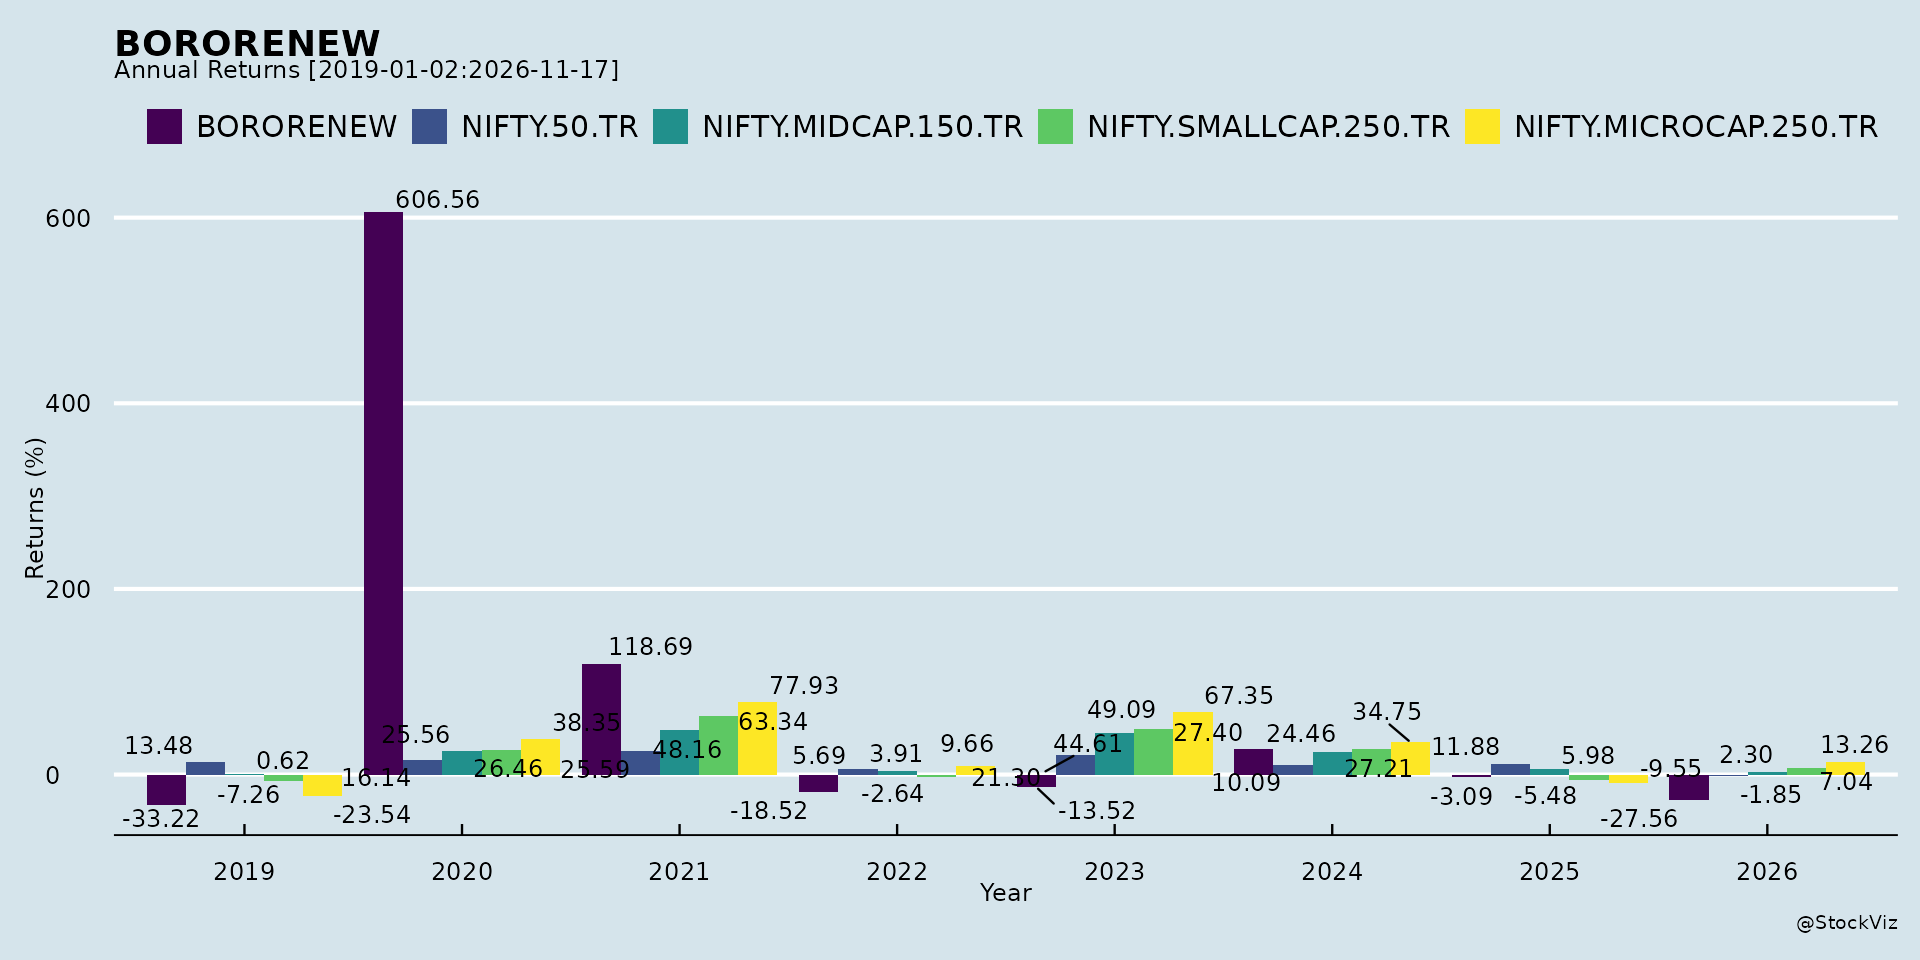
Annual Returns
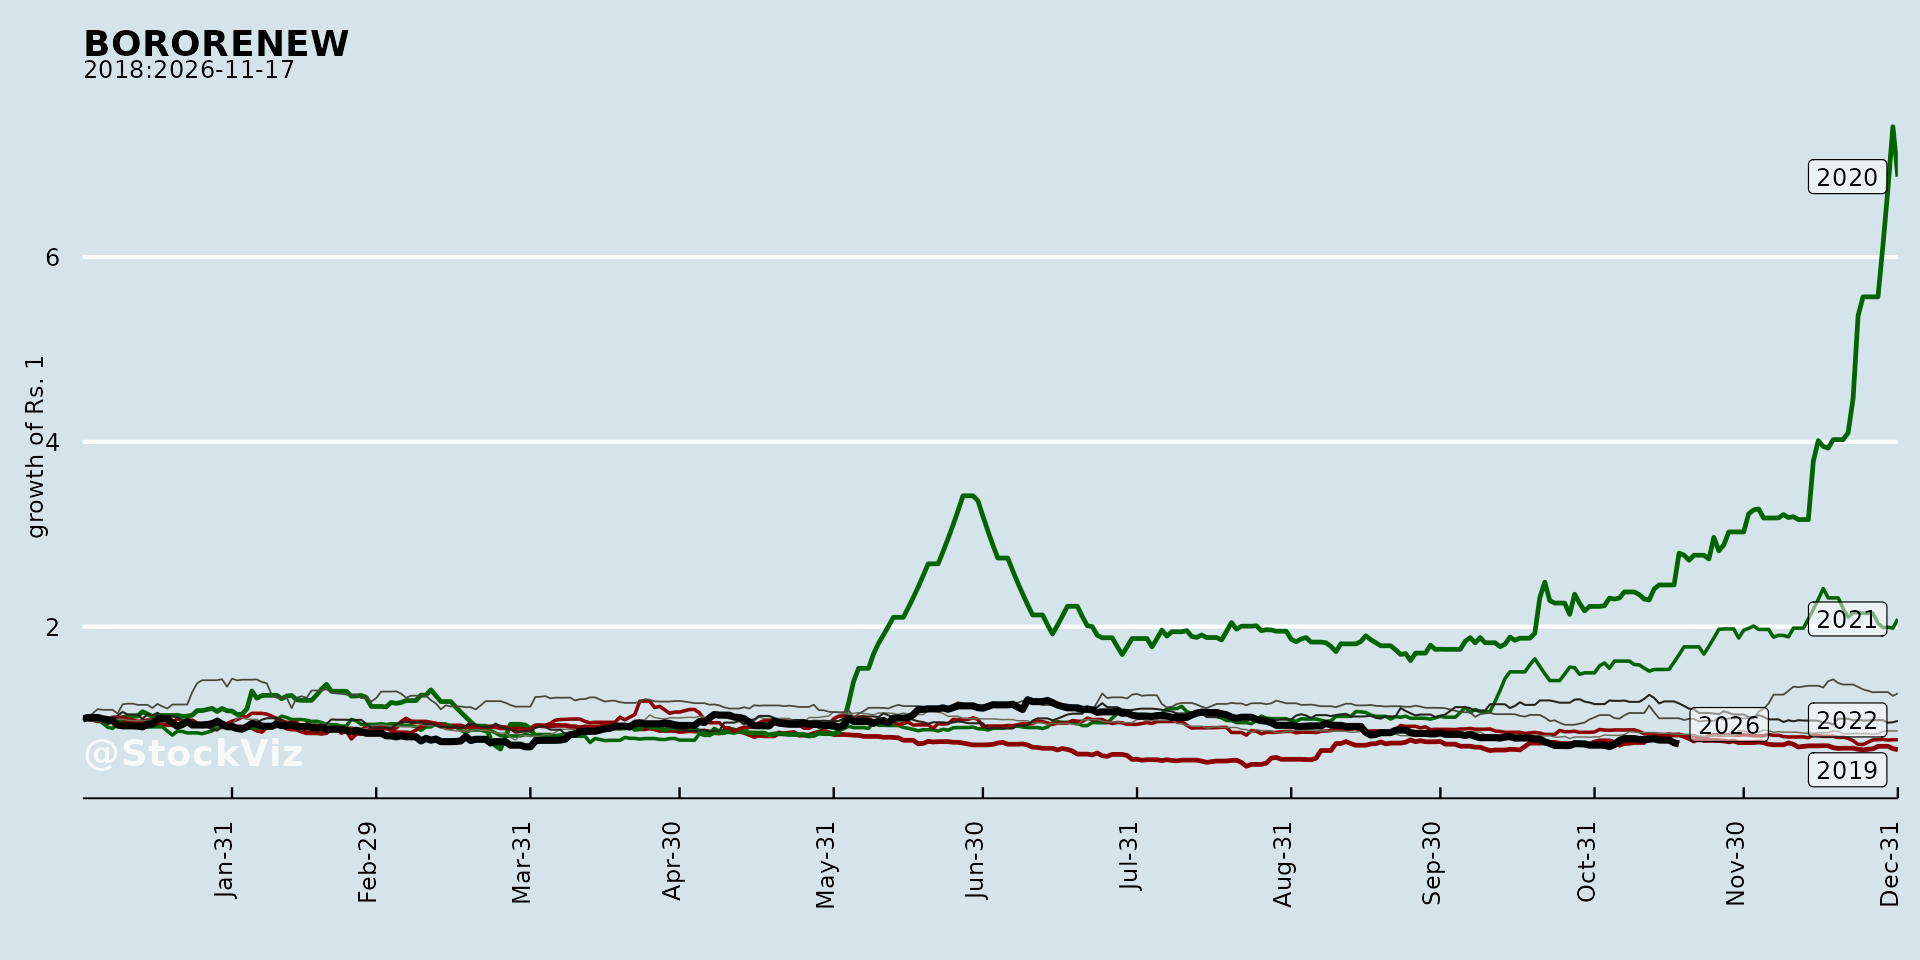
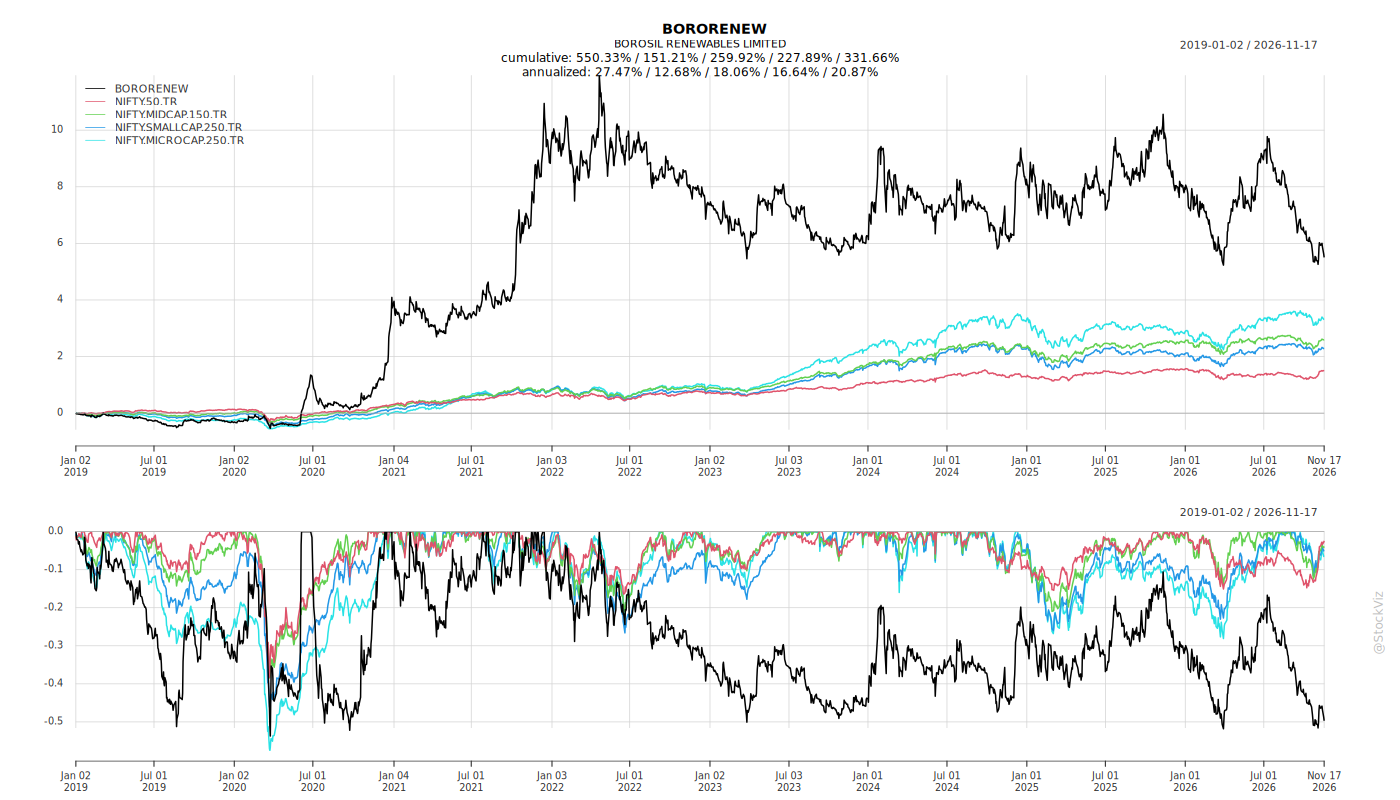
Cumulative Returns and Drawdowns
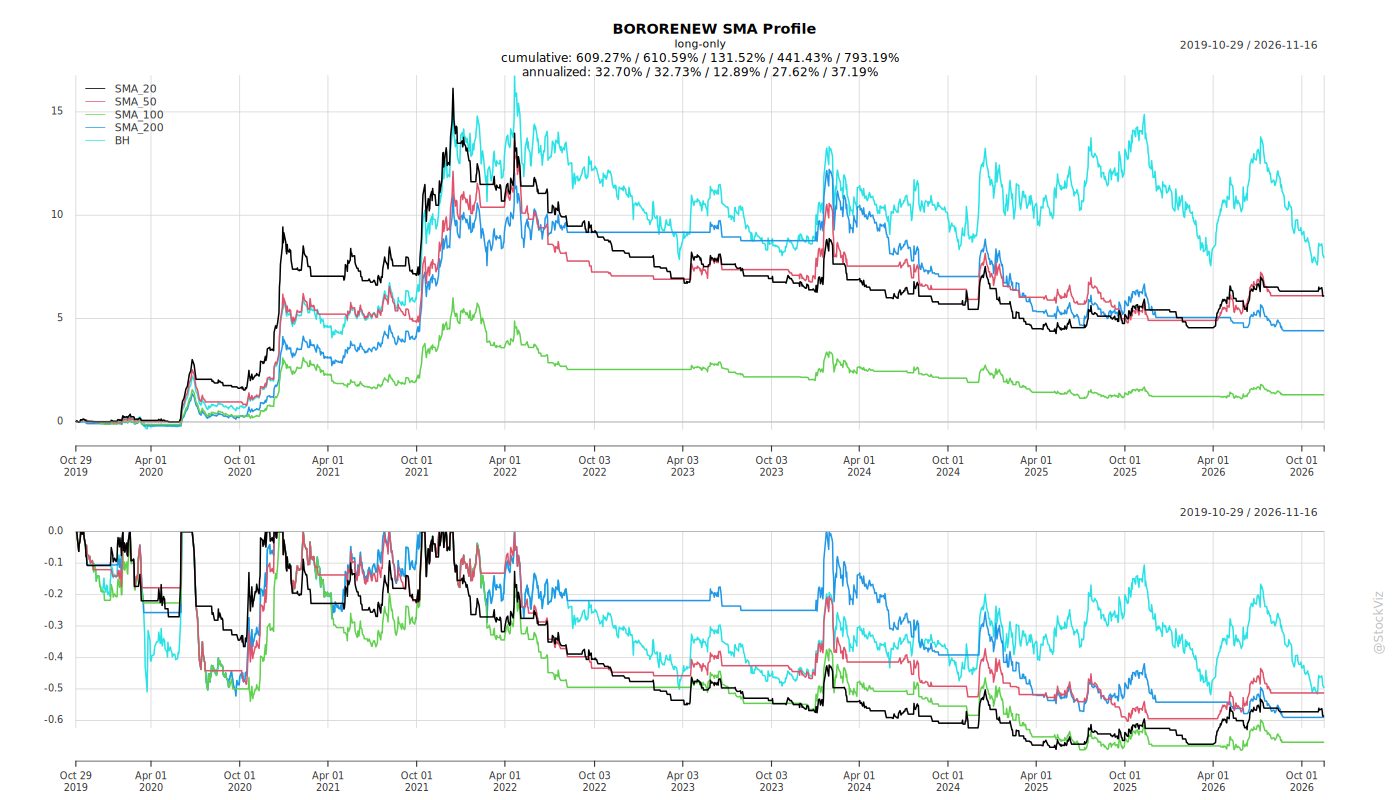
Fundamentals
Ownership
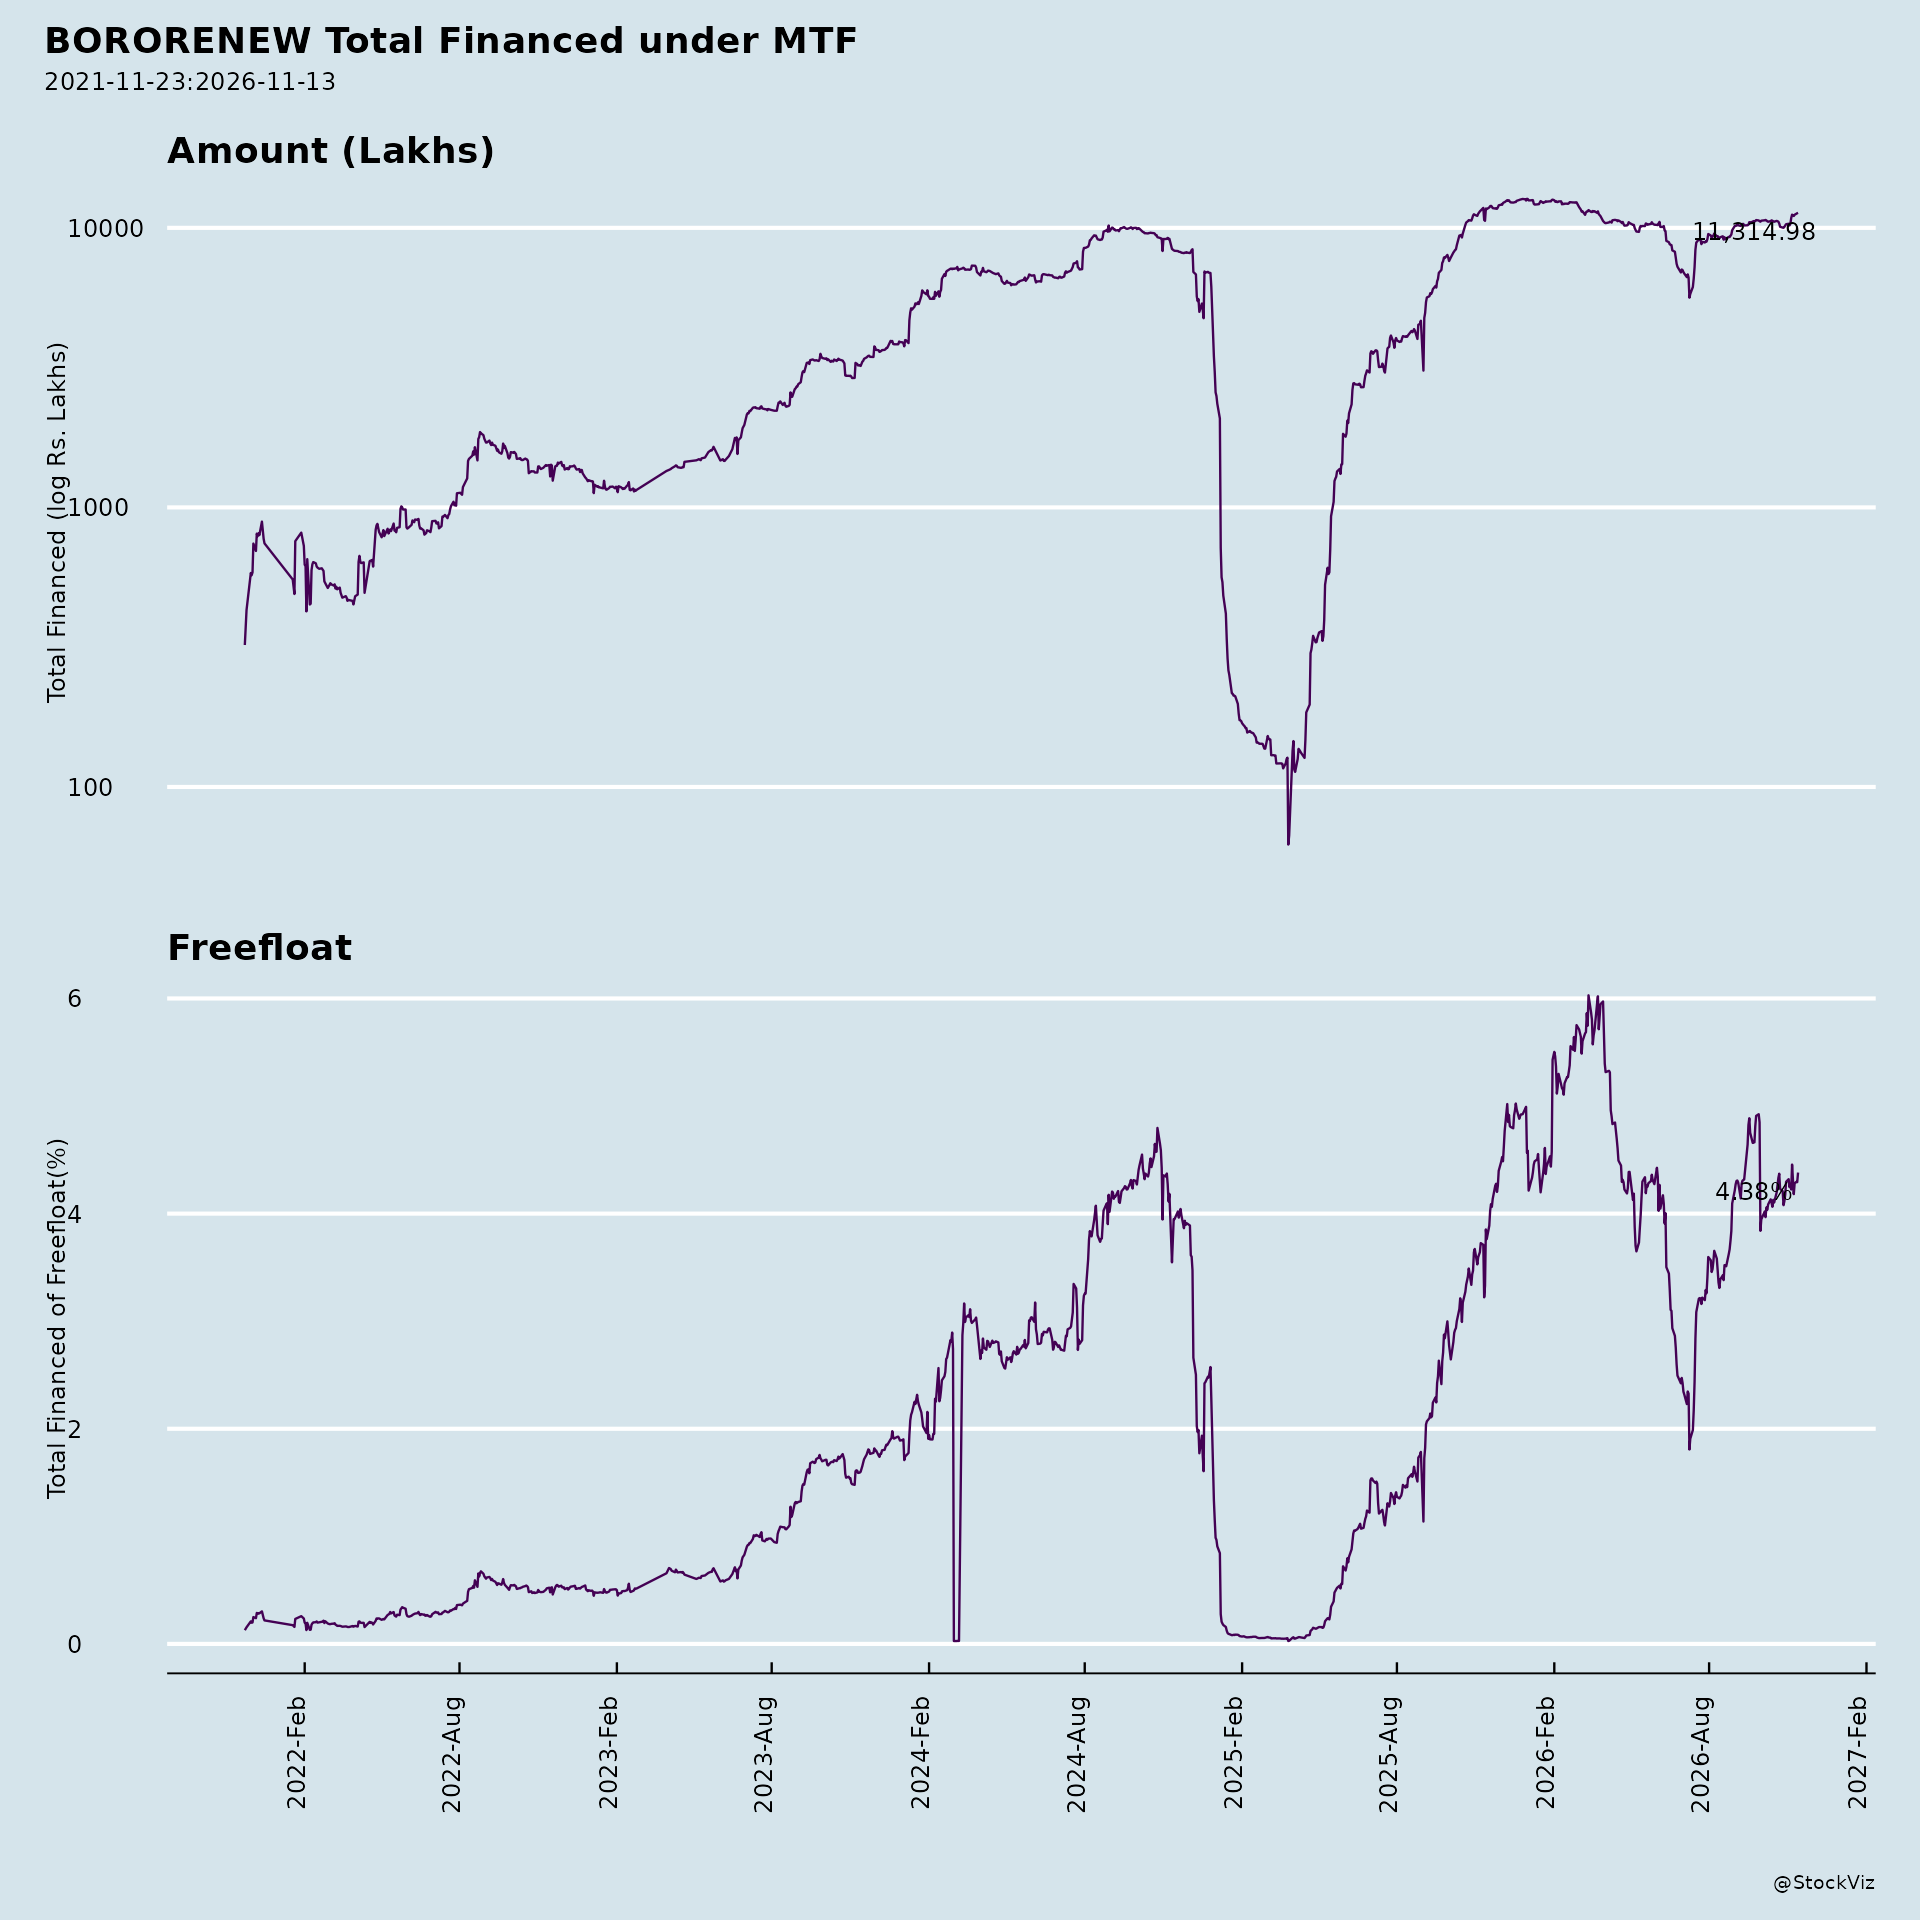
Margined
AI Summary
asof: 2026-09-17
BORORENEW: Recent Developments and Outlook
1. Headwinds and Challenges
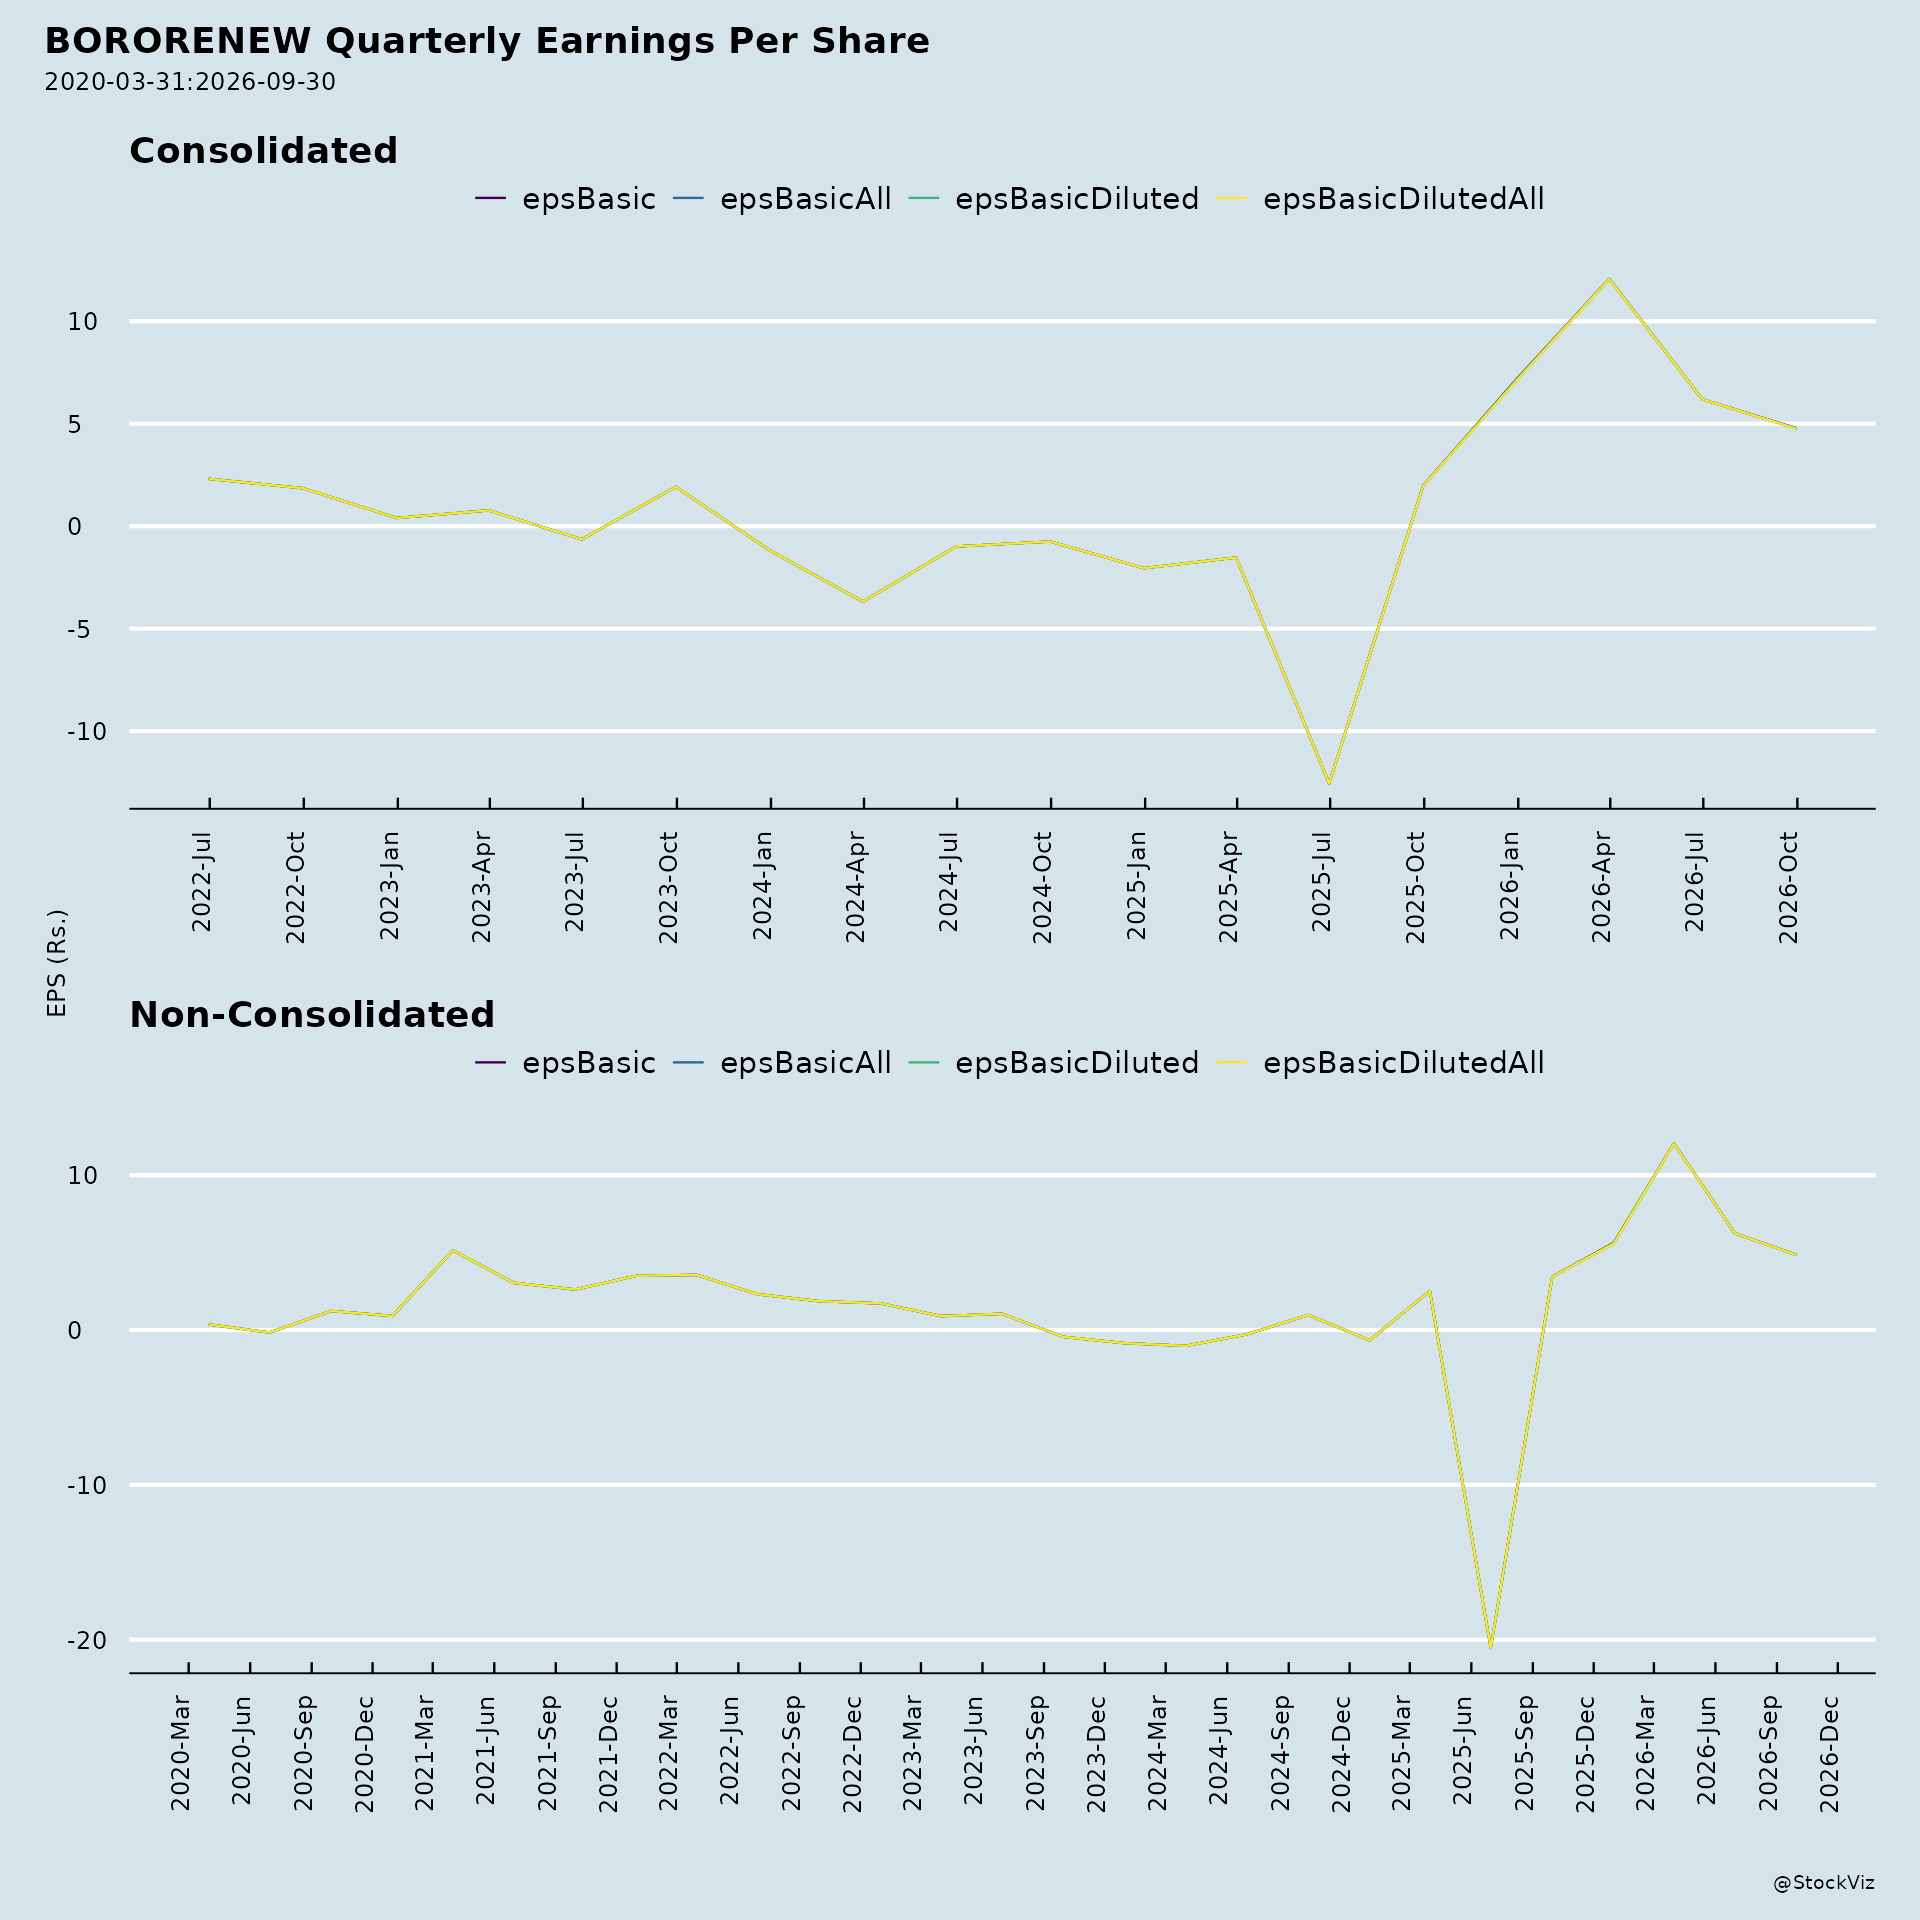
- German subsidiary insolvency: GMB Glasmanufaktur Brandenburg GmbH, a German step-down subsidiary with 350 TPD capacity, filed for insolvency. Geosphere Glassworks GmbH and GMB are both subject to insolvency proceedings that, as of the June 2026 results, were yet to be concluded. The company recognised exceptional items tied to its exposure to these entities — ₹32,590.81 lakhs in the quarter ended June 30, 2025 (standalone) and ₹35,977.85 lakhs for the year ended March 31, 2026 — comprising impairment/write-off of exposure to the German subsidiaries plus ₹3,387.04 lakhs impairment towards Laxman AG, a wholly owned subsidiary. On a consolidated basis, exceptional items were ₹22,230.95 lakhs for Q1 FY26 and ₹21,340.80 lakhs for FY26.
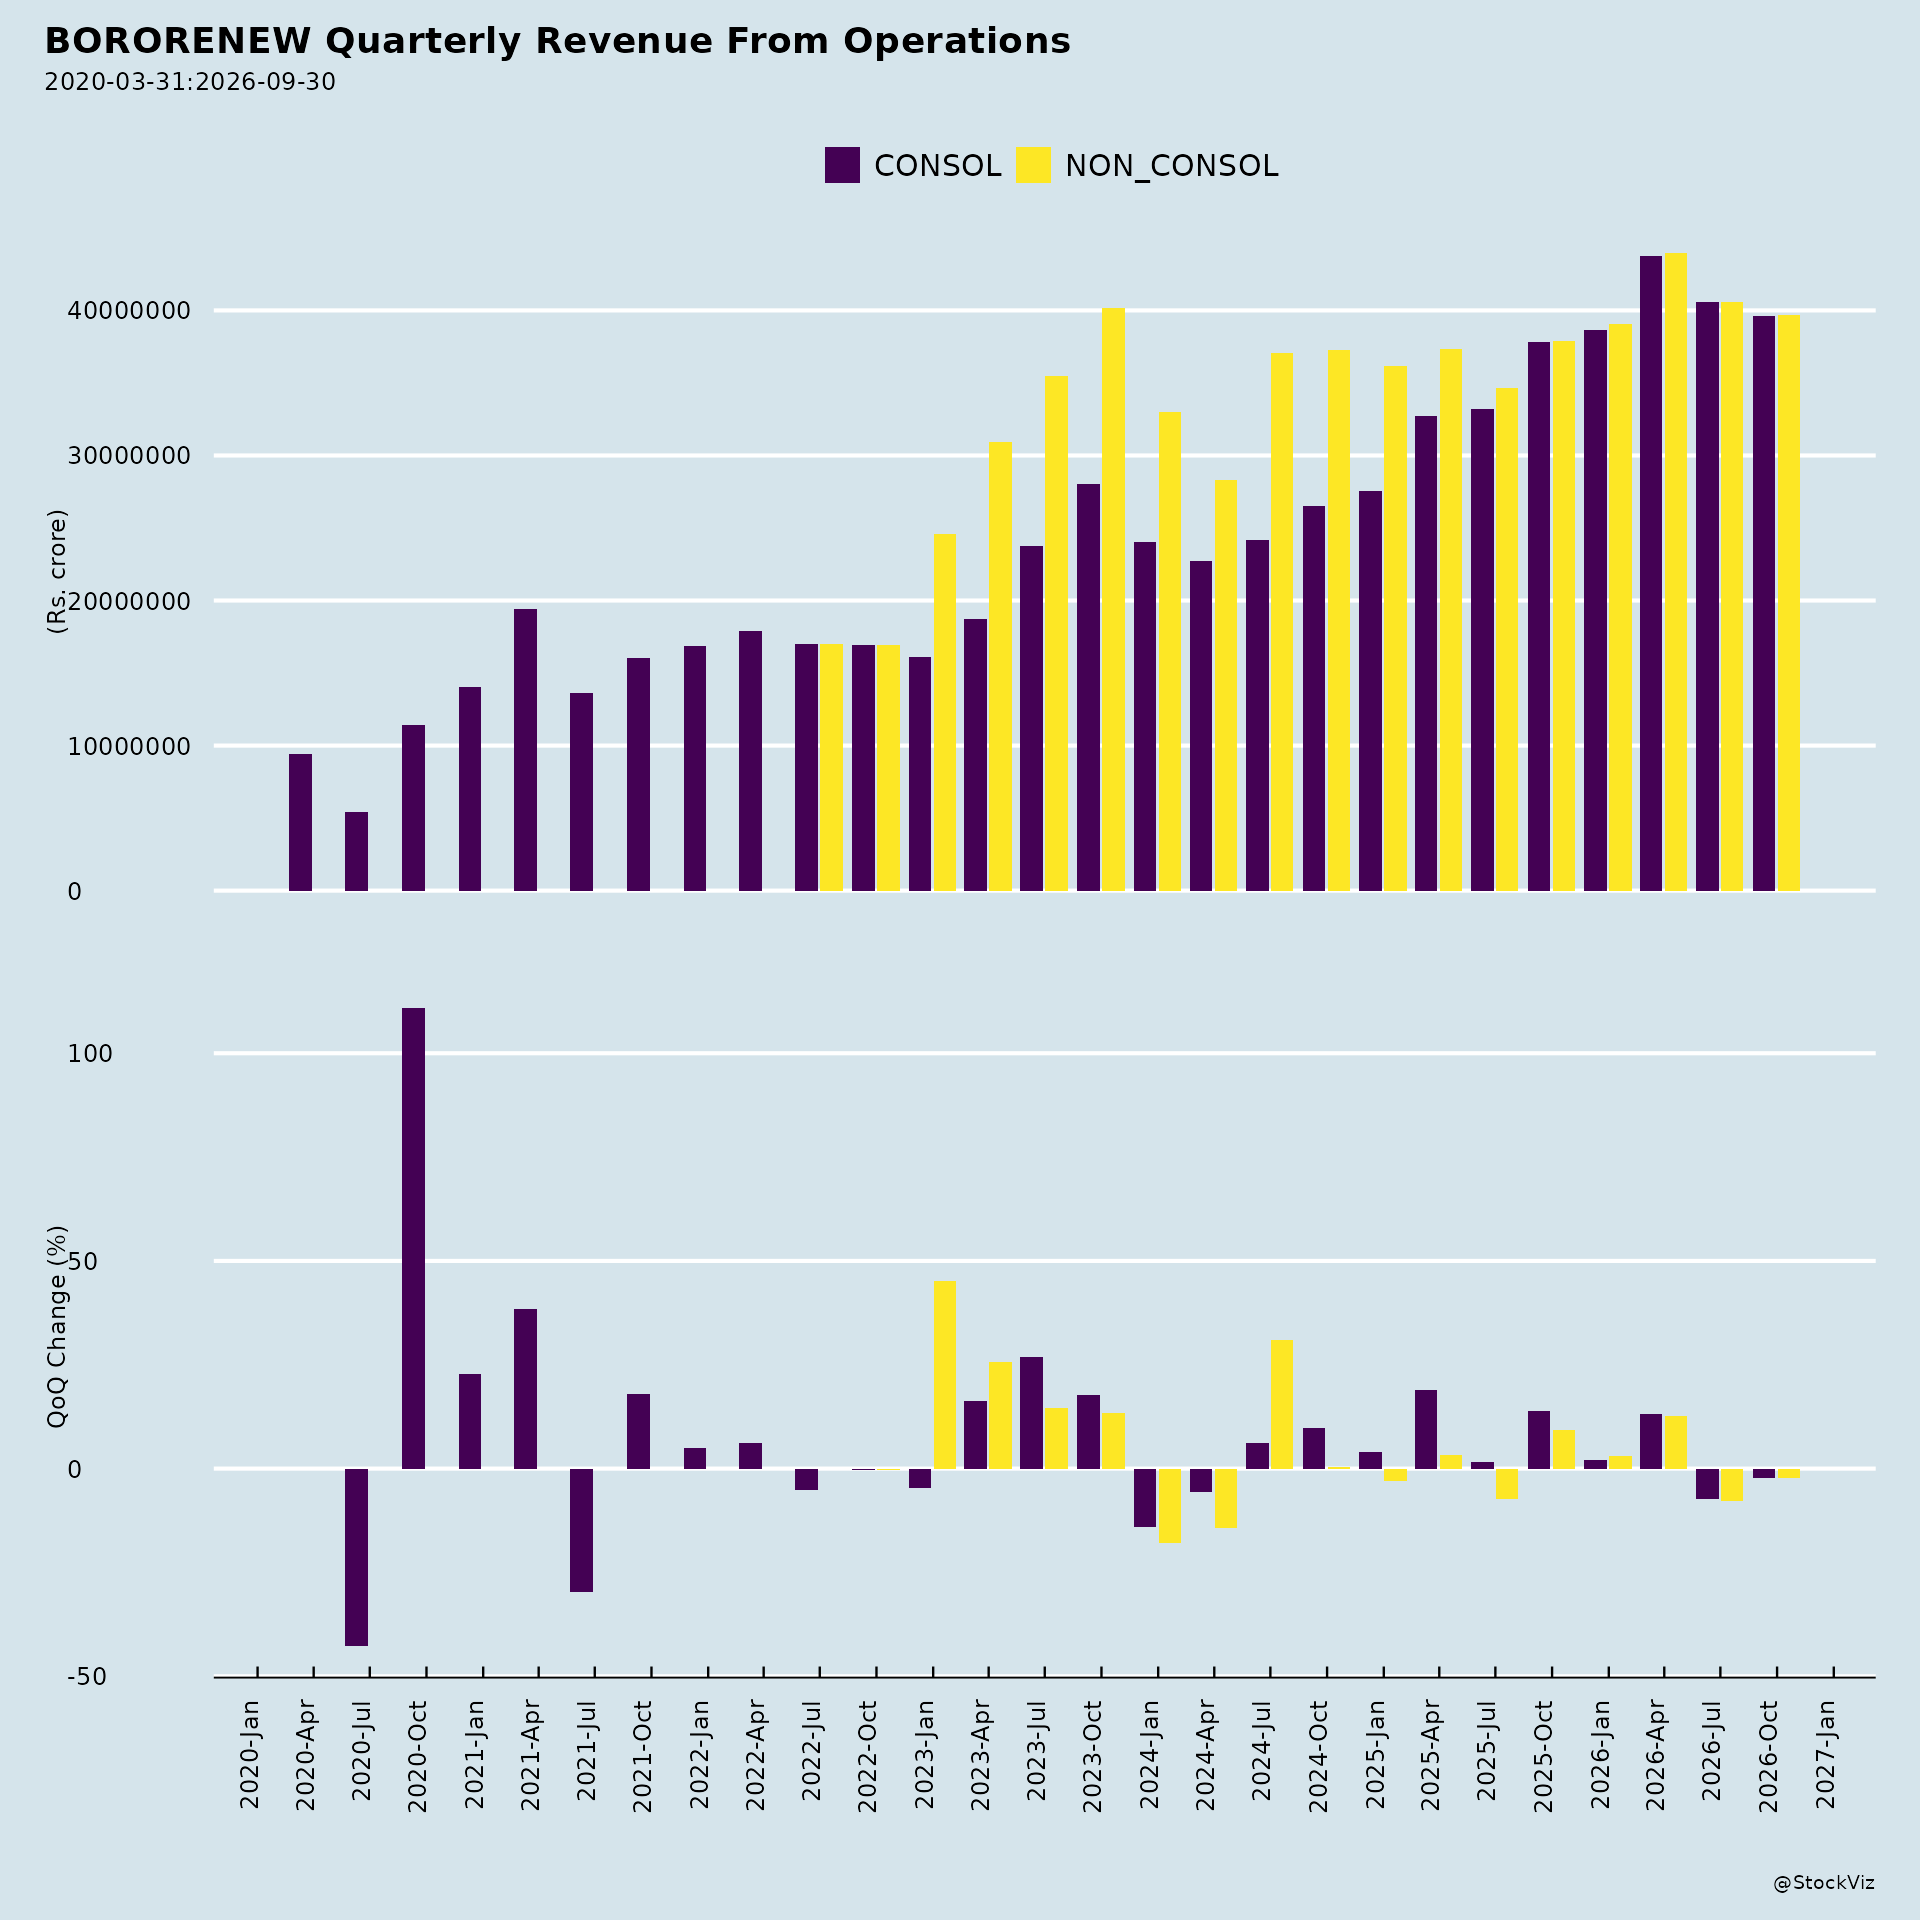
- Sequential revenue decline: Standalone revenue from operations fell to ₹40,569.07 lakhs in Q1 FY27 from ₹43,761.69 lakhs in Q4 FY26, though it rose sharply year-on-year from ₹33,226.04 lakhs in Q1 FY26.
- Export weakness: Standalone revenue from outside India dropped to ₹1,428.73 lakhs in Q1 FY27 from ₹3,462.45 lakhs a year earlier and ₹11,328.95 lakhs for FY26. Consolidated overseas revenue fell to ₹1,428.73 lakhs from ₹4,894.11 lakhs in Q1 FY26.
- Cost pressure: Power and fuel costs rose to ₹10,213.18 lakhs in Q1 FY27 from ₹7,648.07 lakhs in Q1 FY26 (standalone), and other expenses also increased year-on-year.
- Subsidiary drag: The consolidated results include two subsidiaries whose interim financials reflect a net loss after tax of ₹147.12 lakhs for Q1 FY27.
- Forward-looking statement risk: The company notes that forward-looking statements are subject to risks, uncertainties, and assumptions.
2. Tailwinds and Growth Prospects
- Solar demand in India: Total installed power generation capacity reached approximately 552 GW as of July 2026, with growing solar demand and government support through solar installations and policy direction.
- Supply gap: A solar glass capacity shortfall creates a large market opportunity, with an estimated supply gap of 8,400 TPD in FY26.
- Capacity expansion: The company operates a solar glass capacity of 1,000 TPD (roughly 6.5 GW module manufacturing equivalent) and plans to expand to 1,600 TPD (roughly 10.5 GW). Furnace firing for the expansion is scheduled for December 2026.
- Diversification: Expansion into end-to-end rooftop solar solutions.
- Track record: Revenue CAGR of 32.3% and operating EBITDA CAGR of 45.5% (FY19–26, standalone), with over 100 domestic customers and a net cash position.
- Fundraising progress: Under the preferential issue of equity shares and warrants at ₹530 each (aggregate issue size ₹51,766.31 lakhs), the company received ₹374.99 lakhs in Q1 FY27 upon exercise of warrants, allotting 94,338 equity shares; total funds raised under that issue stand at ₹23,889.22 lakhs, with the remaining amount receivable until August 13, 2026. A separate preferential issue of 69,43,691 equity shares at ₹535 each raised ₹37,148.75 lakhs. Proceeds have been deployed towards the SBLC liability for GMB (₹18,500 lakhs), capacity expansion capex (₹5,014.23 lakhs under the first issue; ₹8,552.17 lakhs under the second towards capex and general corporate purposes), with the balance temporarily in mutual funds.
3. Key Risks
- Insolvency exposure: The unresolved insolvency proceedings of Geosphere Glassworks and GMB, and the associated impairment and additional liability recognition, remain a material risk; the consolidated exceptional items reflect the impact after deconsolidation of these subsidiaries.
- Earnings volatility: Q1 FY26 standalone results showed a loss before tax of ₹25,935.29 lakhs and a loss of ₹27,234.57 lakhs for the period, driven by exceptional items, versus profit in Q1 FY27 — illustrating sensitivity to one-off charges.
- Cost and margin sensitivity: Rising power and fuel costs and changes in inventory levels affect profitability.
- Export market exposure: The sharp year-on-year decline in overseas revenue highlights vulnerability in export markets.
- Warrant conversion uncertainty: The remaining warrant proceeds depend on holders exercising their conversion option before the August 13, 2026 deadline.
- Forward-looking uncertainty: Scheduled investor interactions and guidance are subject to change based on investors, organizers, or management.
4. Management Guidance vs. Observed Performance
- Capacity guidance: Management expects domestic solar glass production capacity to rise gradually to 7,900 TPD (50 GW) by March 2027, with its own furnace firing scheduled for December 2026. Observed performance: current capacity stands at 1,000 TPD, with 1,600 TPD planned; capex deployment is underway (₹5,014.23 lakhs and ₹8,552.17 lakhs utilised as of June 30, 2026).
- Turnover guidance: Management projects an expected turnover at full-year run rate post-expansion of approximately ₹2,500 crore (about 60% increase versus FY26). Observed performance: FY26 standalone revenue was ₹1,53,482.50 lakhs and Q1 FY27 standalone revenue was ₹40,569.07 lakhs, with sequential decline from Q4 FY26.
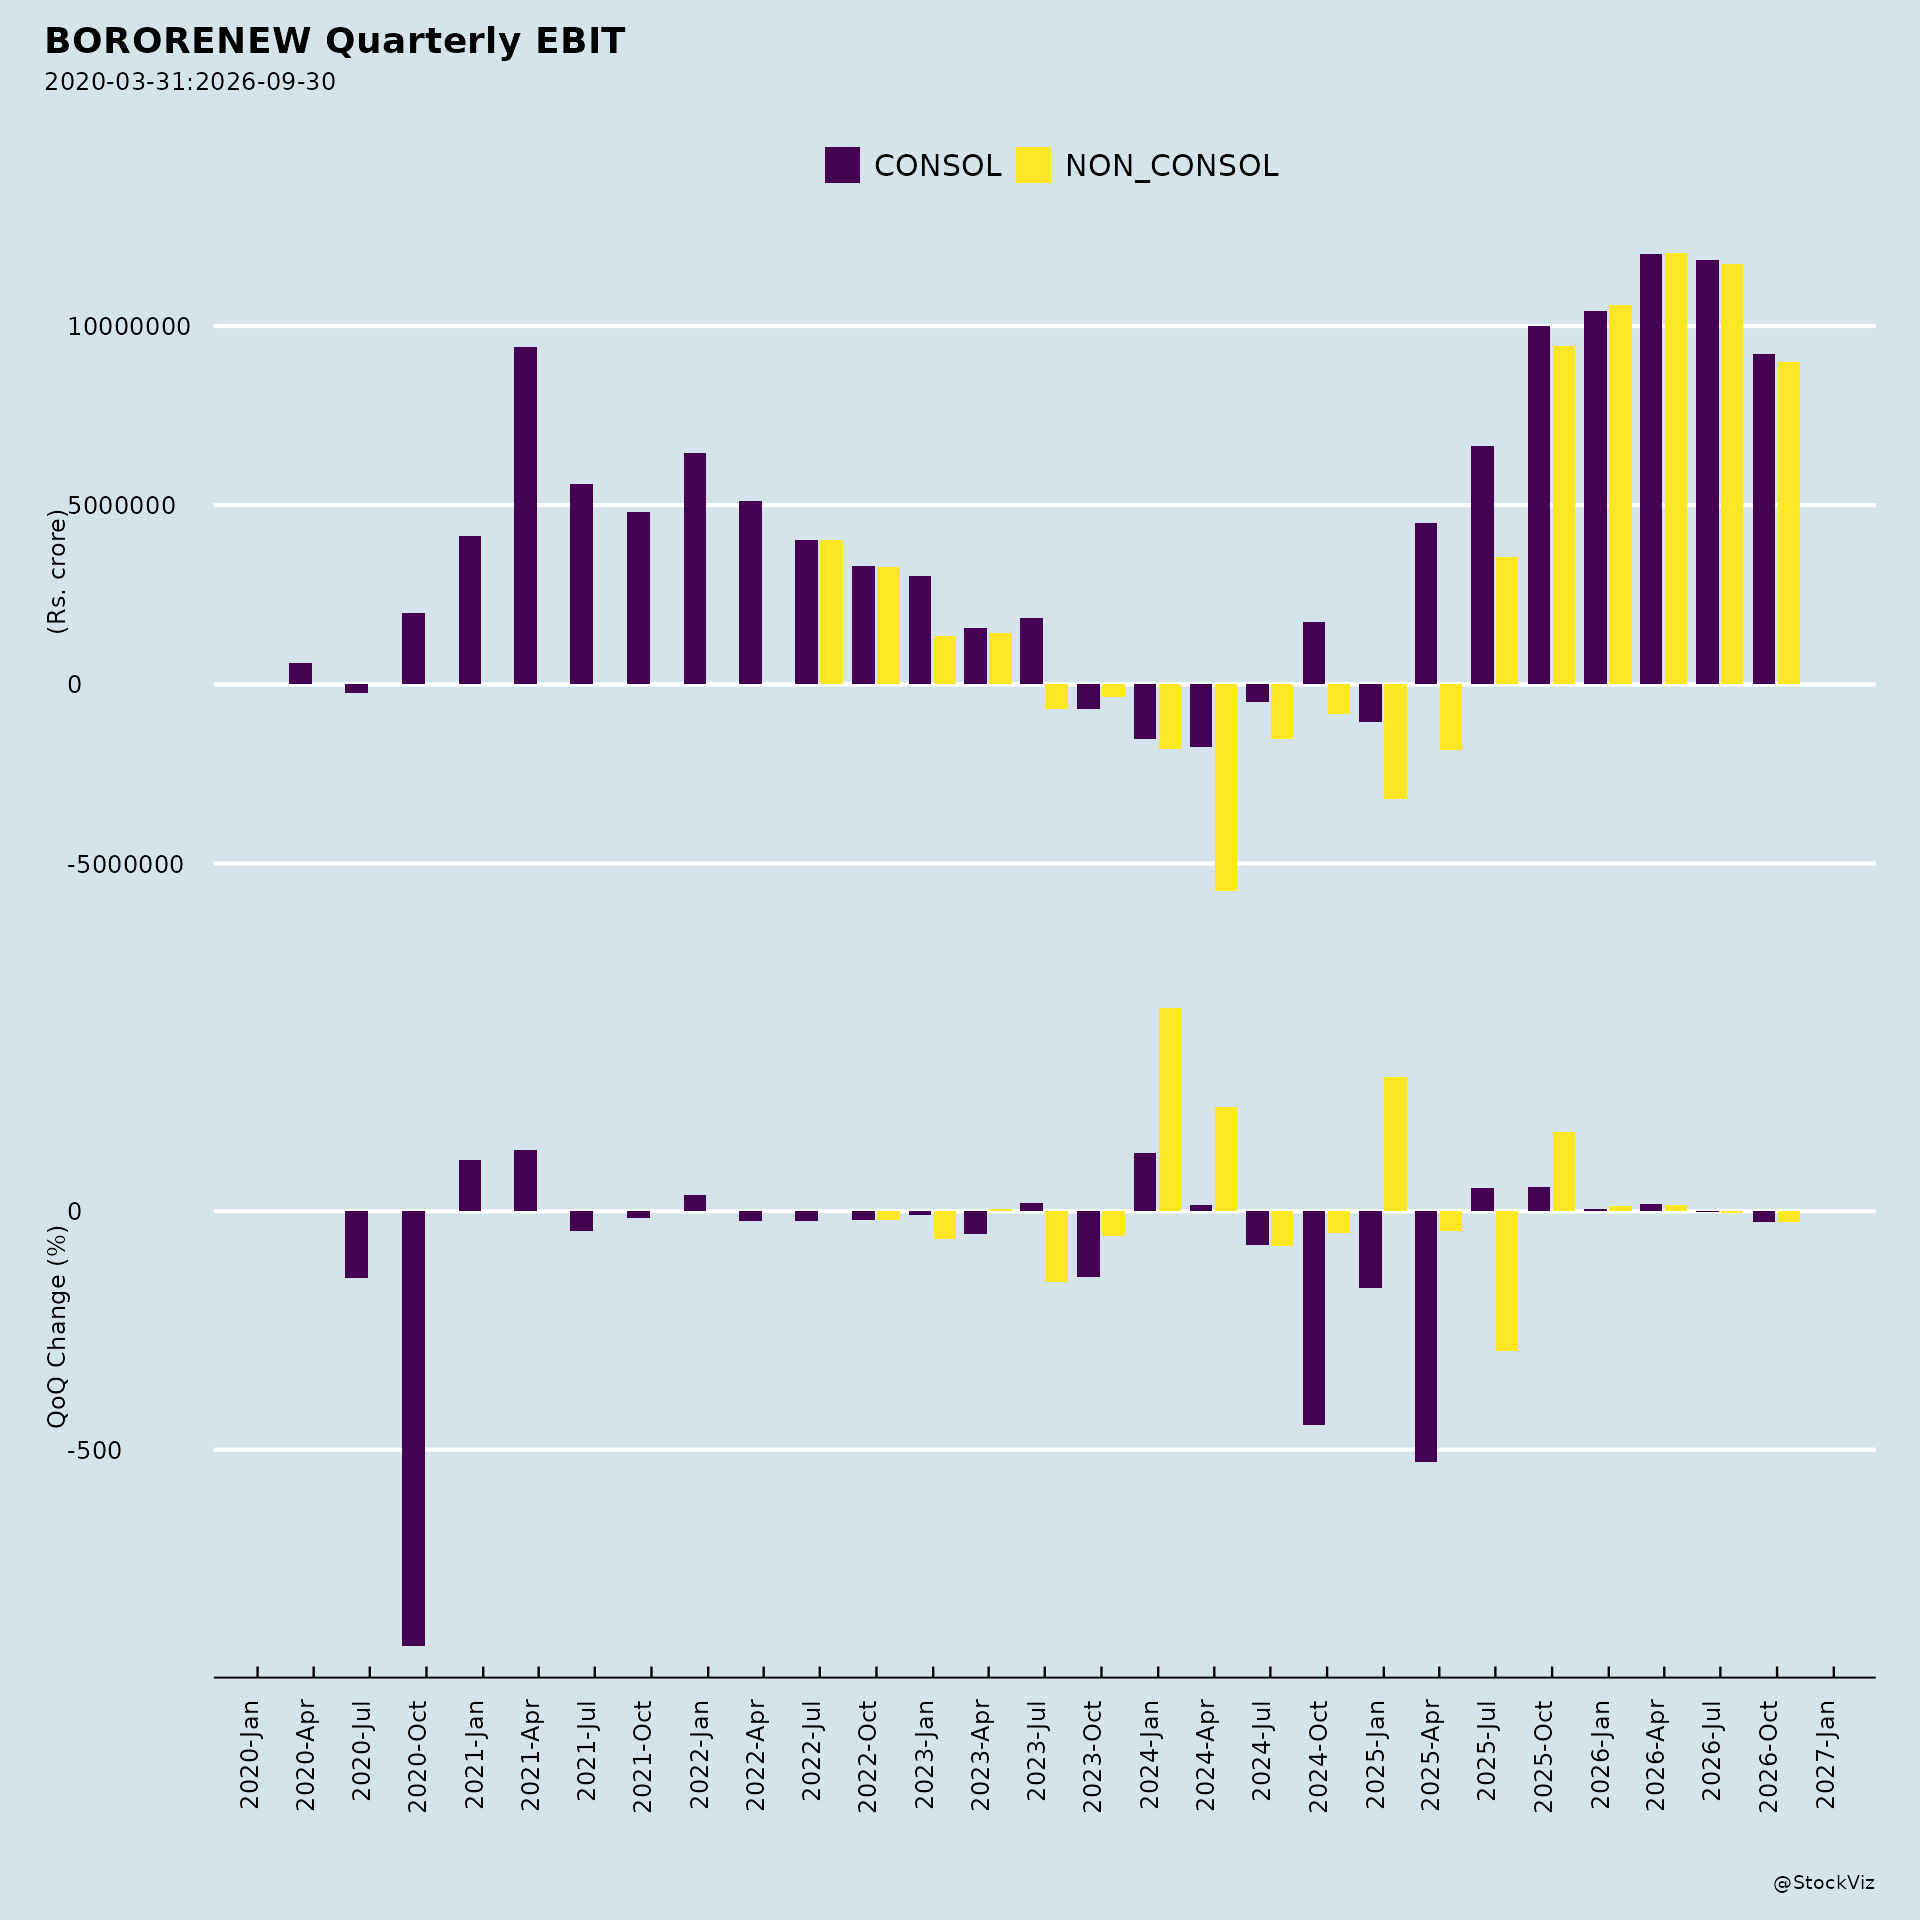
- Margin guidance: Management estimates operating leverage in EBITDA margin of about 3% with higher scale and efficiencies. Observed performance: Q1 FY27 standalone profit before exceptional items and tax was ₹11,834.73 lakhs versus ₹6,655.52 lakhs in Q1 FY26, indicating improved operating profitability year-on-year, though power and fuel costs rose.
- Fundraising guidance: Remaining warrant proceeds are expected as and when holders exercise conversion until August 13, 2026. Observed performance: ₹374.99 lakhs received in Q1 FY27 with 94,338 shares allotted; ₹23,889.22 lakhs raised overall under that issue as of the quarter.
- Investor engagement: Management is scheduled to interact with brokers, analysts, PMS, family offices, and institutions at the JM Financial Environmental & Energy Conclave on September 23, 2026, subject to change.
- Governance: All resolutions in the 63rd AGM notice were passed with the requisite majority at the AGM held August 27, 2026.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.