BALRAMCHIN
Equity Metrics
October 23, 2026
Balrampur Chini Mills Limited
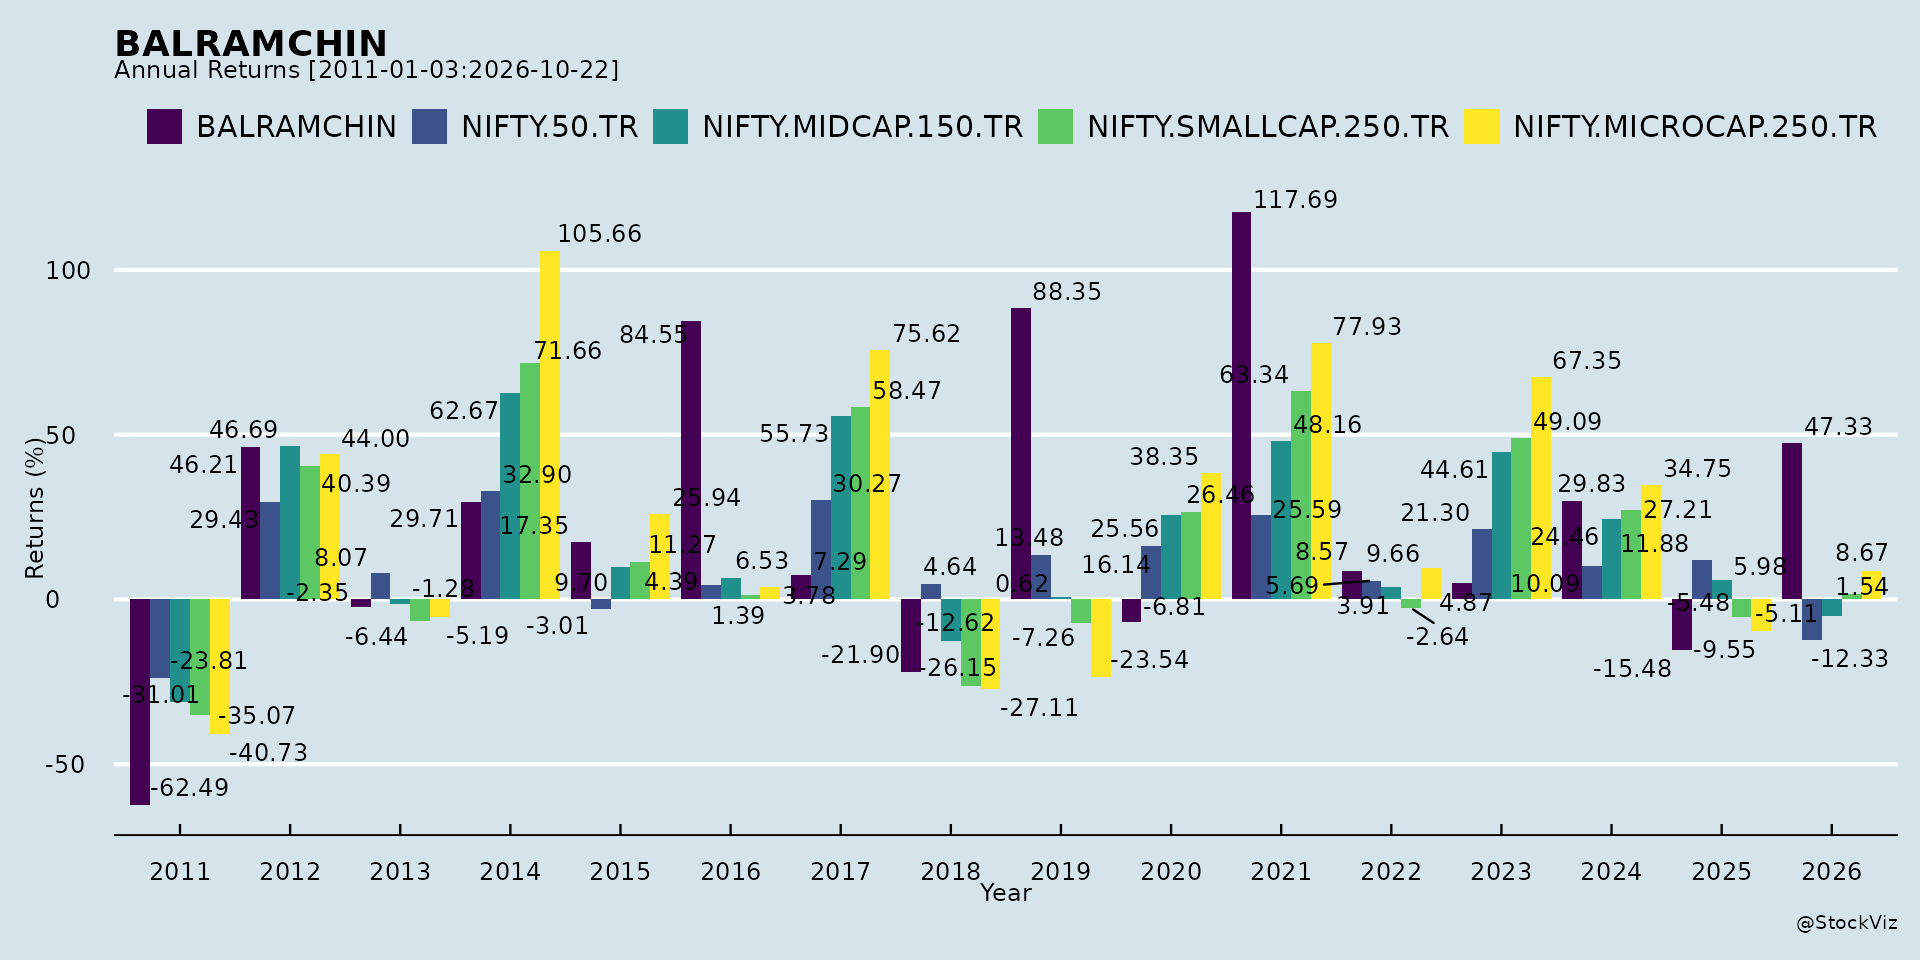
Annual Returns
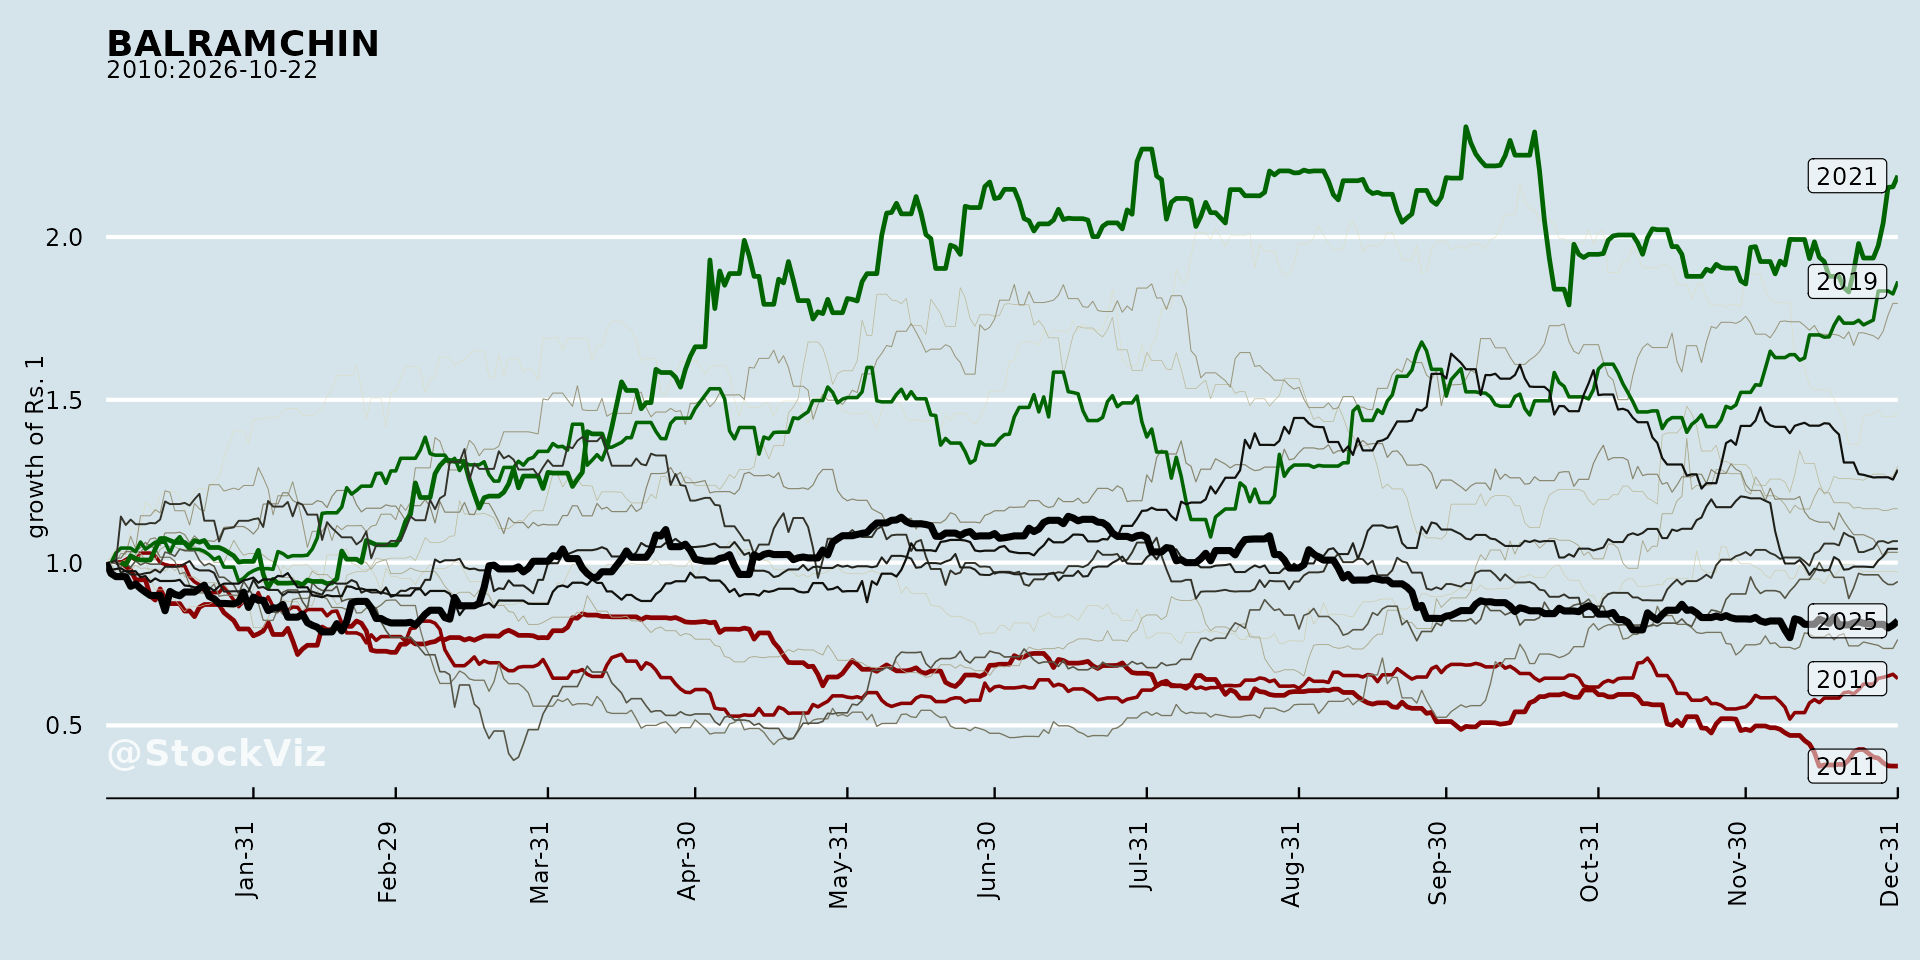
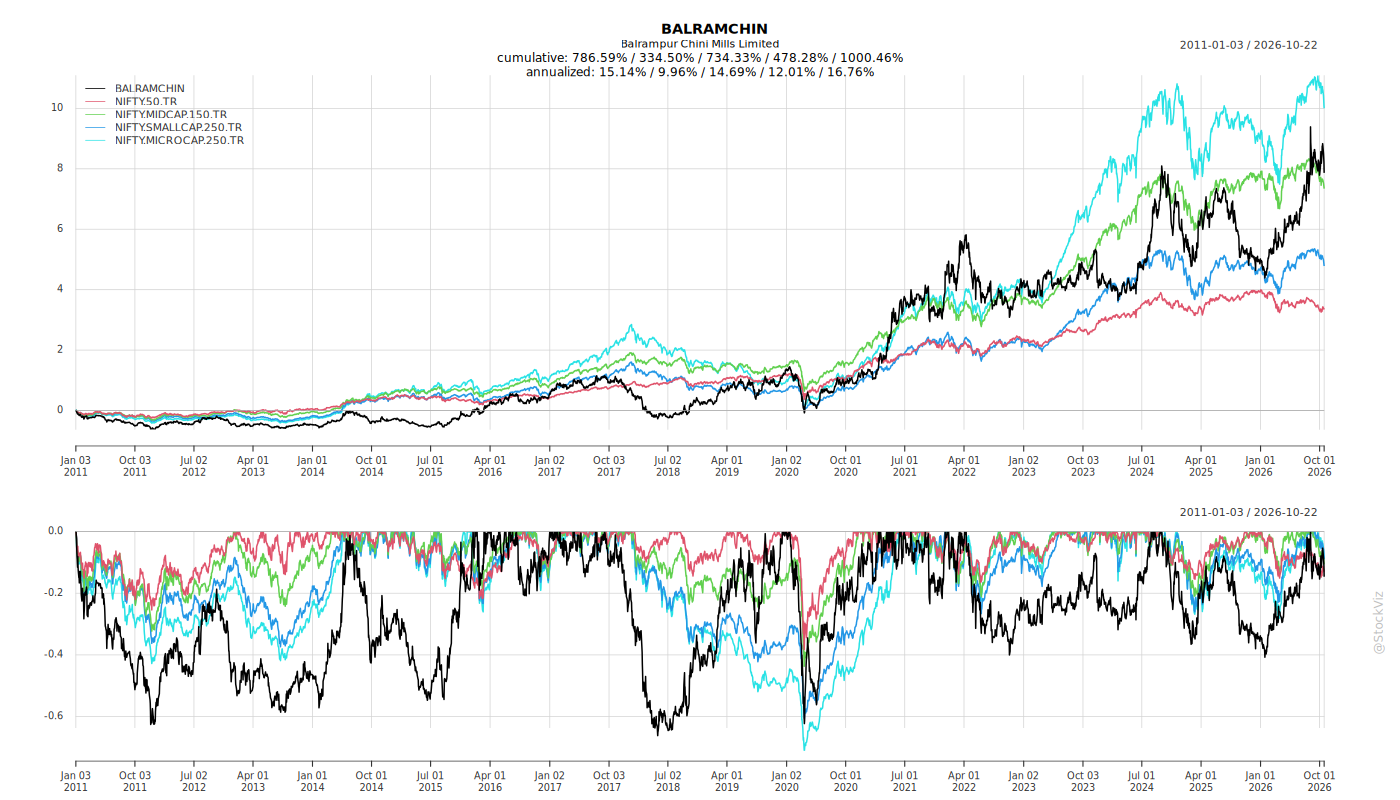
Cumulative Returns and Drawdowns
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-17
Balrampur Chini Mills — Recent Corporate Announcements
1. Headwinds and Challenges
- E20-related concerns were flagged by the Chairman in his AGM overview as a material headwind for the business.
- Compressed ethanol margins: margins in ethanol have been under pressure because prices under the Juice and B-heavy routes have not been increased over the past three years.
- PLA segment losses: the Polylactic Acid (PLA) vertical reported a segment loss before tax, finance costs and exceptional items of Rs. 984.28 lakhs for the quarter ended 30 June 2026, compared with a loss of Rs. 400.99 lakhs in the corresponding quarter of the previous year and Rs. 678.66 lakhs in the preceding quarter.
- Sugar segment weakness: sugar segment results fell to Rs. 3,876.08 lakhs for the quarter ended 30 June 2026, from Rs. 4,806.55 lakhs a year earlier and Rs. 23,129.45 lakhs in the preceding quarter.
- Seasonality: the company notes that sugar is a seasonal industry, so performance varies from quarter to quarter and quarterly results are not representative of annual performance.
- Cost and finance burden: finance costs rose to Rs. 3,248.40 lakhs in the June 2026 quarter from Rs. 2,556.47 lakhs in the preceding quarter, and changes in inventories of finished goods, by-products, stock-in-trade and work-in-progress swung to a negative Rs. 102,480.52 lakhs from a positive Rs. 156,038.96 lakhs in the preceding quarter.
2. Tailwinds and Growth Prospects
- Firming sugar prices: management cites tightness in the demand-supply situation leading to firming up of sugar prices, and the Chairman’s AGM overview referenced the recent firming of sugar prices.
- Higher sugarcane availability during the season is cited as a positive for operations.
- Ethanol and distillery strength: the distillery segment delivered Rs. 8,037.54 lakhs in segment results for the quarter ended 30 June 2026, up from Rs. 7,766.43 lakhs a year earlier and Rs. 5,367.87 lakhs in the preceding quarter.
- PLA project progress: the company is setting up India’s first Poly Lactic Acid plant with a capacity of 80,000 TPA. The revised capex is approximately Rs. 3,080 crores, funded by Rs. 1,650 crores of debt and Rs. 1,430 crores from equity/internal accruals. Management expects commercial operations in H2FY27. A robust project pipeline exceeding 80,000 tonnes per annum is anticipated by the end of 2027.
- Policy support: incentives under the Uttar Pradesh State Government Bio Plastic Industrial Policy 2024.
- PLA awareness and market development: the “Bioyug On Wheels” initiative continued its nationwide outreach, reaching Shree Somnath Temple in Gujarat on 10 July 2026, following activations at Shri Ram Mandir in Ayodhya, Rajkot and Junagadh. The initiative showcases compostable PLA-based alternatives to conventional plastics, including water bottles, cutlery, prasad boxes, compostable garbage bags and 3D printing applications.
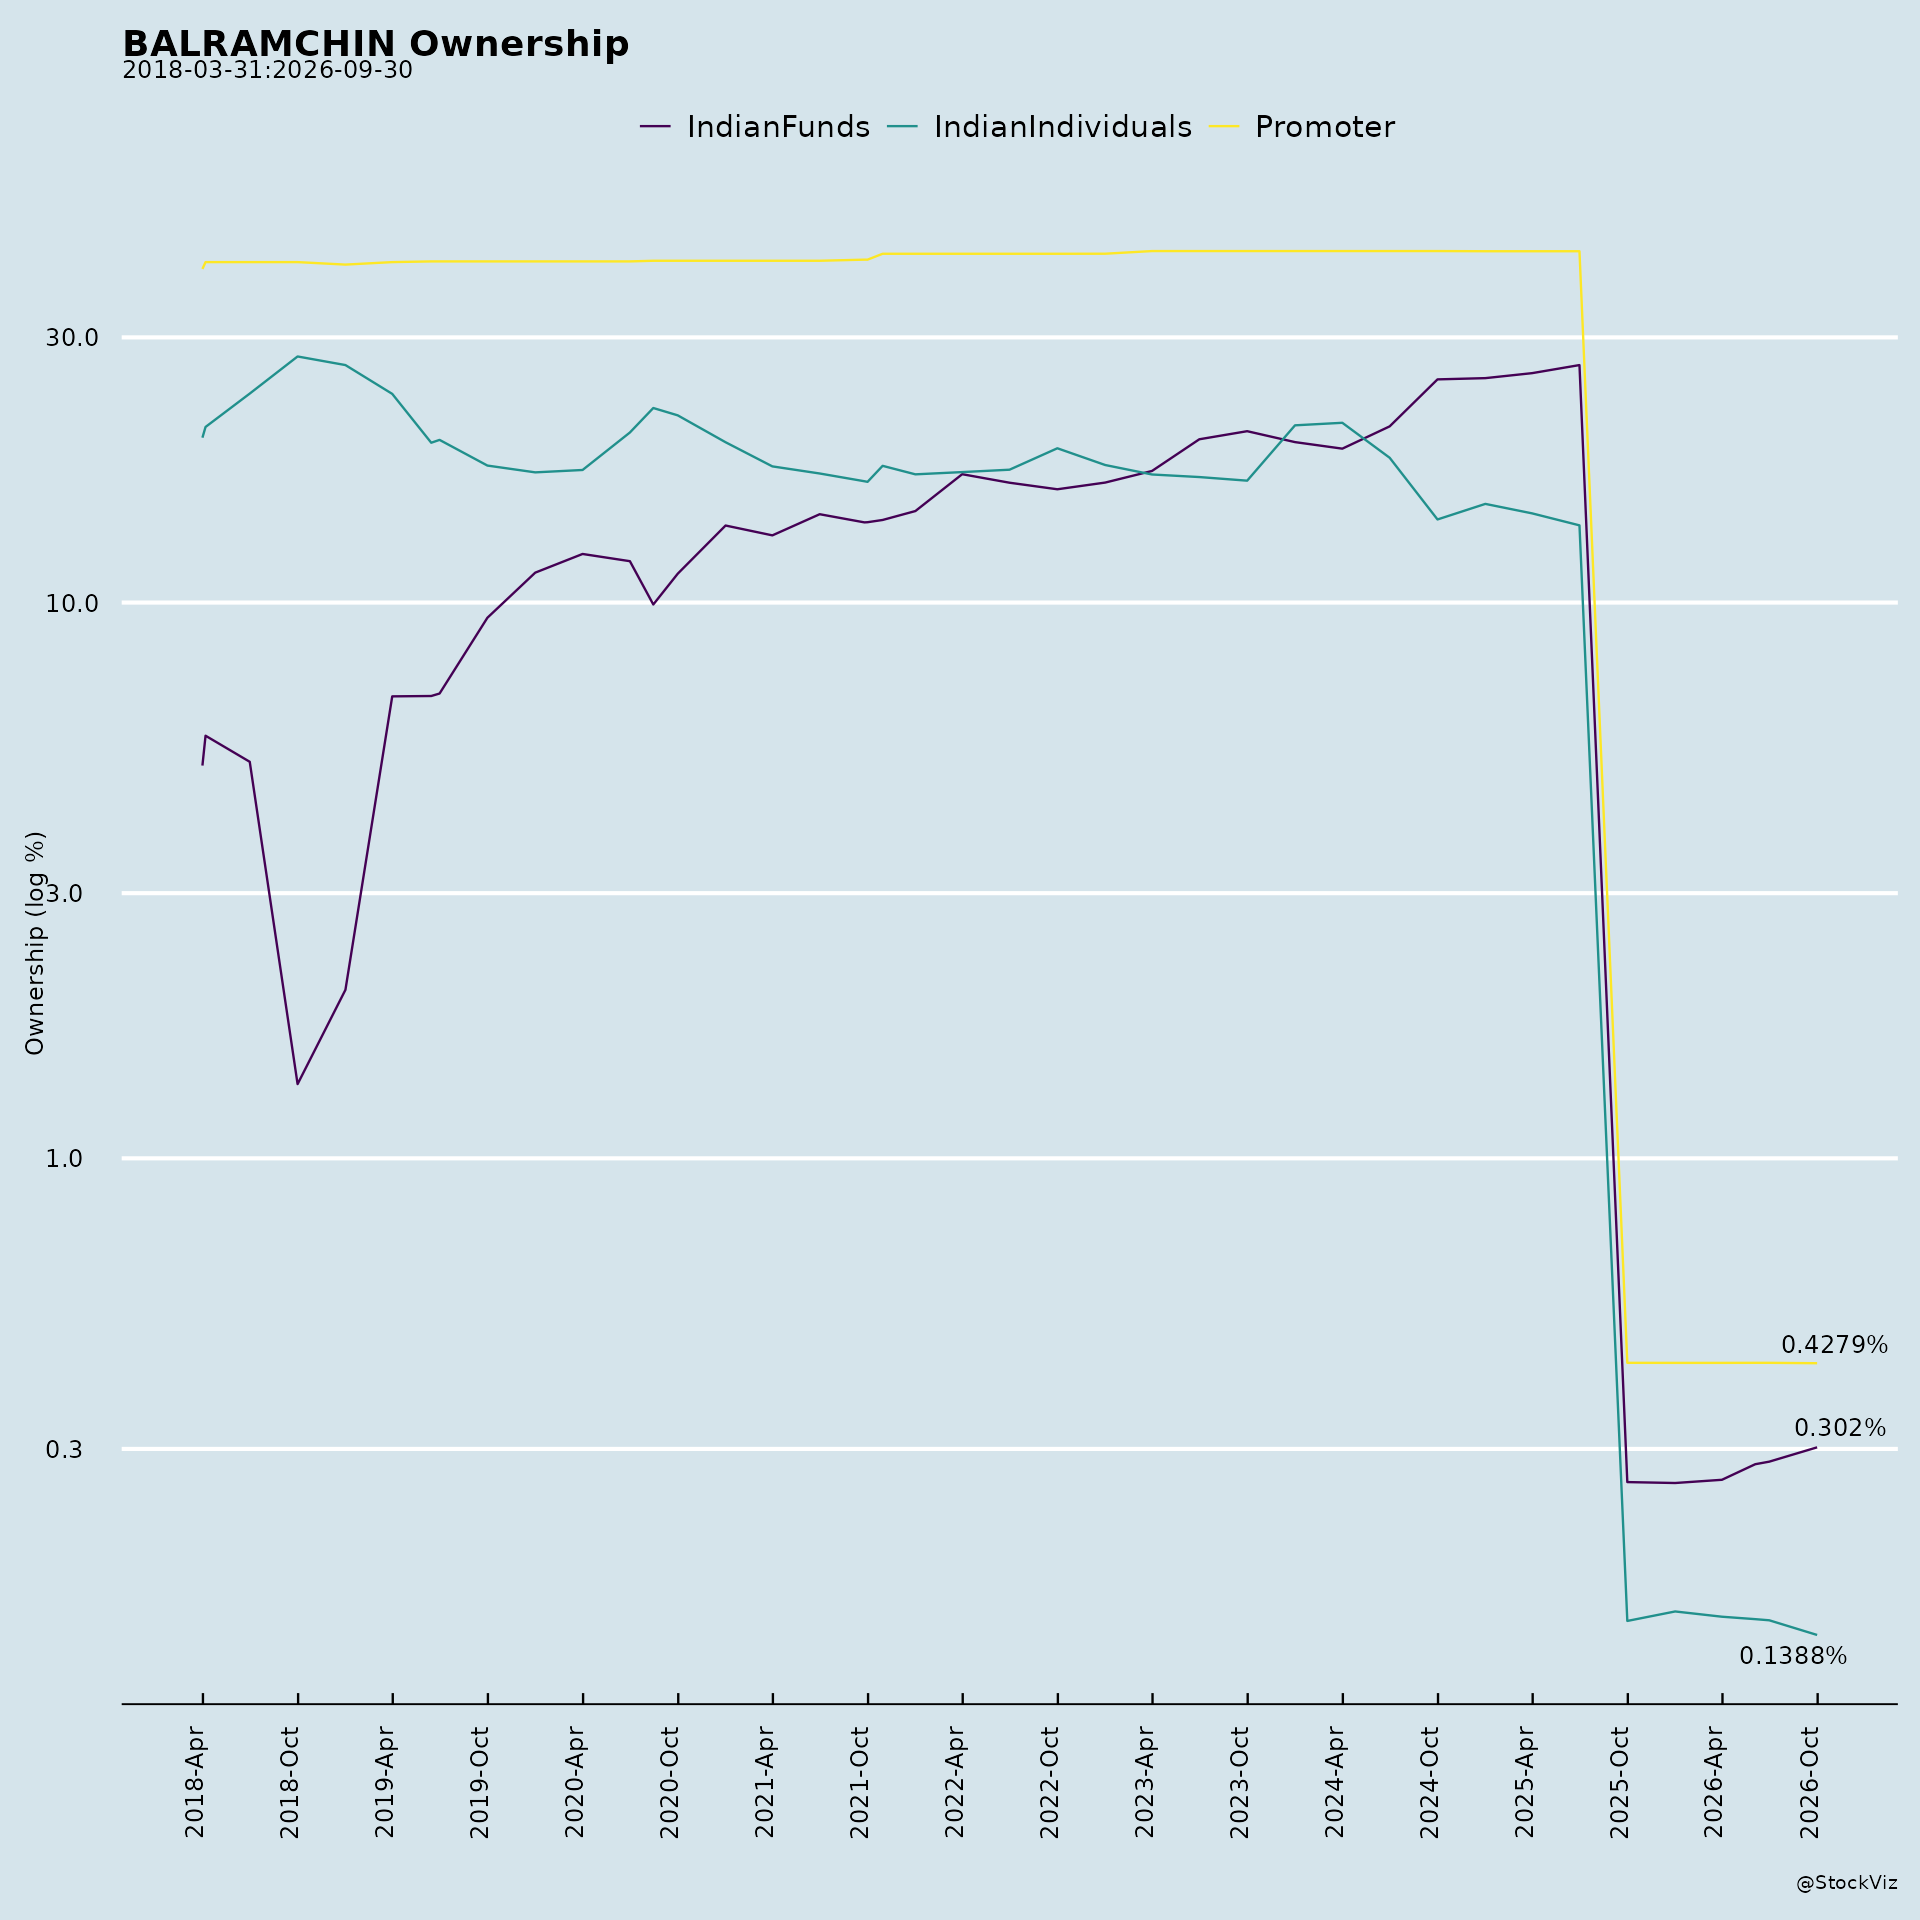
- Fundraise completed: the company issued and allotted 9,316,771 equity shares at Rs. 483 per share (including a securities premium of Rs. 482 per share), aggregating Rs. 45,000.00 lakhs, on a preferential basis. Of this, Rs. 17,074.00 lakhs was utilised towards the objects of the issue during the quarter, with the balance Rs. 27,926.00 lakhs temporarily invested in bank deposits and money market mutual funds.
- ESG recognition: ESGRisk.ai, a SEBI-registered ESG Rating Provider, voluntarily upgraded the company’s ESG rating to ‘59 – Adequate’ on 16 September 2026.
- Board strengthening: Ms. Vartika Shukla was appointed as an Additional Director (Non-Executive Independent Director) for five consecutive years from 11 August 2026 to 10 August 2031. She brings over 38 years of experience, including as Chairman and Managing Director of Engineers India Limited.
3. Key Risks
- Government actions and policy changes.
- Local political or economic developments.
- Agricultural policies.
- Climatic conditions.
- Technological risks.
- Compressed margins in ethanol on account of no increase in prices under the Juice and B-heavy routes over the past three years.
- Continued losses in the PLA segment during the ramp-up phase.
- Seasonality-driven volatility in quarterly performance.
4. Management Guidance vs. Observed Business Performance
- PLA commercial operations: management expects the 80,000 tons PLA plant to commence operations in H2FY27. Observed performance shows the PLA segment still reporting losses (Rs. 984.28 lakhs in Q1FY27) and segment assets rising to Rs. 240,959.71 lakhs as at 30 June 2026 from Rs. 90,637.31 lakhs a year earlier, consistent with ongoing capital expenditure. Segment liabilities for PLA stood at Rs. 28,849.11 lakhs.
- Sugar price firming: management cites tightness in demand-supply leading to firming sugar prices. Observed Q1FY27 sugar segment results were Rs. 3,876.08 lakhs, lower than both the corresponding quarter (Rs. 4,806.55 lakhs) and the preceding quarter (Rs. 23,129.45 lakhs), reflecting seasonal and inventory-related dynamics.
- Ethanol margin pressure: management flags compressed ethanol margins due to unchanged Juice and B-heavy route prices over three years. Observed distillery segment results improved to Rs. 8,037.54 lakhs in Q1FY27 from Rs. 7,766.43 lakhs a year earlier.
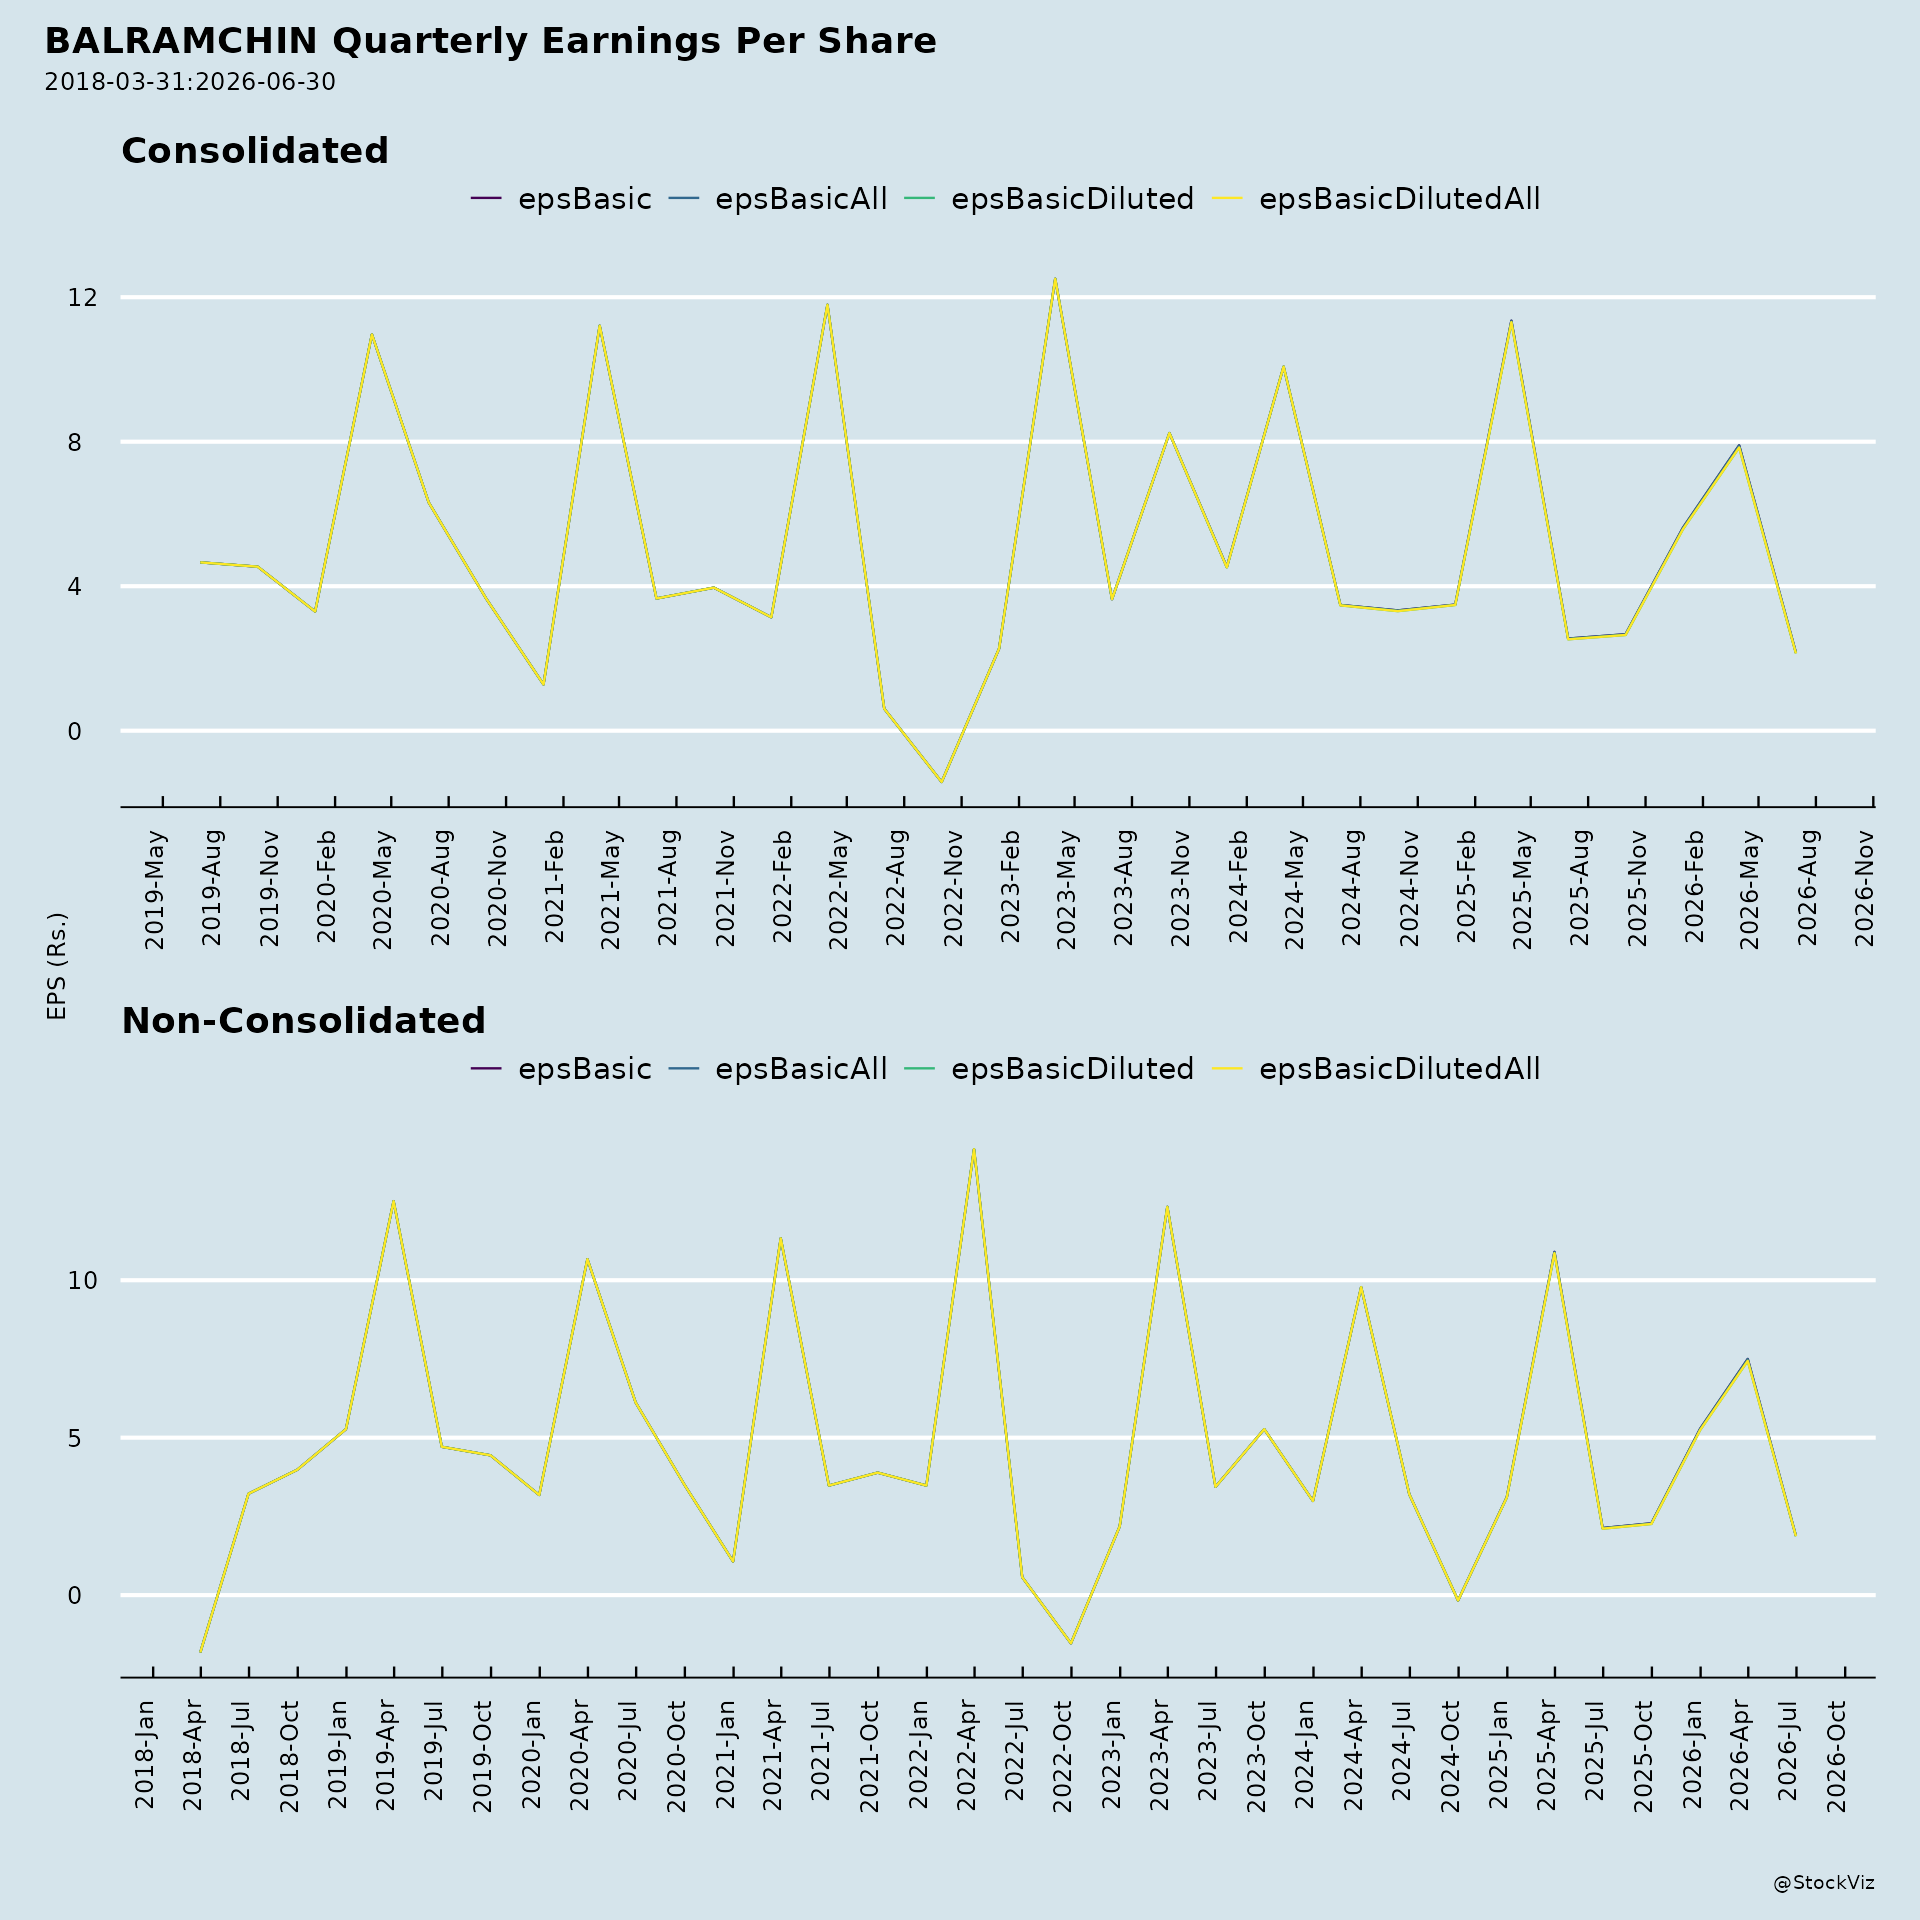
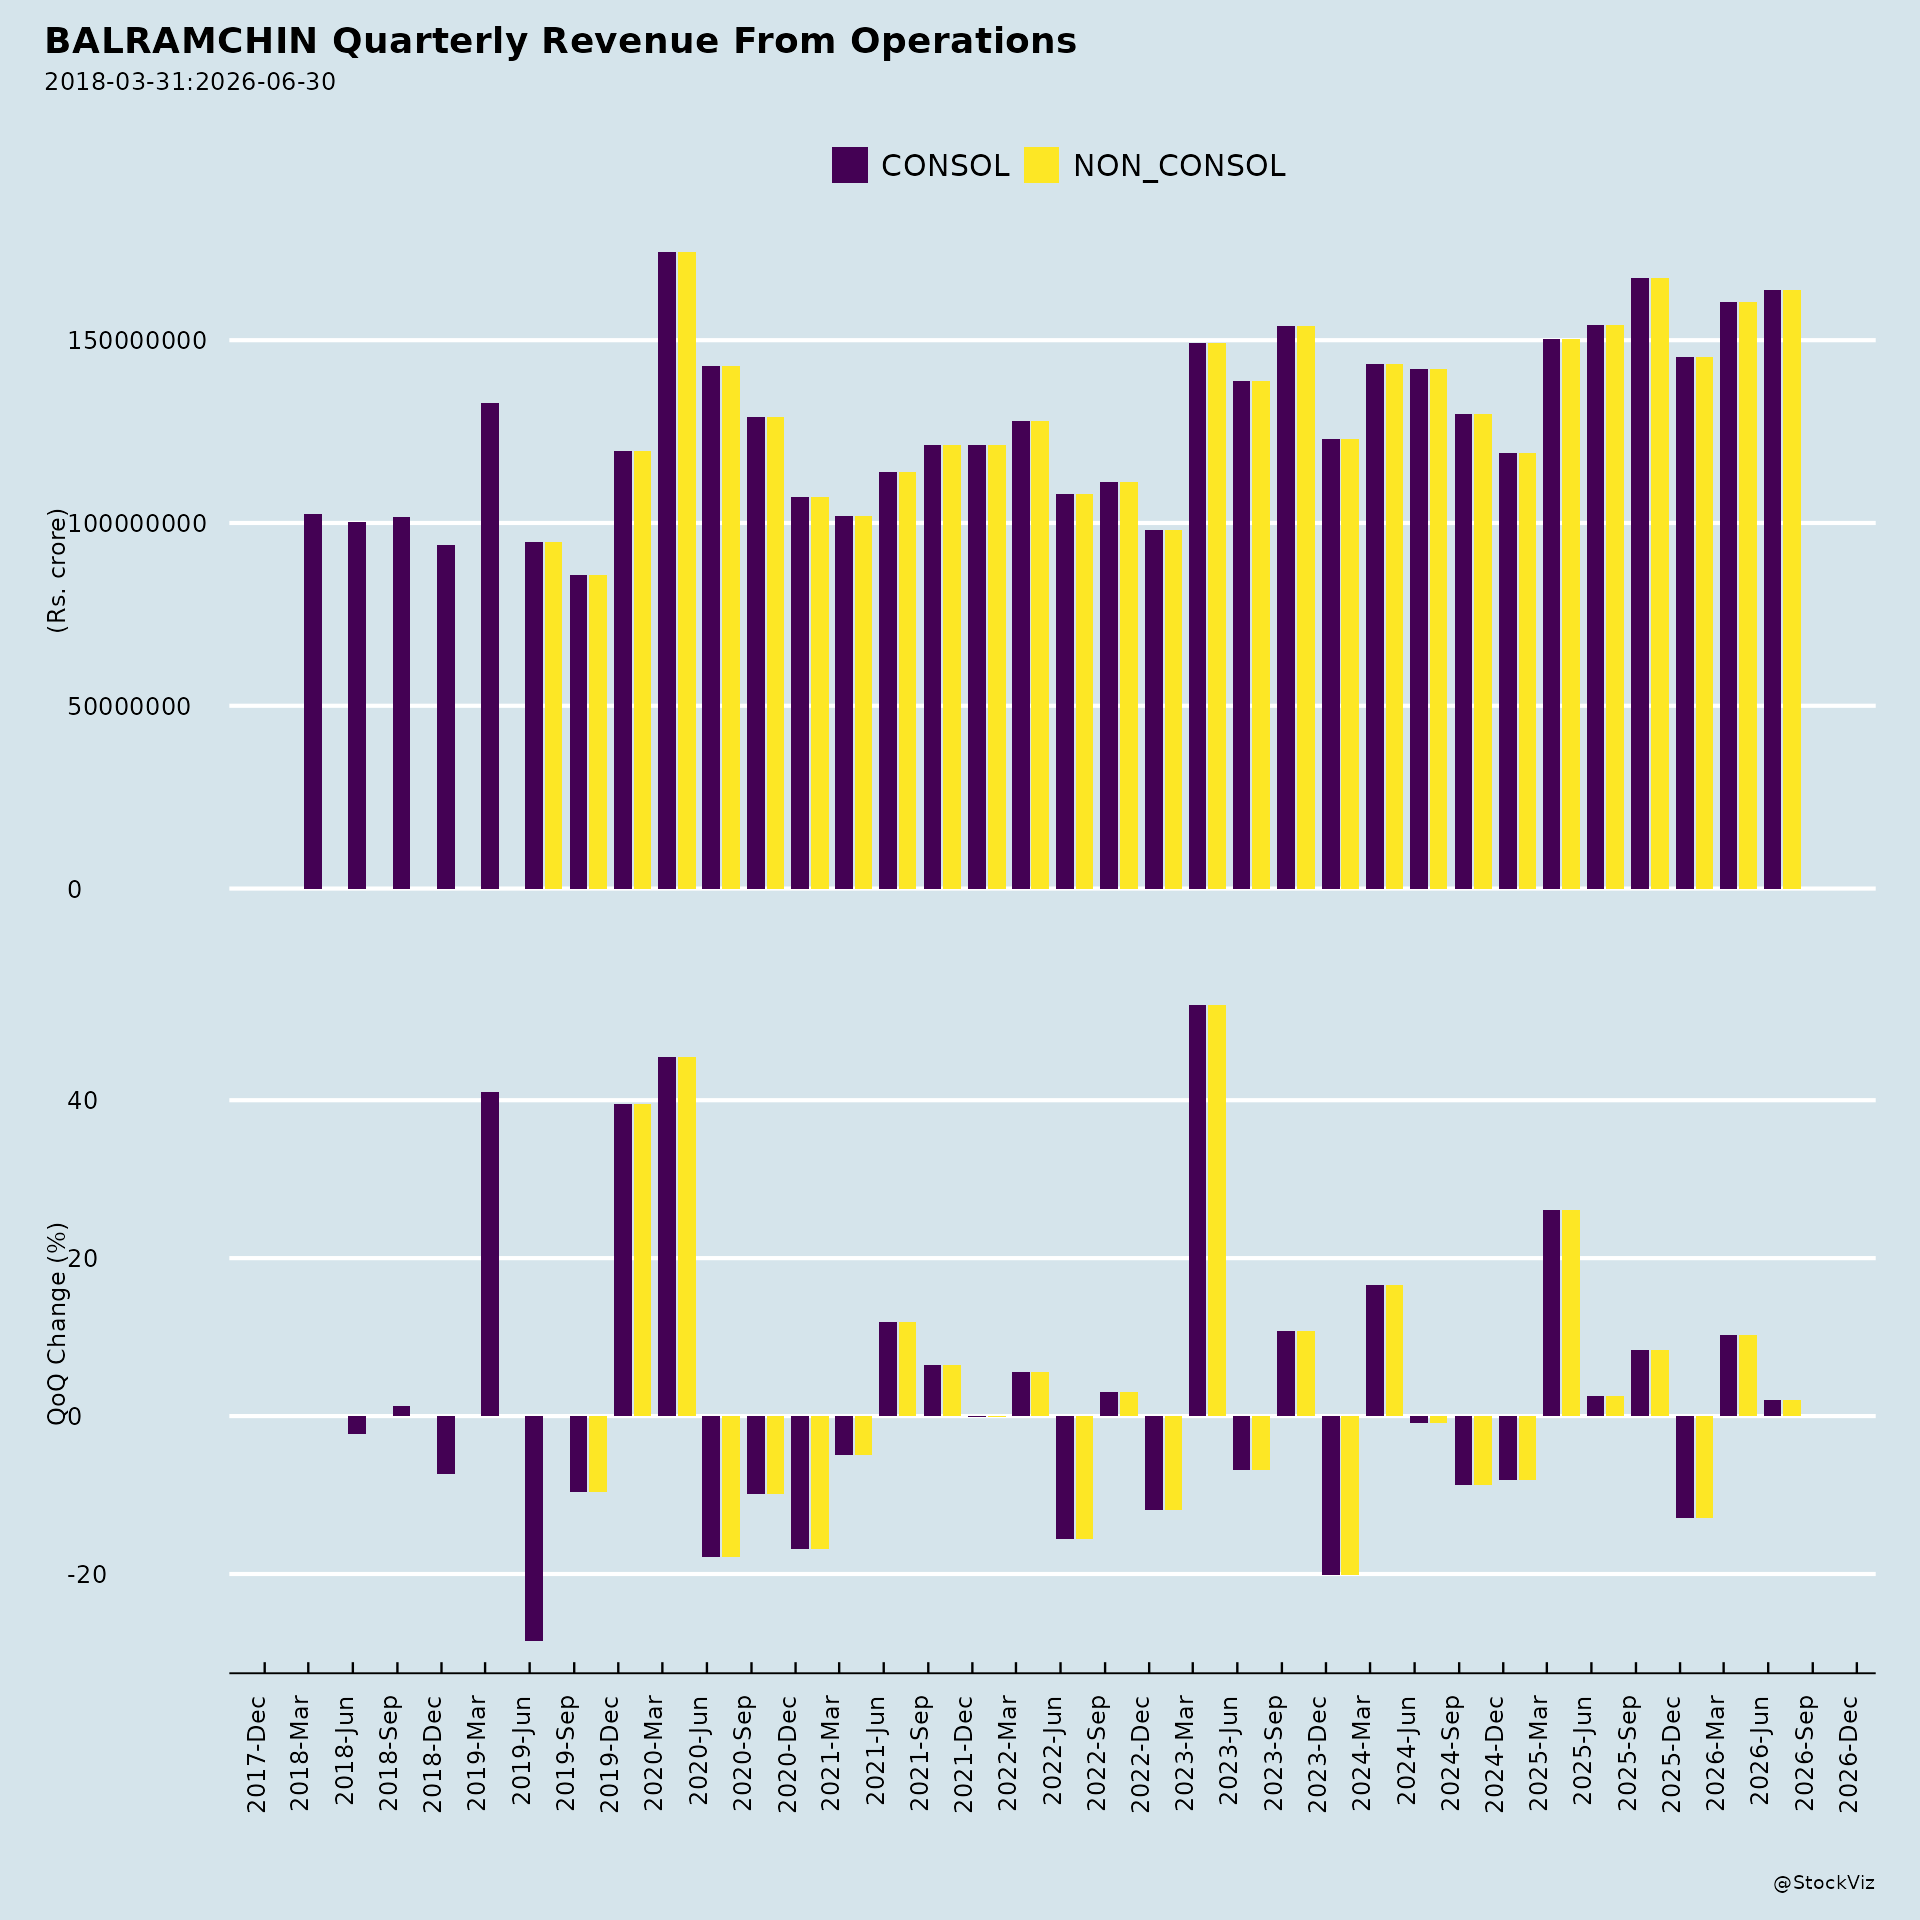
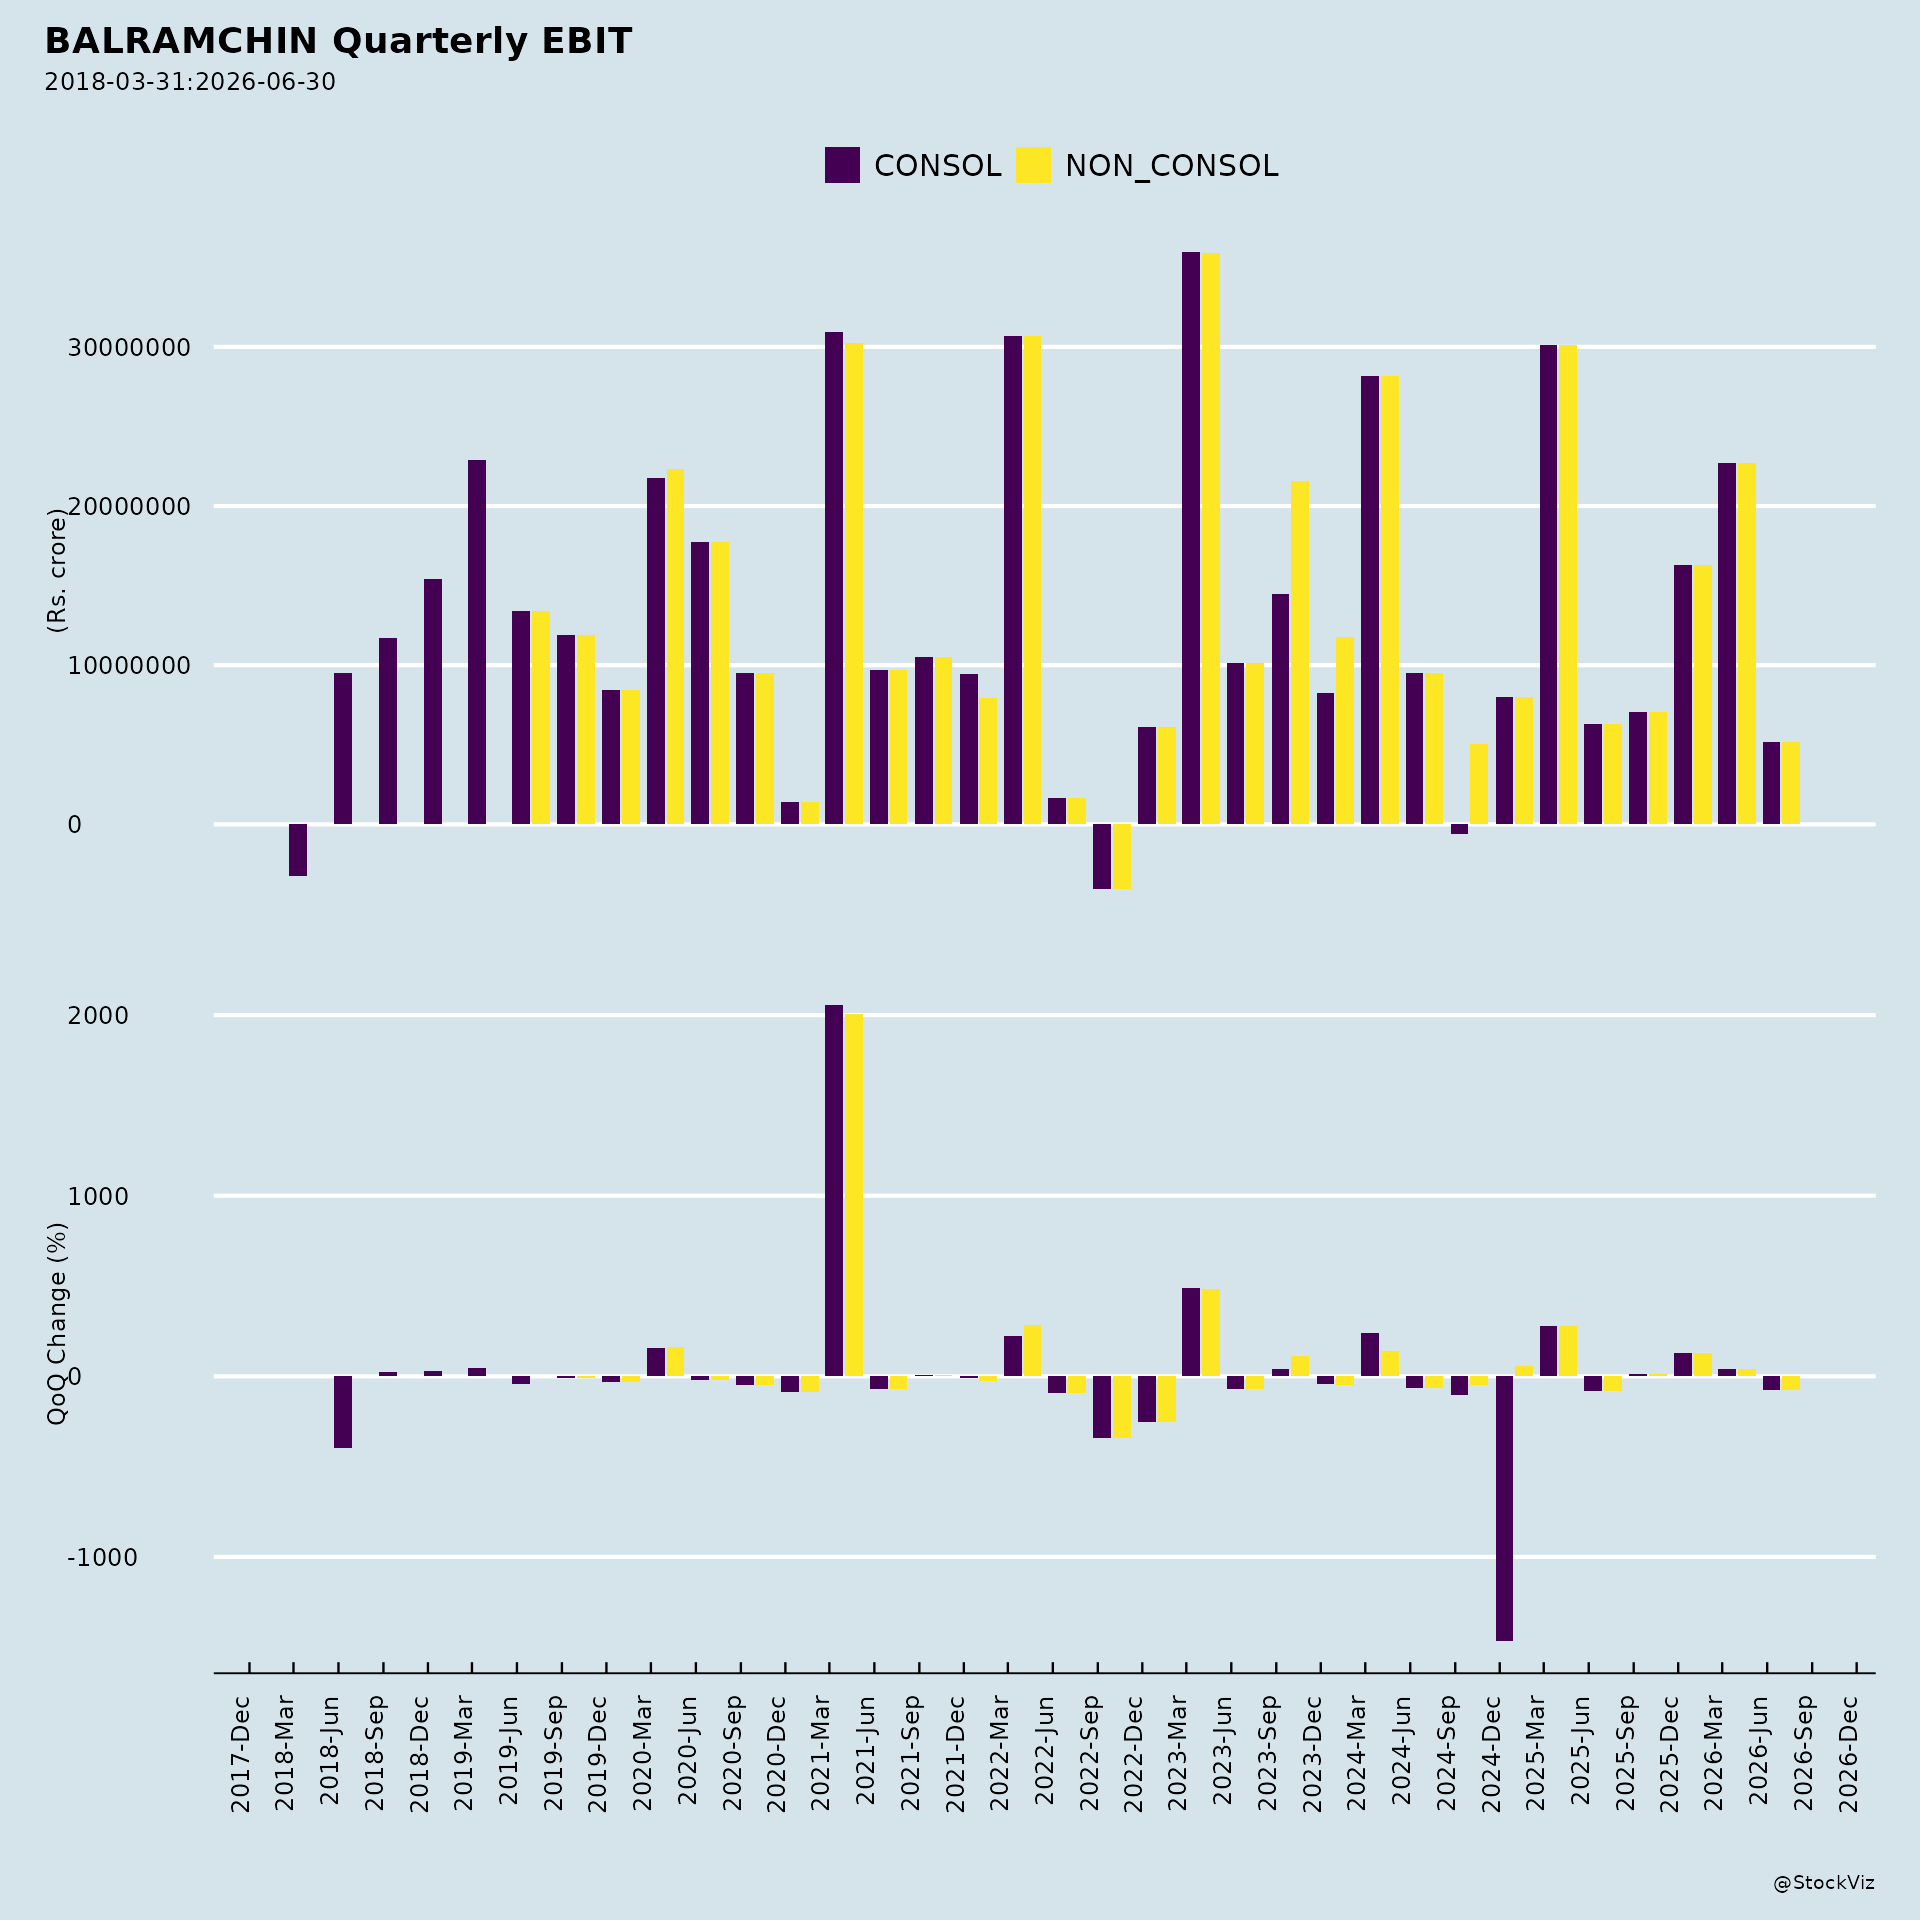
- Overall Q1FY27 performance: consolidated revenue was Rs. 1,636.79 crores, PBT was Rs. 58.53 crores, and total comprehensive income was Rs. 43.52 crores. Standalone profit for the period was Rs. 3,858.63 lakhs, with basic EPS of Rs. 1.88 and diluted EPS of Rs. 1.87.
- Inventory position: the company carries sugar inventory of 45.67 lakh qtls valued at Rs. 37.19 per kg.
- Share capital increase: following the preferential allotment and ESAR exercises, the issued, subscribed and paid-up equity share capital increased to 211,267,207 equity shares of par value Rs. 1 each as at 30 June 2026. A further 461,110 ESARs were exercised up to 28 July 2026, and allotment of 199,907 equity shares arising from ESAR exercises was completed on 29 July 2026.
- Investor engagement: management interacted with analysts/investors in a physical group meet/one-on-one organised by Elara Securities (India) Private Limited on 2 September 2026, with no unpublished price sensitive information discussed.
- AGM: the 50th Annual General Meeting was held on Wednesday, 16 September 2026 at 04:00 P.M. through video conferencing/other audio-visual means, with 107 members in attendance, transacting nine items of business including financial statement adoptions, dividend confirmations and various appointments.
Broker Narrative
The first report framed BALRAMCHIN almost entirely through technicals, weighing near-term selling pressure and RSI weakness against a bullish monthly trend and support-bounce buying. By the last report, the narrative had shifted to fundamentals and policy: ethanol feedstock restrictions, high cane/maize costs, low cane availability, and sharply lower ethanol/distillery earnings. The persistent element was the Buy call, but the optimism drivers changed from chart levels to expected regulatory catalysts such as feedstock flexibility, ethanol price/MSP hikes, and sugar exports.
Broker Timeline
10 broker calls · 2022-03-01 to 2024-11-26
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.