AVONMORE
Equity Metrics
November 18, 2026
Avonmore Capital & Management Services Limited
Non Banking Financial Company (NBFC)
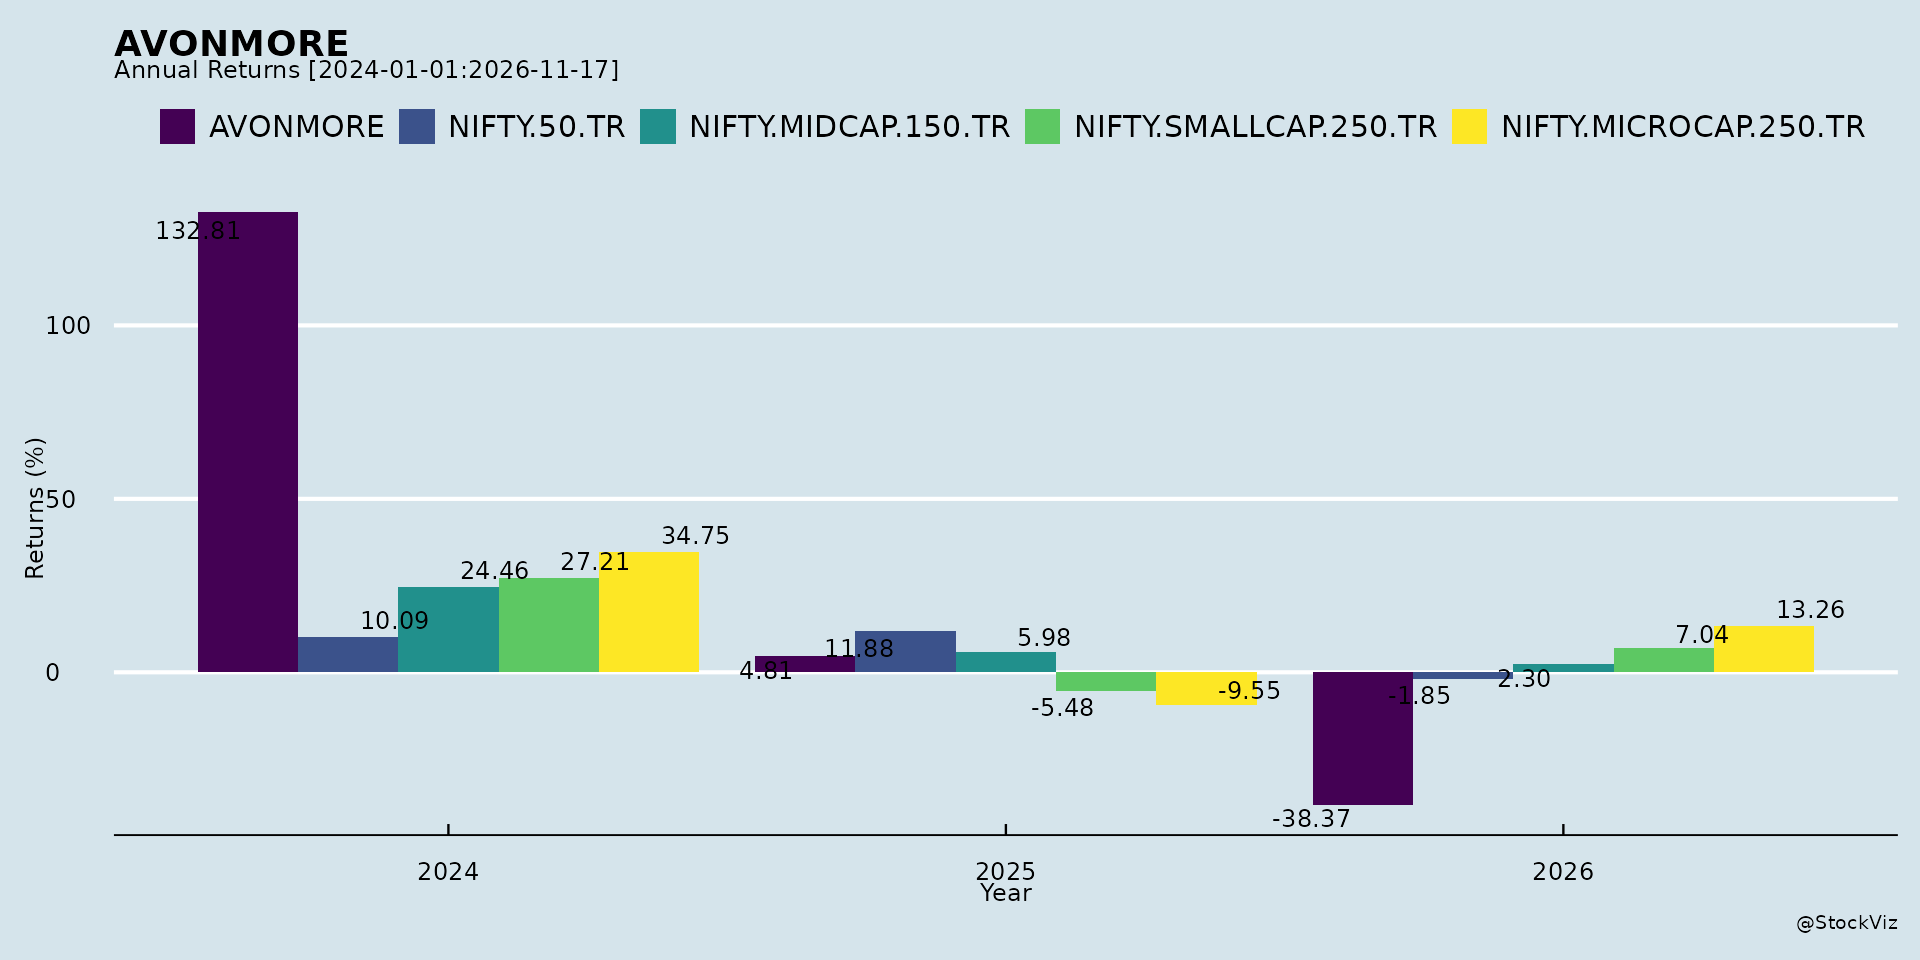
Annual Returns
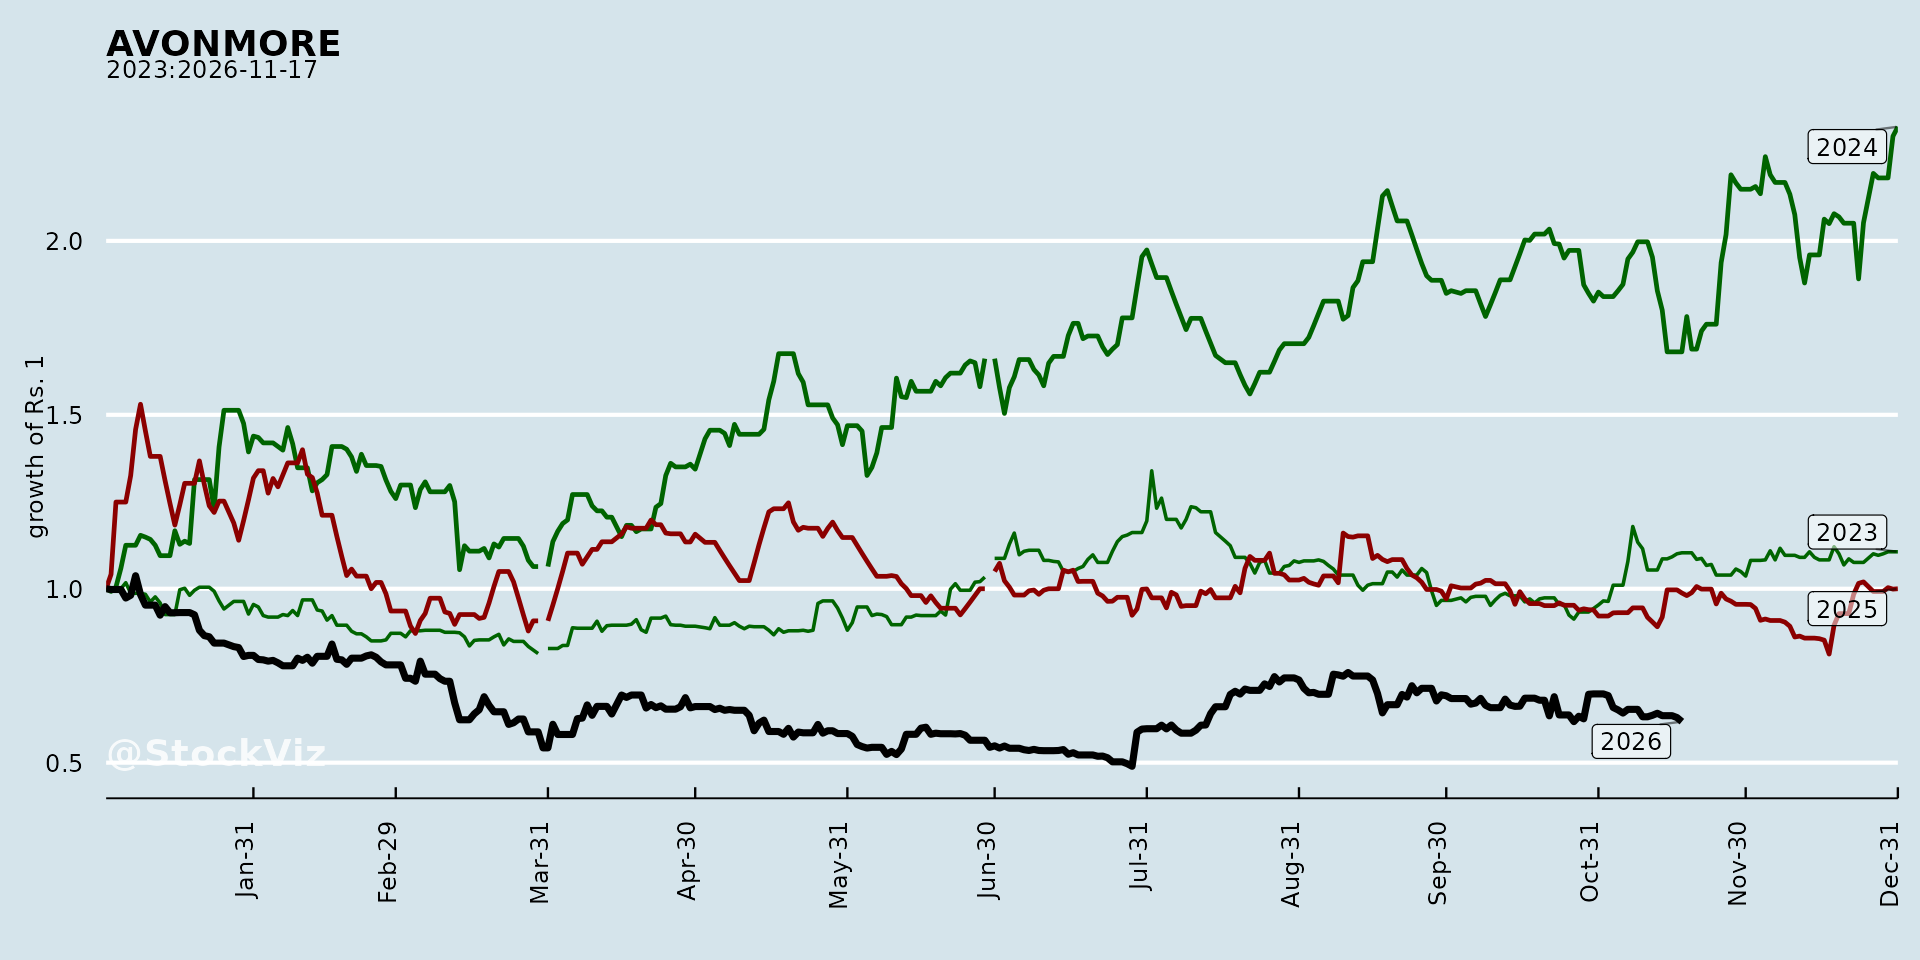
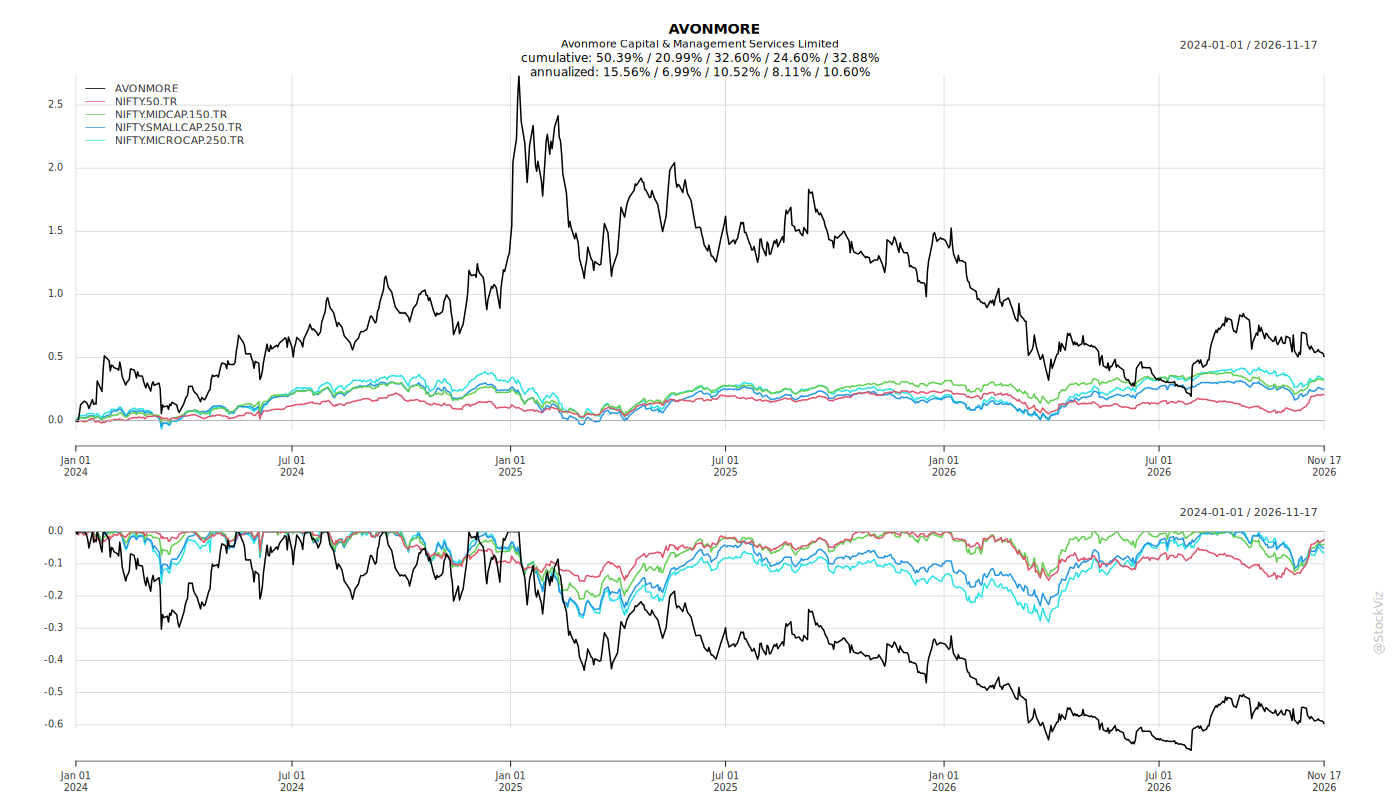
Cumulative Returns and Drawdowns
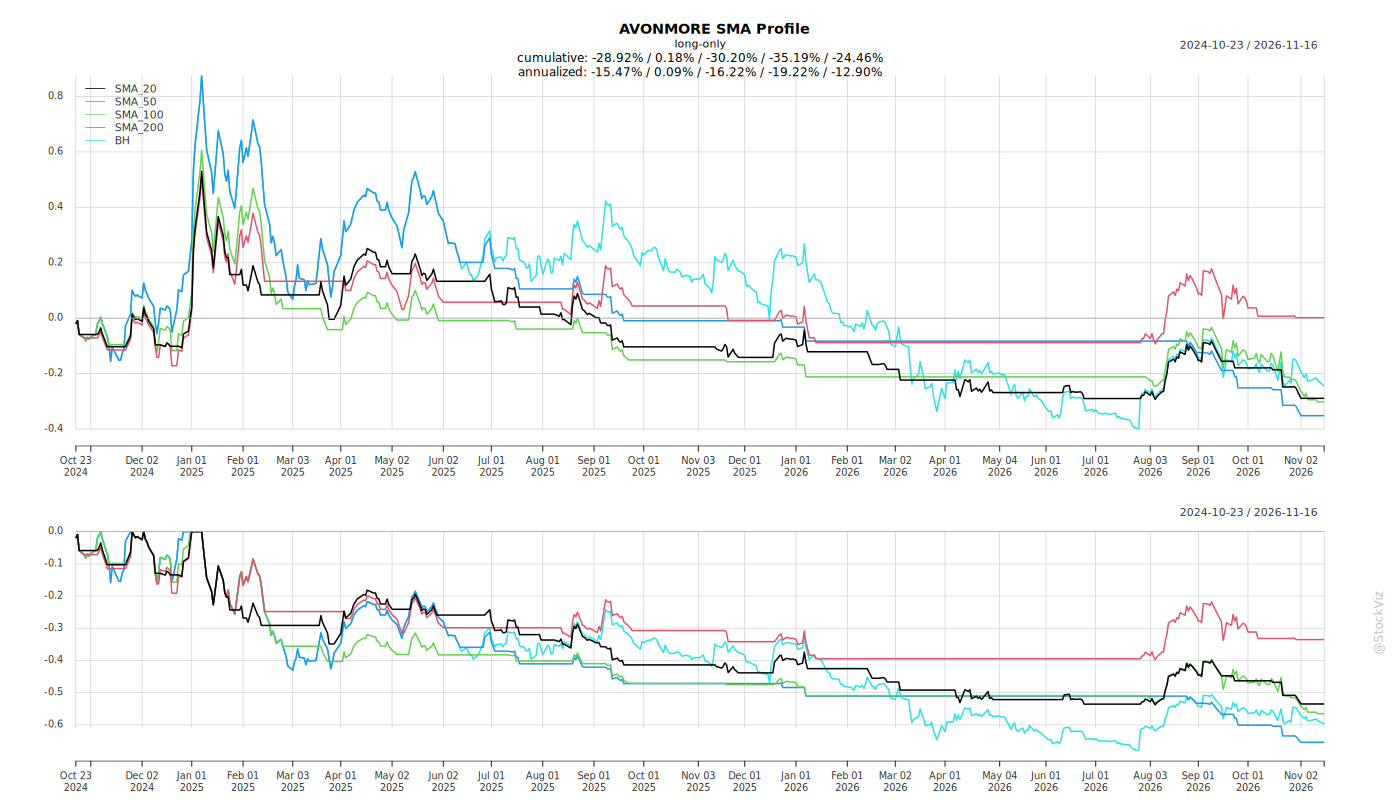
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-19
Avonmore Capital & Management Services — Recent Corporate Announcements
1. Headwinds and Challenges
Green Fuel commercialisation delay: PGIPL’s Odisha plant has completed all planned construction, installation and commissioning activities and is fully ready for commercial operations, but commercial production on a full scale has not commenced because the procurement agreement with the Oil Marketing Companies (OMCs) is still awaited. The procurement will be finalised through a tendering process that the OMCs have not yet floated. The previous tender cycle could not be participated in because the plant was not ready for production at that time.
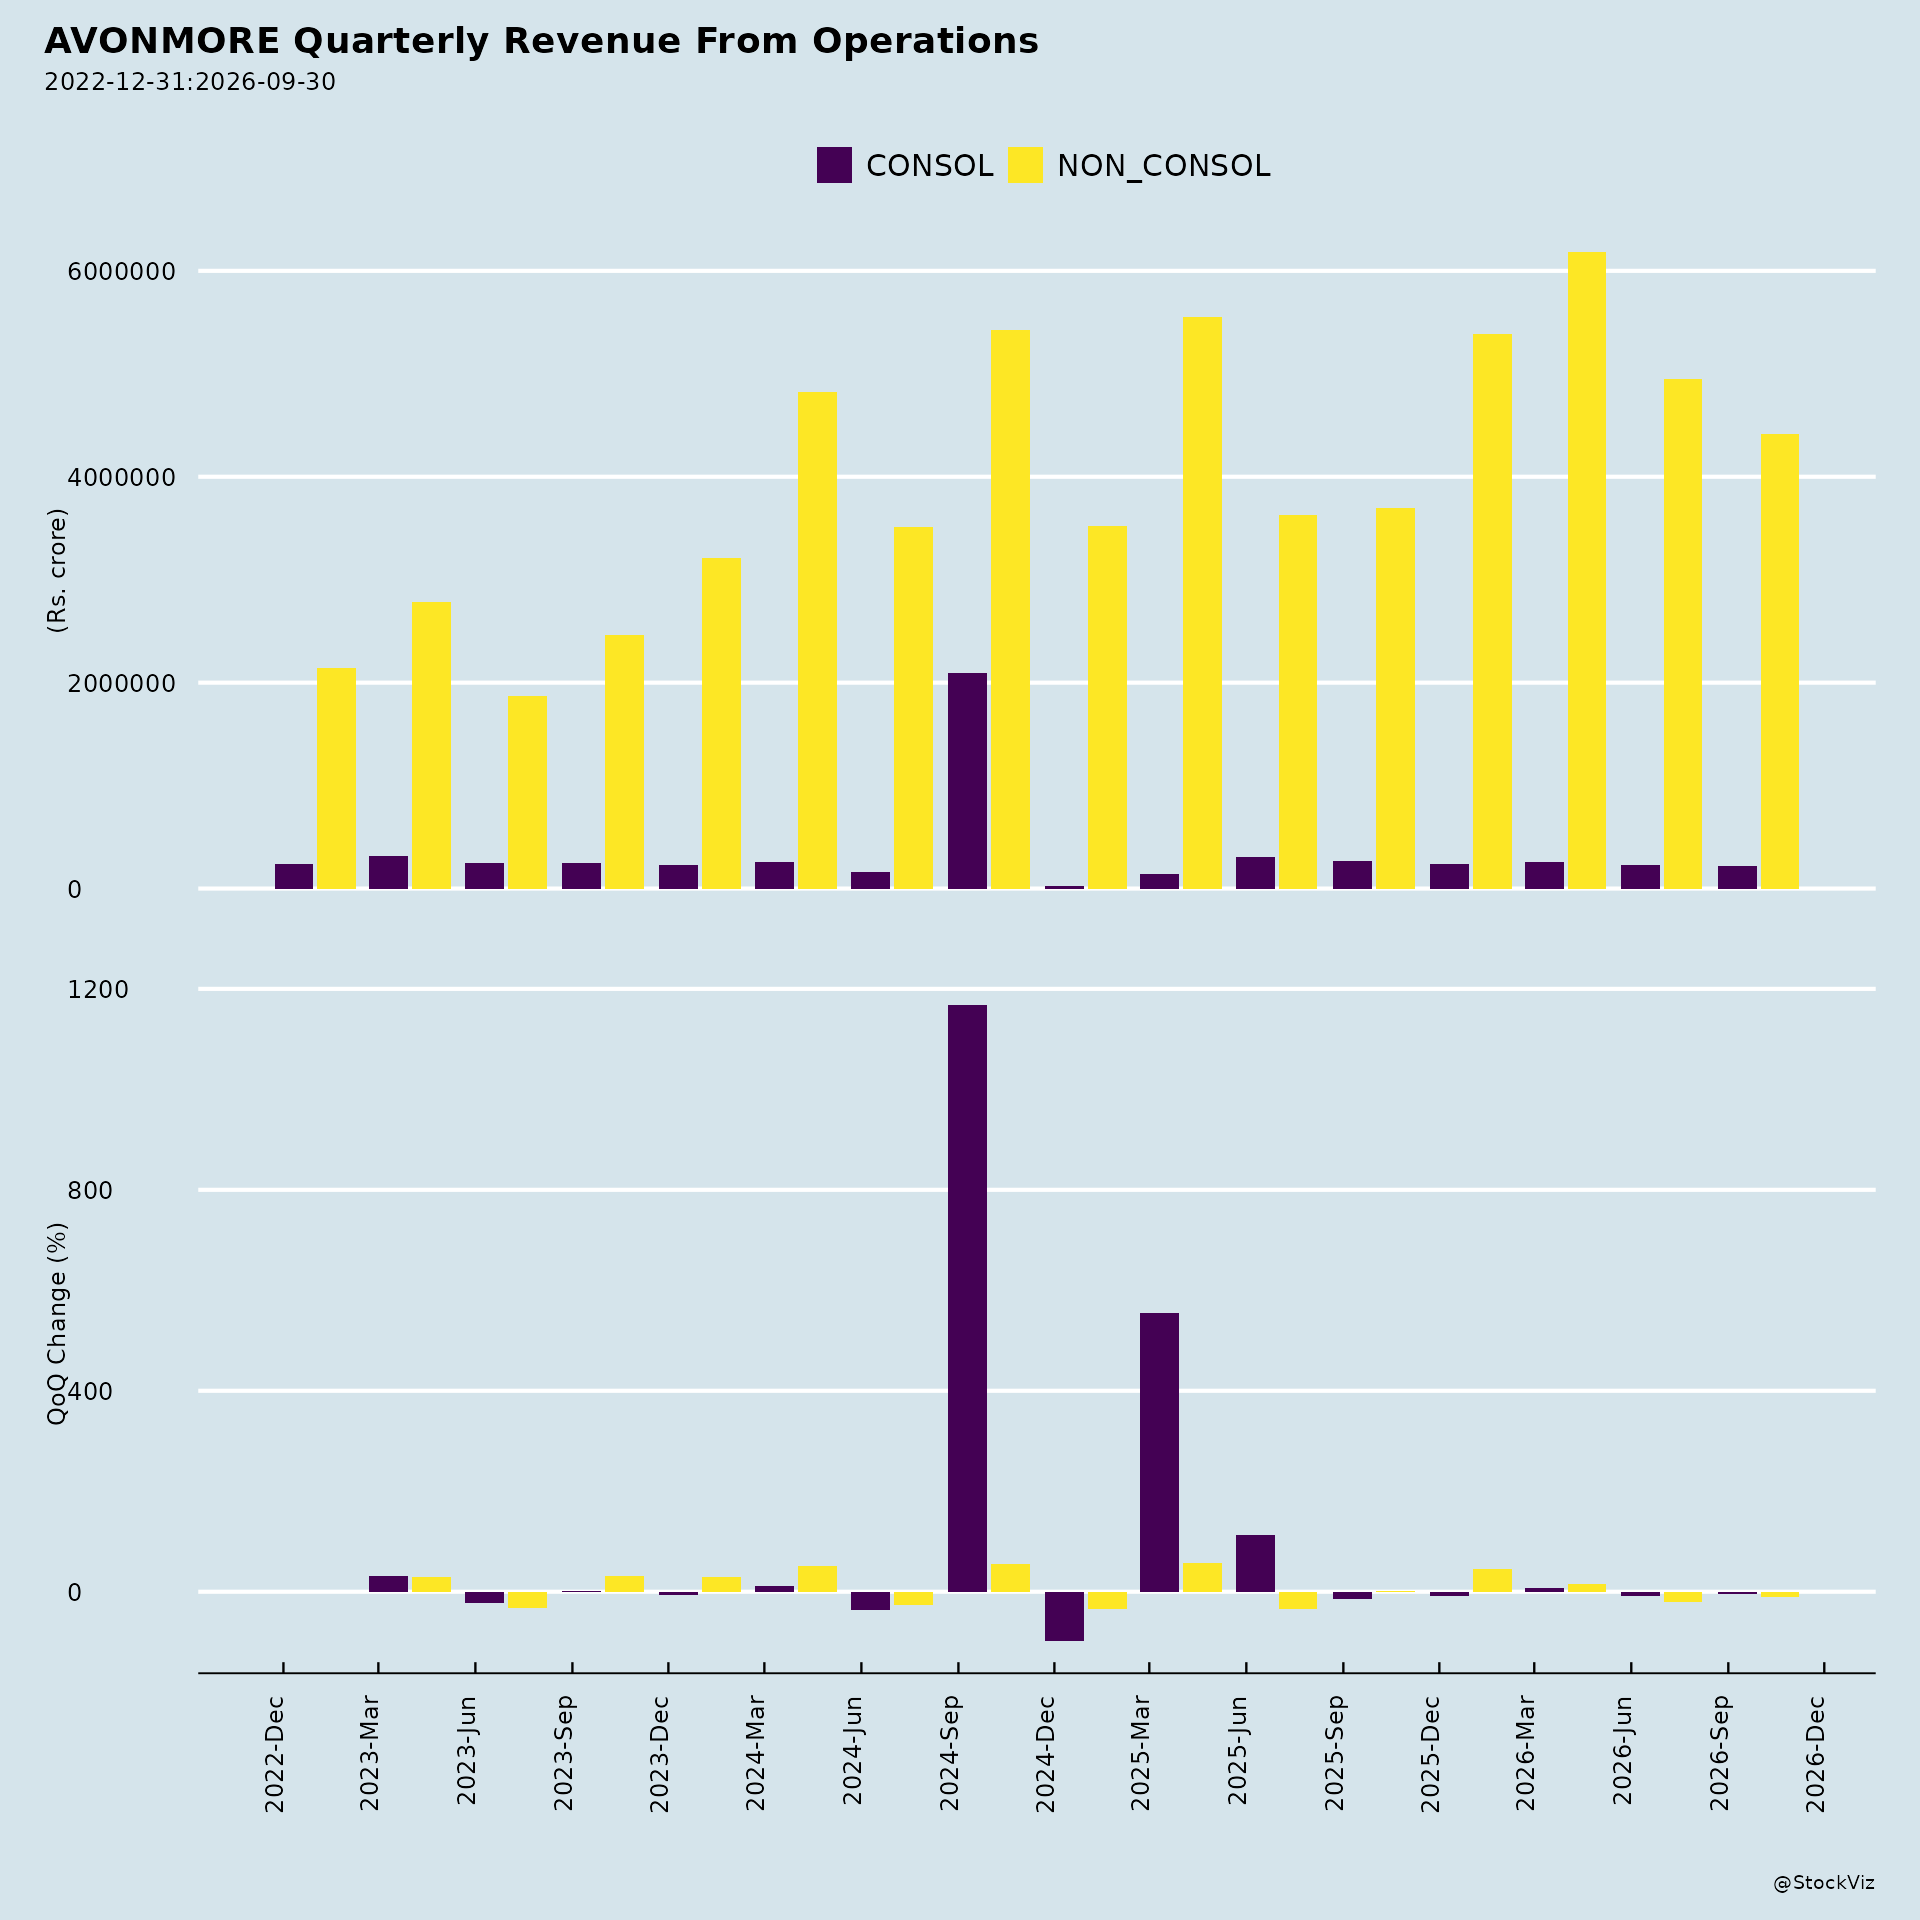
Infrastructure Advisory revenue decline: Revenue fell to Rs. 28.53 crore in 1Q FY 2026-27 from Rs. 51.39 crore in 4Q FY 2025-26. The company attributes this mainly to the year-end effect in March 2026, consistent with market practice in the infrastructure advisory industry.
Capital-market volatility: Mark-to-market losses on debt and equity operations are cited as a headwind, alongside delays in finalising OMC procurement tenders, execution and payment cycle risks in infrastructure advisory mandates, and geopolitical developments affecting energy prices and global growth.
Regulatory filing lapse: The NSE, by email dated June 18, 2026, flagged that the company had not submitted the declaration for unmodified opinion(s). The company stated the declaration in PDF format was inadvertently omitted (the Unmodified Opinion Report had already been submitted in XBRL format) and submitted a revised declaration on June 22, 2026.
2. Tailwinds and Growth Prospects
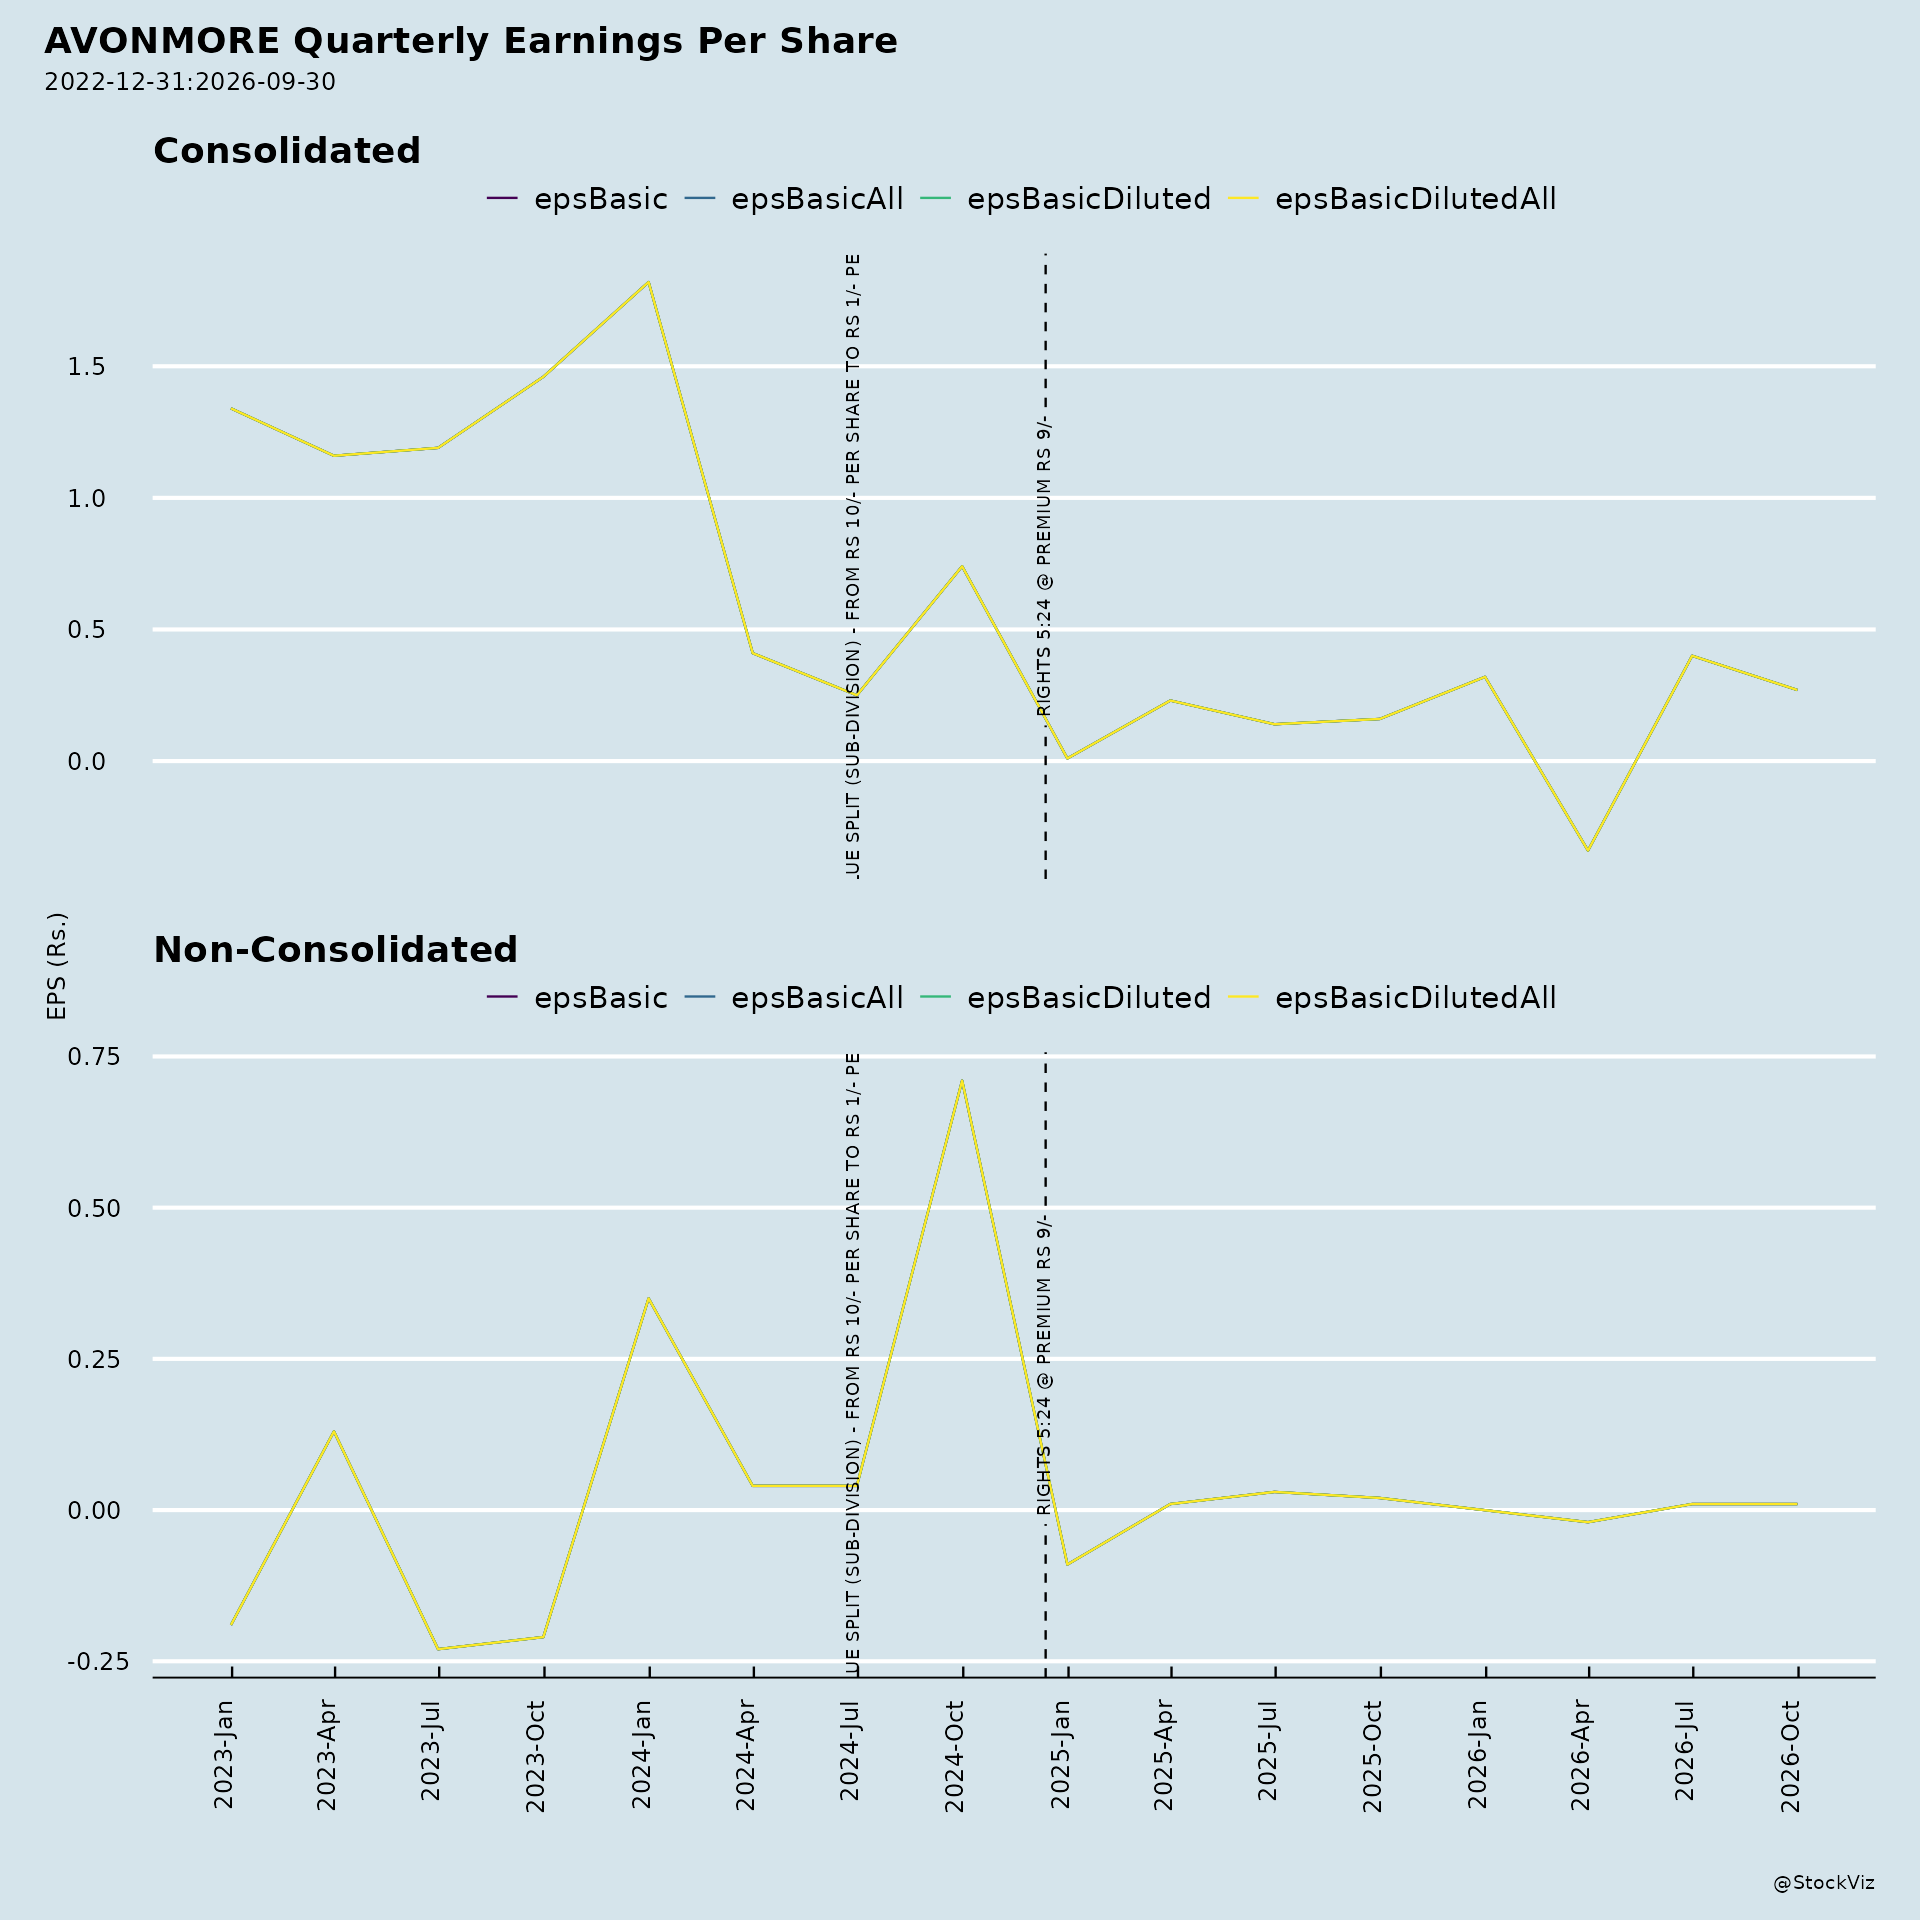
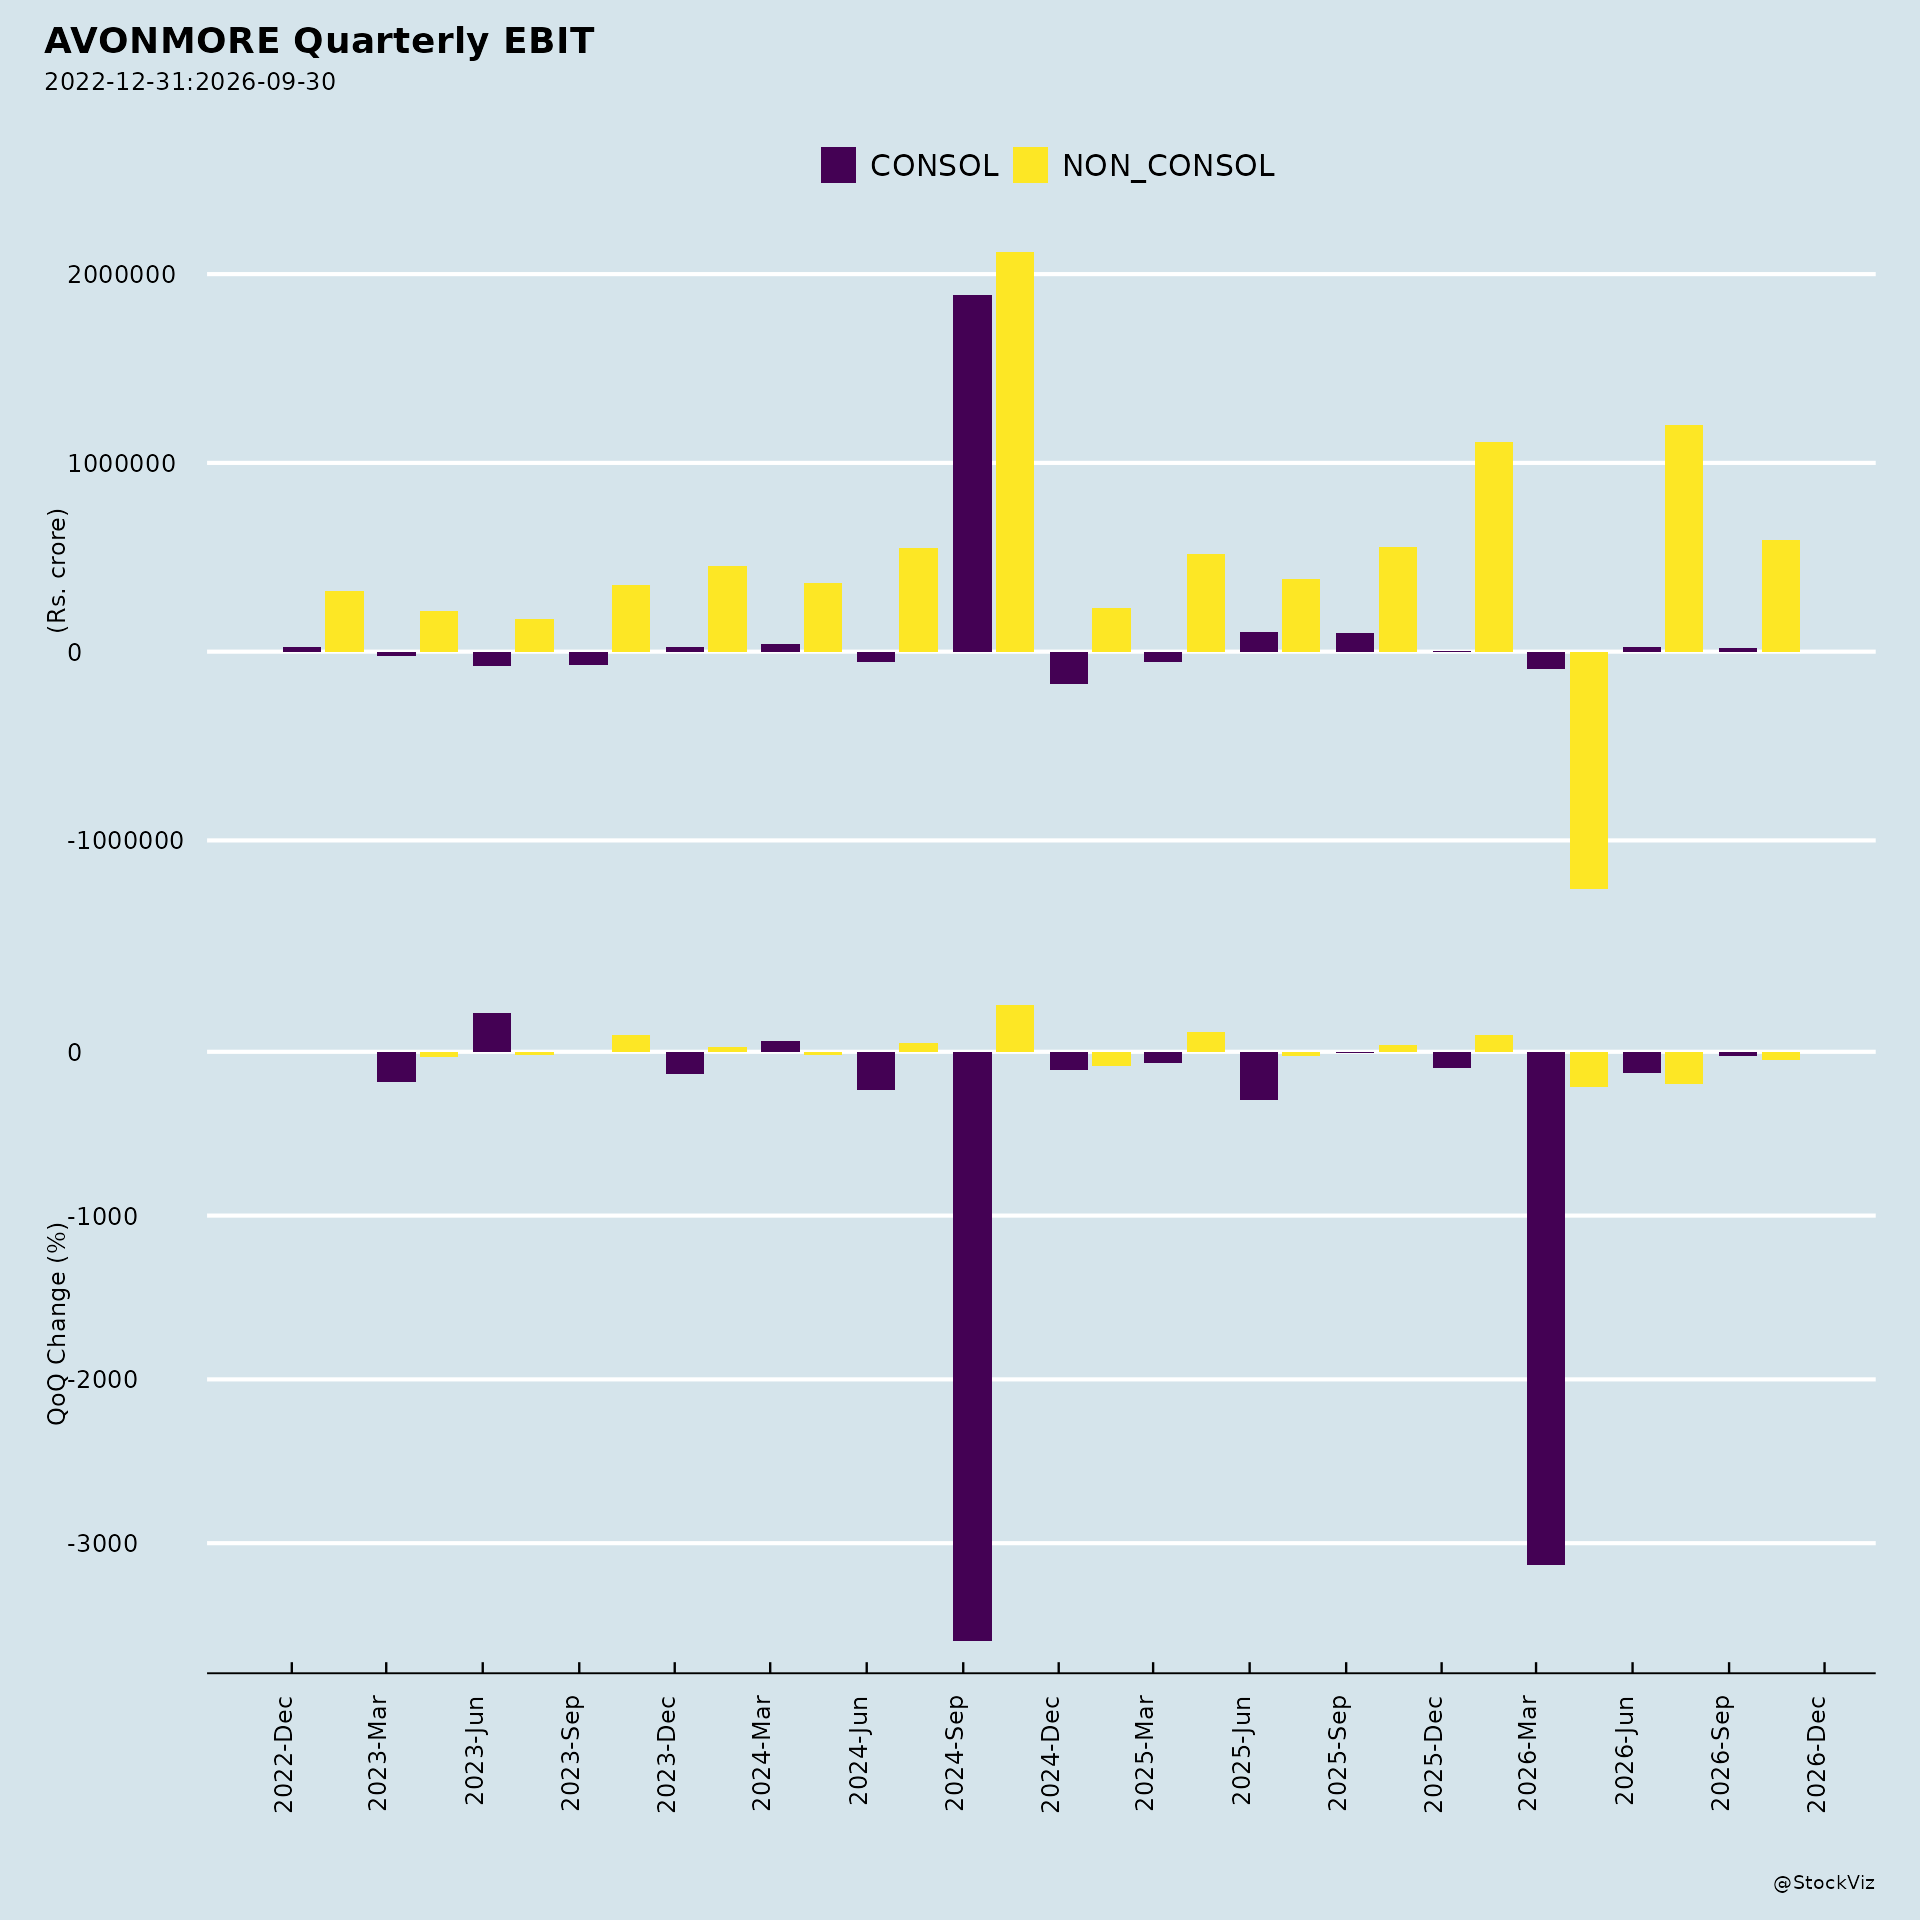
Financial Services recovery: The segment posted revenue of Rs. 17.57 crore with profit of Rs. 8.81 crore in 1Q FY 2026-27, against revenue of Rs. 8.55 crore with a loss of Rs. (13.81) crore in 4Q FY 2025-26. Year-on-year, revenue rose from Rs. 10.64 crore with profit of Rs. 0.48 crore in 1Q FY 2025-26.
Green Fuel capacity readiness: PGIPL’s Odisha plant is fully ready for commercial operations. Once the tender is floated and PGIPL successfully enters the procurement contract with the oil companies, commercial production will commence immediately. PGIPL recorded revenue of Rs. 179.33 crore and profit of Rs. 11.41 crore in 1Q FY 2026-27 (against Rs. 179.35 crore and Rs. 12.15 crore in 4Q FY 2025-26; and Rs. 192.25 crore and Rs. 10.55 crore in 1Q FY 2025-26). The company holds 40.99% of PGIPL’s total equity, while the holding company holds an 8.88% equity stake in PGIPL.
Infrastructure Advisory order book: The company won new business of Rs. 97.32 crore during the current financial year. Year-on-year, 1Q FY 2026-27 revenue of Rs. 28.53 crore with profit of Rs. 2.49 crore compares with Rs. 22.43 crore and Rs. 1.88 crore in 1Q FY 2025-26. The company is hopeful of maintaining a growth trend in revenue and profitability over the previous year.
NBFC improvement: Revenue of Rs. 3.42 crore with profit of Rs. 1.72 crore in 1Q FY 2026-27, versus Rs. 1.85 crore with a loss of Rs. (0.12) crore in 4Q FY 2025-26, and versus Rs. 3.25 crore with profit of Rs. 1.67 crore in 1Q FY 2025-26.
Broader sector tailwinds: Sustained government capital expenditure on national and border-road infrastructure, expansion of India’s ethanol-blending programme, continued formalisation of the economy, and deepening capital markets.
Fundraising: The Board approved raising up to ₹60 crore through unlisted, secured and redeemable Non-Convertible Debentures (NCDs) on a private placement basis.
3. Key Risks
- Capital-market volatility causing mark-to-market losses on debt and equity operations.
- Delays in finalising OMC procurement tenders affecting green-fuel commercialisation.
- Execution and payment cycle risks in infrastructure advisory mandates.
- Geopolitical developments affecting energy prices and global growth.
- Dependence on the OMC tender process for the Odisha plant to begin commercial production.
4. Management Guidance vs. Observed Performance
Infrastructure Advisory: Management guided to 20–22% growth in revenue and profitability for the current financial year compared to the previous financial year in the July 31, 2026 release. A separate communication guides towards approximately 18–20% growth in the Infrastructure Advisory Business, supported by its highest-ever order book and continuing government infrastructure spend. Observed performance: 1Q FY 2026-27 revenue of Rs. 28.53 crore and profit of Rs. 2.49 crore was higher year-on-year (Rs. 22.43 crore and Rs. 1.88 crore in 1Q FY 2025-26) but lower quarter-on-quarter versus 4Q FY 2025-26 (Rs. 51.39 crore and Rs. 2.31 crore), which the company attributes to the March year-end effect. New business won during the current financial year stands at Rs. 97.32 crore.
Green Fuel: Management stated commercial production will commence immediately once the tender is floated and PGIPL enters the procurement contract. Observed performance: the plant is fully ready, but the OMC tender has not yet been floated, so full-scale commercial production has not commenced.
Financial Services: No explicit forward guidance was provided. Observed performance shows a swing from a 4Q FY 2025-26 loss of Rs. (13.81) crore to a 1Q FY 2026-27 profit of Rs. 8.81 crore, and year-on-year improvement from Rs. 0.48 crore profit.
NBFC: No explicit forward guidance was provided. Observed performance shows a swing from a 4Q FY 2025-26 loss of Rs. (0.12) crore to a 1Q FY 2026-27 profit of Rs. 1.72 crore, and a modest year-on-year improvement from Rs. 1.67 crore profit.
Consolidated: 1Q FY 2026-27 consolidated total revenue of Rs. 49.70 crore with profit of Rs. 17.39 crore, compared with 4Q FY 2025-26 total revenue of Rs. 61.81 crore with a loss of Rs. (6.88) crore.
Key Investor Facts
- The 34th Annual General Meeting is scheduled for Wednesday, September 30, 2026 at 1:30 p.m. (IST) through Video Conference (VC) or Other Audio-Visual Means (OAVM).
- The Board met on Tuesday, September 01, 2026, approved the Notice of the AGM and Directors’ Report for the financial year ended March 31, 2026, and approved raising up to ₹60 crore via unlisted, secured, redeemable NCDs on a private placement basis.
- The company operates across four principal business verticals: Financial Services (Wealth advisory / Broking / Corporate Advisory / Merchant Banking with debt and equity operations), Green Fuel Business, Infrastructure Advisory Business, and NBFC Activities.
- For FY 2025-26, standalone total income was Rs. 1,079.82 lakhs with profit after tax of Rs. 84.72 lakhs; consolidated total income was Rs. 19,119.93 lakhs with consolidated profit after tax of Rs. 2,166.03 lakhs. No dividend has been recommended for the financial year.
- The statutory auditors, M/s Mohan Gupta & Company, Chartered Accountants (Firm Registration No: 006519N), expressed no modified opinion in their Audit Report on the Audited Financial Results (Standalone and Consolidated) for the quarter and financial year ended March 31, 2026, as approved by the Board at its meeting held on May 26, 2026.
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.