ATULAUTO
Equity Metrics
September 24, 2026
Atul Auto Limited
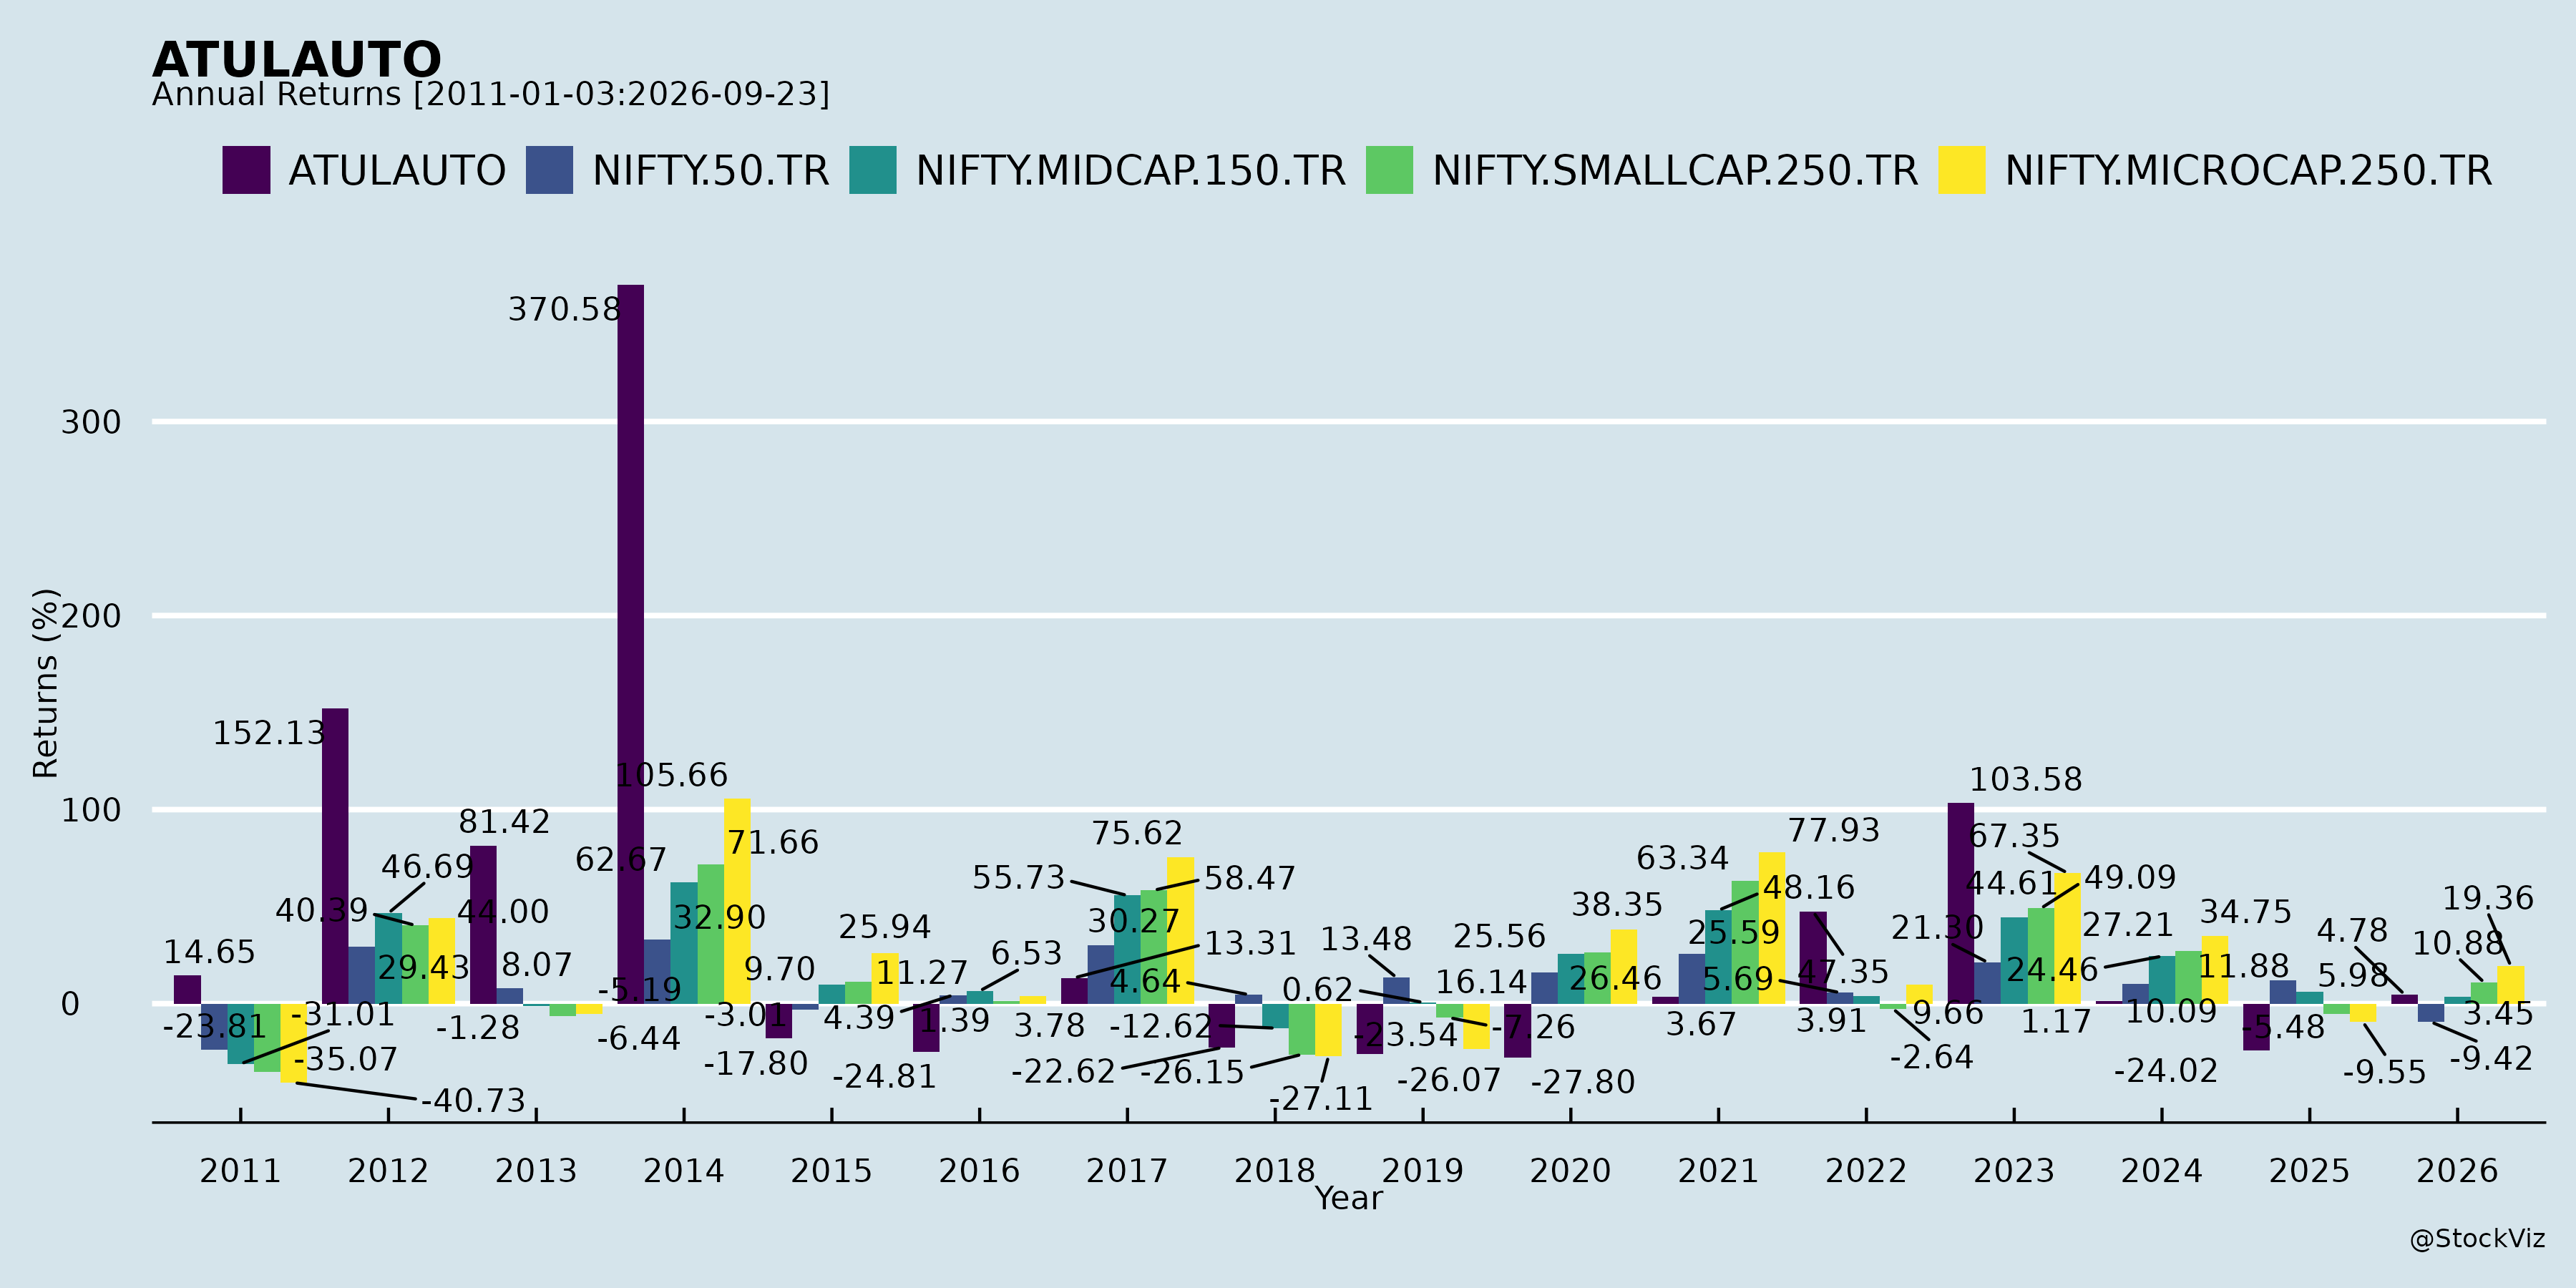
Annual Returns
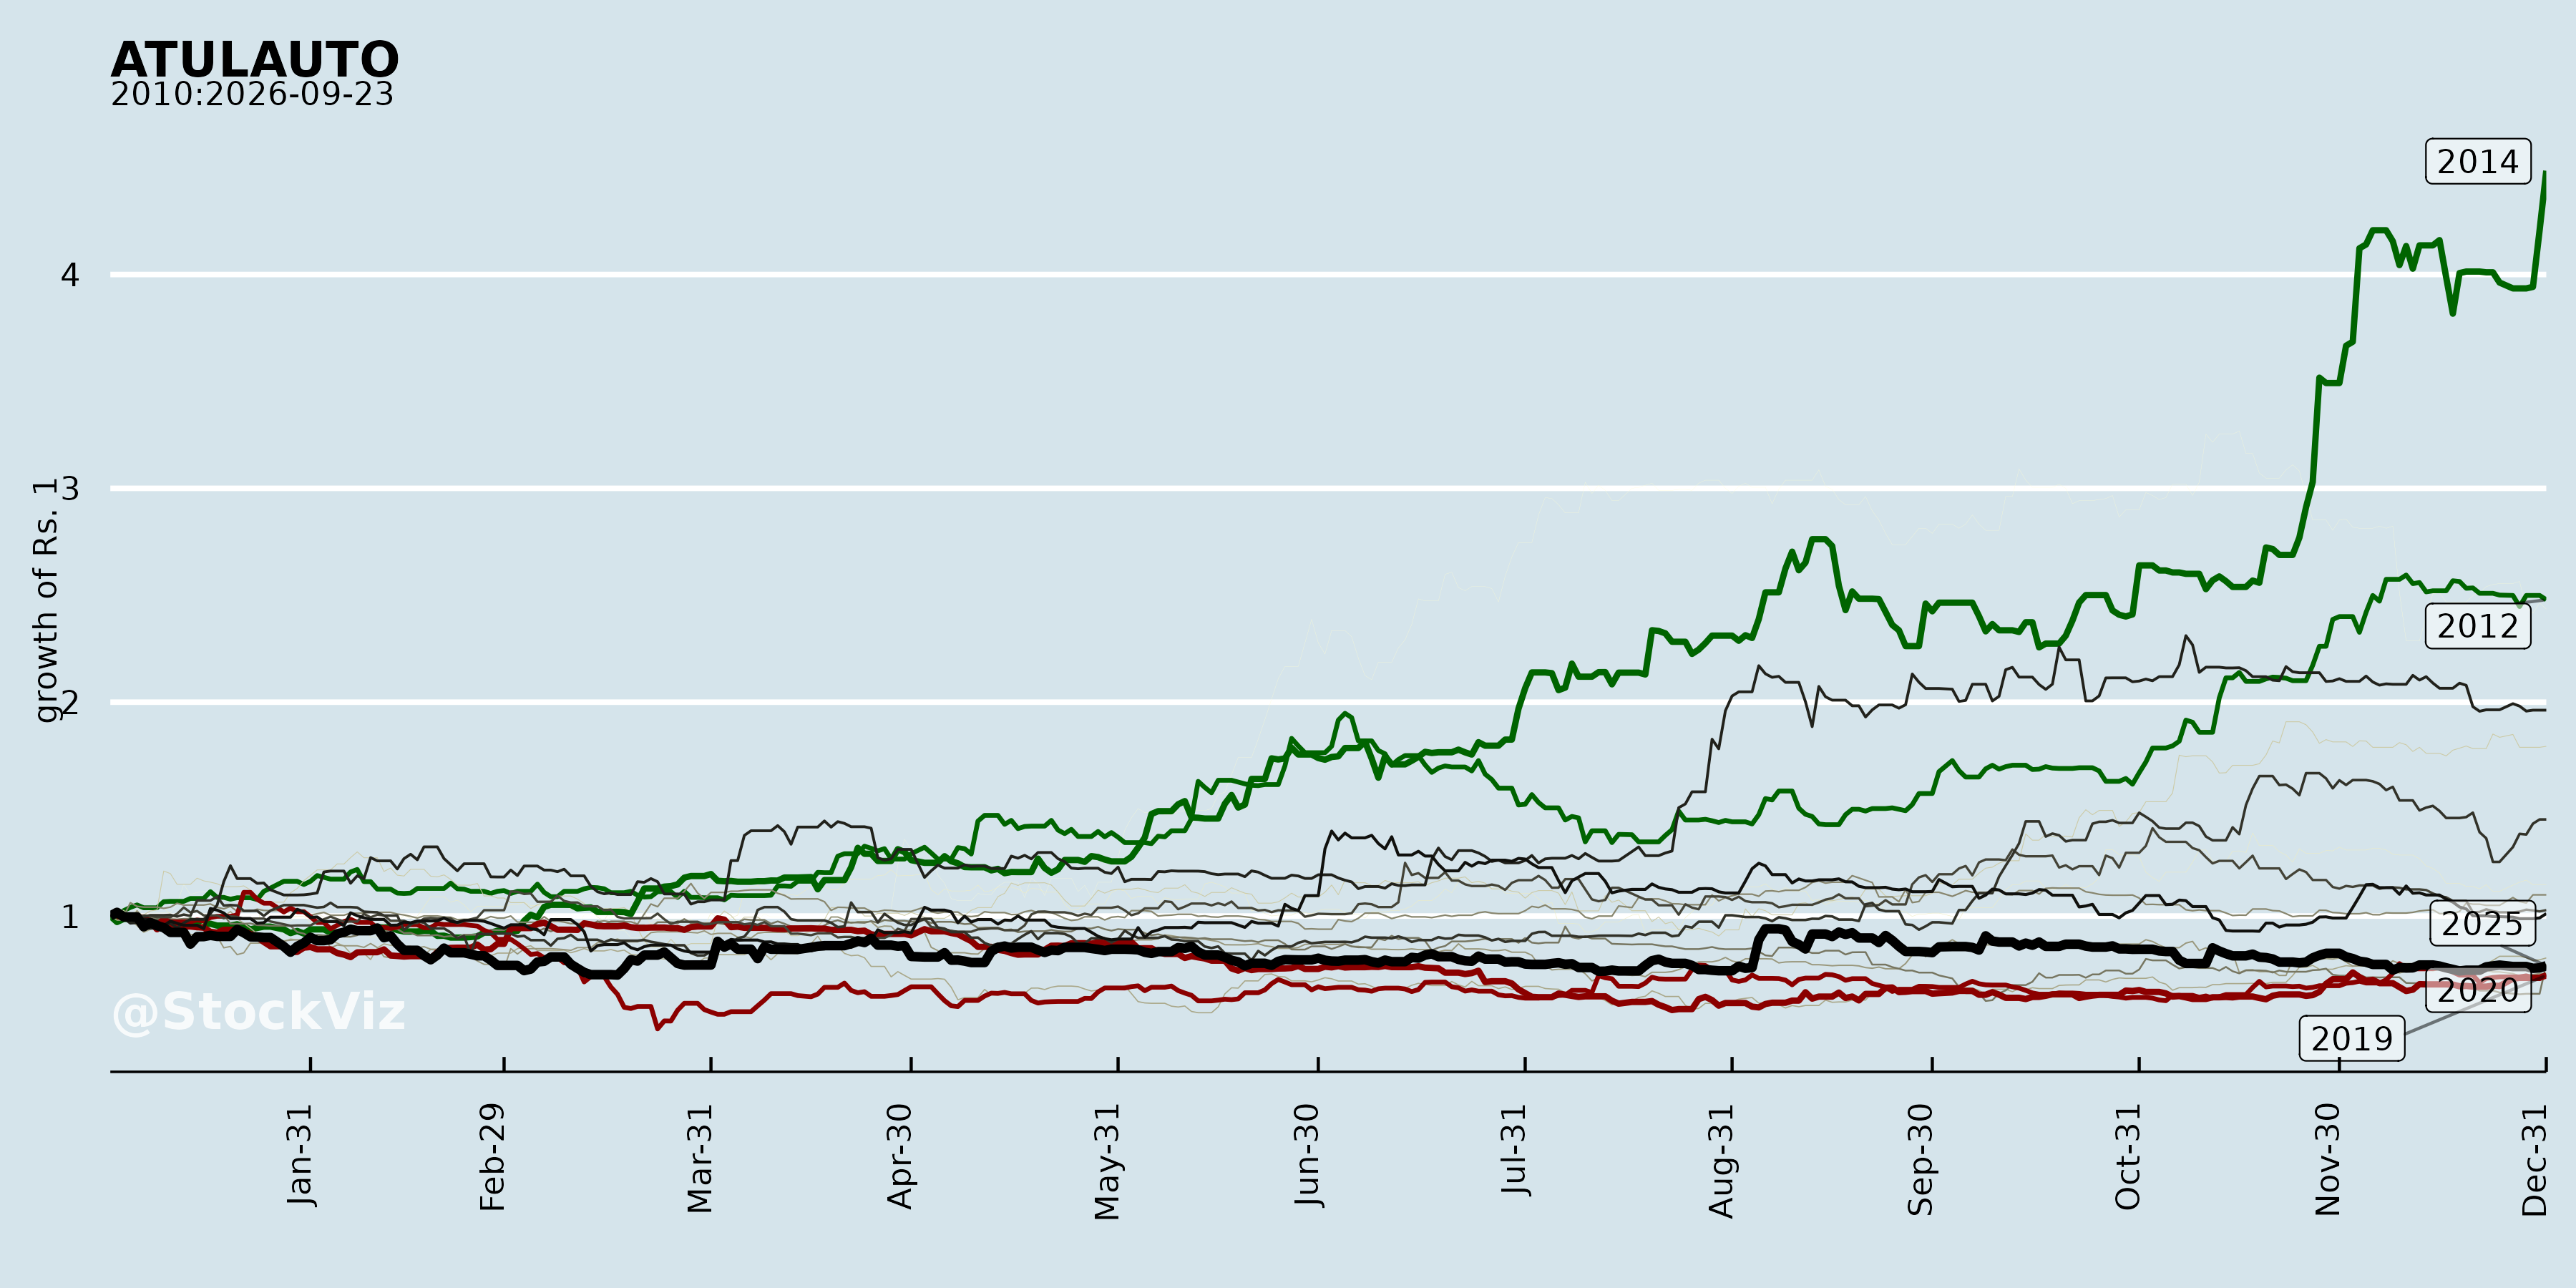
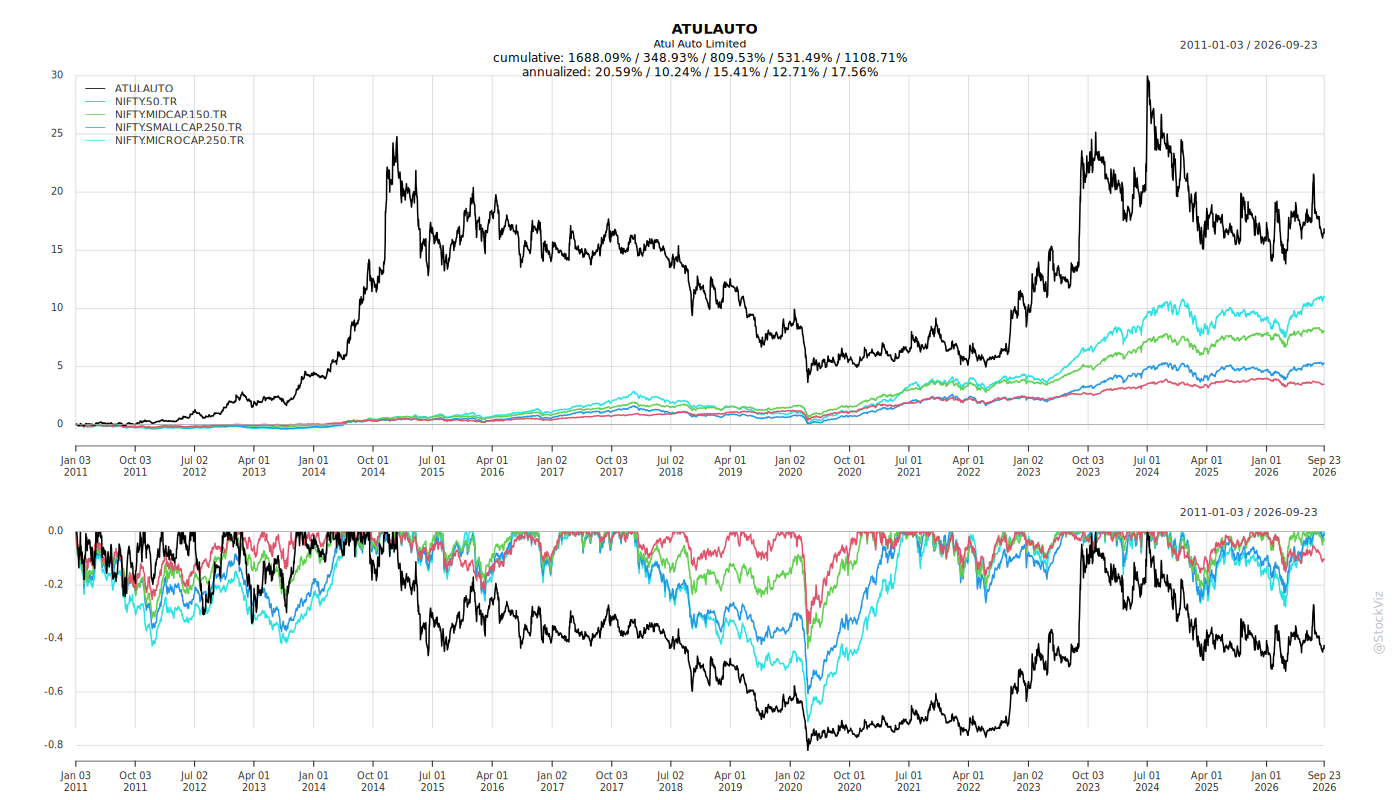
Cumulative Returns and Drawdowns
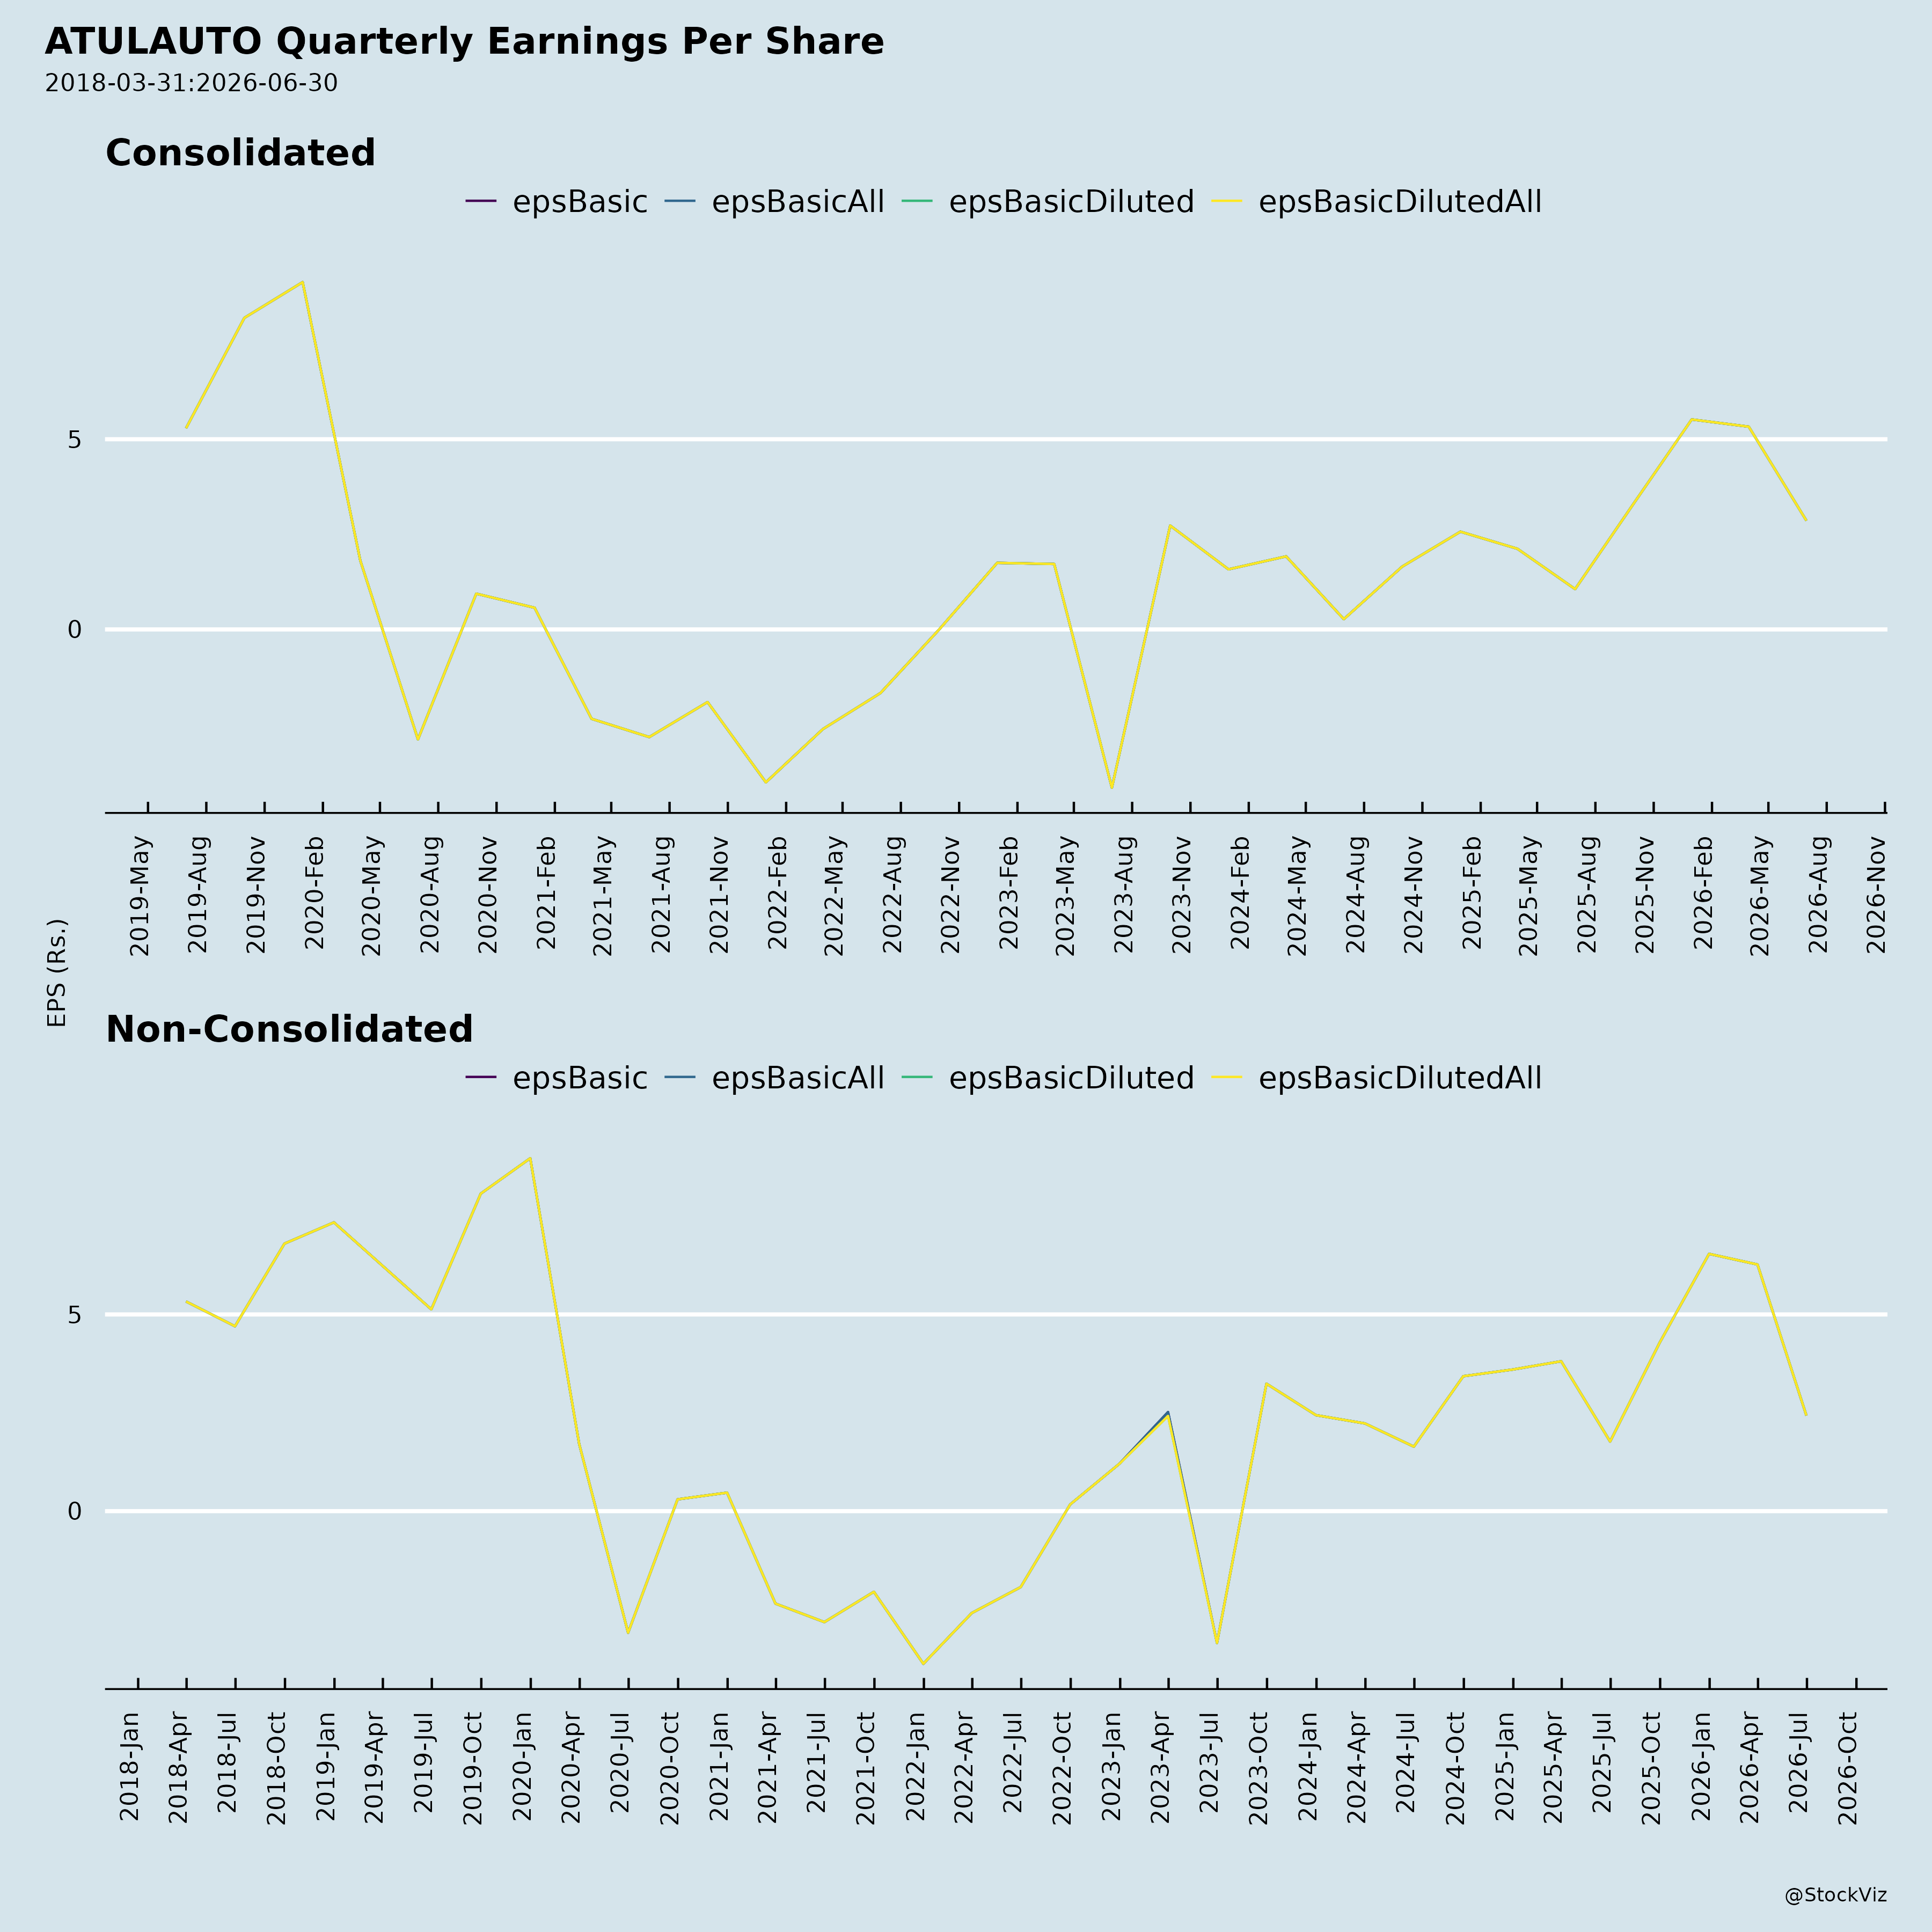
Fundamentals
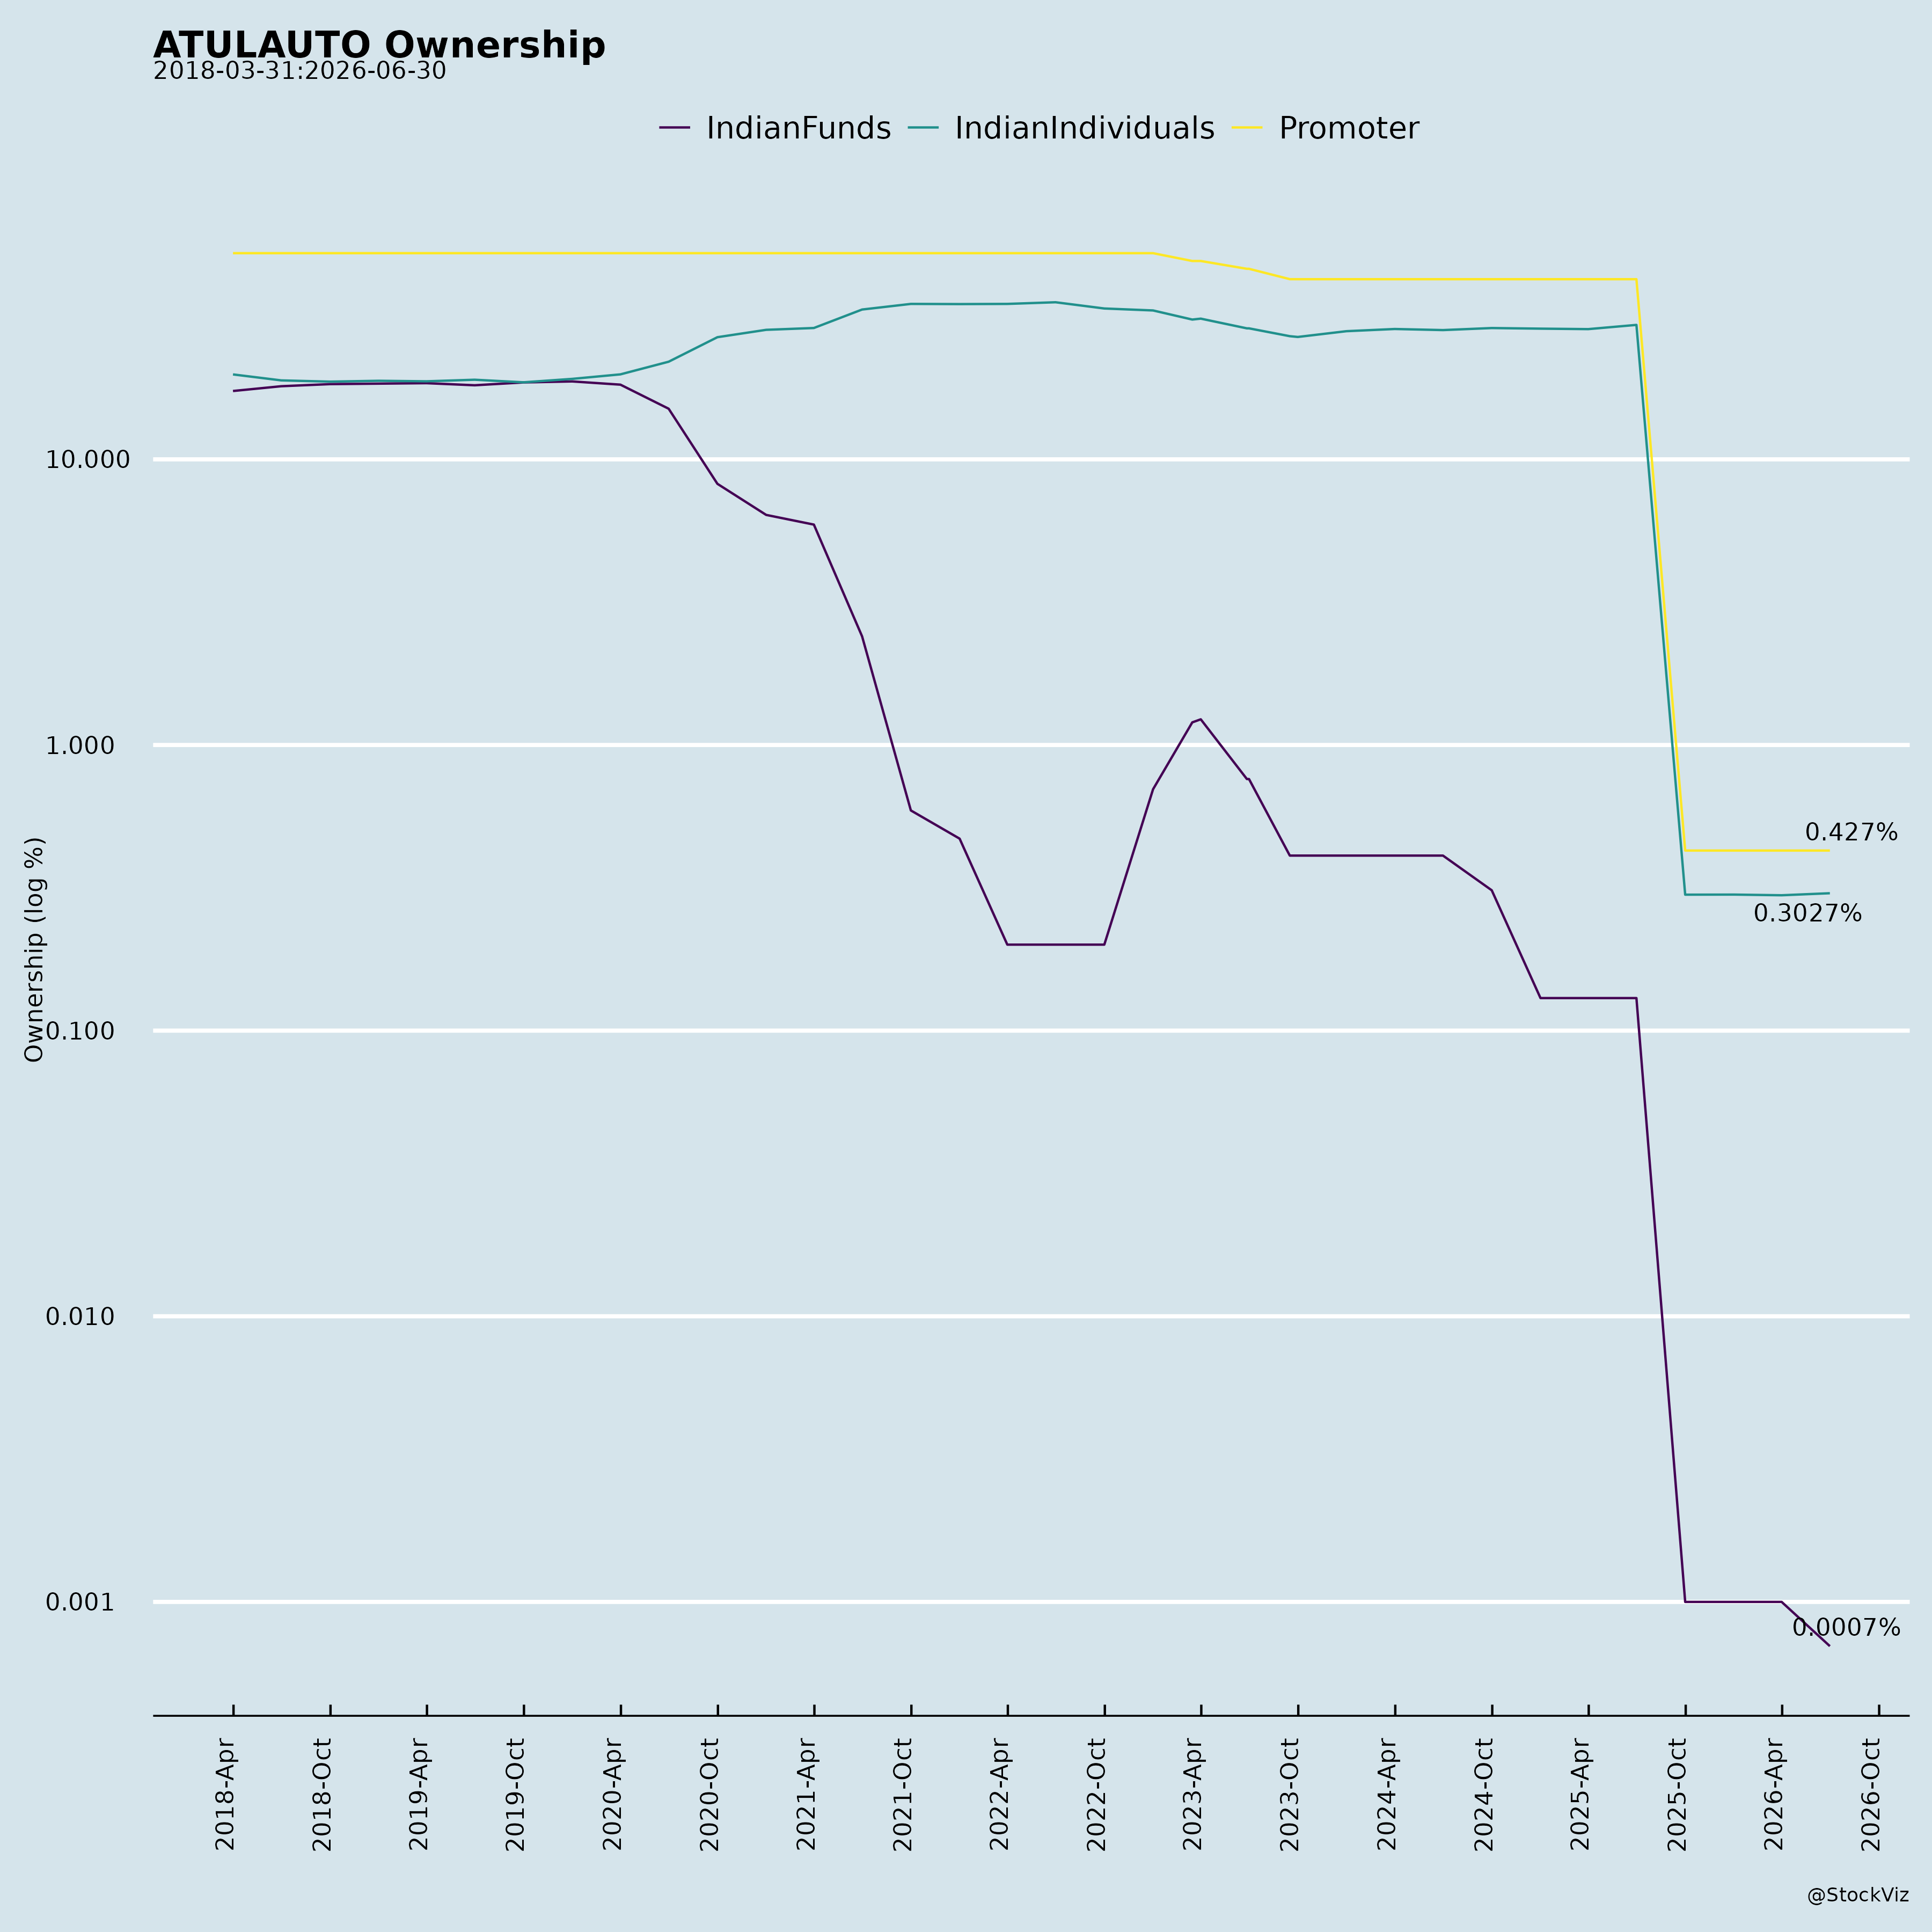
Ownership
Margined
AI Summary
asof: 2026-09-18
Atul Auto Limited — Recent Corporate Developments
1. Headwinds and Challenges
- EV segment weakness: EV sales for August 2026 declined by 11.46% compared to August 2025. Year-to-date FY 2026-27 EV sales fell 2.65% (domestic) and 3.03% (domestic plus export) compared to FY 2025-26. This contrasts with strong growth in the IC engine segment.
- Transition and consolidation costs: The company is closing its existing three-wheeler vehicle and spares manufacturing operations at Shapar (Veraval), Rajkot, with closure targeted on or before December 01, 2026. The Rajkot facility manufactured parts aggregating to ₹4,834 lakhs in FY 2025-26, entirely captively consumed or sold as spare parts, and did not generate independent turnover. The written-down value of the Rajkot land and building was approximately ₹601 lakh as of March 31, 2026 (about 1.28% of net worth).
- Post-COVID operational rationalisation: Management noted that, with a view to economise operations post-COVID, vehicle assembly was shifted to the Ahmedabad facility, and the decision has turned positive in terms of financial benefit. The Rajkot closure is part of this consolidation.
- Lease execution uncertainty: The Rajkot facility lease is subject to shareholder approval at the ensuing Annual General Meeting. The company has received inquiries, but the lease agreement will be executed only after approval, and consideration will be finalised after identification of a suitable lessee.
2. Tailwinds and Growth Prospects
- Strong volume growth: Q1 FY 2026-27 three-wheeler sales rose to 9,878 units from 6,932 units in Q1 FY 2025-26, a growth of approximately 42.5% (standalone). Consolidated sales were 9,878 units versus 6,929 units, up 42.56%.
- Robust financial performance (YoY):
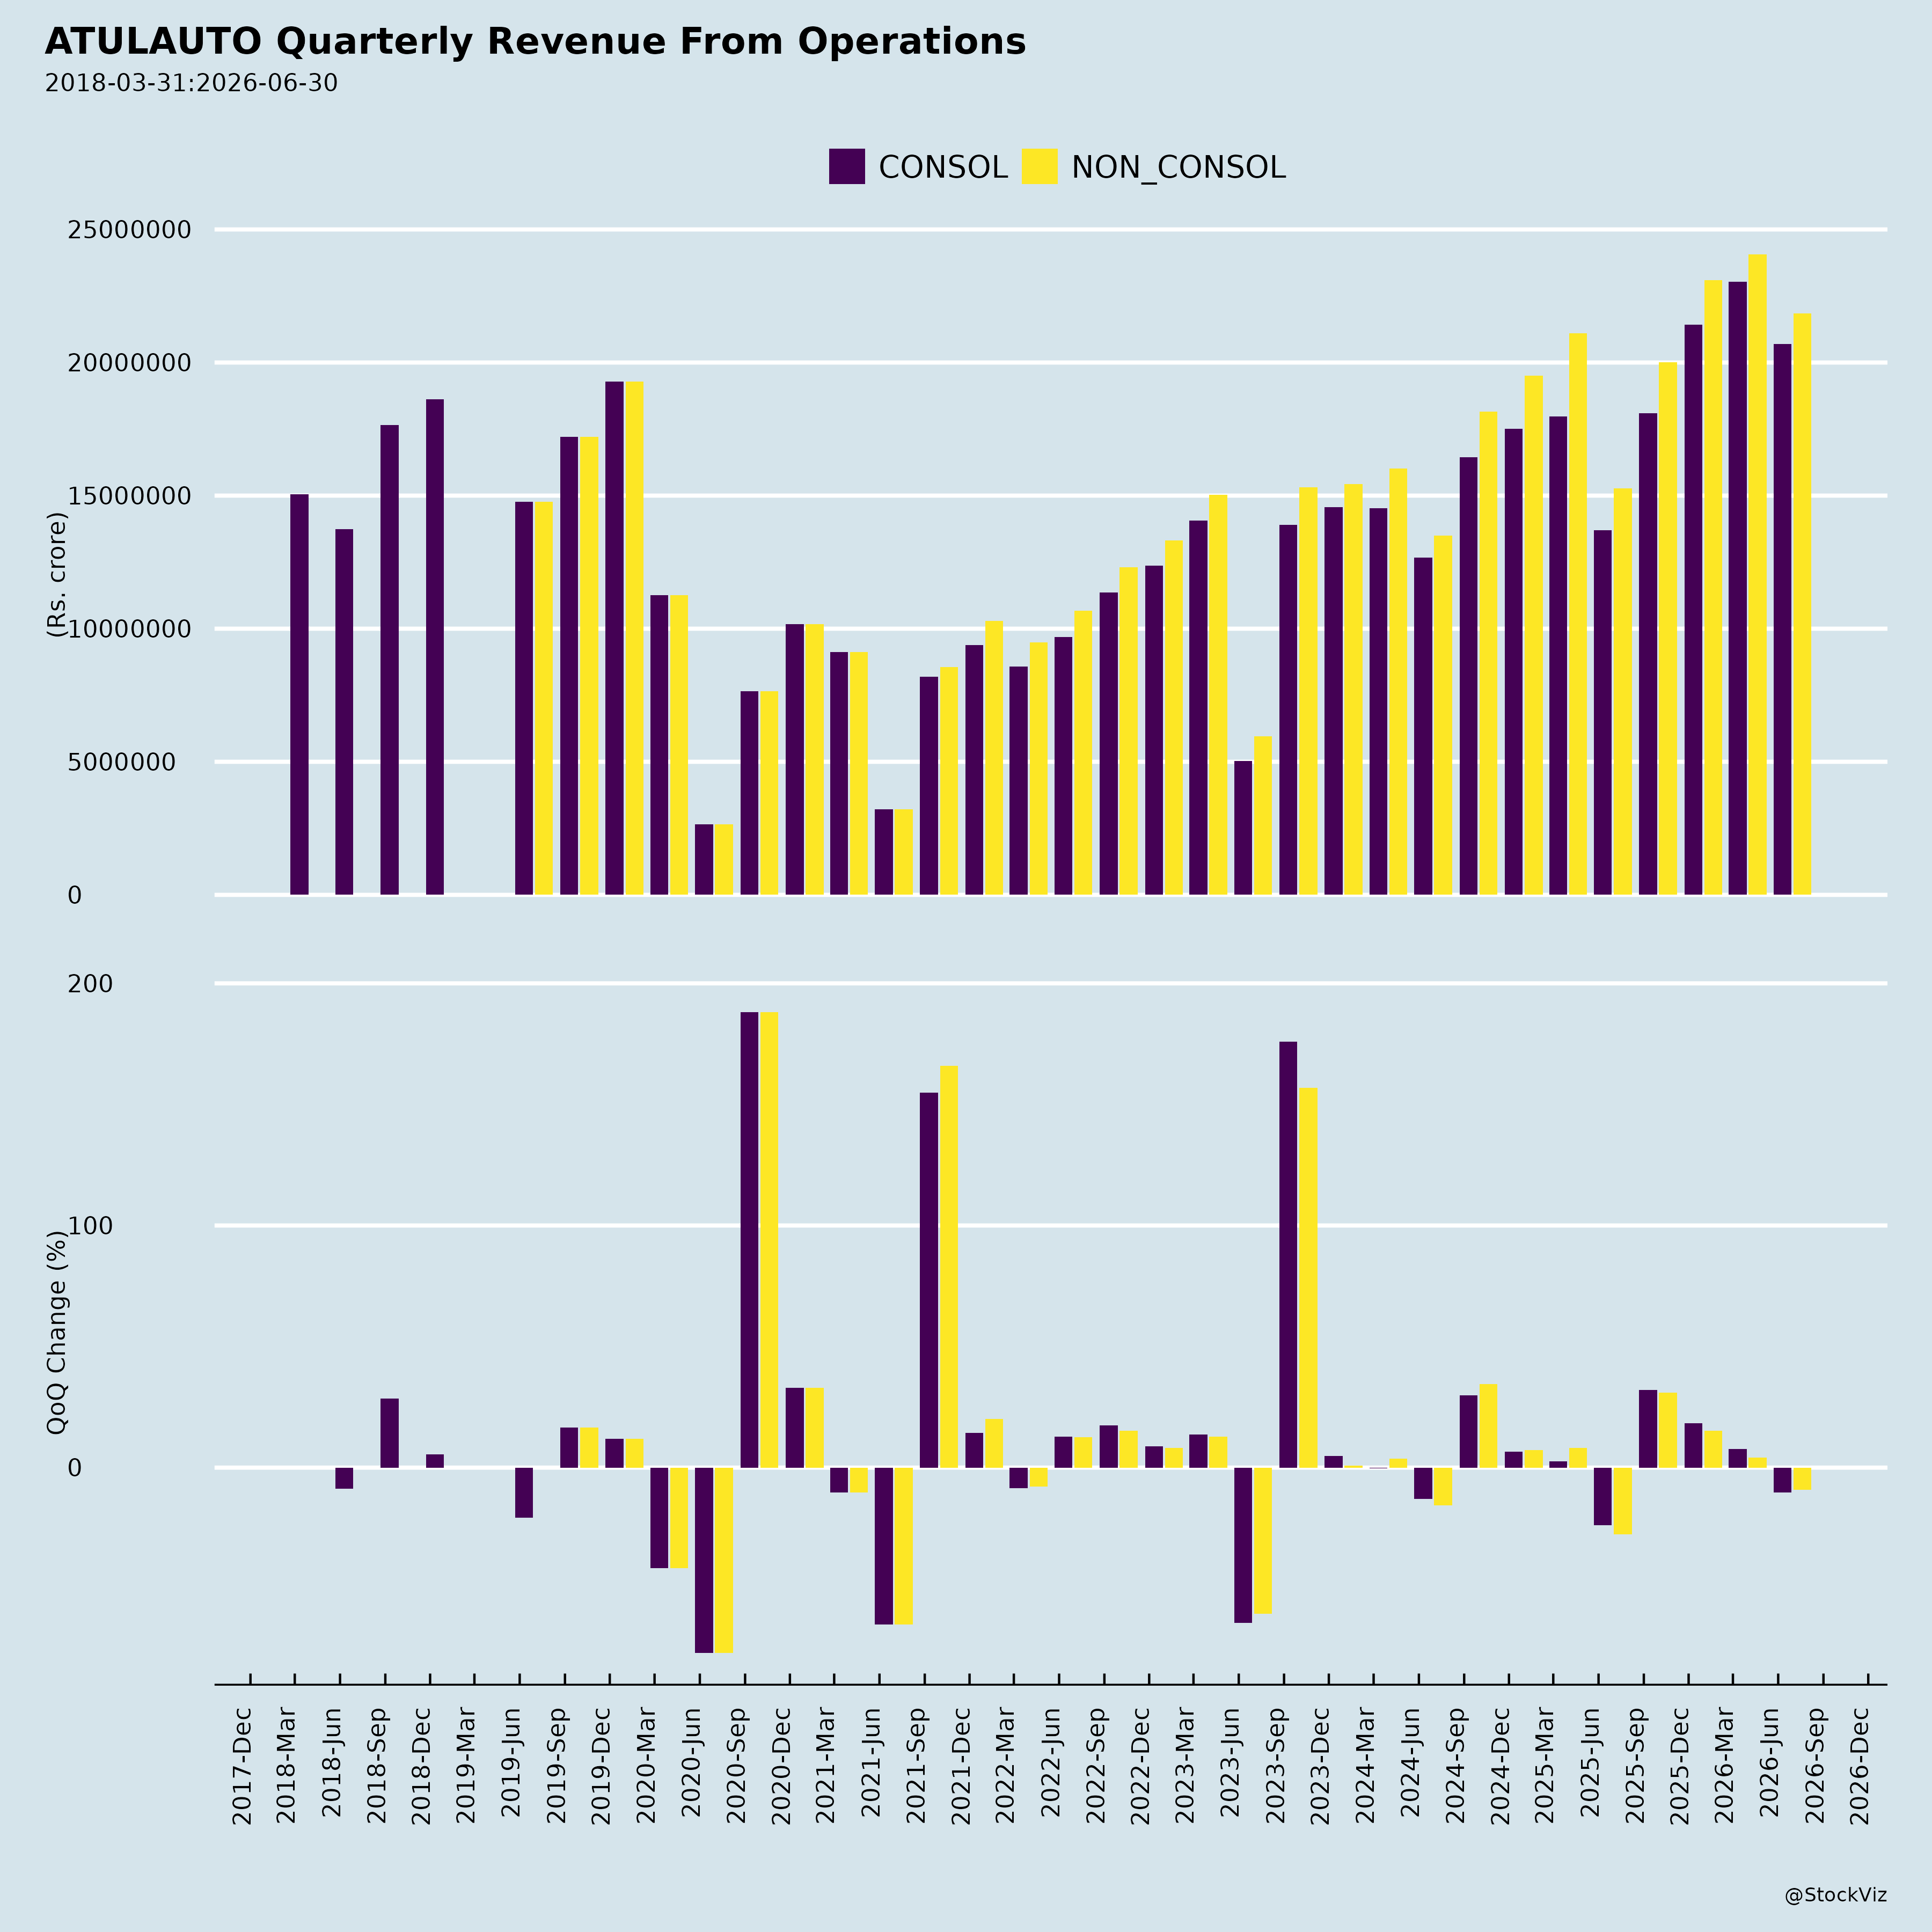
- Standalone revenue from operations increased to ₹20,693 lakh (₹206.93 crore) from ₹14,303 lakh (₹143.03 crore), up 44.67%.
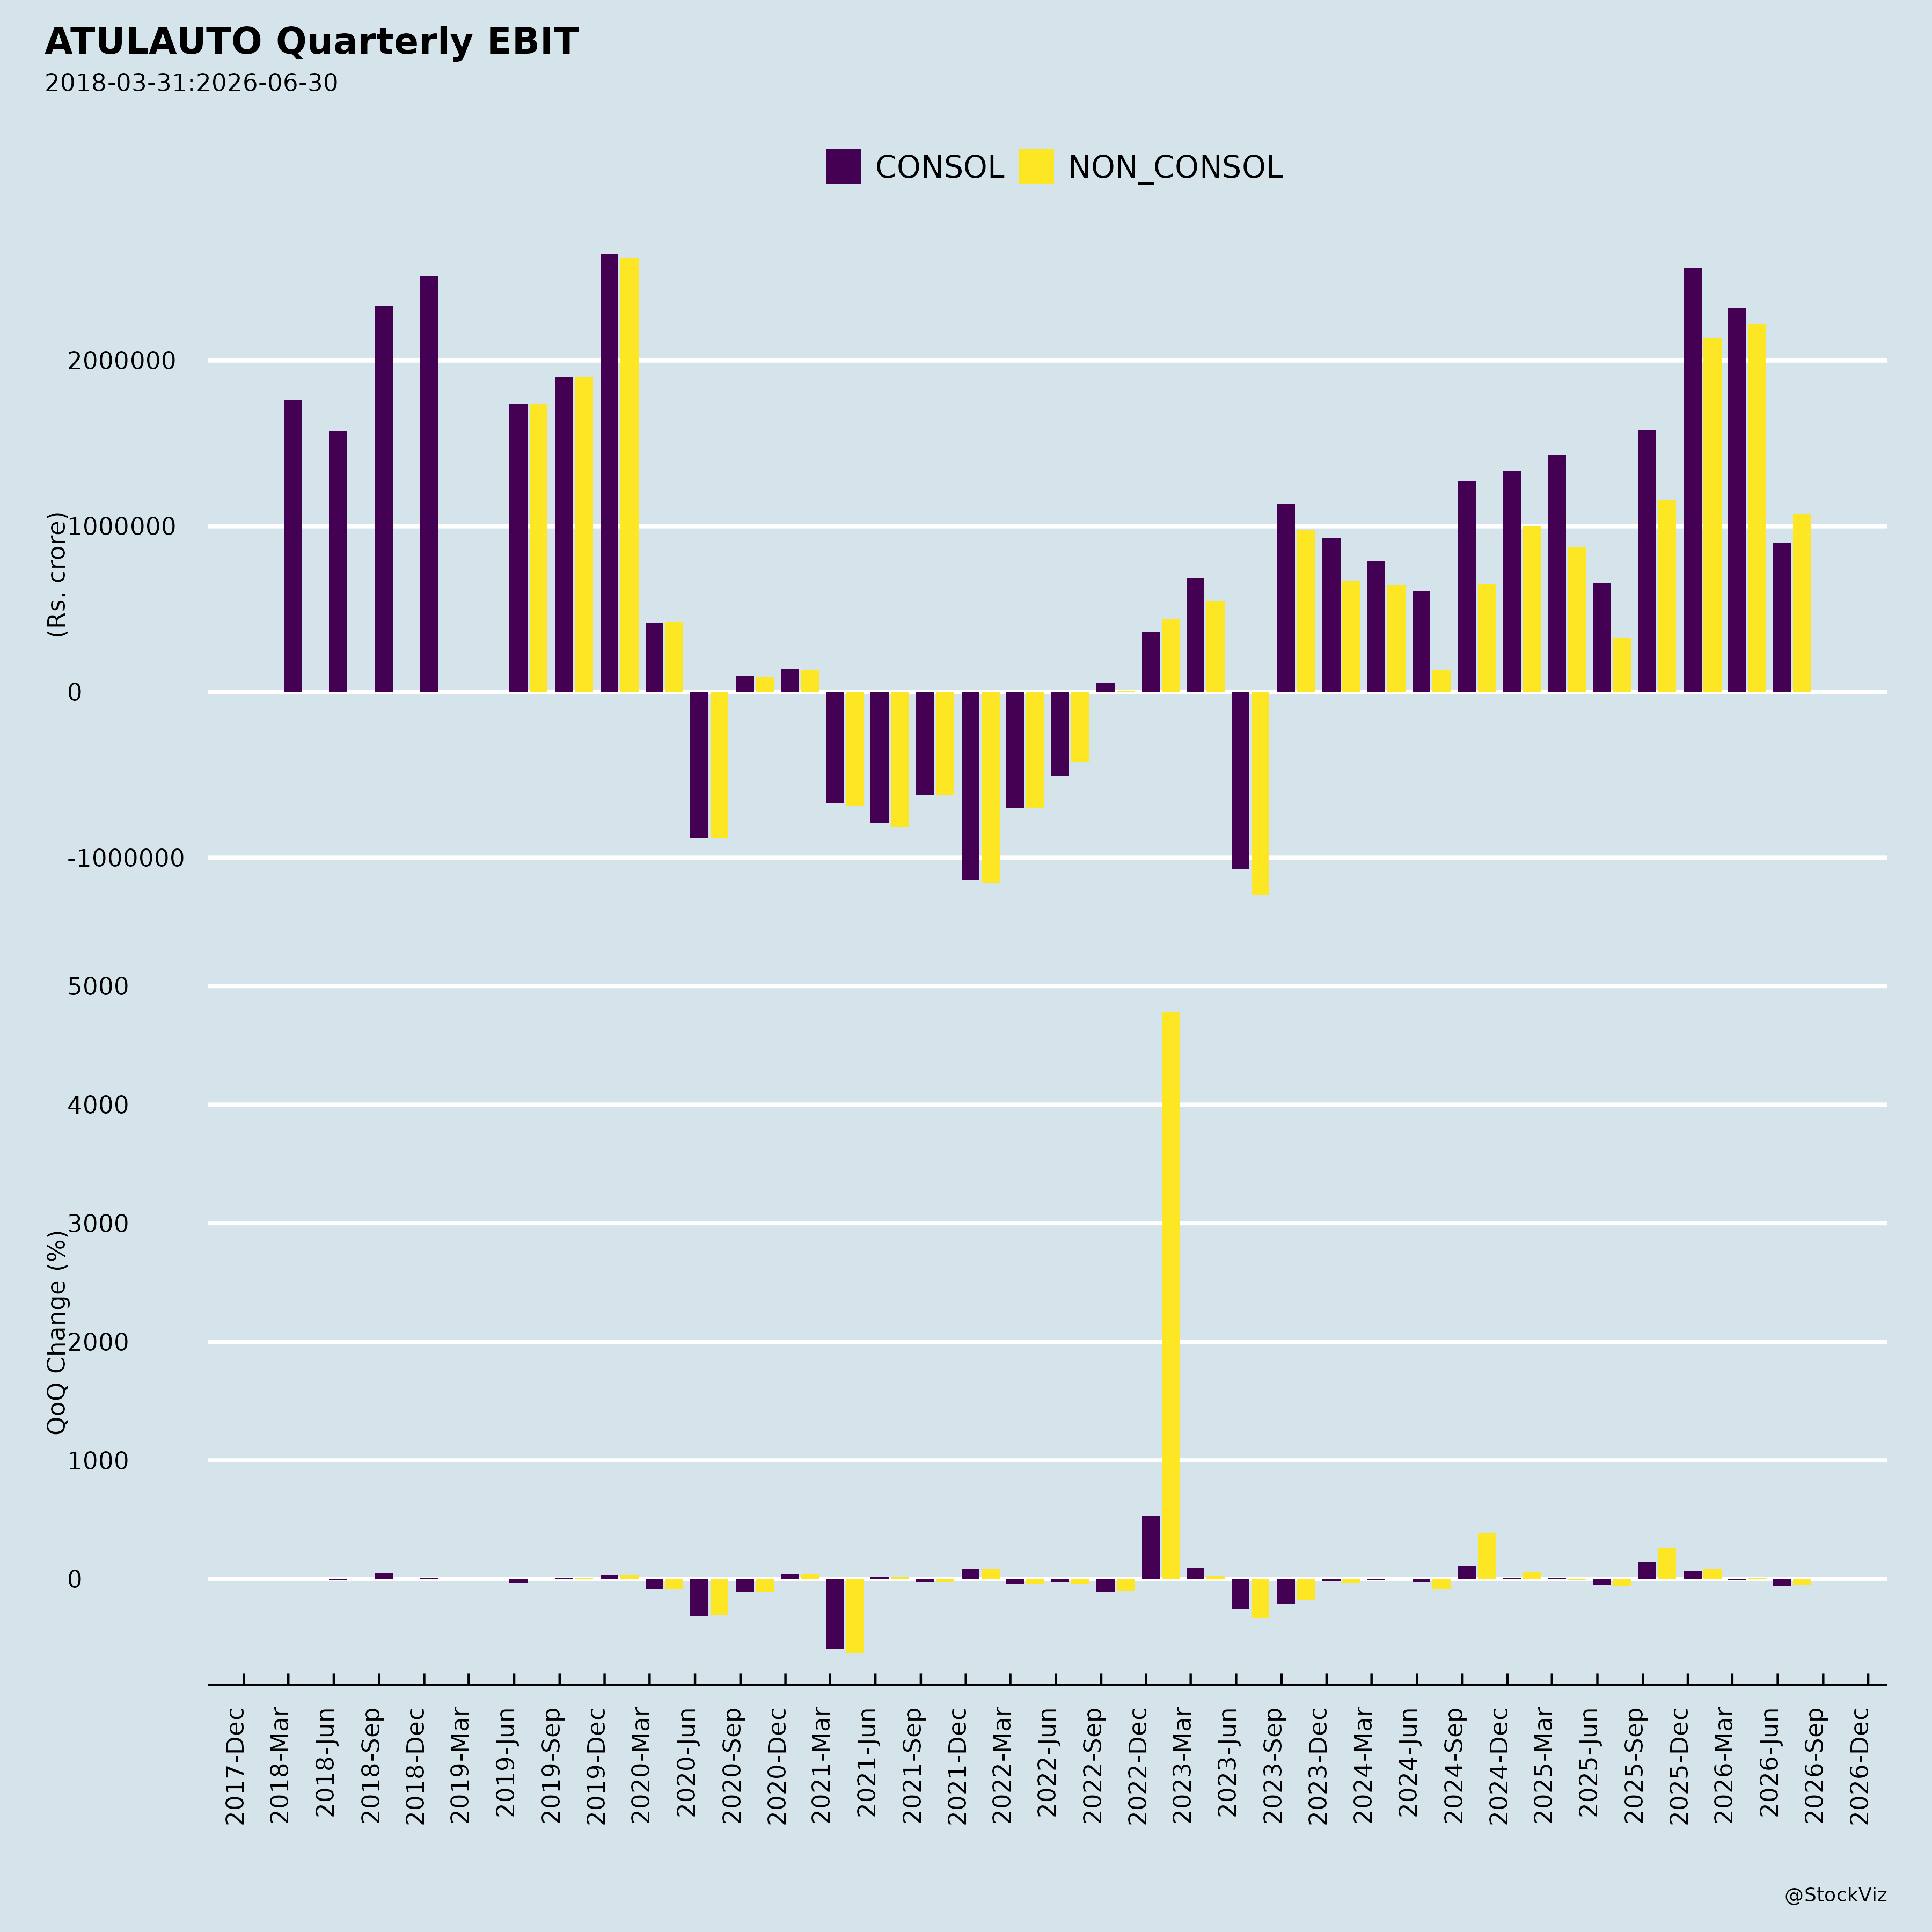
- Standalone profit before tax rose to ₹902 lakh from ₹672 lakh (up 34.23%); profit after tax rose to ₹674 lakh from ₹504 lakh (up 33.74%).
- Consolidated revenue from operations stood at ₹21,843 lakh (₹218.43 crore) versus ₹15,278 lakh (₹152.78 crore), up 42.97%.
- Consolidated profit before tax increased to ₹1,077 lakh from ₹325 lakh (up 231.38%); profit after tax increased to ₹804 lakh from ₹206 lakh (up 290.29%).
- August 2026 sales momentum: Total domestic sales grew 31.14% YoY to 3,411 units, with 3W IC engine domestic sales up 47.04%. Total domestic plus export sales reached 4,012 units, up 32.58% YoY. YTD total domestic plus export sales increased 39.57%.
- Manufacturing consolidation benefits: Consolidating operations at the Ahmedabad facility is expected to improve operational efficiency, optimise manpower and resource utilisation, reduce fixed overheads, and lower operating and administrative costs. The Ahmedabad facility has an installed capacity of approximately 60,000 vehicles per annum, with space to enhance capacity with minimal capex to meet anticipated demand for the next several years. It also offers logistical advantages, superior road connectivity, and proximity to marketing and business functions in Ahmedabad.
- Lease of Rajkot facility: The proposed lease of the Rajkot facility (land plus building, approximately 13 acres, with utility connections) is intended to generate steady recurring cash flows from an underutilised asset.
- Dividend: A final dividend of ₹3.00 per equity share has been recommended for FY 2025-26.
3. Key Risks
- EV demand risk: The declining EV sales trend (August 2026 down 11.46% YoY; YTD down 2.65% domestic and 3.03% domestic plus export) could weigh on the company’s electric three-wheeler portfolio if it persists.
- Execution risk in consolidation: The closure of Rajkot manufacturing operations and the shift to a single location at Ahmedabad must be executed without disrupting production or supply.
- Lease realisation risk: The anticipated recurring cash flows from the Rajkot facility lease depend on shareholder approval, identification of a suitable lessee, and finalisation of terms. No lease agreement has been executed yet.
- Related party exposure: Material related party transactions with Khushbu Auto up to ₹120 crore are proposed for approval at the AGM.
- Regulatory and compliance risk: SEBI mandates that security holders in physical mode must have updated PAN, choice of nomination, contact details, bank account details, and specimen signature to receive payments such as dividends, interest, or redemption exclusively through electronic mode effective April 1, 2024.
4. Management Guidance Versus Observed Business Performance
- Guidance on manufacturing consolidation: Management stated that consolidating manufacturing at the Ahmedabad facility is expected to improve operational efficiency, optimise manpower and resource utilisation, reduce fixed overheads, and reduce operating and administrative costs. It also stated that the Ahmedabad facility can meet existing manufacturing requirements and has space to enhance capacity with minimum capex for anticipated demand over the next several years. The Rajkot closure is targeted on or before December 01, 2026.
- Guidance on the Rajkot lease: Management stated the proposed lease is expected to generate steady additional revenue and cash flows through productive utilisation of an underutilised asset, while enabling continued efficient manufacturing from a single integrated facility. The lease remains subject to shareholder approval and lessee identification.
- Observed performance versus guidance: In Q1 FY 2026-27, the company delivered 42.5% volume growth, 44.67% standalone revenue growth, and 33.74% standalone PAT growth YoY, alongside consolidated PAT growth of 290.29%. August 2026 sales showed continued momentum with total domestic plus export sales up 32.58% YoY and YTD up 39.57%, although EV sales declined. These results are consistent with management’s stated direction of higher three-wheeler volumes, improved profitability, and operational consolidation, while the EV decline represents a divergence from the broader growth trend.
- Board and governance actions: The Board approved the re-appointment of Mr. Mahendra J. Patel as Whole-time Director and CFO for three years from April 1, 2027 to March 31, 2030, and the re-appointment of Mr. Gurudeo Madhukar Yadwadkar as Independent Director for a second term from August 11, 2026 to August 10, 2029, both subject to shareholder approval. The 38th Annual General Meeting is scheduled for September 18, 2026 at 03:30 PM IST through video conferencing or other audio-visual means.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.