ATHERENERG
Equity Metrics
September 24, 2026
Ather Energy Limited
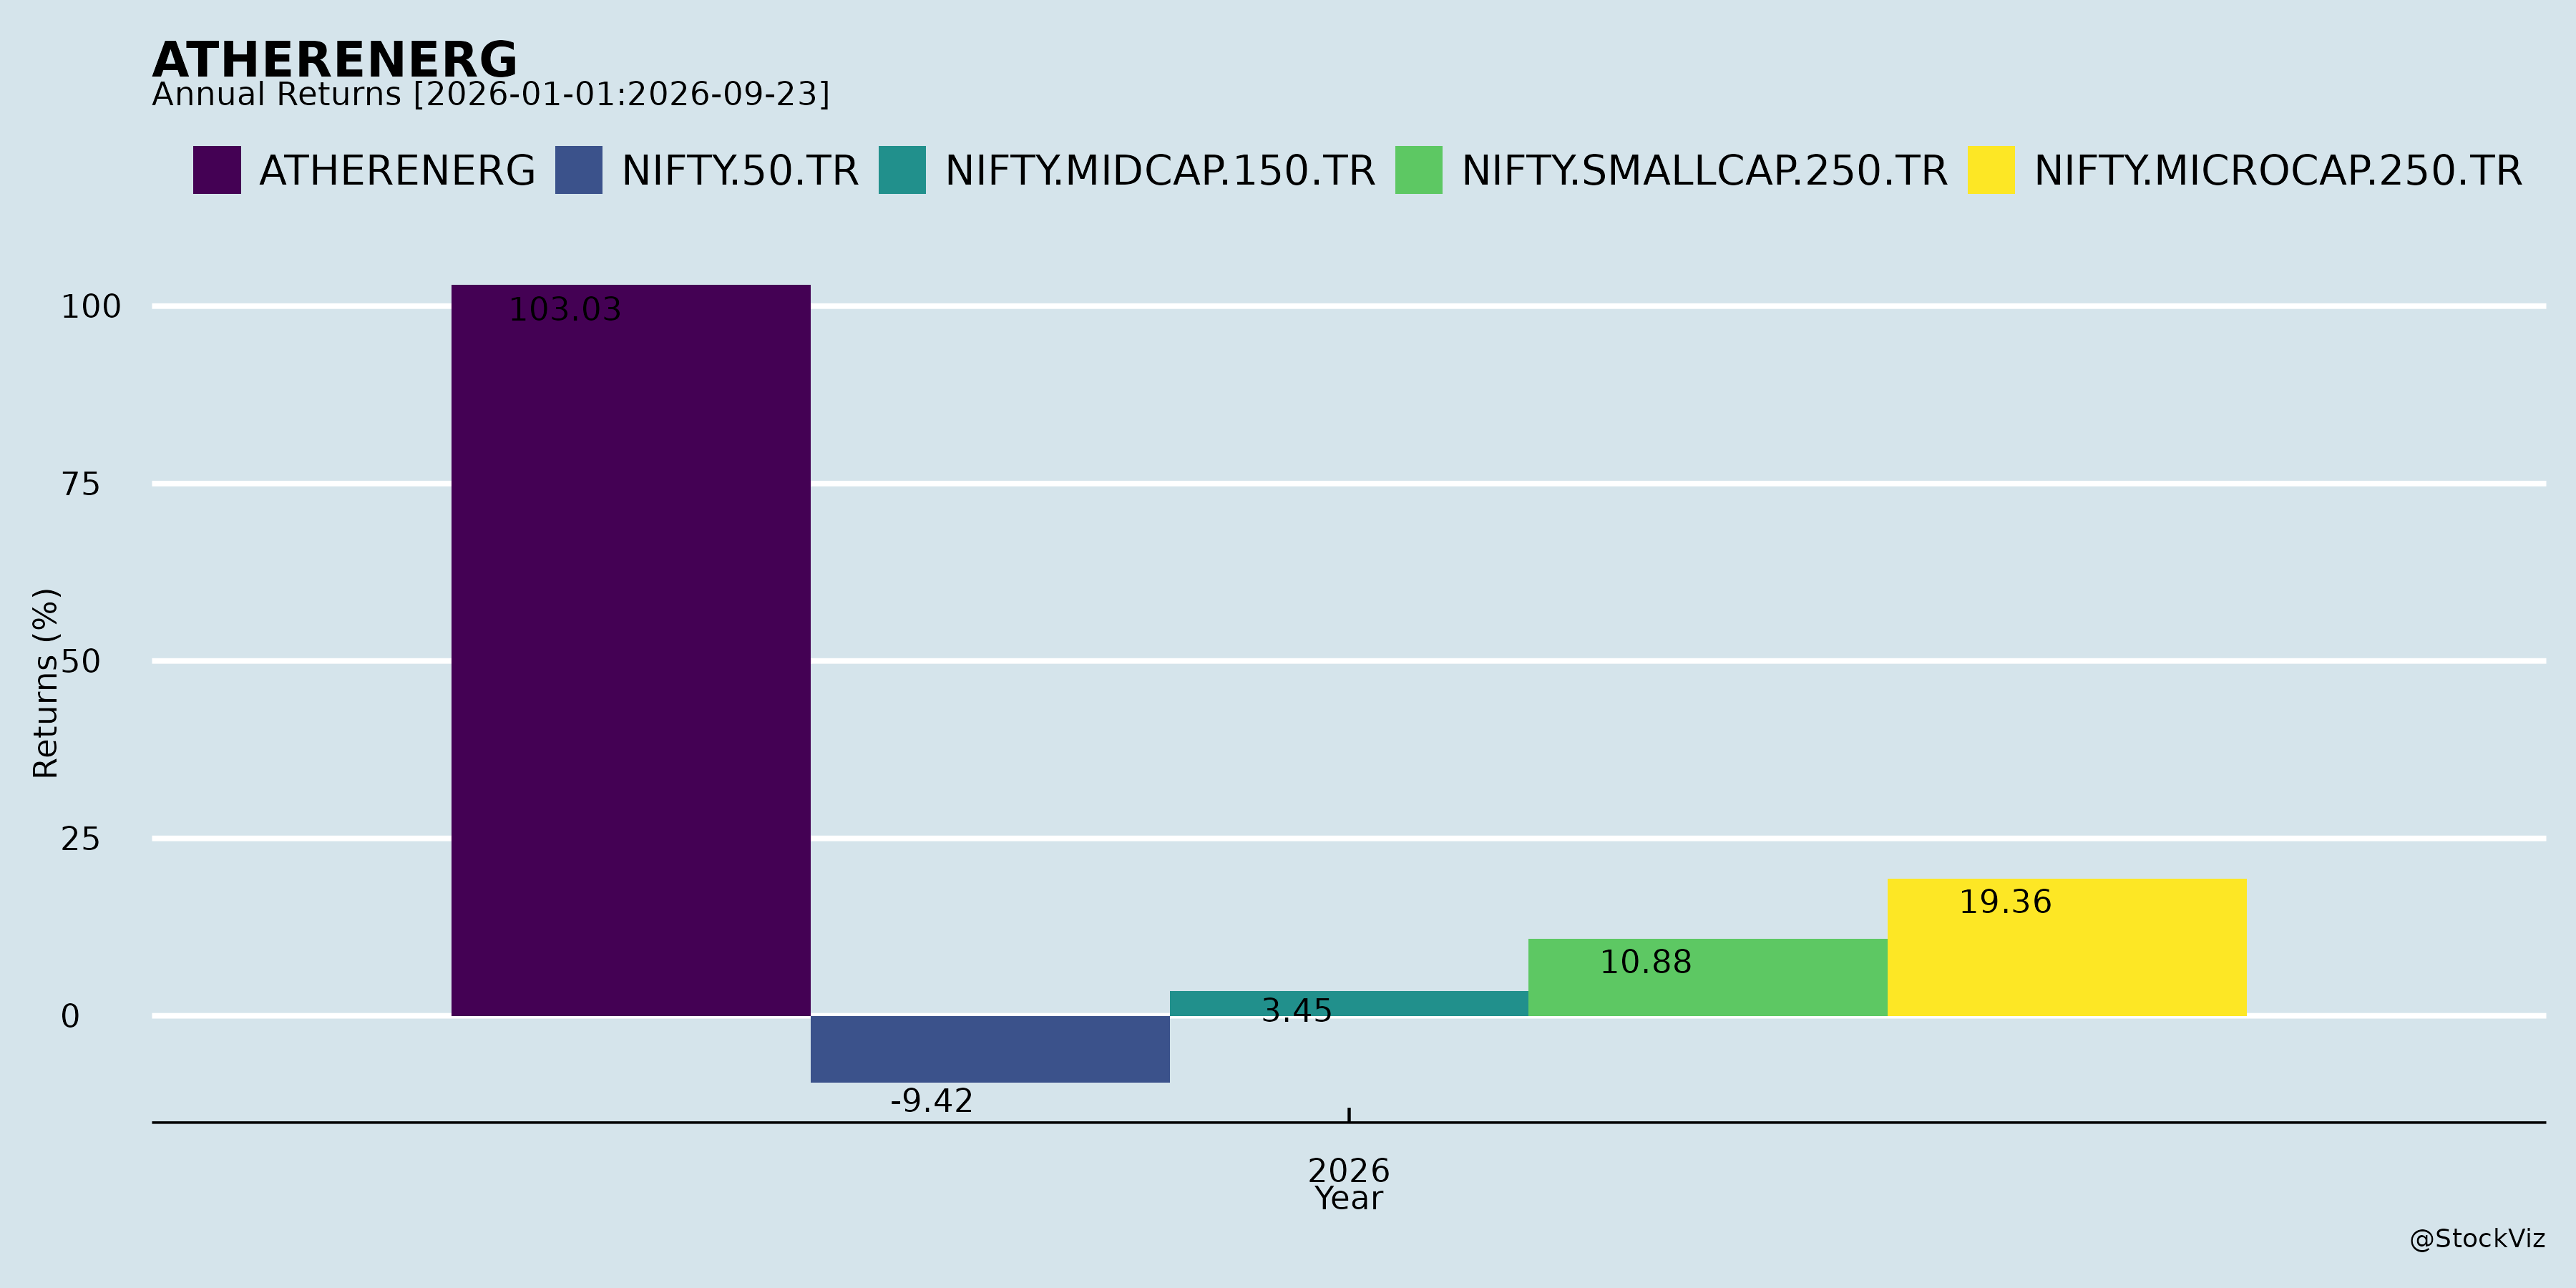
Annual Returns

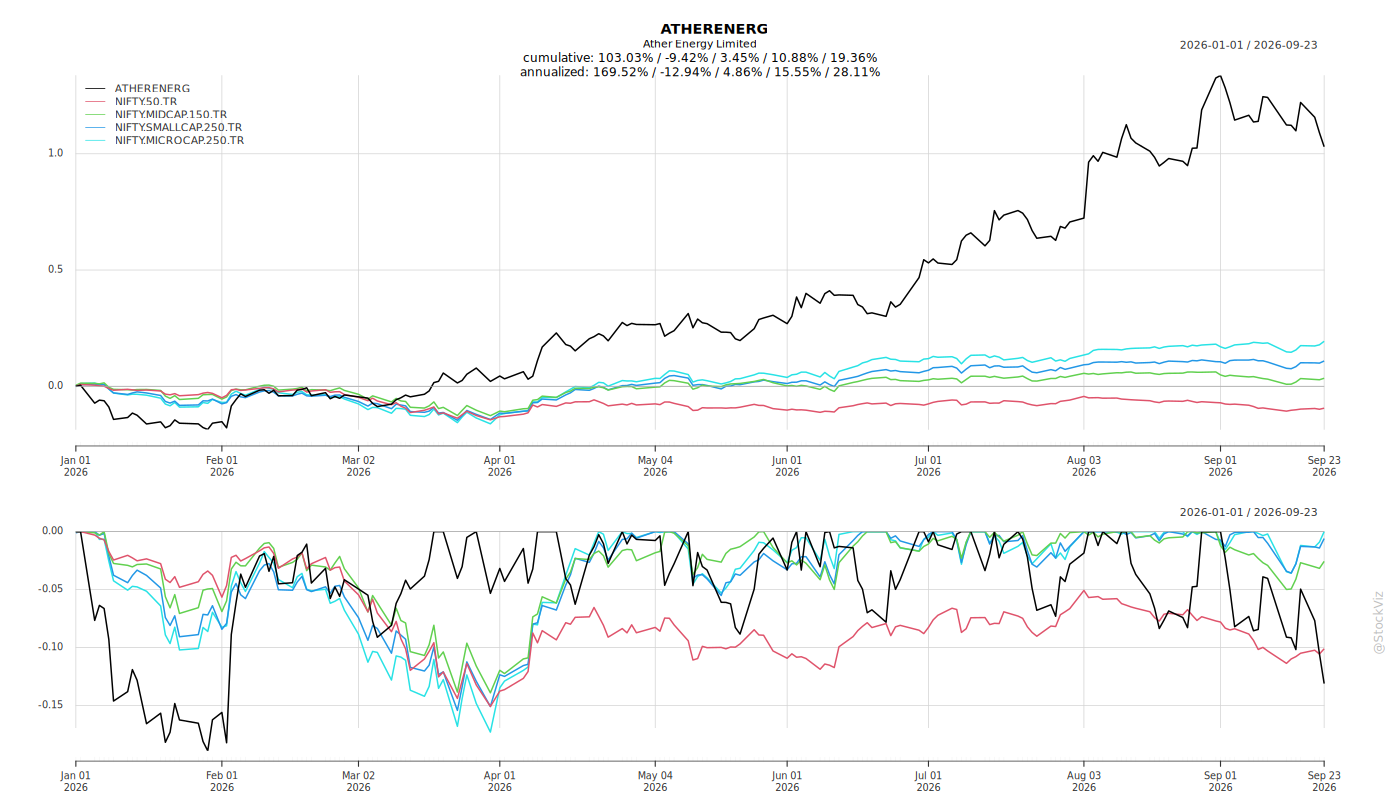
Cumulative Returns and Drawdowns
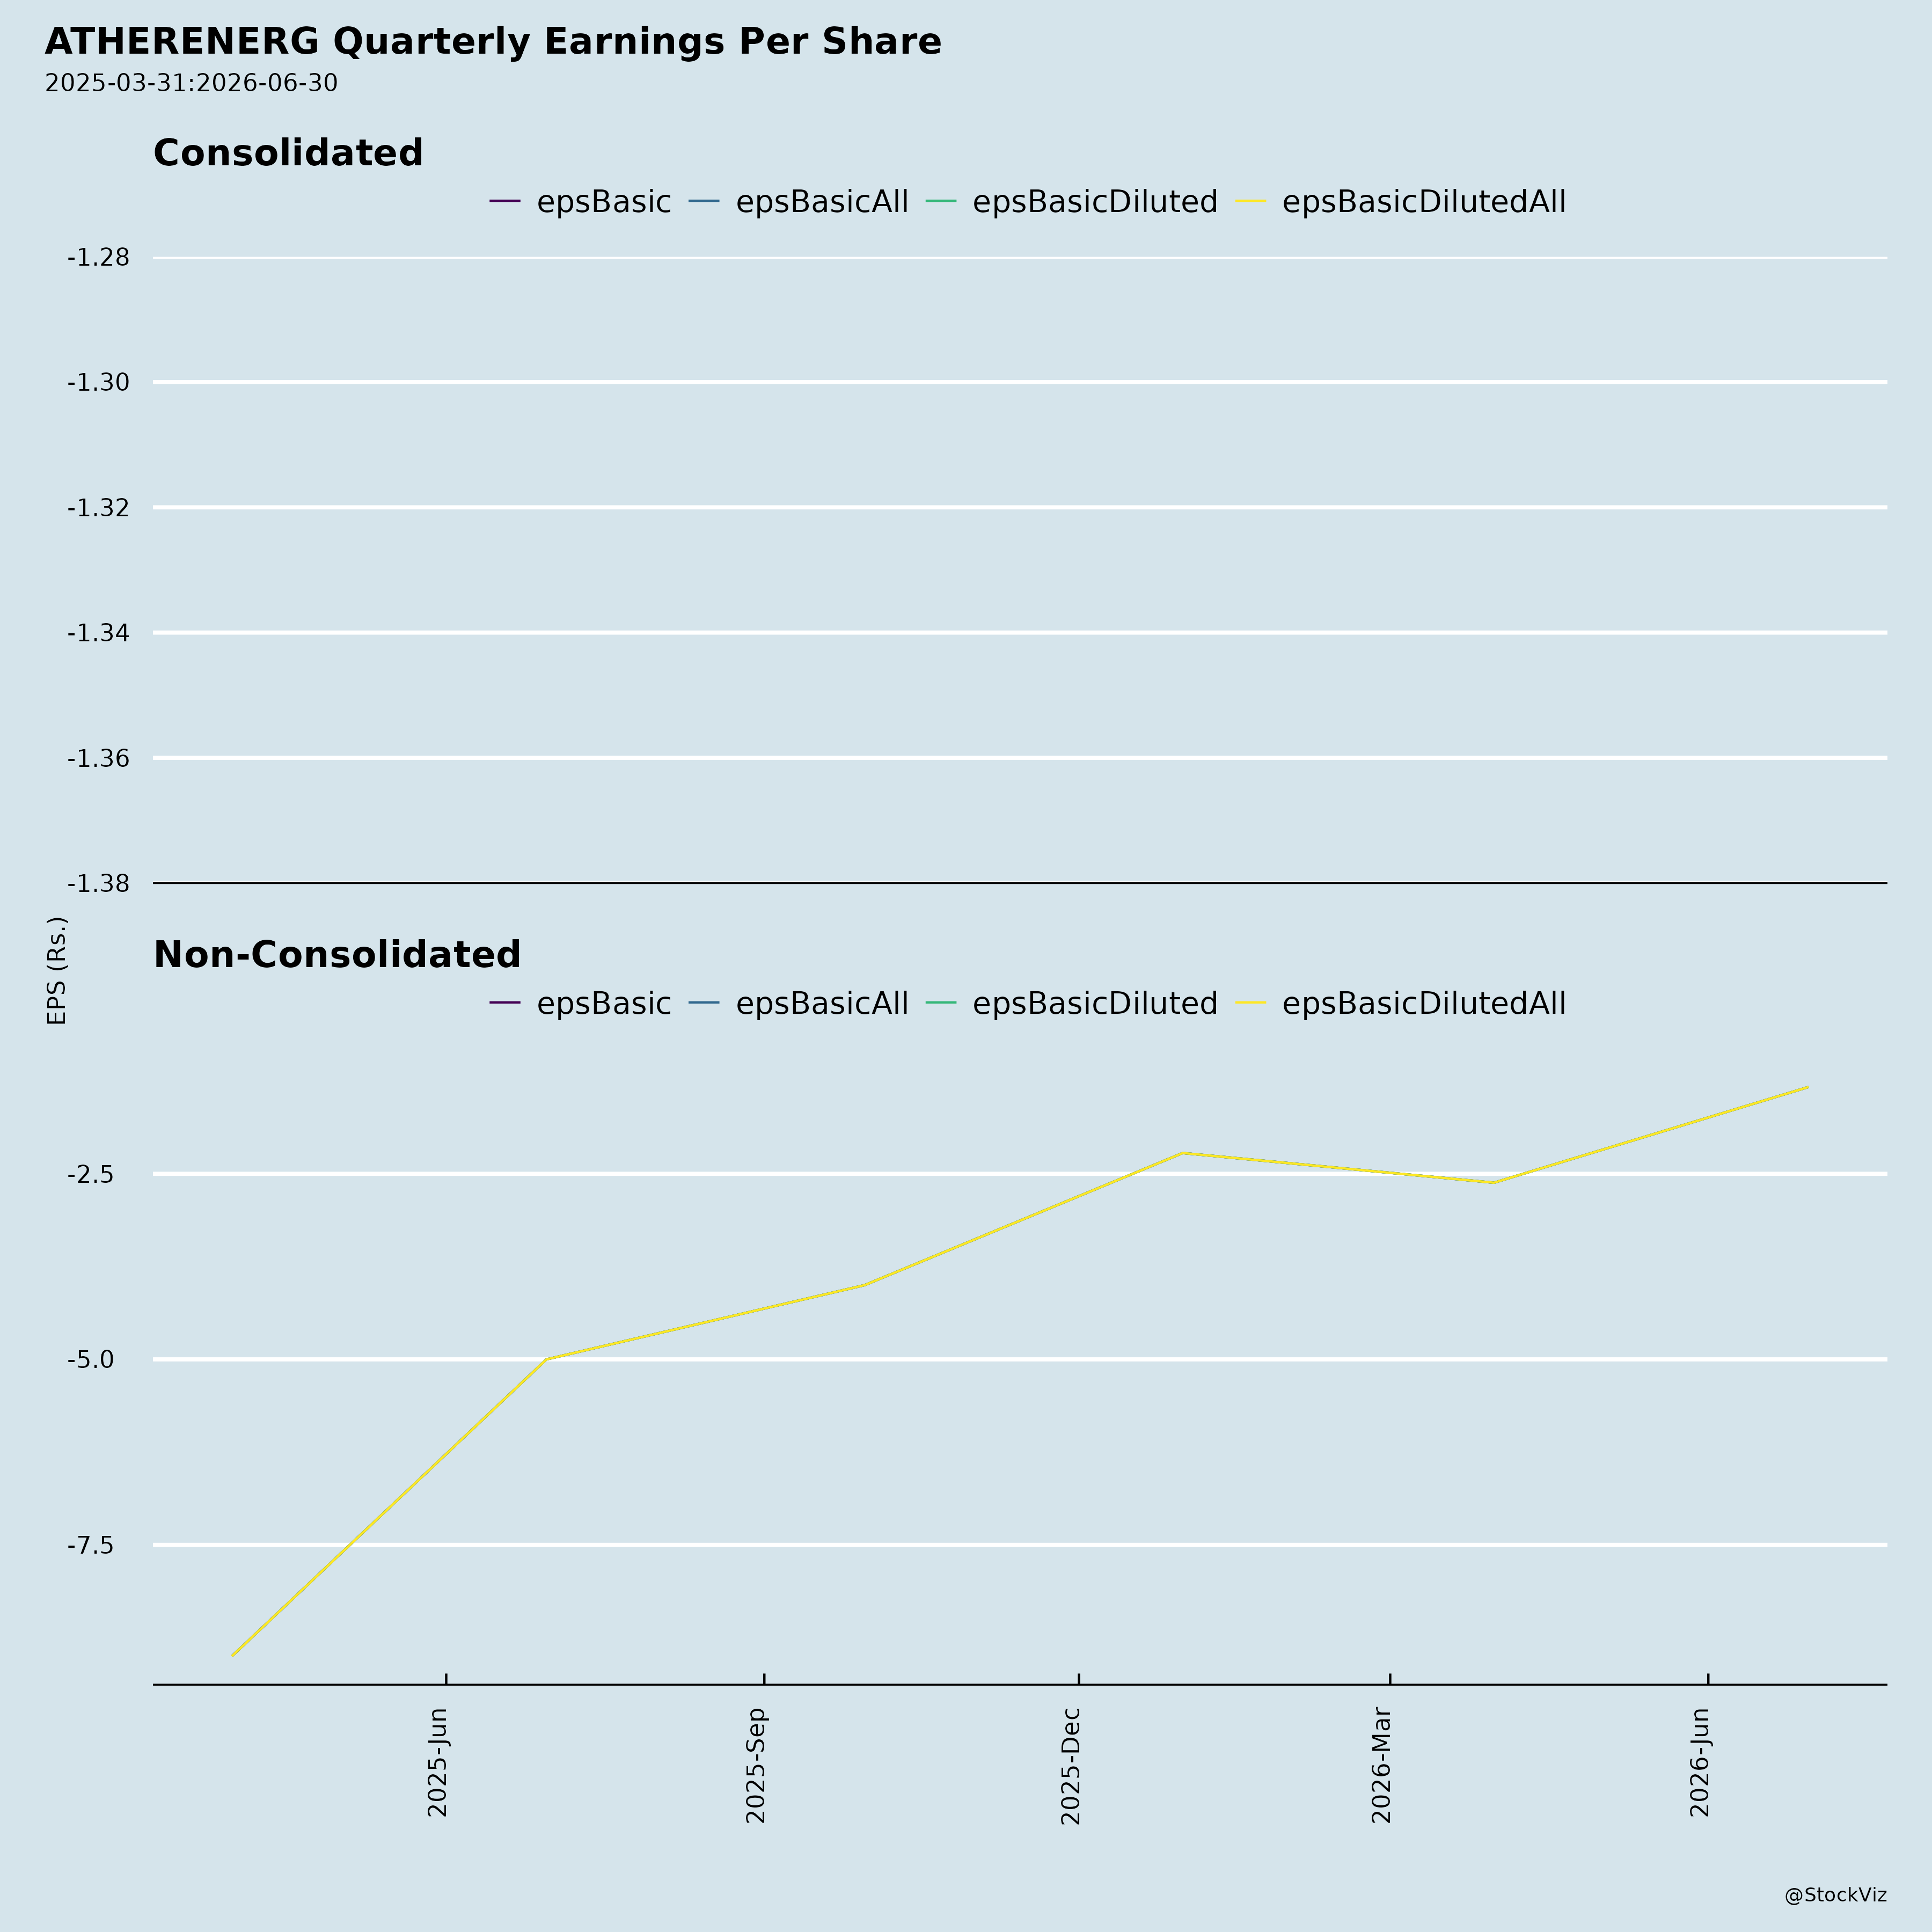
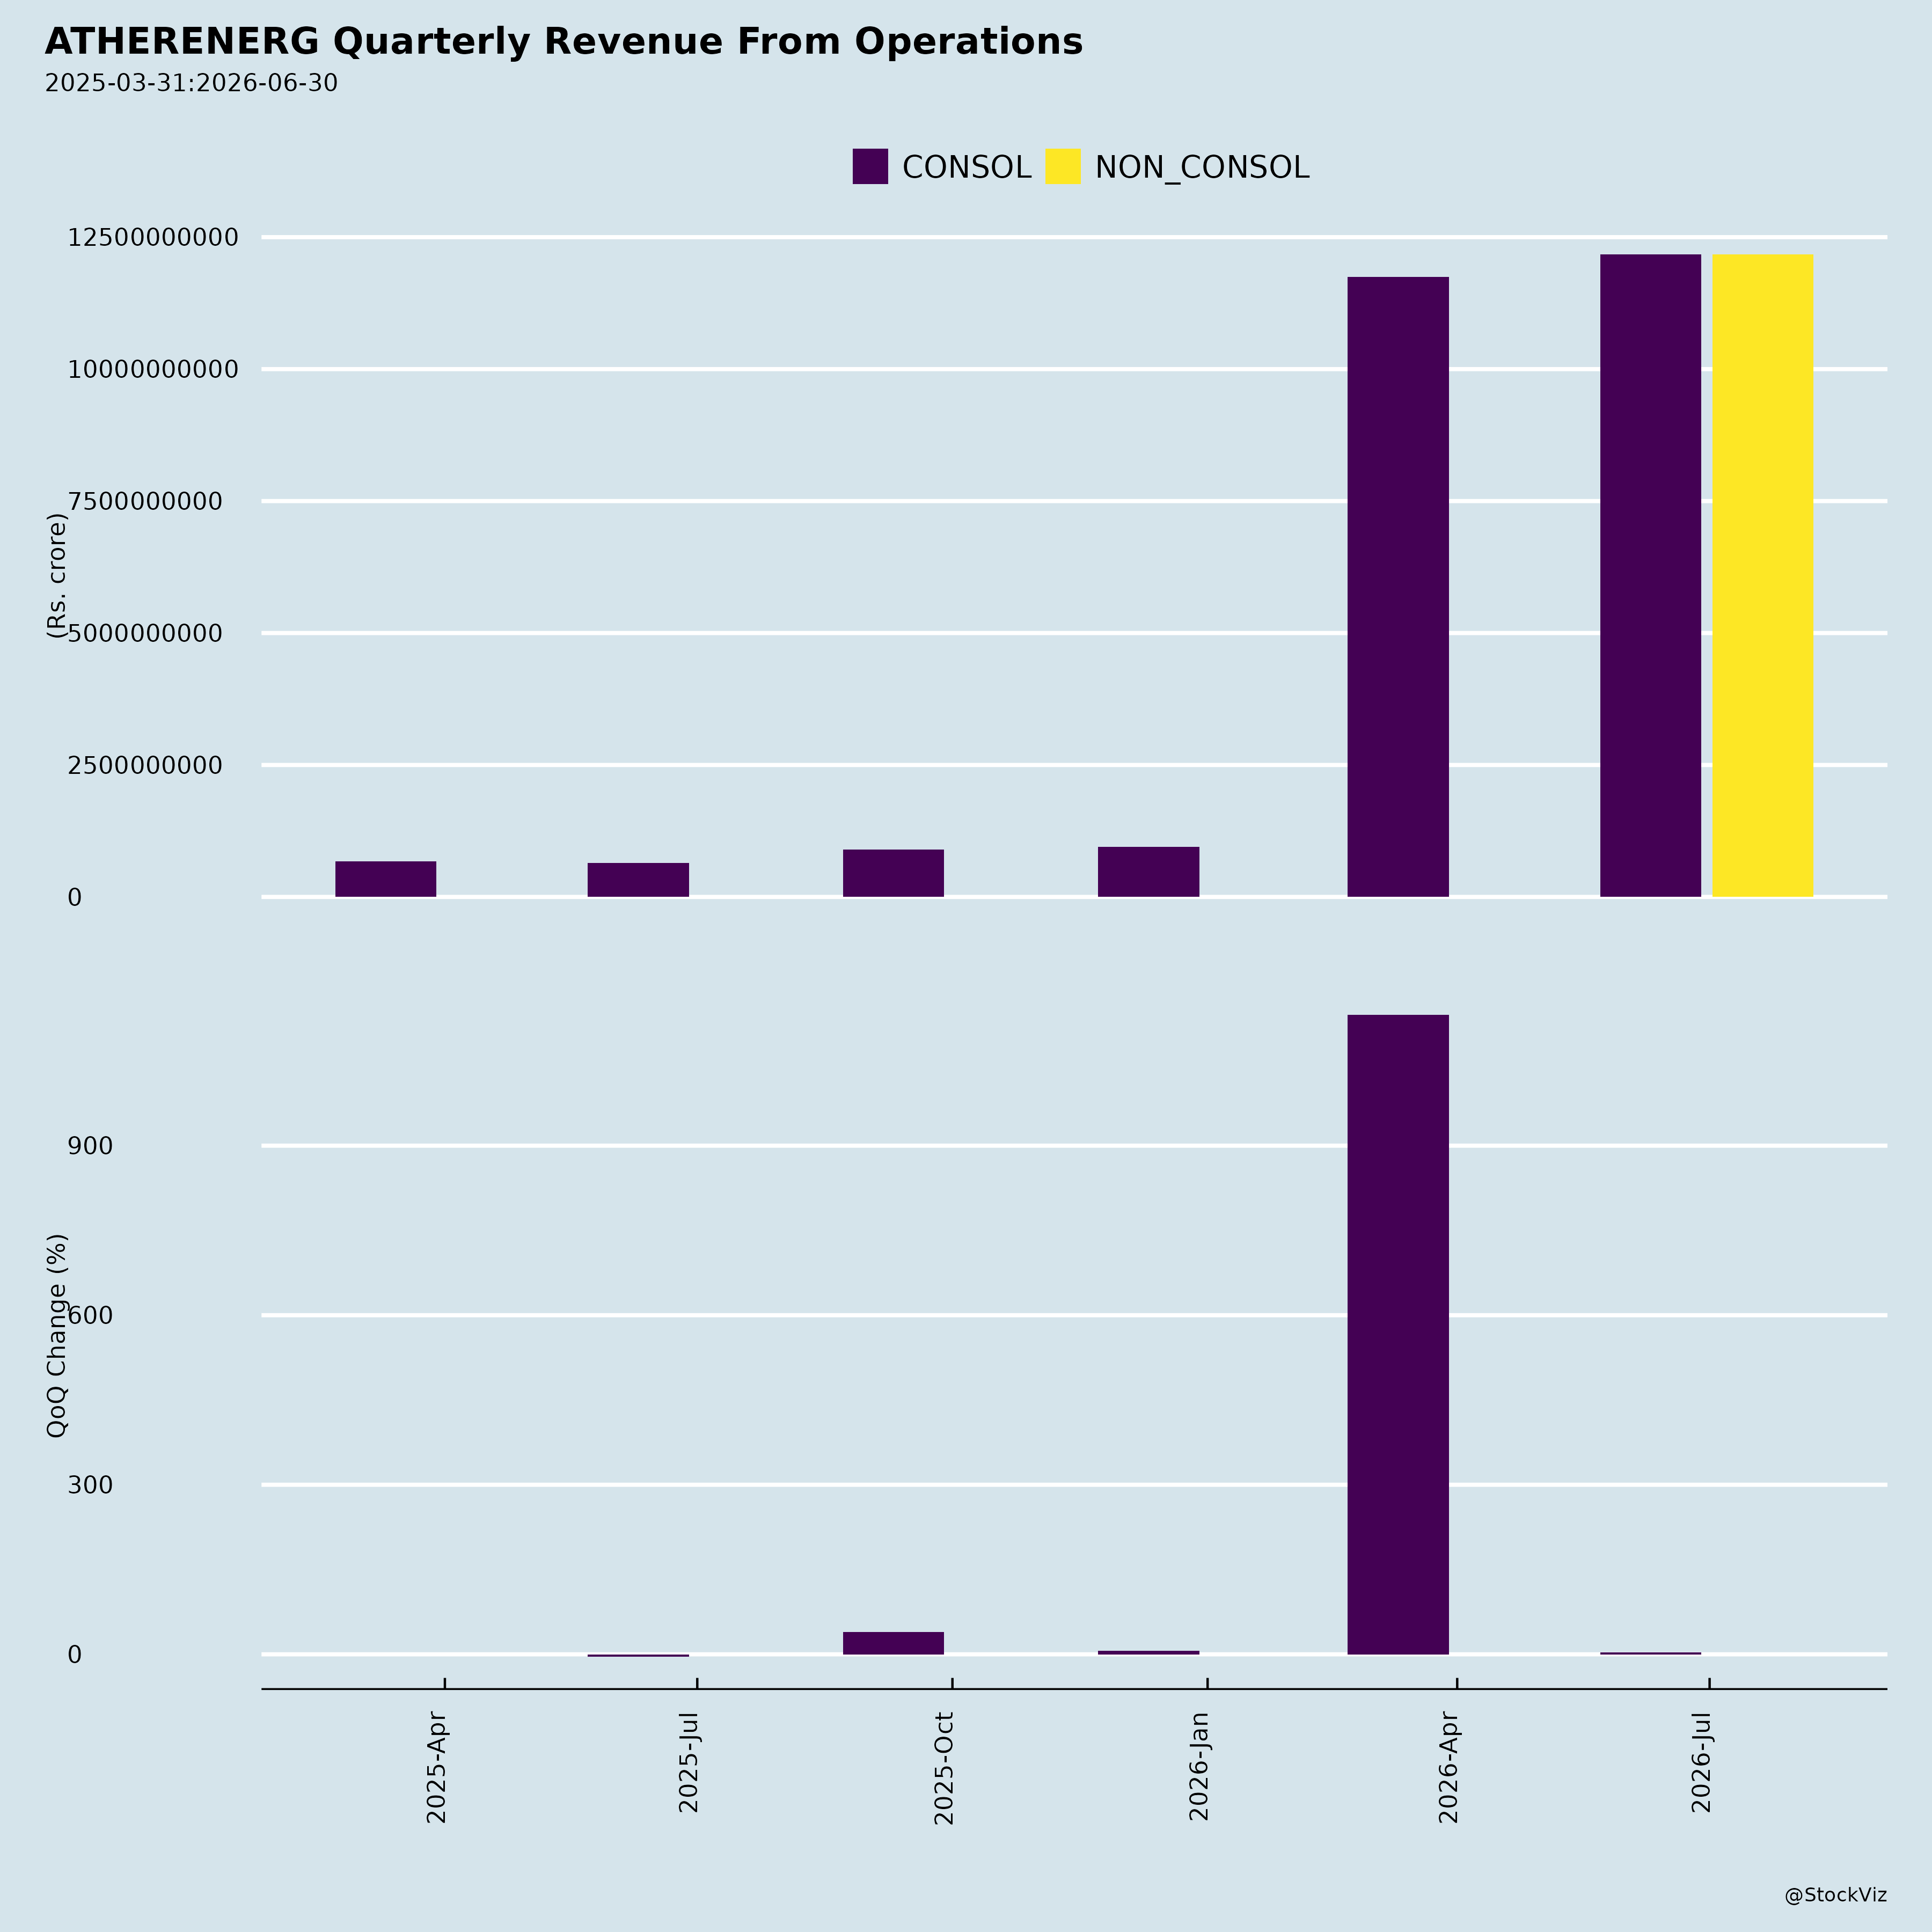
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
Headwinds and Challenges
- Commodity cost inflation: During Q1 FY27, raw material costs rose on higher input costs for copper, aluminium, lithium, and crude-linked materials. This is described as a commodity cost headwind against which the company took calibrated pricing actions, product mix management, cost reductions via value engineering, and supplier negotiations.
- Demand outpacing supply: Customer demand across Ather’s portfolio continued to outpace available production during the quarter. Pre-orders grew 158% YoY to 150k and enquiries rose 95% YoY to 707k, indicating demand was not fully servable from existing capacity.
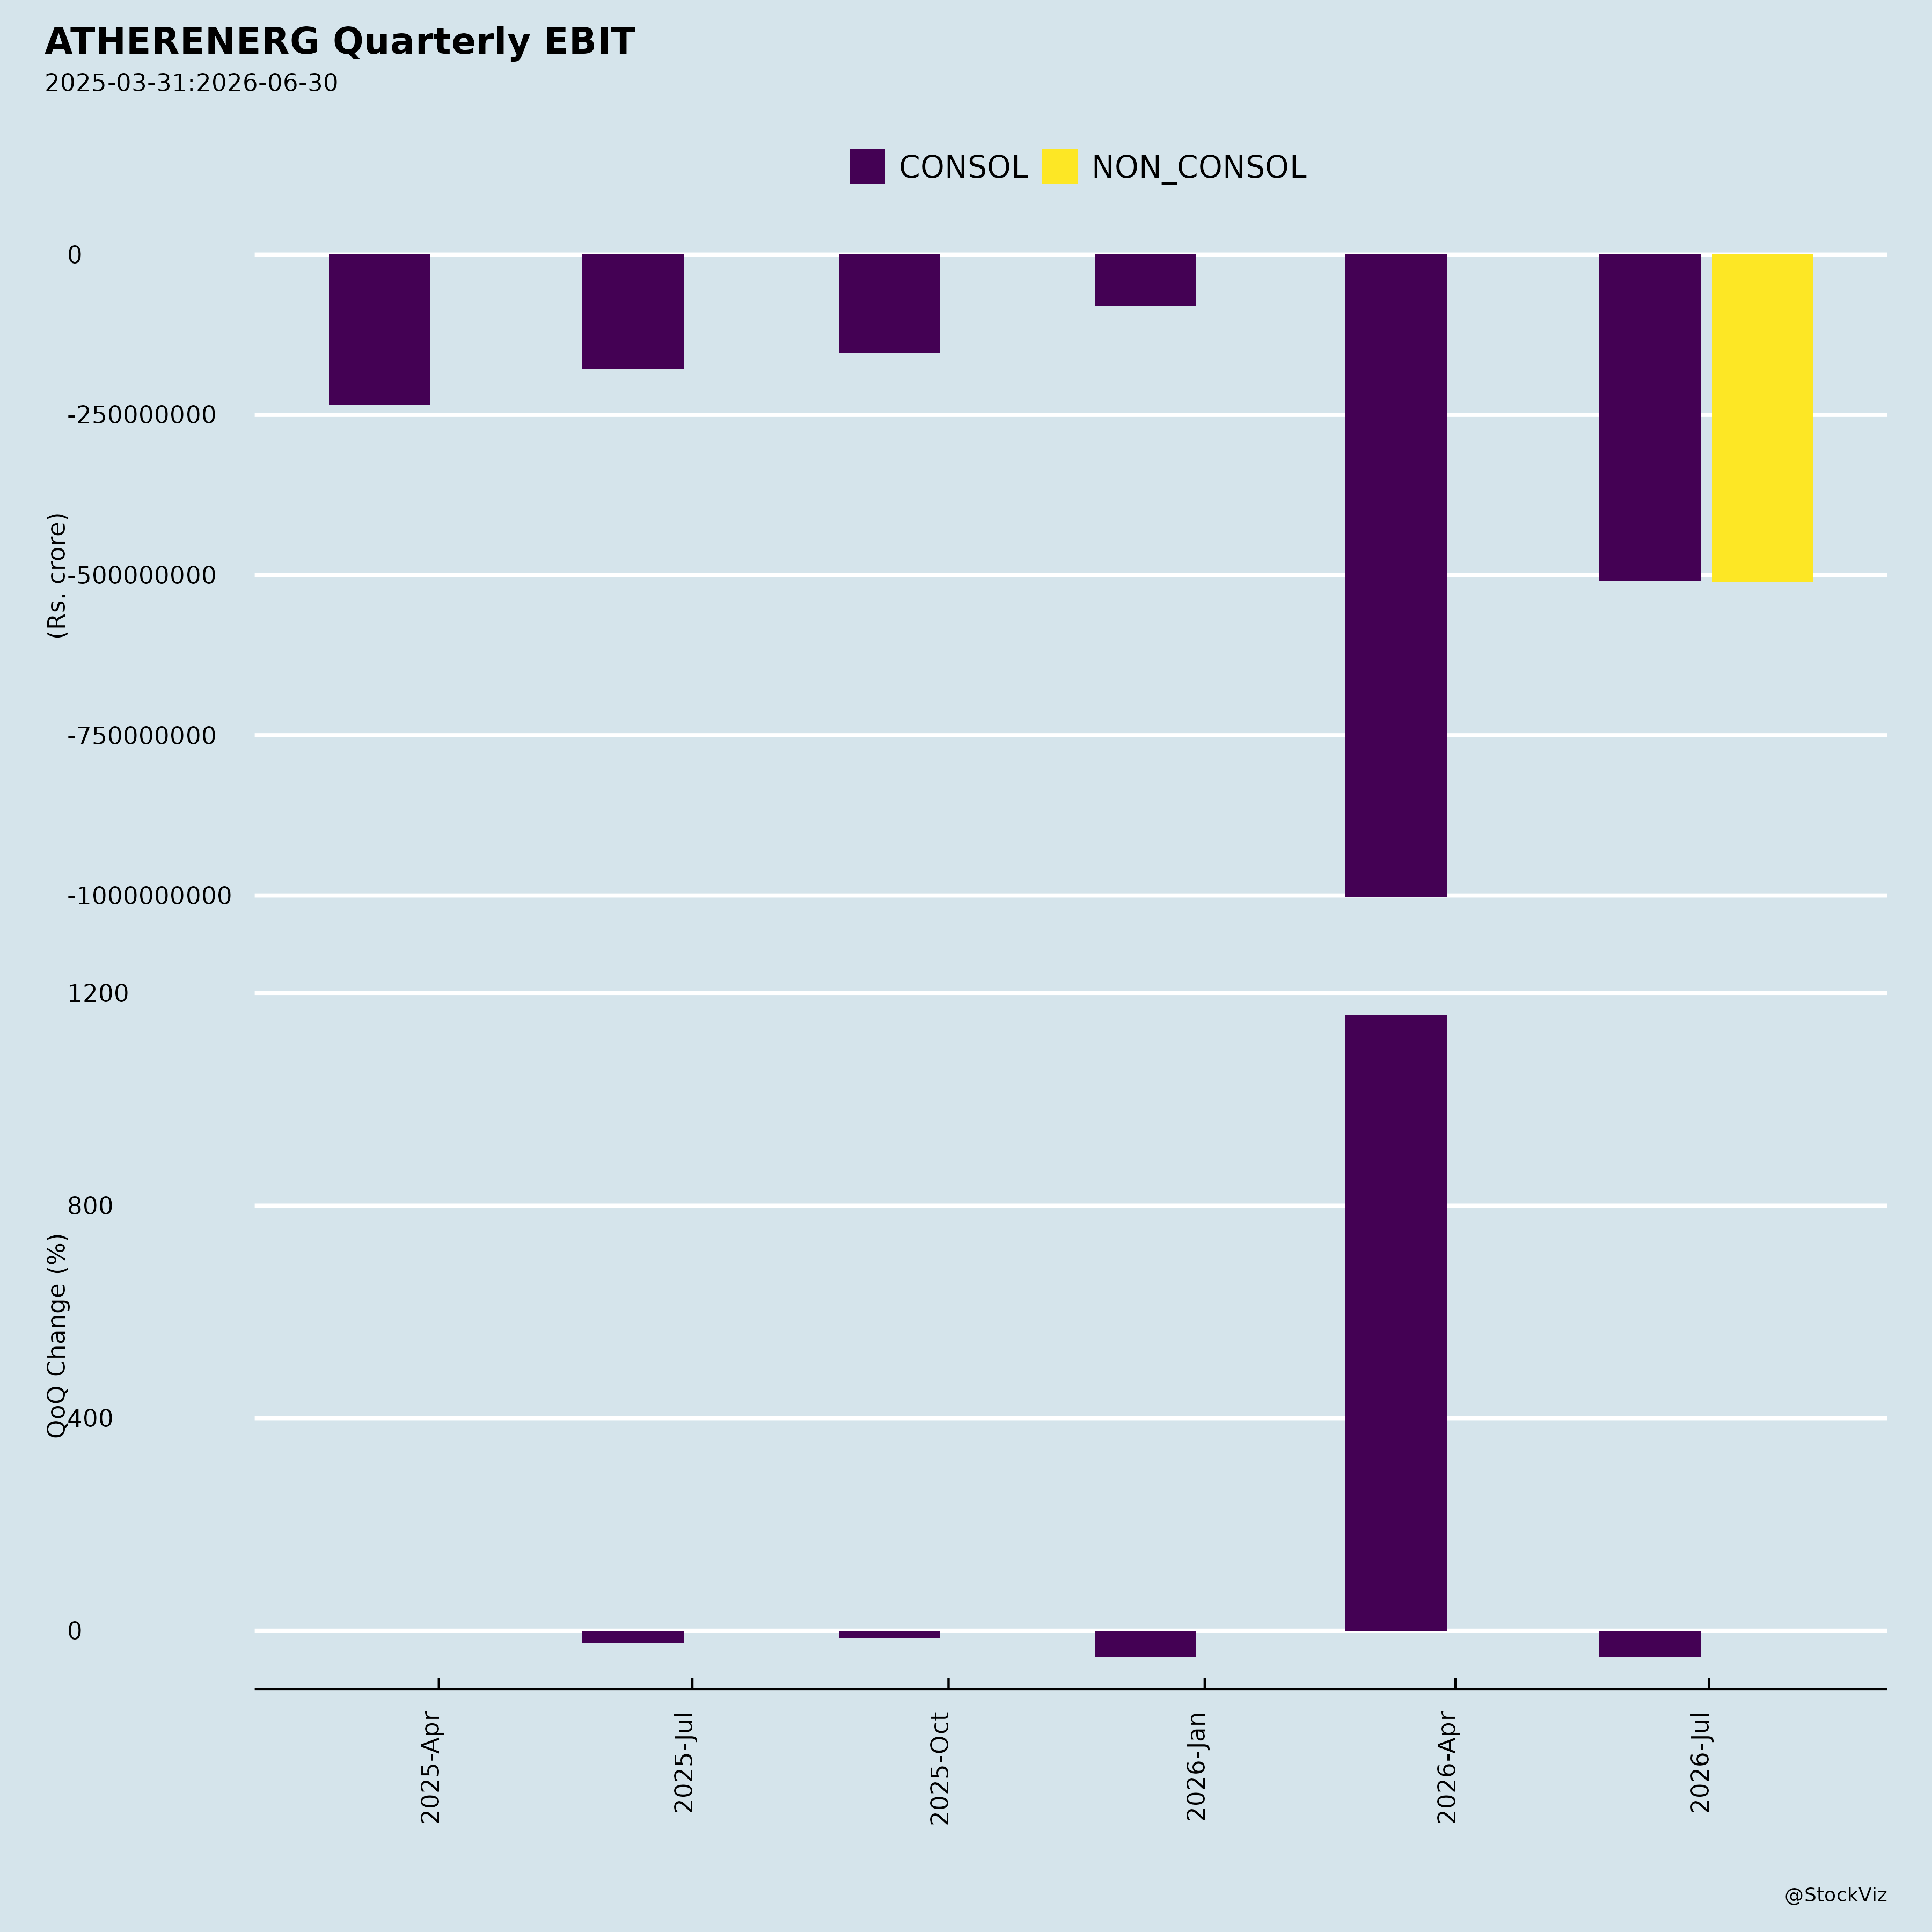
- Continued losses: Despite improvement, the company remained loss-making. Consolidated net loss for Q1 FY27 was ₹51 crore (narrowed from ₹178 crore in Q1 FY26). The newly incorporated wholly owned subsidiary, Ather Insurance Limited, incurred a net loss of ₹0.22 crore in Q1 FY27.
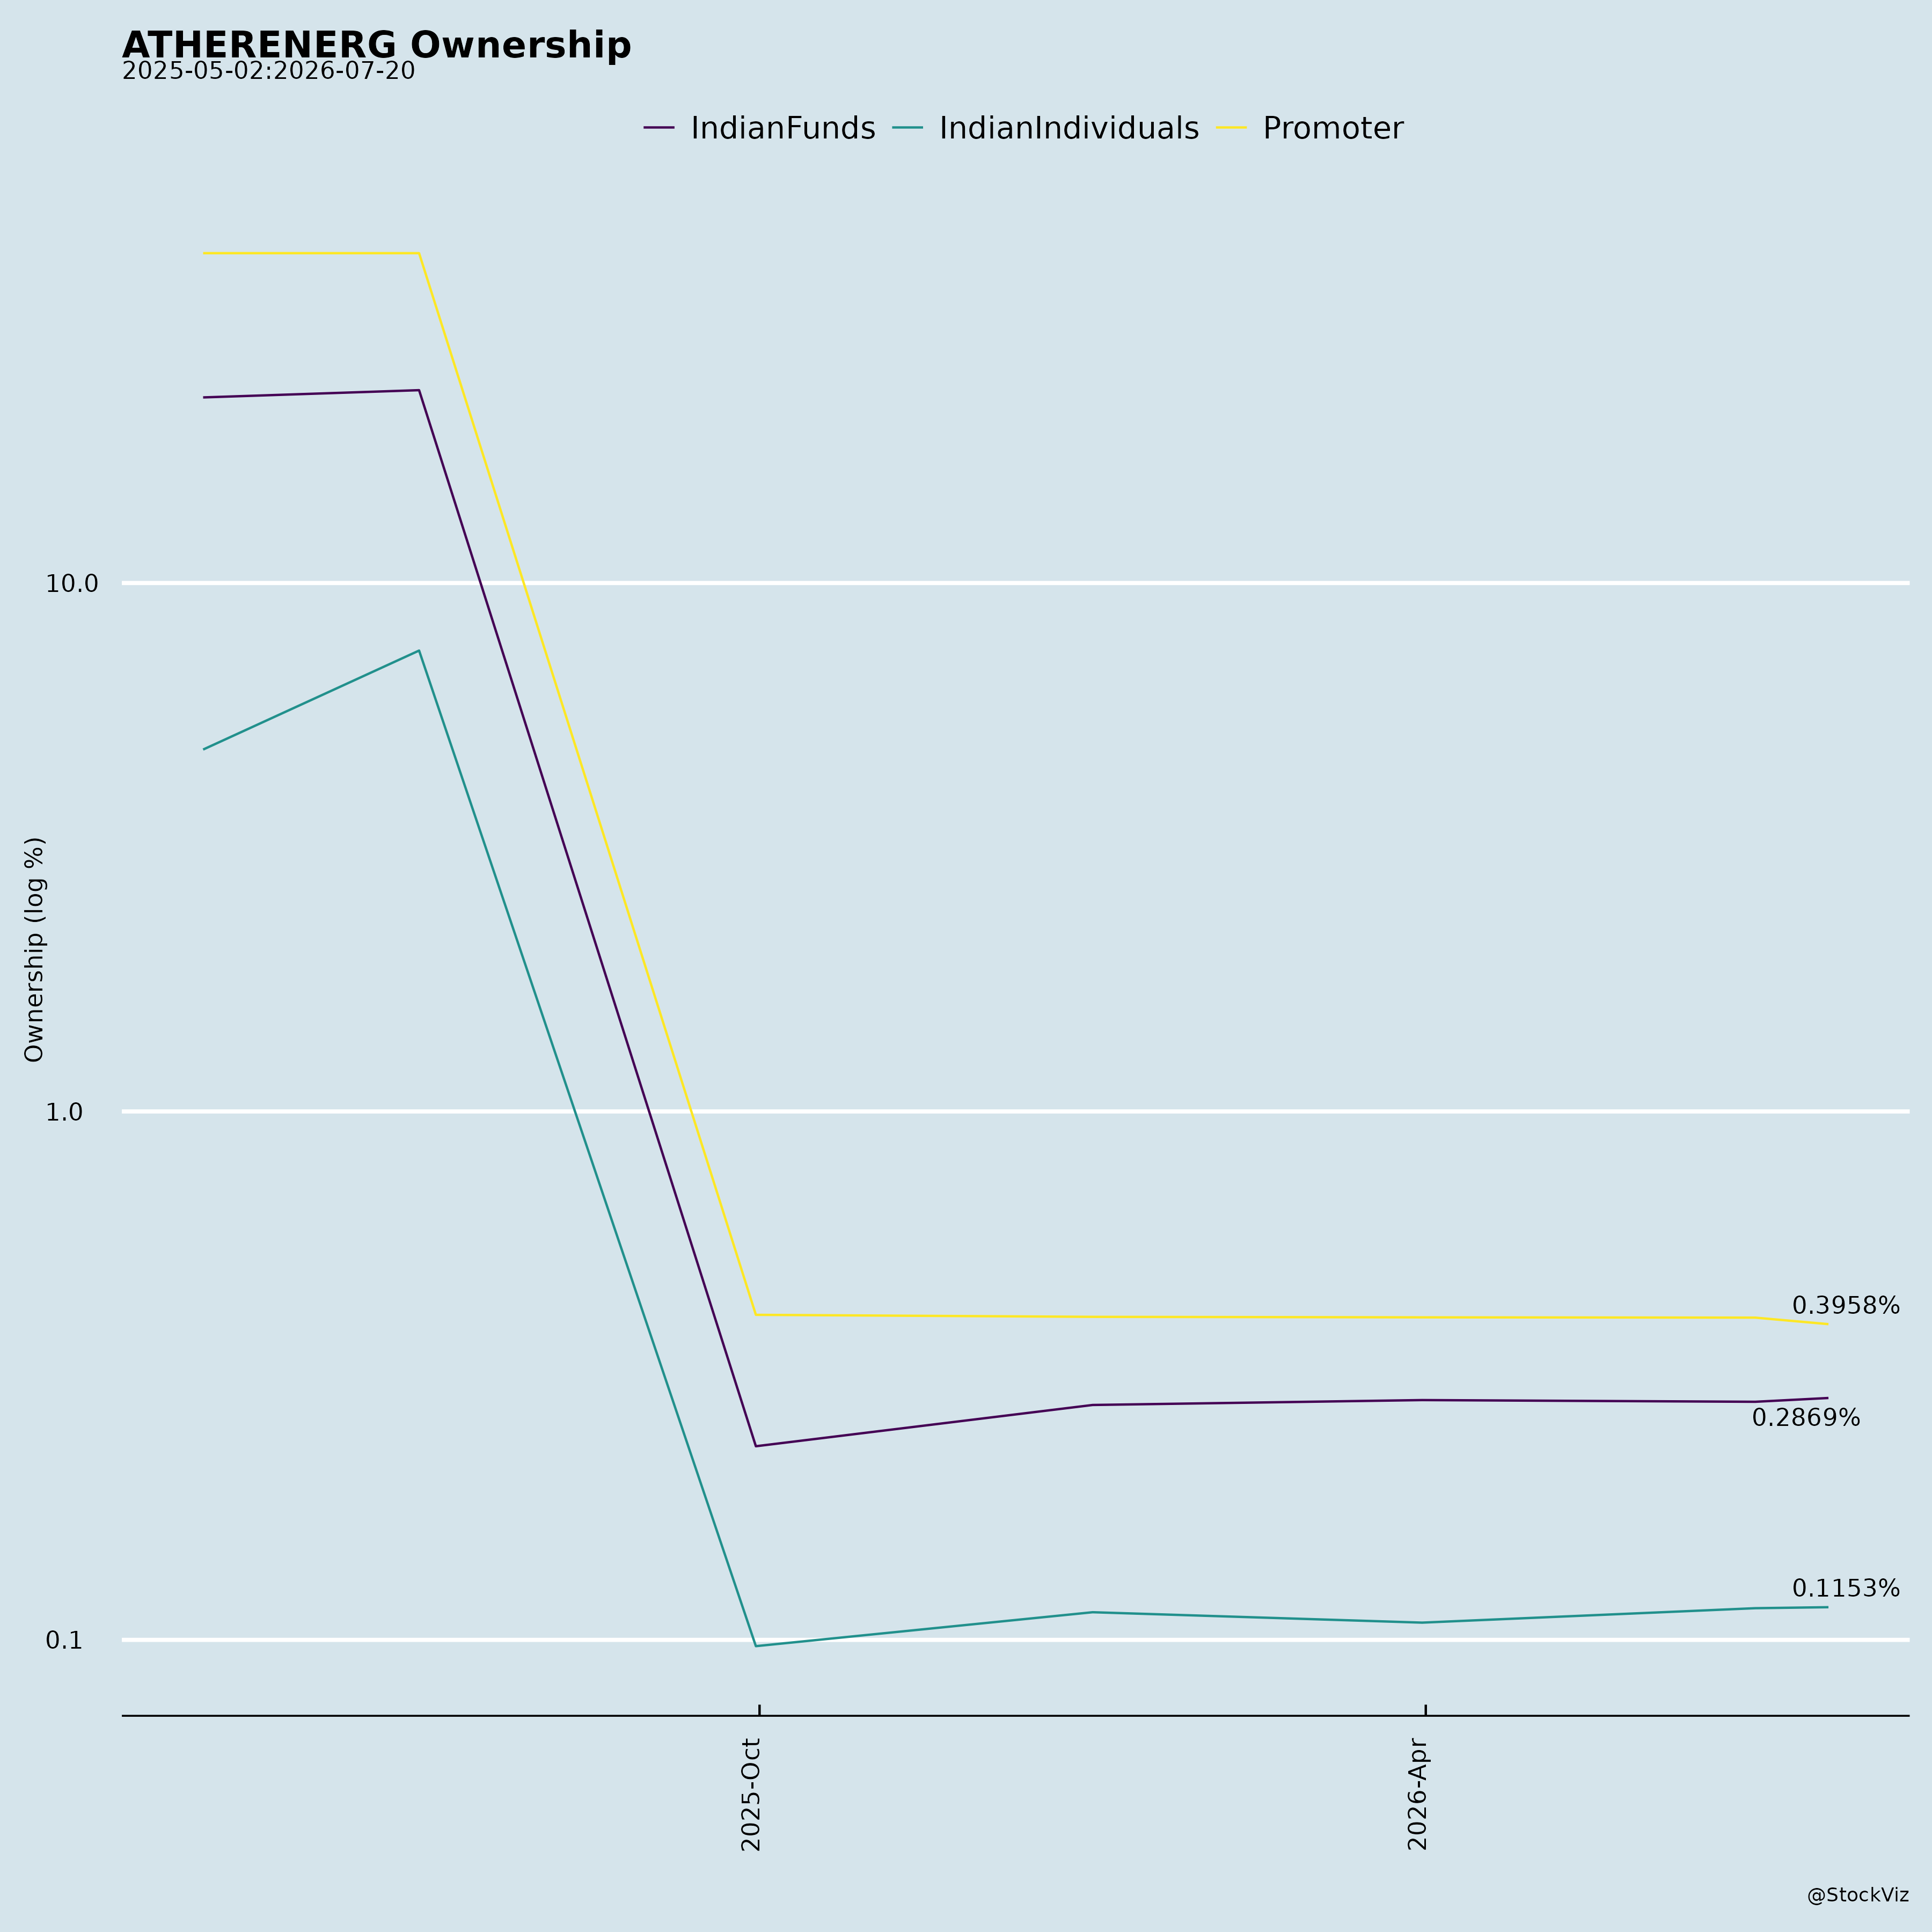
- Dilution from fundraise and ESOPs: A qualified institutions placement allotted 1,08,15,307 equity shares at ₹1,202 per share (closure and allocation approved July 20, 2026). Separately, 3,67,875 equity shares were allotted to ESOP holders, and 80,223 ESOPs were granted (Board meeting August 03, 2026), with an exercise price of ₹1 per option and a five-year exercise period from vesting.
- Shareholder dissent on ESOP extension: At the 13th AGM (August 19, 2026), the special resolution to extend benefits of the Amended and Restated Ather Energy ESOP Plan 2025 to employees of subsidiary companies passed with 86.46% in favour and 13.54% against. Public institutions voted 70.50% in favour and 29.50% against, a notably higher dissent level than on the other resolutions.
Tailwinds and Growth Prospects
- Volume and revenue growth: Q1 FY27 deliveries were 83,173 units, up 80.5% YoY. Consolidated total income was ₹1,260 crore, up 87.2% YoY, attributed to volume growth, calibrated pricing actions, and growing non-vehicle revenue.
- Margin improvement: Consolidated Adjusted Gross Margin was ₹282 crore, up 82.3% YoY. Consolidated EBITDA turned positive at ₹9 crore in Q1 FY27 versus an EBITDA loss of ₹106 crore in Q1 FY26, a 1,650 bps YoY improvement.
- Diversifying revenue mix: Revenue from software subscriptions, charging, accessories, spares, and service rose to 14% of revenue from operations, up from 13% in Q1 FY26.
- Industry momentum: Industry E2W registrations rose 68% YoY to approximately 525k units (Vahan data), and EV penetration crossed 10% for the first time in June 2026.
- Capacity expansion: Factory 3.0 at AURIC in Chhatrapati Sambhaji Nagar remains on schedule. Phase 1 (500,000 units annual capacity) is expected to commence production in Q3 FY27. On completion of Phases 1 and 2, total installed annual capacity across facilities is expected to reach 1.42 million electric two-wheelers.
- New platform and product: The first production scooter on the all-new EL platform is to be unveiled on August 29, 2026 at Ather Community Day 2026. The EL platform is described as the company’s next-generation vehicle architecture and first new platform since the 450, engineered for versatility, scalability, and manufacturing efficiency, and intended to serve a significantly larger customer base.
- Policy and sentiment: Management cited structural tailwinds from policy support and shifting customer sentiment translating into an upsurge in demand.
- R&D and IP base: As of June 30, 2026, Ather holds 323 registered trademarks, 270 registered designs, and 52 registered patents, with pending applications for 142 trademarks, 32 designs, and 667 patents globally. It operates the widest 2W fast charging network in the country (Ather Grid).
Key Risks
- Execution risk on capacity and new platform: The growth outlook depends on Factory 3.0 Phase 1 commencing production in Q3 FY27 as scheduled and on the EL platform product launch proceeding as planned on August 29, 2026.
- Margin sustainability: The company stated it took measures to sustain healthy margins amid commodity inflation; failure of these measures to offset input cost pressure would weigh on margins.
- Loss-making subsidiary: Ather Insurance Limited, a newly incorporated wholly owned subsidiary, incurred a net loss of ₹0.22 crore in Q1 FY27.
- Governance/shareholder alignment: The ESOP extension resolution drew 13.54% votes against overall and 29.50% against among public institutions, indicating meaningful shareholder opposition on this item.
- Dilution risk: The QIP allotment of 1,08,15,307 shares and ongoing ESOP allotments and grants increase the equity base; the Board meeting materials note diluted earnings per share pursuant to share issuance on exercise of options as a disclosure item.
Management Guidance Versus Observed Performance
- Demand commentary: Management stated demand was “far outstripping supply” and that structural tailwinds from policy support and shifting customer sentiment translated into a massive upsurge. Observed data supports this: pre-orders up 158% YoY to 150k, enquiries up 95% YoY to 707k, and the company explicitly noted demand continued to outpace available production during the quarter.
- Capacity guidance: Factory 3.0 Phase 1 (500,000 units annual capacity) is expected to commence production during Q3 FY27, with total installed capacity across facilities expected to reach 1.42 million units upon completion of Phases 1 and 2. The August 03, 2026 disclosure states the project “remains on schedule”; no production commencement has yet been reported in the supplied material.
- Product guidance: The first production scooter on the EL platform is scheduled for unveiling on August 29, 2026 at Ather Community Day 2026. The supplied material does not yet report the outcome of that event.
- Margin trajectory: Management actions (calibrated pricing, mix management, value engineering, supplier negotiations) were described as intended to sustain healthy margins. Observed Q1 FY27 results show EBITDA turning positive at ₹9 crore and AGM up 82.3% YoY despite commodity headwinds, consistent with those measures having had a positive effect in the quarter.
- Investor engagement: The company is participating in investor and analyst group meetings in Bengaluru on September 7, 2026 and September 9, 2026, physically, with discussions based on publicly available information and no UPSI to be shared.
- AGM logistics: Physical letters were dispatched to members without registered e-mail addresses as of July 24, 2026, providing access details for the 13th AGM Notice and FY 2025-26 Annual Report. The 13th AGM was held on August 19, 2026 at 11:00 A.M. IST via video conferencing, and all resolutions were passed with the requisite majority.
Broker Narrative
The broker narrative pivoted completely: the first report was a solar/manufacturing thesis built on ALMM module/cell mandates, PLI support, and import duties, while the last report is an EV-2W thesis built on Ather’s EL platform, Ather Stack, AURIC capacity, and E-2W market growth. The persistent theme is policy-led domestic manufacturing and localization, but the sector focus changed from solar modules to electric two-wheelers. The risk framework also evolved from no flagged headwinds to EV-specific concerns around subsidy expiry, price sensitivity, competition, and cost inflation.
Broker Timeline
6 broker calls · 2025-06-13 to 2026-03-16
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.