ASIANPAINT
Equity Metrics
November 18, 2026
Asian Paints Limited
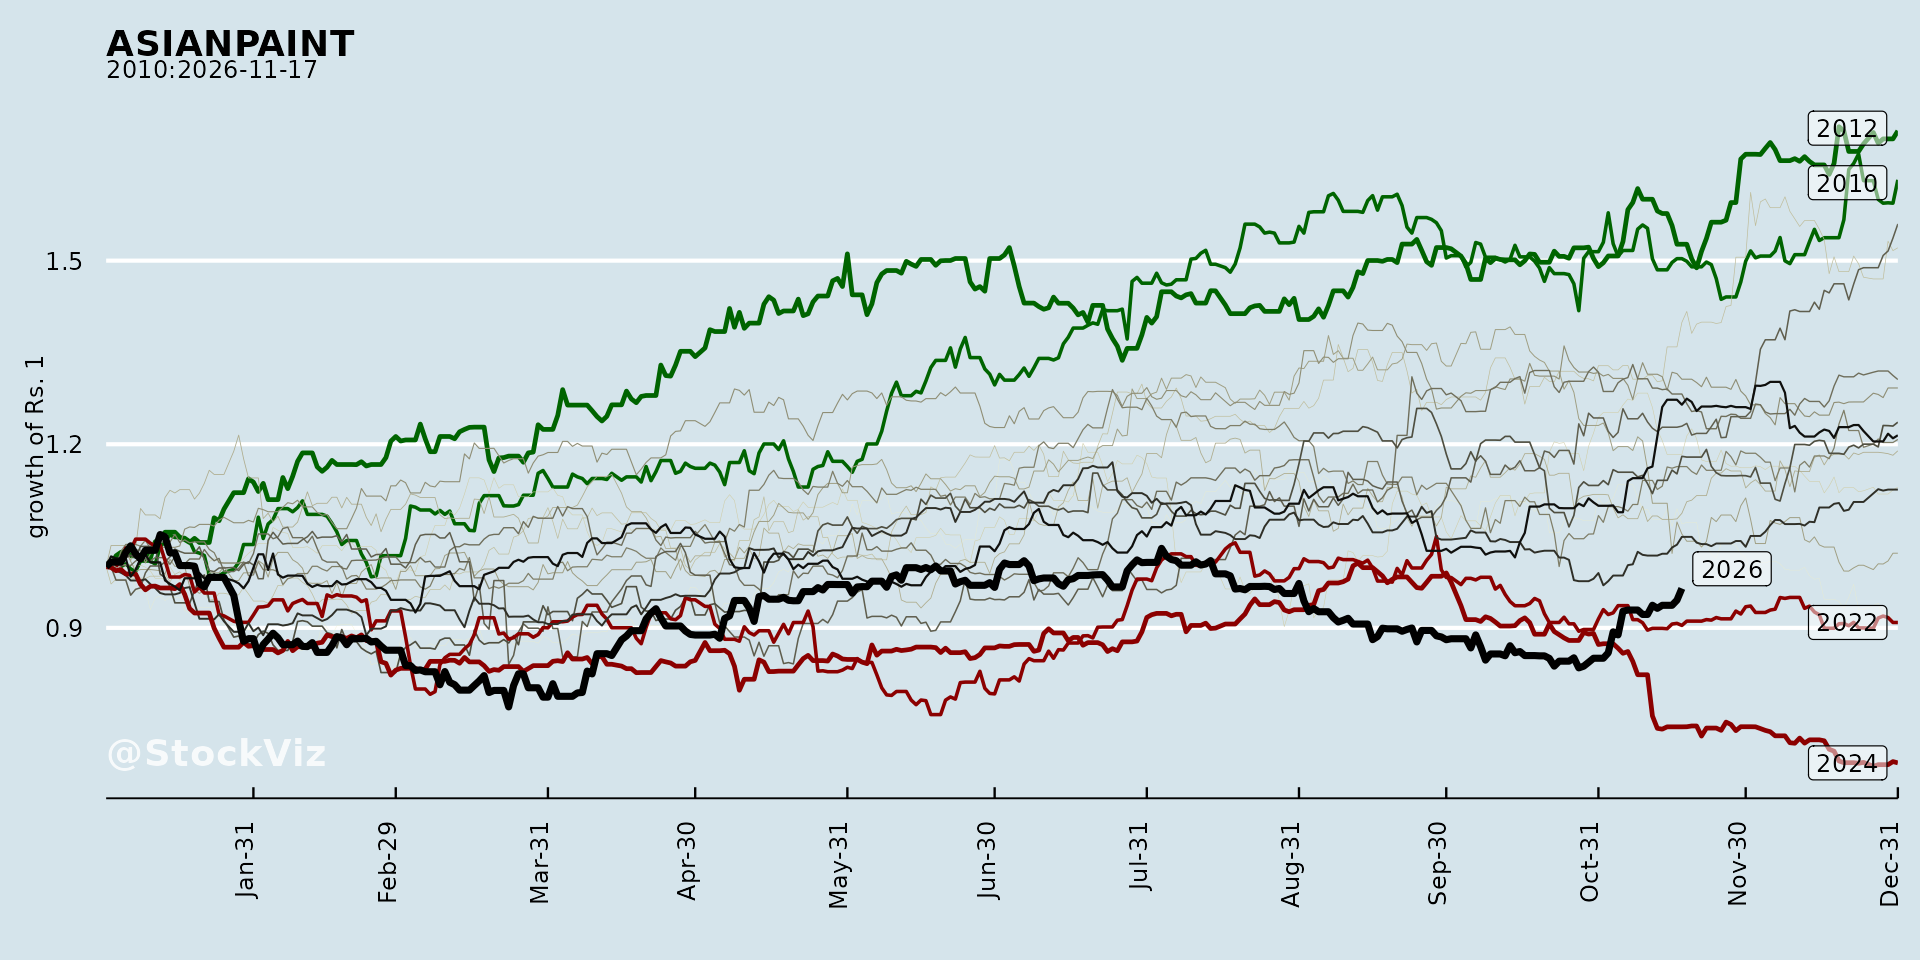
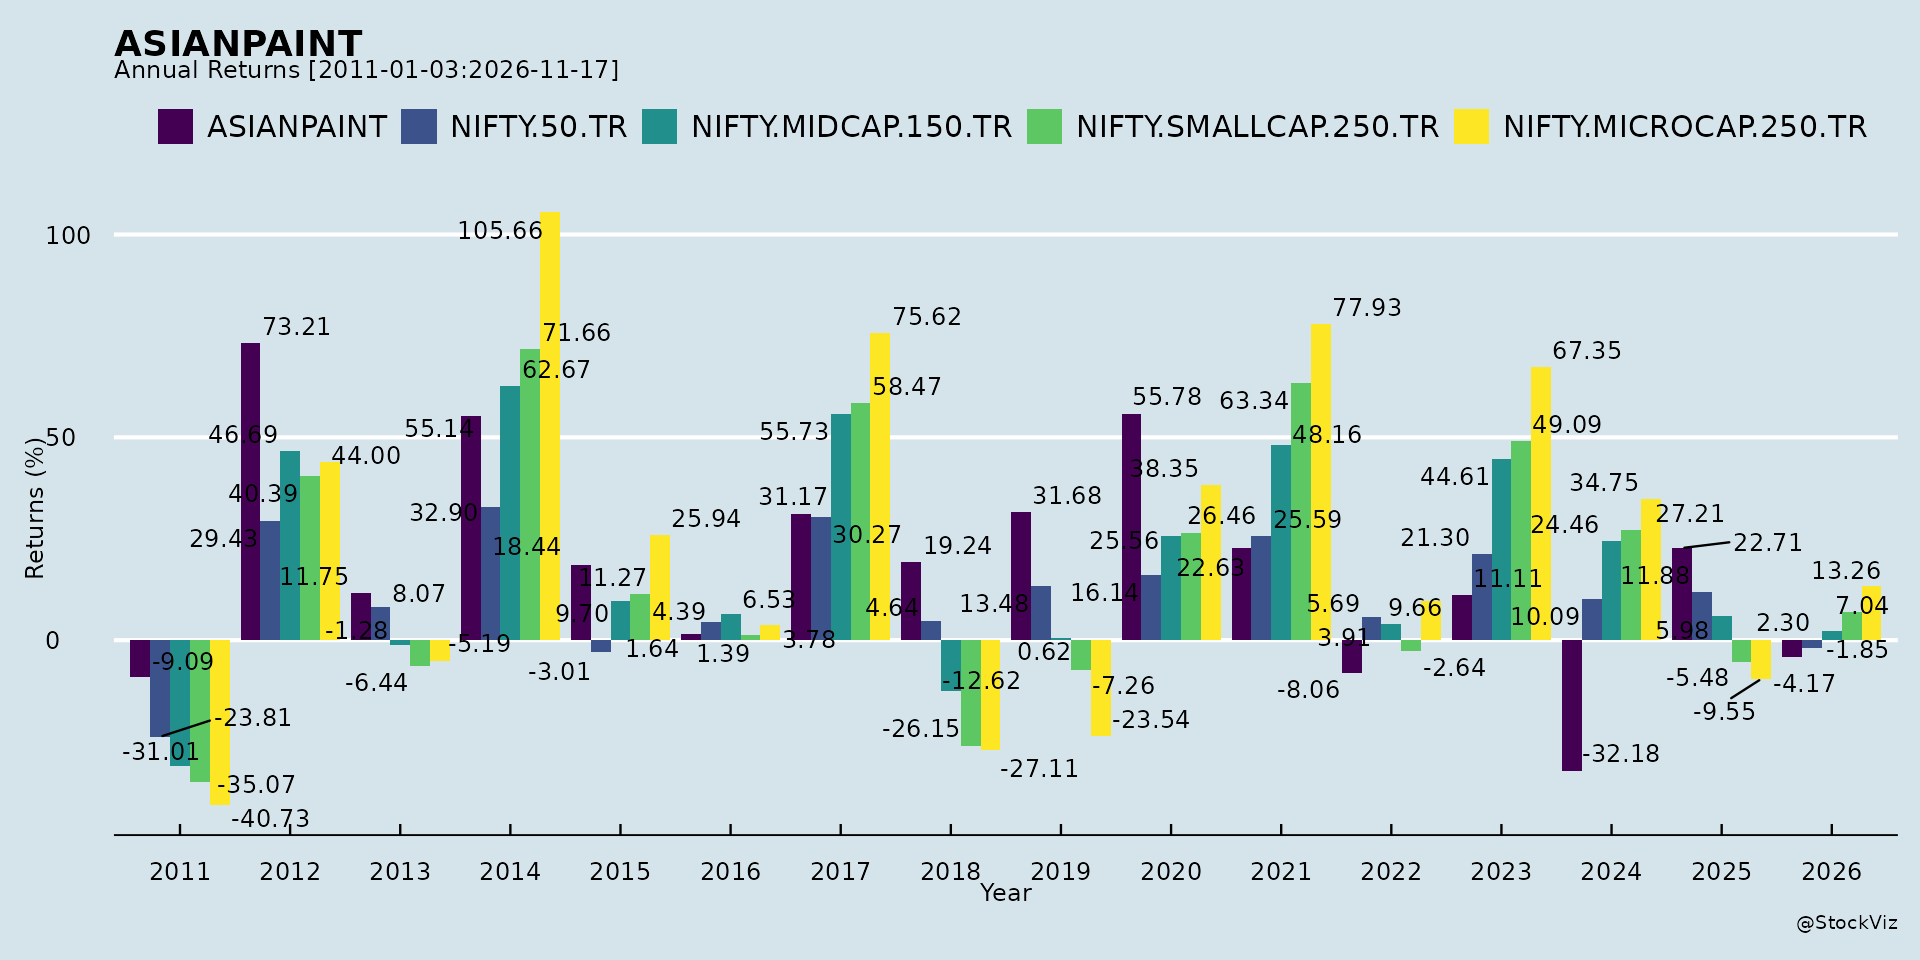
Annual Returns
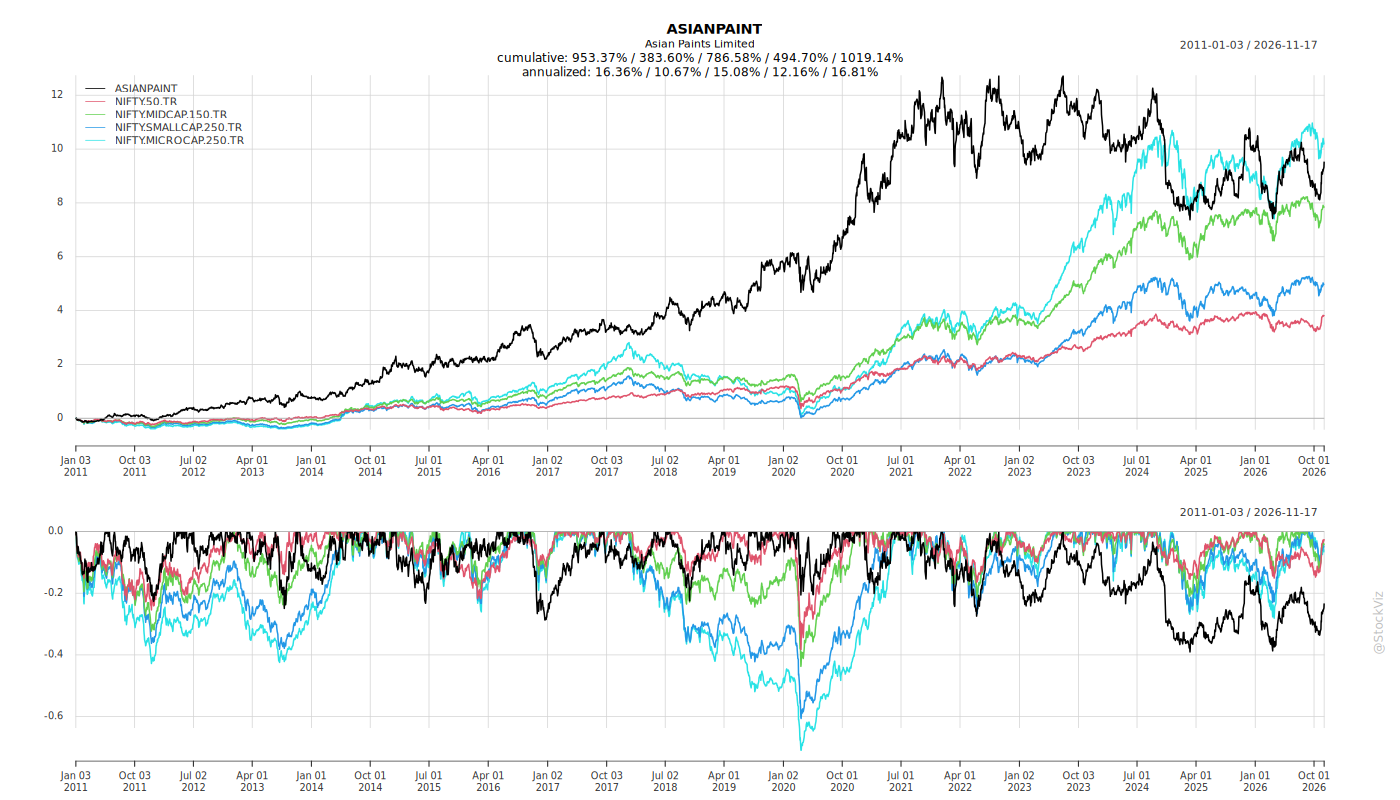
Cumulative Returns and Drawdowns
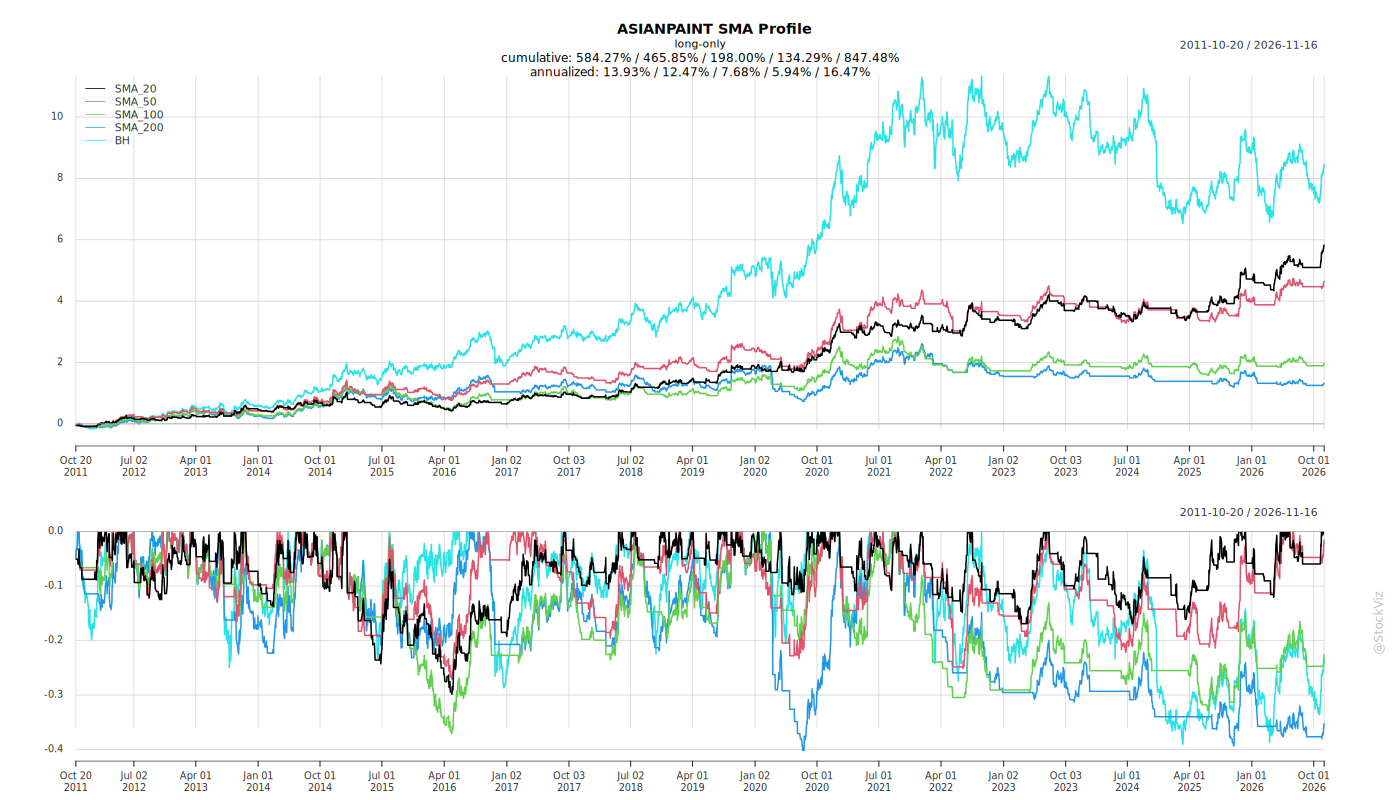
Fundamentals
Ownership
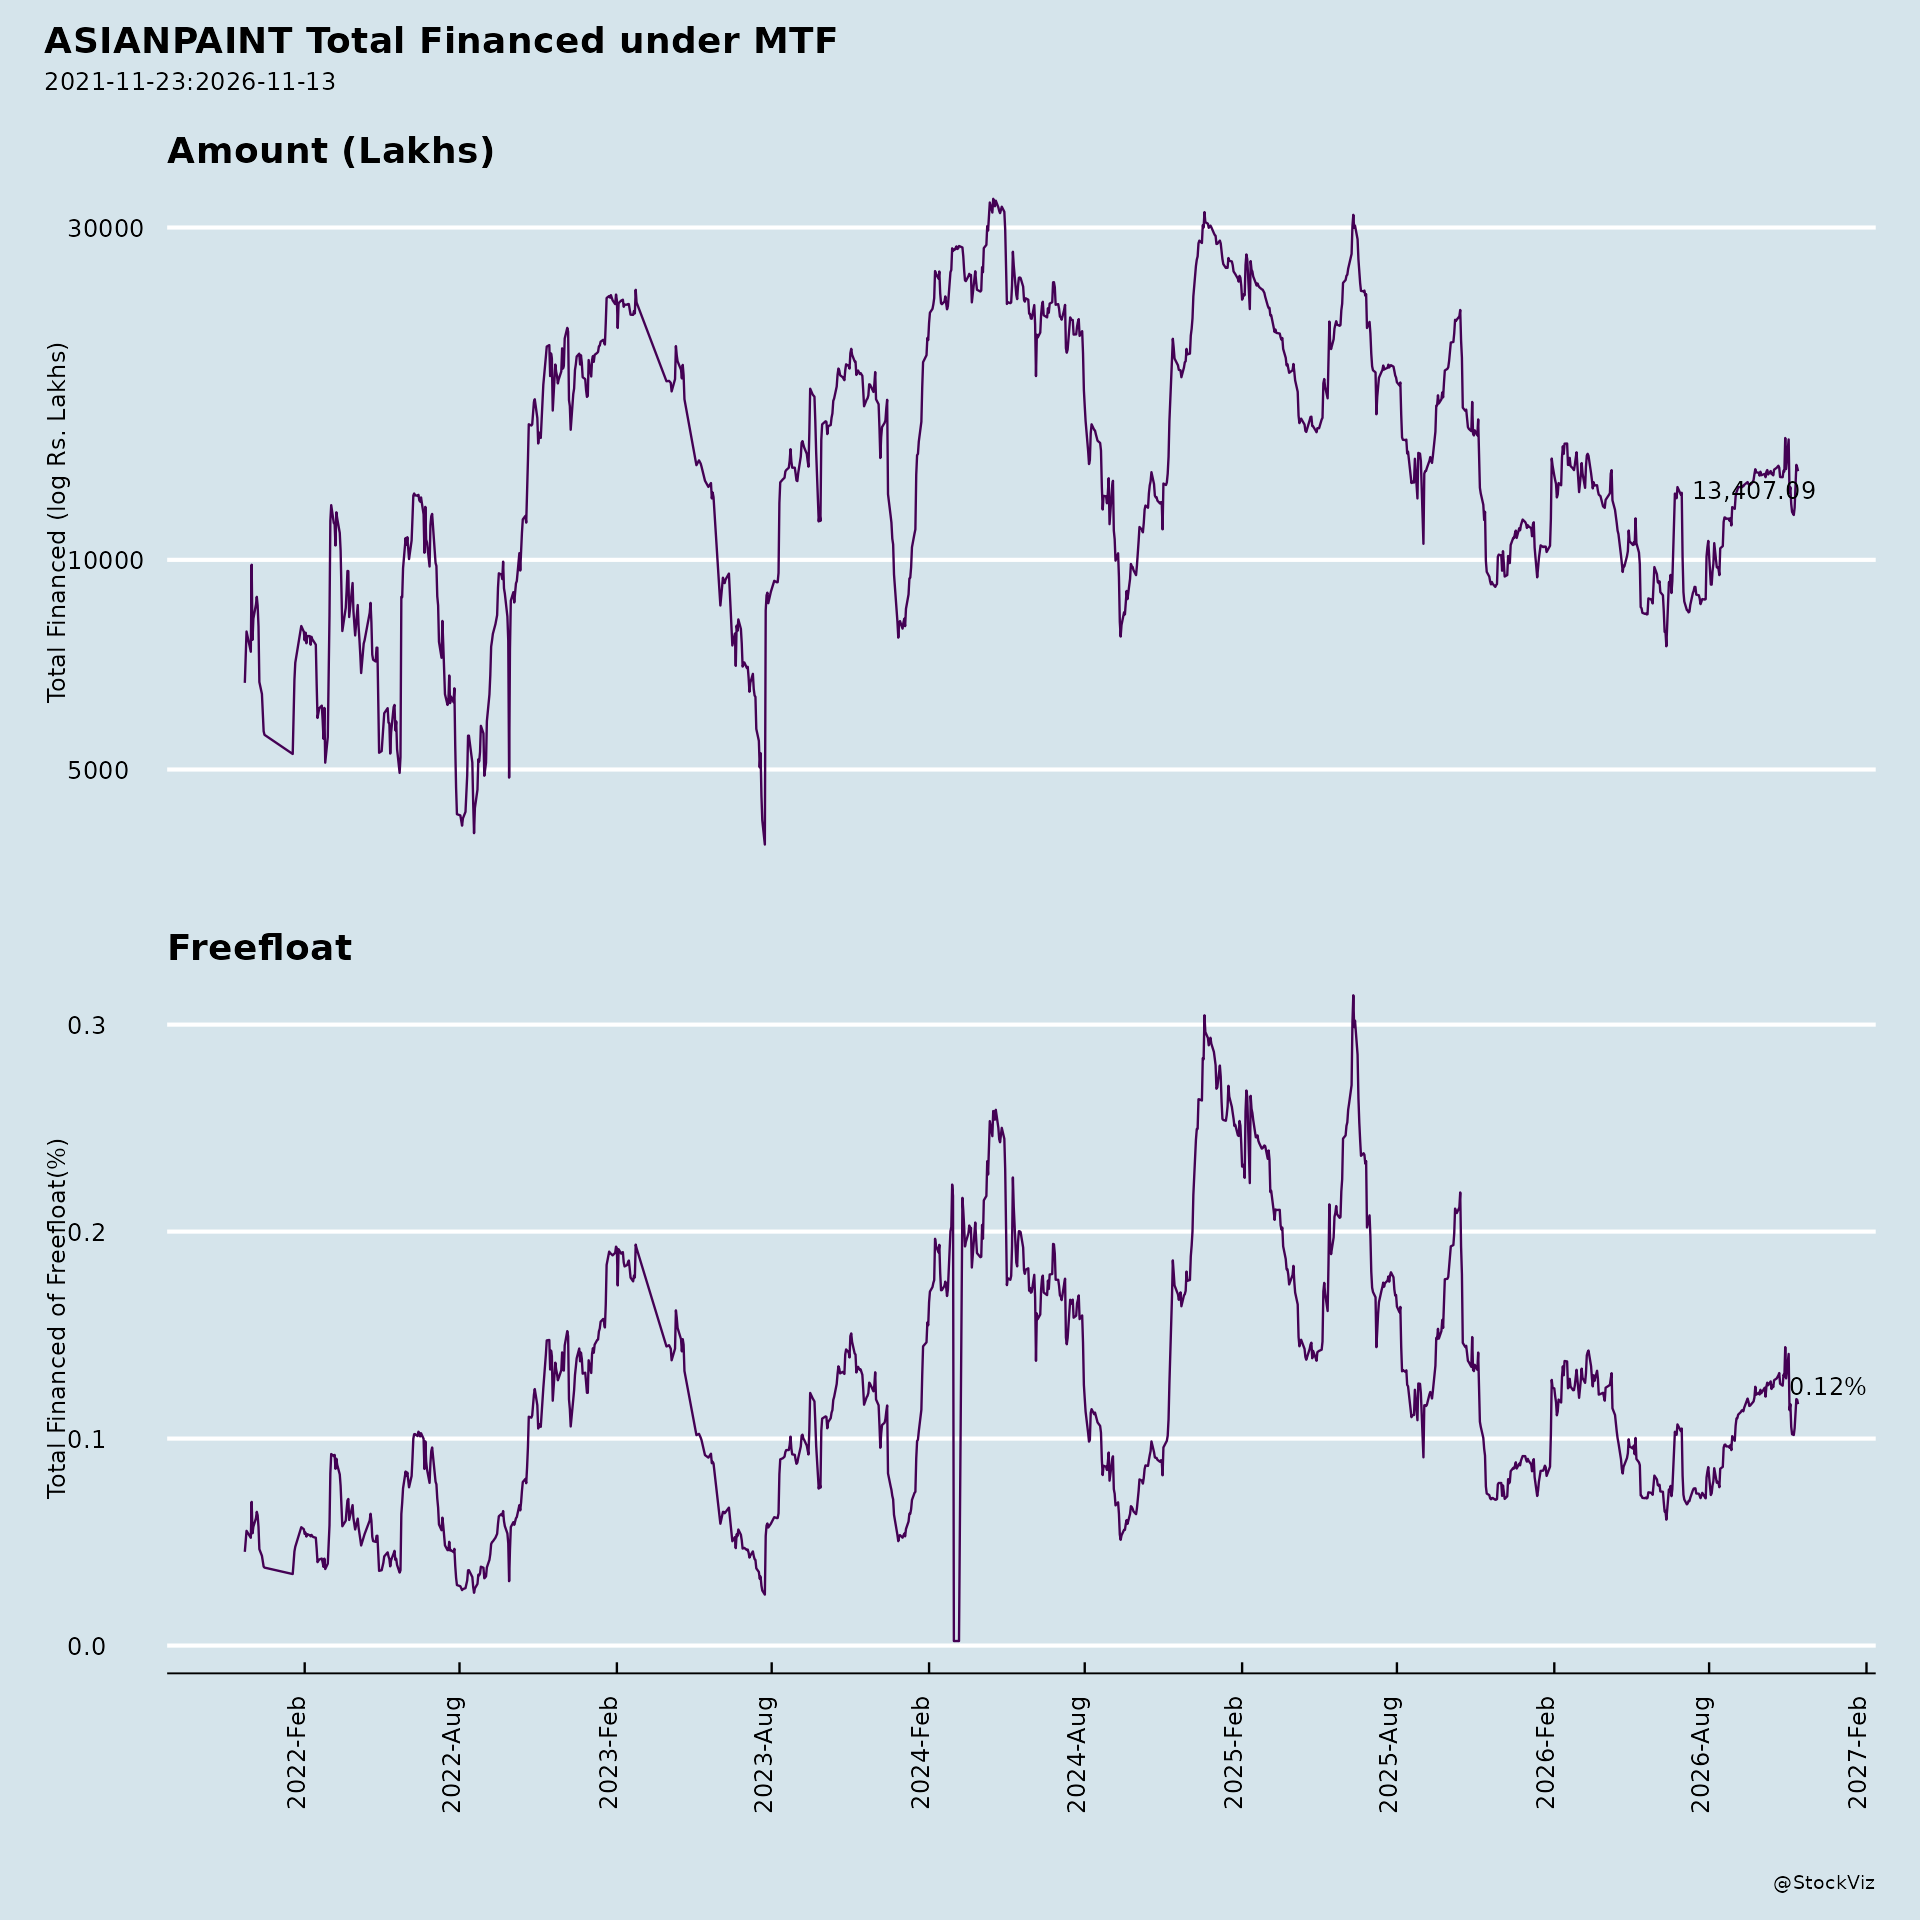
Margined
AI Summary
asof: 2026-09-14
Asian Paints — Q1 FY2027 Corporate Announcements Summary
1. Headwinds and Challenges
- Raw material and supply chain volatility: Management states that “the renewed conflict has intensified volatility across raw material costs and supply chain logistics, keeping the near-term operating environment uncertain.” The standalone gross margin commentary notes that “lower cost inventory & calibrated pricing interventions absorbed the impact of steep inflation,” and the Q1 FY27 gross margin of 43.8% was achieved “despite steep inflation.”
- Competitive intensity: The Q2 FY27 outlook explicitly cites the need to “meet competitive intensity through consumer connect, emotional marketing and technology innovation.”
- Regional conflict affecting international markets: The Middle East performed well “despite market challenges arising from the ongoing conflict in the region.”
- Home Décor segment pressures: Bath Fittings revenue declined 4.3% to ₹84.9 crore, with loss before tax widening to ₹8.8 crore from ₹2.3 crore. White Teak revenue declined 7.4% to ₹18.7 crore.
- Industrial margin compression: PPGAP PBT margin at 15.7% was lower by 119 bps year-on-year; APPPG PBT margin at 6.9% was lower by 114 bps year-on-year.
- ESG rating dispute: NSE Sustainability assigned Asian Paints an ESG rating of 71, placing it in the ‘aspiring’ category (unchanged from the previous year). The company identified “certain factual inaccuracies” in the rating report and has sought a review. The rating was assigned based on publicly available information without company engagement.
2. Tailwinds and Growth Prospects
- Decorative volume and value momentum: Decorative Business (India) delivered volume growth of 9.0% and value growth of 16.6% in Q1 FY27, supported by calibrated pricing actions.
- Broad-based growth: Growth was witnessed across rural and urban markets, with rural markets continuing to grow ahead of urban. B2B Projects business sustained strong momentum across Buildings, Factories and Government segments.
- Premiumization and innovation: New products contributed ~17% of overall revenues. Key launches include Anti-Damp Technology in the economy segment (4-year warranty), Damp Proof dual protection (10-year waterproofing warranty), WoodTech Emporio Orano (8-year warranty), and region-inspired editions (ACE and Tractor Royale, Tribute to Andhra Pradesh and Telangana).
- Services as differentiator: Flagship direct-to-consumer service, waterproofing services for B2B, and AI-led tools (AI Visualizer, AI-led Supervision, AI NPS) are being positioned as differentiators.
- Backward integration: Construction of India’s first integrated VAM-VAE manufacturing ecosystem is underway, with the first phase to be commissioned by Q2 FY27. Annual production capacity of 100,000 MT (VAM) and 150,000 MT (VAE). Management expects this to “meaningfully strengthen our ability to develop and launch differentiated product propositions.”
- International business: Net Sales grew 27.2% in INR terms (20.3% in constant currency), led by Egypt, UAE, Oman, Nepal and Bangladesh. PBT margin expanded 275 bps to 7.9%. New product launches include Royale Stellar (UAE, Bahrain, Oman) and Acrycoat Novi (Egypt).
- Home Décor network: 74 Beautiful Homes stores/studios. Kitchen business revenue up 10.1% to ₹108 crore with PBT loss narrowed to near break-even (₹0.3 crore vs ₹8.8 crore loss in Q1 FY26). Weatherseal revenue up 11.2% to ₹16.9 crore.
- Industrial business: APPPG revenue up 21.3% to ₹372.9 crore; PPGAP revenue up 13.5% to ₹651.9 crore.
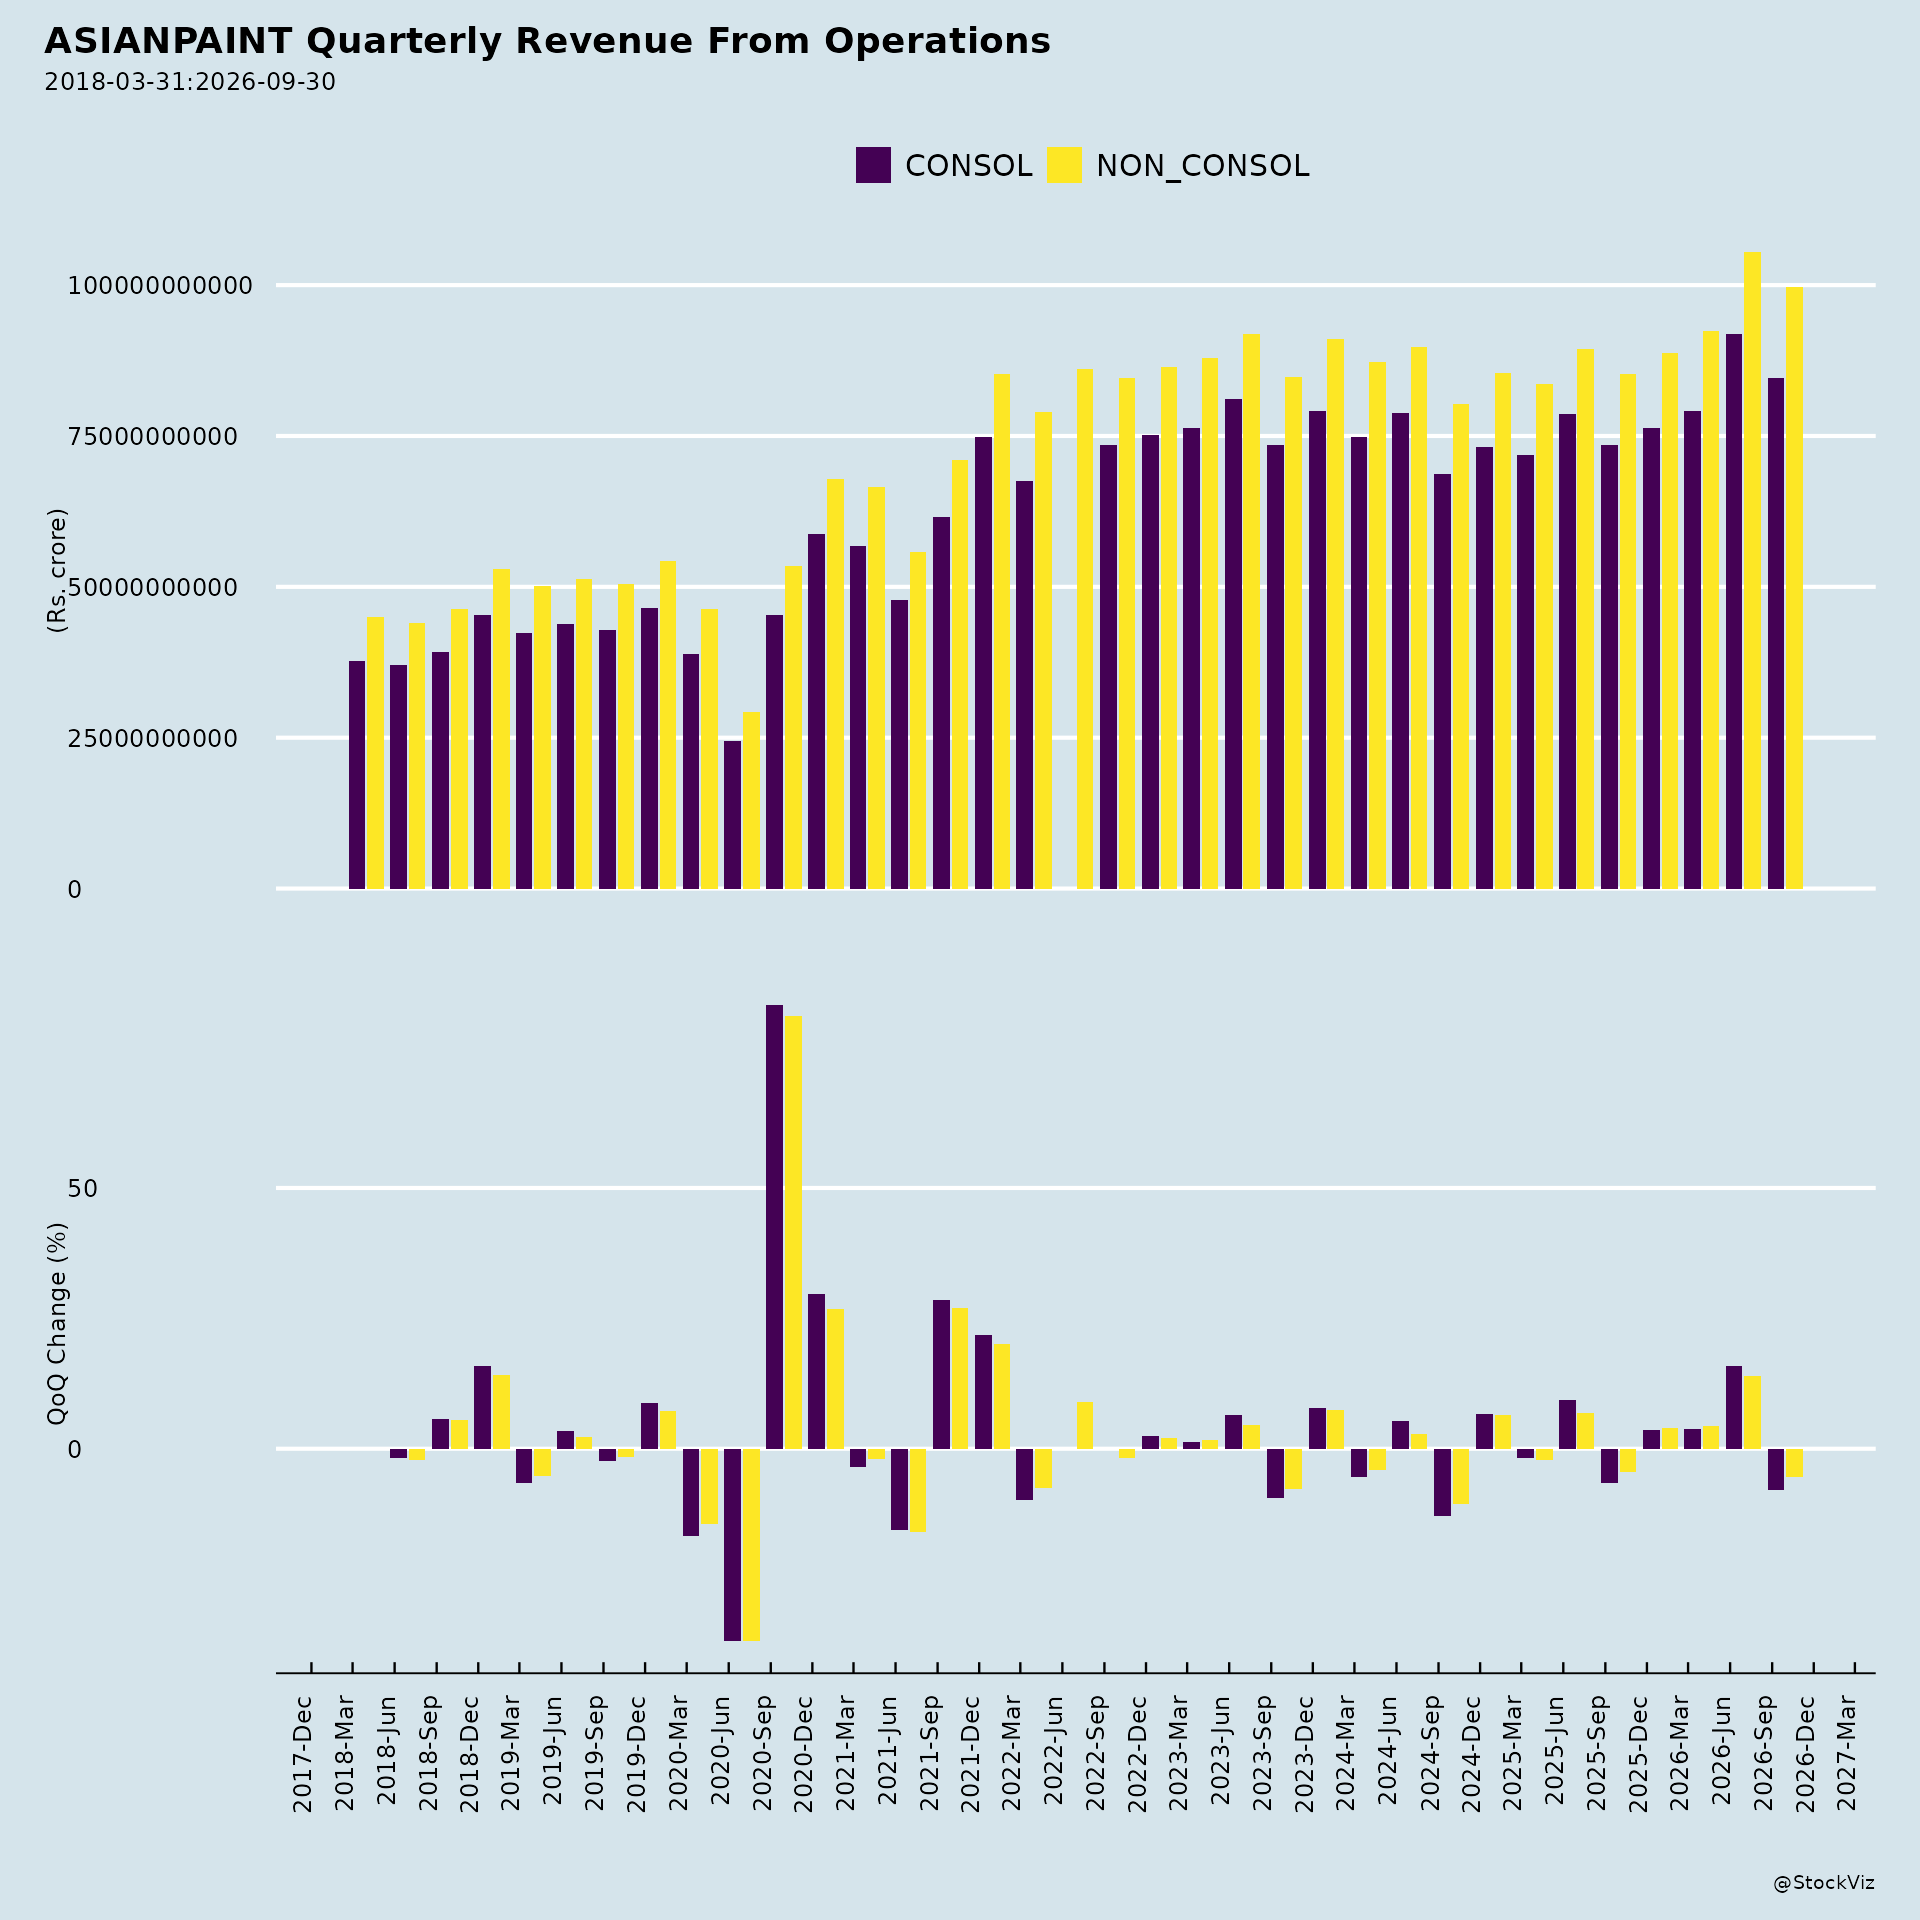
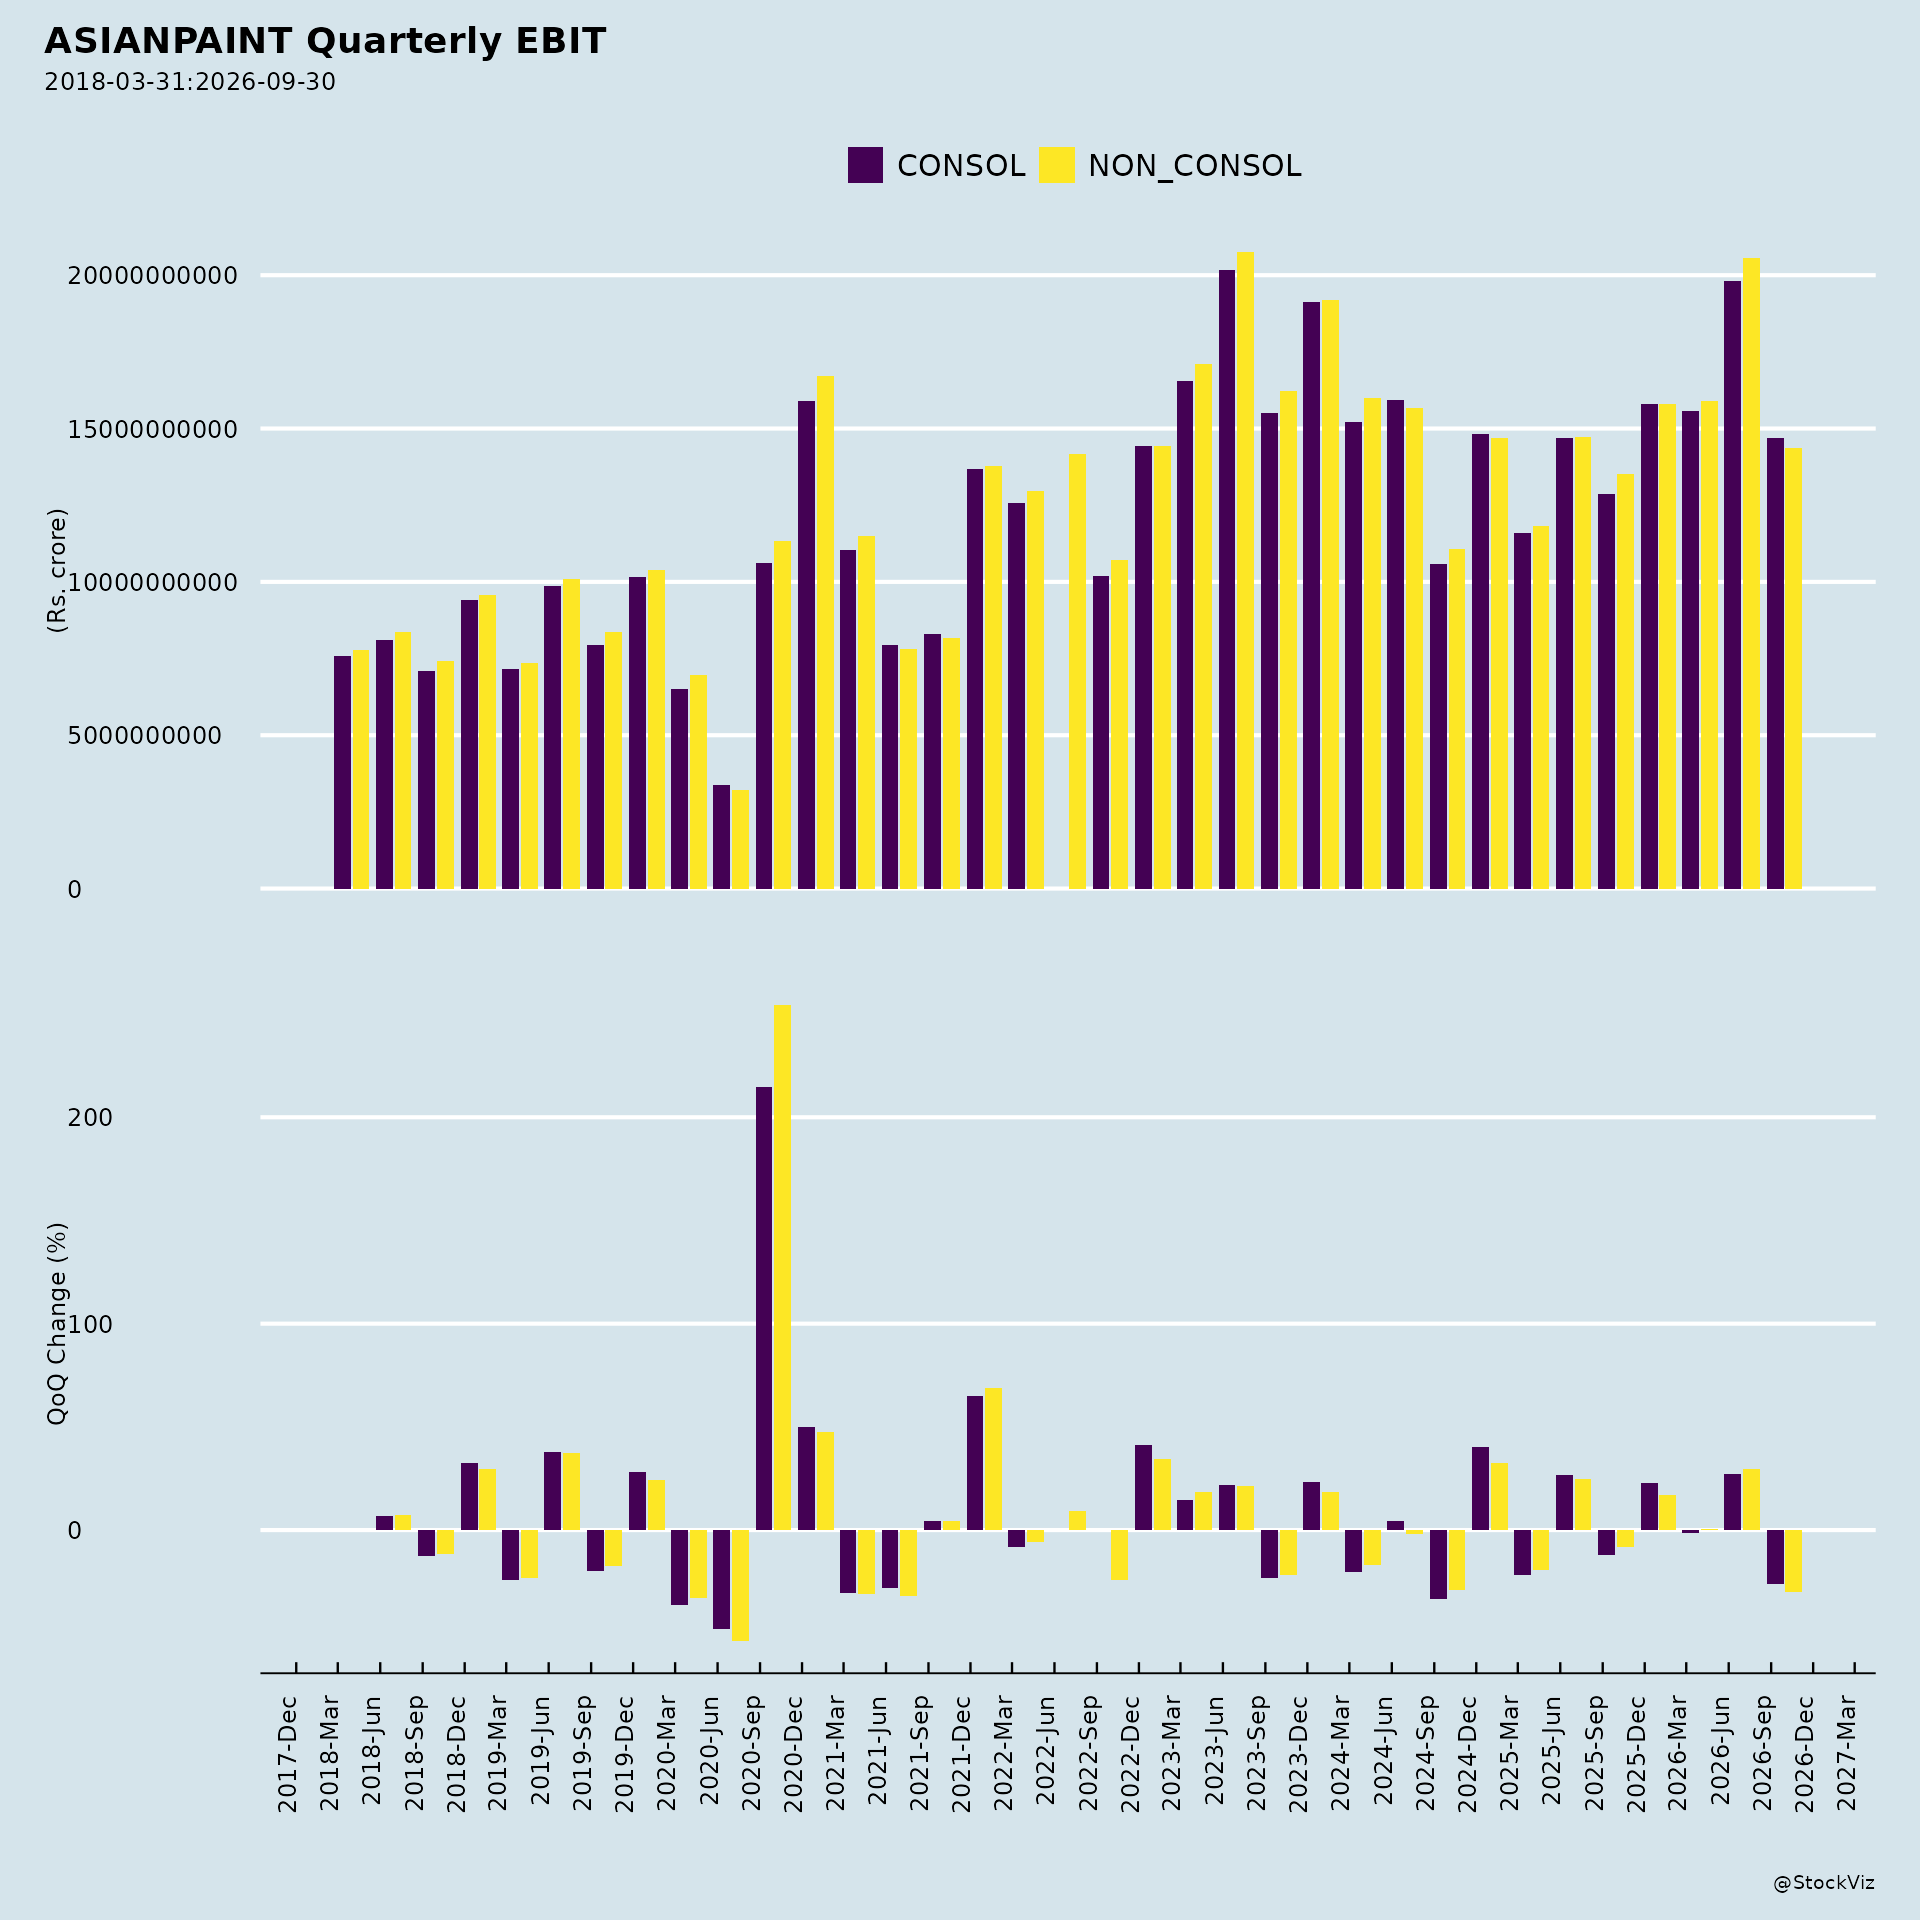
- Financial performance: Consolidated Net Sales up 17.9% to ₹10,521.4 crore; PBDIT margin at 20.6% (+240 bps); PBT up 38.9%; Net Profit after minority interest up 40.0%. Standalone Net Sales up 16.7% to ₹9,156.5 crore; PBDIT margin at 22.0% (+259 bps); PAT up 34.3%.
3. Key Risks
- Forward-looking statement risk: The company’s disclaimer notes that future involves “many risks and uncertainties that could cause actual results to differ materially from the current views being expressed,” including general economic conditions, foreign exchange and commodity price fluctuations, competitive product and pricing pressures, and regulatory developments.
- Raw material inflation: Steep inflation in raw materials is noted, with volatility intensified by the renewed conflict.
- Supply chain logistics: Volatility across supply chain logistics is cited as keeping the near-term operating environment uncertain.
- Competitive pressures: Explicitly referenced as a factor to manage in Q2 FY27.
- Geopolitical/regional conflict: Ongoing conflict in the Middle East is noted as creating market challenges, despite strong performance there.
- ESG rating accuracy: The company has flagged factual inaccuracies in the NSE Sustainability ESG rating report and sought a review; any revision will be disclosed to stock exchanges in due course.
4. Management Guidance vs. Observed Business Performance
- Q2 FY27 outlook (guidance): Management states the priority is to “sustain growth momentum and meet competitive intensity through consumer connect, emotional marketing and technology innovation.” Key priorities include: executing with speed and discipline across markets; stepping up investment in innovation and brand-building; and driving cost efficiencies to absorb external pressures, protect margins and safeguard demand momentum. Management also notes the near-term operating environment remains uncertain due to raw material and supply chain volatility.
- VAM-VAE commissioning guidance: First phase to be commissioned by Q2 FY27. No observed performance data yet, as commissioning is forward-looking.
- Observed Q1 FY27 performance vs. stated priorities: The company delivered strong revenue growth driven by healthy volume growth and pricing action, with a good mix and strong focus on premiumization. Growth was broad-based across rural and urban markets. B2B Projects sustained strong momentum. Distribution reach and network depth continued to be enhanced. Innovation-led propositions gained traction, with new products contributing ~17% of overall revenues. These outcomes align with the stated strategic priorities of innovation, premiumization, distribution expansion, and B2B growth.
- International business guidance vs. performance: Management noted the Middle East performed particularly well despite market challenges. Observed performance: International Net Sales grew 27.2% in INR terms (20.3% constant currency), with PBT margin expansion of 275 bps, led by Egypt, UAE, Oman, Nepal and Bangladesh.
- Home Décor guidance vs. performance: Management stated Home Décor continued to make steady progress through the Beautiful Homes network. Observed performance: Kitchen revenue up 10.1% with loss narrowed to near break-even; Bath Fittings revenue down 4.3% with increased loss; White Teak down 7.4%; Weatherseal up 11.2%.
- Profitability guidance vs. performance: Management attributed strong profitability to measured price increases, better mix, formulation and sourcing efficiencies, and disciplined cost management. Observed: Standalone PBDIT margin at 22.0% (+259 bps yoy); Consolidated PBDIT margin at 20.6% (+240 bps yoy); Standalone gross margin at 43.8% (+66 bps yoy); Consolidated gross margin at 43.5% (+89 bps yoy).
5. Key Investor Facts
- Board meeting and results approval: The Board of Directors met on Wednesday, 29 July 2026, and approved audited standalone and unaudited consolidated financial results for the quarter ended 30 June 2026. The board meeting commenced at 9:30 a.m. IST and continued until its scheduled time up to 4:00 p.m. IST.
- Investor conference: The company held an investor conference at 5:00 p.m. IST on Wednesday, 29 July 2026, where management commented on business and financial performance.
- Auditor: S R B C & CO LLP, Chartered Accountants, is the statutory auditor. The standalone results were audited; the consolidated results were subject to a limited review. The auditor’s report on standalone results gives a true and fair view; the review report on consolidated results states nothing came to attention causing belief that the statement contains material misstatement.
- Dividend: Final dividend of ₹23.00 per equity share of face value ₹1 each for FY2025-26 was approved by shareholders at the AGM held on 9 July 2026 and paid on 13 July 2026.
- Segment reporting: The company is primarily engaged in the business of ‘Paints and Decor’. There is no separate reportable segment as per Ind AS 108.
- Subsidiaries and associates: The consolidated statement includes 25 subsidiaries and 3 associates. Of the subsidiaries, 3 were reviewed by independent auditors (total revenues ₹365.10 crore, net profit after tax ₹40.18 crore); 15 were not reviewed by auditors (total revenues ₹183.47 crore, net profit after tax ₹33.34 crore), which management states are not material to the Group.
- Postal ballot resolution: Members of Asian Paints Limited approved the ordinary resolution for the appointment of Ms. Shubhlakshmi Dani as a Non-Executive Director liable to retire by rotation through postal ballot remote e-voting with the requisite majority.
- Jefferies India Forum: Asian Paints Limited is participating in the Jefferies 5th India Forum on Wednesday, 16 September 2026, from 11:00 a.m. onwards in Gurugram, involving Group & One-on-One meetings. No unpublished price sensitive information will be shared.
- ESG rating: NSE Sustainability Ratings & Analytics Ltd. independently assigned Asian Paints an ESG rating of 71, placing the company in the ‘aspiring’ category, unchanged from the previous assessment year. The rating was assigned based on publicly available information without company engagement. Asian Paints has requested a review due to factual inaccuracies; any revision will be disclosed to the stock exchanges in due course.
- Market capitalization: Approximately ₹2,528 billion as on 30 June 2026.
- Global footprint: Operations in 14 countries across the world with 25 paint manufacturing facilities, servicing consumers in over 60 countries through brands including Asian Paints, Apco Coatings, Asian Paints Berger, Asian Paints Causeway, SCIB Paints, Taubmans and Kadisco Asian Paints.
- Consolidated turnover FY26: ₹35,516 crore (₹355 billion).
- Home Décor positioning: No. 1 Integrated Home Décor Player; No. 1 in Modular Kitchen, Kitchen, Bath Fittings & Sanitaryware, Fabrics & Furnishings, Hardware & Components, Lighting; No. 2 in Wardrobes and Vanities, Furniture, Wall Coverings; No. 1 in Decorative Lighting, Rugs, uPVC Windows and Doors. 74 Beautiful Homes stores/studios. Collaborations with Sabyasachi, Jaipur Rugs, Sarita Handa.
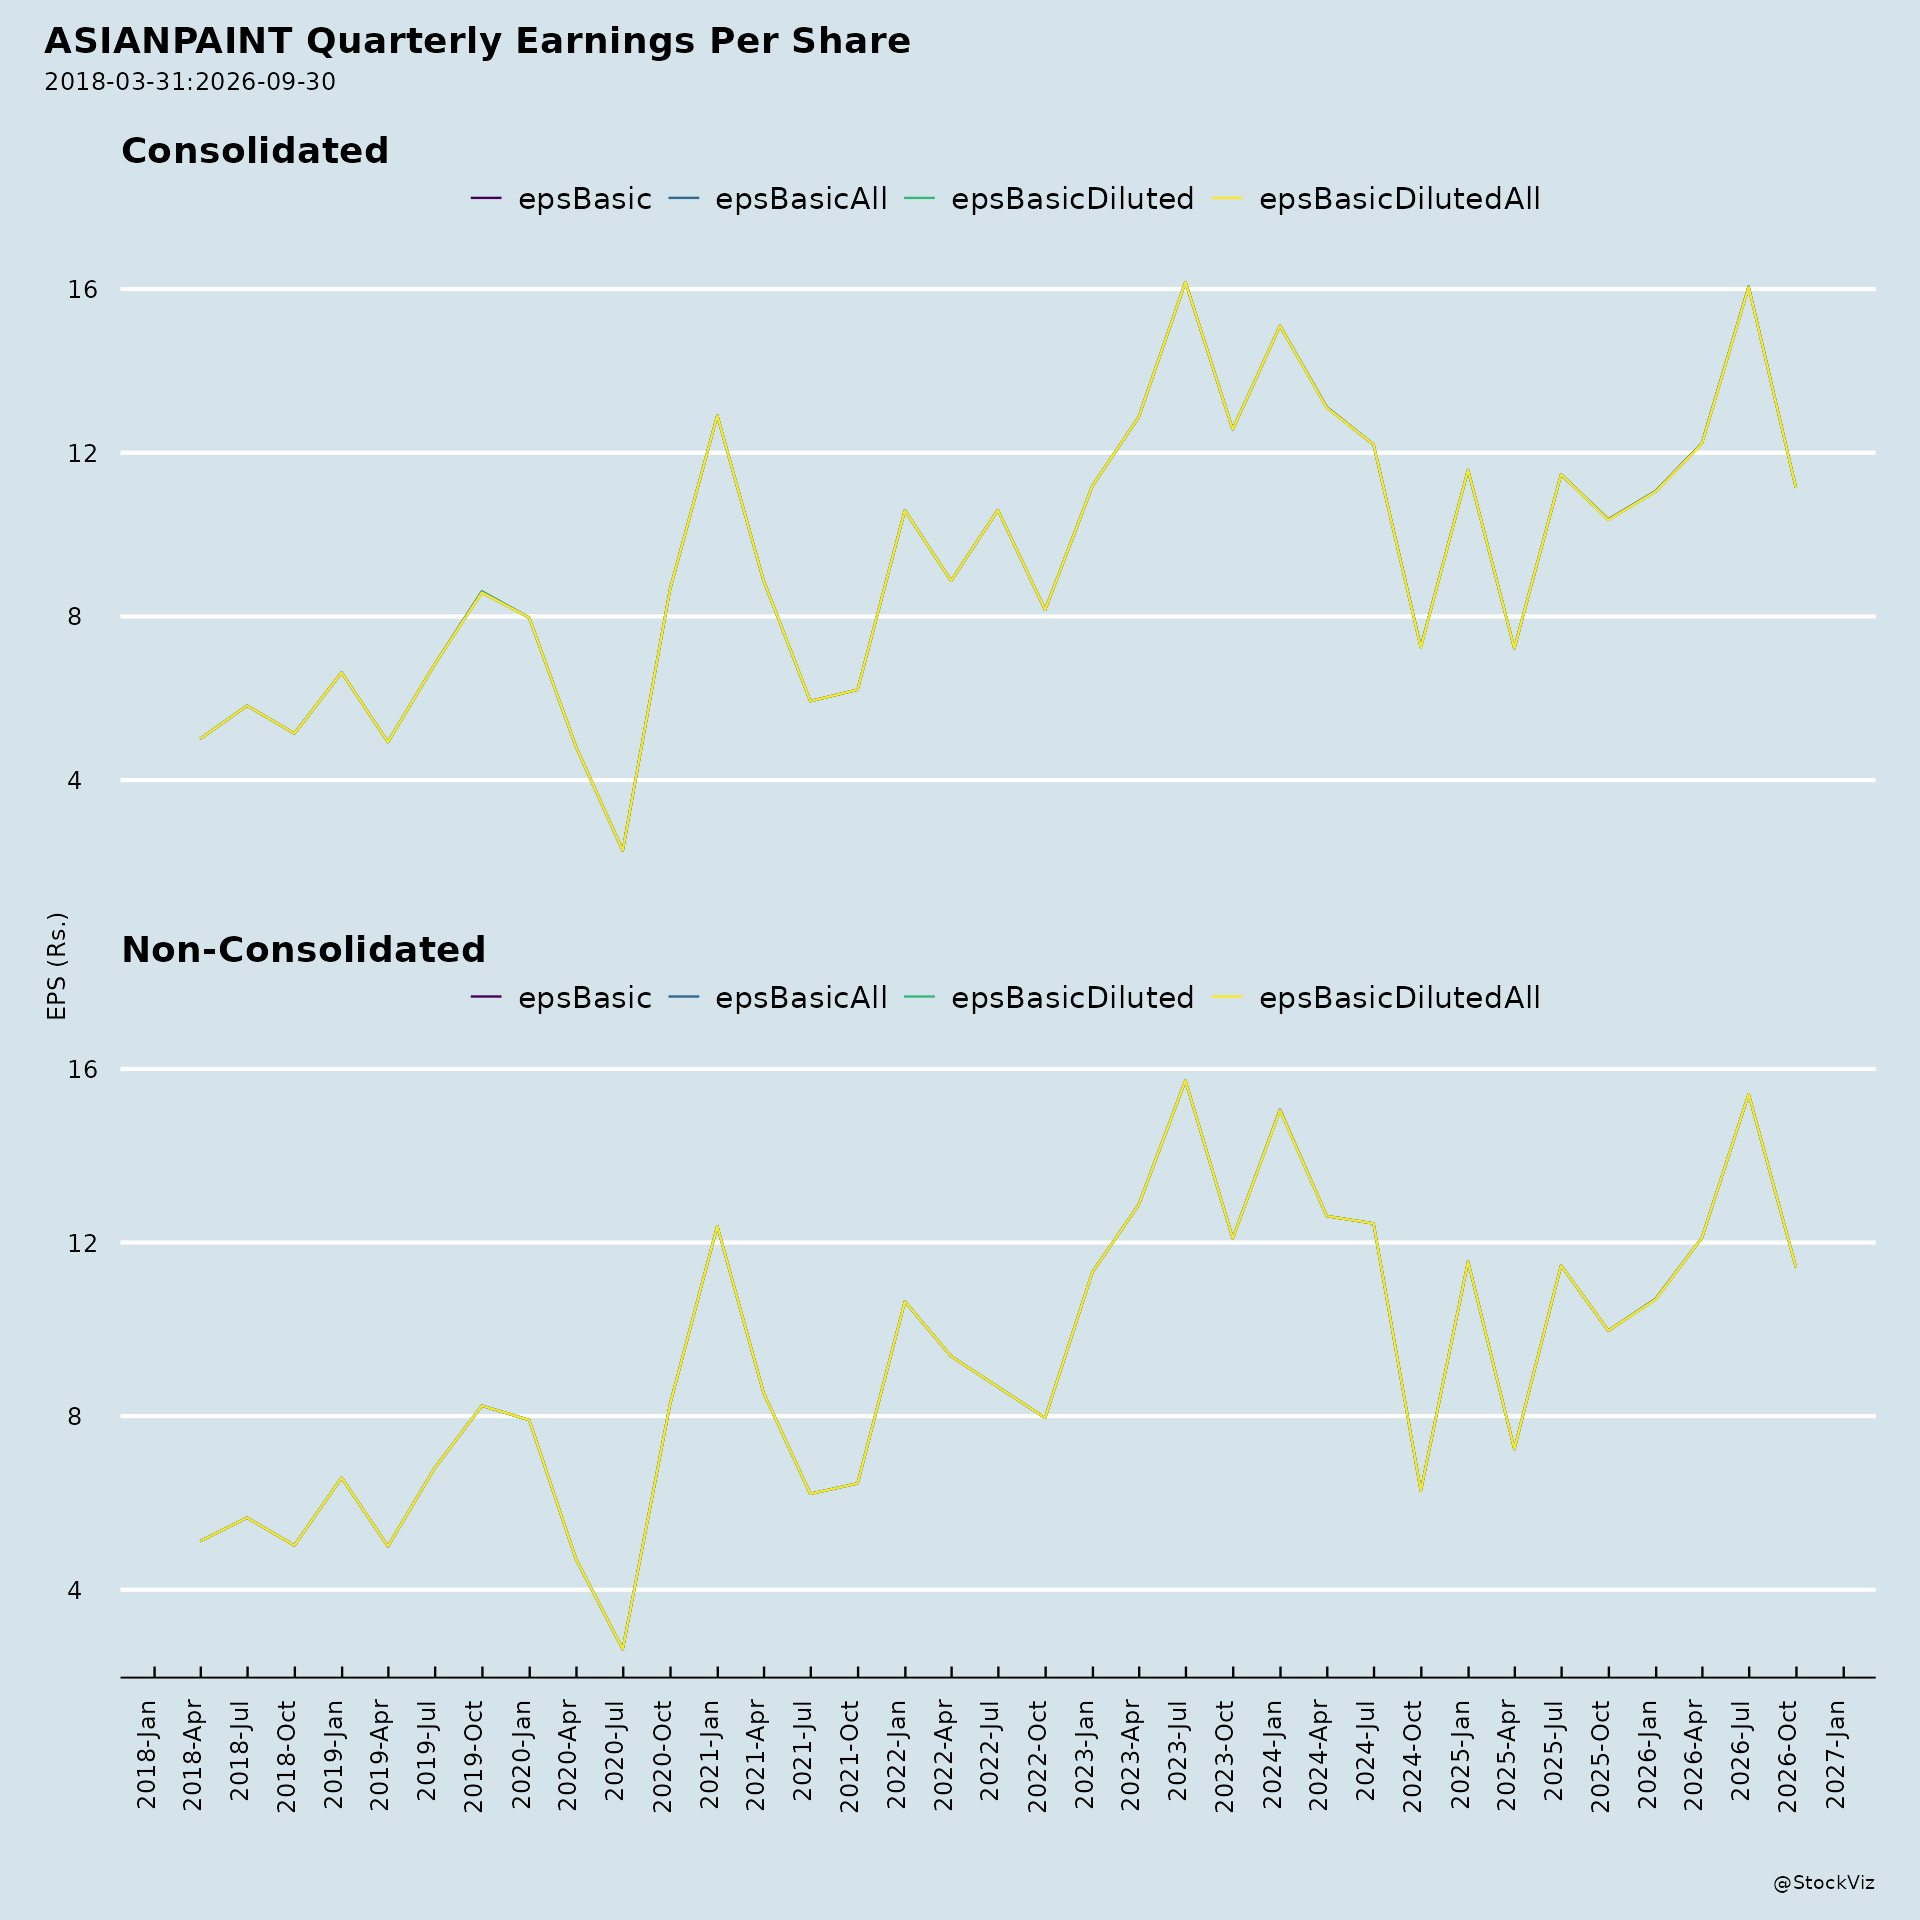
- Earnings per share: Standalone basic and diluted EPS at ₹15.42 (not annualised) for Q1 FY27, compared to ₹11.48 in Q1 FY26. Consolidated basic EPS at ₹16.06 and diluted EPS at ₹16.05 (not annualised) for Q1 FY27, compared to ₹11.47 in Q1 FY26.
- Paid-up equity share capital: ₹95.92 crore (face value ₹1 per share).
- Other equity (standalone): ₹20,685.64 crore as at 31 March 2026.
- Other equity (consolidated): ₹21,275.67 crore as at 31 March 2026.
Broker Narrative
The 2023 report was a bullish Accumulate/Buy thesis built on sustained double-digit decorative volume growth, margin expansion from raw-material deflation, distribution and premium/home-decor expansion, and strength in industrial JVs and international markets, while flagging new competition (Grasim/JSW), segment-level demand softness, TiO2 cost spikes, and a stretched ~51x valuation as risks. Through 2023-2024 the stock de-rated sharply (actuals of -11% to -29%), so Neutral/Reduce calls prevailed and most bullish calls DISAPPOINTED. By the 2026 Buy call, raw-material inflation had reversed the margin story and urban demand had hardened into an explicit headwind, yet the core optimism persisted, now anchored on volume recovery, industrial/international strength, price hikes, and VAE backward integration. The through-line is that competition and valuation concerns faded from the headline risks while raw-material and demand worries intensified and matured into margin-defense and pricing-power themes.
Fears that came true
- Raw material price spikes (TiO2): the 2023 TiO2 cost-pressure flag escalated into ~28% H1FY27 raw-material inflation plus a TiO2 anti-dumping duty, coinciding with the heavy 2023-2024 underperformance where bullish calls DISAPPOINTED with actuals of -11% to -29%.
- Demand slowdown in specific segments: the Q4FY23 weakness in non-paint home segments (Kitchen -23.4%, Bath -11.9% YoY) broadened into the urban decorative demand slowdown still flagged in 2026, consistent with poor returns across 2023-2024.
- Valuation & capex overheads: the 51.1x FY25E P/E concern played out as a sharp de-rating, with essentially every 2023-2024 Accumulate/Buy call predicting +7% to +26% turning into DISAPPOINTMENTs at -6% to -29% actuals.
- Emerging competition (Grasim/JSW): flagged at entry, it is consistent with the prolonged structural underperformance across 2023-2024, where dozens of positive-return predictions DISAPPOINTED.
Optimism that failed
- Margin expansion from raw-material deflation: the 2023 view that deflation would keep expanding margins (GM 42.5%, EBITDA 21.2%) failed as ~28% raw-material inflation reversed it, forcing price hikes and VAE backward integration just to defend EBITDA at 18-20% by FY27.
- Sustained robust volume growth: the 16% YoY decorative volume-growth optimism did not hold, with urban demand now a headwind and decorative volume growth guided down to only 8-9% for H2FY27.
Broker Timeline
81 broker calls · 2023-05-11 to 2026-10-31
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.