ASHOKLEY
Equity Metrics
November 16, 2026
Ashok Leyland Limited
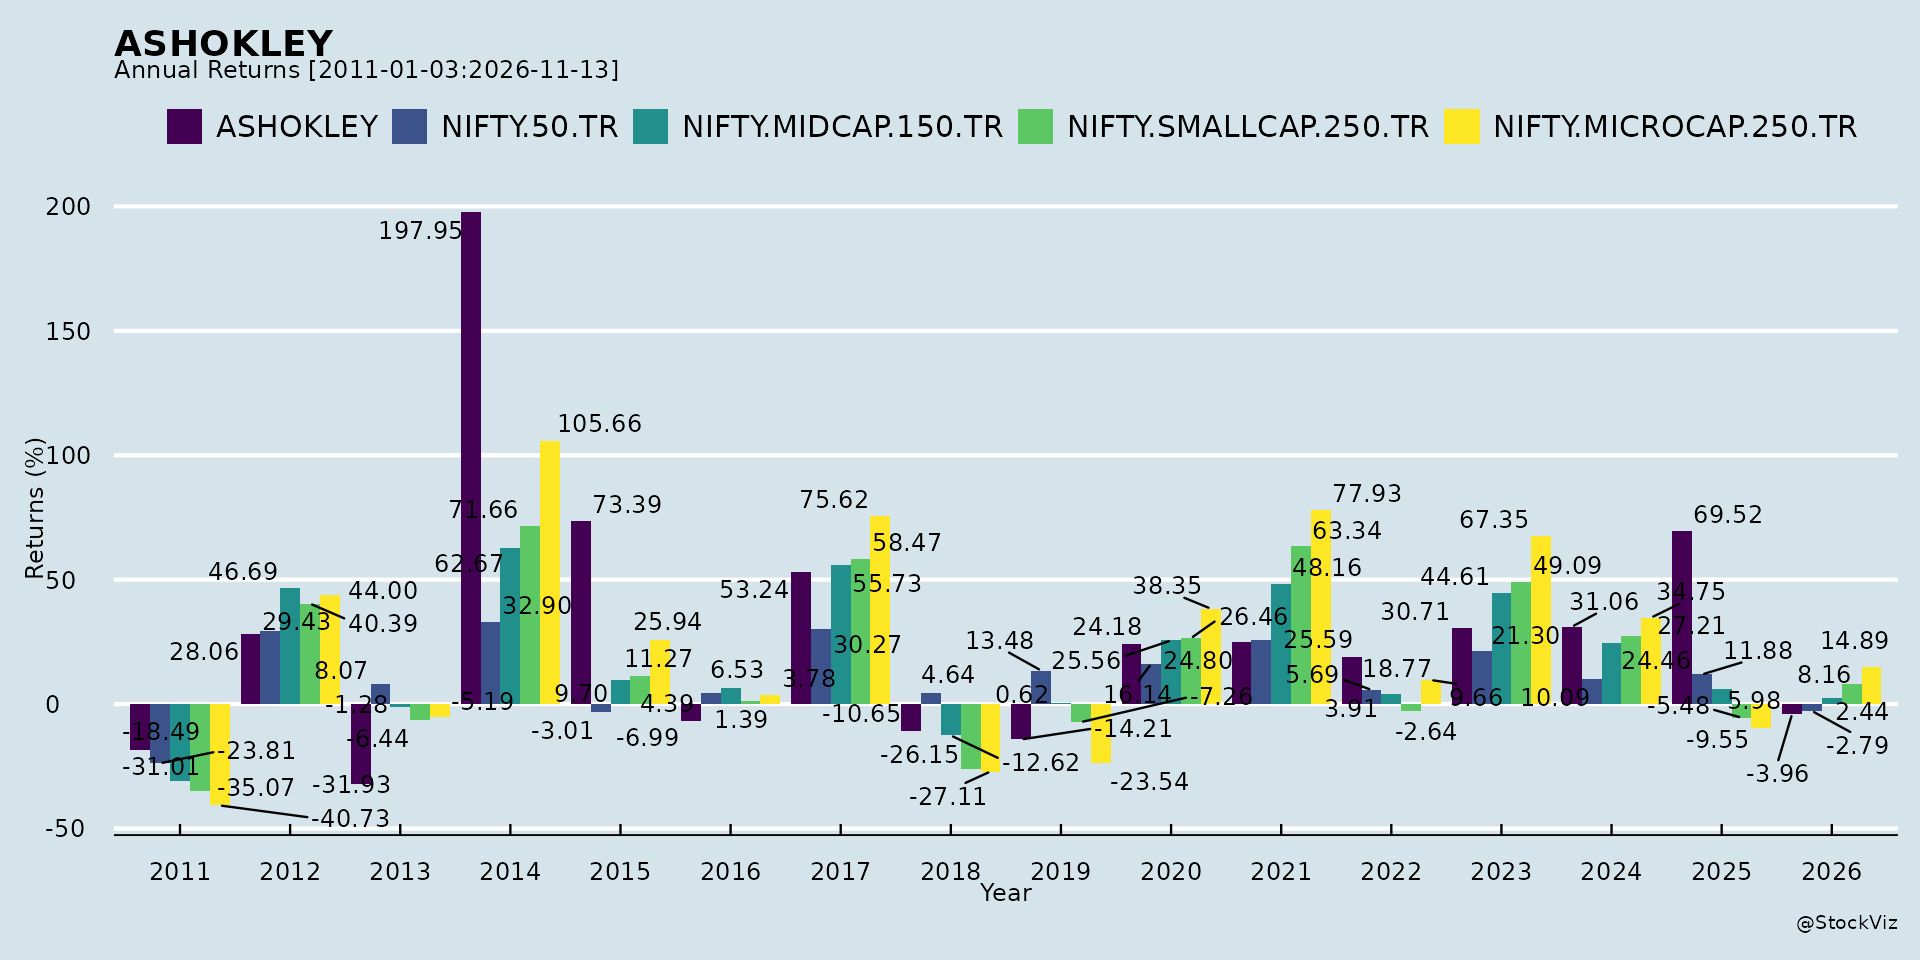
Annual Returns
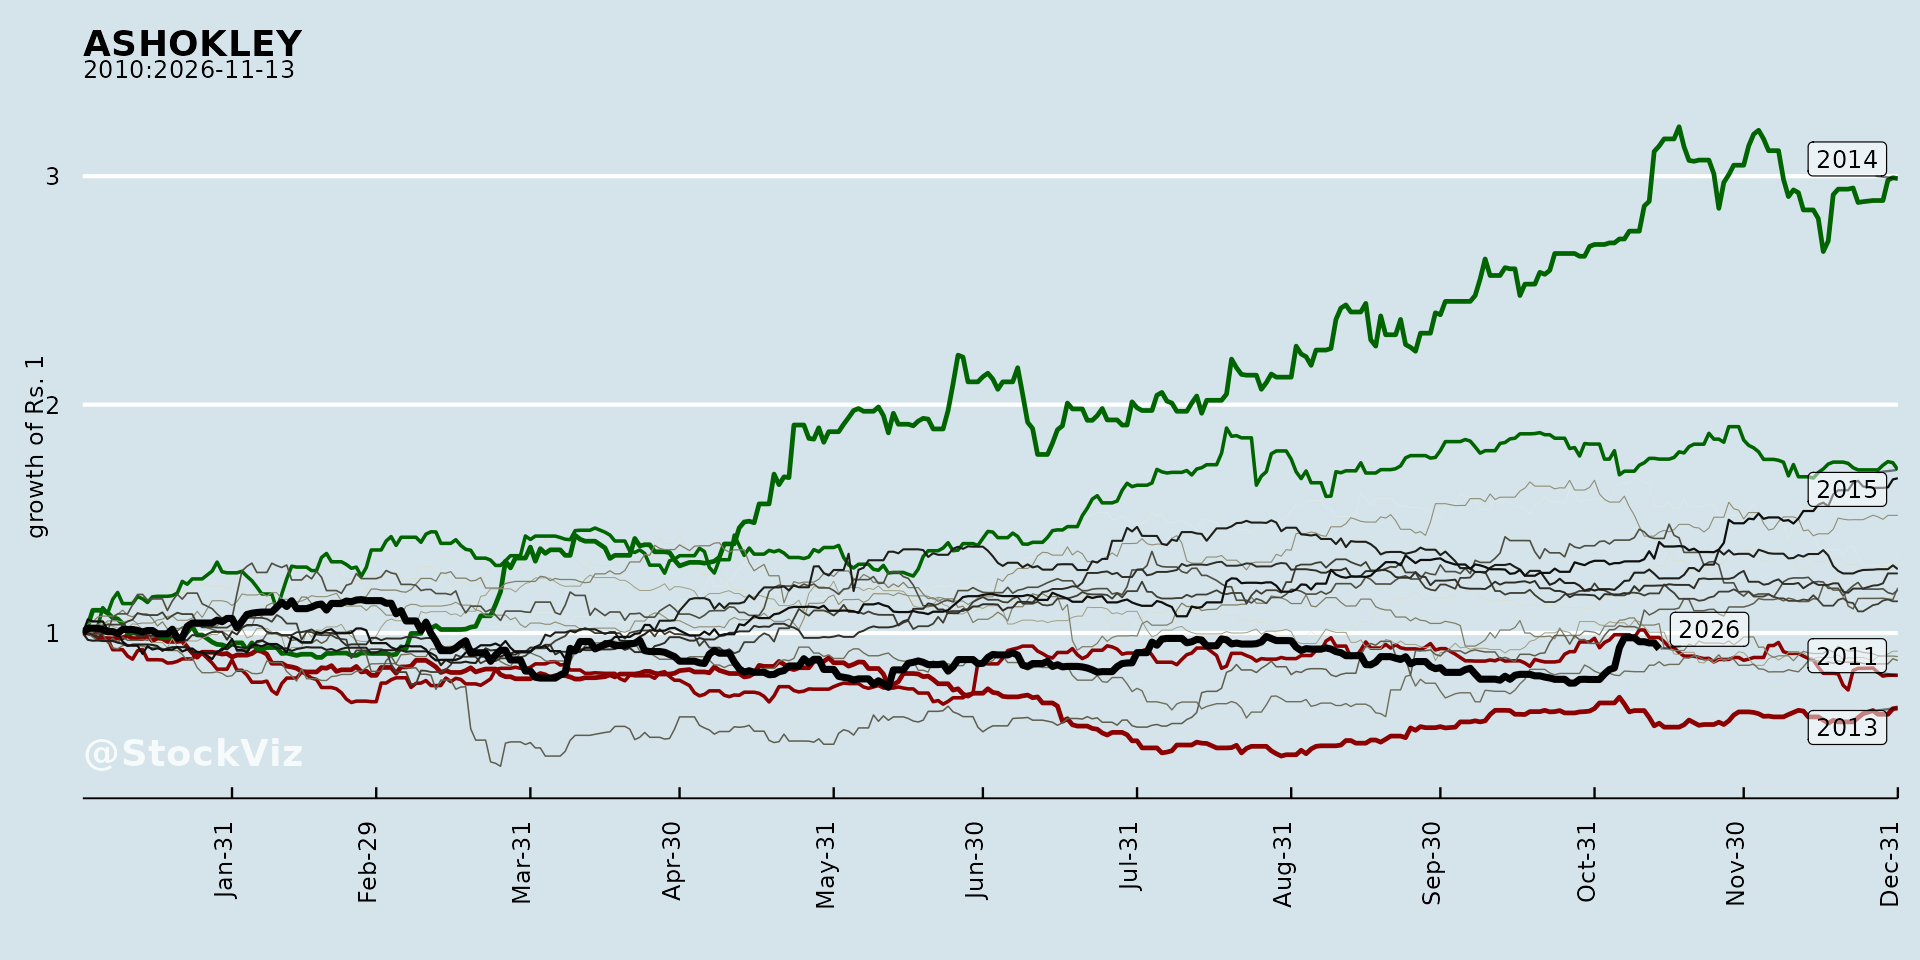
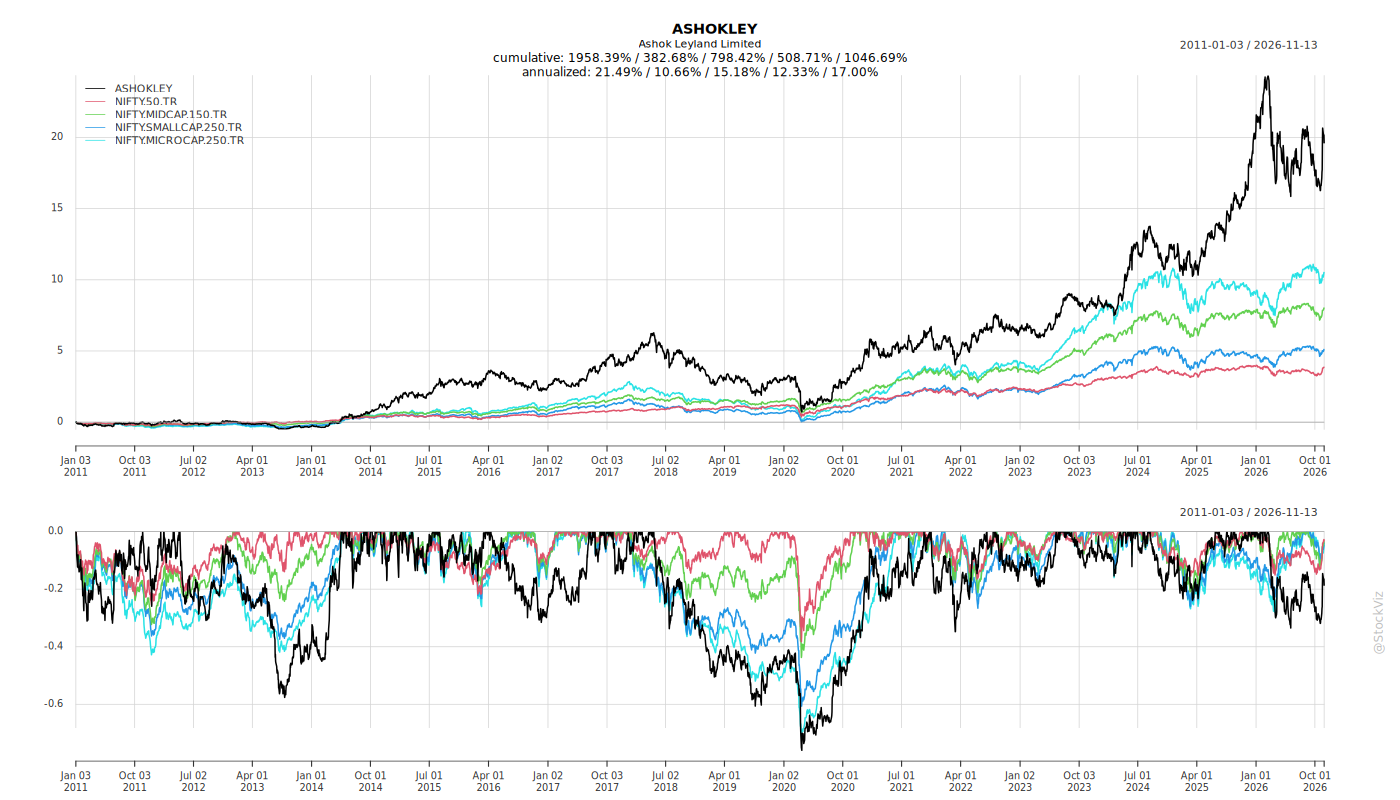
Cumulative Returns and Drawdowns
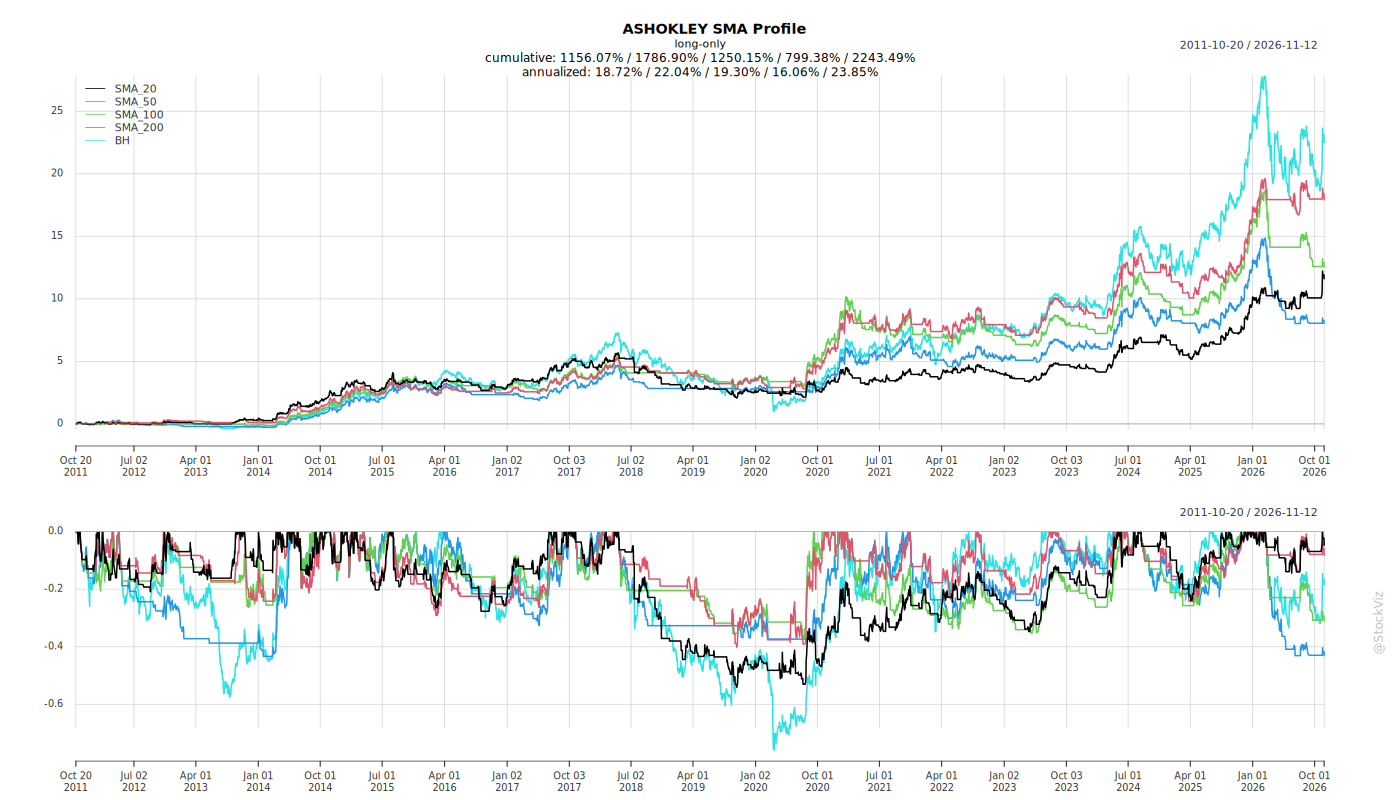
Fundamentals
Ownership
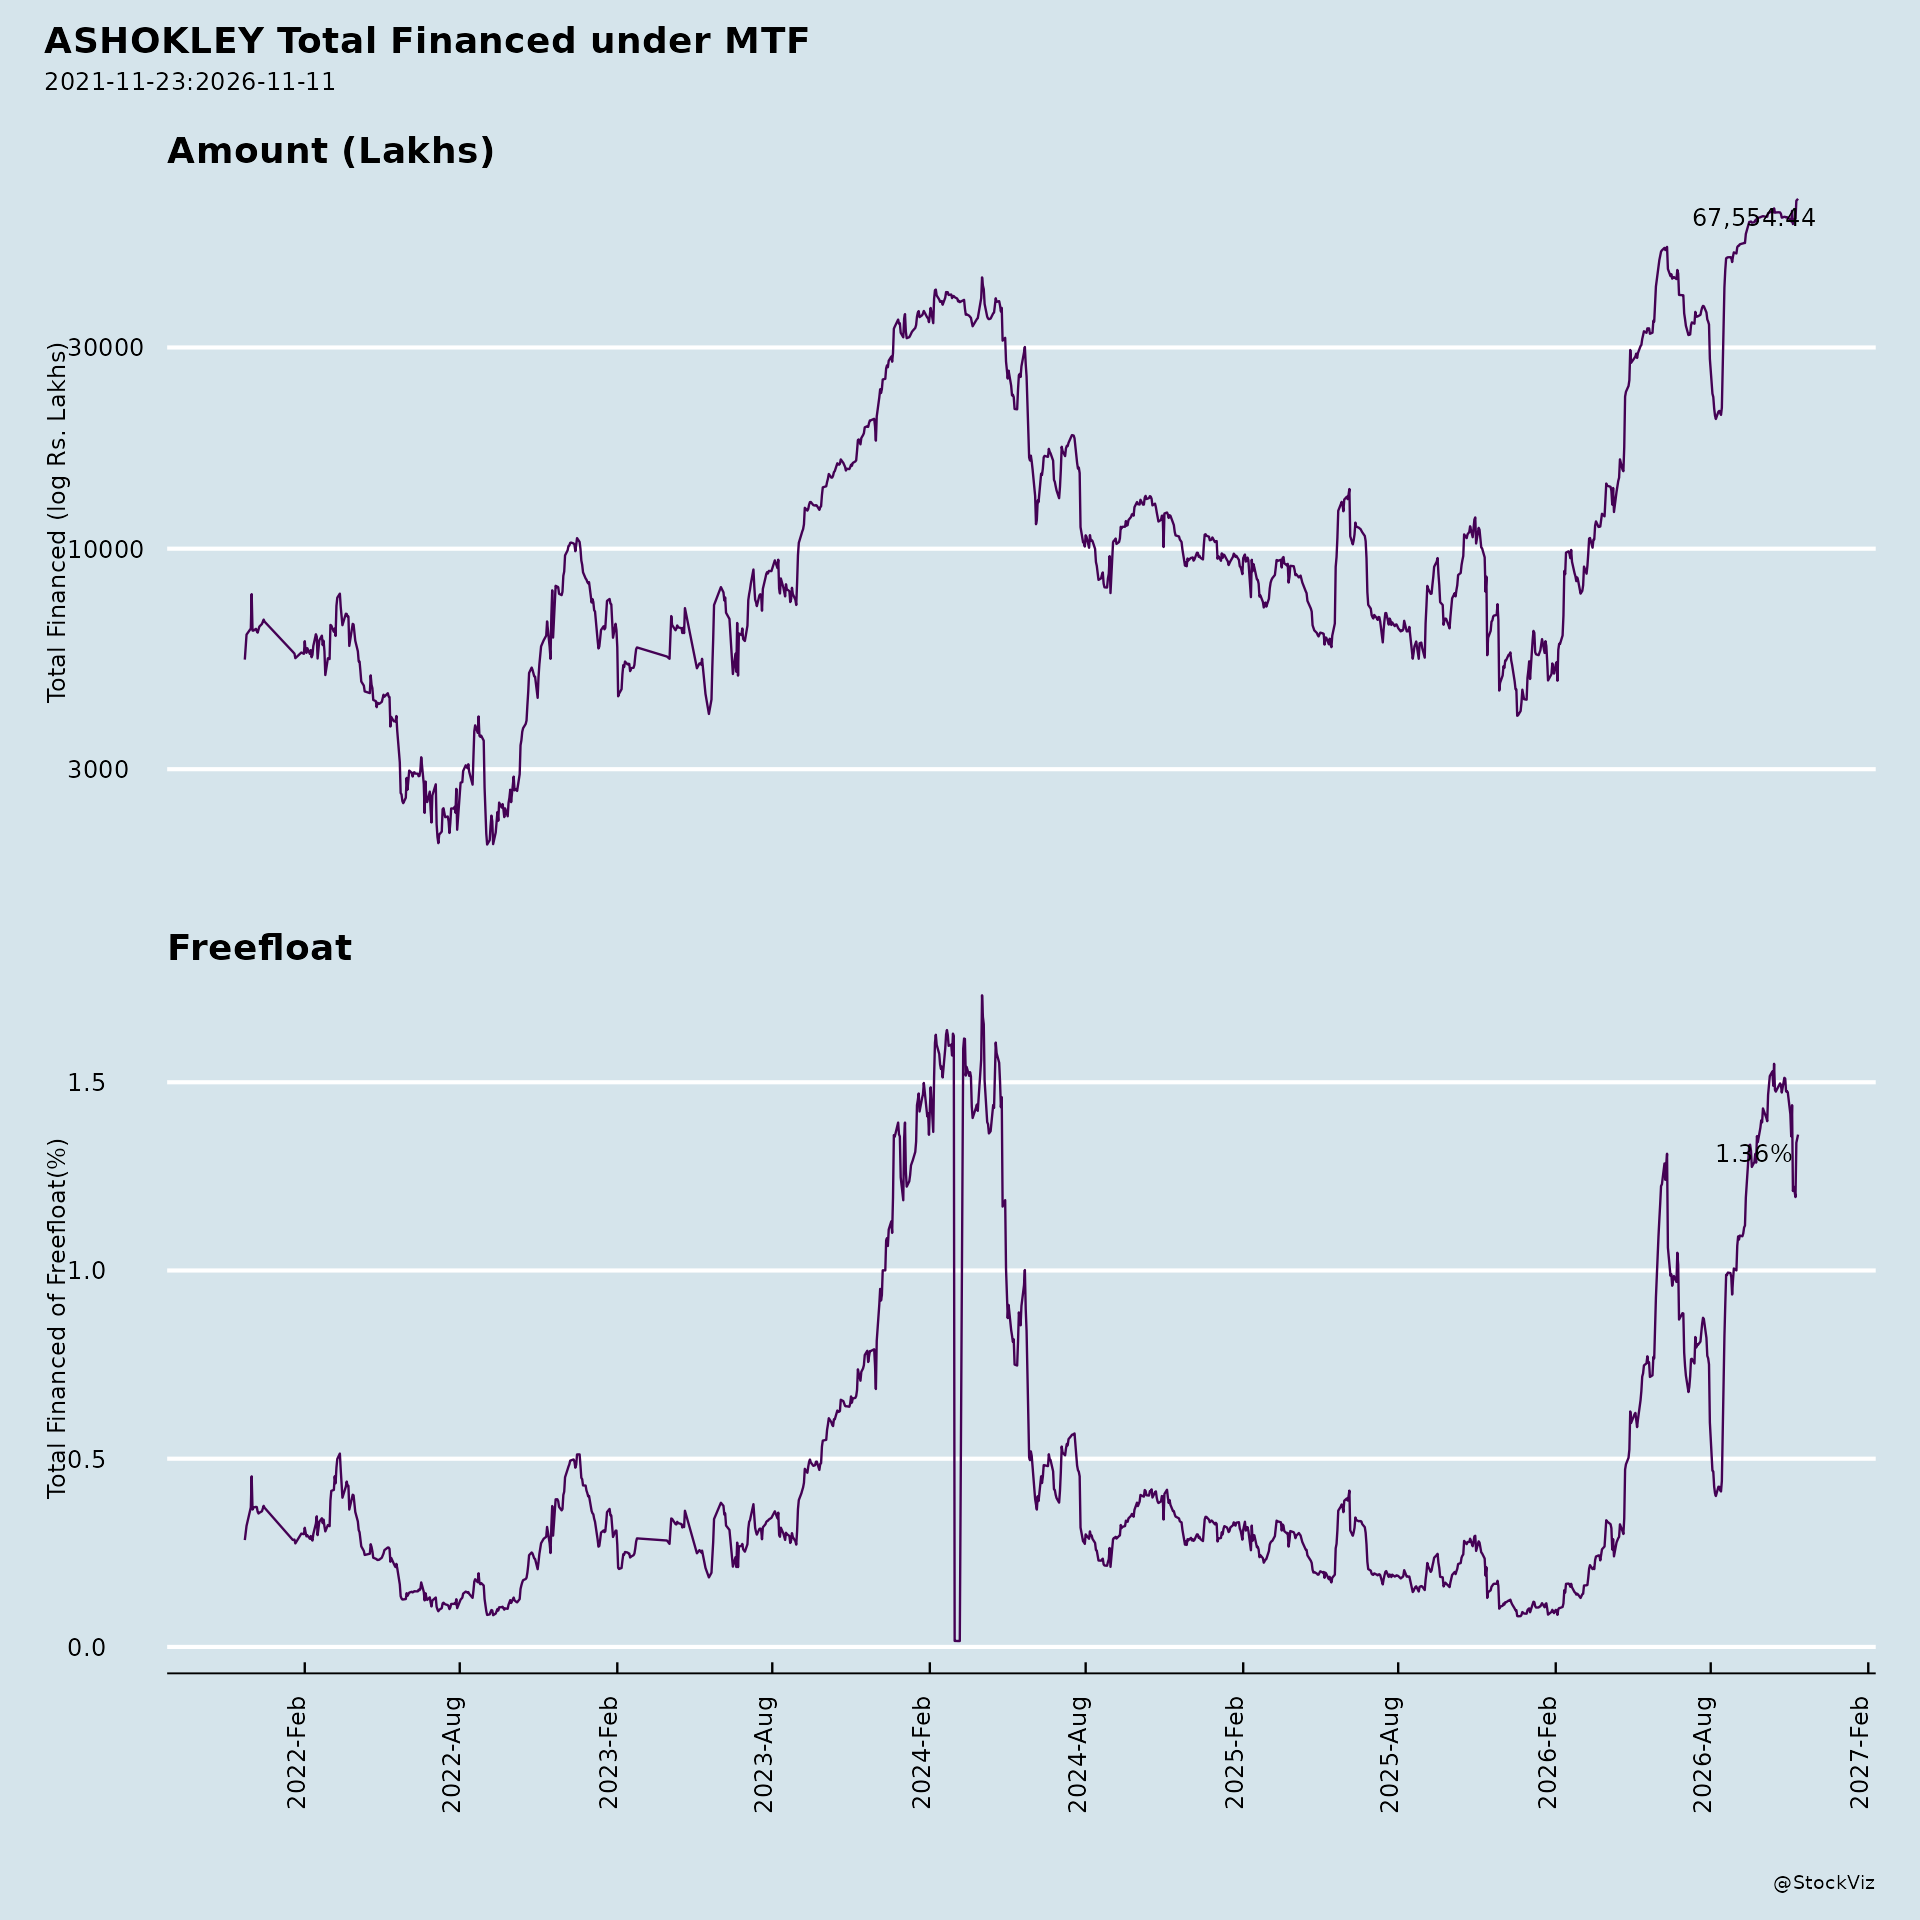
Margined
AI Summary
asof: 2026-09-16
Ashok Leyland — Recent Corporate Announcements: Headwinds, Tailwinds, Risks and Guidance vs Performance
1. Headwinds and Challenges
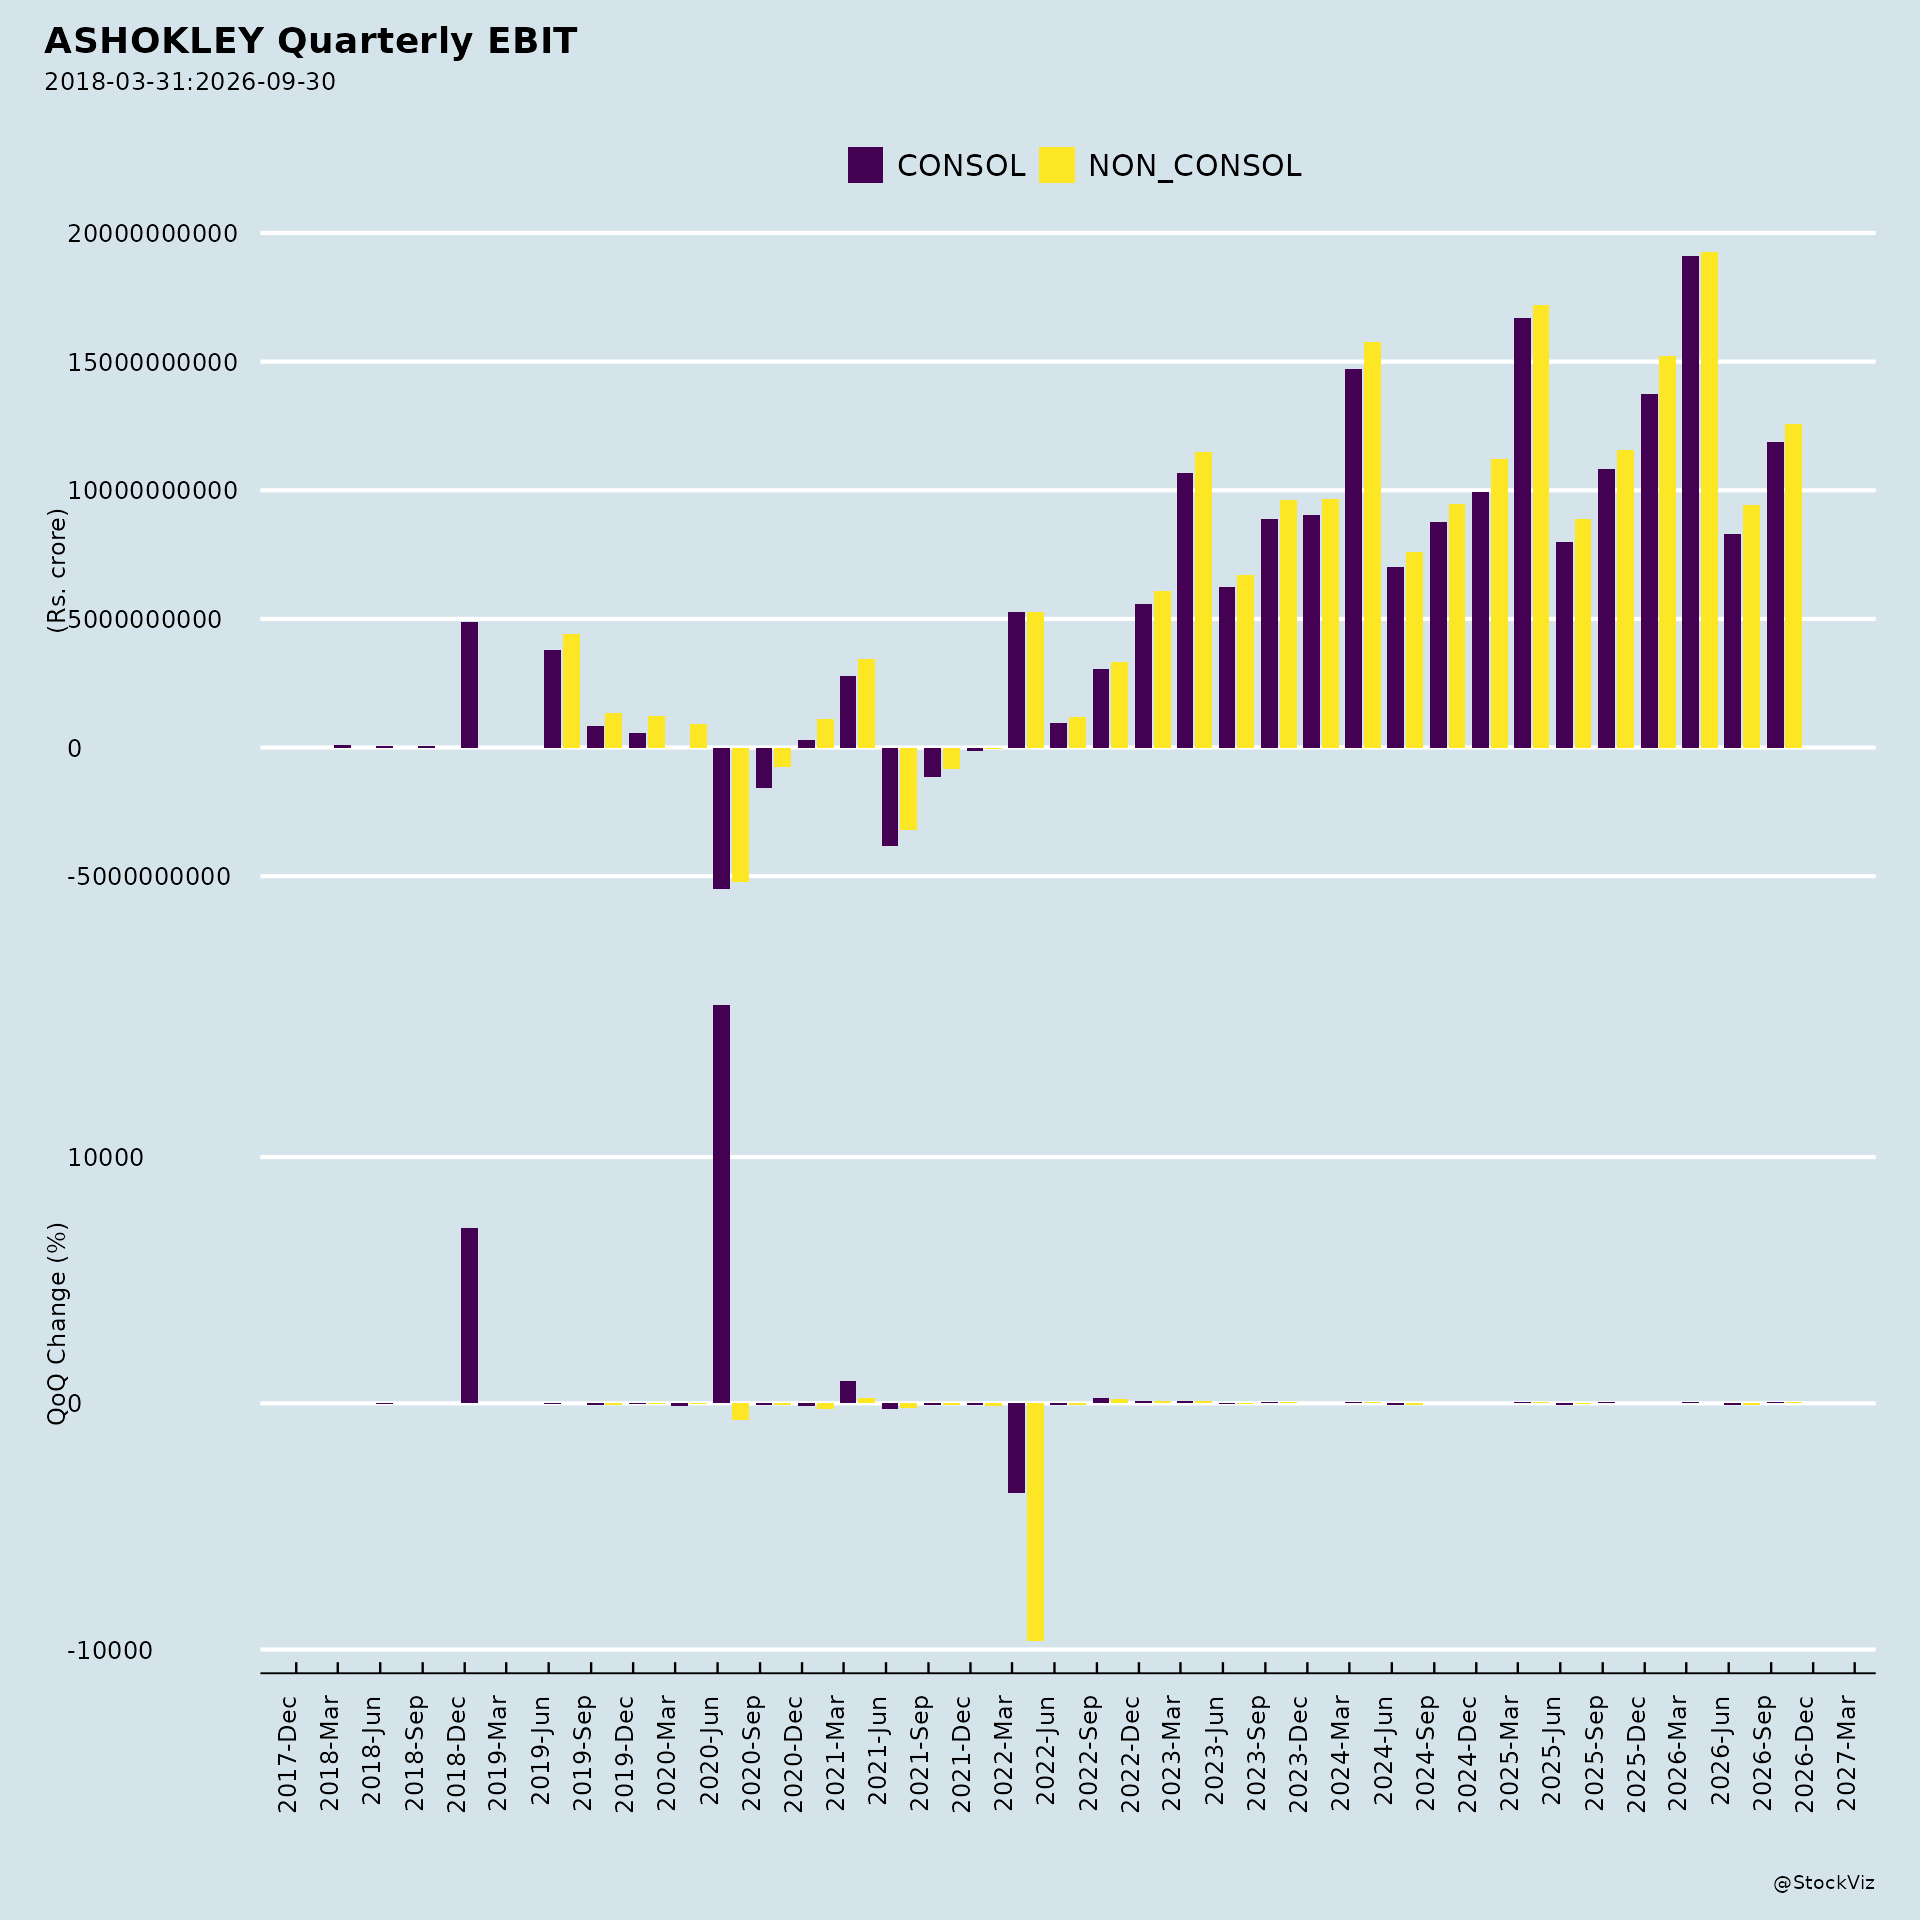
Rising material costs. The Q1 FY27 press release (August 14, 2026) states that EBITDA was 10.1% (Rs. 970 Cr) against 11.1% (Rs. 970 Cr) in Q1 FY26, attributed to rising material costs. The MD & CEO noted that “rising material costs remain a concern” and that the company is taking initiatives towards better price realization, cost saving, product and business mix improvement, and opportunity-based inventory build-up.
Geopolitical headwinds. The MD & CEO stated that the Indian CV industry “remained buoyant in Q1 despite geopolitical headwinds.”
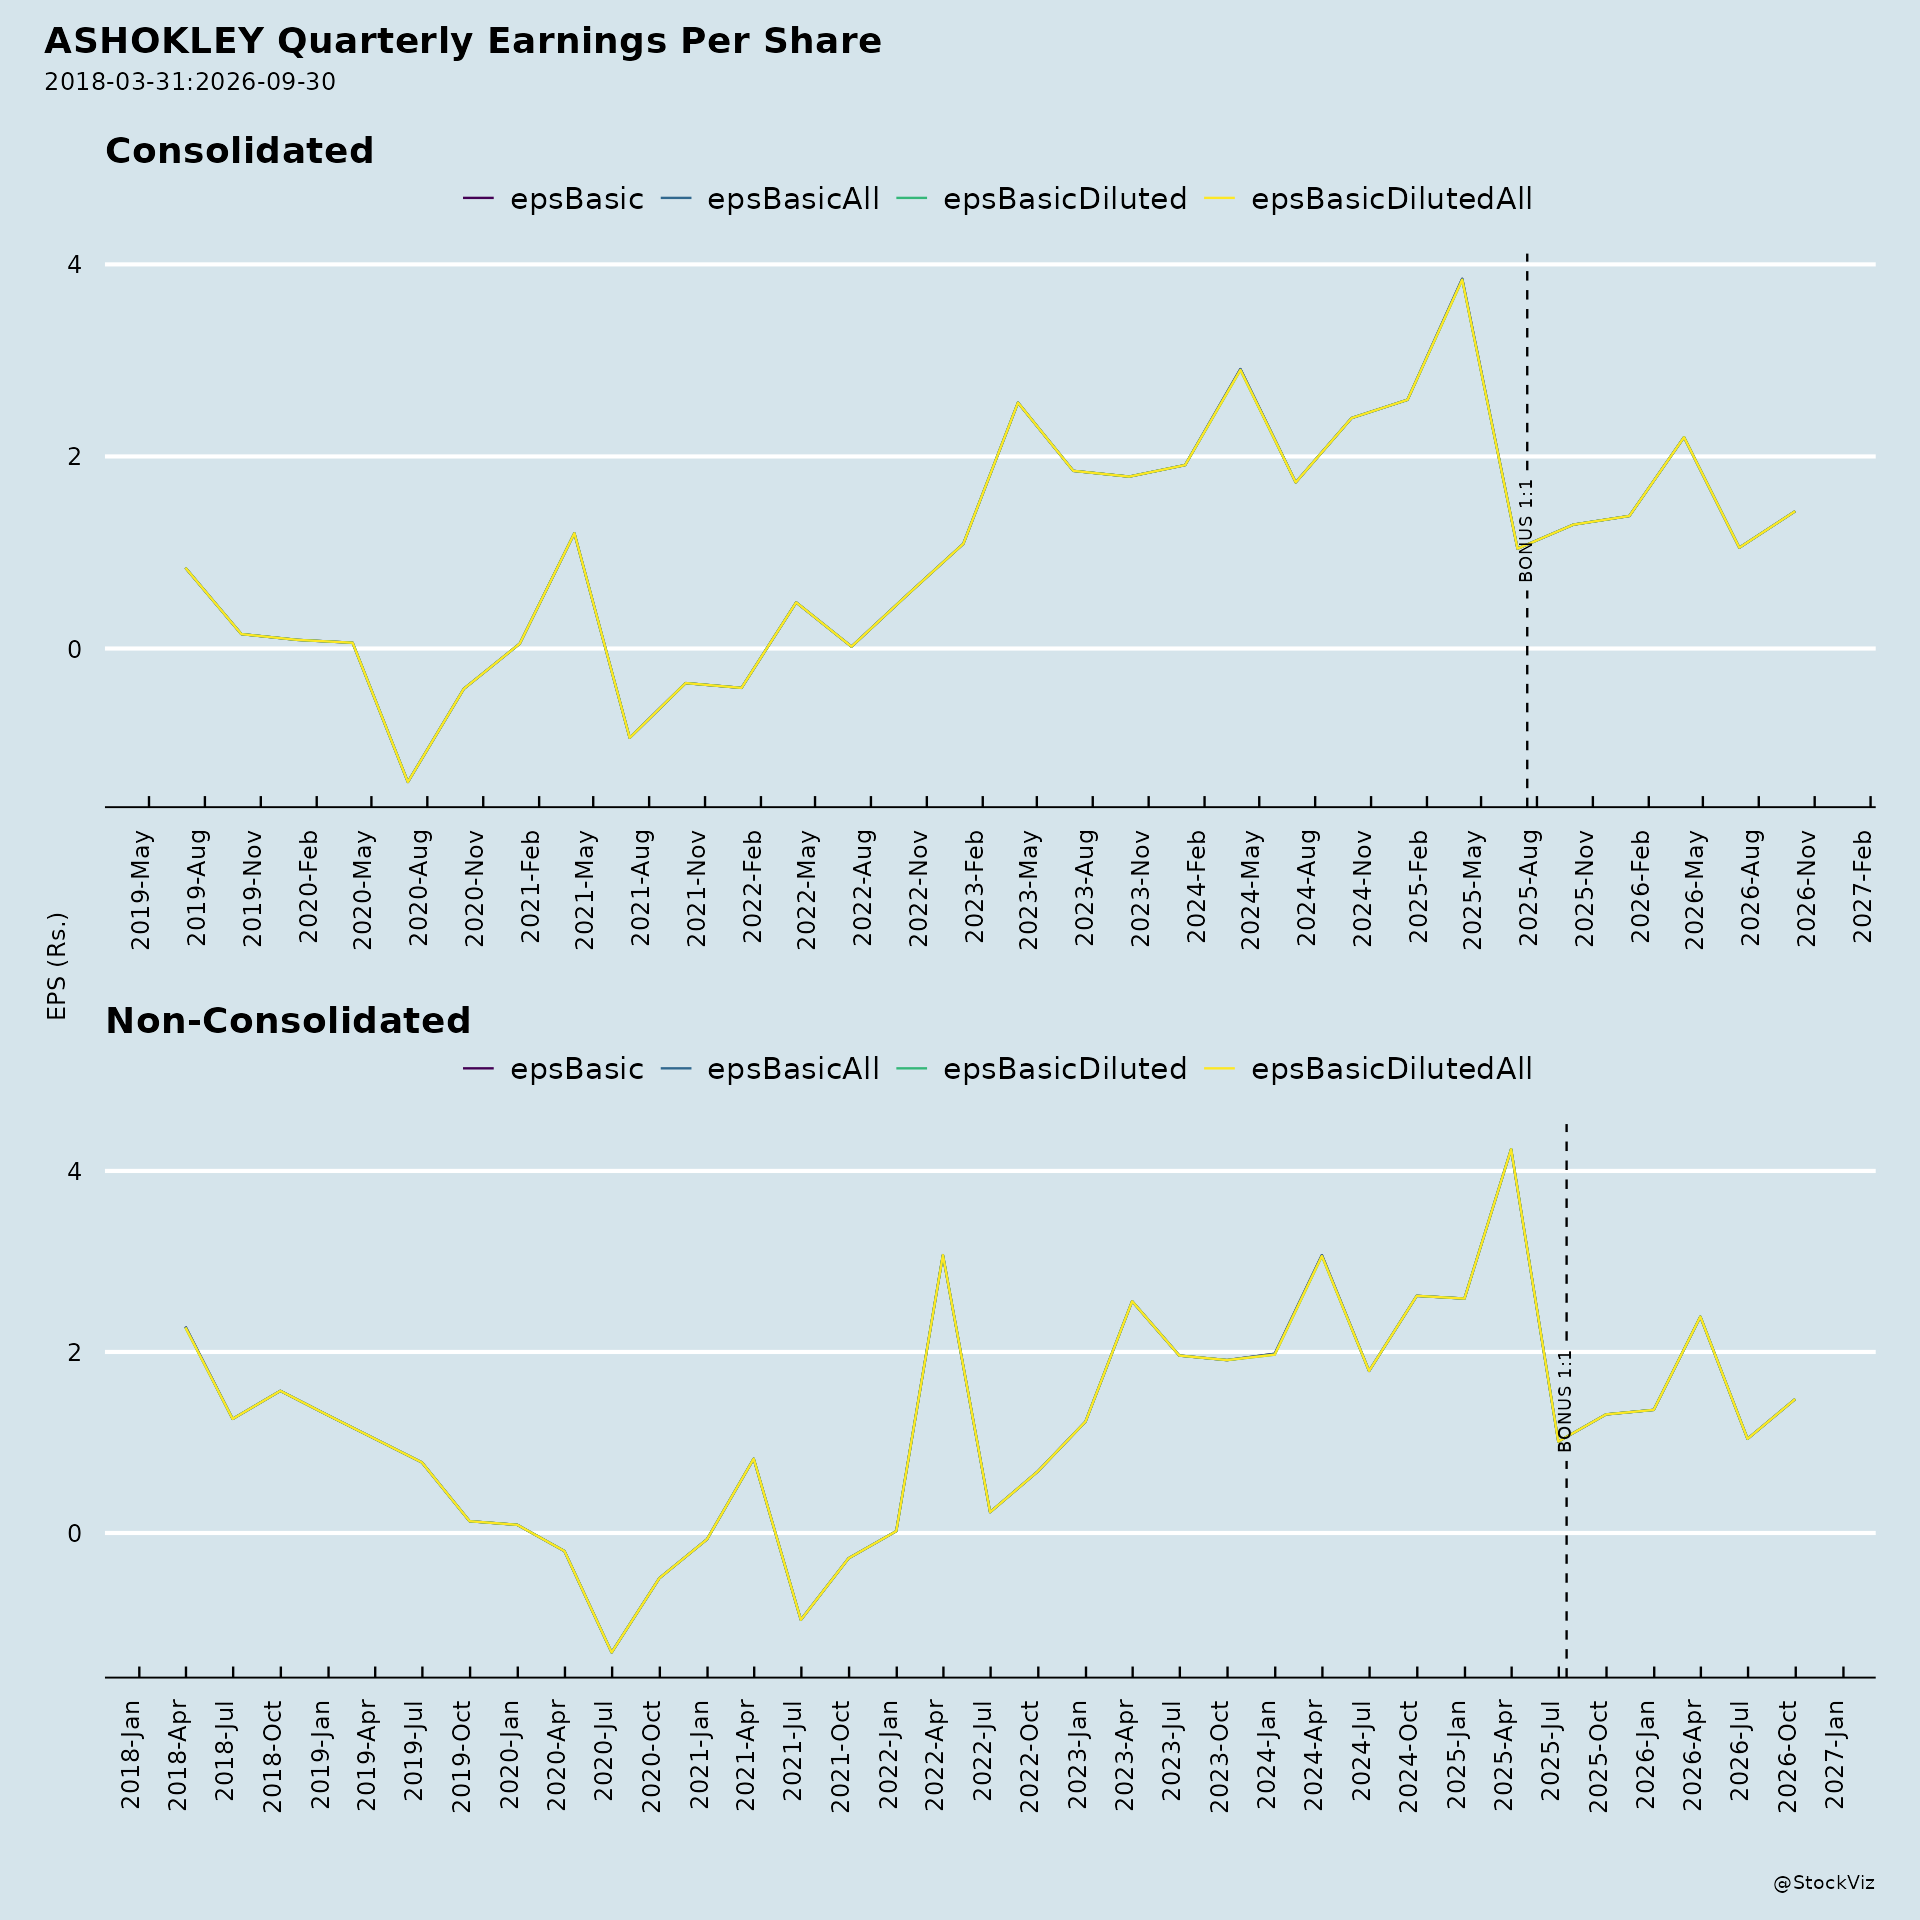
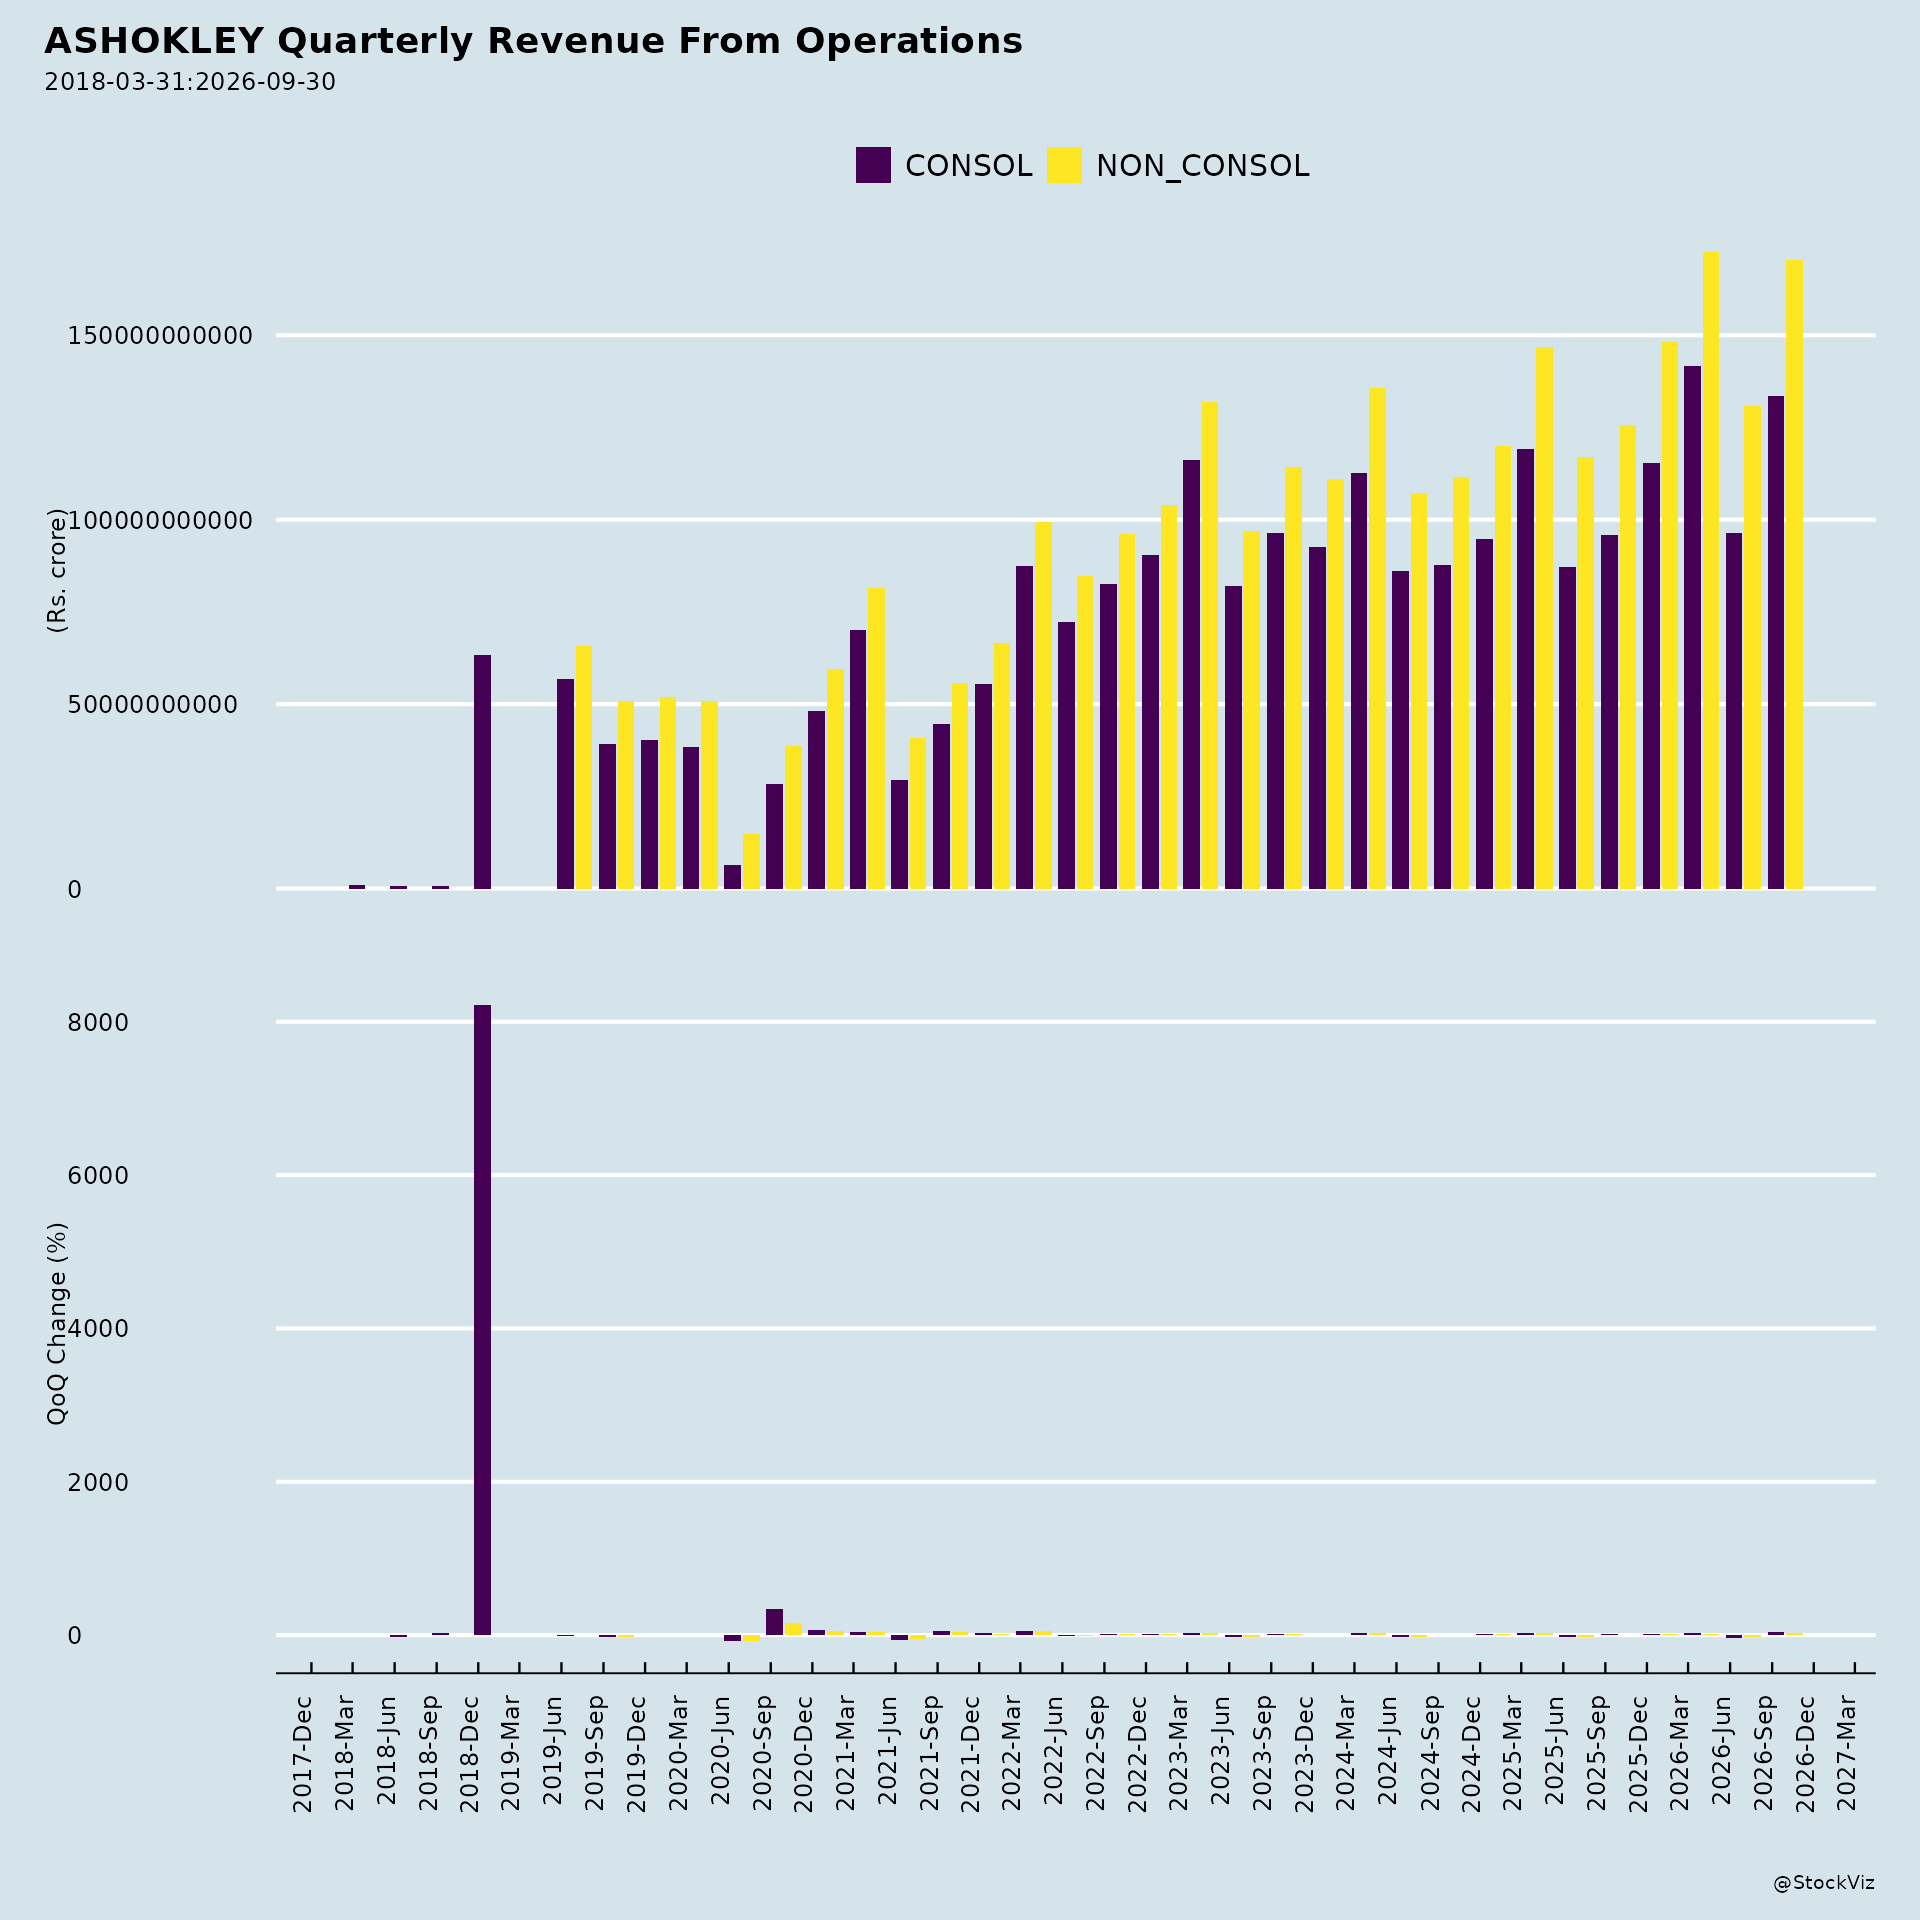
Sequential decline from Q4 FY26. Standalone revenue from operations was Rs. 9,634.35 Cr in Q1 FY27 versus Rs. 14,160.49 Cr in Q4 FY26, and standalone profit for the period was Rs. 609.11 Cr versus Rs. 1,404.72 Cr. Consolidated revenue from operations was Rs. 13,069.59 Cr versus Rs. 17,246.44 Cr, and consolidated profit for the period was Rs. 667.77 Cr versus Rs. 1,381.32 Cr.
M&HCV Bus weakness. Domestic M&HCV Bus for the month of July 2026 was 1,727 units versus 1,627 units (up 6%), but cumulative domestic M&HCV Bus was 5,818 units versus 7,353 units (down 21%). Including exports, M&HCV Bus for July 2026 was 2,461 units versus 2,862 units (down 14%), and cumulative was 7,931 units versus 10,551 units (down 25%).
Margin compression. Standalone operating margin was 10.06% in Q1 FY27 versus 11.11% in Q1 FY26 and 14.59% in Q4 FY26. Standalone net profit margin was 6.32% versus 6.81% in Q1 FY26 and 9.92% in Q4 FY26.
End-of-Life Vehicles (ELV) Rules uncertainty. The Ministry of Environment, Forest and Climate Change notified the Environment Protection (End-of-Life Vehicles) Rules, 2025, effective April 01, 2025. Obligations must be met for vehicles introduced in the domestic market up to June 30, 2026 by purchasing Extended Producer Responsibility (EPR) certificates. The pricing of EPR certificates and operational mechanism are yet to be defined; the company states that a reliable financial estimate of the obligation cannot be made and it will continue to assess its ability to reliably estimate obligations as implementation details become available.
Security cover breach. Note 4 to the financial results states that the security cover ratio exceeds the stipulated limit in the Debenture Trust Deed. The 7.30% NCD series - AL 2027 security cover ratio is 1.15.
DTC arbitration. The company has filed claims against Delhi Transport Corporation arising from a contract for supply of buses. The Arbitral Tribunal partially allowed the company’s claim. The award remains subject to completion of legal evaluation and rights and remedies available to the parties. No receivable or income has been recognised in respect of the award.
2. Tailwinds and Growth Prospects
Record Q1 volumes, revenue and profits. The press release titled “Ashok Leyland posts Record Q1 Volumes, Revenue & Profits” (August 14, 2026) reports highest ever Q1 CV volume of 48,763 units versus 44,238 units in the same period last year. Q1 revenue was highest ever at Rs. 9,634 Cr versus Rs. 8,725 Cr last year. Highest ever Q1 PAT was Rs. 609 Cr against Rs. 594 Cr in the previous year.
Segment growth. MHCV Truck volumes (excluding Defence) grew 15%. LCV domestic Q1 volume grew 21%, with LCV volumes at 18,874 units, highest ever for Q1. Exports volume in Q1 was 2,461 units. Power Solutions, Aftermarket and Defence businesses also contributed strongly.
July 2026 sales momentum. Domestic total vehicles for July 2026 were 17,980 units versus 13,501 units (up 33%); cumulative domestic was 64,282 units versus 54,728 units (up 17%). Including exports, total vehicles for July 2026 were 19,590 units versus 15,064 units (up 30%); cumulative was 68,353 units versus 59,302 units (up 15%). Domestic M&HCV Trucks grew 43% for the month and 23% cumulatively; LCV grew 29% for the month and 23% cumulatively.
Cash position. Net cash was Rs. 2,252 Cr at end of Q1 FY27, a positive swing of Rs. 1,432 Cr on a YoY basis.
Product and network initiatives. In Q1 FY2027, the company launched industry-first “Air Suspension Technology” in its Multi Axle trucks, providing best-in-class payload and total cost of operations. Network expansion continued with addition of 33 more touchpoints.
Government initiatives. The Chairman stated that government initiatives such as Parivartan will further accelerate fleet modernization and support long-term growth of the commercial vehicle industry.
Electric mobility and diversification. Switch Mobility, the electric mobility subsidiary, continues to gain traction. The company is strengthening its presence in international markets and the Defence business to diversify growth drivers.
Demand outlook. The Chairman stated that demand across key segments remains robust and future prospects continue to be encouraging.
Scheme of arrangement. NDL received approval of the Competition Commission of India and the BSE and NSE; HLF received approval of the BSE for the Scheme. HLF and NDL made an application to the NCLT Mumbai Bench on June 01, 2026. The NCLT, vide order dated June 17, 2026, directed HLF to convene meetings of equity shareholders and unsecured creditors (dispensing with secured creditors) and NDL to convene a meeting of equity shareholders. Meetings were held on Thursday, July 30, 2026, and the resolution for approval of the Scheme was passed with requisite majority at both the equity shareholders’ meetings of HLF and NDL and the unsecured creditors’ meeting of HLF.
3. Key Risks
Material cost inflation. Rising material costs are identified as a concern, with the company pursuing price realization, cost savings, product and business mix improvement, and opportunity-based inventory build-up in response.
Geopolitical risk. The MD & CEO referenced geopolitical headwinds affecting the operating environment.
Regulatory uncertainty on ELV Rules. The absence of a defined EPR certificate pricing mechanism and operational framework means the company cannot reliably estimate its obligation under the ELV Rules; the company will continue to assess its ability to reliably estimate obligations as implementation details become available.
Litigation and arbitration. The DTC arbitration award remains subject to legal evaluation and rights and remedies available to the parties; no receivable or income has been recognised. Exceptional items in the year ended March 31, 2026 included a provision for litigation of Rs. 40.00 Cr (standalone) and Rs. 40.00 Cr (consolidated).
Security cover breach. The security cover ratio for the 7.30% NCD series - AL 2027 exceeds the stipulated limit in the Debenture Trust Deed, at 1.15.
Labour Codes impact. Exceptional items for the year ended March 31, 2026 included impact of new Labour Codes of Rs. 308.48 Cr (standalone) and Rs. 350.51 Cr (consolidated).
Auditor transition. Price Waterhouse & Co. Chartered Accountants LLP will complete its 10-year tenure as statutory auditors at the conclusion of the 78th AGM in 2027. The Board approved the appointment of M/s Deloitte Haskins & Sells Chartered Accountant LLP for five consecutive years from the conclusion of the 78th AGM (2027) till the conclusion of the 83rd AGM (2032), subject to shareholder approval at the 78th AGM.
Unreviewed subsidiary financials. The consolidated results include consolidated interim financial information of one subsidiary and interim financial information of eleven subsidiaries and four step-down subsidiaries not reviewed by their auditors, reflecting total revenue of Rs. 793.80 Cr, total net profit after tax of Rs. 9.25 Cr and total comprehensive income of Rs. 8.56 Cr for the quarter ended June 30, 2026. The results also include the Group’s share of net profit after tax of Rs. 6.14 Cr and total comprehensive income of Rs. 1.12 Cr in respect of three associates and four joint ventures based on interim financial information not reviewed by their auditors.
4. Management Guidance Versus Observed Business Performance
Demand outlook. The Chairman stated that demand across key segments remains robust and future prospects continue to be encouraging. Observed performance: Q1 FY27 recorded highest ever Q1 CV volume of 48,763 units, highest ever Q1 revenue of Rs. 9,634 Cr, and highest ever Q1 PAT of Rs. 609 Cr. July 2026 sales showed domestic total vehicles up 33% for the month and 17% cumulatively, and total vehicles including exports up 30% for the month and 15% cumulatively.
Margin pressure response. The MD & CEO stated that while rising material costs remain a concern, the company is taking initiatives towards better price realization, rigorous cost saving efforts, product and business mix improvement, and opportunity-based inventory build-up. Observed performance: EBITDA margin was 10.1% in Q1 FY27 versus 11.1% in Q1 FY26; standalone operating margin was 10.06% versus 11.11% in Q1 FY26 and 14.59% in Q4 FY26.
Long-term focus. The MD & CEO stated that the long-term focus remains intact, with pursuit of premiumization, superior products and services, and operational discipline. Observed performance: the company launched industry-first Air Suspension Technology in Multi Axle trucks and added 33 touchpoints during the quarter.
Diversification. The Chairman stated that the company is strengthening its presence in international markets and the Defence business to diversify growth drivers, and that Switch Mobility continues to gain traction. Observed performance: Exports volume in Q1 was 2,461 units; Power Solutions, Aftermarket and Defence businesses contributed strongly to financial performance.
Cash position. The company strengthened its cash position with net cash of Rs. 2,252 Cr at end of Q1 FY27, a positive swing of Rs. 1,432 Cr on a YoY basis.
Broker Narrative
The broker narrative began in 2021 cautioning about a potential Nifty top and limited near-term upsides, yet the stock surged +183.8% as consensus shifted to predominantly positive Buy ratings through 2025. By 2026, the focus had evolved from broad market correction fears to company-specific headwinds like commodity inflation, falling bus volumes, and war-led export disruptions. Despite this report flagging strong non-CV growth and a CV upcycle, the optimism failed to prevent negative returns, with the actual outcome dropping -1.9% against a +16.2% prediction.
Optimism that failed
- The 2026 tailwinds, including the GST 2.0-driven CV upcycle, record Q1 CV volumes, and strong defence/power revenue growth, failed to support the share price, resulting in a -1.9% actual return versus a +16.2% prediction.
Broker Timeline
64 broker calls · 2021-06-07 to 2026-09-29
CNBC-TV18: ratings, targets and commentary
Extracted from CNBC-TV18 posts; ratings and targets are as published, not current consensus. OCR may contain errors. Speaker attribution is retained; not all speakers are brokers. These statements are separate from the Broker Narrative and Broker Timeline and have no calculated performance or outcomes.
Ratings and targets
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-16 |
Goldman Sachs
|
Neutral
Target: INR 152
Target action: maintained
|
Maintain Neutral on Ashok Leyland with target ₹152; Q2 in line with estimates, revenue/PAT 1%/4% above Goldman Sachs estimates; revenue & EBITDA grow 39% & 16% YoY; steel prices remain elevated, a key margin monitorable; key focus areas include CY27 demand, interest rate impact & pricing actions; export business, shipping rates & LCV portfolio expansion remain key monitorables; reverse merger timeline of financing business also in focus. |
Other company commentary (not broker ratings)
| Published / source (IST) | Speaker / affiliation | Rating / target | Commentary |
|---|---|---|---|
| 2026-11-16 |
Ashok Leyland
|
—
Horizon: FY27
|
FY27 CV growth outlook raised to at least double-digit from single-digit. CV growth for the year is expected to be double-digit. Growth can even go to mid-teens, especially M&HCV. LCV also is going very strong, LCV should also register similar growth. |
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.