ADANIENSOL
Equity Metrics
November 18, 2026
Adani Energy Solutions Limited
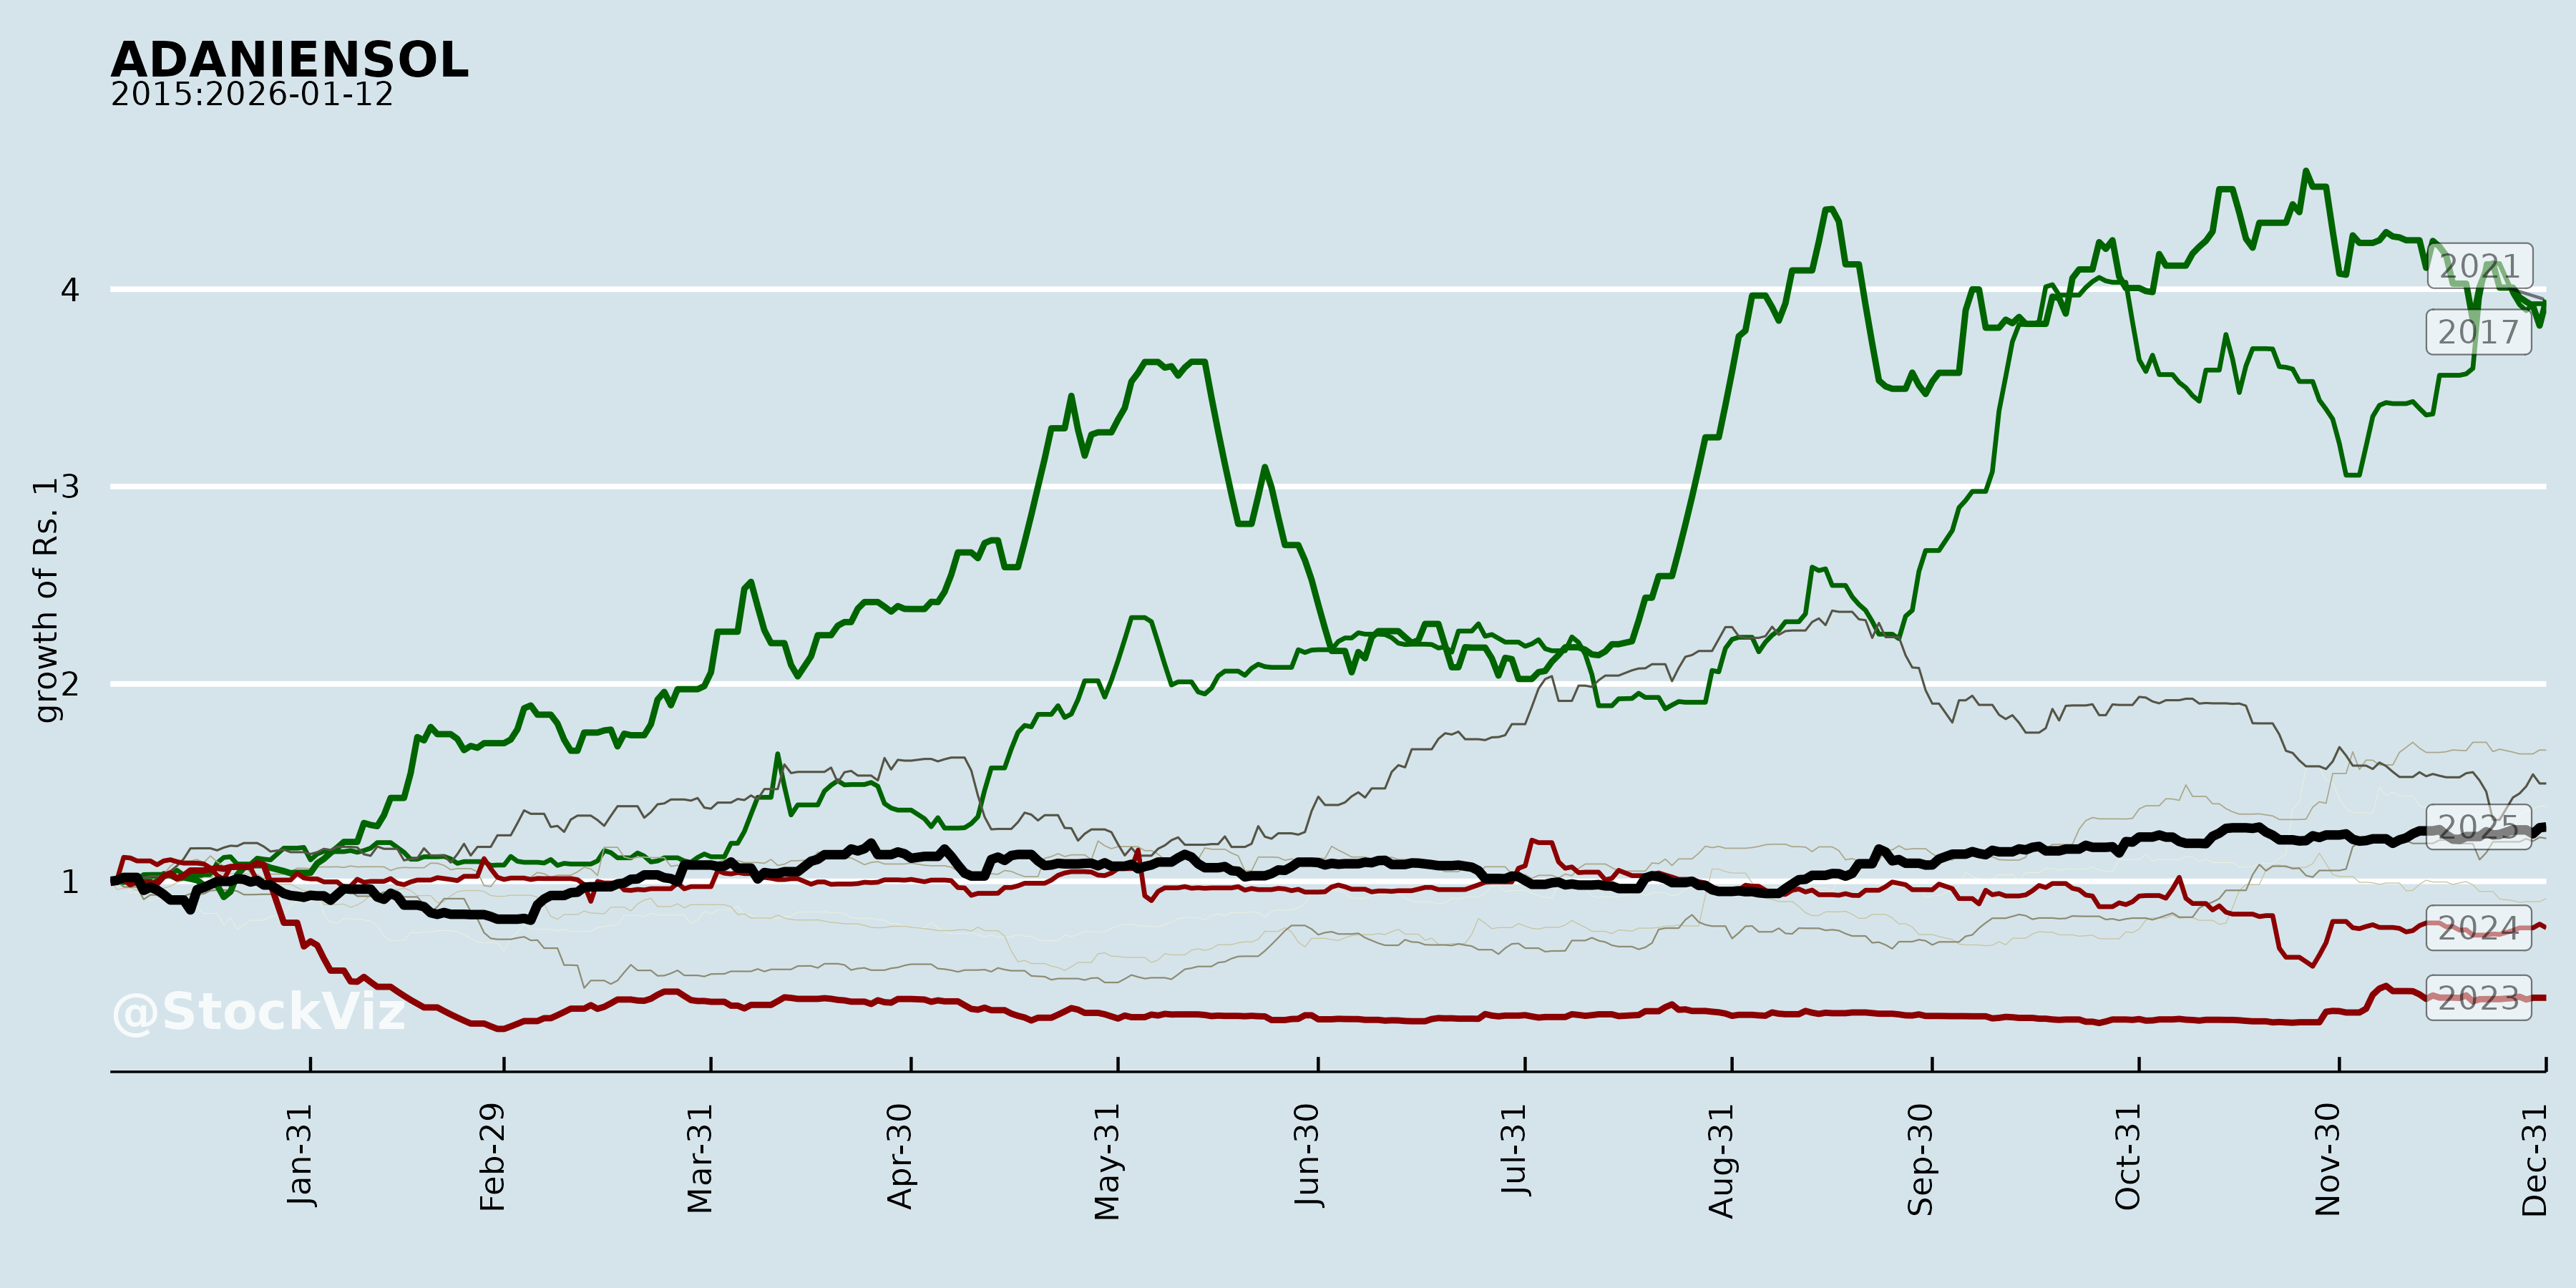
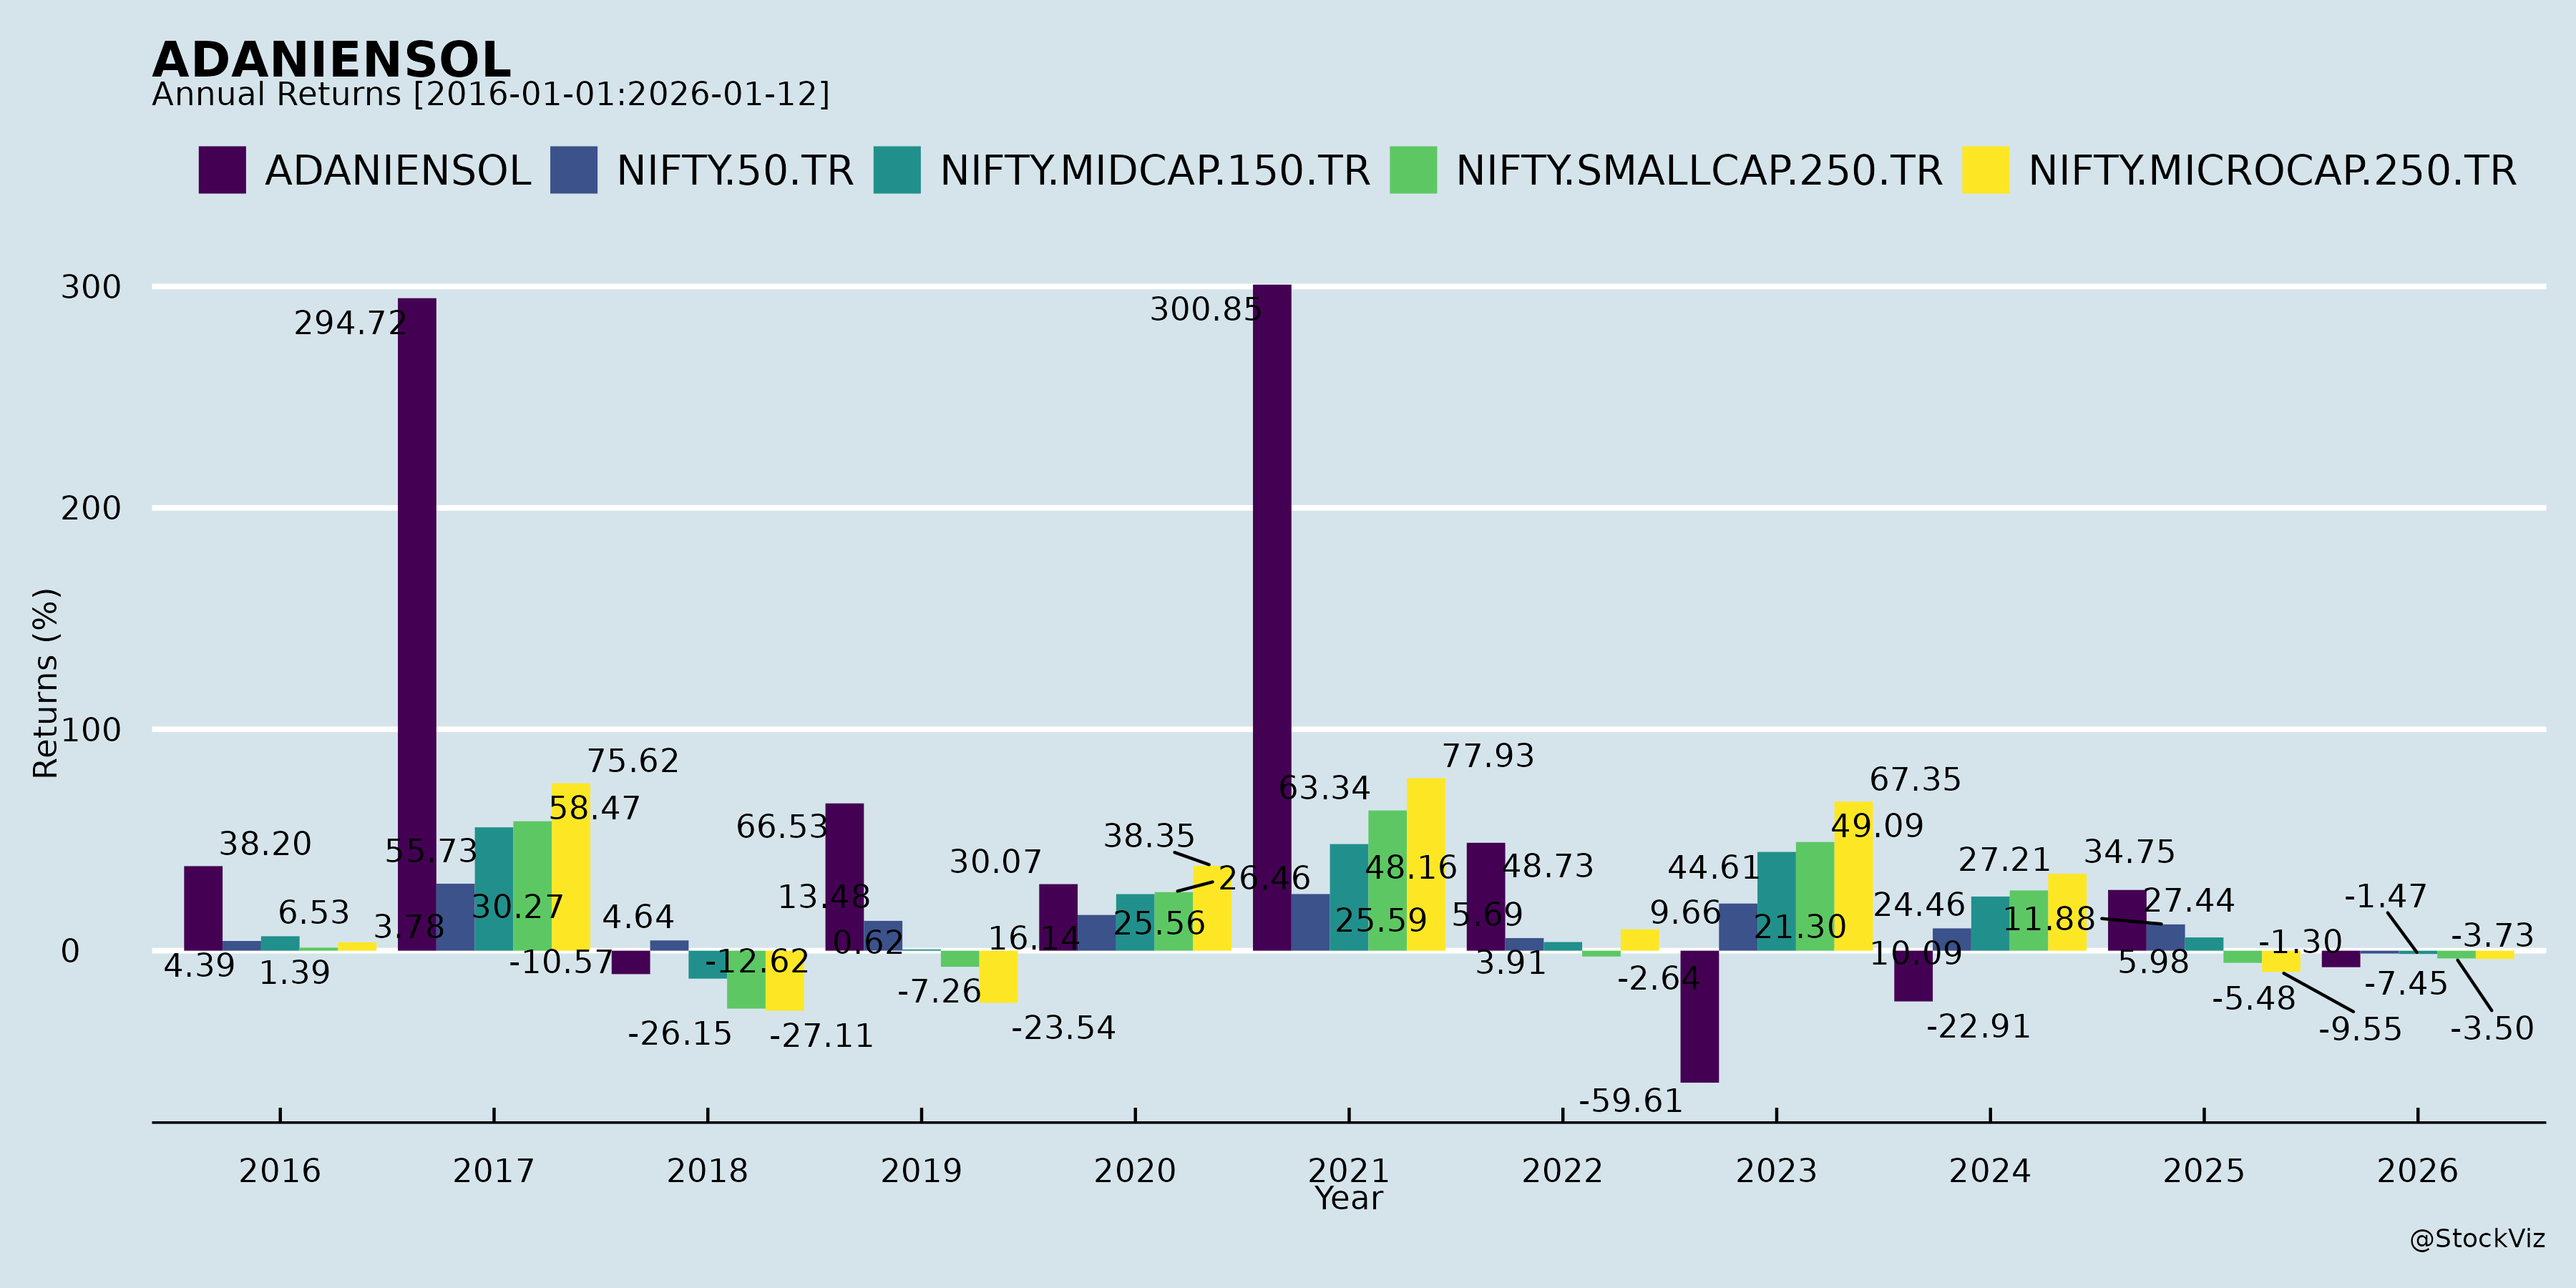
Annual Returns
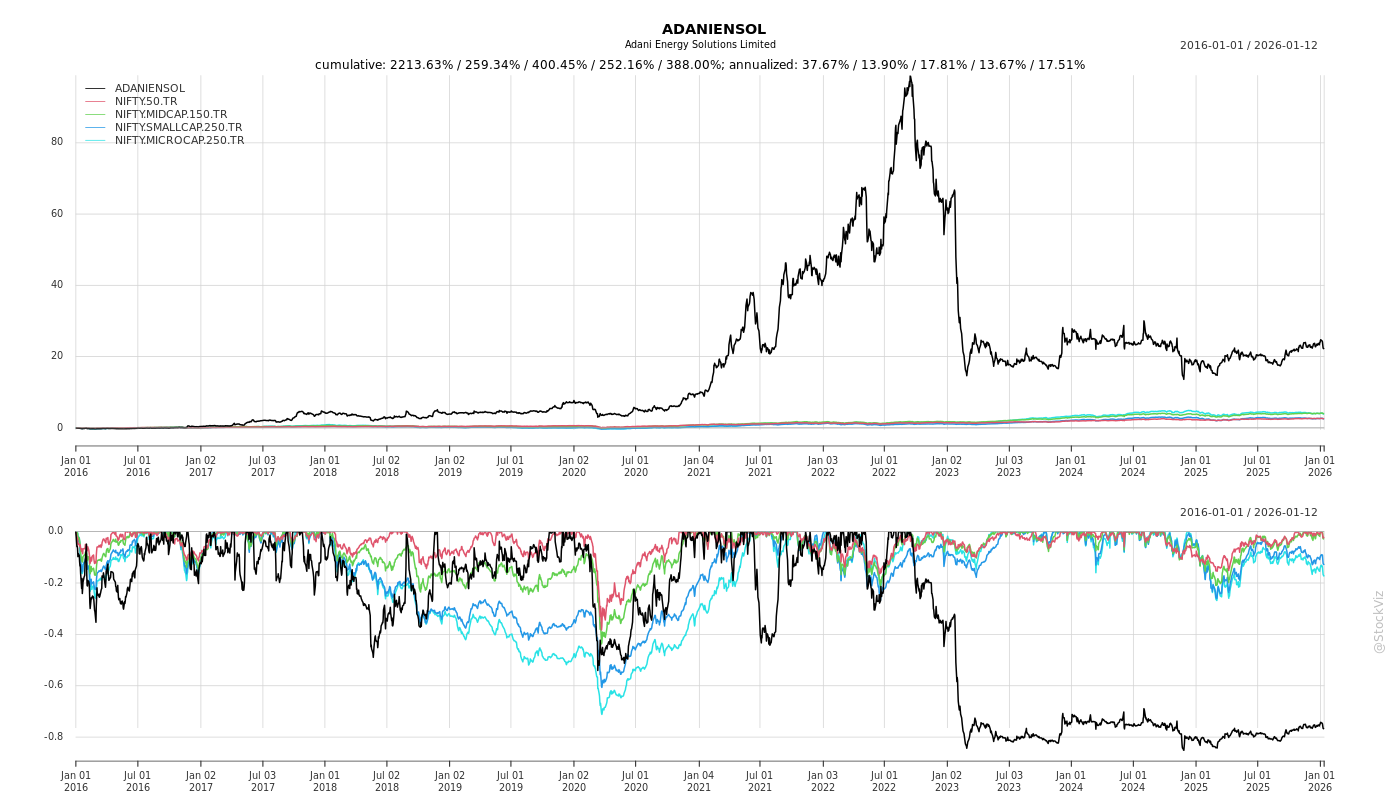
Cumulative Returns and Drawdowns
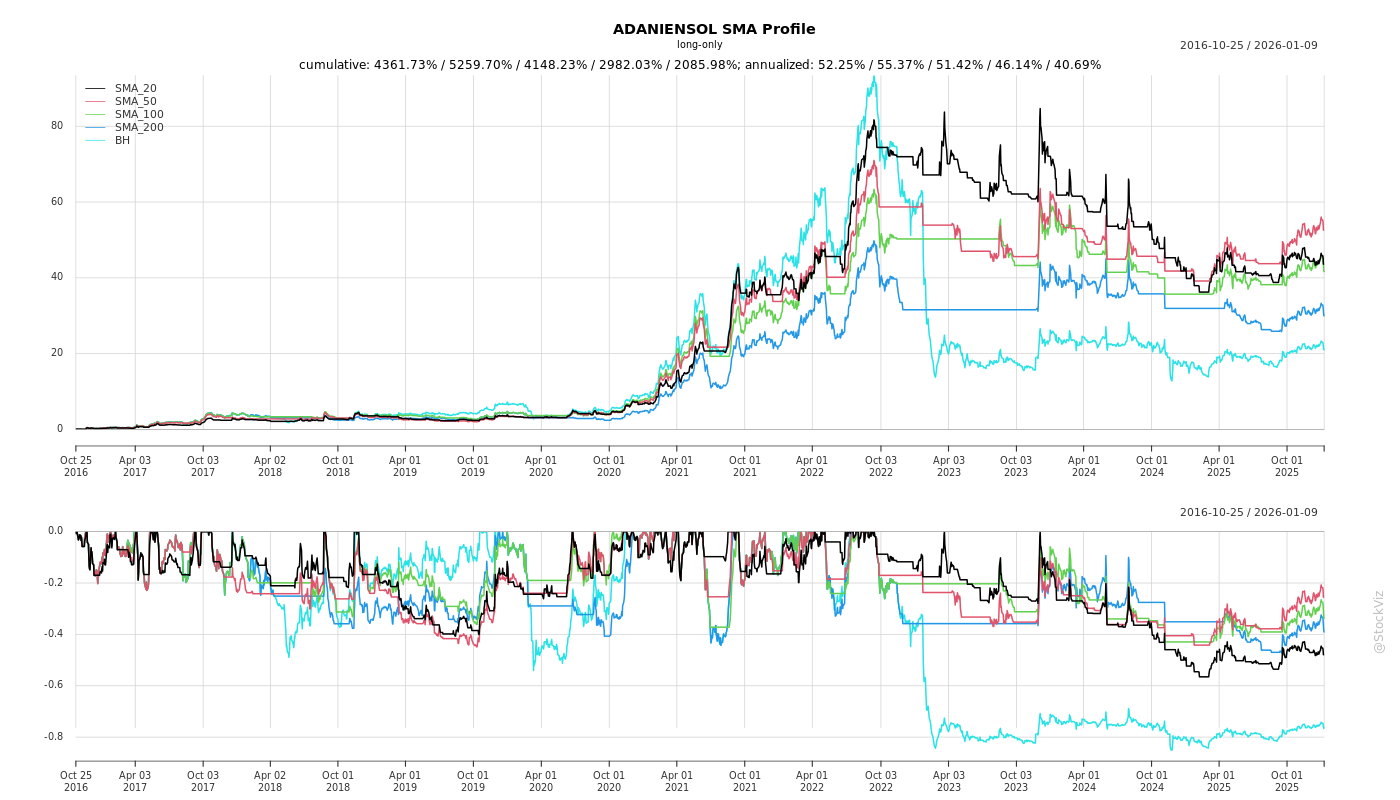
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-14
Headwinds and Challenges
- Regulatory asset accounting movements: Consolidated results show a net movement in Regulatory Deferral Account Balances of ₹(1,095.56) crore for the quarter ended 30 June 2026, compared with ₹(503.89) crore in the quarter ended 30 June 2025. This includes a regulatory gap of ₹(234.53) crore for the current period/year and a recovery of surplus for past years of ₹(861.03) crore.
- Finance costs: Consolidated finance costs were ₹894.03 crore for the quarter ended 30 June 2026, up from ₹954.26 crore in the quarter ended 31 March 2026 and ₹1,151.73 crore in the year-ago quarter.
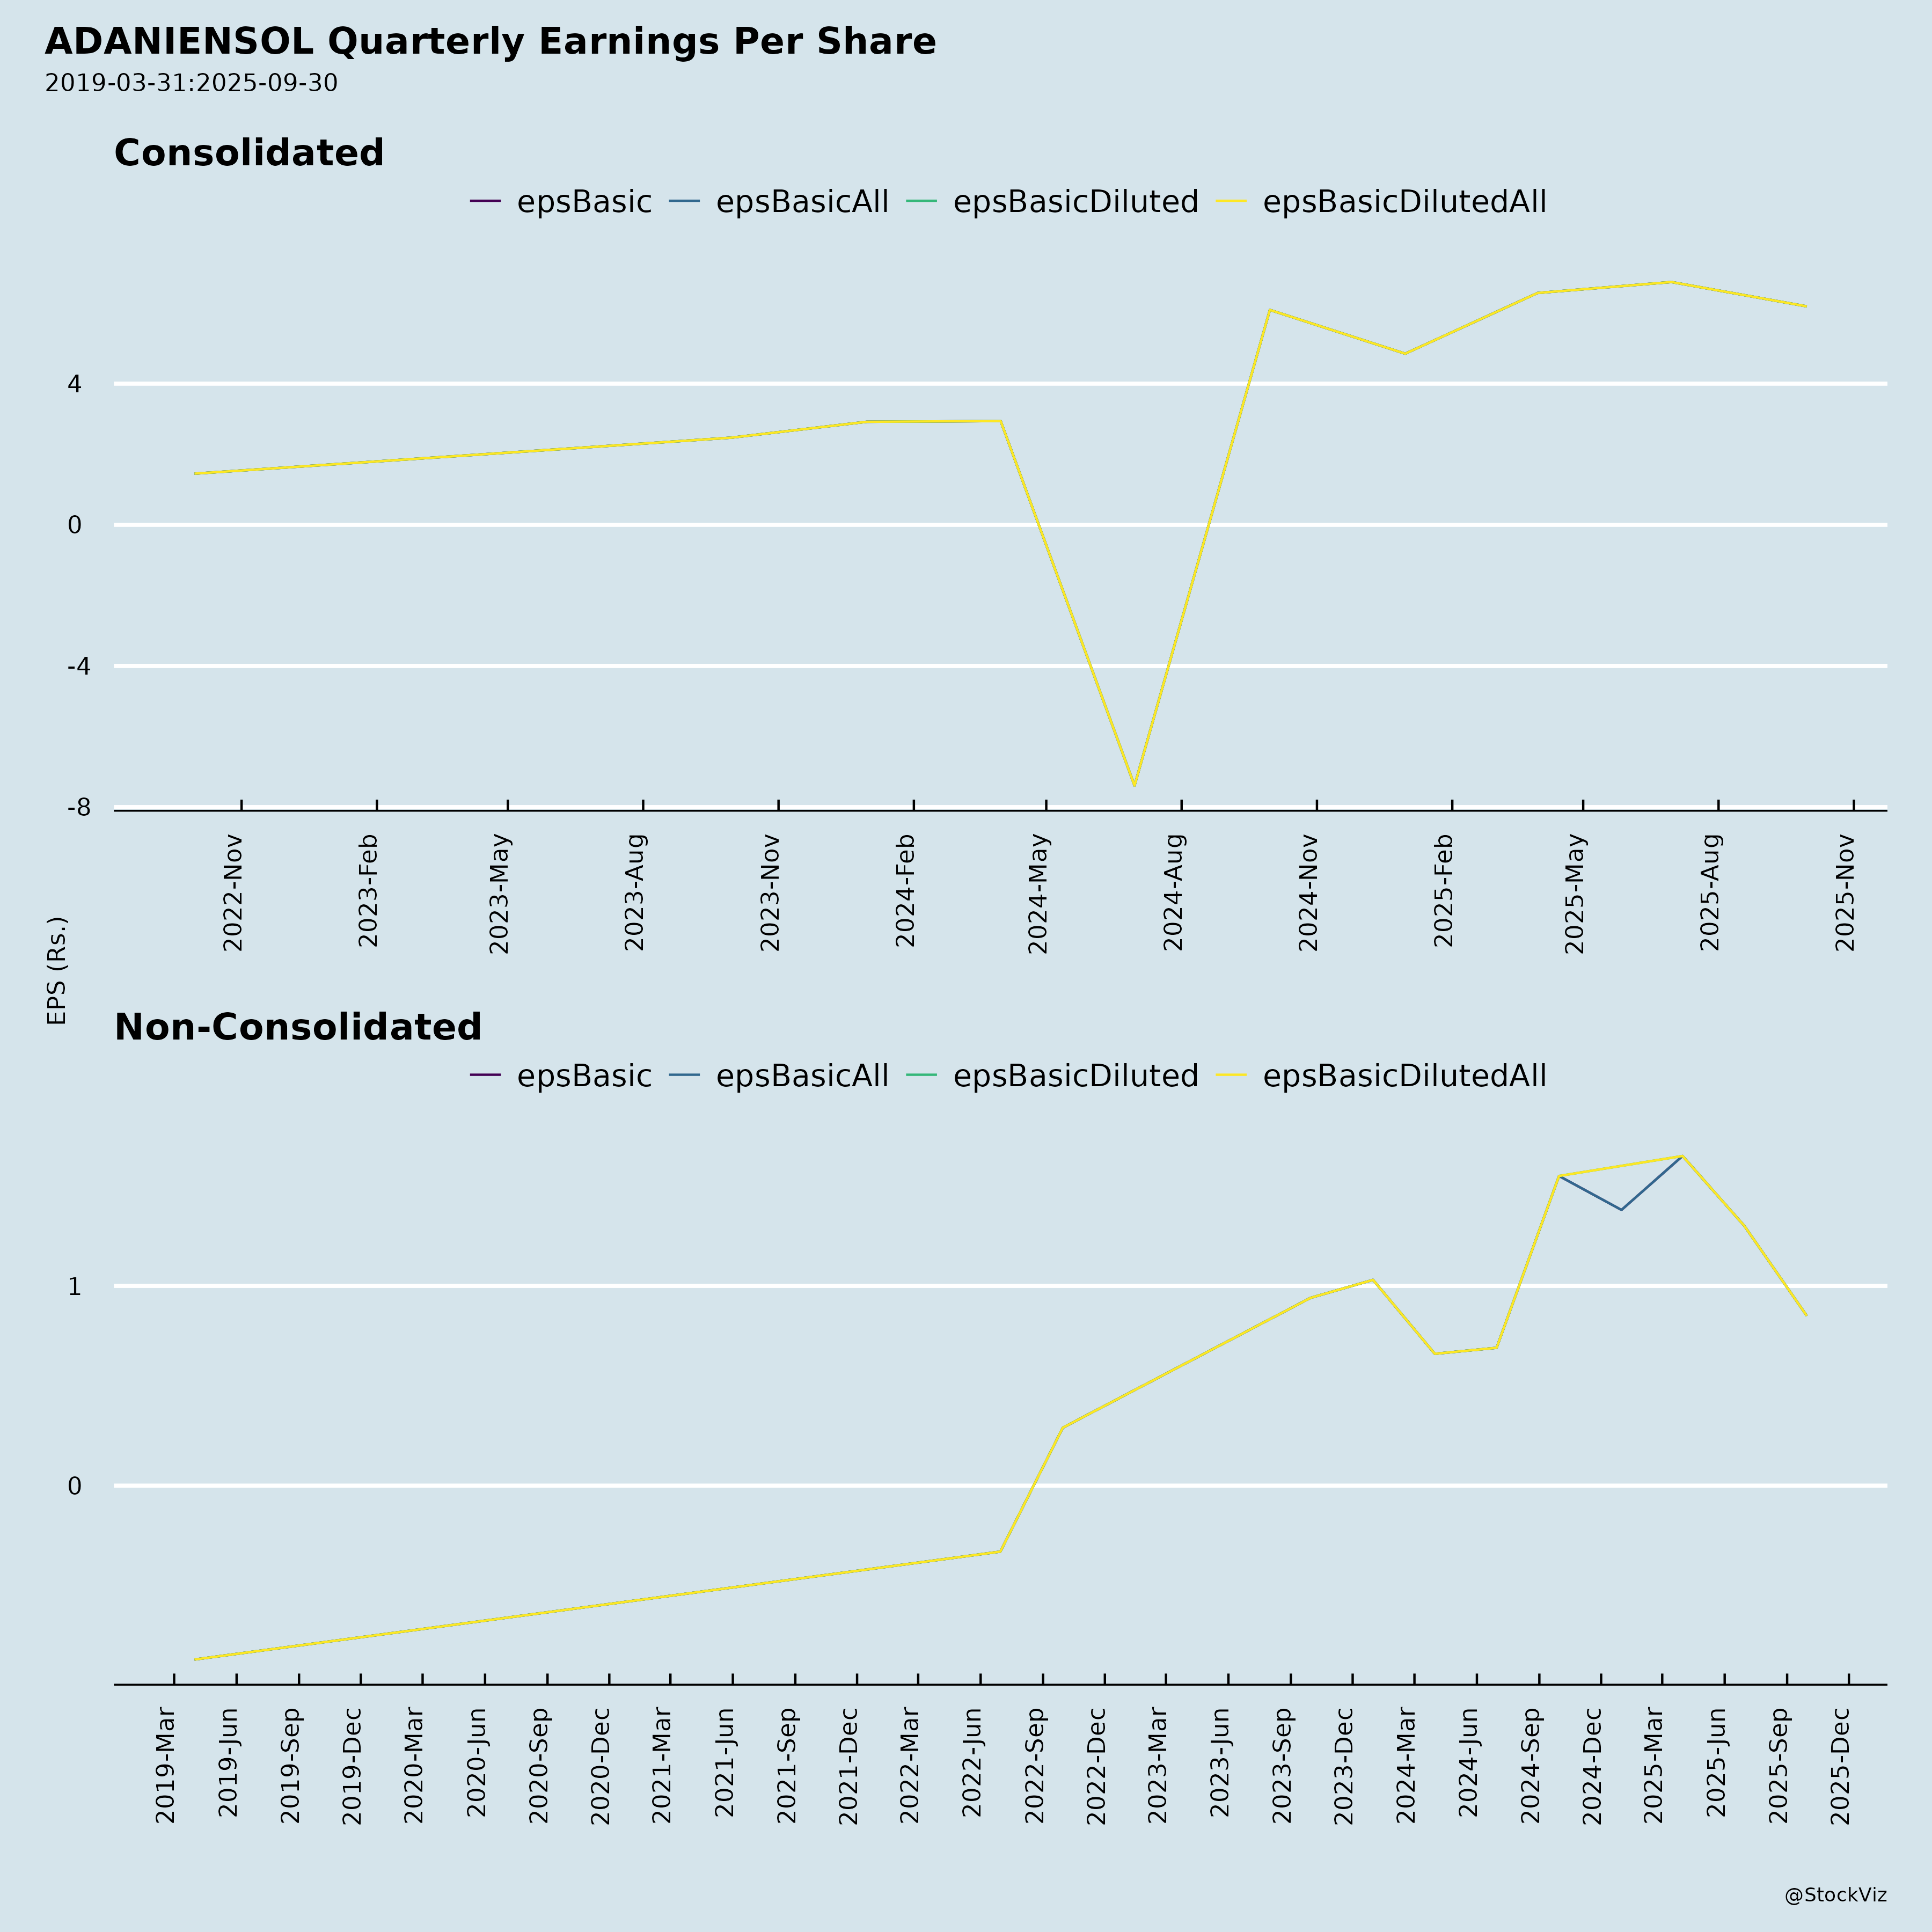
- Profitability pressure at consolidated level: Consolidated profit after tax was ₹538.94 crore for the quarter ended 30 June 2026, compared with ₹722.65 crore in the quarter ended 31 March 2026 and ₹1,236.56 crore in the quarter ended 30 June 2025. Total comprehensive income was ₹599.53 crore, versus ₹1,378.60 crore and ₹1,059.96 crore in the respective comparative periods.
- Standalone profitability decline: Standalone profit before tax was ₹150.00 crore for the quarter ended 30 June 2026, compared with ₹207.72 crore in the quarter ended 31 March 2026 and ₹63.79 crore in the quarter ended 30 June 2025. Standalone total comprehensive income was ₹149.49 crore, versus ₹607.88 crore and ₹32.14 crore in the comparative periods.
- Legal proceedings involving a non-executive director: During FY2024-25, the company became aware of a US DOJ indictment and a US SEC civil complaint against a non-executive director of the company. The allegations include securities fraud conspiracy, wire fraud conspiracy, and making false or misleading statements. The company states it is not named in these matters. As of 31 March 2026, the matter remained pending before the court. During the current quarter, the SEC filed a request for entry of final judgement upon the director’s consent without admitting or denying the allegations, and the DOJ filed a motion to dismiss charges in the indictment with prejudice. A motion is also pending approval before the EDNY.
Tailwinds and Growth Prospects
- Smart metering expansion: AESL is ramping up its smart metering business and is on course to become India’s leading smart metering integrator. The company has identified a new “Smart Meter” segment effective Q2 FY2025-26, reflecting the growing scale of this business.
- Acquisition of IntelliSmart Infrastructure: AESL executed a binding securities purchase and subscription agreement to acquire 100% equity stake in IntelliSmart Infrastructure Private Limited, a leading smart metering JV between the National Investment and Infrastructure Fund (NIIF) and Energy Efficiency Services Limited (EESL). The total consideration is ₹3,050 crore plus 4.7 crore meters, subject to customary and regulatory approvals. The acquisition is expected to strengthen AESL’s position as India’s largest smart metering platform.
- Power supply portfolio expansion: Powerpulse Trading Solutions Limited (PTSL), a wholly-owned subsidiary of AESL, entered into an agreement with Adani Power Limited on 8 September 2026, under which APL assigned all rights and obligations of a Letter of Award from MSEDCL to PTSL for supplying 2,500 MW Round-the-Clock power over 25 years. PTSL subsequently executed a Power Purchase Agreement with MSEDCL on 8 September 2026. The transaction is expected to further strengthen PTSL’s power supply portfolio and reinforce its position in the energy solutions business.
- Distribution network expansion: AESL is expanding its distribution network through parallel licenses and competitive retail solutions, and increasing its share of green power.
- ESG leadership: AESL achieved the distinction of being the highest ESG-scored company globally in the Utilities sector as assessed by S&P Global, securing an ESG Score of 90 out of 100 compared to an industry average of 41, driven by scores of 93 in Environmental, 89 in Social, and 84 in Governance & Economic.
- Capital raising approval: The company received shareholder approval via a special resolution at the Extra-ordinary General Meeting held on 25 July 2026 to raise capital from eligible investors through an issuance of equity shares and/or other eligible securities. The resolution was passed with 99.9995% of votes in favour.
- Segment performance: For the quarter ended 30 June 2026, the Transmission segment reported revenue of ₹3,335.26 crore and segment results of ₹1,327.46 crore. The Distribution segment reported revenue of ₹3,520.43 crore and segment results of ₹356.92 crore. The Energy Solutions Platform segment reported revenue of ₹1,906.83 crore and segment results of ₹590.27 crore.
Key Risks
- Regulatory deferral account volatility: The movement in regulatory deferral account balances significantly affects reported profitability, with a net expense of ₹(1,095.56) crore in the quarter ended 30 June 2026.
- Finance cost sensitivity: Consolidated finance costs remain substantial at ₹894.03 crore for the quarter, and the company’s debt position is significant, with total debt outstanding of ₹50,841.67 crore as at 30 June 2026 on a consolidated basis.
- Legal and regulatory proceedings: The ongoing US DOJ and SEC matters involving a non-executive director, while the company states it is not named, create uncertainty. The outcome of the pending motion before the EDNY remains to be determined.
- Execution risk on acquisitions: The IntelliSmart acquisition is subject to customary and regulatory approvals, and the transaction value is substantial at ₹3,050 crore plus 4.7 crore meters.
- Dependence on regulatory approvals for capital raising: The capital raising approved by shareholders on 25 July 2026 remains subject to the terms of the enabling resolution and applicable regulatory requirements.
Management Guidance Versus Observed Business Performance
- Smart metering: Management states AESL is on course to become India’s leading smart metering integrator. Observed performance shows the company has identified a new Smart Meter segment effective Q2 FY2025-26 and is acquiring IntelliSmart Infrastructure to strengthen its position as India’s largest smart metering platform. The Smart Meter segment is reported with a reconciling item of ₹(336) crore at the segment results level and ₹(11.14) crore at the total assets level for the quarter ended 30 June 2026.
- Power supply portfolio: Management states the PTSL-MSEDCL transaction is expected to further strengthen PTSL’s power supply portfolio and reinforce its position in the energy solutions business through the supply of 2,500 MW Round-the-Clock power over 25 years. The agreement was executed on 8 September 2026, and the PPA was executed on the same date.
- ESG: Management highlights AESL’s achievement of the highest ESG score globally in the Utilities sector by S&P Global, with a score of 90 out of 100. This is a reported achievement rather than a forward-looking guidance item.
- Capital raising: Shareholders approved the special resolution for raising capital on 25 July 2026 with 99.9995% votes in favour. The company has not provided specific guidance on the amount, timing, or terms of the capital raise in the supplied material.
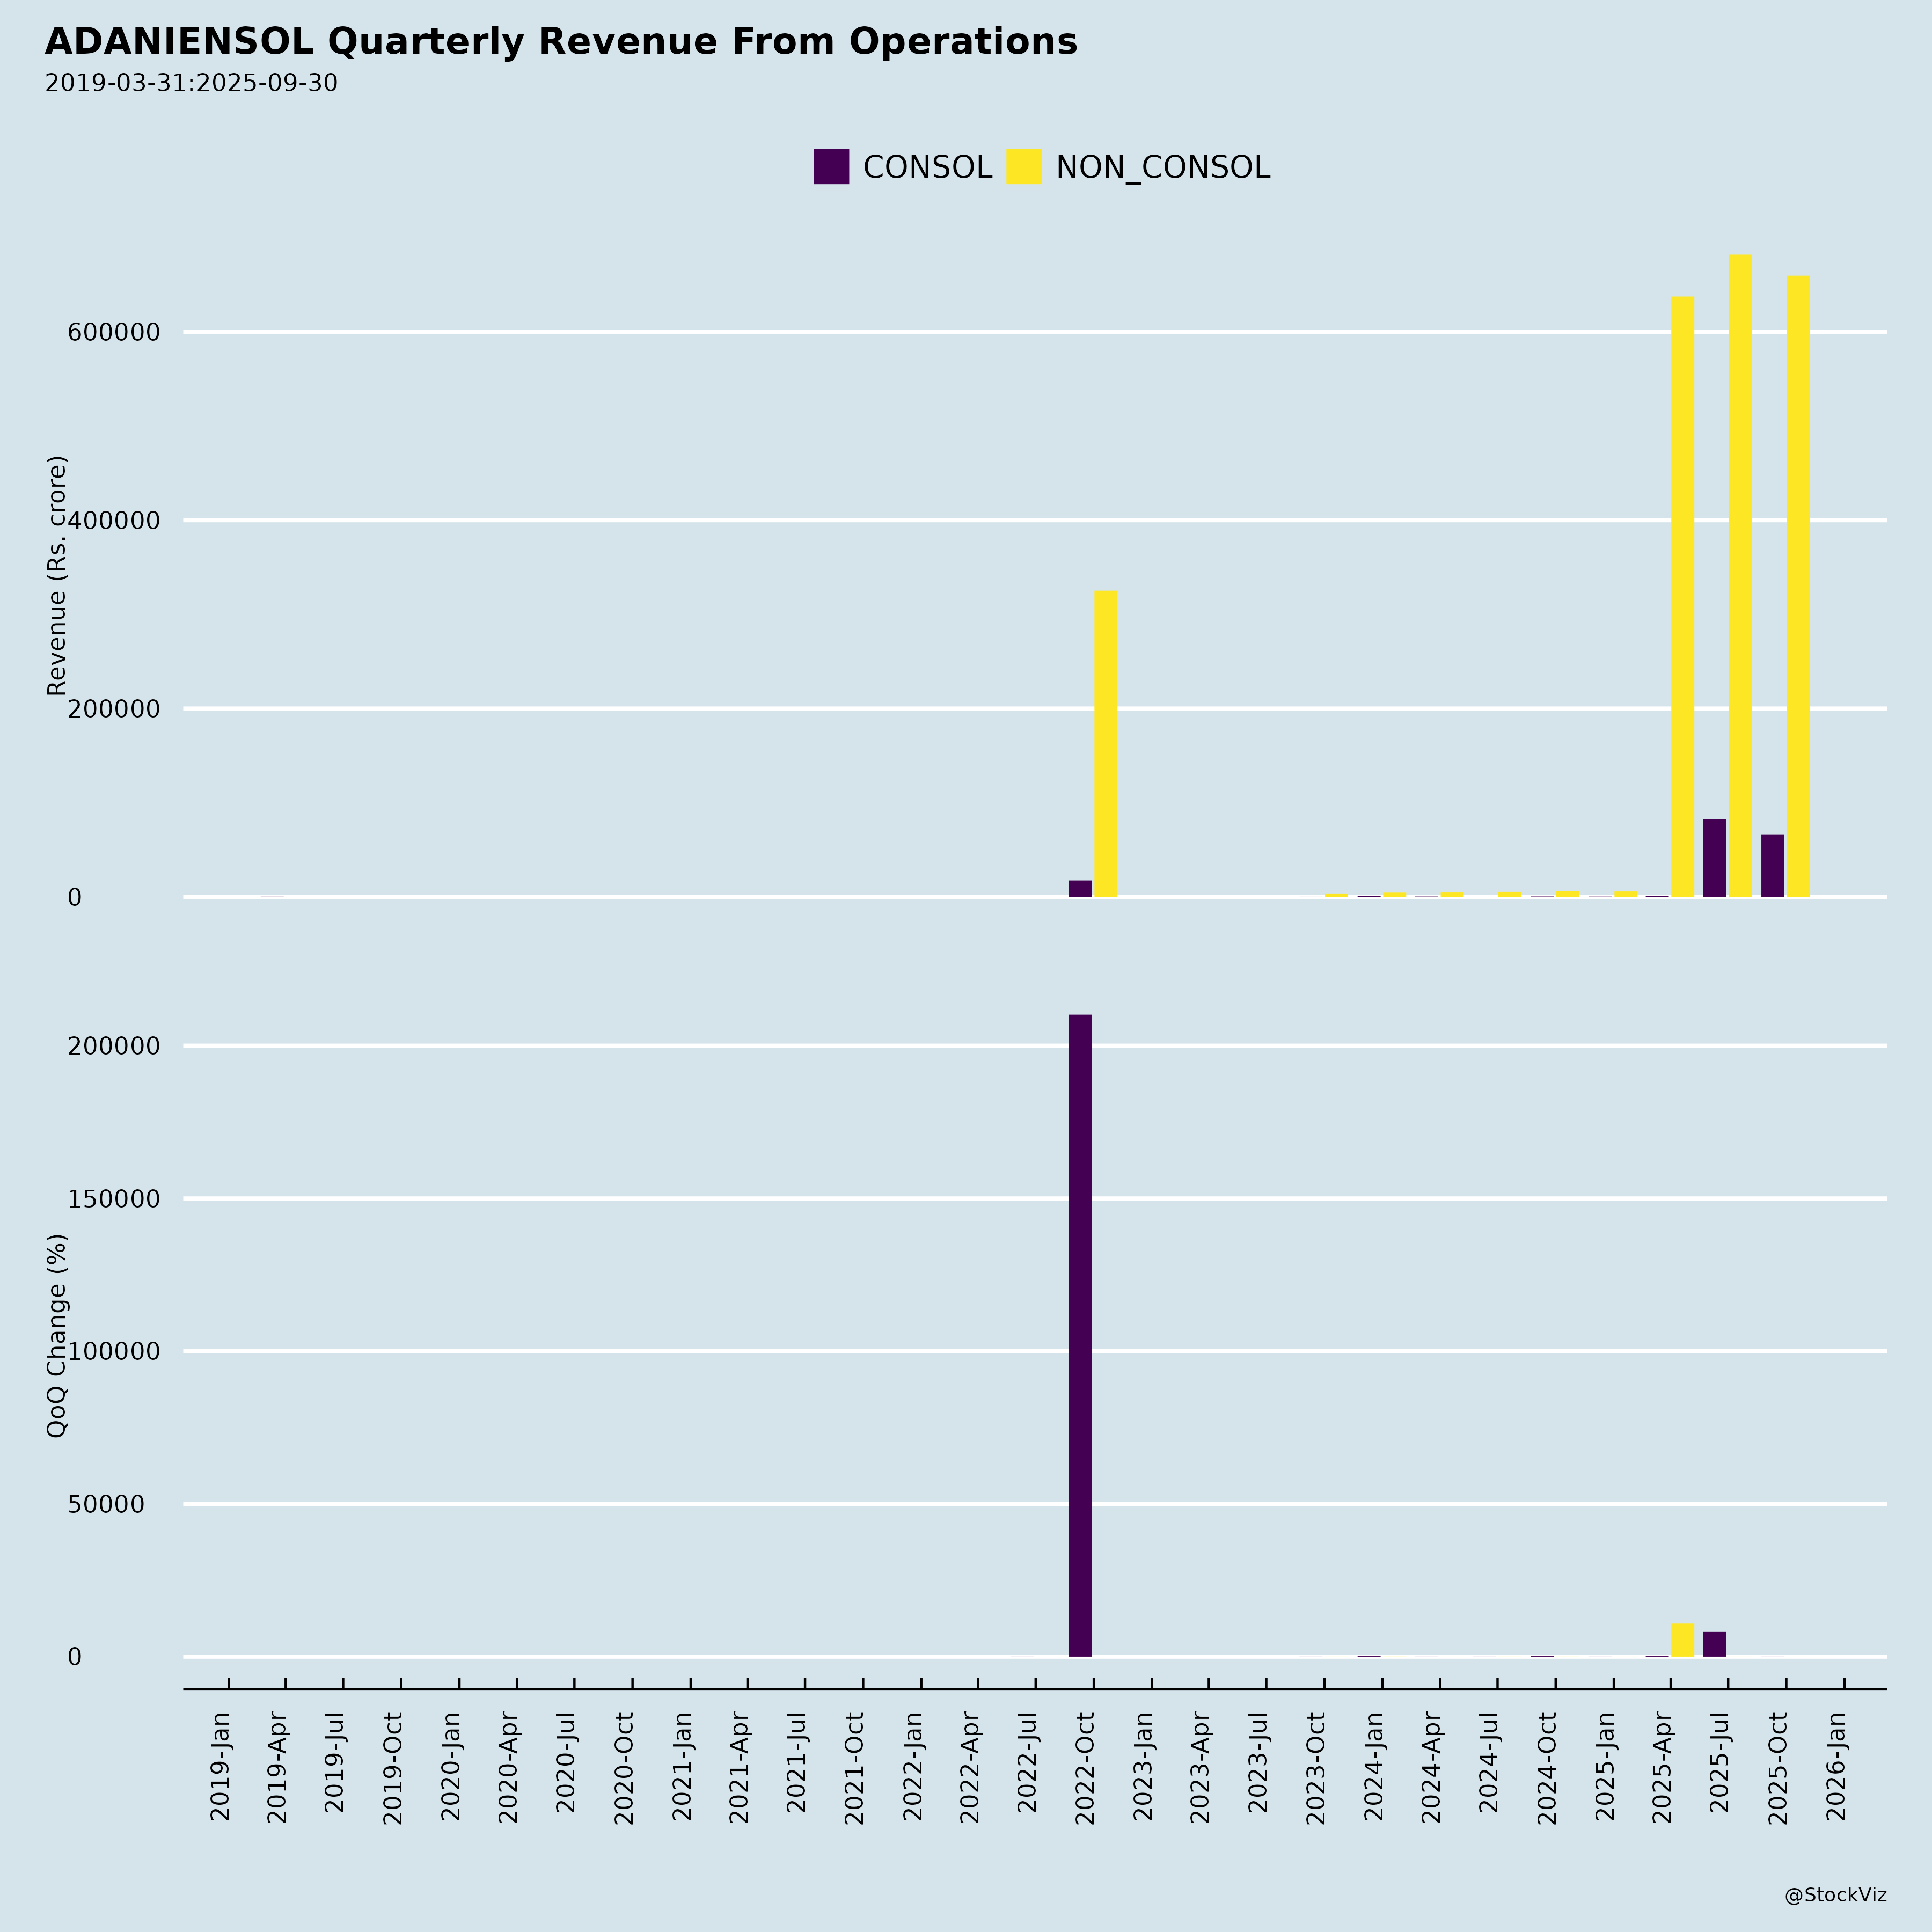
- Financial performance: Management has not provided specific forward-looking financial guidance in the supplied material. Observed performance shows consolidated revenue from operations of ₹9,711.08 crore for the quarter ended 30 June 2026, compared with ₹7,443.27 crore in the quarter ended 31 March 2026 and ₹6,819.28 crore in the quarter ended 30 June 2025. Consolidated profit after tax was ₹538.94 crore, compared with ₹722.65 crore and ₹1,236.56 crore in the respective comparative periods.
Broker Narrative
Broker narrative shifted from an upbeat 2024 view centered on a large transmission and smart meter pipeline, Mumbai DISCOM efficiency, and a 32% EBITDA CAGR, while flagging implementation, counterparty and refinancing risks, to a 2026 view focused on execution slippage—right-of-way delays and slow smart meter installations—despite a strong order book and the Mumbai HVDC commissioning. Early calls mostly delivered strong positive returns, but from mid-2026 several Hold and Buy calls resulted in negative actual returns and DISAPPOINTMENT outcomes as commissioning lagged; the latest October 2026 report turns Buy again on expected H2FY27 and FY28 transmission capitalization.
Fears that came true
- The early implementation risk around right-of-way and clearances materialized as delays in commissioning under-implementation transmission projects and lagged H1FY27 commissioning despite strong capex, coinciding with negative returns and DISAPPOINTMENT ratings.
- The early caution on limited smart meter operating track record and payment risk played out as installations slowed to 3.5 million in H1FY27 versus a 10 million earlier guide, with FY27 guidance cut to 8-9 million, weighing on the stock during disappointing broker periods.
Optimism that failed
- The optimistic smart meter ramp—around INR 1.2 trillion of bids and roughly 20 percent share—did not translate into the expected installation pace, with H1FY27 installations far below the 10 million guidance and FY27 revised down to 8-9 million meters.
Broker Timeline
13 broker calls · 2024-09-30 to 2026-10-25
CNBC-TV18: ratings, targets and commentary
No recorded CNBC-TV18 statements for this ticker.
Management comments
No recorded management comments with an explicit designation and affiliation for this ticker.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.