ABDL
Equity Metrics
September 24, 2026
Allied Blenders and Distillers Limited
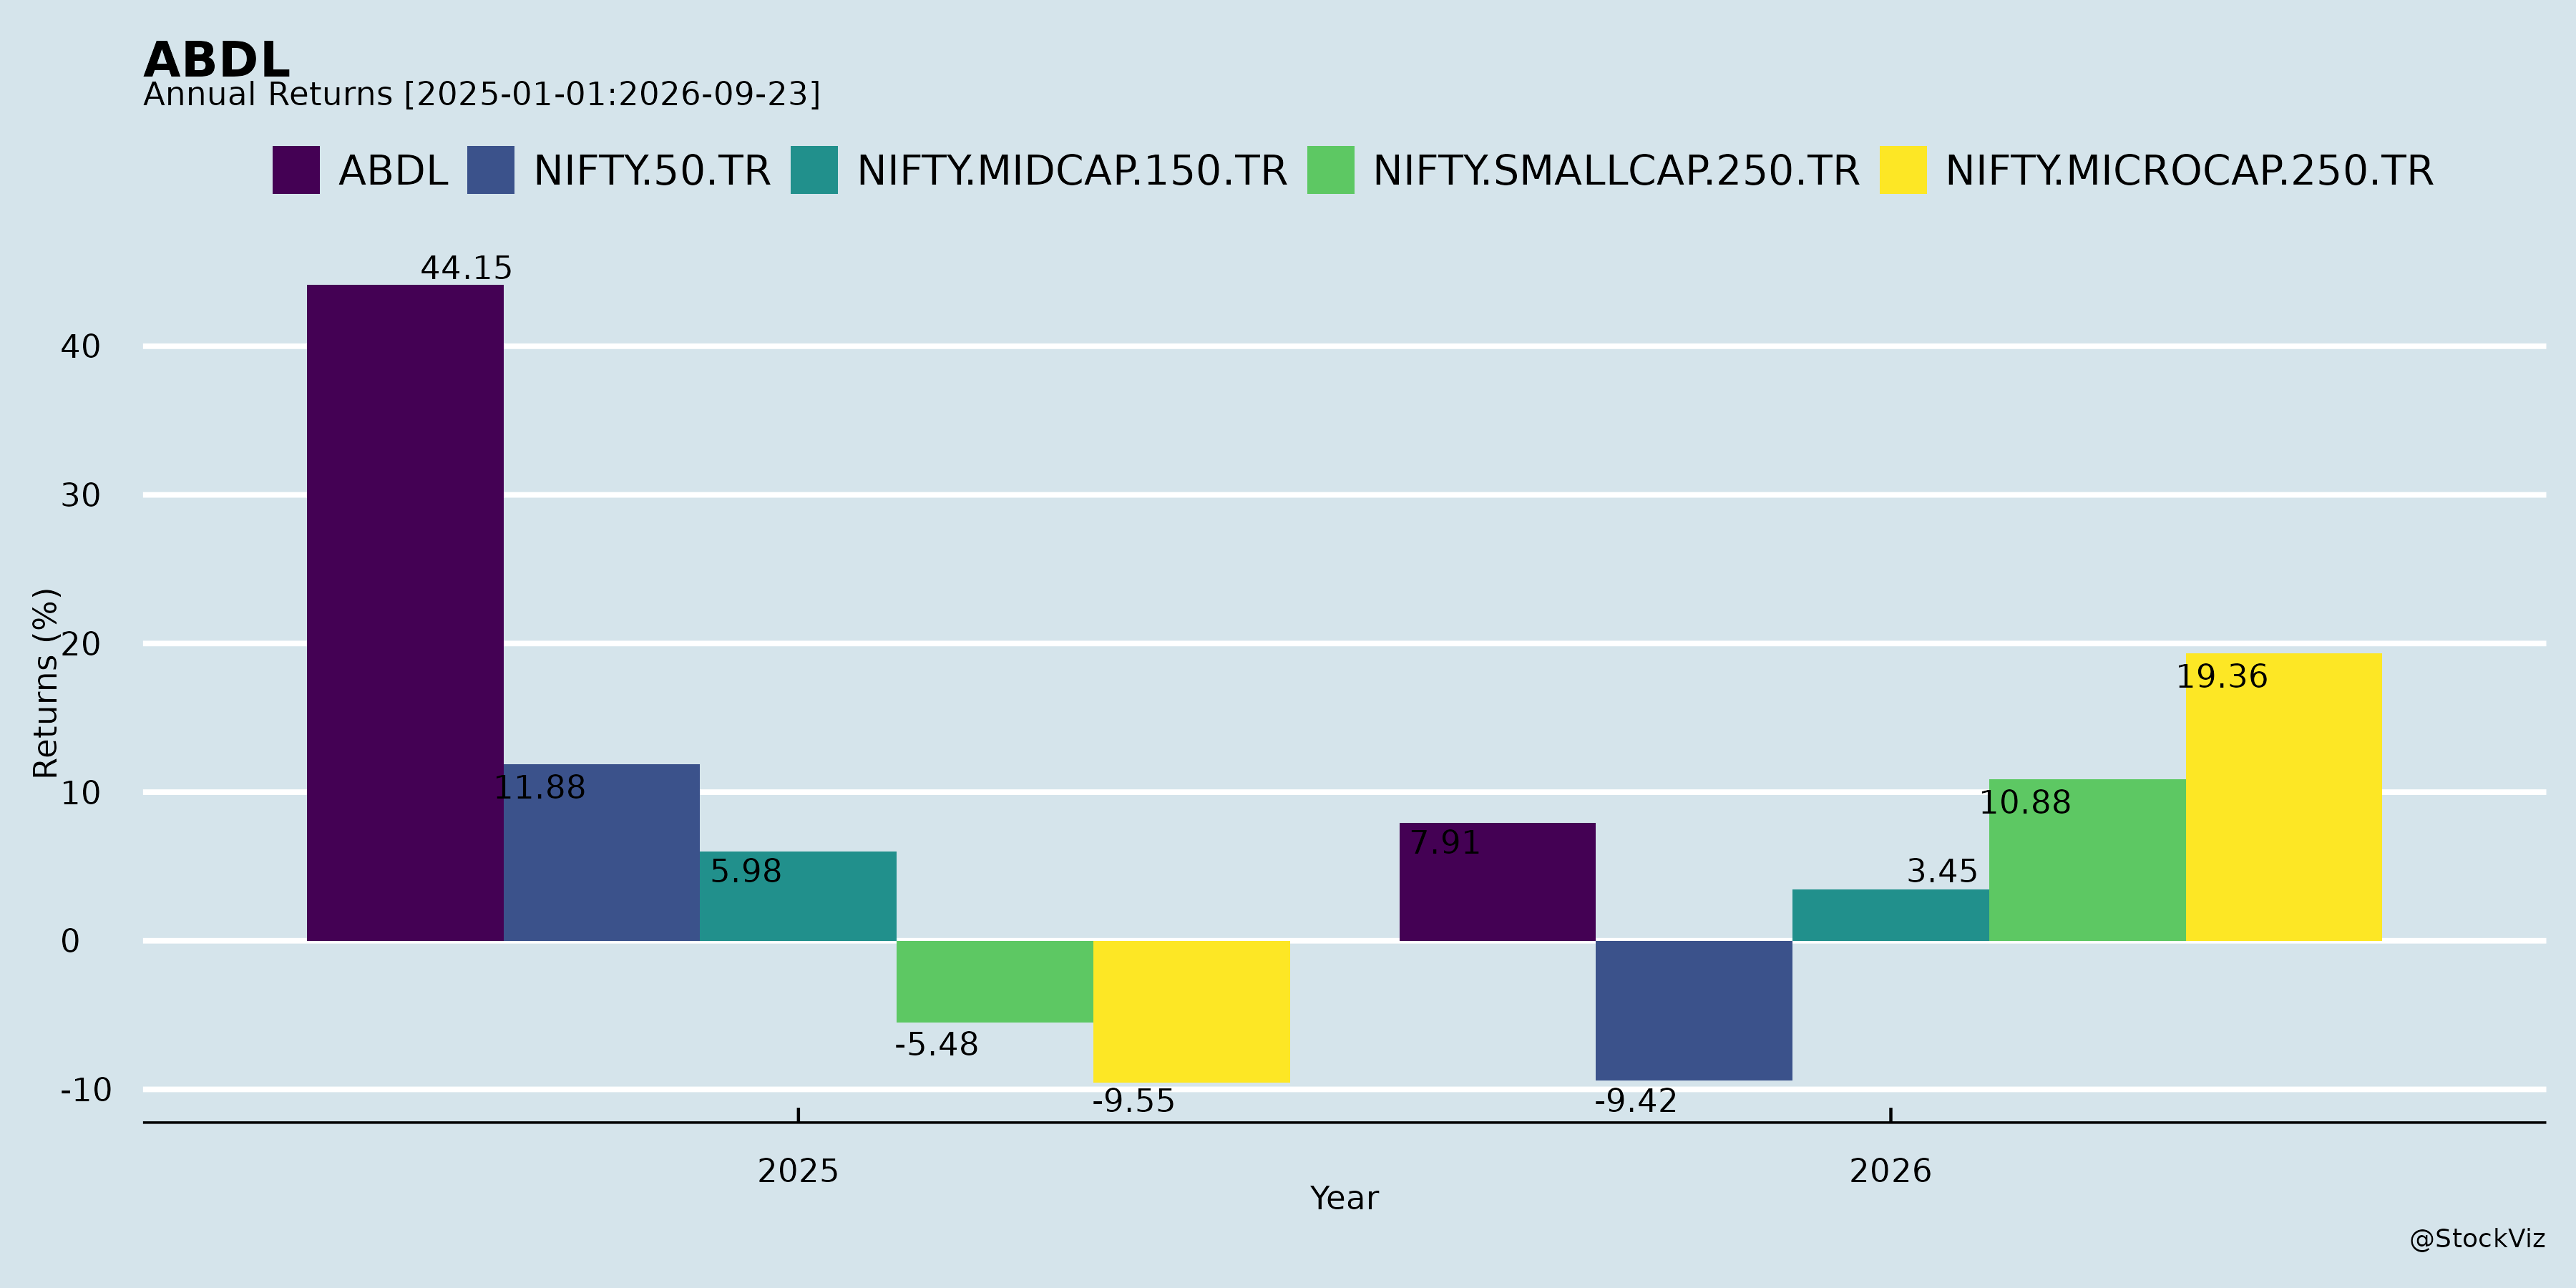
Annual Returns

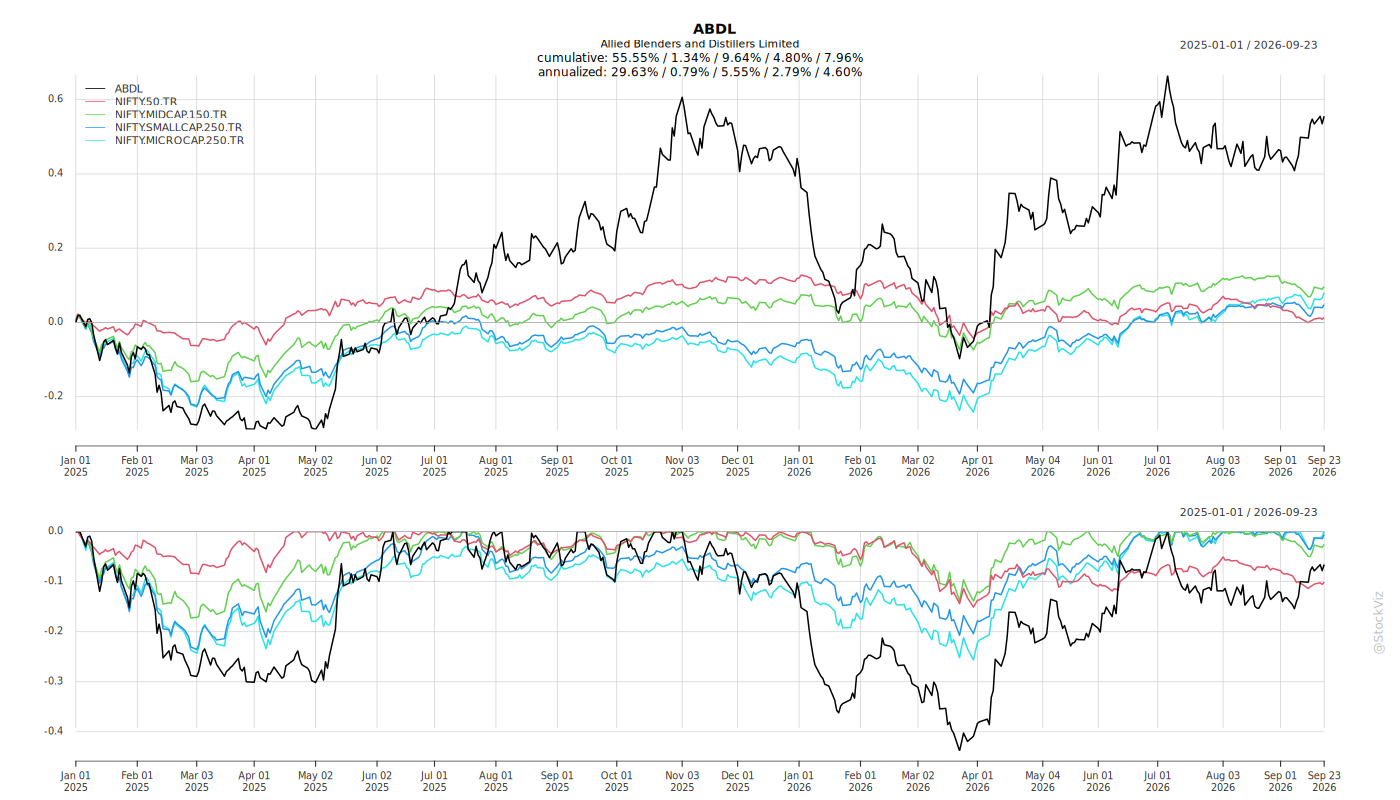
Cumulative Returns and Drawdowns
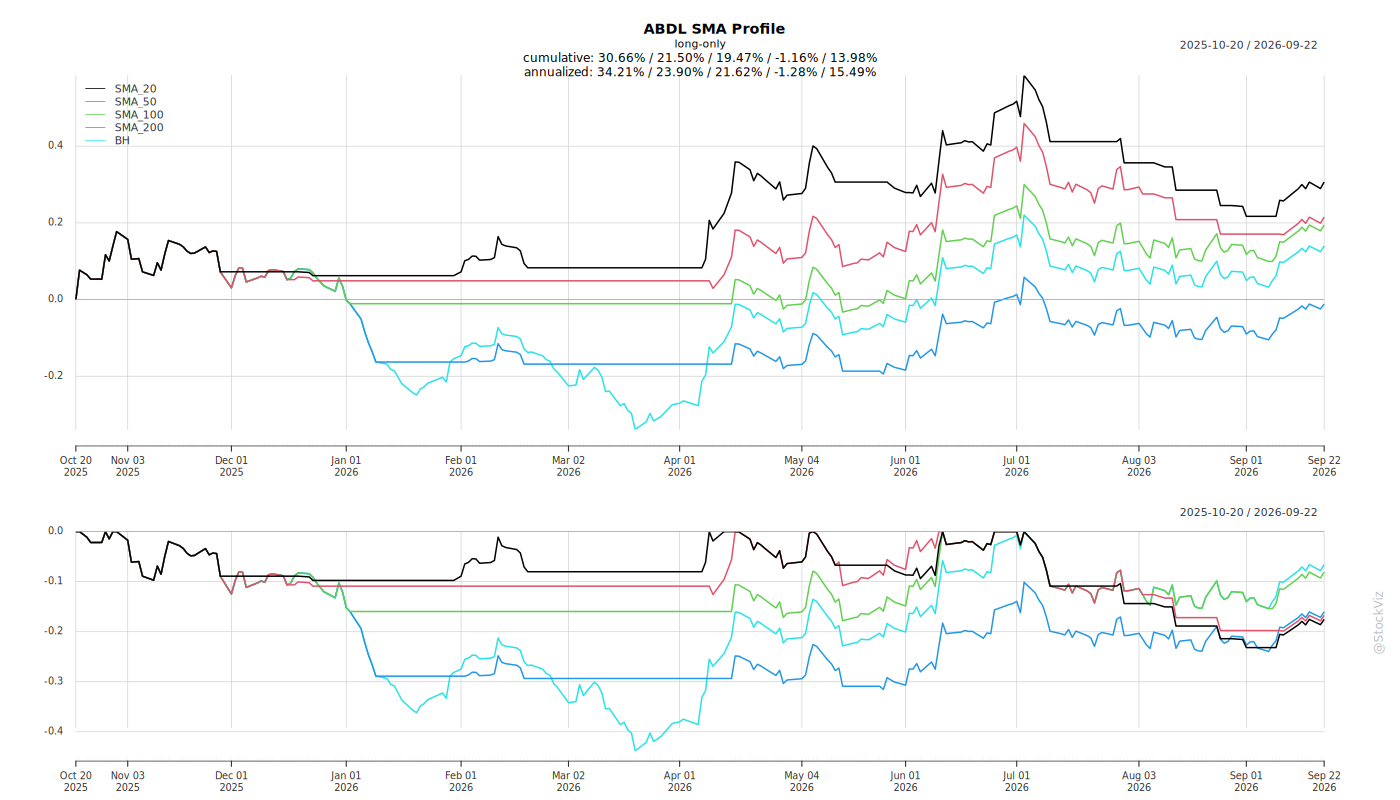
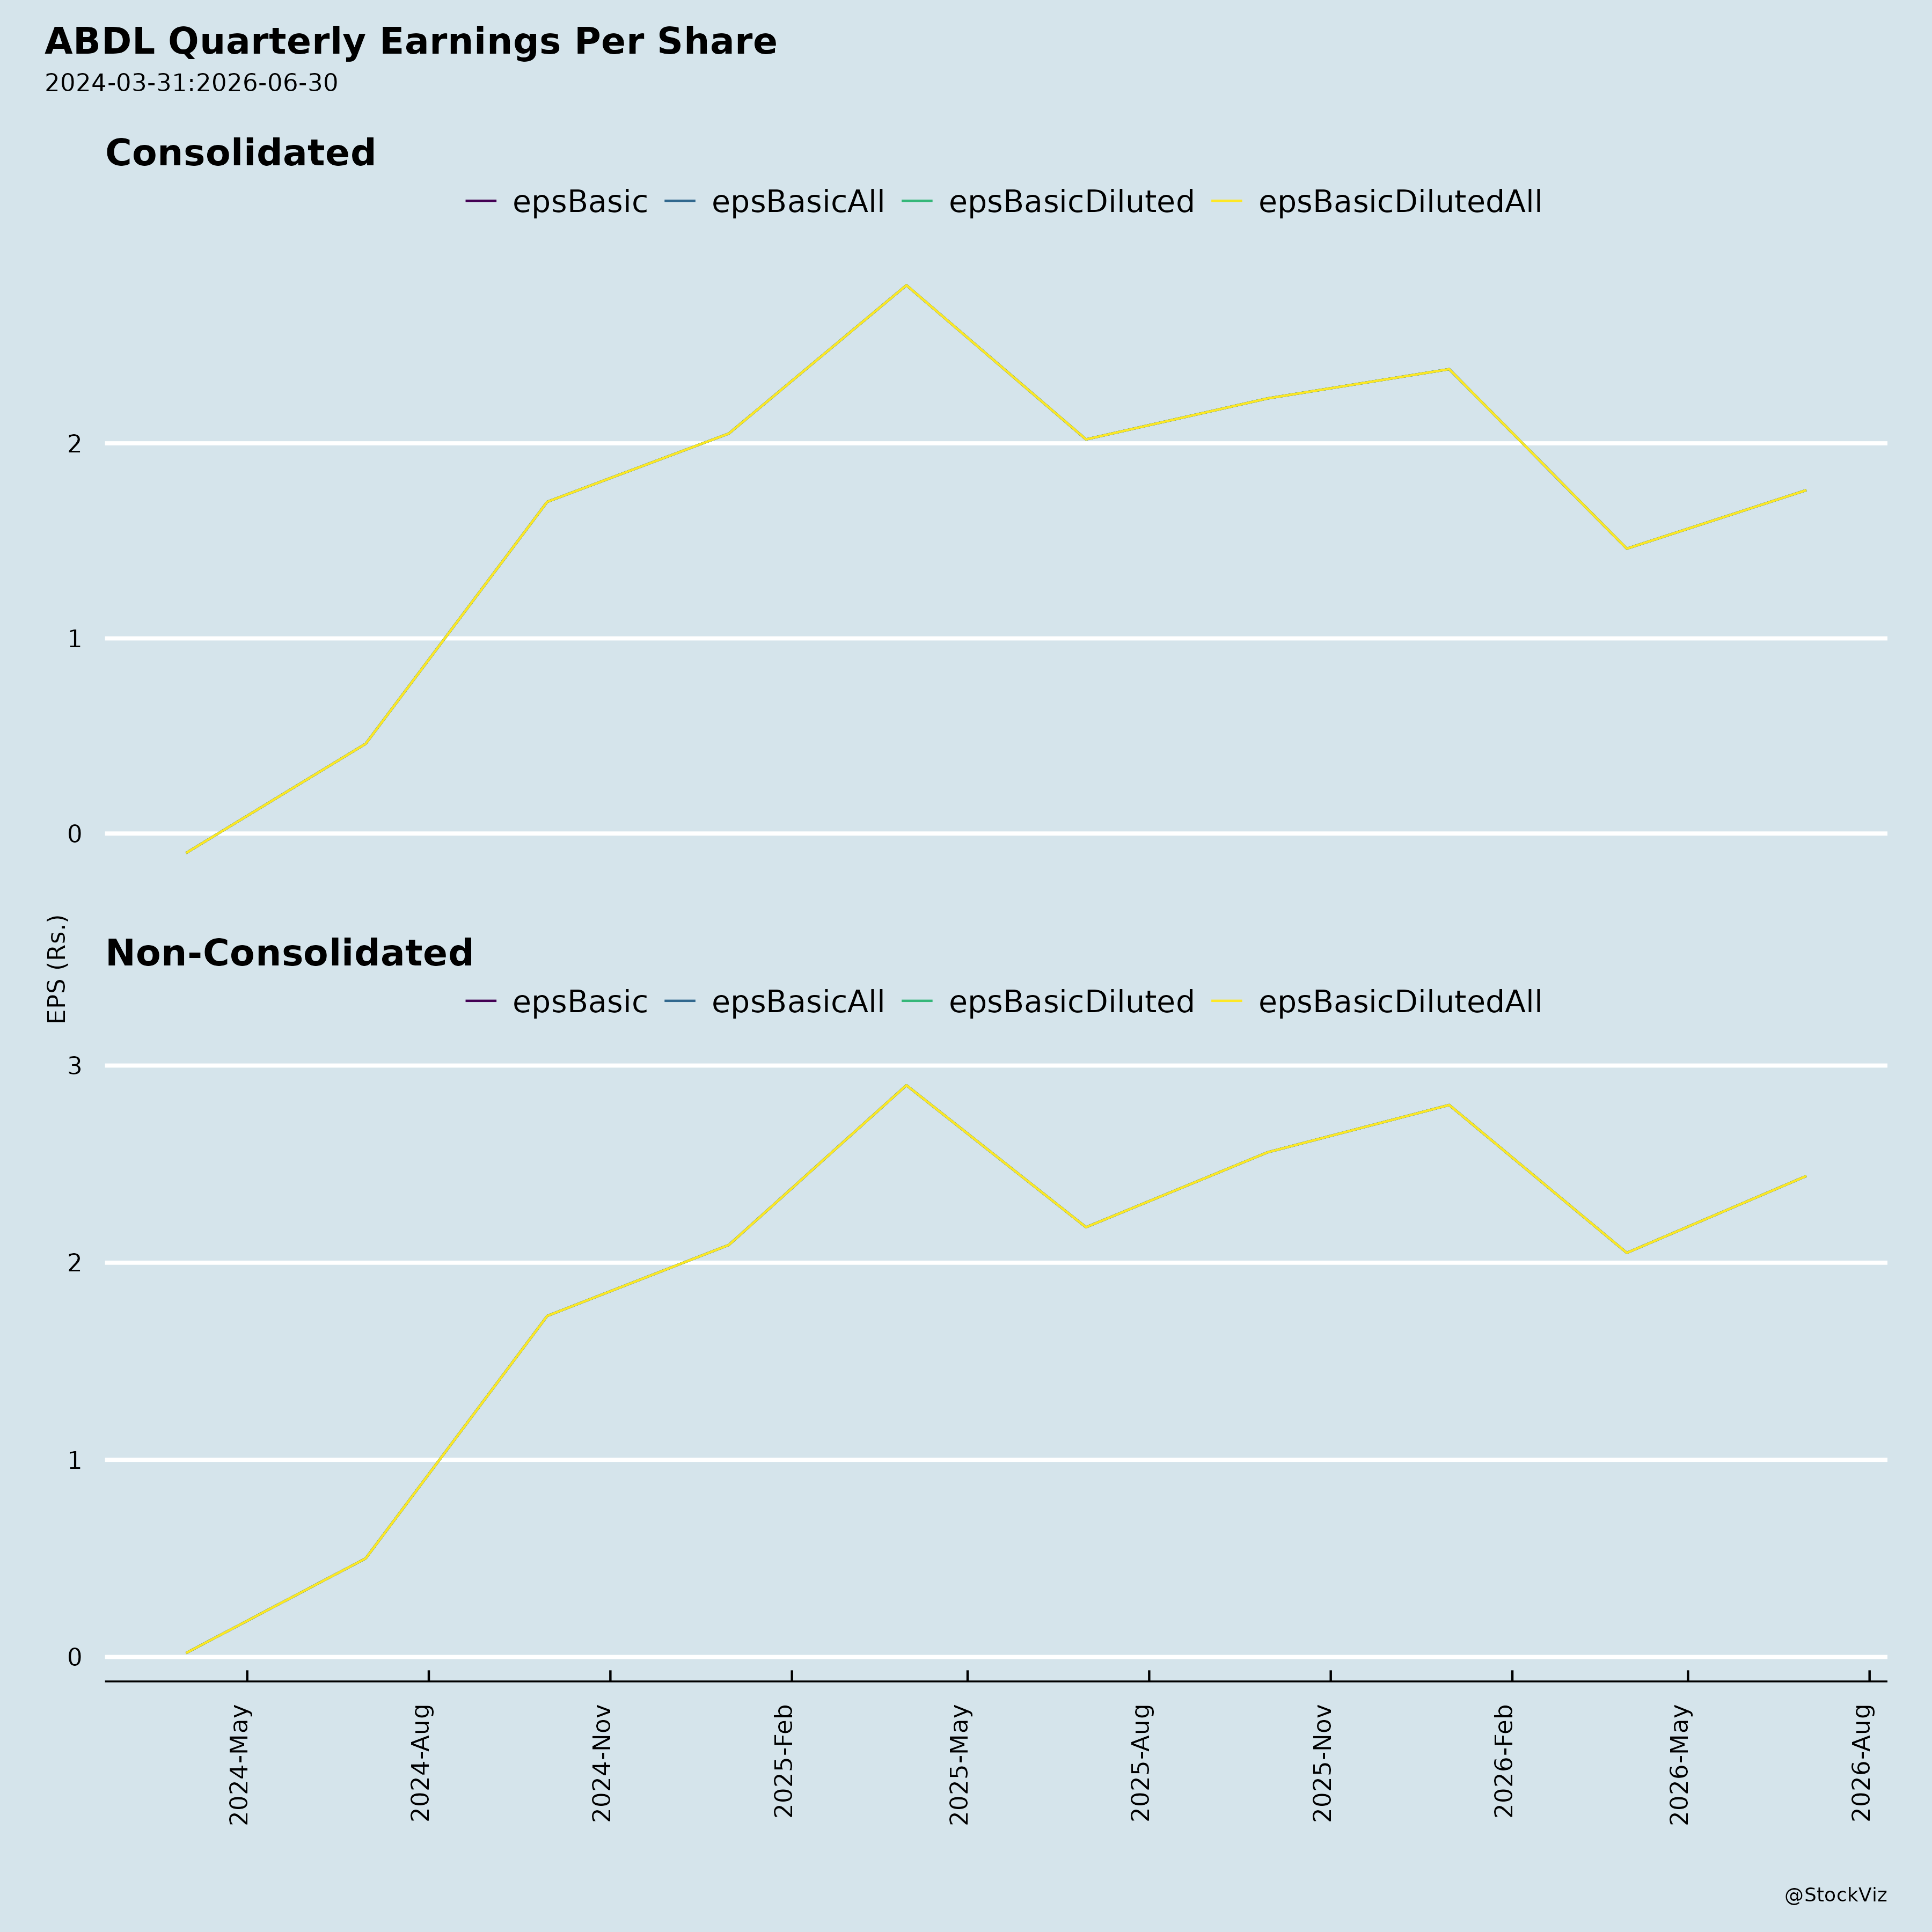
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
ABD Q1FY27: Headwinds, Tailwinds, Risks and Guidance vs Performance
1. Headwinds and Challenges
Global supply chain disruptions. The quarter was affected by temporary global supply chain disruptions, quantified at ₹24 Cr. Excluding this, like-to-like EBITDA would have been ₹144 Cr (+21.4%) with LTL EBITDA margin at 14.7% (+189 bps) and LTL PAT of ₹63 Cr (+13.6%). Reported EBITDA was ₹120 Cr versus ₹119 Cr in Q1FY26, and reported PAT was ₹45 Cr versus ₹56 Cr.
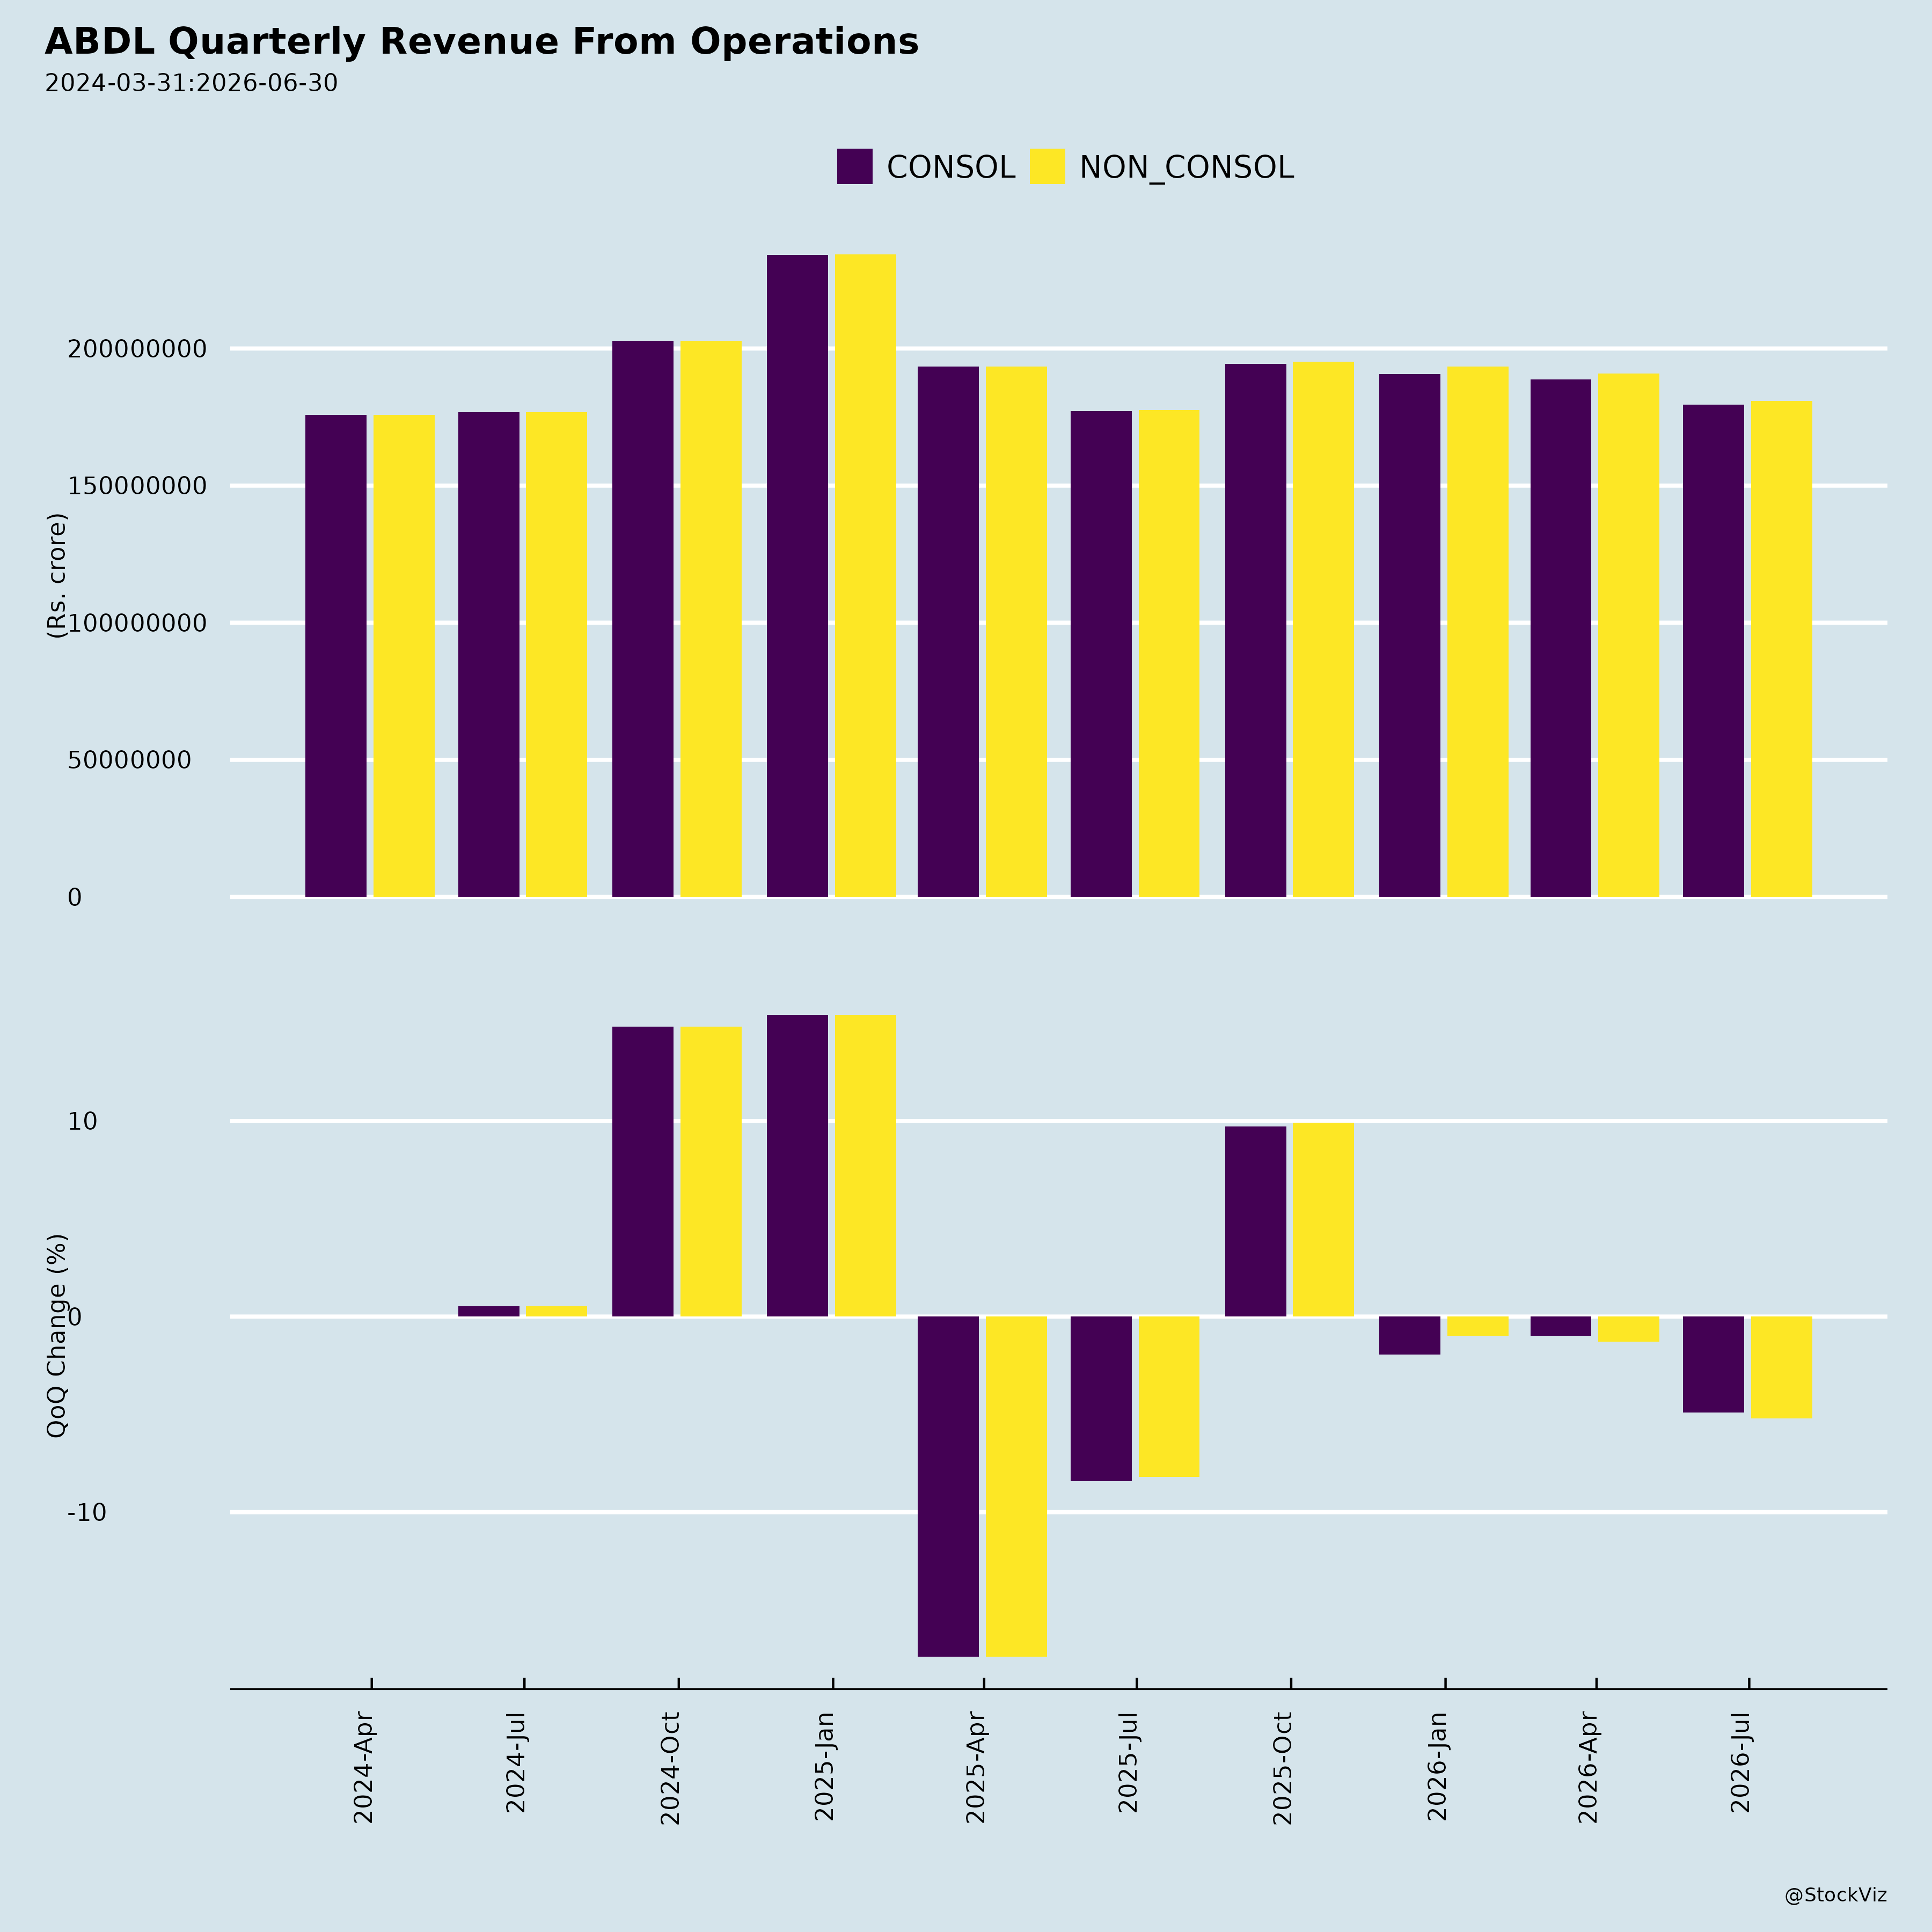
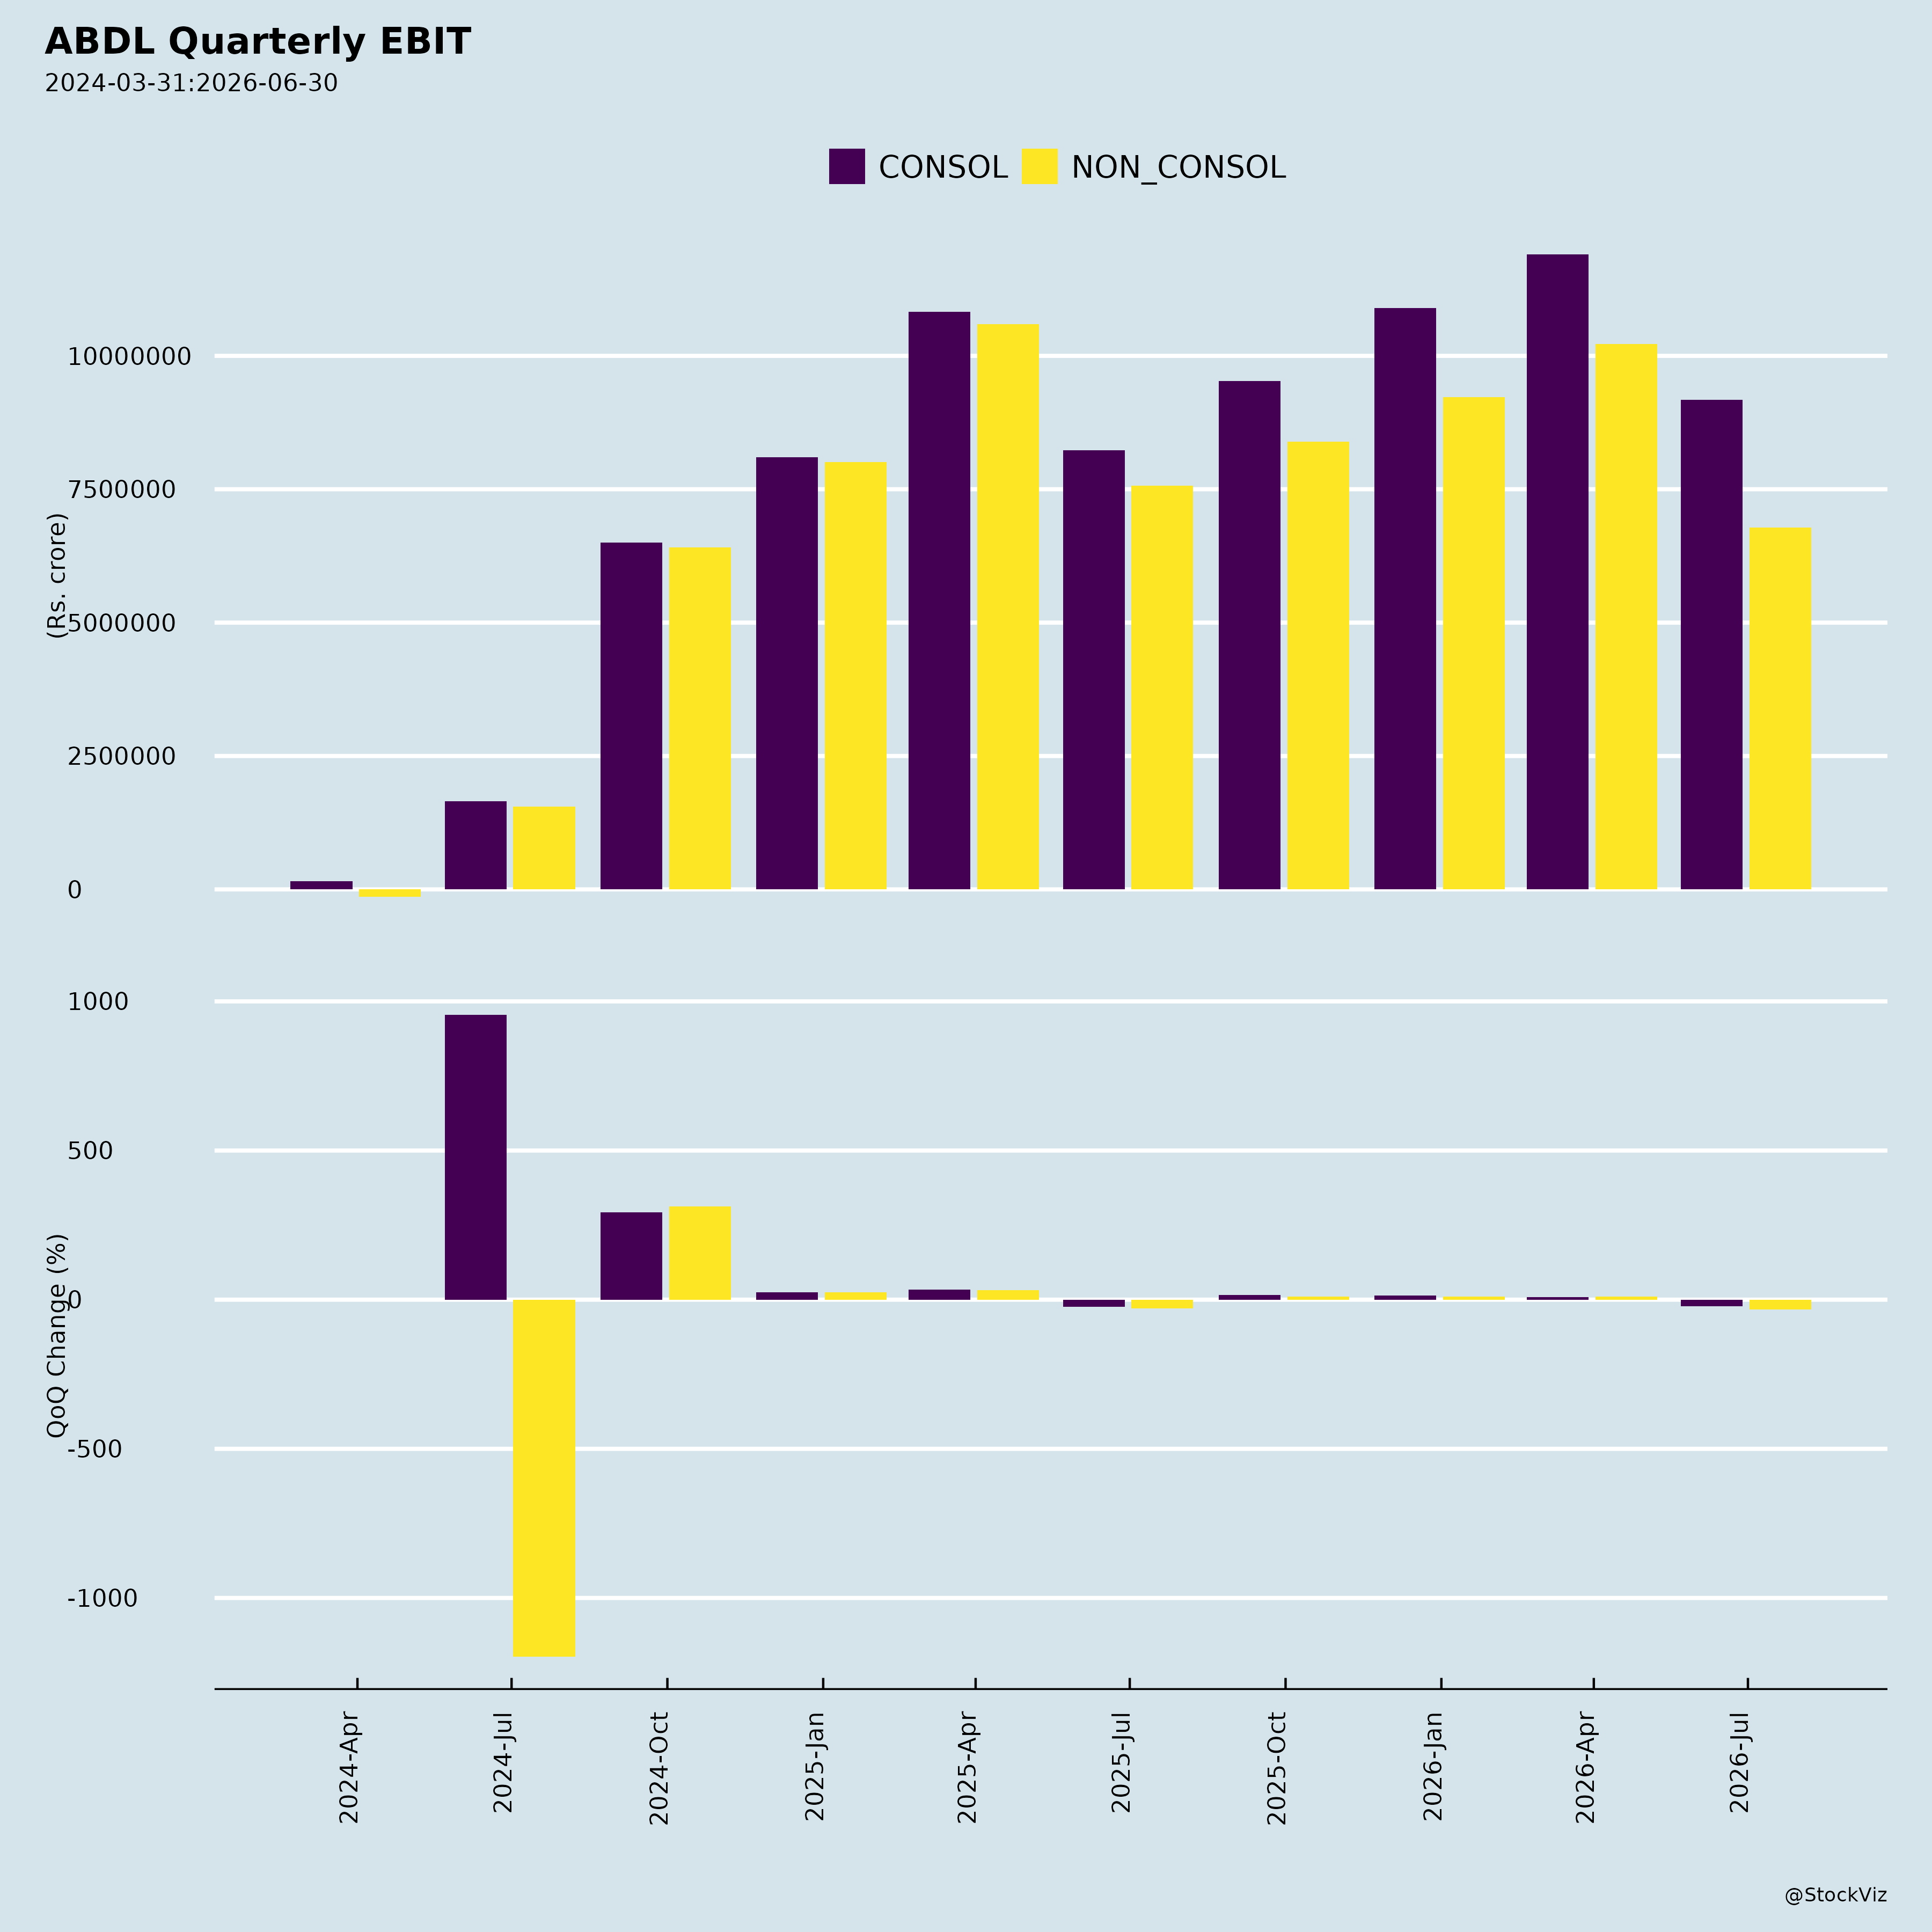
Margin moderation. EBITDA margin came in at 12.2% versus 12.8% in Q1FY26, a decline of 55 bps, as gross margin gains were more than offset by planned investments in people, core brands and the newly established luxury portfolio. Sequentially, EBITDA margin fell from 17.9% in Q4FY26 to 12.2% in Q1FY27.
Seasonality and sequential softness. Q1 is described as a low consumption quarter versus Q4 due to seasonality. Income from operations declined 3.6% Q-o-Q to ₹984 Cr, total volume declined 2.7% Q-o-Q to 9.0 Mn cases, and Mass Premium & Others volume declined 4.8% Q-o-Q.
Mass Premium & Others softness. While this segment grew 2.3% in volume Y-o-Y, sales value was nearly flat at 0.4% Y-o-Y and realization per case declined 1.9% Y-o-Y to ₹824. The “Others” line fell 42.5% Y-o-Y to ₹35 Cr.
Cost escalation. Total operating expenses rose 16.5% Y-o-Y to ₹335 Cr. Depreciation rose 46.6% Y-o-Y to ₹23 Cr and interest rose 7.3% Y-o-Y to ₹29 Cr. Profit before tax declined 10.3% Y-o-Y to ₹68 Cr.
Legacy disputes. A CSD debit memorandum demand of approximately ₹3,398.72 lakhs (net of adjustments) relating to differential trade rates for sales made between 1 March 2012 and 31 October 2017 remains contested through arbitration, with hearings held on 20–21 July 2026 and scheduled for 27–28 July 2026. Separately, an Income Tax search conducted between 11 and 17 December 2023 led to assessment orders for AYs 2014-15 to 2024-25 with an aggregate demand of ₹35,231 lakhs plus interest of ₹24,914 lakhs; this was subsequently revised to ₹2,607.53 lakhs and ₹1,937.71 lakhs respectively, and a tax expense including interest of ₹4,545.24 lakhs was recognised in the quarter and year ended 31 March 2026.
Medium-term inflation. Management notes a sustained emphasis on margin improvement “in a medium-term inflationary environment.”
2. Tailwinds and Growth Prospects
Premiumisation momentum. Prestige & Above (P&A) volume grew 10.7% Y-o-Y to 4.4 Mn cases and P&A sales value grew 16.0% Y-o-Y to ₹563 Cr. P&A realization per case improved 4.8% Y-o-Y to ₹1,293. P&A salience in volume has risen from 37.3% in FY24 to 47.2% in FY26, with a target of 50% by FY28.
ICONiQ White scale-up. ICONiQ White grew 33.8% to 3.1 Mn cases in Q1FY27 versus 2.3 Mn in Q1FY26, after crossing 10.7 Mn cases in FY26 versus 5.7 Mn in FY25. It is described as the fastest growing millionaire whisky brand globally for CY23, CY24 and CY25.
Gross margin expansion. Gross margin expanded 277 bps Y-o-Y to 46.0%, supported by a favourable input cost environment and backward integration benefits. On an LTL basis, gross margin was 48.4% (+522 bps Y-o-Y).
Backward integration. The Rangapur PET bottle manufacturing unit (600 Mn bottles p.a., ₹115 Cr investment) was commissioned in September 2025, is EBITDA accretive from Q3FY26, and secures 70–75% of PET packaging requirements. The Aurangabad ENA distillery was acquired in December 2024 and fully operational in February 2025. Malt distillery at Rangapur (4.0 MLPA, ₹75 Cr) is targeted for H1FY27. Management guides to EBITDA margin enhancement of ~300 bps by FY28 and incremental ~100 bps by FY29 from these initiatives.
Export expansion. The company operates an asset-light export model with profitability ~1.3x domestic and working capital ~1/3rd of domestic. Reach expanded to 39 countries in June 2026 from 36 in Q1FY27, with plans to reach ~1 Mn cases in Africa by FY28 and expand in LatAm, EU, North America and South East Asia.
ABD Maestro luxury portfolio. A 10-brand super-premium to luxury portfolio has been built through a “Build, Buy & Partner” model, with ~80% addressable market presence, ~5,500 premium touchpoints, presence in 6 countries and 4 travel retail locations. The portfolio has won 30+ global awards. Zoya Pink was launched in April 2026, and a new berry-flavoured gin was added.
UK FTA. Expected to enhance margins and strengthen the premium and luxury portfolio through greater sourcing flexibility, with the company described as one of the largest bulk Scotch importers.
Regulatory environment. Described as supportive, with most key state policy updates in place; further momentum expected from the Telangana policy and anticipated price revisions. Improving sentiment in Telangana for gradual clearance of outstanding dues.
Cash flow and balance sheet. Operating cash flow was ₹174 Cr in Q1FY27. Net debt reduced by ₹33 Cr to ₹947 Cr in June 2026 from ₹981 Cr in March 2026. Net Debt/EBITDA was 1.7x and Net Debt/Equity 0.6x, both within the stated framework of <2.0x and <0.75x.
Capital raise authorisation. The AGM held on 6 July 2026 approved raising funds by issuance of equity shares and/or other securities for an amount not exceeding ₹1,000 Cr, and increased borrowing limits under Section 180(1)(c) up to ₹1,600 Cr.
3. Key Risks
Customer dispute. The CSD claim of approximately ₹3,398.72 lakhs (net of adjustments) remains sub judice, with arbitration hearings ongoing. Management, supported by external legal opinion, assesses the probability of the claim fructifying into a liability as remote and treats the receivable as good and recoverable.
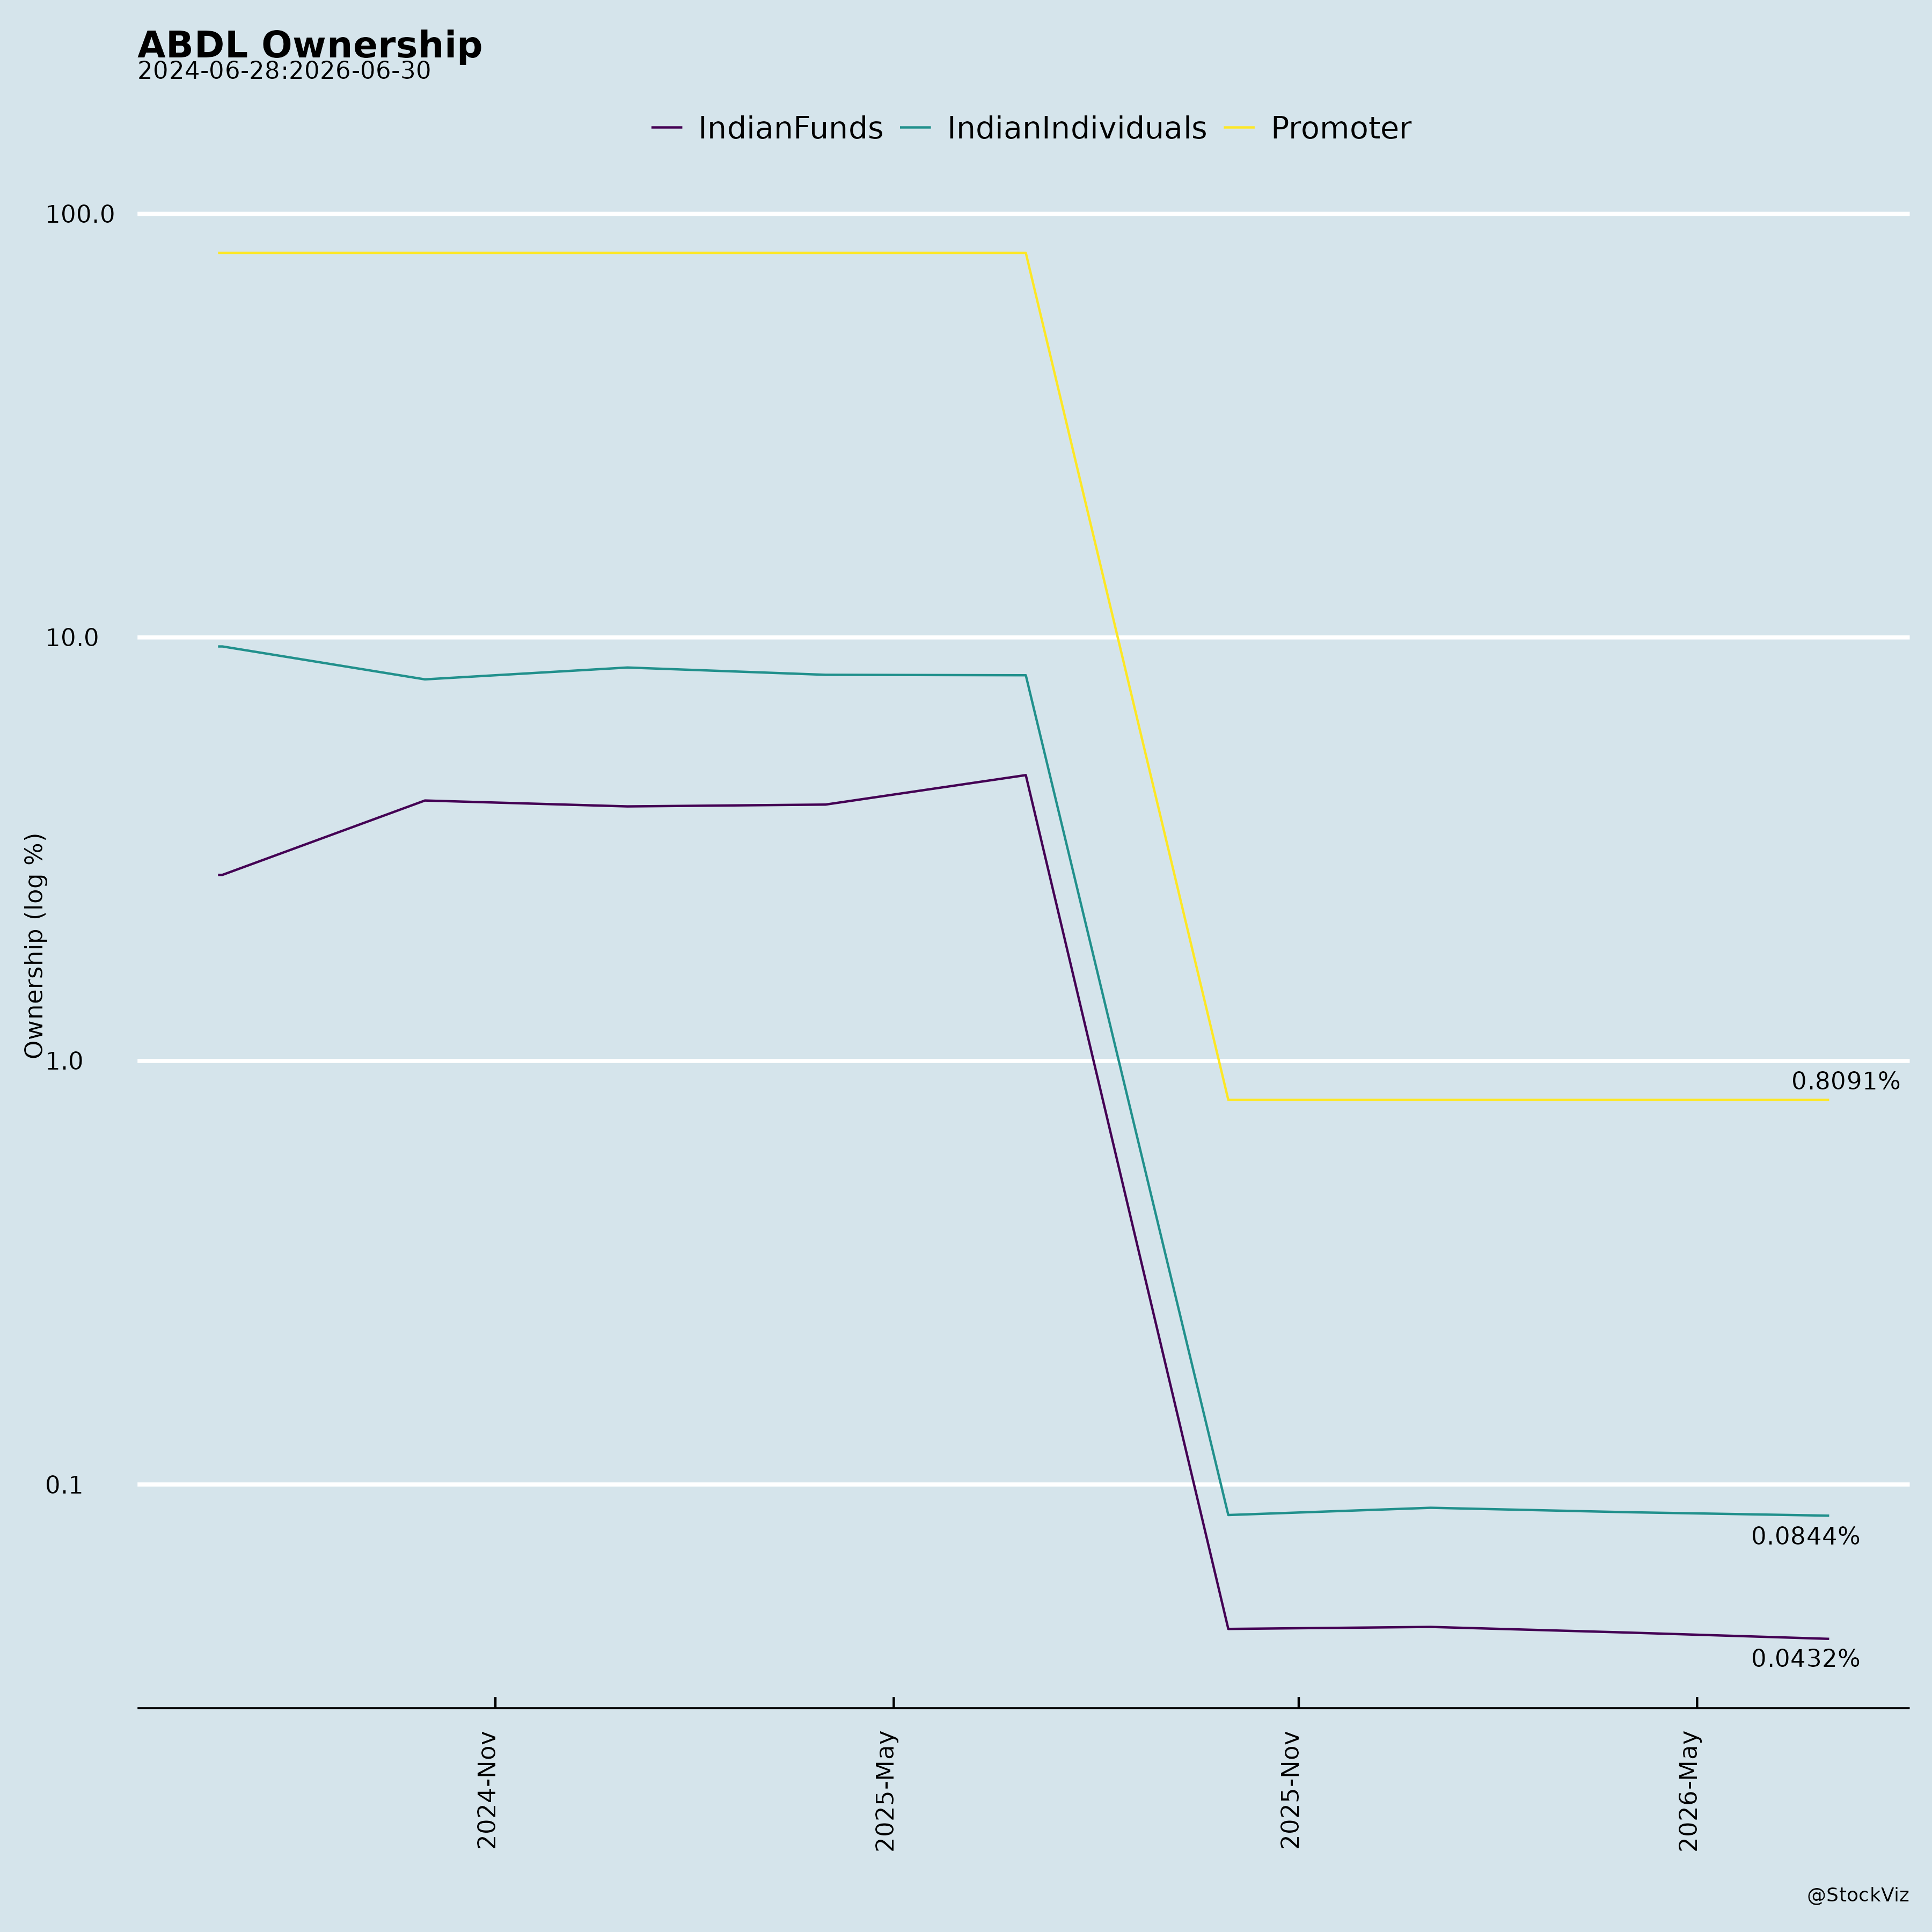
Tax litigation. The Income Tax search and subsequent assessment orders created a demand that was substantially reduced on appeal. The company recognised a tax expense including interest of ₹4,545.24 lakhs for earlier years in the quarter and year ended 31 March 2026 after the time limit to file appeal lapsed. The Board waived the Promoter Chairman’s obligation under his 28 March 2025 undertaking, which had assured personal funding of any ultimate financial impact from this tax liability; the waiver was unanimously approved at the Board meeting held on 14 May 2026.
Execution risk on capex. A multi-year capex program is underway, including Andhra Pradesh dual-mode distillery (₹300 Cr, H1FY29), Maharashtra bottling unit (Q4FY27) and ENA distillery (H1FY28) totalling ₹394 Cr, Telangana malt distillery (₹75 Cr, H1FY27), Aurangabad ENA distillery expansion to 61.0 MLPA (₹340 Cr including acquisition), Moradabad bottling unit (~₹110 Cr, Q3FY27), and the KION acquisition with up to 50% stake and ₹90 Cr equity. These are subject to stated peak capex ratios of Net Debt/EBITDA <2x and Net Debt/Equity <0.75x.
Dependence on flagship brand. Officer’s Choice remains central, described as a key driver of profitability, cash flow generation and market share gains, with 45%+ gross margins and 40%+ market share in Mass Premium.
Input cost and external environment. The favourable input cost environment that supported gross margin expansion may not persist; management references a medium-term inflationary environment.
Regulatory and policy dependence. Performance is tied to state policy updates, price revisions and the Telangana policy, as well as the UK FTA outcome.
4. Management Guidance vs Observed Performance
Revenue growth. Guidance is for revenue growth in mid-teens, underpinned by increasing P&A contribution reaching ~50% by volume by FY28. Observed: Q1FY27 income from operations grew 5.8% Y-o-Y to ₹984 Cr, with P&A volume up 10.7% and Mass Premium & Others volume up 2.3%. FY26 revenue growth was 11.5% versus 5.6% in FY24.
EBITDA margin. Guidance is for ~18.0% by FY28, described as industry best-in-class, from 14.4% in FY26. Observed: Q1FY27 reported EBITDA margin was 12.2%, down 55 bps Y-o-Y, with LTL margin at 14.7% (+189 bps). FY26 EBITDA margin was 14.4% versus 7.5% in FY24.
Gross margin. Guidance is ~48% by FY28 from 45.6% in FY26. Observed: Q1FY27 gross margin was 46.0% (48.4% LTL), up 277 bps Y-o-Y.
ROCE. Guidance is 23%–25% by FY28 from 18.5% in FY26. Observed: ROCE was 18.1% in June 2026 versus 18.5% in March 2026.
Backward integration. Guidance is 100% captive ENA with growth, 100% captive malt with single malt whisky capability, and ~70–75% captive PET. Observed: PET unit commissioned September 2025 at 70–75% captive (over 600 Mn bottles p.a.); malt distillery at 100% captive (~4 Mn litres p.a.) with single malt capability targeted H1FY27; ENA captive projects initiated toward 100%.
Leverage framework. Guidance is Net Debt/EBITDA <2.0x and Net Debt/Equity <0.75x. Observed: 1.7x and 0.6x respectively in June 2026, unchanged from March 2026.
FY27 outlook. Management guides to premiumisation-led revenue growth, sustained investment in people and brands, and disciplined execution of EBITDA-accretive backward integration initiatives, with continued margin focus supported by premium mix, cost efficiencies and operating leverage.
Broker Narrative
Brokerage coverage remained bullish from the first report to the last, with the persistent core narrative being premiumisation (P&A/ICoNIQ growth) and backward-integration-led cost savings. The early broad risk list around regulation, raw-material volatility and downtrading was later narrowed to near-term operational issues—global supply-chain disruption, Q1FY27 EBITDA/PAT decline and ~Rs400 crore dues—while regulatory and input-price risks remained as standing risks. Confidence in the premium segment increased over time, supported by P&A/ICoNIQ volume numbers and new catalysts such as the UK-India FTA.
Fears that came true
- The early warning about supply disruptions/raw material and packaging shortages materialized as the global supply chain disruption that hit Q1FY27 by Rs24 crore and was expected to persist through Q2FY27, aligning with the latest call’s negative actual return of -1.3%.
Optimism that failed
- The early expectation that price increases every 18-24 months and operating leverage would support margin expansion has not materialized so far—Q1FY27 EBITDA margin declined 30 bps YoY to 11.8%.
Broker Timeline
10 broker calls · 2024-11-28 to 2026-07-25
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.