3MINDIA
Equity Metrics
September 24, 2026
3M India Limited
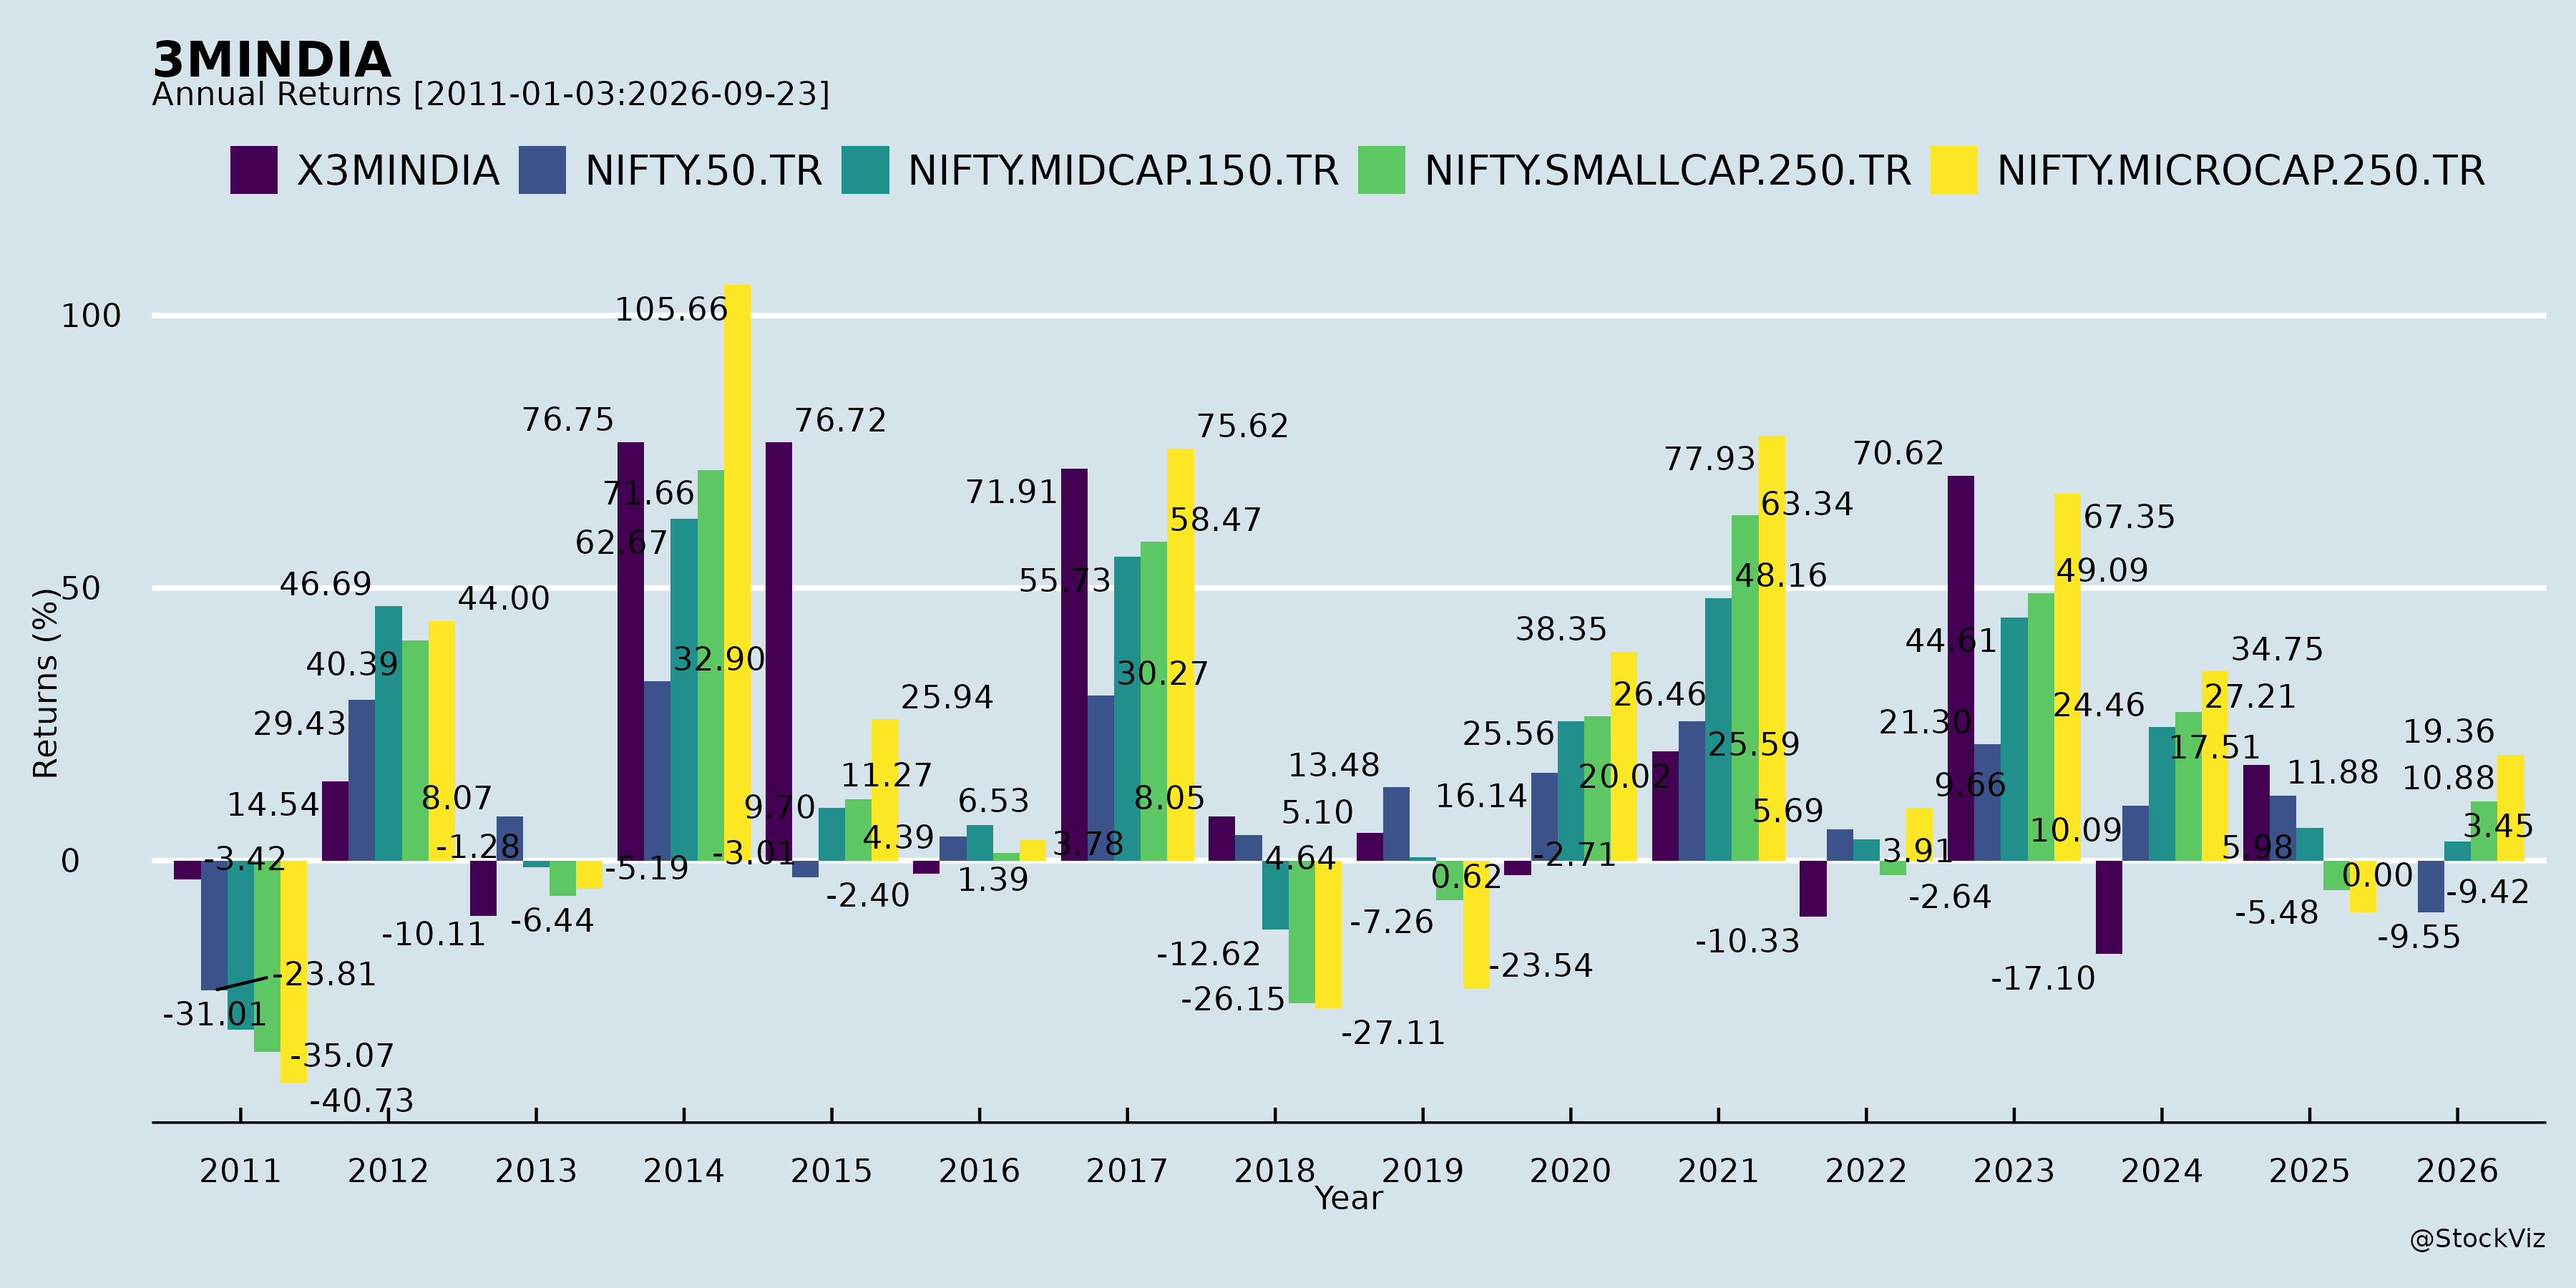
Annual Returns
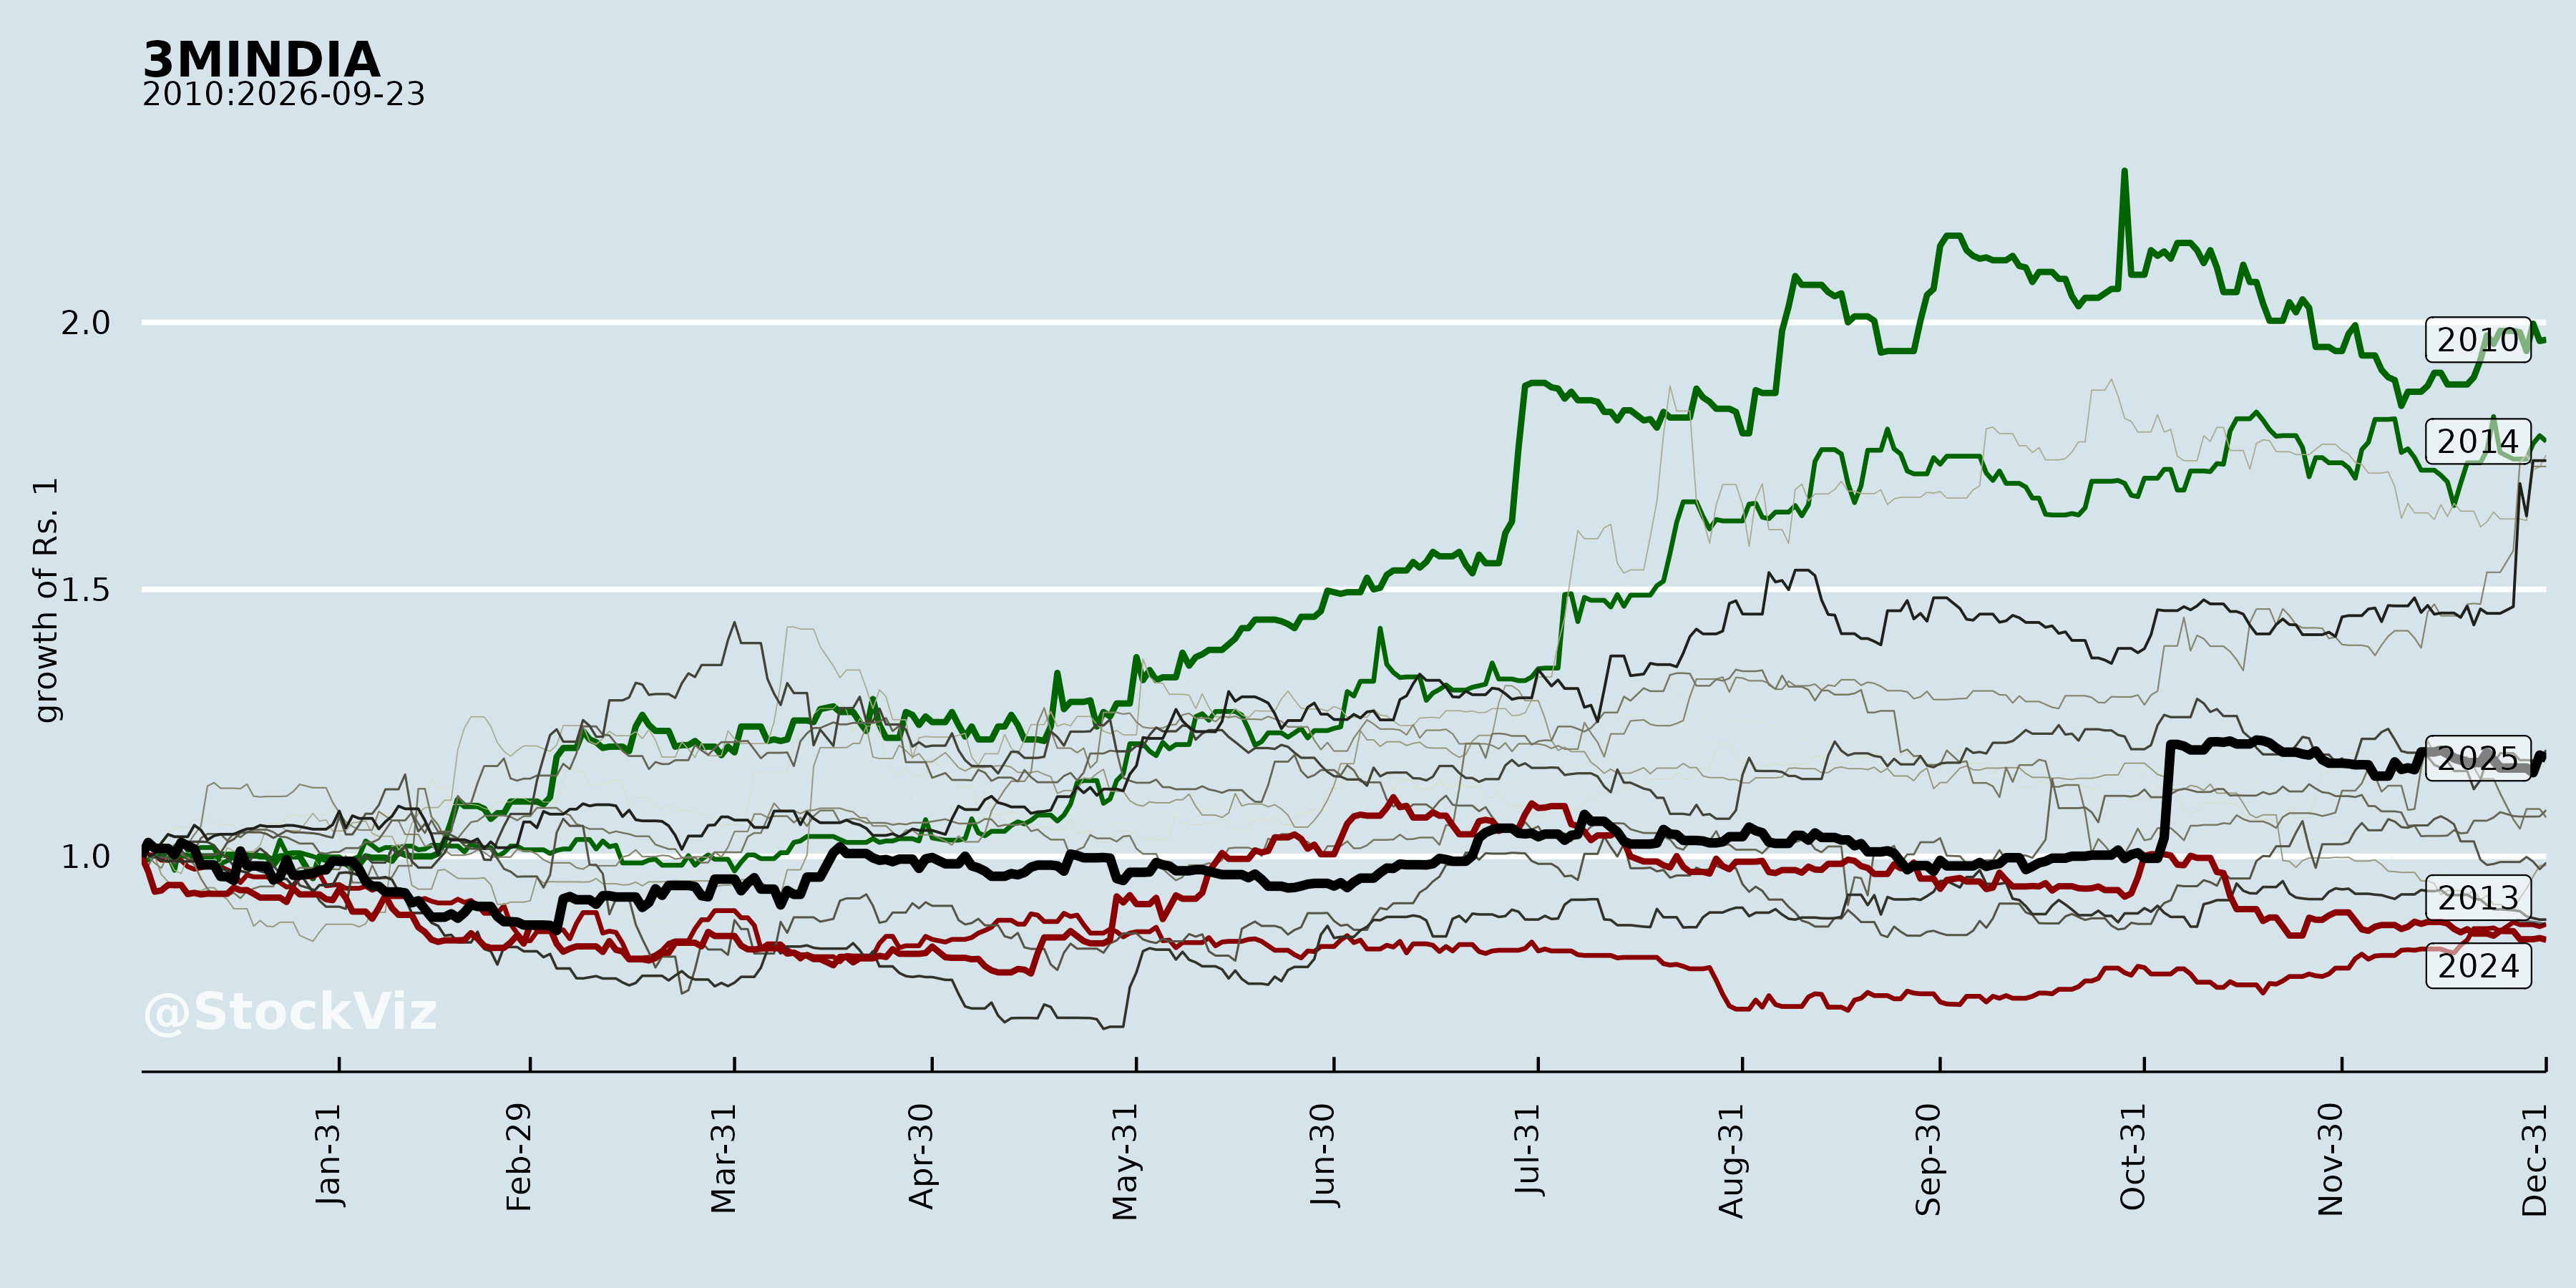
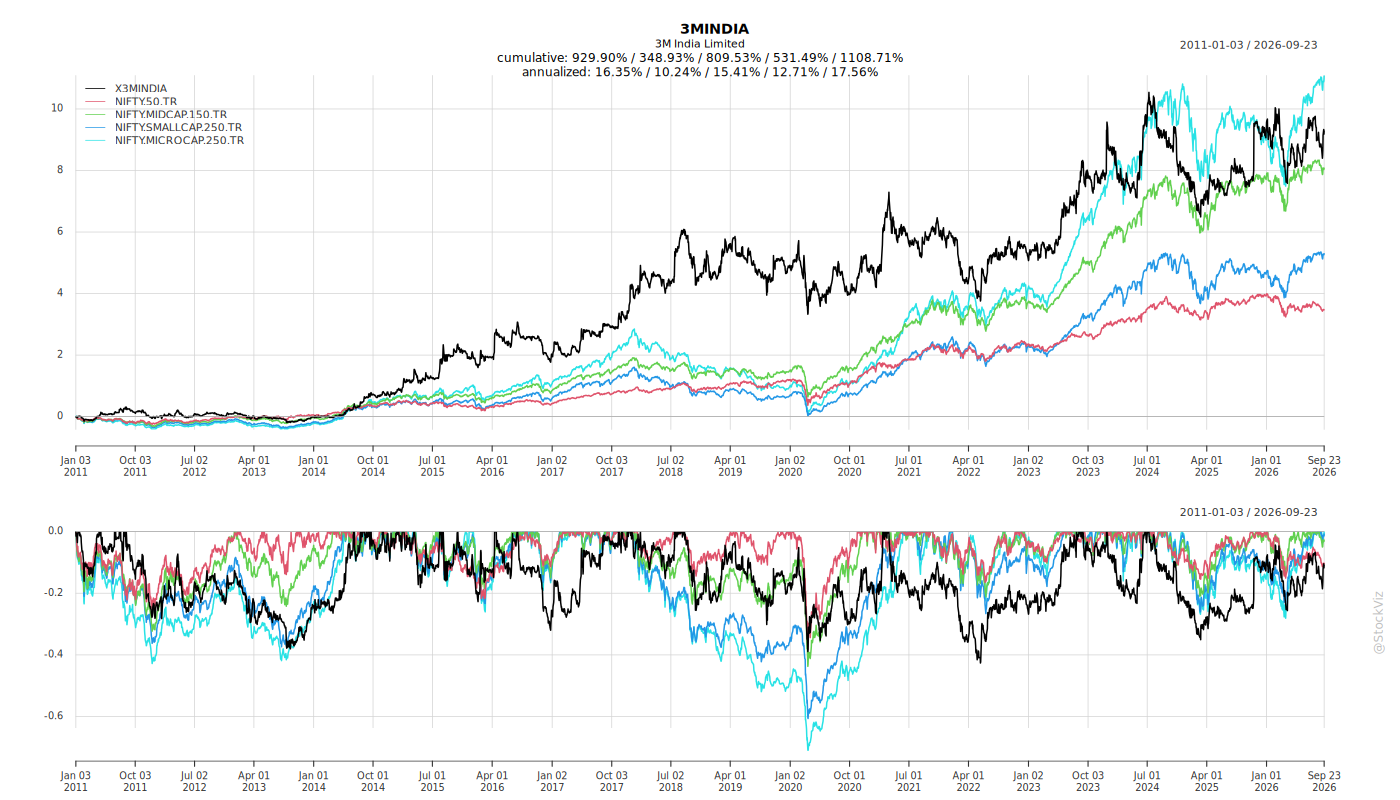
Cumulative Returns and Drawdowns
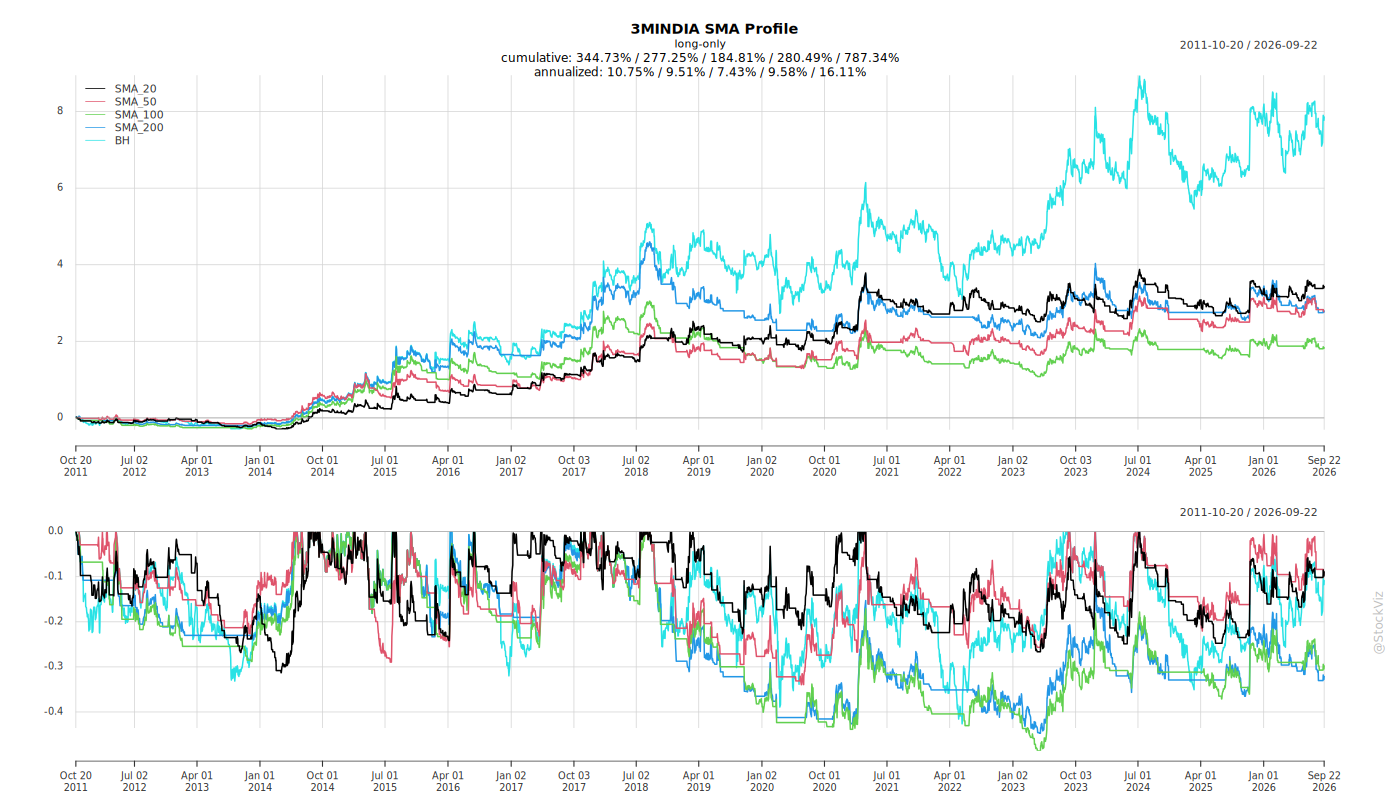
Fundamentals
Ownership
Margined
AI Summary
asof: 2026-09-16
3M India Limited — Recent Corporate Announcements
1. Headwinds and Challenges
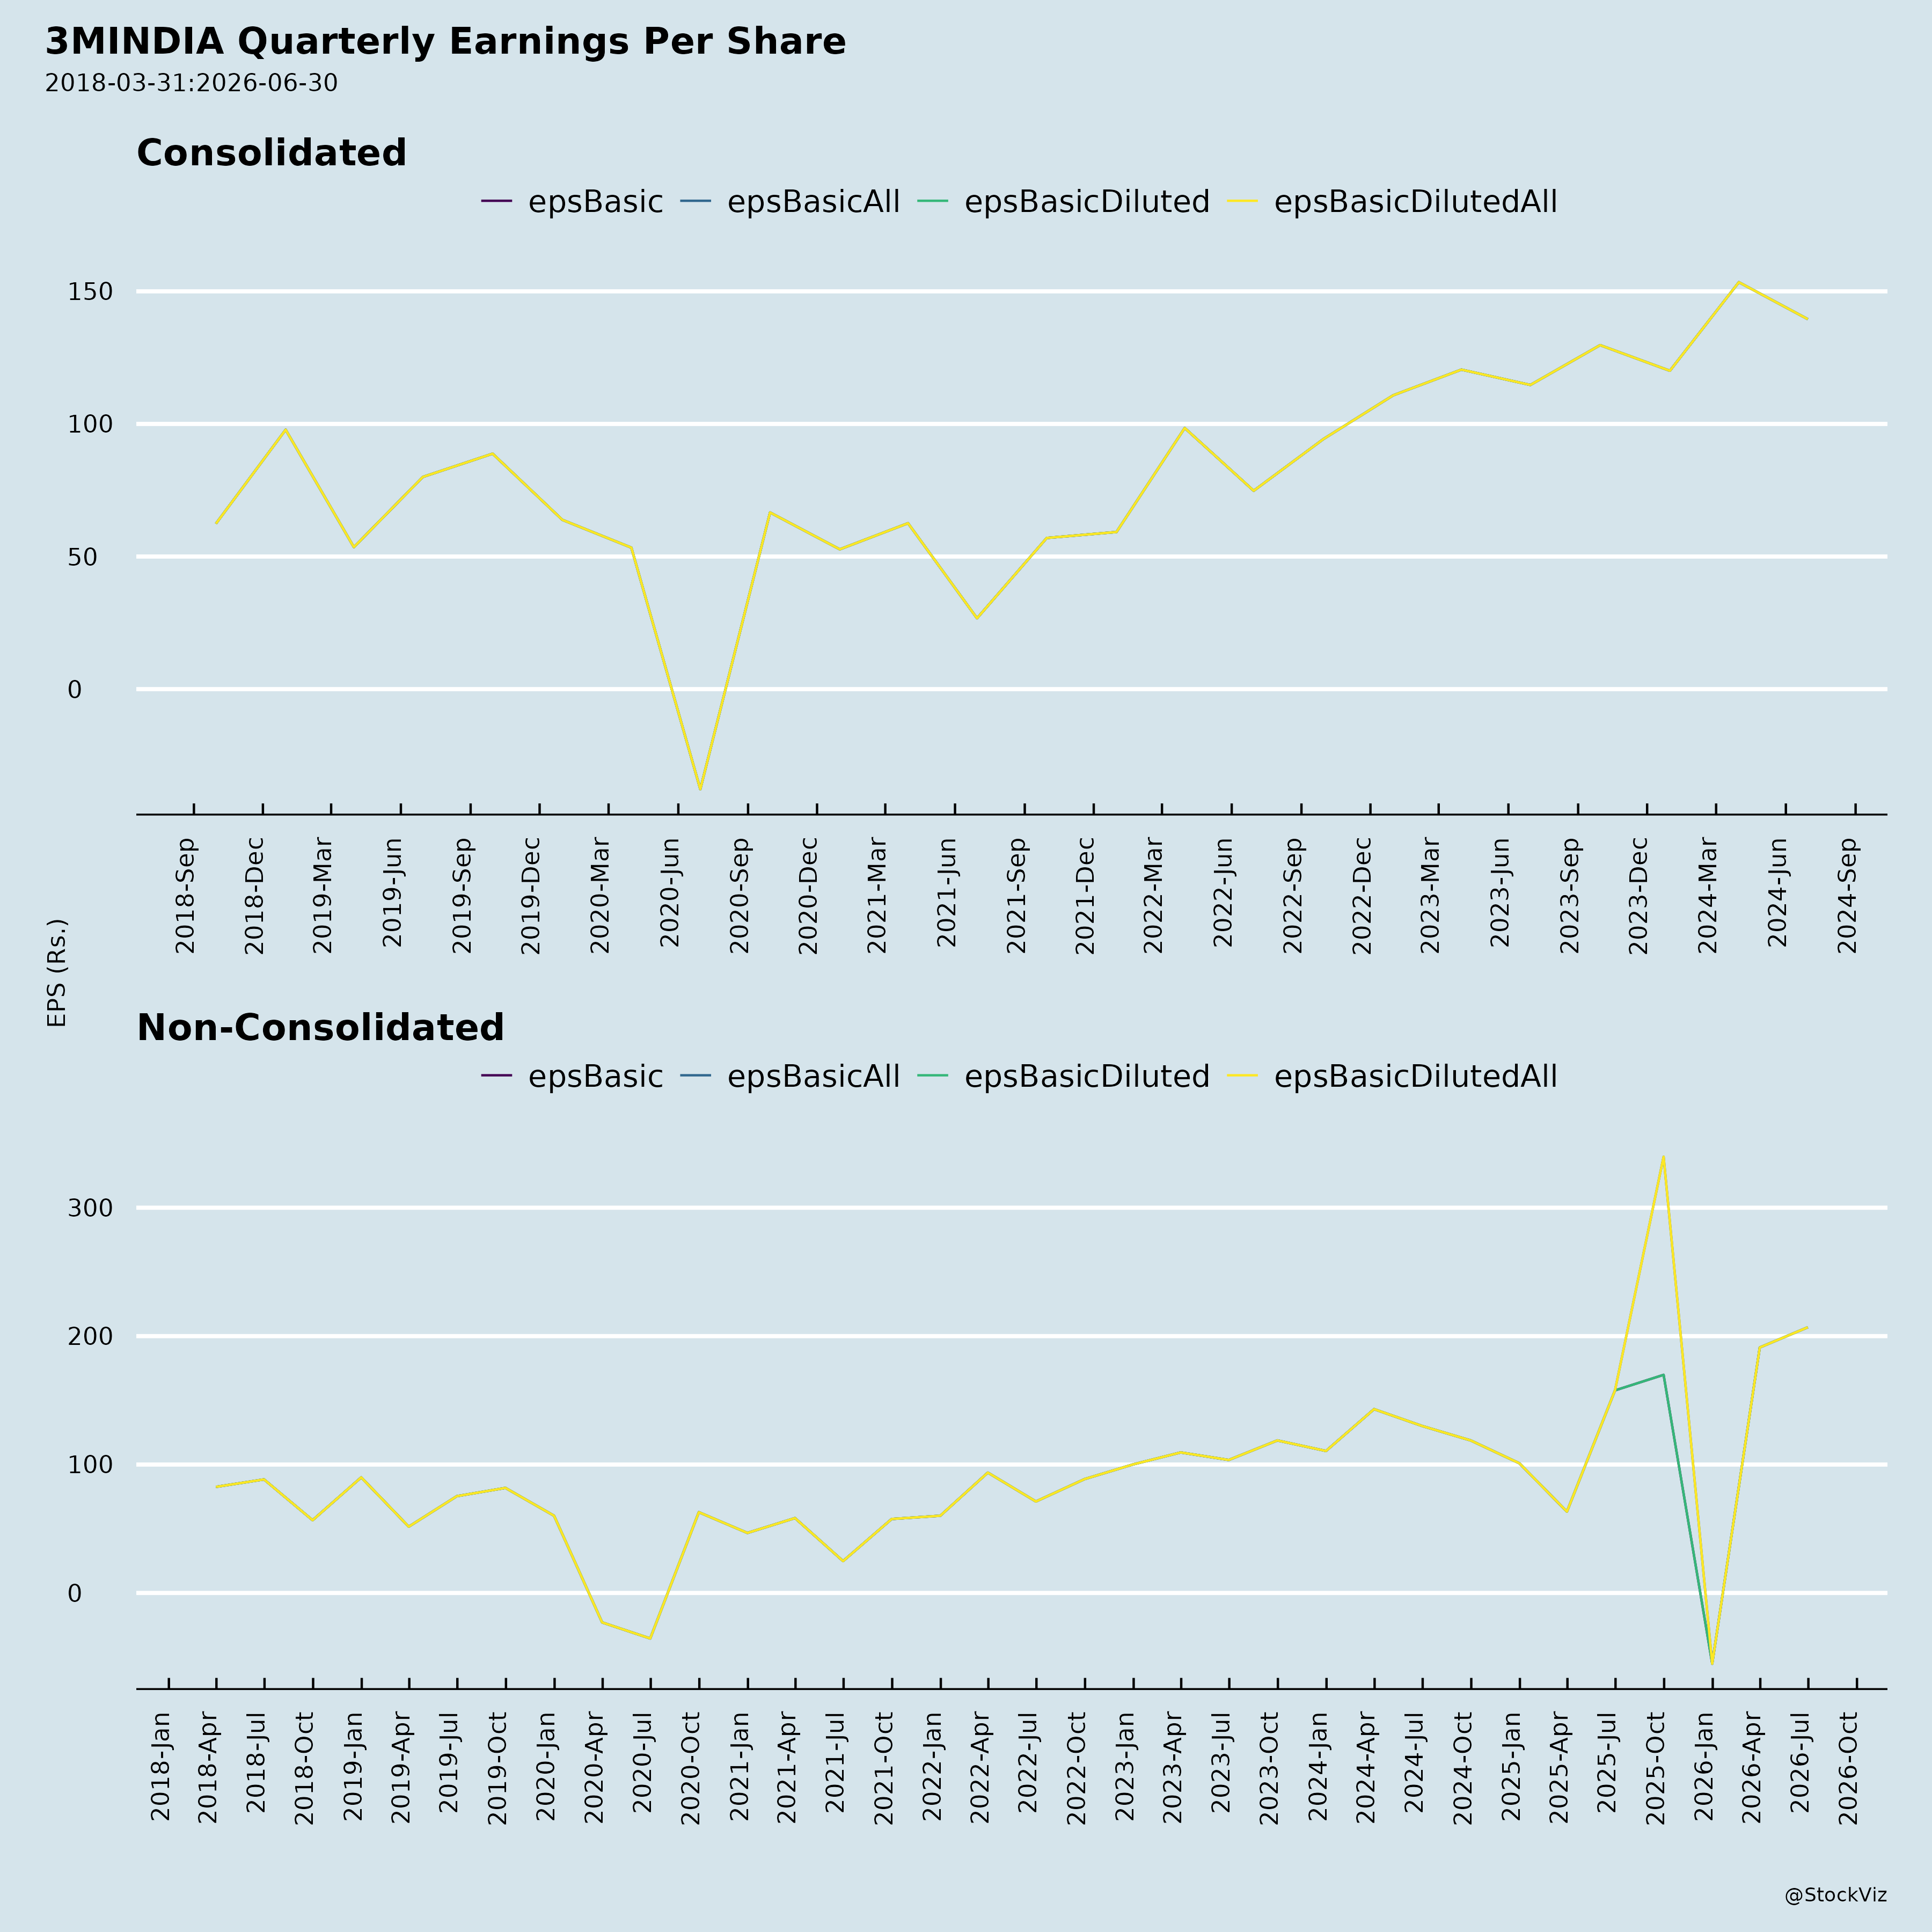
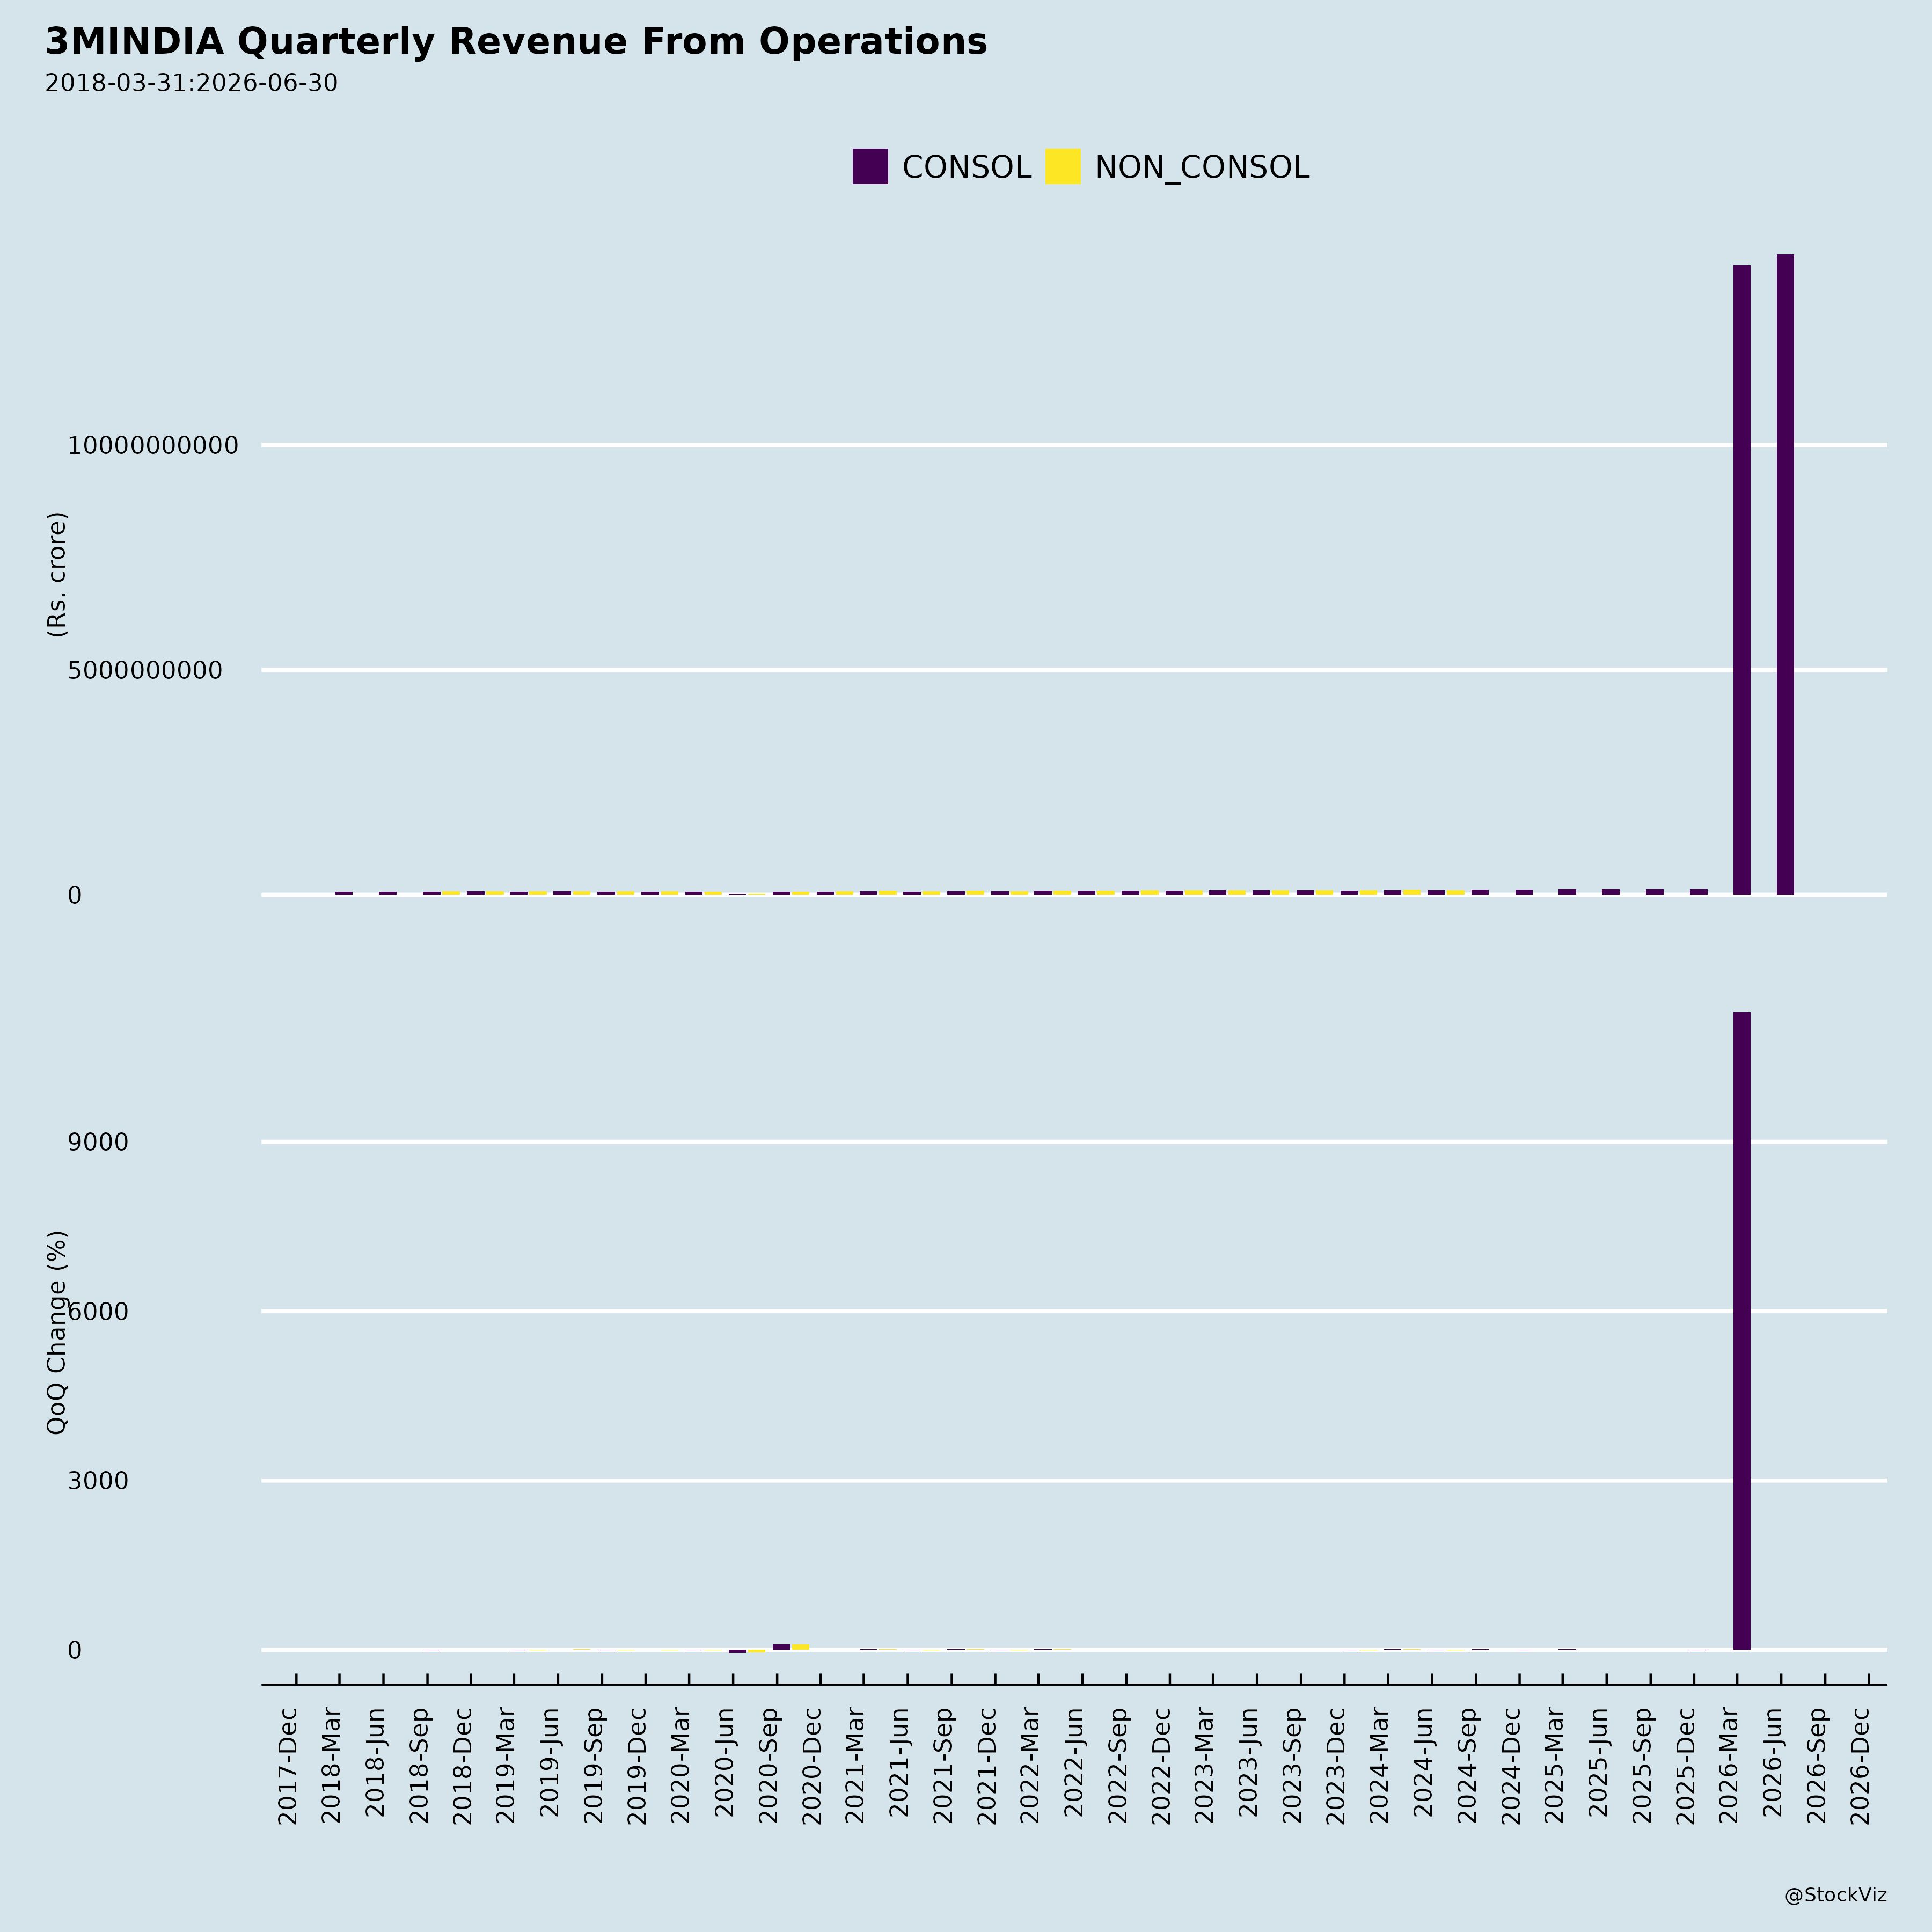
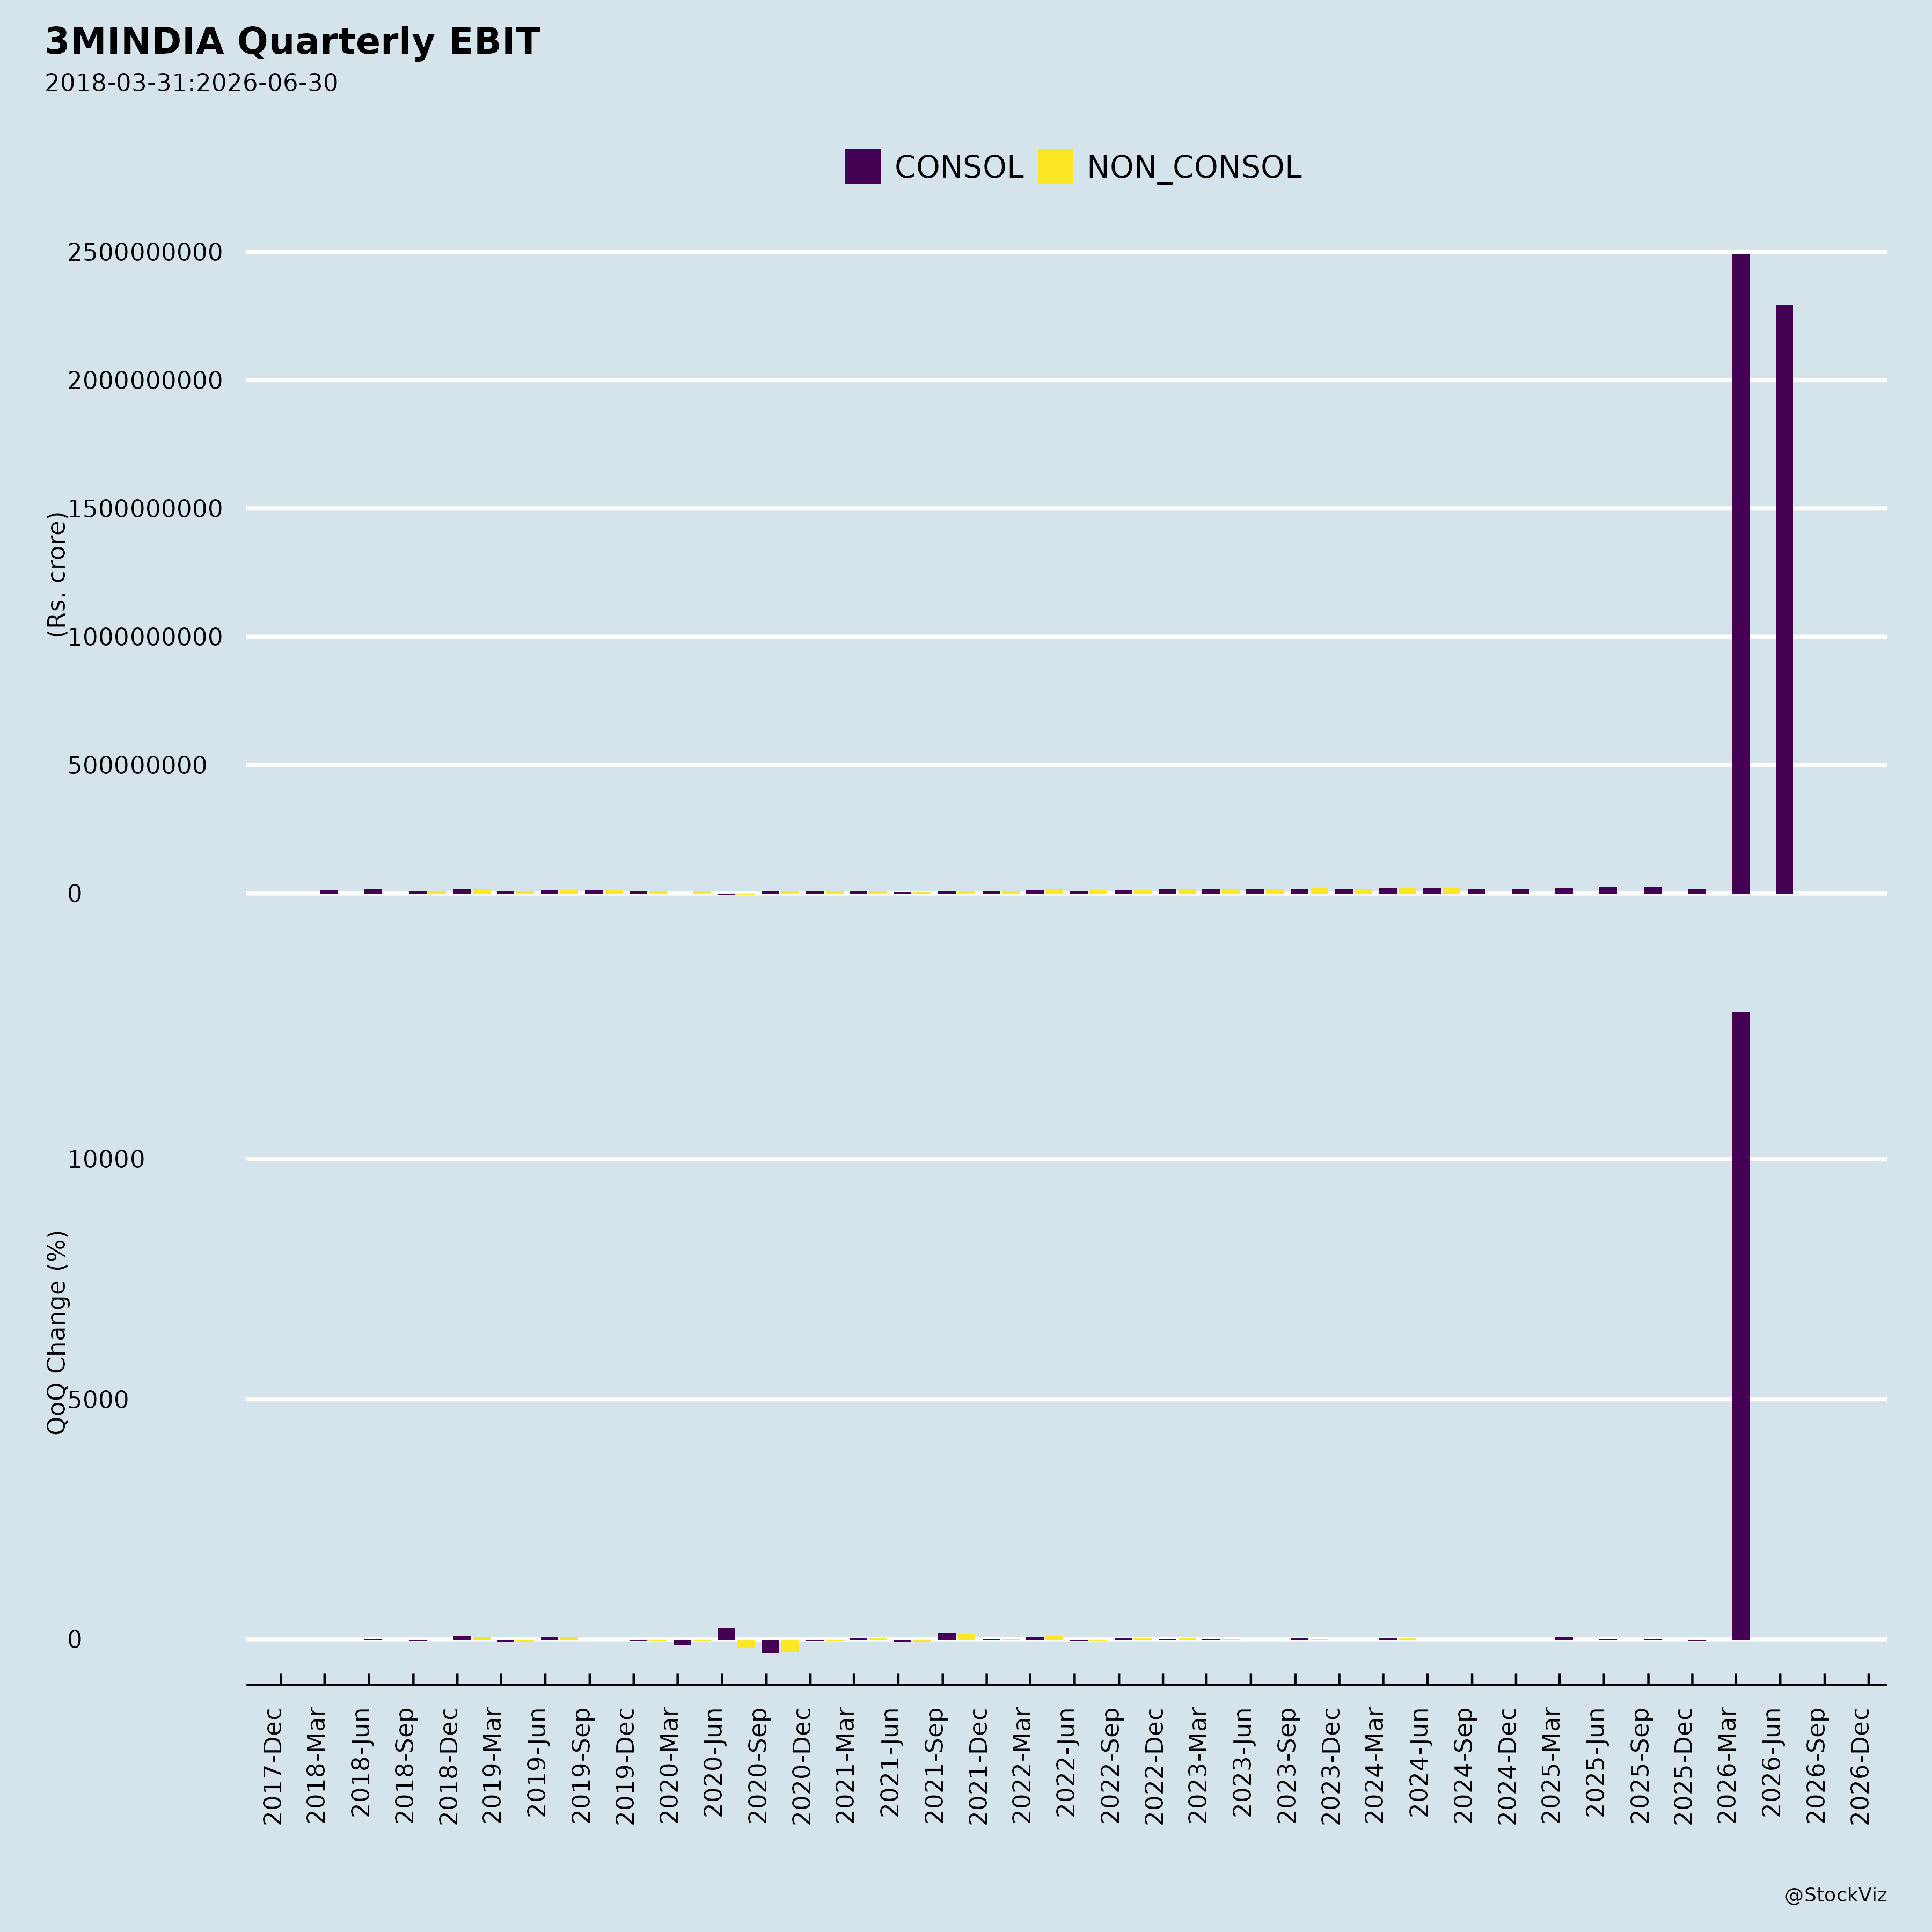
Profitability pressure despite revenue growth. For the first quarter ended June 30, 2026, the company reported revenue growth of 19.0% year-on-year, but EBITDA declined 2.7% and profit before tax excluding exceptional items declined 4.3% year-on-year. Management attributed the profitability decline excluding exceptional items primarily to the impact of Indian Rupee depreciation.
Sequential softness. On a quarter-on-quarter basis, revenue grew only 1.7% (Rs. 1,423 crores versus Rs. 1,399 crores), while EBITDA declined 7.3% and PBT before exceptional items declined 8.0%.
Cost pressures. Employee benefit expenses rose to Rs. 117.60 crores in the June 2026 quarter from Rs. 136.71 crores in the March 2026 quarter and Rs. 136.71 crores in the prior-year comparative, with the company noting that the increase is primarily on account of past service cost for gratuity due to a change in the definition of wages for employees.
Regulatory and labour-code transition. The Government of India notified four Labour Codes on November 21, 2025 — the Code on Wages, 2019; the Industrial Relations Code, 2020; the Code on Social Security, 2020; and the Occupational Safety, Health and Working Conditions Code, 2020 — consolidating 29 existing labour laws. The company evaluated the incremental impact using the best available information and guidance from the Institute of Chartered Accountants of India, and recognised an exceptional item of Rs. 40.24 crores for the year ended March 31, 2026, with no impact on the June 2026 quarter.
Tax litigation history. The company had filed an Advance Pricing Agreement (APA) application on March 28, 2018 to resolve certain ongoing transfer pricing litigation matters pertaining to 2014-15 to 2022-23. Following discussions and negotiations with APA authorities, the company signed an APA with the Central Board of Direct Taxes (CBDT), recognising an expense of Rs. 139.47 crores and related interest thereon of Rs. 31.49 crores during the year ended March 31, 2026.
2. Tailwinds and Growth Prospects
Broad-based revenue growth. All four business segments registered revenue growth year-on-year in Q1 FY26-27: Healthcare grew 23.5%, Safety & Industrial grew 23.0%, Transportation & Electronics grew 14.4%, and Consumer grew 13.4%.
Sustained double-digit growth trajectory. Management stated that Q1 FY26-27 marked the fifth consecutive quarter of double-digit year-on-year sales growth.
Investment traction. Management attributed results to traction from sales and marketing investments the company has been making, along with continued focus on commercial and innovation excellence.
Exceptional gain from land sale. During the quarter ended June 30, 2026, the company sold land located at Pimpri, Pune pursuant to a Conveyance Deed executed on June 29, 2026, for a total consideration of Rs. 82.00 crores, resulting in a net gain of Rs. 73.13 crores recognised as an exceptional item. This contributed to PBT after exceptional items growing 26.2% year-on-year and PAT growing 31.2% to Rs. 233 crores.
Segment asset growth. Segment assets increased across most businesses as of June 30, 2026 compared to March 31, 2026: Safety & Industrial at Rs. 668.72 crores, Transportation & Electronics at Rs. 834.27 crores, Health Care at Rs. 324.06 crores, and Consumer at Rs. 147.67 crores.
Dividend recommendation. The Board recommended a final dividend of Rs. 160 per equity share and a special dividend of Rs. 346 per equity share for the year 2025-26, subject to shareholder approval at the ensuing Annual General Meeting. This is in addition to an interim dividend of Rs. 506 per equity share.
3. Key Risks
Currency risk. Indian Rupee depreciation was cited by management as the primary reason for the decline in profitability excluding exceptional items, indicating exposure to foreign exchange movements.
Regulatory compliance risk. The transition to the new Labour Codes required the company to assess incremental financial impact, and the company recognised a material exceptional charge of Rs. 40.24 crores related to past service cost for gratuity.
Transfer pricing and tax risk. The company’s history of transfer pricing litigation (2014-15 to 2022-23) and the resulting APA settlement expense of Rs. 139.47 crores plus interest of Rs. 31.49 crores illustrate exposure to tax authority disputes.
Dependence on exceptional items for profit growth. PBT growth of 26.2% year-on-year was driven by the land sale gain; excluding exceptional items, PBT declined 4.3%, indicating underlying profitability challenges.
Limited subsidiary structure. The company has no subsidiary or joint venture/associate company as of June 30, 2026.
4. Management Guidance Versus Observed Business Performance
Management commentary on growth. Mr. Aseem Joshi, Managing Director, stated the company delivered 19.0% sales growth in Q1 versus Q1 prior year, with broad-based growth across all four business segments. He noted this was the fifth consecutive quarter of double-digit year-on-year sales growth and attributed results to sales and marketing investments and focus on commercial and innovation excellence.
Management commentary on profitability. Management acknowledged that profitability excluding exceptional items declined year-on-year primarily due to Indian Rupee depreciation. PAT grew 31.2% to Rs. 233 crores including exceptional items.
Observed performance versus commentary. The revenue growth of 19.0% year-on-year aligns with management’s characterization of broad-based growth. However, the decline in EBITDA (-2.7%) and PBT before exceptional items (-4.3%) year-on-year indicates that revenue growth did not translate into underlying profit growth, consistent with management’s attribution to currency depreciation and cost pressures including the gratuity past service cost increase.
No explicit forward guidance. The supplied material does not contain specific forward-looking financial guidance or projections for future periods beyond management’s commentary on the quarter’s performance and strategic focus areas.
5. Additional Key Facts
ESG rating. Crisil ESG Ratings & Analytics Ltd assigned the company an Environmental, Social and Governance (ESG) rating of ‘65’ (Strong) and a Core ESG rating of ‘70’ based on FY 2025-26 data. The company did not engage Crisil for this rating, as it was independently prepared using publicly available data.
Annual General Meeting. All seven agenda items proposed at the 39th Annual General Meeting held on August 26, 2026, were passed by the shareholders with the requisite majority.
Financial reporting. The unaudited financial results for the quarter ended June 30, 2026 were approved by the Board on August 14, 2026, reviewed by the Audit Committee, and subjected to limited review by the statutory auditors (B S R & Co. LLP), who issued an unqualified review opinion. The results were prepared in accordance with Indian Accounting Standards (Ind AS) under Section 133 of the Companies Act, 2013.
Segment performance (Q1 FY26-27 versus Q1 FY25-26). Segment revenue: Safety & Industrial Rs. 465.33 crores (versus Rs. 378.18 crores), Transportation & Electronics Rs. 503.36 crores (versus Rs. 440.04 crores), Health Care Rs. 296.99 crores (versus Rs. 240.48 crores), Consumer Rs. 147.96 crores (versus Rs. 130.52 crores), Others Rs. 9.57 crores (versus Rs. 6.75 crores).
Balance sheet items. Total segment assets as of June 30, 2026 were Rs. 3,137.25 crores (versus Rs. 3,294.44 crores as of March 31, 2026). Total segment liabilities were Rs. 1,369.10 crores (versus Rs. 1,292.93 crores as of March 31, 2026).
Broker Narrative
The early narrative was strongly positive, highlighting broad-based double-digit growth, margin expansion from softer input costs, and multiple growth drivers. By the last report, the tone had turned cautious/Neutral: near-term consumption was mixed, commodity inflation had resurfaced across cocoa/sugar/proteins/freight, and valuation was deemed expensive. Structural themes such as low penetration, premiumization, e-commerce growth, and brand headroom persisted, but near-term optimism about sustained cost relief and uninterrupted growth faded.
Fears that came true
- The early fear of persistent commodity pressures in milk/nutrition segments materialised: the last report still flagged inflation in protein inputs and broader commodity/freight cost volatility, and several 2024 calls ended as DISAPPOINTMENT with negative returns.
Optimism that failed
- The early optimism on softer edible oils, wheat and packaging costs plus stabilizing milk and fuel prices did not hold, as the last report cited persistent inflation in cocoa, sugar, protein inputs and volatility in energy/edible oil/packaging/freight costs.
- The expectation of sustained broad-based double-digit growth across all segments was not borne out by the last report, which described consumption trends as mixed and recovery as only a monitorable.
Broker Timeline
12 broker calls · 2023-08-11 to 2025-11-04
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.