Commodity Chemicals
Industry Metrics
April 16, 2026
Annual Returns
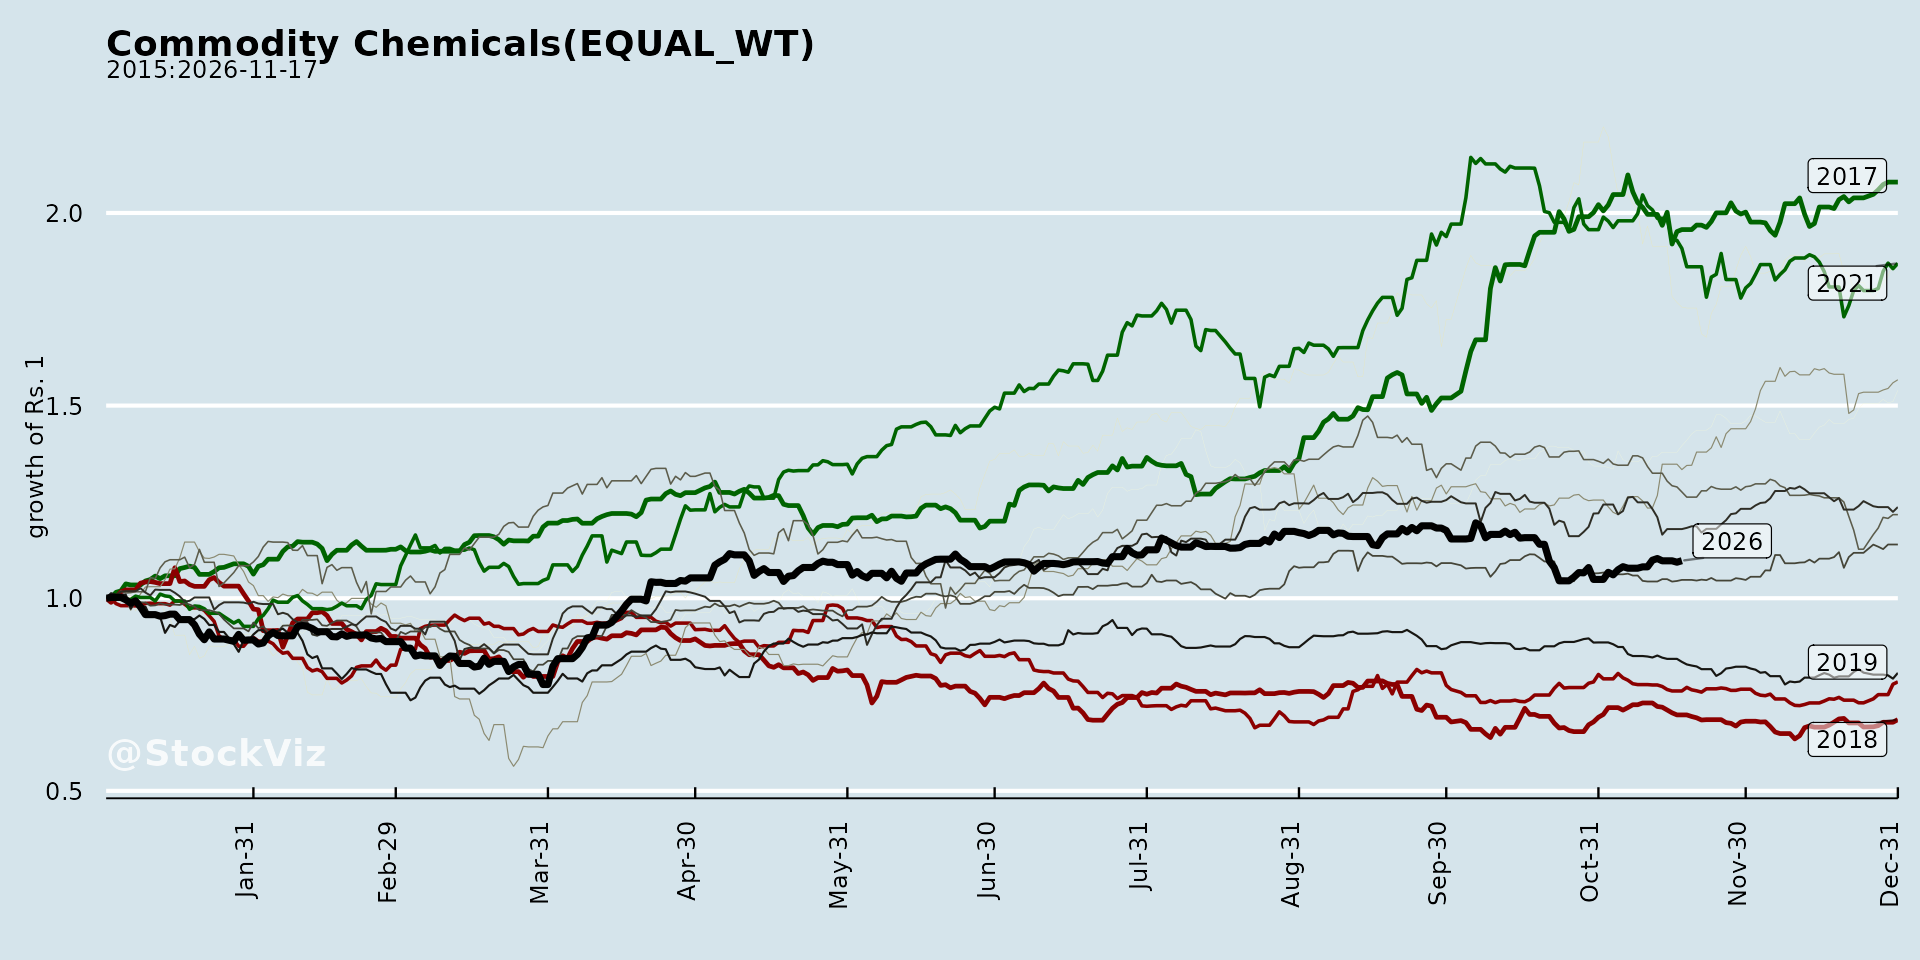
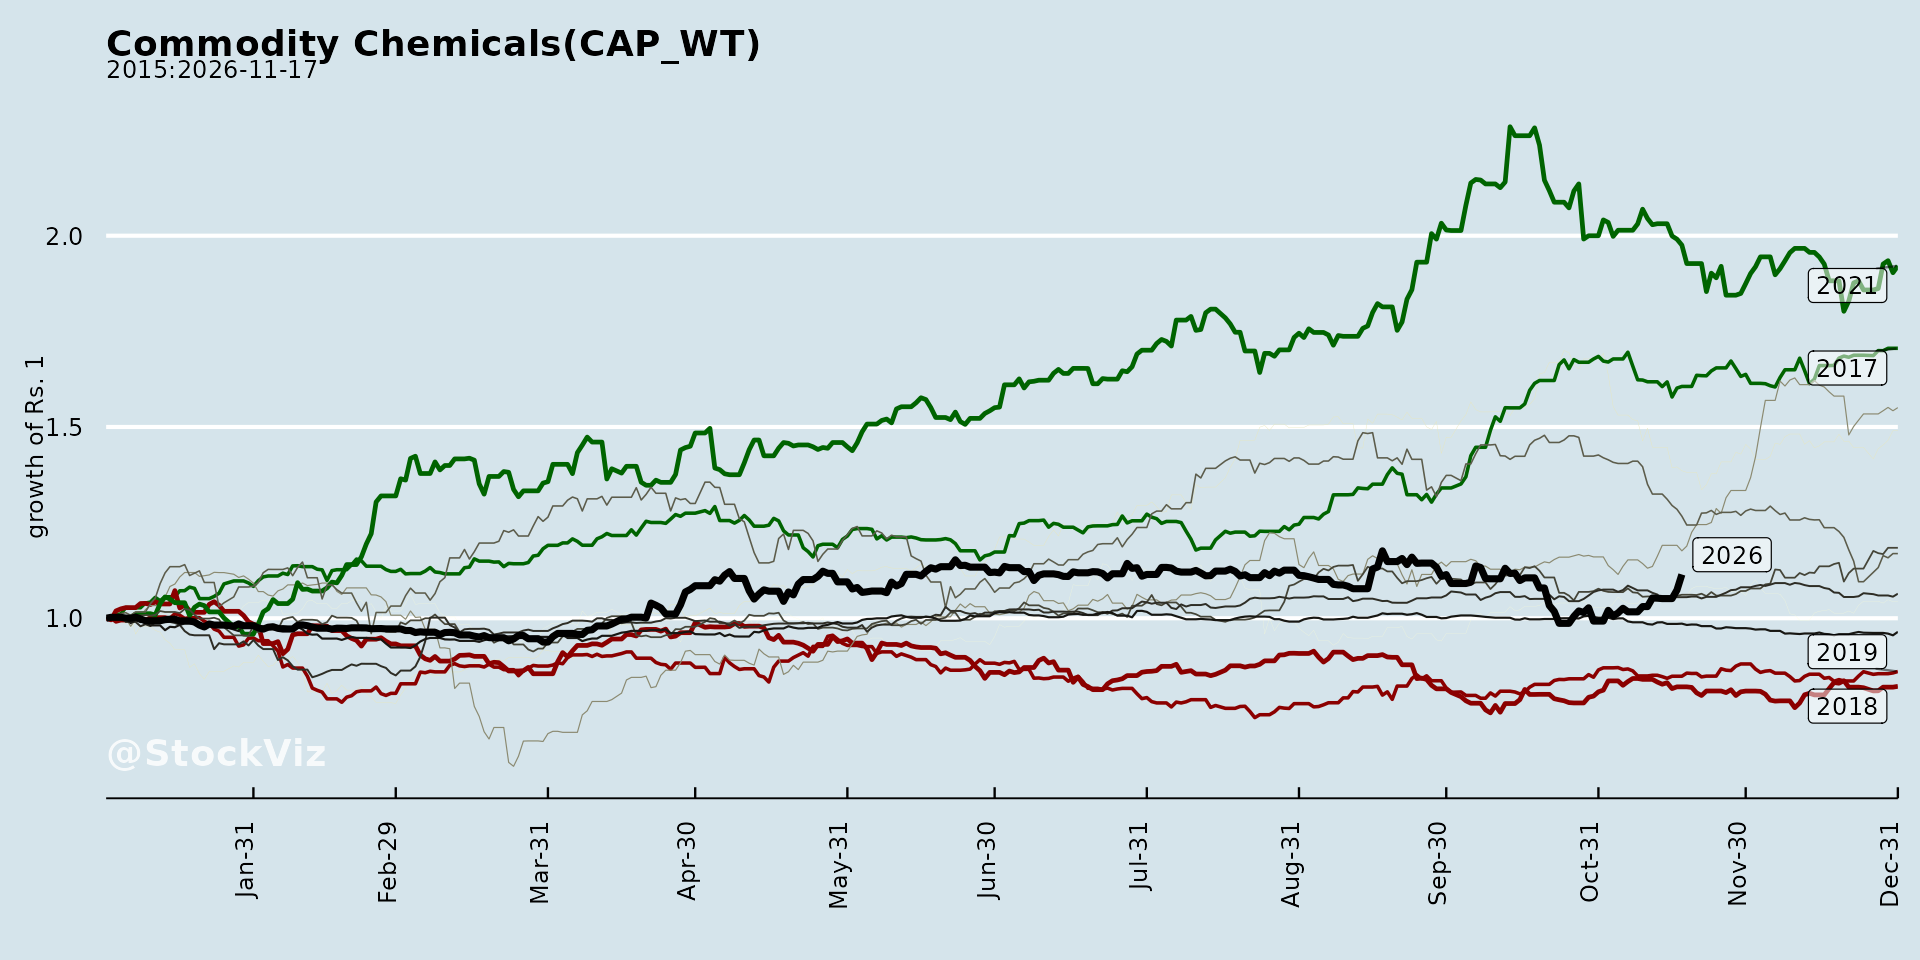
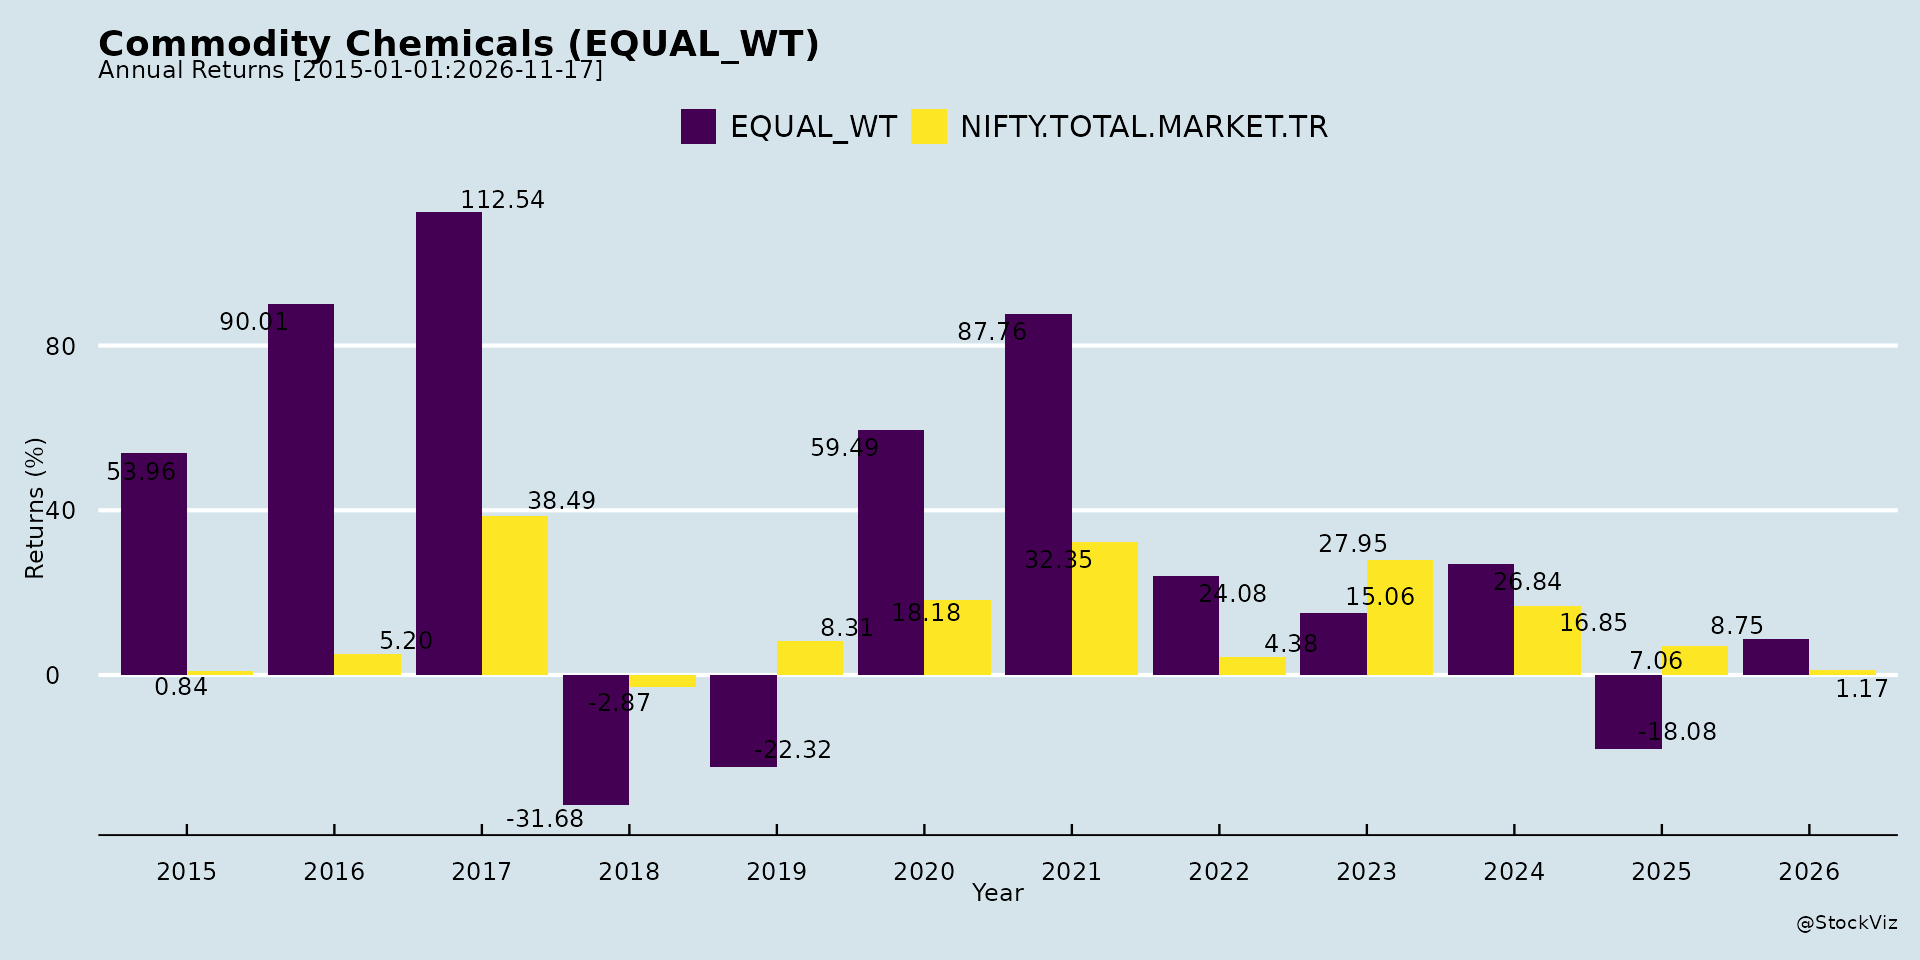
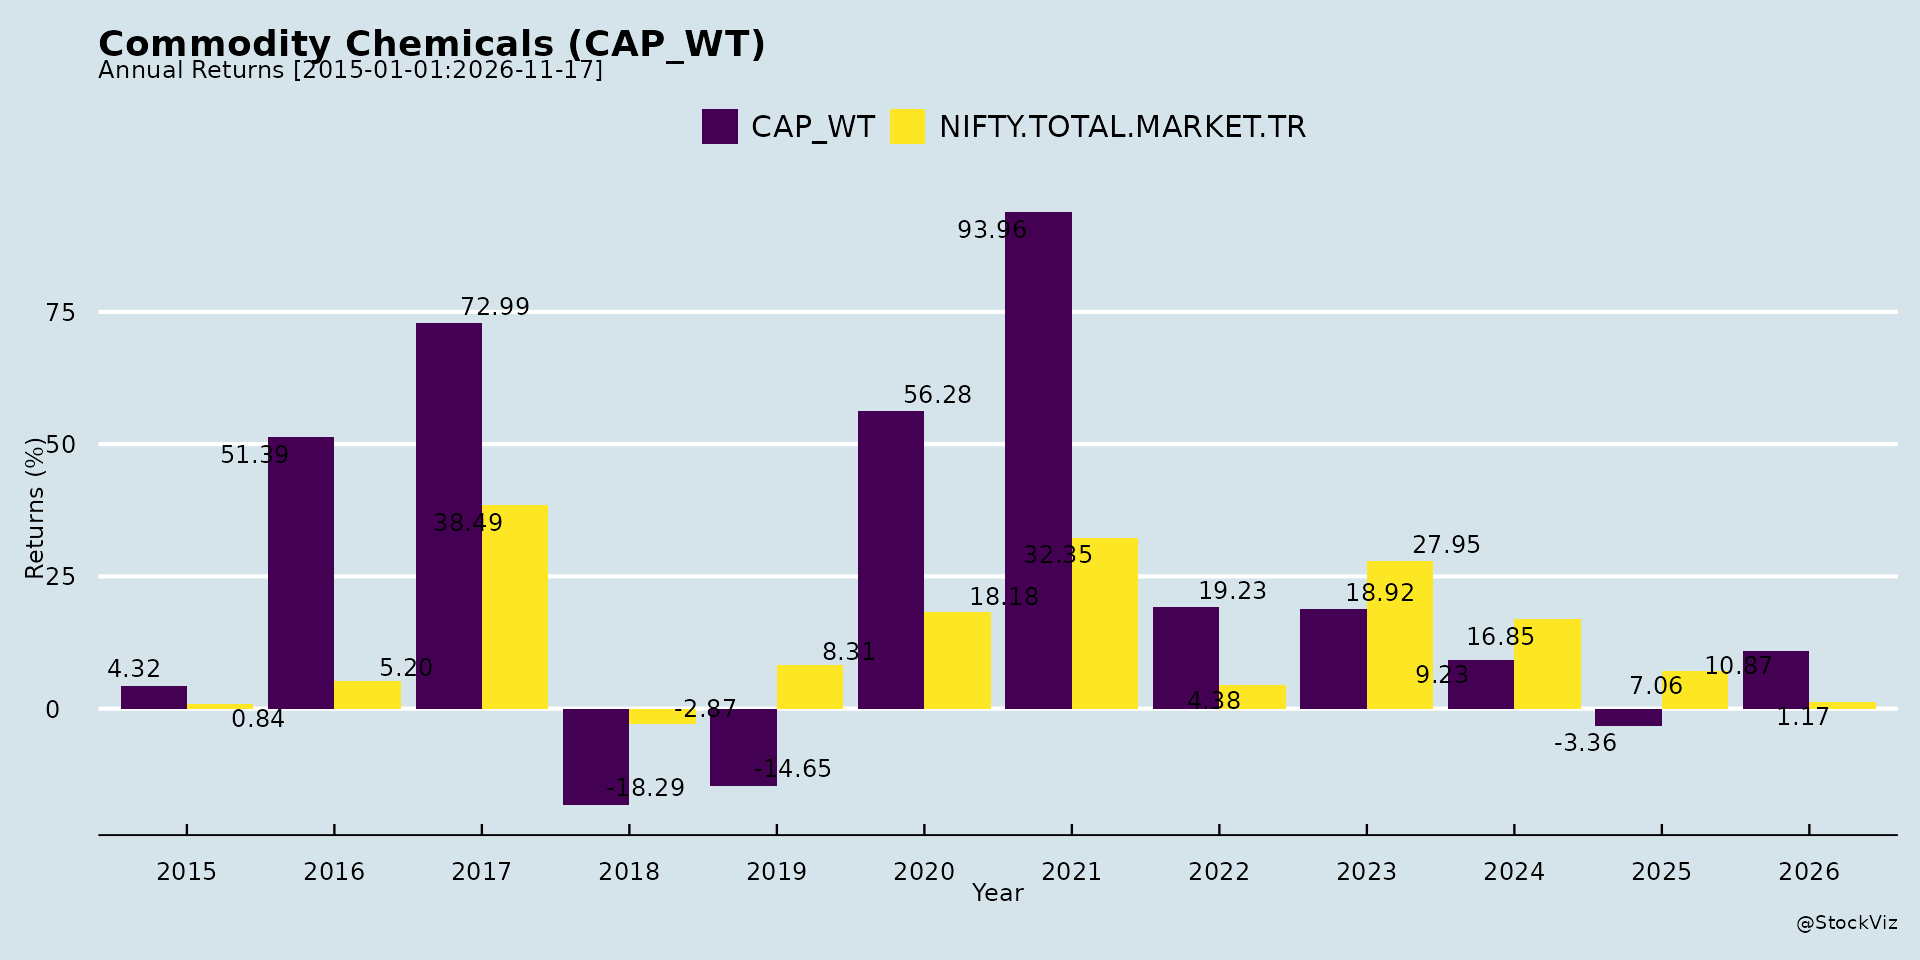
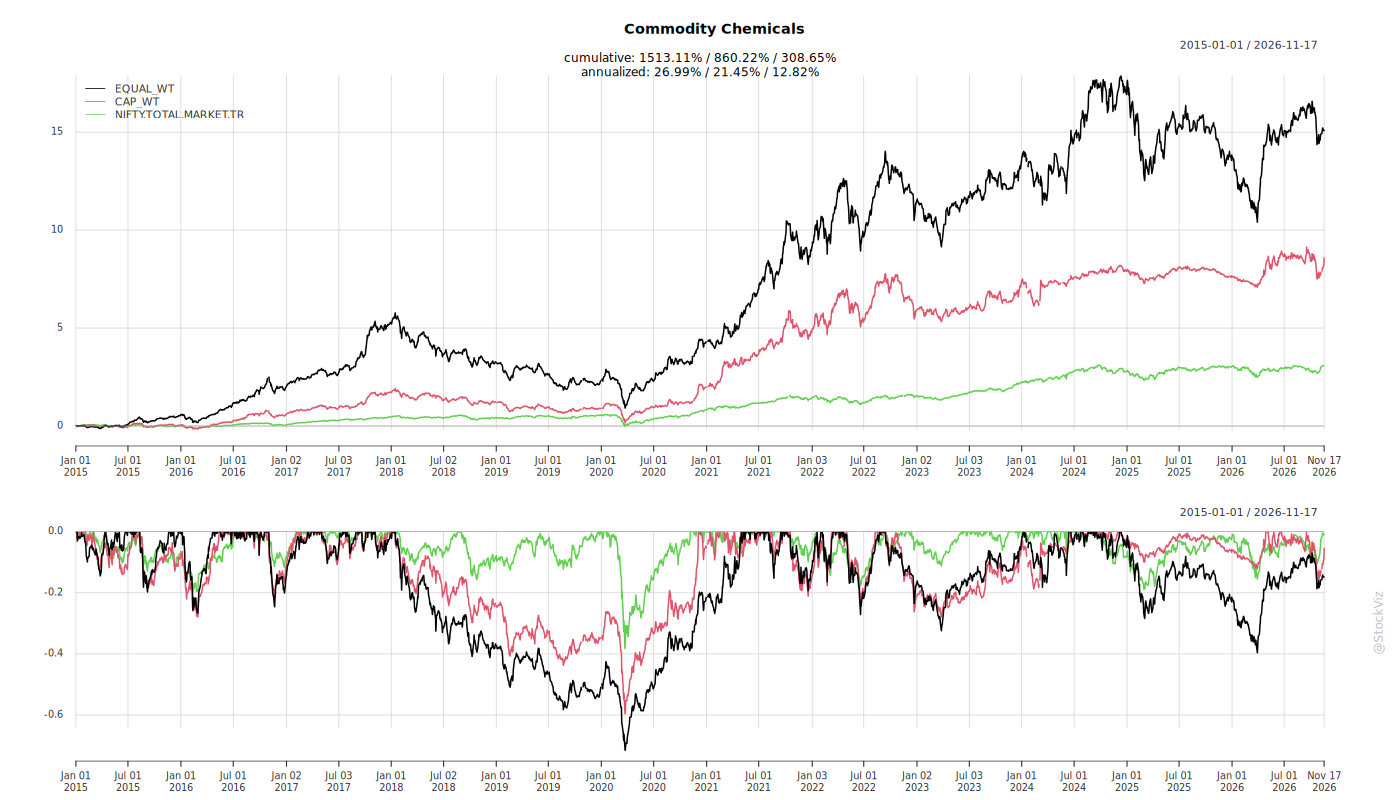
Cumulative Returns and Drawdowns
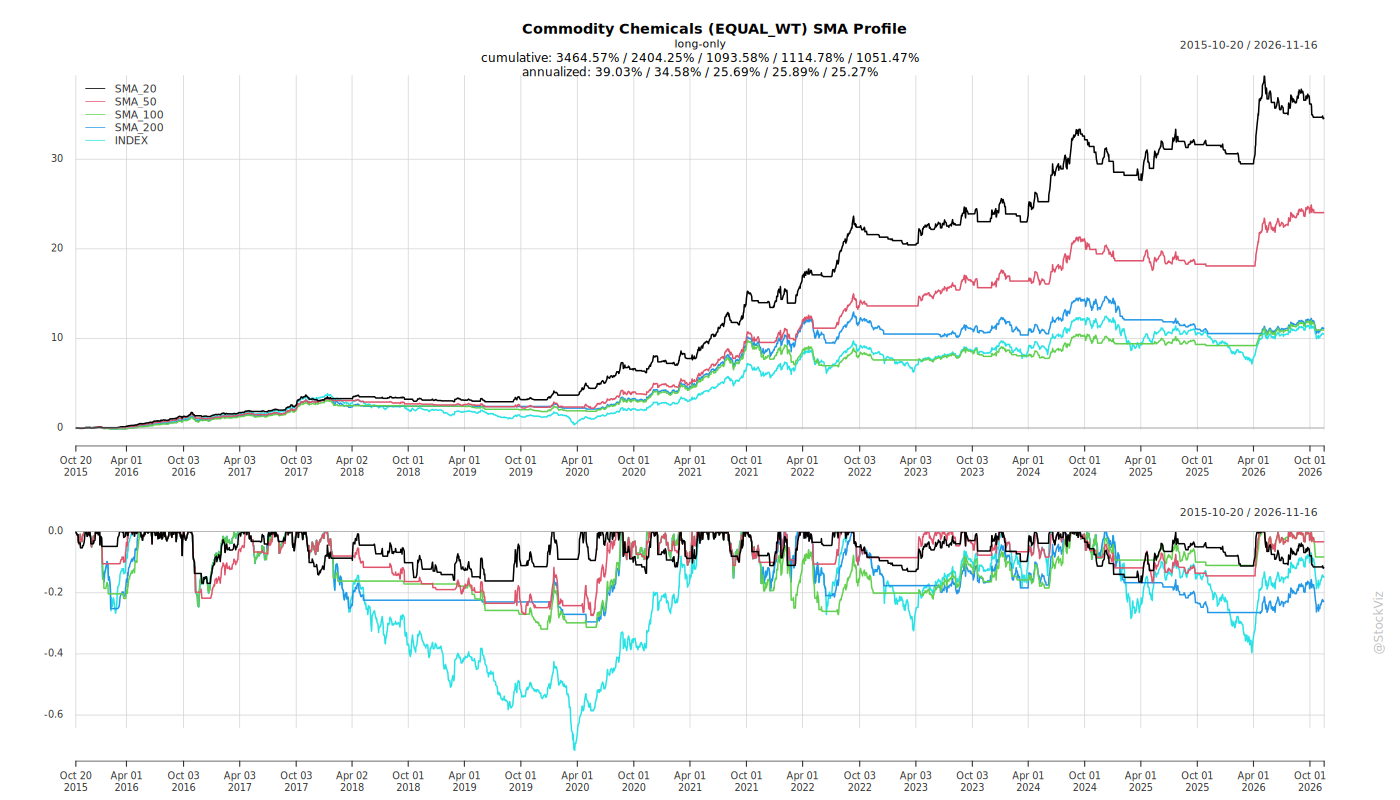
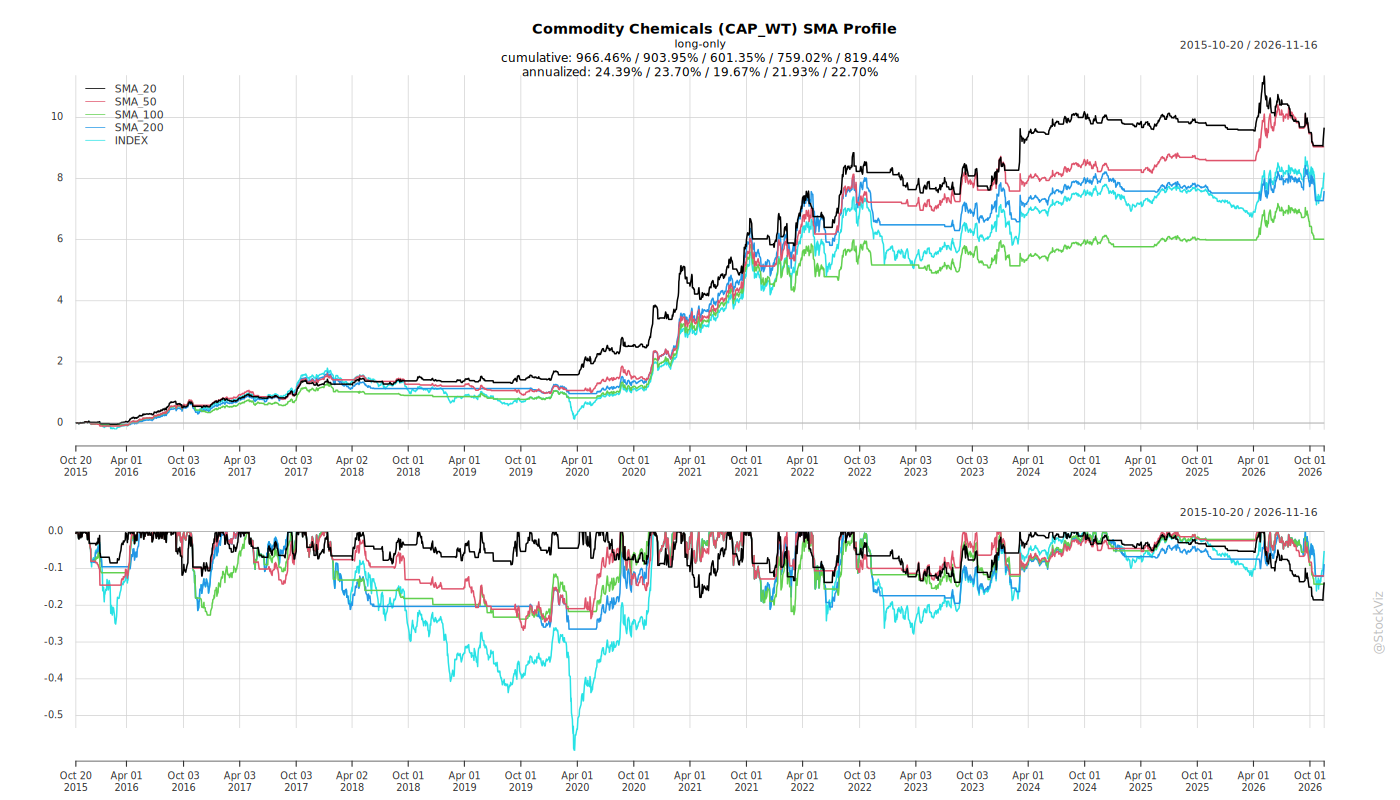
SMA Scenarios
Current Distance from SMA
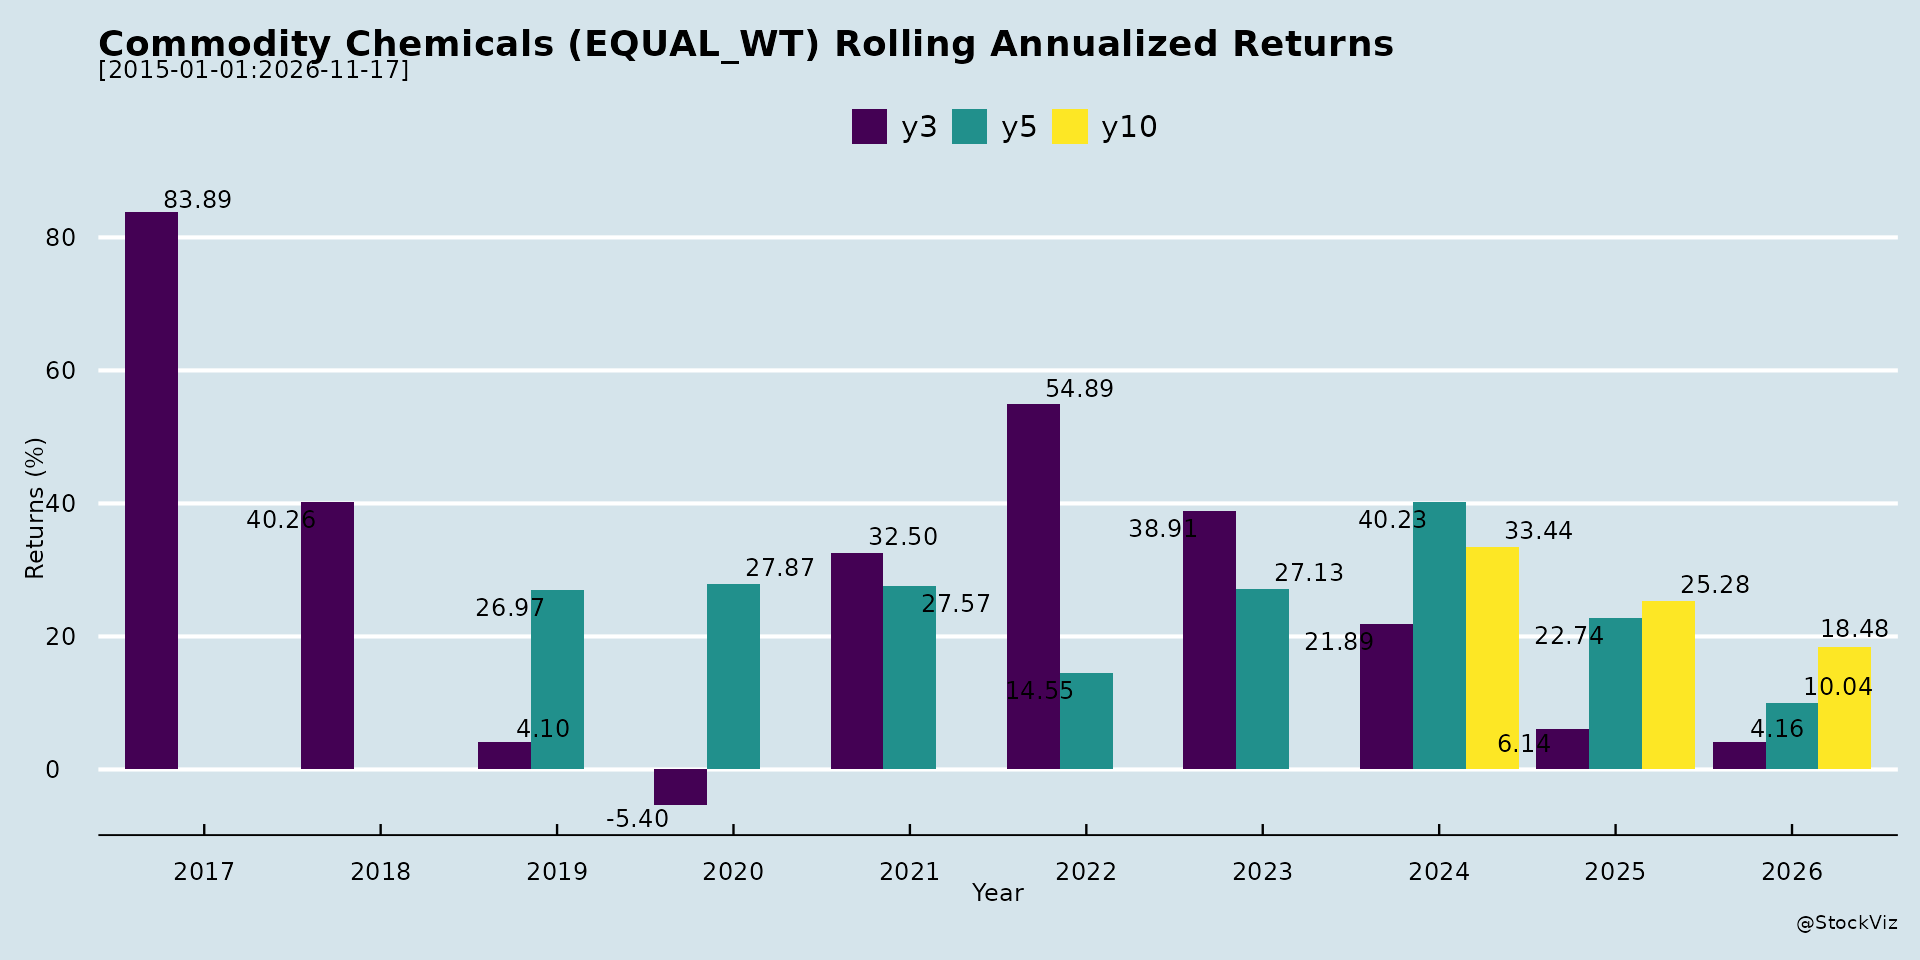
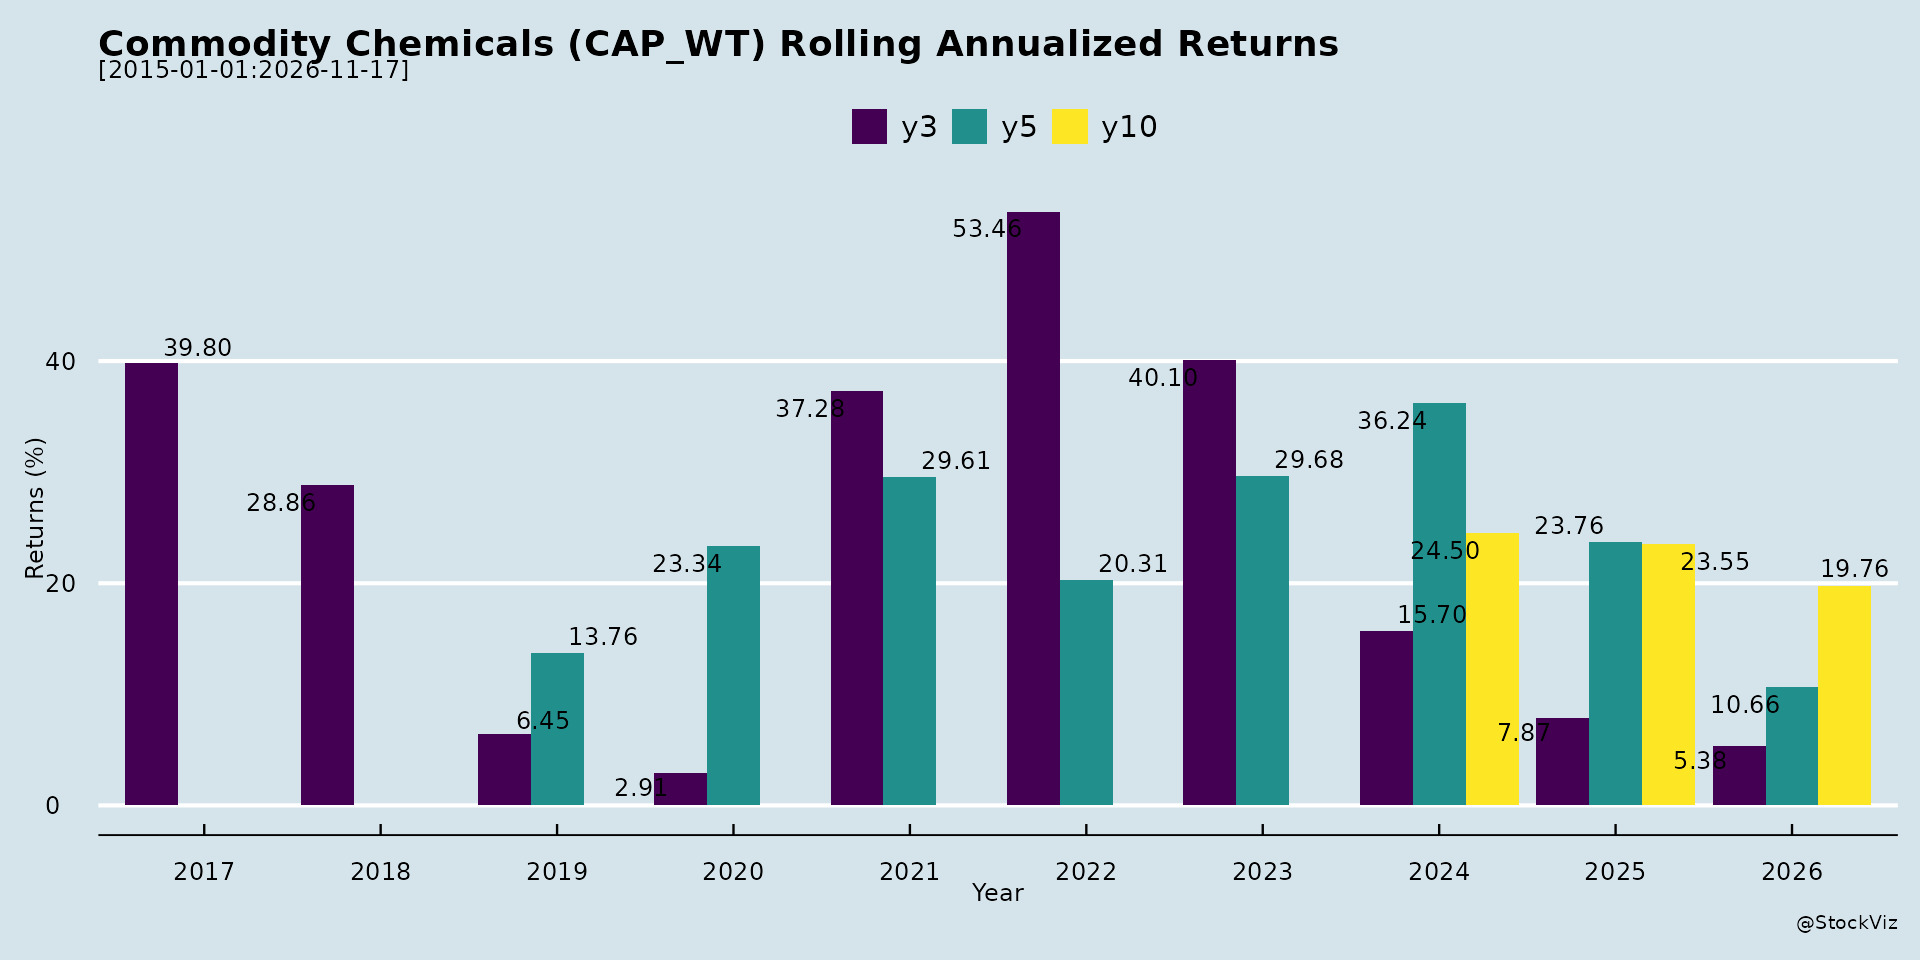
Rolling Returns
Fundamental Ratios
AI Summaries
Analyst
asof: 2025-11-29
Indian Commodity Chemicals Sector Analysis
Based on Q2/H1 FY26 Earnings Transcripts (Tata Chemicals, Deepak Fertilisers, GNFC, Chemplast Sanmar, OCCL, etc.)
The sector faces short-term pressures from oversupply and imports but shows resilience through domestic demand, ADD protections, and capacity expansions. Key sub-segments: Soda Ash, PVC, Fertilisers/TAN, Ammonia/IPA, Insoluble Sulphur, Nitric Acid/AN Melt.
Headwinds (Short-term Challenges)
- Oversupply & Price Pressure: Soda Ash global oversupply (China inventories ~1.65MT, operating rates high); PVC dumping from China/EU/US; Ammonia/IPA volatility (prices down to $300/MT, now rebounding); Insoluble Sulphur realizations soft due to global excess.
- Imports/Dumping: Continued cheap imports despite ADD (e.g., Soda Ash MIP extended but ineffective; PVC arrivals up from China; Malaysia/China undercutting in Insoluble Sulphur).
- Input Cost Inflation: Rising sulphur ($10K/tonne YoY impact on OCCL); gas/power costs; raw material shortages (Deepak Fertilisers).
- Demand/Seasonal Weakness: Monsoon disruptions (TAN/LDAN volumes down); weak China/SE Asia (Solar PV/EV slowdown); extended rains impacting mining/agri.
- Geopolitical/Regulatory: US tariffs (50% on India, impacting OCCL/others); BIS QCO withdrawal for PVC (quality/public health risk); delays in ADD notifications (PVC/Soda Ash).
- Operational: Plant shutdowns/outages (GNFC, Deepak); one-offs (Tata UK provisioning Rs65Cr).
Tailwinds (Supportive Factors)
- ADD/Trade Protections: Soda Ash ADD recommended ($17-100/tonne, DGTR submission); PVC ADD filings (China/EU); TAN export quota hiked (Deepak); Kenya litigation win (Tata).
- Domestic Demand Recovery: Robust India tyre radialization (OCCL 60-65% share target); Crop Nutrition +54% YoY (Deepak); Fertiliser Rabi demand post-monsoon; PVC auto/footwear pickup.
- Cost Efficiencies: UK reconfiguration (Tata EBITDA positive Q3); green power/LNG contracts (Deepak Ammonia breakeven down); AT Kearney savings (GNFC Rs200Cr/yr).
- Subsidy/Policy Support: NBS upward revision (GNFC +Rs872/MT); urea fixed cost revision expected.
- Margin Stabilisation: Ammonia rebound >$400/MT; Soda Ash range-bound; Paste PVC full capacity (Chemplast).
Growth Prospects (Medium-Long Term)
- Capacity Expansions: Tata (Soda Ash +50%, Silicate/Bi-carb); Deepak (TAN Gopalpur 87% complete, Nitric Acid 70%); GNFC (AN Melt 163KT, WNA, Ammonia); Chemplast (CMCD Phase 3/4, R32 refrigerant 14KT+); OCCL (Insoluble Sulphur market share to 65% domestic).
- Value-Added Shift: Specialties 22-35% revenue (Deepak Croptek/TAN B2C); Chemplast CSM (17 products, Rs1,000Cr by FY27 @20-25% EBITDA); GNFC TGU/AN Melt.
- Demand Drivers: Agri/infra/mining (TAN +29% YoY); EV/Solar (Soda Ash); Tyres (India fastest-growing); Import substitution (GNFC BPA/Polyols Rs7-8K Cr).
- Outlook: H1 revenue +9-13% YoY (Deepak/Tata); FY26 EBITDA margins 15-20%; FY27+ growth via 70-80% utilizations (Deepak TAN).
| Key Metrics Snapshot | Q2 FY26 | H1 FY26 YoY |
|---|---|---|
| Revenue Growth | +9-19% | +13% (Deepak) |
| EBITDA Margins | 15% (Deepak), 16.8% (OCCL) | Stable/Up (Tata +67% standalone) |
| PAT Growth | Stable/+16% | +11% (Deepak) |
Key Risks
- Import Persistence/Dumping: ADD delays/non-implementation (PVC/Soda Ash); Malaysia/China price undercutting.
- Commodity Volatility: Sulphur/gas/ammonia prices; China capacity additions (Soda Ash natural/synthetic balance).
- Geopolitical/Trade: US tariffs resolution delay; global tariffs (PV glass in Malaysia/Vietnam).
- Execution/Delays: Capex overruns (Deepak/GNFC Rs2.8K Cr pipeline); ramp-up risks (Chemplast CSM new molecules).
- Demand/Macro: Agri/mining slowdown (monsoons); China weakness spill-over.
- Regulatory: BIS reversal; subsidy revisions; litigation (e.g., GNFC Rs20K Cr telecom demand, low risk).
- Leverage: Net debt up (Deepak 1.74x, Chemplast Rs1.3K Cr); cash flows strained by capex.
Overall Summary: Sector resilient amid oversupply (headwinds dominate Q2), buoyed by ADD/domestic demand (tailwinds). Growth anchored in expansions/specialties (FY27 inflection), but risks from imports/volatility persist. Positive LT outlook (tyre/agri/EV drivers); monitor ADD notifications & RM costs for near-term triggers. Neutral-Positive rating; watch H2 FY26 for capex fruition.
General
asof: 2025-11-29
Analysis of Indian Commodity Chemicals Sector
The provided filings from companies like Tata Chemicals, Deepak Fertilisers, GNFC, Chemplast Sanmar, Gujarat Alkalies, Thirumalaichemicals, J.G. Chemicals (zinc oxide focus), IG Petrochemicals, Amines & Plasticizers, Andhra Sugars, Sree Rayalaseema, and Indo Borax offer insights into basic chemicals (e.g., soda ash, fertilizers, zinc compounds, plasticizers). These reflect a mix of operational updates, compliance issues, expansions, and financial disclosures. Below is a structured analysis of headwinds, tailwinds, growth prospects, and key risks for the sector.
Headwinds (Challenges/Constraints)
- Regulatory and Compliance Pressures: Environmental penalties (e.g., Tata Chemicals’ US subsidiary fined USD 20,400 for calciner test failure) and tax notices (Thirumalaichemicals’ CGST tax under Section 73) highlight rising scrutiny on emissions, pollution, and tax compliance. ESG ratings (GNFC at 51, independent) indicate moderate performance, potentially raising costs for non-compliance.
- Operational Disruptions: Plant halts (Indo Borax resumed Pithampur operations after shutdown) and delays (IG Petrochemicals extended plasticizer plant to Dec 2025, liquidating subsidiary) signal supply chain vulnerabilities and execution risks.
- Administrative/Investor Burdens: Dividend withholding (Amines & Plasticizers, Sree Rayalaseema reminders for IEPF transfers) due to KYC non-compliance affects investor sentiment and liquidity.
- Cost and Input Volatility: Implicit in filings (e.g., zinc scrap sourcing for J.G. Chemicals), with global metal price linkages (LME) exposing to forex/commodity swings.
Tailwinds (Supportive Factors)
- Strategic Investments and Diversification: Deepak Fertilisers’ Rs 75 Cr AIF investment in agritech via subsidiary signals pivot to value-added, low-risk growth. Gujarat Alkalies updated investor presentation for transparency.
- Financial Strength: J.G. Chemicals stands out with 27% revenue growth (Rs 8,479 Mn), 81% EBITDA surge (Rs 961 Mn, 11.33% margin), zero debt post-expansions, and 30% domestic zinc oxide market share. Recycling focus (90% recycled zinc) aids sustainability.
- Operational Resiliences: Quick plant restarts (Indo Borax) and AGM compliance (Chemplast Sanmar, Andhra Sugars director transitions) show adaptability.
- Policy Support: SEBI circulars on disclosures/ESG enhance governance, indirectly benefiting compliant firms.
Growth Prospects
- Capacity and Market Expansion: J.G. Chemicals’ Gujarat greenfield (H1FY27, targeting tyres/ceramics/pharma) and R&D unit (Rs 60 Mn) could boost capacity to 70k+ TPA zinc chemicals. Deepak Fertilisers eyes farmer-centric agritech via AIF for financial/strategic returns.
- Sector Tailwinds: Strong demand from tyres (85% of J.G.’s revenue; serves 9/10 global tyre makers), ceramics (13.5% CAGR to $17 Bn by FY29), fertilizers (6% CAGR to $74 Bn by FY33), EVs/batteries (zinc oxide role). Recycling edge (J.G.: 80% CO2 reduction vs. virgin zinc) aligns with sustainability push.
- Export/ Domestic Balance: J.G.’s 50+ international clients in 10+ countries; sector exports resilient (e.g., Deepak’s AIF for agri-business models).
- Financial Outlook: J.G.’s FY25 PAT doubled to Rs 668 Mn (EPS Rs 16.34); zero-debt status enables capex. Sector GDP-linked growth (India’s 6.5% FY26 projection).
Key Risks
| Risk Category | Description | Examples from Filings | Mitigation |
|---|---|---|---|
| Regulatory/Environmental | Penalties, ESG scrutiny, tax disputes. | Tata penalty; GNFC ESG 51; Thirumalaichemicals GST notice. | Compliance filings; J.G.’s certifications (ISO, WHO-GMP). |
| Operational | Plant delays/shutdowns, raw material sourcing. | IG Petro extension; Indo Borax resumption; zinc scrap dependency (J.G.). | Expansions (J.G. Gujarat); global networks (100+ suppliers). |
| Financial/Market | Commodity price volatility (LME-linked); tyre sector reliance (~85% for J.G.). | Zinc pricing; forex exposure. | Hedging (derivatives); diversification (zinc sulphate, batteries). |
| Compliance/Investor | KYC/IEPF issues; director changes. | Amines/Sree Rayalaseema dividends; Andhra Sugars AGM. | Reminders; governance policies. |
| Execution | Capex delays (R&D, plants). | J.G. FY27 greenfield; IG Petro timeline slip. | Zero-debt flexibility (J.G.). |
Overall Sector Summary: Indian commodity chemicals shows resilience (e.g., J.G. Chemicals’ stellar growth) amid headwinds like regulations and ops disruptions. Tailwinds from investments/diversification support 10-12% CAGR (zinc oxide/fertilizers). Growth hinges on tyres/EVs/ceramics, but risks from compliance/volatility persist. Positive: Recycling/sustainability edge; monitor J.G. as bellwether (India’s #1 zinc oxide maker).
Investor
asof: 2025-11-29
Analysis of Indian Commodity Chemicals Sector (Based on Q2/H1 FY26 Earnings Transcripts)
The provided documents primarily cover earnings calls and filings from key Indian players in commodity chemicals (e.g., Tata Chemicals - soda ash; Deepak Fertilisers - TAN/IPA/Ammonia; GNFC - fertilizers/nitric acid/TDI; Chemplast Sanmar - PVC/custom chemicals; OCCL - insoluble sulphur; Amines & Plasticizers - amines/solvents; others like GHCL). These reveal a cyclical sector under short-term pressure from global oversupply (esp. China) but buoyed by domestic demand, protectionism, and expansions. Below is a structured summary of headwinds, tailwinds, growth prospects, and key risks.
Headwinds (Short-Term Pressures)
- Oversupply & Dumping: Severe in soda ash (China inventories ~1.65MT, prices down 56-58% since FY23; Tata), PVC (China/EU/US dumping; Chemplast), insoluble sulphur (global supply 357KT vs. demand 275-300KT; OCCL). Imports exert pricing pressure despite ADD (e.g., Malaysia/China in sulphur).
- Raw Material Volatility: Rising sulphur prices (OCCL/Tata), gas costs (Deepak Ammonia), ammonia/methanol spikes (GNFC/Chemplast). Offset ADD benefits.
- Geopolitical/Trade Barriers: US 50% tariffs on Indian exports (OCCL impact on US sales ~margins hit); Trump tariffs disrupting PV glass/solar (Tata).
- Demand Softness: China real estate slowdown, monsoon disruptions (Deepak TAN), extended rains (GNFC). Global tyre/PVC demand weak.
- Margin Squeeze: EBITDA margins dipped (e.g., Tata consol EBITDA down; Chemplast 15%; OCCL 16.8% vs. 21.7% prior). One-offs like shutdowns (Deepak), forex losses.
- Operational Issues: Plant shutdowns (Deepak Ammonia, OCCL sulphuric acid), raw material shortages (Deepak fertilizers).
Tailwinds (Supportive Factors)
- Protectionism: ADD imposed/recommended (soda ash on China/Turkey/US; OCCL on China/Japan; PVC on China/EU). MIP extended (Tata soda ash). BIS QCO pushback noted but potential rethink for quality.
- Domestic Demand Resilience: Strong tyre radialization (OCCL 55% share → 60-65%), fertilizers (Deepak Crop Nutrition +54% YoY), agrochem/power (GNFC TGU/AN Melt).
- Cost Efficiencies: Green energy (Chemplast/Amines solar), Equinor LNG (Deepak Ammonia), consultancy savings (GNFC Rs.600Cr target).
- Subsidy/Support: NBS upward revision (GNFC +Rs.872/MT), tax settlements (Tata Kenya).
- Stable Volumes: Domestic tyre/OEM growth (OCCL 70% util.), TAN full capacity (Deepak +29% YoY).
Growth Prospects (Medium-Long Term)
- Capacity Expansions: Aggressive capex (Tata: +50% soda ash, silica; GNFC: Rs.2,800Cr AN Melt/nitric acid; Deepak: TAN 87%/Nitric 70% complete; Chemplast: R32 refrigerant 14KT → more; OCCL domestic share).
- Value-Addition Shift: Commodities → specialties (Deepak Croptek 54%; Tata FOS/bicarb; Amines 43 new products).
- Sector Tailwinds: EV/solar (soda ash demand), mining/infra (Deepak TAN B2C +33%), tyre growth (India fastest insoluble sulphur market), HFC quotas (Chemplast R32 by 2027).
- Exports: TAN quota +50KT (Deepak), global NMMO leadership (Amines 85+ countries).
- Projections: Revenue/EBITDA growth (Deepak H1 +13%/2%; GNFC TDI/AN Melt ramps; OCCL 2-3% global demand CAGR).
Key Risks
- Import Persistence: ADD delays/non-implementation (Tata soda ash pending MoF; Chemplast PVC deadline lapsed?), circumvention (Malaysia post-China ADD).
- Input Cost Escalation: Sulphur/gas/ammonia volatility; China synthetic-to-natural soda ash shift (Tata: +5-6MT natural by 2029-30).
- Geopolitical/Trade: US-India tariffs, China oversupply/export bans, EU capacity shutdowns redirecting to India.
- Execution/Demand: Capex delays (Deepak Q4 commissioning), monsoon/mining slowdowns, China real estate drag.
- Currency/One-Offs: Forex (Tata GBP depreciation), shutdowns/litigation (Tata Kenya resolved but appeal risk).
- Competition: New capacities (India PVC/soda ash), global oversupply normalization uncertain (18 months; Tata).
Overall Summary
Short-term (FY26): Challenging with oversupply/pricing pressure (soda ash/PVC/sulphur) capping margins at 10-19% despite ADD. Volumes stable domestically but exports muted (US tariffs). Revenue growth modest (e.g., Tata +19% standalone; Deepak +9-13%).
Medium-term (FY27+): Optimistic via expansions (multi-billion capex pipeline), domestic protectionism, and tyre/agro/infra demand. Sector poised for 2-5% CAGR globally, higher in India (tyres/fertilizers). Shift to specialties/R32 enhances resilience.
Strategic Focus: Cost control, ADD advocacy, green energy, R&D (Amines 43 new products). Bull case: Domestic self-reliance + EV/mining boom (EBITDA 20-25%). Bear case: Prolonged China dumping + input spikes (margins <10%).
Data as of Q2/H1 FY26 transcripts (Nov 2025); sector cyclicality warrants monitoring China/global trade.
Press Release
asof: 2025-11-30
Analysis of Indian Commodity Chemicals Sector (Q2/H1 FY26 Insights)
The provided documents cover financial results and press releases from key players in the Indian commodity chemicals sector (e.g., Tata Chemicals, Deepak Fertilisers, GHCL, Chemplast Sanmar, Amines & Plasticizers, OCCL, Lords Chloro Alkali, GNFC). These firms primarily deal in soda ash, fertilizers, PVC, caustic soda, amines, insoluble sulphur, and nitro chemicals. Overall, the sector shows resilient volumes amid pricing headwinds, with standalone improvements via cost discipline but consolidated pressures from imports and volatility. H1 FY26 revenue growth averaged ~5-15% YoY where reported, but EBITDA margins contracted 100-400 bps due to external factors. Below is a structured analysis of headwinds, tailwinds, growth prospects, and key risks, synthesized from common themes.
Headwinds (Key Challenges)
- Oversupply & Pricing Pressure: Soda ash (Tata, GHCL) markets globally oversupplied with high inventories; prices weakened 3-20% YoY. PVC (Chemplast) and IPA/Ammonia (Deepak) faced subdued realizations due to weak demand and imports.
- Cheap Imports: Dominant issue—anti-dumping duties sought/pending on soda ash (GHCL), PVC/insoluble sulphur (OCCL, Chemplast) from China/EU/US. GHCL noted “predatory import pricing”; Chemplast cited EU imports eroding Paste PVC margins.
- Raw Material Volatility: Ammonia/EO shortages (Amines), benzene/acetone price drops (Deepak), impacting costs. Energy costs high pre-renewables.
- Seasonal/External Factors: Monsoon reduced mining/fertilizer volumes (Deepak, Tata); geopolitical tensions raised input costs.
- Financial Impact: EBITDA down 6-35% YoY (avg. ~15%); PAT flat/negative in some (Chemplast loss widened).
Tailwinds (Positive Drivers)
- Domestic Demand Resilience: Strong in fertilizers (Deepak +13% rev YoY), mining chemicals (TAN volumes +29% YoY), tyres/auto (OCCL insoluble sulphur), caustic (Lords +59% rev). Good monsoon boosted agri/fertilizer outlook.
- Cost Optimization: Aggressive measures—e.g., Tata/Deepak volumes/cost control lifted standalone EBITDA 35-67%; solar plants cut energy costs 19% (Lords). GHCL/OCCL renewables ahead of targets.
- Policy Support: Anti-dumping duties on China/Japan (OCCL) improved realizations; export quotas eased (Deepak TAN).
- Operational Efficiency: Higher utilizations (Deepak DNA 102%, IPA 104%); reconfiguration (Tata UK to specialties).
- Financial Impact: Volumes up 10-50% in key products; EBITDA margins held 15-20% via discipline (Lords 20.8%, OCCL 19%).
Growth Prospects
- Capacity Expansions: Aggressive capex (~₹4,000-5,000 Cr sector-wide): | Company | Key Projects | Capex/Impact | |———|————–|————-| | Deepak | TAN Gopalpur (87% complete), Nitric Dahej (70%), PBS acquisition | +₹1,000 Cr rev; Asia’s largest Nitric producer | | Tata/GNFC | Ammonia revamp, Coal Cogen, Weak Nitric Acid-III | ₹51-100 Cr annual savings; +48% capacity | | Lords | +100 TPD Caustic/Sulphuric Acid, +21 MW Solar | Total ₹355 Cr FY24-28 | | GHCL/Chemplast/OCCL | Bromine/salt, MPB expansions, PVC | Diversification to specialties |
- Diversification: Shift to specialties (Tata non-cyclical, Deepak Croptek +54% vol, GHCL solar glass); exports (Deepak TAN quota +50KT).
- Sustainability: Solar/NG contracts (Deepak Equinor) for cost edge; GNFC IT arm (nCode) +₹80 Cr rev.
- Market Tailwinds: Infra/mining boom (TAN demand), EV/solar glass (soda ash), Rabi agri season (fertilizers). Sector CAGR ~10% (GNFC chemicals).
- Outlook: FY26 “range-bound” but resilient; H2 recovery via monsoon/post-monsoon demand.
Key Risks
| Risk Category | Details | Mitigation Noted |
|---|---|---|
| Imports/Competition | Persistent cheap Chinese/EU/US imports; ADD delays (GHCL, OCCL). | Duties filed; domestic focus. |
| RM/Commodity Volatility | Ammonia/EO/sulphur spikes (Deepak, Amines); sulphur +50% US duty risk (OCCL). | Backward integration, hedging. |
| Execution/Demand | Capex delays (GHCL greenfield slow); monsoon/economic slowdown (Deepak volumes -7% QoQ). | Phased commissioning (Q4 FY26). |
| Geopolitical/Macro | Trade wars, forex (Deepak OCI forex hedges); global oversupply (soda ash). | Diversification, cost controls. |
| Financial/Regulatory | Debt rise (Deepak net debt +₹97 Cr); IT/penalty appeals (Deepak, GNFC). | Strong cash flows (Deepak ops ₹47 Cr). |
Summary
| Aspect | Sector Snapshot (H1 FY26) |
|---|---|
| Performance | Revenue +5-60% YoY (driven volumes); EBITDA -15% avg., margins 15-20% via costs. PAT resilient (e.g., Lords +743%). |
| Net | Mildly Positive: Tailwinds from domestic demand/costs offset headwinds; expansions position for 10-15% CAGR. |
| Outlook | Cautious optimism—H2 growth via projects/duties; risks tilted to imports/volatility. Focus: Specialties (28-50% rev share), green energy. |
The sector demonstrates defensive resilience (cost focus, policy wins) but needs import safeguards for sustained margins. Investors should monitor ADD outcomes and capex execution. Data as of Nov 2025 reports.
Copyright © 2023 SAS Data Analytics Pvt. Ltd. All rights reserved.